
Bangladesh Textile Manufacturing Market Analysis by Mordor Intelligence
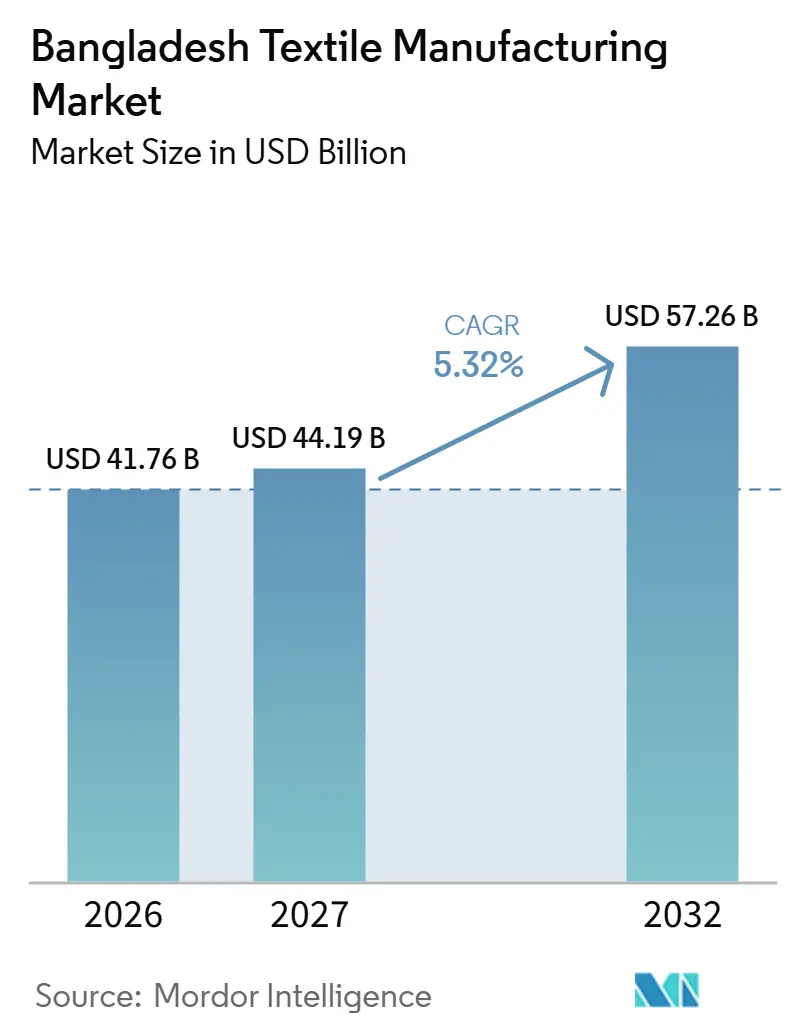
The Bangladesh textile manufacturing market size is expected to grow from USD 41.76 billion in 2026 to USD 44.19 billion in 2027 and is forecast to reach USD 57.26 billion by 2032 at 5.32% CAGR over 2027-2032.
Preferential access and buyer emissions expectations reward Bangladeshi fabric exporters that can qualify regional inputs, add rooftop solar and treat wastewater, which makes those capabilities part of how mills compete for export orders. The Strait of Hormuz closure during the US-Iran war disrupted QatarEnergy's LNG supplies to Bangladesh beginning in April 2026. A fire-related technical shutdown at Excelerate's Moheshkhali floating storage and regasification unit (FSRU) disrupted national gas supply from July 2026. These shocks make process-energy continuity the condition for turning tariff eligibility into shipped fabric, because wet-processing lines stop when fuel is cut.
Key Report Takeaways
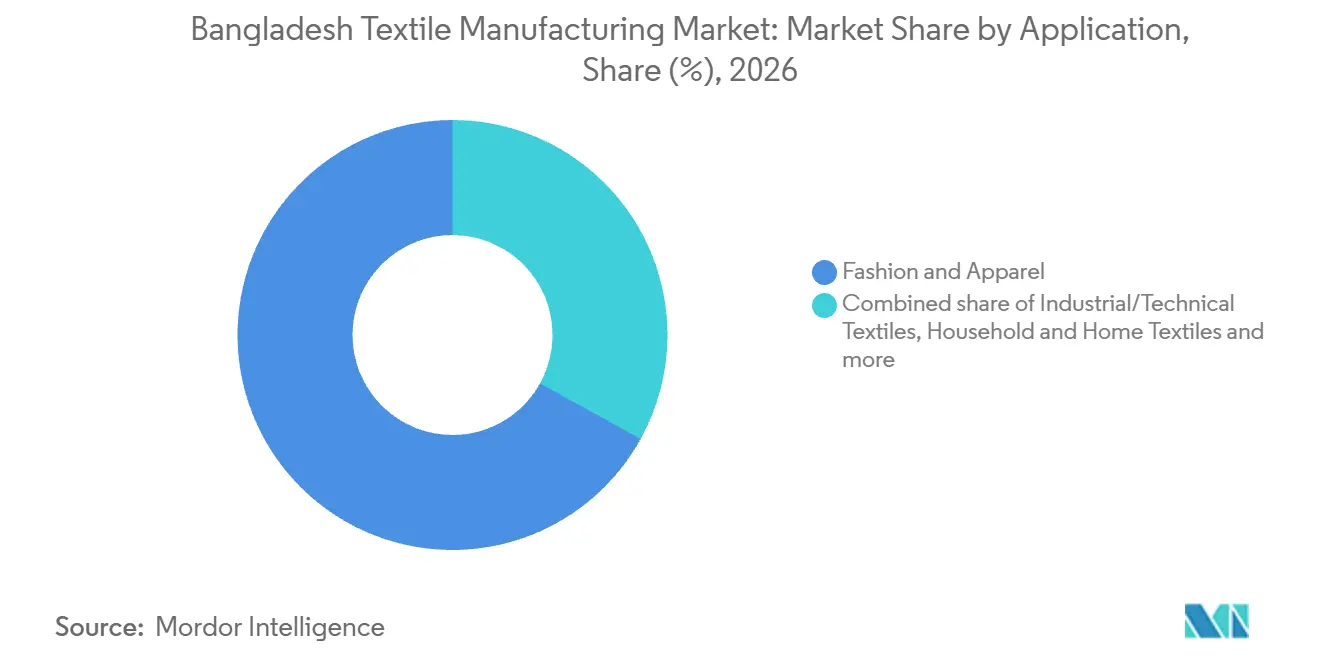
- By application, fashion and apparel held a 66.96% Bangladesh textile manufacturing market share in 2026, while industrial/technical textiles are forecast to be the fastest-growing segment at 5.96% CAGR over 2027-2032.
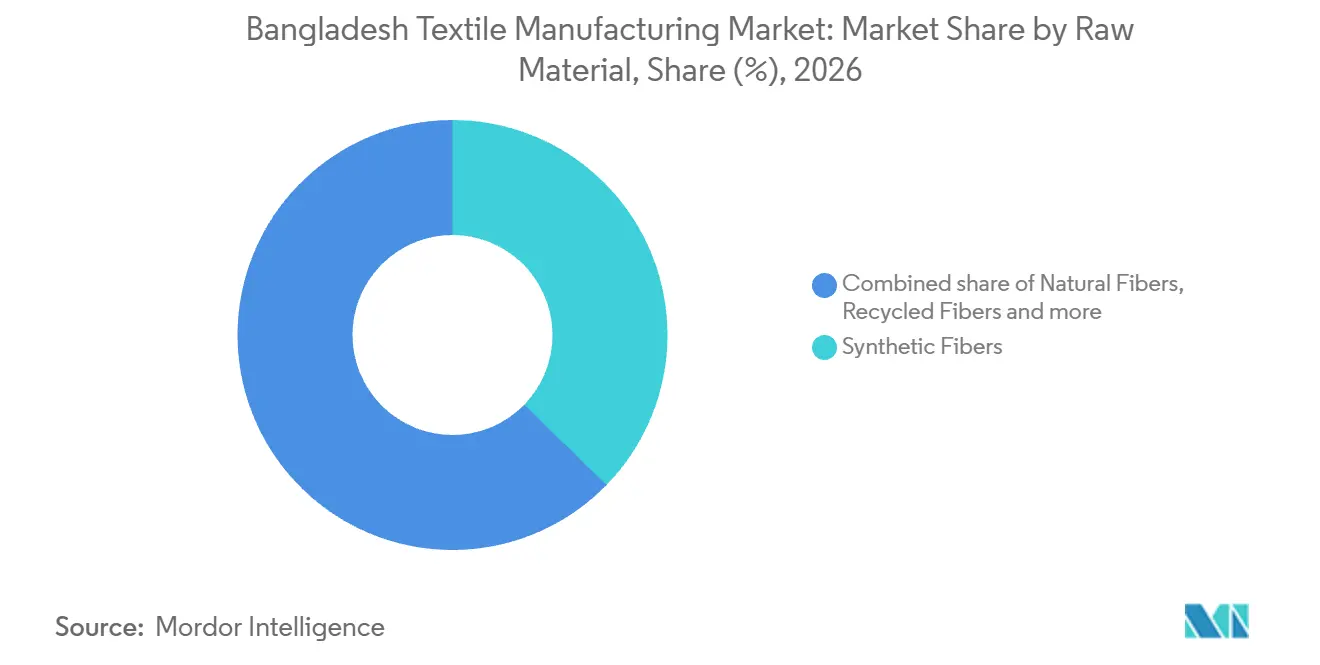
- Synthetic fibers led raw materials with a 37.28% share of the Bangladesh textile manufacturing market size in 2026 and are forecast to be the fastest-growing segment at 6.1% CAGR over 2027-2032.
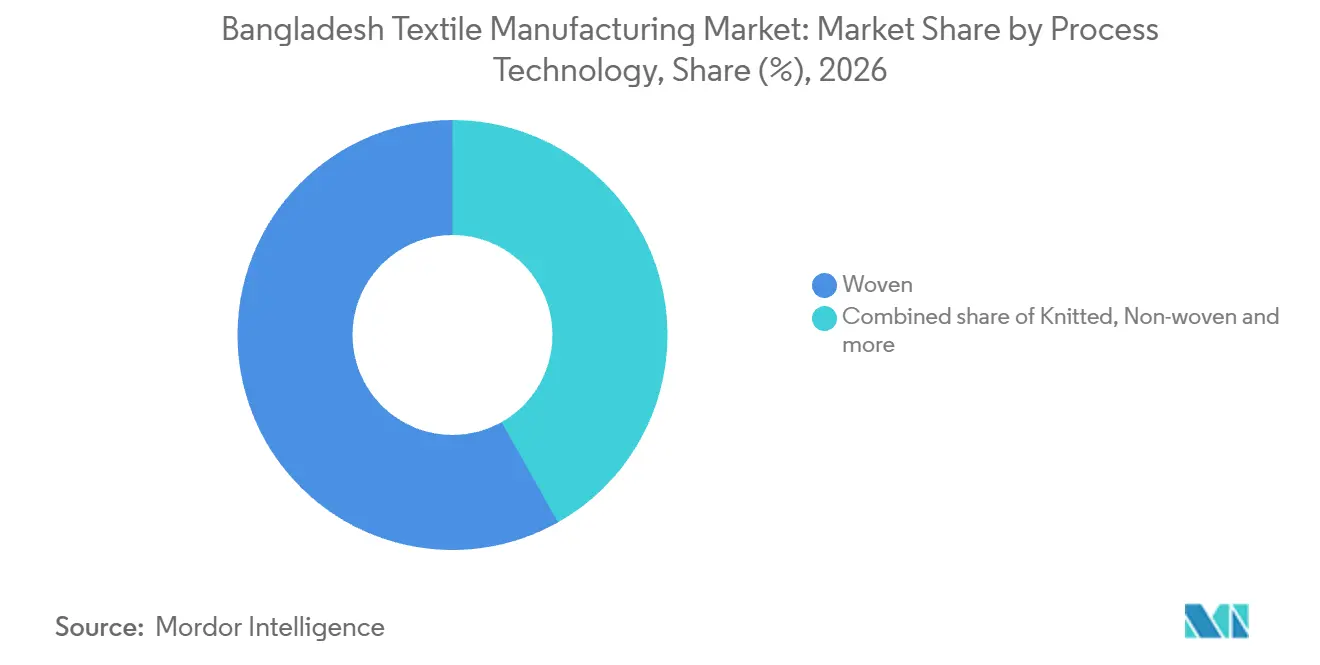
- Across processes and technologies, woven held a 58.17% share in 2026, while non-woven is forecast to be the fastest-growing segment at 5.9% CAGR over 2027-2032.
- Geographically, Dhaka held 52.33% of the market in 2026, while Chittagong is forecast to be the fastest-growing geography at 5.45% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Bangladesh Textile Manufacturing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Duty-free access extension under UK DCTS & potential EU GSP+ access | +3.5% | Nationwide | Short term (≤ 2 years) |
| Brand-mandated renewable-energy (rooftop solar) projects lower Scope-2 emissions | +1.7% | Nationwide | Short term (≤ 2 years) |
| Compliance readiness for EU Corporate Sustainability Due Diligence Directive boosts sourcing | +1.5% | Nationwide | Medium term (2-4 years) |
| Competitive green-finance window for zero-liquid-discharge dyeing lines | +1.2% | Nationwide | Medium term (2-4 years) |
| National Special Economic Zone integrated textile & logistics hub | +0.7% | Mirsharai economic zone | Long term (≥ 4 years) |
| Gen-AI on-loom defect analytics enabling profitable micro-lot orders | +0.2% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Duty-free access extension under UK DCTS & potential EU GSP+ access
Preferential access supports export demand by preserving tariff eligibility while giving manufacturers more flexibility over qualifying inputs. Effective January 1, 2026, UK Developing Countries Trading Scheme (DCTS) rules allow eligible Asian regional inputs to count as Bangladeshi origin after final processing there for export to the UK.[1] Bangladesh is scheduled to graduate from UN least developed country (LDC) status on November 24, 2026, while its February 18, 2026, request for a 3-year preparatory-period extension awaits a decision. Under the adopted framework, Everything But Arms (EBA) preferences continue for 3 more years, at least through 2029, while Generalized System of Preferences Plus (GSP+) requires a separate application, qualifying conditions and broader sustainability commitments. Textiles represented almost 94% of EU imports from Bangladesh in 2025. This transition gives export mills time to qualify new input routes while preparing to retain European tariff benefits under the next eligibility framework.
Brand-mandated renewable-energy (rooftop solar) projects lower Scope-2 emissions
Rooftop solar gives textile exporters a tangible way to respond to buyers' emissions expectations while retaining control over factory electricity investment. In March 2026, DBL Group's managing director reported pressure from global buyers to reduce emissions and described rooftop solar as a practical option. DBL had installed 5.4 MW of rooftop solar in Bangladesh by that month. H&M Group, BESTSELLER, Gap Inc., Mango, Ralph Lauren, Marks & Spencer and Tchibo were developing investment proposals for emissions-reduction projects at shared suppliers in Bangladesh and India. A supplier can therefore make its energy assets part of the sourcing proposition, giving buyers an operating capability to assess alongside the textile product itself.
Compliance readiness for EU Corporate Sustainability Due Diligence Directive boosts sourcing
Supplier preparation can strengthen access to European buyers by making labor and environmental information easier to assess before procurement decisions. The amended CSDDD entered into force on March 18, 2026, with EU member-state transposition due July 26, 2028, and application from July 26, 2029. Article 16 reporting applies to financial years starting January 1, 2030, or later. SMEs are outside direct coverage, although smaller business partners may be affected indirectly through covered companies' value chains. The EU's 2025-2029 Decent Work Due Diligence Bangladesh project covers labor-standard monitoring in 370 garment and textile factories to support broader human rights due diligence. For suppliers, building usable labor records before application offers a route into demanding sourcing relationships where verifiable operating practices influence buyer assessment.
Competitive green-finance window for zero-liquid-discharge dyeing lines
Capital access can make water-treatment investment feasible for export dyehouses even when the equipment does not directly expand fabric output. The European Investment Bank signed a green credit line with BRAC Bank on December 30, 2025, for textile, garment and other export-focused green projects.[2] BRAC Bank is the financial intermediary linking the EIB financing with eligible private-sector investments in Bangladesh. Wastewater treatment and circular-economy projects are eligible categories for companies operating mainly in ready-made garments and textiles. This credit route can bring wastewater upgrades into an export dyehouse's capital program alongside fabric-making equipment.
Restraints Impact Analysis of Bangladesh Textile Manufacturing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic gas-supply shortfalls despite delayed LNG terminal expansion | -2% | Nationwide | Short term (≤ 2 years) |
| Climate-driven cotton price volatility strains working capital | -0.9% | Nationwide | Short term (≤ 2 years) |
| Digitization gap among tier-3 subcontractors risks capacity under-utilization | -0.4% | Nationwide | Medium term (2-4 years) |
| IoT-linked cybersecurity vulnerabilities risk costly downtime | -0.2% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Chronic gas-supply shortfalls despite delayed LNG terminal expansion
The constraint affected both imports and regasification, combining disrupted QatarEnergy deliveries from April 2026 with the Excelerate-operated Moheshkhali FSRU's fire-related technical shutdown from July 21, which Bangladesh's state minister linked to nationwide gas disruption. In August 2026, Bangladesh Textile Mills Association President Showkat Aziz Russell reported that more than 900 of its over 1,800 member mills were completely shut because of gas disruptions.[3] The FSRU resumed supply on August 22 after a separate 3-day halt. In October 2026, the government purchase committee returned China National Energy Engineering & Construction's proposed third floating LNG terminal at Moheshkhali, Cox's Bazar, for further review. Installed textile equipment cannot offset lost fuel supply, leaving restored process hours as the immediate condition for expanding shipments.
Climate-driven cotton price volatility strains working capital
Weather-related cotton price swings can strain a spinner's finances when raw-material commitments and yarn receipts fall at different points in the production cycle. If replacement fiber becomes more expensive after a yarn price is agreed, the same order can require a larger cash commitment before the manufacturer receives payment. Falling cotton prices can leave earlier stocks carrying higher costs. On December 23, 2025, the Bangladesh Textile Mills Association asked Bangladesh Bank to extend the 360-day import-credit period for cotton and other industrial raw materials through December 31, 2026. The association warned that reverting to 180 days would strain working capital and disrupt export-oriented textile production. That warning identifies a cash-cycle constraint that can leave cotton spinners with less room to finance the next yarn batch.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Bangladesh Textile Manufacturing Market Segment Analysis
By Application:
Apparel Scale and Infrastructure DemandFashion and apparel accounted for a 66.96% share of the Bangladesh textile manufacturing market size in 2026. Bangladesh's ready-made garment exports totaled USD 38.7 billion in FY2025-26, down 1.64% from FY2024-25. This downstream export base spans both knitted and woven garments, giving the largest segment more than one garment-production channel. Apparel-focused mills therefore serve a broad garment base whose export value declined in FY2025-26, so breadth alone does not remove their exposure to that downstream contraction.
Industrial/technical textiles are forecast to be the fastest-growing segment, with a 5.96% CAGR over 2027-2032. A Bangladesh Water Development Board contract-awarded tender covers supplying, filling and dumping polyester-fabric geotextile bags in Barguna Sadar, with work tentatively scheduled from June 15, 2026, to June 30, 2027. The package links textile supply to execution of a specific civil-works project, opening a demand channel beyond garment production. Household and home textiles reach a separate export channel, with provisional Export Promotion Bureau data showing a 6.52% increase in Bangladesh's home-textile exports in FY2025-26. Serving the technical-textile project requires a fabric offer that can be delivered with filling and placement services, rather than fabric volume alone.



By Raw Material:
Synthetic Scale and Fiber RecoverySynthetic fibers represented a 37.28% Bangladesh textile manufacturing market share in 2026, making them the largest segment, and are forecast to be the fastest-growing segment at 6.1% CAGR over 2027-2032. Modern Syntex, a TK Group concern, operated a facility with annual polyester staple-fiber capacity of 78,750 metric tons in September 2026. It also had annual capacity for 43,750 metric tons of polyester filament yarn and 38,500 metric tons of PET chips. These distinct product forms give textile manufacturers several polyester input options within one operating production complex.
Modern Syntex management reported in September 2026 that its facility met nearly 21% of Bangladesh's polyester-product demand. The reported demand coverage shows a domestic outlet for an operating polyester complex, giving local textile manufacturers an alternative source of these inputs. Recycled fibers have a separate manufacturing route, illustrated by Envoy Textiles Ltd.'s 2 mechanical recycling plants operating in Bhaluka, Mymensingh, in April 2026. The plants converted fabric waste into recovered fiber that fed back into yarn production. Large-scale polyester supply and internal fiber recovery therefore create different input strategies, with producers able to build around either established material throughput or reuse within yarn making.

By Process / Technology:
Woven Upgrades and Non-woven SpecificationsWoven accounted for 58.17% of the market in 2026, making it the largest segment. Envoy Textiles Ltd. expanded annual denim-fabric capacity from 52 million to 60 million yards, with added capacity in commercial use from the final quarter of FY2025-26. The company installed 40 replacement looms and expanded dyeing capacity in line with weaving capacity. This approach links replacement investment to the throughput of the textile chain, with weaving and wet processing considered together. Coordinating dyeing with weaving capacity lets a denim producer use existing downstream equipment more fully, so replacing looms can expand the fabric offer without rebuilding every stage.
Non-woven is forecast to be the fastest-growing segment, with a 5.9% CAGR over 2027-2032. Western Superior Jute Industries Ltd., a Western Group subsidiary, reports maximum non-woven geotextile capacity of 900 metric tons per month at Salna, Gazipur. Bangladesh Water Development Board civil-works specifications require needle-punched geotextile made from 100% polypropylene for geobags unless a drawing specifies another material. For non-woven geotextile producers such as Western Superior, the Board's specification defines an infrastructure application whose fiber and construction requirements shape the fabric offer.
Geography Analysis
Dhaka Textile Manufacturing Market
Dhaka accounted for 52.33% of the Bangladesh textile manufacturing market size in 2026. The Bangladesh Garment Manufacturers and Exporters Association's 2026 public-profile dataset included 116 garment factories in Dhaka, identifying a local downstream customer base for textile inputs. Pretty Composite Textiles Ltd. manufactures knitted fabric in Ashulia, Savar, Dhaka, as part of a business that also produces garments. For such manufacturers, fabric specifications can be coordinated with the garment process inside the same organization, linking textile decisions to downstream production requirements. This structure gives local textile development a direct route to garment use, while the wider factory base supports demand beyond any single integrated producer.
Chittagong Textile Manufacturing Market
Chittagong is the fastest-growing geography, with a forecast 5.45% CAGR over 2027-2032. American & Efird, an Elevate Textiles subsidiary, opened a spun and filament thread manufacturing operation in Chittagong on March 20, 2025. Huarun Tex Co. Ltd.'s July 16, 2026, land lease with the Bangladesh Export Processing Zones Authority covered a planned Mirsharai plant producing yarn and 20 million meters of gray woven fabric annually once fully operational. Operating thread production and prospective yarn and fabric capacity point to a broader input-supply offer, giving the region more than one route to manufacturing expansion.
In FY2024-25, Tamijuddin Textile Mills PLC's Konabari spinning mill in Gazipur produced and sold cotton and polyester yarn locally and exported under back-to-back letters of credit to knitwear and woven industries. This links spinning activity to 2 distinct downstream production routes, allowing the same upstream operation to address knitting and weaving requirements. The rest of Bangladesh includes a different channel opportunity in Narayanganj, where the textiles and jute minister described Jamdani Village project implementation on March 24, 2026. The government project targeted research, improved weaving varieties and market access, with site preparation and drainage work then in their final stages. These areas offer different expansion paths, combining yarn-supply relationships in Gazipur with efforts to improve market access for traditional weaving elsewhere.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions at national and local levels from the perspective of an integrated textile mill planning establishment or expansion. Bangladesh's Environment Conservation Act requires environmental clearance before industrial establishments or projects are established or expanded. The Environment Conservation Rules 2023 classify integrated textile mills combining spinning, weaving or knitting, dyeing and finishing as Red-category industries.
Regulatory Table of Bangladesh Textile Manufacturing Market
| Decision factor | Bangladesh | Gazipur |
|---|---|---|
| Primary authority | Department of Environment, Director General | Department of Environment, Director General |
| Key instruments or direction | Environment Conservation Act and Environment Conservation Rules 2023 | National Act and 2023 Rules applied locally |
| Commercial effect | Prior environmental clearance for establishment and expansion | Same clearance gate for local industrial projects |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
Bangladesh's Medium rating reflects the prior-clearance gate and Red classification for integrated textile mills, which make environmental preparation part of establishment and expansion. Gazipur's Medium rating reflects the national clearance requirement applying to industrial establishments and expansions in that location. On March 6, 2026, the Department of Environment (DoE) sought consultants for a planned amendment of the 2023 Rules, with consultancy services scheduled from June 1, 2026, to June 30, 2028. The continuing clearance and classification requirements support No change in both columns, while the planned consultancy places policy development on a separate 2026-2028 horizon.
Value Chain Stages
The value chain compares yarn spinning, fabric formation and wet processing by their revenue sources and dependence on adjacent production stages. In August 2026, Al Madina Textile Mill described buying processed yarn from sizing mills, making gray fabric and selling it to other factories for dyeing. A fabric maker's yarn purchases and sales to dyeing factories tie its revenue to throughput on both sides of its own looms.
Value Chain Analysis Table of Bangladesh Textile Manufacturing Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Yarn spinning | Yarn manufacturers such as Square Textiles PLC, Little Star Spinning Mill | Yarn sales | Power availability during spinning | Match production loads to available grid and backup power |
| Fabric formation | Fabric manufacturers such as Al Madina Textile Mill, Envoy Textiles Ltd. | Gray-fabric and denim-fabric sales | Coordination with downstream dyeing and finishing | Align weaving expansion with wet-processing capability |
| Dyeing and finishing | Integrated denim processors such as Envoy Textiles Ltd.; wet-processing specialists such as AR Wet Processing Ltd., a Fashion Globe Group company | Dyed-fabric sales and processing income | Fuel interruptions affecting wet processing | Sequence production around secured process-energy supply |
| Source: Mordor Intelligence | ||||
In August 2026, Little Star Spinning Mill reported output below 40% of capacity despite using electricity, solar and batteries, with gas pressure at 1 to 1.5 PSI. Its experience shows why diversified power sources need to be assessed against the production load they can actually sustain. Reliable spinning therefore protects the availability of yarn for separate fabric-making businesses, extending the value of energy continuity beyond the mill where the fuel is consumed.
Competitive Landscape
Market Concentration
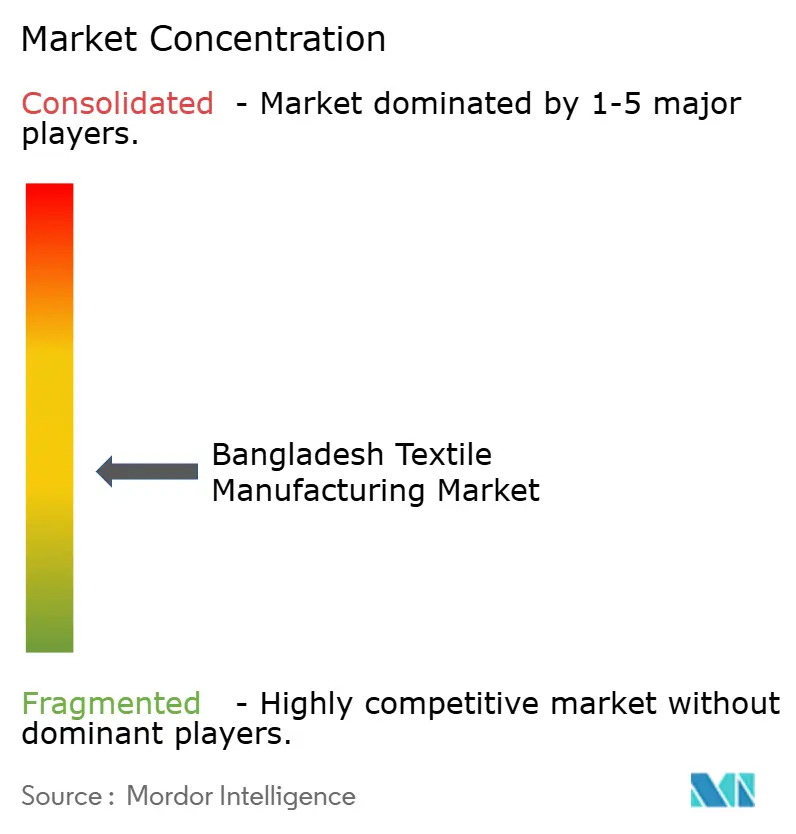
The field combines textile and garment groups such as Ha-meem Group with weaving-focused companies such as Noman Textiles Mills Limited. By February 2025, Ha-meem Group had a second rooftop solar plant installed by FloSolar Solutions, adding 4.4 MWp and taking renewable generating capacity to 12.2 MWp. Noman Group company Noman Textiles Mills Limited reported daily woven-fabric output of 100,000 yards in April 2025. Bangladesh's interim government announced in December 2025 that it would lease Beximco factories through open tender after shelving a near-final proposed restart with Revival Project Limited. Noman's measured fabric output demonstrates production capability, while Ha-meem's solar capacity supports factory energy supply and Beximco's announced leasing route concerns the potential return of idle factories.
Square Textiles PLC (formerly Square Textiles Ltd.) increased its export sales quantity by 16.35% in FY2024-25 versus FY2023-24, providing a measured volume result from an established yarn manufacturer. DBL Group's acquisition of Glory Textile and Apparels Limited was reported completed in March 2025, adding a textile and apparel business to its footprint. Square's higher export volume shows yarn already reaching overseas buyers. DBL's acquisition instead gives it a textile and apparel business under one owner, an option for buyers that want fabric and garments from a single group.
Energy integration and governance compliance address different operating requirements for textile manufacturers. In April 2025, Noman Textiles Mills Limited reported controlling weaving-floor temperature through humidity, no longer using chillers and using generator exhaust to run boilers. Square Textiles PLC's FY2024-25 annual report assigned its compliance auditor responsibility for certifying compliance with Bangladesh's Corporate Governance Code 2018 and relevant Bangladesh Secretarial Standards. That remit concerns corporate oversight rather than the mill-level energy practices described by Noman. In Noman's reported arrangement, generator exhaust supplied boiler heat, linking process steam to power generation without a separate boiler fuel stream.
Bangladesh Textile Manufacturing Industry Leaders
-
Ha-meem Group
-
Noman Group
-
Beximco Textile Division Ltd.
-
Square Textiles PLC
-
DBL Group
- *Disclaimer: Major Players sorted in no particular order
Bangladesh Textile Manufacturing Market Companies Covered in this Report
- Ha-meem Group
- Noman Group
- Beximco Textile Division Ltd.
- Square Textiles PLC
- DBL Group
- Viyellatex Group
- Epyllion Group
- Mohammadi Group
- Fakir Group
- Akij Textile Mills Ltd.
- Pakiza Group
- Masco Industries Ltd.
- Envoy Textiles Ltd.
- Pacific Jeans
- Youngone Corporation (BD Units)
- Regent Textile
- Givensee Group
- Opex Sinha Group
- Ananta Group
- Partex Denim Mills
Key Opportunities for Market Participants
The opportunities compare cotton, blended and recycled-content yarn applications from the perspective of manufacturers importing covered textile inputs. Bangladesh's 2026 Withholding Tax Rules reduced advance income tax from 2% to 0% on specified HS-coded inputs, including cotton, textile waste and certain artificial and synthetic staple fibers. Miswar Group produces cotton, polyester, recycled-cotton and recycled-polyester yarns for knitting and weaving in Bangladesh, illustrating production capability across these applications.
Market Opportunities Table of Bangladesh Textile Manufacturing Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Cotton yarn for woven production | Lower advance-tax cash outlay on covered cotton inputs | Woven-fabric mills | Connect qualifying cotton purchases with committed yarn supply | Input repricing against fixed-price export orders | Cotton spinners such as Miswar Group, where imports qualify |
| Cotton and manmade-fiber blended yarn | Cash relief on covered portions of fiber blends | Knitwear yarn buyers | Develop blends around the buyer's required yarn application | Limited cost pass-through in apparel supply contracts | Blended-yarn producers such as Miswar Group, where imports qualify |
| Recovered-content yarn supply | Reduced advance-tax outlay on covered textile-waste imports | Knitting and weaving buyers of recycled-content yarn | Pair a recovery partner with yarn-spinning capability | Energy-cost exposure during yarn production | Recycled-yarn producers such as Miswar Group, where input arrangements qualify |
| Source: Mordor Intelligence | |||||
In April 2026, Bangladeshi textile millers described difficulty managing higher cotton and yarn costs against export orders typically fixed at least 3 months in advance. Advance-tax relief therefore creates commercial value when the importer can preserve its cash advantage through production and sale. The central opening is to connect covered input purchases with a defined yarn application and contract terms that accommodate cost changes, keeping the financing benefit attached to saleable output.
Recent Industry Developments in Bangladesh Textile Manufacturing Market
- Oct 2026: Wendler Interlining Group celebrated the opening of a new LEED Gold-certified factory in Bangladesh on October 3.
- Jul 2026: Envoy Textiles Ltd.'s board acknowledged an increase in annual denim-fabric capacity from 52 million to 60 million yards, with the added capacity already in commercial production.
Bangladesh Textile Manufacturing Market Report Scope and Research Methodology
Market Definition and Coverage
The Bangladesh textile manufacturing market is the annual value of textile manufacturing output produced in Bangladesh, measured as manufacturers' ex-factory sales of textile fibers, yarns, fabrics and other textile materials. These sales supply apparel, household, industrial, medical, transport and other uses across Bangladesh.
Scope exclusions: Pure trading and distribution margins unrelated to local manufacturing output, finished apparel and other finished goods made from textiles, textile machinery and separately sold production services, and textile products manufactured outside Bangladesh are excluded.
Segments Covered in This Report
- By Application
- Fashion & Apparel
- Industrial/Technical Textiles
- Household & Home Textiles
- Medical & Healthcare Textiles
- Automotive & Transport Textiles
- Others (Protective, Sports Textiles, etc.)
- By Raw Material
- Natural Fibers
- Cotton
- Wool
- Silk
- Synthetic Fibers
- Polyester
- Nylon
- Rayon / Viscose
- Acrylic
- Polypropylene
- Recycled Fibers
- Others (Specialty High-Performance Fibers (Aramid, Carbon, UHMWPE))
- Natural Fibers
- By Process / Technology
- Woven
- Knitted
- Non-woven
- Spunlaid (Spunbond / Melt-blown)
- Dry-laid Hydro-entangled
- Wet-Laid
- Needle-punched
- 3-D Weaving & Spacer Fabrics
- By Geography
- Dhaka
- Gazipur
- Chittagong
- Rest of Bangladesh
Data Sources, Market Sizing, and Validation
Desk Research
Public and official sources such as Bangladesh Investment Development Authority materials, Bangladesh Bank's commodity-wise export series and Bangladesh Garment Manufacturers and Exporters Association export tables provide policy context and trade indicators, while the United States Department of Agriculture Foreign Agricultural Service's Bangladesh cotton annual informs fiber availability, mill use and yarn production trends. These sources help distinguish textile input and intermediate-product signals from downstream garment exports, which are contextual indicators rather than direct textile-manufacturing sales.
Company annual reports, exchange filings and investor materials can add plant capacity, product mix and utilization evidence, while reputable Bangladesh business press can clarify policy changes, plant events and operating disruptions. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include owners and senior executives of textile manufacturers, along with functional leaders and managers in spinning, weaving, knitting, dyeing, finance, exports and procurement, across large, mid-sized and smaller Bangladesh producers. Questions would test secondary evidence on output, ex-factory prices, capacity use, material mix, process mix, end uses and location, and would clarify how integrated operations avoid counting the same output twice. If supporting records do not resolve a material input difference, analysts would ask a relevant respondent to clarify the cause and check the explanation against independent trade, production and company evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The national estimate would start with a top-down view of Bangladesh-produced textile materials sold at ex-factory prices, using textile output and trade data to establish the production pool and removing imported products and downstream finished-goods sales. Analysts would compare cotton and man-made fiber availability and mill use, yarn and fabric production, textile export shipments, mill capacity and utilization, and reported product prices. These indicators help explain output volume, the domestic-versus-export outlet mix and realized value. Application, raw-material, process and location shares would be built from reported production mix, mill capacities and product destinations, checked against company disclosures and relevant Bangladesh industry evidence. For the annual outlook through 2032, scenario analysis would vary output, utilization, material and product mix, price realization and energy availability, with each variable tied to its observable indicator and reviewed by relevant primary respondents. Selective bottom-up checks would multiply sampled supplier output or capacity by supported utilization and ex-factory prices, then compare those roll-ups with the national estimate. Missing observations would be bounded with documented public indicators and tested across scenarios rather than filled with unsupported precision.
Data Validation & Update Cycle
Analysts would triangulate the estimate against independent production, trade, capacity and company signals, then investigate anomalies such as output growth that conflicts with fiber use, export shipments or reported mill utilization. When a material discrepancy, definition change or operating event affects an input, analysts would revisit relevant respondents and compare the evidence again against source definitions, units, year alignment, double counting and segment totals. The model would be refreshed annually, updated between cycles for material events such as major energy or trade-policy changes, and checked again in a fresh pre-delivery review, with anomalies resolved before sign-off.
Mordor Intelligence's Bangladesh Textile Manufacturing Industry Study Market Estimate Compared With Other Published Estimates
Published Bangladesh textile figures can diverge because some count textile materials at the factory gate while others include finished apparel, and because their measurement years and valuation pools differ. Mordor Intelligence's estimate follows a textile-material boundary, whereas Commercial Research Publisher A explicitly includes garment assembly and finished garments, which extends its measured value into downstream apparel sales.
Key Gap Drivers are the product boundary, transaction stage and measurement period. Counting finished garments alongside textile materials can add downstream conversion value to a broad industry total, while the report's definition counts the textile manufacturer's ex-factory sale and excludes the later garment sale. Commercial Research Publisher B reports an earlier base year in a rising series, which contributes to a lower figure against the report's later comparison year, while its broader inclusion of garments would push in the opposite direction.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 44.19 B (2027) | |
| Commercial Research Publisher A | USD 52.8 B (2026) | At its 2026 base, this estimate is 19.5% above this report's 2027 value of USD 44.19 B, 1 year later. Its published boundary includes garment assembly and finished garments, adding downstream apparel sales beyond textile materials sold at the factory gate. |
| Commercial Research Publisher B | USD 39.63 B (2025) | At its 2025 base, this estimate is 10.3% below this report's 2027 value of USD 44.19 B, 2 years later. Its published base year is earlier than the comparison year in a rising value series, which contributes to a lower figure. |
The broader industry figure adds finished apparel conversion to textile-material sales, while the earlier estimate is tied to an older base year and also includes finished garments. The comparison therefore reflects distinct product boundaries and market years, with the year gap and broader inclusion affecting the two external figures in different directions.
Key Questions Answered in the Report
What is the Bangladesh textile manufacturing market size and growth outlook?
It is expected to reach USD 44.19 billion in 2027 and USD 57.26 billion by 2032, with a 5.32% CAGR over 2027-2032.
What supports demand for Bangladeshi textile production?
UK Developing Countries Trading Scheme rules effective January 1, 2026, let eligible Asian regional inputs count as Bangladeshi origin after final processing in Bangladesh for UK export. DBL Group's managing director reported buyer pressure to cut emissions in March 2026.
Which application leads the Bangladeshi textile manufacturing industry?
Fashion and apparel held the largest share at 66.96% in 2026.
Which companies compete in Bangladesh's textile sector?
Ha-meem Group, Noman Group, Square Textiles PLC and DBL Group are established competitors. Beximco factories were slated for leasing through open tender, as announced in December 2025.
What is the main operating challenge for Bangladeshi textile mills?
Gas availability is a major constraint. In August 2026, the Bangladesh Textile Mills Association president reported more than 900 of its over 1,800 member mills completely shut because of gas disruptions.
Which Bangladeshi textile manufacturing locations lead and grow fastest?
Dhaka held the largest share at 52.33% in 2026, while Chittagong is forecast to grow fastest at 5.45% CAGR over 2027-2032.