
Sauces, Condiments, And Dressings Market Size and Share
Sauces, Condiments, And Dressings Market Analysis by Mordor Intelligence
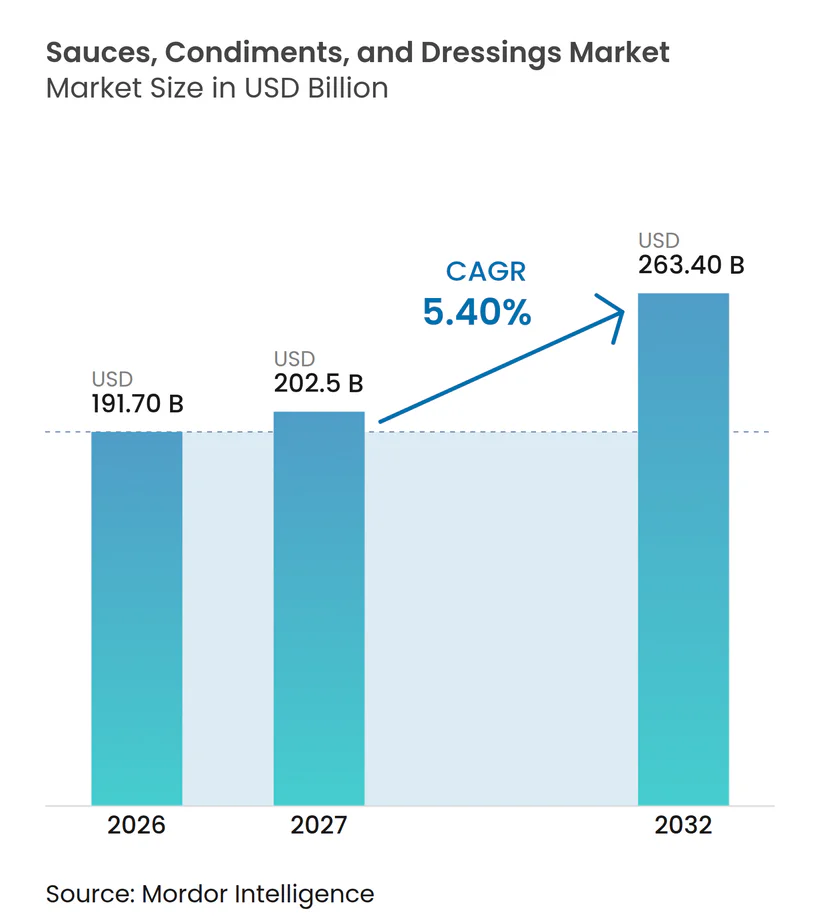
The sauces, condiments, and dressings market size was valued at USD 191.7 billion in 2026 and estimated to grow from USD 202.5 billion in 2027 to reach USD 263.4 billion by 2032, at a CAGR of 5.4% during the forecast period (2027-2032).
Growth depends on translating flavor experimentation into ready-to-use sauces for everyday meals, with natural formulations providing another point of differentiation. In the United Kingdom, flavor discovery and natural-ingredient condiments create complementary routes to shoppers. Ingredient-price swings and nutrient-based labeling plans in Singapore raise formulation and pricing risks for affected retail sauce producers. Competition consequently favors suppliers that connect clear meal uses with reproducible formulations, turning broader flavor choice into products suited to recurring household or foodservice occasions.
Key Report Takeaways
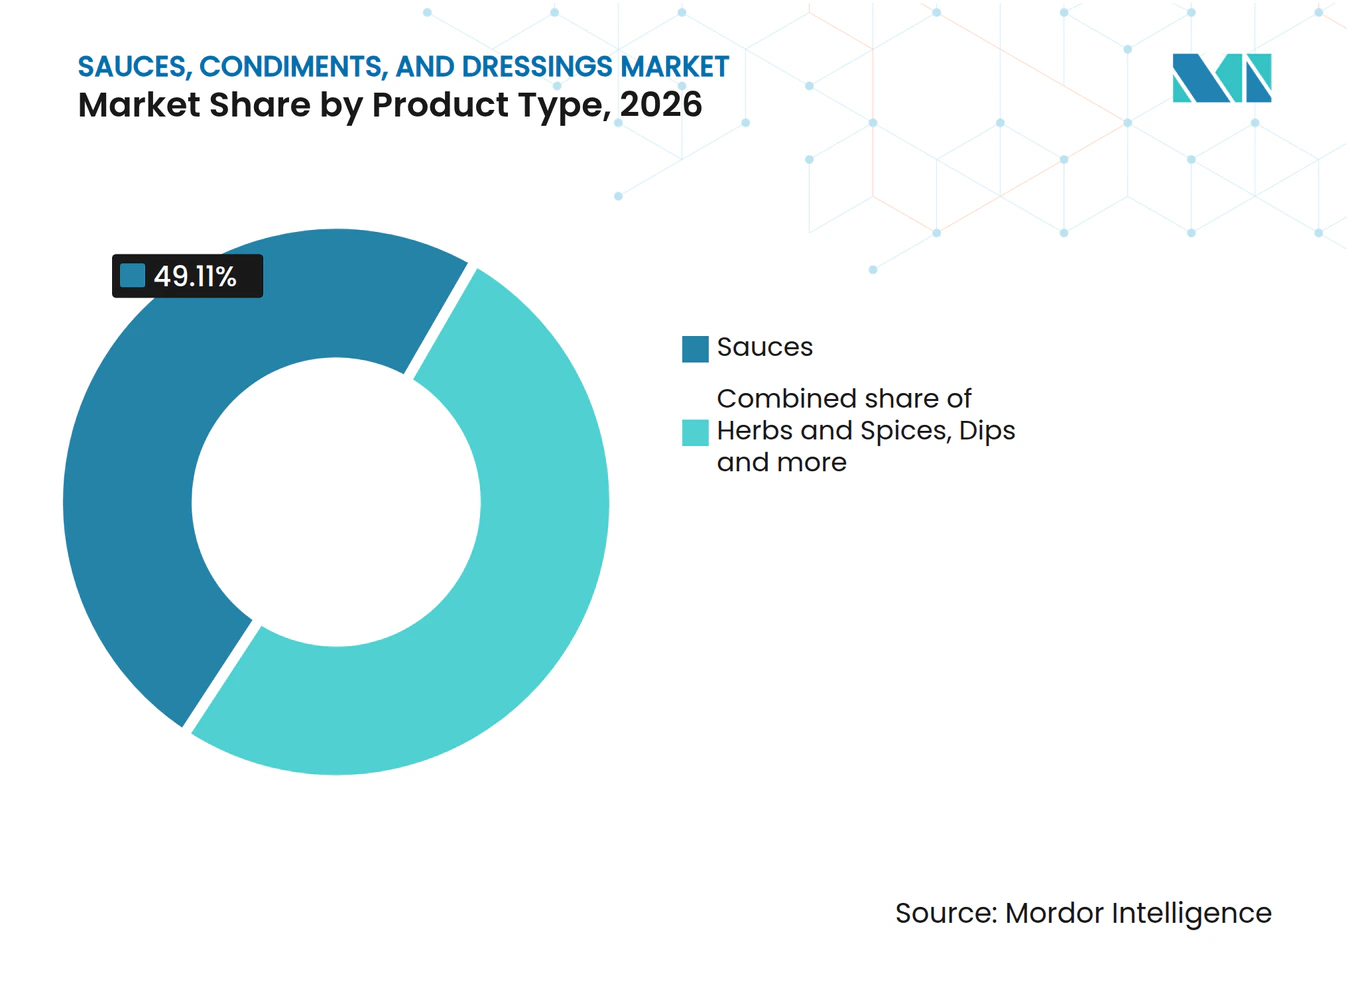
- By product type, sauces held a 49.11% sauces, condiments, and dressings market share in 2026, while dressings are forecast to grow at a CAGR of 6.4% during 2027-2032.
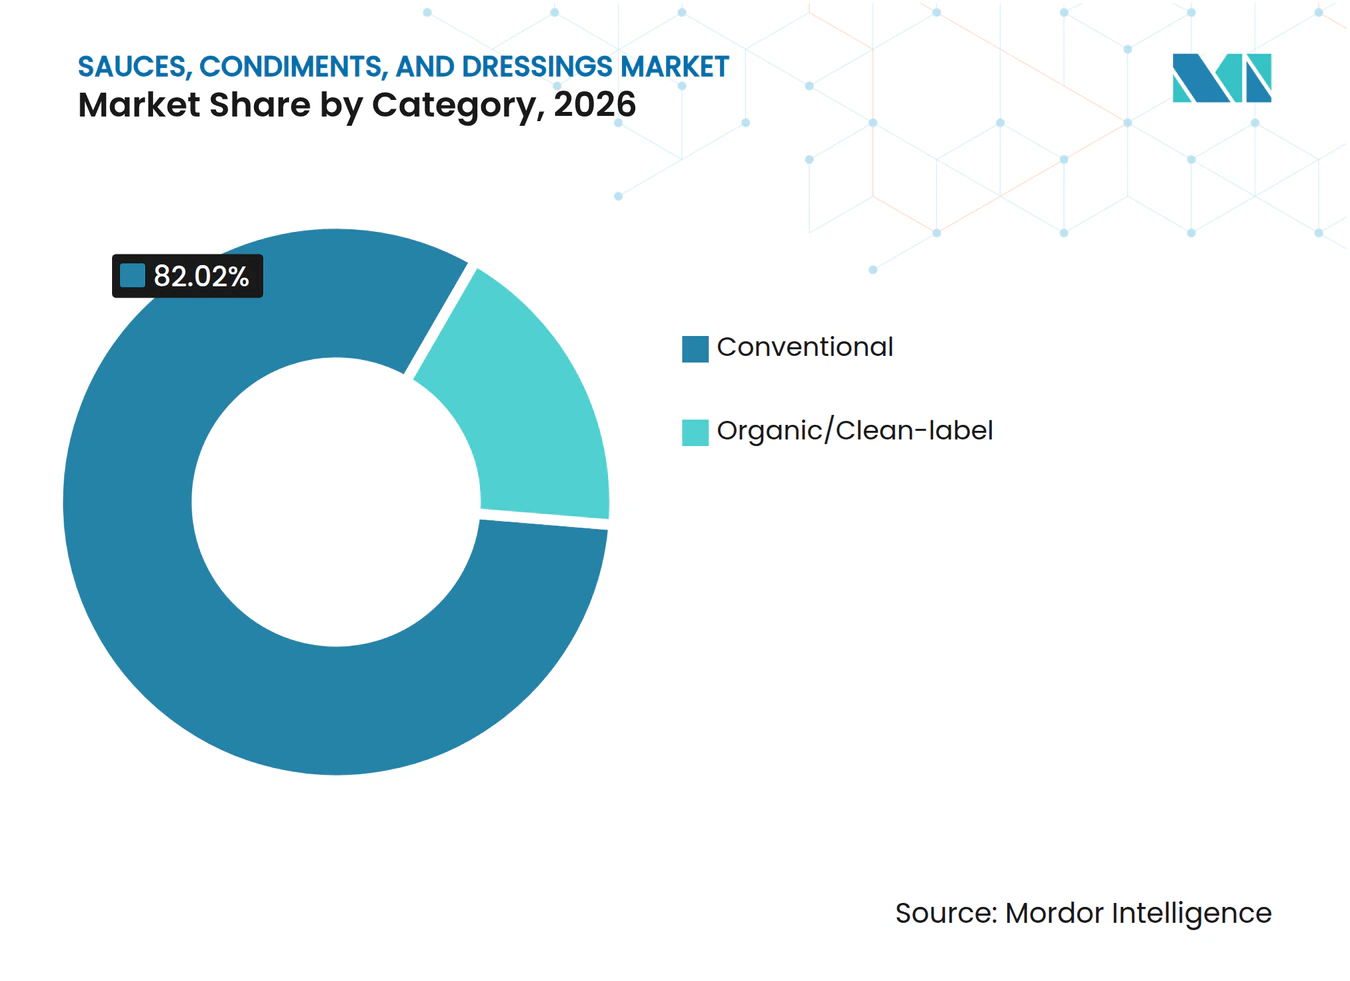
- The category mix was led by conventional products with an 82.02% share of the sauces, condiments, and dressings market size in 2026, and organic/clean-label products are projected to record a 5.85% CAGR during 2027-2032.
- Packaging demand was led by PET/glass bottles at 43.27% of the market in 2026, with sachets/pouches expected to grow at a CAGR of 5.65% during 2027-2032.
- Across distribution channels, supermarkets/hypermarkets accounted for 58.63% of the market in 2026, while online retail stores are forecast to record a 6.45% CAGR during 2027-2032.
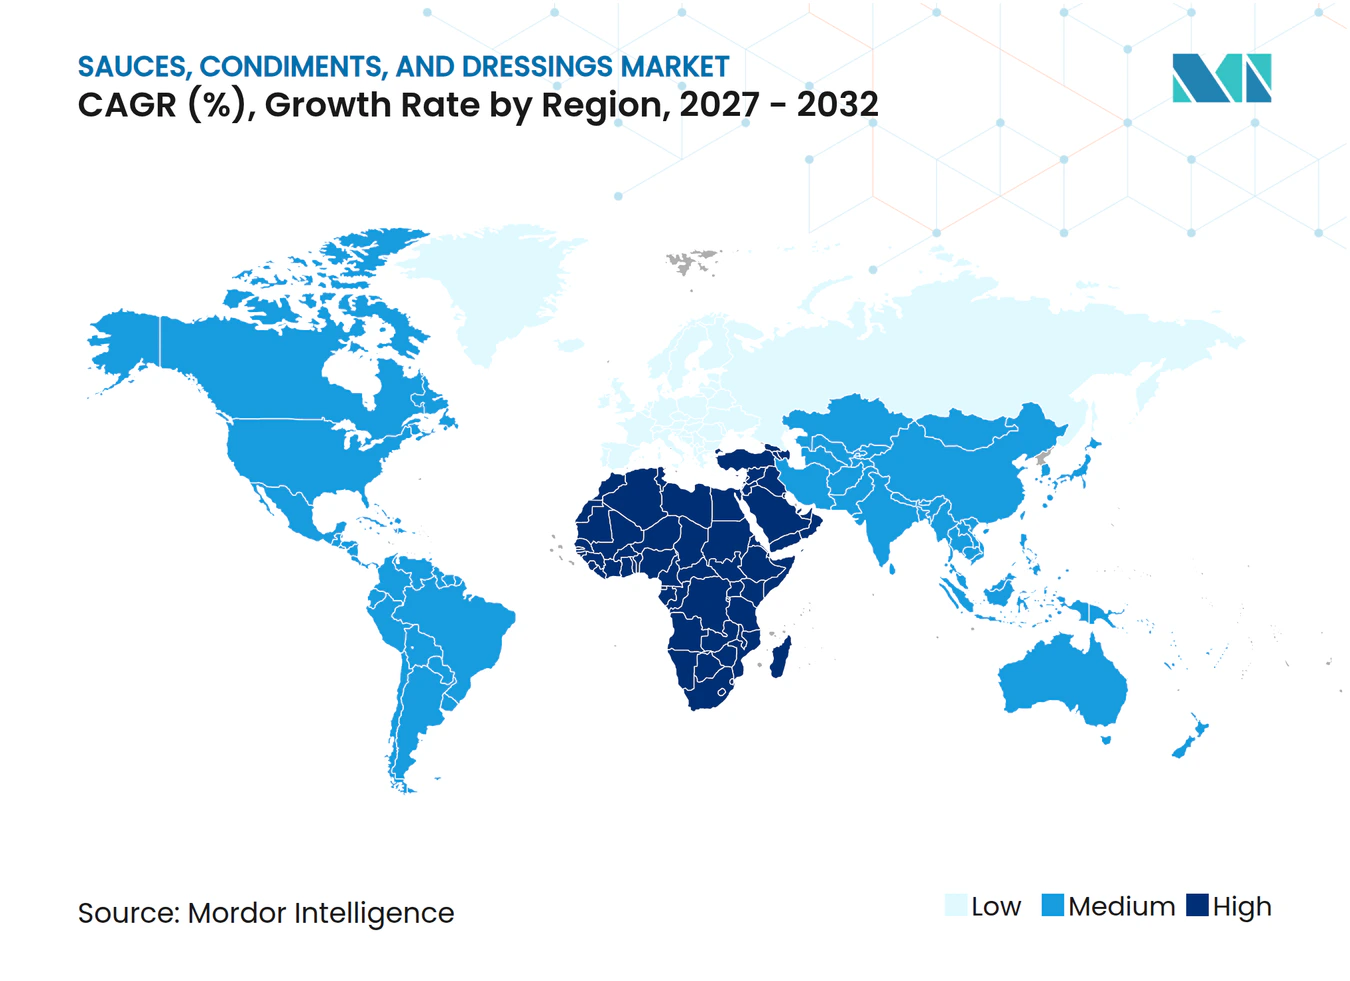
- Geographically, Asia-Pacific represented 41.57% of the market in 2026, and the Middle East and Africa is projected to grow fastest at a 7% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Sauces, Condiments, And Dressings Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Product innovation and flavor diversification | +2% | United States, North America | Medium term (2-4 years) |
| Rising popularity of ethnic and regional cuisines | +1.8% | South Korea, United States and Europe | Medium term (2-4 years) |
| Premium-priced clean-label formulations | +1.5% | United Kingdom, Europe | Medium term (2-4 years) |
| Influence of Food Culture and Social Media | +1.3% | United Kingdom, Europe | Short term (≤ 2 years) |
| Rising Home Cooking and Hybrid Meal Occasions | +0.9% | United States, North America | Short term (≤ 2 years) |
| Fortification of condiments with functional ingredients | +0.4% | Japan, Asia-Pacific region | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Product innovation and flavor diversification
Product innovation can expand sauce demand by making a complex flavor combination usable through a single ready-to-use formulation. In April 2026, Nestlé USA launched Minor’s Kitchen nationwide in the United States exclusively on Amazon, with 4 varieties encompassing lemon garlic aioli, Korean BBQ, chili truffle and American smokehouse flavors. Hormel Foods’ LA VICTORIA brand introduced Chipotle, Fiery Jalapeño and Sweet & Spicy topping sauces and Verde Habanero Salsa for US grocery retailers in August 2025. Amazon exclusivity and grocery availability create different paths for bringing those new flavors into home meals. These launches can add preparation occasions for packaged sauce beyond switching flavors within an existing meal.
Rising popularity of ethnic and regional cuisines
Demand for recognizable regional flavors gives sauce exporters an opening beyond supplying familiar domestic recipes. South Korea’s sauce exports to the United States reached USD 92.2 million in 2025, up 5% year over year.[1] The country’s agriculture ministry linked US consumption of gochujang and other sauces to growing demand for spicy-sweet flavors. South Korean sauce exports to Europe reached USD 17.5 million in the first half of 2026, up 17.2% year over year. For exporters, these distinct destination markets support developing flavor-led assortments with uses that consumers can recognize across meal occasions.
Premium-priced clean-label formulations
A premium formulation needs an ingredient promise that gives the buyer a specific reason to choose that condiment. Ocado Retail reported in June 2025 that sales of Hunter & Gather’s unsweetened, natural condiments on Ocado.com rose 90% year over year. This provides a concrete demand signal for a defined formulation approach within UK online grocery. For a brand seeking premium positioning, an unsweetened recipe can make the product’s ingredient choice central to its proposition. Product development then has to deliver the intended flavor without making sweetness the basis of the experience. The reported rise gives UK online grocers a sales-based reason to keep these unsweetened natural lines listed.
Influence of Food Culture and Social Media
Online food discovery can increase condiment demand by giving familiar meals additional flavor options. Savanta surveyed 2,126 UK adults for Ocado Retail in May 2025, with the retailer linking younger consumers’ condiment experimentation to social media and online food content. Among respondents aged 25 to 34, 66% reported having significantly more condiments than 5 years earlier.[2] In that same age group, 75% reported using some kind of sauce with most meals. These findings make demonstrations of repeatable meal uses a commercially relevant connection between online discovery and the dinner table. A flavor discovered online needs uses beyond its first trial, so everyday meal demonstrations can give brands a path from experimentation to repeated use.
Restraints Impact Analysis of Sauces, Condiments, And Dressings Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High sugar/salt and preservative concerns | -1% | Singapore, Asia-Pacific region | Medium term (2-4 years) |
| Volatile tomato/chili commodity prices | -0.8% | Metro Manila area | Short term (≤ 2 years) |
| Regional labeling-compliance costs for exporters | -0.4% | United States and Europe | Medium term (2-4 years) |
| Consumer skepticism toward additives and preservatives | -0.3% | Australia, Asia-Pacific region | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High sugar/salt and preservative concerns
Restrictions tied to sodium and saturated fat can constrain a sauce brand’s marketing options and formulation choices. Singapore’s Health Promotion Board plans to extend Nutri-Grade to prepacked retail sauces in 2028, replacing the previously announced mid-2027 timeline.[3] The planned system would require Grade C and D products to display the label on packs and online listings, while Grade A and B labeling would be optional. Advertising promoting Grade D products would be prohibited online and in physical settings. The specifications remain subject to WTO consultations and gazettal. Moving implementation from mid-2027 to 2028 gives brands more time, but affected sauce producers still face reformulation decisions, Grade C or D label redesigns, or Grade D advertising limits.
Volatile tomato/chili commodity prices
Sudden ingredient-price moves can make a fixed sauce recipe harder to supply at a stable selling price. Official Philippine monitoring recorded a 32.09% increase in Metro Manila’s average green-chili retail prices from August 17 to September 9, 2026. That local retail-price proxy illustrates how quickly a named condiment ingredient can become more expensive. Reformulation offers another response, but changing chili content could put the intended heat and flavor profile at risk. If an exposed producer passes a comparable increase through to finished-sauce prices, affordability becomes an additional constraint on demand.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Sauces, Condiments, And Dressings Market Segment Analysis
By Product Type:
Sauce Scale and Wider Dressing ApplicationsSauces accounted for a 49.11% share of the sauces, condiments, and dressings market size in 2026, making them the largest segment. Marzetti reported that Bachan’s, the Japanese barbecue-sauce brand it acquired on May 1, 2026, contributed USD 15.4 million in net sales for the 2 months ended June 30, 2026. The company also reported Circana data showing Bachan’s sales growth of 8.7% and distribution-point growth of more than 16% in the 13 weeks ended June 28, 2026. The acquisition illustrates a route to sauce scale through an identifiable product proposition with both an established net sales base and expanding retail presence.
Dressings are the fastest-growing segment, with a forecast CAGR of 6.4% during 2027-2032. Kewpie broadened its Deep-Roasted Sesame Dressing range with new varieties, reduced-calorie versions and seasonal products, while proposing uses across more dishes in Japan. The company said these initiatives increased sales and revitalized the dressing category in the first half of FY2026, ended May 31, 2026. Linking range development with additional dishes gives the supplier more ways to develop the same product family. A single sesame identity stretched across reduced-calorie and seasonal variants lets a supplier add occasions without building a new brand for each.



By Category:
Conventional Scale and Organic DevelopmentConventional products represented an 82.02% sauces, condiments, and dressings market share in 2026, making them the largest segment. In February 2025, Heinz Qingdao, a Kraft Heinz production subsidiary in China, had its fifth ketchup line in final commissioning with annual capacity of 20,000 metric tons. A line of that capacity depends on steady ketchup volume to justify itself, which ties mainstream formulations to manufacturing throughput.
Organic/clean-label products are the fastest-growing segment, with a projected CAGR of 5.85% during 2027-2032. US consumer sales of organic condiments reached USD 618 million in 2025, up 2.1% from 2024. Retail distribution offers a route to expansion by making an organic formulation available in more everyday shopping locations. Ketchup Please’s organic ketchup expanded from 7 Wisconsin Meijer stores in May 2024 to 67 locations across the state by April 2025. Widening an existing retail relationship offers an organic ketchup brand a way to expand availability without depending on a new product launch.

By Packaging:
Bottle Materials and Pouch Value PropositionsPET/glass bottles held 43.27% of the market in 2026, making them the largest segment. Kewpie uses bottles made from 100% recycled PET for all 10 Japan-made 380-milliliter retail dressing and dressing-type condiment items. Its 2025 plan focused on the 380-milliliter size, which had higher sales volume than its 180-milliliter range. Because the 380-milliliter size uses more plastic per bottle, converting it gives Kewpie’s largest estimated annual cut in new plastic among its recycled PET initiatives for dressings.
Sachets/pouches are the fastest-growing segment, with a projected CAGR of 5.65% during 2027-2032. National Foods reported ketchup growth in Pakistan from July to December 2025, supported by nationwide pouch price-offs and Ketchup Champs expansion to schools. A price-off can make the pouch proposition easier to try, while the school program provides a separate route to brand engagement.
By Distribution Channel:
Supermarket Reach and Online Product MomentumSupermarkets/hypermarkets accounted for 58.63% of the market in 2026, making them the largest segment. Total US supermarket sales reached USD 1 trillion in 2025. Separately, Tesco customers in the United Kingdom bought an additional 2.5 million bottles of hot sauce in the 12 months before its mid-2025 disclosure. Tesco’s additional hot-sauce bottles show a specialized condiment adding volume on ordinary supermarket shelves.
Online retail stores are the fastest-growing segment, with a forecast CAGR of 6.45% during 2027-2032. Ocado.com’s average active customer base, excluding Zoom by Ocado, rose 10.6% year over year to 1.28 million in the 26 weeks ended May 31, 2026. Customers count as active if they shopped on Ocado.com within the previous 12 weeks, and the reported figure is the average number of active customers over the 26 weeks. Ocado Retail also reported 96% year-over-year sales growth for M&S Oyster Sauce during July 28, 2025, through July 26, 2026. This creates an opportunity to develop a focused oyster-sauce offer within a growing grocery service.
Geography Analysis
Asia-Pacific Sauces, Condiments, And Dressings Market
Asia-Pacific accounted for a 41.57% share of the sauces, condiments, and dressings market size in 2026. Within its overseas business, Kewpie reported 11% sales growth in Asia-Pacific in FY2025 on a local-currency basis, illustrating a producer’s regional commercial activity. Expanded factories in Thailand and Indonesia operate at full scale alongside production bases in Malaysia and Vietnam, forming a 4-country network that Kewpie links to rapidly increasing regional demand.
Middle East and Africa Sauces, Condiments, And Dressings Market
The Middle East and Africa is the fastest-growing region, with a forecast CAGR of 7% during 2027-2032. In March 2026, Rawa announced a hot-sauce production line in Qatar, offering 473-milliliter and 3-kilogram sizes in response to growing restaurant and foodservice demand. The 473-milliliter and 3-kilogram sizes give the announced range 2 order sizes within the foodservice channel. Separately, Libstar completed its South African integration of Dickon Hall Foods into Montagu Foods by August 2026, with expected improvements in labor productivity, occupancy costs, manufacturing efficiency and service capability. Restaurant demand in Qatar provides a commercial rationale for adding dedicated hot-sauce capacity, as Rawa’s announced line illustrates.
North America’s supply base includes California, where USDA’s August 2026 forecast put contracted processing-tomato production at 10 million short tons for 2026, 10% below 2025. Europe’s EU27 extra-EU condiment and seasoning export value, excluding the United Kingdom, fell 4% during April 2025 through March 2026 versus the preceding 12 months. In South America, Kikkoman do Brasil exported 5 products to Peru in June 2025, comprising 2 soy sauce sizes, tare, oyster and Worcestershire-style sauces, with Peruvian sales starting in September. Jamaica has sauce co-manufacturer GK Manufacturing within GraceKennedy Foods, Portugal has Paladin’s consumer adaptation described by its owner’s CEO in February 2026, and Ecuador has McCormick licensee ALIMEC’s sauce production. Kikkoman do Brasil’s Peru range and Paladin’s Portuguese positioning show suppliers tailoring sauces to individual national markets.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of manufacturers placing packaged condiments on consumer markets. Nutrition information turns recipe composition into a package-design and product-information decision for covered foods. An existing nutrition-labeling duty and a proposed front-of-pack requirement create different commercial planning needs because the latter can add a separate redesign decision. Voluntary front-of-pack guidance gives a manufacturer another presentation option without making that choice compulsory.
Regulatory Table of Sauces, Condiments, And Dressings Market
| Decision factor | United States | Germany | Japan | Brazil |
|---|---|---|---|---|
| Primary authority | FDA | State food-control authorities | Consumer Affairs Agency | ANVISA |
| Key instruments or direction | 21 CFR 101.9; proposed front-of-pack nutrition box | Regulation (EU) No 1169/2011; food-information impact assessment | Food Labeling Standards; voluntary front-of-pack nutrition guideline | RDC 429/2020 and IN 75/2020; proposal to open a review considered in June 2025 |
| Commercial effect | Nutrition information unless exempt; proposed front-label box for most Nutrition Facts-labeled foods | Ingredient, allergen, operator and nutrition information, subject to exceptions | Nutrition information for covered packaged processed foods; voluntary front-of-pack nutrition format | Nutrition-panel rules and front-of-pack labeling provisions |
| Current policy attractiveness | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Hardening | No change | No change | No change |
| Source: Mordor Intelligence | ||||
All 4 jurisdictions receive Medium ratings because established nutrition-labeling duties provide a defined baseline while requiring product-specific label work for covered foods. The US Hardening direction reflects prospective additional package-design work under the proposed nutrition box, with the regulatory agenda projecting a final rule for December 2026. Germany’s and Brazil’s No change judgments reflect continued application of their operative frameworks alongside the European Commission’s assessment of possible revisions and Brazil’s June 2025 consideration of opening a review. Japan’s No change judgment reflects mandatory nutrition declarations paired with voluntary front-of-pack guidance, leaving adoption of the additional format to the manufacturer.
Value Chain Stages
The value chain compares dispensing-component supply, sauce formulation and manufacturing, and foodservice distribution. In August 2025, Marubeni completed a minority investment in Thailand’s Win Chance Foods, a condiment manufacturer serving major packaged-food companies and restaurant chains in Thailand and neighboring countries. Win Chance Foods uses a database of more than 2,000 recipes to develop tailored sauces, and its manufacturing technology supports flexible, stable small-batch production. This links recipe-development capability with commercial production, placing value in the ability to supply a customer-specific sauce consistently rather than in the formulation alone.
Value Chain Analysis Table of Sauces, Condiments, And Dressings Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Dispensing-component supply | Specialty-sauce closure suppliers such as Aptar Closures | Closure sales | Matching dispensing design to the sauce’s flow | Qualify the closure and sauce together before selecting the production format |
| Sauce formulation and manufacturing | Condiment manufacturers such as Win Chance Foods | Sauce sales to packaged-food companies and restaurant chains | Reconciling recipe variety with repeatable production | Validate recipes within controlled batch and quality routines |
| Foodservice distribution | Foodservice distributors such as Sysco | Product resale to foodservice customers | Coordinating sauce availability with operator delivery windows | Plan routine delivery routes and reserve capacity for special orders |
| Source: Mordor Intelligence | ||||
Tailored sauce development concentrates value in the handoff from a recipe to repeatable production. Aptar Closures introduced 4 specialty-sauce closure types in December 2025, offering dispensing options that a producer can qualify against each sauce’s flow. In fiscal 2026, Sysco’s operating sites offered daily delivery to certain customer locations and short-notice special-order capability, providing distribution options relevant to supplying customer-specific sauces to foodservice operators.
Competitive Landscape
Market Concentration
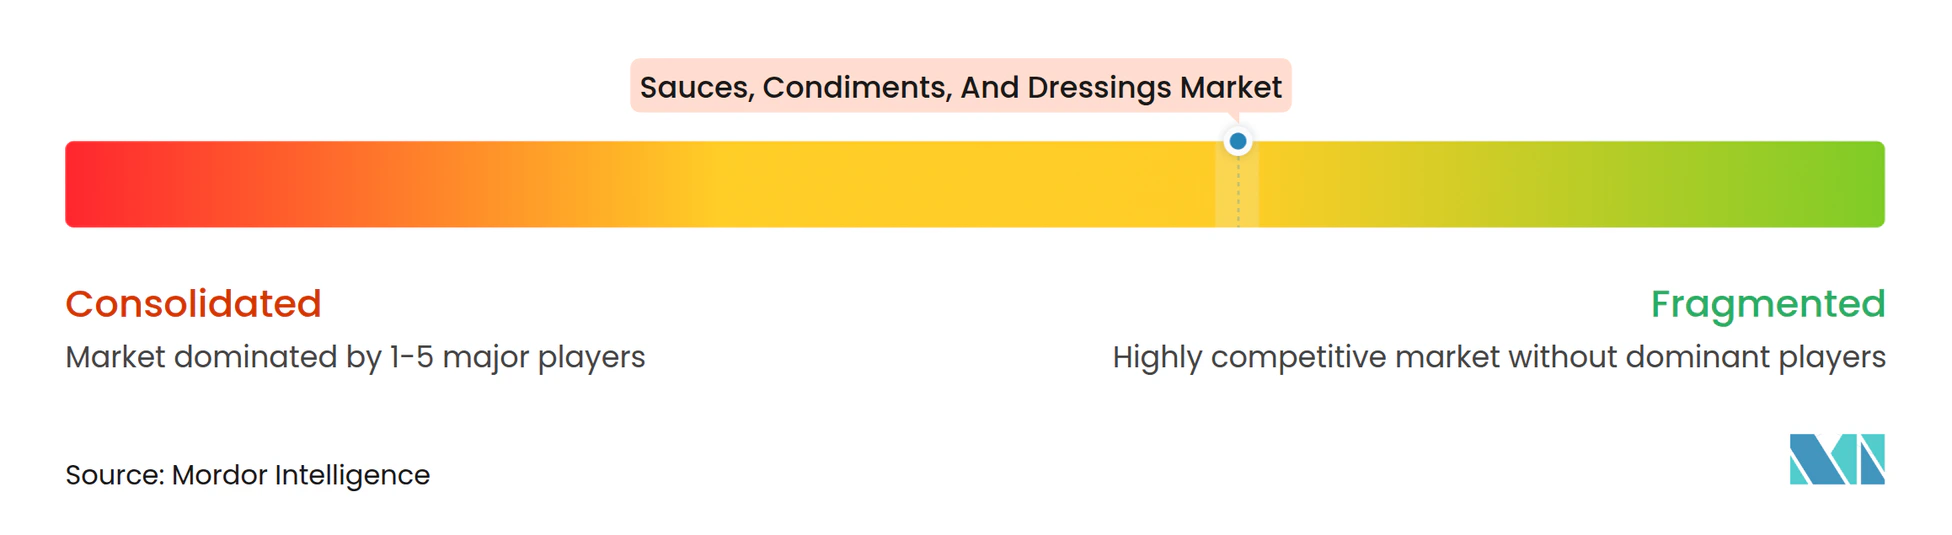
Competition combines a broad supplier base with established international brand owners serving different flavor and customer requirements. McCormick & Co Inc serves retailers through Consumer and business customers through Flavor Solutions, selling condiments and other flavor products, with global Consumer sales up 2.6% in 2025 versus 2024. Other major players include The Kraft Heinz Company and Unilever Plc, whose Foods business spans condiments and sauces. Soy-sauce manufacturer Kikkoman Corporation reported 5.2% consolidated revenue growth in fiscal 2026, while Mizkan Holdings Co. Ltd.’s North American pasta-sauce business includes RAGÚ and Bertolli. These businesses compete across different product and customer scopes, making a retail brand portfolio and supply to food manufacturers distinct dimensions of competition.
On January 2, 2026, McCormick completed its acquisition of an additional 25% interest in McCormick de Mexico from Grupo Herdez, raising its ownership to a controlling 75%. The Mexican portfolio includes mayonnaise, mustard and hot sauce among other foods, giving McCormick control over an established range of condiment lines. Kikkoman Foods, Inc., Kikkoman Corporation’s US manufacturing subsidiary, began soy sauce brewing at Jefferson, Wisconsin, in May 2026, with its September announcement scheduling shipments for October. Kikkoman linked the plant to growing North American soy sauce demand and steadily increasing shipments from its Walworth plant. The added US brewing base offers buyers a route to locally produced supply tailored to demand, with commercial shipments dependent on the announced timetable.
On March 31, 2026, McCormick and Unilever agreed to combine McCormick with Unilever Foods, excluding India and other specified businesses. The proposed combination would bring together portfolios spanning herbs, spices, seasonings, cooking aids, condiments and sauces. Completion was subject to regulatory approvals and other closing conditions, making the agreement a conditional route to portfolio integration. The geographic exclusions would also limit the reach of a single integrated commercial offer across countries. The announcement put the businesses’ combined fiscal 2025 revenue at approximately USD 20 billion, and completion would place portfolios from 2 of the 5 major players within one company.
Sauces, Condiments, And Dressings Industry Leaders
-
McCormick & Co Inc
-
The Kraft Heinz Company
-
Unilever Plc
-
Kikkoman Corporation
-
Mizkan Holdings Co. Ltd.
- *Disclaimer: Major Players sorted in no particular order
Sauces, Condiments, And Dressings Market Companies Covered in this Report
- Kikkoman Corporation
- The Kraft Heinz Company
- McCormick & Co Inc
- Unilever Plc
- Conagra Brands Inc.
- Lee Kum Kee Company Ltd.
- Nestle SA
- Foshan Haitian Flavouring & Food Ltd
- PepsiCo Inc
- Vilore Foods Company
- Kewpie Corp
- The Clorox Company
- Barilla Holding SpA
- The Campbell's Company
- Ajinomoto Co Inc
- Strauss Group Ltd
- Mizkan Holdings Co. Ltd.
- S Narendrakumar & Co
- S&B Foods Inc
- Ken's Foods Inc
Key Opportunities for Market Participants
These opportunities compare buyer openings created by one French school-catering tender. Separately, England’s voluntary guidance covers commercial baby foods for children up to 36 months, including stir-in pasta sauces, with nutrition, labeling and marketing implementation expected by the end of February 2027. On October 9, 2026, Lycée polyvalent international Robert Badinter in Blois published a grocery tender including sauces, condiments and seasonings for January 1, 2027, through December 31, 2029. Blois bids are due November 10, 2026, at 17:00 Paris time, with award weights of 50% for quality, 45% for price and 5% for environment.
Market Opportunities Table of Sauces, Condiments, And Dressings Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Sauce assortments for institutional meals | Quality leads the tender’s award weighting | French school catering | Match a focused sauce range to clearly described meal uses | Demonstrating product quality within a competitive quotation | Qualified sauce producers and catering distributors |
| Cost-controlled seasoning supply | Price has substantial weight alongside quality | Institutional herbs and spices buyers | Quote seasoning formats with transparent comparable costs | Preserving flavor suitability while controlling the delivered price | Seasoning suppliers serving institutional kitchens |
| Condiment supply with efficient deliveries | Environmental performance forms part of the award criteria | Institutional condiment buyers | Combine an appropriate condiment range with a substantiated delivery proposal | Showing environmental value without weakening price competitiveness | Condiment suppliers with consolidated distribution |
| Source: Mordor Intelligence | |||||
England’s guidance creates a sauce-development opening extending beyond a single catering award. Businesses responding to the guidelines requested more implementation time for recipe testing, shelf-life analysis and packaging changes. A baby-food pasta sauce whose recipe and pack are revised together can address the guidance’s nutrition and labeling expectations in one development program before the end of February 2027.
Recent Industry Developments in Sauces, Condiments, And Dressings Market
- Oct 2026: Singapore’s Health Promotion Board revised the planned Nutri-Grade extension to prepacked retail sauces from mid-2027 to 2028, with specifications subject to WTO consultations and gazettal.
- May 2026: Kikkoman Foods, Inc., Kikkoman Corporation’s US manufacturing subsidiary, began soy sauce brewing at its Jefferson, Wisconsin, plant.
- May 2026: The Marzetti Company completed its acquisition of Bachan’s, Inc., bringing the Japanese barbecue-sauce brand into its US food business.
Sauces, Condiments, And Dressings Market Report Scope and Research Methodology
Market Definition and Coverage
The sauces, condiments, and dressings market measures annual global spending on distinct food products sold for seasoning or accompanying food through retail and foodservice. Product form, formulation, channel, and region classify those same sales.
Scope exclusions: Fresh, unbranded homemade preparations, in-store prepared foods not sold as distinct sauce, condiment, or dressing products, finished meals and restaurant dishes containing counted products, and fresh tomatoes and chili peppers sold as agricultural commodities are excluded.
Segments Covered in This Report
- By Product Type
- Sauces
- Condiment Sauces
- Cooking Sauces
- Herbs and Spices
- Dips
- Dressings
- Other Product Types
- Sauces
- By Category
- Conventional
- Organic/Clean-label
- By Packaging
- PET/Glass Bottles
- Sachets/Pouches
- Others (Tetra packs, Jars, Cups, and others)
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Official data sets such as the U.S. Department of Agriculture Economic Research Service Food Expenditure Series track food spending by outlet and purchaser, FAOSTAT food balances describe supply and utilization across countries, United Nations Statistics Division classification detail clarifies the HS 2103 sauce and condiment category, and UNdata trade records provide sauce trade values and quantities.
Company filings and investor materials can cross-check reported product sales, production capacity, geographic exposure, and price or mix changes, while reputable business and trade press can clarify dated launches, acquisitions, and channel developments. These sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews with manufacturers, ingredient and packaging suppliers, retail buyers, and foodservice purchasers across the global market can test how reported product sales, channels, and regions fit the defined transaction boundary. Where secondary sources use broad product or channel categories, analysts can use interviews to check whether the reported sales fit that boundary and clarify gaps in product or channel coverage. When accounts conflict, analysts triangulate them against independent public indicators and company disclosures, then document unresolved gaps and sensitivity checks.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 15% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 20% | Managers: 50% | Americas: 30% |
Market-Sizing & Forecasting
The model estimates annual global value for distinct commercial sauce, condiment, dressing, dip, herb, and spice products sold through retail and foodservice, then allocates the total across the accepted product, formulation, packaging, channel, and regional cuts. A top-down estimate starts with food spending and category demand, adjusted to the market boundary, while selective bottom-up checks use supplier sales roll-ups and sampled average selling price multiplied by product volume. Relevant indicators include food expenditure by outlet, food supply and utilization, trade values and weights for sauce-related customs categories, company-reported sales, and product price and mix. Each helps test market direction or a particular channel and region. Scenario analysis projects value by considering how population and income, retail and foodservice activity, trade, and product price or mix may change, with segment shares built from evidence on product sales, channel exposure, formulation, and packaging and reconciled to the total. Primary experts can review the variable-level assumptions and forecast direction, and gaps in a selective bottom-up check can be bridged with comparable public data and company disclosures, with any remaining difference retained for analyst review.
Data Validation & Update Cycle
Analysts triangulate the estimate against independent spending, trade, supply, and company signals, then check trends, segment totals, and year-over-year movements for anomalies or unexplained variance. A second review verifies source periods, market-boundary treatment, calculations, and segment reconciliation, and analysts resolve anomalies before sign-off by checking the underlying source or seeking clarification from relevant respondents when a material assumption conflicts with new evidence. The model is refreshed annually, updated between cycles when material market or regulatory events affect the inputs, and reviewed again against the latest available evidence before delivery.
Mordor Intelligence's Sauces Condiments and Dressing Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The sauces, condiments, and dressings market measures annual global spending on distinct food products sold for seasoning or accompanying food through retail and foodservice.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Relevant indicators include food expenditure by outlet, food supply and utilization, trade values and weights for sauce-related customs categories, company-reported sales, and product price and mix.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 202.5 B (2027) | |
| Global Consultancy A | USD 178.6 B (2026) | At its 2026 base, this estimate is 11.8% below this report's 2027 value of USD 202.5 B, 1 year later. Its page forecasts continued growth beyond the 2026 estimate. |
| Global Consultancy B | USD 189.2 B (2026) | At its 2026 base, this estimate is 6.6% below this report's 2027 value of USD 202.5 B, 1 year later. Its page forecasts continued growth beyond the 2026 estimate. |
Mordor Intelligence's analysts triangulate the estimate against independent spending, trade, supply, and company signals, then check trends, segment totals, and year-over-year movements for anomalies or unexplained variance.
Key Questions Answered in the Report
How large is the sauces, condiments, and dressings market size?
The market is estimated at USD 202.5 billion in 2027 and projected to reach USD 263.4 billion by 2032, at a CAGR of 5.4% during 2027-2032.
Which forces drive demand for packaged condiments?
Regional flavors, natural formulations and online food discovery support demand. South Korean sauce export value to the United States rose 5% in 2025.
Which product type has the largest share?
Sauces held 49.11% of the market in 2026, making them the largest product-type segment.
Which companies are major suppliers of sauces, condiments, and dressings?
Major players include McCormick & Co Inc, The Kraft Heinz Company, Unilever Plc, Kikkoman Corporation and Mizkan Holdings Co. Ltd.
Which challenges shape the outlook for packaged condiments?
Ingredient-price volatility and prospective nutrient-related marketing restrictions create commercial risks. Singapore plans a 2028 Nutri-Grade extension for prepacked retail sauces, with specifications subject to WTO consultations and gazettal.
Which region leads the industry, and which is growing fastest?
Asia-Pacific held 41.57% of the market in 2026. The Middle East and Africa is forecast to grow at a CAGR of 7% during 2027-2032.