
Protective DNS Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 0.83 Billion |
| Market Size (2032) | USD 1.86 Billion |
| Growth Rate (2027 - 2032) | 17.47 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Protective DNS Services Market Analysis by Mordor Intelligence
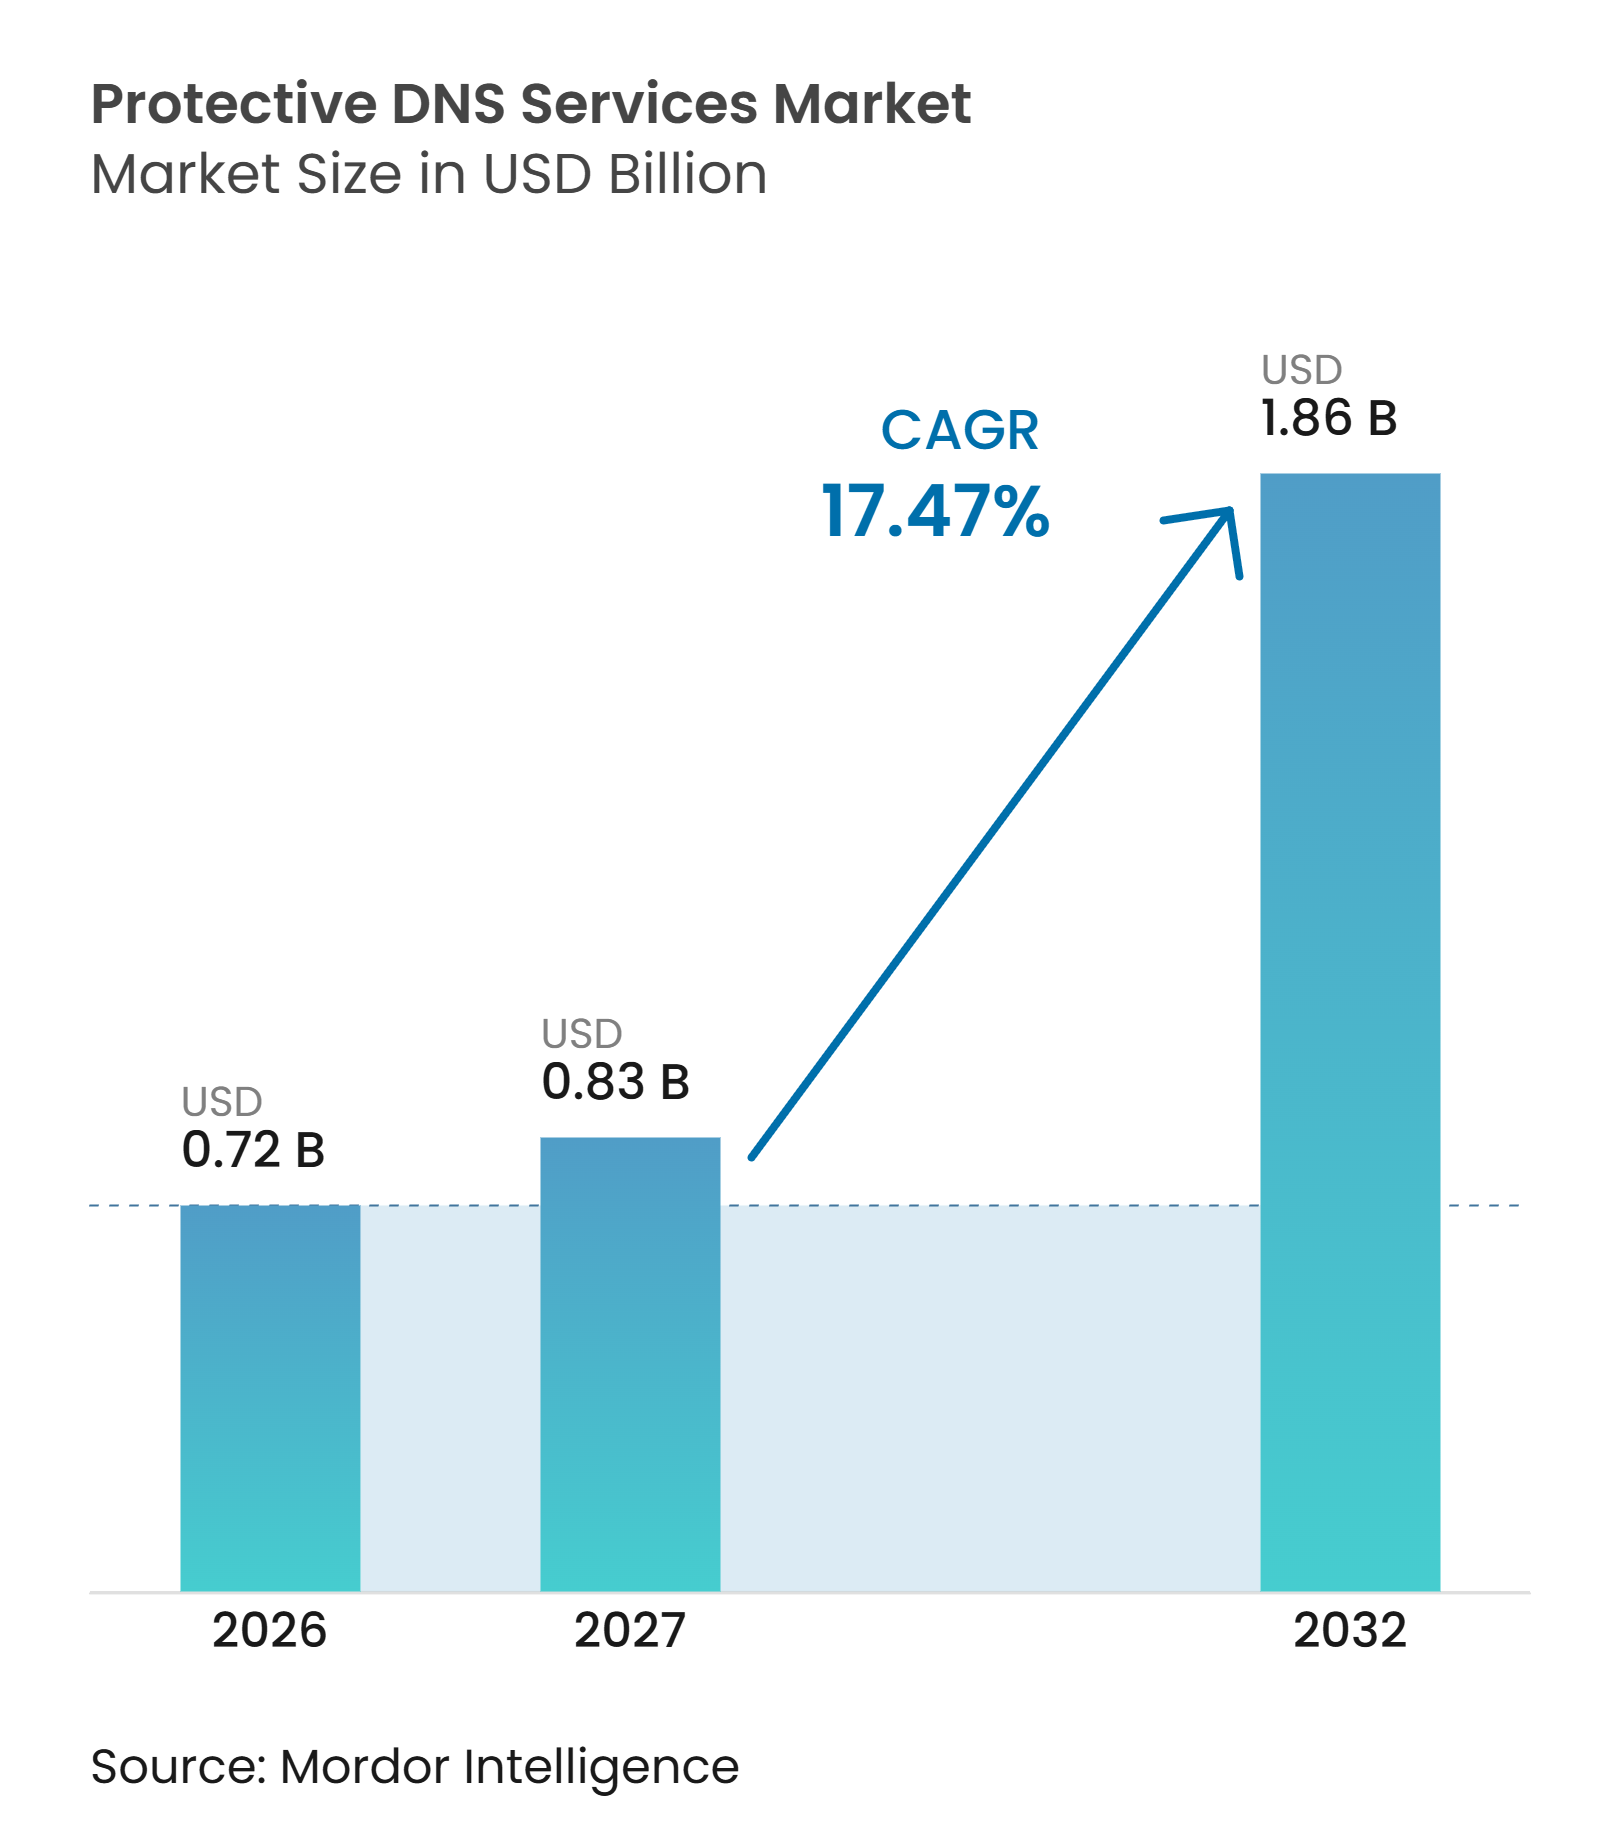
The protective DNS services market size is expected to increase from USD 0.72 billion in 2026 to USD 0.83 billion in 2027 and reach USD 1.86 billion by 2032, growing at a CAGR of 17.47% over 2027-2032. The Protective DNS services market is moving beyond its traditional role in network routing, as organizations now use DNS controls to identify and block malicious connections early. More cloud workloads, remote users, mobile devices, and connected equipment have widened the number of DNS paths that security teams must protect. Government requirements and widely used cybersecurity standards are also making DNS protection a more routine part of security procurement. Vendors are responding by combining DNS intelligence with zero-trust, secure access service edge, and identity systems, which increases the value of integrated platforms. The Protective DNS services market also has room for specialized providers that reach smaller organizations through managed-service providers, internet service providers, and device partnerships.
Key Report Takeaways
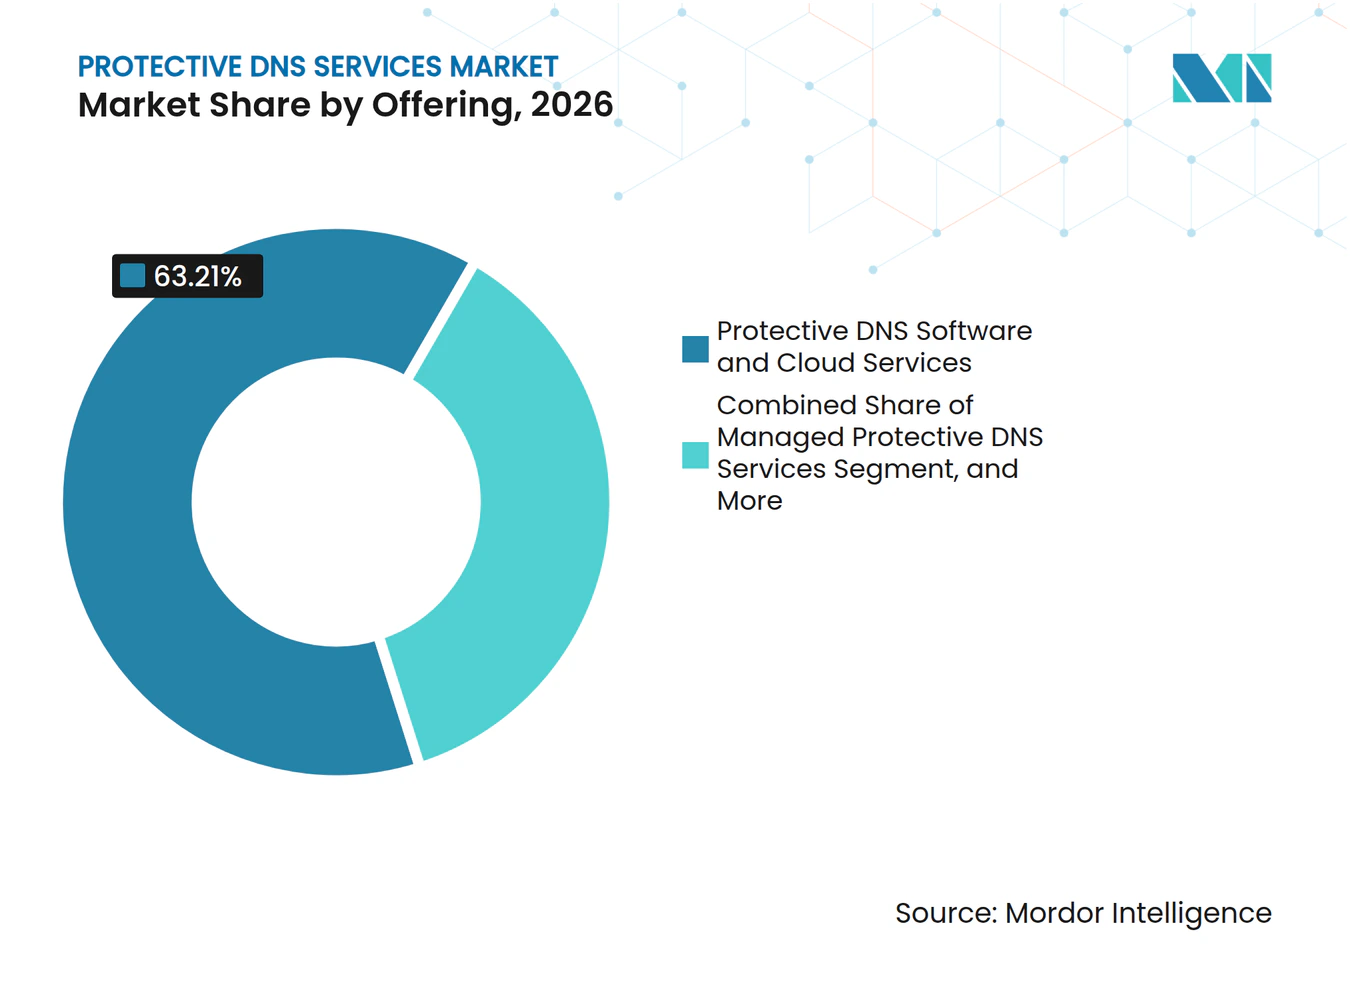
- By offering protective DNS software and cloud services, it held 63.21% of the protective DNS services market share in 2026, while managed protective DNS Services are projected to expand at a 20.84% CAGR through 2032.
- By deployment, cloud-based solutions accounted for 64.89% of the protective DNS services market size in 2026 and are expected to advance at a 22.63% CAGR through 2032.
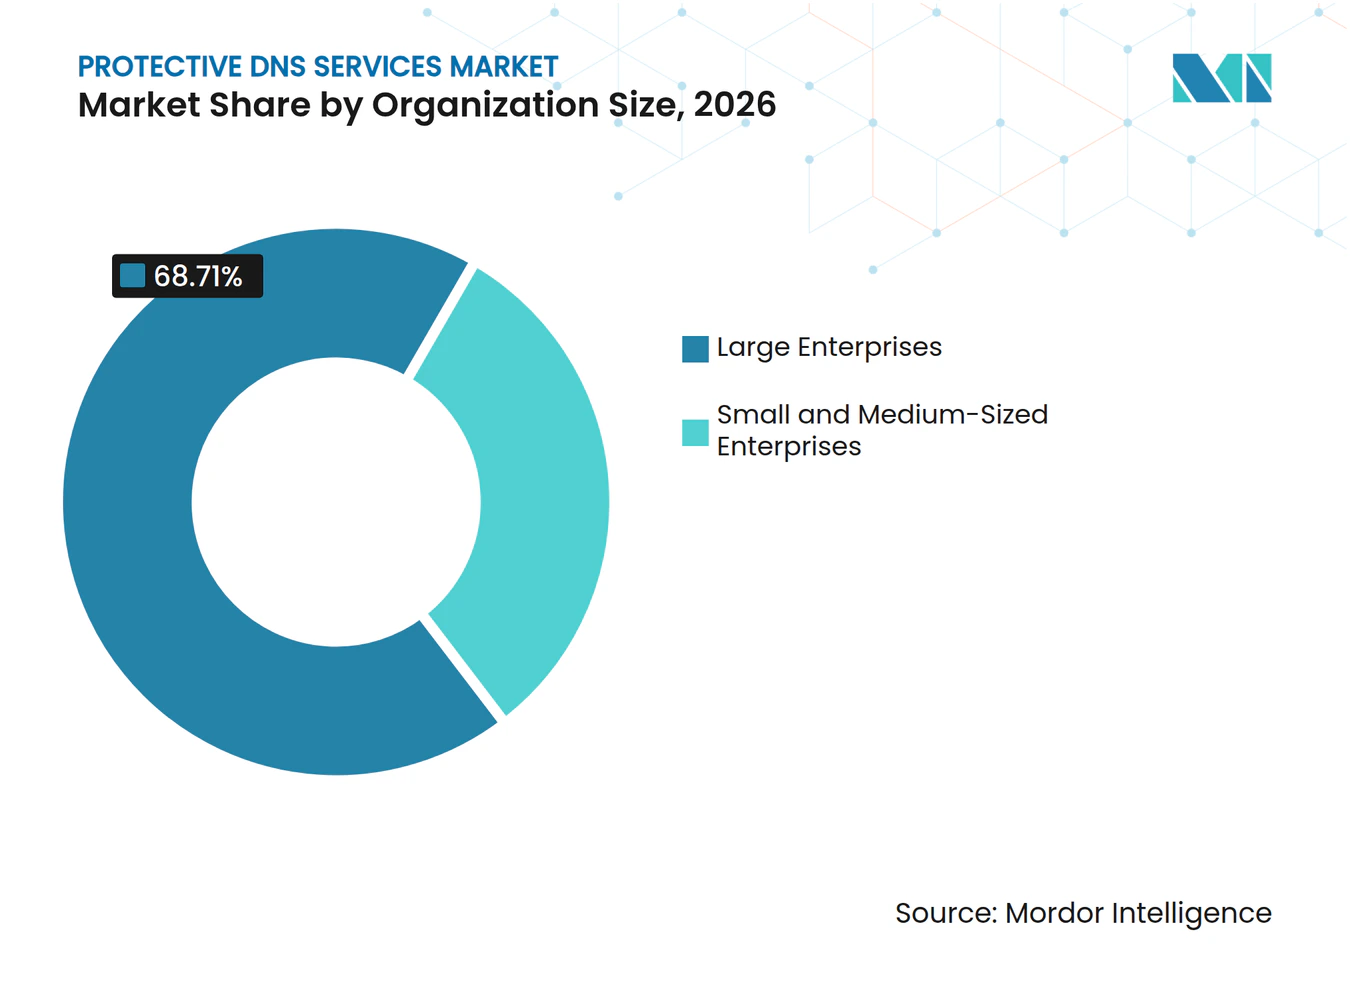
- By organization size, Large Enterprises held 68.71% revenue share in 2026, while Small and Medium-Sized Enterprises are projected to expand at a 21.97% CAGR through 2032.
- By industry vertical, IT and Telecommunications accounted for 38.26% of revenue in 2026, while Healthcare and Life Sciences are forecast to grow at a 23.58% CAGR through 2032.
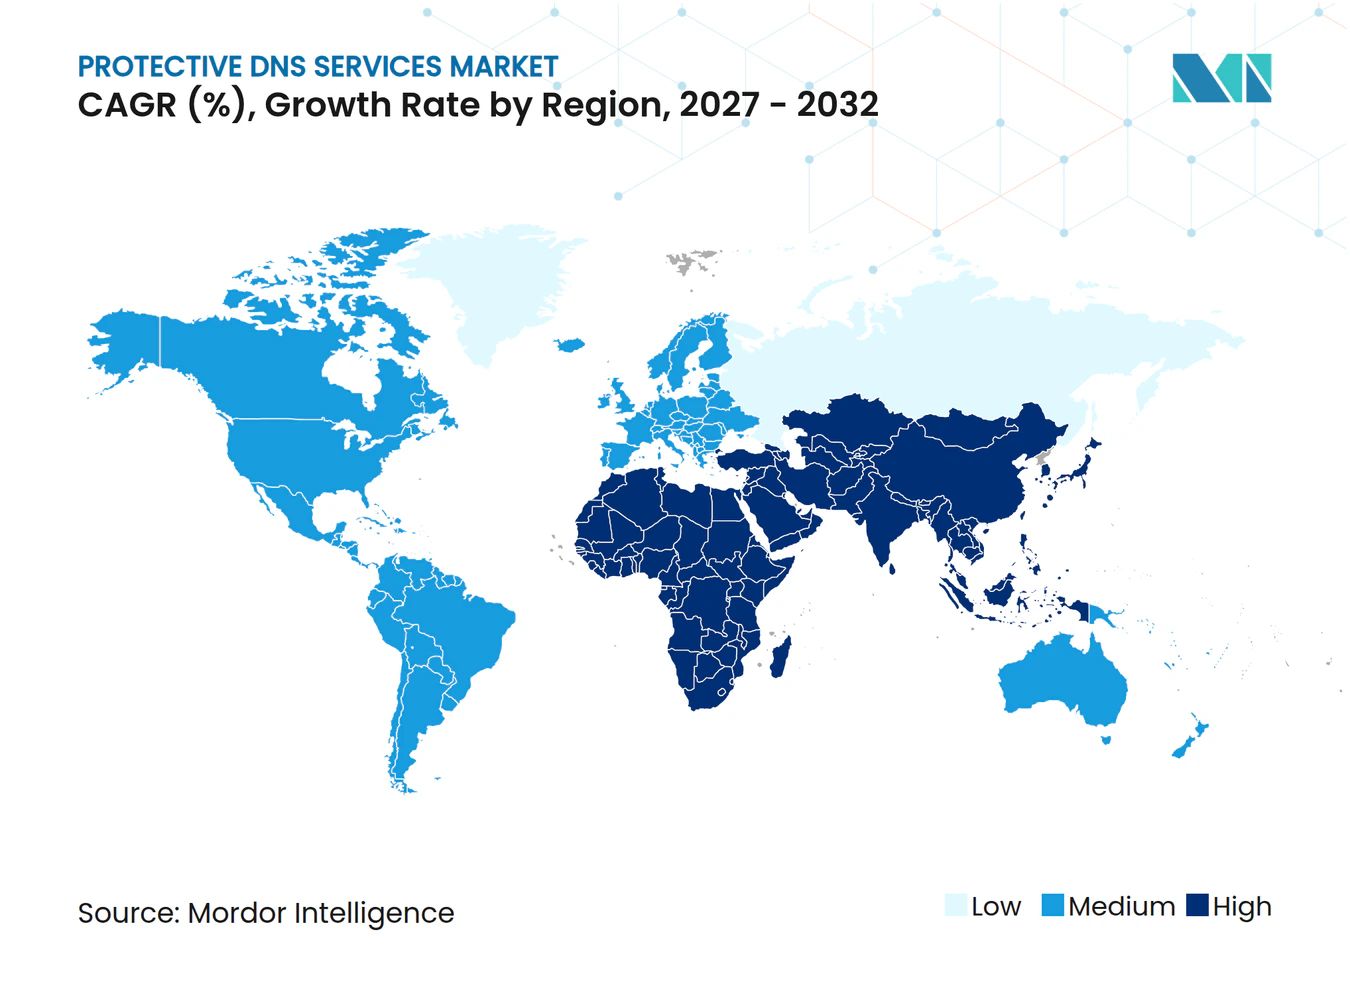
- By geography, North America held a 34.76% revenue share in the protective DNS services market in 2026, while Asia-Pacific is projected to expand at a 22.73% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Global Protective DNS Services Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising DNS-Layer Threat Volume and Evasive Domain Infrastructure | +4.2% | Global | Short term (≤ 2 years) |
| Expansion of Cloud, Mobile, Roaming, and Hybrid-Work Assets | +3.5% | Global, with concentration in North America and Europe | Medium term (2-4 years) |
| Government and Critical-Infrastructure Protective DNS Mandates | +3.0% | North America and EU core, spillover to Asia-Pacific and Middle East | Medium term (2-4 years) |
| Convergence of DNS Threat Intelligence With Zero-Trust Enforcement | +2.5% | North America and Western Europe, expanding to Asia-Pacific | Long term (≥ 4 years) |
| Frontier-AI-Enabled One-Time-Use Domains and Malicious Adtech | +1.8% | Global | Short term (≤ 2 years) |
| Telecom Bundling of Protective DNS Into Consumer and IoT Security | +1.2% | Asia-Pacific and Europe, spillover to Middle East and Africa | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising DNS-Layer Threat Volume and Evasive Domain Infrastructure
The protective DNS services market benefits from DNS serving as a staging layer for attacks that exploit otherwise legitimate network traffic. EfficientIP reported that malware-related DNS hits nearly doubled to 3.84 billion in the first half of 2026, reaching 32.6 million daily hits in April.[1] The same report recorded total threat-signal volume of 13.85 billion hits, up 24% from 11.18 billion in the second half of 2025. Domain Generation Algorithm activity strengthened in February 2026, and newly observed domains increased in March, showing that DNS telemetry can reveal preparation activity before payload delivery. This early signal supports security teams that need time to block suspicious destinations before an attack reaches users or workloads. EfficientIP also found that 95% of surveyed security decision-makers reported a DNS-related incident in the prior year, with reported attack costs ranging from USD 500,000 to USD 5 million.
Expansion of Cloud, Mobile, Roaming, and Hybrid-Work Assets
Cloud applications, remote work, mobile broadband, and hybrid networks create DNS traffic that does not always pass through a corporate network. On-premises DNS controls protect traffic routed through the local network, but a cloud-delivered resolver can apply the same policy to devices that connect to other networks. Cloudflare reported that DNS-based attacks represented 34.3% of network-layer attack activity in the first half of 2026.[2] The company also reported that DNS Flood attacks increased from 25.7% to 40.0% of network-layer attacks quarter over quarter. Medical devices, industrial controllers, and smart-facility equipment often cannot run endpoint agents, so network-level domain blocking can provide practical control for these systems. The protective DNS services market therefore benefits when organizations seek a single policy layer across office, cloud, and roaming environments.
Government and Critical-Infrastructure Protective DNS Mandates
Government policies are moving protective DNS from a discretionary purchase toward a baseline control for covered organizations. CISA states that Federal Civilian Executive Branch agencies must use the protective DNS Resolver service for egress DNS queries under 6 U.S.C. § 663 and OMB M-22-09. The January 2025 executive order on cybersecurity also directed agencies to adopt encrypted DNS measures for federal environments. NIST published SP 800-81r3 in March 2026, its first major update to federal DNS security guidance in 13 years, and described protective DNS as an active control within zero-trust programs. NSA and CISA updated their guidance on selecting a protective DNS service in March 2025, providing federal contractors and critical infrastructure operators with a recognized vendor assessment reference. These requirements can influence procurement beyond government because suppliers and operators often need to demonstrate similar safeguards to meet contract and audit expectations.
Convergence of DNS Threat Intelligence With Zero-Trust Enforcement
Zero-trust programs require organizations to verify access continuously, which gives DNS a larger role in policy enforcement. Microsoft’s Zero Trust DNS feature for Windows 11 Enterprise blocks IP traffic to destinations that were not resolved by a trusted, policy-aware resolver. This approach makes the resolver a point for allowing or denying network destinations rather than a passive directory service. The Cloud Security Alliance has also described DNS as an identity-aware policy decision point that can operate before name resolution. The protective DNS services market is supported when these controls become part of access and identity workflows, since replacing the resolver may then require redesigning connected policies. Vendors that support encrypted protocols, audit logging, and integration with identity platforms can be more relevant to buyers with established zero-trust programs.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Integration Complexity Across Legacy DNS, DoH, DoT, and IPv6 | -1.5% | Global, most acute in South America, Middle East, and Africa | Medium term (2-4 years) |
| Privacy, Sovereignty, and Enterprise Visibility Tradeoffs | -1.2% | EU core, expanding to Asia-Pacific national markets | Long term (≥ 4 years) |
| Resolver Bypass Through Encrypted Tunnels, Applications, and Alternate Resolvers | -0.9% | Global | Medium term (2-4 years) |
| Scarcity of DNS-Security Skills and Difficulty Proving Avoided-Loss ROI | -0.7% | Global, most acute in emerging markets | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Integration Complexity Across Legacy DNS, DoH, DoT, and IPv6
Many organizations must support traditional DNS, DNS-over-HTTPS, DNS-over-TLS, and IPv6 simultaneously. They may also manage on-premises BIND servers, Windows DNS, cloud-managed zones, and third-party software-as-a-service platforms. Maintaining identical filtering rules across these separate tools can increase operating effort and delay deployment. NIST recommends a hybrid design that combines cloud-delivered filtering with local DNS firewall or Response Policy Zone capabilities for continuity.[3] Regulated organizations also need records that demonstrate filtering coverage across all relevant resolution paths. The protective DNS services market faces a practical adoption barrier when buyers cannot easily apply a single policy across both older and newer infrastructure.
Privacy, Sovereignty, and Enterprise Visibility Tradeoffs
Protective DNS requires a resolver to inspect DNS queries, which can raise privacy and data governance concerns. Cloud-delivered products may retain query logs on provider infrastructure, requiring organizations to consider residency and sovereignty obligations. Encrypted DNS can improve individual privacy while limiting a corporate resolver’s ability to apply authorized filtering if browsers or applications use another resolver. CISA’s encrypted DNS guidance advises organizations to configure compatible browsers and applications to use approved resolvers. Governance work is significant because policy must address browser settings, applications, and network configurations. These tradeoffs can slow adoption for organizations that must balance security monitoring with privacy duties.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Offering: Software and Cloud Services Lead While Managed Services Expand
Protective DNS Software and Cloud Services held 63.21% of revenue in 2026. Large enterprises and government buyers often select these offerings because they connect DNS controls with security information and event management systems, secure access service edge platforms, and identity providers. The protective DNS services market depends on these platforms because buyers can customize blocking policies and retain query logs within their own environment. Platform contracts can remain durable when integrations and policy rules are incorporated into broader security operations.
Managed protective DNS Services are projected to expand at a 20.84% CAGR through 2032. The protective DNS services market can reach mid-market and public-sector buyers through providers that operate DNS threat controls on their behalf. The UK National Cyber Security Center directs private-sector organizations to procure commercial protective DNS services, thereby supporting the managed-service channel.[4] DNSFilter reported more than 6,000 managed-service-provider partners and 40% year-over-year partner-sourced revenue growth in 2025.



By Deployment: Cloud-Based Delivery Supports Broad Endpoint Coverage
Cloud-Based deployment accounted for 64.89% of the protective DNS services market size in 2026. It is also expected to advance at a 22.63% CAGR through 2032. The protective DNS services market favors cloud delivery because it can enforce policies across office networks, remote employees, mobile devices, and cloud workloads from a single management plane. Local installations usually protect only traffic that stays on the physical corporate network.
On-Premises deployments retain a role in defense, government, and critical-infrastructure environments where classified or air-gapped networks cannot direct queries to an external resolver. NIST’s 2026 guidance supports hybrid architectures that combine cloud filtering with local DNS firewall or Response Policy Zone controls. The protective DNS services market also includes hybrid options for organizations migrating to cloud platforms while operating older DNS infrastructure. F-Secure and Hutchison Telecommunications Hong Kong used network-level delivery in their 2026 5G broadband offering.[5]
By Organization Size: Large Enterprises Anchor Spending While SMEs Gain Access
Large enterprises held 68.71% of revenue in 2026. Their high DNS query volumes, compliance requirements, and distributed work environments can justify investments in advanced threat intelligence and policy management tools. Infoblox reported that generative AI is reducing the effort required to create deceptive DNS infrastructure. The protective DNS services market serves these buyers through closely integrated controls across access, identity, network, and cloud environments.
Small and medium-sized enterprises are forecast to expand at a 21.97% CAGR through 2032. Cloud-native products reduce the infrastructure requirements that once limited DNS filtering for smaller organizations. The protective DNS services market reaches these buyers through managed-service and broadband packages that reduce the need for a separate procurement process. Suppliers in regulated value chains may also be asked to demonstrate their cybersecurity controls during third-party assessments.

By Industry Vertical: Telecommunications Leads While Healthcare Addresses Exposure
IT and telecommunications accounted for 38.26% of revenue in 2026. The sector controls the resolver infrastructure that serves large subscriber bases, enabling providers to offer DNS protection through premium broadband and managed security services. The protective DNS services market benefits from network-level policies that providers can apply without requiring each subscriber to install software. Banking, financial services, insurance, and government users also face significant credential theft, compliance, and cybersecurity obligations.
The healthcare and life sciences industry is projected to accelerate at a 23.58% CAGR through 2032. The protective DNS services market provides a practical blocking layer for medical devices, imaging systems, and other connected equipment that may not support endpoint security agents. Health-ISAC identified AI-enabled attacks as a leading sector concern for 2026 and stated that it distributed more than 1,200 targeted threat alerts in 2025. Healthcare buyers must also protect sensitive records and ensure continuity of care delivery.
Geography Analysis
North America accounted for 34.76% of revenue in 2026. United States federal policy has made protective DNS a defined procurement category for covered agencies because CISA provides a resolver service for Federal Civilian Executive Branch use.[6] NIST’s March 2026 deployment guidance provides an evaluation framework relevant to federal, contractor, and private-sector security programs. Cisco, Infoblox, Cloudflare, and Akamai have major product and engineering operations in the region. Their presence supports frequent product updates and cloud service options.
Asia-Pacific is forecast to expand at a 22.73% CAGR through 2032. The protective DNS services market is supported by cloud infrastructure investment, exposure to cybercrime in financial and healthcare organizations, and evolving national cybersecurity regulations across India, Japan, South Korea, Australia, and Southeast Asia. India’s incident-reporting requirements, Japan’s privacy framework, and Australia’s cybersecurity strategy have each increased attention to DNS and critical-infrastructure controls. F-Secure and HTHK launched AI Net Protect in May 2026, embedding DNS security in HTHK’s 5G Broadband PRO service with no end-user software installation. That approach shows why provider-led, network-level delivery is important in the region.
Europe has a significant position because the United Kingdom and Germany have mature cybersecurity programs and broad enterprise demand. The EU NIS2 Directive expanded the group of organizations subject to cybersecurity obligations, making DNS safeguards relevant to more regulated entities. The United Kingdom’s National Cyber Security Centre operates a Protective DNS service for government and also provides guidance for commercial users. South America, the Middle East, and Africa offer room for cloud-delivered services as digital infrastructure expands, supported by Brazil’s data-protection framework, UAE and Saudi Arabian digital transformation programs, and mobile broadband adoption in Nigeria, South Africa, and Kenya.
Competitive Landscape
Market Concentration
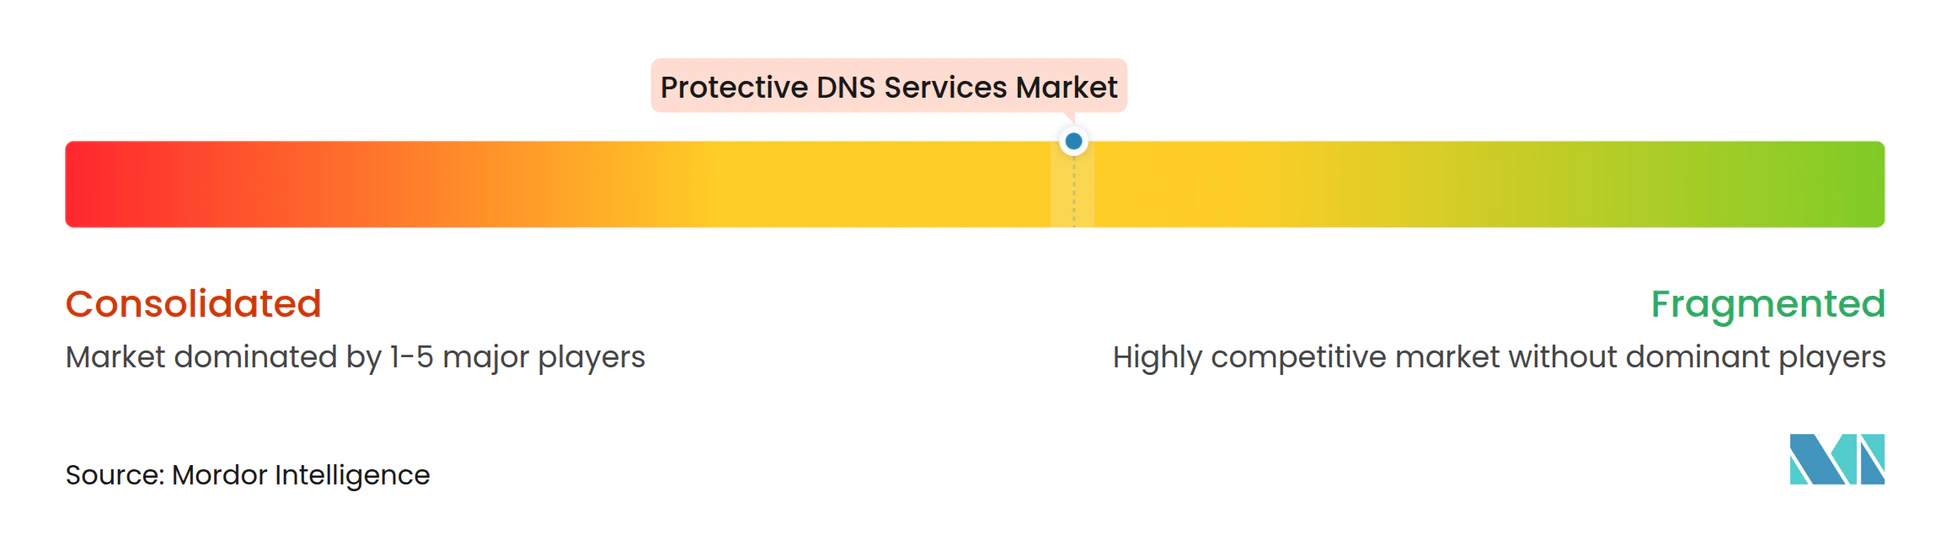
The protective DNS services market is moderately concentrated among enterprise platforms, where Cisco, Infoblox, Cloudflare, and Akamai sell DNS capabilities as part of larger security portfolios. Their products connect DNS filtering with secure access service edge, zero-trust, cloud security, and network controls. NIST’s 2026 guidance favors platforms that support encrypted DNS protocols, DNSSEC validation, and audit logging for public-sector requirements. The protective DNS services market, therefore, competes on technical integration, governance features, and operational fit rather than domain blocking alone.
Infoblox expanded its Threat Defense capabilities in August 2025 and stated that it would power Google Cloud’s DNS Armor service. Akamai introduced an agentless multicloud DNS Posture Management product in June 2025 for AWS, Azure, Google Cloud Platform, and Akamai Cloud DNS. Cisco introduced Secure Access DNS Defense in May 2025 as an entry point to its universal zero-trust network access offering. These moves embed DNS security within wider cloud and access architectures. The protective DNS services market can reward vendors that link resolvers to identity-aware policy controls.
Channel-focused competitors have a different route to market. Whalebone focuses on telecommunications operators, while TitanHQ offers an MSP-oriented WebTitan product for distribution via managed services. DNSFilter launched an OEM Partner Program in July 2026 for ISPs, device makers, and application developers who wish to embed its protection under their own brands. Quad9’s nonprofit resolver blocks known malicious domains without logging user IP addresses, providing a lower-cost alternative for some smaller-user cases.
Protective DNS Services Industry Leaders
-
Cisco Systems, Inc.
-
Infoblox Inc.
-
Akamai Technologies, Inc.
-
Cloudflare, Inc.
-
Open Text Corporation
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: DNSFilter launched its OEM Partner Program, enabling ISPs, device manufacturers, and app developers to embed its protective DNS and VPN capabilities under their own brand. The platform processes 200 billion queries per day across more than 225 servers in 85-plus countries and supports over 65 million daily users, with Amazon’s eero and Brave browser as existing integrations.
- July 2026: Cloudflare released Cloudflare Internal DNS as generally available for Enterprise customers, providing authoritative and recursive DNS for private networks on the same global control plane used for Zero Trust and networking services, eliminating the need for separate internal DNS infrastructure.
- June 2026: DNSFilter launched a three-tier MSP Partner Program, Select, Accelerator, and Strategic, restructuring its channel with branded campaign assets, self-paced training, and volume-based pricing for all 6,000-plus MSP partners.
- May 2026: F-Secure and Hutchison Telecommunications Hong Kong launched "AI Net Protect," a DNS security service embedded in HTHK’s 5G Broadband PRO offering. The service uses AI to block malicious connections at the network level with no end-user software installation required.
- March 2026: NIST published SP 800-81r3, the first major federal DNS security guidance update in 13 years, explicitly positioning protective DNS as an active security control and Zero Trust policy enforcement point covering DoT, DoH, and DoQ protocols. The publication immediately influenced enterprise procurement frameworks and vendor evaluation criteria globally.
Global Protective DNS Services Market Report Scope
The protective DNS services market comprises cloud-based or managed DNS security solutions that inspect DNS requests against threat intelligence feeds and organizational policies to block or redirect access to malicious, phishing, malware-hosting, command-and-control, or otherwise restricted domains. These services provide early network security control by blocking risky connections at the domain resolution stage, before a device establishes a connection to the destination.
The Protective DNS Services Market Report is Segmented by Offering (Protective DNS Software and Cloud Services, Managed Protective DNS Services, Professional and Integration Services, and Support and Maintenance Services), Deployment Mode (Cloud-Based, On-Premises, and Hybrid), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), Industry Vertical (Banking, Financial Services, and Insurance (BFSI), IT and Telecommunications, Healthcare and Life Sciences, Government and Public Administration, Retail and E-Commerce, Manufacturing and Industrial, Energy and Utilities, Media and Entertainment, and Other Industry Verticals), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
| Protective DNS Software and Cloud Services |
| Managed Protective DNS Services |
| Professional and Integration Services |
| Support and Maintenance Services |
| Cloud-Based |
| On-Premises |
| Hybrid |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| Banking, Financial Services, and Insurance (BFSI) |
| IT and Telecommunications |
| Healthcare and Life Sciences |
| Government and Public Administration |
| Retail and E-Commerce |
| Manufacturing and Industrial |
| Energy and Utilities |
| Media and Entertainment |
| Other Industry Verticals |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia and New Zealand | |
| Southeast Asia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Kenya | |
| Rest of Africa |
| By Offering | Protective DNS Software and Cloud Services | |
| Managed Protective DNS Services | ||
| Professional and Integration Services | ||
| Support and Maintenance Services | ||
| By Deployment | Cloud-Based | |
| On-Premises | ||
| Hybrid | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By Industry Vertical | Banking, Financial Services, and Insurance (BFSI) | |
| IT and Telecommunications | ||
| Healthcare and Life Sciences | ||
| Government and Public Administration | ||
| Retail and E-Commerce | ||
| Manufacturing and Industrial | ||
| Energy and Utilities | ||
| Media and Entertainment | ||
| Other Industry Verticals | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia and New Zealand | ||
| Southeast Asia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Kenya | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the 2026 size of the protective DNS services market?
The protective DNS services market size is expected to increase from USD 0.72 billion in 2026 to USD 0.83 billion in 2027 and reach USD 1.86 billion by 2032, growing at a CAGR of 17.47% over 2027-2032.
What CAGR is expected through 2032?
The sector is projected to register a 17.47% CAGR from 2027 to 2032.
Which offering leads revenue?
Protective DNS Software and Cloud Services led with 63.21% share in 2026.
Why are cloud-delivered DNS controls being adopted?
Cloud delivery can apply consistent DNS policies across offices, remote users, mobile devices, and cloud workloads.
Which end-user group is expected to expand fastest?
Healthcare and Life Sciences are projected to expand at a 23.58% CAGR through 2032.
Which region is forecast to advance fastest?
Asia-Pacific is projected to accelerate at a 22.73% CAGR through 2032.