
Propylene Oxide Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 23.90 Billion |
| Market Size (2031) | USD 31.43 Billion |
| Growth Rate (2026 - 2031) | 5.63 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Propylene Oxide Market Analysis by Mordor Intelligence
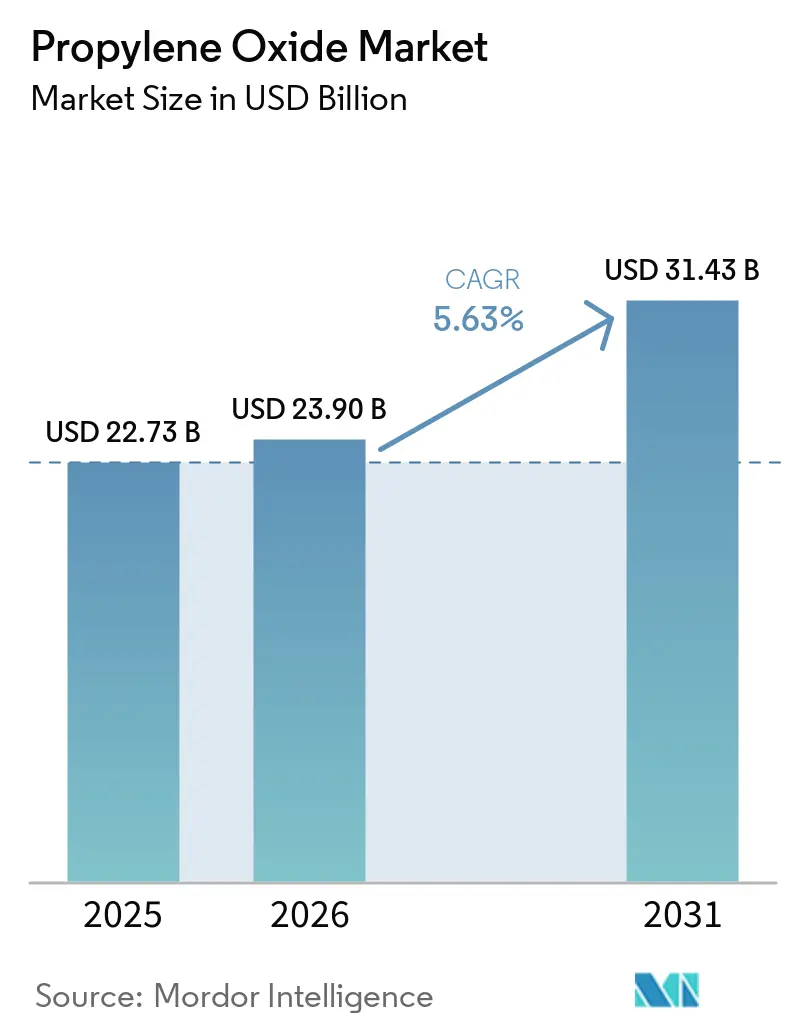
The propylene oxide market size is projected to expand from USD 22.73 billion in 2025 and USD 23.90 billion in 2026 to USD 31.43 billion by 2031, at a CAGR of 5.63% between 2026 and 2031. The propylene oxide market is supported by building rules that increase demand for efficient insulation materials. Polyurethane use in electric vehicle parts also broadens demand beyond conventional vehicle interiors. Environmental restrictions on chlorohydrin production favor cleaner production routes, particularly hydrogen peroxide to propylene oxide technology. Producers are responding through integrated facilities that convert propylene oxide into polyols or propylene glycol on the same site. This approach reduces exposure to spot pricing and makes downstream capability more important across the propylene oxide market.
Key Report Takeaways
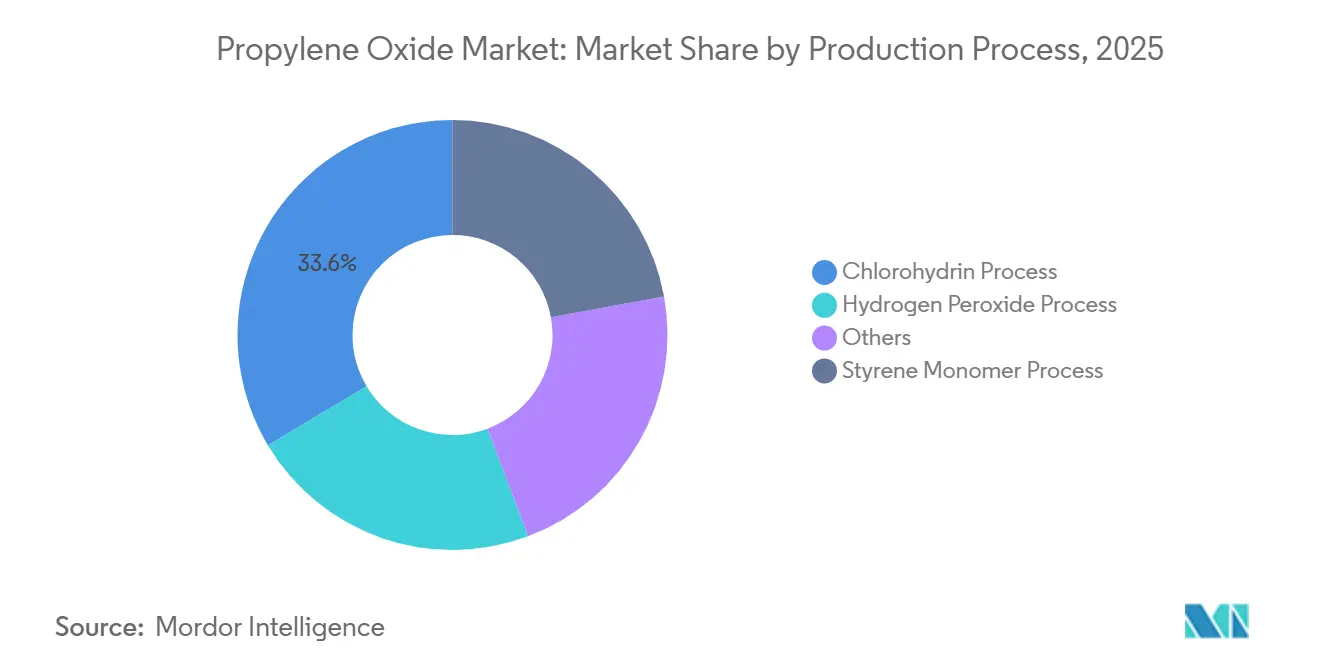
- By production process, the chlorohydrin process held 33.56% of the propylene oxide market share in 2025, while the hydrogen peroxide process is expected to grow at a CAGR at 5.97% through 2031.
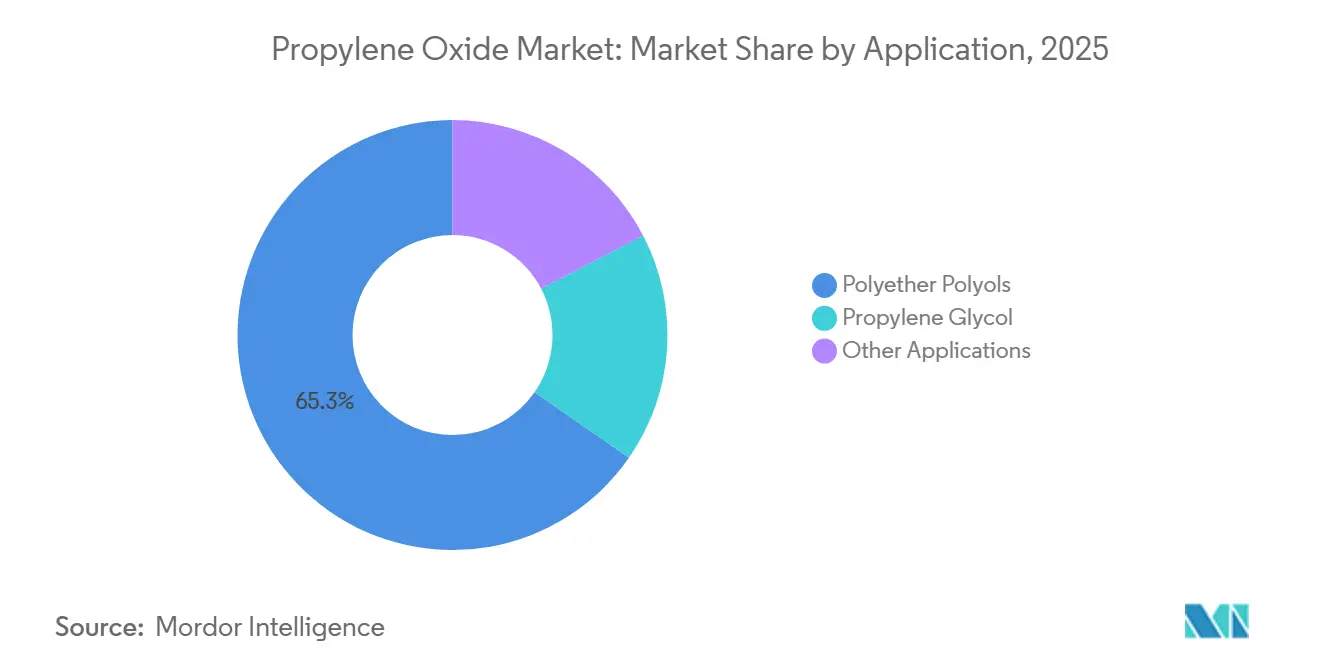
- By application, polyether polyols accounted for 65.32% of the propylene oxide market size in 2025, while propylene glycol is forecast to expand at a 6.13% CAGR through 2031.
- By end-use industry, building and construction held 36.14% of revenue in 2025, while automotive recorded the highest projected CAGR at 6.67% through 2031.
- By geography, Asia Pacific held 48.83% revenue share in 2025, and is expected to be the fastest growing region with a CAGR of 6.45% through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global Propylene Oxide Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Energy-Efficient Building Foam Demand | +1.4% | Global, strongest in EU, North America, and urban Asia-Pacific | Medium term (2-4 years) |
| Vehicle Lightweighting Adoption | +1.0% | Global, led by China, Germany, and South Korea | Medium term (2-4 years) |
| Propylene Glycol Demand Expansion | +0.8% | Global, strongest in North America, EU, and emerging Asia-Pacific | Long term (≥ 4 years) |
| Asia-Pacific Capacity and Downstream Integration | +0.7% | Asia-Pacific core, with spillover to Middle East and Africa and South America | Medium term (2-4 years) |
| Cleaner Production Technology Commercialization | +0.6% | Global, with China and EU as primary regulatory drivers | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Demand for Polyurethane Foams in Energy-Efficient Buildings
The propylene oxide market benefits from building rules that require better thermal performance in new construction and retrofits, which makes insulation specifications an important source of demand. The European Union revised Energy Performance of Buildings Directive requires zero-emission buildings for new public buildings from 2028 and for all new buildings from 2030 [1]. Rigid polyurethane foam can deliver thermal conductivity as low as 0.022 W/m·K, making it useful where building designs limit the available insulation thickness. The U.S. Department of Energy Building Technologies Office supports improvements in building efficiency and technologies for existing buildings. These rules increase demand for spray foam and boardstock systems that use propylene oxide-derived polyether polyols, rather than treating insulation selection as a solely discretionary choice. They also direct attention toward materials that meet thermal requirements without major changes to wall or roof designs. Integrated producers can meet tighter viscosity and reactivity requirements better than suppliers focused only on commodity-grade material, which connects regulatory demand to a greater emphasis on product consistency.
Lightweight Materials Adoption in Electric and Conventional Vehicles
The propylene oxide market gains from polyurethane use in vehicle components that replace heavier materials, while retaining the functional requirements of vehicle systems. Global vehicle production reached 96.4 million units in 2025, an increase of 3.9% from 2024, according to Organisation Internationale des Constructeurs d'Automobiles (OICA). Covestro states that its Baypreg STM polyurethane technology can reduce the weight of battery pack enclosures by up to 60% compared with steel. These systems can also provide electrical insulation and flame-retardant performance in the same component, avoiding the need to rely only on separate materials for each function. Electric vehicle applications, therefore, require specialty polyether polyols for semi-rigid encapsulants and structural foams, unlike many established flexible foam uses. The resulting shift toward higher-value grades can support producers that have formulation and downstream processing capability, particularly where vehicle manufacturers seek fewer components and reduced weight.
Expansion of Propylene Glycol Demand in Food, Pharmaceutical, and Personal Care Applications
The propylene oxide market has a broader demand base because propylene glycol serves food, pharmaceutical, and personal care uses with different purchasing patterns. EU Regulation No 1333/2008 lists propylene glycol as food additive E1520 in its permitted additive lists. This status supports its use as a humectant, solvent, and preservative in bakery products, confectionery, beverages, dairy formulations, and other food preparations. Demand from these applications is less directly tied to construction and vehicle cycles, which broadens the end-use profile for producers with propylene glycol capacity. Suppliers that meet pharmacopeial and traceability requirements can differentiate their offering from industrial-grade suppliers and serve buyers with more demanding material documentation needs.
Asia-Pacific Capacity Expansion and Downstream Integration
The propylene oxide market is being reshaped by new Asia-Pacific capacity and deeper downstream integration, which affects both local supply and export competition. Solvay licensed its hydrogen peroxide process technology to North Huajin Refining and Petrochemical Company for a 300,000-tonne-per-year plant in Panjin, China[2]. The planned facility illustrates how technology licensing supports the expansion of cleaner production routes at the same time as local operators expand their production base. Producers are also combining hydrogen peroxide-based propylene oxide units with polyether polyol facilities, allowing intermediate material to move directly into derivative production. This configuration keeps a larger share of value within one integrated chain and gives operators more control over the use of their output. It also reduces the volume exposed to the merchant propylene oxide market and increases pressure on standalone suppliers that must sell a larger share of their production externally.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Propylene Feedstock and Energy Price Volatility | -1.3% | Global, most acute in Europe and Northeast Asia | Short term (≤ 2 years) |
| Environmental and Occupational Safety Compliance Burden | -0.7% | EU and North America primarily, increasing in China | Long term (≥ 4 years) |
| Coproduct Exposure in PO-Styrene and PO-TBA Routes | -0.7% | Western Europe, North America, and Japan | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Propylene Feedstock and Energy Price Volatility
The propylene oxide market remains sensitive to propylene and energy costs because propylene comes from crude oil, natural gas, and related processing routes that respond to broader energy conditions. This exposure affects both pricing and producer margins, and it can also influence the relative competitiveness of different regions. The supplied draft reported that East Asian propylene moved from USD 865 per metric ton in late June 2026 to USD 1,010 per metric ton by mid-July 2026. The cited source for that movement does not meet the required source standard, so the figure is not used in this report. Cost shocks can be especially difficult for producers with older assets, limited integration, or a higher dependence on purchased feedstock. Repeated cost pressure can accelerate capacity closures and reduce the diversity of regional supply, leaving buyers more exposed to disruptions at the remaining large plants.
Environmental and Occupational Safety Compliance Burden
The propylene oxide market faces substantial costs for safe storage, handling, emissions control, and disclosure because the substance has demanding hazard classifications. The European Chemicals Agency includes propylene oxide on its Candidate List of substances of very high concern. The classification requires supply-chain communication for articles containing the substance above the relevant threshold and adds a continuing compliance requirement for affected operators. The Seveso III Directive requires major-accident prevention and control measures for covered facilities. In the United States, OSHA identifies an 8-hour permissible exposure limit of 100 ppm for propylene oxide. NIOSH recommends a lower 2 ppm exposure limit, which can increase engineering requirements for facilities that follow more protective practices.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Production Process: Cleaner Routes Gain Strategic Importance
The chlorohydrin process held 33.56% of the propylene oxide market share in 2025, mainly because of its installed base. The process faces a policy-driven phaseout in China and an economic contraction in Europe. The propylene oxide industry still uses styrene monomer and cumene hydroperoxide routes at major integrated facilities. Those routes can be exposed to the pricing of their coproducts. Hydrogen peroxide technology is the fastest-growing production process, with a projected CAGR of 5.97% through 2031. Its coproduct-free output and fit with stricter environmental requirements support new investment.
The size of the hydrogen peroxide technology segment is expected to gain from projects located beside polyether polyol capacity. Solvay’s licensed 300,000-tonne-per-year Panjin project demonstrates continued commercial interest in this route. KBR’s agreement with Sumitomo Chemical expands access to propylene oxide by cumene technology. Both technologies reduce dependence on markets for styrene monomer or tertiary butyl alcohol. In Europe, closures of older assets indicate that replacement investment may remain limited. In the Asia Pacific region, integrated projects can process output internally instead of selling it into the spot market. This difference changes the competitive position of suppliers that do not have derivative operations.

By Application: Polyether Polyols Retain Volume Leadership
Polyether polyols accounted for 65.32% of the propylene oxide market size in 2025. Their scale reflects use in flexible and rigid polyurethane foam for construction, furniture, automotive, and appliances. Propylene glycol is the fastest-growing application, with a projected CAGR of 6.13% through 2031. It benefits from demand across food, pharmaceuticals, and personal care. The propylene oxide market, therefore, combines a high-volume polyurethane base with applications that have different demand cycles. Other uses include glycol ethers and specialty chemicals for coatings, surfactants, and agrochemicals.
The propylene oxide market is seeing a shift within polyether polyols toward application-specific systems. Electric vehicle battery enclosures and modules require flame-retardant, semi-rigid, and structurally durable formulations. Covestro’s battery pack solution shows the functional requirements that support these higher-value polyurethane applications. Pharmaceutical-grade propylene glycol adds a separate opportunity for suppliers that can meet traceability expectations. Food additive approval in the EU provides an established regulatory basis for further food applications. These specialized outlets can reduce dependence on standard flexible foam demand.
By End-Use Industry: Construction Supports Volume and Automotive Leads Growth
Building and construction accounted for 36.14% of propylene oxide revenue in 2025. Rigid polyurethane foam insulation supports demand in commercial and residential buildings. Energy-performance requirements make a share of that demand less dependent on short-term building cycles. Automotive is the fastest-growing end-use sector, with a forecast CAGR of 6.67% through 2031. Conventional vehicles use polyurethane in seats, dashboards, and noise, vibration, and harshness components. The propylene oxide market also benefits from newer uses in electric vehicle battery enclosures and thermal management systems.
Construction's share reflects the large installed base of insulation uses. The European Union’s building directive establishes a longer-term policy direction toward more efficient new buildings. Vehicle production of 96.4 million units in 2025 provides a broad base for automotive polyurethane demand. Battery applications differ from traditional vehicle foam because they combine structural, insulation, and safety functions. Covestro reports that Baypreg STM can combine these functions while lowering enclosure weight compared with steel. Chemicals provide demand from glycol ethers, surfactants, and industrial solvents. Consumer goods, footwear, and mattresses add recurring demand linked to urbanization and household consumption.
Geography Analysis
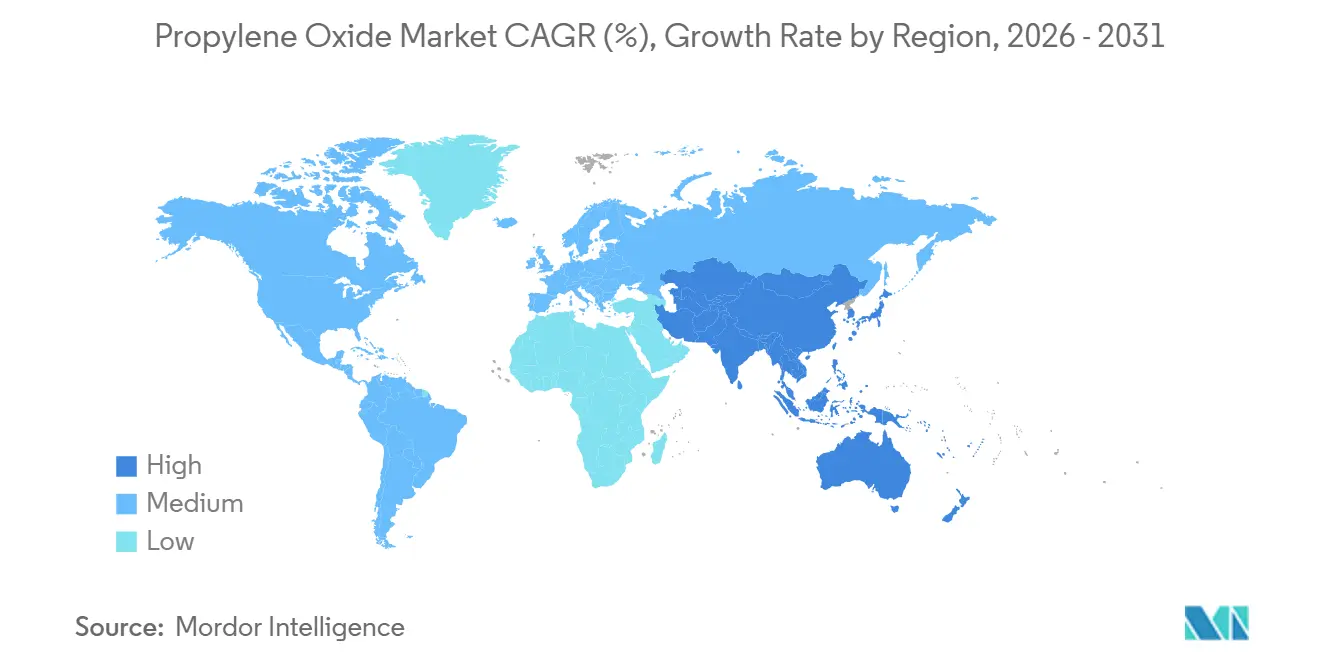
Asia-Pacific held 48.83% of the propylene oxide market size in 2025 and is forecast to grow at a 6.45% CAGR through 2031. China is central to regional production, capacity additions, and downstream integration. The supplied research draft described excess Chinese capacity as a source of export pressure in Southeast Asia, the Middle East, and Africa. India adds regional demand through urbanization, pharmaceutical activity, personal care, and infrastructure development. Japan and South Korea remain important for high-purity polyols and pharmaceutical-grade propylene glycol. The propylene oxide market in these countries faces growing pressure from lower-cost Chinese supply.
North America is the second-largest regional propylene oxide market, supported by feedstock availability and integrated production assets. LyondellBasell reported unplanned downtime at its Bayport PO/TBA facility during the second quarter of 2026 and said that the facility restarted in June. This event showed the importance of large plants to regional supply. Europe experienced a structural reduction in supply after permanent closures in 2025. LyondellBasell and Covestro permanently closed the PO11 unit at Maasvlakte in March 2025. Demand remains tied to automotive and construction, while procurement increasingly relies on imports and remaining integrated facilities.
South America and the Middle East and Africa remain smaller markets in the propylene oxide market. Brazil supports South American demand through construction and automotive manufacturing, where polyurethane materials are used in insulation, vehicle systems, furniture, and other consumer products across major urban, industrial, and regional centers. Argentina has demand from agrochemical and personal care production, which provides derivative outlets beyond the construction cycle. Saudi Arabia has integrated petrochemical operations that benefit from competitive propylene feedstock and can support regional availability of chemical intermediates. South Africa and other Sub-Saharan markets have growing demand for insulation and furniture foam as urban development increases the need for building materials and household products. The propylene oxide market could gain from local downstream investment as urbanization and consumer goods manufacturing develop, although the supplied draft did not provide verified market-size figures for these countries. Local conversion of propylene oxide into polyols, propylene glycol, coatings inputs, and specialty chemicals would reduce the need to move all intermediate material over long distances. It would also give regional manufacturers more direct access to inputs for construction, appliances, automotive production, footwear, mattresses, and personal care products. The level of investment will depend on the availability of reliable feedstock, suitable production technology, and demand that is sufficient to support derivative plants. These regions therefore remain relevant as destinations for supply and as potential locations for value-added processing, even though their current role is smaller than that of Asia-Pacific, North America, and Europe.
Competitive Landscape
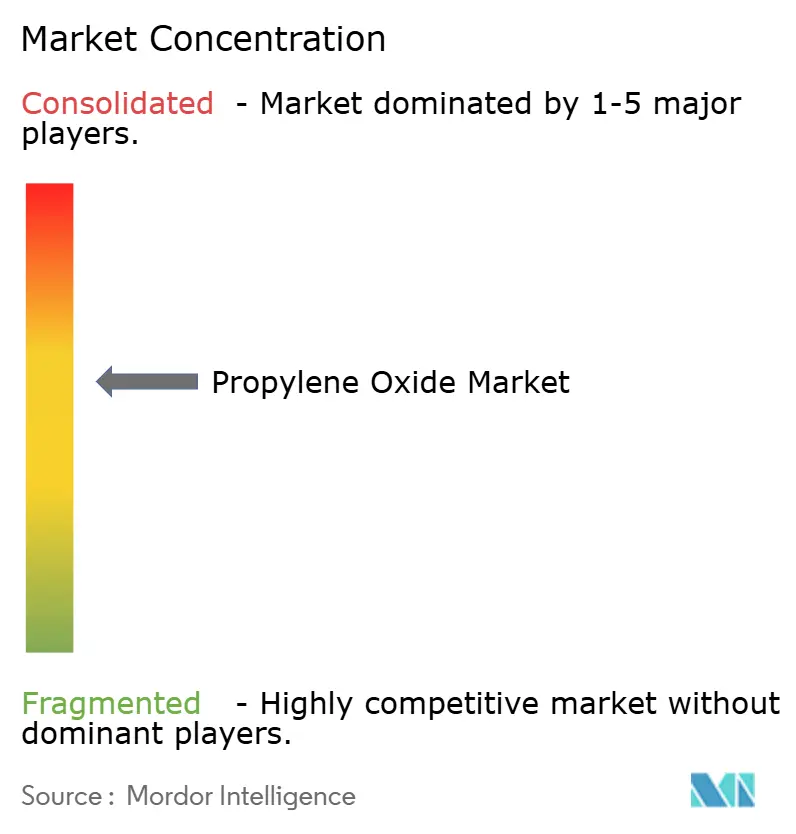
The propylene oxide market is moderately consolidated, with 6 to 8 large producers controlling most nameplate capacity in the supplied research draft. Competition differs between Western suppliers that rationalize high-cost assets and Chinese producers that expand integrated capacity. Dow supports North American supply through Gulf Coast integration. BASF’s Antwerp complex, developed with Evonik, remains an established European hydrogen peroxide to propylene oxide facility. Repsol licenses POSM technology and participates in integrated operations. Huntsman supplies specialty polyols for automotive and construction through its Nanjing Jinling joint venture in China.
LyondellBasell and Covestro provided a clear example of capacity rationalization when they announced the permanent PO11 closure in March 2025. The closure cited global overcapacity, Asian imports, and European production costs. Solvay provided a second strategic example through its 2024 technology license for the North Huajin plant in China. That agreement supports new hydrogen peroxide to propylene oxide capacity rather than older chlorohydrin technology. Evonik’s licensed hydrogen peroxide plant in Leshan began operations on June 18, 2026. These moves show that technology access and integrated feedstock arrangements are key competitive tools.
The propylene oxide market favors companies that can convert output into polyols, propylene glycol, and other derivatives rather than relying on merchant sales of the intermediate. Integration reduces direct exposure to merchant price movements because material can be consumed within the producer’s own production network. It also lets producers tailor materials for insulation, vehicle, pharmaceutical, personal care, coatings, surfactant, and industrial solvent applications that require different performance characteristics. Standalone producers face more direct commodity pressure when capacity expands faster than downstream demand or when local buyers can source imported product. The main competitive distinction is therefore not only plant scale but also process technology, consistent feedstock access, and derivative capability. The supplied draft also described a divide between capacity rationalization in Western markets and expansion by Chinese producers. That divide can change the geographic balance of supply because older assets face higher compliance and operating requirements while newer assets use cleaner technology. Companies that operate hydrogen peroxide-based facilities can avoid the direct coproduct exposure associated with PO-styrene monomer and PO-tertiary butyl alcohol plants. Companies that operate co-oxidation units can still benefit from refinery and petrochemical integration, but they remain exposed to market conditions for their associated products. The commercial value of integration is especially clear where producers combine propylene oxide units with polyether polyol production. These configurations can supply polyurethane systems for construction, furniture, appliances, conventional vehicles, and electric vehicle components without relying on the same volume of external intermediate sales. Propylene glycol provides a second derivative channel that reaches food, pharmaceutical, and personal care uses. This broader portfolio can help producers balance the more cyclical patterns associated with construction and automotive demand. It does not remove exposure to feedstock costs or safety requirements, but it can improve the range of outlets for a producer’s output. For this reason, technology licensing has become a meaningful competitive lever alongside direct capacity investment. Solvay’s Panjin license and the KBR and Sumitomo Chemical alliance both show how technology owners can influence future capacity without operating every plant themselves. Such arrangements can also shape where new projects are built and which production routes become commercially accessible. The competitive picture remains affected by the permanent closure of PO11 at Maasvlakte, which removed an established European source of supply. Buyers in Europe may therefore place greater weight on remaining domestic production, imports, and the reliability of integrated suppliers. The Bayport downtime reported by LyondellBasell during 2026 similarly showed that disruptions at large facilities can affect a regional supply balance. Producers with more than one route to derivatives may be better placed to manage short-term shifts in availability. The supplied research draft did not provide a verified combined share for the leading companies. It therefore supports a moderate rather than highly concentrated description of the propylene oxide market.
Propylene Oxide Industry Leaders
-
Dow
-
LyondellBasell Industries N.V.
-
BASF
-
Shell plc
-
Indorama Ventures Public Company Limited
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: LyondellBasell's Bayport PO/TBA facility in Texas experienced unplanned downtime in Q2 2026, with an estimated EBITDA impact of USD 250 million attributable to Middle East-related supply disruptions. The plant restarted in June 2026, with the company guiding for 85% utilization in Q3 2026, compared to 65% in Q2, positioning the segment for improved volumes in H2 2026.
- June 2026: The Evonik-licensed hydrogen peroxide megaplant operated by Fuhua in Leshan, Sichuan Province, China, commenced operations on June 18, 2026, reaching in-specification production within days. With an annual capacity of 200,000 tons of industrial-grade H₂O₂, the facility is one of the largest in the region and will supply key HPPO feedstock to the Evonik Fuhua New Materials joint venture as well as the regional merchant market.
Global Propylene Oxide Market Report Scope
Propylene oxide is a clear, colorless, and extremely flammable liquid with an ether-like odor, mainly used to manufacture polyether polyols for polyurethane plastics.
The propylene oxide market is segmented by production process, application, end-use industry, and geography. By production process, the market is segmented into chlorohydrin process, styrene monomer process, hydrogen peroxide process, and others. By application, the market is segmented into polyether polyols, propylene glycol, and other applications. By end-use industry, the market is segmented into automotive, building and construction, chemicals, and other end-use industries. By geography, the market is segmented into Asia Pacific, North America, Europe, South America, the Middle East and Africa. The report also covers the propylene oxide market size and forecasts for the propylene oxide market in 15 countries across major regions. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
| Chlorohydrin Process |
| Styrene Monomer Process |
| Hydrogen Peroxide Process |
| Others |
| Polyether Polyols |
| Propylene Glycol |
| Other Applications |
| Automotive |
| Building and Construction |
| Chemicals |
| Other End-Use Industries |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Production Process | Chlorohydrin Process | |
| Styrene Monomer Process | ||
| Hydrogen Peroxide Process | ||
| Others | ||
| By Application | Polyether Polyols | |
| Propylene Glycol | ||
| Other Applications | ||
| By End-Use Industry | Automotive | |
| Building and Construction | ||
| Chemicals | ||
| Other End-Use Industries | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the present and projected value of the propylene oxide market by 2031?
The propylene oxide market is forecast to reach USD 31.43 billion by 2031, expanding at a 5.63% CAGR from USD 23.90 billion in 2026.
Which production process is growing fastest for propylene oxide?
Hydrogen peroxide process is the fastest-growing process, with a projected CAGR of 5.97% through 2031.
Which application uses the most propylene oxide?
Polyether polyols led applications with 65.32% of consumption in 2025, supported by polyurethane foam uses.
Which region leads propylene oxide demand?
Asia-Pacific led with 48.83% of revenue in 2025 and is forecast to grow at a 6.45% CAGR through 2031.