
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 257.10 Million |
| Market Size (2027) | USD 264.5 Million |
| Market Size (2032) | USD 304.5 Million |
| Growth Rate (2027 - 2032) | 2.86 % |
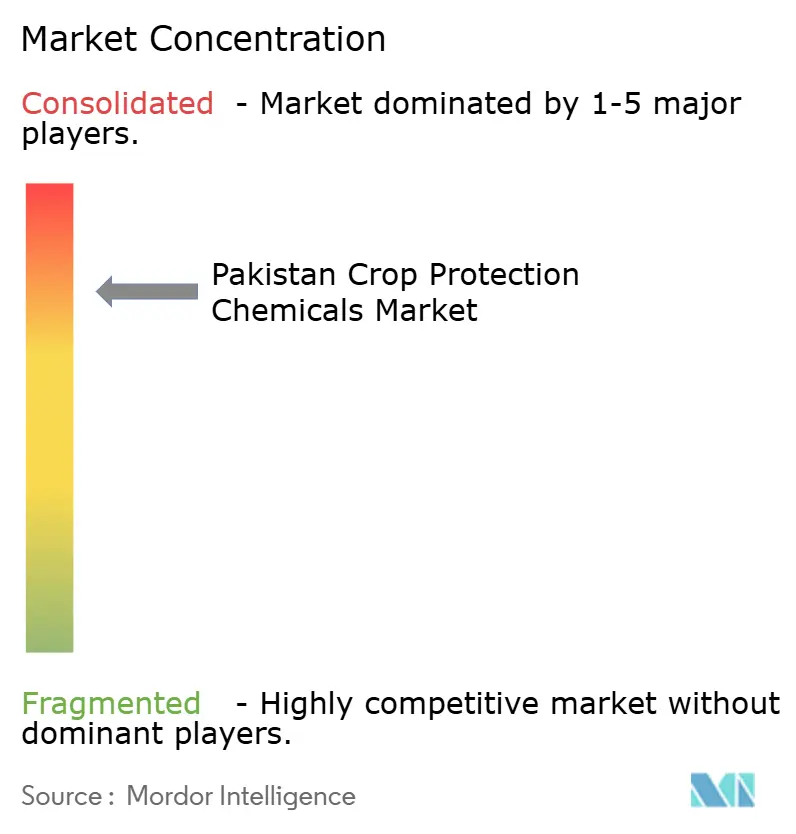
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Pakistan Crop Protection Chemicals Market Analysis by Mordor Intelligence
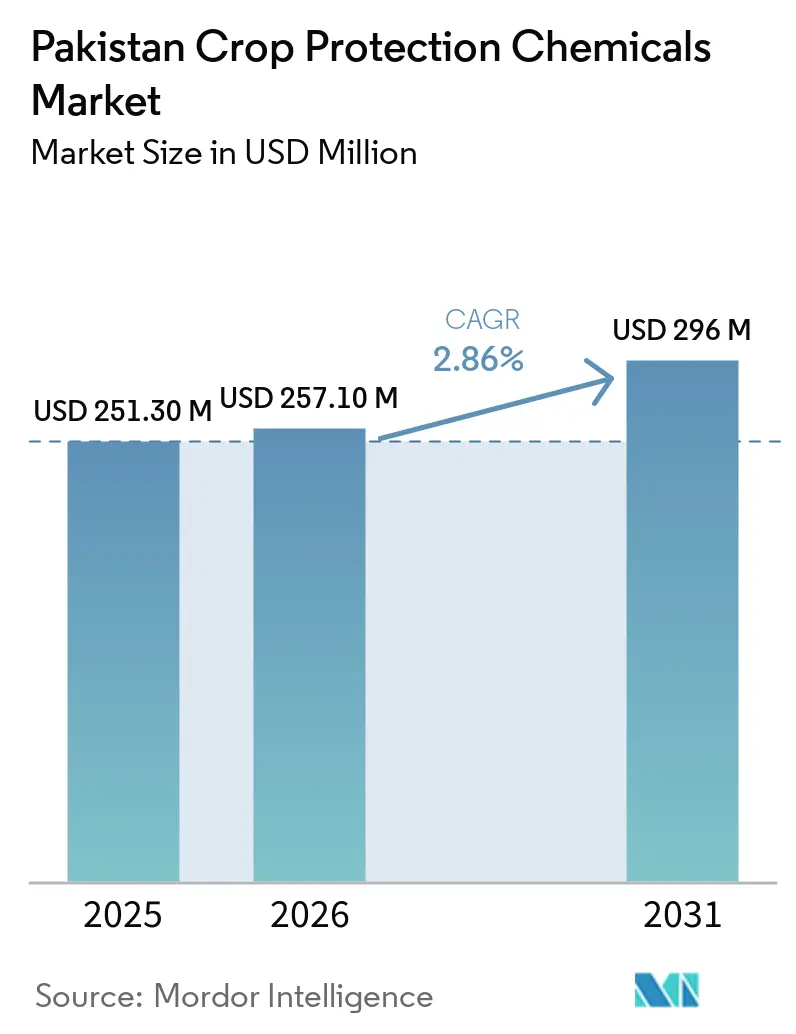
The Pakistan crop protection chemicals market size was valued at USD 257.10 million in 2026 and is forecast to grow from USD 264.50 million in 2027 to USD 304.50 million by 2032, at a CAGR of 2.86% from 2027 to 2032. Pakistan’s agriculture sector grew by 2.89% in FY2026, up from 1.53% in FY2025, supporting demand for agricultural inputs. However, demand for crop protection chemicals remains sensitive to input costs, credit availability, and farmers’ ability to finance timely applications[1]. Imported supply remains central to the market, leaving local formulators exposed to foreign-exchange movements, overseas technical-material prices, port-dependent supply channels, and broader disruptions across China-routed supply chains. Regulation is also shifting product demand, as the retirement of older active ingredients creates a need for registered replacement chemistries in paddy, cotton, and horticulture programs. International suppliers compete in higher-value registered products, while domestic formulators compete through dealer networks, local formulation capabilities, and pricing. These conditions are increasing the importance of compliant replacement products and authenticated distribution channels, while creating opportunities for investment in local manufacturing, precision applications, and products that address pest resistance or soil health needs. However, product availability continues to depend on imported technical materials, crop-specific pest calendars, timely dealer supply, and the purchasing capacity of smallholder farms.
Key Report Takeaways
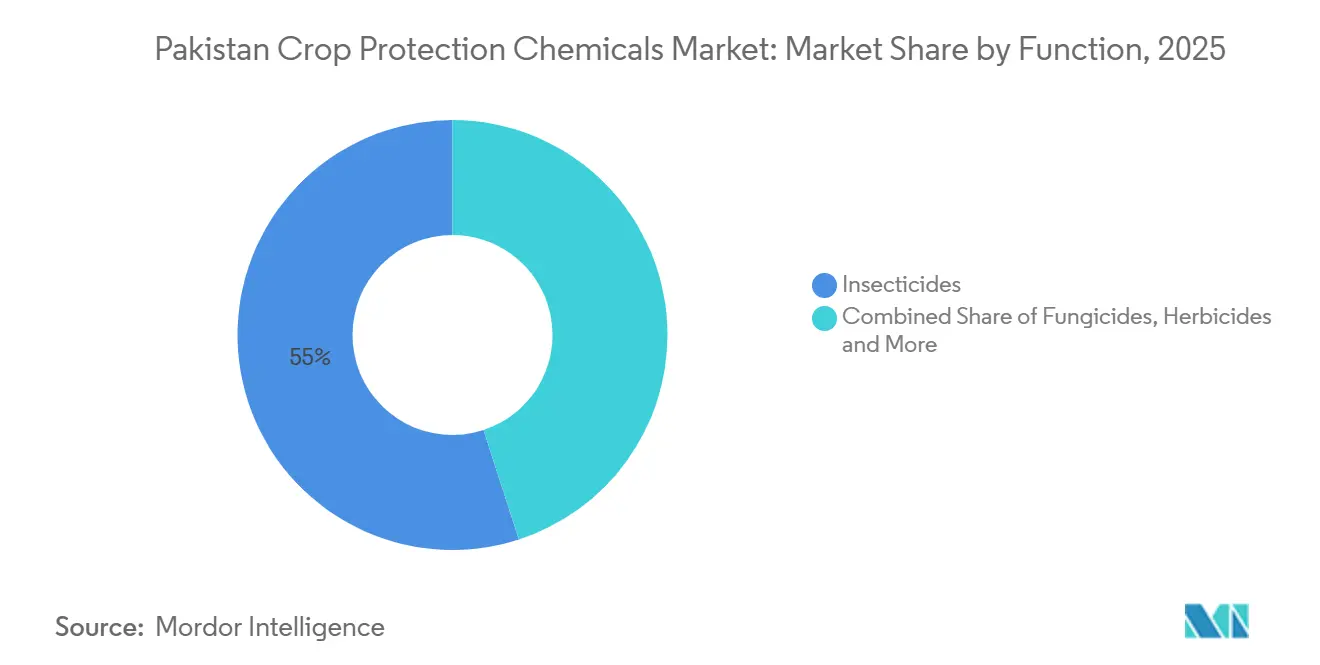
- By function, insecticides accounted for 55% of the Pakistan crop protection chemicals market share in 2026, while herbicides are forecast to grow at a CAGR of 4.1% from 2027 to 2032.
- By application mode, foliar application accounted for 52% of the Pakistan crop protection chemicals market size in 2026, while soil treatment is forecast to grow at a CAGR of 3.7% from 2027 to 2032.
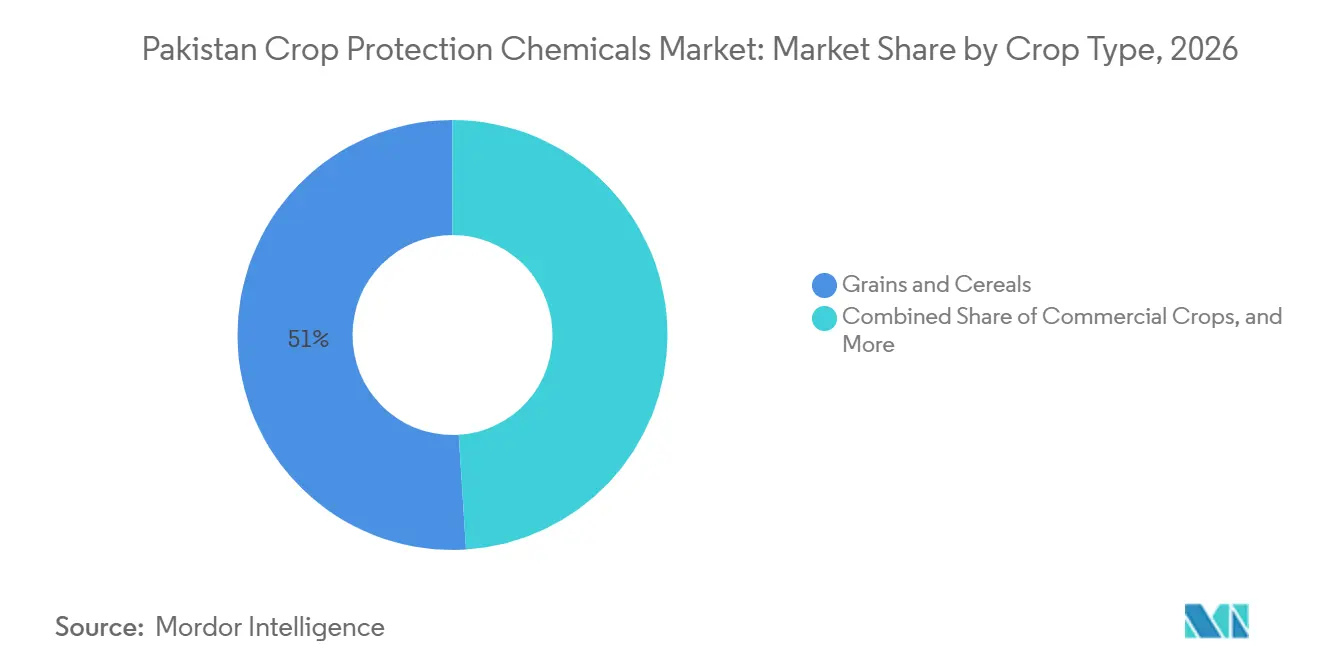
- By crop type, grains and cereals accounted for 51% of the market share in 2026, while commercial crops are forecast to grow at a CAGR of 3.6% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Pakistan Crop Protection Chemicals Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expanding Insect Pressure in Cotton, Rice, and Cereals | +0.7% | National, with concentrated impact in Punjab cotton belt and Sindh rice districts | Short term (≤ 2 years) |
| Weed Control Demand from Labor-Constrained Mechanized Farming | +0.6% | National, with early gains in Punjab wheat and sugarcane production zones | Medium term (2-4 years) |
| Export Residue Compliance Driving Crop Protection Upgrades | +0.5% | National, with concentrated impact in Punjab basmati and Sindh rice export chains | Medium term (2-4 years) |
| Digital Platforms and Direct-to-Farm Distribution | +0.3% | National, with early gains in remote Punjab and Sindh farm clusters | Medium term (2-4 years) |
| Climate-Driven Pest Migration and Irregular Crop Seasons | +0.6% | National, with heightened risk in flood affected Sindh and southern Punjab districts | Short term (≤ 2 years) |
| Import-Led Formulation and Local Manufacturing Upgrades | +0.3% | National, with concentrated investment in Karachi and Lahore industrial zones | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expanding Insect Pressure in Cotton, Rice, and Cereals
The Pakistan crop protection chemicals market continues to depend on insecticide use in cotton, rice, and cereal production. Cotton bollworm resistance to pyrethroid products has raised the need for more effective programs. Rice stem borer cycles have also moved beyond their earlier seasonal pattern in several growing areas. Heat-stressed crop periods have increased whitefly pressure and narrowed the time available for treatment[2]. Formulators with registered newer chemistries stand to benefit, as these products carry a higher per-unit active-ingredient cost than many of the molecules they replace. The shift toward newer insecticide chemistries is also increasing the importance of resistance-management programs across major crop-producing regions, supporting continued demand for products with different modes of action as growers adjust application programs to changing pest pressure.
Weed Control Demand from Labor-Constrained Mechanized Farming
Herbicide adoption is expanding beyond its traditional wheat base as mechanized farming reaches sugarcane and maize, creating a clearer path to demand for products that replace manual weeding. More intensive farming can increase weed problems, encouraging farmers to use soil-applied herbicides that provide longer-lasting weed control. Mechanized operations also favor weed-control solutions that can be applied efficiently across larger cultivated areas, reducing reliance on labor-intensive manual practices. As mechanization and input-intensive farming practices expand, demand is likely to shift further toward herbicides that reduce labor requirements and improve weed-control efficiency.
Export Residue Compliance Driving Crop Protection Upgrades
Residue compliance is changing the product requirements of rice export chains in Punjab and Sindh. The 2025 paddy insecticide restrictions were prompted by residue concerns in European, U.S., and Japanese import markets. Formulation companies must retire, reformulate, or replace affected active ingredients through the Department of Plant Protection registration process. BASF SE and Corteva Agriscience, Inc. are well-positioned in this environment, given their international quality systems and registered crop protection products. SRO 231(I)/2024 also strengthened accreditation requirements for imports. The NAFSA digital platform, launched in July 2025, adds another control point that can favor certified products over substandard supply. These measures can increase demand for registered products with established residue profiles and compliance documentation. Export-oriented growers and processors may therefore place greater emphasis on crop protection programs that meet destination-market maximum residue limits.
Digital Platforms and Direct-to-Farm Distribution
Digital farm services and direct-to-farm distribution channels can improve access to crop protection chemicals in remote agricultural areas. Pakistan’s large agricultural base and dispersed farming communities create opportunities for digital platforms that connect farmers with input suppliers. Four Brothers Group’s partnership with Telenor Pakistan integrates access to agricultural inputs with digital channels that serve farmers. Such models can improve product availability, provide price information, and reduce reliance on conventional retail networks. Digital advisory services can also help farmers access information on crop protection products and their appropriate use. As these channels expand, they may improve distribution efficiency and strengthen access to crop protection chemicals across underserved farming communities.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Imported Active Ingredient and Currency Exposure | -0.6% | National, with amplified impact on Karachi port dependent import channels | Short term (≤ 2 years) |
| Registration Delays, Banned Molecules, and Reformulation Cost | -0.3% | National, with concentrated burden on Department of Plant Protection registered formulators across Punjab and Sindh | Medium term (2-4 years) |
| Counterfeit and Substandard Product Leakage | -0.2% | National, with heightened concentration in remote Sindh and southern Punjab retail networks | Short term (≤ 2 years) |
| Smallholder Affordability and Credit Volatility | -0.3% | National, with concentrated impact in smallholder dominated Punjab, Sindh, and Khyber Pakhtunkhwa districts | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Imported Active Ingredient and Currency Exposure
Pakistan relies on imported active ingredients for much of its domestic pesticide formulation market, exposing the crop protection chemicals market to rupee depreciation and fluctuations in Chinese technical-grade prices. Pakistan Bureau of Statistics data recorded pesticide imports of 30,341 metric tons, valued at USD 150.3 million, from July to March FY2025–FY2026, compared with 20,995 metric tons, valued at USD 108.5 million, in the corresponding prior-year period. This increase in import volume and total value highlights the growing value of imported pesticide supplies and the potential exposure of domestic formulators to international sourcing costs and currency movements. Formulators without contracted offtake or protected procurement arrangements may face greater margin pressure and have less capacity to fund product innovation. Higher import costs can also increase the prices of formulated crop protection products, particularly when rupee depreciation raises the local-currency cost of imported inputs. These pressures can constrain farmers' purchasing power and delay product replacement or adoption in price-sensitive crop segments.
Registration Delays, Banned Molecules, and Reformulation Cost
Product registration requirements can slow the availability of replacement crop protection products. The Agricultural Pesticides Ordinance, 1971, and the Consolidated Agricultural Pesticides Rules, 1973, form the core compliance framework. The 2025 restrictions on hazardous active ingredients and methyl bromide affected several established product programs, requiring formulators to manage affected inventory while preparing compliant replacement portfolios. The Department of Plant Protection has also increased oversight through its digital registration and monitoring process. These requirements increase the cost and time needed to bring new or reformulated products to market. Additional testing, documentation, and approval requirements can extend product development timelines and increase regulatory expenditure for formulators, delaying the introduction of alternative products and limiting the speed at which the market can transition away from restricted active ingredients.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Function: Insecticides Lead as Herbicides Record Fast Growth
Insecticides accounted for 55% of the Pakistan crop protection chemicals market share in 2026. This reflects recurring pest pressure in cotton, paddy, and vegetable production across Punjab and Sindh. Bollworm, whitefly, and stem borer treatments remain central to farm crop protection schedules. The 2025 restrictions on older insecticide molecules are shifting demand toward diamides and spinosyns. This transition is reducing volumes of older organophosphates and pyrethroids while expanding the role of formulators with registered newer products.
Herbicides are forecast to grow at a CAGR of 4.1% from 2027 to 2032. They are replacing manual weeding in wheat and are gaining use in sugarcane and maize. Fungicides are increasingly used in citrus and mango production, where export programs require certified crop protection practices. Lucky Core Industries Limited and Bayer AG hold fruit-crop fungicide registrations, while molluscicides and nematicides are becoming more relevant in rice and intensive horticulture, where soil-health constraints prevail.

By Application Mode: Foliar Application Dominates, Soil Treatment Gains
Foliar application accounted for 52% of the Pakistan crop protection chemicals market share in 2026. Smallholder spray equipment and the need to reach crop canopies support this position. Control of whitefly, bollworm, and stem borer commonly requires direct foliar coverage. Cotton and paddy canopies also favor liquid canopy-directed application. These conditions make foliar spraying the most established method and align with current farm infrastructure.
Soil treatment is forecast to grow at a CAGR of 3.7% from 2027 to 2032. Nematode pressure in vegetable zones and sugarcane areas of central Punjab supports this growth. Fumigation faces disruption following restrictions on methyl bromide for post-harvest rice use, creating a registration opportunity for phosphine-based alternatives. Seed treatment is receiving investment as a combined fungicide-insecticide input at planting. Bayer AG's Emesto 24% FS and UPL Limited's seed-treatment portfolio reflect this approach, while chemigation remains a smaller opportunity in drip-irrigated orchards in Balochistan and Khyber Pakhtunkhwa.
By Crop Type: Grains and Cereals Lead, Commercial Crops Record Growth
Grains and cereals accounted for 51% of the market share in 2026. Wheat and rice production in Punjab and Sindh provides the volume base for this segment. Post-emergence herbicides are used in wheat production to control weeds that compete with crops for nutrients, water, and light. Rice growers are also adjusting to the 2025 insecticide restrictions, creating an inventory challenge for paddy protection programs while opening demand for diamide and alternatives.
Commercial crops are forecast to grow at a CAGR of 3.6% from 2027 to 2032. Cotton remains an important driver of pesticide demand, while sugarcane creates opportunities for herbicide use to manage weeds. Fruits and vegetables also contribute to demand for crop protection chemicals, with pesticide expenditure varying by crop and production system. Pulses and oilseeds represent additional crop categories within the market, while turf and ornamental applications serve more specialized uses, including urban landscaping.
Geography Analysis
Punjab is the largest provincial market for crop protection chemicals in Pakistan, owing to its leading contribution to national agricultural production and extensive cultivation of major crops, including wheat, rice, cotton, and sugarcane. Herbicide use is concentrated in the mechanized wheat belt from Faisalabad to Multan, where row-sown wheat creates uniform weed pressure and supports post-emergence treatment programs. Punjab also hosts most of the licensed formulation and packaging facilities, and its dealer networks supply a large part of the national market.
Punjab's 2025 paddy insecticide restrictions are shifting provincial demand toward diamide and spinosyn chemistry, creating an opening for newly registered alternatives. Sindh is the second-largest provincial market for crop protection chemicals in Pakistan. Demand is concentrated in rice and cotton districts, including Sukkur, Larkana, Mirpurkhas, and Hyderabad. Cotton has historically accounted for a large share of provincial insecticide spending during the June to October spray period. The 2025 monsoon floods reduced planted area in several districts, while non-basmati rice continues to drive fungicide and herbicide use under residue-compliance programs.
Khyber Pakhtunkhwa and Balochistan together account for a smaller share of crop protection demand, with requirements that differ from the commodity chemistry used more widely in Punjab and Sindh. Tobacco, potato, and high-value vegetables in Khyber Pakhtunkhwa require specialized fungicide and insecticide programs. Apple, grape, and pomegranate production in Balochistan drives demand for premium fungicides tied to quality standards. In October 2026, Pakistan discussed field trials with Schelkovo Agrohim through the Pakistan Agricultural Research Council and National Agricultural Research Centre, which could expand product availability for mountainous and arid production areas[3].
Competitive Landscape
The Pakistan crop protection chemicals market was moderately fragmented in 2026, with competition divided between multinational and domestic suppliers. Bayer AG, Syngenta Group, FMC Corporation, BASF SE, and Corteva Agriscience, Inc. form the multinational tier, competing through established active ingredients and agronomy services. Ali Akbar Group, Four Brothers Group, Tara Group, Auriga Group, Suncrop Group, Lucky Core Industries Limited, and Swat Agro Chemicals (Private) Limited form an important domestic supplier base, competing through formulation flexibility, dealer proximity, and generic product pricing.
Competition is shifting from generic volume alone toward registration, traceability, and crop-specific product capabilities. SRO 231(I)/2024 and the Department of Plant Protection’s digital framework strengthen oversight of pesticide imports and increase compliance requirements for suppliers. These requirements make product registration and regulatory compliance important factors in maintaining market access. Domestic suppliers also compete by leveraging established distribution networks to reach farmers across major agricultural regions.
Company initiatives include research collaboration and digital distribution. In July 2026, Bayer Pakistan signed a memorandum of understanding with the University of Sargodha to collaborate on crop protection solutions, biotechnology, and advanced agricultural technologies. In January 2026, Four Brothers Group partnered with Telenor Pakistan to distribute authenticated agricultural inputs through digital services. These developments reflect efforts to support agricultural research and improve access to crop protection products in Pakistan.
Pakistan Crop Protection Chemicals Industry Leaders
-
Bayer AG
-
Syngenta Group
-
FMC Corporation
-
BASF SE
-
UPL Limited
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: Bayer Pakistan (Private) Limited signed a memorandum of understanding with the University of Sargodha to collaborate on agricultural research and innovation. The partnership covers crop protection solutions, modern biotechnology, and advanced agricultural technologies. A joint consultative committee was established to oversee the collaboration.
- September 2025: Tara Group Pakistan signed a series of memoranda of understanding with Chinese agricultural partners at the 2nd Pakistan-China B2B Investment Conference in Beijing. The agreements covered agricultural research and development, biotechnology, local seed production for field crops and vegetables, and seed and crop science technology initiatives.
- July 2025: Pakistan’s Department of Plant Protection launched the NAFSA initiative as part of broader regulatory reforms. Following an internal audit and verification of a suspicious methyl bromide import, the department suspended the company’s license and, in coordination with Pakistan Customs, intercepted four shipments valued at approximately USD 1 million before clearance. These actions strengthened oversight of pesticide imports and enforcement of registration and import requirements.
Pakistan Crop Protection Chemicals Market Report Scope
Crop protection chemicals are substances used in agriculture to control pests, diseases, weeds, and other harmful organisms that affect crop yield and quality. They include herbicides, insecticides, fungicides, nematicides, and molluscicides applied to crops, seeds, and soil. The scope excludes biological crop protection products, microbial pesticides, botanical biopesticides, organic crop protection products, fertilizers, plant growth regulators, and other agricultural inputs that do not primarily function as conventional chemical pesticides.
The Pakistan crop protection chemicals market report is segmented by function (fungicide, herbicide, insecticide, molluscicide, and nematicide), by application mode (chemigation, foliar, fumigation, seed treatment, and soil treatment), and by crop type (commercial crops, fruits and vegetables, grains and cereals, pulses and oilseeds, and turf and ornamental). The market size and forecasts are provided in terms of value (USD) and volume (metric tons) for all the above segments.
By Function
| Fungicide |
| Herbicide |
| Insecticide |
| Molluscicide |
| Nematicide |
By Application Mode
| Chemigation |
| Foliar |
| Fumigation |
| Seed Treatment |
| Soil Treatment |
By Crop Type
| Commercial Crops |
| Fruits and Vegetables |
| Grains and Cereals |
| Pulses and Oilseeds |
| Turf and Ornamental |
| By Function | Fungicide |
| Herbicide | |
| Insecticide | |
| Molluscicide | |
| Nematicide | |
| By Application Mode | Chemigation |
| Foliar | |
| Fumigation | |
| Seed Treatment | |
| Soil Treatment | |
| By Crop Type | Commercial Crops |
| Fruits and Vegetables | |
| Grains and Cereals | |
| Pulses and Oilseeds | |
| Turf and Ornamental |
Market Definition
- Function - Crop Protection Chemicals are apllied to control or prevent pests, including insects, fungi, weeds, nematodes, and mollusks, from damaging the crop and to protect the crop yield.
- Application Mode - Foliar, Seed Treatment, Soil Treatment, Chemigation, and Fumigation are the different type of application modes through which crop protection chemicals are applied to the crops.
- Crop Type - This represents the consumption of crop protection chemicals by Cereals, Pulses, Oilseeds, Fruits, Vegetables, Turf, and Ornamental crops.
| Keyword | Definition |
|---|---|
| IWM | Integrated weed management (IWM) is an approach to incorporate multiple weed control techniques throughout the growing season to give producers the best opportunity to control problematic weeds. |
| Host | Hosts are the plants that form relationships with beneficial microorganisms and help them colonize. |
| Pathogen | A disease-causing organism. |
| Herbigation | Herbigation is an effective method of applying herbicides through irrigation systems. |
| Maximum residue levels (MRL) | Maximum Residue Limit (MRL) is the maximum allowed limit of pesticide residue in food or feed obtained from plants and animals. |
| IoT | The Internet of Things (IoT) is a network of interconnected devices that connect and exchange data with other IoT devices and the cloud. |
| Herbicide-tolerant varieties (HTVs) | Herbicide-tolerant varieties are plant species that have been genetically engineered to be resistant to herbicides used on crops. |
| Chemigation | Chemigation is a method of applying pesticides to crops through an irrigation system. |
| Crop Protection | Crop protection is a method of protecting crop yields from different pests, including insects, weeds, plant diseases, and others that cause damage to agricultural crops. |
| Seed Treatment | Seed treatment helps to disinfect seeds or seedlings from seed-borne or soil-borne pests. Crop protection chemicals, such as fungicides, insecticides, or nematicides, are commonly used for seed treatment. |
| Fumigation | Fumigation is the application of crop protection chemicals in gaseous form to control pests. |
| Bait | A bait is a food or other material used to lure a pest and kill it through various methods, including poisoning. |
| Contact Fungicide | Contact pesticides prevent crop contamination and combat fungal pathogens. They act on pests (fungi) only when they come in contact with the pests. |
| Systemic Fungicide | A systemic fungicide is a compound taken up by a plant and then translocated within the plant, thus protecting the plant from attack by pathogens. |
| Mass Drug Administration (MDA) | Mass drug administration is the strategy to control or eliminate many neglected tropical diseases. |
| Mollusks | Mollusks are pests that feed on crops, causing crop damage and yield loss. Mollusks include octopi, squid, snails, and slugs. |
| Pre-emergence Herbicide | Preemergence herbicides are a form of chemical weed control that prevents germinated weed seedlings from becoming established. |
| Post-emergence Herbicide | Postemergence herbicides are applied to the agricultural field to control weeds after emergence (germination) of seeds or seedlings. |
| Active Ingredients | Active ingredients are the chemicals in pesticide products that kill, control, or repel pests. |
| United States Department of Agriculture (USDA) | The Department of Agriculture provides leadership on food, agriculture, natural resources, and related issues. |
| Weed Science Society of America (WSSA) | The WSSA, a non-profit professional society, promotes research, education, and extension outreach activities related to weeds. |
| Suspension concentrate | Suspension concentrate (SC) is one of the formulations of crop protection chemicals with solid active ingredients dispersed in water. |
| Wettable powder | A wettable powder (WP) is a powder formulation that forms a suspension when mixed with water prior to spraying. |
| Emulsifiable concentrate | Emulsifiable concentrate (EC) is a concentrated liquid formulation of pesticide that needs to be diluted with water to create a spray solution. |
| Plant-parasitic nematodes | Parasitic Nematodes feed on the roots of crops, causing damage to the roots. These damages allow for easy plant infestation by soil-borne pathogens, which results in crop or yield loss. |
| Australian Weeds Strategy (AWS) | The Australian Weeds Strategy, owned by the Environment and Invasives Committee, provides national guidance on weed management. |
| Weed Science Society of Japan (WSSJ) | WSSJ aims to contribute to the prevention of weed damage and the utilization of weed value by providing the chance for research presentation and information exchange. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


