
OT Vulnerability Management Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 3.70 Billion |
| Market Size (2032) | USD 9.40 Billion |
| Growth Rate (2027 - 2032) | 20.48 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
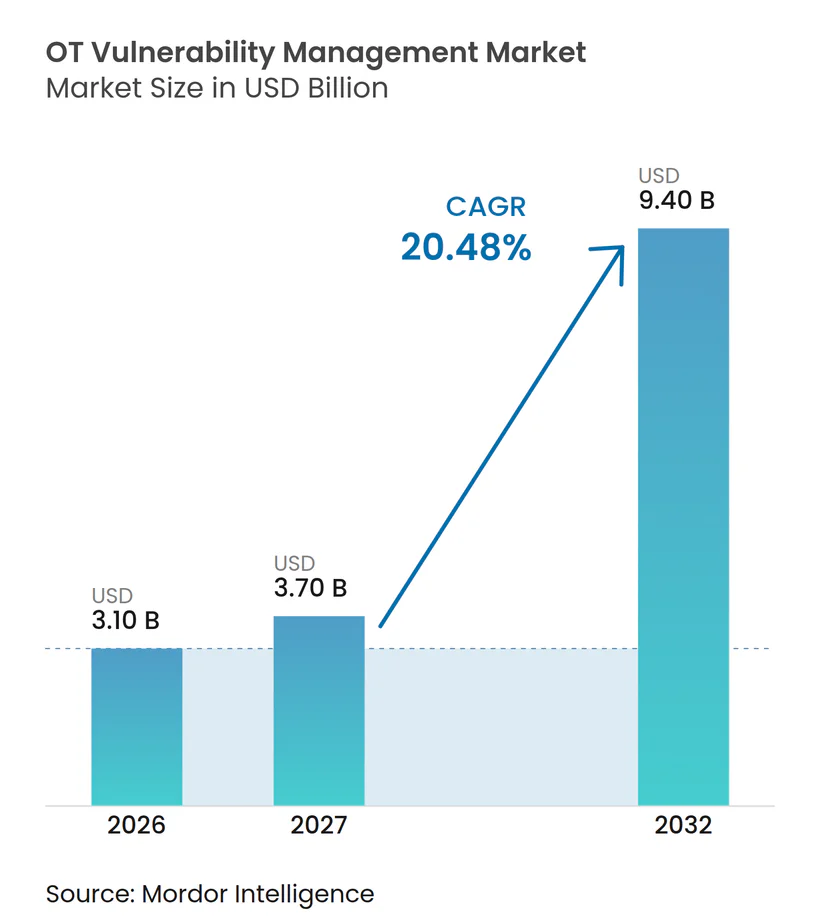
OT Vulnerability Management Market Analysis by Mordor Intelligence
The OT vulnerability management market size is projected to expand from USD 3.10 billion in 2026 to USD 9.40 billion by 2032, registering a CAGR of 20.48% between 2027 and 2032. Demand is shifting from periodic security reviews toward continuous identification and prioritization of operational exposure. Industrial operators are responding to attacks that target process information and control environments rather than enterprise data alone. Regulatory obligations and growing inventories of connected devices are making documented vulnerability programs more important in procurement and governance decisions. Providers are responding by combining asset visibility, risk assessment, remediation support, and managed services. This creates room for suppliers that can work safely across legacy industrial environments while meeting compliance and audit requirements.
Key Report Takeaways
- By component, software held 68.91% of the OT vulnerability management market share in 2026, while services are projected to expand at a 22.39% CAGR through 2032.
- By asset type, programmable logic controllers held 61.29% of the OT vulnerability management market share in 2026, while Industrial Internet of Things devices are projected to expand at a 21.77% CAGR through 2032.
- By deployment mode, on-premises deployment held 67.44% of the OT vulnerability management market share in 2026, while cloud deployment is projected to expand at a 22.06% CAGR through 2032.
- By organization size, large enterprises held 70.14% of the OT vulnerability management market share in 2026, while small and medium enterprises are projected to expand at a 22.70% CAGR through 2032.
- By end-user industry, industrial manufacturing held 30.12% of the OT vulnerability management market share in 2026, while healthcare and life sciences are projected to expand at a 21.05% CAGR through 2032.
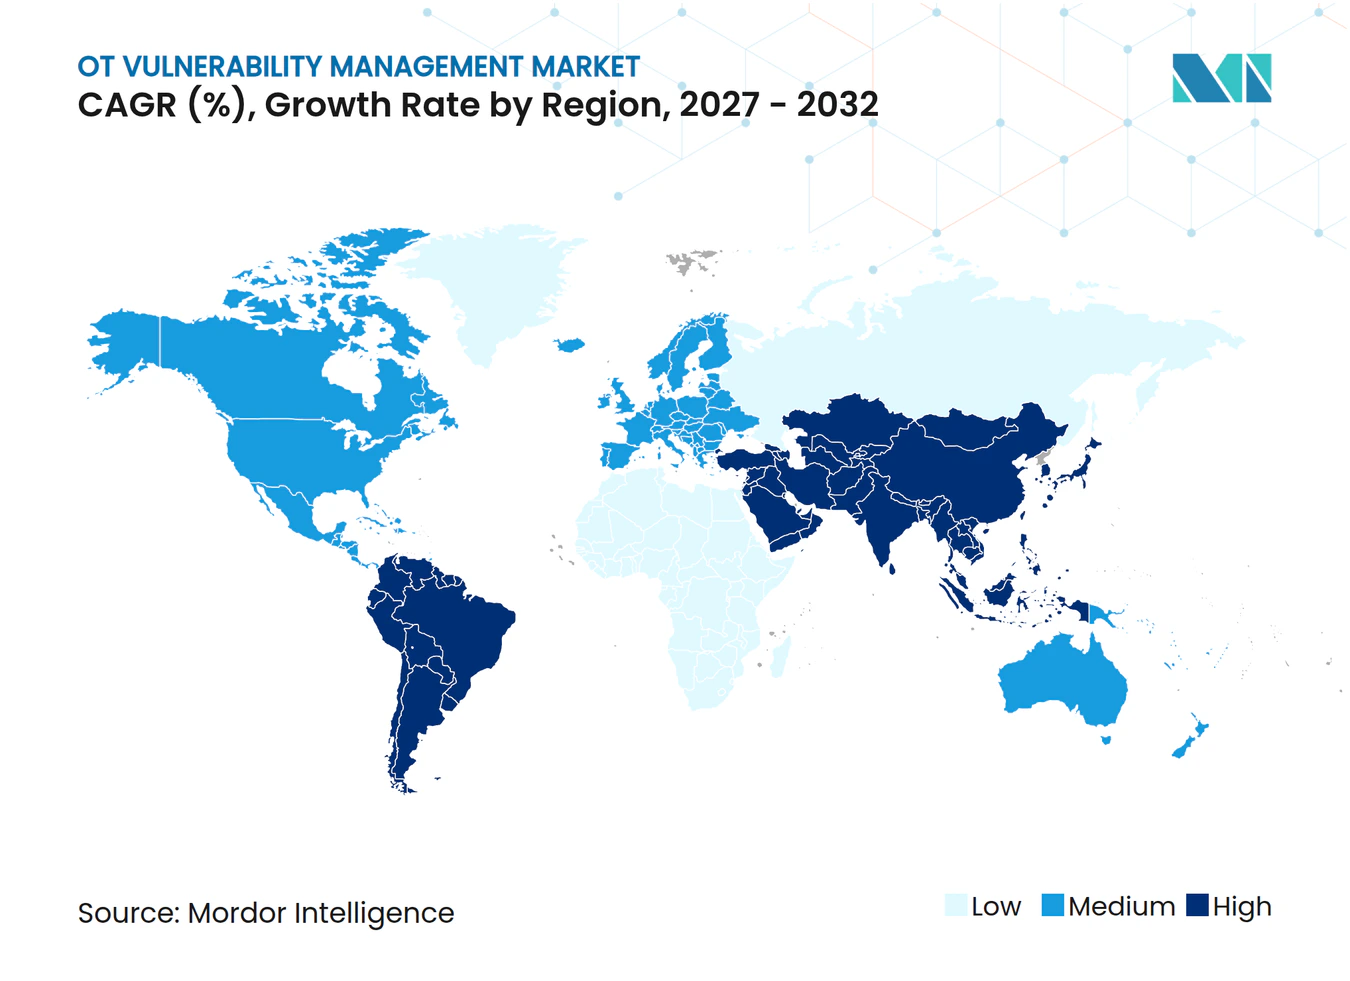
- By geography, North America held 37.45% of the OT vulnerability management market share in 2026, while Asia-Pacific is projected to expand at a 21.36% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of OT Vulnerability Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Cyberattacks Against Critical Infrastructure | +4.2% | Global | Short term (≤ 2 years) |
| IT/OT Convergence Expanding the Attack Surface | +3.8% | Global | Short term (≤ 2 years) |
| Stricter Regulatory and Compliance Requirements | +3.2% | North America and Europe, spill-over to Asia-Pacific | Medium term (2-4 years) |
| Expansion of Industrial Internet of Things Deployments | +2.6% | Global, strongest in Asia-Pacific | Medium term (2-4 years) |
| Increasing Adoption of Risk-Based Vulnerability Prioritization | +2.0% | North America and Europe, spill-over to Asia-Pacific | Medium term (2-4 years) |
| Growing Use of Remote Operations and Third-Party Access | +1.6% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Cyberattacks Against Critical Infrastructure
Threat groups are examining industrial control loops and process configurations in ways that can support physical disruption. Dragos identified Sylvanite, Azurite, and Pyroxene as newly tracked threat groups in its 2026 review. The same review recorded 3,300 ransomware attacks against industrial organizations in 2025, and an average attacker dwell time of 5 days. Forescout reported that attacks using OT-specific protocols increased by 84% in 2025, with Modbus accounting for 57% of this activity. These attacks make it harder for operators to treat security monitoring as a back-office task. The OT vulnerability management market benefits when operators need a clearer view of exposed equipment, weaknesses, and safe mitigation options.
IT/OT Convergence Expanding the Attack Surface
Industrial systems are increasingly connected to enterprise networks, remote support tools, and cloud services. TXOne Networks found that 96% of reported OT security incidents began with an IT-level compromise. Dragos reported that 73% of its incident-response cases involved exploitation or credential reuse through VPNs and jump hosts. This connection creates routes for lateral movement into production environments. It also increases the need to identify assets and prioritize weaknesses based on operational consequences. The OT vulnerability management market is therefore moving toward tools that connect enterprise security signals with plant-level risk decisions.
Stricter Regulatory and Compliance Requirements
Regulatory change is moving vulnerability management from a recommended practice toward a documented responsibility. The Federal Energy Regulatory Commission approved NERC Reliability Standard CIP-003-11 in March 2026, extending mandatory cybersecurity controls to low-impact Bulk Electric System assets. The OT Cyber Coalition has also called for ISA/IEC 62443 to serve as a unifying framework for the United States OT cybersecurity policy. These requirements raise the value of asset inventories, evidence trails, and repeatable assessment methods. They also give suppliers a clearer path to align their offerings with customer procurement requirements. The OT vulnerability management market gains where organizations must show that controls cover systems previously treated as low priority.
Expansion of Industrial Internet of Things Deployments
Connected sensors, edge controllers, and remote monitoring systems are enlarging industrial asset inventories. CISA issued 2,155 ICS-related CVEs across 508 advisories in 2025, according to TXOne Networks' analysis. A CISA, FBI, and NSA advisory documented active exploitation of internet-connected programmable logic controllers used across the United States critical infrastructure.[1] Japan's Ministry of Economy, Trade, and Industry published OT security guidelines for semiconductor device factories in October 2025. These developments expand the range of devices that must be found, assessed, and monitored. The OT vulnerability management market has a greater demand for passive discovery to ensure safety and continuity during assessments.
Restraints Impact Analysis of OT Vulnerability Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Implementation and Lifecycle Costs | -1.2% | Global, most acute among small and medium enterprises in emerging markets | Short term (≤ 2 years) |
| Legacy-System and Proprietary-Protocol Compatibility Limitations | -1.0% | Global, strongest in Europe and Asia-Pacific | Medium term (2-4 years) |
| Shortage of OT-Specific Cybersecurity Talent | -0.8% | Global | Long term (≥ 4 years) |
| Risk of Operational Disruption During Assessment and Remediation | -0.6% | Global, highest in continuous-process industries | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Implementation and Lifecycle Costs
A complete program requires more than platform licenses. Operators may need passive monitoring equipment, network segmentation, consulting support, and internal governance processes. OPSWAT found that only 9% of security professionals dedicate all of their work time to ICS or OT security. This limits deployment depth even when initial funding is available. Equipment replacement cycles and restricted maintenance windows can turn project costs into recurring operational expenses. The OT vulnerability management market must address this constraint through phased deployment, managed services, and models that lower upfront spending.
Legacy-System and Proprietary-Protocol Compatibility Limitations
Many industrial environments contain systems built before modern assessment tools became common. Dragos found that 15% of assessed vulnerabilities had incorrect CVSS severity data and that 64% of those incorrect ratings understated severity. Protocols such as Modbus, PROFINET, and DNP3 often require specialized passive analysis rather than conventional endpoint agents. Vendors must avoid disrupting processes when collecting evidence or testing remediation. This raises engineering effort and can delay adoption at sites with complex, multi-vintage equipment. The OT vulnerability management market depends on suppliers that can provide an accurate assessment without creating production risk.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
OT Vulnerability Management Market Segment Analysis
By Component:
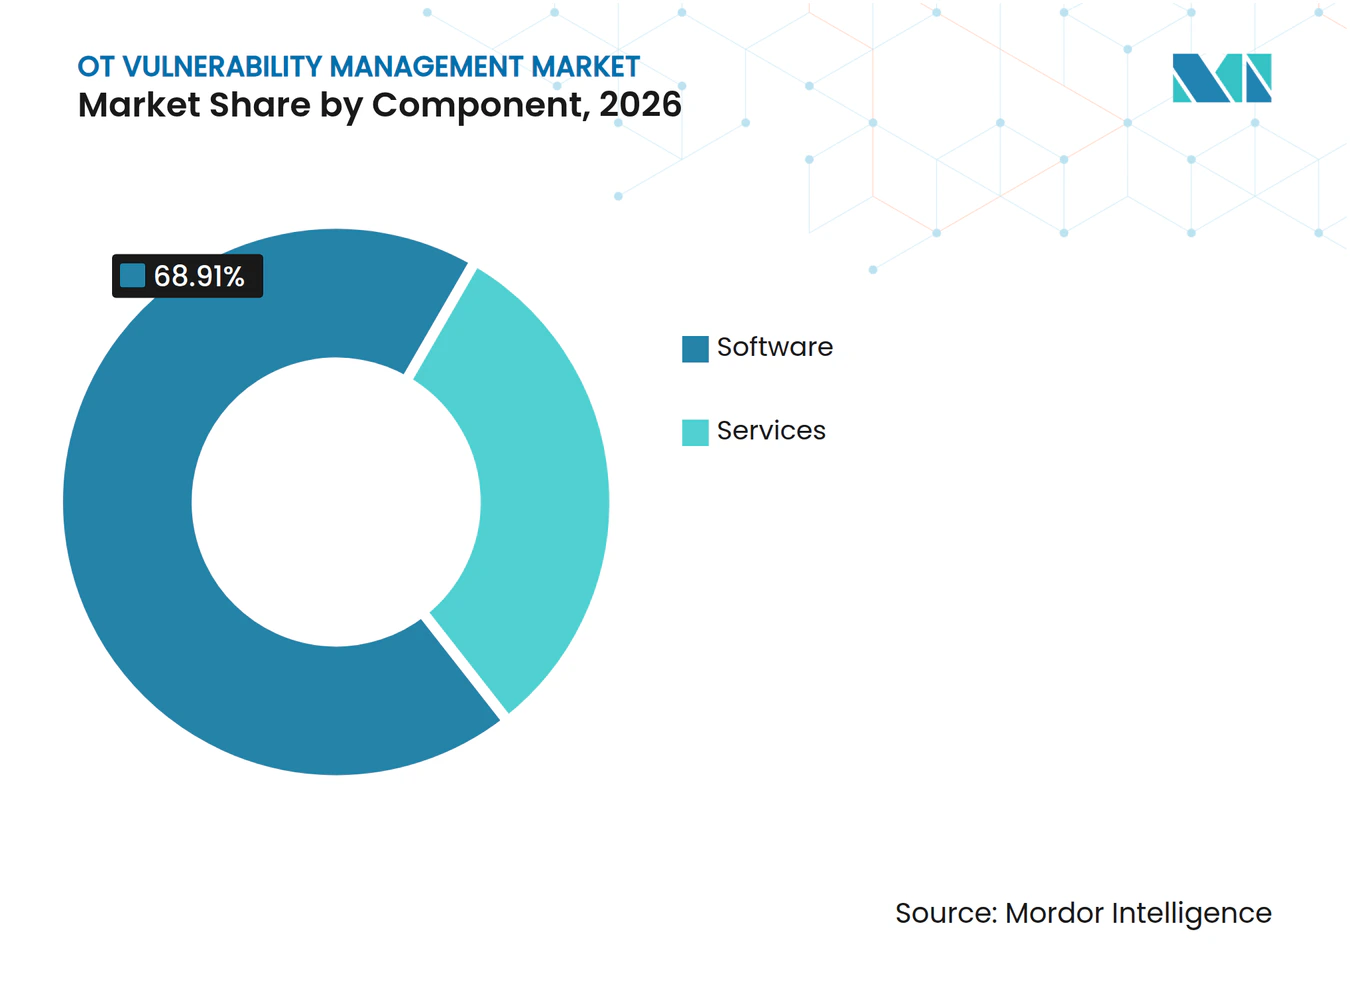
Services Gain Ground as Operators Seek Managed OutcomesSoftware accounted for 68.91% of the component segment in 2026. The segment is supported by enterprise licenses for vulnerability scanning, industrial asset inventories, and patch management consoles integrated with SCADA environments. Replacing an installed platform can require staff retraining, data migration, and changes to operating procedures. This creates meaningful switching friction for established suppliers. The OT vulnerability management industry continues to depend on software as the central layer for asset visibility and workflow control.
Services are projected to expand at a CAGR of 22.39% through 2032. Organizations are using managed assessment, consulting, and incident response support to address internal capability limitations. OPSWAT reported that 55% of organizations increased OT security budgets over 2 years. TXOne Networks introduced its Sennin family in April 2026 to support OT risk assessment and enterprise orchestration. Products that combine technology with program support are narrowing the boundary between software and services.


By Asset Type:
PLCs Lead While Industrial Internet of Things Devices Add ExposureProgrammable logic controllers held 61.29% share of the asset-type segment in 2026. Their broad use in power, manufacturing, and water infrastructure makes them central to many security programs. The April 2026 joint advisory from CISA, the FBI, and the NSA identified Iranian-affiliated activity targeting internet-connected PLCs from Rockwell Automation, Schneider Electric, and Siemens. SCADA systems and distributed control systems form another important group, especially in energy, oil and gas, and chemical operations. Process continuity limits the frequency and method of patching in these environments.
Industrial Internet of Things devices are projected to grow at a CAGR of 21.77% through 2032. Connected sensors and edge controllers extend the security perimeter across factories and utilities. The 2,155 ICS-related CVEs issued in 2025 show the growing volume of weaknesses that must be evaluated. Dragos reported that 52% of reviewed advisories required an alternative mitigation because a vendor patch was unavailable. Operators, therefore, need controls that account for devices remaining in service after their vendor support period ends.
By Deployment Mode:
Cloud Adoption Grows Alongside On-Premises RequirementsOn-premises deployment accounted for 67.44% of the deployment segment in 2026. This position reflects long-standing concern about routing operational data beyond a site or enterprise boundary. Air-gapped design principles and local operational control remain important for critical infrastructure owners. Many installed platforms were designed around individual sites and locally managed data. These factors maintain demand for on-premises deployment in sensitive production settings.
Cloud deployment is projected to grow at a CAGR of 22.06% through 2032. Greenfield facilities and managed-security providers can use cloud-based analytics without replicating infrastructure at every site. Large operators with distributed assets can also bring vulnerability intelligence together through a central platform. Data residency controls will remain important where national or sector rules apply. The OT vulnerability management market will increasingly support hybrid arrangements that keep selected controls local while aggregating risk information elsewhere.
By Organization Size:
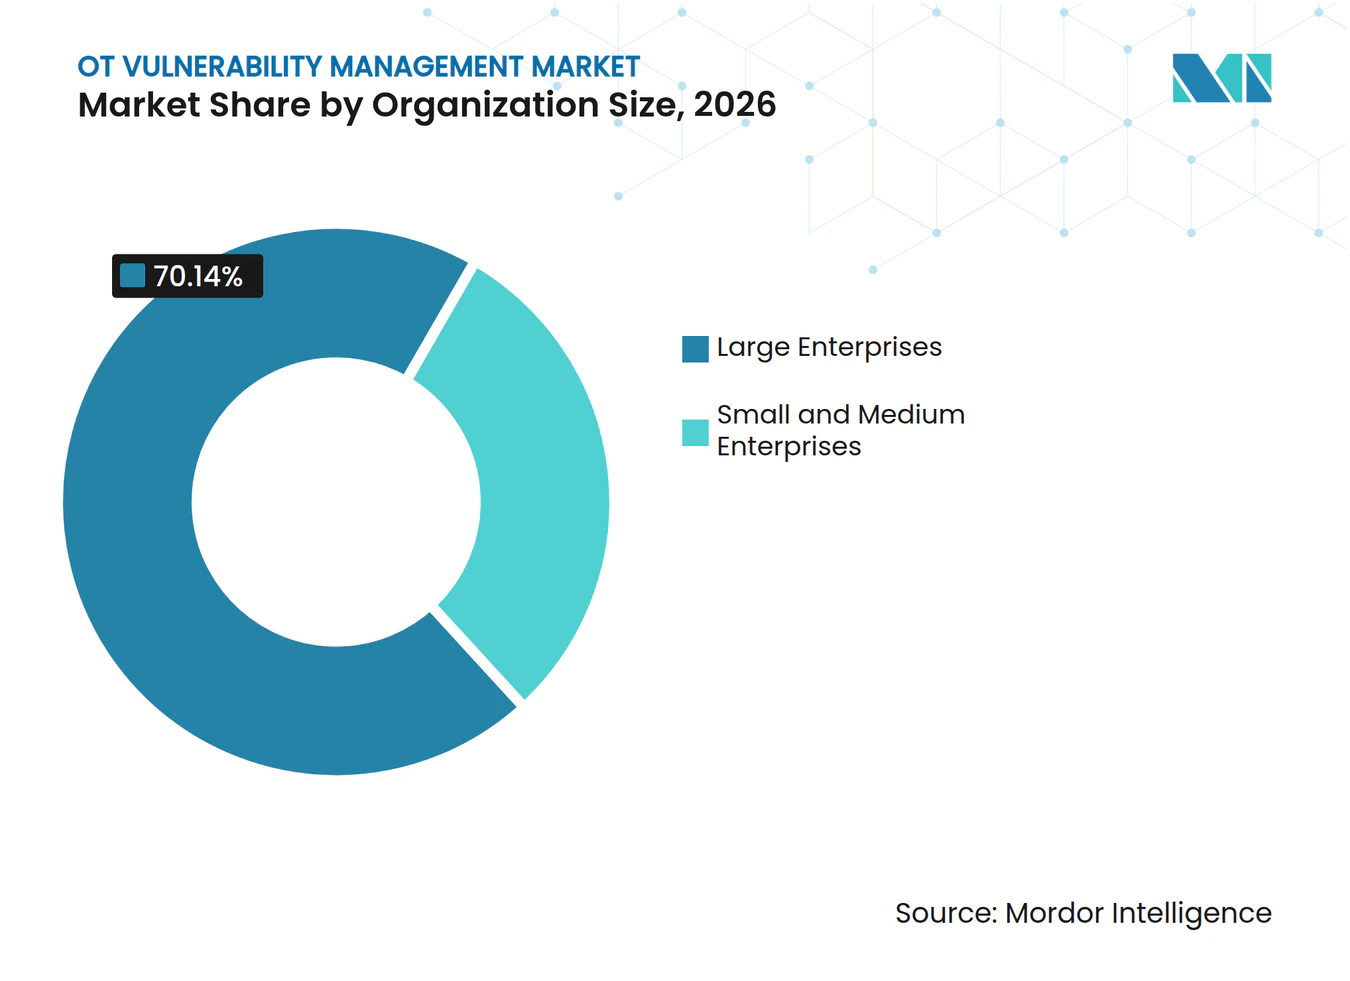
Small and Medium Enterprises Become a Faster-Growth GroupLarge enterprises held 70.14% share of the organization-size segment in 2026. Their greater financial capacity supports broader programs and more frequent assessments. Operators of critical infrastructure also face rules that require ongoing management rather than occasional reviews. Larger organizations commonly operate across several sites, technologies, and suppliers. This complexity supports the demand for centralized vulnerability management.
Small and medium enterprises are projected to expand at a CAGR of 22.70% through 2032. These companies can serve as an entry point to larger production networks when they connect through trusted supplier relationships. The 2026 State of OT Security analysis found that small and medium manufacturing enterprises had the lowest OT security maturity, with weak scores in third-party and vendor access controls. Cloud subscriptions and managed offerings can reduce the barrier to entry for this group. This broadens the potential customer base for the OT vulnerability management market.

By End-User Industry:
Healthcare and Life Sciences Gain Attention Alongside ManufacturingIndustrial manufacturing accounted for 30.12% of the end-user segment in 2026. The sector operates extensive fleets of PLCs, SCADA systems, robotics, and connected production equipment. Dragos reported that manufacturing was the target for more than 50% of observed industrial ransomware attacks.[2] This operating environment makes security weaknesses a direct threat to production schedules and safety procedures. Manufacturers remain a core source of demand for the OT vulnerability management industry.
Healthcare and life sciences are projected to grow at a CAGR of 21.05% through 2032. Connected medical devices, laboratory systems, and building controls are extending the category of assets that require protection. Forescout reported that healthcare moved from the eighth to the fourth most affected sector in 2025. Energy and utilities, oil and gas, transportation, chemicals and pharmaceuticals, and water and wastewater remain additional demand pools. Their buying decisions are shaped by operational criticality, infrastructure investment, and sector-specific rules.
Geography Analysis
The Americas OT Vulnerability Management Market
North America held 37.45% of the OT vulnerability management market share in 2026. The region combines dense critical infrastructure with a regulatory environment that supports continuous security posture management. FERC's approval of CIP-003-11 extends mandatory cybersecurity controls to low-impact Bulk Electric System assets.[3] Canada's National Cyber Threat Assessment states that state-sponsored actors are probing internet-connected OT systems in critical infrastructure. South America is an emerging demand area, supported by oil and gas infrastructure in Brazil and industrial activity in Argentina and Chile.
APAC OT Vulnerability Management Market
Asia-Pacific is projected to expand at a CAGR of 21.36% through 2032. Industrialization, smart-manufacturing investment, and government security programs are increasing the need for automated asset discovery and vulnerability assessment. Japan issued its OT Security Guidelines for Semiconductor Device Factories in October 2025, using SEMI E187, SEMI E188, and NIST Cybersecurity Framework 2.0 as reference points. China's Industrial Internet Platform programs and India's Production Linked Incentive schemes are contributing to connected industrial deployments. South Korea's semiconductor and electronics sites are an important demand group.
Europe OT Vulnerability Management Market
Europe represents a substantial share of the OT vulnerability management market in 2026. NIS2 obligations and Cyber Resilience Act requirements are encouraging operators and product suppliers to formalize vulnerability processes. The German Federal Office for Information Security reported 119 new IT and OT vulnerabilities each day in 2025, a 24% increase from the prior year. Germany is the region's largest demand center because of its manufacturing base and connected industrial equipment. The United Kingdom is advancing its Cyber Security and Resilience Bill. France, Italy, and Benelux provide further demand through manufacturing and energy operations.
Competitive Landscape
Market Concentration
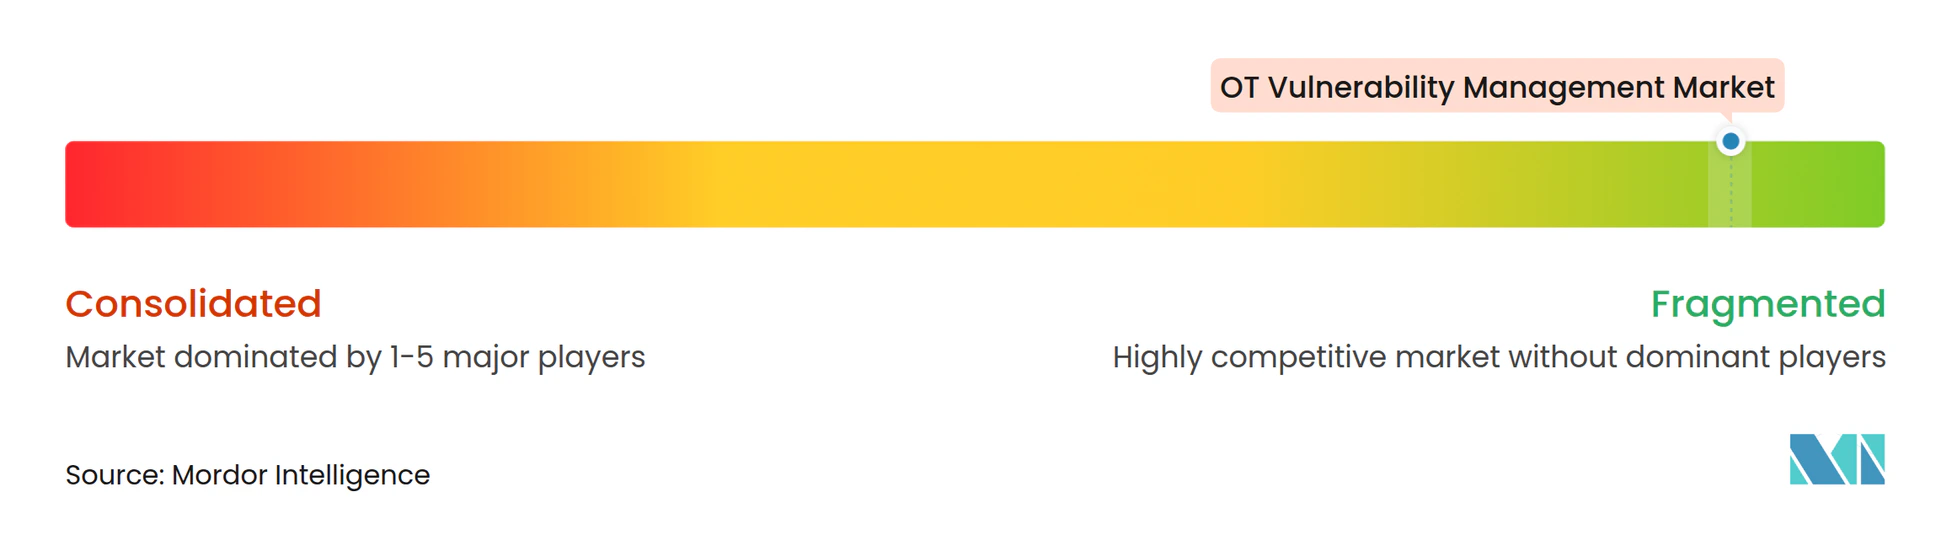
The OT vulnerability management market remains fragmented, with more than 20 specialist vendors alongside industrial technology companies and broader security platforms. Specialists developed capabilities in industrial protocols, passive scanning, and operational safety that general IT security products did not initially provide. Competition is now shifting toward platform coverage, compliance documentation, and managed delivery. Accenture agreed in June 2026 to acquire a majority stake in Dragos, as well as all of runZero and NetRise, for a combined enterprise value of USD 4.175 billion. The transaction reflects buyer demand for an integrated approach across IT, OT, cloud, and connected-device environments.
Mitsubishi Electric completed its acquisition of Nozomi Networks in January 2026, while Nozomi retained a vendor-neutral product roadmap. Nozomi served 5 of the top 10 oil and gas companies and 7 of the top 10 utilities globally at the time of closing. Claroty raised USD 150 million in Series F funding in January 2026 to expand its cyber-physical systems protection platform.[4] In June 2026, Claroty added microsegmentation integrations with Akamai, ColorTokens, Corsha, Elisity, and Zero Networks. These moves show vendors extending beyond detection into enforcement and containment.
Suppliers are also investing in firmware analysis, software bill-of-materials generation, and control-loop mapping. This makes risk reduction, rather than vulnerability detection alone, a more important basis for competition. ISA/IEC 62443 is gaining relevance in regulated procurement because it provides a common reference for security requirements. Healthcare, transportation, and water and wastewater remain areas where specialized solutions can address sector-specific asset profiles and operating constraints.
OT Vulnerability Management Industry Leaders
-
Claroty Ltd.
-
Dragos, Inc.
-
Nozomi Networks Inc.
-
Waterfall Security Solutions Ltd.
-
Radiflow Ltd.
- *Disclaimer: Major Players sorted in no particular order
OT Vulnerability Management Market Companies Covered in this Report
- Claroty Ltd.
- Dragos, Inc.
- Nozomi Networks Inc.
- Radiflow Ltd.
- Waterfall Security Solutions Ltd.
- TXOne Networks Inc.
- Mission Secure, Inc.
- Opscura, Inc.
- Otorio Ltd.
- Shift5, Inc.
- Applied Risk B.V.
- Verve Industrial Protection
- Rhebo GmbH
- Industrial Defender, Inc.
- Fortress Information Security, Inc.
- S2 Group, Inc.
- Cyberbit Ltd.
- Veracity Networks
- SecurityGate.io
- Shieldworkz Inc.
Recent Industry Developments in OT Vulnerability Management Market
- September 2026: Dragos, Inc. officially completed the acquisitions of runZero and NetRise following the close of Accenture's majority investment. The combined extended OT (xOT) platform delivers integrated asset visibility, firmware and software supply-chain analysis, and OT threat detection across IT, OT, cloud, and connected-device environments, supporting NERC CIP and NIS2 audit-evidence workflows.
- July 2026: Claroty announced a partnership with Frenos, an AI-native simulated OT penetration-testing company, enabling continuous adversarial validation of defensive posture and risk-prioritized remediation based on demonstrated exploitability of detected vulnerabilities within the Claroty Platform for industrial environments.
- June 2026: Accenture announced an agreement to acquire a majority stake in Dragos and 100% of runZero and NetRise at a combined enterprise value of approximately USD 4.175 billion, forming an end-to-end OT security platform spanning critical infrastructure, including power grids, pipelines, manufacturing facilities, and data centers.
- June 2026: Claroty announced microsegmentation technology integrations with Akamai, ColorTokens, Corsha, Elisity, and Zero Networks through its Technology Alliances Program, extending lateral-movement containment capabilities across industrial CPS environments.
Global OT Vulnerability Management Market Report Scope
The OT Vulnerability Management Market comprises revenues generated from software solutions and services used to identify, assess, prioritize, monitor, and remediate cybersecurity vulnerabilities across operational technology (OT) environments, industrial control systems (ICS), industrial IoT devices, and critical infrastructure assets. These solutions provide vulnerability discovery, risk-based prioritization, exposure analysis, remediation management, and continuous vulnerability monitoring capabilities to reduce cyber risk and improve operational resilience. The market supports security and compliance initiatives across industrial networks, control systems, production environments, and connected operational assets while minimizing disruption to industrial operations.
The OT Vulnerability Management Market Report is Segmented by Component (Software, and Services), Asset Type (Programmable Logic Controllers, Supervisory Control and Data Acquisition Systems, Distributed Control Systems, Industrial IoT Devices, and Other Asset Types), Deployment Mode (On-Premises, and Cloud), Organization Size (Large Enterprises, and Small and Medium Enterprises), End-User Industry (Industrial Manufacturing, Energy and Utilities, Oil and Gas, Transportation and Logistics, Chemicals and Pharmaceuticals, Water and Wastewater, Healthcare and Life Sciences, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Software |
| Services |
| Programmable Logic Controllers |
| Supervisory Control and Data Acquisition Systems |
| Distributed Control Systems |
| Industrial IoT Devices |
| Other Asset Types |
| On-Premises |
| Cloud |
| Large Enterprises |
| Small and Medium Enterprises |
| Industrial Manufacturing |
| Energy and Utilities |
| Oil and Gas |
| Transportation and Logistics |
| Chemicals and Pharmaceuticals |
| Water and Wastewater |
| Healthcare and Life Sciences |
| Other End-User Industries |
| North America | United States |
| Canada | |
| South America | Brazil |
| Argentina | |
| Mexico | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Component | Software | |
| Services | ||
| By Asset Type | Programmable Logic Controllers | |
| Supervisory Control and Data Acquisition Systems | ||
| Distributed Control Systems | ||
| Industrial IoT Devices | ||
| Other Asset Types | ||
| By Deployment Mode | On-Premises | |
| Cloud | ||
| By Organization Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By End-User Industry | Industrial Manufacturing | |
| Energy and Utilities | ||
| Oil and Gas | ||
| Transportation and Logistics | ||
| Chemicals and Pharmaceuticals | ||
| Water and Wastewater | ||
| Healthcare and Life Sciences | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| South America | Brazil | |
| Argentina | ||
| Mexico | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the OT vulnerability management market?
The market is valued at USD 3.10 billion in 2026 and is projected to reach USD 9.40 billion by 2032, at a CAGR of 20.48% from 2027 to 2032.
What is driving demand for OT vulnerability management?
Rising attacks on critical infrastructure, IT and OT convergence, regulatory requirements, and connected industrial devices are driving demand.
Which component leads OT vulnerability management spending?
Software leads with 68.91% share in 2026, while services are projected to grow faster at a 22.39% CAGR through 2032.
Which deployment model is growing faster?
Cloud deployment is projected to grow at a 22.06% CAGR through 2032, although on-premises deployment holds 67.44% share in 2026.
Which end-user sector is expanding fastest?
Healthcare and life sciences is projected to grow at a 21.05% CAGR through 2032 as connected medical and laboratory assets require stronger protection.
Which region is expanding fastest?
Asia-Pacific is projected to grow at a 21.36% CAGR through 2032, supported by industrial digitalization and government security programs.