
Managed UCaaS Operations Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 3.92 Billion |
| Market Size (2032) | USD 7.43 Billion |
| Growth Rate (2027 - 2032) | 13.64 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed UCaaS Operations Services Market Analysis by Mordor Intelligence
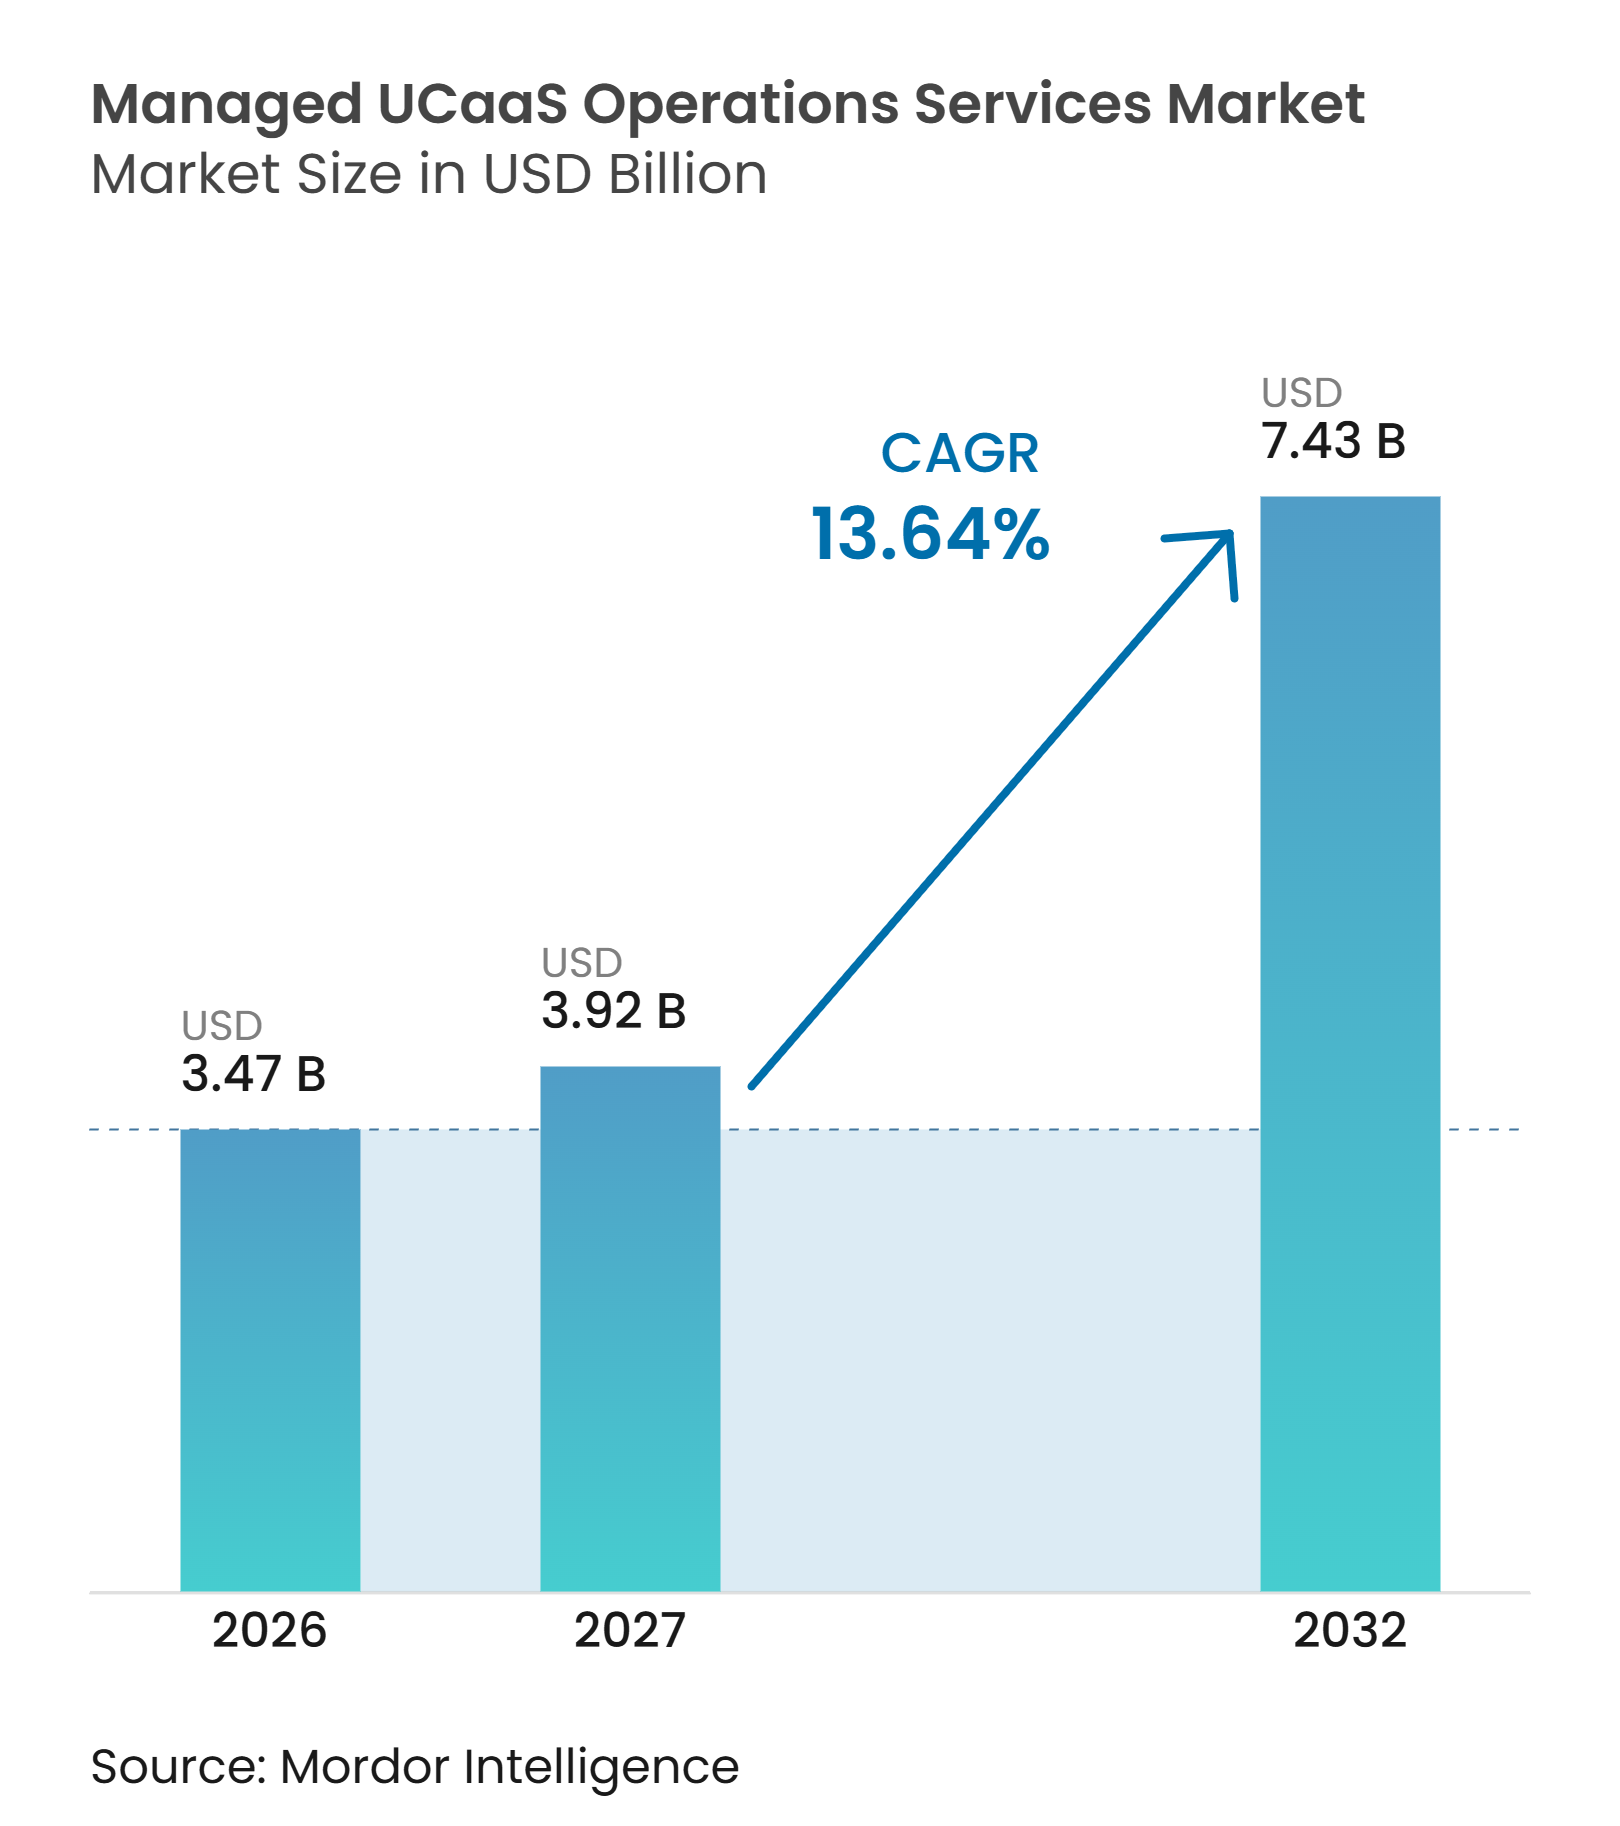
The managed UCaaS operations services market size is projected to expand from USD 3.47 billion in 2026 and USD 3.92 billion in 2027 to USD 7.43 billion by 2032, registering a CAGR of 13.64% between 2027 to 2032. The managed UCaaS operations services market is moving beyond platform deployment toward outsourced provisioning, monitoring, security, analytics, and carrier interconnection. Hybrid work has widened the number of locations, networks, and devices that communications teams must support. Legacy PBX replacement also creates demand for providers that can manage migration without interrupting voice services. Providers are broadening contracts as enterprises link employee communications with contact center operations. Automation can improve service delivery capacity, although skilled staff and security controls remain important limits on growth.
Key Report Takeaways
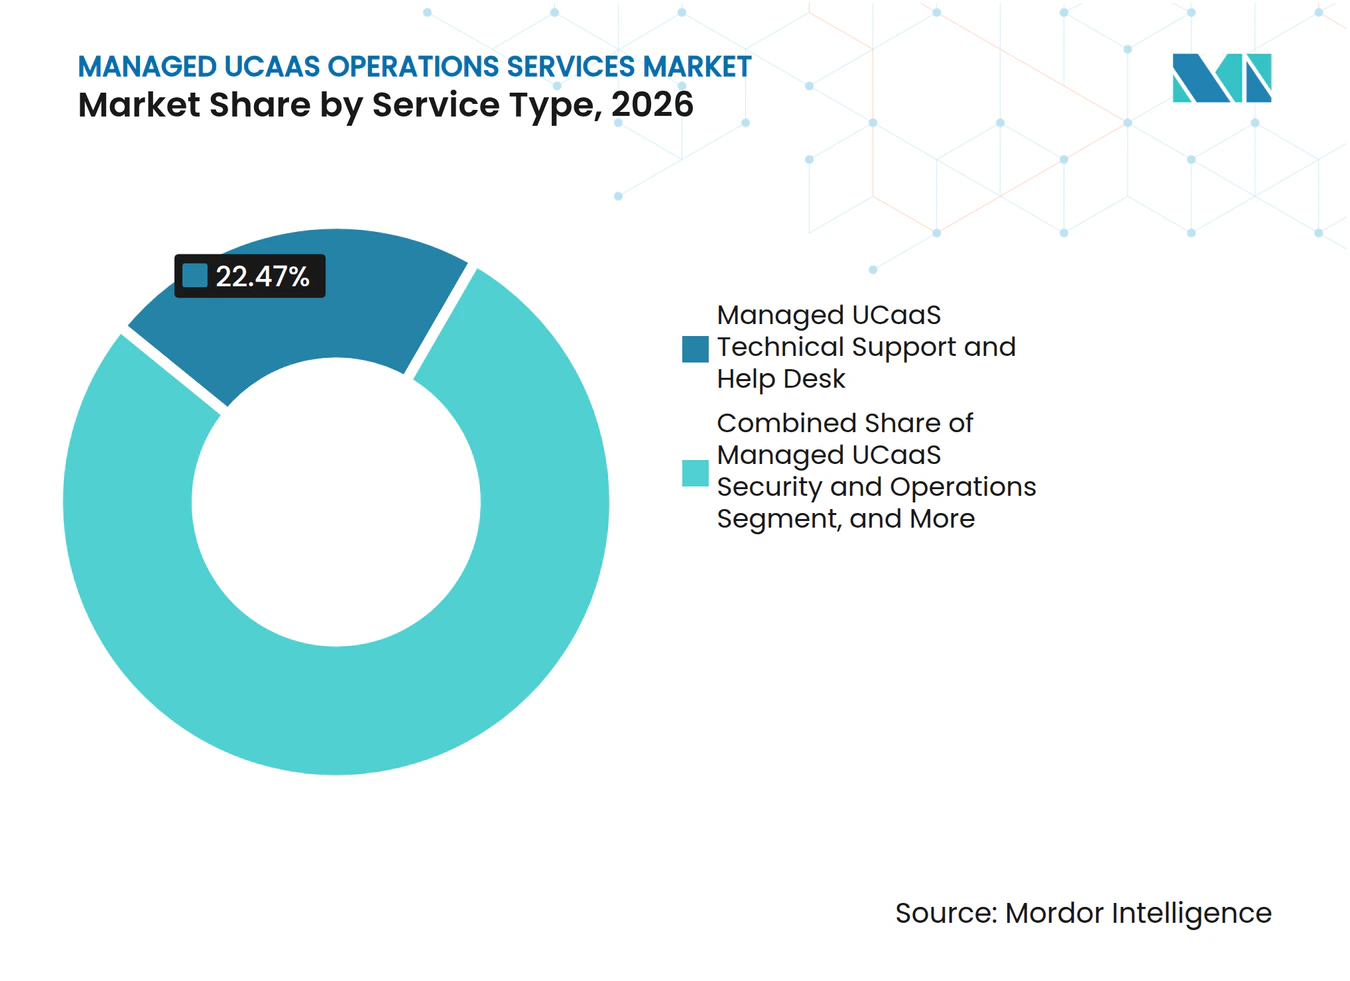
- By service type, technical support and help desk services held 22.47% of the managed UCaaS operations services market share in 2026, while analytics and optimization services are projected to expand at a 14.83% CAGR through 2032.
- By enterprise size, large enterprises accounted for 64.37% of revenue in 2026, while SMEs are expected to record the highest CAGR of 14.42% through 2032.
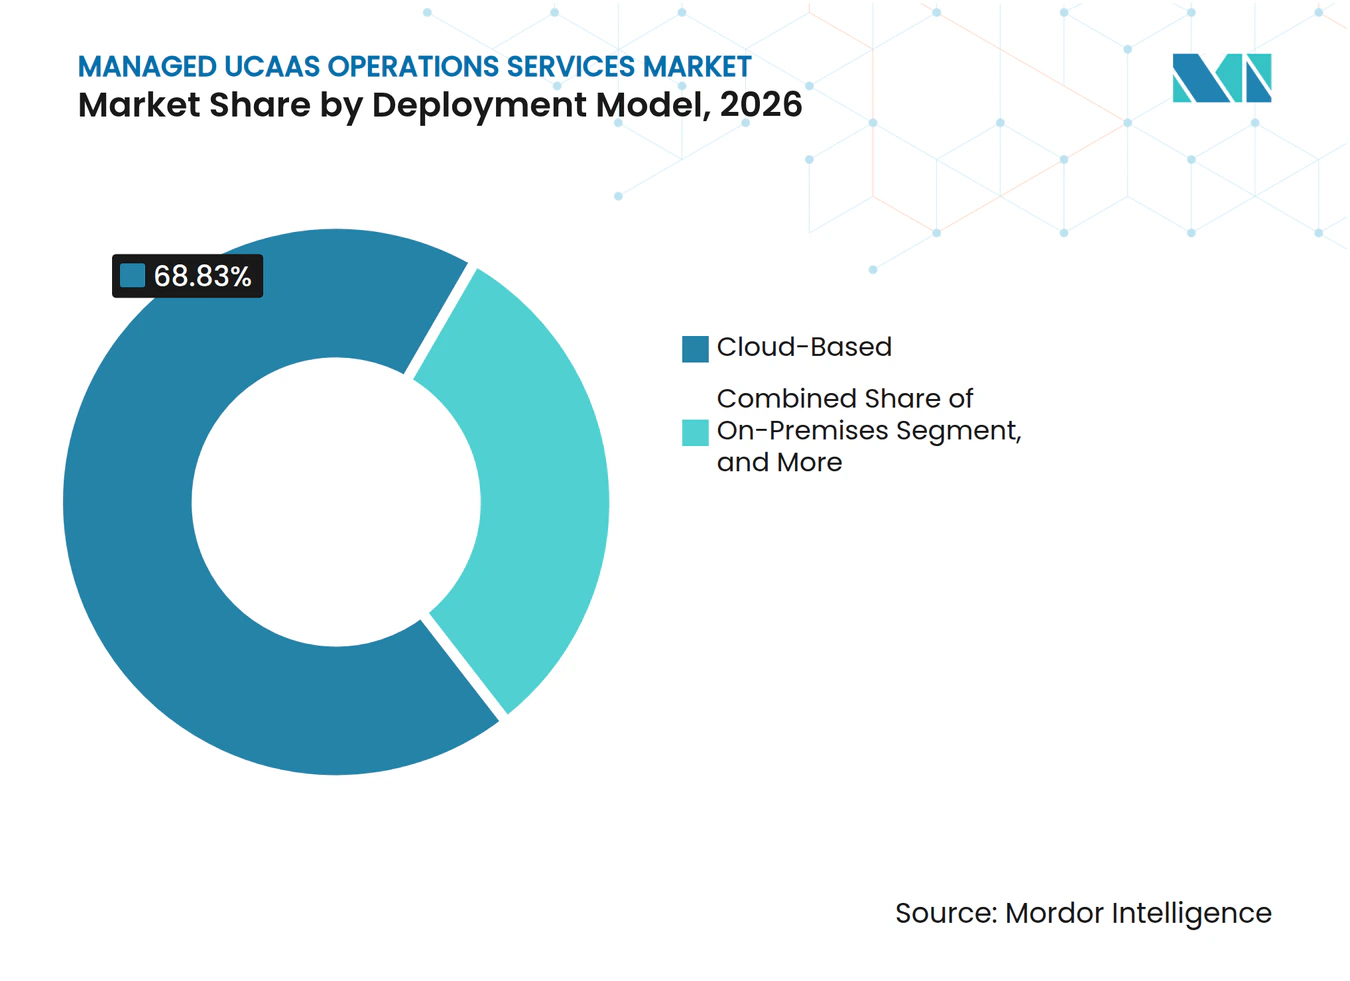
- By deployment model, cloud-based deployments accounted for 68.83% of the managed UCaaS operations services market in 2026, while hybrid deployments are projected to grow at a 14.27% CAGR through 2032.
- By end-user industry, information technology and telecommunications accounted for 24.63% of revenue in 2026, while healthcare is projected to grow at a 14.63% CAGR through 2032.
- By geography, North America held 38.27% of revenue in 2026, while Asia-Pacific is expected to expand at a 14.52% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed UCaaS Operations Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hybrid Work and Distributed Workforce Expansion | +3.5% | Global, with concentration in North America and Western Europe | Short term (≤ 2 years) |
| Cloud Migration and Legacy PBX Modernization | +2.8% | Global, with early gains in North America and Asia-Pacific | Medium term (2-4 years) |
| UCaaS Integration With Contact Center and Communications Platforms | +2.0% | North America and EU | Short term (≤ 2 years) |
| AI-Enabled Administration, Analytics, and Employee Assistance | +1.8% | Global, with North America and Asia-Pacific as primary adoption markets | Medium term (2-4 years) |
| Rising Demand for Outcome-Based Communications Operations | +1.5% | Global | Medium term (2-4 years) |
| Localization Through Direct Routing, Local Cloud Zones, and Carrier Interconnection | +0.8% | Asia-Pacific core, with spillover to the Middle East and South America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Hybrid Work and Distributed Workforce Expansion
Enterprise communications now span offices, home locations, branches, and mobile devices. This operating model raises the burden of provisioning, troubleshooting, and applying consistent policies. The managed UCaaS operations services market benefits when internal IT teams cannot provide 24/7 assurance across those environments. Large organizations increasingly seek single accountability for service levels across platform, network, and endpoint layers. Residential connectivity and inconsistent device settings can create localized voice-quality issues that are harder to isolate than a data-center outage. Sangoma identified hybrid UCaaS procurement requirements that include stronger uptime expectations and operational controls, which support the role of managed providers in distributed deployments.
Cloud Migration and Legacy PBX Modernization
PBX replacement remains a practical source of managed migration work. Enterprises must retire older call-control systems while maintaining service continuity for employees, customers, and emergency calling. The managed UCaaS operations services market, therefore, benefits from providers that can coordinate migration, testing, and post-cutover support across several platforms. Mid-sized organizations often retain a mix of Cisco, Mitel, Avaya, and newer cloud tools during this transition. This mix requires cross-platform administration rather than a single vendor configuration skill. NUWAVE introduced its Teleport capability in January 2025 to automate PBX migration across Microsoft Teams, Cisco Webex, and Zoom, showing how repeatable migration work can be delivered through a more standardized model.
UCaaS Integration with Contact Center and Communications Platforms
The boundary between employee collaboration and customer communications is becoming less distinct. Enterprises increasingly want a provider to manage unified communications and contact center operations under one service agreement. This model can bring presence, recording, analytics, and support workflows into a common operating structure. The managed UCaaS operations services market broadens in scope when the provider assumes accountability across both communications environments. RingCentral launched Customer Journey Analytics in June 2025 to provide visibility across UCaaS and CCaaS environments, and made its AI Agent Assist generally available for customer service use.[1] RingCentral and Spectrum Business expanded their partnership in March 2026 to offer contact center and conversation intelligence capabilities over a managed network, illustrating a broader managed-service boundary.
AI-Enabled Administration, Analytics, and Employee Assistance
AI tools are changing routine administrative work in communications operations. Providers can use these tools to search usage records, identify recurring incidents, and support configuration tasks. The managed UCaaS operations services market can gain from lower resolution times and greater delivery capacity per technician. The value is greater when an operator can assess data across multiple communication platforms. Cisco described AI-based capabilities for natural-language reporting, issue remediation, and search within Webex Control Hub in 2025. Oracle also introduced its Intelligent Communications Orchestration Network Cloud Service in October 2025, bringing UCaaS, CCaaS, and voice AI services into a common orchestration layer.
Restraints Impact Analysis of Managed UCaaS Operations Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Multi-Vendor UC Stack Skills Shortage | -0.9% | Global, with acute pressure in North America and Europe | Medium term (2-4 years) |
| Toll Fraud, SIP Trunk Abuse, and Identity-Based Attacks | -0.7% | Global | Short term (≤ 2 years) |
| Public Internet Voice-Quality Variability | -0.5% | Asia-Pacific core, South America, and Africa | Long term (≥ 4 years) |
| Data Sovereignty and Cross-Border Compliance Complexity | -0.4% | EU, Middle East, and Asia-Pacific national markets | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Multi-Vendor UC Stack Skills Shortage
The shortage of professionals capable of operating multiple UC platforms can limit delivery capacity. A single enterprise account may combine Microsoft Teams, Cisco Webex, Zoom, SIP trunks, and older voice infrastructure. Each environment has separate administration controls, monitoring tools, and security settings. The managed UCaaS operations services market depends on providers capable of maintaining certification and operational depth across this mix. Providers with limited expertise may need to narrow their scope of services or rely on specialist partners. Continuant's acquisition of Fidelus in 2025 added Cisco-focused managed services to its Microsoft Teams practice, which shows why broader platform capability has strategic value
Toll Fraud, SIP Trunk Abuse, and Identity-Based Attacks
Fraud and unauthorized changes can create material exposure in shared voice environments. A configuration weakness may enable expensive calling activity before normal monitoring identifies the issue. The managed UCaaS operations services market must therefore include tighter controls for access, provisioning, and SIP traffic. Voice operations also need to align with caller-identity requirements that affect call completion and regulatory compliance. BroadSource released its EMU CAPP tool in July 2025 to detect and reverse unauthorized configuration changes in BroadWorks environments. Providers that have not standardized detection and response practices can face higher delivery costs and lower contract margins.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed UCaaS Operations Services Market Segment Analysis
By Service Type:
Help Desk Supports Revenue While Analytics ExpandsTechnical support and help desk services accounted for 22.47% of revenue in 2026, making them the largest service category, as voice incidents, license issues, carrier coordination, and user escalations still require human judgment even when self-service tools are available. These contracts are often the first managed engagement for an enterprise, giving providers a route to add migration, administration, monitoring, security, and carrier operations as the customer’s requirements become clearer. The service category also reflects the need to resolve issues across multiple platforms and endpoint types, rather than only within a single vendor application. Migration and implementation work benefits from PBX retirement, while administration and monitoring are shifting from reactive incident work toward predictive operating practices.
Analytics and optimization services are projected to grow at a 14.83% CAGR through 2032 as organizations seek support in translating quality-of-experience data, adoption metrics, and call costs into operational decisions. This demand supports the managed UCaaS operations services market because many organizations lack a dedicated communications analytics function capable of interpreting data spanning platforms, networks, devices, and carrier services. Natural-language reporting can give customers more direct access to data, but it does not remove the need to identify causes or assign responsibility when issues cross vendor boundaries. Cisco’s 2025 collaboration updates included AI-supported reporting and search capabilities that reflect this change in service delivery.



By Enterprise Size:
Large Enterprises Lead While SMEs Add VolumeLarge enterprises accounted for 64.37% of revenue in 2026, reflecting the operational burden of estates with many sites, multiple communications tools, formal security requirements, and regional service commitments. These organizations use managed services to transfer operational risk and reduce internal workloads, and their contracts can cover platform integration, carrier interconnection, compliance monitoring, analytics, and support coordination. Large enterprise demand provides the managed UCaaS operations services market with a stable base, as a communications outage can disrupt extensive employee and customer operations. Providers with broad delivery coverage can offer a single accountable service model across regional locations.
SMEs are projected to grow at a 14.42% CAGR through 2032, supported by subscription bundles that make managed communications easier to adopt without a large internal support team. Channel partners can package platform licenses, operations, and local support for smaller organizations that want a simpler purchasing and implementation process. RingCentral introduced the Empower wholesale program in 2026 to help partners sell UCaaS, CCaaS, and AI services through their own commercial arrangements. This route can expand the customer base while reducing average contract values, which raises the need for standardized processes and automated provisioning. Providers that automate monitoring and first-line support are better placed to manage a larger group of smaller customers without weakening service quality.
By Deployment Model:
Cloud Is the Volume Base While Hybrid Requires Broader OperationsCloud-based deployments accounted for 68.83% of revenue in 2026 and constitute the main installed base for the managed UCaaS operations services market. On-premises systems continue to serve some defense, manufacturing, and government users with strict continuity, latency, data, or local-control requirements, so providers must operate both cloud tools and residual infrastructure. Spain’s data protection authority stated in 2026 that data residency alone does not confer operational sovereignty, making the availability and control of supporting architecture relevant to service design. A full transition may therefore take time, where enterprise risk, regulatory obligations, or existing investments prevent a move to a single cloud environment.
Hybrid deployments are projected to grow at a 14.27% CAGR through 2032 because enterprises may combine public cloud platforms, local call control, session border controllers, PSTN gateways, and backup connectivity during a phased transition. Each component creates a separate management and compliance responsibility, resulting in a broader operational perimeter than a purely cloud-based or entirely on-premises deployment. Sangoma cited cellular backup, caller-identity controls, and Teams-compatible SIP architectures among the factors shaping hybrid UCaaS adoption. This complexity gives providers a basis for service scopes that reflect the full environment instead of only the application layer. The managed UCaaS operations services market gains where operators can coordinate the dependencies between cloud platforms, local equipment, and carrier networks.

By End-User Industry:
IT and Telecom Leads While Healthcare AcceleratesInformation technology and telecommunications accounted for 24.63% of revenue in 2026, driven by dense UC environments, multi-cloud operations, and the need for specialized management of communications infrastructure. These users may require platform integration, carrier links, compliance monitoring, analytics, and service levels tied to user experience rather than infrastructure availability alone. The managed UCaaS operations services market benefits from providers' ability to coordinate these connected responsibilities across internal and external teams. Manufacturing, retail and e-commerce, government, and defense add demand with different security, purchasing, and implementation requirements.
Healthcare is projected to expand at a 14.63% CAGR through 2032 as providers replace older telephony systems with cloud-based tools that integrate with care and scheduling workflows. Healthcare contracts may require audit logs, encrypted recordings, and role-based access controls to be built into routine service delivery. Ellit Groups and Talkdesk announced a healthcare service-desk partnership in February 2026 that connected managed contact center services with Epic, Oracle Health, Athenahealth, and ServiceNow.[2] These workflow and compliance requirements can favor specialized providers over general communications operators. The managed UCaaS operations services market has room for providers that combine clinical workflow knowledge with communications management.
Geography Analysis
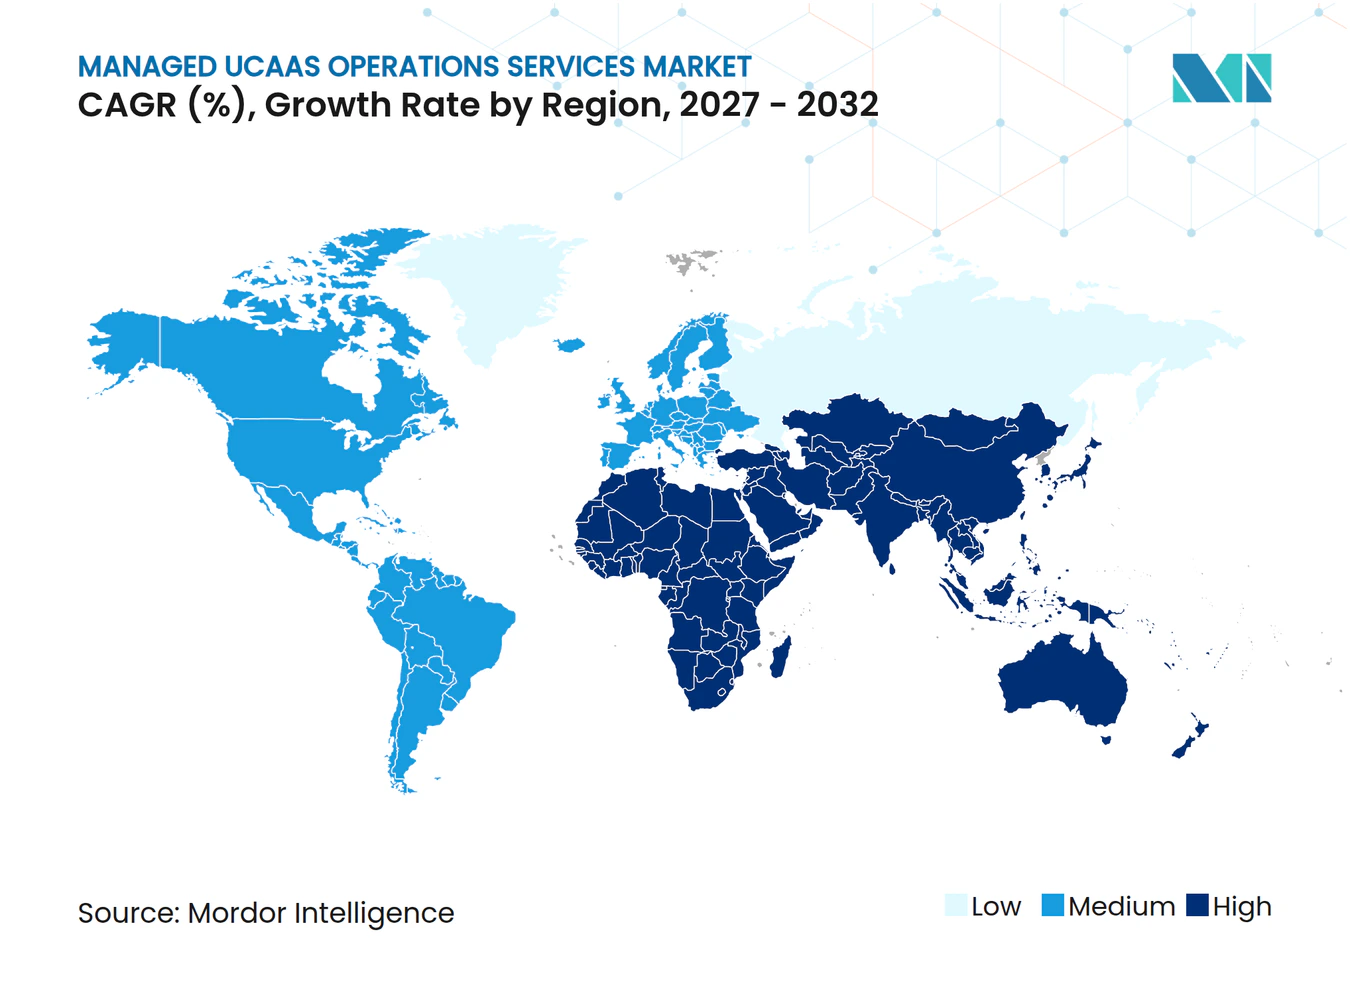
North America accounted for 38.27% of revenue in 2026, the largest regional share in the managed UCaaS operations services market, supported by large enterprise deployments and an established managed services channel. Emergency calling and caller-identity requirements add operational responsibilities to voice deployments, while the United States also has a large base of older PBX infrastructure that requires migration support. Canada and Mexico contribute to regional demand through bundled connectivity and communications offers, particularly when providers can combine local service delivery with broader network coverage. Scale providers can bring network assurance, carrier interconnection, and UC operations together under a single service agreement. This regional operating model remains attractive to organizations that need clear responsibility for communications performance across numerous locations.
Asia-Pacific is projected to grow at a 14.52% CAGR through 2032, the fastest regional rate, with mature environments in Japan, Australia, India, and South Korea, and wider expansion across Southeast Asia. Managed delivery must adapt to varying carrier rules, cloud locations, and data requirements across countries, so providers cannot assume that a single regional design will fit every market. Zoom added local Thai-language numbers and AI features for Zoom Phone and Zoom Contact Center in December 2025, showing the importance of localized service design. Tata Communications reported digital portfolio revenue growth in its first quarter of fiscal 2026, supported by integrated collaboration and managed UCaaS activity.
Europe remains a meaningful revenue contributor, led by the United Kingdom, Germany, and France, where privacy rules and operational sovereignty concerns are shaping provider selection in regulated sectors. The AEPD’s 2026 guidance placed attention on service availability and control of supporting infrastructure as well as data location. The managed UCaaS operations services market in these countries can therefore favor contracts that specify the governance, resilience, and technical dependencies of the wider service, rather than treating hosting location as the sole indicator of control. The Middle East is developing through digital transformation programs in Saudi Arabia and the UAE, while local data requirements can influence contract design. African demand is concentrated in South Africa, Egypt, and Nigeria, although connectivity gaps continue to limit demand in other markets.
Competitive Landscape
Market Concentration
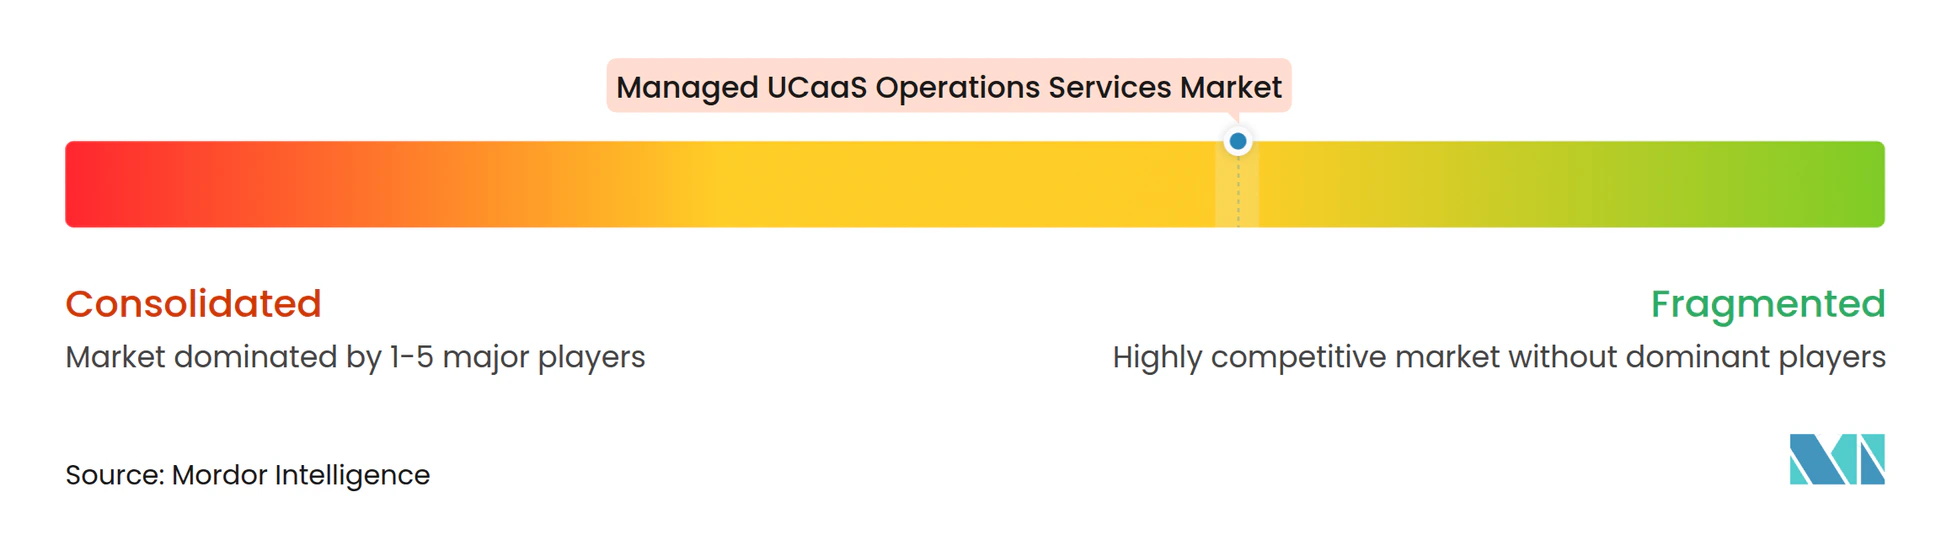
The managed UCaaS operations services market is moderately fragmented, with telecom carriers, IT services providers, and platform-native managed providers competing across overlapping service areas. Verizon Communications, ATandT Inc., Deutsche Telekom AG, NTT Communications Corporation, and Vodafone Group Plc can combine connectivity, voice assurance, carrier interconnection, and UC operations under a single agreement. Kyndryl and other IT services firms compete through broader enterprise technology operations and automation. Court Square Capital Partners acquired CallTower in April 2026, which reflects continued interest in providers with multi-platform managed communications capabilities. Network reach, certifications, and global delivery capacity remain material advantages for the largest suppliers.
Providers are differentiating through automation and contact center integration. Cisco’s AI collaboration work supports partner use of automated task execution and operational intelligence across connected business systems. RingCentral and Spectrum Business expanded their managed contact center partnership in March 2026, combining customer experience tools and managed network delivery. NetSpeek introduced Lena in October 2025 for multi-vendor AV and UC operations using natural-language automation.[3] The managed UCaaS operations services market favors firms that can turn these tools into consistent operational quality.
Healthcare and SME customers offer distinct opportunities for competitive positioning, since healthcare requires controls and workflow integration while SMEs often buy partner-packaged subscriptions and support. European buyers may favor providers that can address privacy, local hosting, and operational sovereignty requirements. The managed UCaaS operations services market therefore rewards firms that specialize by vertical, geography, or platform mix instead of competing only on basic support. In this managed UCaaS operations services market, a smaller provider can compete where its local relationships, platform skills, and specialized operations address a defined customer need that broader providers may not prioritize.
Managed UCaaS Operations Services Industry Leaders
-
Microsoft Corporation
-
Cisco Systems, Inc.
-
Zoom Video Communications, Inc.
-
RingCentral, Inc.
-
Verizon Communications Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed UCaaS Operations Services Market Companies Covered in this Report
- Microsoft Corporation
- Cisco Systems, Inc.
- Zoom Video Communications, Inc.
- RingCentral, Inc.
- Verizon Communications Inc.
- 8x8, Inc.
- BT Group plc
- AT&T Inc.
- Vodafone Group Plc
- NTT Communications Corporation
- Deutsche Telekom AG
- Orange Business Services
- Tata Communications Limited
- Wipro Limited
- IBM Corporation
- Mitel Networks Corporation
- Avaya LLC
- Gamma Communications plc
- Nextiva, Inc.
- Sify Technologies Limited
- Kyndryl, Inc.
Recent Industry Developments in Managed UCaaS Operations Services Market
- October 2026: Tata Communications secured a large managed secure edge services contract for a leading life insurance company across 155 locations, combining its UCaaS platform, devices, network, and managed services into a single, integrated collaboration delivery, demonstrating how bundling connectivity and managed communications operations is becoming a preferred procurement model in financial services.
- August 2026: Digital Island, a New Zealand cloud communications provider, entered a strategic partnership with RingCentral to deploy RingCentral's Agentic Voice AI, UCaaS, and contact center solutions across New Zealand businesses, extending RingCentral's managed partner footprint in the Asia-Pacific SME segment as part of the Empower wholesale program expansion.
- April 2026: Court Square Capital Partners completed the acquisition of CallTower, a managed UCaaS provider serving more than 3,000 enterprise customers across Microsoft Teams, Cisco Webex, and Zoom, in a transaction signaling sustained private equity conviction in the managed communications consolidation thesis.
- March 2026: Spectrum Business and RingCentral expanded their partnership to make RingCX, an AI-first omnichannel contact center, and AI Conversation Expert available to Spectrum Business enterprise customers over Spectrum's managed network, creating a managed unified customer experience platform integrating UC, contact center, and embedded AI under a single SLA framework.
Global Managed UCaaS Operations Services Market Report Scope
The managed UCaaS operations services market covers third-party services that support the monitoring, administration, optimization, security, and maintenance of Unified Communications as a Service (UCaaS) platforms. These services help organizations manage cloud-based communication and collaboration tools, including voice, video conferencing, messaging, contact center, and collaboration applications.
The Managed UCaaS Operations Services Market Report is Segmented by Service Type (Managed UCaaS Administration, Managed UCaaS Monitoring and Service Assurance, Managed UCaaS Security and Operations, Managed UCaaS Migration and Implementation, Managed UCaaS Technical Support and Help Desk, Managed UCaaS Network and Carrier Operations, and Managed UCaaS Analytics and Optimization), Enterprise Size (Large Enterprises and Small and Medium Enterprises), Deployment Model (On-Premises, Cloud-Based, and Hybrid), End-User Industry (Information Technology and Telecommunications, BFSI, Healthcare, Retail and E-Commerce, Manufacturing, Government and Defense, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed UCaaS Administration |
| Managed UCaaS Monitoring and Service Assurance |
| Managed UCaaS Security and Operations |
| Managed UCaaS Migration and Implementation |
| Managed UCaaS Technical Support and Help Desk |
| Managed UCaaS Network and Carrier Operations |
| Managed UCaaS Analytics and Optimization |
| Large Enterprises |
| Small and Medium Enterprises |
| On-Premises |
| Cloud-Based |
| Hybrid |
| Information Technology and Telecommunications |
| BFSI |
| Healthcare |
| Retail and E-Commerce |
| Manufacturing |
| Government and Defense |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Rest of Africa |
| By Service Type | Managed UCaaS Administration | |
| Managed UCaaS Monitoring and Service Assurance | ||
| Managed UCaaS Security and Operations | ||
| Managed UCaaS Migration and Implementation | ||
| Managed UCaaS Technical Support and Help Desk | ||
| Managed UCaaS Network and Carrier Operations | ||
| Managed UCaaS Analytics and Optimization | ||
| By Enterprise Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By Deployment Model | On-Premises | |
| Cloud-Based | ||
| Hybrid | ||
| By End-User Industry | Information Technology and Telecommunications | |
| BFSI | ||
| Healthcare | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Government and Defense | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed UCaaS operations services sector?
The managed UCaaS operations services market size is USD 3.47 billion in 2026 and is projected to reach USD 7.43 billion by 2032, at a 13.64% CAGR.
What is driving demand for managed UCaaS operations services?
Hybrid work, PBX replacement, cloud migration, and the combination of UCaaS with contact center operations are expanding demand for managed support.
Which service type is growing fastest in managed UCaaS operations?
Analytics and optimization services are projected to grow at a 14.83% CAGR through 2032 as organizations seek better visibility into service quality and adoption.
Which deployment approach is expanding fastest?
Hybrid deployments are expected to grow at a 14.27% CAGR through 2032 because organizations continue to operate mixed cloud and on-premises communications environments.
Which end-user sector has the strongest projected growth?
Healthcare is projected to grow at a 14.63% CAGR through 2032, supported by cloud telephony adoption and integration with clinical workflows.
Which region is growing fastest for managed UCaaS operations services?
Asia-Pacific is expected to grow at a 14.52% CAGR through 2032, supported by local platform requirements and expanding enterprise communications needs.