
Managed Contact Center Technology Operations Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 23.91 Billion |
| Market Size (2032) | USD 40.91 Billion |
| Growth Rate (2027 - 2032) | 13.83 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Contact Center Technology Operations Services Market Analysis by Mordor Intelligence
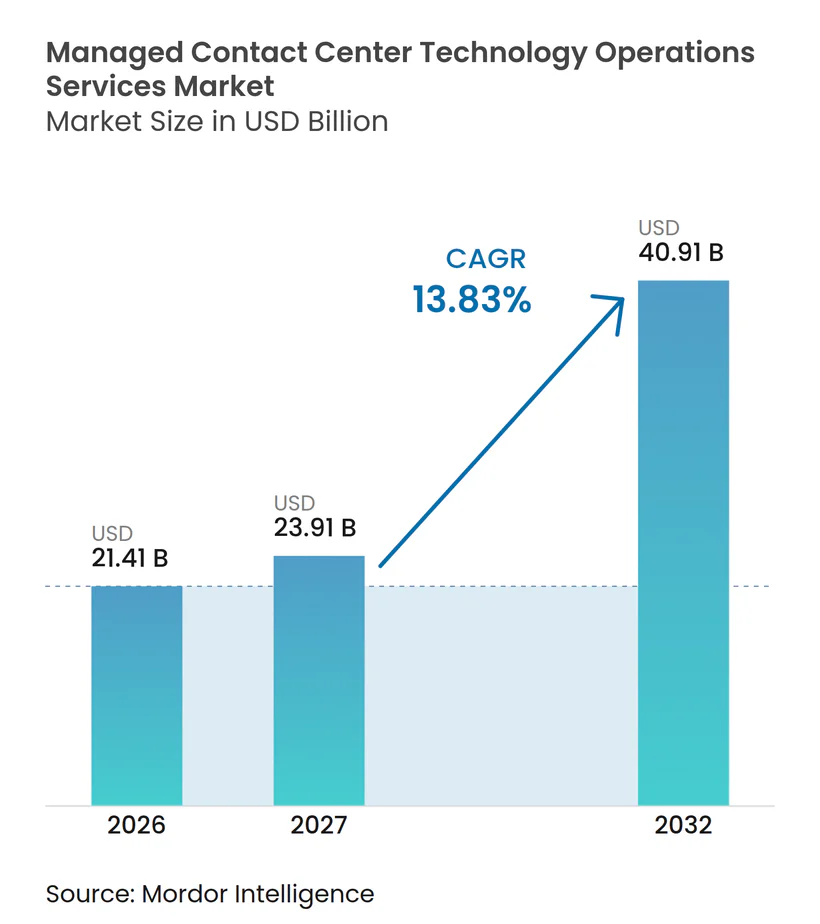
The managed contact center technology operations services market size is projected to expand from USD 21.41 billion in 2026 to USD 40.91 billion by 2032, registering a CAGR of 13.83% between 2027 and 2032. Enterprises are moving away from fixed-cost, self-operated technology models and toward managed arrangements that place platform risk, integration work, and staffing responsibilities with specialist providers. Contact center performance is increasingly tied to revenue retention and customer experience measures, rather than cost control alone. This change places managed operations decisions higher on executive priorities. AI has also changed the work expected from providers, moving the focus beyond platform availability toward AI agent governance, orchestration design, and outcome measurement. The managed contact center technology operations services market therefore favors providers that can combine operational accountability, platform knowledge, and compliance support.
Key Report Takeaways
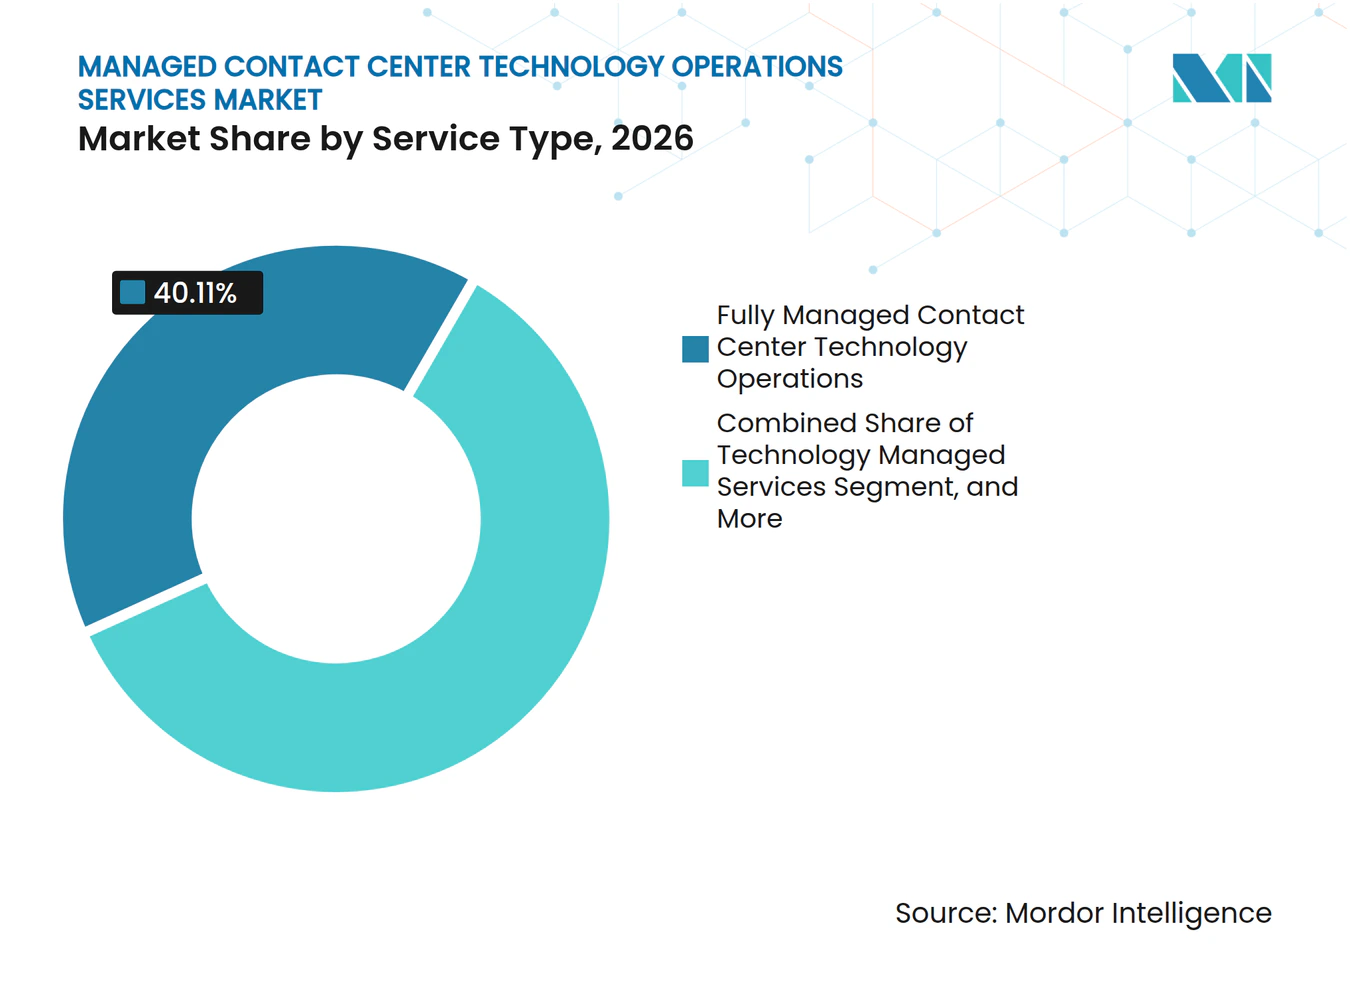
- By service model, fully managed arrangements held 40.11% of the managed contact center technology operations services market share in 2026 and are projected to expand at a 14.98% CAGR through 2032.
- By technology environment, cloud-native contact center-as-a-service environments accounted for 37.32% of the managed contact center technology operations services market size in 2026 and are projected to expand at a 14.45% CAGR through 2032.
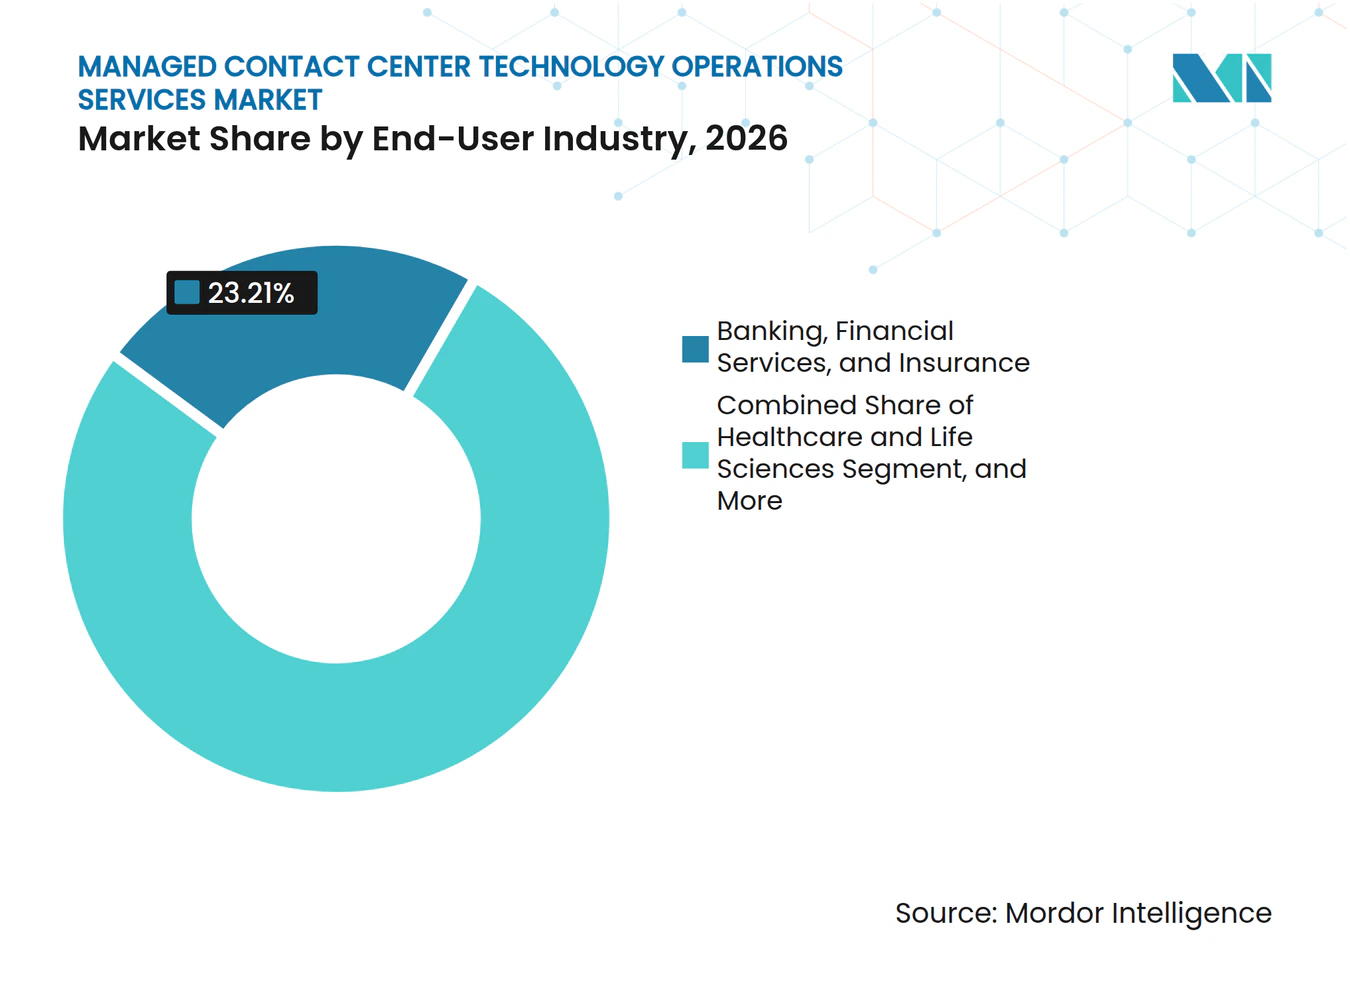
- By end-user industry, banking, financial services, and insurance held 23.21% of revenue in 2026, while healthcare and life sciences are projected to expand at a 14.82% CAGR through 2032.
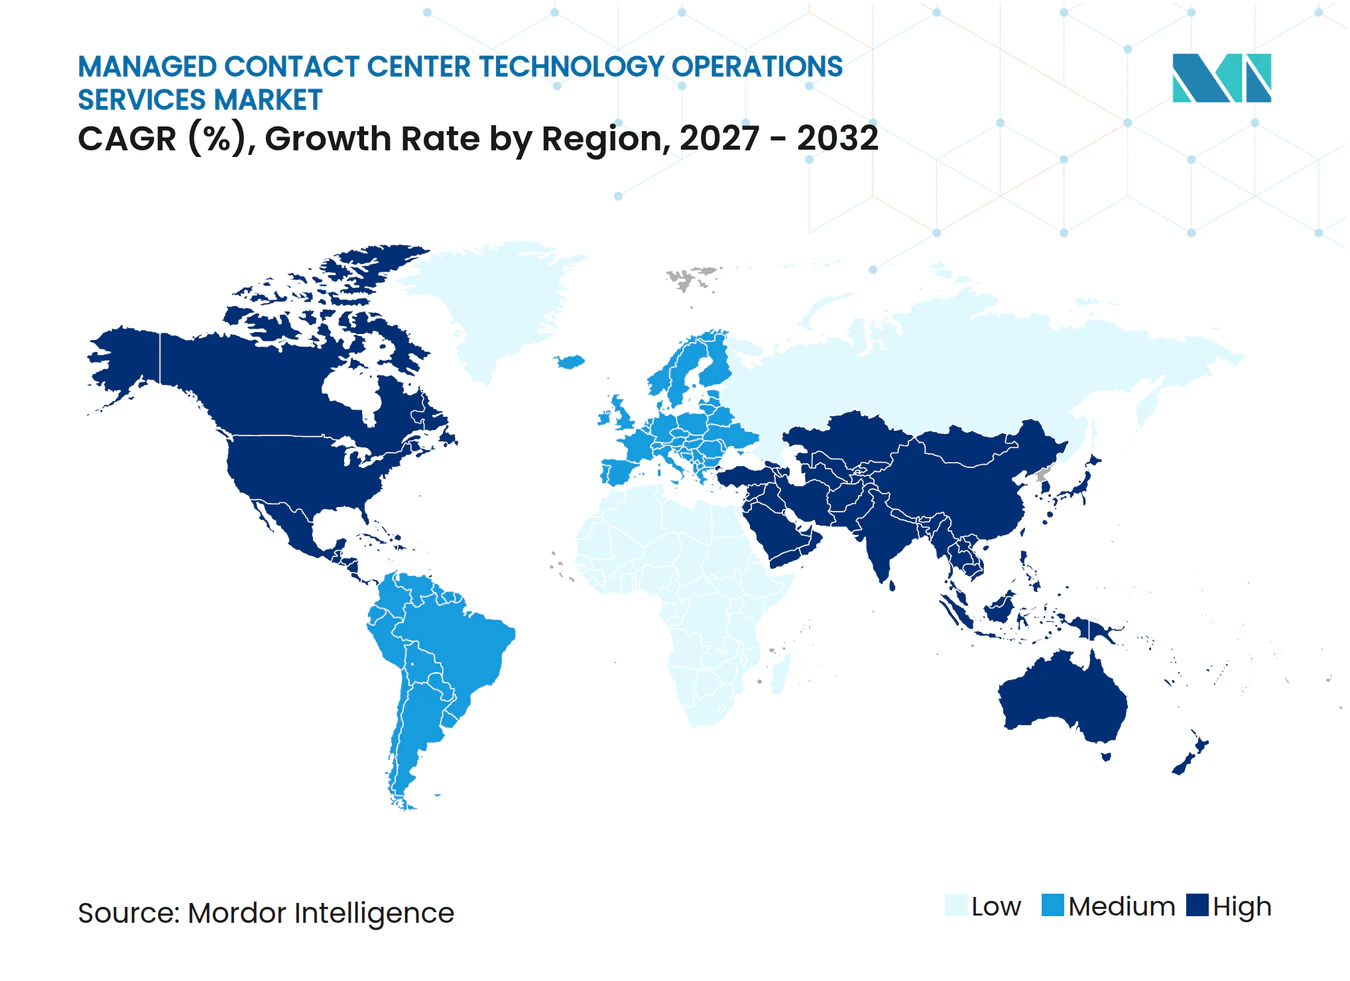
- By geography, North America held 38.54% of revenue in 2026, while Asia-Pacific is projected to expand at a 14.86% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Contact Center Technology Operations Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Enterprise Shift to Managed Cloud Operations | +3.2% | Global, with highest velocity in North America and Europe | Medium term (2-4 years) |
| AI Agent Assist and Autonomous Interaction Orchestration | +2.8% | Global, led by North America and Asia-Pacific enterprise buyers | Medium term (2-4 years) |
| Omnichannel Reliability and Outcome-Based SLAs | +2.1% | Global, with accelerating adoption in Asia-Pacific and South America | Short term (≤ 2 years) |
| Shortage of Cloud, Data, and Automation Specialists | +1.6% | Global, most acute in North America and Western Europe | Medium term (2-4 years) |
| Digital-First Customer Journeys in Emerging Markets | +1.3% | Asia-Pacific, Middle East, Africa, and South America | Long term (≥ 4 years) |
| Multi-Cloud and Multi-Platform CX Estate Complexity | +1.0% | Global, highest complexity in large enterprises and regulated sectors | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Enterprise Shift From Customer-Owned Platforms to Managed Cloud Operations
On-premises contact center infrastructure is being retired, and managed operations providers are receiving the workloads that leave those environments. The move to cloud contact center software does not remove the need for operational accountability. Enterprises still need specialists to manage configuration, AI tuning, integration availability, and compliance reviews. NTT DATA signed a Strategic Collaboration Agreement with AWS in October 2025 for Managed Customer Experience services on Amazon Connect, aimed at financial services, healthcare, telecommunications, and retail organizations.[1] The agreement reflects the need for a managed operating layer alongside cloud software. The managed contact center technology operations services market benefits because cloud adoption creates an operations requirement that software licenses alone do not address.
AI Agent Assist and Autonomous Interaction Orchestration Adoption
AI agents have widened the responsibilities of contact center operations providers. Providers now need to govern AI agents, design orchestration rules, and measure customer outcomes on an ongoing basis. Salesforce reported that AI-driven customer-service actions in financial services increased at an average monthly rate of 105% in the first half of 2025.[2] The same report stated that agent creation across organizations rose 119% from January through June 2025. NICE reported USD 328 million in AI annual recurring revenue in its full-year 2025 results, a 66% increase from the prior year, and said AI components were included in all seven-figure CCaaS contracts. The managed contact center technology operations services market gains from this shift because customers need operating partners with platform-specific AI skills and clear governance practices.
Demand for Omnichannel Reliability and Outcome-Based SLAs
Organizations are placing greater weight on resolution quality and customer satisfaction when they buy managed services. Platform availability and agent occupancy remain relevant, but they no longer fully describe the service expected by buyers. Outcome-based service-level agreements connect provider compensation more directly with service performance. GDT stated that organizations using its managed contact center model achieved more than 15% improvement in agent productivity and 75% higher customer satisfaction than self-operated benchmarks.[3] Crescendo launched its Total Outcome Guarantee in October 2025, under which clients pay only when AI-powered interactions outperform incumbent services on quality, speed, and customer satisfaction. This approach supports demand in the managed contact center technology operations services market because it gives buyers a direct way to evaluate operating performance.
Shortage of Contact Center Cloud, Data, and Automation Specialists
Organizations face difficulty finding people who can manage cloud contact center systems, data, and automation tools. The skills requirement is rising as platforms add AI, analytics, and workflow features. The shortage makes it harder for enterprises to maintain capable internal teams across multiple platforms. CloudEmpower graduated its first ForwardProgress cohort in May 2026, with professionals trained in Amazon Connect, contact center automation, and conversational AI. The program shows that technical capability is becoming part of the service offered by managed operations providers. This supply constraint directs more buyers toward providers that can deliver trained teams as part of the operating contract.
Restraints Impact Analysis of Managed Contact Center Technology Operations Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Residency, Recording, and Cross-Border Compliance Burden | -1.4% | Global, most acute in Europe, Asia-Pacific, and the Middle East | Medium term (2-4 years) |
| Migration Risk From Legacy Routing, CRM, and Workforce Systems | -1.1% | Global, most severe in large enterprises across North America and Europe with multi-decade legacy estates | Medium term (2-4 years) |
| Unclear Economics of Consumption-Based AI and Automation Pricing | -0.8% | Global, particularly in mid-market enterprise segments | Short term (≤ 2 years) |
| Scarcity of Platform Specific Operations Talent and Change Fatigue | -0.7% | Global, especially concentrated in markets with aggressive multi-platform rollouts | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Residency, Recording, and Cross-Border Compliance Burden
Cross-border data rules make managed contact center deployments more complex. GDPR Articles 44-49 restrict transfers of personal data outside the European Union without valid transfer mechanisms. Providers must maintain regional processing arrangements, audit records, and contractual safeguards for the jurisdictions they serve. Call recordings and AI-generated transcripts increase the burden because they contain personal information. The European Union AI Act also establishes transparency and governance requirements for certain automated systems, extending the compliance scope for AI-enabled customer interactions. These requirements raise the cost and operational effort needed to provide consistent services across regions.
Migration Risk from Legacy Routing, CRM, and Workforce Systems
Migration from legacy infrastructure to a managed cloud environment can disrupt customer service when data or workflows are poorly prepared. The main issue is often not telephony conversion, but the quality of customer records and the consistency of routing rules. Organizations may carry duplicate records and undocumented processes that reduce the value of new AI tools. NICE identifies service disruption, data corruption risk, and lower agent productivity among the key concerns in legacy-platform migration. These risks can delay decisions, particularly at large organizations with complex CRM and workforce systems. They also increase the value of providers that can manage preparation, transition, and ongoing operating accountability.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Contact Center Technology Operations Services Market Segment Analysis
By Service Model:
Fully Managed Arrangements Lead Enterprise DemandFully managed arrangements held 40.11% of service model revenue in 2026 and are projected to expand at a 14.98% CAGR through 2032. This model leads the managed contact center technology operations services market share because it gives one provider broad responsibility for daily operations, platform configuration, and service delivery. Enterprises use fully managed services when they cannot maintain platform configuration, service-level accountability, and compliance reviews with internal resources alone. The arrangement is particularly relevant where AI systems need regular oversight, documented governance, and coordinated change management. Co-managed arrangements remain available for organizations that want direct control over part of the environment.
Shared responsibility can make accountability harder to define when several teams oversee the same customer journey. Technology managed services and premium support are also moving toward wider operating mandates as legacy platforms reach end of life. Professional services often provide the first step for organizations leaving self-operated systems, then become longer-term managed contracts after implementation. Financial services and insurance organizations place particular importance on audit trails, recording rules, and AI oversight across complex contact center environments. The managed contact center technology operations services market continues to favor full-service arrangements where regulatory requirements make fragmented ownership difficult.



By Technology Environment:
Cloud-Native Platforms Extend Their LeadCloud-native contact center-as-a-service environments accounted for 37.32% of technology environment revenue in 2026 and are projected to expand at a 14.45% CAGR through 2032. Cloud-native environments provide faster access to AI functions, integrations, and elastic capacity. These features are difficult to reproduce on hosted or on-premises platforms through management services alone. The managed contact center technology operations services market size for cloud-native environments is supported by organizations that need frequent platform updates and consistent operating controls. Managed providers can apply changes and governance controls more consistently in standardized cloud deployments.
This operating model is important in the managed contact center technology operations services market for enterprises that want new AI capabilities without managing every platform release internally. Hosted and dedicated platforms continue to serve large enterprises that prioritize data sovereignty and predictable performance, particularly in parts of Europe and Asia-Pacific. On-premises platforms remain in use where cloud migration is restricted, although providers increasingly offer regional cloud options instead of maintaining aging hardware. Hybrid and multi-cloud environments are becoming more relevant for multinational organizations that retain regional nodes for restricted markets. Talkdesk introduced Automation Flows in the first quarter of 2026, enabling AI agents to move through CRM records and resolve requests without human routing.
By End-User Industry:
Financial Services Leads While Healthcare Advances FastestBanking, financial services, and insurance held 23.21% of end-user revenue in 2026, making the sector the largest user group. The sector has high interaction volumes, demanding compliance requirements, and a strong interest in AI-supported customer service. Salesforce found that customers who regularly used financial services AI agents were 222% more likely to report an improved overall experience. These requirements support demand for providers that can manage systems, controls, and customer outcomes together. Retail and consumer goods is another important user group because organizations must coordinate e-commerce, stores, and social commerce interactions.
Within the managed contact center technology operations services market, healthcare and life sciences are projected to expand at a 14.82% CAGR through 2032, the highest rate across end-user industries. Patient interactions are increasing, while care coordination remains distributed across systems and compliance requirements remain strict. CloudHesive reported that its managed Amazon Connect deployment for Envera Health improved first-call resolution by 10% and reduced telecommunications costs by 30%. Telecommunications and technology organizations are buyers because they operate large internal contact centers while upgrading customer-facing infrastructure. Government, travel, transportation, and hospitality organizations also seek reliable omnichannel operations, although procurement cycles can slow adoption in public sector settings.

Geography Analysis
North America held 38.54% of the managed contact center technology operations services market share in 2026. The managed contact center technology operations services market in the region has a large base of enterprise buyers, cloud-ready infrastructure, and experienced managed service providers. The United States supports this position through a competitive supplier base that includes NICE, Genesys, and Five9, and NICE reported 66% year-over-year growth in AI annual recurring revenue in 2025. Mexico remains an important nearshore delivery location. Europe remains a major geography because data residency and recording requirements make proven in-region operating capability important in vendor selection.
Asia-Pacific is projected to expand at a 14.86% CAGR through 2032, making it the fastest-growing geography. Enterprises in India, Indonesia, and the Philippines are deploying cloud-native managed operations on first-generation modern infrastructure, reducing some legacy migration complexity. The region combines demand for managed operations with a large delivery workforce. Japan, Australia, and South Korea add demand from established enterprises with complex customer-service requirements. The managed contact center technology operations services market in Asia-Pacific is strengthened by buyers that want AI-ready operations without building large internal technology teams.
South America is an emerging region, with Brazil as the primary contributor through wider adoption of cloud, data, and AI systems for automation and personalized customer interactions. The managed contact center technology operations services market in the Middle East is advancing in the United Arab Emirates and Saudi Arabia through Arabic-language AI and cloud contact center deployments. ZIWO secured growth credit in February 2026 to expand Arabic-first AI-powered managed CCaaS operations across the Gulf Cooperation Council. Africa remains at an earlier stage, although Huawei and Kenya's Konza Technopolis Development Authority launched an AI-assisted BPO contact center in March 2026 as a model for additional digital hubs.
Competitive Landscape
Market Concentration
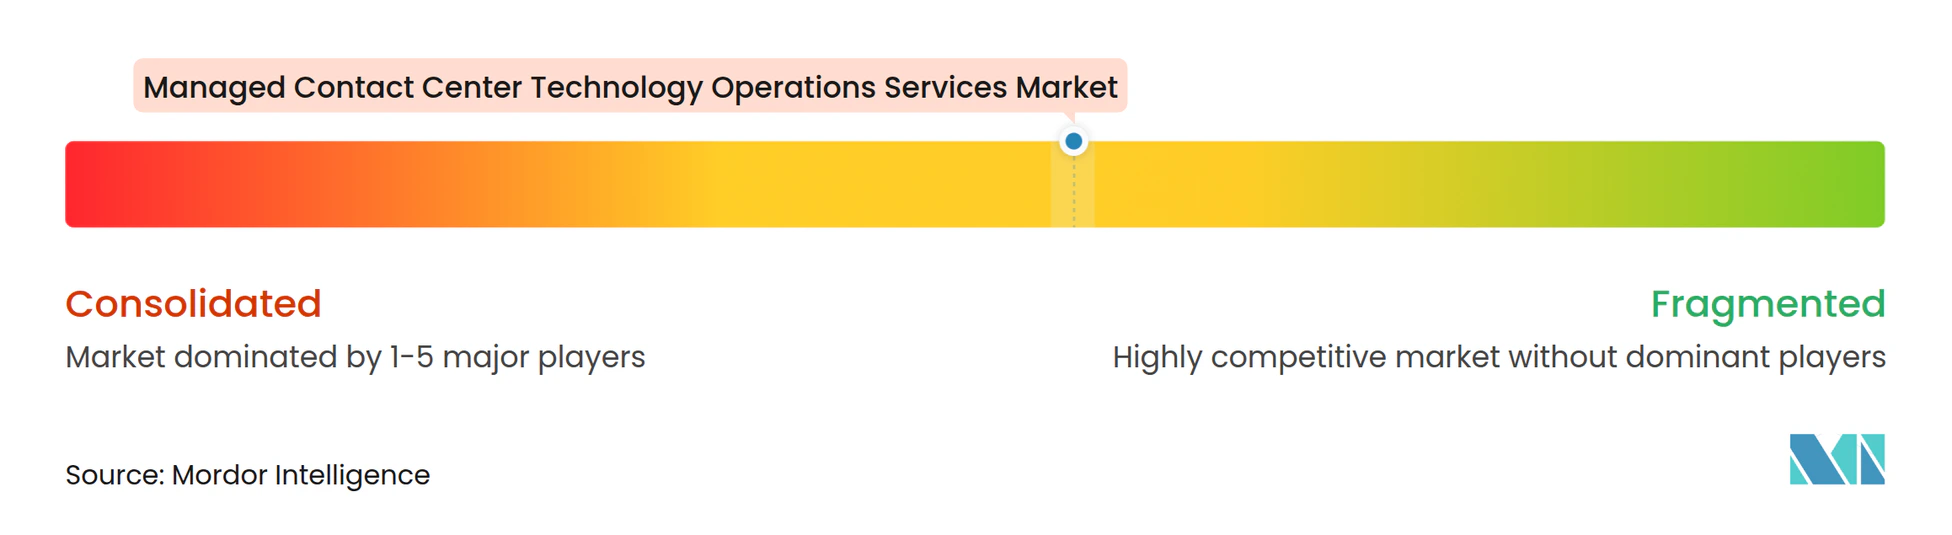
The managed contact center technology operations services market is moderately concentrated at the platform level and fragmented at the services and delivery level. NICE, Genesys, Five9, Talkdesk, and Content Guru are leading suppliers in CCaaS, while many system integrators and regional providers compete for implementation and operating work. In the managed contact center technology operations services market, large platforms can provide deeper integration, broader compliance support, and established service-level processes. Smaller providers compete through regional delivery, specialized sector knowledge, and tailored operating models. The managed contact center technology operations services market rewards providers that can show technical capability and clear operational responsibility.
NICE uses an integrated platform approach and closed its acquisition of Cognigy for USD 955 million in September 2025. The acquisition integrated conversational and agentic AI capabilities into CXone Mpower for more than 25,000 existing CXone customers. Genesys follows a partnership-oriented approach and received USD 1.5 billion in combined strategic investment from Salesforce and ServiceNow in July 2025. The investment reinforces its position with enterprises using Salesforce and ServiceNow workflows. Both approaches seek to make platform switching more difficult for established enterprise users.
Within the managed contact center technology operations services market, mid-market buyers with 200 to 1,000 agent seats offer space for providers that balance enterprise capabilities with simpler service models. Crescendo targets this group with pricing linked to customer-experience performance. Interoperability is becoming more important as enterprises connect AI agents, CRM systems, and workflow platforms. NICE has worked with Sierra and Meta on open standards for personal AI agents, reflecting the growing importance of platform integration.
Managed Contact Center Technology Operations Services Industry Leaders
-
NICE Ltd.
-
Genesys Cloud Services, Inc.
-
Five9, Inc.
-
Talkdesk, Inc.
-
Content Guru Limited
- *Disclaimer: Major Players sorted in no particular order
Managed Contact Center Technology Operations Services Market Companies Covered in this Report
- NICE Ltd.
- Genesys Cloud Services, Inc.
- Five9, Inc.
- Talkdesk, Inc.
- Content Guru Limited
- Odigo SAS
- Puzzel AS
- UJET, Inc.
- Enghouse Systems Limited
- Dialpad, Inc.
- 8x8, Inc.
- Vonage Holdings Corp.
- Diabolocom SAS
- Call Center Studio LLC
- Bright Pattern, Inc.
- Evolve IP, LLC
- Alvaria, Inc.
- Vocalcom S.A.
- Luware AG
- Kore.ai, Inc.
Recent Industry Developments in Managed Contact Center Technology Operations Services Market
- October 2026: Genesys acquired Pinkfish, a contact center automation specialist, adding programmable autonomous orchestration capabilities to Genesys Cloud and strengthening its managed operations proposition for high-volume enterprise contact centers seeking to reduce human intervention in routine workflows.
- October 2026: GDT enhanced its managed services platform powered by Cisco Webex Contact Center, delivering integrated AI, analytics, and workforce optimization under a single outcome-based service agreement. Cisco's partner managed services data indicates businesses using this managed model achieve more than 15% improvements in agent productivity and 75% higher CSAT versus self-operated benchmarks.
- October 2026: Crescendo launched the Total Outcome Guarantee, committing to outperform any incumbent AI on customer-experience quality, speed, and CSAT, or waive all charges. The model extends outcome-based pricing across every element of managed customer care, consolidating multiple BPO and technology vendors into a single managed solution with performance-linked economics.
- August 2026: Dialpad announced a partnership with enterprise AI search platform Glean, integrating Dialpad's conversational intelligence into Glean's enterprise knowledge layer, extending managed contact center operations data as an intelligence resource across the broader organization.
Global Managed Contact Center Technology Operations Services Market Report Scope
The Global Managed Contact Center Technology Operations Services Market refers to the industry focused on the outsourcing, management, monitoring, optimization, and continuous operation of contact center technology environments by specialized service providers.
The Managed Contact Center Technology Operations Services Market Report is Segmented by Service Model (Fully Managed Contact Center Technology Operations, Co-Managed Contact Center Technology Operations, Technology Managed Services and Premium Support, and Professional Services Attached to Managed Operations), Technology Environment (Cloud-Native Contact Center-as-a-Service, Hosted or Dedicated Contact Center Platform, On-Premises Platform Under Third-Party Management, and Hybrid and Multi-Cloud Contact Center Environment), End-User Industry (Banking, Financial Services, and Insurance, Retail and Consumer Goods, Telecommunications and Technology; Healthcare and Life Sciences, Government and Public Sector, Travel, Transportation, and Hospitality; Utilities and Energy, and Other End-User Industries), and Geography (North America [United States, Canada, and Mexico], South America [Brazil, Argentina, Colombia, and Rest of South America], Europe [United Kingdom, Germany, France, Italy, Spain, and Rest of Europe], Asia-Pacific [China, India, Japan, Philippines, Australia, Indonesia, and Rest of Asia-Pacific], Middle East [United Arab Emirates, Saudi Arabia, Turkey, Israel, and Rest of Middle East], and Africa [South Africa, Nigeria, Egypt, and Rest of Africa]). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Fully Managed Contact Center Technology Operations |
| Co-Managed Contact Center Technology Operations |
| Technology Managed Services and Premium Support |
| Professional Services Attached to Managed Operations |
| Cloud-Native Contact Center-as-a-Service |
| Hosted or Dedicated Contact Center Platform |
| On-Premises Platform Under Third-Party Management |
| Hybrid and Multi-Cloud Contact Center Environment |
| Banking, Financial Services, and Insurance |
| Retail and Consumer Goods |
| Telecommunications and Technology |
| Healthcare and Life Sciences |
| Government and Public Sector |
| Travel, Transportation, and Hospitality |
| Utilities and Energy |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Colombia | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| Philippines | |
| Australia | |
| Indonesia | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Israel | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Egypt | |
| Rest of Africa |
| By Service Model | Fully Managed Contact Center Technology Operations | |
| Co-Managed Contact Center Technology Operations | ||
| Technology Managed Services and Premium Support | ||
| Professional Services Attached to Managed Operations | ||
| By Technology Environment | Cloud-Native Contact Center-as-a-Service | |
| Hosted or Dedicated Contact Center Platform | ||
| On-Premises Platform Under Third-Party Management | ||
| Hybrid and Multi-Cloud Contact Center Environment | ||
| By End-User Industry | Banking, Financial Services, and Insurance | |
| Retail and Consumer Goods | ||
| Telecommunications and Technology | ||
| Healthcare and Life Sciences | ||
| Government and Public Sector | ||
| Travel, Transportation, and Hospitality | ||
| Utilities and Energy | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Colombia | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| Philippines | ||
| Australia | ||
| Indonesia | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Israel | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed contact center technology operations services market?
The market is valued at USD 21.41 billion in 2026 and is projected to reach USD 40.91 billion by 2032, at a 13.83% CAGR from 2027 to 2032. Demand in the managed contact center technology operations services market reflects the move from self-operated platforms to arrangements that include operational accountability, integration support, and specialist staffing.
Which service model leads managed contact center technology operations services?
Fully managed arrangements lead with 40.11% of service model revenue in 2026 and are projected to expand at a 14.98% CAGR through 2032. They place configuration, service-level responsibility, compliance work, and routine platform governance under one provider.
Why are organizations adopting managed contact center operations?
Organizations use managed providers to shift platform operations, AI governance, integrations, staffing, and compliance work to specialist teams. This approach is useful when internal teams cannot maintain several technology, workforce, and governance responsibilities at the same time.
Which technology environment is most important for managed operations?
Cloud-native contact center-as-a-service environments held 37.32% of technology environment revenue in 2026 and are projected to expand at a 14.45% CAGR through 2032. They provide more direct access to AI functions, integrations, elastic capacity, and frequent platform updates.
Which end-user sector is expanding fastest?
Within the managed contact center technology operations services market, healthcare and life sciences are projected to expand at a 14.82% CAGR through 2032, supported by patient interaction needs and compliance requirements. Managed providers can help healthcare organizations coordinate systems, improve service performance, and maintain operating accountability.
Which region is expanding fastest for managed contact center operations?
Asia-Pacific is projected to expand at a 14.86% CAGR through 2032, supported by cloud-native deployments in India, Indonesia, and the Philippines. The region combines enterprise demand, first-generation modern infrastructure, and a large delivery workforce.