
Managed Cloud IDS/IPS Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 2.18 Billion |
| Market Size (2032) | USD 4.43 Billion |
| Growth Rate (2027 - 2032) | 15.24 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Cloud IDS/IPS Services Market Analysis by Mordor Intelligence
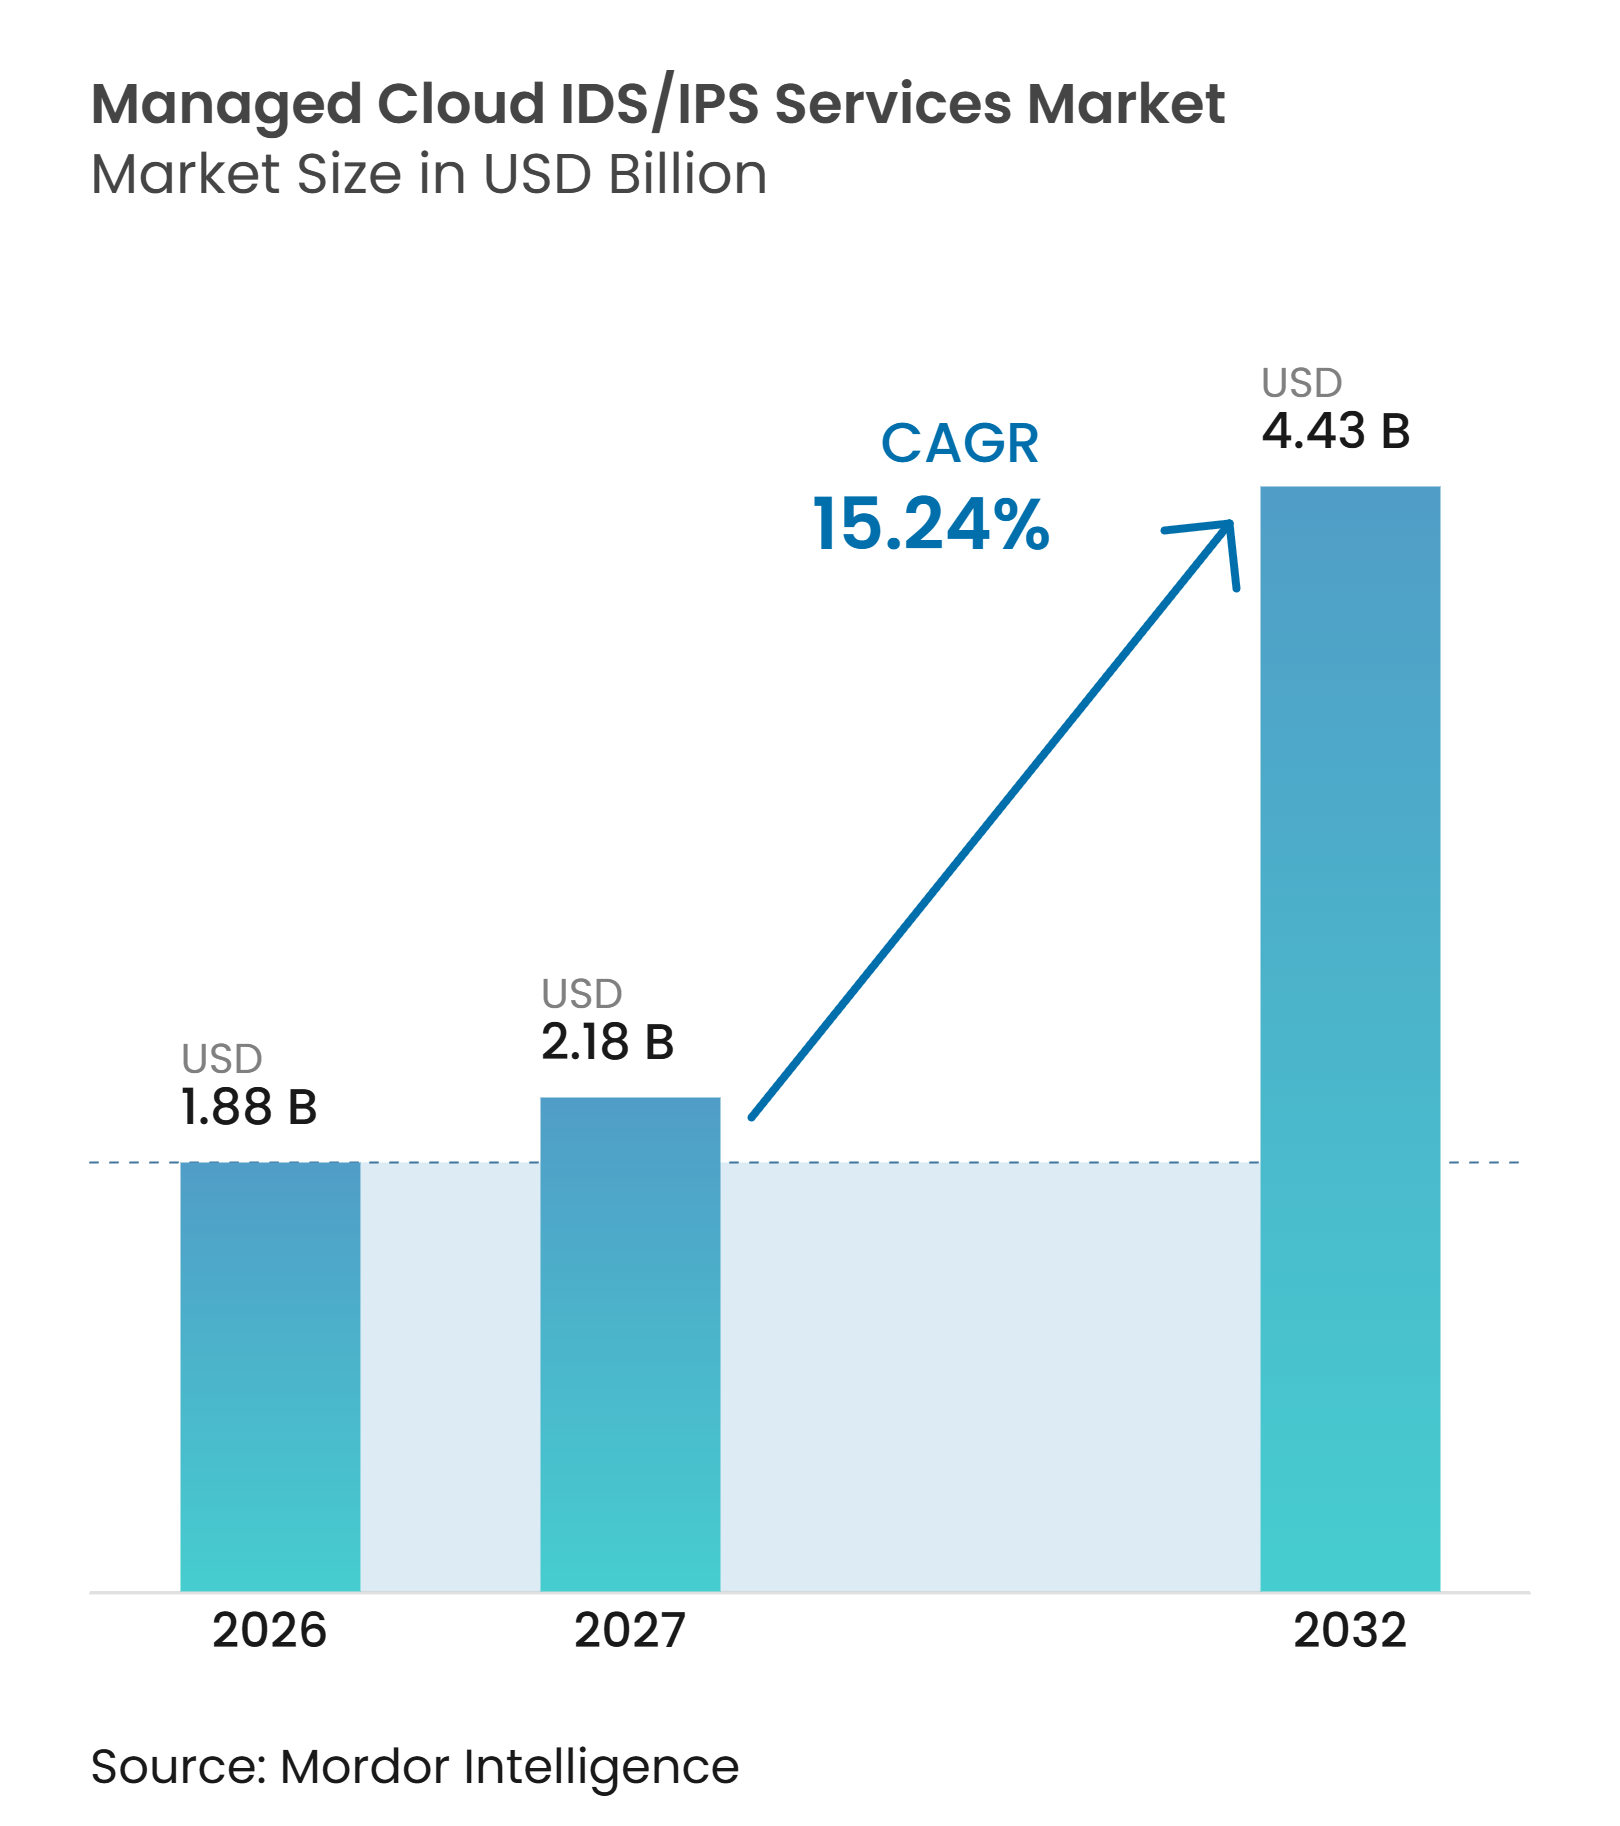
The cloud-based managed IDS/IPS services market size was valued at USD 1.88 billion in 2026 and is projected to reach USD 4.43 billion by 2032, registering a CAGR of 15.24% between 2027 and 2032. Demand is moving toward continuously managed controls that can cover cloud workloads, interfaces, and network activity. Multi-cloud use is expanding the number of systems that security teams must monitor. Compliance requirements are also making timely detection and incident reporting more important for regulated buyers. Providers that combine local data handling with cloud-based analysis can address a key buyer concern. The cloud-based managed IDS/IPS services market is therefore shaped by operational coverage, regulatory readiness, and the ability to manage encrypted traffic without weakening privacy safeguards or increasing work for client security teams.
Key Report Takeaways
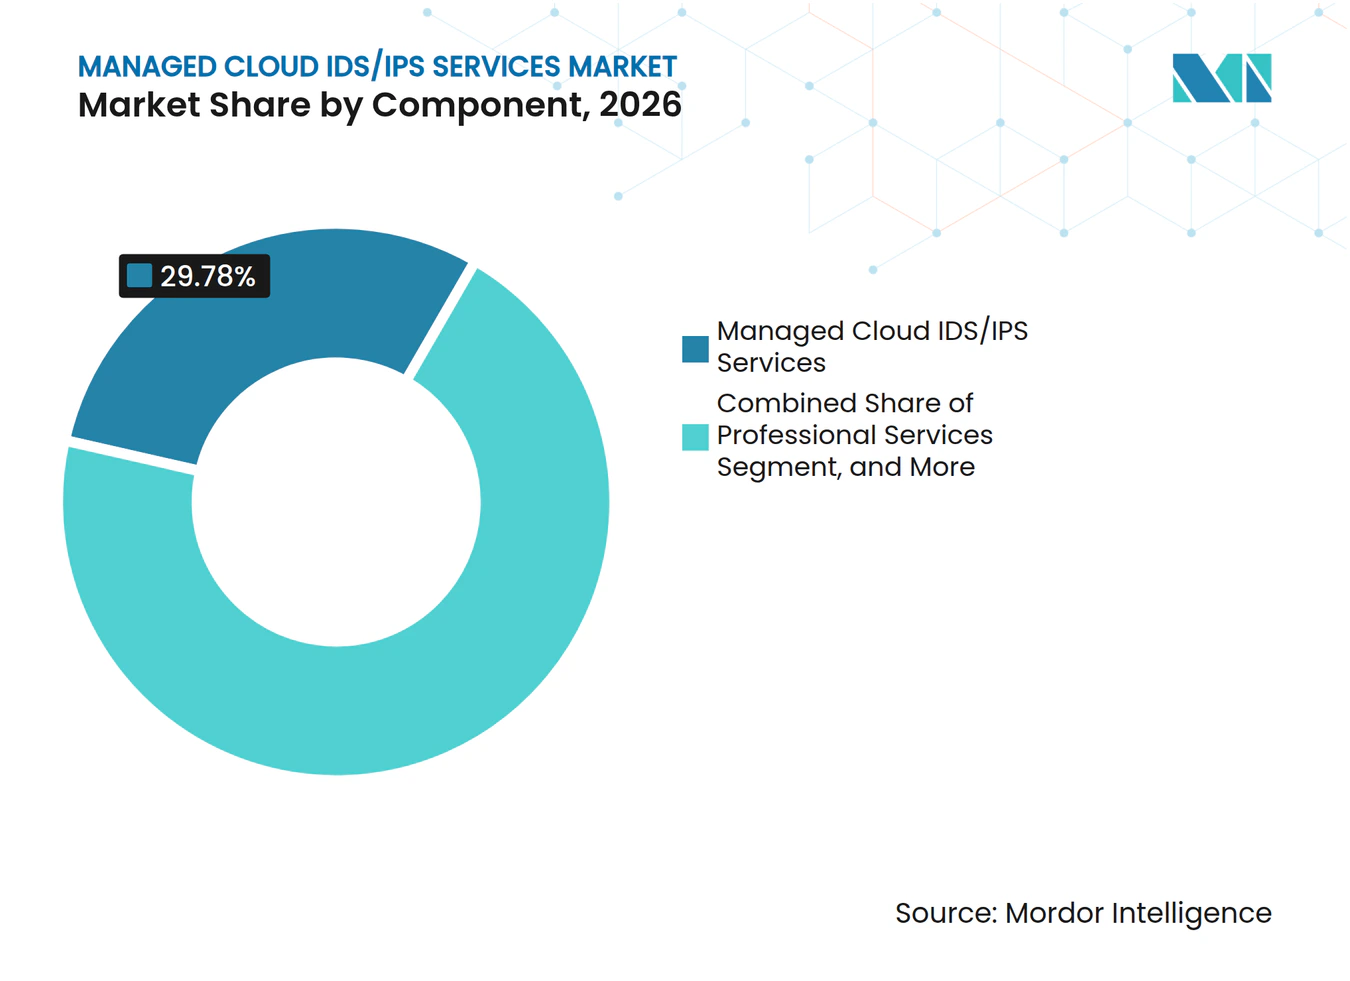
- By component, Managed Cloud IDS/IPS Services held 29.78% of revenue in 2026 in the Managed Cloud IDS/IPS Services Market, while Professional Services is projected to expand at a 17.84% CAGR through 2032.
- By deployment mode, Public Cloud held 36.12% of revenue in 2026, while Hybrid Cloud is projected to expand at a 17.66% CAGR through 2032.
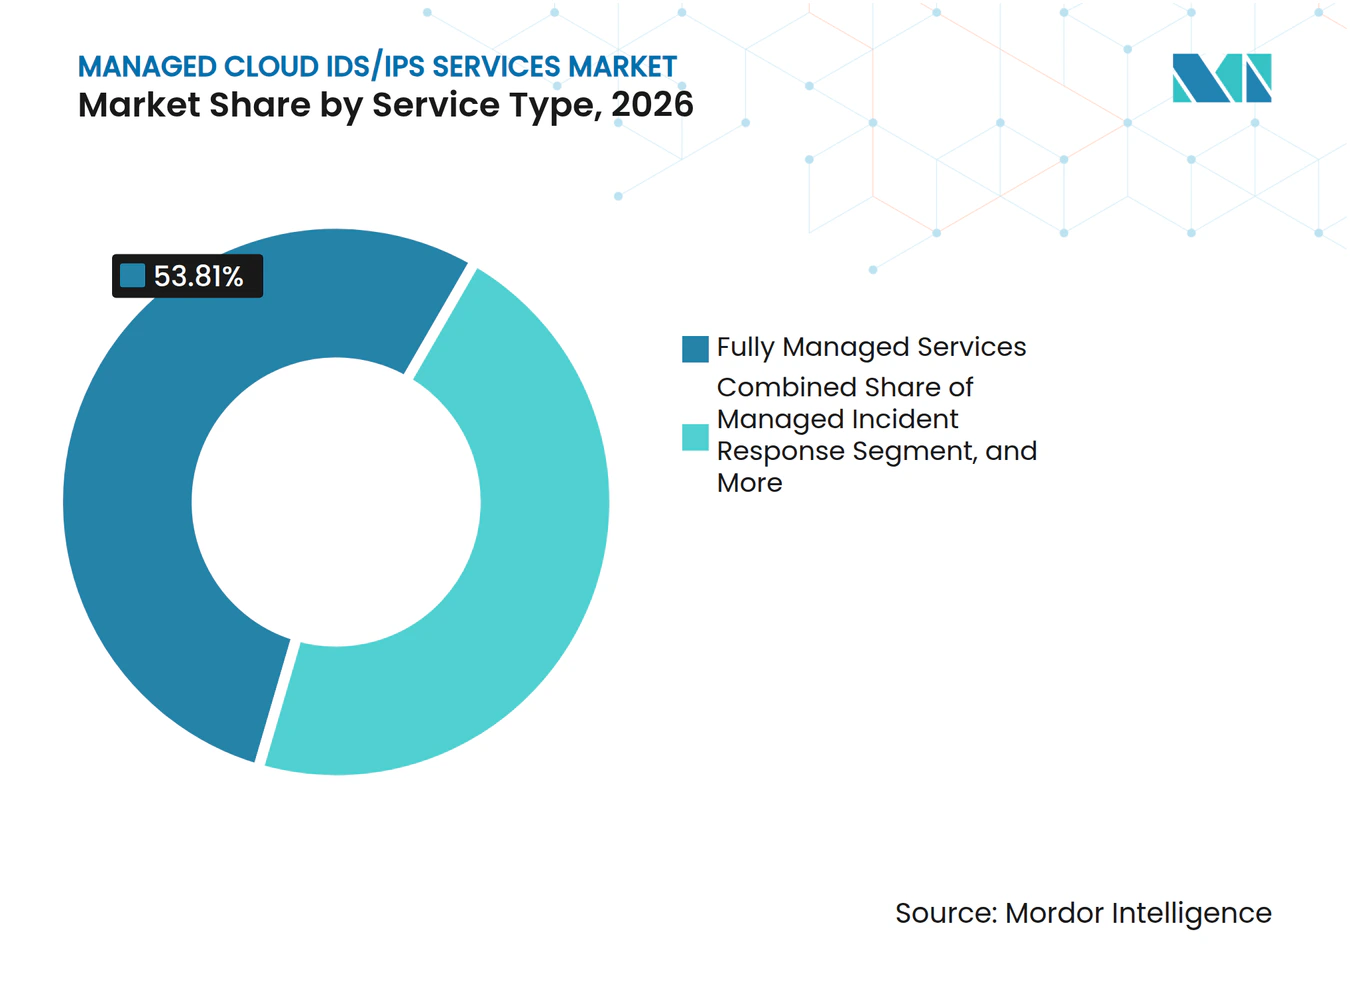
- By service type, Fully Managed Services held 53.81% of revenue in 2026, while Managed Detection and Response Add-ons are projected to expand at a 17.79% CAGR through 2032.
- By organization size, Large Enterprises held 66.33% of revenue in 2026, while Small and Medium Enterprises are projected to expand at a 17.58% CAGR through 2032 in the Managed Cloud IDS/IPS Services Market.
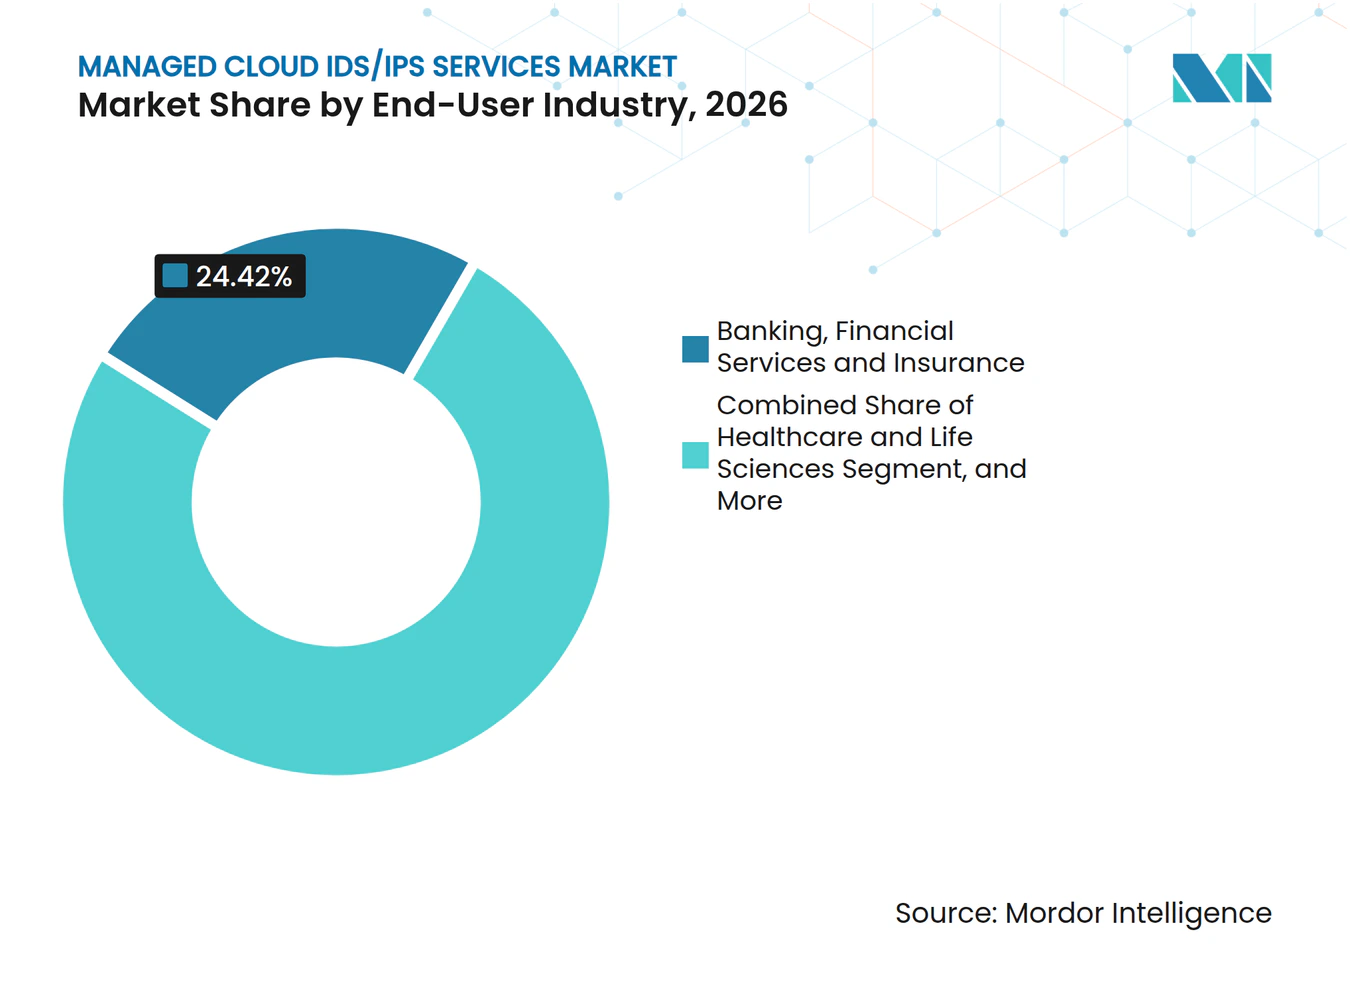
- By end-user industry, Banking, Financial Services, and Insurance held 24.42% of revenue in 2026, while Healthcare and Life Sciences are projected to expand at a 17.98% CAGR through 2032.
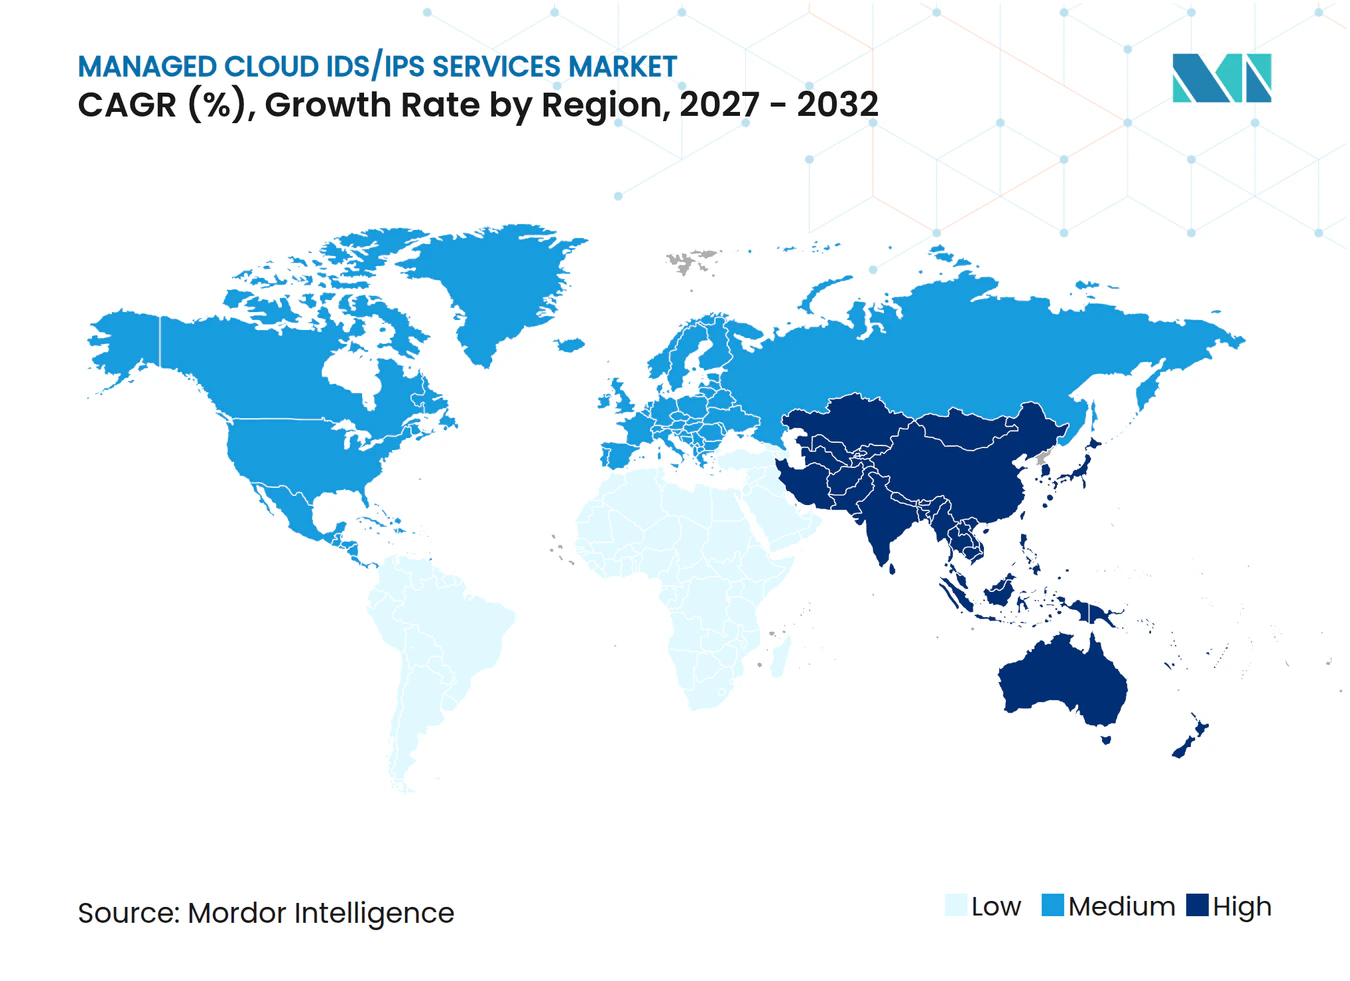
- By geography, North America held 39.88% of revenue in 2026, while Asia-Pacific is projected to expand at a 17.13% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Cloud IDS/IPS Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Multi-Cloud Attack Surface | +3.80% | Global, concentrated in North America and Asia-Pacific | Short term (≤ 2 years) |
| AI-Led SOC Automation and XDR Adoption | +3.20% | Global, early adoption in North America and Europe | Medium term (2-4 years) |
| Compliance-by-Design for Continuous Detection | +2.90% | North America and EU core, spill-over to Asia-Pacific and Middle East and Africa | Medium term (2-4 years) |
| Cybersecurity Talent Shortages Driving Co-Managed Monitoring | +2.50% | Global | Short term (≤ 2 years) |
| Encrypted-by-Default Traffic Creating Demand for Cloud-Native Inspection | +1.60% | Global, concentrated in enterprise-dense economies | Medium term (2-4 years) |
| Identity-Centric East-West Visibility for Ephemeral Workloads | +1.20% | North America, EU, Asia-Pacific core | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating Multi-Cloud Attack Surface
Each additional cloud tenant, container cluster, or interface can create a detection gap. This issue becomes harder to manage when workloads move across cloud environments and use different event formats. Security teams need complete visibility, but older perimeter tools do not provide consistent coverage for short-lived cloud workloads. The cloud-based managed IDS/IPS services market benefits when buyers need a provider to consolidate monitoring across these environments. Managed providers with vendor-neutral collection and normalization capabilities can reduce the work of joining disparate security data. The need to identify exposures continuously supports the cloud-based managed IDS/IPS services market as part of wider enterprise security programs.
AI-Led SOC Automation and XDR Adoption
Automation is changing the cost and delivery model for security operations centers. A systematic review of 189 peer-reviewed studies found that 65% examined detection automation, making it the most common application of artificial intelligence in security operations.[1] The cloud-based managed IDS/IPS services market can benefit when automation helps providers triage larger volumes of alerts with the same analyst teams. Buyers in regulated sectors still need human oversight for material containment decisions. Providers that define when an analyst must review an automated action can make the service easier to accept in these settings. This approach supports faster investigation without presenting autonomous action as a substitute for accountable decision-making.
Compliance-by-Design for Continuous Detection
Regulation is turning intrusion detection into an operational requirement for many organizations. The Digital Operational Resilience Act applied from January 2025 and requires financial entities to classify and report major information and communication technology incidents under defined timelines.[2] The cloud-based managed IDS/IPS services market gains relevance when buyers need persistent monitoring to recognize and investigate an incident quickly. A managed provider can supply continuous oversight when internal teams do not operate around the clock. Compliance-driven contracts may also be more durable because control requirements do not disappear when discretionary budgets tighten. For the cloud-based managed IDS/IPS services market, audit trails, incident workflows, and documented response procedures are important features of the offering.
Cybersecurity Talent Shortages Driving Co-Managed Monitoring
The shortage of experienced security personnel continues to make external monitoring attractive. ISC2 reported a global cybersecurity workforce gap of 4.8 million people in its 2025 study.[3] Many organizations need continuous alert monitoring but cannot sustain a large internal team for every shift. The cloud-based managed IDS/IPS services market offers an option to assign triage and routine response work to a specialist provider. Co-managed arrangements allow the client to retain control over security architecture and major business decisions. In the cloud-based managed IDS/IPS services market, service quality at renewal depends on better detection and response performance without added operational friction.
Restraints Impact Analysis of Managed Cloud IDS/IPS Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-Sovereignty and Outsourcing Trust Concerns | -1.80% | Europe, Asia-Pacific, Middle East and Africa, nations with data-residency mandates | Short term (≤ 2 years) |
| Tool Sprawl and Integration Complexity | -1.50% | Global | Short term (≤ 2 years) |
| Encrypted Traffic Inspection and Privacy Trade-Offs | -0.90% | Global, heightened in GDPR-regulated jurisdictions | Medium term (2-4 years) |
| MSSP Liability and Service-Level Exposure | -0.70% | Global, heightened in regulated sectors, Banking, Financial Services and Insurance and healthcare | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data-Sovereignty and Outsourcing Trust Concerns
Data-residency rules can limit how a provider collects and analyzes security telemetry across borders. The cloud-based managed IDS/IPS services market must therefore support regional delivery models for financial, government, and other sensitive workloads. Buyers may hesitate to send security logs to a provider when the logs contain data that is subject to local controls. Providers need clear controls for where data is processed, retained, and accessed. In-jurisdiction delivery and complete audit records can reduce this concern for buyers. These requirements can also raise the cost of building a compliant service footprint, favoring providers with established regional capacity.
Tool Sprawl and Integration Complexity
Security teams often operate many tools that collect overlapping data and follow different workflows. A joint IBM and Palo Alto Networks study reported that the average organization uses 83 security products from 29 vendors, while 52% identified complexity as the largest barrier to effective security. Fragmented environments can slow implementation and reduce the quality of detection available to a managed provider. Sumo Logic reported that 55% of organizations cited too many point solutions and 63% identified operating costs as their primary challenge. The cloud-based managed IDS/IPS services market needs strong integrations because client tool complexity can erode both service outcomes and provider margins. In the cloud-based managed IDS/IPS services market, consolidated data collection and clear ownership boundaries can reduce these obstacles during onboarding.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Cloud IDS/IPS Services Market Segment Analysis
By Component:
Managed Cloud Detection Anchors Revenue, Professional Services AcceleratesManaged Cloud IDS/IPS Services held 29.78% of revenue in 2026. For the cloud-based managed IDS/IPS services market, this position shows that buyers value a provider that accepts responsibility for daily detection work. They increasingly prefer managed coverage over handling signature updates, rule tuning, and alert queues on their own. Wipro expanded its partnership with Palo Alto Networks in June 2026 to offer AI-driven managed detection and response services through its CyberShield platform and 8 Cyber Defense Centers. The cloud-based managed IDS/IPS services market, therefore, rewards offerings that combine technology, trained analysts, and defined operational accountability.
Professional Services is projected to expand at a 17.84% CAGR through 2032. Complex environments need work before a managed service can operate reliably. Providers must map log sources, adapt detection logic, and redesign workflows for the client’s existing tools. CrowdStrike introduced Falcon Platform Indicators of Attack in Falcon Next-Gen SIEM in July 2026, providing maintained detections across endpoints, identities, and cloud environments. Such vendor-maintained content shifts more detection engineering from the client to the provider.



By Deployment Mode:
Public Cloud Leads, Hybrid Cloud Reflects Strategic ComplexityPublic Cloud held 36.12% of revenue in 2026. Cloud-based workloads are often easier to monitor with services designed for the same operating environment. Elastic capacity also allows clients to add coverage without the procurement cycle required for additional on-premises sensors. Private Cloud remains relevant for buyers who require dedicated infrastructure or tight control over data. Financial institutions and government organizations often maintain these environments because of residency, accreditation, and risk requirements.
Hybrid Cloud is projected to expand at a 17.66% CAGR through 2032. Many large organizations will continue to operate a mix of legacy infrastructure and public cloud workloads. The cloud-based managed IDS/IPS services market size for Hybrid Cloud is supported by the need to identify activity moving between these environments. Kyndryl opened a Cyber Defense Operations Center in Bengaluru in February 2026 to unite network and security operations for global enterprise hybrid IT environments. Integration capability is therefore a central requirement for hybrid deployments.
By Service Type:
Fully Managed Services Dominant, MDR Add-Ons Fastest GrowingFully Managed Services accounted for 53.81% of revenue in 2026. The share reflects the operational difficulty of sustaining 24/7 detection with internal staff alone. The 4.8 million cybersecurity workforce gap reported by ISC2 shows why many organizations seek a provider that can manage the full function. Co-managed services, managed rule tuning, threat hunting, and managed incident response remain relevant where large clients maintain mature internal security teams. Cisco launched Splunk Enterprise Security Premier Edition in September 2025 with tools for triage, playbook authoring, and investigation.
Managed Detection and Response Add-ons are projected to expand at a 17.79% CAGR through 2032. Clients use these services to add response and investigation capabilities to core alert monitoring. The services can expand the provider’s role within the client environment and deepen the relationship throughout the contract period. Fortinet introduced FortiSOC in March 2026 and expanded FortiGuard SOC-as-a-Service with third-party log ingestion and FortiCNAPP cloud visibility. This shows how established vendors are adding broader telemetry and response capabilities to their managed offerings.

By Organization Size:
Large Enterprises Lead, Small and Medium Enterprises AccelerateLarge Enterprises held 66.33% of revenue in 2026. These organizations tend to have larger security budgets, established vendor relationships, and formal compliance duties. Many are moving established detection teams toward co-managed models as automation reduces the advantages of handling every task internally. The IBM and Palo Alto Networks study found that organizations using unified security platforms detected incidents 72 days faster than those using best-of-breed stacks. This result strengthens the case for managed platforms that bring data and workflows together.
Small and Medium Enterprises are projected to expand at a 17.58% CAGR through 2032. These buyers need continuous monitoring, but often cannot fund large internal operations teams. Standardized services distributed through cloud marketplaces can simplify onboarding and lower the operational barrier. The cloud-based managed IDS/IPS services market offers smaller organizations access to specialized monitoring without requiring them to build a complete security operations center. Clear service tiers are important because smaller buyers need to understand what is monitored and how response responsibilities are shared.
By End-User Industry:
Banking, Financial Services and Insurance Anchors Revenue, Healthcare and Life Sciences SurgesBanking, Financial Services, and Insurance held 24.42% of revenue in 2026. This sector faces high-value attacks, demanding regulatory duties, and mature security purchasing practices. The Office of the Comptroller of the Currency identifies cybersecurity and financial system resilience as a supervisory priority for national banks and federal savings associations. The cloud-based managed IDS/IPS services market supports the sector’s need for persistent monitoring, incident investigation, and auditable procedures. Government buyers may also require domestically hosted services and certifications such as FedRAMP or ISO 27001.
Healthcare and Life Sciences are projected to expand at a 17.98% CAGR through 2032. Clinical systems hold sensitive data and cannot tolerate extended disruption. The HIPAA Security Rule requires covered entities and business associates to implement safeguards for electronic protected health information. Ransomware can turn detection and response into a patient-safety issue rather than a purely technical concern. Managed coverage can help organizations maintain monitoring when they do not have internal teams for round-the-clock operations.
Geography Analysis
North America Managed Cloud IDS/IPS Services Market
North America held 39.88% of the cloud-based managed IDS/IPS services market share in 2026. The region has a dense base of cloud-native enterprises and managed security providers. Financial-sector supervision reinforces the need for strong cybersecurity controls and timely incident management. The Office of the Comptroller of the Currency has emphasized the operational risks posed by cyber incidents to the financial system. Within the cloud-based managed IDS/IPS services market, Canada supports demand through financial services and public-sector activity, while Mexico is an emerging market as enterprise cloud use and compliance programs advance.
APAC Managed Cloud IDS/IPS Services Market
Asia-Pacific is projected to expand at a 17.13% CAGR through 2032. India, Japan, and South Korea are important sources of demand as organizations build cloud environments and address skills shortages. The cloud-based managed IDS/IPS services market size in Asia-Pacific is also influenced by regulations requiring more formal security operations. Japan reflects a shift from perimeter devices toward cloud-native monitoring. Local delivery capability remains important because national rules can restrict cross-border handling of security data.
EMEA and South America Managed Cloud IDS/IPS Services Market
Europe is shaped by the compliance duties created by the Digital Operational Resilience Act and the NIS2 Directive. South America is an emerging region, with Brazil and Argentina benefiting from financial services digitization and domestic compliance requirements. Demand in the Middle East and Africa is growing through government, energy, and financial services projects, particularly in Saudi Arabia and the United Arab Emirates. Regional data-residency expectations can favor providers that operate local or sovereign delivery models.
Competitive Landscape
Market Concentration
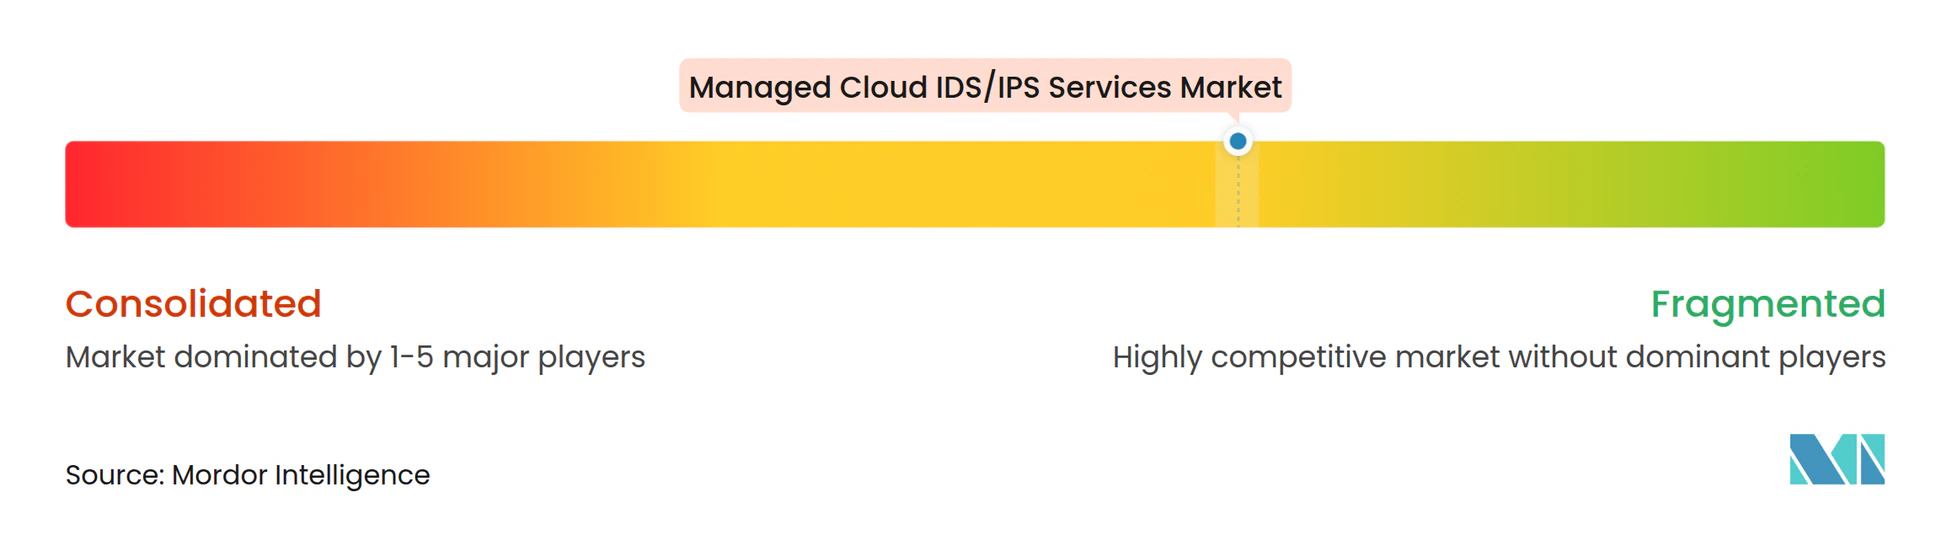
The cloud-based managed IDS/IPS services market is moderately fragmented. Hyperscale cloud providers, security platform vendors, and global information technology services firms serve different client requirements. Amazon.com, Microsoft, Google, Palo Alto Networks, CrowdStrike, Fortinet, Check Point, Accenture, Tata Consultancy Services, Wipro, and Kyndryl are among the active providers. Platform vendors extend managed detection through their security stacks, while services firms package it within wider outsourcing relationships. Opportunity remains in mid-market organizations and regulated sectors in emerging economies that need locally compliant delivery.
Palo Alto Networks announced an agreement to acquire CyberArk in July 2025 for USD 25 billion in equity value. The planned combination brings identity security together with its network and security operations platforms. Fortinet’s March 2026 FortiSOC release added a cloud-delivered operations platform with expanded third-party log ingestion and cloud visibility. These moves show that larger vendors are broadening the data and response capabilities around intrusion detection. Providers that offer interoperable tools can reduce the buyer’s need to engage separate specialists.
Information technology services firms compete through integration capability, regional delivery, and flexible co-managed options. Wipro expanded its Palo Alto Networks partnership in June 2026, combining Cortex XSIAM with its CyberShield platform and SOC GURU runbook framework. Kyndryl opened its Bengaluru Cyber Defense Operations Center in February 2026 for hybrid enterprise environments. ISO 27001, SOC 2 Type 2, and FedRAMP can favor providers with established certifications and local delivery capacity.
Managed Cloud IDS/IPS Services Industry Leaders
-
Cisco Systems, Inc.
-
Palo Alto Networks, Inc.
-
Fortinet, Inc.
-
Check Point Software Technologies Ltd.
-
International Business Machines Corporation
- *Disclaimer: Major Players sorted in no particular order
Managed Cloud IDS/IPS Services Market Companies Covered in this Report
- Cisco Systems, Inc.
- Palo Alto Networks, Inc.
- Fortinet, Inc.
- Check Point Software Technologies Ltd.
- International Business Machines Corporation
- Microsoft Corporation
- Amazon.com, Inc.
- Google LLC
- Trend Micro Incorporated
- CrowdStrike Holdings, Inc.
- Broadcom Inc.
- AT&T Inc.
- Verizon Communications Inc.
- Secureworks Corp.
- NTT Security Holdings Corporation
- Accenture plc
- Tata Consultancy Services Limited
- Wipro Limited
- Kyndryl, Inc.
- Orange Cyberdefense
Recent Industry Developments in Managed Cloud IDS/IPS Services Market
- July 2026: CrowdStrike launched Falcon Platform Indicators of Attack (IOAs) to general availability in Falcon Next-Gen SIEM, delivering CrowdStrike-maintained, adversary-driven detections across endpoints, identities, and cloud environments. The capability shifts detection-content engineering from client security teams to CrowdStrike, accelerating coverage of zero-day threats and reducing operational burden on managed service buyers.
- June 2026: Wipro expanded its partnership with Palo Alto Networks to offer AI-driven MDR services, combining Palo Alto Networks' Cortex XSIAM with Wipro's CyberShield managed security platform and the proprietary SOC GURU runbook framework, delivered through 8 global Cyber Defense Centers.
- April 2026: NWN launched an AI-enabled managed security operations suite as Top National Partner with Cisco, Arctic Wolf, and Palo Alto Networks, bundling MDR, offensive security, ransomware protection, and vCISO consulting into a unified service model.
- April 2026: German providers Guardsix and SpaceNet formed a strategic partnership to deliver a Managed SIEM service across Germany and Europe, combining Guardsix's analytics platform with SpaceNet's sovereign IT operations expertise to address NIS 2 and DORA compliance obligations.
Global Managed Cloud IDS/IPS Services Market Report Scope
The Managed Cloud IDS/IPS Services Market Report is Segmented by Component (Solutions, Services, Managed Cloud IDS/IPS Services, and Professional Services), Deployment Mode (Public Cloud, Private Cloud, and Hybrid Cloud), Service Type (Fully Managed Services, Co-Managed Services, Managed Detection and Response Add-ons, Managed Rule Tuning and Threat Hunting, and Managed Incident Response), Organization Size (Large Enterprises and Small and Medium Enterprises), End User Industry (Banking, Financial Services and Insurance, Government and Defense, Healthcare and Life Sciences, IT and Telecom, Retail and E-Commerce, Manufacturing and Industrial, and Other End User Industry), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). The Market Forecasts Are Provided in Terms of Value (USD).
Segmentation Overview
| Solutions |
| Services |
| Managed Cloud IDS/IPS Services |
| Professional Services |
| Public Cloud |
| Private Cloud |
| Hybrid Cloud |
| Fully Managed Services |
| Co-Managed Services |
| Managed Detection and Response Add-ons |
| Managed Rule Tuning and Threat Hunting |
| Managed Incident Response |
| Large Enterprises |
| Small and Medium Enterprises |
| Banking, Financial Services and Insurance |
| Government and Defense |
| Healthcare and Life Sciences |
| IT and Telecom |
| Retail and E-Commerce |
| Manufacturing and Industrial |
| Other End User Industry |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| South Africa | |
| Egypt | |
| Rest of Middle East and Africa |
| By Component | Solutions | |
| Services | ||
| Managed Cloud IDS/IPS Services | ||
| Professional Services | ||
| By Deployment Mode | Public Cloud | |
| Private Cloud | ||
| Hybrid Cloud | ||
| By Service Type | Fully Managed Services | |
| Co-Managed Services | ||
| Managed Detection and Response Add-ons | ||
| Managed Rule Tuning and Threat Hunting | ||
| Managed Incident Response | ||
| By Organization Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By End User Industry | Banking, Financial Services and Insurance | |
| Government and Defense | ||
| Healthcare and Life Sciences | ||
| IT and Telecom | ||
| Retail and E-Commerce | ||
| Manufacturing and Industrial | ||
| Other End User Industry | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| South Africa | ||
| Egypt | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the size of the cloud-based managed IDS/IPS services market?
The cloud-based managed IDS/IPS services market was valued at USD 1.88 billion in 2026 and is projected to reach USD 4.43 billion by 2032, at a 15.24% CAGR from 2027 to 2032.
What is driving demand for managed intrusion detection and prevention services?
Multi-cloud environments, continuous compliance requirements, and shortages of cybersecurity personnel are increasing demand for outsourced 24/7 monitoring.
Which service type leads managed IDS/IPS demand?
Fully Managed Services held 53.81% of revenue in 2026, reflecting the need for providers to take full responsibility for daily monitoring and response work.
Which deployment model is expanding fastest?
Hybrid Cloud is projected to expand at a 17.66% CAGR through 2032 because enterprises continue to operate both legacy infrastructure and public cloud workloads.
Which end-user sector is expanding fastest?
Healthcare and Life Sciences is projected to expand at a 17.98% CAGR through 2032, supported by the need to protect clinical systems and sensitive health information.
Which region is expanding fastest for managed IDS/IPS services?
Asia-Pacific is projected to expand at a 17.13% CAGR through 2032, supported by cloud adoption, security skills shortages, and more formal cyber-resilience requirements.