
Low Density Polyethylene Market Analysis by Mordor Intelligence
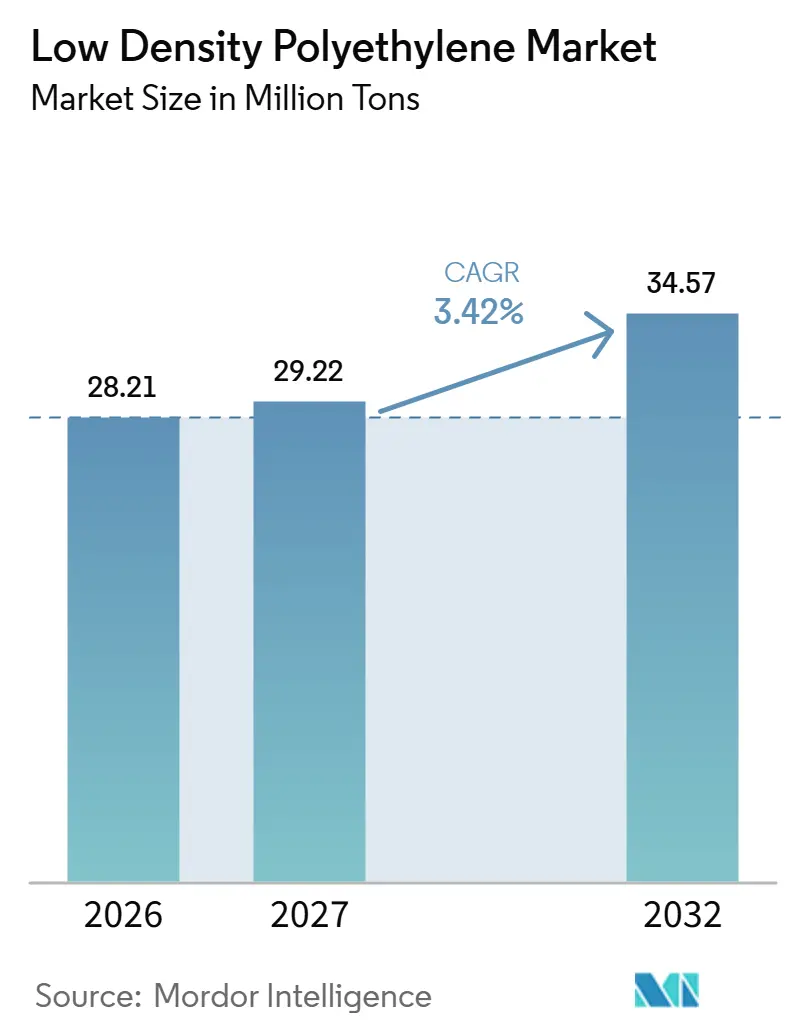
The low density polyethylene market size is expected to increase from 28.21 million tons in 2026 to 29.22 million tons in 2027 and reach 34.57 million tons by 2032, growing at a CAGR of 3.42% over 2027-2032.
Film demand from online shipping and agricultural use creates a resin outlet, but recycled-content specifications make the material mix commercially important. Supplier responses can combine application development in China with resin formulations suited to future packaging-content and design requirements. The Middle East conflict following U.S. and Israeli bombing of Iranian targets on February 28, 2026, raised European feedstock costs and pressured converter cost recovery. Growth therefore favors producers that qualify LDPE for recycled-content packaging and coating uses, while suppliers of readily replaceable grades face substitution and feedstock-cost pressure.
Key Report Takeaways
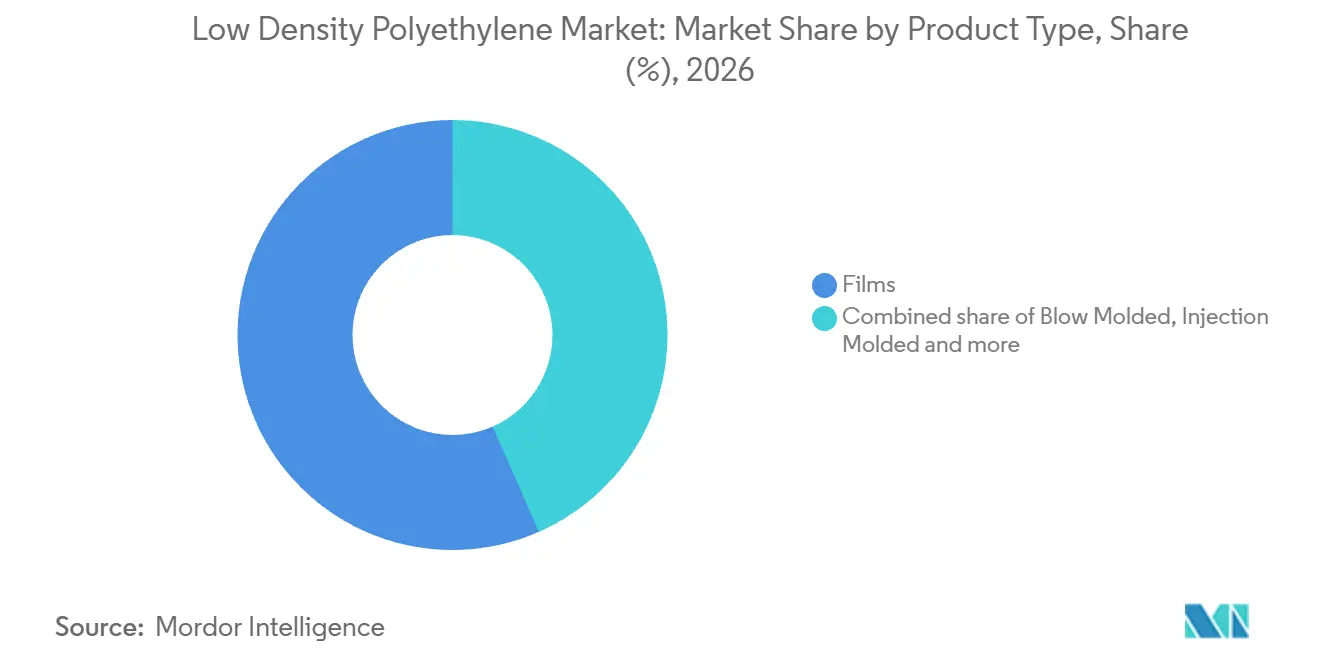
- By product type, films held a 56.58% low density polyethylene market share in 2026, while wire and cable insulation is the fastest-growing segment at a forecast CAGR of 4.1% over 2027-2032.
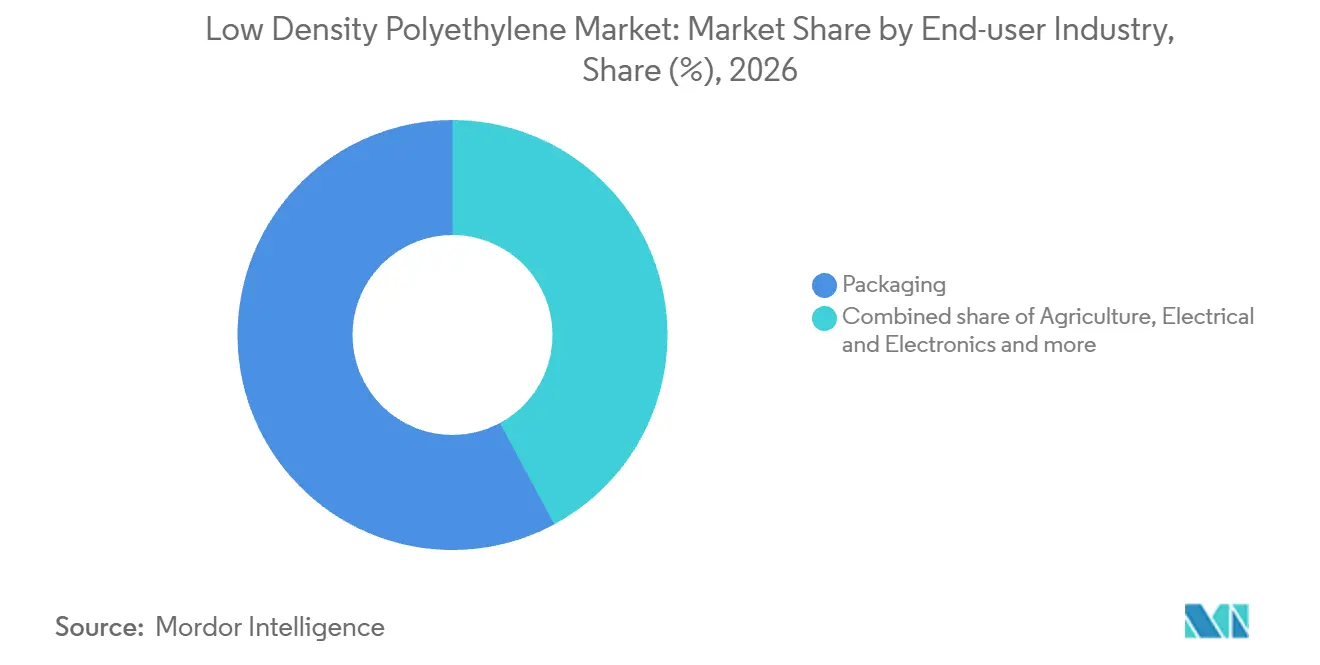
- Among end-user industries, packaging accounted for a 57.86% share of the low density polyethylene market size in 2026, and healthcare and pharma is the fastest-growing segment with a CAGR of 4.05% over 2027-2032.
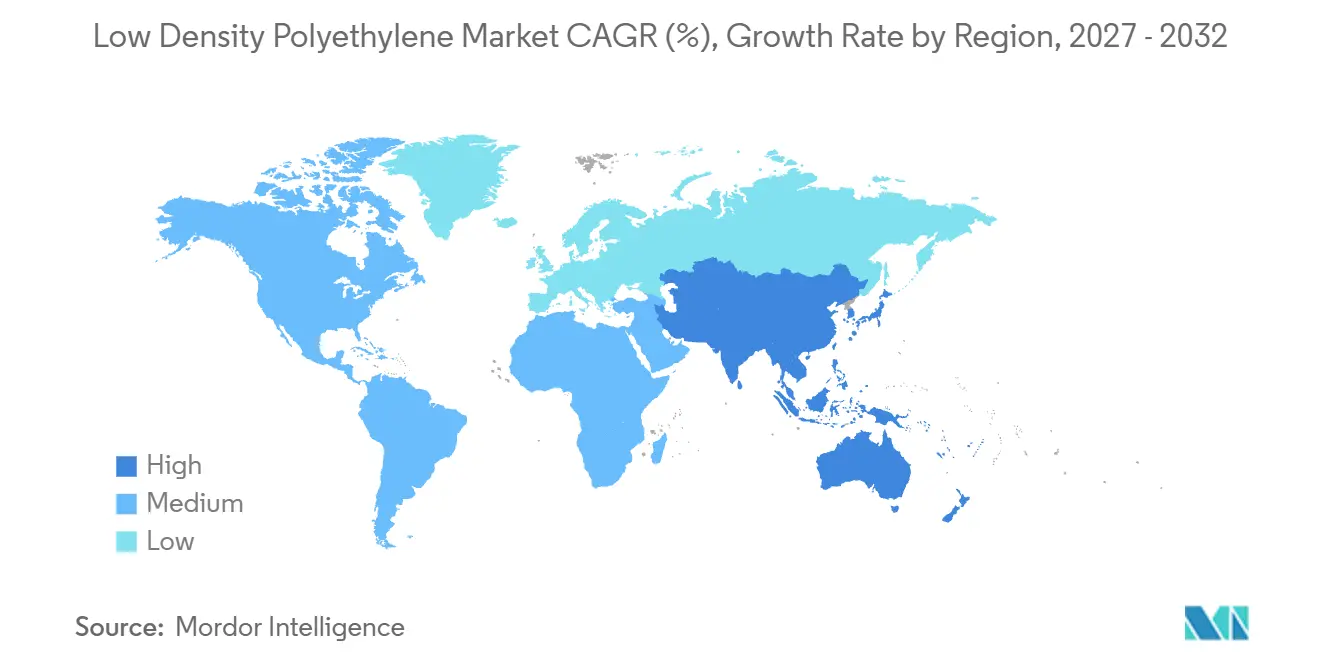
- Geographically, Asia-Pacific led with a 47.77% share in 2026 and is also the fastest-growing region, with a forecast CAGR of 4.3% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Low Density Polyethylene Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth in e-commerce flexible packaging | +1.8% | Continental Europe | Short term (≤ 2 years) |
| Rising demand for agricultural films | +1.5% | United States and China | Medium term (2-4 years) |
| Preference for extrusion-coated applications | +1.3% | Mainland China and Southeast Asia | Short term (≤ 2 years) |
| Solar-panel encapsulant film uptake | +0.3% | India | Long term (≥ 4 years) |
| Advanced recycling enabling premium LDPE grades | +0.2% | Australia | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growth in e-commerce flexible packaging
Outbound mailer use can expand demand for LDPE films as online retailers increase their shipping-packaging requirements. ABOUT YOU used 1,020.7 metric tons of LDPE poly mailers for outbound shipping in FY 2024/2025, compared with 886.9 metric tons in FY 2023/2024. Its mailer weight rose about 15% year over year. The retailer said its poly mailers contained more than 90% post-consumer recycled material, with smaller additive proportions that were difficult to reduce. Higher mailer tonnage creates a larger downstream outlet for converters supplying this application. For converters buying resin for those mailers, supporting greater film output must go together with meeting the retailer's recycled-content specification.
Rising demand for agricultural films
Agricultural-film demand is tied to weed and water management as well as the expansion of covered cultivation. Commercially available mulch films in the United States are typically made from LDPE and used mainly on fruit and vegetable cash crops.[1] These films help control weeds, increase soil temperature, and reduce water loss. In Weifang, China, mapped plastic-covered greenhouse area increased 21.3% to 752 square kilometers from 2016 to 2025. Soil-cover applications and protected cultivation create distinct routes for suppliers serving agricultural buyers. Any substitute for LDPE mulch must therefore match its weed control, soil warming, and water retention, which sets the performance bar a substitute resin must meet.
Preference for extrusion-coated applications
Coating-market development can broaden an LDPE producer's commercial reach without requiring entry into another resin category. Asia Polymer reported total LDPE sales of 27,538 metric tons in H1 2026, a 7-year high. The producer also described continued development of coating markets in mainland China and Southeast Asia. For a supplier with an operating LDPE sales base, targeting coating converters creates an application-specific route to additional customers across those destinations. The opportunity depends on converting that market development into coating-grade resin orders.
Solar-panel encapsulant film uptake
An LDPE supplier can gain from encapsulant-film uptake only where module specifications include its resin. The relevant buyer is the converter making the specified film, so module capacity provides only an indirect guide to resin opportunity. For any qualifying formulation, sales potential depends on its LDPE content and the amount of encapsulant film required by each module design. A converter expanding output with an unchanged formulation would create a different resin requirement from one changing its material mix at the same production volume. This distinction makes formulation inclusion and resin intensity more useful commercial entry criteria than solar installation totals alone.
Restraints Impact Analysis of Low Density Polyethylene Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Competition from LLDPE and HDPE | -0.8% | Italy | Short term (≤ 2 years) |
| Ethylene feedstock price volatility | -0.6% | Europe | Short term (≤ 2 years) |
| European Union's 2030 bans on certain single-use polyolefin films | -0.35% | European Union member states | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Competition from LLDPE and HDPE
Price premiums expose LDPE demand to substitution wherever competing grades can satisfy the same technical specifications. In February 2026, some Italian buyers opted for mLLDPE or LLDPE instead of LDPE amid LDPE's price premium, where technical specifications allowed. This response shows that a higher LDPE price can move an order to another polymer wherever the specification permits. For suppliers serving these applications, the pricing decision therefore carries a volume risk beyond the immediate price negotiation. Technical requirements limit that exposure by determining which orders can move to linear grades. The resulting constraint is concentrated in replaceable applications, where maintaining a premium can mean surrendering resin sales.
Ethylene feedstock price volatility
The Middle East conflict following U.S. and Israeli bombing of Iranian targets on February 28, 2026, disrupted supply chains and raised European feedstock costs. The European ethylene contract price for April 2026 delivery rose 39% from March.[2] In April 2026, many European converters reduced polyethylene purchases to below 50% of normal levels as higher costs became difficult to pass on. The broader polyethylene price rally began with LDPE before extending to other grades. The resulting purchasing pressure shows how upstream cost increases can constrain orders when converters lack equivalent selling-price recovery. Higher resin prices can therefore coexist with reduced physical sales to converters caught between upstream and downstream prices.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Low Density Polyethylene Market Segment Analysis
By Product Type:
Films Lead While Cable Applications ExpandFilms accounted for a 56.58% share of the low density polyethylene market size in 2026. Westlake Corporation reported annual rated LDPE capacity of 1.5 billion pounds at Lake Charles, Louisiana, and Longview, Texas, as of February 18, 2026. Its LDPE end uses include shrink films, food packaging, and coated paperboard alongside other applications. The producer sells polyethylene to external customers as pelletized resin. Because that capacity also serves coated paperboard, closures, and general purpose molding, the total sets an upper bound on the resin pool available to film converters.
Wire and cable insulation is the fastest-growing segment, with a forecast CAGR of 4.1% over 2027-2032. A 2025 industry analysis identified cable undergrounding, cross-regional power transmission, and offshore wind as forces expected to expand China's cable-specific LDPE demand during its 15th Five-Year Plan. For resin suppliers, this links application growth to investment in power delivery and connection assets. The analysis also forecasts stronger demand growth for high- and ultra-high-voltage grades than for cable-specific LDPE overall. Producers selling high- and ultra-high-voltage grades are therefore exposed to the faster part of that forecast.



By End-user Industry:
Packaging Scale Meets Pharmaceutical SpecializationPackaging represented a 57.86% low density polyethylene market share in 2026. Rompetrol Rafinare S.A. produced 31,506 metric tons of LDPE across its grades in Romania in 2025. Its LDPE grade mix included B21/05 for liquid-packaging film, alongside heat-shrinkable-film grades, connecting its production to more than one packaging format. The producer reported stable operation of its LDPE and polypropylene units in H1 2026. Thin-film and thick-bag grades broaden the range of film requirements packaging buyers can source from this Romanian producer.
Healthcare and pharma is the fastest-growing segment, with a forecast CAGR of 4.05% over 2027-2032. The Ritedose Corporation forms LDPE ampoules, fills them with sterile liquid medicines, and seals them through aseptic blow-fill-seal processing. By January 2026, it had installed 2 additional high-speed lines adding 360 million unit doses of capacity for ophthalmic and respiratory medications. U.S. drug manufacturers must use protective containers and follow written specifications and test methods, with sterilization where required by the drug's nature. Added drug-manufacturing capacity can create more LDPE container demand, with pharmaceutical quality requirements setting the conditions for commercial supply.

Geography Analysis
Asia-Pacific Low Density Polyethylene Market
Asia-Pacific held a 47.77% low density polyethylene market share in 2026 and is the fastest-growing region, with a forecast CAGR of 4.3% over 2027-2032. Asia Polymer Corporation operated its LDPE production in Taiwan at full capacity in Q1 2026 except for routine maintenance. The producer's LDPE sales during that quarter exceeded levels seen in recent years. It also actively expanded export-market development in January and February 2026. China's Yulongdao Refining & Petrochemical Phase 2 added regional capacity through its mid-January 2026 EVA-LDPE startup, with combined nameplate capacity of 300,000 metric tons per year.
North America's LDPE supply base includes LyondellBasell's Morris plant in Illinois, which also produces other polyethylene grades. In Europe, Rompetrol Rafinare restarted its Romanian LDPE plant in 2025 and delivered 26,311 metric tons of LDPE to domestic and export customers during the year. Rompetrol's 2025 deliveries were split 54% domestic and 46% export, so international orders formed a nearly equal second outlet. The restarted unit's commercial value therefore rests on retaining domestic buyers and preserving export market access.
South America's supplier base includes Braskem S.A.'s LDPE unit in Cubatão, São Paulo, Brazil. Across Braskem's Brazil/South America crackers, Q4 2025 utilization fell from Q3 amid lower São Paulo feedstock supply, Bahia maintenance completed in January 2026, and production adjustments for seasonally lower demand. Middle-East and Africa includes Saudi Kayan Petrochemical Company's Jubail operations, where LDPE was among the key products contributing to the producer's revenue in 2025. For Saudi Kayan's LDPE offering, packaging films, bags, and food containers are potential application outlets. Its packaging exposure therefore spans several finished formats within a wider petrochemical business.
Regional Editions
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of converters using virgin LDPE in agricultural and packaging films. The rules connect commercial access to film specifications, extended producer responsibility (EPR), or post-consumer recycled (PCR) content. A duty placed on the packaging manufacturer creates a different exposure from a collection duty placed on the agricultural-film user. Transition dates determine when converters face additional material specifications or administrative requirements.
Regulatory Table of Low Density Polyethylene Market
| Decision factor | China | United States | Germany | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Local market-regulation authorities for product quality; agriculture authorities for use and recovery | CalRecycle in California | Zentrale Stelle Verpackungsregister for EPR authorization | Ministry of the Environment and Climate Change (MMA) for collective-system authorization | Minister of Forestry, Fisheries and the Environment |
| Key instruments or direction | Plastics-control opinion; Agricultural Film Management Measures; 2026 mandatory mulch-film standard revision project with a 12-month project period | California SB 54 rules, effective May 1, 2026, with targets through 2032 | Packaging and Packaging Waste Regulation (PPWR) authorization procedure for packaging not subject to system participation | Decree 12.688/2025; content obligations began in January 2026 for large companies and July 2026 for small and medium-sized companies | Plastic carrier and flat bag regulations, Notice 317 |
| Commercial effect | PE agricultural mulch film thinner than 0.01 mm prohibited; manufacturers keep sales records; users recover non-biodegradable agricultural film | California producers must achieve 25% less single-use plastic and recyclable or compostable packaging by 2032 | From January 1, 2028, covered producers require ZSVR authorization, with prior transition periods; obligations may be fulfilled directly or through a producer-responsibility organization | Manufacturers, importers, distributors and sellers finance proportionate reverse logistics; manufacturers and importers face 22% recycled content in 2026 and 24% in 2027; specific-rule exemptions apply, with food-contact packs covered where law permits PCR under MMA guidance | Specified bags require at least 75% post-consumer recyclate from 2025 and 100% from January 1, 2027; persons unable to meet the 2027 level may apply for exemption |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Low |
| Future direction of policy attractiveness | Hardening | Hardening | Hardening | Hardening | Hardening |
| Source: Mordor Intelligence | |||||
China's existing product rules support Medium attractiveness, while its 2026 standards project would add mandatory requirements for additional mulch-film types and weathering performance. California's producer obligations and 2032 targets support a Medium assessment with a hardening direction for converters serving that state. Germany's Medium rating reflects the administrative preparation associated with authorization for packaging outside system participation from January 2028. Brazil's financing duties support Medium, while South Africa's 75% bag minimum supports Low, with both hardening through their scheduled 2027 recycled-content increases.
Value Chain Stages
Value capture is compared across ethylene supply, LDPE resin manufacturing, and downstream film or packaging conversion. LDPE resin is produced by polymerizing ethylene at high pressure in autoclave or tubular reactors. Asia Polymer's domestic sales were mainly LDPE in 2025, while ethylene-vinyl acetate (EVA) was its main export product. Buyers of those resins included converters and trading companies, placing resin sales before the sale of converted film or packaging.
Value Chain Analysis Table of Low Density Polyethylene Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Ethylene production | Ethylene producers such as LyondellBasell Industries Holdings BV | Ethylene sales | Exposure to feedstock and resin-price movements | Link commercial pricing terms to feedstock movements |
| LDPE polymerization | Resin producers such as Asia Polymer Corporation and LyondellBasell Industries Holdings BV | LDPE resin sales | Dependence on high-pressure reactor assets | Coordinate reactor maintenance with grade-production schedules |
| Film and packaging conversion | Polyethylene-film producers such as Ecoplast Limited; aseptic packaging converters such as UFlex Limited | Film and converted-packaging sales | Matching resin processing to film and laminate specifications | Qualify resin grades for the selected conversion route |
| Source: Mordor Intelligence | ||||
PTT Global Chemical PLC reported an average LDPE price of USD 1,121 per metric ton in 2025, down from USD 1,182 in 2024.[3] The reported LDPE-to-ethylene spread widened from USD 219 to USD 282 per metric ton over the same period. PTTGC's reported resin-price premium over ethylene therefore increased by USD 63 per metric ton while its LDPE price fell by USD 61 per metric ton.
Competitive Landscape
Market Concentration
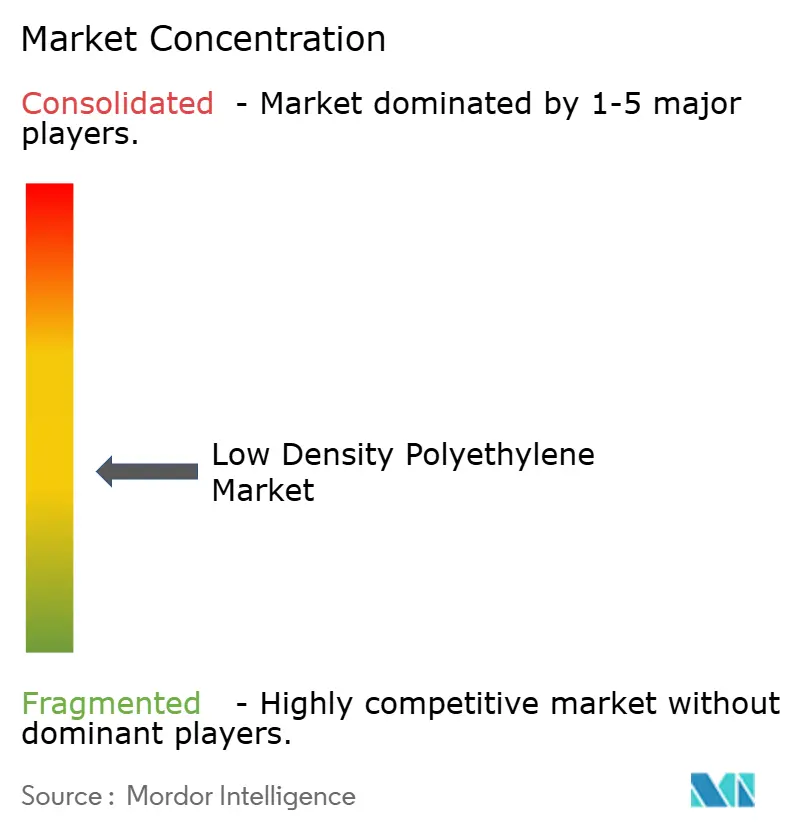
Major participants include ExxonMobil Corporation, LyondellBasell Industries Holdings BV, which supplies LDPE resins, Dow, SABIC, and China Petrochemical Corporation. ExxonMobil started its wholly owned Huizhou complex in Guangdong Province, China, in 2025, with 3 polyethylene and 2 polypropylene lines totaling more than 2.5 million metric tons of combined annual capacity. Built as China's first 100% foreign-owned petrochemical complex, the facility was intended to serve domestic polyethylene and polypropylene demand being met by imports. The local production base gives ExxonMobil a manufacturing route to those buyers alongside imported supply.
LDPE-unit availability shapes the supply alternatives open to converters within a large producer's broader polymer portfolio. CCFGroup's schedule for July 6, 2026, listed Sinopec Yanshan Petrochemical's LDPE unit in China as shut since May 25, 2025. The named operator's unit had rated annual capacity of 380,000 metric tons. An idle LDPE unit can create a commercial opening for competing suppliers whose operating assets and grades provide a suitable alternative for converter orders. Any orders left open during such a shutdown can move only to producers with spare LDPE capacity in grades converters already accept.
Application-specific healthcare grades and restrictions on convenience packaging create different competitive conditions for resin suppliers. In November 2025, Borouge launched the first Made-in-UAE healthcare LDPE at Ruwais, using Borealis' Bormed technology for an additive-free grade engineered for blow-fill-seal bottles and ampoules. From January 1, 2030, Regulation (EU) 2025/40 will bar operators from placing single-use plastic grouped packaging encouraging point-of-sale multi-item purchases on the EU market, except packaging necessary for handling. For suppliers, the relevant boundary is the packaging use rather than the polymer alone. The restriction narrows the outlet for collation films and shrink wrap used for that convenience grouping, while leaving grouped packaging needed for handling untouched.
Low Density Polyethylene Industry Leaders
-
ExxonMobil Corporation
-
LyondellBasell Industries Holdings BV
-
Dow
-
SABIC
-
China Petrochemical Corporation
- *Disclaimer: Major Players sorted in no particular order
Low Density Polyethylene Market Companies Covered in this Report
- Borealis AG
- Braskem S.A.
- Chevron Phillips Chemical Company LLC
- China Petrochemical Corporation
- Dow
- ExxonMobil Corporation
- Formosa Plastics Corporation
- Hanwha Solutions Corporation (Chemical Division)
- INEOS Group
- LG Chem
- LyondellBasell Industries Holdings BV
- Mitsui Chemicals, Inc.
- NOVA Chemicals Corporation
- PetroChina
- PTT Global Chemical PLC
- Qatar Chemical Company Ltd
- Reliance Industries Limited
- Repsol S.A.
- SABIC
- Sumitomo Chemical Co., Ltd.
- TotalEnergies SE
- Versalis S.p.A. (Eni)
- Westlake Corporation
Key Opportunities for Market Participants
Opportunities are compared for LDPE resin suppliers serving packaging converters under EU material-content and design requirements. The Packaging and Packaging Waste Regulation has applied since August 12, 2026, with recycled-content and design obligations on later schedules. Constantia Flexibles commissioned a 5-layer blown-film line in Pirk, Germany, in 2025 to produce PE-based mono-material packaging films. The relevant opening for LDPE suppliers is to support additional converter formulations, with material evidence and design performance treated as parts of the resin offer.
Market Opportunities Table of Low Density Polyethylene Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| LDPE resins with post-consumer inputs for mailer films | Applicable EU recycled-content minima from January 1, 2030, or 3 years after the relevant implementing act enters into force, whichever is later | Converters of non-contact-sensitive mailer films for ordinary goods | Qualify LDPE input mixtures and verify recycled content on the applicable plant-and-year basis | Formulation qualification and verified post-consumer input accounting | Recycled-LDPE suppliers and mailer-film converters |
| LDPE resins for mono-material packaging redesign | EU design-for-recycling requirements from January 1, 2030, or 24 months after the relevant delegated acts enter into force, whichever is later | Flexible-packaging converters serving ordinary consumer products | Develop LDPE grades and film structures against applicable packaging recyclability criteria | Achieving a qualifying packaging recyclability assessment | LDPE resin suppliers; PE-film converters such as Constantia Flexibles |
| LDPE resin offers with documented material inputs | Commission timeline schedules recycled-content calculation methods by December 31, 2026 | Packaging converters preparing recycled-input records | Supply LDPE with input-composition records aligned with the applicable calculation rules | Verification of input records against implementing-act methods | LDPE suppliers with verifiable material-composition records |
| Source: Mordor Intelligence | |||||
Recycled content and recyclability create separate qualification tests for an LDPE resin offer. The calculation methodology and design criteria have scheduled milestones of December 31, 2026, and January 1, 2028, respectively. Suppliers can therefore pursue converter qualification before the later packaging obligations apply, with the central opening in resin formulations supported by verifiable material data.
Recent Industry Developments in Low Density Polyethylene Market
- Aug 2026: Asia Polymer reported H1 2026 total LDPE sales of 27,538 metric tons, a 7-year high, and continued development of coating markets in mainland China and Southeast Asia.
- Aug 2026: The EU Packaging and Packaging Waste Regulation began applying across member states on August 12, 2026.
- Jan 2026: Yulongdao Refining & Petrochemical Phase 2 started up an EVA-LDPE unit in China in mid-January with combined nameplate capacity of 300,000 metric tons per year.
Low Density Polyethylene Market Report Scope and Research Methodology
Market Definition and Coverage
Low density polyethylene market measures annual volumes of low density polyethylene resin sold to converters globally, in tons. These sales are classified by converted product form, end-user industry, and region of demand.
Scope exclusions: Linear low-density polyethylene and high-density polyethylene resin, ethylene feedstock, ethylene-vinyl acetate resin, and finished plastic products made with LDPE are excluded.
Segments Covered in This Report
- By Product Type
- Blow Molded
- Films
- Injection Molded
- Sheets
- Foams
- Wire and Cable Insulation
- By End-user Industry
- Agriculture
- Electrical and Electronics
- Packaging
- Construction
- Automotive
- Consumer Goods
- Healthcare and Pharma
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Qatar
- United Arab Emirates
- Nigeria
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Public datasets provide indicators for resin supply and the downstream uses that draw on it. Illustrative public sources such as Eurostat, which reports plastic packaging waste in metric tons, and United Nations Comtrade, which records HS 390110 trade for polyethylene with a density below 0.94 and serves as a directional resin-trade check because that customs category does not isolate LDPE from all linear grades, are complemented by World Bank industry and manufacturing value-added series for comparing industrial demand across countries and by Plastics Europe reporting on regional plastics production, conversion, consumption, trade, and circularity trends.
Company filings, annual reports, investor materials, and reputable trade press can cross-check producer capacity, outages, end-use developments, and market conditions. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews with resin producers, distributors, converters, and procurement or technical leads would clarify grade use, order patterns, capacity utilization, and changes in application demand across global regions. Structured surveys of market participants would test secondary-source assumptions on product, end-user, and regional shares, while follow-up questions would resolve material differences between reported sales, output, and converter requirements. Where a response or public series is unavailable, analysts would retain a documented range and triangulate it with trade, capacity, and downstream indicators before using it in the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 45% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates annual global tons of LDPE resin sold to converters, then splits that total by converted product form, end-user industry, and demand region. A top-down demand view is built from packaging film and converter activity, agricultural film use, grid and cable investment, industrial output, and reported LDPE capacity and utilization. Eurostat packaging indicators, World Bank industrial activity, trade flows, producer disclosures, and public project information provide observable checks, with customs data treated only as a directional signal where its resin classification is broader than LDPE.
Scenario analysis carries the 2027 volume base through 2032 by varying the pace of packaging and industrial demand, resin substitution, capacity availability, and application growth. Segment shares are derived from reported application mixes, end-use disclosures, regional production and trade balances, and evidence on where converters consume LDPE, then checked so each view reconciles to the global total. Selective bottom-up checks compare producer sales or capacity-based supply roll-ups with regional demand signals, and sampled selling prices are used only to check unit consistency rather than to replace the volume model. When local or segment data are missing, analysts use the nearest supported indicator, document the range, and retain the top-down total as the anchor. Interviews and survey responses would test variable-level forecasts and challenge assumptions about application substitution, utilization, and regional demand before estimates are finalized.
Data Validation & Update Cycle
Analysts triangulate the global estimate against producer output and sales, trade flows, converter activity, and independent end-use indicators, then investigate material variances by checking units, geography, timing, grade definition, and duplicate distributor transactions. Anomalies are resolved through source review and, where a material discrepancy remains, follow-up with the relevant respondent. Analysts record the explanation and complete a second review before sign-off. The model is refreshed annually, reopened between cycles when a material capacity, regulatory, or demand event changes the outlook, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Low Density Polyethylene Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Low density polyethylene market measures annual volumes of low density polyethylene resin sold to converters globally, in tons.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Eurostat packaging indicators, World Bank industrial activity, trade flows, producer disclosures, and public project information provide observable checks, with customs data treated only as a directional signal where its resin classification is broader than LDPE.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | 29.22 million tons (2027) | |
| Global Consultancy A | 25.1 million tons (2025) | At its 2025 base, this estimate is 14.1% below this report's 2027 value of 29.22 million tons, 2 years later. Its earlier market-volume base and stated forecast path imply a lower intervening-year total. |
| Global Consultancy B | 18.3422 million tons (2024) | At its 2024 base, this estimate is 37.2% below this report's 2027 value of 29.22 million tons, 3 years later. The estimate covers LDPE packaging applications only, and its earlier base year also contributes to a lower total. |
Mordor Intelligence's analysts triangulate the global estimate against producer output and sales, trade flows, converter activity, and independent end-use indicators, then investigate material variances by checking units, geography, timing, grade definition, and duplicate distributor transactions.
Key Questions Answered in the Report
What is the low density polyethylene market size and growth outlook?
The market is projected at 29.22 million tons in 2027 and 34.57 million tons in 2032, with a CAGR of 3.42% over 2027-2032.
What supports demand for LDPE flexible packaging?
E-commerce shipping supports demand for LDPE films. ABOUT YOU used 1,020.7 metric tons of LDPE outbound poly mailers in FY 2024/2025.
Which LDPE product type has the largest share?
Films led with 56.58% of the 2026 resin-volume total. Wire and cable insulation is the fastest-growing segment, with a CAGR of 4.1% over 2027-2032.
Who are the leading LDPE resin suppliers?
Major suppliers include ExxonMobil Corporation, LyondellBasell Industries Holdings BV, Dow, SABIC, and China Petrochemical Corporation.
What constrains LDPE demand?
Feedstock costs and resin substitution constrain demand. Europe's ethylene contract price for April 2026 delivery rose 39% from March.
Which region leads LDPE resin demand?
Asia-Pacific held 47.77% of the 2026 total and is also the fastest-growing region, with a CAGR of 4.3% over 2027-2032.