
Instant Coffee Market Size and Share
Instant Coffee Market Analysis by Mordor Intelligence
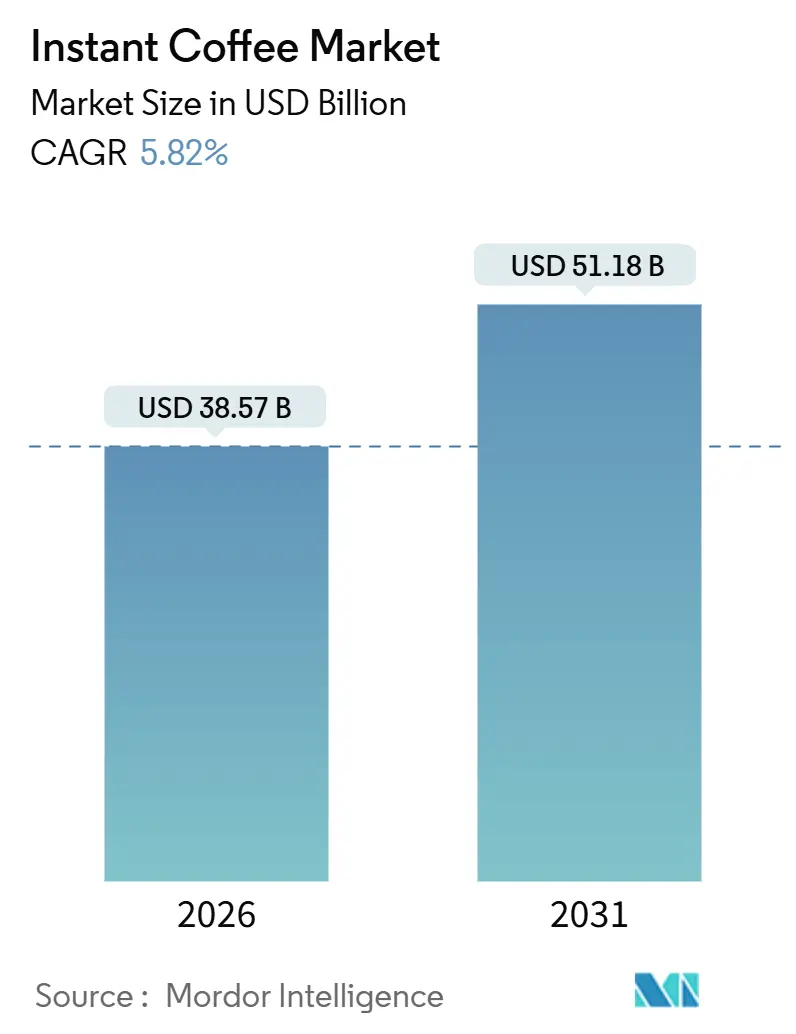
The instant coffee market size is expected to increase from USD 38.57 billion in 2026 to USD 40.81 billion in 2027 and reach USD 54.46 billion by 2032, growing at a CAGR of 5.94% over 2027-2032.
Convenient soluble preparation, including cold-water formats in Japan, is widening the occasions on which coffee is bought. Additional processing capacity and contract packing give brands more ways to build that offer through specialized suppliers. Nutritional positioning and ready-to-drink competition can limit that opportunity by affecting promotion and the preparation effort demanded of consumers. Growth therefore favors suppliers that pair a distinctive drink format with access to soluble capacity.
Key Report Takeaways
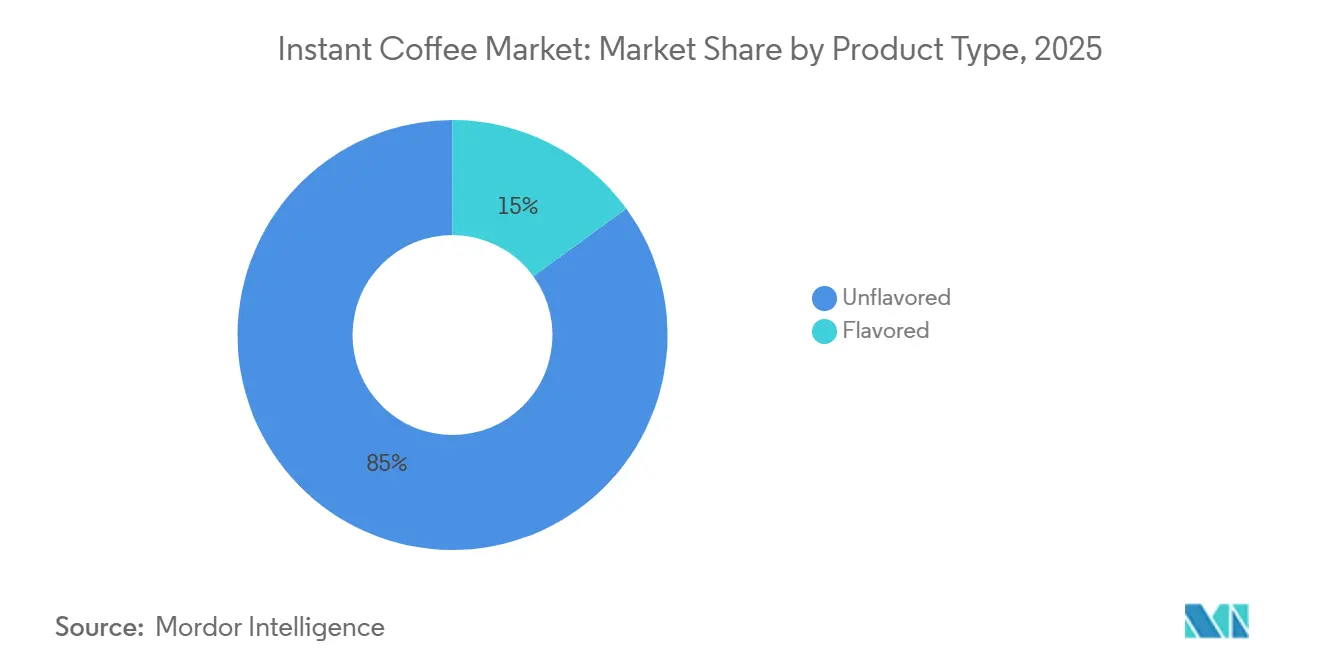
- Within product types, unflavored coffee held an 84.75% instant coffee market share in 2026, while flavored coffee is forecast to grow fastest at a CAGR of 7.8% during 2027-2032.
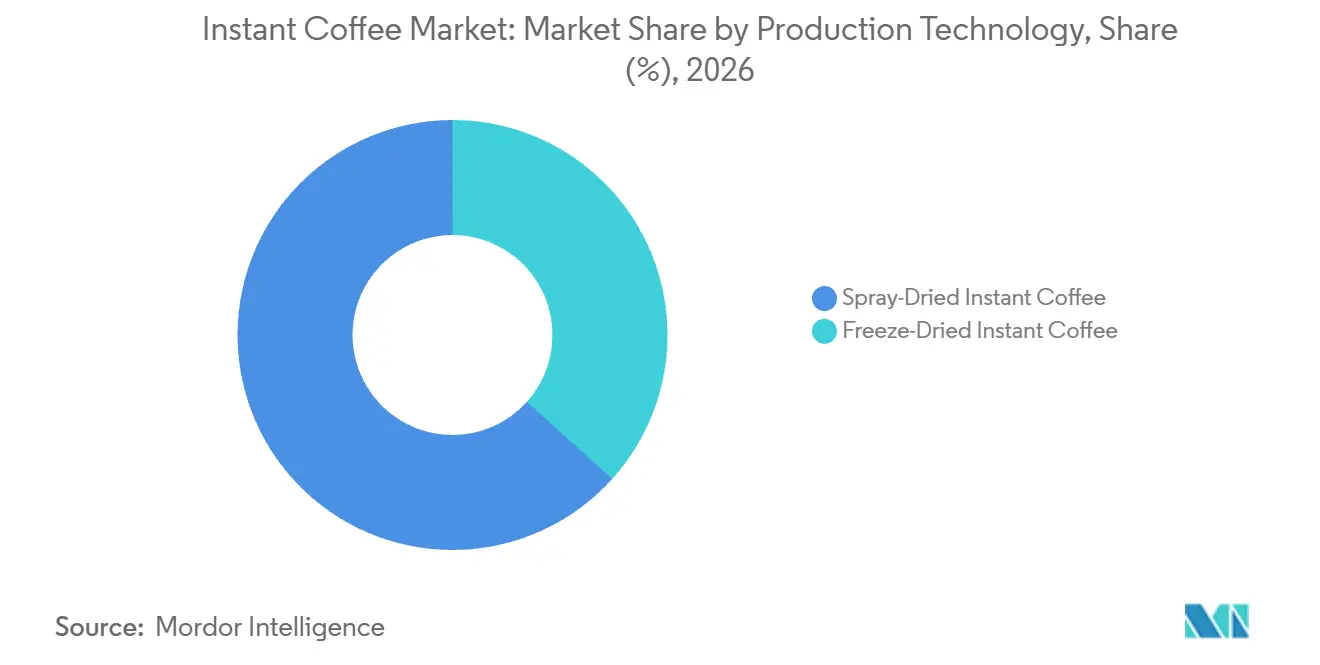
- By production technology, spray-dried instant coffee accounted for a 63.33% share of the instant coffee market size in 2026, and freeze-dried instant coffee is forecast to expand fastest at a CAGR of 6.5% during 2027-2032.
- Across price tiers, mass-priced products led with an 82.52% share in 2026, with premium products forecast to grow fastest at a CAGR of 7.45% during 2027-2032.
- Among packaging formats, sachets are forecast to grow fastest at a CAGR of 6.2% during 2027-2032, while jars held the largest share of 58.39% in 2026.
- By distribution channel, online retail is forecast to grow fastest at a CAGR of 7% during 2027-2032, whereas supermarkets/hypermarkets accounted for the largest share of 51.68% in 2026.
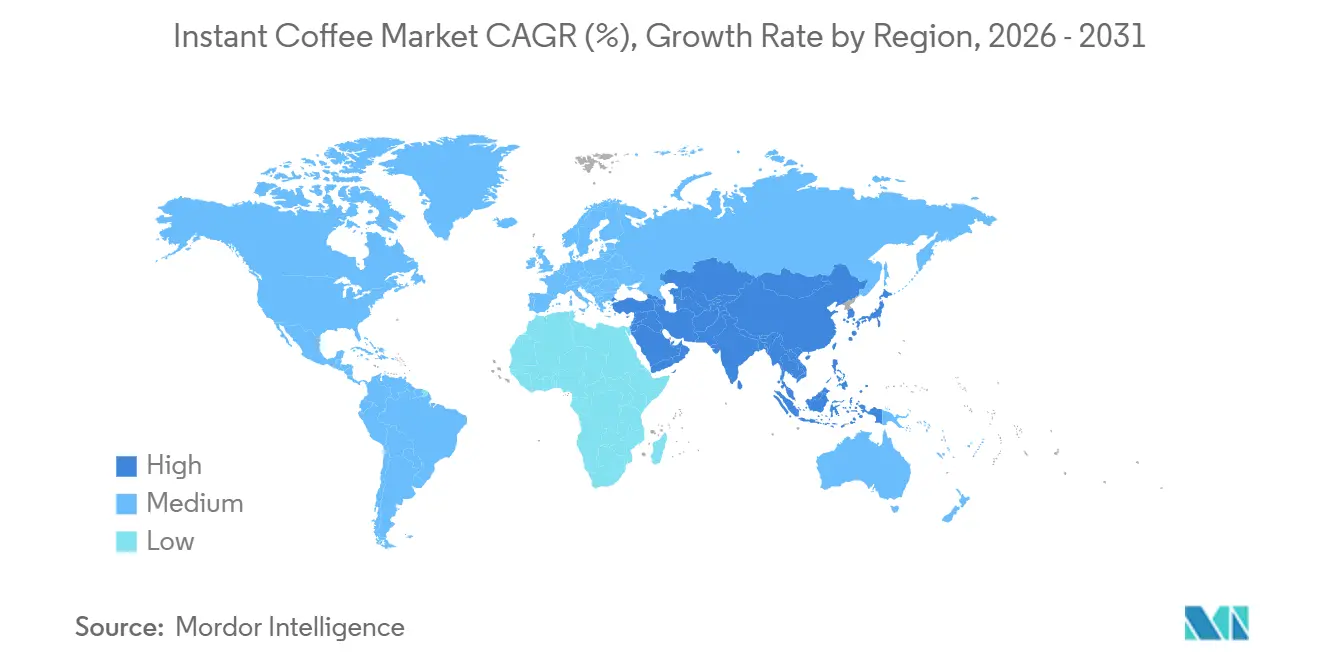
- Across geographies, Asia-Pacific led with a 38.53% share in 2026, and South America is forecast to grow fastest at a CAGR of 7.35% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Instant Coffee Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for premium single-origin instant coffee | +1.1% | Asia-Pacific and Europe | Medium term (2-4 years) |
| Technological advances in freeze-drying | +1.7% | Asia-Pacific, particularly Japan | Medium term (2-4 years) |
| Increasing demand for ready-to-mix coffee for on-the-go consumption | +1.9% | Asia-Pacific, particularly Vietnam | Short term (≤ 2 years) |
| Strategic capacity expansion by soluble coffee exporters | +1.6% | South America and Asia-Pacific | Medium term (2-4 years) |
| Expansion of retail channels and e-commerce platforms improves product accessibility | +0.9% | North America, particularly Canada | Short term (≤ 2 years) |
| Growing café culture influences at-home coffee consumption habits | +0.6% | Europe, particularly United Kingdom | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising demand for premium single-origin instant coffee
Single-origin positioning gives premium instant coffee a way to distinguish the underlying coffee while retaining soluble preparation. The proposition combines a specified origin with an easy-to-mix product, allowing a brand to offer an origin-led choice within the consumer’s familiar preparation format. For buyers who value that identity, differentiation can center on the source of the coffee as well as the finished taste. A narrower origin claim also limits which coffee can fit that product, making source continuity part of sustaining the offer. The premium route therefore pairs consumer differentiation with tighter control of coffee identity through the soluble product’s supply.
Technological advances in freeze-drying
Rapid cold dissolution makes freeze-drying commercially relevant to users who want an iced drink without a brewing step. Nestlé Japan launched Nescafé Ice Blend in Japan on March 10, 2025, using its new Crystal Frozen freeze-drying process to make soluble coffee dissolve quickly in cold water or milk.[1] The company estimated that sales from March through December 2025 equaled about 100 million cup equivalents, calculated at 2 grams per cup. In August 2026, Nestlé Japan said the product’s main new users were people in their 20s and 30s who were unfamiliar with instant coffee. Cold preparation can therefore position processing innovation as a route to reach buyers unfamiliar with the category.
Increasing demand for ready-to-mix coffee for on-the-go consumption
Time pressure favors soluble coffee when buyers want to complete a drink with a short mixing step. In December 2025, the US Department of Agriculture’s Foreign Agricultural Service (USDA FAS) reported that busy lifestyles and longer working hours were boosting instant-coffee demand in Vietnam. Because soluble coffee is sold as a dry product, final dilution can occur at the point of use with water or milk. This separates the shipment of coffee from the preparation of a finished beverage, giving brands a way to serve quick-consumption occasions through packaged solids. For brands, that makes the time a pack saves at preparation the practical basis on which soluble coffee competes for Vietnam’s time-pressed occasions.
Strategic capacity expansion by soluble coffee exporters
Additional soluble processing capacity increases producers’ ability to serve coffee demand. On May 9, 2025, ofi inaugurated its soluble coffee facility in Linhares, Brazil, with 2 lines producing freeze-dried and spray-dried instant coffee.[2] Vintage Coffee and Beverages Limited commissioned 4,500 metric tons per annum of additional soluble capacity at its wholly owned subsidiary’s facility in Telangana, India, effective March 23, 2026. That addition raised installed capacity from 6,500 to 11,000 metric tons per annum. Operating both processes lets ofi offer freeze-dried or spray-dried coffee to the global customers it serves. Vintage’s addition, approximately 69% of its earlier installed capacity, widens the volume it can offer buyers seeking larger soluble-coffee orders.
Restraints Impact Analysis of Instant Coffee Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Health concerns over added sugar and additives | -0.7% | Asia-Pacific, particularly Singapore | Short term (≤ 2 years) |
| Competition from ready-to-drink coffee and cold brews | -0.6% | Asia-Pacific, particularly Vietnam | Short term (≤ 2 years) |
| High caffeine content may deter sensitive consumers | -0.3% | United States and Japan | Short term (≤ 2 years) |
| Climate-induced yield volatility raises costs | -0.4% | Brazil, Vietnam, Colombia, Ethiopia, and Indonesia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Health concerns over added sugar and additives
Sweetened instant coffee faces a commercial constraint when nutritional composition determines its labeling and permitted advertising routes. Singapore requires prepackaged beverages graded C or D, including covered 3-in-1 instant coffee mixes, to carry Nutri-Grade marks.[3] Advertising for Grade D beverages is prohibited across media except for prepackaged beverage advertising at points of sale within variety shops, including supermarkets and convenience stores. The measures took effect on December 30, 2022, and aim to identify beverages higher in sugar and saturated fat. Nutritional composition therefore affects both how an affected mix appears and where its supplier can promote it. The retail exception leaves a limited promotional route, while the broader restriction makes demand development outside stores more difficult.
Competition from ready-to-drink coffee and cold brews
Ready-to-drink coffee competes most directly where consumers need a finished drink at the moment of purchase. Vinacafé Biên Hòa Joint-Stock Company’s 2025 annual report identified ready-to-drink beverages, including canned coffee, as products intended to replace coffee in Vietnam. Such products can serve that occasion without a separate liquid or mixing step, unlike a dried soluble pack. An instant coffee supplier therefore competes against a different delivery format as well as another brand, making preparation effort relevant to the buyer’s choice. Because canned coffee is one of several ready-to-drink formats identified as intended replacements, instant suppliers in Vietnam face substitution pressure across a category of finished drinks.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Instant Coffee Market Segment Analysis
By Product Type:
Unflavored Versatility and Flavored Drink PropositionsUnflavored instant coffee was the largest product segment, accounting for 84.75% of the market in 2026. In a July 2026 notice on US action against Brazilian trade practices, the US Trade Representative reported commenters’ assertion that alternatives could not reliably replace Brazilian producers’ unflavored instant-coffee volumes supplied to US manufacturers. The comments identified inability to meet manufacturers’ technical specifications among the replacement constraints. For manufacturers using those supplies, qualifying another source therefore involves matching specifications as well as finding available volume.
Flavored instant coffee is forecast to be the fastest-growing segment, with a CAGR of 7.8% during 2027-2032. During the year ended September 30, 2025, Salada Foods Jamaica reported export-market launches, distributor engagement, and in-market promotions for flavored coffees and Golden Turmeric Latte in Barbados and the United Kingdom. Its flavored coffees included Coconut Cappuccino, Caramel, and Cinnameg 3-in-1 mixes. For Salada, distributor access in Barbados and the United Kingdom creates an expansion lever beyond adding variants to its Jamaican beverage portfolio.



By Production Technology:
Spray-Dried Scale and Freeze-Dried Value DevelopmentSpray-dried instant coffee represented a 63.33% instant coffee market share in 2026, making it the largest segment. The Brazilian Soluble Coffee Industry Association (ABICS) reported that Brazilian domestic spray-dried soluble-coffee consumption reached 23,891 metric tons in 2025, up 9.1% from 2024. In the same ABICS series, freeze-dried consumption was 3,117 metric tons, so spray-dried volume was roughly 7.7 times as large. The gap makes spray-dried supply central to serving Brazil’s existing soluble-coffee consumption, even as the freeze-dried tier grows faster.
Freeze-dried instant coffee is forecast to be the fastest-growing segment, with a CAGR of 6.5% during 2027-2032. Brazilian consumption of freeze-dried soluble coffee rose 13.3% by volume in January-August 2026 compared with January-August 2025. Buencafé, a Colombian freeze-dried coffee producer, reported total company revenue of USD 285.6 million in 2025. ABICS characterized freeze-dried coffee as higher value-added, connecting the manufacturing method with the kind of soluble offer available to buyers. Consumption growth in Brazil and specialist producer scale in Colombia give the technology distinct demand and supply foundations.

By Price:
Mass Affordability and Premium Drink PositioningMass-priced instant coffee formed the largest segment, with an 82.52% share in 2026. At this price tier, cost control and shelf availability matter because adding expense to a basic coffee offer can weaken its central affordability proposition. For a manufacturer considering private-label supply, the retailer would be the buyer, linking the offer to a retail price point. That route would place the commercial emphasis on repeatable basic coffee and dependable delivery. The resulting manufacturing challenge is to support soluble-coffee volume without making a premium selling price essential to the offer.
Premium instant coffee is forecast to be the fastest-growing segment, with a CAGR of 7.45% during 2027-2032. The retail-data firm NIQ reported UK retail value-sales growth of 93.2% for Nescafé’s Latte range and 59.1% for Gold Cappuccino in the 52 weeks ending June 13, 2026. These pricier, barista-style ranges give the premium proposition a specific drink identity, with retail spending providing a commercial measure of demand. Suppliers can compete for latte and cappuccino spending within soluble coffee, making the finished drink proposition more commercially useful than a higher price alone.
By Packaging Format:
Jar Capacity and Single-Portion ApplicationsJars accounted for a 58.39% share of the instant coffee market size in 2026, making them the largest segment. Nestlé began operating a glass-jar packaging line for soluble coffee at its Tri An factory in Vietnam on August 21, 2026, with initial capacity above 350,000 jars per day. The line adds packing throughput for jarred soluble coffee at the Tri An factory, so jar volumes there depend on packaging capacity as well as on soluble output.
Sachets are forecast to be the fastest-growing segment, with a CAGR of 6.2% during 2027-2032. Ajinomoto AGF reported that estimated sales value for its defined Japanese stick-black coffee category in October 2025-March 2026 was about 218% of the October 2021-March 2022 level, excluding mail-order and online sales. The black-coffee application gives the portioned format a defined drink proposition, connecting packaging with the way the soluble coffee is prepared. Because the measured growth occurred outside mail-order and online sales, sachet suppliers have a demand case for single-serve black coffee beyond digital distribution.
By Distribution Channel:
Physical Retail Reach and Digital Brand EntrySupermarkets and hypermarkets were the largest distribution segment, accounting for 51.68% of the market in 2026. Fire Department Coffee’s late-2025 Walmart Canada rollout included Skull-Crushing Instant Espresso Coffee among 7 initial products covering ground coffee, pods, and instant coffee. By September 2026, the brand’s broader coffee range was available in 380 Walmart locations. A mixed-format shelf set lets the brand test demand for one instant product while sharing its retail entry with ground coffee and pods.
Online retail is forecast to be the fastest-growing segment, with a CAGR of 7% during 2027-2032. In June 2025, CCL Products reported introducing its UK-origin premium instant-coffee brand Percol in India and rolling it out through e-commerce and quick-commerce platforms. CCL said the brand targeted younger, urban consumers and occupied the upper end of the instant-coffee segment. Channel selection can concentrate the launch on younger urban black-coffee buyers, giving an upper-tier entrant a more specific audience than instant-coffee households generally.
Geography Analysis
Asia-Pacific Instant Coffee Market
Asia-Pacific held a 38.53% instant coffee market share in 2026, making it the largest geography. During FY2025-26, CCL Products (India) Ltd.’s wholly owned Vietnamese subsidiary Ngon Coffee Company Limited brought expanded instant-coffee capacity of 36,000 metric tons per year into operation. The expanded capacity gives CCL Products more room to accommodate soluble-coffee orders through its Vietnamese operation. With its factory in India and the Vietnamese unit, CCL Products produces soluble coffee at 2 sites inside Asia-Pacific.
South America Instant Coffee Market
South America is forecast to be the fastest-growing geography, with a CAGR of 7.35% during 2027-2032. ABICS reported that Brazilian domestic soluble-coffee consumption reached 19,700 metric tons in January-August 2026, 11.9% above the same period in 2025. The association also reported Brazilian exports of 65,300 metric tons of soluble coffee during January-August 2026, up 12.8% from the same period in 2025. For Brazilian processors, the paired increase combines a developing domestic consumption base with international shipment growth, giving the country’s soluble-coffee producers commercial growth routes in both local use and international trade.
In North America, 35% of American adults had instant coffee at home in 2025, compared with 62% who had drip coffee makers. The narrower presence leaves room to position instant alongside established home-brewing methods. In Europe, Tchibo’s January 2026 survey found that 17% of German monthly coffee drinkers aged 18 to 75 regularly drank instant coffee, and respondents could name several types. In Middle East and Africa, Nestlé India introduced Nescafé Sunrise instant coffee-chicory mixture in the United Arab Emirates and Saudi Arabia during the financial year ended March 31, 2026, opening a finished-blend export route. That year, it began NESCAFÉ Bulk exports to the United Arab Emirates for use in 3-in-1 offerings for sale in member countries of the Gulf Cooperation Council (GCC), giving ingredient suppliers another mixed-coffee route.
Mordor Intelligence provides coverage of the instant coffee market across other key regional markets. Detailed country-level analysis extends to United States incorporating local coverage and market participation, as required.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of packaged instant-coffee manufacturers selling plain products and coffee mixes. Formulation matters because labeling duties and exemptions can depend on the product and its claims. In the United States, plain unsweetened instant coffee is exempt from nutrition labeling when required nutrients are insignificant and no nutrition claims or other nutrition information appear.
Regulatory Table of Instant Coffee Market
| Decision factor | United States | Germany | China | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | State food-control authorities, the Länder | State Administration for Market Regulation | Anvisa | Department of Health and municipal health services |
| Key instruments or direction | 21 CFR 101.9(j)(4); Part 117 for covered facilities | Regulation 1169/2011 and LMIDV | GB 28050-2011; revised GB 28050-2025 from March 16, 2027 | RDC 429/2020 and IN 75/2020 | R146 with amendments R1091 and R45 |
| Commercial effect | Conditional nutrition-label relief for plain unsweetened coffee; food-safety duties for covered facilities | Applicable mandatory particulars and German-language labels | Additional sugar and saturated-fat declarations for covered foods from March 16, 2027, subject to exemptions | Applicable nutrition tables and front-label requirements, with specified exceptions | Applicable ingredient, allergen, batch, date and manufacturer information |
| Current policy attractiveness | High | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | Hardening | No change | No change |
| Source: Mordor Intelligence | |||||
Conditional US relief for plain unsweetened coffee limits the reach of FDA’s January 2025 nutrition-box proposal, while German-language labeling and state controls anchor Germany’s baseline compliance work. China’s additional sugar and saturated-fat declarations for covered foods from March 16, 2027, support a harder compliance direction relative to GB 28050-2011. Brazil’s established nutrition-labeling duties support continuity for covered formulations, and Anvisa proposed a coordinated public consultation during its April 2026 sector dialogue on ingredient-quantity, digital, and irradiated-food labeling. South Africa’s R146 listing anchors basic labeling requirements, while R3337 was published as a proposal in 2023.
Value Chain Stages
The value chain compares how suppliers earn revenue from green coffee, soluble processing, contract packing, and branded finished products. These activities require different capabilities even when one business performs several of them. Nestlé reported that 94.3% of its coffee was responsibly sourced in 2025, illustrating the upstream sourcing work behind a branded coffee business. Commercial value therefore depends on both converting beans and organizing the supply relationships needed to deliver a finished pack.
Value Chain Analysis Table of Instant Coffee Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Green-coffee sourcing | Green-coffee suppliers such as ofi | Green-coffee sales | Dependence on available beans from suitable origins | Maintain sourcing options across producing origins |
| Soluble-coffee manufacturing | Soluble-coffee manufacturers such as CCL Products (India) Ltd. | Sales of processed soluble coffee | Matching drying and granulation capability to the required product | Match orders to suitable production processes |
| Contract packing | Contract coffee producers and integrated jar makers such as Instanta | Sales of coffee packed under client brands | Coordination between container availability and coffee filling | Coordinate jar manufacture with packing schedules |
| Branded commercialization | Branded soluble-coffee suppliers such as Nestlé S.A. | Finished branded product sales | Dependence on demand for the specific branded offer | Differentiate the finished product beyond processing capability |
| Source: Mordor Intelligence | ||||
Instanta produces its own glass jars while also packing coffee under clients’ brands, showing how packaging integration can support contract production. This arrangement places responsibility for container supply and filling within the same business, making coordination a source of supplier value. Nestlé identified Nescafé soluble as the largest contributor to its coffee-category growth in 2025. Contract manufacturers and consumer brands can consequently earn revenue from different capabilities within the same finished product.
Competitive Landscape
Market Concentration
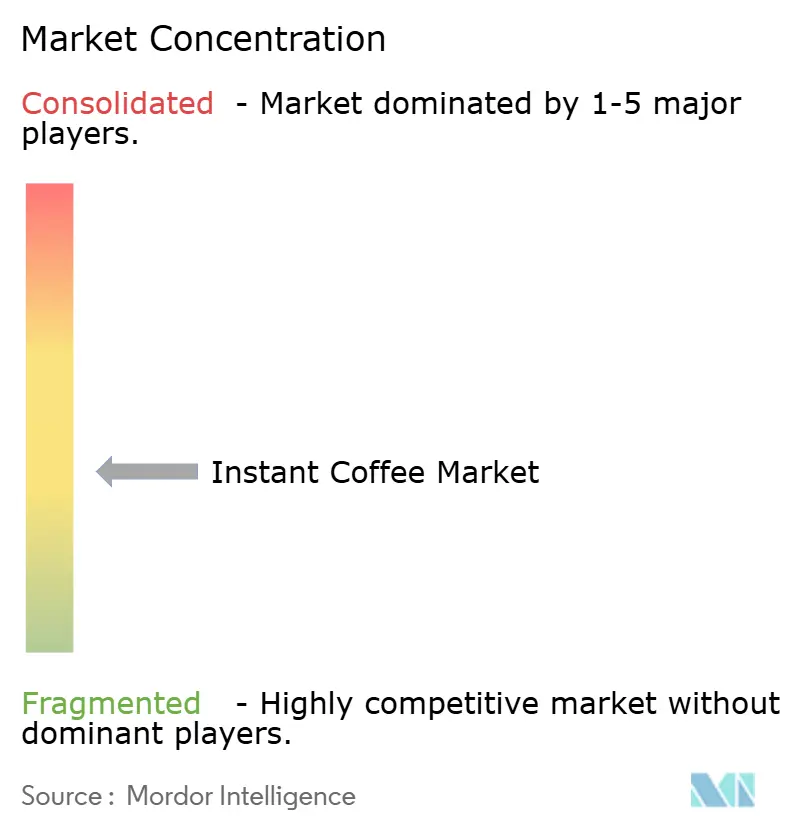
The industry has a moderately fragmented supply structure, combining established coffee-brand portfolios with producer-suppliers that reach buyers through different commercial roles. Major competitors include Nestlé S.A., J.M. Smucker Company, Kraft Heinz Company, and Luigi Lavazza S.p.A., with JDE Peet’s business represented by its acquirer, Keurig Dr Pepper. JDE Peet’s reported double-digit organic sales growth in its Instants category for FY2025, providing a commercial rationale for developing soluble products within a broader coffee portfolio. Coffee producers, including the CCL Products (India) Ltd. group and ofi, also bring operating manufacturing capabilities into this competitive structure.
Kraft Heinz offers Maxwell House Original Roast Instant Coffee in the United States, while Lavazza includes instant coffee in country-tailored retail ranges, placing both companies in consumer-facing branded retail. At Linhares, ofi reported Rainforest Alliance-certified soluble output and fully traceable beans supplied to the facility. Documented sourcing gives a processor serving global customers a basis for differentiation even when the consumer-facing brand belongs to another company.
Keurig Dr Pepper acquired 96.22% of JDE Peet’s N.V.’s shares in the offer on April 1, 2026. The transaction illustrates ownership consolidation around a coffee business with an established Instants category, shifting the setting for decisions about brands, manufacturing relationships, and product development. In an August 25, 2026, interview, Nestlé Japan’s soluble-coffee business head said Nescafé Ice Blend was selling nearly twice as much as in the previous year. Ownership of an Instants business consolidated under Keurig Dr Pepper while Nestlé reported growth for a Japanese product built on its own freeze-drying process. Meanwhile, ofi and CCL Products have each added soluble production capacity, widening the supplier tier’s production base as brand ownership concentrates.
Instant Coffee Industry Leaders
-
Nestlé S.A.
-
J.M. Smucker Company
-
Kraft Heinz Company
-
Luigi Lavazza S.p.A.
-
JDE Peet's B.V.
- *Disclaimer: Major Players sorted in no particular order
Instant Coffee Market Companies Covered in this Report
- Nestlé S.A.
- J.M. Smucker Company
- Kraft Heinz Company
- Tata Consumer Products Limited
- Luigi Lavazza S.p.A.
- JDE Peet's B.V.
- Tchibo GmbH
- Strauss Group Ltd.
- The Coca-Cola Company
- Unilever PLC
- UCC Ueshima Coffee Co., Ltd.
- Trung Nguyen Group JSC
- Massimo Zanetti Beverage Group
- Sleepy Owl Coffee
- PT Kapal Api Global
- Matthew Algie & Company Limited
- Zino Davidoff Group
- TGL Company
- CCL Products (India) Ltd.
- Blueberry Agro Products Pvt. Ltd.
Key Opportunities for Market Participants
The opportunities compare ways to serve caffeine-management needs in Japan and additional soluble-coffee consumption in Vietnam. In the August 2025 survey by UCC Ueshima Coffee Co., Ltd., about half of Japanese monthly coffee drinkers in their 20s said they practiced caffeine management. In May 2026, USDA FAS estimated Vietnam’s domestic soluble-coffee consumption at 1.5 million 60-kilogram bags of green-bean equivalent for marketing year (MY) 2025/26 and forecast 1.55 million bags for MY 2026/27. The commercial task is to translate those buyer conditions into packaged offers with a clear product and preparation proposition.
Market Opportunities Table of Instant Coffee Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Multi-serve decaffeinated instant coffee | UCC refreshed its 45-gram instant-decaf jar for March 2, 2026, with flavor unchanged | Japanese coffee drinkers managing caffeine intake | Develop clearly identified multi-serve decaffeinated soluble offers | Competition from reduced-caffeine alternatives | UCC Ueshima Coffee Co., Ltd. |
| Portioned lower-caffeine soluble coffee | A Caffeine Half stick-black format is offered in Japan | Japanese consumers seeking single-cup caffeine management | Pair portioned formats with clear serving and caffeine-comparison information | Communicating dose-dependent caffeine positioning | Nestlé’s Nescafé business |
| Locally tailored soluble-coffee ranges in Vietnam | The MY 2026/27 soluble-consumption forecast exceeds the MY 2025/26 estimate | Vietnamese soluble-coffee users | Develop distinct black-coffee and mixed-coffee propositions | Differentiation from existing G7 offers | Trung Nguyên Legend Corporation |
| Source: Mordor Intelligence | |||||
The central opening is to turn a broad drinking need into a specific soluble product whose preparation and caffeine positioning are clear. Nescafé Gold Blend Caffeine Half’s approximately 50% caffeine reduction compares 2 grams in 140 milliliters of hot water with the Japanese 2020 food-composition reference coffee infusion. That reference-based distinction gives suppliers a concrete communication task when offering lower-caffeine coffee alongside decaffeinated alternatives. Precise serving information can make the choice between those products more useful to buyers managing their intake.
Recent Industry Developments in Instant Coffee Market
- Aug 2026: UCC Ueshima Coffee Co., Ltd. announced a UCC &Healthy functional instant coffee product for Japan, specifying September 1, 2026, as its planned release date.
- Aug 2026: Nestlé began operating a glass-jar packaging line for soluble coffee at its Tri An factory in Vietnam on August 21, with initial capacity above 350,000 jars per day.
Instant Coffee Market Report Scope and Research Methodology
Market Definition and Coverage
Instant coffee market covers annual manufacturer sales of packaged soluble coffee intended to dissolve in hot or cold water or milk for home, office, and food-service preparation worldwide. Its value is measured at the manufacturer's selling price across global regions, with sales classified by product characteristics, production method, price, package, sales channel, and geography.
Scope exclusions: Ready-to-drink coffee, coffee concentrates, single-serve coffee pod and capsule systems, green coffee beans and soluble coffee extract sold as manufacturing inputs, and ground and whole-bean coffee are excluded.
Segments Covered in This Report
- By Product Type
- Flavored
- Unflavored
- By Production Technology
- Spray-Dried Instant Coffee
- Freeze-Dried Instant Coffee
- By Price
- Mass
- Premium
- By Packaging Format
- Sachets
- Pouches
- Jars
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience/Grocery Stores
- Specialty Stores
- Online Retail
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
The Food and Agriculture Organization's coffee resources and FAOSTAT provide production, trade, and country series that frame the supply base, while the USDA Foreign Agricultural Service's coffee reports, such as its Vietnam annual, describe soluble exports, processing capacity, and local conditions. The National Coffee Association's National Coffee Data Trends provides consumer behavior and preparation indicators for the United States. These sources help distinguish finished soluble products from green coffee inputs and broader coffee totals.
Company filings, annual reports, investor materials, and reputable business and trade press can cross-check capacity changes, product launches, channel activity, and reported sales context against those public series. The named sources are illustrative, not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would target soluble-coffee manufacturers, brand owners, packaging and processing specialists, and retail or food-service channel professionals across APAC, EMEA, and the Americas. Their evidence would check secondary estimates of product mix, price tiers, packaging, channel routes, regional demand, and forecast drivers. Analysts would investigate material conflicts, fill data gaps with the strongest comparable public indicators, and triangulate each view against separate supply and demand evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 20% | Managers: 45% | Americas: 30% |
Market-Sizing & Forecasting
The model starts top down with global manufacturer sales of finished packaged soluble coffee, sets the 2026 base and 2027 current-year value, and then projects value by geography and the accepted product, production, price, packaging, and channel cuts. Key inputs include soluble-coffee production and export volumes, installed processing capacity, green-coffee prices as a cost and pricing signal, consumer coffee-use patterns, and channel and product mix. Country and company observations indicate where demand and supply are shifting. A multivariate regression can relate historical market value to these drivers, with scenario analysis used when input paths such as coffee costs or capacity additions are uncertain. Product and regional shares are built from reported sales or shipment mix, market evidence, and comparable company disclosures, then checked to sum to the global total. Selective bottom-up checks compare supplier-reported soluble sales or sampled finished-product price times volume with the top-down result, while missing splits are estimated from the nearest supported public indicators and flagged for review rather than treated as observed facts. In a primary-research program, knowledgeable respondents would check whether each driver and segment forecast fits actual purchasing, production, and route-to-market conditions, and unresolved differences would be tested against independent indicators before adoption.
Data Validation & Update Cycle
Analysts triangulate company disclosures, government and association series, trade data, and market estimates, then compare independent demand and supply signals for each major region and segment. They investigate unusual year-to-year movements, cross-source variances, and totals that do not reconcile, record the evidence used to resolve them, and seek clarification from an appropriate source when a material conflict remains. A second analyst review checks calculations, units, period alignment, and narrative consistency before sign-off. The model is refreshed annually, revisited between cycles after material market events, and given a fresh pre-delivery review.
Mordor Intelligence's Instant Coffee Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Instant coffee market covers annual manufacturer sales of packaged soluble coffee intended to dissolve in hot or cold water or milk for home, office, and food-service preparation worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include soluble-coffee production and export volumes, installed processing capacity, green-coffee prices as a cost and pricing signal, consumer coffee-use patterns, and channel and product mix.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 40.81 B (2027) | |
| Global Consultancy A | USD 15.4 B (2025) | At its 2025 base, this estimate is 62.3% below this report's 2027 value of USD 40.81 B, 2 years later. Its published forecast grows more slowly than this report's, contributing directionally to the lower estimate. |
| Regional Consultancy B | USD 16.45 B (2024) | At its 2024 base, this estimate is 59.7% below this report's 2027 value of USD 40.81 B, 3 years later. Its earlier estimate year contributes to the lower comparison, while its faster stated forecast rate partly offsets that timing effect. |
Mordor Intelligence's analysts triangulate company disclosures, government and association series, trade data, and market estimates, then compare independent demand and supply signals for each major region and segment.
Key Questions Answered in the Report
What is the instant coffee market size and growth outlook?
The size is projected at USD 40.81 billion in 2027 and USD 54.46 billion by 2032, with a CAGR of 5.94% during 2027-2032.
What is driving demand for soluble coffee?
Convenience and cold preparation are key forces. Nestlé Japan’s March 2025 Nescafé Ice Blend launch used Crystal Frozen freeze-drying to enable rapid dissolution in cold water or milk.
Which instant coffee product type holds the largest share?
Unflavored products led with an 84.75% share in 2026. Flavored products are forecast to grow fastest at a CAGR of 7.8% during 2027-2032.
Who are the prominent instant coffee suppliers?
Prominent businesses include Nestlé S.A., J.M. Smucker Company, Kraft Heinz Company, Luigi Lavazza S.p.A., and Keurig Dr Pepper, which acquired 96.22% of JDE Peet’s N.V.’s shares in the offer on April 1, 2026.
What can constrain demand for sweetened instant coffee?
In Singapore, Grade D beverages face an advertising ban across media, except for prepackaged beverage advertising at points of sale within variety shops. This limits promotion routes for affected coffee mixes.
Which region leads instant coffee and which is forecast to grow fastest?
Asia-Pacific held the largest share of 38.53% in 2026. South America is forecast to grow fastest at a CAGR of 7.35% during 2027-2032.