
Indonesia Plastics Market Analysis by Mordor Intelligence
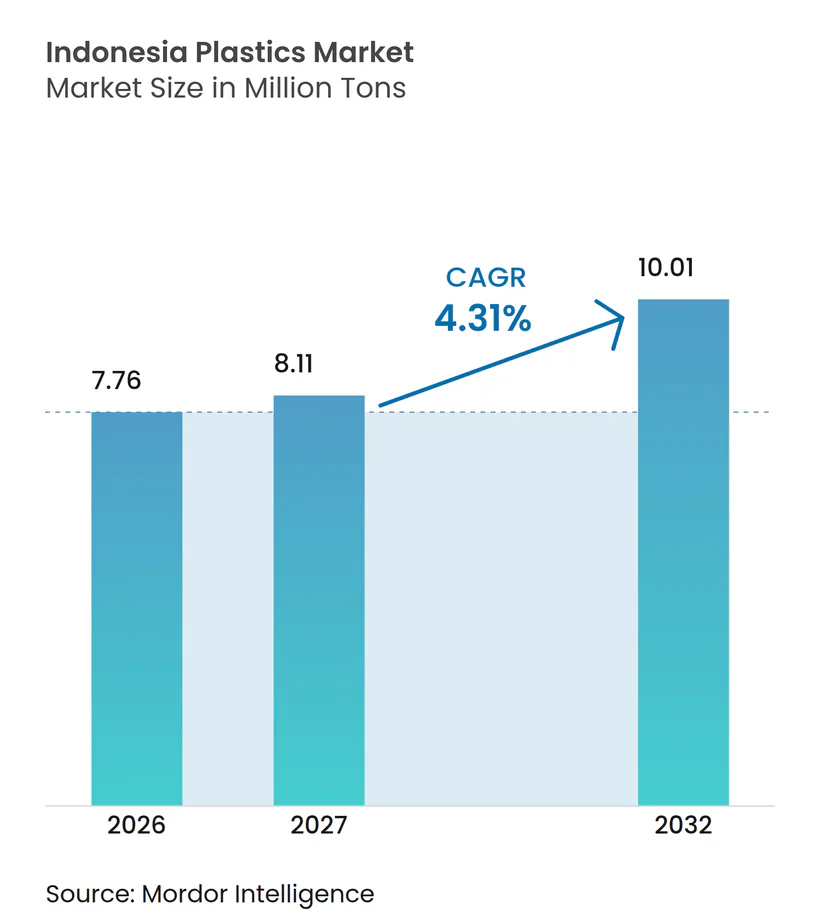
The Indonesia plastics market size is expected to increase from 7.76 million tons in 2026 to 8.11 million tons in 2027 and reach 10.01 million tons by 2032, growing at a CAGR of 4.31% over 2027-2032.
Domestic polypropylene production and parcel-shipping requirements create complementary resin opportunities in Indonesia, joining a local production base with protective packaging applications. Covered producers’ waste-reduction duties favor recyclable offers where take-back is chosen, while application-specific grades and certified products let suppliers address distinct conversion and sustainability specifications. Carbon-related electricity-cost exposure can constrain conversion returns. Strait of Hormuz shipping disruption following US and Israeli military operations against Iran from February 28, 2026, had by April constrained naphtha and LPG availability at an Indonesian petrochemical operation, making feedstock access a limit on near-term resin supply.
Key Report Takeaways
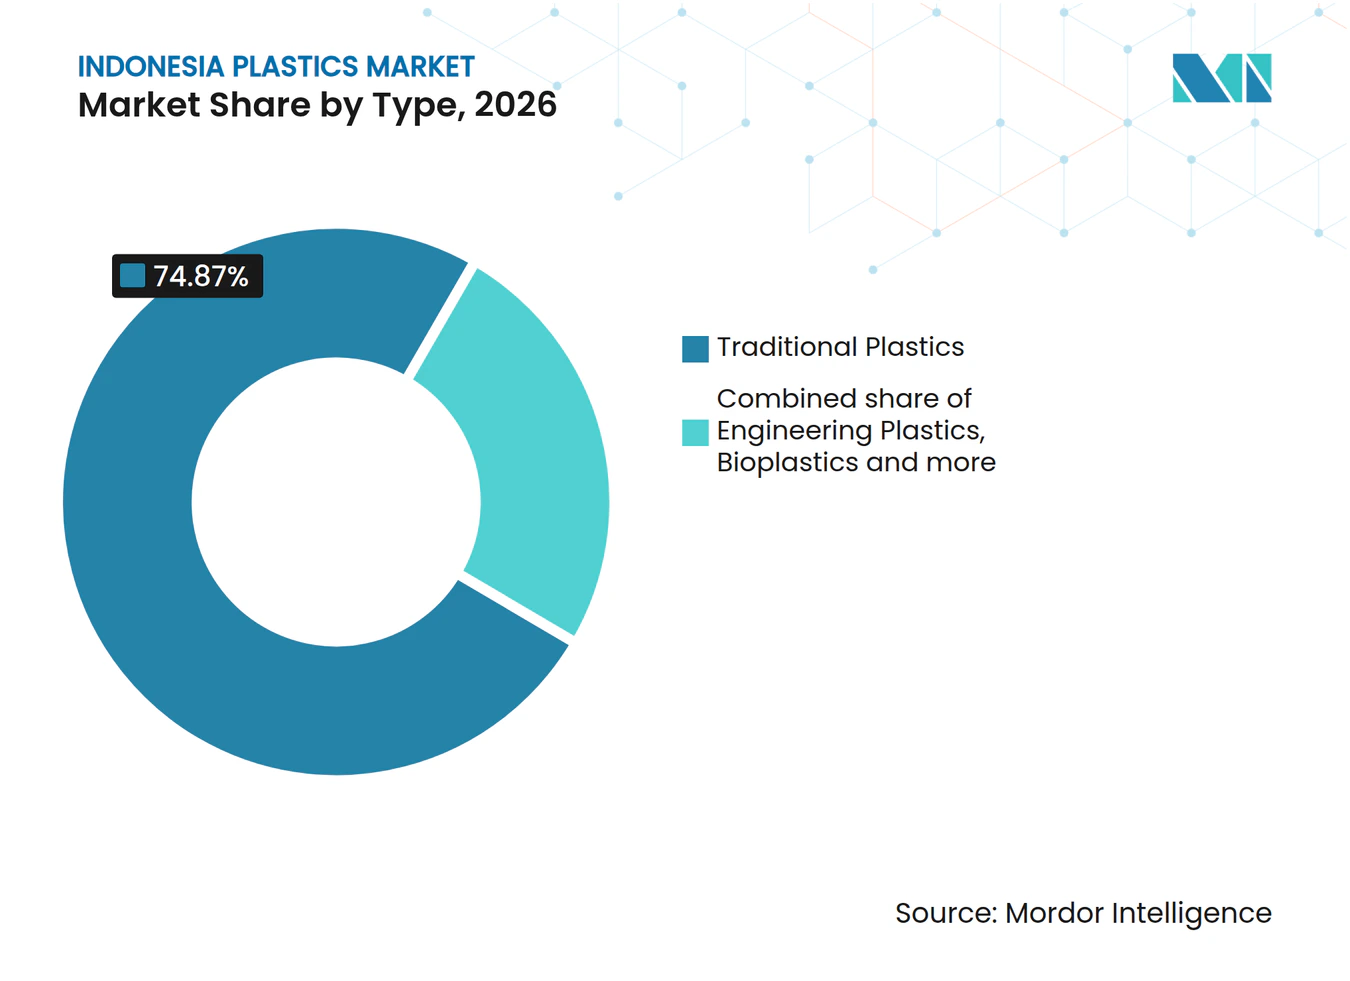
- By type, traditional plastics held a 74.87% Indonesia plastics market share in 2026, and bioplastics are forecast to grow fastest at a 5.85% CAGR over 2027-2032.
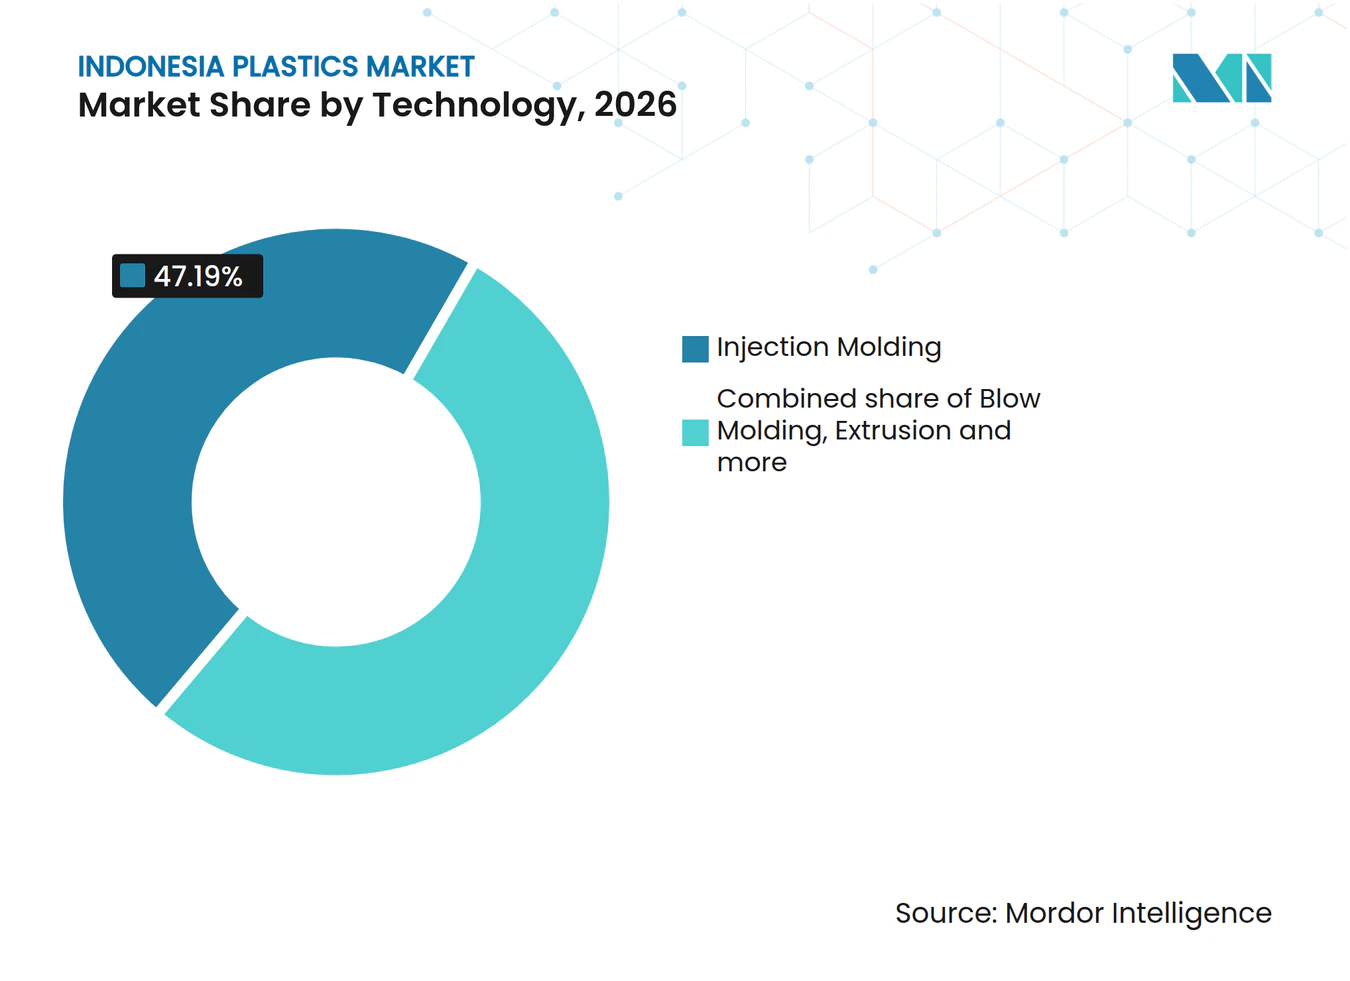
- Injection molding led processing technologies with a 47.19% share of the Indonesia plastics market size in 2026, while blow molding is forecast to grow fastest at a 5.05% CAGR over 2027-2032.
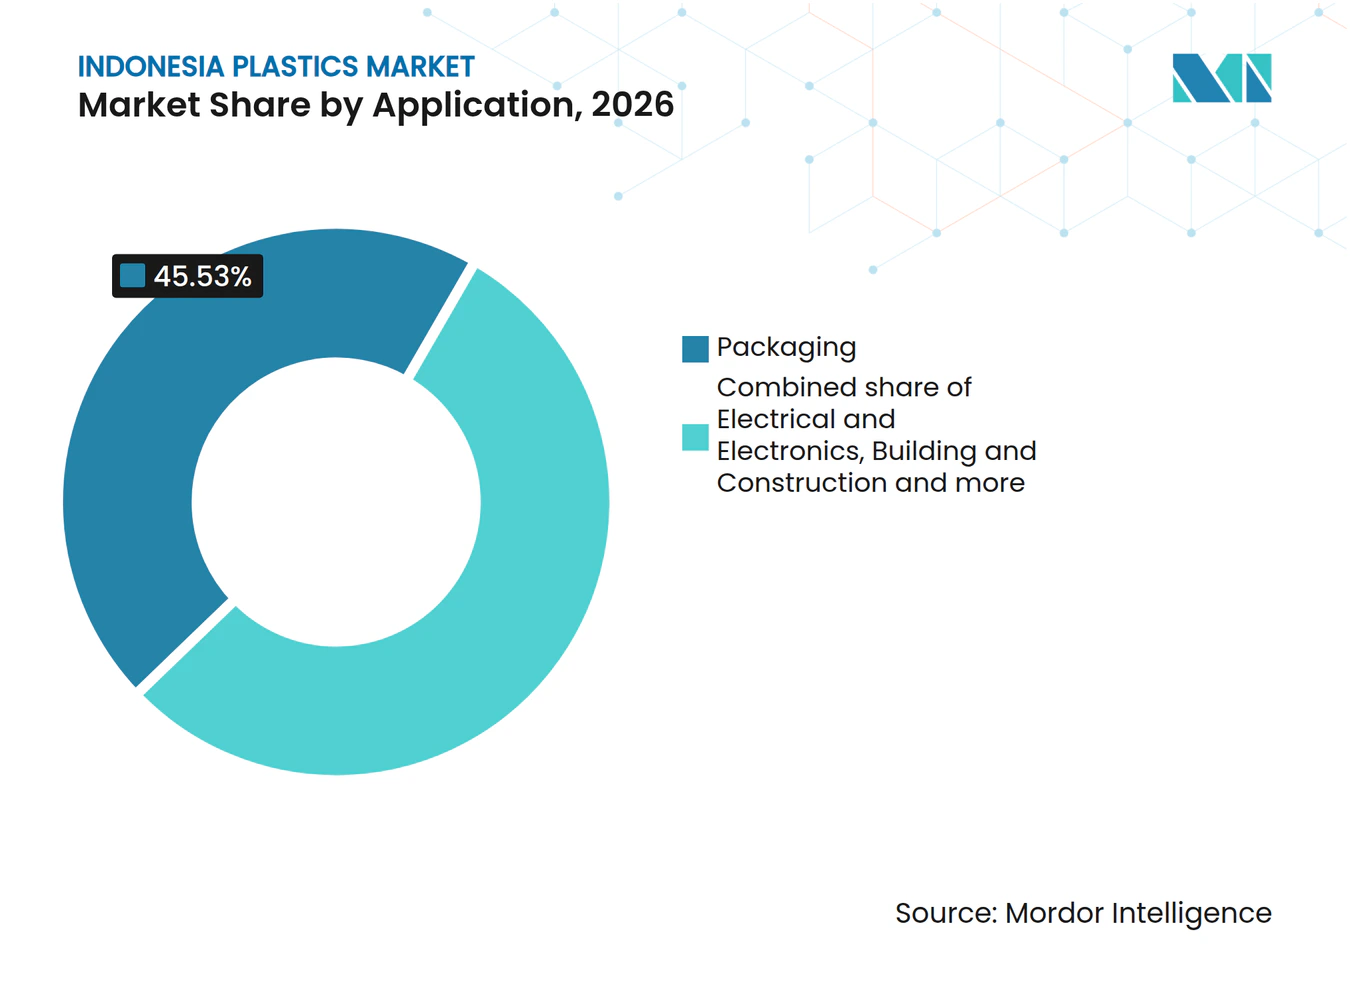
- Within applications, packaging held the largest share at 45.53% of resin volume in 2026 and is forecast to grow fastest at a 5% CAGR over 2027-2032.
- Geographically, Java leads resin off-take and hosts polyethylene production at Merak and polypropylene production at Balongan.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indonesia Plastics Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of downstream petro-complexes (Cilegon, Tuban) | +1.7% | Cilegon industrial area | Medium term (2-4 years) |
| Lightweight auto-parts adoption by OEMs | +1% | Nationwide | Medium term (2-4 years) |
| E-commerce logistics boom needing durable secondary packs | +1.4% | Nationwide | Short term (≤ 2 years) |
| Mandatory EPR and waste-segregation pilots fueling recyclable resin demand | +1.1% | Nationwide | Medium term (2-4 years) |
| Seaweed-based bioplastics clusters in East Java | +0.3% | Sidoarjo, East Java | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of downstream petro-complexes (Cilegon, Tuban)
Domestic petrochemical expansion can support plastics demand by creating a local production base for downstream conversion. LOTTE Chemical Indonesia completed construction of its Cilegon complex in May 2025, with annual polypropylene capacity of 350,000 metric tons. At the November 6, 2025 inauguration, Indonesia’s energy and mineral resources minister projected a 70% domestic and 30% overseas marketing split for the Cilegon complex’s total production capacity. The ministry also projected replacement of up to USD 1.4 billion in annual petrochemical imports. On April 8, 2026, LOTTE Chemical Indonesia reported reduced production after Strait of Hormuz disruption affected naphtha and LPG availability and forced procurement-route changes. The expansion gives polypropylene processors a domestic supply option, but realizing that capacity depends on feedstock availability.
Lightweight auto-parts adoption by OEMs
In Indonesia, an OEM considering an injection-molded bumper in place of a heavier design creates a potential lightweighting route for resin demand. That opportunity depends on meeting the bumper’s impact and surface requirements with the proposed polymer formulation. The component supplier would need to qualify the molded part, rather than treat lower material weight as sufficient proof of suitability. Resin demand would increase only where the qualified substitution adds polymer content to vehicles entering production. The commercial opening lies in winning the material specification for a defined bumper program, with demand tied to that program’s production rather than a general preference for lighter vehicles.
E-commerce logistics boom needing durable secondary packs
Demand for protective outer packs can expand as online sellers dispatch more parcels, linking logistics activity to a separate packaging purchase. J&T Express’s shipments in Indonesia grew by more than 60% in 2025. In its January 2025 seller shipping guidance, Everpro required outer packaging for all products and recommended options including poly mailer bags and plastic seals. These requirements put the sender at the point where a general need for parcel protection becomes a choice among material formats. Converters offering suitable mailers and seals can therefore address seller demand through shipping-service requirements, even when the courier is not the packaging purchaser.
Mandatory EPR and waste-segregation pilots fueling recyclable resin demand
Extended producer responsibility can make recyclable packaging design a commercial consideration for businesses subject to waste-reduction duties. Under PermenLHK P.75/2019, covered Indonesian producers must prepare roadmaps for 2020-2029, targeting 30% waste reduction by 2029 through prevention, recycling via take-back, or reuse. Recycling through take-back creates a compliance route around which material suppliers can develop recyclable resin and packaging offers. Because prevention and reuse are alternative routes, the strongest demand connection is with producers that choose a recovery-based approach. Material selection then becomes part of the compliance plan, because a take-back route only works if the packaging can be recovered and recycled.
Restraints Impact Analysis of Indonesia Plastics Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Potential excise on single-use plastic bags | -0.6% | Nationwide | Medium term (2-4 years) |
| Carbon-pricing scheme raising energy costs | -0.4% | Java, Madura and Bali | Long term (≥ 4 years) |
| Rail-infrastructure gaps inflating inland resin logistics | -0.2% | Tanjung Priok Port, Jakarta | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Potential excise on single-use plastic bags
An excise on single-use plastic bags would place a product-specific cost burden on converters serving retail shopping-bag buyers. If buyers responded by reducing bag use or changing formats, the effect could move upstream through lower resin requirements for the affected product. The exposure would be concentrated in any taxed bag format, making the precise product definition commercially significant. Converters could respond with alternative formats, but redesigning an offer would not remove the cost of serving an application that remained taxable. The remaining risk would be a narrower viable outlet for bag-resin suppliers as any tax-induced cost increases reached converters and their customers.
Carbon-pricing scheme raising energy costs
Carbon pricing creates a conditional energy-cost restraint for plastics processors exposed to electricity-price changes. By March 2026, Indonesia had implemented an emissions-trading system for power-sector emissions, while its carbon tax was unimplemented. Presidential Regulation 110/2025 requires an operator of a regulated installation to pay carbon tax if the installation exceeds its greenhouse-gas emissions cap. A 2025 simulation of the Java, Madura and Bali power system over 2024-2030 associated higher modeled carbon taxes with higher electricity prices. Any resulting pass-through would increase conversion costs and could weaken the case for expanding resin throughput at electricity-exposed operations.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indonesia Plastics Market Segment Analysis
By Type:
Conventional Resin Scale and Local Biopolymer ProductionTraditional plastics accounted for a 74.87% share of the Indonesia plastics market size in 2026. Polytama Propindo produced 266,262 metric tons of polypropylene resin in Indonesia in 2025.[1] Its Masplene resin is used in products including medical-mask materials, rice sacks, packaging, and household plastic goods. For this largest segment, that spread of uses connects producer throughput with several different converting businesses, creating multiple potential destinations for established polypropylene output.
Bioplastics is the fastest-growing segment, with a forecast CAGR of 5.85% over 2027-2032. CJ Biomaterials, a business of CJ CheilJedang, produces the bioplastic amorphous PHA at its Pasuruan facility in Indonesia. The company’s commercial model includes selling PHA pellets to downstream companies that melt and mold them into products. Because outside companies mold CJ Biomaterials’ pellets into products, expanding PHA sales depends on their conversion demand, making product development at the molding stage a route to bioplastics growth.



By Technology:
Installed Molding Capacity Connects Different Buyer GroupsInjection molding represented a 47.19% Indonesia plastics market share in 2026. PT Asia Pramulia operated 23 injection molding machines at its Surabaya plant during 2025. PT Indonesia Thai Summit Plastech combines injection molding, spray painting, and vehicle-interior assembly in its automotive plastic-components business. These operations illustrate how the largest segment can serve both packaging manufacturing and vehicle-component production, with different downstream processing requirements.
Blow molding is the fastest-growing segment, with a forecast CAGR of 5.05% over 2027-2032. In 2025, PT Asia Pramulia operated 24 blow-molding machines at its Surabaya plant and 10 at its Pasuruan plant to make plastic packaging. Its Pasuruan blow-molding equipment was supported by leak testing, labeling, and bottle-printing equipment. Linking container forming with those later operations can make the commercial offer more complete for packaging buyers, because the conversion process extends beyond producing a hollow shape.

By Application:
Operating Packaging Output Anchors Further Film InvestmentPackaging held the largest segment share at 45.53% of resin volume in 2026 and is forecast to be the fastest-growing segment, with a 5% CAGR over 2027-2032. PT Panca Budi Idaman produced 128,000 metric tons of plastic packaging in 2025. The producer’s finished-packaging output demonstrates an established conversion outlet for resin suppliers, giving this application a commercial base alongside future investment in additional lines. Resin producers serve that base by turning production capability into material used by operating packaging businesses, so finished-product throughput can matter as much as announced conversion capacity.
Packaging investment also opens a commercial role for materials that can support alternative polyolefin film routes. PT Indopoly Swakarsa Industry inaugurated a hybrid biaxially oriented polypropylene and polyethylene packaging-film line in Indonesia on May 21, 2025. The line added 25,000 metric tons per year of capacity. That investment creates a defined production setting in which polypropylene and polyethylene film opportunities can be developed around the same hybrid production asset.
Geography Analysis
Java Plastics Market
Java holds the leading position in resin off-take. PT LOTTE CHEMICAL TITAN Nusantara produces polyethylene at its Merak facility in Banten, while Polytama Propindo’s polypropylene plant is located in Balongan, West Java. Java therefore hosts both polyethylene production at Merak and polypropylene production at Balongan alongside its leading resin off-take.
Sumatra Plastics Market
Sumatra’s distinct contribution includes refinery-linked polypropylene production in South Sumatra. The Plaju refinery in South Sumatra produced 50,050 metric tons of Polytam polypropylene resin in 2025. Polytam serves packaging, automotive, and household industries as a raw material. This connects a specific resin-producing location with several downstream uses, allowing its commercial relevance to extend across different types of converting businesses.
Karawang Plastics Market
Changsu opened its first overseas factory through PT Changsu Industrial Indonesia at Suryacipta Industrial Park in Karawang on January 15, 2026, for BOPA film production. Dongsung Chemical began full-scale Karawang operations in February 2025, and in April 2025 reported combined annual capacity of 67,000 tons for prepolymers, polyester polyols, and polyurethane resins. On April 30, 2025, Dongsung said it planned to use Karawang’s port proximity and automotive supply-chain position to support customer deliveries. It presented the plant as a planned expansion base for Southeast Asia, the Americas, and Europe. Film conversion and polyurethane materials give Karawang distinct industrial roles alongside the polyethylene and polypropylene production at Java’s Merak and Balongan sites.
Regulatory Framework and Outlook
This comparison covers selected jurisdictions, focusing on how national and Jakarta rules affect resin suppliers serving single-use retail shopping-bag manufacturers. National policy includes a scheduled shopping-bag prohibition, while Jakarta already restricts those shopping bags in specified retail venues. On October 6, 2026, the Ministry of Environment / Environmental Control Agency consulted on a draft replacement for P.75/2019. The draft proposed packaging-design-based producer fees and full obligations from 2028, with adoption targeted for November 2026.
Regulatory Table of Indonesia Plastics Market
| Decision factor | Indonesia | Jakarta |
|---|---|---|
| Primary authority | Ministry of Environment / Environmental Control Agency, with competent subnational authorities | Environmental Agency coordinating the trade agency and Civil Service Police Unit |
| Key instruments or direction | P.75/2019; shopping-bag prohibition scheduled January 1, 2030, subject to earlier local bans | Governor Regulation 142/2019; retail shopping-bag restriction effective July 1, 2020 |
| Commercial effect | Future restriction of a single-use shopping-bag outlet | Restricted shopping-bag demand at shopping centers, supermarkets, and traditional markets |
| Current policy attractiveness | Medium | Low |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
National attractiveness is Medium because the transition leaves a period for business, but the 2030 prohibition and proposed 2028 obligations support a Hardening direction. Jakarta is Low for shopping-bag resin suppliers because specified retail outlets already face a restriction, with the operative framework supporting No change for that local product use. The separate permission for single-use plastic packaging bags for unpackaged food lasts until a more environmentally friendly alternative is available. Jakarta’s earlier restriction narrows the local transition opportunity, leaving the national deadline more relevant to suppliers serving other permitted retail locations.
Value Chain Stages
The value chain compares how resin producers, supply intermediaries, and packaging converters earn revenue while connecting domestic production with downstream demand. In January 2026, domestic polypropylene producers were reported to supply about half of Indonesia’s annual polypropylene needs, with the balance dependent on imports. That supply structure gives intermediaries a commercial role alongside local plants, because domestic production and imported material must both reach processors. Supplier revenue can therefore accrue at production, resin supply, and packaging conversion, making the value chain broader than a count of local resin plants.
Value Chain Analysis Table of Indonesia Plastics Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Resin production | Polypropylene producers such as PT Polytama Propindo; polyethylene producers such as PT LOTTE CHEMICAL TITAN Tbk together with PT LOTTE CHEMICAL TITAN Nusantara | Resin sales | Domestic polypropylene supply shortfall | Expand domestic production while retaining alternative supply routes |
| Resin trade and supply | Resin suppliers such as PT Sumitomo Indonesia; resin traders such as PT Panca Budi Idaman | Resin trading and distribution earnings | Matching local and imported grades to converter needs | Maintain qualified domestic and overseas sourcing options |
| Packaging conversion and distribution | Packaging manufacturers such as PT Asia Pramulia and PT Panca Budi Idaman | Finished-packaging sales and distribution earnings | Aligning resin availability with product-specific conversion capability | Test candidate grades through intended molding lines before expanding production |
| Source: Mordor Intelligence | ||||
PT Polytama Propindo began engineering, procurement, and construction work for its Polypropylene Plant Balongan project in Indramayu on June 22, 2026. The start of that work represents a producer-side response whose commercial benefit depends on future execution, while trade channels can serve demand during the investment cycle. Conversion businesses capture value further downstream through saleable packaging, making processing capability essential to the commercial use of an expanded resin base. Additional domestic capacity can change the sourcing mix without eliminating the intermediary’s role in assembling a suitable supply portfolio.
Competitive Landscape
Market Concentration
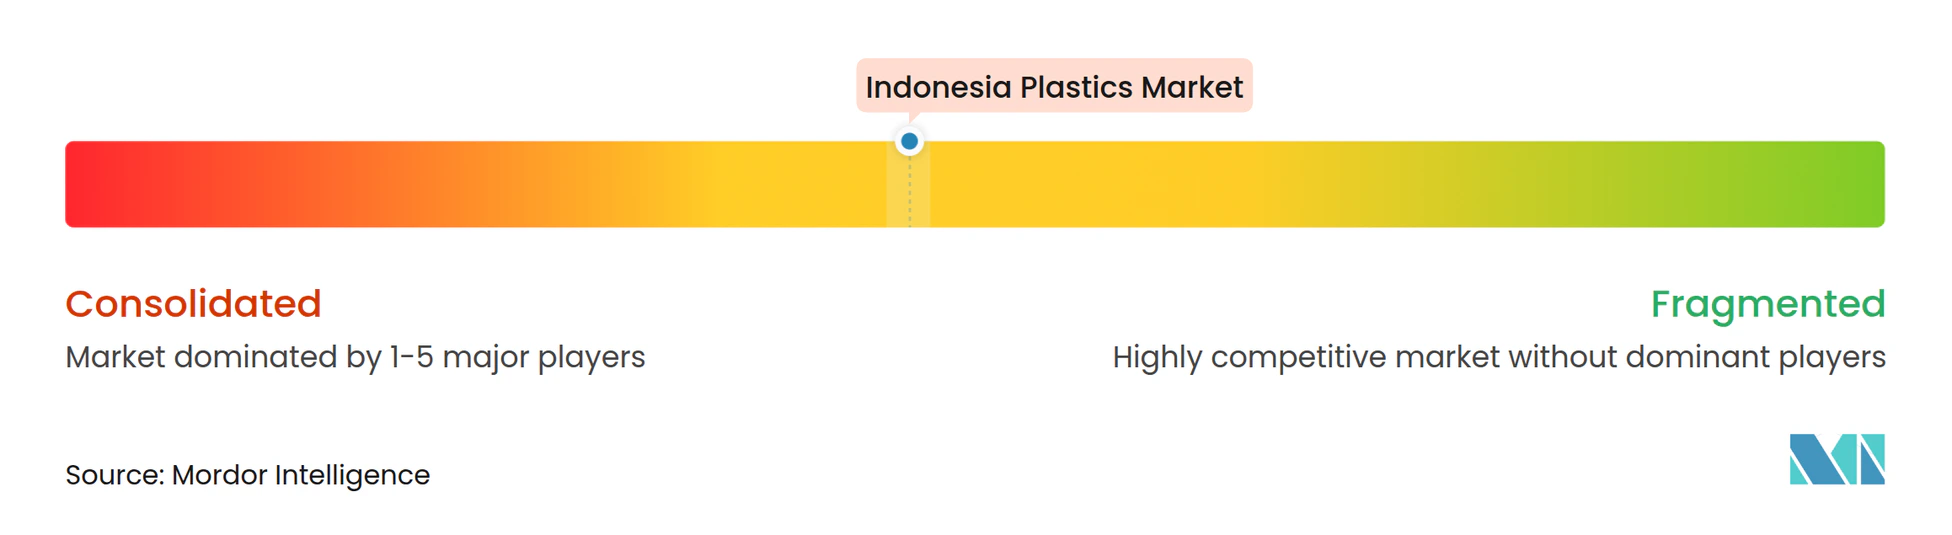
Supply has an established producer core comprising Chandra Asri Group, LOTTE CHEMICAL TITAN HOLDING BERHAD, Asahimas Chemical Company, PT Pertamina (Persero), and Sulfindo Adiusaha. Chandra Asri Group received a 2025 National Energy Efficiency Award for initiatives that included reducing energy intensity in polyethylene production and improving energy performance in polypropylene production. Sulfindo Adiusaha’s polyvinyl chloride (PVC) business is a joint venture with PT Satomo Indovyl Polymer. PT Lotte Chemical Indonesia, a subsidiary of LOTTE CHEMICAL TITAN HOLDING BERHAD, develops and operates the Cilegon complex, whose annual design capacities include ethylene and propylene alongside polypropylene.
As of September 30, 2025, PT Tuban Petrochemical Industries held 99.999% of PT Polytama Propindo and was 63% owned by Pertamina. In October 2025, Milliken & Company and PT Polytama Propindo launched Masplene MAS9475, described by Milliken as Indonesia’s first UL-validated polypropylene resin specifically for thin-wall injection molding. The collaboration connects a local resin producer with a technology partner, giving the grade an application-specific position within a broader polypropylene offering. Validation of a named grade can make application development more useful to thin-wall molding buyers than an undifferentiated increase in polypropylene supply.
In June 2025, Asahimas Chemical Company’s Anyer plant obtained ISCC PLUS certification covering PVC resin and associated chemical products.[2] That qualification can help the supplier address customers whose material specifications include internationally recognized sustainability standards. In July 2025, AGC reported that the certification covered sustainable management and traceability of biomass-derived and renewable raw materials through manufacturing. The certified scope covers PVC resin together with vinyl chloride monomer, caustic soda, hydrochloric acid, and sodium hypochlorite at the Anyer plant. Site-linked traceability therefore gives sustainability-focused buyers a basis for qualifying the supplying plant as well as its PVC resin.
Indonesia Plastics Industry Leaders
-
Chandra Asri Group
-
LOTTE CHEMICAL TITAN HOLDING BERHAD
-
Asahimas Chemical Company
-
PT Pertamina (Persero)
-
Sulfindo Adiusaha
- *Disclaimer: Major Players sorted in no particular order
Indonesia Plastics Market Companies Covered in this Report
- Asahimas Chemical Company
- Chandra Asri Group
- Dow
- LOTTE CHEMICAL TITAN HOLDING BERHAD
- LyondellBasell Industries N.V.
- Mitsubishi Chemical Group Corporation
- PT Indonesia Nanya Indah Plastics
- PT Pertamina (Persero)
- PT Polychem Indonesia Tbk
- PT Standard Toyo Polymer (Tosoh Corporation)
- PTT Global Chemical Public Company Limited
- Sulfindo Adiusaha
- TORAY INDUSTRIES, INC.
Key Opportunities for Market Participants
The opportunities compare ways to turn prospective recycled-polyolefin supply into useful resin offerings for different conversion buyers. On October 15, 2026, Circulate Capital announced growth capital for Indonesian recycler Bumi Baru Plastik to scale recycled polypropylene and polyethylene processing and add downstream manufacturing lines.[3] The announced objectives included specialized compounds and bubble wrap for industrial and commercial customers, connecting recycling investment with specific downstream uses. These objectives create openings for material qualification and buyer development while the additional capacity and manufacturing lines are planned.
Market Opportunities Table of Indonesia Plastics Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Qualified recycled polypropylene supply | Announced capital supports expanded recycled PP processing | Industrial plastics converters | Qualify recycled PP against a defined component specification | Achieving repeatable material performance as processing scales | Bumi Baru Plastik and participating converters |
| Recycled polyethylene for protective packaging | Planned downstream integration includes bubble wrap | Protective-packaging converters serving industrial and commercial users | Develop recycled PE supply around a specified protective-packaging application | Matching recycled feedstock quality to the conversion process | Bumi Baru Plastik and protective-packaging producers |
| Application-specific recycled-polyolefin compounds | Specialized compounds are part of the announced downstream objectives | Industrial buyers requiring tailored compounds | Co-develop formulations for a defined industrial use | Translating formulation requirements into consistent commercial production | Bumi Baru Plastik and industrial compound users |
| Source: Mordor Intelligence | |||||
The central opening is to qualify recycled polyolefin resin around defined industrial applications ahead of the planned processing expansion. Resin sales would allow independent converters to perform the later transformation, while direct compound and packaging sales would retain more of that activity within the recycler. The announced objective of expanding recycled PP and PE processing capacity by a factor of 5 over the following 2 years makes early material qualification useful before the planned volume arrives.
Recent Industry Developments in Indonesia Plastics Market
- Oct 2026: Circulate Capital announced growth capital for Indonesian recycler Bumi Baru Plastik to expand recycled polypropylene and polyethylene processing and establish downstream manufacturing lines, including specialized compounds and bubble wrap.
- Oct 2026: Indonesia’s Ministry of Environment / Environmental Control Agency consulted on a draft regulation to replace P.75/2019, proposing packaging-design-based producer fees and full obligations from 2028.
- Jun 2026: PT Polytama Propindo began engineering, procurement, and construction work for its second polypropylene plant in Indramayu on June 22, expanding its project pipeline for domestic resin production.
Indonesia Plastics Market Report Scope and Research Methodology
Market Definition and Coverage
The Indonesia plastics market measures the annual volume of plastics resin consumed by processors in Indonesia, in tons. It covers resin classified by plastic type, conversion technology, and end-use application.
Scope exclusions: Naphtha, monomers, and other plastic feedstocks sold separately from resin, finished plastic articles and packaged goods, and plastics processing machinery are excluded.
Segments Covered in This Report
- By Type
- Traditional Plastics
- Polyethylene (PE)
- Polypropylene (PP)
- Polyvinyl Chloride (PVC)
- Polystyrene (PS)
- Engineering Plastics
- Polyethylene Terephthalate (PET)
- Polyamides
- Polycarbonates
- Styrene Copolymers (ABS and SAN)
- Polybutylene Terephthalate (PBT)
- Fluoropolymers
- Polyoxymethylene (POM)
- Polymethyl Methacrylate (PMMA)
- Other Engineering Plastics
- Bioplastics
- Traditional Plastics
- By Technology
- Blow Molding
- Extrusion
- Injection Molding
- Other Technologies
- By Application
- Packaging
- Electrical and Electronics
- Building and Construction
- Automotive and Transportation
- Furniture and Bedding
- Other Applications
Data Sources, Market Sizing, and Validation
Desk Research
Desk research uses sources such as Indonesia's WTO notification of customs import quantities for ethylene-alpha-olefin copolymers (HS 3901.40.00), the Indonesian Ministry of Environment's producer roadmap FAQ, UNEP's legal record of PermenLHK P.75/2019, and World Bank analysis of plastic material flows. The Ministry FAQ and UNEP record describe which producers and packaging materials fall under P.75/2019 waste-reduction duties, while the World Bank analysis frames plastics material flows in Indonesia. Analysts distinguish resin entering domestic conversion from articles, waste, and feedstocks by reconciling trade and production records.
Company filings, annual reports, investor materials, producer disclosures, and reputable Indonesian business and trade press can add evidence on operating capacity, output, planned projects, product grades, and customer applications. Analysts compare those disclosures with official trade and regulatory evidence and seek clarification where reported quantities overlap or use different units. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Structured interviews and surveys with Indonesian resin producers and importers, converters, distributors, and downstream procurement or operations leaders can clarify how much resin enters domestic conversion and how demand is divided by material, process, and application. Respondents can test secondary findings, explain gaps in reported capacity, output, trade, and utilization, and help reconcile conflicting quantities through follow-up questions and comparison with independent source records.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 43% | Functional/Unit leaders: 35% | |
| Smaller Players: 23% | Managers: 45% |
Market-Sizing & Forecasting
A top-down estimate starts with Indonesia's apparent domestic resin availability by combining domestic resin production and resin imports, then subtracting resin exports and adjusting for documented inventory changes or material that does not enter Indonesian conversion. Key indicators include production and utilization at local polymer plants, customs quantities for resin families, converter throughput and capacity, end-use production in packaging, construction, automotive, and electronics, and resin prices that can signal material substitution or inventory behavior. When production and trade records are reconciled with converter activity, the national consumption estimate takes shape. Historical volume and segment shares are reconciled across type, conversion technology, and application using producer output, trade records, converter activity, and disclosed end-use demand. Selective supplier roll-ups and sampled converter throughput checks test the national total, with gaps bounded using the closest comparable years and explicit assumptions. Time-series patterns and these demand indicators support a multivariate regression forecast, while scenario analysis tests announced capacity, import availability, and regulation-driven changes in resin use. Indonesian industry experts can review the direction and practical plausibility of variable-level forecasts, and unresolved inputs are carried as ranges rather than treated as observed facts.
Data Validation & Update Cycle
Analysts triangulate production, trade, capacity, converter demand, and end-use signals, then investigate outliers, double counting, unit mismatches, and material differences between independent estimates before sign-off. A second review checks source dates, calculations, segment totals, and forecast drivers, with respondent re-contact triggered by unexplained variances or material changes in capacity, trade, regulation, or reported demand. The evidence base is refreshed annually, updated between cycles after material market events, and checked again in a fresh pre-delivery review.
Mordor Intelligence's Indonesia Plastics Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Indonesia plastics market measures the annual volume of plastics resin consumed by processors in Indonesia, in tons.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key indicators include production and utilization at local polymer plants, customs quantities for resin families, converter throughput and capacity, end-use production in packaging, construction, automotive, and electronics, and resin prices that can signal material substitution or inventory behavior.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | 8.11 million tons (2027) | |
| Global Consultancy A | 7,126 KMT (2025) | Its estimate is for an earlier measurement year than the 2027 report figure. |
| Regional Consultancy B | 5 million metric tons (2026) | At its 2026 base, this estimate is 38.3% below this report's 2027 value of 8.11 million tons, 1 year later. It covers core commodity resins, while the report's total also includes engineering plastics and bioplastics. |
Mordor Intelligence's analysts triangulate production, trade, capacity, converter demand, and end-use signals, then investigate outliers, double counting, unit mismatches, and material differences between independent estimates before sign-off.
Key Questions Answered in the Report
What is the Indonesia plastics market size and projected growth?
Volume is expected to rise from 7.76 million tons in 2026 to 8.11 million tons in 2027 and 10.01 million tons by 2032, at a 4.31% CAGR over 2027-2032.
Which forces support plastics demand in Indonesia?
Domestic petrochemical capacity and parcel-shipping requirements are important forces. J&T Express’s shipments in Indonesia grew by more than 60% in 2025.
Which application leads Indonesian plastics demand?
Packaging held 45.53% of resin volume in 2026 and is forecast to grow fastest at a 5% CAGR over 2027-2032.
Which companies shape Indonesia’s resin industry?
Major participants include Chandra Asri Group, LOTTE CHEMICAL TITAN HOLDING BERHAD, Asahimas Chemical Company, PT Pertamina (Persero), and Sulfindo Adiusaha.
What could constrain plastics processing investment in Indonesia?
Carbon-pricing exposure may weigh on conversion economics. A 2025 simulation for Java, Madura and Bali linked higher modeled carbon taxes to higher electricity prices.
Which region anchors Indonesia’s plastics industry?
Java leads resin off-take and hosts polyethylene production at Merak and polypropylene production at Balongan.