
- Africa
- Asia
- Bangladesh
- Brazil
- Bulgaria
- Canada
- Chile
- China
- Colombia
- Egypt
- Europe
- France
- Germany
- Indonesia
- Iraq
- Italy
- Japan
- Jordan
- Kenya
- Malaysia
- Mexico
- Middle East
- Morocco
- Nigeria
- North America
- Norway
- Pakistan
- Philippines
- Poland
- Qatar
- Russia
- Saudi Arabia
- Singapore
- South Africa
- South America
- South East Asia
- South Korea
- Sri Lanka
- Thailand
- United Arab Emirates
- United Kingdom
- United States
- Vietnam
India Lubricants Market Analysis by Mordor Intelligence
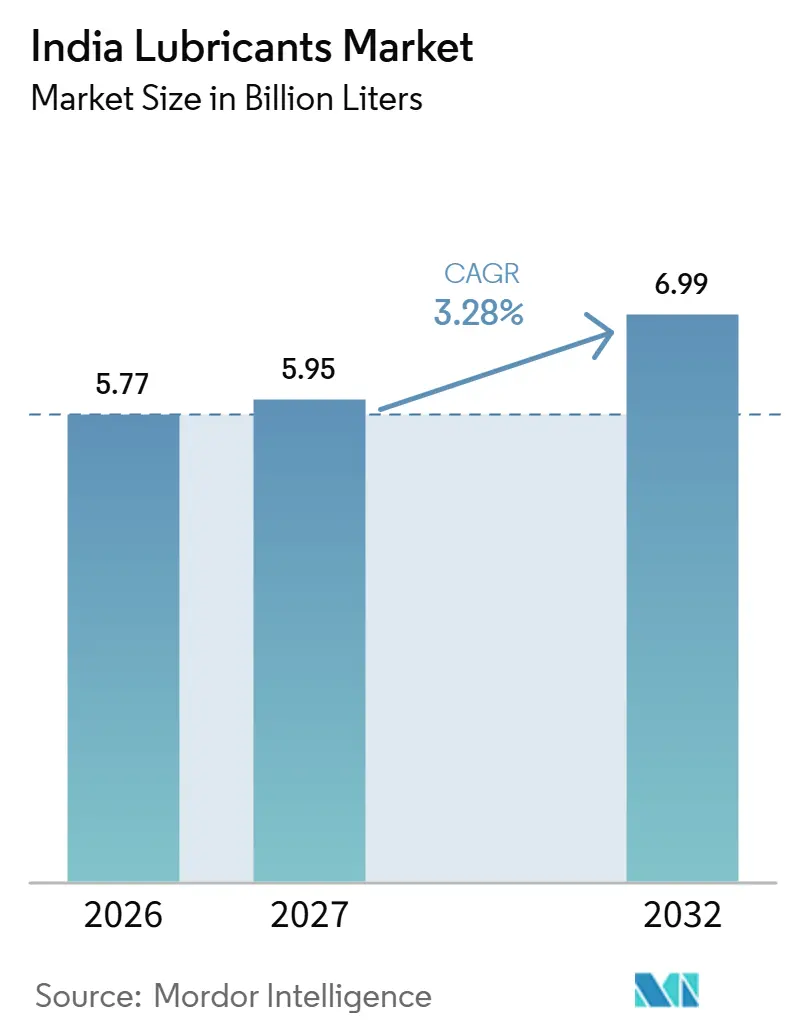
The India lubricants market size is expected to increase from 5.77 billion liters in 2026 to 5.95 billion liters in 2027 and reach 6.99 billion liters by 2032, growing at a CAGR of 3.28% over 2027-2032.
Vehicle servicing and manufacturing expansion in India support lubricant demand, while more demanding engine applications encourage formulation upgrades. These forces create room for suppliers to combine access to maintenance customers with oils suited to specific vehicle applications. Input-cost volatility and prospective electric-vehicle substitution constrain the demand that producers can capture profitably. Competitive responses include portfolio development, partnerships, and ownership changes that can reshape how specialized lubricants reach their users. Growth therefore depends on translating the operating vehicle and industrial base into sustained lubricant applications while managing cost pressure and changes in combustion-engine servicing demand.
Key Report Takeaways
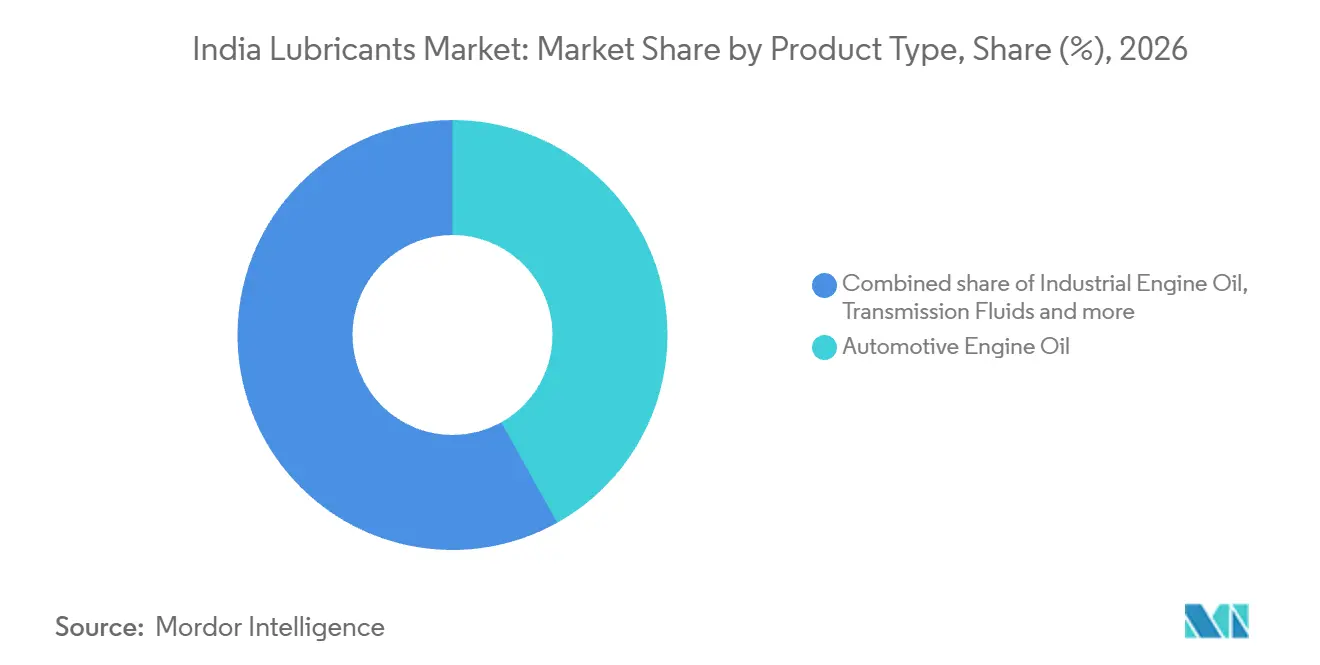
- By product type, automotive engine oil held a 41.89% India lubricants market share in 2026, while metalworking fluids are forecast to be the fastest-growing segment with a CAGR of 5.4% over 2027-2032.
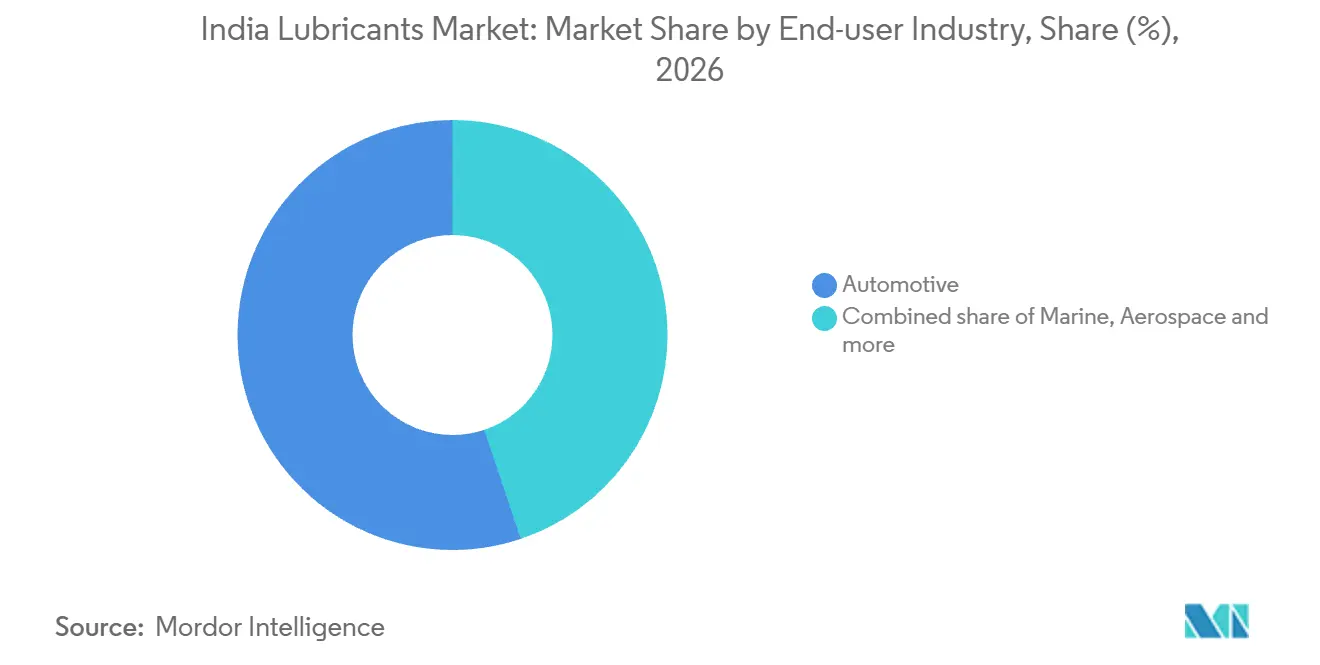
- Across end-user industries, automotive accounted for a 55.14% share of the India lubricants market size in 2026 and is the fastest-growing segment with a CAGR of 5.25% over 2027-2032.
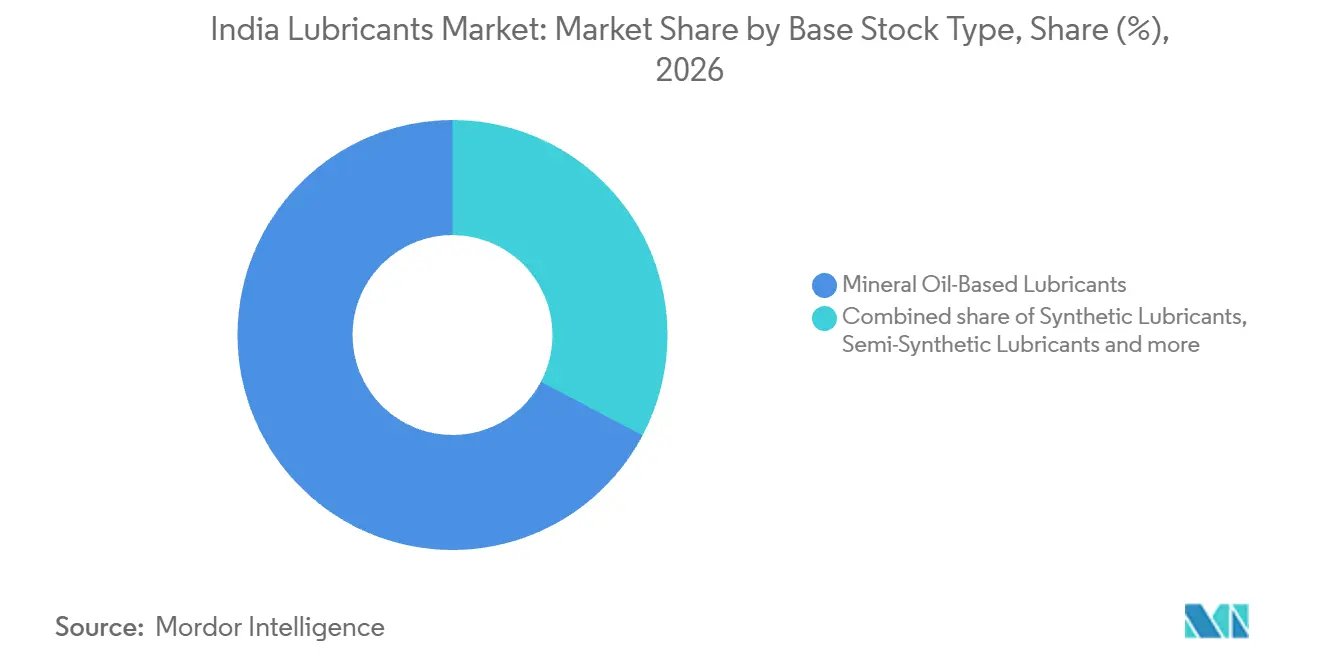
- Within base stock categories, mineral oil-based lubricants held 67.26% of India's lubricant volume in 2026, while synthetic lubricants are forecast to be the fastest-growing segment with a CAGR of 4.55% over 2027-2032.
- Geographically, Western India is the largest consumption center for engine and process oils, with Maharashtra and Gujarat central to that position.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Lubricants Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Vehicle Parc and Miles Driven | +1.8% | Nationwide | Medium term (2-4 years) |
| Industrial Output Growth Under “Make in India” | +1.3% | Nationwide | Medium term (2-4 years) |
| BS-VI and CAFE Norms Pushing Premium Lubricants | +1% | Nationwide | Medium term (2-4 years) |
| Rapid CNG Fleet Expansion Needs Dedicated Engine Oils | +0.7% | Nationwide | Medium term (2-4 years) |
| Digital Condition-monitoring Enabling Predictive Lube Changes | +0.2% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Vehicle Parc and Miles Driven
Vehicle additions can increase engine-oil change occasions as combustion-engine vehicles enter service, broadening the demand lubricant suppliers can address. SIAM reported domestic commercial-vehicle sales of 1,079,871 in India in FY2025-26, up from 958,679 in FY2024-25. On August 5, 2026, Castrol India reported about 950 Rural Service Express units catering to bikes in India. In its 3Q2025 earnings call, Castrol India said focused mechanic programs helped convert first-time users and accelerate repeat buying among bikers. Successive oil changes can extend the value of a newly reached rural customer, linking service-network expansion to a longer sales relationship.
Industrial Output Growth Under “Make in India”
Manufacturing expansion creates a demand opportunity tied to operating equipment as well as new factory investment. India's manufacturing component of the Index of Industrial Production grew 7.5% in April-August 2026-27, versus 4.2% in April-August 2025-26, with August 2026 figures classified as quick estimates.[1] More output can support additional lubricant use where it entails greater operation of lubricated machinery. The April-August comparison places the expansion across a 5-month period, rather than relying on August's quick estimate alone. Where that extra activity increases top-ups and change-outs, the commercial gain can come through more frequent replenishment by industrial users.
BS-VI and CAFE Norms Pushing Premium Lubricants
BS-VI-linked adoption of premium grades directs vehicle-servicing demand toward synthetic and low-viscosity lubricants. Castrol India reported in FY2025 that regulatory developments including BS-VI norms accelerated premiumization, with rising adoption of synthetic and low-viscosity lubricants.[2] Hyundai Motor India designates synthetic 0W-30 API SP as an optional engine oil for its BS-VI petrol and diesel models. Its routine maintenance schedule is every 10,000 kilometers or one year, whichever comes first. Hyundai's schedule creates an oil-service occasion at least annually, when the optional synthetic grade can compete for maintenance demand.
Rapid CNG Fleet Expansion Needs Dedicated Engine Oils
CNG vehicle additions expand the potential demand for engine oils suited to gas-fueled road transport. SIAM reported that CNG vehicle sales in India exceeded 1.2 million in FY2024-25, up 24% year over year and 157% over 3 years. Chevron's technical guidance says Cummins CES 20092 specifies lower ash than typical diesel oils and enhanced oxidation and nitration performance for extended drain intervals in mobile natural-gas engines. This mobile-engine specification illustrates how oil requirements can differ from diesel applications, connecting engine technology with a distinct formulation need. Suppliers can address the Indian sales expansion through engine-matched offerings, competing on suitability for the vehicles they serve.
Restraints Impact Analysis of India Lubricants Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatility in Base-oil and Additive Prices | -0.8% | Nationwide | Short term (≤ 2 years) |
| Accelerating EV Adoption Curbing ICE Lubricant Demand | -0.6% | Nationwide | Long term (≥ 4 years) |
| Import Dependency on Group III/IV Base Oils | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Volatility in Base-oil and Additive Prices
A volatile input bill makes stable finished-oil pricing harder for lubricant producers and their commercial customers. Castrol India reported that crude-oil and base-oil prices remained volatile in 2025 amid geopolitical events and refinery turnarounds. Gulf Oil Lubricants India's raw-material costs rose 60% year over year in Q2 2026, reaching 70% of total costs.[3] That company-specific burden illustrates how input inflation can narrow the room to absorb additional cost without changing selling prices. Passing costs through can constrain customer purchases, while absorbing them reduces the resources available to support those purchases. Either response leaves suppliers with less pricing flexibility precisely when unstable inputs make commercial commitments harder to sustain.
Accelerating EV Adoption Curbing ICE Lubricant Demand
Electrification constrains the future service demand available to suppliers focused on combustion-engine two-wheelers. On April 29, 2025, Castrol India management forecast a 10% correction in India's total two-wheeler lubricant volume requirement 5 to 8 years later under its EV-adoption scenario. The scenario assumed annual vehicle-parc growth of 8% over 7 to 8 years and an EV share of about 10% at that stage. The reduction is measured against the requirement that the assumed parc expansion would otherwise create. Offsetting that lost opportunity would require a supplier to win a larger share of the remaining combustion-engine oil changes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Lubricants Market Segment Analysis
By Product Type:
Engine-Oil Scale and Specialized Fluid DemandAutomotive engine oil accounted for a 41.89% share of the India lubricants market size in 2026. As the largest segment, it gives suppliers a substantial application base in which individual product categories can generate distinct demand opportunities. Castrol India reported that its passenger-car-oil volumes grew 7% in FY2025, nearly 1.5 times overall vehicle-parc expansion. That company result identifies passenger-car oil as a commercially active part of engine-oil demand, with product-volume growth exceeding its vehicle-base comparison. Competing for oil changes within the existing passenger-car population can expand a supplier's volumes faster than vehicle additions alone.
Metalworking fluids are forecast to be the fastest-growing segment, with a CAGR of 5.4% over 2027-2032. In its Q2 2026 earnings call on August 5, 2026, Castrol India reported advancing localization by introducing Alusol SL 61 XBB, a specialized industrial coolant in its metalworking-fluid range. Localization can position a specialized fluid supplier closer to the production applications it serves. Transformer oil serves a separate equipment requirement, illustrated by Western Railway's April 1, 2025 order for Nynas Nytro 10 oil from Madhva Enterprises India Private Limited for Siemens EMU rake main transformers. Localizing a coolant for demanding machining operations gives metalworking-fluid suppliers a product-specific way to compete for industrial applications.



By End-user Industry:
Automotive Demand Combines Scale and GrowthAutomotive was the largest segment with a 55.14% share of lubricant volume in 2026 and is the fastest-growing segment, with a CAGR of 5.25% over 2027-2032. SIAM reported domestic two-wheeler sales of 21.7 million units in FY2025-26, up 10.7% from FY2024-25. That scale gives lubricant suppliers a substantial vehicle category to address through the products used in combustion-engine models. Commercial coverage can be organized around the service needs of individual riders while also accommodating supply relationships associated with vehicle production. Rider servicing after purchase is where the combustion-engine portion of those additions can become recurring oil volume.
Automotive aftermarket supply also offers a contracted distribution route through vehicle manufacturers' service networks. PETRONAS Lubricants (India) Pvt. Ltd., a subsidiary of PETRONAS Lubricants International, was awarded Mahindra & Mahindra Ltd.'s Aftermarket Service Fill contract on June 23, 2025. The contract provided for sole distribution of Maximile vehicle fluids through Mahindra's South Zone authorized dealers, workshops, and stockists. Its portfolio spanned 50 stock-keeping units, including engine oils, transmission oils, axle oils, and steering fluids for passenger cars and SUVs. The South Zone mandate combines multiple fluid applications in one authorized network, making this distribution award broader than an engine-oil supply agreement.

By Base Stock Type:
Mineral-Oil Volume and Synthetic Contract AccessMineral oil-based lubricants represented a 67.26% India lubricants market share in 2026. The segment's scale rests on cost-led demand in legacy engines and farm equipment. For these buyers, mineral grades compete on the cost of meeting existing lubrication requirements. Premiumization erodes that volume base when buyers move to synthetic grades, making retention of price-sensitive applications central to suppliers' mineral-oil business.
Synthetic lubricants are forecast to be the fastest-growing segment, with a CAGR of 4.55% over 2027-2032. Castrol India signed a supply agreement with motorcycle manufacturer Triumph in 1Q2025 for Castrol POWER1, a two-wheeler engine oil with full-synthetic technology. Savita Oil Technologies commissioned Phase 2 of its synthetic-ester manufacturing plant at Mahad, Maharashtra, on February 28, 2026. Designed primarily for transformer-fluid applications, the multipurpose plant is also intended to produce synthetic esters for high-performance automotive and industrial lubricants. Manufacturer contracting and domestic ester production provide distinct routes to expand synthetic use, with growth depending on converting product access and input capability into lubricant sales.
Geography Analysis
Western India Lubricants Market
Western India is the largest consumption center for engine and process oils, with Maharashtra and Gujarat central to that position. On July 1, 2025, the Maharashtra Pollution Control Board decided to grant ExxonMobil Lubricants Private Limited first operating consent for annual blending capacity of 159 million liters at Isambe in Maharashtra. The plant had held a consent to establish since June 19, 2022, so the later decision concerned its transition toward operation. That transition would add blending capability within Western India's consumption center, connecting regional demand with an in-region supply investment. The July 2025 decision tied consent issuance to verified installation of the plant and its pollution-control systems before commercial operation.
Tamil Nadu, Maharashtra, Gujarat, Uttar Pradesh, and Haryana were the 5 leading states for registered manufacturing employment in FY2024-25, together accounting for about 56% of the national total. Their combined manufacturing presence gives industrial lubricant suppliers a geographically concentrated set of potential customer locations to address. A state-by-state industrial sales strategy can target equipment operators across this group, with application coverage shaped by each customer's production processes. Industrial technical coverage across these 5 states can reach major manufacturing locations beyond the western consumption center.
Tamil Nadu also has a distinct lubricant-manufacturing role through a completed addition to its supply infrastructure. In Chennai, Tamil Nadu, IndianOil commissioned an integrated lube blending plant with capacity of 672,000 metric tons annually during FY2025-26. The completed commissioning contrasts with the conditional July 2025 operating-consent decision in Maharashtra. Tamil Nadu's position among the leading manufacturing-employment states also creates a separate industrial sales opportunity. Distribution relationships can develop around the commissioned plant, while industrial sales depend on serving equipment operators across the state's manufacturing base.
Regulatory Framework and Outlook
The comparison covers India and Maharashtra from the perspective of lubricant producers subject to used-oil extended producer responsibility, with Maharashtra's pollution-control board administering hazardous-waste authorization. India's regime requires covered base-oil and lubrication-oil producers and used-oil importers to register with CPCB and meet recycling obligations under the Hazardous and Other Wastes (Management and Transboundary Movement) Rules, 2016, as amended in 2023. CPCB's February 2025 letter asked state boards, responsible for implementation under Rule 37(2)(i), to issue notices and directions for used-oil EPR stakeholders to register.
Regulatory Table of India Lubricants Market
| Decision factor | India | Maharashtra |
|---|---|---|
| Primary authority | Central Pollution Control Board for producer registration and the EPR portal | Maharashtra Pollution Control Board for state implementation and hazardous-waste authorization |
| Key instruments or direction | National used-oil EPR rules, in force since April 2024 | National used-oil EPR implementation and hazardous-waste authorization procedures |
| Commercial effect | Covered producers must organize compliance with recycling obligations | Producers address national EPR obligations alongside state waste-management administration |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
India's established registration route supports a Medium rating, while its scheduled producer recycling targets rise from 20% in 2027-28 to 40% in 2028-29 and 2029-30, then 50% from 2030-31 onward. Targets use base oil or lubrication oil sold or imported 2 financial years earlier. Units established after April 1, 2024 start 2 years after the end of their establishment financial year. Maharashtra's Medium rating reflects the combination of national obligations and state authorization, and its Hardening direction follows that same scheduled national increase.
Value Chain Stages
The comparison follows lubricant manufacturing, distribution, and vehicle servicing to distinguish where suppliers capture earnings and where delivery can fail. In FY2024-25, Veedol Corporation Limited reported 5 manufacturing plants and more than 30 depots, illustrating the physical infrastructure behind product supply. On August 5, 2026, Castrol India reported a national footprint of approximately 160,000 outlets, showing the separate reach required after manufacturing.
Value Chain Analysis Table of India Lubricants Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Lubricant manufacturing | Lubricant manufacturers such as Bharat Petroleum Corporation Limited and Veedol Corporation Limited | Finished-lubricant sales | Production interruptions can restrict supply to downstream channels | Coordinate production across the manufacturing footprint |
| Distribution to outlets | Lubricant suppliers such as Castrol India and Bharat Petroleum Corporation Limited | Wholesale lubricant sales | Broad outlet coverage complicates local replenishment | Align depot dispatch with distributor replenishment needs |
| Vehicle servicing | Branded service-network providers such as Castrol India | Workshop maintenance service fees | Uneven service availability can limit access to vehicle owners | Extend workshop access across additional towns |
| Source: Mordor Intelligence | ||||
On August 5, 2026, Castrol India reported that its branded Auto Service network was 850 strong, establishing a service presence beyond product distribution. That reach gives the downstream stage a distinct commercial function because workshops connect maintenance activity with vehicle owners. The chain's constraint can therefore shift downstream even when blending capacity is available, making workshop coverage a separate condition for turning finished product into serviced demand.
Competitive Landscape
Market Concentration
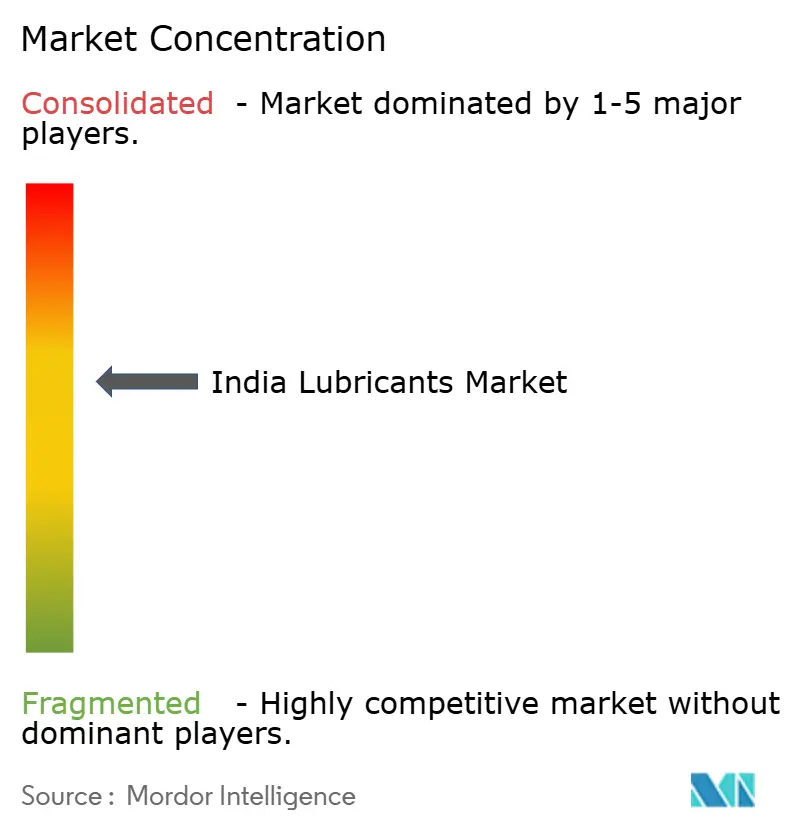
Branded lubricant competition brings Indian Oil Corporation Limited's SERVO and BP p.l.c.'s Castrol India alongside Bharat Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, and Shell plc. Bharat Petroleum markets MAK automotive and industrial lubricants and greases, HPCL markets lubricants, and Shell owns lubricant businesses in India. Castrol India reported 8 consecutive quarters of volume growth ahead of the market in its FY2025 performance discussion. Castrol India reported gaining market share through those 8 quarters, so established competing brands face a supplier expanding both its sales and its relative position.
Hindustan Petroleum Corporation Limited and LANXESS signed a memorandum of understanding in May 2026 to explore aviation and industrial lubricant marketing opportunities in India and SAARC countries. The agreed exploration paired HPCL's marketing role with LANXESS's branded lubricant portfolio, creating a potential route toward specialized applications. Shell Lubricants completed its acquisition of 100% of Raj Petro Specialities Pvt. Ltd. from the Brenntag Group on July 1, 2025. The MoU concerns exploration of marketing opportunities, leaving potential sales dependent on a subsequent commercial arrangement. Shell's completed acquisition brings the acquired Indian business and its customer relationships under Shell Lubricants' ownership.
Ownership changes add a separate dimension to competition because control of a lubricant business can change before its customer-facing operations do. In December 2025, BP p.l.c. agreed to sell 65% of its global Castrol lubricants business to Stonepeak and retain 35%, subject to customary approvals and expected completion by the end of 2026. Castrol India reported that its day-to-day operations, market presence, and customer commitments were unchanged. India's used-oil EPR rules require base-oil and lubrication-oil producers and used-oil importers to register with CPCB and place the recycling obligation entirely on the producer. Ownership and partnership changes can reshape supply to Indian customers while leaving each producer's compliance duty in place.
India Lubricants Industry Leaders
-
Indian Oil Corporation Limited
-
BP p.l.c.
-
Bharat Petroleum Corporation Limited
-
Hindustan Petroleum Corporation Limited
-
Shell plc
- *Disclaimer: Major Players sorted in no particular order
India Lubricants Market Companies Covered in this Report
- Bharat Petroleum Corporation Limited
- BP p.l.c.
- Chevron Corporation
- Exxon Mobil Corporation
- FUCHS
- Gulf Oil International Ltd
- Hindustan Petroleum Corporation Limited
- Indian Oil Corporation Limited
- MOTUL
- PETRONAS Lubricants International
- Shell plc
- TotalEnergies
- Valvoline Cummins Private Limited
- Veedol Corporation Limited
Key Opportunities for Market Participants
The comparison considers prospective lubricant supply to automotive workshops, commercial fleets, and industrial users against a planned increase in manufacturing capacity. In August 2026, Gulf Oil Lubricants India announced plans to expand capacity at Chennai and Silvassa by around 70% over the following 2 years, citing expected automotive and industrial demand growth. That planned headroom creates a potential opening for differentiated customer coverage if manufacturing investment is matched with access to the relevant users.
Market Opportunities Table of India Lubricants Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Replacement-lubricant supply through workshops | Automotive demand outlook accompanies planned supply expansion | Automotive workshops | Pair lubricant supply with workshop technical support | Reaching individual service locations | Automotive lubricant suppliers such as Gulf Oil Lubricants India |
| Fleet lubricant supply agreements | Planned capacity could support additional automotive accounts | Commercial vehicle fleets | Build account-specific lubricant supply and service proposals | Converting production headroom into repeat fleet business | Fleet lubricant suppliers such as Gulf Oil Lubricants India |
| Industrial lubricant application support | Industrial demand outlook underpins the expansion plan | Industrial plant operators | Combine lubricant selection support with recurring plant supply | Establishing application performance at each plant | Industrial lubricant suppliers such as Gulf Oil Lubricants India |
| Source: Mordor Intelligence | |||||
The central opening is to convert additional manufacturing headroom into repeat business at the point where lubricants enter service. A workshop relationship, a fleet account, and a plant supply arrangement require different forms of customer access despite drawing on the same production base. Capacity investment becomes commercially productive when suppliers can turn that access into sustained lubricant use, rather than relying on added output alone.
Recent Industry Developments in India Lubricants Market
- Oct 2026: Indian Oil Corporation Limited and Jindal Stainless renewed their lubricants Vendor Managed Inventory partnership for 5 years, with the signing ceremony at Jindal Stainless' Hisar unit.
- Aug 2026: Gulf Oil Lubricants India announced plans to expand lubricant manufacturing capacity at Chennai and Silvassa by around 70% over the following 2 years, citing expected automotive and industrial demand growth.
- May 2026: LANXESS and Hindustan Petroleum Corporation Limited signed a memorandum of understanding to explore marketing and business development for aviation and industrial lubricants in India and SAARC countries.
India Lubricants Market Report Scope and Research Methodology
Market Definition and Coverage
The India lubricants market measures the annual volume of finished lubricant products consumed in India. It covers consumption across end-user industries, including domestically supplied and imported products.
Scope exclusions: Separately sold lubricating base oils, separately sold lubricant additives, fuel additives, and non-lubricant automotive fluids including engine coolant are excluded.
Segments Covered in This Report
- By Product Type
- Automotive Engine Oil
- Industrial Engine Oil
- Transmission Fluids
- Gear Oil
- Brake Fluids
- Hydraulic Fluids
- Greases
- Process Oil (Including Rubber Process Oil and White Oil)
- Metalworking Fluids
- Turbine Oil
- Transformer Oil
- Other Product Types
- By End-user Industry
- Automotive
- Passenger Vehicles
- Commercial Vehicles
- Two-Wheelers
- Marine
- Aerospace
- Heavy Equipment
- Construction
- Mining
- Agriculture
- Industrial
- Power Generation
- Metallurgy and Metalworking
- Textiles
- Oil and Gas
- Other End-Use Industries
- Automotive
- By Base Stock Type
- Mineral Oil-Based Lubricants
- Synthetic Lubricants
- Semi-Synthetic Lubricants
- Bio-Based Lubricants
Data Sources, Market Sizing, and Validation
Desk Research
Public research uses sources such as the Petroleum Planning and Analysis Cell's Industry Consumption Review for petroleum consumption context and lubricants and greases data, the Society of Indian Automobile Manufacturers' annual reports for domestic vehicle sales and production, Castrol India's annual report for company-reported lubricant trends and industry context, the Ministry of Road Transport and Highways Vahan registry for vehicle registrations, and Press Information Bureau releases of the Index of Industrial Production for manufacturing output. PPAC series help check consumption patterns, while vehicle registration and industrial production indicators inform vehicle-related demand and industrial activity.
Company annual reports, exchange filings, investor presentations, and reputable business press can clarify capacity, product mix, customer channels, input costs, and announced investments. Each item is checked for India relevance and whether it measures finished lubricants, an input, or a related activity. These examples are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
India-focused interviews and surveys draw on lubricant manufacturers and blenders, distributors, automotive service channels, and industrial lubricant users, with senior leaders and functional managers explaining purchasing, sales, and application patterns. Interviews and survey responses test secondary findings on consumption, product mix, channel movement, and forecast drivers, and check how those patterns vary by customer type and application. Where sources or respondents leave a gap, analysts compare independent supply, channel, vehicle, and industrial indicators and seek a second source or targeted follow-up before using the item.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The estimate uses a top-down model of annual finished-lubricant consumption in liters in India, checked selectively against producer supply, imports, distributor movement, and sampled selling volumes where available. Vehicle parc and domestic vehicle sales help estimate automotive service and factory-fill demand. Industrial production and activity in lubricant-intensive sectors inform industrial and heavy-equipment use. Product specifications, drain intervals, and the mix of mineral, synthetic, semi-synthetic, and bio-based grades help explain liters consumed by application. Product, end-user, and base-stock shares are built from corresponding demand indicators and checked against one another so each view describes the same national consumption pool.
A time-series forecast can extend the historical volume path, with scenario adjustments for vehicle additions, manufacturing activity, longer drain intervals, and electrification. Primary experts can test whether each variable's assumed direction and application are plausible. Selective bottom-up checks, such as supplier volume roll-ups or sampled average selling price times volume where value checks are useful, test the scale without replacing the top-down estimate. If a company or channel input is unavailable, the model uses the closest public supply, vehicle, or sector indicator and keeps assumptions explicit for review.
Data Validation & Update Cycle
Analysts triangulate the consumption estimate against PPAC petroleum series, reported supplier activity, vehicle indicators, and industrial signals, then investigate material variance from the prior period or between independent indicators. A reviewer checks scope, units, arithmetic, segment-share consistency, source dates, and anomaly explanations before sign-off. Unresolved differences trigger source re-checks or targeted respondent follow-up. The evidence is refreshed annually, updated between cycles when a material policy, supply, or demand event changes the outlook, and reviewed again in a fresh pre-delivery pass.
Mordor Intelligence's India Lubricants Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The India lubricants market measures the annual volume of finished lubricant products consumed in India.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. If a company or channel input is unavailable, the model uses the closest public supply, vehicle, or sector indicator and keeps assumptions explicit for review.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | 5.95 billion liters (2027) | |
| Global Consultancy A | USD 5.15 B (2026) | Its published estimate is value-based, so dollars incorporate price and product mix rather than annual consumed liters. |
| Industry Supplier B | 3.01 billion liters (2025) | At its 2025 base, this estimate is 49.4% below this report's 2027 value of 5.95 billion liters, 2 years later. The public estimate uses an earlier measurement year, which can place its reported volume below a later-year estimate. |
Mordor Intelligence's analysts triangulate the consumption estimate against PPAC petroleum series, reported supplier activity, vehicle indicators, and industrial signals, then investigate material variance from the prior period or between independent indicators.
Key Questions Answered in the Report
What is the India lubricants market size and growth outlook?
The size is forecast to rise from 5.95 billion liters in 2027 to 6.99 billion liters by 2032, growing at a CAGR of 3.28% over 2027-2032.
What supports demand for lubricants in India?
Vehicle servicing, manufacturing expansion, and BS-VI-related formulation upgrades support demand in India. CNG vehicle sales exceeded 1.2 million in FY2024-25, widening the potential customer base for oils suited to CNG engines.
Which lubricant product category has the largest share?
Automotive engine oil held the largest product share at 41.89% of lubricant volume in 2026. Metalworking fluids are forecast to be the fastest-growing product segment with a CAGR of 5.4% over 2027-2032.
Which companies compete in India's lubricant industry?
Major suppliers include Indian Oil Corporation Limited, BP p.l.c., Bharat Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, and Shell plc.
What challenges shape the outlook for lubricant suppliers?
Input-cost volatility and prospective EV substitution constrain suppliers in India. Gulf Oil Lubricants India's raw-material costs rose 60% year over year in Q2 2026, reaching 70% of its total costs.
Which part of India leads engine and process-oil consumption?
Western India is the largest consumption center for engine and process oils, with Maharashtra and Gujarat central to that position.