
Germany Diabetes Care Drugs and Devices Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 5.62 Billion |
| Market Size (2027) | USD 5.86 Billion |
| Market Size (2032) | USD 7.24 Billion |
| Growth Rate (2027 - 2032) | 4.33 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Germany Diabetes Care Drugs and Devices Market Analysis by Mordor Intelligence
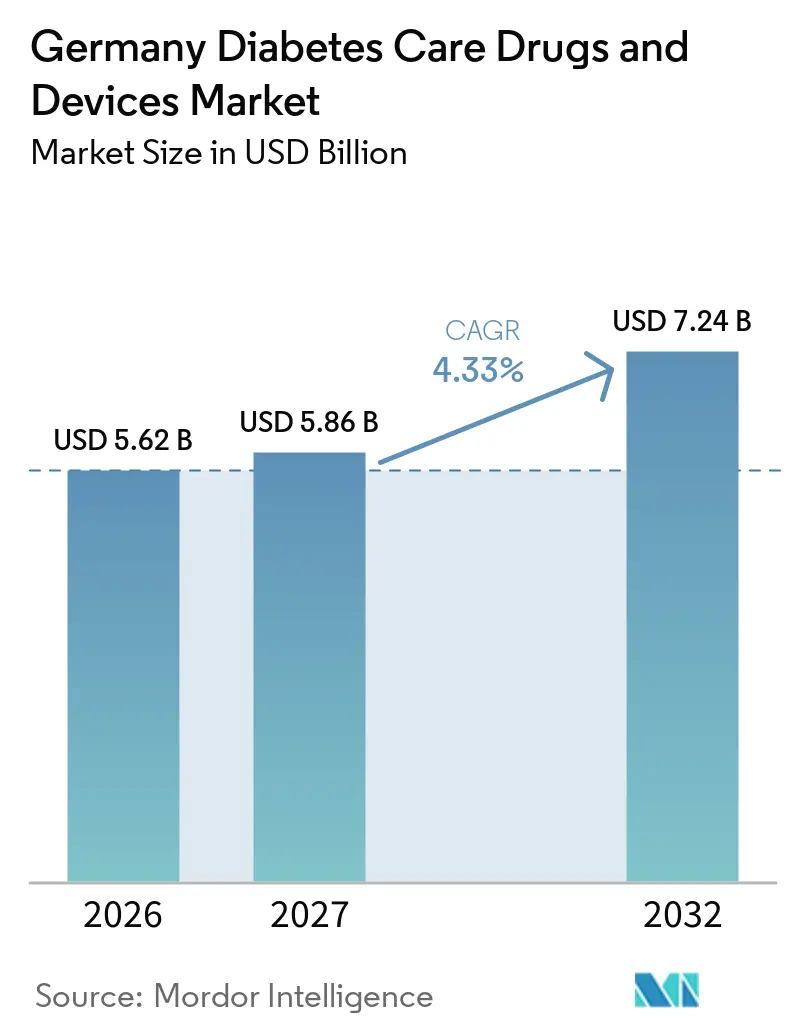
The Germany Diabetes Care Drugs And Devices Market size was valued at USD 5.62 billion in 2026 and is estimated to grow from USD 5.86 billion in 2027 to reach USD 7.24 billion by 2032, at a CAGR of 4.33% during the forecast period (2027-2032).
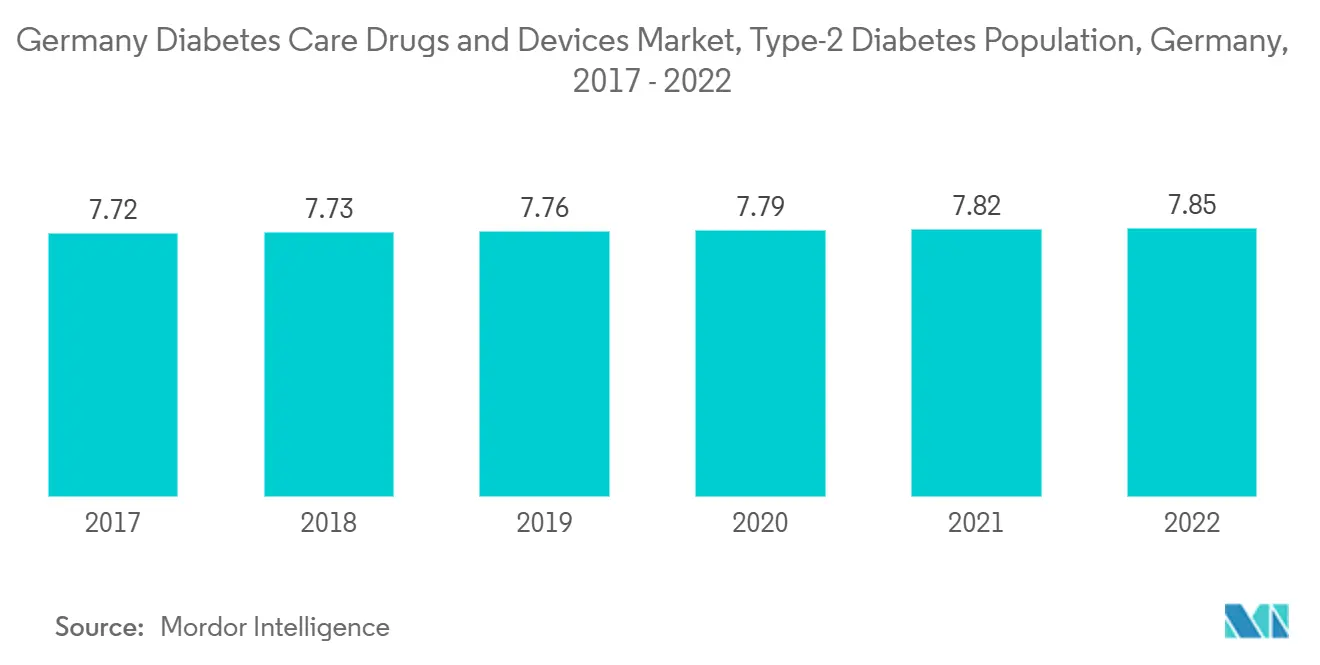
Diabetes drugs and devices are designed to stabilize and control blood sugar levels in people with diabetes. Antidiabetic drugs have become potential candidates for treating diabetic patients affected by SARS-CoV-2 infection during the novel coronavirus disease (COVID-19) pandemic. According to the German Diabetes Center (DDZ), at least 7.2% of the German population currently has diabetes, and the trend is expected to increase significantly over the next 20 years. It has been observed that the rate of new diagnoses of type 1 and type 2 diabetes is increasing, mainly due to obesity, unhealthy diet, and lack of exercise. Rapid increases in the incidence and prevalence of diabetes and health care costs indicate an increase in the use of antidiabetic drugs.
Redemption and pricing policies are highly regulated, which drives the market and increases acceptance of new advanced technologies. Market opportunities for players in the German diabetes care devices market include numerous new product introductions, increased international research collaboration for technological advances, and increased public education on diabetes. Thus, the above factors are expected to drive market growth over the forecast period.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
The continuous Glucose Monitoring Segment is Expected to Witness the Highest Growth Rate Over the Forecast Period
The continuous blood glucose monitoring segment is projected to grow at a CAGR of around 5.6% during the forecast period.
According to the European Health System and Policy Watchdog 2021, Germany has the world's oldest social insurance system (GKV). Health insurance is compulsory. People whose income exceeds certain limits or belong to certain occupational groups can opt out of statutory health insurance and enroll in private health insurance (PKV). About 11% of the population has private health insurance, and 89% have statutory health insurance. The insurance covers all legal residents, but only 0.1% of her population does not have health insurance.
The frequency of observing glucose levels depends on the write of diabetes, which varies from patient to patient. Type-1 diabetic patients must verify their blood glucose levels at common intervals, supervise their blood glucose levels, and adjust the insulin dosing. Therefore, if a patient accomplishes 5-6 tests daily, the ordinary money on test strips may be over USD 100 / month. These expenses add to the already elevated costs of diabetes management and add to the industry's development. The common CGM equipment accurately represents blood glucose patterns and tendencies compared to daily tasks to check glucose levels at set periods.
Continual glucose monitoring devices have become a well-liked choice for portable finger-prick glucometers accessible in the industry for the comfort of diabetic patients. Continued glucose observing equipment is becoming less expensive with the advent of new technologies, like cell phone integration, which will probably maneuver the slice development during the forecast period.
Rising diabetes prevalence
Diabetes prevalence in Germany has risen significantly in recent years. People with diabetes require several interventions each day to maintain target blood glucose levels, including oral antidiabetic medications, blood glucose monitoring, and carbohydrate intake when needed. New diagnoses of type 1 and type 2 diabetes are increasing, largely because of obesity, unhealthy diets, and physical inactivity. The growing incidence and prevalence of diabetes, coupled with rising healthcare expenditure, are driving the use of diabetes medications and devices.
Diabetes poses a significant health concern and remains one of the primary challenges facing Germany's healthcare system. Diagnosed type 1 and type 2 diabetes is highly prevalent among the German adult population, while a considerable number of individuals remain undiagnosed. The aging population and unhealthy lifestyles are likely to steadily increase the prevalence of type 2 diabetes in the coming years. High-quality care, including effective monitoring, risk factor assessment, and active self-management, is essential to prevent complications in German patients with type 2 diabetes.
Oral antidiabetic agents are widely available and are recommended when lifestyle modifications alone do not sufficiently manage type 2 diabetes and treatment intensification is necessary. Oral medications typically serve as the first-line treatment for type 2 diabetes, owing to their diverse mechanisms of action, established efficacy, and safety profiles. These medications enable people with diabetes to manage their condition and lower the risk of diabetes-related complications. Patients may require lifelong antidiabetic treatment to maintain blood glucose control and prevent hypoglycemia and hyperglycemia. Oral antidiabetic drugs are easy to administer and comparatively affordable. These advantages position them as an attractive alternative to insulin therapy and support higher patient acceptance and treatment adherence.
Diabetes management increasingly relies on data, with real-world health and treatment data supporting integrated and personalized chronic disease care. Patients and diabetes care providers can use continuously collected metabolic, therapeutic, and lifestyle data to make shared treatment decisions. The growing incidence, prevalence, and progression of diabetes have accelerated the development of new drugs, expanding treatment options for patients. Key opportunities for participants in the German diabetes drug market include new product launches, greater international research collaboration to advance technology, and increased public awareness and education regarding diabetes.

Competitive Landscape
Market Concentration
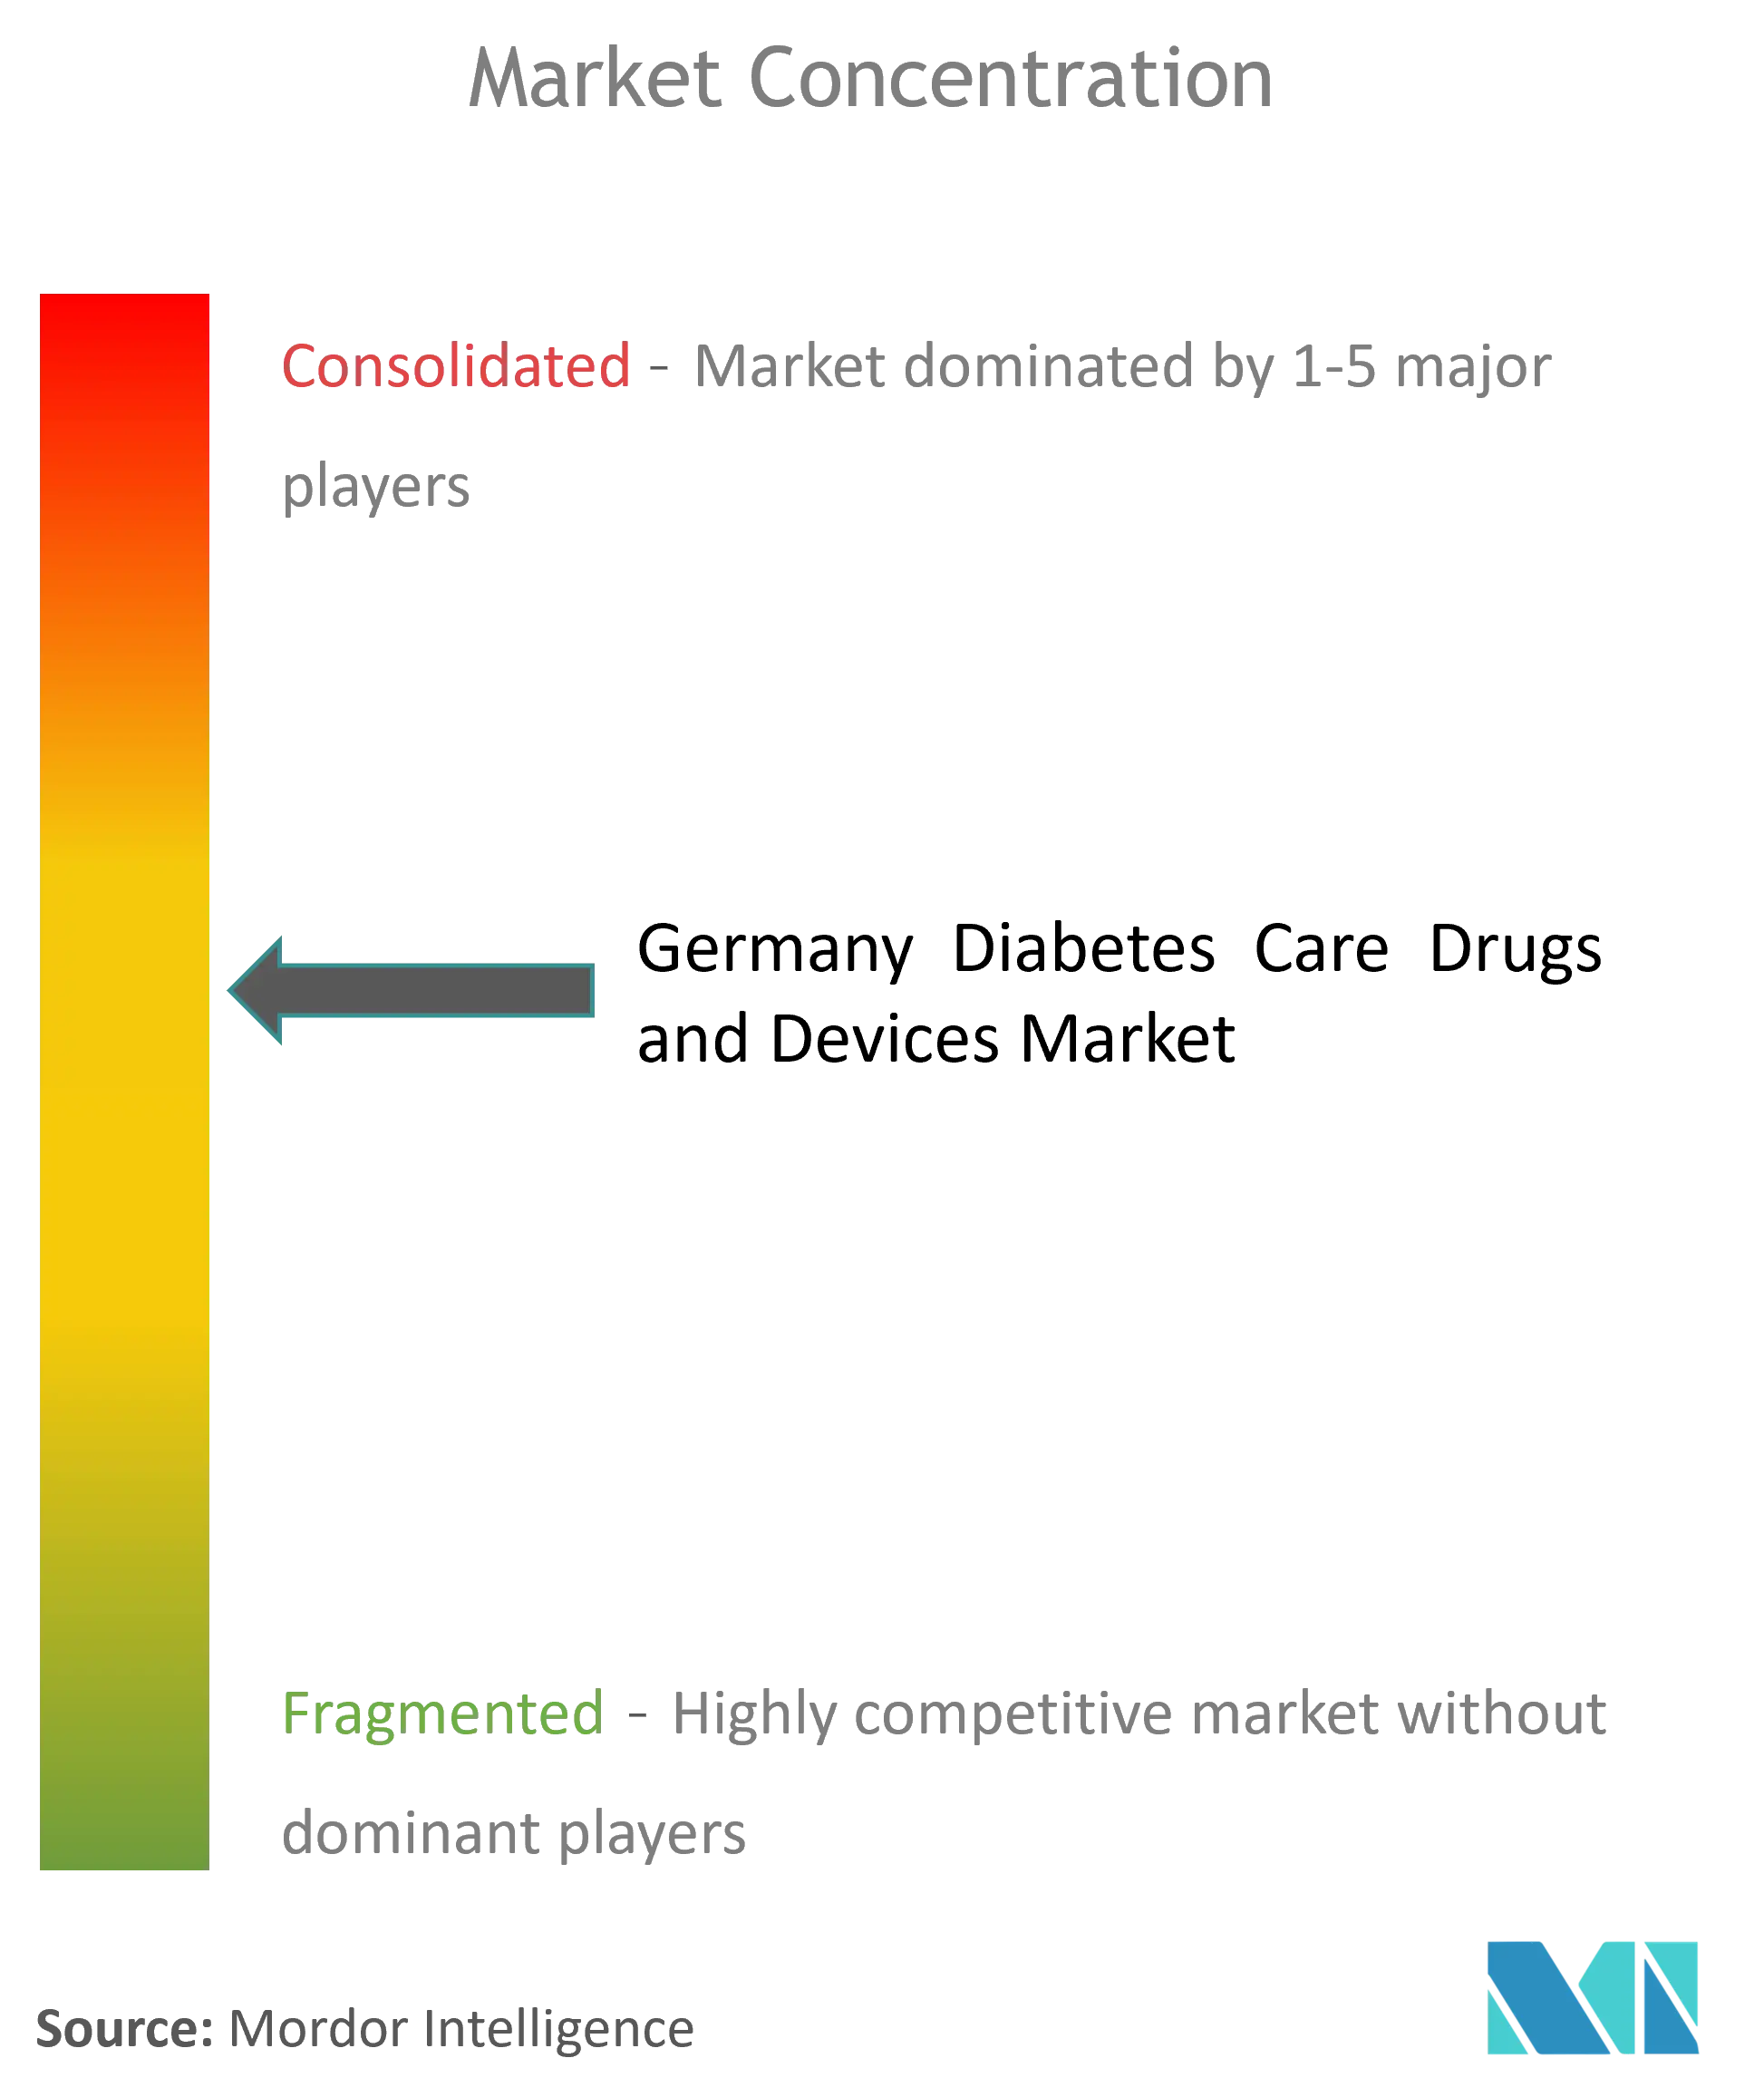
The German diabetes care drugs and devices market is moderately consolidated, with key players including Abbott, Roche, Dexcom, Medtronic, Novo Nordisk, Sanofi, Eli Lilly, and Insulet competing through product innovation, strategic collaborations, and portfolio expansion. The market is characterized by strong adoption of continuous glucose monitoring (CGM) systems, insulin pumps, connected insulin pens, and advanced insulin therapies, supported by Germany's well-established reimbursement framework and healthcare infrastructure. Companies are increasingly focusing on integrated diabetes management solutions that combine glucose monitoring, digital health platforms, and insulin delivery technologies to improve patient outcomes and treatment adherence, while continuous investments in research and development and the introduction of next-generation diabetes care products are expected to intensify competition in the market.
Germany Diabetes Care Drugs and Devices Industry Leaders
-
Medtronics
-
Roche
-
NovoNordisk
-
Sanofi
-
Omnipod
- *Disclaimer: Major Players sorted in no particular order
Germany Diabetes Care Drugs and Devices Market Companies Covered in this Report
- Novo Nordisk
- Medtronic
- Insulet
- Tandem Diabetes Care
- Ypsomed
- Novartis
- Sanofi
- Eli Lilly and Company
- Abbott Laboratories
- Roche
- AstraZeneca
- Dexcom
- Pfizer
Read Analysis of Germany Diabetes Care Drugs and Devices Companies
Market Opportunities and Future Outlook
Germany's diabetes care opportunity set is expanding around connected care pathways that combine drugs, devices, and digitally enabled services within the country's regulated reimbursement environment. The clearest focus is on scaling integrated insulin delivery and monitoring ecosystems (CGM linked to pumps and automated insulin delivery algorithms), supported by growing adoption of integrated systems and early uptake of advanced diabetes technologies in Germany. Digital companion programs that support adherence and self-management also create differentiation potential, particularly when they fit statutory insurance workflows and documentation requirements.
Germany's future outlook for diabetes care products is shaped by tighter evidence and data expectations for digital health solutions, along with supply-chain and component considerations for sensors and disposables. The Federal Institute for Drugs and Medical Devices (BfArM) is linked to the DiGA framework, and starting in Q3 2026, requires DiGA manufacturers to submit usage data every six months, with the first dataset due April 15, 2027, which reinforces the role of real-world data in market access. On the product side, shifts in type 2 diabetes therapy toward GLP-1 agonists and continued integration of CGM with closed-loop systems keep both pharma portfolios and device platforms active. Efforts to reduce component cost volatility for sensor electronics, enzyme chemistry, and medical-grade adhesives support broader access strategies across statutory and private insurance channels.
Recent Industry Developments in Germany Diabetes Care Drugs and Devices Market
- July 2026: Diabeloop: DBLG2 Automated Insulin Delivery (AID) system integrated with ViCentra Kaleido insulin patch pump and Dexcom G7 CGM opened for prescription in Germany. The rollout expands access to advanced integrated pump CGM therapy in the German market and supports broader adoption of closed-loop diabetes management approaches.
- July 2026: Medtrum: Medtrum 300U tubeless patch pump listed in Germany's Hilfsmittelnummer directory for GKV reimbursement. The reimbursement pathway for a high-capacity tubeless patch pump supports Medtrum's market entry and pricing position in the German diabetes device market.
- July 2026: Novo Nordisk and Smartpatient: Novo Nordisk partners with Smartpatient to launch a diabetes care program for type 2 diabetes in Germany. The digital care program expands payer and patient engagement and aligns with integrated care trends in Germany.
Germany Diabetes Care Drugs and Devices Market Report Scope and Research Methodology
Market Definition and Coverage
For this report, the market covers revenue generated in Germany from diabetes care drugs and diabetes care devices used to treat, manage, and monitor diabetes, with values tracked in USD.
Scope exclusions: We exclude general hospital services, physician visits, broad diabetes diagnostics not tied to diabetes monitoring devices, and non-medical wellness products.
Segments Covered in This Report
- Devices
- Monitoring Devices
- Self-monitoring Blood Glucose Devices
- Continuous Blood Glucose Monitoring
- Management Devices
- Insulin Pump
- Insulin Syringes
- Insulin Cartridges
- Disposable Pens
- Monitoring Devices
- Drugs
- Oral Anti-Diabetes Drugs
- Insulin Drugs
- Combination Drugs
- Non-Insulin Injectable Drugs
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure of the market and to pin down realistic demand anchors for Germany. We mainly used public health and reimbursement signals, then connected them to therapy patterns and device adoption topics that are specific to diabetes care.
Commonly referenced public sources include Germany health statistics and disease burden releases, such as Robert Koch Institute publications, OECD Health Statistics, WHO diabetes indicators, and European Commission and Eurostat health and trade tables when relevant. We also reviewed annual reports and investor presentations for relevant manufacturers and distributors, along with association pages and major medical congress summaries when they provided Germany specific context. For model hygiene checks, we selectively used paid subscriptions that provide company financial intelligence, news and financials, and patent databases to understand innovation and timing. The sources listed here are illustrative, and many other references were used for data collection, cross checks, and clarifying assumptions.
Primary Interviews and Surveys
Primary work focused on confirming what desk sources cannot fully show, including current therapy mix, switching patterns, device utilization behavior, and how reimbursement and tenders shape unit volumes. We spoke with a mix of clinical experts, diabetes educators, pharmacy and distribution stakeholders, and device focused channel participants across Germany to validate assumptions and align on realistic price and volume ranges.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 28% | CXOs: 14% |
| Mid tier: 53% | Functional/Unit leaders: 41% |
| Smaller Players: 19% | Managers: 45% |
Market-Sizing & Forecasting
The core model starts from a top-down demand pool built from Germany diabetes prevalence, treated share, and therapy split across insulin, oral anti-diabetics, non-insulin injectables, and combinations, then connected to average dosing or utilization norms. On the device side, units were reconstructed using user counts and replacement cycles for key categories such as SMBG and CGM, and for insulin delivery tools like pens, pumps, syringes, cartridges, and related consumables.
To keep the totals practical, we cross checked the outputs with selective bottom-up approximations using sampled average selling prices and volumes by channel, plus supplier and distributor level sense checks gathered in interviews. Inputs that mattered most included reimbursed uptake trends for CGM versus SMBG, pump penetration in applicable patient cohorts, typical testing frequency patterns, mix shifts toward newer drug classes, and price progression expectations under Germany pricing and reimbursement dynamics. Forecasts were built using scenario analysis, with the main scenario reflecting the most consistent expert view on adoption curves and price pressure, and alternative scenarios used to test faster or slower device penetration. Where smaller subcategories had sparse public signals, gaps were handled by using conservative replacement cycle assumptions and then revalidated through follow-up calls.
Data Validation & Update Cycle
Model outputs are checked against independent signals such as patient pool math, utilization logic by device type, and the implied per-patient spend trend over time. If a segment shows a sharp jump that cannot be explained by a change in prevalence, penetration, replacement, or price, the assumptions are reworked and experts are recontacted to confirm what changed.
Before sign-off, a second analyst reviews the calculations, units, currency conversions, and the consistency between historical years and forecast drivers. Reports are refreshed annually, and interim updates are triggered when material events occur, such as reimbursement rule changes, notable guideline updates, or major product transitions. Right before delivery, we run a fresh pass to ensure the view reflects the latest available public data and interview feedback.
Mordor Intelligence's Germany Diabetes Care Drugs and Devices Market Estimate Compared With Other Published Estimates
Published numbers for Germany diabetes care can appear far apart because authors do not always count the same basket, and they can apply different price points, timing, and growth assumptions. Another source may focus more on devices, or it may bundle broader diabetes related spending that is not directly tied to drugs and patient used monitoring and management tools.
Some estimates expand the market to include wider diabetes management and broader diagnostic and care spending, which pushes the value up. In this Mordor Intelligence estimate, the total is limited to diabetes drugs plus patient facing monitoring and management devices, and the sizing stays consistent by linking volumes to treated cohorts and replacement cycles before pricing is applied.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 6.06 B (2025) | |
| Trade Journal A | USD 21.51 B (2022) | Appears to use a broader diabetes market construct, which can fold in wider spending beyond the defined drugs and patient used monitoring and management devices, and it is also anchored to an earlier base year. |
| Industry Publisher B | USD 30.40 B (2028) | Uses a broader diabetes market framing and a more aggressive forward view, with limited visibility on how therapy mix, reimbursement driven price pressure, and device replacement cycles were constrained for Germany. |
The spread is mainly explained by what gets counted and how volumes are tied back to real user behavior in Germany. By keeping units connected to treated cohorts, adoption rates, and replacement timing, the estimate remains traceable and easier to reproduce, even when pricing and mix shift over the forecast period.
Key Questions Answered in the Report
What is the current market size?
The market is expected to increase from USD 5.62 billion in 2026 to USD 7.24 billion by 2032, with revenues reaching USD 5.86 billion in 2027 and growing at a CAGR of 4.33% during 2027-2032.
Who are the key players in market?
Medtronics, Roche, NovoNordisk, Sanofi and Omnipod are the major companies operating in the undefined.
What years does this market cover?
The report covers the historical market size for years: 2021, 2022, 2023, 2024, 2025, and 2026. The report also forecasts the undefined size for years: 2027, 2028, 2029, 2030, 2031, and 2032.