
Cryptographic Discovery and Inventory Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
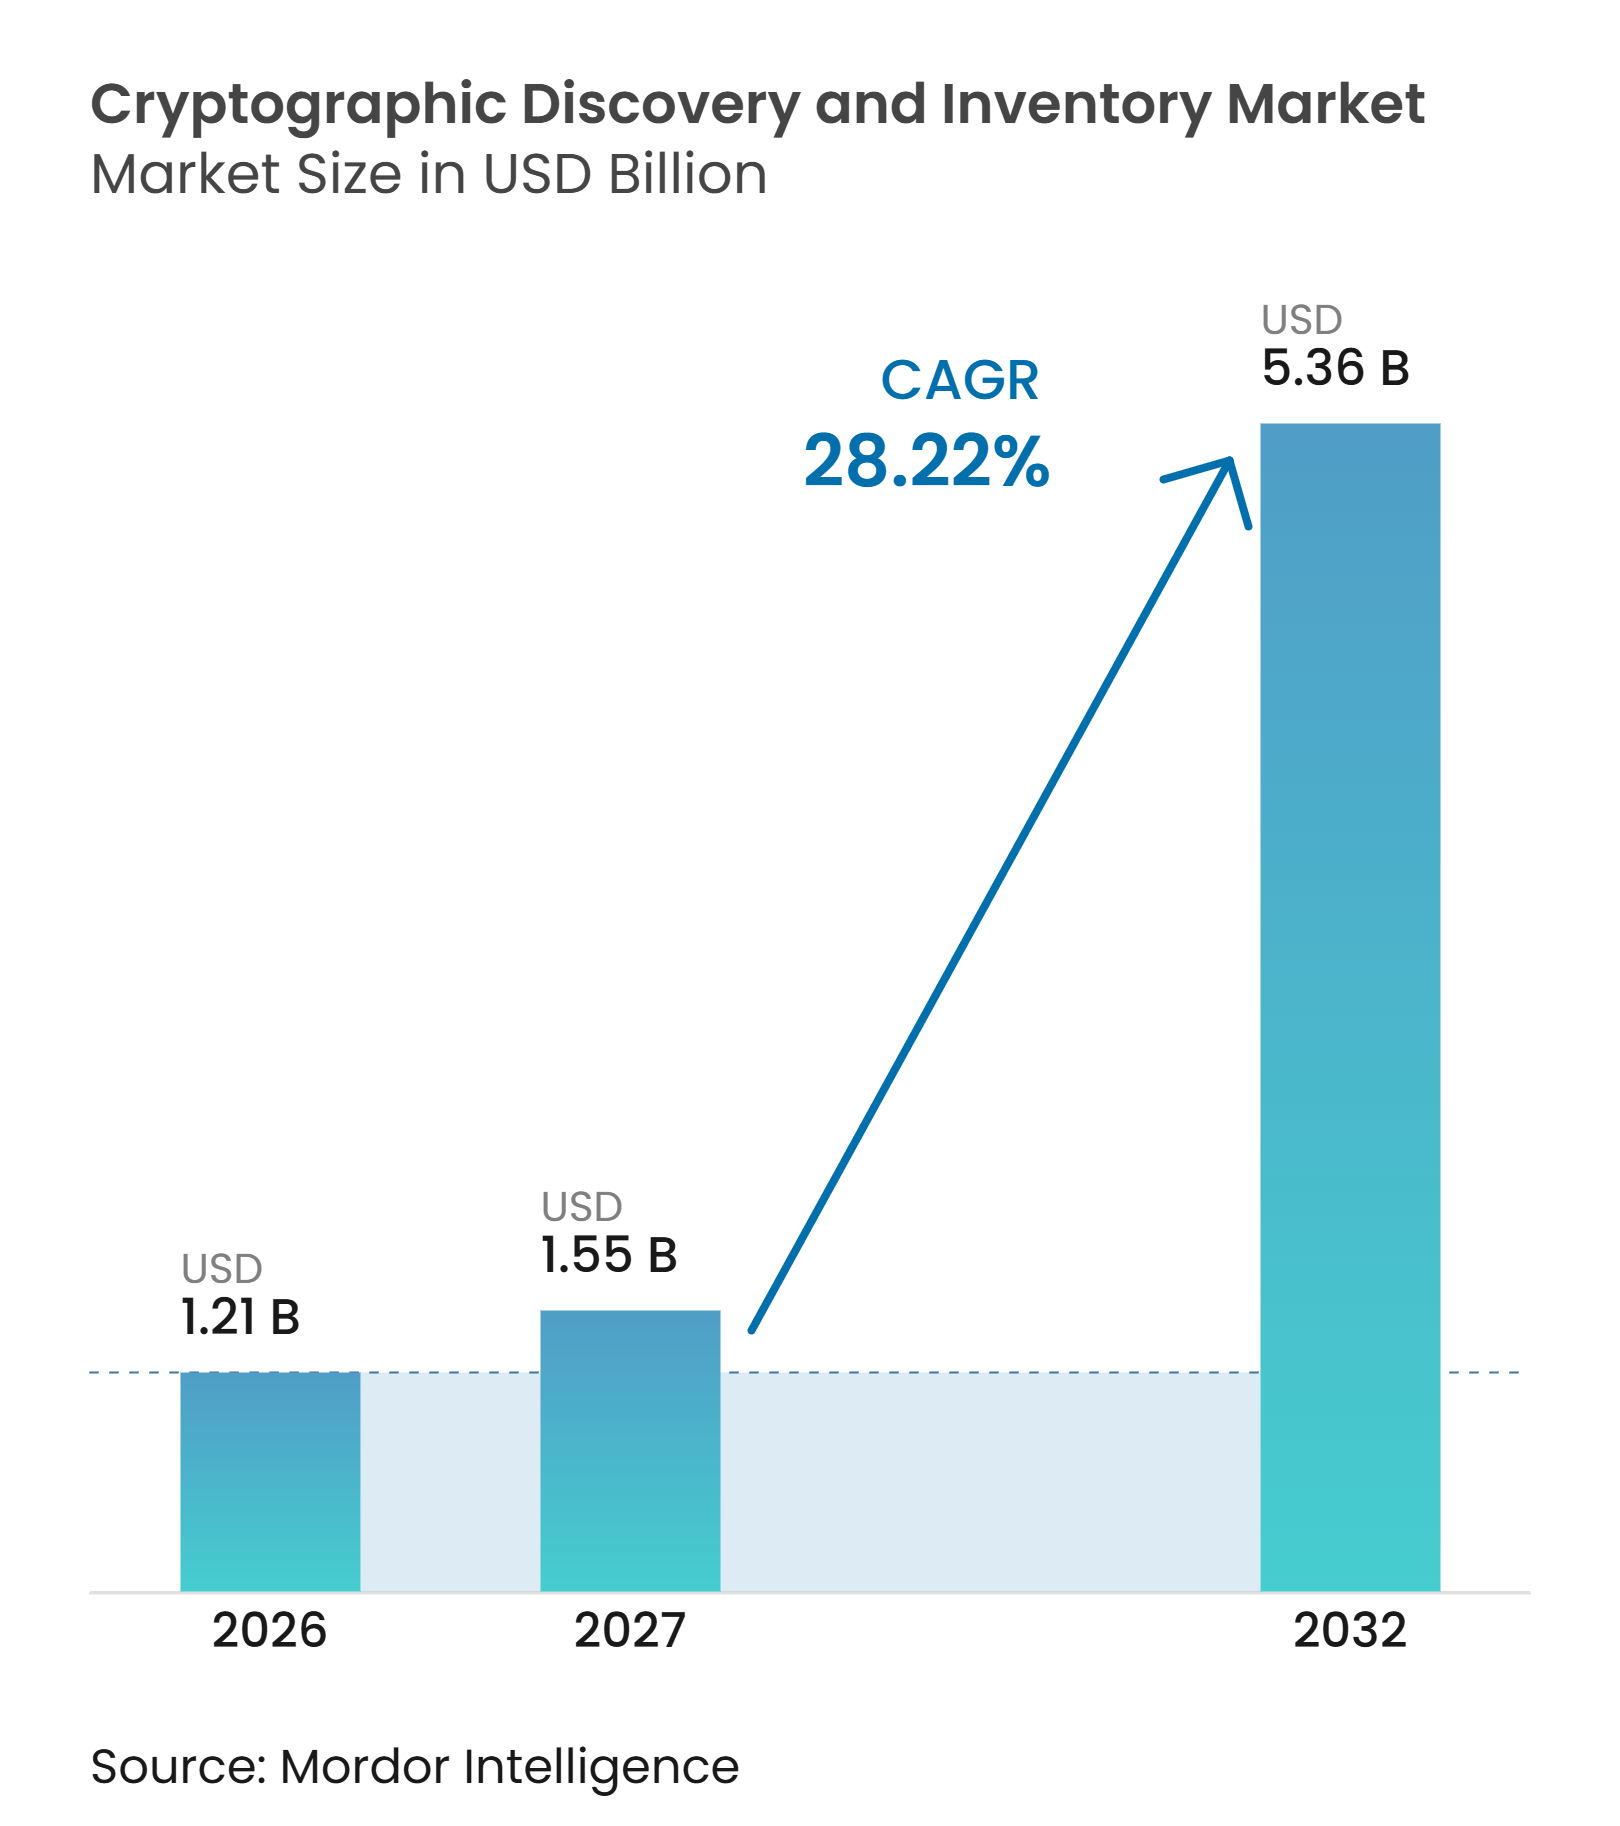
| Market Size (2027) | USD 1.55 Billion |
| Market Size (2032) | USD 5.36 Billion |
| Growth Rate (2027 - 2032) | 28.22 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Cryptographic Discovery and Inventory Market Analysis by Mordor Intelligence
The Cryptographic Discovery and Inventory Market size is projected to be USD 1.21 billion in 2026, USD 1.55 billion in 2027, and reach USD 5.36 billion by 2032, growing at a CAGR of 28.22% from 2027 to 2032. The Cryptographic Discovery and Inventory Market is being shaped more by mandatory post-quantum cryptography transition programs than by discretionary security spending. These programs make an accurate asset inventory necessary before an organization can plan a migration, which supports demand for continuous discovery tools. The Cryptographic Discovery and Inventory Market also benefits from the widening gap between policy deadlines and the time needed to update complex technology estates. Vendors are responding by combining code, network, and host-level visibility with certificate and machine-identity management capabilities. This creates opportunities for platforms that can reduce the work required to identify cryptographic assets across cloud, on-premises, and hybrid environments.
Key Report Takeaways
- By discovery method, static code analysis held 66.45% of the Cryptographic Discovery and Inventory Market revenue in 2026, while multi-method discovery is projected to expand at a 29.33% CAGR through 2032.
- By deployment model, on-premises deployment held 68.12% of the Cryptographic Discovery and Inventory Market revenue in 2026, while cloud deployment is projected to expand at a 29.72% CAGR through 2032.
- By organization size, large enterprises held 71.32% of the Cryptographic Discovery and Inventory Market revenue in 2026, while small and medium-sized enterprises are projected to expand at a 30.10% CAGR through 2032.
- By end user, BFSI held 29.41% of the Cryptographic Discovery and Inventory Market revenue in 2026, while government and public administration are projected to expand at a 28.76% CAGR through 2032.
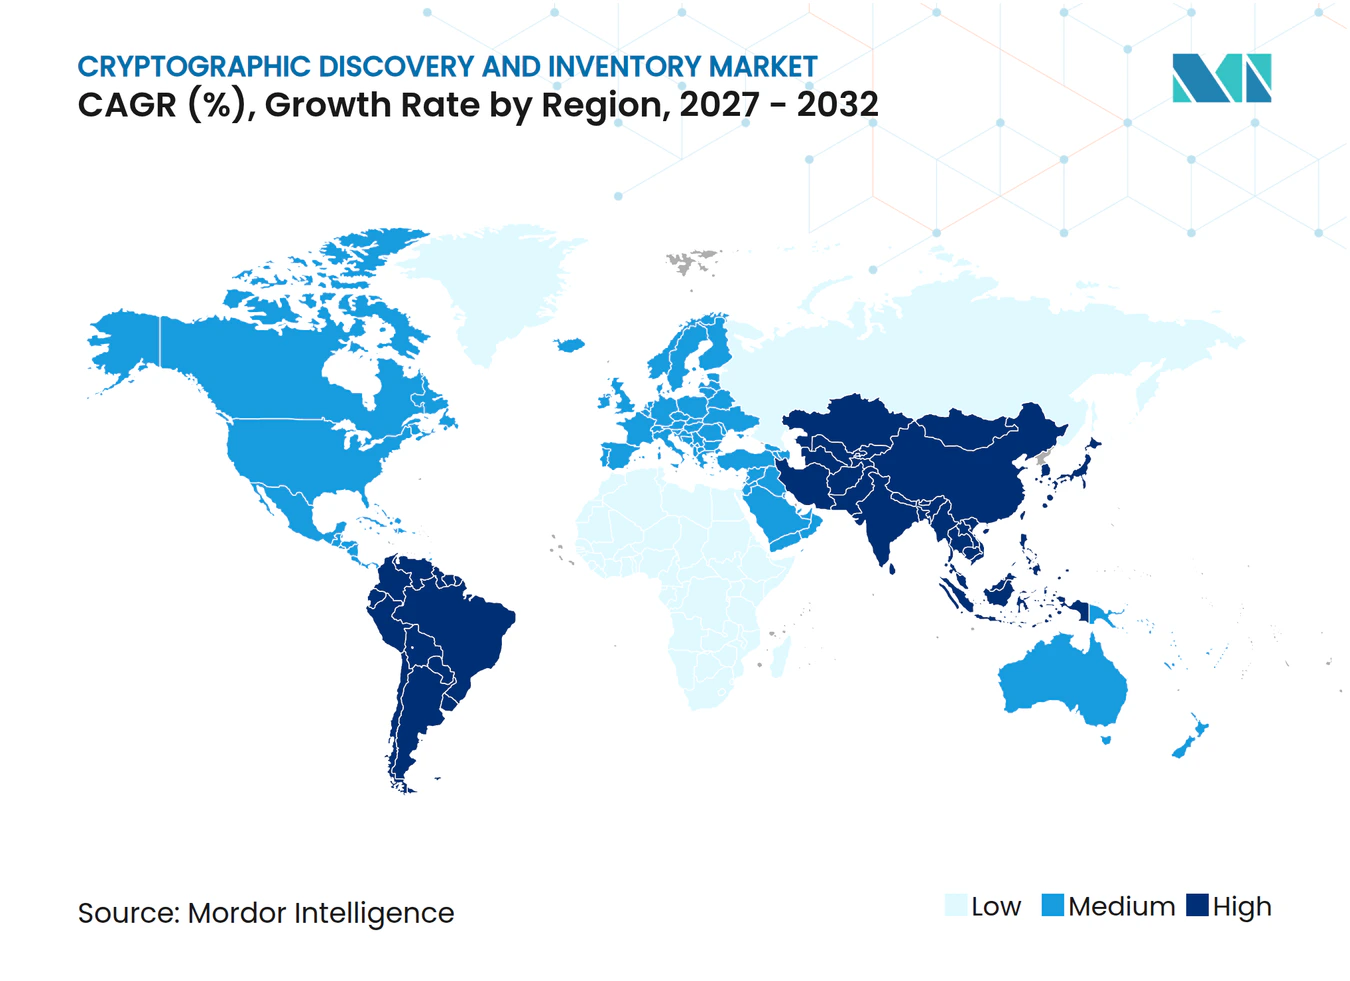
- By geography, North America held 35.39% of revenue in 2026, while Asia-Pacific is projected to expand at a 29.05% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Cryptographic Discovery and Inventory Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Post-Quantum Cryptography Inventory Mandates | +7.2% | Global, with binding obligations concentrated in the United States, EU member states, Australia, Singapore, and Japan | Short term (≤ 2 years) |
| NIST Algorithm Standardization and Migration Deadlines | +5.5% | Global, with earliest compliance pressure in North America and the EU, followed by Asia-Pacific national frameworks | Short term (≤ 2 years) |
| Harvest-Now, Decrypt-Later Risk Prioritization | +4.4% | Global, with high-risk exposure in North American defense, European financial infrastructure, and Asia-Pacific banking hubs | Medium term (2-4 years) |
| Cryptographic Sprawl Across Cloud, Containers, APIs, and Edge | +4.1% | Global, particularly hyperscaler-dependent enterprises in North America and cloud-growth markets across Asia-Pacific | Medium term (2-4 years) |
| Certificate and Machine-Identity Lifecycle Consolidation | +3.3% | North America and the EU, followed by Asia-Pacific as TLS lifespan requirements extend internationally | Medium term (2-4 years) |
| Continuous Cryptographic Bill of Materials Adoption | +3.0% | Global, with mandated reporting in U.S. federal procurement and EU supply-chain compliance frameworks | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Post-Quantum Cryptography Inventory Mandates
Post-quantum cryptography inventory mandates are the strongest driver of demand for the Cryptographic Discovery and Inventory Market. Executive Order 14412, issued in June 2026, requires U.S. federal agencies to name a PQC migration lead, manage an agency-wide cryptographic inventory, and submit migration plans within defined time frames. The EU Coordinated Implementation Roadmap requires member states to begin their PQC transitions by the end of 2026 and complete high-risk use cases by 2030. CISA also set out an automated discovery and inventory approach that calls for recurring cryptographic inventories by federal civilian agencies. These requirements establish recurring compliance work for the Cryptographic Discovery and Inventory Market. As contractors align with federal requirements, tools first bought for public-sector work can become part of wider enterprise security programs.
NIST Algorithm Standardization and Migration Deadlines
NIST published FIPS 203, FIPS 204, and FIPS 205 in August 2024 and selected HQC for standardization in March 2025, reducing uncertainty around which algorithms organizations should prepare to use. NIST IR 8547 proposes moving away from quantum-vulnerable public-key algorithms after 2030 and not allowing them after 2035. Its December 2025 guidance on cryptographic agility identifies discovery and inventory as preparatory work for organizations that need to change algorithms without disrupting systems. ANSSI stated in June 2026 that it will stop certifying or qualifying security products without PQC support from 2027. This supports earlier planning in the Cryptographic Discovery and Inventory Market. This procurement requirement underscores the importance of organizations that use ANSSI-qualified products understanding their cryptographic dependencies before the certification deadline.
Harvest-Now, Decrypt-Later Risk Prioritization
The harvest-now, decrypt-later threat turns a future quantum risk into a current security concern because encrypted traffic can be collected before a cryptographically relevant quantum computer is available. NIST IR 8547 places the possible arrival of such systems between 2030 and 2040, while noting substantial uncertainty. Research in Applied Sciences found that healthcare and financial services can face long exposure periods when they delay PQC adoption, while hybrid key exchange and forward-secure methods can reduce that exposure. A 2026 Cloud Security Alliance survey found that 75% of businesses were worried about this risk, but only 23% had a strategy to address it. Network monitoring becomes particularly important because code scans cannot show which encrypted traffic is active across live enterprise systems. This need strengthens demand in the Cryptographic Discovery and Inventory Market.
Cryptographic Sprawl Across Cloud, Containers, APIs, and Edge
Cryptographic sprawl is expanding as organizations use certificates, SSH keys, API keys, code-signing certificates, and cloud access tokens across more distributed systems. In 2025, Palo Alto Networks reported that machine identities outnumbered human identities by 82-to-1 in enterprise environments.[1] CyberArk reported that 42% of security leaders cited the lack of a machine-identity strategy as their main concern, while 34% still relied on manual certificate tracking. Short-lived container certificates are difficult to capture with static or agent-only approaches, which supports multi-method discovery in the Cryptographic Discovery and Inventory Market. CyberArk also noted that a planned 47-day public TLS certificate life by 2029 would require far more frequent certificate rotation than annual cycles.
Restraints Impact Analysis of Cryptographic Discovery and Inventory Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Unfunded Legacy Modernization Budgets | -2.0% | North America federal and state governments and EU legacy infrastructure operators | Short term (≤ 2 years) |
| Fragmented Ownership Across Security, Infrastructure, and Application Teams | -1.4% | Global, most pronounced in large enterprises and public-sector environments with siloed IT governance | Medium term (2-4 years) |
| Restricted Telemetry in Air-Gapped and Sensitive Environments | -1.1% | North American defense and national-security systems and selected EU government networks | Medium term (2-4 years) |
| Cryptography Skills Scarcity and Tool Qualification Cycles | -0.8% | Global, with the sharpest shortfall in Asia-Pacific emerging markets and mid-tier economies | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Unfunded Legacy Modernization Budgets
Legacy modernization budgets are an immediate constraint on deployment schedules in the Cryptographic Discovery and Inventory Market. The GAO reported that USD 82 billion of the USD 102 billion U.S. federal IT budget in fiscal 2024 went to operating and maintaining existing systems, leaving USD 20 billion for development and modernization. A 2025 Swimlane survey found that 85% of security teams had experienced budget or resource changes in the prior 6 months, and 46% reported lower planned security investment for 2025. Mandates preserve the need for discovery, but financial pressure can delay broad deployments and favor subscriptions over large on-premises purchases. This puts more focus on operating costs in the Cryptographic Discovery and Inventory Market. Vendors that can demonstrate rapid operational benefits and lower upfront infrastructure needs are better positioned in constrained accounts.
Fragmented Ownership Across Security, Infrastructure, and Application Teams
Fragmented ownership can slow discovery programs before scanning begins because security, infrastructure, and application teams may not share responsibility for cryptographic risk. Without a clear owner, algorithm inventories, certificate maps, and CBOM reports may not lead to an agreed-upon remediation plan. OMB M-26-15 requires agencies to designate PQC migration leads with authority over cryptographic inventory management. A 2025 paper from HSBC, InfoSec Global, and Thales described cross-functional cryptographic governance as necessary for moving from basic cryptography use to appropriate cryptography use. This governance challenge can slow decisions in the Cryptographic Discovery and Inventory Market. ISC2 found that 59% of respondents reported critical skills gaps in 2025, compared with 44% in 2024, which can add to project delays where ownership is already divided.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Cryptographic Discovery and Inventory Market Segment Analysis
By Discovery Method:
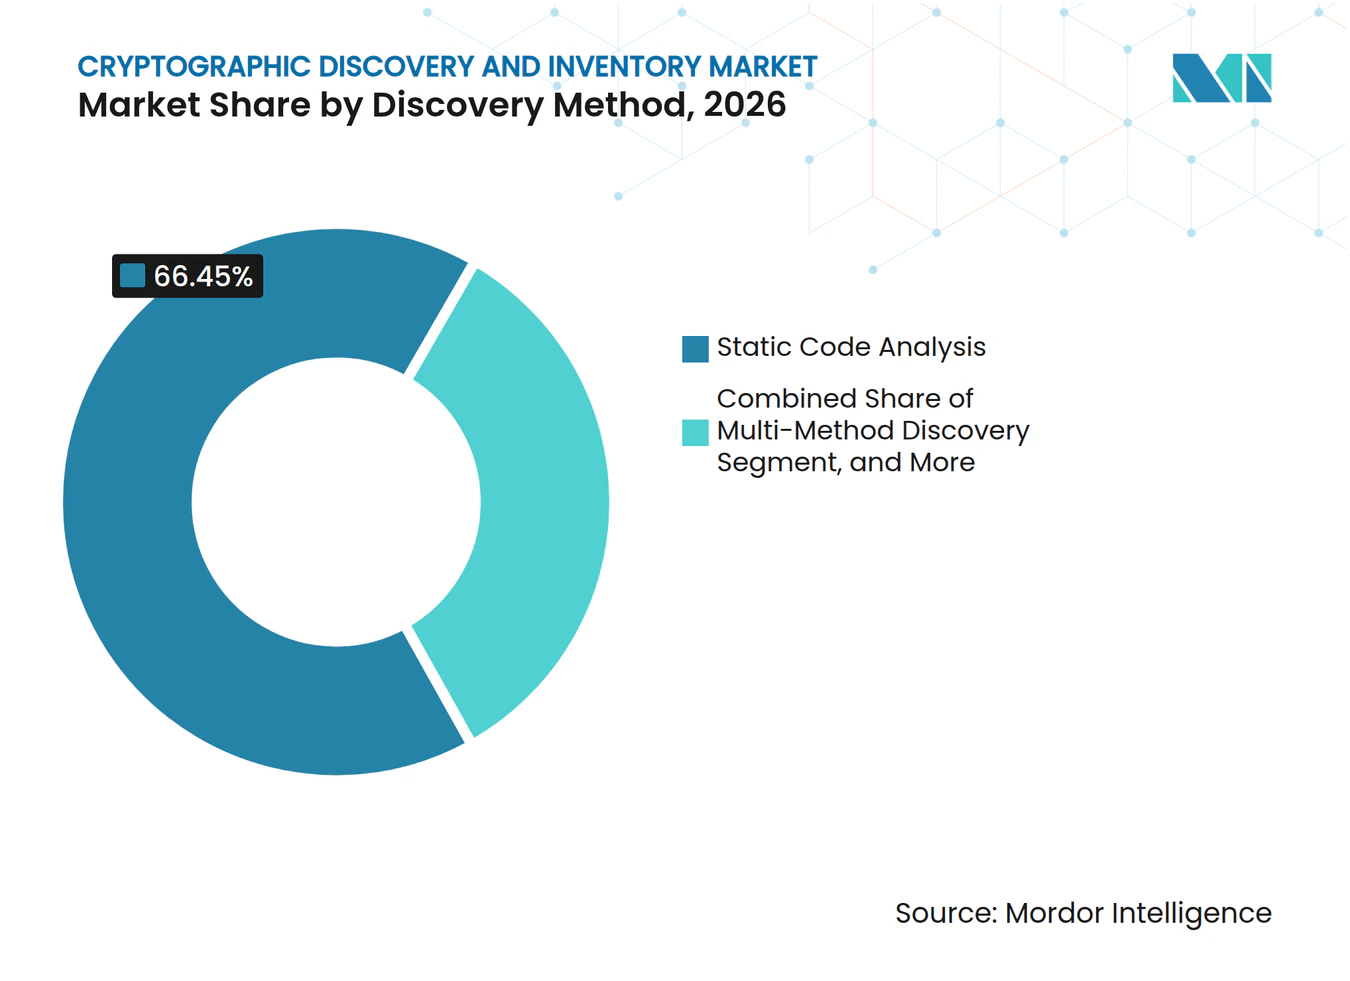
Multi-Method Approaches Improve Scanning CoverageStatic code analysis held 66.45% of the Cryptographic Discovery and Inventory Market share in 2026. Within the Cryptographic Discovery and Inventory Market, it is established in software development workflows because it can scan source code, repositories, build artifacts, and application packages. This method helps teams identify embedded algorithms, outdated ciphers, and cryptographic libraries before software reaches production. Passive network monitoring provides a different view by capturing cipher suite negotiations, TLS handshake parameters, and protocol use in live traffic. It is important to find shadow cryptographic assets that do not appear in source code.
Multi-method discovery is projected to grow at a 29.33% CAGR from 2027 to 2032. The Cryptographic Discovery and Inventory Market size for this approach is supported by the limits of any single scanning method in cloud-native environments. Agent-based host scanning can identify operating-system cryptographic calls and runtime library loading, which is useful for binary and proprietary software. CycloneDX version 1.6 standardized the CBOM schema, and providers such as QuSecure and AppViewX use multi-source inventories to produce machine-readable CBOMs. TNO found in March 2025 that only 1 specialist provider it assessed could detect PQC algorithms, leaving room for broader algorithm-aware coverage.



By Deployment Model:
Cloud Delivery Gains Ground as Software-as-a-Service Adoption RisesOn-premises deployment held 68.12% of revenue in 2026. Within the Cryptographic Discovery and Inventory Market, government, defense, and financial organizations often retain this model because data residency requirements, FedRAMP thresholds, and air-gapped environments restrict cloud-hosted scan telemetry. The installed base also reflects the early design of dedicated discovery products for enterprise-owned infrastructure. Large organizations can have replacement cycles that extend for years, thereby supporting the continued use of established on-premises systems. Keyfactor introduced AgileSec as a software-as-a-service offering in March 2026 to lower infrastructure complexity and improve time to value.
Cloud deployment is projected to grow at a 29.72% CAGR from 2027 to 2032. The Cryptographic Discovery and Inventory Market can reach organizations with cloud-native workloads and limited capacity to manage their own scanning infrastructure through this delivery model. Consumption-based pricing can lower total ownership costs compared with conventional on-premises license structures. SandboxAQ achieved FedRAMP Ready status for AQtive Guard in 2025, establishing a clear path for federal civilian agencies to assess cloud-delivered discovery services. TNO noted that full-stack commercial tools can cost large organizations significant amounts per year, making per-asset cloud offerings more accessible below the largest enterprise tier.
By Organization Size:
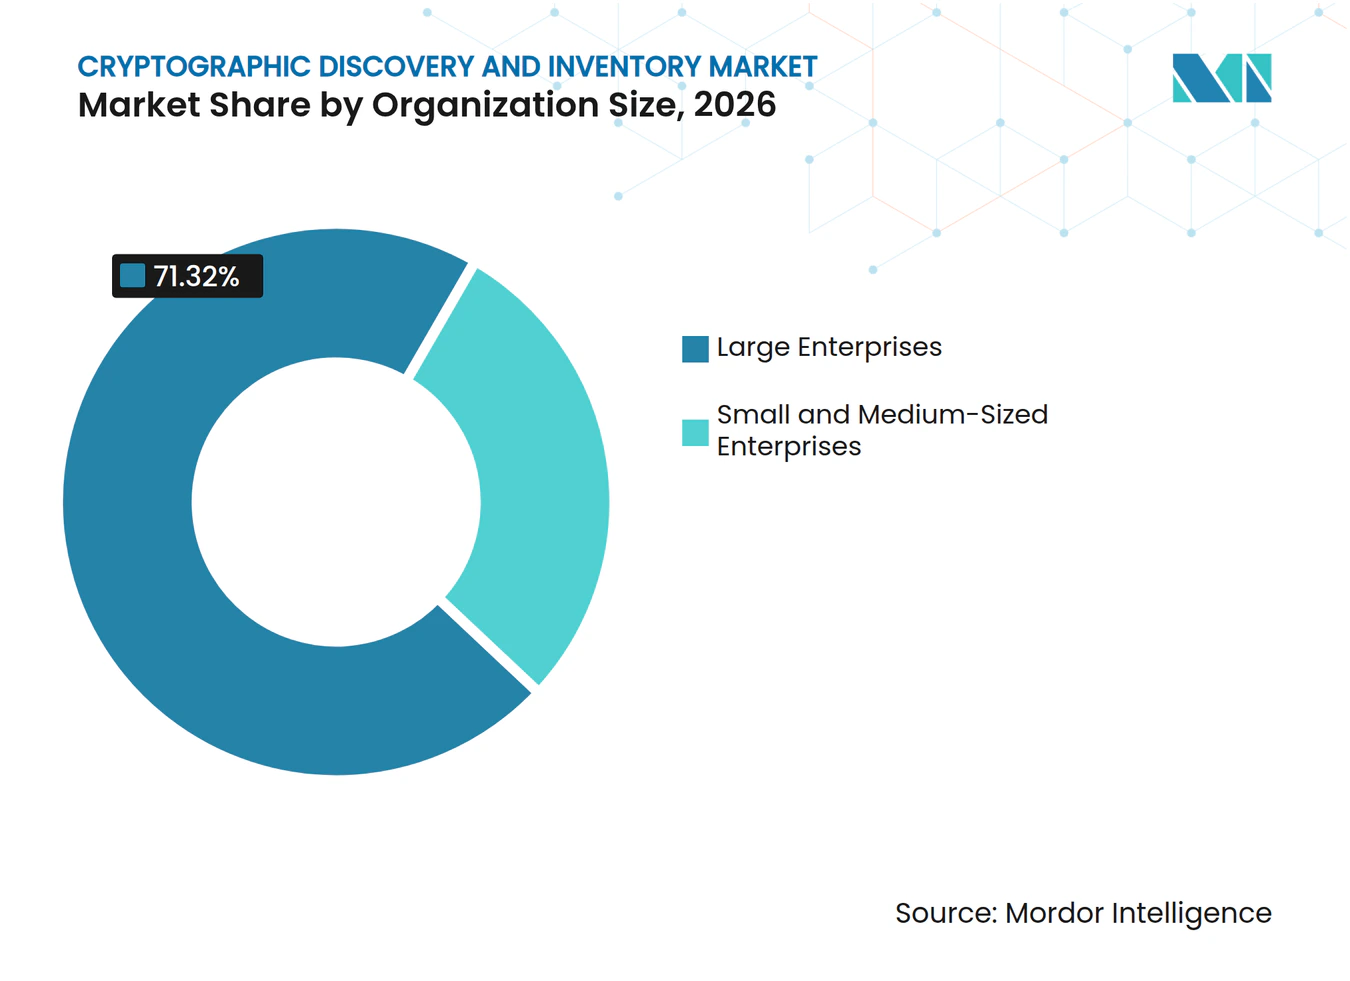
Small and Medium-Sized Enterprises Become a Distinct Source of DemandLarge enterprises held 71.32% of revenue in 2026. Their scale, early regulatory exposure, and long-standing cryptographic estates make them the established buyers in the Cryptographic Discovery and Inventory Market. These organizations may manage thousands of certificates, many cryptographic libraries, and hybrid cloud systems across several business units. Even enterprises with mature certificate management can lack visibility into algorithm dependencies inside applications. This gap provides vendors with opportunities to extend deployments within existing customer accounts.
Small and medium-sized enterprises are projected to grow at a 30.10% CAGR from 2027 to 2032. The Cryptographic Discovery and Inventory Market industry is becoming more accessible to these organizations as cloud tools reduce implementation requirements. An MDPI Computers study estimated that it would take 5 to 7 years for small enterprises to complete PQC migration under optimistic assumptions. QuSecure offers its QuProtect Reconnaissance module without charge to qualifying organizations, which can reduce the initial barrier to discovery.[2] The NIS2 framework introduces financial exposure for covered smaller European organizations that cannot demonstrate state-of-the-art cryptographic controls.

By End User:
Government Demand Accelerates While BFSI Retains a Large Installed BaseBFSI held 29.41% of revenue in 2026. Its large position reflects long-term use of digital certificates for transaction authentication, settlement systems, and cross-border payments. Financial records can remain confidential for decades, which makes harvested encrypted data a clear operational and credit risk. The Bank for International Settlements urged financial institutions to begin PQC migration in July 2025. Project Leap Phase 2 tested PQC-signed transfers in the TARGET2 system during 2025 and identified packet-size and performance issues that reinforce the need for a detailed inventory before migration.
Government and public administration are projected to grow at a 28.76% CAGR from 2027 to 2032. The Cryptographic Discovery and Inventory Market industry is supported in this segment by agency-wide procurement programs and fixed policy deadlines. SandboxAQ signed a 5-year agreement with the U.S. Department of War's Chief Information Officer in December 2025 for automated discovery and inventory across department systems. IT and telecommunications also face pressure because 5G infrastructure can remain in use beyond the anticipated quantum-risk window. Healthcare, manufacturing, energy, utilities, automotive, and mobility users add demand with different data, continuity, and certification requirements.
Geography Analysis
North America Cryptographic Discovery and Inventory Market
North America held 35.39% of the Cryptographic Discovery and Inventory Market share in 2026. Executive Order 14412 requires federal inventory reviews of high-value assets, while NSA CNSA 2.0 stopped approving RSA, DH, and ECC for new National Security Systems acquisitions as of 2025.[3] Canada set separate migration plans and high-priority system deadlines in its June 2025 roadmap, broadening regional demand beyond U.S. federal agencies. The U.S. Department of Health and Human Services also sought information on FedRAMP High-certified discovery tools in 2026, indicating growing interest in healthcare.
Europe Cryptographic Discovery and Inventory Market
Europe is the second-largest regional market. Its coordinated roadmap provides a common transition timeline across member states rather than separate agency-led programs. ANSSI stated that PQC-ready support would become a certification requirement starting in 2027, increasing the urgency for organizations that use qualified products. Spain issued CCN-TEC 009 and BP-37 in July 2026, with inventory deliverables due by December 31, 2026, while Campus Cyber published a 2026 overview of PQC migration tools that describes inventory as the first phase of migration planning.
South America, APAC and MEA Cryptographic Discovery and Inventory Market
Asia-Pacific is projected to grow at a 29.05% CAGR from 2027 to 2032. The Cryptographic Discovery and Inventory Market is supported by national transition programs across the region. Australia requires designated support for ML-KEM-1024 and ML-DSA-87 in new cryptographic equipment and applications by 2030, supported by a PQC transition plan deadline at the end of 2026. Singapore issued guidance for critical infrastructure with a 2031 migration milestone and recommends discovering crown-jewel systems before broader inventory work. South Korea selected 4 domestic KpqC algorithms in January 2025 for phased government deployment, while NEC and Daiwa Securities Group completed a financial-services PQC proof of concept in Japan in March 2026. South America, the Middle East, and Africa remain early-stage regions, where multinational financial institutions and Arqit’s September 2026 demonstration with Es’hailSat in Qatar are creating initial demand for critical infrastructure.
Competitive Landscape
Market Concentration
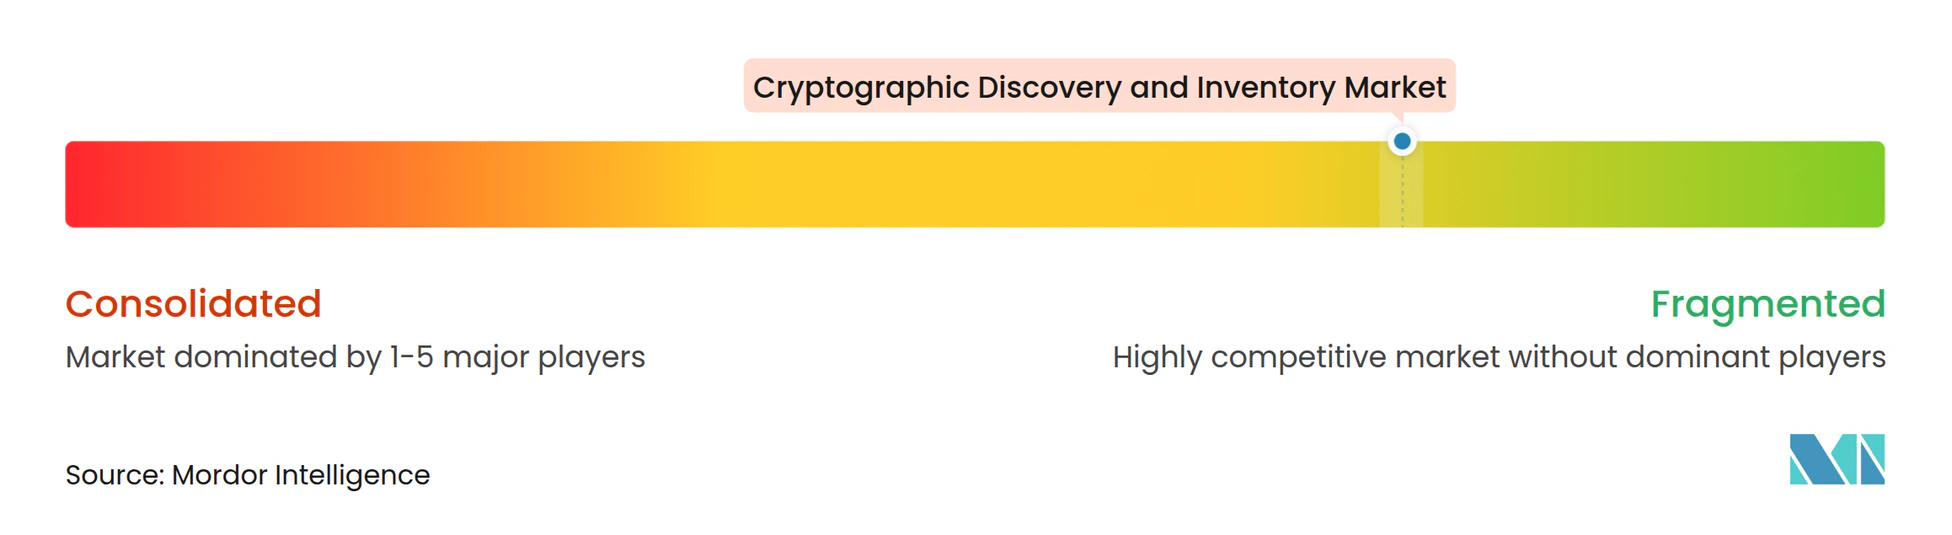
The Cryptographic Discovery and Inventory Market is moderately fragmented. Specialist automated cryptographic discovery and inventory platforms compete with broader security providers that extend certificate lifecycle management, secrets management, or HSM portfolios with discovery capabilities. SandboxAQ uses runtime analysis, network telemetry, and runtime tracing to identify dynamically loaded libraries and shadow cryptographic instances. Keyfactor combines host scanning, network monitoring, and certificate lifecycle functions in its AgileSec Analytics workflow. Summit Partners led a USD 1 billion+ strategic growth investment in Keyfactor in July 2026 to support product innovation, geographic expansion, and acquisitions.
AppViewX Quantum Trust Hub, CryptoNext Security COMPASS, and QuSecure QuProtect Reconnaissance focus on CBOM output and developer-facing integration. These capabilities support government submissions and fit existing CI/CD processes. Arqit acquired Ampliphae’s encryption intelligence analytics business, while Keyfactor acquired InfoSec Global, demonstrating how acquisitions can fill product coverage gaps. TNO found that none of the specialist tools it assessed in March 2025 were active in operational technology environments, and only 1 could detect PQC algorithms, leaving industrial and critical-infrastructure users with limited specialist coverage.
Managed services are becoming a viable option for customers without in-house cryptographic expertise. NTT DATA and Fortanix announced a global Cryptography-as-a-Service partnership in October 2025, combining Fortanix’s Data Security Manager with NTT DATA’s cybersecurity delivery capability.[4] Utimaco announced that its ML-KEM and ML-DSA implementations passed NIST CAVP testing in October 2025, providing a validated HSM foundation for partner integrations. Akeyless also achieved FIPS 140-3 validation in 2025, supporting its position in secrets management and non-human identity discovery. These moves show that the Cryptographic Discovery and Inventory Market is competing by integrating managed delivery and validated cryptographic capabilities, rather than relying on standalone asset discovery.
Cryptographic Discovery and Inventory Industry Leaders
-
Keyfactor, Inc.
-
CryptoNext Security SAS
-
QuSecure, Inc.
-
SandboxAQ, Inc.
-
PQShield Ltd.
- *Disclaimer: Major Players sorted in no particular order
Cryptographic Discovery and Inventory Market Companies Covered in this Report
- Keyfactor, Inc.
- CryptoNext Security SAS
- InfoSec Global Inc.
- ISARA Corporation
- Qrypt, Inc.
- QuSecure, Inc.
- SandboxAQ, Inc.
- PQShield Ltd.
- Arqit Quantum Inc.
- Fortanix, Inc.
- EverTrust SAS
- Crypto4A Technologies Inc.
- Utimaco GmbH
- Futurex, L.P.
- Akeyless Security Ltd.
- AppViewX, Inc.
- Prime Factors, Inc.
- SafeLogic Inc.
- Qubrisk Ltd.
- Tychon, Inc.
Recent Industry Developments in Cryptographic Discovery and Inventory Market
- September 2026: QuSecure's QuProtect R3 achieved Technical Readiness Level 7 at Project Convergence Capstone 6, demonstrating quantum-resistant communications, cryptographic agility, and cryptographic discovery and inventory for U.S. Army tactical mission systems operating under Executive Order 14412 deadlines of 2030 and 2031.
- September 2026: Arqit Quantum, Es'hailSat, and Advanced International Electronic Equipment Company successfully demonstrated quantum-safe satellite security across the operational communications infrastructure in Qatar, establishing a reference deployment for critical infrastructure operators across the Middle East and Africa.
- September 2026: Utimaco and 01 Quantum formalized a global Post-Quantum Cryptography Technology Alliance, combining 01 Quantum's PQC software and cryptographic discovery capabilities with Utimaco's HSM and key management infrastructure to support government and enterprise PQC migration programs.
- September 2026: Prime Factors integrated EncryptRIGHT with the Entrust nShield 5c HSM to deliver a FIPS 140-3 certified, quantum-ready, crypto-agile data protection platform, enabling enterprises to enforce encryption, tokenization, and digital signing policies from a single console across applications, databases, and cloud environments.
Global Cryptographic Discovery and Inventory Market Report Scope
The Cryptographic Discovery and Inventory Market comprises revenues generated from software platforms and associated services that identify, inventory, classify, monitor, and analyze cryptographic assets, certificates, keys, algorithms, machine identities, cryptographic libraries, and dependencies across enterprise environments. These solutions provide organizations with visibility into cryptographic usage, support cryptographic risk assessment, enable cryptographic bill of materials (CBOM) generation, facilitate post-quantum migration planning, and help ensure regulatory compliance. The market supports continuous discovery and inventory of cryptographic assets across applications, cloud environments, networks, endpoints, containers, and hybrid infrastructures.
The Cryptographic Discovery and Inventory Market Report is Segmented by Discovery Method (Static Code Analysis, Passive Network Monitoring, Agent-Based Host Scanning, Multi-Method Discovery, and Other Discovery Methods), Deployment Model (On-Premises, and Cloud), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), End User (Government and Public Administration, Banking, Financial Services, and Insurance [BFSI], IT and Telecommunication, Healthcare and Life Sciences, Industrial Manufacturing, Energy and Utilities, Automotive and Mobility, and Other End Users), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Static Code Analysis |
| Passive Network Monitoring |
| Agent-Based Host Scanning |
| Multi-Method Discovery |
| Other Discovery Methods |
| On-Premises |
| Cloud |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| Government and Public Administration |
| Banking, Financial Services, and Insurance (BFSI) |
| IT and Telecommunication |
| Healthcare and Life Sciences |
| Industrial Manufacturing |
| Energy and Utilities |
| Automotive and Mobility |
| Other End Users |
| North America | United States |
| Canada | |
| South America | Brazil |
| Argentina | |
| Mexico | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Discovery Method | Static Code Analysis | |
| Passive Network Monitoring | ||
| Agent-Based Host Scanning | ||
| Multi-Method Discovery | ||
| Other Discovery Methods | ||
| By Deployment Model | On-Premises | |
| Cloud | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By End User | Government and Public Administration | |
| Banking, Financial Services, and Insurance (BFSI) | ||
| IT and Telecommunication | ||
| Healthcare and Life Sciences | ||
| Industrial Manufacturing | ||
| Energy and Utilities | ||
| Automotive and Mobility | ||
| Other End Users | ||
| By Geography | North America | United States |
| Canada | ||
| South America | Brazil | |
| Argentina | ||
| Mexico | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the Cryptographic Discovery and Inventory Market?
The sector is projected at USD 1.21 billion in 2026 and USD 5.36 billion by 2032, with a 28.22% CAGR from 2027 to 2032.
Why are organizations buying cryptographic discovery tools?
PQC transition requirements make a complete inventory of algorithms, keys, certificates, and cryptographic libraries necessary before migration work can proceed.
Which discovery approach is growing fastest?
Multi-method discovery is projected to grow at a 29.33% CAGR through 2032 because code, network, and host scanning address different visibility gaps.
Why is cloud delivery gaining acceptance?
Cloud deployment is projected to grow at a 29.72% CAGR through 2032 as it can lower infrastructure requirements and improve access for cloud-native organizations.
Which customer group is expanding fastest?
Small and medium-sized enterprises are projected to expand at a 30.10% CAGR through 2032 as cloud-delivered tools lower the entry barrier.
Which region is projected to grow fastest?
Asia-Pacific is projected to grow at a 29.05% CAGR through 2032, supported by transition programs in Australia, Singapore, South Korea, and Japan.