
China E-commerce Market Analysis by Mordor Intelligence
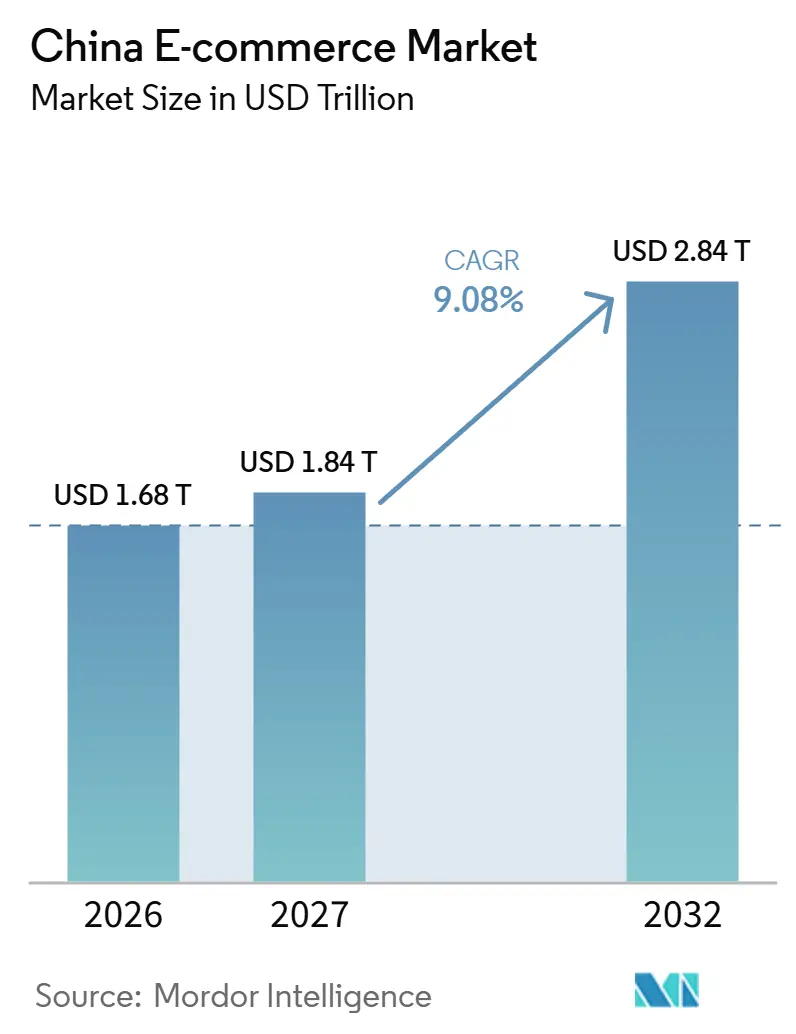
The China e-commerce market size is estimated at USD 1.68 trillion in 2026 and is projected to be USD 1.84 trillion in 2027, reaching USD 2.84 trillion by 2032, growing at a CAGR of 9.08% from 2027 to 2032.
China's growth opportunity rests on deeper purchasing activity within an established online audience, especially for fresh grocery served through instant retail formats. Merchant tools and integrated mobile workflows can broaden participation and support more of each shopping transaction. Competition therefore links product discovery with fulfillment, as physical retail networks provide another route to differentiated customer service. Privacy duties and merchant protections limit monetization choices, making clear terms and reliable execution central to the commercial value of that wider reach.
Key Report Takeaways
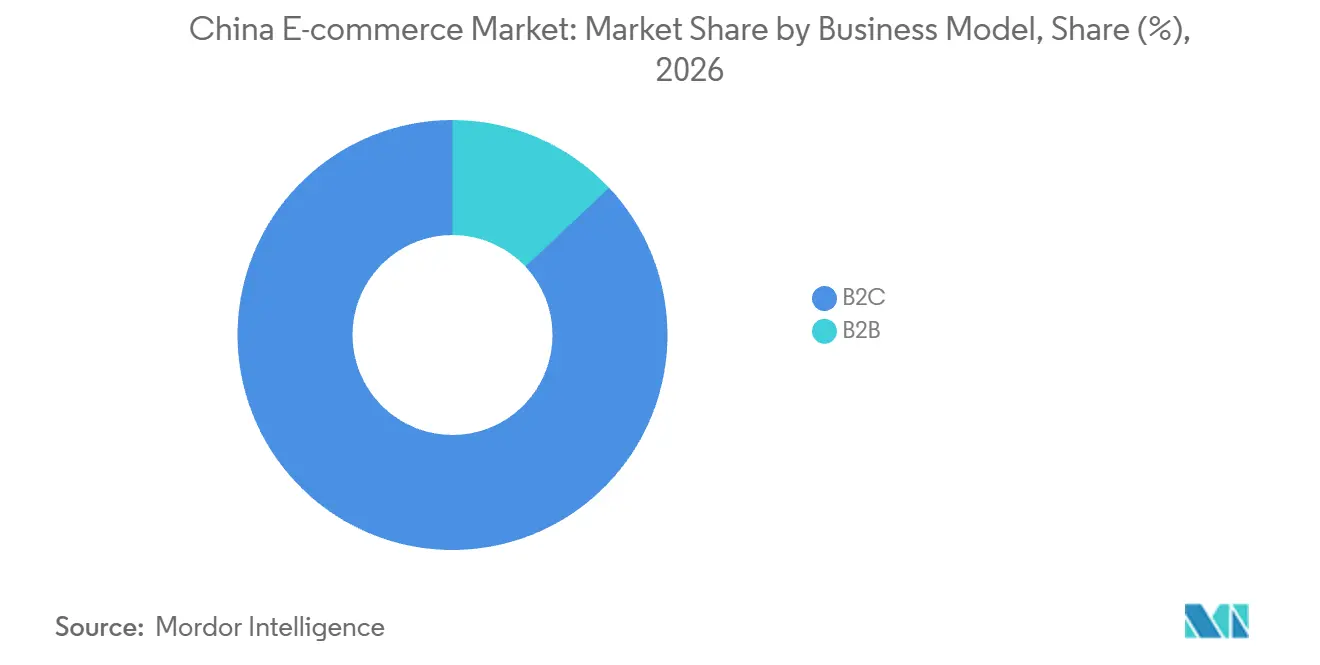
- By business model, B2C held an 87.01% China e-commerce market share in 2026, while B2B is forecast to grow fastest at a CAGR of 11.02% from 2027 to 2032.
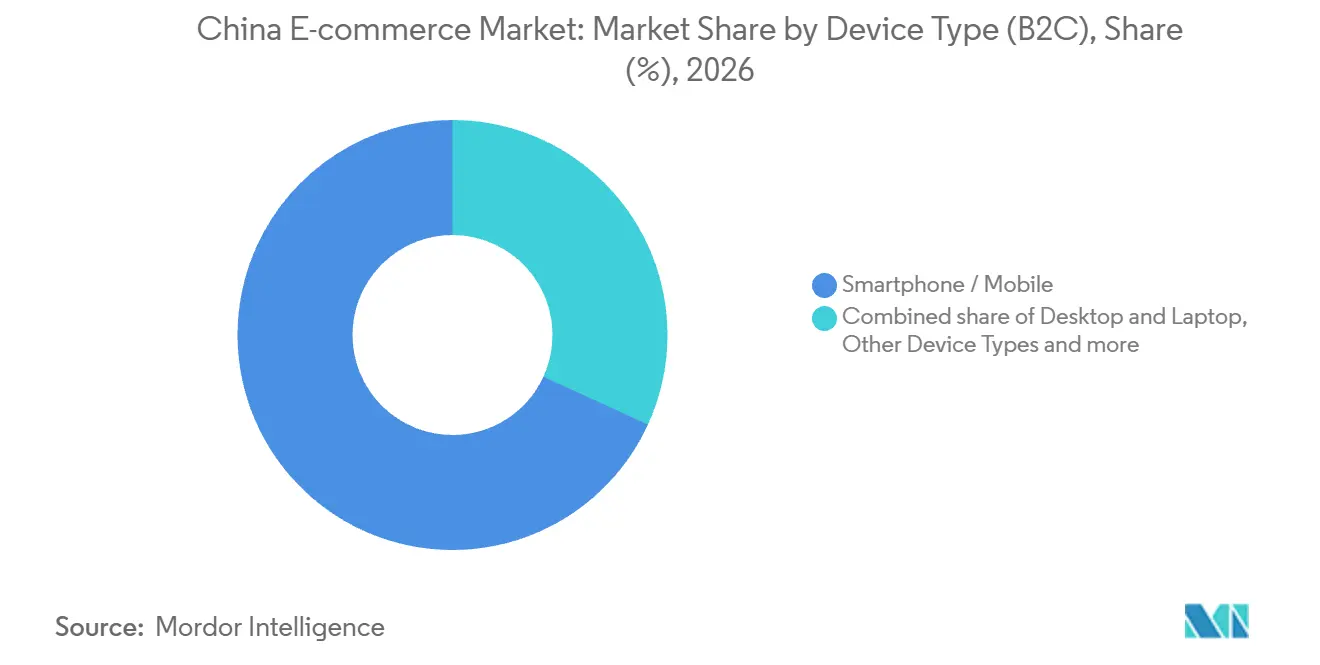
- Across device types, smartphone/mobile led with a 68.16% share in 2026 and is projected to grow fastest at a 9.76% CAGR from 2027 to 2032.
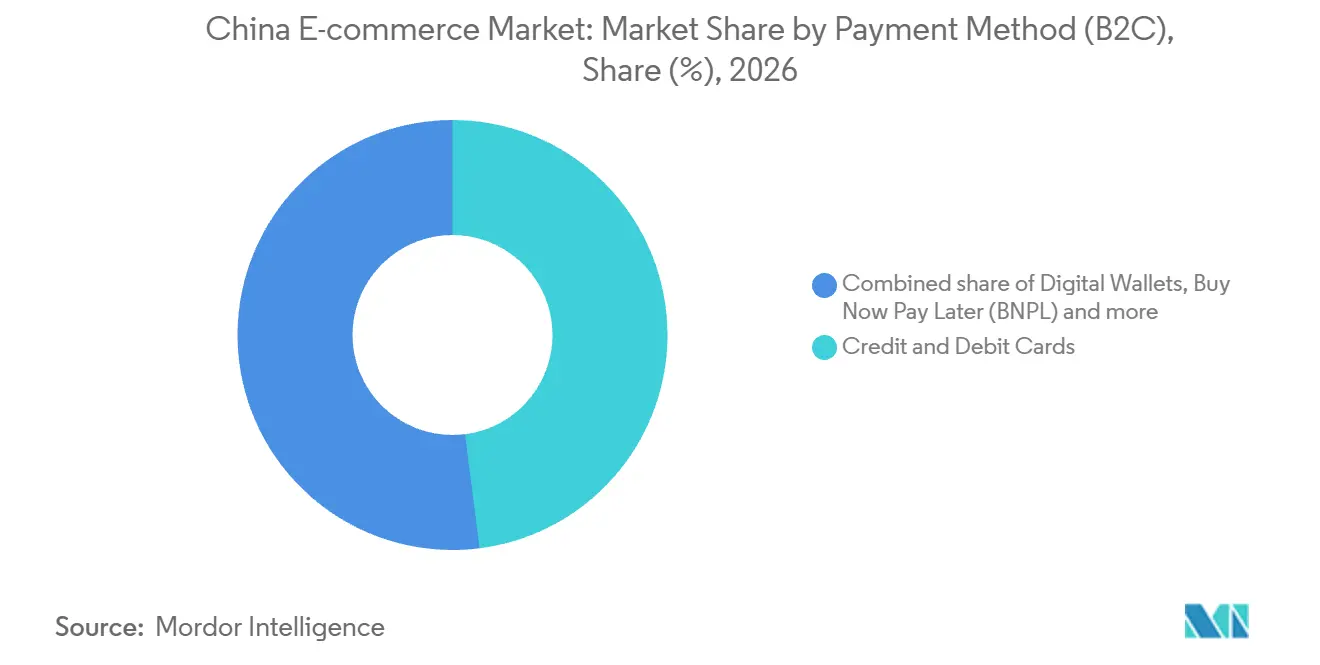
- Payment methods were led by credit and debit cards with a 47.99% share in 2026, while digital wallets are projected to grow fastest at a 12.2% CAGR from 2027 to 2032.
- Within product categories, consumer electronics accounted for a 21.58% share of the China e-commerce market size in 2026, and food and beverages are forecast to grow fastest at an 11.45% CAGR from 2027 to 2032.
- Geographically, East China led in 2025, supported by established online demand in Jiangsu, Zhejiang, and Shanghai.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of China E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Livestream commerce expansion in lower-tier cities | +3.2% | County-based industrial belts nationwide | Medium term (2-4 years) |
| Same-day logistics unlocking FMCG and fresh grocery online | +3.5% | Cities across China | Short term (≤ 2 years) |
| Private-traffic WeChat mini-program enablement for SMEs | +2.2% | Nationwide | Medium term (2-4 years) |
| Cross-border duty exemption boosting imported cosmetics | +1.5% | Nationwide | Short term (≤ 2 years) |
| AI-driven personalized sizing solutions reducing returns | +0.7% | Nationwide | Medium term (2-4 years) |
| Renewable-energy powered data-centers enhancing ESG appeal | +0.3% | Guangdong, Jiangsu, Sichuan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Livestream commerce expansion in lower-tier cities
Lower-tier city merchants can use the real-time presentation format of livestream commerce to make products understandable during the selling encounter. For goods whose appeal depends on fit, appearance, or demonstrated use, that format can address a purchase question before an order is placed. A seller with a narrow assortment can focus the session on a small set of product decisions, giving presentation quality a direct commercial role. The resulting opportunity depends on linking interest to ordering and fulfillment, because audience reach alone does not create a completed sale. Platform growth from this channel therefore rests on helping merchants turn a geographically dispersed viewing audience into transactions that can actually be served.
Same-day logistics unlocking FMCG and fresh grocery online
For fresh-food sellers, delivery speed determines which immediate consumption occasions an online channel can realistically serve. Meituan launched Flash Purchase across China on April 15, 2025, with a reported average delivery time of 30 minutes after ordering.[1] Vegetables and fruit were among its offered categories, connecting rapid fulfillment directly with perishable household purchases. Separately, Meituan's Xiaoxiang Supermarket expanded to 68 operating cities in Q2 2026, extending the geographic footprint of its grocery-retail business. These developments make neighborhood service coverage a meaningful limit on addressable demand, since the commercial promise depends on reaching a buyer's location within a useful shopping interval.
Private-traffic WeChat mini-program enablement for SMEs
Small merchants gain a more practical route into online selling when store-building tools connect with an established commerce environment. In the first half of 2025, Weimob's WIME artificial intelligence (AI) store-building tool served small and micro e-commerce operators and joined the WeChat Mini Store Service Market. A separate Weimob integration linked WeChat Mini Shop with Mini Programs. Among merchants enabling that feature, average month-on-month growth in monthly orders was 27% during the first half of 2025. Monthly membership in that same cohort grew 26% on an average month-on-month basis during the period. The commercial mechanism is additional merchant capacity to operate connected storefronts, extending the transaction opportunity through the tools available within WeChat's commerce environment.
Cross-border duty exemption boosting imported cosmetics
Imported cosmetics gain a price-based route to Chinese consumers when transactions qualify for preferential cross-border retail import taxation. Under the policy effective January 1, 2019, qualifying imports within prescribed limits receive a 0% tariff, while VAT and consumption tax are charged at 70% of statutory amounts. The list adjusted effective March 1, 2022, includes lipstick, eye makeup, nail cosmetics, powder, and skin-care products. Prohibited-import exclusions and wildlife documentation conditions restrict eligibility for specified goods. A qualifying single item above the transaction limit but below the annual cap is fully taxed, while exceeding that cap triggers general-trade management. These conditions make tariff classification and transaction design central to whether an imported beauty assortment can sustain its price advantage.
Restraints Impact Analysis of China E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-privacy and antitrust regulations curbing monetization | -1% | Nationwide | Short term (≤ 2 years) |
| Weak IP enforcement deterring luxury brand presence | -0.7% | Nationwide | Long term (≥ 4 years) |
| Mobile-internet user saturation in tier-1 cities | -0.5% | Nationwide | Medium term (2-4 years) |
| Cross-border carbon tariffs inflating shipping costs | -0.2% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Data-privacy and antitrust regulations curbing monetization
Platform monetization faces limits where revenue depends on individualized marketing or the fees charged to participating merchants. Article 24 of China's Personal Information Protection Law, effective November 1, 2021, requires personal-information processors using automated commercial marketing to offer a non-personalized option or convenient refusal. The State Administration for Market Regulation's February 2026 nonbinding guidance flags dominant-platform fees far above comparable services under similar conditions, or above-normal increases when costs are broadly stable, as antitrust risks. Commercial reach therefore cannot automatically be treated as permission to personalize every message or increase every merchant fee. In FY2026, more than 41 million users accessed Taobao's privacy module, which allows consent changes for permissions, advertisements, and recommendations. Compliance becomes a recurring design cost for advertising and merchant charging, even after usable consent controls are installed.
Weak IP enforcement deterring luxury brand presence
Authenticity risk can make online luxury purchases costly to resolve even when most of a product appears to be genuine. A Douyin buyer purchased a near-new secondhand Louis Vuitton shoulder bag after the seller called it genuine, but examination identified non-genuine zipper workmanship. The remaining parts were described as using genuine workmanship, making the fault a component-level authenticity failure. Citing the time since delivery, the seller refused a full refund, and the parties later reached a mediated settlement after a Jiangsu court found fraud. Component-level verification and post-sale dispute handling can therefore make secondhand luxury transactions more expensive to support, even when legal redress ultimately succeeds.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
China E-commerce Market Segment Analysis
By Business Model:
Consumer Scale Meets Enterprise ExpansionB2C was the largest segment by business model in 2026, accounting for an 87.01% market share. Mainland China's online-shopping user base fell from 974.4 million in December 2024 to 936.9 million in December 2025. A large consumer audience can support B2C scale even when the number of online shoppers declines, making audience size and transaction activity distinct commercial considerations. Differentiation therefore depends on converting a substantial audience into sustained purchasing activity, a more demanding task than simply reaching consumers who already shop online.
B2B is the fastest-growing business-model segment, with a projected CAGR of 11.02% from 2027 to 2032. JINGDONG Industrials' gross merchandise value (GMV) from key enterprise customers rose 26.5% in 2025. The number of such customers served increased from about 10,600 in 2024 to about 13,300 in 2025. The company attributed the GMV increase mainly to the expansion in its served key-enterprise customer base, connecting transaction growth with account coverage. Enterprise coverage becomes a commercial asset because each additional business relationship can add procurement activity, giving industrial platforms a specific route to expand their transaction base.

By Device Type (B2C):
Mobile Apps Extend the Shopping WorkflowSmartphone/mobile was the largest and fastest-growing device segment, with a 68.16% share in 2026 and a projected 9.76% CAGR from 2027 to 2032. JD.com reported that over 90% of the orders it fulfilled in 2025 were placed through its mobile apps. At that level of use, the mobile interface carries the commercial responsibility associated with a main ordering channel. Retailers serving a similar order mix have a clear reason to prioritize mobile checkout and service continuity, since improvements reach the interface used to place most purchases.
Mobile development also expands the range of transaction tasks a single app can support for a shopper. On May 11, 2026, Alibaba launched a Qwen-powered shopping assistant in the Taobao app, enabling users in China to browse, compare, order, and manage deliveries through conversation. Bringing those tasks together gives an operator a way to connect product discovery with post-order service in the same interface. The purchase interface consequently becomes a service interface too, giving app operators a broader field of differentiation than product discovery alone.
By Payment Method (B2C):
Cards Anchor Access as Wallet Use BroadensCredit and debit cards represented a 47.99% China e-commerce market share in 2026, making them the largest payment segment. China had 10.22 billion bank cards in circulation at year-end 2025, comprising 9.52 billion debit cards and 696 million credit and combined credit-debit cards. That installed base gives card-based commerce a substantial pool of existing payment instruments, allowing expansion to draw on accounts already opened. The selling opportunity is to put that installed capacity to work at checkout, where an available instrument can support a completed online purchase.
Digital wallets are the fastest-growing payment segment, with a projected 12.2% CAGR from 2027 to 2032. Wallets had a substantial role in China's e-commerce transaction value in 2025. Tencent reported year-on-year growth in commercial payment transaction count in Q2 2026 compared with Q2 2025. Weixin Pay is Tencent's consumer-facing mobile payment tool, while the transaction count covers its broader commercial-payment activity. The commercial growth route is deeper payment participation within commerce, which gives merchants a reason to treat wallet acceptance as part of selling across product categories.
By Product Category (B2C):
Electronics Scale and Food ExpansionConsumer electronics accounted for a 21.58% share of the China e-commerce market size in 2026, making it the largest product segment. Household appliances and audiovisual equipment online sales grew 4.8% year on year in China in 2025. Communications equipment online sales increased 10.2% year on year over the same period, providing another growth signal within related electronics categories. These different product trajectories make electronics an assortment-specific opportunity, with communications equipment providing a stronger recent online sales signal than home and audiovisual equipment.
Food and beverages are the fastest-growing product segment, with a projected 11.45% CAGR from 2027 to 2032. China's online retail sales of food-category goods rose 15.8% year on year in January-September 2026. Dingdong identified more monthly transacting users and higher order frequency in Q4 2025, alongside new frontline fulfillment stations that improved density and market penetration in East China. Those mechanisms connect customer activity with the physical reach of grocery fulfillment, making local service intensity part of the growth opportunity. The commercial advantage comes from supporting more usable purchasing occasions within a service area, connecting demand with an operating network that can fulfill it.
Geography Analysis
East China E-commerce Market
East China led the China e-commerce market in 2025, with substantial online activity across its principal demand centers. Jiangsu recorded online retail sales of CNY 1.37 trillion (USD 191.2 billion) in 2025, up 7.9%. Zhejiang's physical-goods online retail sales totaled CNY 1.75 trillion (USD 242.8 billion) that year, up 2.1%. Shanghai's online-shopping transaction value, covering goods and services, reached CNY 2.21 trillion (USD 307.5 billion) in 2025, up 21.3%. Retailers can build regional scale across several substantial demand centers, making East China's commercial appeal broader than dependence on a single city.
Regional specialization divides the opportunity between services for concentrated merchant supply and services for cross-border transactions, even within an established domestic consumption base. Jiangsu had 123 e-commerce specialty industrial belts and 42 county-level e-commerce clusters in 2025, providing a geographically distributed merchant ecosystem for providers seeking industrial-cluster customers.[2] Zhejiang's cross-border e-commerce exports grew 24.9% in 2025, while Ningbo's cross-border e-commerce bonded online-shopping imports ranked second nationwide that year. Selling the same service across these locations would overlook whether the customer is organizing industrial supply, completing an export transaction, or distributing bonded imports.
The city-level distinction concerns established retail operators and their contribution to local consumption, adding a domestic channel-development opportunity to the cross-border roles. Hangzhou's above-designated-size units recorded 15.6% growth in retail sales through public networks in 2025. In Suzhou, above-designated-size wholesale and retail units recorded 5.4% growth through public networks in 2025, contributing 0.8 percentage points to total retail sales growth. This contribution gives local online commerce a relevance extending beyond the turnover of individual online sellers. Above-designated-size retailers consequently offer a defined customer group for ongoing commerce services, with Suzhou's contribution connecting online sales execution to aggregate retail growth.
Regulatory Framework and Outlook
The table compares selected jurisdictions from an online trading platform operator's perspective, distinguishing national duties from Shanghai's local merchant protections. National platform-rule measures promulgated December 18, 2025, took effect February 1, 2026, and govern the formulation, amendment, and implementation of platform rules.[3] Most changes require at least 7 days' public notice, while rules involving very large user numbers, extensive revisions, or important interests require at least 15 days. These procedures make rule changes an operating commitment that must fit into commercial rollout schedules.
Regulatory Table of China E-commerce Market
| Decision factor | China | Shanghai |
|---|---|---|
| Primary authority | State Administration for Market Regulation and Cyberspace Administration of China | Shanghai Municipal Administration for Market Regulation |
| Key instruments or direction | Platform-rule measures effective February 2026; July 2026 draft E-Commerce Law amendment | June 2025 merchant-rule guidance; national platform-rule measures and proposed amendment |
| Commercial effect | Public consultation and advance publication of platform-rule changes | At least 7 days' merchant-rule notice and protection against forced promotional participation under local guidance |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
China's Medium rating reflects clear publication duties that add procedural costs and limit the speed of platform-rule changes. Shanghai's Medium rating also reflects local merchant protections, with its regulator monitoring 9 key platforms and guiding 48 platforms and livestreaming service agencies in 2025. The July 2026 consultation draft proposed broader platform duties and enforcement tools, with an August 4, 2026, feedback deadline. Those proposals support a Hardening direction for both columns because they would add obligations for platform operators in Shanghai as well as elsewhere in China.
Value Chain Stages
The value chain compares how merchandise sellers, marketplace operators, and fulfillment providers earn from the same online purchase. By the end of 2025, JD Fashion's on-demand retail service had onboarded over 1,000 merchants, including retailers and apparel and sports brands. Alibaba earned a majority of its China commerce retail revenue from customer-management services in FY2025, charging mainly by clicks, impressions, time, and sales. The distinction matters because expanding merchandise turnover creates different earnings opportunities for the seller, the platform connecting the transaction, and the service provider moving the goods.
Value Chain Analysis Table of China E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Merchandise supply and selling | Merchants such as Topsports, ANTA, Li-Ning | Goods sales | Connecting an assortment with online demand | Diversify selling channels and match assortments to each channel |
| Discovery and transactions | Marketplace operators such as Alibaba Group Holding Ltd., JD.com Inc. | Merchant marketing and transaction fees | Converting customer attention into completed purchases | Align merchant services with measurable customer actions |
| Warehousing and fulfillment | Logistics network providers such as Cainiao, JD Logistics | Logistics and supply-chain service revenue | Matching storage and picking capacity to promotional peaks | Combine suitable automation with partner-network capacity |
| Source: Mordor Intelligence | ||||
Fulfillment resilience depends on matching physical capacity with the transaction activity generated upstream. By December 31, 2025, JD Logistics had over 20 operating LangzuTech automated warehouses in nearly 20 Chinese cities, supporting high-density storage and picking from millions of stock-keeping units. Cainiao serves Alibaba businesses, including Tmall Supermarket, and third parties through its logistics and supply-chain services in China. Shared logistics capabilities therefore create an opening for specialist providers to earn beyond a single storefront, while automation makes the choice of operating nodes more consequential.
Competitive Landscape
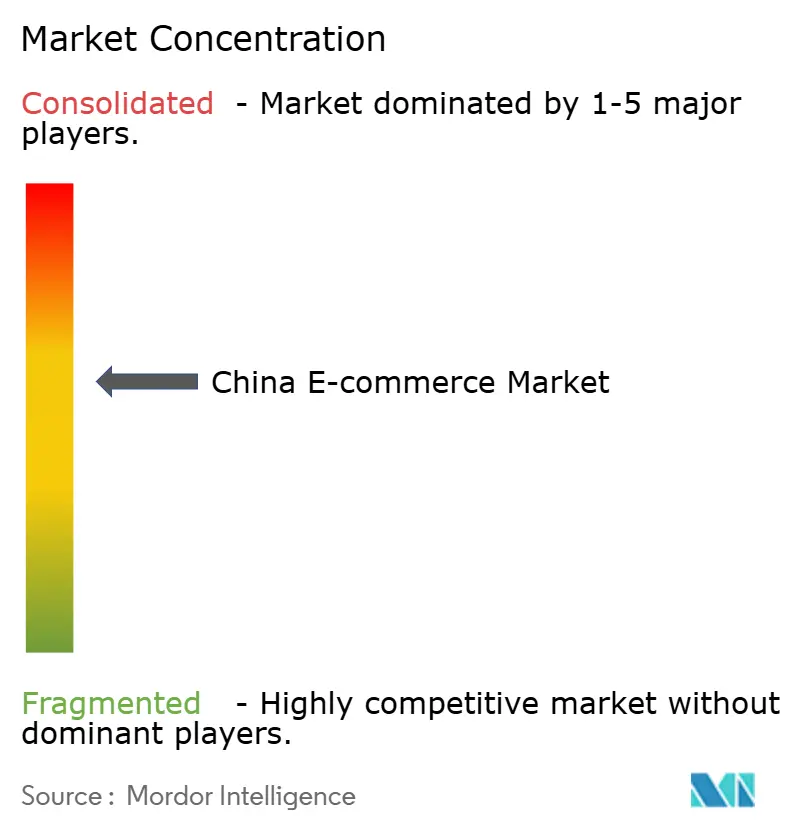
Competition centers on several large platform groups, with differentiated retailers preserving distinct positions alongside them. JD.com Inc. provides China-focused retail, marketplace, and marketing services, while PDD Holdings Inc. operates Pinduoduo in China separately from Temu. Suning.com Co. Ltd. serves county and township markets through Retail Cloud, while Alibaba Group Holding Ltd. operates Taobao and Tmall. Vipshop Holdings Ltd., an online brand-discount retailer, recorded 732.4 million orders company-wide in 2025 across its app, website, and WeChat Mini-Program. Specialization can therefore support substantial transaction activity alongside broad platforms, giving brand-discount retailers a commercial avenue distinct from competing across every retail category.
Physical retail investment gives online operators another way to differentiate their customer-facing capabilities and the geographic reach of their electronics and home-appliance businesses. JD.com opened Fujian's first JD MALL in Xiamen and launched JD Appliance City Flagship Stores in 15 cities in Q4 2025. Suning.com closed 238 low-efficiency stores and opened or refurbished 79 Suning Max and Suning Pro experience stores in 2025. Expansion and selective restructuring therefore present different routes to a stronger retail footprint, with the commercial test being whether each location adds enough useful customer service to justify the operating resources committed to it.
A further competitive route connects content discovery with transaction execution, adding partner interfaces to the capabilities a commerce operator must manage. In May 2025, Alibaba said Taobao and Tmall had deepened their partnership with Xiaohongshu, allowing direct links from content to storefronts. This arrangement lets a content partner participate in discovery while established storefronts provide the transaction interface, creating a route for specialized partners. Clear rules governing those interfaces can also support a more dependable merchant proposition, giving transparent platform governance a competitive role. Specialists can compete at the referral interface, while the platform operator bears the broader coordination burden of turning outside attention into a reliable purchase.
China E-commerce Industry Leaders
-
JD.com Inc.
-
PDD Holdings Inc.
-
Suning.com Co. Ltd.
-
Alibaba Group Holding Ltd.
-
Vipshop Holdings Ltd.
- *Disclaimer: Major Players sorted in no particular order
China E-commerce Market Companies Covered in this Report
- Alibaba Group Holding Ltd.
- JD.com Inc.
- PDD Holdings Inc.
- Vipshop Holdings Ltd.
- Suning.com Co. Ltd.
- Meituan (Beijing) Technology Co., Ltd.
- Xingyin Information Technology (Shanghai) Co., Ltd.
- Dangdang Inc.
- Mogu Inc.
- NetEase (Hangzhou) Network Co., Ltd.
- SHEIN (Roadget Business Pte. Ltd.)
- Kaola E-commerce (China) Co., Ltd.
- Hangzhou Weidian Technology Co., Ltd.
- Shanghai Shizhuang Information Technology Co., Ltd.
- Beijing DHgate Information Technology Co., Ltd.
- 1688.com (Alibaba (China) Co., Ltd.)
- Beijing Xiaomi Electronic Products Co., Ltd.
- Beijing Douyin Information Service Co., Ltd.
- Beijing Kuaishou Technology Co., Ltd.
- Taobao Instant Commerce (Shanghai Rajax Information Technology Co., Ltd.)
Key Opportunities for Market Participants
The opportunities compare ways to help smaller merchants enter online selling, improve daily operations, and access shared commercial resources. China's July 2026 action plan identifies fragmented supply chains, high logistics costs, and weak marketing capacity among individual businesses. Those practical obstacles favor services tied to a specific operating task, giving providers a clearer commercial proposition than a broad technology package that requires several capabilities to adopt.
Market Opportunities Table of China E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Guided entry into platform selling | July 2026 plan targets training, tools, and lower transformation costs by end-2027 | Individual-business platform merchants | Bundle storefront onboarding with practical operating training | Transformation costs and limited operating capability | Participating platforms and merchant-service providers |
| Focused retail operating tools | July 2026 guidance supports retail digitalization and smaller-merchant technology services over 2026-2030 | Small and medium-sized online merchants | Start with a defined retail workflow and expand after adoption | Integrating tools into merchant operations | Commerce software providers and platform service units |
| Shared supply and delivery coordination | Local merchant-resource coordination is included in the 2026 action plan | Individual businesses in local industries | Organize supply and delivery services around a merchant cluster | Fragmented supply and high logistics costs | Participating platforms and logistics-service partners |
| Source: Mordor Intelligence | |||||
The central opening is ongoing operating support for merchants whose practical limitations prevent them from using a storefront effectively. Training can make a tool usable, while coordinated supply and delivery can make its transactions fulfillable. A provider connecting those tasks can seek recurring service revenue, making continued merchant activity commercially more valuable than a one-time onboarding count.
Recent Industry Developments in China E-commerce Market
- Aug 2026: ALO partnered with Tmall as its exclusive e-commerce platform in China, announcing a flagship store for August 12 as the fashion and lifestyle brand entered the country.
- Jul 2026: Costco partnered with JD.com on July 22 as its sole official e-commerce partner in China, offering curated global goods through its JD.com flagship store, with delivery as fast as the same day.
- May 2026: Alibaba connected Qwen to Taobao's entire product catalog and launched a conversational shopping assistant in the Taobao app on May 11, allowing users in China to browse, compare, order, and manage deliveries.
China E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
China e-commerce market measures the annual value of goods and services transacted online by residents and businesses located in mainland China, including cross-border transactions when the buyer or seller is within China. Values are gross merchandise value at end-buyer prices across consumer, business and consumer-to-consumer transactions.
Scope exclusions: Purely digital content, in-game items, crypto assets, ride-hailing fares and online transactions with no mainland China buyer or seller are excluded.
Segments Covered in This Report
- By Business Model
- B2C
- B2B
- By Device Type (B2C)
- Smartphone / Mobile
- Desktop and Laptop
- Other Device Types
- By Payment Method (B2C)
- Credit and Debit Cards
- Digital Wallets
- Buy Now Pay Later (BNPL)
- Other Payment Methods
- By Product Category (B2C)
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories
Data Sources, Market Sizing, and Validation
Desk Research
Official sources such as the National Bureau of Statistics of China, the Ministry of Commerce of China, the U.S. International Trade Administration and the U.S. Department of Agriculture supply online retail sales, category growth, rural and cross-border activity, platform formats and food-category trade context that anchor demand and cross-check modeled totals. The statistical series and agency market guides provide complementary measures of retail activity, geographic reach and trade conditions.
Company filings, investor materials and reputable press can clarify transaction growth, fulfillment investment and changes in business models, and can cross-check patterns in public indicators. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include China-based marketplace and merchant-service executives, online sellers, payment specialists, logistics operators and category leaders, with respondent roles spanning strategic, functional and operating responsibilities. Analysts would use their explanations to test secondary-source definitions and key assumptions, investigate gaps in segment evidence, and triangulate transaction drivers and constraints across business models and product categories.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model starts with a top-down estimate of China's annual online transaction value at end-buyer prices, then checks selected components with supplier and channel evidence and sampled average selling price times transaction volume where reliable inputs exist. National online retail sales and physical-goods sales anchor the consumer pool, while business procurement activity and cross-border trade help assess business transactions and transactions with a mainland China party. Internet-shopping participation, rural online sales, category sales and express-delivery activity indicate changes in reach, purchasing frequency and fulfillment capacity. Segment shares are built from the available transaction mix by business model, device, payment method and product category, with the same sale counted once and device or payment classifications treated as attributes of B2C transactions.
For forecasts, a multivariate regression can relate transaction value to these demand, access and fulfillment indicators, with scenario analysis for material policy or logistics changes and sensitivity checks where series are incomplete. Primary experts would examine whether each variable's direction and timing fit China market conditions and help interpret gaps in reported series. Selective supplier or channel estimates would be retained only when their definitions align, with missing inputs bounded against official totals and comparable historical signals.
Data Validation & Update Cycle
Analysts triangulate official retail and trade series with company disclosures, platform and logistics indicators, and selective channel checks, then investigate anomalies and material variance from prior periods or related indicators before sign-off. A second analyst reviews definitions, calculations and segment reconciliations, and targeted re-contact is triggered when a source changes its basis, a major event shifts activity, or independent signals remain inconsistent. The evidence is refreshed annually, reviewed between cycles after material market or policy events, and checked again in a fresh pre-delivery pass.
Mordor Intelligence's China Ecommerce Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. China e-commerce market measures the annual value of goods and services transacted online by residents and businesses located in mainland China, including cross-border transactions when the buyer or seller is within China.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. For forecasts, a multivariate regression can relate transaction value to these demand, access and fulfillment indicators, with scenario analysis for material policy or logistics changes and sensitivity checks where series are incomplete.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 1.84 T (2027) | |
| Regional Consultancy A | USD 1.07 T (2025) | At its 2025 base, this estimate is 41.8% below this report's 2027 value of USD 1.84 T, 2 years later. The earlier measurement base and stated growth outlook place the estimate below the later report year. |
| Regional Consultancy B | USD 1.19 T (2024) | At its 2024 base, this estimate is 35.3% below this report's 2027 value of USD 1.84 T, 3 years later. The earlier measurement base and stated growth outlook place the estimate below the later report year. |
Mordor Intelligence's analysts triangulate official retail and trade series with company disclosures, platform and logistics indicators, and selective channel checks, then investigate anomalies and material variance from prior periods or related indicators before sign-off.
Key Questions Answered in the Report
What is the China e-commerce market size and growth outlook?
The market is estimated at USD 1.68 trillion in 2026 and projected to reach USD 2.84 trillion by 2032, with a 9.08% CAGR from 2027 to 2032.
Which forces support online retail demand in China?
Rapid grocery fulfillment and merchant tools support online activity. Meituan's Xiaoxiang Supermarket expanded to 68 operating cities in Q2 2026.
Which business model leads China's online commerce?
B2C led with an 87.01% share in 2026. B2B is forecast to grow fastest, at a CAGR of 11.02% from 2027 to 2032.
Which companies are major e-commerce competitors in China?
Major competitors include JD.com Inc., PDD Holdings Inc., Suning.com Co. Ltd., Alibaba Group Holding Ltd., and Vipshop Holdings Ltd., spanning platforms and specialized retailers.
What challenges shape the outlook for China's e-commerce platforms?
Article 24 of China's Personal Information Protection Law requires personal-information processors using automated commercial marketing to offer a non-personalized option or convenient refusal. Compliance adds recurring operating work as online commerce expands.
Which part of China led e-commerce activity?
East China was the leading geography in 2025, supported by online activity in Jiangsu, Zhejiang, and Shanghai.