
Car Body Kit Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 128.09 Billion |
| Market Size (2031) | USD 168.77 Billion |
| Growth Rate (2026 - 2031) | 5.47 % |
| Fastest Growing Market | Europe |
| Largest Market | Asia-Pacific |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Car Body Kit Market Analysis by Mordor Intelligence
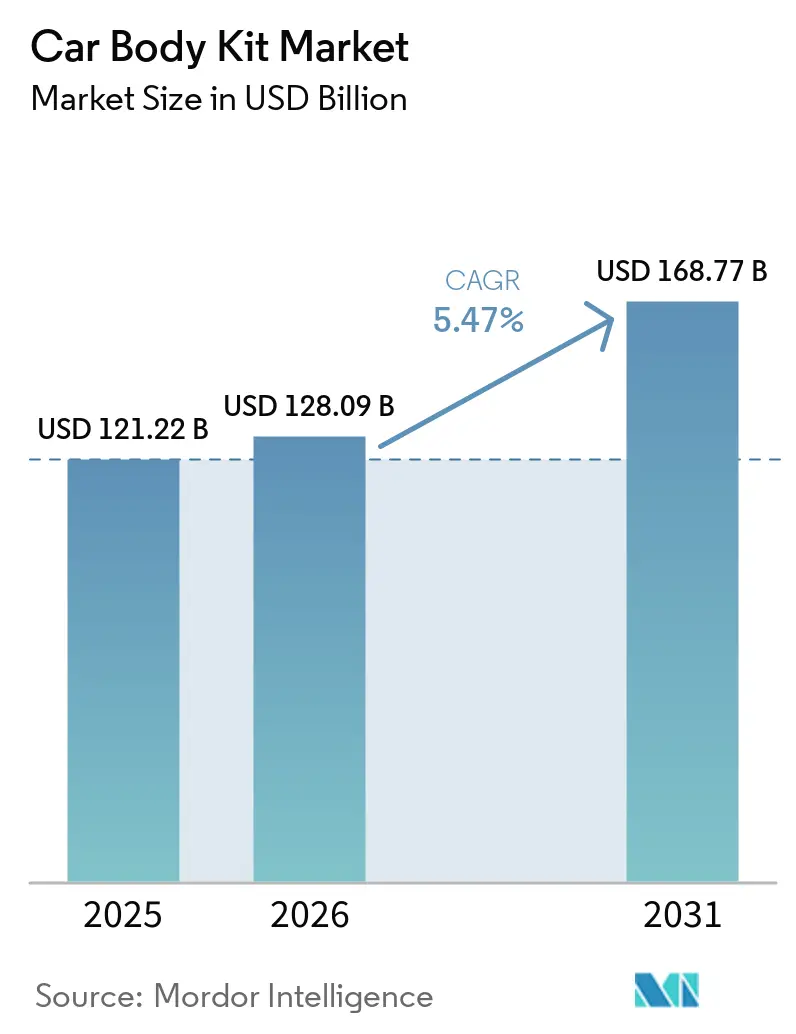
The car body kit market size was valued at USD 121.22 billion in 2025 and is projected to reach USD 128.09 billion in 2026 and USD 168.77 billion by 2031, growing at a CAGR of 5.67% from 2026 to 2031. Continuous styling refresh cycles, flourishing online parts marketplaces, and factory-approved aerodynamic packages for electric vehicles are the major catalysts for demand. Asia-Pacific already commands the highest share and benefits from permissive modification rules that encourage cosmetic upgrades. At the same time, digital storefronts are lowering entry barriers for niche tuners, while sustainability pressures are steering materials research toward flax- and recycled-fiber composites. Tightening safety regulations in North America and Europe, however, raise compliance costs for smaller installers[1].
Key Report Takeaways
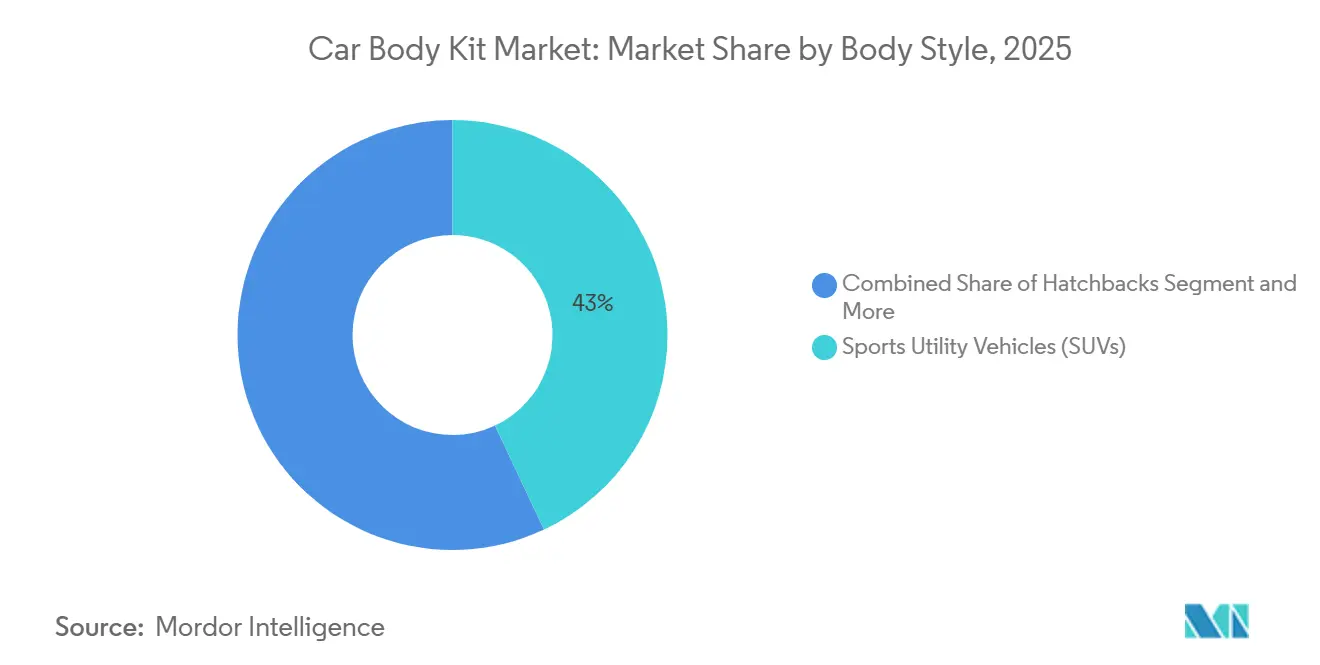
- By body style, SUVs held 43.01 % of the 2025 car body kit market share while MPVs are projected to post the fastest 7.11 % CAGR through 2031.
- By material, fiberglass captured 38.46 % of revenue in 2025; carbon fiber is expected to grow the quickest at 9.51 % CAGR.
- By component, full-body kits accounted for 34.41 % of 2025 sales and lead growth at an 8.81 % CAGR.
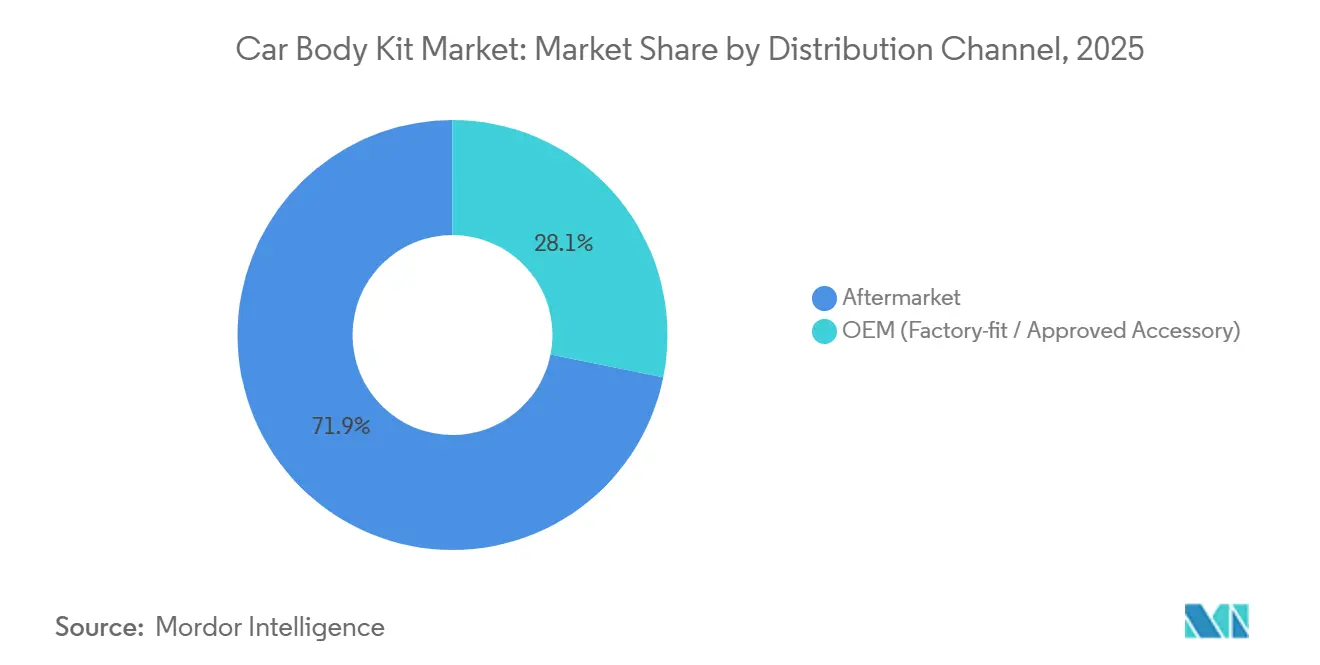
- By distribution channel, the aftermarket generated 71.86 % of 2025 value, whereas the OEM route is expanding at 11.67% CAGR to 2031.
- By sales channel, offline outlets still control 60.73 % of 2025 demand while online platforms are rising at an 11.67 % CAGR.
- Asia-Pacific contributed 46.56 % of global revenue in 2025 and is set to register the highest 7.57 % regional CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Car Body Kit Market*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| E-Commerce Expansion | +1.2% | Global, with early gains in North America & Asia | Short term (≤ 2 years) |
| Rising Passenger-Car Parc | +1.0% | Global | Long term (≥ 4 years) |
| Aero-Optimized Body Kit Adoption | +0.9% | North America, Europe, China | Medium term (2-4 years) |
| Increasing Vehicle Personalization | +0.8% | Asia-Pacific, Middle East, North America | Medium term (2-4 years) |
| Bio-Composite Body-Kit Materials | +0.5% | Europe, North America | Long term (≥ 4 years) |
| 3-D Printing for Bespoke Kits | +0.3% | North America, Europe, Japan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
E-Commerce Expansion for Aftermarket Parts
Digital storefronts anchor the discovery process for kits, letting hobbyists compare styles, shipping times and verified fitment from a single screen. Direct-to-consumer sales shave away distributor margins, so smaller tuners can price competitively while reaching export customers they once ignored. Fulfillment data gathered online also feeds rapid design tweaks, helping brands refresh molds in weeks instead of seasons. Fit-guides, augmented-reality previews, and community install videos reduce buyer anxiety, nudging first-time modifiers to click “buy” with confidence. Growth momentum will persist as marketplace algorithms surface niche products that traditional stores rarely stock[2].
Rising Passenger-car Parc
Vehicle fleets are aging, yet owners still crave a showroom look, so cosmetic overhauls become an appealing stop-gap before a new-car purchase. Older body panels lack embedded sensors, meaning bumper swaps or wider fenders can be fitted without complex recalibration, which keeps labor bills modest. In markets bearing steep import duties, a visual refresh costs far less than trading up, encouraging households to stretch vehicle life cycles. Repair shops therefore stock affordable fiberglass bumpers and polyurethane lips that hide dents while adding flair. The cumulative effect is a broad, durable base of demand for entry-level styling parts.
OEM Adoption of Aero-Optimized EV Wide-body Kits
Electric platforms share similar skateboard proportions, so automakers partner with design houses to differentiate silhouettes and reclaim brand identity. Factory-approved flares, diffusers and splitters not only sharpen aesthetics but also trim drag, yielding real-world range gains. Because kits are homologated by the automaker, buyers keep full warranty coverage, removing a key hesitation that shadows traditional aftermarket work. The smart #5 tuned by BRABUS highlighted this model, merging performance cues with full compliance paperwork.
Increasing Preference for Vehicle Personalization
Social feeds reward uniqueness, pushing drivers to move beyond stock paint and wheels toward bespoke exterior lines. Influencer culture turns a weekend bumper swap into shareable content, reinforcing a feedback loop that normalises modification even for mainstream commuters. Regional tastes vary, Japan favors subtle OEM-plus lips while the Middle East embraces full wide-arch conversions, but the common thread is self-expression. Lower-cost wrap films and bolt-on skirts let novices experiment before committing to pricier carbon pieces. As personalization spreads from performance cars to daily runabouts, suppliers diversify catalogs to cover ever-smaller vehicle niches.
Restraints Impact Analysis of Car Body Kit Market*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent Modification Regulations | -0.6% | North America, Europe, Australia | Medium term (2-4 years) |
| Costly Carbon-Fiber Kits | -0.4% | Global, acute in emerging markets | Long term (≥ 4 years) |
| Insurance Surcharges | -0.3% | North America, Europe, Australia | Short term (≤ 2 years) |
| Supply-Chain Volatility | -0.2% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stringent Modification Regulations
Safety agencies require proof that altered bumpers, lights or crash structures still satisfy baseline impact rules, and those engineering tests cost money. Installers must affix compliance labels and retain documentation, exposing small workshops to liability if paperwork lapses. Rule books also differ by state or province, so multi-site retailers juggle overlapping height, lighting and pedestrian-protection clauses. The bureaucracy slows product rollouts because each new bumper mold may need fresh certification. Over time, only well-capitalized tuners can afford these hurdles, trimming the pool of competitors and shrinking consumer choice in tightly regulated regions.
High Cost of Premium Carbon-Fiber Kits
Carbon weave signals performance pedigree, yet lay-up time, autoclave energy and specialized trimming keep sticker prices high. Even though recycled fibers and bio-based resins promise savings, headline costs still dwarf those of fiberglass, deterring buyers outside luxury segments. When a full kit costs more than a used city hatchback, enthusiasts in emerging economies pivot to cheaper plastics or partial overlays. Dealers also worry about repair bills because cracked carbon requires expert patches, not quick filler and paint. Until scalable alternatives such as flax-hybrid laminates move from pilot lines to mass presses, carbon’s market ceiling will stay limited.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Car Body Kit Market Segment Analysis
By Body Style:
SUVs Lead, MPVs AccelerateSUVs commanded 43.01 % of sales in 2025, giving them outsized influence on product roadmaps. Designers prioritize rugged bumper guards, roof spoilers and arch extensions that reinforce the utility image prized by crossover buyers. Broad platform commonality lets mold makers amortize tooling across several nameplates, keeping prices keen despite generous panel sizes. This scale advantage also ensures a brisk cadence of face-lifted styles that track automakers’ mid-cycle refreshes. Seasonal off-road festivals and social-media showcases further stoke demand for tall, adventurous aesthetics.
MPVs, although smaller in absolute terms, record the fastest 7.11 % CAGR as families look to add flair to otherwise utilitarian people-movers. Suppliers bundle body-color side skirts, illuminated grilles and subtle spoilers that avoid compromising sliding-door clearance. Ride-hail fleets adopt similar kits to stand out on curbside pickup lanes, creating a commercial revenue layer. Dealers market these packages as warranty-safe enhancements, soothing owners wary of aftermarket risks. As urban parking remains tight, compact but stylish MPV treatments resonate with drivers who juggle school runs and weekend getaways.

By Body-Kit Material:
Fiberglass Dominates, Carbon Fiber AdvancesFiberglass held 38.46 % share in 2025 because its chop-strand mats cure quickly, sand easily and mend with household tools. Decades-old mold libraries cover everything from classic coupes to current crossovers, letting shops deliver same-day replacements after parking mishaps. Paint shops appreciate the substrate’s stability, which cuts color-matching touch-ups. Insurance adjusters likewise favor fiberglass due to predictable claim costs, reinforcing its seat at the volume table. Local artisans even create limited-run styles without major capital outlay, ensuring a steady stream of fresh looks.
Carbon fiber are set to post the swiftest 9.51 % CAGR to 2031 as enthusiasts chase weight savings and motorsport cachet. Visible twill patterns telegraph exclusivity, so owners often leave panels unpainted under a glossy clear-coat for showroom drama. Suppliers temper expenses by offering partial-overlay bonnets or mirror caps that deliver visual punch without a full body swap. Motorsport teams feed technology trickle-down, standardizing pre-preg lay-ups that aftermarket brands later adapt. Sustainability conversations now highlight flax-carbon hybrids that cut fossil content yet retain stiffness, hinting at broader adoption once production volumes climb.
By Body-Kit Component:
Full-Body Kits Gain MomentumFull-body packages seized 34.41 % of the total market size in 2025, reflecting an appetite for unified design language over mix-and-match upgrades. Tuners present rendered mock-ups that reveal how bumpers, skirts and diffusers flow together, persuading buyers to commit to the entire ensemble. The result is showroom impact akin to a factory special edition, achieved without a new-car loan. Package pricing often includes color-coded hardware, saving installers time hunting for matching fasteners. Launching coordinated bundles also simplifies marketing because a single hero image circulates across social feeds and forums.
These same kits chart the quickest 8.81 % CAGR to 2031 as payment-plan providers make higher ticket prices digestible through monthly installments. Limited-run series with serialized plaques add collectability, spurring early adoption before units sell out. OEM approval programs further boost appeal by guaranteeing sensor compatibility and corrosion standards. Workshops prefer packages because bundled labor simplifies scheduling and job quoting. As augmented-reality apps let shoppers preview full conversions on their driveway, hesitation fades and upgrade cycles shorten.
By Distribution Channel:
Aftermarket Prevails, OEM Builds PresenceThe independent aftermarket accounts for 71.86 % of revenue in 2025, so its ecosystem of mold shops, paint booths and e-commerce storefronts sets the competitive tone. Workshops tailor catalogues to local tastes, whether drift-inspired lips in Japan or desert-ready fender vents in the Gulf. Agile producers iterate quickly, releasing new molds within months of a vehicle launch, long before factory catalogs respond. Importantly, the aftermarket nurtures parts for discontinued models, keeping older cars stylish and on the road. Word-of-mouth reviews and influencer installs cement trust in standout regional brands.
OEM channels are set to grow the fastest at 11.67% CAGR in relative terms because automakers see lucrative parts margins and tighter brand control. Dealer-installed kits arrive pre-painted to factory codes, reassuring customers who fear mismatched panels. Factory warranty continuity also minimizes resale-value anxiety versus third-party modifications. Strategic alliances with prestige tuners inject credibility while lightening the R&D burden on in-house design studios. As automakers bundle financing for accessories into vehicle loans, up-front price friction diminishes and uptake edges upward.
By Sales Channel:
Offline Retains Scale, Online SurgesPhysical outlets accounted for 60.73 % of sales in 2025 because complex installs demand lifts, spray booths and alignment rigs that a home garage lacks. Face-to-face consultations help buyers navigate local law, paint codes and wheel-arch clearances. Body shops often hold sample panels so customers can inspect gloss depth or carbon-weave density before committing. Regional fashion cues spread quickly when a freshly converted car parks outside the store, creating a tangible billboard. Loyalty programs further tether enthusiasts by bundling periodic detailing and discount vouchers.
Online platforms, logging an 11.67 % CAGR, democratize access to rare styles once limited to car-show insiders. High-resolution configurators match bumper lines to factory paint codes, reducing costly return shipments. Drop-shipping from overseas warehouses bypasses local stock shortages, shrinking lead times for specialty parts. User forums and unboxing videos build social proof, nudging fence-sitters toward checkout. Hybrid service models now let customers order online and schedule professional fitting at affiliated garages, blending convenience with craftsmanship.
Geography Analysis
APAC Car Body Kit Market
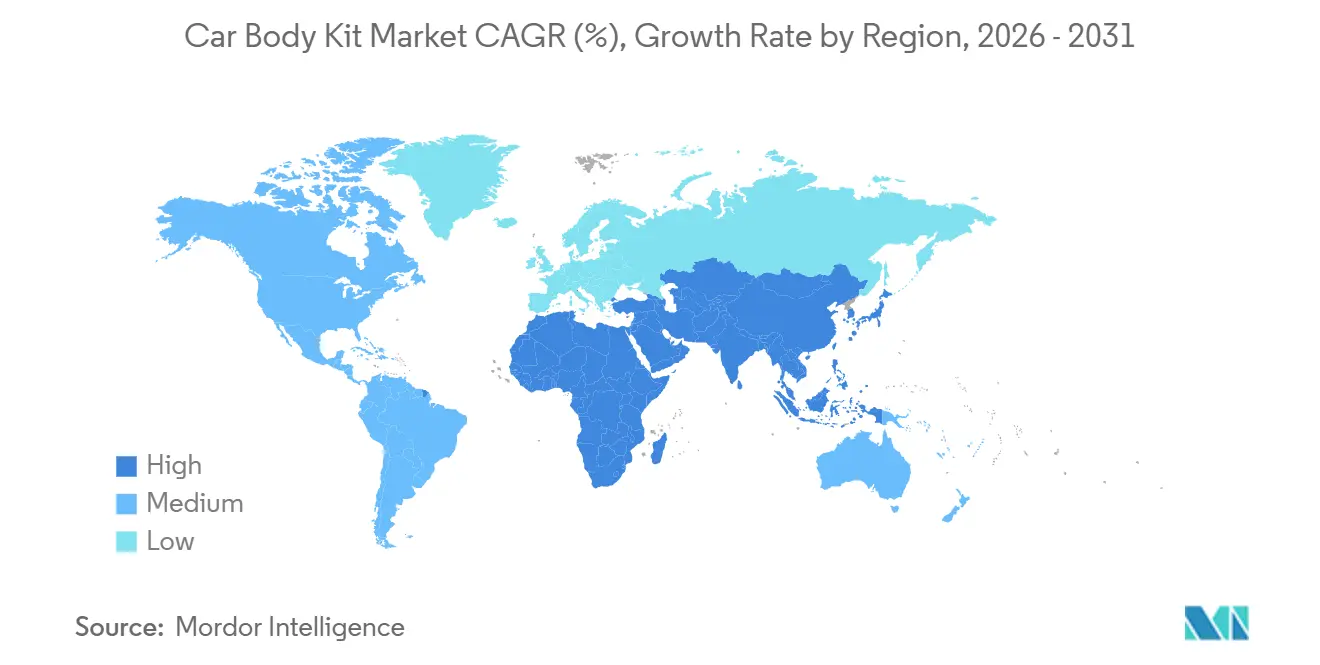
The Asia-Pacific region accounted for 46.56% of global revenue in 2025 and is expected to grow at the fastest CAGR of 7.57%. This growth is driven by several factors unique to the region. In Japan and Thailand, relaxed modification laws have created an environment where vibrant tuner cultures thrive, allowing car enthusiasts to personalize their vehicles with fewer restrictions. Across Southeast Asia, rising household incomes are enabling more consumers to spend on aesthetic upgrades, reflecting a growing interest in vehicle customization. Additionally, local manufacturers in China are playing a crucial role by producing competitively priced molds. These molds not only reduce lead times for export shipments but also enhance the region's position as a leader in supply, making it a key player in the global market.
North America Car Body Kit Market
North America continues to see steady demand, supported by an aging vehicle fleet and a strong enthusiast community that values vehicle customization. However, growth in this region faces challenges due to federal crash-safety regulations and insurance surcharges, which can make modifications more expensive and complex. These hurdles have led smaller shops to specialize in compliance documentation, helping customers navigate the regulatory landscape. At the same time, online platforms are expanding access to parts and services for rural buyers, who often lack convenient access to urban parts stores. This broader geographic reach is helping to offset some of the challenges posed by regulatory requirements, ensuring that customization remains accessible to a wider audience.
Europe Car Body Kit Market
Europe, known for its rich motorsport history, also faces some of the strictest modification regulations in the world. Buyers in this region are increasingly opting for TÜV-certified components to maintain their vehicles' resale values and avoid potential inspection issues. The push toward electric mobility is opening up new opportunities for innovative styling and customization, as consumers look for ways to personalize their electric vehicles. However, economic challenges, including inflation and reduced discretionary spending, are limiting the extent to which consumers can invest in these upgrades. Despite these hurdles, Europe remains a significant market where tradition and innovation intersect, offering unique opportunities for growth in the long term.
Competitive Landscape
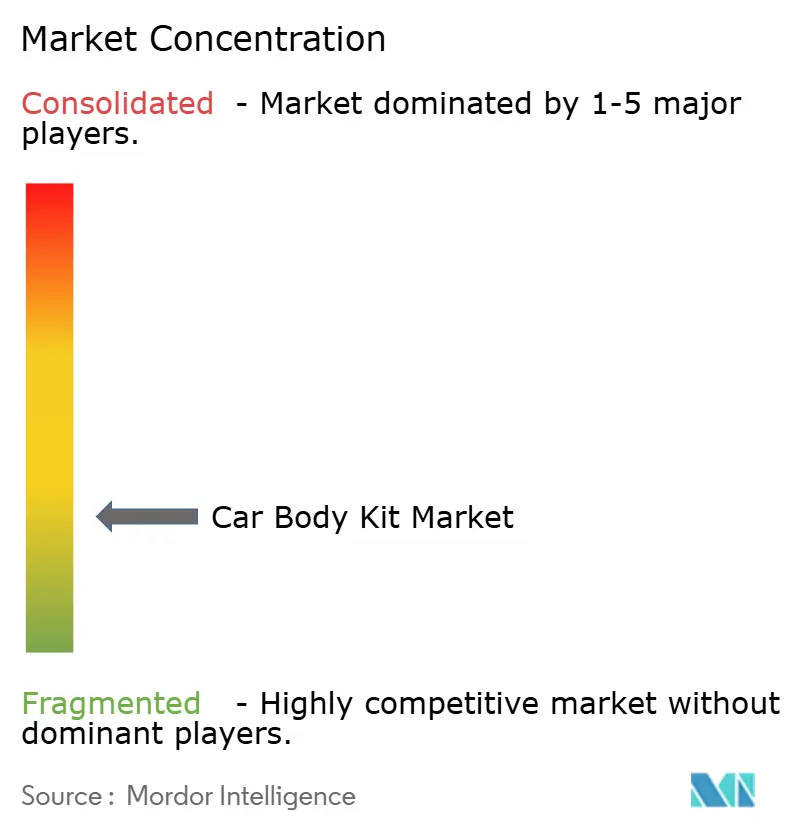
The car body kit market remains broadly dispersed, with dozens of regional specialists jostling alongside a handful of headline tuner brands. Liberty Walk, BRABUS, Mansory, ABT Sportsline and TECHART exert outsize cultural influence, yet plenty of niche artisans still flourish by mastering local tastes. Creative freedom is high because no giant wields the purchasing power to dictate universal design standards. Cult followings on social media allow even small outfits to spark global trends overnight. This dynamism fosters a continuous churn of styles that keeps the market vibrant and unpredictable.
Technology investment sets leaders apart: computational fluid-dynamics simulations inform aero tweaks, while large-format 3-D printers slash prototype cycles from weeks to hours. Materials science also serves as a battleground, with flax-hybrid laminates and recycled carbon riding a sustainability wave. Tuners that secure factory-backed partnerships gain access to CAD data, ensuring perfect fitment on new-model launches. Conversely, workshops that neglect certification risk exclusion from regions enforcing strict safety audits. Intellectual-property enforcement tightens too, prompting reputable brands to embed holographic tags that thwart copycat molds.
Market entry barriers revolve less around machinery than around branding, compliance and distribution reach. E-commerce storefronts let newcomers test overseas demand without costly brick-and-mortar networks, but customer service and warranty handling still separate premium players from drop-ship resellers. Successful firms curate step-by-step install media, reducing return rates and building community goodwill. Collaboration with content creators provides organic exposure, often more persuasive than traditional advertising. As electric-vehicle volumes climb, tuners able to integrate sensor housings and cooling channels into aero panels will gain early-mover cachet, setting the stage for a fresh competitive reshuffle.
Car Body Kit Industry Leaders
-
Brabus GmbH
-
TECHART Automobildesign GmbH
-
Mansory Design & Holding GmbH
-
Liberty Walk Co., Ltd.
-
ABT Sportsline GmbH
- *Disclaimer: Major Players sorted in no particular order
Car Body Kit Market Companies Covered in this Report
- Liberty Walk Co., Ltd.
- BRABUS GmbH
- Mansory Design and Holding GmbH
- TECHART Automobildesign GmbH
- ABT Sportsline GmbH
- Novitec Group
- Maxton Design
- LARTE Design
- APR Performance
- Extreme Dimensions (Duraflex)
- VARIS Co., Ltd.
- Prior-Design GmbH
Recent Industry Developments in Car Body Kit Market
- July 2026: Suzuki introduced the GOZEL styling package for the Jimny Sierra and Jimny Nomade (5-door) in Japan, available through its dealer network under the "Suzuki Select Plus" accessories catalog.
- July 2026: Liberty Walk launched a full-body kit for the Lamborghini Urus, including a Front Lip, Side Skirts, Rear Diffuser, Rear Wing, Trunk Wing, and Wide Fenders, with optional add-ons.
- June 2026: Suzuki introduced a Sports Edition of the Fronx crossover SUV in Malaysia, featuring cosmetic updates such as a piano black grille, dark chrome bar, black logo, and black-painted splitter.
- June 2026: Suzuki introduced a factory-backed body kit for the Swift Sport in Japan, developed with aftermarket specialist Awin, months after the Swift Sport ZC33S Final Edition was discontinued.
Global Car Body Kit Market Report Scope
A car body kit comprises aerodynamically optimized components, primarily exterior modifications, typically including front and rear bumpers (fenders), side skirts, and spoilers for the painted portion of the car.
The car body kit market is analyzed across multiple segmentation dimensions to provide comprehensive market intelligence. By Body Style, the market is segmented into Hatchbacks, Sedans, SUVs, and MPVs. By Body-Kit Material, the market is segmented into Fiberglass, ABS Plastic, Polyurethane, Carbon Fiber, and Composites (GFRP, CFRP, etc.). By Body-Kit Component, the market is segmented into Full-Body Kits, Front and Rear Bumper Kits, Spoilers and Wings, and Other Components (Lips, Side Skirts, etc.). By Distribution Channel, the market is segmented into OEM (Factory-fit / Appointed Dealers) and Aftermarket. By Sales Channel, the market is segmented into Online and Offline (Specialty Shops, etc.). By Geography, the market is segmented into North America (United States, Canada, and Rest of North America), South America (Brazil, Argentina, and Rest of South America), Europe (United Kingdom, Germany, Spain, Italy, France, Russia, and Rest of Europe), Asia-Pacific (India, China, Japan, South Korea, and Rest of Asia-Pacific), and Middle East and Africa (United Arab Emirates, Saudi Arabia, Turkey, Egypt, South Africa, and Rest of Middle East and Africa).
Market forecasts are provided in terms of Value (USD) and Volume (Units).
Segmentation Overview
| Hatchbacks |
| Sedans |
| Sports Utility Vehicles (SUVs) |
| Multi-Purpose Vehicles (MPVs) |
| Fiberglass |
| ABS Plastic |
| Polyurethane |
| Carbon Fiber |
| Composites (GFRP, CFRP hybrids) |
| Full-Body Kits |
| Front and Rear Bumper Kits |
| Spoilers and Wings |
| Other Components (Lip-kits, Grilles, Hoods) |
| OEM (Factory-fit / Approved Accessory) |
| Aftermarket |
| Online |
| Offline (Specialty Shops, Dealers) |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| Spain | |
| Italy | |
| France | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | India |
| China | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East & Africa | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Egypt | |
| South Africa | |
| Rest of Middle-East and Africa |
| By Body Style | Hatchbacks | |
| Sedans | ||
| Sports Utility Vehicles (SUVs) | ||
| Multi-Purpose Vehicles (MPVs) | ||
| By Body-Kit Material | Fiberglass | |
| ABS Plastic | ||
| Polyurethane | ||
| Carbon Fiber | ||
| Composites (GFRP, CFRP hybrids) | ||
| By Body-Kit Component | Full-Body Kits | |
| Front and Rear Bumper Kits | ||
| Spoilers and Wings | ||
| Other Components (Lip-kits, Grilles, Hoods) | ||
| By Distribution Channel | OEM (Factory-fit / Approved Accessory) | |
| Aftermarket | ||
| By Sales Channel | Online | |
| Offline (Specialty Shops, Dealers) | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| Spain | ||
| Italy | ||
| France | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | India | |
| China | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East & Africa | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Egypt | ||
| South Africa | ||
| Rest of Middle-East and Africa | ||
Key Questions Answered in the Report
How large is the car body kit market today?
The market was valued at USD 121.22 billion in 2025 and is expected to register a CAGR of 5.67 % through 2031.
Which body style generates the most kit sales?
Sports utility Vehicles (SUVs) accounted for 43.01 % of global revenue in 2025.
What material is most widely used in kits?
Fiberglass leads with 38.46 % share because it balances cost and ease of repair.
Why is Asia-Pacific so dominant?
Permissive modification rules and cost-efficient manufacturing underpin its 46.56 % share and highest regional growth rate.
Are online channels overtaking physical stores?
Online platforms log the fastest 11.67 % CAGR, but offline outlets still perform most complex installations.