
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 81.04 Billion |
| Market Size (2026) | USD 92.16 Billion |
| Market Size (2031) | USD 175.21 Billion |
| Growth Rate (2026 - 2031) | 13.71 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Asia Pacific Electric Commercial Vehicles Market Analysis by Mordor Intelligence
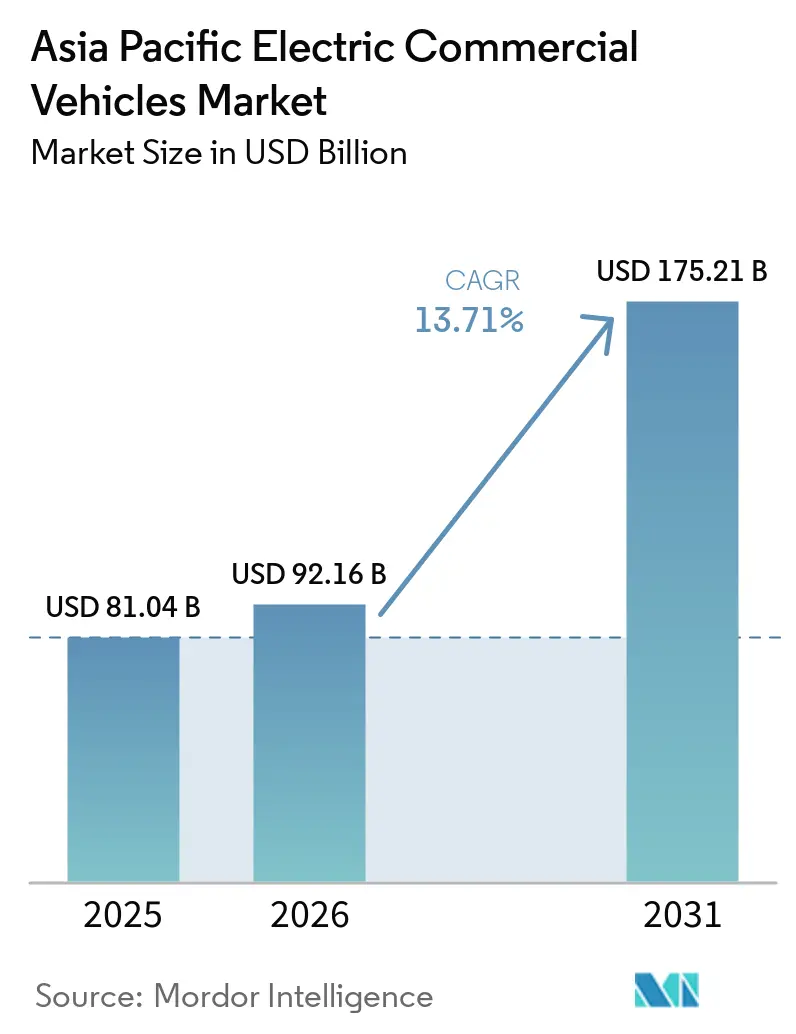
The Asia Pacific Electric Commercial Vehicles Market size was valued at USD 81.04 billion in 2025, and expected to reach USD 92.16 billion in 2026, and projected to grow to USD 175.21 billion by 2031, growing at a CAGR of 13.71% from 2026 to 2031. Fleet purchases accelerated after China extended its dual-credit policy to light commercial vans and Japan funded megawatt-scale depot chargers, making battery-electric adoption financially viable for logistics operators. Battery-leasing schemes trimmed upfront costs by up to 40%, widening access for small carriers in Indonesia and Thailand. Simultaneously, zero-emission mandates for public bus tenders in China, India, and South Korea created predictable demand pipelines that de-risked OEM capacity expansion. Heavy-duty truck electrification gained momentum as ASEAN port cities imposed stricter SOX and NOX caps, while surging e-commerce orders compressed delivery windows and favored vehicles that recharge during loading breaks.
Key Report Takeaways
- By vehicle body type, buses led with 47.18% of the Asia Pacific electric commercial vehicle market share in 2025, whereas heavy-duty trucks are set to post the fastest 14.73% CAGR through 2031.
- By propulsion, battery-electric models captured 78.36% share in 2025, while fuel-cell electric vehicles are on track for the highest 14.81% CAGR during the outlook period.
- By battery chemistry, LFP packs held 53.16% share in 2025, but emerging LMFP and sodium-ion chemistries are projected to expand at 15.86% CAGR.
- By end-use application, public transit commanded 58.71% share in 2025, and urban logistics is forecast to advance at a 15.83% CAGR.
- By charging power band, 51-150 kW systems accounted for 45.63% of installations in 2025, whereas units rated 351 kW and above are set to grow at a 15.75% CAGR.
- By geography, China held 38.71% share in 2025, while India is anticipated to record the quickest 15.77% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Asia Pacific Electric Commercial Vehicles Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging Intra-City E-Commerce Deliveries | +3.1% | China, India, Indonesia, Thailand, Vietnam | Short term (≤ 2 years) |
| Government Purchase Mandates | +2.8% | China, India, South Korea, Singapore | Medium term (2-4 years) |
| China's Dual-Credit Policy Extension | +2.4% | China, with spillover to ASEAN exporters | Short term (≤ 2 years) |
| Battery-Leasing Models | +2.2% | China, India, Indonesia, Thailand | Medium term (2-4 years) |
| Megawatt-Scale Depot Charging Roll-Outs | +1.9% | China, Japan, South Korea, Singapore | Medium term (2-4 years) |
| SOX/NOX Caps in ASEAN Port Cities | +1.3% | Singapore, Malaysia, Thailand, Indonesia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Surging Intra-City E-Commerce Deliveries
Urban online retail penetration is increasing in China and India, raising daily parcel density beyond the payload efficiency of diesel vans. JD Logistics has deployed electric vans across Chinese megacities, citing an operating-cost advantage over diesel alternatives. Alibaba’s Cainiao unit has ordered electric vans for phased delivery in the coming years. In India, Delhivery and Ecom Express have adopted small electric vans to avoid traffic-restriction fines and achieve break-even within a relatively short period. Improved vehicle uptime and charging schedules that align with depot operations are reinforcing growth in the Asia Pacific electric commercial vehicle market.
Government Purchase Mandates for Zero-Emission Buses
Municipal transport agencies across China, India, and South Korea finalized contracts requiring all newly commissioned buses to be fully electric. Shenzhen completed the transition of its bus fleet, while Beijing allocated funding to replace buses within the coming years. In India, the government budgeted funding under FAME-III, prompting state-level orders for electric buses. South Korea established an electric vehicle quota for new metropolitan buses, supported by government incentives. Singapore also issued a tender for electric buses to be delivered under a long-term concession. These mandates support consistent production volumes, reduce battery costs through large-scale procurement contracts, and strengthen supply chain stability in the Asia-Pacific electric commercial vehicle market.
China's Dual-Credit Policy Extension to Commercial LCVs
The government added light vans to the New Energy Vehicle credit scheme, requiring OEMs to offset diesel vehicle output with credits that carried a high cost. SAIC and Dongfeng launched eight electric LCV models apiece to serve e-commerce operators such as JD Logistics. BYD received CNY 12.47 billion (USD 1.8 billion) in government subsidies related to its daily operations in 2025, bundling them with fleet-financing packages that cut total ownership cost and further stimulate the Asia Pacific electric commercial vehicle market [1].
Battery-Leasing Models Slashing Up-Front Cost
CATL and BYD pioneered battery-as-a-service contracts, substantially reducing electric commercial vehicle sticker prices. Fleet operators instead pay a per-kilometer fee for battery use, transferring depreciation risk to leasing providers. Tata Motors adopted a similar model for its Ace EV, reducing the entry price and securing a significant number of subscriptions across Indian cities. Pertamina and Gotion also announced a joint venture targeting buses and trucks in Indonesia. These financing innovations reduce balance-sheet pressure and expand access to the Asia-Pacific electric commercial vehicle market for cash-constrained operators.
Restraints Impact Analysis of Asia Pacific Electric Commercial Vehicles Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Inadequate Residual-Value Financing Norms | -1.8% | India, Indonesia, Thailand, Philippines | Medium term (2-4 years) |
| Grid-Upgrade Delays Around Urban Freight Hubs | -1.4% | Indonesia, Philippines, Vietnam, India | Medium term (2-4 years) |
| High Axle-Load Penalties on E-Trucks | -1.2% | India | Short term (≤ 2 years) |
| Lack of Hydrogen Supply Logistics | -0.9% | ASEAN, India, Australia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Inadequate Residual-Value Financing Norms
Banks across major ASEAN economies still price electric trucks using conservative five-year depreciation curves, lifting monthly payments 18-25% over diesel loans. India’s draft guidelines issued in late 2025 remain unevenly applied by state banks, while Indonesia and Thailand lack verified battery-health protocols. The higher cost of capital erodes already-slim EBITDA margins for logistics firms, slowing vehicle replacement decisions and tempering short-term growth in the Asia-Pacific electric commercial vehicle market.
Grid-Upgrade Delays Around Urban Freight Hubs
Utilities in Jakarta, Manila, and Ho Chi Minh City report prolonged backlogs for high-capacity depot connection approvals. In Jakarta, a significant share of recently submitted applications is awaiting substation capacity expansions, forcing fleet operators to lease diesel-powered mobile chargers at a substantial premium per kWh. Similar deferrals in several tier-two Indian cities delay the commissioning of chargers already financed under the national FAME incentive program, creating a chicken-and-egg trap that constrains the growth of the Asia-Pacific electric commercial vehicle market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia Pacific Electric Commercial Vehicles Market Segment Analysis
By Vehicle Body Type:
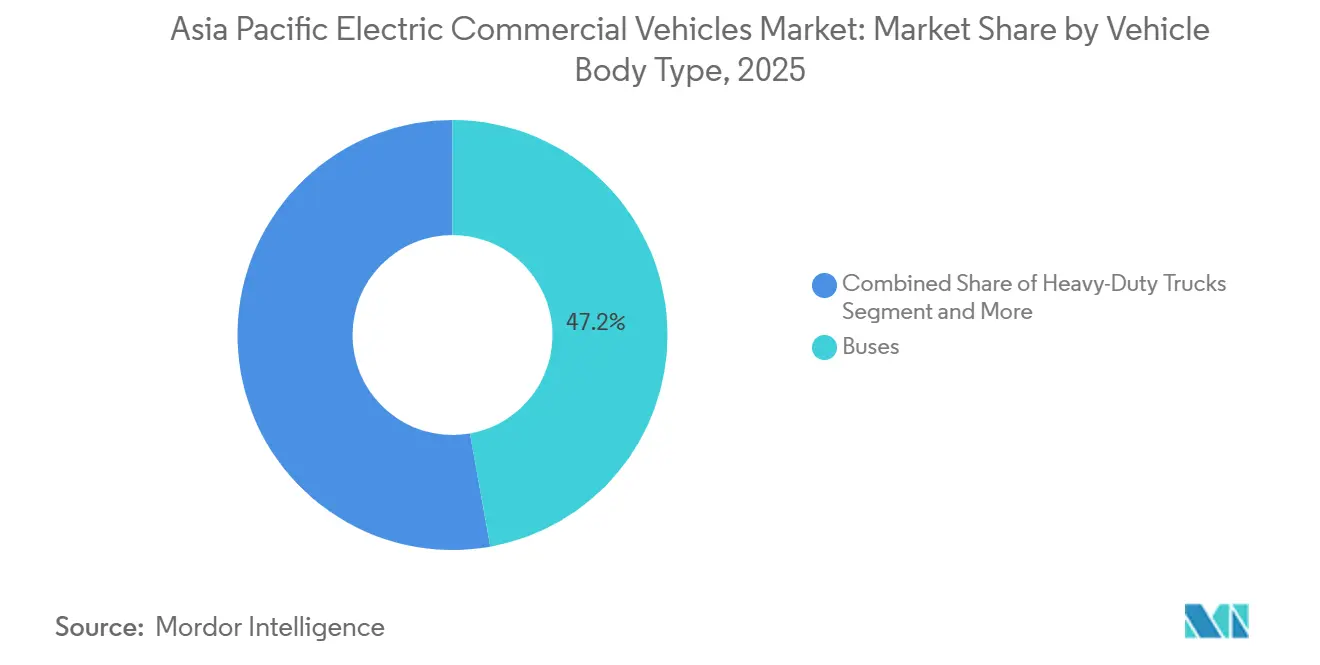
Buses Retain Scale, Heavy-Duty Trucks AccelerateBuses generated 47.18% of the Asia Pacific electric commercial vehicle market size in 2025 after municipal tenders locked in zero-emission purchases during 2023-2024. Heavy-duty trucks are forecast to expand at a 14.73% CAGR through 2031 as port authorities in Singapore, Busan, and Shanghai mandate low-emission drayage. BYD shipped mutiple electric buses regionwide in 2025, while SAIC and Dongfeng each released multiple medium-truck models aimed at e-commerce carriers.
Ultra-fast chargers rated 351-500 kW, now rolling out along Chinese and Japanese freight corridors, enable heavy rigs to recharge within driver rest mandates, boosting utilization beyond 75%. Light vans remain vital for last-mile delivery; Tata Motors’ battery-leased Ace EV attracted 1,200 subscriptions by mid-2025 in India. Collectively these trends raise the Asia Pacific electric commercial vehicle market share of heavy-duty platforms over the forecast horizon without eroding the bus segment’s scale advantage.

By Propulsion Category:
BEVs Dominate While FCEVs Gain FootholdsBattery-electric configurations commanded 78.36% of the Asia Pacific electric commercial vehicle market size in 2025, reflecting clear total-cost-of-ownership advantages on urban routes. Fuel-cell trucks and buses are set for a 14.81% CAGR. South Korea and Japan have established hydrogen refueling infrastructure. Last year, Hyundai supplied Xcient FCEVs to Korean carriers, which achieved high uptime on the Seoul–Busan corridor.
Plug-in hybrids bridge infrastructure gaps in Indonesia and the Philippines, yet their share is expected to contract as grid upgrades arrive. China’s continued dominance in battery supply chains and India’s FAME-III incentives will anchor BEV leadership in the Asia Pacific electric commercial vehicle market, while FCEVs address weight-sensitive or longer-haul operations where battery mass limits payload.
By Battery Chemistry:
LFP Leads, LMFP and Sodium-Ion Scale UpLFP cells occupied 53.16% share in 2025, favored for long cycle life and stable thermal profile. Emerging LMFP and sodium-ion designs are projected to capture a larger slice of the Asia Pacific electric commercial vehicle market share by 2031 after notching a 15.86% CAGR on improved energy density and cost savings. CATL’s second-generation LMFP packs reached 210 Wh/kg and 18% lower material cost, debuting in BYD buses.
These chemistries suit tropical ASEAN routes where ambient temperatures stress nickel-rich batteries. BYD’s Blade Battery, an LFP variant, already supplied 28% of regional demand in 2025 at USD 85/kWh. Sodium-ion variants will initially target low-range vans but could displace LFP in climates where cold-weather performance matters, reinforcing diversification inside the Asia Pacific electric commercial vehicle market.
By End-Use Application:
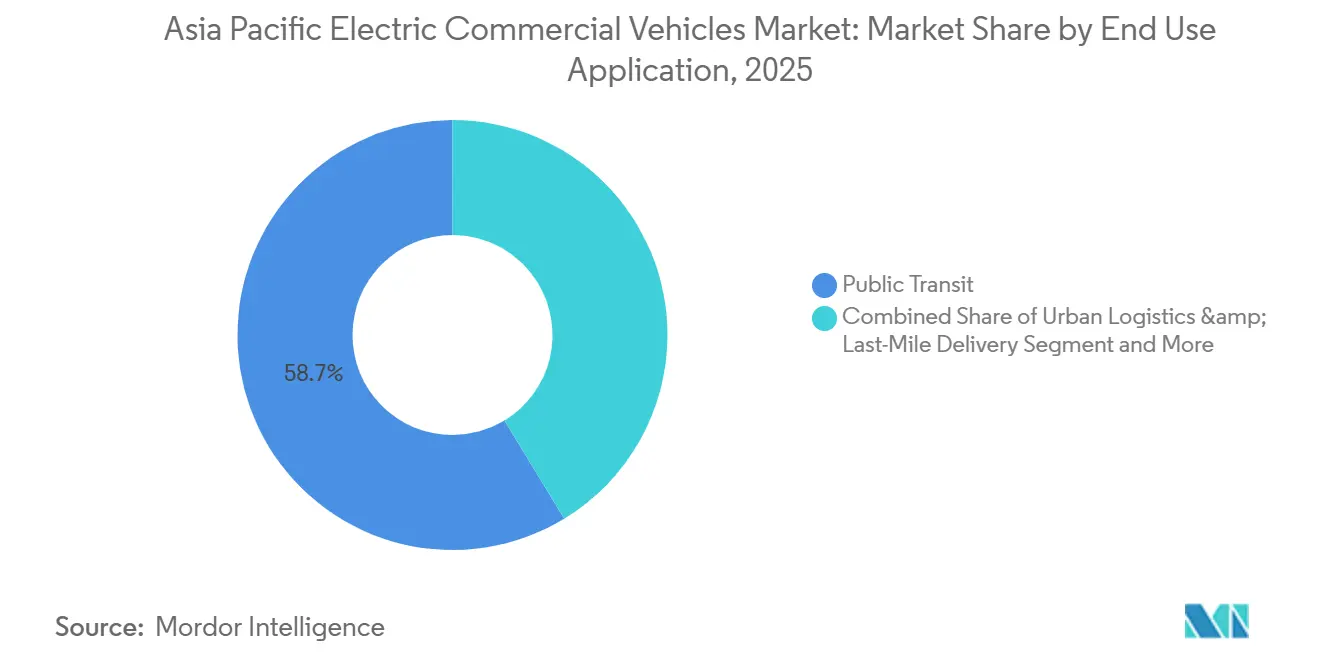
Public Transit Dominates, Logistics SurgesPublic transit absorbed 58.71% of 2025 demand after multi-year bus contracts materialized, ensuring dependable offtake for OEMs and battery makers. Urban logistics will register a 15.83% CAGR as e-commerce penetration increases in major Chinese metros and in India’s tier-1 cities. JD Logistics operates numerous electric vans, and Indonesia’s GoTo Group trials 500 units in Jakarta’s low-emission zones.
Airport and seaport ground fleets also adopt electric drayage and baggage tractors to meet local emission targets. Inter-city freight remains constrained by charger scarcity beyond 300 km corridors, but announced megawatt hubs should ease that limit post-2027, widening the Asia Pacific electric commercial vehicle market addressable segments.
By Charging Power Band:
Mid-Range Dominates, Ultra-Fast Gains GroundChargers rated 51-150 kW met 45.63% of fleet demand in 2025, aligning with overnight depot routines for buses and light vans. Systems delivering 351 kW or more will advance at a 15.75% CAGR as heavy-truck operators chase sub-45-minute turnaround. China alone installed 1.2 GW of depot capacity in 2025, while Japan funded multi-megawatt hubs near Tokyo and Osaka.
Lower rated <50 kW units linger in rural India and ASEAN where smaller batteries suffice. As standardized 800-V vehicle architectures proliferate, average session power will climb, reinforcing a technology step-change that sustains momentum in the Asia Pacific electric commercial vehicle market size through 2031.
Geography Analysis
Asia Pacific Electric Commercial Vehicles Market in China
China continues to dominate the Asia Pacific electric commercial vehicles market, commanding approximately 87% of the regional market share in 2024. The country's leadership position is reinforced by its robust manufacturing capabilities, extensive supply chain network, and advanced battery technology ecosystem. The government's unwavering commitment to sustainable transportation through comprehensive policy support, including purchase subsidies and infrastructure development initiatives, has created a conducive environment for market growth. Chinese manufacturers have demonstrated remarkable innovation in developing diverse electric commercial vehicle portfolios, ranging from urban delivery electric vans to heavy-duty electric trucks. The country's strategic focus on reducing urban pollution and achieving carbon neutrality goals has accelerated the adoption of electric commercial vehicles across various sectors. Furthermore, China's established charging infrastructure network, coupled with decreasing battery costs and improving vehicle performance, has significantly enhanced the commercial viability of electric vehicles for fleet operators and logistics companies.
Asia Pacific Electric Commercial Vehicles Market in Indonesia
Indonesia is emerging as the region's fastest-growing market for electric commercial vehicles, with a projected growth rate of approximately 37% from 2024 to 2029. The country's transformation is driven by its ambitious vision to become a major hub for electric vehicle manufacturing in Southeast Asia. Indonesia's unique position as a global leader in nickel reserves, a critical component for electric vehicle batteries, has attracted significant investments in the electric vehicle supply chain. The government's comprehensive approach includes developing a robust charging infrastructure network, implementing favorable tax policies, and promoting local manufacturing capabilities. The country's large-scale urbanization and growing emphasis on sustainable transportation solutions have created substantial opportunities for electric commercial vehicle adoption. Additionally, Indonesia's strategic partnerships with international manufacturers and technology providers have accelerated knowledge transfer and technological advancement in the sector. The increasing awareness of environmental sustainability among businesses and the rising total cost of ownership advantages of electric vehicles have further catalyzed market growth.
Asia Pacific Electric Commercial Vehicles Market in Japan
Japan's electric commercial vehicles market exemplifies the country's commitment to technological innovation and environmental sustainability. The nation's advanced automotive manufacturing capabilities and strong focus on research and development have positioned it as a pioneer in electric vehicle technology. Japanese manufacturers have particularly excelled in developing efficient powertrains and advanced battery management systems for commercial applications. The country's mature logistics sector has been instrumental in driving the adoption of electric commercial vehicles, particularly in urban delivery and municipal services. Japan's unique approach to electrification, which includes a balanced focus on battery electric vehicles and fuel cell technology, has created diverse opportunities for commercial vehicle electrification. The integration of smart charging solutions and vehicle-to-grid technologies has enhanced the appeal of electric commercial vehicles for fleet operators. Furthermore, Japan's strong emphasis on quality and reliability has established high standards for electric commercial vehicle manufacturing across the region.
Asia Pacific Electric Commercial Vehicles Market in India
India's electric commercial vehicles market is experiencing a remarkable transformation driven by the country's push towards sustainable mobility solutions. The nation's vast commercial vehicle sector presents significant opportunities for electrification, particularly in urban logistics and public transportation. The government's production-linked incentive scheme has attracted substantial investments in electric vehicle manufacturing, creating a robust ecosystem for commercial vehicle electrification. Indian manufacturers have focused on developing cost-effective electric commercial vehicles tailored to local operating conditions and requirements. The country's growing emphasis on reducing oil dependency and improving urban air quality has accelerated the adoption of electric buses and delivery vehicles. The emergence of innovative business models, including battery swapping and vehicle leasing, has addressed key adoption barriers. Additionally, India's strong IT capabilities have facilitated the integration of telematics and fleet management solutions, enhancing the operational efficiency of electric commercial vehicles.
Asia Pacific Electric Commercial Vehicles Market in Other Countries
The electric commercial vehicles market in other Asia Pacific countries, including South Korea, Malaysia, Thailand, and Australia, demonstrates diverse adoption patterns and growth trajectories. These markets are characterized by varying levels of infrastructure development, government support, and industry readiness for electrification. South Korea's technological prowess and strong automotive manufacturing base have enabled significant advances in electric commercial vehicle development. Malaysia and Thailand have positioned themselves as emerging manufacturing hubs, leveraging their established automotive industries to attract investments in electric vehicle production. Australia's vast distances and unique operating conditions have led to specialized applications of electric commercial vehicles, particularly in urban and regional logistics. These markets benefit from knowledge sharing and technology transfer within the region, while developing distinct approaches to address their specific transportation needs and environmental goals. The collective progress in these countries contributes to the broader regional transition towards sustainable commercial transportation solutions.
Competitive Landscape
In 2025, the top five OEMs held a significant market share, indicating a moderately consolidated landscape. Chinese brands leverage in-house battery and drivetrain production to undercut their Japanese and Korean counterparts by a notable margin. BYD’s Blade Battery plays a crucial role in regional battery pack demand, while CATL’s LMFP design expands chemistry options for cost-conscious fleets.
Established truck manufacturers, including Hino, Mitsubishi Fuso, and Isuzu, face margin pressure as customers prioritize total cost of ownership over brand legacy. Meanwhile, newer entrants such as Switch Mobility and JBM Auto are establishing a presence in the city bus segment by offering battery-leasing models that significantly reduce upfront cash outlays. The increase in patent filings for thermal management systems highlights the industry’s focus on improving battery longevity in hotter climates.
In Vietnam, Malaysia, and the Philippines, secondary freight corridors remain underserved, creating opportunities for hybrid and plug-in solutions to address infrastructure gaps. Partnerships, such as Tata’s collaboration with Cummins for drive units and the Hyundai-Kia alliance for fuel-cell stacks, underscore the competitive race to lead the emerging electric commercial vehicle market in Asia-Pacific.
Asia Pacific Electric Commercial Vehicles Industry Leaders
-
BYD Auto Co. Ltd.
-
Daihatsu Motor Co. Ltd.
-
Dongfeng Motor Corporation
-
Hyundai Motor Company
-
Mitsubishi Motors Corporation
- *Disclaimer: Major Players sorted in no particular order
Asia Pacific Electric Commercial Vehicles Market Companies Covered in this Report
- BYD Auto Co. Ltd.
- Dongfeng Motor Corporation
- Hino Motors Ltd.
- Hyundai Motor Company
- Tata Motors Ltd.
- Ashok Leyland Ltd.
- Zhengzhou Yutong Bus Co. Ltd.
- SAIC Motor Corp. Ltd.
- Foton Motor Group
- CATL (Contemporary Amperex Technology Co. Limited)
- Mitsubishi Fuso Truck & Bus Corp.
- JBM Auto Ltd.
- NFI Group
- Switch Mobility Ltd.
- Isuzu Motors Ltd.
- Higer Bus Company Ltd.
- Geely Commercial Vehicles
- King Long United Automotive
- Maxus (SAIC)
- Mahindra & Mahindra Ltd.
- Arrival Ltd.
Recent Industry Developments in Asia Pacific Electric Commercial Vehicles Market
- June 2026: At the 30th Greater Bay Area Auto Show, BYD Commercial Vehicles presented its full portfolio for the first time and announced that its cumulative global commercial vehicle sales had exceeded 203,000 units.
- January 2026: CAM EV officially launched the EV48, its next-generation e-Platform electric van, in Malaysia. Designed for logistics applications, the cargo van offers a 6 m³ cargo capacity and a 53.58 kWh CATL LFP battery, providing a CLTC range of 390 km. The EV48 secured substantial fleet orders before its official debut.
- January 2026: Tata Motors introduced 17 trucks from 7-55 tonnes under the new I-MOEV modular platform and launched the Ace Pro EV mini-truck and Intra EV pickup.
- January 2026: Mitsubishi Fuso and Al Habtoor Motors unveiled the next-generation eCanter for Middle-East fleets, underscoring export diversification.
- January 2026: Mitsubishi Fuso Truck and Bus Corporation and Foxconn announced plans to establish an independent Japanese bus venture that will market zero-emission models from late 2026.
Asia Pacific Electric Commercial Vehicles Market Report Scope
The scope of the report includes Vehicle Body Type (Buses, Heavy-Duty Trucks, and More), Propulsion (BEV and More), Battery Chemistry (LFP and More), End-use (Urban Logistics and More), Charging Power (Less than or equal to 50 kW and More), and Geography.
Segmentation Overview
By Vehicle Body Type
| Buses |
| Heavy-Duty Trucks |
| Medium-Duty Trucks |
| Light Commercial Vans |
| Light Trucks |
By Propulsion/Fuel Category
| Battery Electric Vehicle (BEV) |
| Plug-in Hybrid Electric Vehicle (PHEV) |
| Hybrid Electric Vehicle (HEV) |
| Fuel-Cell Electric Vehicle (FCEV) |
By Battery Chemistry
| LFP |
| NMC |
| Others |
By End-use Application
| Urban Logistics & Last-Mile Delivery |
| Inter-city Freight |
| Public Transit |
| Airport & Seaport Services |
By Charging Power Band
| Less than or equal to 50 kW |
| 51 to 150 kW |
| 151 to 350 kW |
| More than or equal to 351 kW |
By Country
| Australia |
| China |
| India |
| Indonesia |
| Japan |
| Malaysia |
| Singapore |
| South Korea |
| Thailand |
| Vietnam |
| Philippines |
| Rest of Asia-Pacific |
| By Vehicle Body Type | Buses |
| Heavy-Duty Trucks | |
| Medium-Duty Trucks | |
| Light Commercial Vans | |
| Light Trucks | |
| By Propulsion/Fuel Category | Battery Electric Vehicle (BEV) |
| Plug-in Hybrid Electric Vehicle (PHEV) | |
| Hybrid Electric Vehicle (HEV) | |
| Fuel-Cell Electric Vehicle (FCEV) | |
| By Battery Chemistry | LFP |
| NMC | |
| Others | |
| By End-use Application | Urban Logistics & Last-Mile Delivery |
| Inter-city Freight | |
| Public Transit | |
| Airport & Seaport Services | |
| By Charging Power Band | Less than or equal to 50 kW |
| 51 to 150 kW | |
| 151 to 350 kW | |
| More than or equal to 351 kW | |
| By Country | Australia |
| China | |
| India | |
| Indonesia | |
| Japan | |
| Malaysia | |
| Singapore | |
| South Korea | |
| Thailand | |
| Vietnam | |
| Philippines | |
| Rest of Asia-Pacific |
Market Definition
- Vehicle Type - The category covers light, medium, and heavy duty commercial vehicle.
- Vehicle Body Type - This includes Light Commercial Pick-up Trucks, Light Commercial Vans, Medium-duty Commercial Trucks, Heavy-duty Commercial Trucks, and Medium and Heavy Duty Buses.
- Fuel Category - The category exclusively covers electric propulsion systems, including various types such as HEV (Hybrid Electric Vehicles), PHEV (Plug-in Hybrid Electric Vehicles), BEV (Battery Electric Vehicles), and FCEV (Fuel Cell Electric Vehicles).
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


