
Vietnam Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 456.59 Million |
| Market Size (2026) | USD 487.44 Million |
| Market Size (2031) | USD 676.63 Million |
| Growth Rate (2026 - 2031) | 6.76 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Vietnam Data Center Networking Market Analysis by Mordor Intelligence
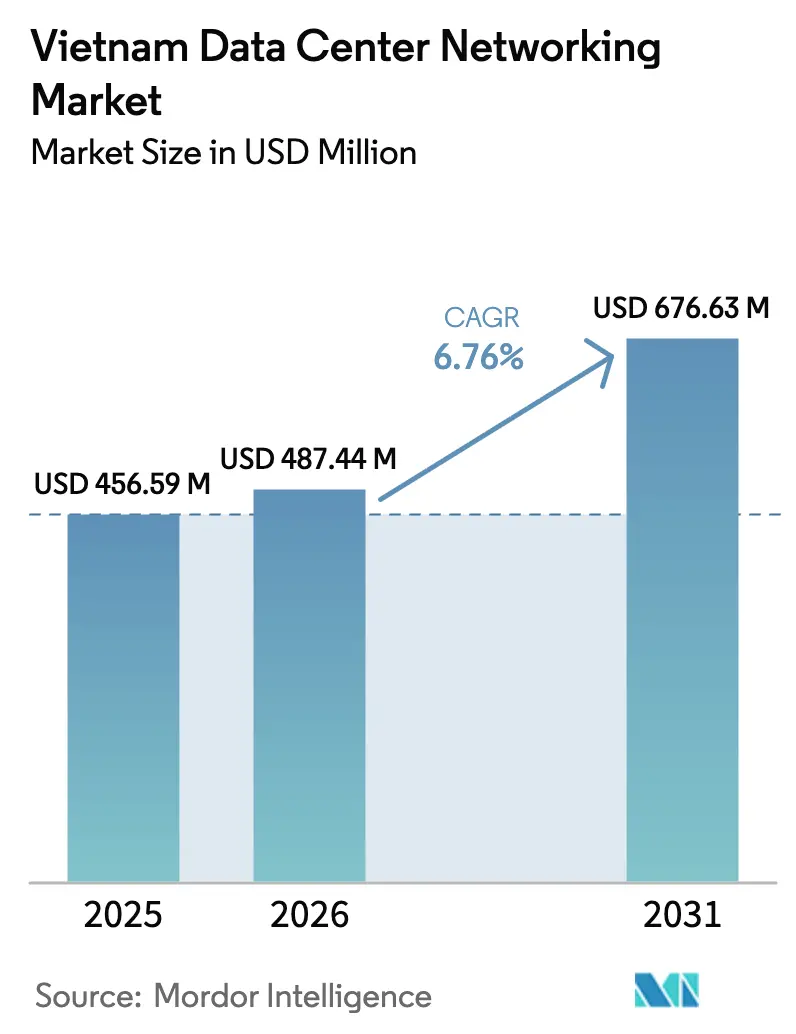
The Vietnam data center networking market size was valued at USD 456.59 million in 2025 and estimated to grow from USD 487.44 million in 2026 to reach USD 676.63 million by 2031, at a CAGR of 6.76% during the forecast period (2026-2031). Mandatory data-localization rules, continuous rollout of 5G, and heavy cloud capital expenditure give the market a firm growth foundation. Public-sector digital programs—most notably the National Digital Transformation Programme through 2025—anchor near-term demand, while record-scale private investments such as Viettel’s 140 MW facility signal durable long-term momentum. Hyperscalers, financial services institutions, and manufacturers are simultaneously upgrading to 25 GbE and 100 GbE architectures, which lifts switching, routing, and optical-interconnect revenue. Supply-chain tightness in advanced silicon and rising power tariffs remain headwinds, yet broad-based domestic and foreign investment keeps the overall outlook positive.
Key Report Takeaways
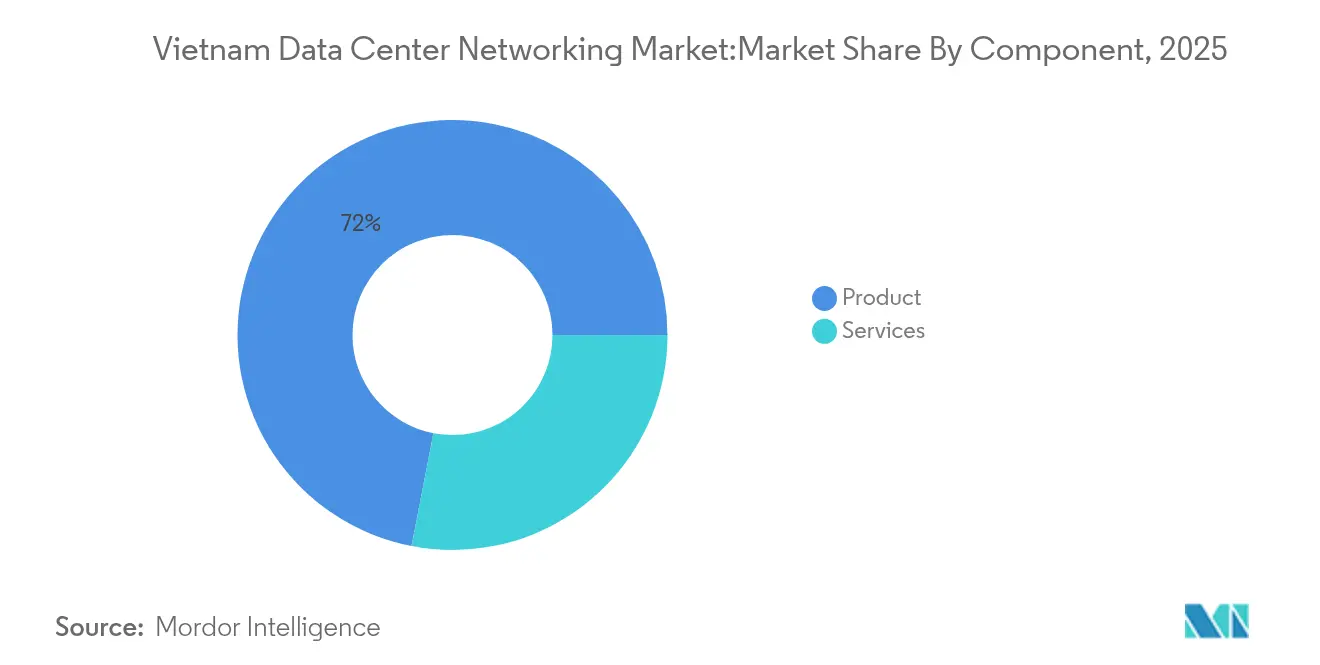
- By component, products held 71.95% of the Vietnam data center networking market share in 2025; Services are projected to log the fastest 6.88% CAGR to 2031.
- By end-user, IT and Telecommunications led with 35.30% revenue share in 2025, while Manufacturing and Industrial is poised for the highest 7.05% CAGR through 2031.
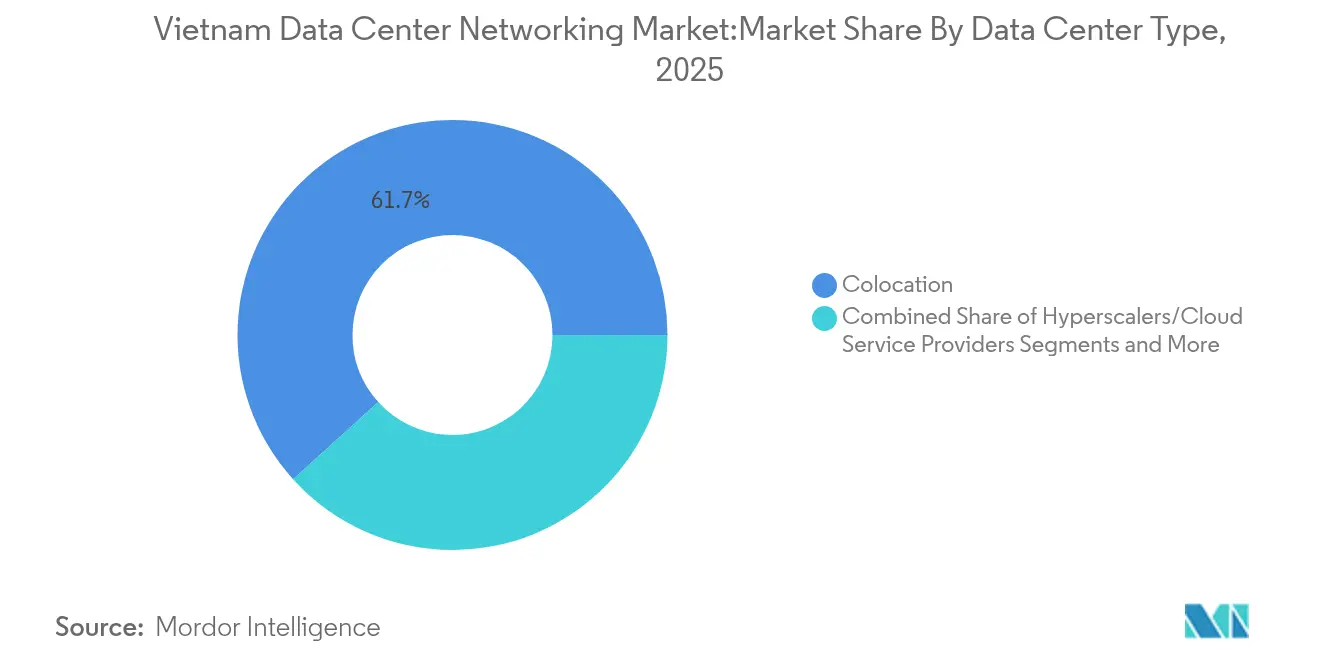
- By data-center type, colocation facilities captured 61.70% share of the Vietnam data center networking market size in 2025; Hyperscalers and Cloud Service Providers are forecast to grow at 7.95% CAGR toward 2031.
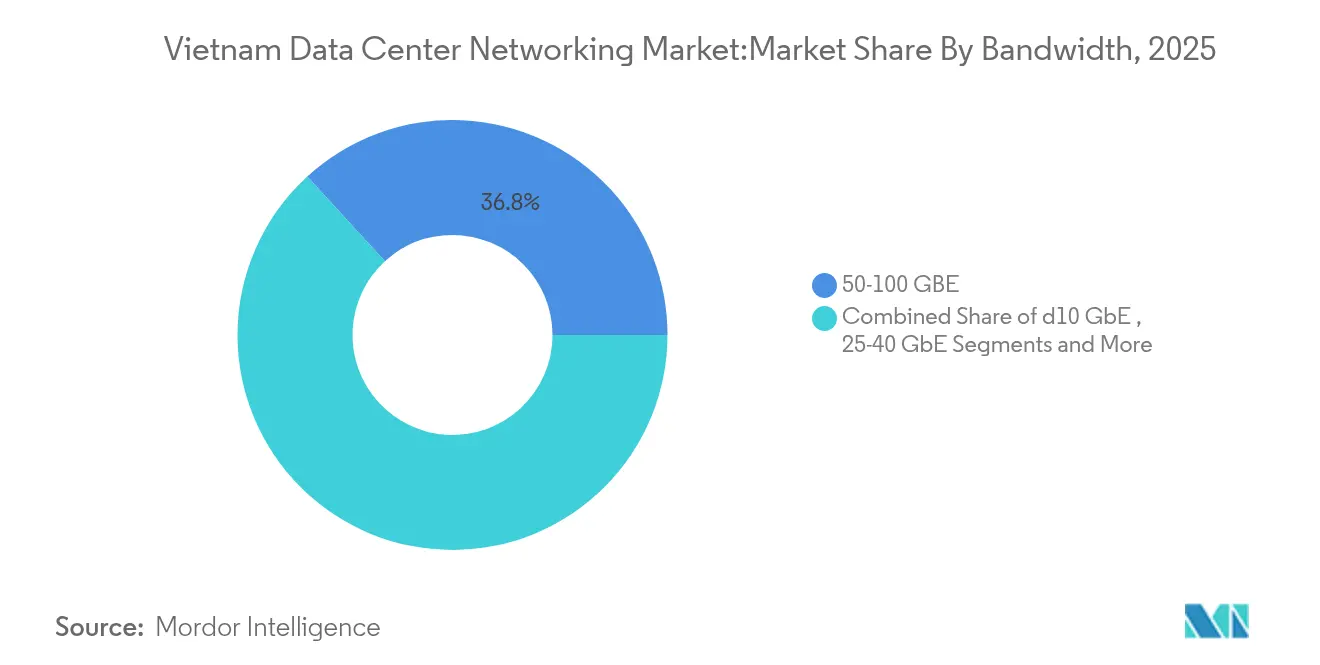
- By bandwidth, the 50-100 GbE class commanded 36.80% of the Vietnam data center networking market size in 2025, whereas greater than 100 GbE deployments should advance at an 8.35% CAGR over the same horizon.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Vietnam Data Center Networking Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing hyperscale and cloud CAPEX in Vietnam | +1.8% | National, concentrated in Ho Chi Minh City and Hanoi | Medium term (2-4 years) |
| Surge in edge-computing needs for smart-city and manufacturing projects | +1.2% | National, with early gains in Ho Chi Minh City, Da Nang, Binh Duong | Long term (≥ 4 years) |
| Government incentives (National DC Strategy 2025) | +1.5% | National | Short term (≤ 2 years) |
| Shift toward SDN and intent-based networking | +0.9% | National, enterprise-focused | Medium term (2-4 years) |
| 5G rollout driving DC router refresh | +1.1% | National, telecom operator-led | Short term (≤ 2 years) |
| Corporate ESG mandates favoring energy-efficient silicon | +0.7% | National, multinational enterprise-focused | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growing hyperscale and cloud CAPEX in Vietnam
Hyperscale builds now dominate large-ticket ICT spending as operators race to satisfy data-localization rules and regional hub ambitions. Viettel’s USD 261 million, 140 MW campus sets a new domestic benchmark, offering 10 kW racks that are optimised for AI workloads. [1]Viettel Group, “Viettel launches 140 MW data center,” viettel.com.vn VNPT’s 23,000 m² Hanoi facility with 2,000 racks supports 2 Gbps per rack, underscoring the rapid transition from 1 GbE to 25 GbE and 100 GbE switching backbones. Government targets calling for 870 MW of national capacity by 2030 underpin multi-year demand for high-bandwidth routing, optical-transport, and software-defined fabrics. Foreign cloud providers such as Alibaba Cloud have announced local zones to comply with storage rules, bringing new procurement volume to the Vietnam data center networking market.
Surge in edge-computing needs for smart-city and manufacturing projects
Samsung’s USD 20 billion cluster—producing 925 million handsets—operates thousands of real-time quality-control sensors that require local compute nodes and low-latency Ethernet fabrics. Foxconn’s deployment of 2,500 VDIs across six plants demonstrates the shift toward micro data centers and SDN controllers at factory floors. Binh Duong and Da Nang city programs add public-sector edge demand, driving incremental switch and firewall shipments. As operators densify 5G radios, tower-based micro data centers further enlarge the Vietnam data center networking market footprint.
Government incentives (National DC Strategy 2025)
Mandatory in-country processing for critical citizen and enterprise data forces cloud migrations onto domestic sites. The National Digital Transformation Programme stipulates 100% cloud adoption for state agencies by 2030, while Project 06’s biometric identity roll-out already serves 50 million citizens. Tax holidays and land-lease discounts for semiconductor and AI projects lighten capex burdens and catalyse facility build-outs. Two new green data centers totalling 241.5 MW are slated for completion by 2025, further enlarging addressable switch and router pools.
Shift toward SDN and intent-based networking
Vietnam International Bank cut transaction latency 85% after migrating 400 apps to Cisco Application Centric Infrastructure, enabling near-monthly mobile-banking feature releases. [2]Cisco Systems, “VIB accelerates with Cisco ACI,” cisco.com Banking digitisation—93% of institutions pursue tech upgrades—creates a sustained appetite for controller-based fabrics that automate policy, security, and QoS. Huawei’s intent-based portfolio resonates with enterprises wary of single-vendor lock-in. Manufacturing fabs also need rapid, policy-driven network re-configurations when production lines switch SKUs, lifting SDN penetration across the Vietnam data center networking market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Export-control-driven ASIC lead-time risk | -1.4% | Global supply chain affecting Vietnam | Short term (≤ 2 years) |
| Shortage of advanced network-architecture talent | -0.8% | National, concentrated in major cities | Medium term (2-4 years) |
| Rising electricity tariffs eroding TCO | -0.6% | National | Long term (≥ 4 years) |
| Persistent cybersecurity gaps in enterprises | -0.5% | National, SME-focused | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Export-control-driven ASIC lead-time risk
Advanced switching silicon now requires 40-60 week lead times because of expanded U.S. dual-use controls, doubling historical norms and inflating capex.[3]Bureau of Industry and Security, “Commerce Control List updates,” commerce.govVietnam still imports USD 50 billion in electronic parts annually, exposing local data-center builds to shipment slips and price spikes. Global surveys show 44% of operators suffered outages tied to parts shortages, underscoring operational risk within the Vietnam data center networking market.
Shortage of advanced network-architecture talent
Vietnam counts only 6,000 semiconductor engineers yet targets 1 million technology workers by 2030. Even with Cisco’s Networking Academy certifying 100,000 professionals, demand for AI-ready, high-density data-center designers outstrips supply. The skills gap raises labor costs, elongates deployment schedules, and compels many operators to outsource network operations.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Products Retain Revenue Dominance
Products generated 71.95% of Vietnam data center networking market revenue in 2025, reflecting the hardware-intensive stage of the country’s digital build-out. Core-to-edge switch refreshes from 1 GbE to 25 GbE and 100 GbE contribute the bulk, while router upgrades align with 5G backhaul expansion. Storage-area networking, application delivery controllers, and next-generation firewalls add incremental volume as data-localization laws amplify in-country storage and security needs. The Vietnam data center networking market size for Products is expected to widen in absolute terms even as growth decelerates relative to Services.Services, though only 28.05% of the 2025 spend, will advance at a 6.88% CAGR through 2031. Skill shortages make professional services indispensable for design, migration, and lifecycle support. Managed network services are especially attractive to mid-sized manufacturers and banks seeking outcome-based contracts that trim capex and de-risk operations. As SDN and intent-based platforms proliferate, vendors earn recurring revenue from controller licensing, network-analytics subscriptions, and security-policy automation, reinforcing the services uptrend across the Vietnam data center networking industry.


By End-User: Telecom Leads, Manufacturing Rises Fast
Telecom and IT operators commanded 35.30% of 2025 revenue, mirroring Viettel, VNPT, and FPT’s aggressive 5G and cloud rollouts. Techcombank’s LinuxONE stack that quadrupled transaction throughput demonstrates how financial institutions also drive enterprise-grade routing and switching demand. Government projects tied to national digital identity broaden the user base, while media, healthcare, and education add new workloads such as UHD streaming and telehealth services.Manufacturing and Industrial verticals, buoyed by China-plus-one relocations, are poised for a 7.05% CAGR. Samsung’s factories in Thai Nguyen and Bac Ninh require AI-enabled defect inspection and IoT telemetry, prompting micro data center and high-bandwidth switch installations. Industrial parks replicate this template, ensuring that the Vietnam data center networking market expands beyond the traditional metro hubs.
By Data-Center Type: Colocation Dominates Today
Colocation facilities accounted for 61.70% of the Vietnam data center networking market share in 2025. Viettel IDC, CMC Telecom, and VNPT secure enterprise and public-sector workloads that want Tier III uptime without heavy upfront capex. High-density colocation suites already offer 10 kW racks, setting the stage for AI hardware adoption.Hyperscalers and Cloud Service Providers will post an 7.95% CAGR, the fastest segment growth. Alibaba Cloud’s planned local zone and Viettel’s 140 MW campus illustrate the hyperscale pivot. These facilities need leaf-spine fabrics, 400 GbE aggregation, and automated optics, lifting the Vietnam data center networking market size substantially over the forecast period.
By Bandwidth: Migration to greater than 100 GbE Accelerates
The 50-100 GbE tier held 36.80% share in 2025, balancing cost and performance for most enterprises. VNPT’s engineering rule of 2 Gbps per rack reflects typical design in current builds. Legacy ≤10 GbE links persist in branch and edge sites, while 25-40 GbE serves as the mainstream migration path. 100 GbE is the fastest-growing tier at 8.35% CAGR. Viettel’s new data center supports average rack power of 10 kW and up to 60 kW, necessitating 400 GbE spine connectivity. Cisco and NVIDIA’s Spectrum-X roadmap provides integrated 400/800 GbE AI fabrics, widening availability of ultra-high-speed options. The Asia Direct Cable’s 50 Tbps link supplies the long-haul capacity to knit these data centers together.
Geography Analysis
Ho Chi Minh City and Hanoi anchor the Vietnam data center networking market thanks to robust telecom backbones, data-ready power grids, and proximity to corporate headquarters. Ho Chi Minh City hosts Viettel’s 140 MW super facility and NTT’s Saigon Hi-Tech Park build, solidifying its role as the primary hyperscale cluster. Municipal authorities’ smart-city roadmap mandates pervasive IoT, necessitating edge nodes in district offices and public transport corridors. Hanoi, the administrative and R&D center, benefits from Samsung’s USD 220 million research hub and VNPT’s latest 2,000-rack data center. National digital-government workloads bring low-latency requirements that boost premium routing and cybersecurity spend. Da Nang emerges as a third pole with six operational facilities and submarine-cable landing stations offering 90 Tbps of bandwidth. Provincial zones such as Binh Duong, Thai Nguyen, and Bac Ninh leverage manufacturing clusters to justify micro data centers and 5G edge nodes. Federal infrastructure plans allocating USD 36 billion in 2025 for roads and fiber backbones tighten latency between these growth corridors, deepening penetration of the Vietnam data center networking market nationwide.
Regulatory Landscape
Vietnam has moved data centers into a clearer telecom and data-governance perimeter through a sequence of laws taking effect across 2024-2026. The Law on Telecommunications 2023 (effective July 1, 2024) recognizes data center services as value-added telecommunications services under Ministry of Information and Communications (MIC) oversight, while the Data Law (effective July 1, 2025) sets a data classification framework and domestic storage obligations for important data. From a compliance standpoint, the Personal Data Protection Law (effective January 1, 2026) tightens requirements around privacy, cross-border data transfers, and security duties for critical information infrastructure, with implementation supported by the Authority of Information Security (AIS).
On the infrastructure side, Circular 42/2025/TT-BKHCN (effective February 1, 2026) updates Vietnam data center standards by referencing TCVN 9250:2021 and aligning with widely used frameworks such as ANSI/TIA-942-C:2024 and Uptime Institute practices, reinforcing Tier-oriented design and operational controls that influence switching, routing, and security architecture choices. For investors and developers, Decree 96/2026/ND-CP introduces a special investment procedure for projects in high-tech zones, streamlining approvals and expanding incentives, which is relevant for hyperscale and semiconductor-adjacent projects seeking faster licensing and build cycles.
Competitive Landscape
The Vietnam data center networking market combines state-owned telecom incumbents with multinational vendors that localise production. Viettel IDC’s 40% service share and VNPT’s cloud expansion give domestic firms purchasing scale, but they depend on Cisco, HPE, Juniper, and Huawei for switching, routing, and SDN controllers. Cisco’s relocation of 30% of its global hardware assembly to Vietnam strengthens supply resiliency and lowers import duties, enabling competitive pricing.
Strategic differentiation now hinges on AI optimisation and sustainability. Cisco’s Silicon One plus NVIDIA Spectrum-X stack targets energy-efficient 400 GbE neural-network training clusters, addressing ESG mandates. FPT’s AI Factory, built with NVIDIA and HPE, illustrates a Vietnamese integrator moving up the value chain. Specialist players such as Broadcom and Intel supply merchant silicon, while domestic firms like CMC Telecom develop SD-WAN overlays tailored to local compliance rules.
Market entry barriers remain moderate. Colocation operators procure off-the-shelf leaf-spine fabrics, letting new entrants like NTT and ST Telemedia establish footprints through greenfield builds. Conversely, edge-computing and SME cloud remain fragmented, creating white-space for startups focused on software-defined security or intent-based network analytics. Overall, competition is vigorous but not prohibitive, which sustains innovation for end-users of the Vietnam data center networking industry.
Vietnam Data Center Networking Industry Leaders
Cisco Systems Inc.
Arista Networks Inc.
Dell Technologies Inc.
Hewlett Packard Enterprise
Huawei Technologies Co. Ltd.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
AI-oriented and hyperscale campus build-out is a primary opportunity in Vietnam, since it increases demand for higher-bandwidth leaf-spine switching, optical interconnects, and low-latency security stacks. April 2026 approvals and announcements in major parks point to near-term momentum, including Ho Chi Minh City approvals for two hyperscale projects at Saigon Hi-Tech Park totaling nearly USD 1 billion (Evolution DC VN HCMC at 52 MW and StarMason at 60 MW) and CMC Corporation approval for a USD 250 million hyperscale data center at Saigon Hi-Tech Park with an initial 30 MW. In Hanoi, G-Group Technology Corporation announced a USD 300 million, 30 MW Tier III AI-specialized data center campus at Hoa Lac, while Viettel also publicized Hoa Lac 2 as an Uptime Tier III site with NVIDIA H200-class supercomputing, reinforcing the shift toward AI-ready network fabrics.
A second opportunity comes from compliance-driven network modernization linked to evolving data governance and national digital infrastructure programs. This lifts demand for secure, auditable data center networking and managed services. Decision 1091/QD-TTg (June 17, 2026) calls for the formation of at least 10 large-scale strategic technology enterprises to develop national digital infrastructure, including at least five new large-scale data centers, which creates room for suppliers to package switching, routing, SDN controllers, and security appliances into standardized reference architectures. In parallel, Decree 96/2026/ND-CP supports faster investment processing in high-tech zones, benefiting developers and operators that can execute repeatable network designs and then run them under PDPL-era privacy and cross-border transfer controls.
Recent Industry Developments
- July 2026: G-Group Technology Corporation received investment certificate for the US$300 million G-Campus AI-ready data center and high-tech complex in Hoa Lac Hi-Tech Park. The launch expands Vietnam's AI compute capacity and strengthens integration between data center development and the adjacent industrial park ecosystem.
- July 2026: Sembcorp Development received approval for a 90MW data center complex in Saigon Hi-Tech Park, Ho Chi Minh City, via StarMason joint venture with BB Holdings. The capacity addition in Ho Chi Minh City expands domestic data center scale and underpins cross-border collaboration within the regional cloud services network.
- July 2026: Saigon Asset Management SAM announced plans for the 150MW SAM DigitalHub, claimed to be Vietnam's largest data center campus, at VSIP. The project accelerates market scale and intensifies competition among developers by creating a new benchmark for campus sized deployments.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers networking hardware and related software used inside Vietnam-based data centers to move, manage, and secure traffic between racks, rows, and external links, and it is sized in revenue terms for the period analyzed.
Scope exclusions: It excludes servers, storage systems, facility power and cooling equipment, and telecom access services delivered outside the data center network.
Segmentation Overview
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- less than or equal to10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater than 100 GbE
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the country demand context and to anchor the model to observable infrastructure build indicators. We reviewed public sources such as Vietnam's MIC publications on digital infrastructure and telecom, GSO statistical releases, ITU indicators, and IEA power and electricity statistics to understand data growth drivers and supply constraints that can affect upgrades. We also used datasets and commentary from organizations such as the World Bank and ASEAN-related digital economy references to cross-check investment cycles and import reliance.
On the industry side, we relied on company filings, investor decks, and reputable press coverage to identify capacity announcements, new facility timelines, and typical refresh behavior in colocation and enterprise sites. Import and export shipment level data and a patent database were also selectively referenced to sense-check equipment flow and technology direction, and then assumptions were refined before primary validation. The desk sources listed are illustrative, and many other public references were used for data collection, cross-checking, and clarification.
Primary Interviews and Surveys
Primary work focused on confirming what is actually being bought in Vietnam data centers, and when those refreshes happen, since published infrastructure news does not always translate into near-term network spend. We spoke with a mix of operators, system integrators, distributors, and enterprise IT teams across key demand pockets in the country to validate adoption of higher-speed architectures, typical port mixes, and budgeting behavior. Inputs from these discussions were used to close gaps in utilization, price progression, and the timing of upgrades, and then totals were aligned back to desk signals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 15% |
| Mid tier: 54% | Functional/Unit leaders: 31% |
| Smaller Players: 15% | Managers: 54% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs addressable networking spend from Vietnam data center capacity additions and upgrade intensity, and then it is mapped to typical equipment refresh cycles. In practice, we linked the demand pool to indicators such as new data center builds and expansions, rack and power density trends, the shift toward 25 GbE and 100 GbE links, and the mix of colocation versus enterprise deployments, which changes how fast networks are refreshed.
To keep the totals realistic, the output was corroborated with selective bottom-up approximations, such as sampled price times volume checks for key device classes, distributor channel feedback on shipment momentum, and operator-level capex splits between compute and networking. Where a bottom-up view was incomplete for smaller sites, we filled gaps using adoption ratios observed in similar facilities and then rechecked the outcome with interview feedback.
For forecasting, we used scenario analysis supported by short-run smoothing on key drivers, since investment timing can move with permitting, power availability, and large customer commitments. The forward view was adjusted based on primary inputs around procurement lead times, expected speed migration, and price movements for high-speed ports and optics, which helped keep the forecast tied to buying behavior rather than headline capacity alone.
Data Validation & Update Cycle
Validation was handled through triangulation across independent signals, and then by reviewing outliers before sign-off. We compared the modeled networking spend against capacity announcements, observed import intensity, and practical refresh windows shared by respondents, and any large variance triggered a second pass on assumptions such as upgrade timing or the share of high-speed ports.
Before finalizing, the model goes through multi-step analyst reviews where calculations are checked for consistency across years and for abrupt jumps that do not match known build schedules. Reports are refreshed annually, with interim updates when material events occur, such as major facility announcements, regulatory changes, or sharp pricing moves. Before delivery, an analyst performs a fresh pass so clients receive the latest updated view.
Mordor Intelligence's Vietnam Data Center Networking Market Size Compared Against Other Published Estimates
Published market values for Vietnam data center networking often vary because sources do not always size the same spend pool, and they also differ on base year, price assumptions, and how quickly they reflect new project announcements.
Managed network services and broader enterprise campus upgrades sit outside Mordor Intelligence's scope here, which is why estimates that bundle services or non data center networks can look higher even when they cite similar demand drivers.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 456.59 M (2025) | |
| Regional Consultancy A | USD 501.00 M (2023) | Uses an earlier base year and appears to include software and services alongside equipment, which can inflate totals when services are priced as recurring revenue. |
| Industry Portal B | USD 427.36 M (2022) | Likely reflects a narrower equipment basket and older price points, and it may not capture the post-2022 step-up in higher-speed upgrades and new facility timelines. |
Overall, the spread is mainly explained by what gets counted as networking spend, and by how quickly each estimate updates prices and speed-migration timing. By keeping the scope tied to in-data-center networking revenue and then validating upgrade intensity with operator and channel feedback, the estimate remains traceable to clear drivers and repeatable checks.


Key Questions Answered in the Report
How large is the Vietnam data center networking market today?
The Vietnam data center networking market reached USD 487.44 million in 2026 and is projected to hit USD 676.63 million by 2031.
Which component category is expanding the fastest?
Services will grow at 6.88% CAGR to 2031, driven by demand for design, integration, and managed network operations.
Why are greater than 100 GbE deployments accelerating?
AI workloads, hyperscale builds, and new submarine cables require ultra-high throughput, moving many operators directly to 400 GbE classes.
What role do localization laws play in market growth?
Rules mandating domestic storage of Vietnamese user data compel foreign and local firms to build in-country facilities, boosting hardware and services demand.
Page last updated on:
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Construction Market Construction worldwide, split by tier, facility size and facility type.
- Vietnam Data Center Storage Market Vietnam storage, split by storage technology, storage type and facility type.
- Vietnam Data Center Rack Market Vietnam's racks, split by facility size and tier.
- Vietnam Data Center Power Market Vietnam power systems, split by component, facility type and facility size.
- Indonesia Data Center Processor Market Processors demand across Indonesia, covering processor type, application and architecture.
- Mexico Data Center Cooling Market Cooling in Mexico, split by cooling technology, type and end-user industry.
- Vietnam Hyperscale Data Center Market Hyperscale sites in Vietnam, split by facility type, component and tier.





