
Sinus Dilation Devices Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 3.5 Billion |
| Market Size (2031) | USD 5.15 Billion |
| Growth Rate (2026 - 2031) | 8.02 % CAGR |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order. Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. |

Sinus Dilation Devices Market Analysis by Mordor Intelligence
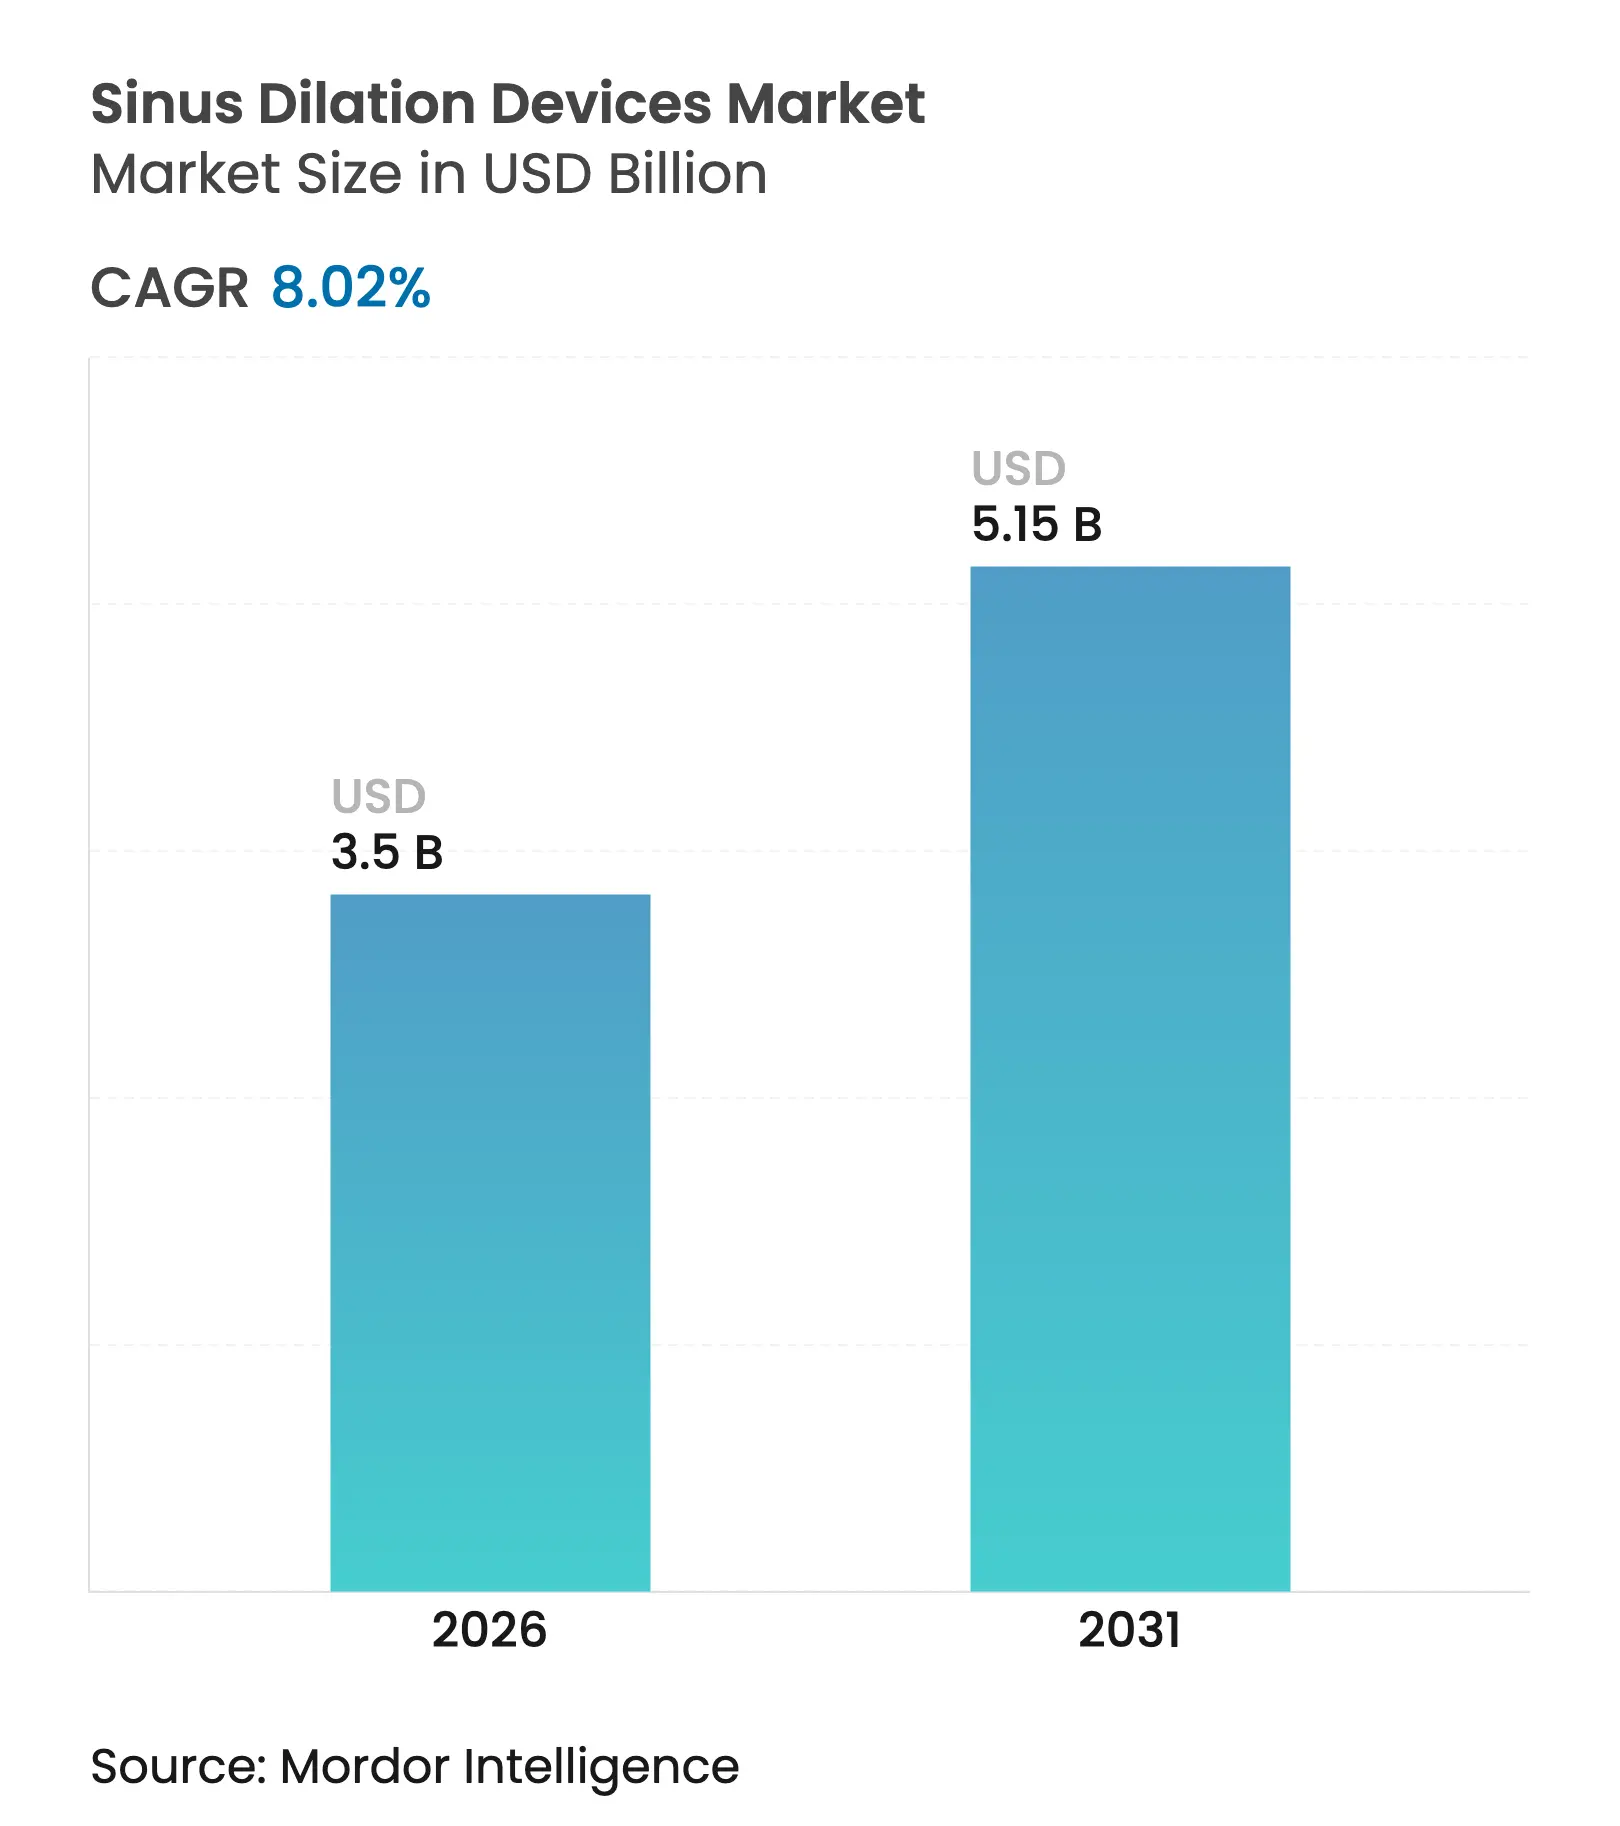
The sinus dilation devices market size was valued at USD 3.24 billion in 2025 and estimated to grow from USD 3.5 billion in 2026 to reach USD 5.15 billion by 2031, at a CAGR of 8.02% during the forecast period (2026-2031). The shift from traditional functional endoscopic sinus surgery to balloon-based techniques is anchored in rising chronic rhinosinusitis prevalence, rapid device innovation, and an accelerating move toward office-based care that lowers overall treatment costs. Demand receives further support from drug-eluting implants that keep sinuses patent, AI-guided navigation systems that raise first-pass success, and payer policies that reimburse minimally invasive approaches across major markets. Hospitals still perform most procedures, yet ENT specialty clinics are gaining ground as focused care delivery models show better patient flow and shorter wait times. Regionally, North America holds leadership through well-defined reimbursement codes, while Asia Pacific shows the steepest adoption curve as infrastructure rises and an aging population drives need.
Key Report Takeaways
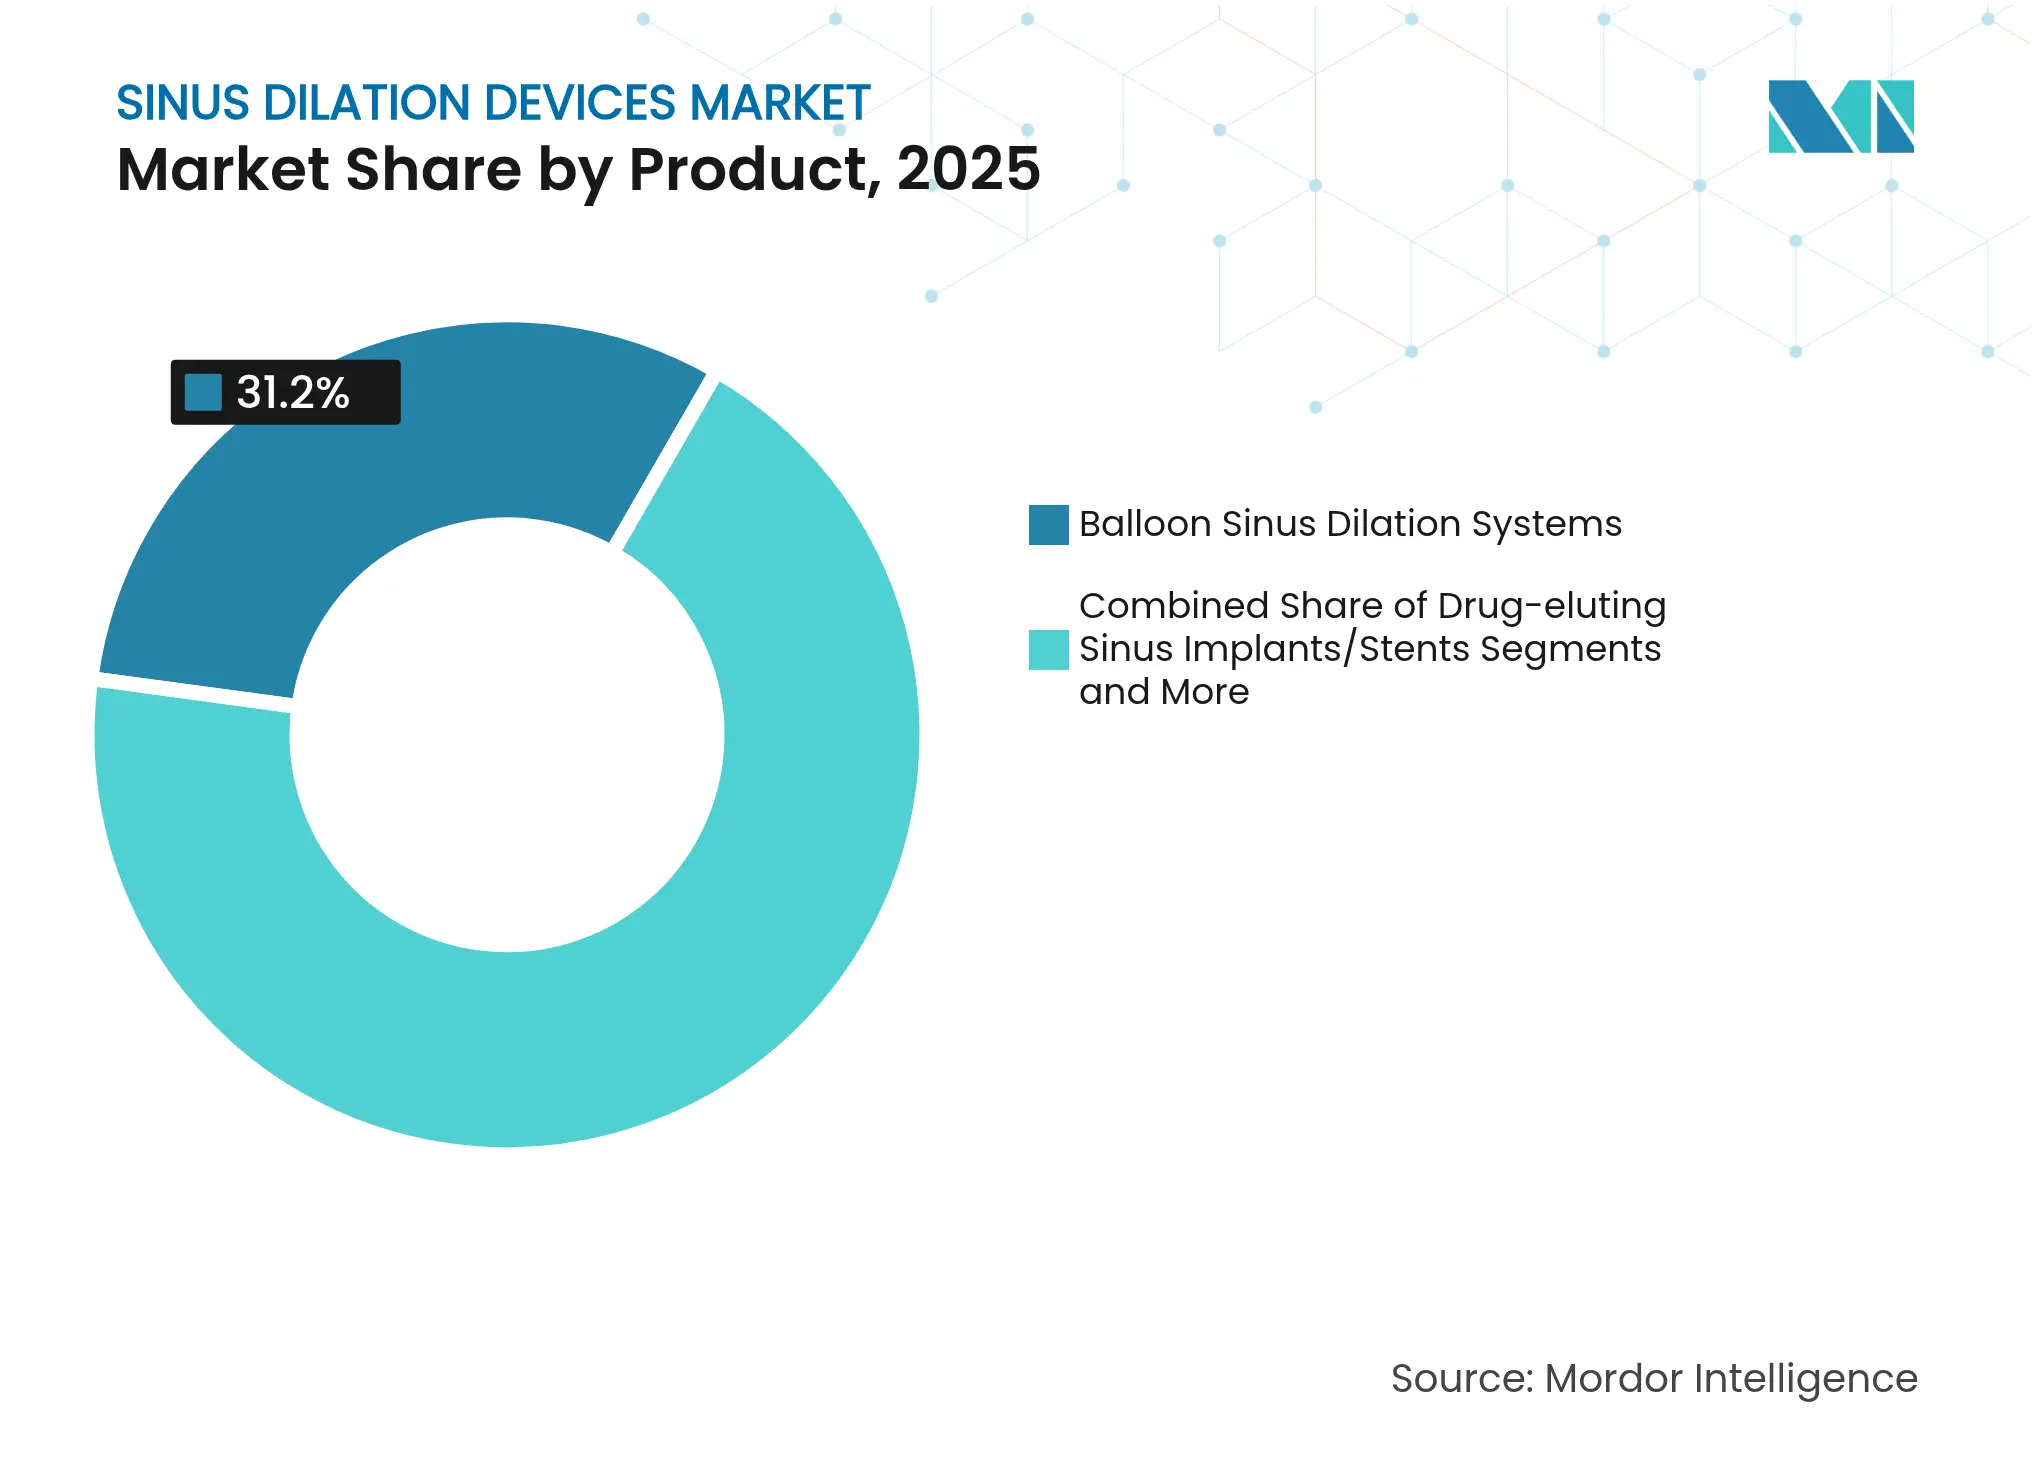
- By product category, balloon sinus dilation systems secured 31.20% of the sinus dilation devices market share in 2025, while navigation software and AI solutions are projected to expand at an 11.23% CAGR to 2031.
- By procedure, stand-alone sinus dilation devices captured 31.60% of the sinus dilation devices market share in 2025; office-based procedures are poised to register the highest growth at a 10.72% CAGR through 2031.
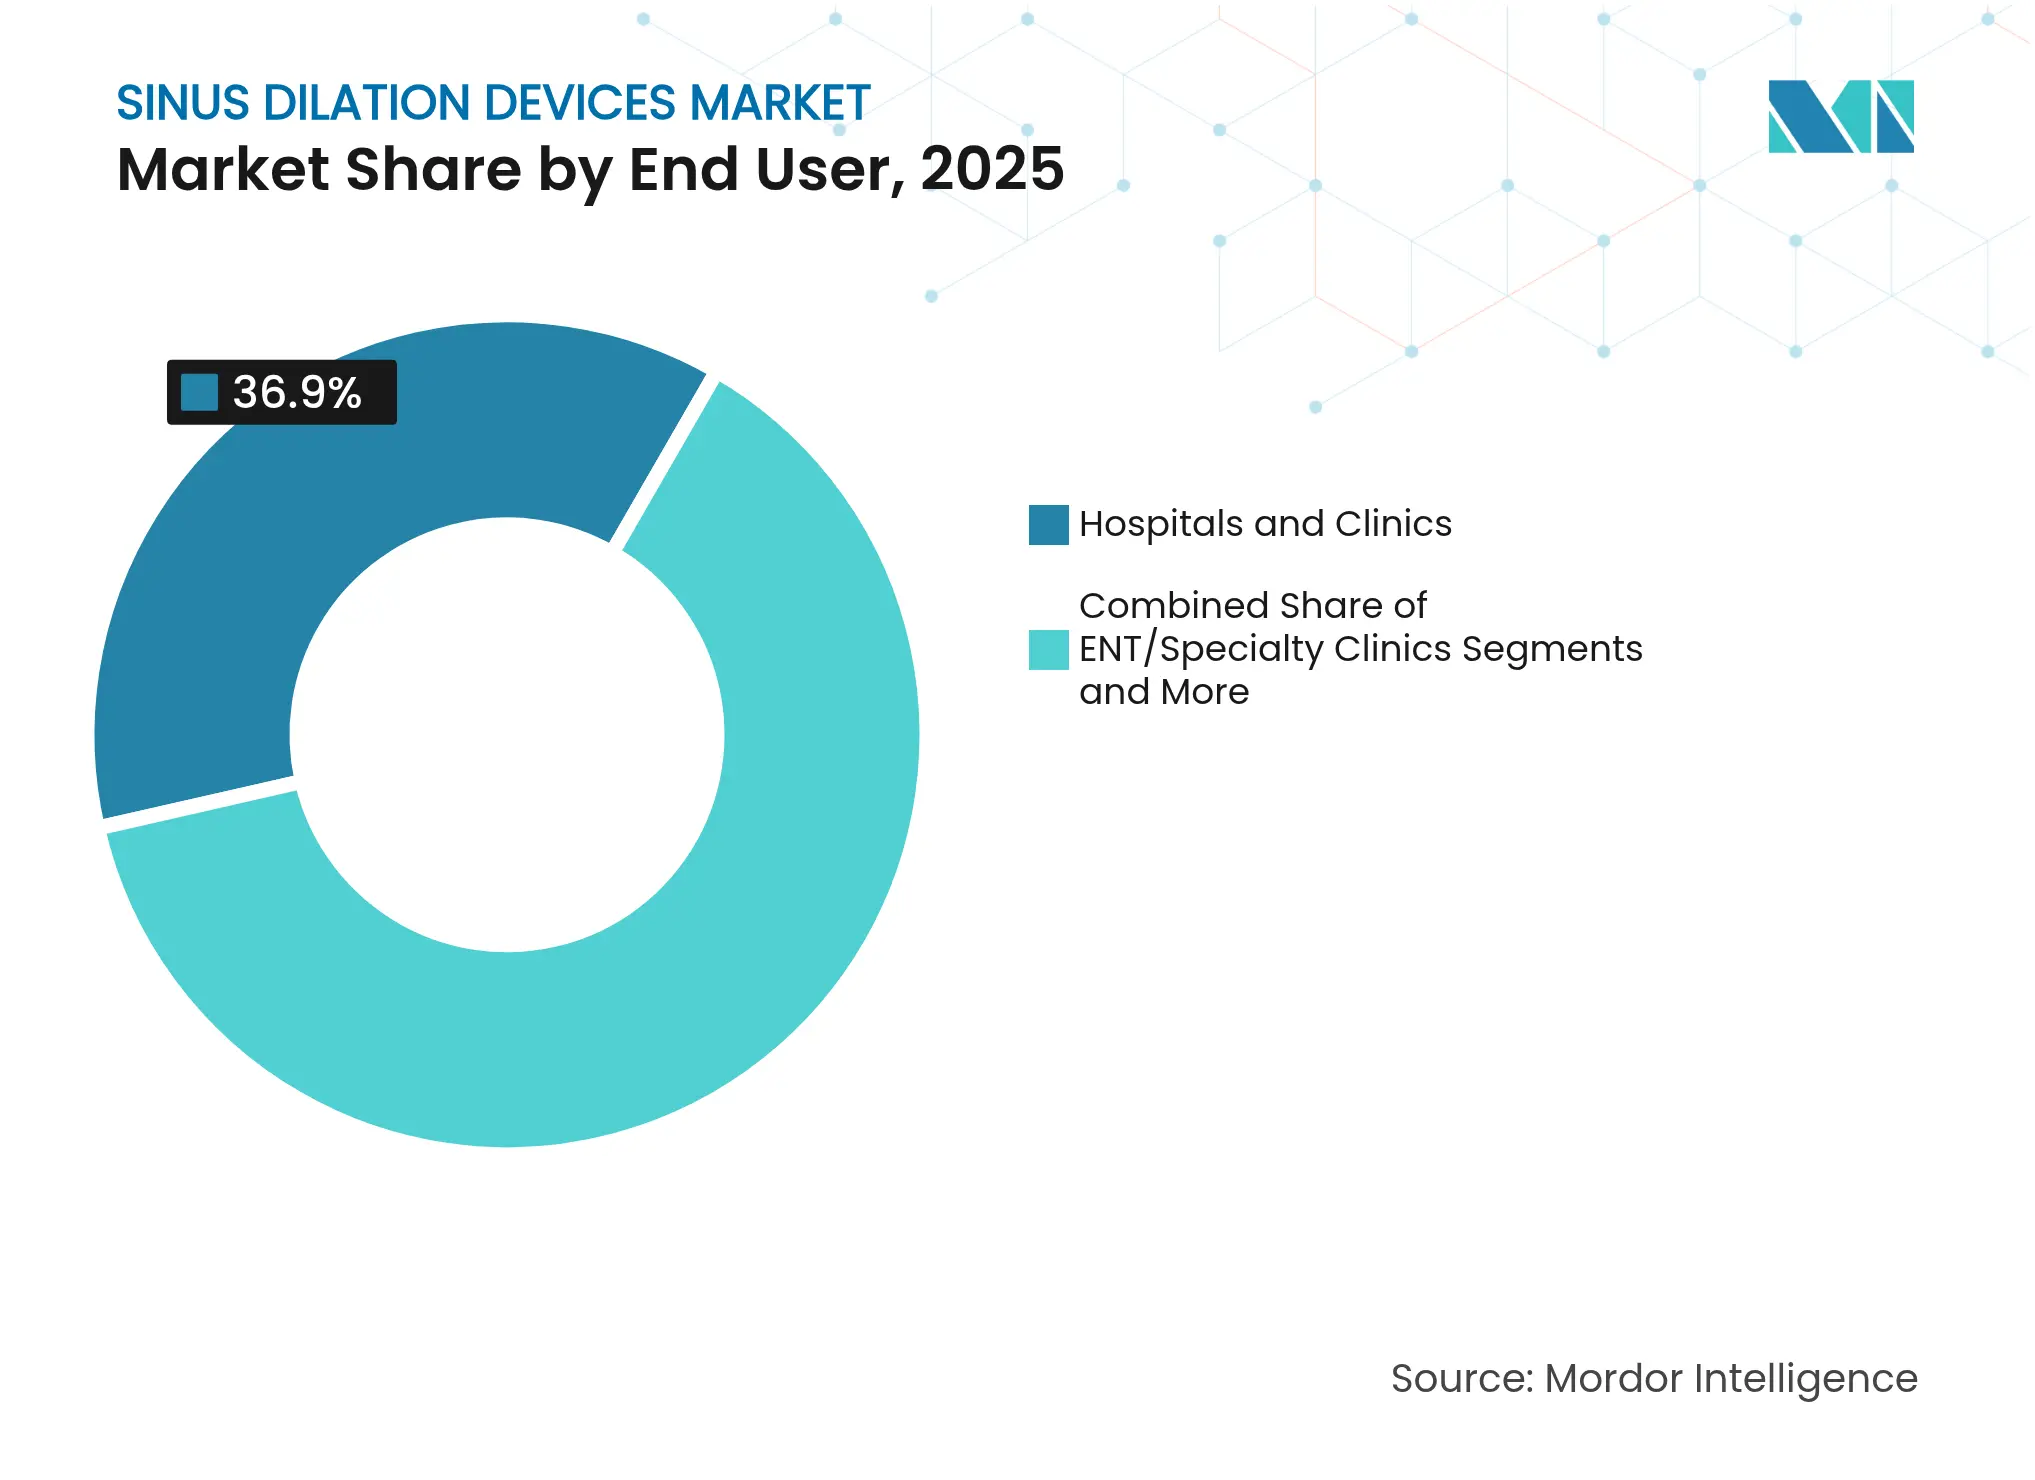
- By end-user, hospitals and clinics commanded 36.90% of the sinus dilation devices market size in 2025, whereas ENT specialty clinics are forecast to grow at an 8.65% CAGR between 2026 and 2031.
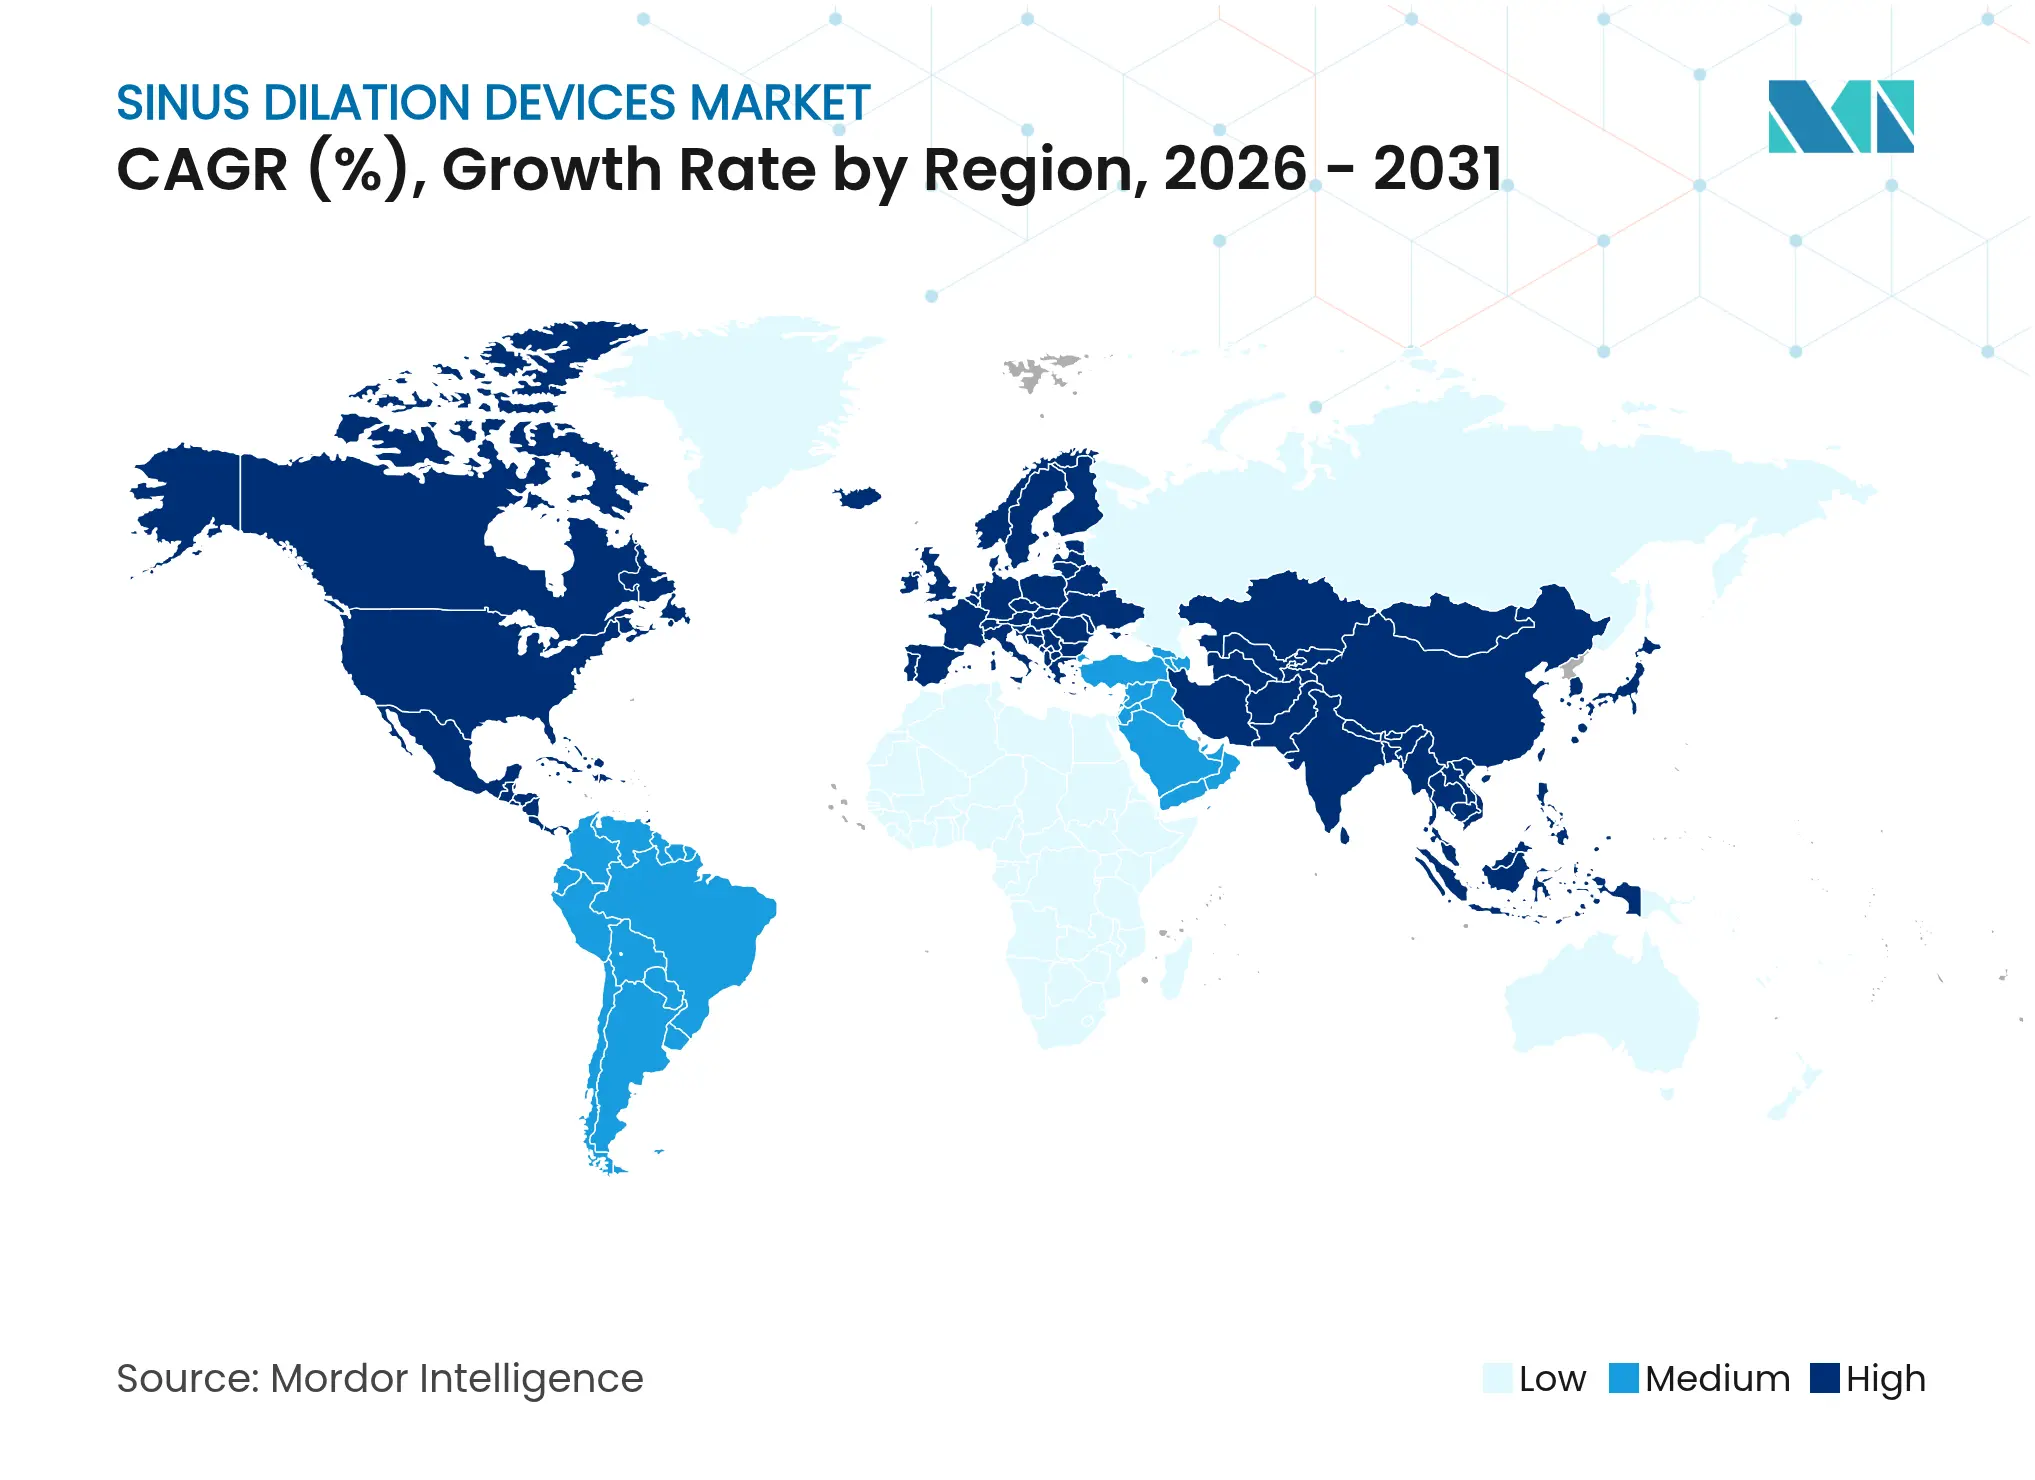
- By geography, North America accounted for 30.00% of the sinus dilation devices market size in 2025, while Asia Pacific is expected to be the fastest-growing region with a 9.43% CAGR over the same period.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence's proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Sinus Dilation Devices Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
Rising prevalence of chronic rhinosinusitis | +1.80% | Global; stronger in North America and Europe | Long term (≥ 4 years) |
Growing preference for minimally invasive sinus dilation devices | +2.10% | Global; led by developed markets | Medium term (2-4 years) |
Technological advances in drug-eluting stents and image-guided systems | +1.50% | North America and EU core; expanding to Asia Pacific | Medium term (2-4 years) |
Favorable reimbursement policies in the US and EU | +1.20% | North America and Europe | Short term (≤ 2 years) |
Shift toward office-based ENT procedures that lower total cost | +0.90% | North America; gaining in developed Asia Pacific markets | Short term (≤ 2 years) |
AI-enabled endoscopic visualization that improves first-pass success | +0.80% | North America and EU; early uptake in Japan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Prevalence of Chronic Rhinosinusitis
Chronic rhinosinusitis affects 12% of adults worldwide, expanding the candidate pool for sinus dilation device procedures. Environmental factors such as pollution and urban living intensify mucosal inflammation and shorten the time to surgical intervention when medication fails. Clinical guidance now positions balloon dilation earlier in the treatment pathway, increasing overall procedure volume. Aging populations in developed regions add to the burden, correlating with higher per-capita treatment rates. The resulting uptick in surgical demand boosts device sales and encourages new product launches that target durability and ease of use.
Growing Preference for Minimally Invasive Sinus dilation devices
Patients favor procedures that limit tissue trauma and shorten recovery, prompting a steady migration from conventional sinus surgery to balloon-based dilation. Clinical studies note lower complication rates and a return-to-work window measured in days rather than weeks. Office-based feasibility eliminates general anesthesia and reduces facility fees, easing both payer costs and patient copays. Coverage uniformity across major private insurers lowers financial uncertainty for providers. These dynamics combine to accelerate uptake across hospitals, ambulatory surgery centers, and physician offices.
Technological Advances: Drug-Eluting Stents and Image-Guided Systems
Drug-eluting sinus implants sustain localized steroid delivery for up to 90 days, maintaining ostial patency and cutting revision rates.[1] AI-driven navigation platforms overlay intraoperative imagery onto patient anatomy, raising accuracy and shortening learning curves for newer surgeons.[2]The merger of real-time imaging and balloon dilation allows precise deployment while preserving the mucosa. Demand for these integrated systems bolsters premium pricing and skews purchasing decisions toward vendors with robust R&D pipelines.
Favorable Reimbursement Policies in the US and EU
Medicare retains status-quo payment for balloon dilation under the 2025 Physician Fee Schedule, assuring providers' financial viability.[3] Clear CPT codes streamline billing, reduce claim denial rates, and encourage more physicians to add the service line. European payers conduct cost-effectiveness reviews that place balloon procedures ahead of conventional surgery on total cost and quality-adjusted life-year metrics, solidifying access within national health systems. Stable reimbursement frameworks lower adoption barriers and support continuous volume growth.
Restraints Impact Analysis of Sinus Dilation Devices Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
Peri-operative risks and post-operative complications | -0.70% | Global; higher in emerging markets | Short term (≤ 2 years) |
Shortage of skilled otolaryngologists in emerging nations | -1.10% | Asia Pacific emerging markets, Middle East and Africa, Latin America | Long term (≥ 4 years) |
Average selling price compression from low-cost Asian OEM devices | -0.90% | Global; pronounced in price-sensitive markets | Medium term (2-4 years) |
EU-MDR uncertainty for biodegradable sinus implants | -0.60% | Europe; spillover to other regulated markets | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Peri-Operative Risks and Post-Operative Complications
Although generally safe, balloon dilation can cause orbital injury, cerebrospinal fluid leak, or bleeding when performed without adequate visualization. MAUDE reports cite stent migration and mucosal irritation linked to corticosteroid-eluting implants. Variability in surgeon skill magnifies these risks, especially in settings with limited training resources. Safety concerns may delay adoption in health systems that demand robust outcome data before switching to new techniques. Structured training and clear patient selection criteria remain essential to mitigate complications.
Shortage of Skilled Otolaryngologists in Emerging Nations
Many emerging economies face a low otolaryngologist-to-population ratio that restricts procedure availability. Training programs require time and investment, while brain drain sends specialists to higher-income regions. Limited access slows sinus dilation devices market penetration despite high disease prevalence. Partnerships that combine remote mentoring, simulation centers, and short-course certification aim to close the gap but will take years to mature.
Sinus Dilation Devices Market Segment Analysis
By Product: Navigation Systems Drive Innovation
Balloon sinus dilation systems continue to hold 31.20% of the sinus dilation devices market in 2025, reflecting their role as the procedural cornerstone. Navigation software, AI consoles, and real-time imaging hardware, however, are forecast to record an 11.23% CAGR and are pulling the overall sinus dilation devices market toward data-rich, precision-guided workflows. Drug-eluting implants that deliver mometasone furoate for three months reduce revision surgery and open new revenue channels with premium margins. Hand-held dilation tools remain important in cost-constrained settings, ensuring that lower-income markets can still access the therapy.
Accessories and consumables generate predictable revenue for manufacturers. Single-use balloons, guidewires, and irrigation kits form the bulk of procedural spend. Hybrid devices that blend balloon dilation with drug release occupy a growing niche, allowing providers to justify higher per-case reimbursement. The strong link between consumable pull-through and capital unit placement encourages suppliers to create leasing and service models that lower upfront costs and secure long-term account loyalty. The sinus dilation devices market size contribution from high-margin navigation platforms is expected to widen as hospitals refresh fleets to meet digital surgery initiatives.
Note: Segment shares of all individual segments available upon report purchase
By Procedure: Office-Based Growth Accelerates
Stand-alone balloon dilation accounted for 31.60% of the sinus dilation devices market in 2025, yet office-based cases are projected to rise at a 10.72% CAGR due to economic benefits and patient convenience. In-office deployment slashes facility fees and enables same-day discharge, which resonates with payers aiming to control episodic costs. Comparative studies show non-inferior outcomes to operating-room procedures, supporting insurer confidence. The sinus dilation devices market size captured by office settings is therefore expected to expand steadily through 2031.
Hybrid balloon plus FESS techniques remain important for complex anatomies that require both dilation and tissue removal. These combined approaches broaden indications beyond simple ostial blockage, allowing surgeons to tailor interventions per patient. The procedural mix fuels demand for modular instrument sets that can pivot between dilation and resection without costly re-sterilization cycles. Educational workshops and cadaver labs sponsored by device firms aim to shorten learning curves and encourage hybrid adoption.
By End-User: Specialty Clinics Gain Momentum
Hospitals and multispecialty clinics retained 36.90% of the sinus dilation devices market share in 2025, but ENT-dedicated clinics are forecast to outpace them at an 8.65% CAGR. Specialty centers centralize expertise and sustain higher procedural volumes that translate into greater proficiency and patient satisfaction. These facilities often bundle diagnostic imaging and surgery in one visit, improving throughput. The sinus dilation devices market benefits as streamlined workflows permit more cases per day without compromising outcomes.
Ambulatory surgery centers and physician offices leverage lower overhead to offer competitive pricing. Capital-light platforms—such as cart-based navigation coupled with disposable balloons, fit compact spaces and appeal to independent practitioners. Pay-for-performance reimbursement structures further reward practices that demonstrate reduced infection rates and shorter recovery times. As ENT clinics build brand equity around minimally invasive care, referrals shift away from general hospitals, cementing the long-term growth path for this end-user segment.
Note: Segment shares of all individual segments available upon report purchase
Geography Analysis
North America Sinus Dilation Devices Market
North America accounted for USD 0.97 billion of the sinus dilation devices market size in 2025 and maintained 30.00% share thanks to CPT-coded reimbursement, mature surgeon training programs, and widespread adoption of AI-enhanced navigation. Canada’s single-payer system supports consistent access, while Mexico’s private hospitals drive cross-border procedure volumes.
Europe Sinus Dilation Devices Market
Europe follows with a diversified payer landscape; Germany, the United Kingdom, France, Italy, and Spain lead uptake under national health insurance frameworks that recognize the cost-benefit of minimally invasive sinus care. EU-MDR compliance, however, introduces timelines that may slow the rollout of biodegradable implants, affecting near-term growth.
APAC Sinus Dilation Devices Market
Asia Pacific posts the fastest trajectory at 9.43% CAGR. China’s regulatory reforms streamline device approvals, and provincial reimbursement pilots improve affordability. Japan’s aging population and preference for technology drive premium platform sales, whereas India focuses on cost-effective dilation kits paired with training programs that expand specialist coverage. Combined, these factors are set to lift regional revenue past Europe by 2030, reinforcing Asia Pacific as the primary incremental contributor to global sinus dilation devices market expansion.
Competitive Landscape
Market Concentration
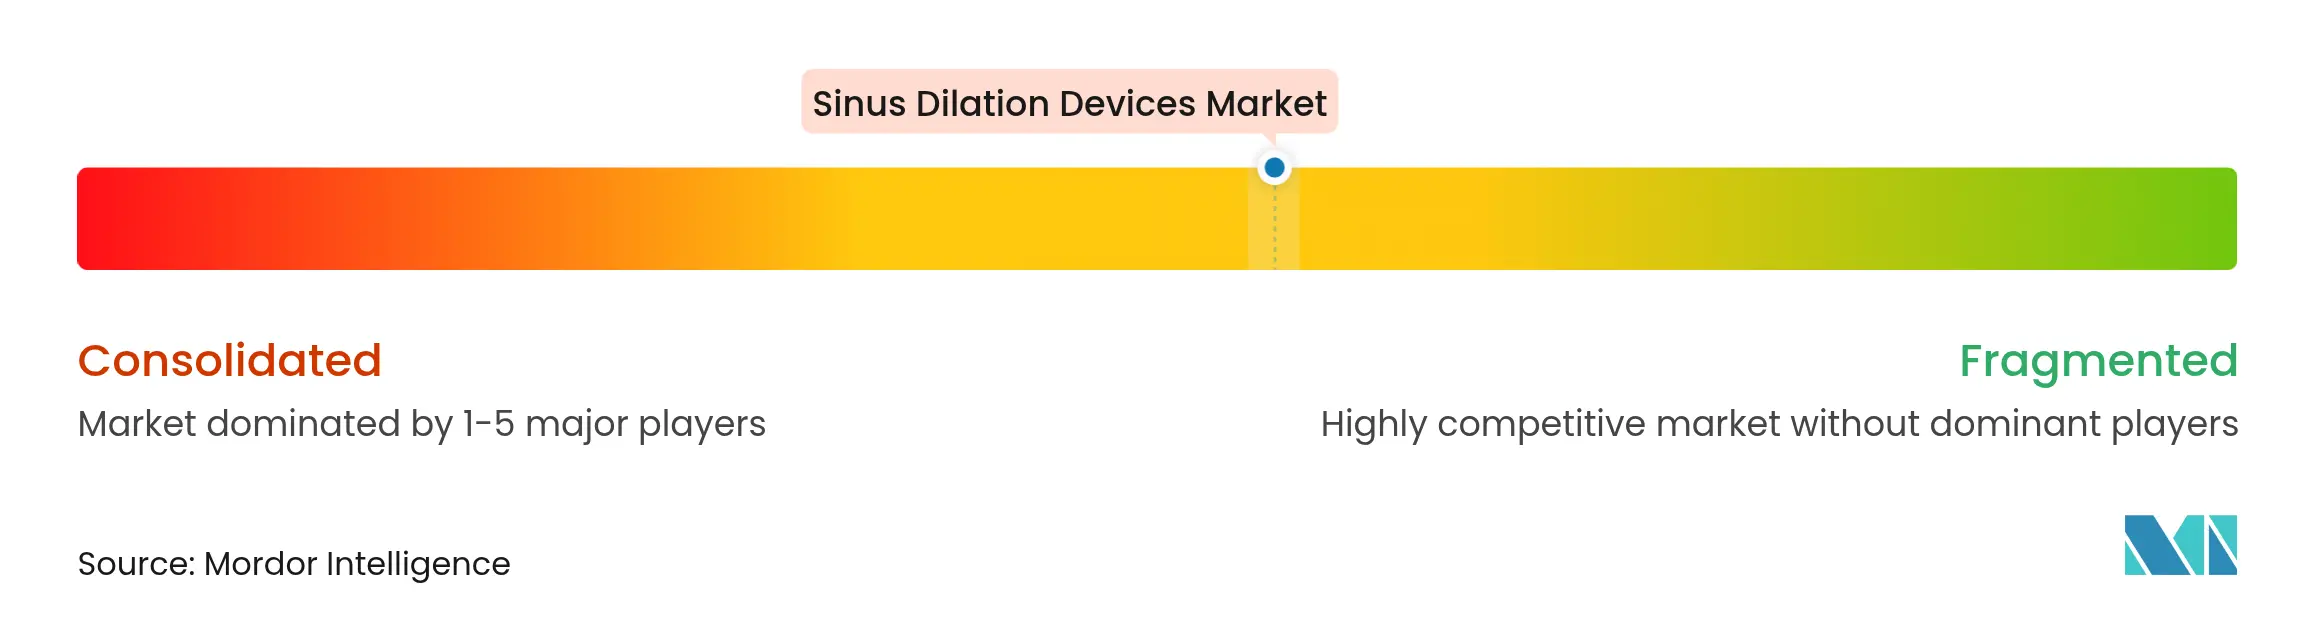
The sinus dilation devices market shows moderate consolidation. In 2024, Integra LifeSciences acquired Acclarent from Johnson & Johnson for USD 280 million, adding an estimated USD 1 billion to its addressable ENT portfolio. Medtronic strengthened its drug-eluting offerings through the purchase of Intersect ENT, while Stryker refined its XprESS system to improve seeker-based control during dilation.
Mid-tier players such as Smith & Nephew, SinuSys, and Meril Life Sciences pursue differentiated niches that include pediatric-sized balloons and cost-optimized kits for emerging markets. AI navigation remains a white-space opportunity; companies that pair software algorithms with proprietary hardware expect premium valuation multiples. Price competition from domestic Asian OEMs challenges multinationals, prompting a pivot toward service contracts, data analytics packages, and surgeon education programs designed to lock in customer loyalty.
White-label manufacturing partnerships enable regional newcomers to compete quickly, yet regulatory know-how and brand recognition still favor incumbents in markets with strict oversight. Strategic alliances that combine navigation software, drug delivery, and disposable instrumentation are emerging as the next layer of competitive differentiation.
Sinus Dilation Devices Industry Leaders

*Disclaimer: Major Players sorted in no particular order
Sinus Dilation Devices Market Companies Covered in this Report
- Medtronic
- Johnson & Johnson (Acclarent)
- Stryker Corporation (Entellus)
- Smiths Group
- Olympus
- Intersect ENT
- SinuSys
- Meril Life Science
- Intersect ENT
- Dalent Medical
- InnAccel Technologies
- Accurate Surgical & Scientific Instruments
- Karl Storz
- Summit Medical LLC
- Boston Scientific
- Olympus
- OptiNose Inc.
- Bentley Innomed GmbH
- Jilin Coronado Medical Equipment Co.
- Chengdu Mechan Electronic Technology
Recent Industry Developments in Sinus Dilation Devices Market
- February 2025: Teleflex agreed to acquire BIOTRONIK’s Vascular Intervention business for EUR 760 million, underscoring consolidation across interventional device segments.
- April 2024: Integra LifeSciences completed the USD 280 million takeover of Acclarent, expanding its sinus surgery portfolio.
- March 2024: FDA approved XHANCE fluticasone propionate nasal spray, the first drug specifically indicated for chronic rhinosinusitis.
- September 2024: Stryker launched an upgraded MiniFESS portfolio that increases balloon flexibility and reduces procedure time.
Table of Contents for Sinus Dilation Devices Industry Report
1. Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2. Research Methodology
3. Executive Summary
4. Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence Of Chronic Rhinosinusitis
- 4.2.2 Growing Preference For Minimally?Invasive Balloon Sinuplasty
- 4.2.3 Technological Advances: Drug-Eluting Stents & Image-Guided Systems
- 4.2.4 Favorable Reimbursement Policies In The US & EU
- 4.2.5 Shift Toward Office-Based ENT Procedures Lowers Total Treatment Cost
- 4.2.6 AI-Enabled Endoscopic Visualization Improving First-Pass Success
- 4.3 Market Restraints
- 4.3.1 Peri-Operative Risks & Post-Operative Complications
- 4.3.2 Shortage Of Skilled Otolaryngologists In Emerging Nations
- 4.3.3 ASP Compression From Influx Of Low-Cost Asian OEM Devices
- 4.3.4 EU-MDR Uncertainty For Biodegradable Sinus Implants
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5. Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Balloon Sinus Dilation Systems
- 5.1.2 Drug-eluting Sinus Implants/Stents
- 5.1.3 Hand-held Dilatation Instruments
- 5.1.4 Endoscopes & Navigation Systems
- 5.1.5 Accessories & Consumables
- 5.1.6 Other Products
- 5.2 By Procedure
- 5.2.1 Standalone Balloon Sinuplasty
- 5.2.2 Hybrid Balloon + FESS Procedures
- 5.3 By End-User
- 5.3.1 Hospitals
- 5.3.2 ENT / Specialty Clinics
- 5.3.3 Ambulatory Surgical Centers
- 5.3.4 Office-based Physician Practices
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
6. Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products, and Recent Developments)
- 6.3.1 Medtronic Plc
- 6.3.2 Johnson & Johnson (Acclarent)
- 6.3.3 Stryker Corporation (Entellus)
- 6.3.4 Smith & Nephew plc
- 6.3.5 Olympus Corporation
- 6.3.6 Intersect ENT Inc.
- 6.3.7 SinuSys Corporation
- 6.3.8 Meril Life Sciences Pvt. Ltd.
- 6.3.9 Dalent Medical
- 6.3.10 InnAccel Technologies
- 6.3.11 Accurate Surgical & Scientific Instruments
- 6.3.12 KARL STORZ SE & Co. KG
- 6.3.13 Summit Medical LLC
- 6.3.14 Boston Scientific Corporation
- 6.3.15 OptiNose Inc.
- 6.3.16 Bentley Innomed GmbH
- 6.3.17 Jilin Coronado Medical Equipment Co.
- 6.3.18 Chengdu Mechan Electronic Technology
7. Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment
Sinus Dilation Devices Market Report Scope and Research Methodology
Market Definition and Coverage
Our study defines the sinus dilation devices market as the global sales revenue generated from single-use or reusable balloon sinus dilation systems, drug-eluting stents, handheld dilators, endoscopes with navigation, and essential accessories that physically enlarge paranasal sinus ostia in chronic rhinosinusitis patients.
Scope exclusion: pharmacological decongestants, steroid sprays, and any postoperative drug therapy are not counted.
Segments Covered in This Report
- By Product
- Balloon Sinus Dilation Systems
- Drug-eluting Sinus Implants/Stents
- Hand-held Dilatation Instruments
- Endoscopes & Navigation Systems
- Accessories & Consumables
- Other Products
- Balloon Sinus Dilation Systems
- By Procedure
- Standalone Balloon Sinuplasty
- Hybrid Balloon + FESS Procedures
- Standalone Balloon Sinuplasty
- By End-User
- Hospitals
- ENT / Specialty Clinics
- Ambulatory Surgical Centers
- Office-based Physician Practices
- Hospitals
- Geography
- North America
- United States
- Canada
- Mexico
- United States
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Germany
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- China
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- GCC
- South America
- Brazil
- Argentina
- Rest of South America
- Brazil
- North America
Data Sources, Market Sizing, and Validation
Primary Research
Mordor analysts interviewed practicing rhinologists, ambulatory surgery center managers, and procurement heads across North America, Europe, and Asia. The discussions clarified office-based versus hospital adoption shifts, realistic price concessions, and procedure mix changes, thereby refining model coefficients and validating secondary assumptions.
Desk Research
We started with publicly available clinical registries, national procedure volumes from agencies such as the US HCUP and NHS HES, customs shipment codes for balloon catheters, and incidence estimates from the Global Burden of Disease database. Trade association white papers from AAO-HNS, peer-reviewed ENT journals, and device 10-K filings supplied adoption rates and median selling prices. Where granular company data was scarce, subscription feeds from D&B Hoovers, Dow Jones Factiva, and Questel helped triangulate revenue signals and patent pipelines. This list is illustrative; many other open and paid sources informed our desk work.
Market-Sizing & Forecasting
Bottom-up builds of annual procedures by country, multiplied by average selling price and adjusted for reuse factors, provided the first estimate. A top-down cross-check using chronic sinusitis prevalence, surgical penetration rates, and capacity utilization of ENT suites flagged outliers, which were then reconciled. Key variables include: (1) chronic sinusitis prevalence per 100,000 adults, (2) balloon sinuplasty share of total functional endoscopic sinus surgeries, (3) average device reuse ratio, (4) ASP erosion from tenders, and (5) outpatient shift percentage. Forecasts employ multivariate regression blended with scenario analysis; prevalence and ASP trends drive the base case, while expert-elicited high and low adoption scenarios bound uncertainty.
Data Validation & Update Cycle
Every iteration passes a two-analyst peer review that benchmarks outputs against fresh regulatory filings and quarterly device revenues. Material divergences trigger re-contact with select experts. Reports refresh annually, and any major recall, reimbursement revision, or M&A event prompts an interim update before client delivery.
How Mordor Intelligence's Sinus Dilation Devices Market Size Compares to Other Published Estimates
Published figures vary because firms pick differing device lists, price assumptions, and refresh cadences.
Scope breadth, base year exchange rates, and how reused instruments are discounted also widen gaps.
Benchmark comparison
| Market Size | Anonymized source | Primary gap driver |
|---|---|---|
USD 3.24 B | Mordor Intelligence | - |
USD 3.63 B | Global Consultancy A | Includes nasal drug implants and counts diagnostic endoscopes, inflating totals |
USD 3.15 B | Trade Journal B | Applies uniform ASPs across regions and uses 2024 exchange rates without adjustment |
USD 2.86 B | Industry Publisher C | Excludes physician-office procedures and assumes 10% higher device reuse |
