
- Argentina
- Australia
- Austria
- Bahrain
- Bangladesh
- Cambodia
- Chile
- China
- Denmark
- Egypt
- Europe
- France
- Germany
- India
- Indonesia
- Israel
- Italy
- Japan
- Kuwait
- Malaysia
- Mexico
- Myanmar
- New Zealand
- Nigeria
- Oman
- Philippines
- Qatar
- Singapore
- South Africa
- Spain
- Sweden
- Thailand
- Turkey
- United Arab Emirates
- United Kingdom
- United States
- Vietnam
Saudi Arabia ICT Market Analysis by Mordor Intelligence
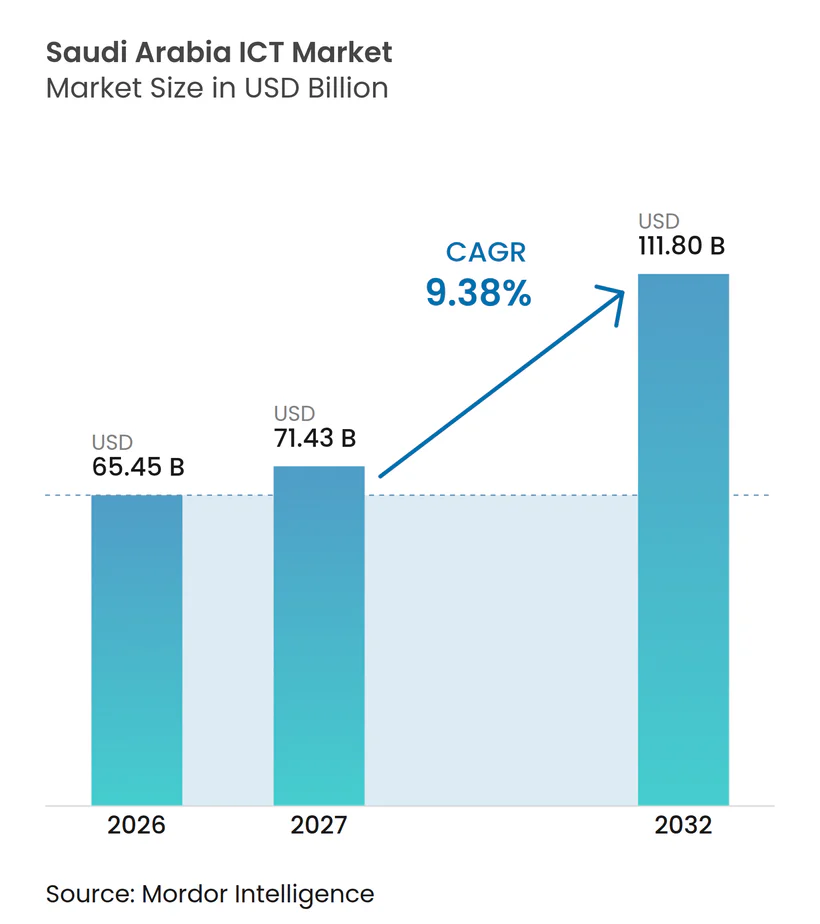
The Saudi Arabia ICT market size was valued at USD 65.45 billion in 2026 and estimated to grow from USD 71.43 billion in 2027 to reach USD 111.8 billion by 2032, at a CAGR of 9.38% during the forecast period (2027-2032).
Public-sector digitization in Saudi Arabia and demand for home broadband connect infrastructure investment with ongoing use of cloud and communications services. Industrial fleet applications add implementation opportunities, while available AI capacity enables specialized workloads. Government agencies and home-broadband households need providers able to operate these services, making delivery capability a competitive differentiator. Shortages of emerging digital skills and restrictions on transferring government data abroad favor suppliers combining delivery teams with Saudi hosting capacity, except where Saudi law or regulation expressly permits overseas transfers.
Key Report Takeaways
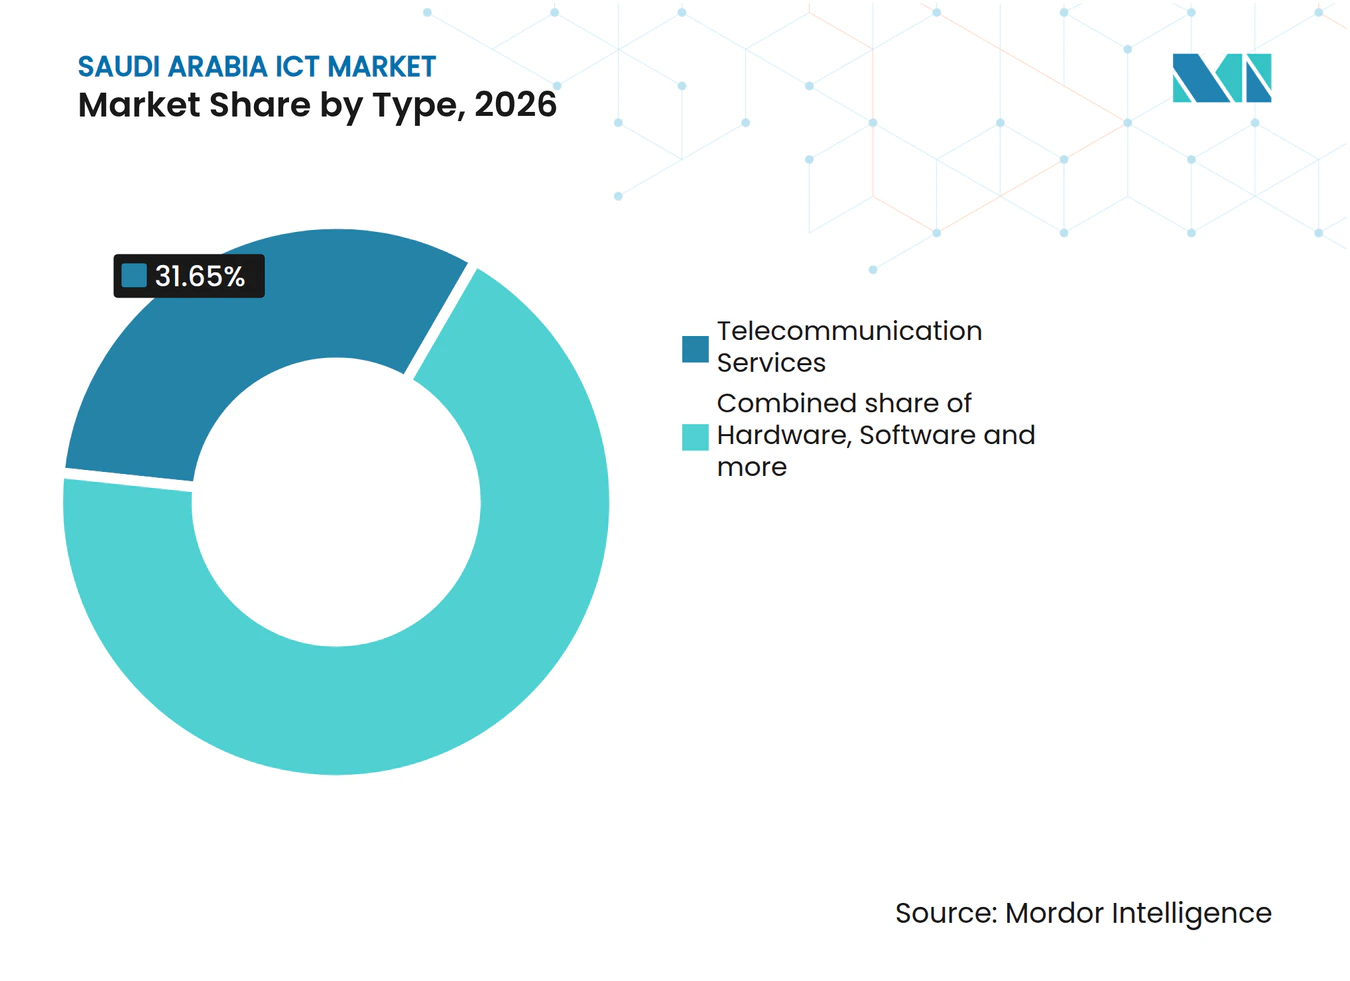
- By type, telecommunication services led with a 31.65% Saudi Arabia ICT market share in 2026, while software is forecast to be the fastest-growing segment at a 9.78% CAGR during 2027-2032.
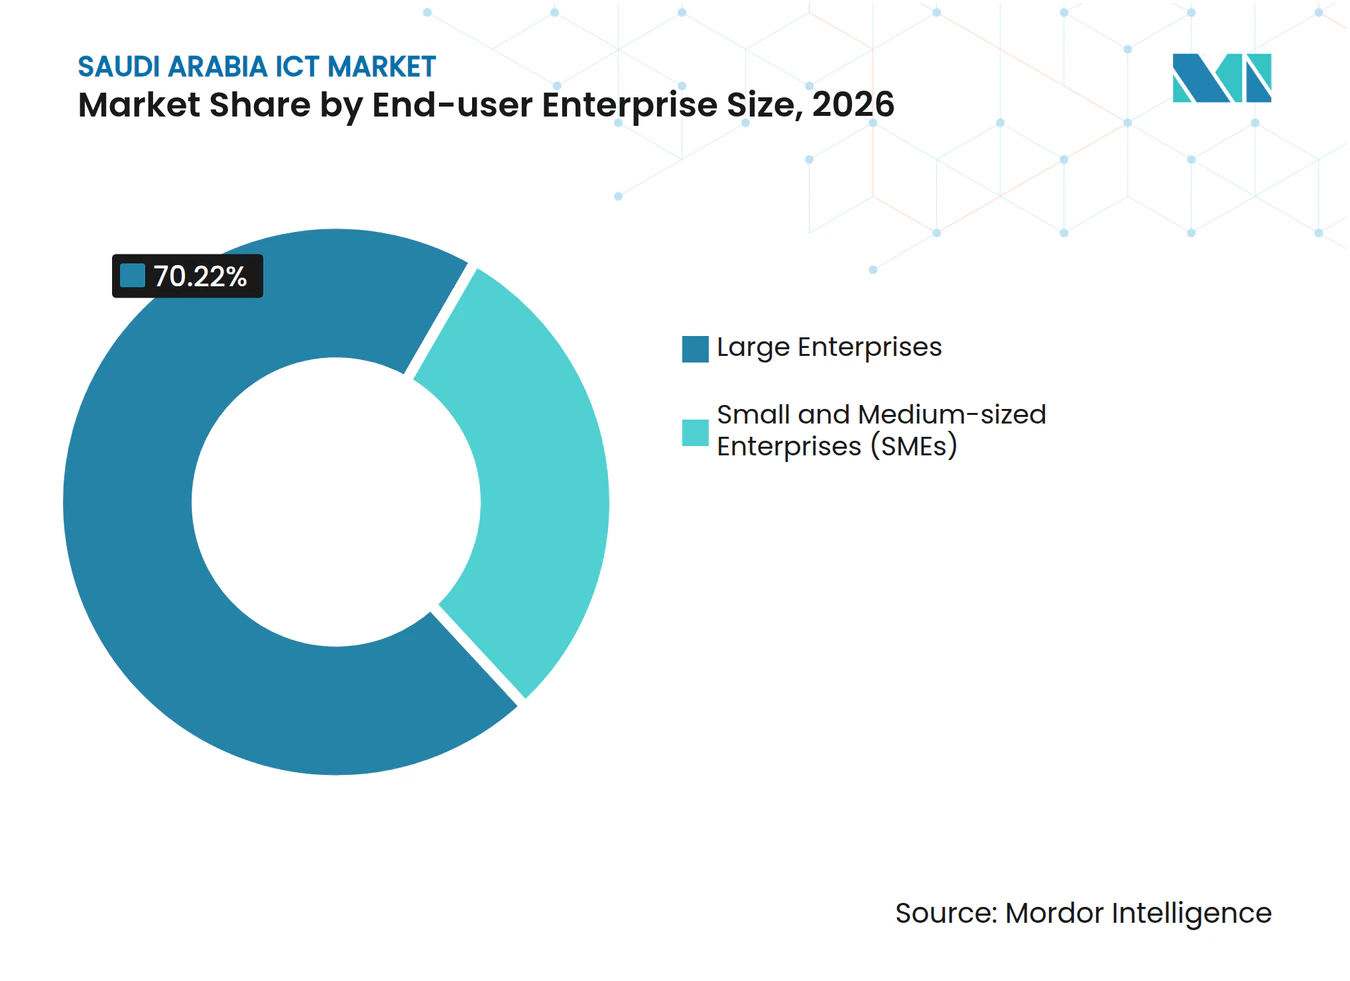
- Across enterprise sizes, large enterprises led with a 70.22% share of the Saudi Arabia ICT market size in 2026, while small and medium-sized enterprises (SMEs) are forecast to be the fastest-growing segment at a 10.85% CAGR during 2027-2032.
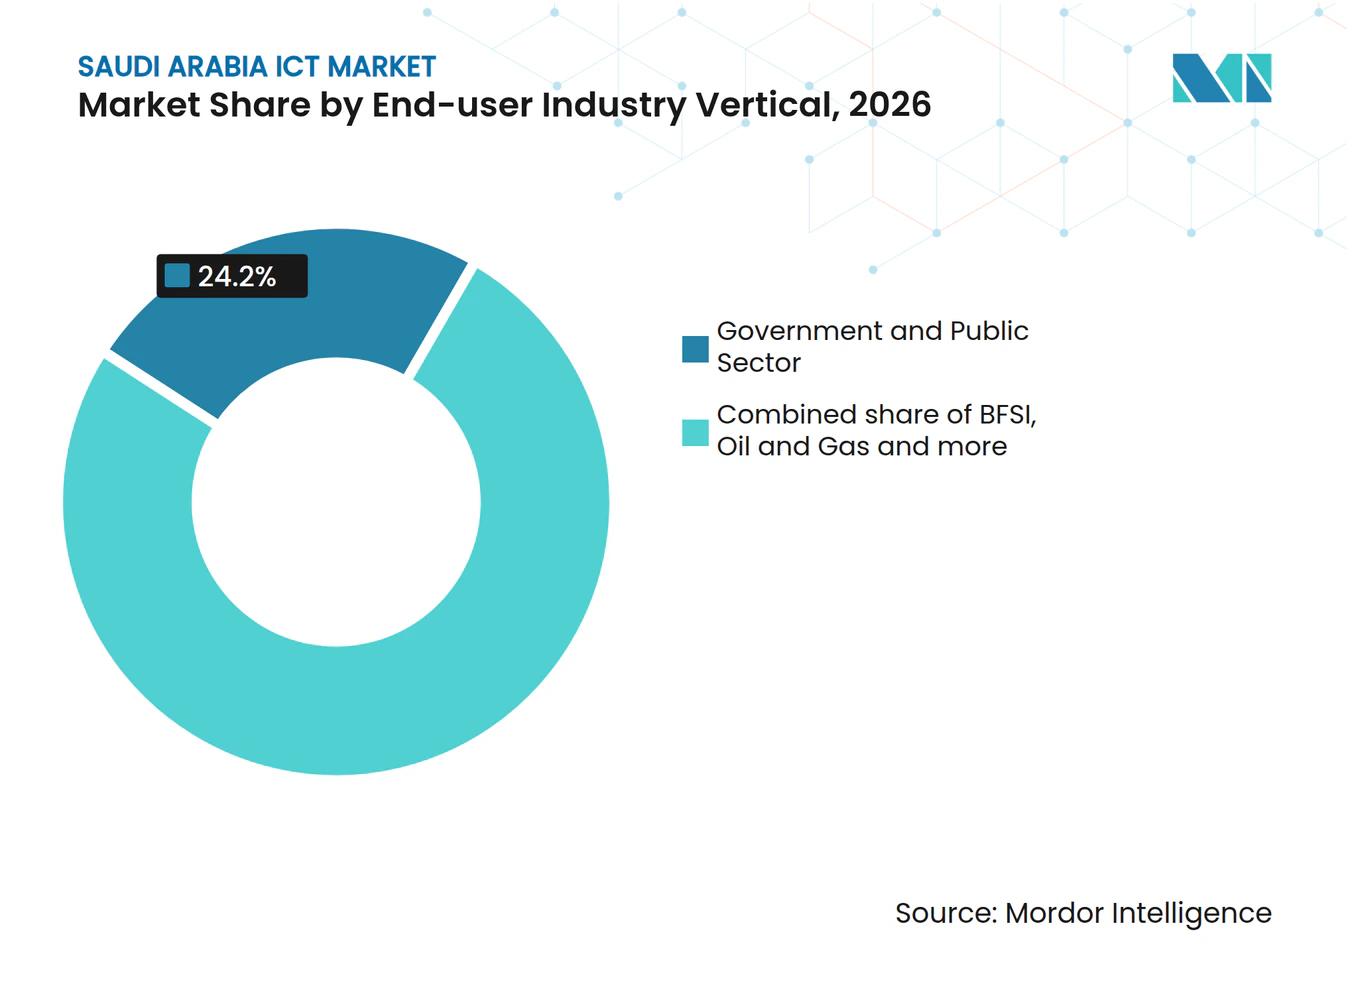
- Among end-user industries, government and public sector led with a 24.2% share in 2026, while healthcare is forecast to be the fastest-growing segment at a 13.7% CAGR during 2027-2032.
- For deployment models, cloud led with a 45.44% share in 2026 and is forecast to be the fastest-growing segment at a 14.2% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Saudi Arabia ICT Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vision 2030 public-sector digitization programs | +3.2% | Nationwide | Medium term (2-4 years) |
| 5G network rollout and subscriber monetization | +2.6% | Nationwide | Short term (≤ 2 years) |
| Accelerated cloud and SaaS adoption by SMEs | +2.2% | Nationwide | Medium term (2-4 years) |
| IoT-enabled industrial modernization in oil and gas | +2% | Nationwide | Medium term (2-4 years) |
| NEOM and other giga-projects’ hyperscale demand (under-the-radar) | +1.4% | Oxagon in NEOM | Medium term (2-4 years) |
| Sovereign-cloud mandates spurring local DC builds (under-the-radar) | +1% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Vision 2030 public-sector digitization programs
Public-sector digitization creates demand both for operating digital services and for extending their capabilities through additional computing resources. Saudi government spending on cloud computing increased 42% in 2025 compared with 2024. Spending on artificial intelligence and emerging technologies rose 20% across the same government sector in 2025 compared with 2024. Saudi Arabia’s Vision 2030 Annual Report 2025 counted 490 government digital platforms in operation. Cloud expenditure expands the infrastructure opportunity, while AI and emerging-technology spending creates room for more specialized implementation work. With hundreds of platforms already operating, combining cloud expansion with specialized AI implementation can address capability upgrades within an established government service estate.
5G network rollout and subscriber monetization
Home broadband links 5G rollout to a recurring household service, making subscriber uptake an important commercial complement to deployed network coverage. At year-end 2025, stc Group reported 63% 5G coverage across Saudi Arabia.[1] In 2025, Mobily reported growth in its 5G fixed wireless access customer base, reflecting rising demand for high-speed wireless home connectivity. Zain KSA reported that data revenue represented 46% of its 2025 revenue, excluding value-added services and SMS. Zain KSA’s revenue mix shows the commercial weight of data connectivity, so Mobily’s fixed wireless growth opens a household route into an established operator revenue line.
Accelerated cloud and SaaS adoption by SMEs
For an SME with limited internal ICT capacity, cloud and SaaS can turn a business application into a service-delivery decision. In November 2025, the Small and Medium Enterprises General Authority (Monsha’at) announced that Huawei Cloud services had joined its Mazaya platform for SMEs, offering cloud computing, data management, storage, analytics, and AI services. The buyer can scope the requirement around one operating function while leaving the application’s technical operation with a provider. This model can create demand where a separate internal installation would require capabilities beyond the small firm’s team. For the announced Mazaya channel, the provider must make the function usable, since computing resources alone do not perform the SME’s business task. Bundled application operation gives the supplier a defined delivery obligation and the SME a way to begin digitizing without staffing a separate installation.
IoT-enabled industrial modernization in oil and gas
Fleet management gives industrial IoT a defined operating use, connecting platform demand with implementation work inside a major energy group. In a February 26, 2026 announcement, Aramco Digital said it was already implementing Cumulocity’s industrial AIoT platform for a fleet-management program supporting Aramco’s operations in Saudi Arabia. Aramco Digital had the implementation role, while Cumulocity was the platform provider. Fleet management bounds the implementation around a defined workflow, making the application a concrete unit of work for an industrial implementer. Cumulocity’s industrial-platform opportunity in the announced program depends on Aramco Digital’s implementation work, connecting its commercial reach to the energy group’s own delivery organization.
Restraints Impact Analysis of Saudi Arabia ICT Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of advanced ICT talent and Saudi nationalization gap | -1.2% | Nationwide | Medium term (2-4 years) |
| Cyber-security skills deficit inflating OPEX | -0.9% | Nationwide | Medium term (2-4 years) |
| Local-content/hosting rules limiting foreign cloud entrants (under-the-radar) | -0.6% | Nationwide | Long term (≥ 4 years) |
| Supply-chain volatility for network hardware (under-the-radar) | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shortage of advanced ICT talent and Saudi nationalization gap
The skills constraint concerns which capabilities are available for emerging technologies, making workforce development relevant alongside expansion of ICT infrastructure. The 2025 Digital Sector Skills Framework identified a shortage of emerging digital skills in Saudi Arabia alongside an oversupply of traditional skills. That mismatch can leave a technically staffed team short of the capabilities required for a new implementation, adding development work to the delivery requirement. In April 2025, the National eLearning Center announced that the Ministry of Communications and Information Technology (MCIT) and Oracle launched Mustaqbali on FutureX, aiming to equip 50,000 Saudi citizens with AI and digital technology skills. The framework’s call to prioritize recruitment for new-skill roles and reskill existing staff means suppliers may need to allow hiring and training time before emerging-technology work can start.
Cyber-security skills deficit inflating OPEX
Saudi Arabia’s 2025 Digital Sector Skills Framework identified cybersecurity among the digital sector’s specialized skills needs. In October 2025, King Abdullah University of Science and Technology published cybersecurity professional Jameel Showail’s assessment that qualified Saudi nationals were insufficient to meet cybersecurity demand. Showail, who worked at a giga-project, said some needs were met through international hires or consultants. For a provider seeking qualified Saudi cybersecurity staff, this gap can require a separate recruitment or training effort before a new service is supported. International recruitment or consultant engagement offers an alternative, but arranging that specialist capacity can delay the point when additional secure-service work becomes deliverable.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Saudi Arabia ICT Market Segment Analysis
By Type:
Telecommunications Scale Meets Software ProcurementTelecommunication services accounted for a 31.65% share of the Saudi Arabia ICT market size in 2026. In 2025, stc Group’s Commercial Unit reported 30 million mobile subscribers in Saudi Arabia. In H1 2026, stc’s Saudi mobile customer base reached 30.3 million, up 4.8% from H1 2025. Supporting that established base while serving additional customers gives telecommunications operators continuing service demand beyond the installation of new network equipment.
Software is forecast to be the fastest-growing segment, at a CAGR of 9.78% during 2027-2032. On September 3, 2026, the Government Expenditure and Projects Efficiency Authority (EXPRO) and its government partners signed a framework covering infrastructure and data licenses and software for government entities.[2] Contractors can offer covered products through the Etimad government procurement platform so government entities can issue purchase orders. Hardware has a separate channel through EXPRO’s renewed framework for technology devices and accessories, including computers, tablets, and meeting-room equipment. Participation in the relevant framework gives license and device suppliers access to government ordering through that channel, before any resulting purchase order can be won.



By End-user Enterprise Size:
Large Enterprise Scale Meets SME Payment AdoptionLarge enterprises represented a 70.22% Saudi Arabia ICT market share in 2026. On September 16, 2025, Arabian Internet and Communications Services Company (solutions) signed a framework agreement with Saudi Aramco. It covered the supply, installation, and maintenance of digital computing devices. Combining device supply with installation and maintenance makes the buyer requirement broader than equipment delivery alone, creating work for providers able to cover the device lifecycle. Under the Aramco framework, competing for the device business therefore entails covering installation and maintenance as part of the offering.
Small and medium-sized enterprises (SMEs) are forecast to be the fastest-growing segment, at a CAGR of 10.85% during 2027-2032. A 2026 Mastercard study reported that 77% of surveyed SMEs in Saudi Arabia accepted online payments. In Visa’s March-April 2026 survey of 262 Saudi SMEs, 30% cited difficulty tracking outstanding invoices. Linking payment acceptance with invoice status gives SME software providers a specific workflow to address, with value resting on identifying unpaid invoices rather than simply adding payment methods.

By End-user Industry Vertical:
Public Services and Digital Care Shape DemandGovernment and public-sector users formed the largest segment, accounting for a 24.2% share in 2026. The Digital Government Authority recorded SAR 31.90 billion (USD 8.51 billion) in Saudi government spending on telecommunications and information technology services in 2025. Telecommunications and IT services cover distinct functions, so government expenditure in these categories can support both communications delivery and broader technology operations. That spending base gives communications operators and IT service specialists distinct public-sector revenue opportunities, so a supplier can target a defined service requirement without covering the entire technology stack.
Healthcare is forecast to be the fastest-growing segment, at a CAGR of 13.7% during 2027-2032. Seha Virtual Hospital completed more than 11.5 million virtual clinic appointments in 2025, 56% more than in 2024.[3] Growth in completed appointments makes the healthcare opportunity one of supporting delivered clinical activity, placing emphasis on services that can sustain use at scale. BFSI includes Neotek, which began full operations linking banks and other entities through application programming interfaces after receiving Saudi Arabia’s first final open-banking license from the Saudi Central Bank on March 30, 2026. The buying case differs by workload, with Seha’s scale emphasizing appointment delivery and Neotek’s model emphasizing customer-consented financial-data sharing.
By Deployment Model:
Cloud Adoption Extends Into Core Business FunctionsCloud was the largest segment, with a 45.44% share in 2026, and is forecast to be the fastest-growing segment, at a CAGR of 14.2% during 2027-2032. The General Authority for Statistics (GASTAT) found in its 2025 establishment ICT survey that 51.3% of surveyed Saudi establishments used cloud computing services. Establishments using cloud services provide a business customer base for the deployment model, linking provider opportunities with organizational uses of ICT. First-time migration can address establishments outside the cloud-using portion of the survey, giving providers a customer group with a different starting point from established cloud users.
By January 6, 2025, Almarai had completed implementation of RISE with SAP on Google Cloud, migrating its data and core functions to the cloud. Almarai attributed uninterrupted operations during the migration to close collaboration with SAP and Google Cloud. Moving core functions makes cloud adoption a decision about the organization’s operating applications, extending the supplier opportunity beyond isolated computing capacity. The example links application and cloud-platform providers within the same migration, making coordination a part of the delivery model. For core-function migrations, Almarai’s continuity account supports a delivery role for integrators coordinating SAP applications with Google Cloud.
Geography Analysis
Riyadh provides an example of city-service digitization, connecting a neighborhood parking operation with a digital permit service for residents and their guests. The Riyadh Parking Project launched non-paid managed residential parking in August 2025, beginning in Al-Wurud and making resident and guest permits available through its app. The combination of neighborhood management and digital permits makes application delivery central to this service model, tying ICT use to a specific local operating requirement. The scheme targets vehicles that do not belong to residents, so its digital permits distinguish resident and guest access from commercial-area parking spillover.
The Eastern Province’s Dhahran example centers on specialized computing within an industrial organization’s infrastructure, providing a different ICT setting from municipal service delivery. In November 2025, Aramco and Pasqal deployed the Middle East’s first quantum computer dedicated to industrial applications at Aramco’s data center in Dhahran. The placement at Aramco’s own data center ties the deployment to the industrial user’s infrastructure, giving the computing technology a defined organizational setting. This creates a route for specialized technology suppliers through an industrial host, so access to this kind of local computing requirement runs through the host relationship.
NEOM’s Oxagon example concerns construction of computing infrastructure, placing its ICT opportunity at an earlier delivery stage than an operating digital application. On August 31, 2026, NEOM reported that HUMAIN and DataVolt had construction underway on 100 MW of an AI-ready data center at Oxagon. That development forms part of a planned 360 MW first phase of the campus. The announced construction scope bounds the immediate supplier task to the initial facility, separating it from the wider first-phase capacity. Construction makes facility delivery the immediate opening at Oxagon, with customer-workload integration dependent on the future availability of computing capacity.
Regulatory Framework and Outlook
The comparison examines selected jurisdictions from the perspective of a public-sector organization buying and operating digital services. The Communications, Space and Technology Commission (CST) issued version 4 Cloud Computing Service Provisioning Regulations, effective nationwide on October 10, 2023, superseding the prior framework and provider guides. The National Cybersecurity Authority’s ECC-2:2024 controls apply to Saudi government agencies. Riyadh’s policy assigns its authentication duty to users of the municipality’s own applications, not their service providers.
Regulatory Table of Saudi Arabia ICT Market
| Decision factor | Saudi Arabia | Riyadh |
|---|---|---|
| Primary authority | Communications, Space and Technology Commission; National Cybersecurity Authority | Riyadh Municipality for its own websites and applications |
| Key instruments or direction | Cloud Computing Service Provisioning Regulations version 4; ECC-2:2024 | Secure Usage of Applications policy |
| Commercial effect | National cloud and cybersecurity frameworks govern public-sector service use | Users must activate multifactor authentication or available fingerprint verification |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national Medium rating reflects restrictions on cloud providers and subscribers transferring government-agency data abroad, including temporary storage and backup, unless another Saudi law or regulation expressly permits transfer. Cloud version 4 has applied since October 10, 2023, with ECC-2:2024 the national cybersecurity edition and no announced replacement for either instrument, supporting a No change outlook. For a public-sector operator, Riyadh’s Medium rating reflects an explicit authentication condition on its municipal application users, with fingerprint verification conditional on availability. Riyadh’s September 4, 2026 policy retained ECC-1:2018 and has no announced transition, so its No change outlook reflects continuing user-facing requirements under that municipal instrument.
Value Chain Stages
The value chain compares network connectivity, cloud infrastructure, and managed service delivery as successive foundations for operating ICT services. stc Group provides integrated communications and IT solutions that include telecommunications, cloud, managed services, and IoT. Oracle offers cloud infrastructure from its Riyadh cloud region in Saudi Arabia. These roles create distinct sources of supplier earnings even when an integrated provider participates at more than one stage.
Value Chain Analysis Table of Saudi Arabia ICT Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Network connectivity | Telecommunications service providers such as stc Group | Connectivity service sales | Dependence on suitable network access | Match service design to available access capacity |
| Cloud infrastructure provision | Cloud infrastructure providers such as Oracle | Cloud infrastructure service sales | Workload placement within available operating regions | Stage migration around operating capacity |
| Managed ICT service delivery | Managed service providers such as stc Group | Managed service contracts | Coordinating connectivity and cloud responsibilities | Define operating responsibilities before service handover |
| Source: Mordor Intelligence | ||||
AWS announced in 2026 that its first Saudi cloud infrastructure region was on track to launch in December 2026. Oracle’s operating Riyadh region provides an existing infrastructure option, while the AWS announcement identifies a planned addition to local choices. The December 2026 target makes migration preparation a distinct service opportunity, while production placement depends on a region actually opening.
Competitive Landscape
Market Concentration
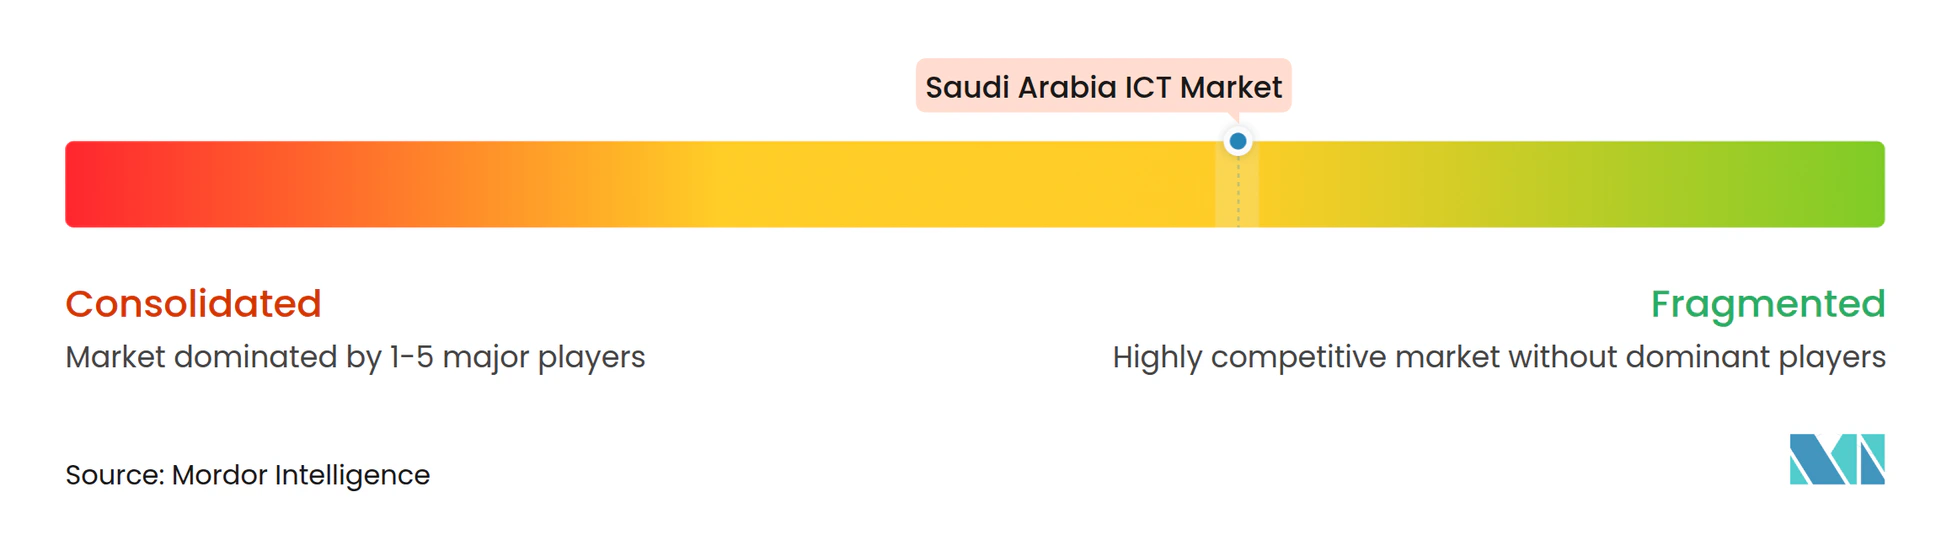
The supplier base is moderately fragmented beyond integrated telecom operators, with global technology vendors and Saudi AI specialists addressing different service layers. Enterprise software provider IBM Corporation, technology vendor Dell Technologies, Inc., and security technology supplier Palo Alto Networks, Inc., address different ICT requirements. Cloud provider Amazon Web Services Inc. (Amazon.com Inc.) and AI specialist nybl Ltd. add infrastructure and application capabilities to that competitive mix. Diriyah Company selected IBM Maximo Application Suite on February 12, 2025, to monitor and manage assets across the Diriyah Project. Dell’s MoUs with Aramco Digital, Armada, and Salam at LEAP 2026 show a technology vendor pursuing several Saudi partners at once, while IBM’s Diriyah selection concerned a single named project.
In May 2025, AWS and HUMAIN announced plans for a Saudi AI Zone combining dedicated AWS AI infrastructure, AWS services, and AI training and talent development. Cyberani, an Aramco Digital company, provides Saudi managed security operations center services and managed detection and response services using Palo Alto Networks’ Cortex XDR technology. The planned AI capacity contrasts with a managed-security service operated by a Saudi company using another vendor’s technology, separating infrastructure expansion from service operation. Buyers of Cyberani’s services rely on the local operator for security delivery, so Palo Alto Networks’ technology reaches them through an operating partner rather than a direct service relationship.
In February 2025, nybl announced a technology collaboration with US-based NOV to enhance its AI offerings for the oil and gas industry. Under the Saudi Central Bank’s (SAMA) hybrid and public cloud controls, SAMA-regulated member organizations should assess provider and service cybersecurity risks, conduct due diligence, and obtain SAMA approval before cloud use or contract signing. A contract including cybersecurity requirements should also be in place before cloud use. Industrial partnerships and regulated cloud procurement create different entry conditions, linking supplier positioning to sector knowledge in one case and provider assessment in the other. For suppliers pursuing these regulated cloud contracts, preparing security documentation early can help the buyer complete provider assessment before seeking SAMA approval and signing.
Saudi Arabia ICT Industry Leaders
-
IBM Corporation
-
Dell Technologies, Inc.
-
Palo Alto Networks, Inc.
-
Amazon Web Services Inc. (Amazon.com Inc.)
-
nybl Ltd.
- *Disclaimer: Major Players sorted in no particular order
Saudi Arabia ICT Market Companies Covered in this Report
- Saudi Telecom Company (stc Group)
- Etihad Etisalat Company (Mobily)
- Mobile Telecommunications Company Saudi Arabia (Zain KSA)
- Integrated Telecom Company (Salam)
- Etihad GO Telecom Co. (GO Telecom)
- IBM Corporation
- Dell Technologies, Inc.
- Amazon Web Services Inc. (Amazon.com Inc.)
- Hewlett Packard Enterprise Company
- Cisco Systems, Inc.
- Palo Alto Networks, Inc.
- Trend Micro Incorporated
- Lockheed Martin Corporation
- Accenture plc
- Skillsoft Corp. (Global Knowledge)
- Al Moammar Information Systems Co. (MIS)
- nybl Ltd.
- Virgin Mobile Saudi Consortium LLC
- Huawei Tech Investment Saudi Arabia Co. Ltd.
- Oracle Systems Saudi Arabia Ltd.
Key Opportunities for Market Participants
The opportunities comparison examines training, inference, and readiness services that providers could sell to technology companies adopting AI, using available computing and a defined adoption framework. On August 31, 2026, AMD, Cisco, and HUMAIN reported live Saudi AI infrastructure enabling GPU-as-a-service for model training and inference. HUMAIN operated the service for customers in the Kingdom and beyond, with AMD and Cisco supplying computing and networking technology. On July 27, 2026, the Communications, Space and Technology Commission (CST) outlined readiness checks covering context, data, infrastructure, skills and expertise, and organizational culture in its AI adoption guide for technology companies.
Market Opportunities Table of Saudi Arabia ICT Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Model-training implementation services | GPU-as-a-service supports training workloads | Technology companies developing AI models | Scope a model-training workload around available compute | Data and skills readiness | HUMAIN and model-development specialists |
| AI inference application integration | The operating service supports inference | Technology companies deploying AI applications | Connect an inference workload to a defined application | Selecting a suitable implementation scale | HUMAIN and application integrators |
| AI readiness and deployment services | Defined readiness dimensions guide project selection | Technology companies selecting initial AI projects | Combine readiness assessment with staged implementation | Coordination of data, infrastructure, and skills | AI implementation and advisory providers |
| Source: Mordor Intelligence | |||||
The strongest opening is to connect usable computing services with a workload that a technology-company buyer is ready to implement. The platform’s training and inference capabilities widen the application choices, while the readiness framework provides a basis for sequencing the work. Providers can package readiness assessment with an initial training or inference implementation, so a technology-company buyer can choose a project scope that fits its data, infrastructure, and skills.
Recent Industry Developments in Saudi Arabia ICT Market
- Sep 2026: The Government Expenditure and Projects Efficiency Authority (EXPRO) and its government partners signed a framework covering infrastructure and data licenses and software for government entities. It enables contractors to offer products through the Etimad government procurement platform so agencies can issue purchase orders.
- Aug 2026: AMD, Cisco, and HUMAIN put AI infrastructure powered by AMD Instinct MI355X GPUs, AMD EPYC CPUs, and Cisco networking into production in Saudi Arabia, serving HUMAIN customers in the Kingdom and beyond.
Saudi Arabia ICT Market Report Scope and Research Methodology
Market Definition and Coverage
The Saudi Arabia ICT market measures annual spending on information and communication technology products and services in Saudi Arabia. It covers purchases by enterprises and public-sector organizations across deployment models.
Scope exclusions: Standalone semiconductor and generic component sales to ICT manufacturers, data-center land, building construction and real-estate costs, and revenue from downstream goods or services sold by ICT-using industries are excluded.
Segments Covered in This Report
- By Type
- Hardware
- Data-center Hardware
- Networking Equipment
- End-user Devices
- Software
- Enterprise Applications
- Operating Systems and Middleware
- Security Software
- IT Services
- Managed Services
- Professional and Consulting Services
- Telecommunication Services
- Hardware
- By End-user Enterprise Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- By End-user Industry Vertical
- BFSI
- Government and Public Sector
- Oil and Gas
- IT and Telecom
- Retail and E-commerce
- Manufacturing
- Energy and Utilities
- Healthcare
- Other End-user Industry Vertical (Transportation, Education, Hospitality)
- By Deployment Model
- On-premise
- Cloud
- Hybrid
Data Sources, Market Sizing, and Validation
Desk Research
The research uses public indicators from sources such as the Communications, Space and Technology Commission's market and connectivity releases and the General Authority for Statistics' establishment ICT survey, ICT survey methodology, and digital economy statistics to track Saudi spending, adoption and policy conditions. These sources distinguish market transactions from related measures such as establishment use, sector operating revenue and ICT goods trade, which are used as context or cross-checks rather than added mechanically to the market total.
Company annual reports, regulatory filings, investor presentations, procurement announcements and reputable Saudi business press provide additional evidence on operator revenue, enterprise demand, technology investment and contract timing. Reported figures are checked for Saudi scope, period and overlap before use. The named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured questionnaires would target Saudi telecom operators, ICT vendors and integrators, enterprise and public-sector technology buyers, cloud and software providers, and procurement specialists, with respondents selected for direct knowledge of spending and delivery. Their evidence would test secondary-source interpretations of component boundaries, buyer and industry allocations, deployment choices and forecast drivers, while gaps would be recorded and triangulated against independent public data, company disclosures and channel evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 15% | |
| Mid tier: 45% | Functional/Unit leaders: 40% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates Saudi annual end-user expenditure from the top down, using national ICT and communications spending indicators and allocating the total across hardware, software, IT services and telecommunication services. Saudi establishment ICT-use rates, government ICT expenditure, operator and vendor disclosures, enterprise investment announcements, cloud adoption and sector-specific procurement provide checks on demand levels and on shares by buyer size, industry and deployment model. Shares are built from category-specific expenditure evidence and reconciled to the total. A multivariate regression or scenario analysis relates historical market movement to indicators such as government digital spending, telecommunications activity, establishment cloud use, ICT goods imports as a supply signal, and announced data-center and network investment, with adoption and price or service-mix evidence guiding assumptions where value changes differ from activity. Analysts use supplier revenue roll-ups, sampled channel checks and selected average selling price times volume estimates to test material categories, reconcile these checks with the top-down total, and investigate coverage or timing gaps against filings and public records. Expert interviews would test the direction and commercial plausibility of variable-level forecasts and segment allocations, while unresolved gaps would use documented proxy ranges and scenario bounds rather than unsupported precision.
Data Validation & Update Cycle
Analysts triangulate expenditure estimates against official spending and adoption series, supplier disclosures, procurement records and interview evidence, then investigate anomalies in period, currency, scope, overlap and growth before sign-off. A second review checks source traceability, arithmetic, segment reconciliation and forecast drivers, with re-contact triggered by conflicting material evidence or an unclear transaction boundary. The dataset is refreshed annually, updated between cycles when a material regulatory, investment or market event changes an input, and receives a fresh pre-delivery review.
Mordor Intelligence's Saudi Arabia Ict Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Saudi Arabia ICT market measures annual spending on information and communication technology products and services in Saudi Arabia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression or scenario analysis relates historical market movement to indicators such as government digital spending, telecommunications activity, establishment cloud use, ICT goods imports as a supply signal, and announced data-center and network investment, with adoption and price or service-mix evidence guiding assumptions where value changes differ from activity.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 71.43 B (2027) | |
| Commercial Research Firm A | USD 47.8 B (2024) | At its 2024 base, this estimate is 33.1% below this report's 2027 value of USD 71.43 B, 3 years later. The published type list covers hardware, software and IT services, excluding telecommunication services counted in this report. |
| Saudi Industry Authority A | USD 48 B (2024) | At its 2024 base, this estimate is 32.8% below this report's 2027 value of USD 71.43 B, 3 years later. The official release measures the communications-and-technology market in 2024, an earlier measurement year than this report's annual spending estimate. |
Mordor Intelligence's analysts triangulate expenditure estimates against official spending and adoption series, supplier disclosures, procurement records and interview evidence, then investigate anomalies in period, currency, scope, overlap and growth before sign-off.
Key Questions Answered in the Report
What is the Saudi Arabia ICT market size and growth outlook?
The size is estimated at USD 71.43 billion in 2027 and forecast to reach USD 111.8 billion by 2032, at a 9.38% CAGR during 2027-2032.
What is driving demand for ICT services?
Saudi government cloud spending rose 42% in 2025 compared with 2024. Mobily also reported growth in its 5G fixed wireless access customer base in 2025.
Which ICT category is the largest?
The largest category was telecommunication services, with a 31.65% share in 2026.
Which companies are major ICT suppliers?
Major players include IBM Corporation, Dell Technologies, Inc., Palo Alto Networks, Inc., Amazon Web Services Inc. (Amazon.com Inc.), and nybl Ltd.
What could constrain the pace of ICT deployment?
The 2025 Digital Sector Skills Framework identified an emerging-skills shortage and traditional-skills oversupply. In October 2025, cybersecurity professional Jameel Showail reported too few qualified Saudi nationals to meet cybersecurity demand.
How do ICT applications differ across Saudi locations?
Riyadh’s initial non-paid parking rollout in Al-Wurud offered resident and guest permits through an app in August 2025. Dhahran hosted Aramco and Pasqal’s industrial-purpose quantum deployment in November 2025.