
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
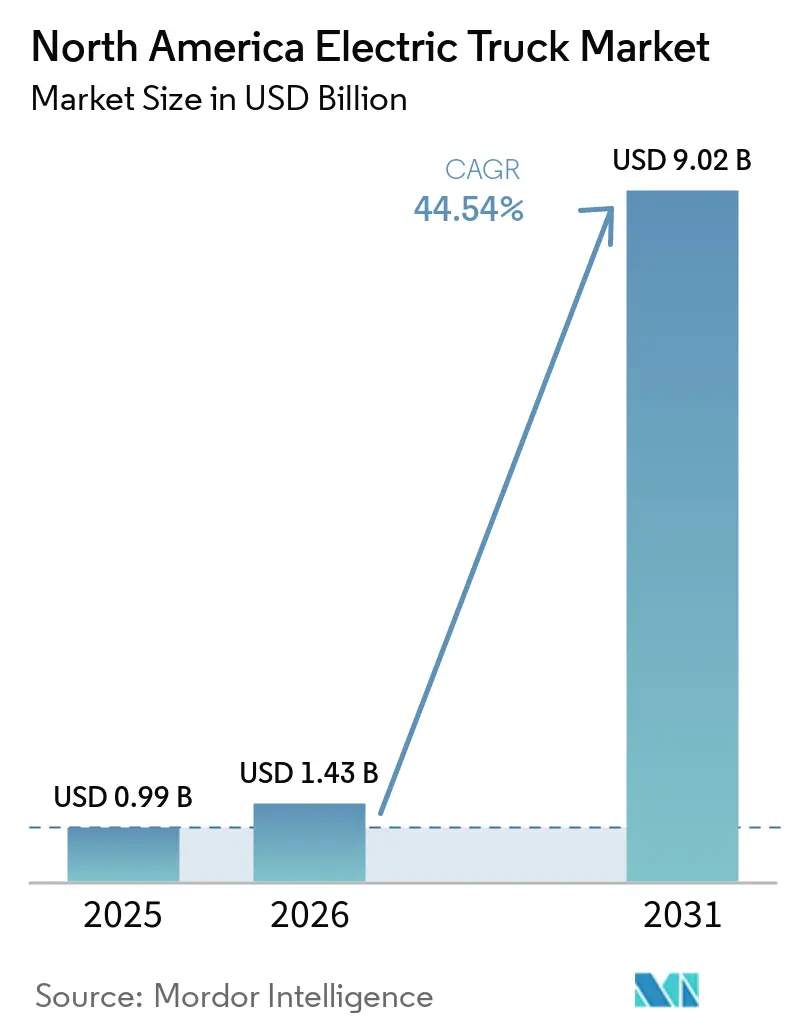
| Base Year Market Size (2025) | USD 0.99 Billion |
| Market Size (2026) | USD 1.43 Billion |
| Market Size (2031) | USD 9.02 Billion |
| Growth Rate (2026 - 2031) | 44.54 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Electric Truck Market Analysis by Mordor Intelligence
The North American electric truck market size was valued at USD 0.99 billion in 2025, is estimated at USD 1.43 billion in 2026, and is projected to reach USD 9.02 billion by 2031, growing at a CAGR of 44.54% from 2026 to 2031. The powerful growth trajectory is underpinned by overlapping zero-emission mandates, the steep decline in battery-pack prices, and increasingly aggressive net-zero targets announced by large shippers and retailers. The Advanced Clean Trucks rule in California and the states that have adopted it, the EPA Phase 3 heavy-duty GHG standards, and the rapid scale-up of domestic battery capacity have combined to pull forward purchase decisions among fleet operators, while megawatt-class charging demonstrations indicate that range constraints in long-haul duty cycles will ease before mid-decade. Competitive dynamics are also shifting: incumbent heavy-duty OEMs are accelerating platform rollouts to defend share against vertically integrated newcomers that promise faster software updates and lower running costs. These factors create new whitespace for infrastructure developers and battery-leasing specialists, but they also intensify execution risk related to grid interconnection queues and raw-material price swings.
Key Report Takeaways
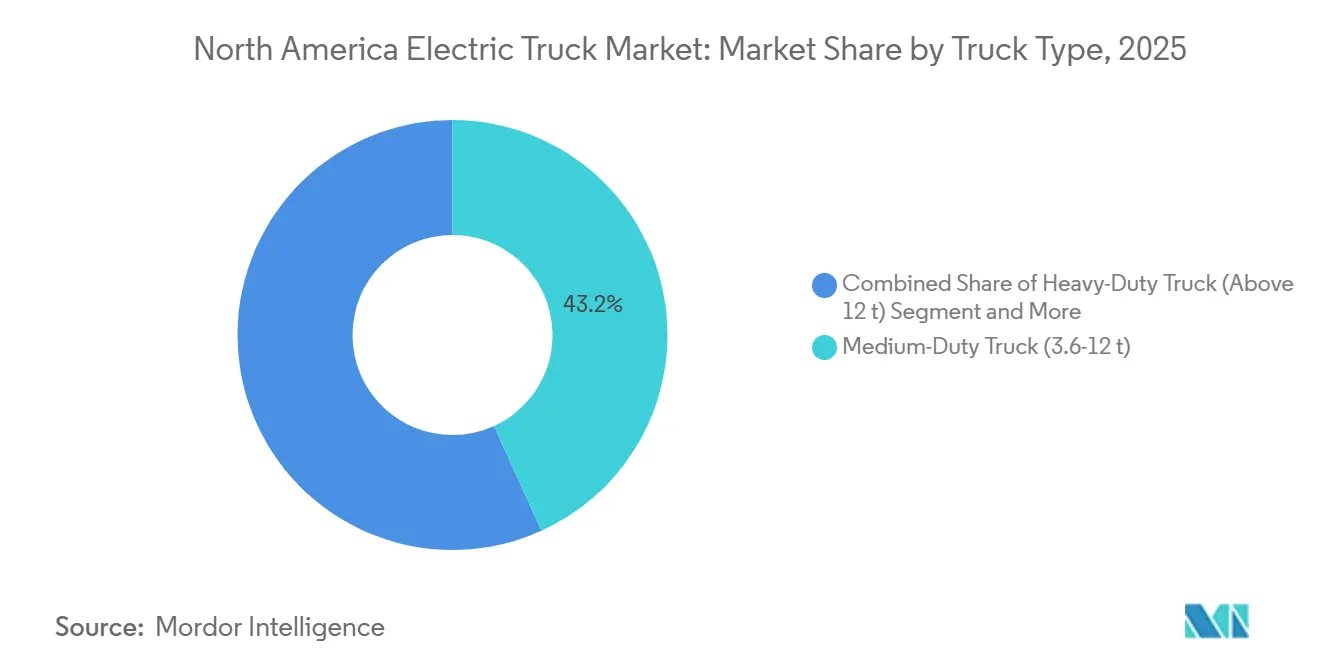
- By truck type, medium-duty models led with 43.15% of the North American electric truck market share in 2025, while heavy-duty models above 12 t GVW are advancing at a 45.22% CAGR through 2031.
- By propulsion type, battery-electric vehicles captured 77.45% revenue share in 2025, while fuel-cell electric vehicles are expanding at a 50.13% CAGR between 2026 and 2031.
- By range, urban trucks below 150 km accounted for a 47.13% share in 2025, while trucks with ranges above 500 km are projected to grow at a 46.18% CAGR by 2031.
- By battery capacity, 201-400 kWh models held a 53.44% share in 2025, while trucks with capacities above 800 kWh are set to expand at a 47.03% CAGR by 2031.
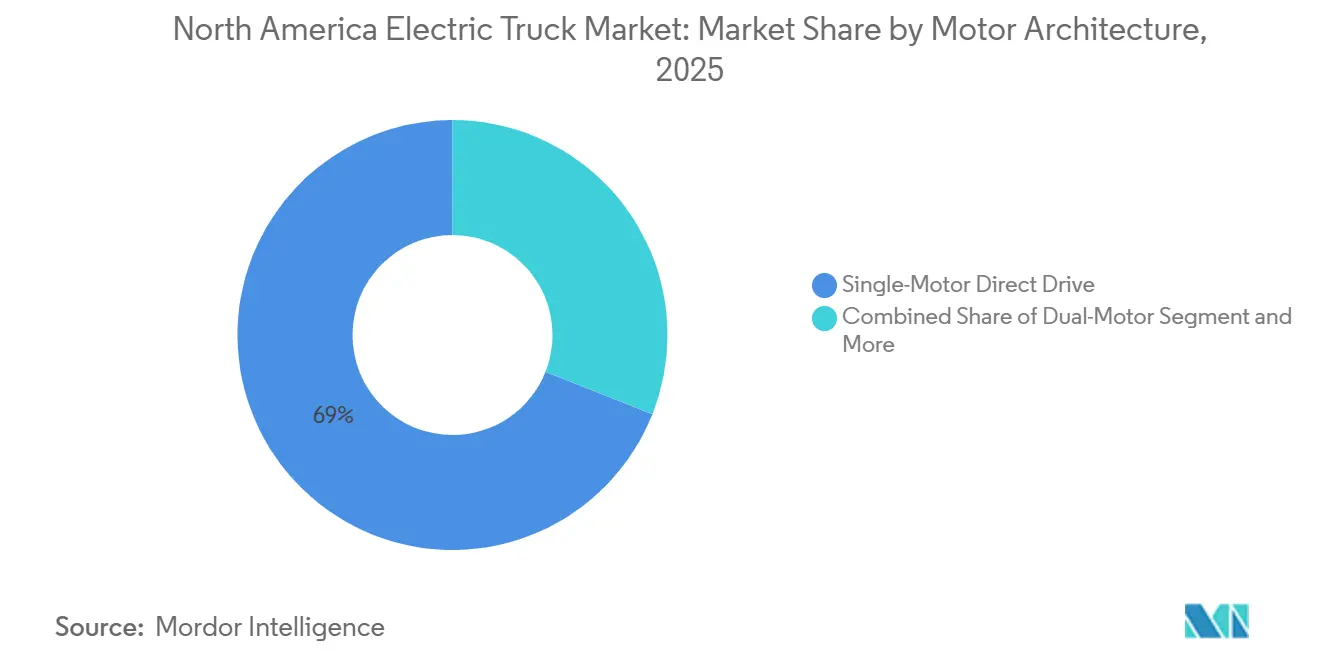
- By motor architecture, single-motor direct drive captured 69.03% revenue share in 2025, while the integrated eAxle is projected to grow at a 46.71% CAGR by 2031.
- By application, logistics and parcel delivery controlled 60.14% of the 2025 volume; construction and mining applications are projected to post a 45.85% CAGR to 2031.
- By country, the United States commanded 84.02% of regional sales in 2025, whereas Mexico is forecast to grow at a 47.35% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Electric Truck Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tightening ZEV and CO2 Rules | +9.2% | CA, WA, OR, NY; Canada | Medium term (2–4 years) |
| Falling Battery Costs Reach Parity | +8.7% | National | Short term (≤2 years) |
| Depot and Corridor Charging | +7.5% | USMCA freight corridors | Medium term (2–4 years) |
| Rising Corporate Net-Zero Freight | +6.8% | National | Short term (≤2 years) |
| USMCA Megawatt-Charging Corridors | +5.4% | Cross-border corridors | Long term (≥4 years) |
| Drayage Battery-Swap Pilots | +3.1% | CA and BC ports | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Stricter ZEV Mandates and HDV CO₂ Standards
EPA Phase 3 rules demand a notable CO₂ cut for model-year 2027 vocational trucks, while California’s Advanced Clean Fleets measure forces high-priority fleets to transition drayage tractors to 100% zero emissions by 2035 [1]. In Washington, Oregon, and several Northeastern states, copycat adoption now accounts for a significant portion of the United States truck registrations. Transport Canada’s draft mandate targets 35% ZEV medium- and heavy-duty sales by 2030, broadening regulatory pull. Despite facing a considerable increase in certification costs, Daimler Truck anticipates that ZEV models will contribute meaningfully to its North American revenue in the coming years. These overlapping mandates not only tighten product-launch timelines but also establish a baseline of captive demand, providing a buffer for OEM volumes amidst freight downturns
Rapid Battery-Pack Cost Decline Enabling TCO Parity
In early 2025, commercial LFP pack prices experienced a significant decline, driven by an oversupply of Chinese cathodes and the scaling effects of gigafactories. Similarly, high-nickel NMC 811 packs saw a notable reduction in costs, following the ramp-up of a production line in Michigan during late 2024. In California, heavy-commercial electric vehicles achieved cost parity with diesel under specific conditions related to fuel and electricity prices. A study by NACFE, which analyzed a large number of delivery vehicles, revealed that electric vehicles offered a shorter payback period compared to diesel vehicles. This advantage was primarily due to reduced maintenance expenses and the availability of voucher incentives. Consequently, the decreasing costs of packs are broadening the scope of fleet adoption, extending beyond initial urban pilot programs.
Expansion of Depot and Corridor Fast-Charging in North America
The NEVI formula program is directing significant funding to install DC fast chargers at regular intervals along Alternative Fuel Corridors, with several truck-capable sites expected to become operational in the near future [2]. Following suit, private companies have committed substantial investments to equip truck stops with high-capacity dispensers over the coming years. Depot infrastructure currently provides the majority of electric-truck energy, as fleets prioritize control over demand charges and charger availability. These investments collectively reduce dwell times, enhance route flexibility, and mitigate risks associated with long-haul asset utilization. Yet, challenges like charger reliability and payment interoperability continue to trouble early adopters.
Corporate Net-Zero Freight Commitments
Walmart aims to transition its private truck fleet to zero-emission units by 2040, showing a clear preference for BEV models on shorter routes. UPS deployed a significant number of electric vans over the years, achieving notable diesel savings. Meanwhile, FedEx has allocated substantial resources for EV capital expenditures over the next few years. Notably, Tesla reveals that a majority of its Semi reservations are from corporate fleets targeting Scope 3 carbon reductions. Such public commitments not only bolster OEM order books but also expedite the formation of a secondary market by ensuring scale.
Restraints Impact Analysis of North America Electric Truck Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Costs and Model Shortages | -4.3% | National | Medium term (2–4 years) |
| Grid Interconnection Delays | -3.6% | CA, TX, ON, QC | Short term (≤2 years) |
| Volatile Lithium Prices | -2.8% | National | Short term (≤2 years) |
| Safety Skill Gaps in Fleets | -1.9% | Midwest & Southeast US | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
High Upfront Price and Limited HD Model Availability
In Q4 2025, a Class 8 tractor with advanced battery capacity was significantly more expensive than its diesel counterpart, with batteries accounting for a substantial portion of the bill of materials. While tax credits are available to offset costs, limitations on the number of eligible units create uncertainty for buyers. Among the available models, only a few sleeper-cab BEVs offer long-range capabilities, compared to a much larger variety of diesel options. Production remains limited, with manufacturers facing capacity constraints. Smaller fleets encounter stricter lease terms and higher initial costs, which slow adoption outside the largest carriers.
Utility Interconnection Delays for ≥1 MW Depots
Surveys by EPRI reveal that sites in CA, TX, and ON requiring significant service upgrades face lengthy wait times, primarily due to necessary enhancements to distribution transformers and feeders. PG&E highlights that a majority of large-scale requests necessitate costly network upgrades, a financial burden initially shouldered by fleets under Rule 15. In recent years, ERCOT's queue for commercial EV chargers has grown substantially, leading to extended timelines. In Ontario, cases can take even longer, especially when voltage conversions are mandated. While California's AB 2061 mandates utilities to complete studies within a shorter timeframe for smaller projects, the actual implementation remains inconsistent.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Electric Truck Market Segment Analysis
By Truck Type:
Medium-Duty Dominance Gives Way to Heavy-Duty SurgeMedium-duty models commanded 43.15% of 2025 revenue, reflecting early alignment with depot charging and municipal duty cycles. Heavy-duty entries will deliver the steepest upside, posting a 45.22% CAGR that will lift the North American electric truck market size for Class 8 tractors significantly by 2031, aided by megawatt-charging corridors and 800 kWh battery packs.
Capital intensity stays lower in Class 6 platforms, yet the performance gap is narrowing. The North American electric truck market share for medium-duty units, therefore, peaks early and transitions toward proportional parity with heavy-duty by 2030.



By Propulsion Type:
BEV Supremacy Faces Rapid FCEV AccelerationBattery-electric vehicles held 77.45% of the 2025 revenue and generated the largest slice of the North American electric truck market share due to 85–90% well-to-wheel efficiency and the broadest charging footprint. Fuel-cell electric vehicles are projected to climb at a 50.13% CAGR, pushing the collective North America electric truck market size for hydrogen platforms by 2031. Plug-in hybrids offered a middle ground for fleets with mixed duty cycles, yet policy incentives have begun shifting away from transitional technologies, tilting investment toward pure zero-emission powertrains.
As the outlook period unfolds, the dominance of Battery Electric Vehicles (BEVs) begins to wane. This shift is largely attributed to the advent of corridor megawatt chargers and a drop in green-hydrogen prices, making it feasible to refuel quickly for long distances. Supporting this transition, Original Equipment Manufacturers (OEMs) are making notable announcements: Nikola is set to establish a significant number of hydrogen stations, while Hyundai's XCIENT program has demonstrated high reliability and extensive fleet performance. Despite this, BEVs, favored for their compatibility with depots, continue to be the preferred choice for urban and regional operators. These operators are primarily focused on predictable routes spanning shorter distances. Consequently, the competitive landscape is evolving: BEVs are solidifying their hold on high-volume metropolitan routes, while Fuel Cell Electric Vehicles (FCEVs) are carving out niches, especially for payload-sensitive and refrigerated long hauls.
By Range:
Urban-Skewed Mix Evolving Toward Extended-Range AdoptionVehicles rated below 150 km captured 47.13% of 2025 deployments due to last-mile delivery and refuse collection routes that return to base nightly. Trucks capable of 301–500 km range held a modest share but will expand at a notable CAGR as Tesla's Semi and Daimler's eCascadia validate 480 km real-world performance with 82,000-lb GCW.
Over the forecast horizon, the above-500 km band scales fastest at 46.18% CAGR, raising its share of the North America electric truck market size by 2031. With megawatt-charging corridors being established under NEVI funding and CharIN MCS pilots, the essential infrastructure is being firmly set in place. Simultaneously, the adoption of advanced battery chemistries is elevating pack density beyond the payload break-even point. While urban-focused fleets are opting for shorter-range chassis to cut down on battery costs, blended operations—such as milk-run logistics—are leaning towards middle-range platforms that strike a balance between capital expenditure and versatility.
By Battery Capacity:
Mid-Range Packs Dominate as 800 kWh Systems Gain TractionPacks in the 201–400 kWh bracket controlled 53.44% of 2025 uptake by exploiting cost-performance sweet spots, yielding 250–300 km range for Class 6-7 box trucks. Systems exceeding 800 kWh constituted only a nominal share of deliveries yet are projected to rocket at 47.03% CAGR, expanding the segment’s North America electric truck market share by the end of 2031.
Pricing for LFP systems sets the economic foundation, making them significantly more cost-effective compared to NMC systems. However, operators with heavier gross weights are willing to pay the premium for NMC systems due to the advantage of megawatt charging, which can rapidly replenish the state-of-charge, reducing downtime compared to diesel. Leading companies including LG Energy Solution, and Ford through its CATL-licensed BlueOval Battery Park Michigan, are establishing LFP production lines in the United States, which are expected to further reduce costs and address supply risks.
By Motor Architecture:
Single-Motor Solutions Yielding Ground to Integrated eAxlesSingle-motor direct-drive setups held 69.03% share in 2025 as fleets valued simplicity and cost-effectiveness of components. Integrated eAxles represented a minimal share but are forecast to outpace every other architecture at 46.71% CAGR, raising the North America electric truck market share for eAxles by 2031.
Dana’s advanced e-Powertrain and ZF’s highly efficient CeTrax 2 contribute to weight reduction and range improvement by minimizing energy losses. Dual-motor systems continue to play a crucial role in meeting the demands of torque-intensive vocational tasks, whereas in-wheel hubs remain a specialized option until technological challenges are resolved. Additionally, regulatory efficiency standards are subtly encouraging OEMs to adopt integrated configurations, leveraging weight and drag reductions to meet compliance requirements.

By Application:
Logistics Rule Softens as Construction and Mining AccelerateIn 2025, logistics and parcel delivery have emerged as the dominant segment with 60.14% share, driven by the procurement strategies of industry leaders such as Amazon, UPS, and FedEx. Meanwhile, the construction and mining sectors, though smaller in share, are experiencing a rapid growth of 45.85% CAGR. This expansion is significantly contributing to the North American electric truck market, with notable advancements in fuel-cost efficiency demonstrated by vehicles like Volvo CE haulers and BYD dump trucks.
Municipal services are also gaining momentum, supported by city mandates aimed at achieving zero emissions for refuse fleets within the next decade. Retail and FMCG sectors are exploring electric refrigeration units that optimize energy usage by separating HVAC loads from traction packs. At the same time, utility companies are adopting bucket trucks designed to reduce emissions during stationary operations. Each of these applications now benefits from a purpose-built chassis, addressing the historical challenge of retrofitting passenger-car technology for commercial use.
Geography Analysis
North America Electric Truck Market in the United States
The United States dominates the North America Electric Truck Market, commanding approximately 84% of the total market volume in 2024, while also exhibiting the strongest growth trajectory with an expected growth rate of around 24% from 2024 to 2029. The market's robust performance can be attributed to the country's comprehensive approach to electric truck adoption, supported by substantial federal and state-level incentives. The U.S. government's ambitious environmental goals, particularly through initiatives like the Advanced Clean Trucks regulation, have created a favorable environment for electric truck adoption. Major metropolitan areas are leading the transition, with cities implementing low-emission zones and developing dedicated charging infrastructure. The presence of leading manufacturers and their significant investments in research and development has further accelerated market growth. Additionally, the country's well-developed logistics sector and increasing corporate commitments to sustainability have driven demand, particularly in the commercial transportation segment.
North America Electric Truck Market in Canada
Canada's electric truck market demonstrates significant potential, driven by the country's strong commitment to environmental sustainability and clean transportation. The government's comprehensive approach includes both federal and provincial initiatives to accelerate the adoption of electric commercial truck vehicles in commercial transportation. Provinces like Quebec and British Columbia are at the forefront, implementing their own zero-emission vehicle mandates and providing additional incentives for fleet electrification. The country's robust electricity infrastructure and clean energy mix provide an advantageous foundation for electric transport truck operations. Canadian cities are increasingly integrating electric trucks into their municipal fleets, setting an example for private sector adoption. The market is further strengthened by growing collaboration between government agencies, utilities, and private sector stakeholders in developing charging infrastructure. Local manufacturing capabilities and research institutions are contributing to technological advancements in cold-weather performance, addressing specific challenges posed by Canada's climate.
North America Electric Truck Market in Mexico
Mexico's electric truck market is experiencing a transformative phase, characterized by increasing awareness of sustainable transportation solutions and growing environmental concerns in urban areas. The country's strategic position in North American trade and manufacturing has attracted significant investment in electric vehicle production capabilities. Major cities, particularly Mexico City, are driving adoption through progressive environmental policies and restrictions on conventional vehicles in urban centers. The country's automotive manufacturing expertise is gradually shifting toward electric vehicle production, creating a robust ecosystem for electric truck development. Local governments are implementing supportive policies and working with international partners to develop charging infrastructure. The market is particularly active in last-mile delivery and urban logistics segments, where electric trucks offer operational advantages. Mexico's commitment to reducing urban air pollution has led to increased interest from fleet operators in electric alternatives, particularly in densely populated areas.
North America Electric Truck Market in Other Countries
The broader North American region demonstrates varying levels of electric truck adoption, influenced by local regulations, economic conditions, and infrastructure development. Each country's approach to electrification reflects its unique economic priorities and environmental goals. The market development is closely tied to regional trade relationships and cross-border cooperation in establishing charging networks and standardizing regulations. Local initiatives and pilot programs are helping to demonstrate the viability of electric trucks in different operating conditions and use cases. The success of early adopters is encouraging other markets to accelerate their transition to electric vehicles, particularly in the commercial transportation sector. International partnerships and knowledge sharing are playing crucial roles in developing market expertise and technical capabilities across the region.
Regional Editions
Competitive Landscape
Market Concentration
The OEMs—Daimler Truck, Volvo Group, PACCAR, and Tesla—held a notable share of the North American electric truck market in 2025. Daimler and Volvo leverage existing dealer footprints and bundled maintenance contracts to keep lifetime costs predictable, while Tesla and Rivian exploit vertical integration and direct-to-fleet sales that bypass traditional dealerships. PACCAR has carved a niche among owner-operators through modular battery configurations and integrated telematics.
Tesla's Semi, now rolling off the production line in significant numbers, offered a price advantage over diesel tractors while the Section 45W credit was available through September 2025, and now competes on total cost of ownership alone. This gives major shippers like PepsiCo a significant edge in cost-per-ton-mile. Following a major expansion in Portland, Daimler's eCascadia has ramped up production. Meanwhile, Volvo's VNR Electric has established a notable presence in California's regional haul market, bolstering its appeal with service bundles priced at a competitive rate.
New entrants like BYD, Lion Electric, and Xos are eyeing untapped opportunities. BYD's plant in California sidesteps tariffs and leverages in-house LFP cells, achieving a significant cost reduction compared to standard NMC packs. Partnerships, especially those aligning with the CharIN megawatt standard, are emerging as pivotal differentiators, potentially reshaping the industry's landscape by 2030.
North America Electric Truck Industry Leaders
-
Daimler Truck Holding AG
-
Volvo Group
-
PACCAR Inc.
-
BYD Auto Co., Ltd.
-
Tesla, Inc.
- *Disclaimer: Major Players sorted in no particular order
North America Electric Truck Market Companies Covered in this Report
- Daimler Truck Holding AG
- Volvo Group
- PACCAR Inc.
- BYD Auto Co., Ltd.
- Ford Motor Company
- Orange EV
- Tesla, Inc.
- Rivian Automotive LLC
- Lion Electric Co.
- Xos, Inc.
- International Motors, LLC
- Mitsubishi Fuso Truck and Bus Corporation
- Isuzu Motors
- Workhorse Group
- Hyundai Motor Company
- GreenPower Motor Company Inc.
Recent Industry Developments in North America Electric Truck Market
- August 2026: Ford announced that its Louisville Assembly Plant is on track to fully launch production of its new midsize electric truck in 2027. The company stated that it had spent the previous eight months converting the Louisville Assembly Plant from a gasoline vehicle facility into a fully electric manufacturing plant to prepare for the production launch of the new midsize electric truck in 2027.
- June 2026: BYD Commercial Vehicles delivered 100 T75 electric light trucks to Mexico, marking a significant milestone in the company’s expansion across Latin America. The delivery reinforces BYD’s commitment to supporting Mexico’s transition toward sustainable transportation and logistics.
- April 2026: Swedish trucking company Einride announced a partnership with Amazon.com to deploy 75 manually operated electric heavy-duty trucks and supporting charging infrastructure across five locations in the United States in the e-commerce giant's freight network.
- April 2026: Elemental Trucks Inc. (ETI), a Canadian leader in zero-emission heavy-duty vehicles, launched North America’s first commercially available 63.5-tonne hydrogen fuel cell truck at Truck World 2026. The launch demonstrated ETI’s ability to decarbonize the most demanding trucking operations.
North America Electric Truck Market Report Scope
The scope includes segmentation by truck type (light truck (≤3.5 t), medium-duty truck (3.6-12 t), and heavy-duty truck (above 12 t)), propulsion type (battery-electric vehicle, fuel-cell electric vehicle, plug-in hybrid electric vehicle, and hybrid electric vehicle), range (below 150 km (urban), 150-300 km (regional), 301-500 km (long-haul), and above 500 km (extended)), battery capacity (≤200 kWh, 201-400 kWh, 401-800 kWh, and above 800 kWh), motor architecture (single-motor direct drive, dual-motor, integrated eAxle, and in-wheel hub motor), and application (logistics and parcel, municipal services, construction and mining, retail and FMCG delivery, and utility and other industrial). The analysis also covers country-level segmentation, including the United States, Canada, and Mexico. Market size and growth forecasts are presented by value in USD and by volume in units.
Segmentation Overview
By Truck Type
| Light Truck (Less than/Equals 3.5 t) |
| Medium-Duty Truck (3.6-12 t) |
| Heavy-Duty Truck (Above 12 t) |
By Propulsion Type
| Battery Electric Vehicle (BEV) |
| Fuel-Cell Electric Vehicle (FCEV) |
| Plug-in Hybrid Electric Vehicle (PHEV) |
| Hybrid Electric Vehicle (HEV) |
By Range
| Below 150 km (Urban) |
| 150-300 km (Regional) |
| 301-500 km (Long-Haul) |
| Above 500 km (Extended) |
By Battery Capacity
| Less than/Equals 200 kWh |
| 201-400 kWh |
| 401-800 kWh |
| Above 800 kWh |
By Motor Architecture
| Single-Motor Direct Drive |
| Dual-Motor |
| Integrated eAxle |
| In-Wheel Hub Motor |
By Application
| Logistics and Parcel |
| Municipal Services (Waste, Street-sweep) |
| Construction and Mining |
| Retail and FMCG Delivery |
| Utility and Other Industrial |
By Country
| United States | California |
| Texas | |
| Florida | |
| New York | |
| Illinois | |
| Washington | |
| Pennsylvania | |
| Ohio | |
| Michigan | |
| Georgia | |
| North Carolina | |
| New Jersey | |
| Virginia | |
| Canada | Ontario |
| Quebec | |
| British Columbia | |
| Alberta | |
| Manitoba | |
| Saskatchewan | |
| Nova Scotia | |
| New Brunswick | |
| Newfoundland and Labrador | |
| Prince Edward Island | |
| Mexico | Baja California |
| Sonora | |
| Chihuahua | |
| Nuevo Leon | |
| Coahuila | |
| Jalisco | |
| Guanajuato | |
| Estado de Mexico | |
| Puebla | |
| Veracruz | |
| Yucatan | |
| Quintana Roo |
| By Truck Type | Light Truck (Less than/Equals 3.5 t) | |
| Medium-Duty Truck (3.6-12 t) | ||
| Heavy-Duty Truck (Above 12 t) | ||
| By Propulsion Type | Battery Electric Vehicle (BEV) | |
| Fuel-Cell Electric Vehicle (FCEV) | ||
| Plug-in Hybrid Electric Vehicle (PHEV) | ||
| Hybrid Electric Vehicle (HEV) | ||
| By Range | Below 150 km (Urban) | |
| 150-300 km (Regional) | ||
| 301-500 km (Long-Haul) | ||
| Above 500 km (Extended) | ||
| By Battery Capacity | Less than/Equals 200 kWh | |
| 201-400 kWh | ||
| 401-800 kWh | ||
| Above 800 kWh | ||
| By Motor Architecture | Single-Motor Direct Drive | |
| Dual-Motor | ||
| Integrated eAxle | ||
| In-Wheel Hub Motor | ||
| By Application | Logistics and Parcel | |
| Municipal Services (Waste, Street-sweep) | ||
| Construction and Mining | ||
| Retail and FMCG Delivery | ||
| Utility and Other Industrial | ||
| By Country | United States | California |
| Texas | ||
| Florida | ||
| New York | ||
| Illinois | ||
| Washington | ||
| Pennsylvania | ||
| Ohio | ||
| Michigan | ||
| Georgia | ||
| North Carolina | ||
| New Jersey | ||
| Virginia | ||
| Canada | Ontario | |
| Quebec | ||
| British Columbia | ||
| Alberta | ||
| Manitoba | ||
| Saskatchewan | ||
| Nova Scotia | ||
| New Brunswick | ||
| Newfoundland and Labrador | ||
| Prince Edward Island | ||
| Mexico | Baja California | |
| Sonora | ||
| Chihuahua | ||
| Nuevo Leon | ||
| Coahuila | ||
| Jalisco | ||
| Guanajuato | ||
| Estado de Mexico | ||
| Puebla | ||
| Veracruz | ||
| Yucatan | ||
| Quintana Roo | ||
Market Definition
- Vehicle Type - The category covers truck category.
- Vehicle Body Type - This includes Medium-duty Commercial Trucks and Heavy-duty Commercial Trucks
- Fuel Category - The category includes various fuel types such as Gasoline, Diesel, LPG (Liquefied Petroleum Gas), CNG (Compressed Natural Gas), HEV (Hybrid Electric Vehicles), PHEV (Plug-in Hybrid Electric Vehicles), BEV (Battery Electric Vehicles), and FCEV (Fuel Cell Electric Vehicles)
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


