
Nigeria Air Freight Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
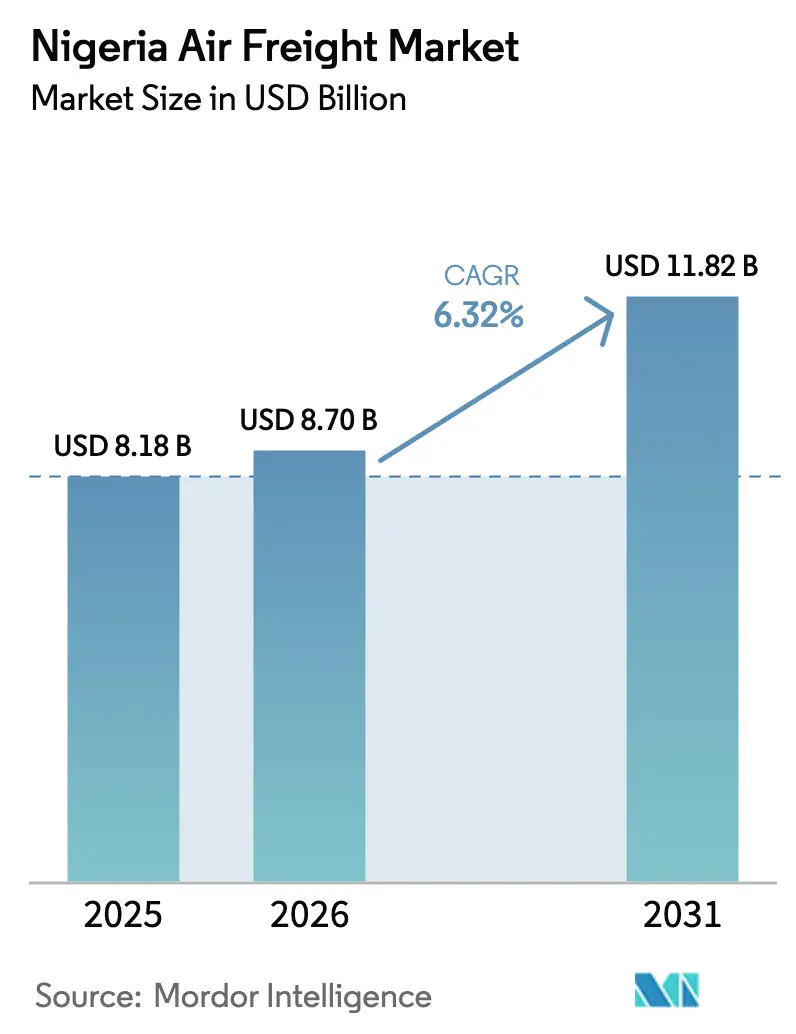
| Base Year Market Size (2025) | USD 8.18 Billion |
| Market Size (2026) | USD 8.7 Billion |
| Market Size (2031) | USD 11.82 Billion |
| Growth Rate (2026 - 2031) | 6.32 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Nigeria Air Freight Market Analysis by Mordor Intelligence
The Nigeria Air Freight Market size was valued at USD 8.18 billion in 2025 and estimated to grow from USD 8.7 billion in 2026 to reach USD 11.82 billion by 2031, at a CAGR of 6.32% during the forecast period (2026-2031).
Growth is anchored by the country’s position as West Africa’s main economic hub, which pulls high-value, time-critical shipments toward air transit even as basic infrastructure struggles to keep pace. International routes still move the bulk of volume, yet domestic lanes—energised by fast-growing e-commerce networks and new cargo-friendly airports—are increasing more quickly and gradually reducing Nigeria’s dependency on cross-border flows. Ongoing customs digitisation is cutting clearance times and lowering transaction costs, encouraging exporters of perishables and pharmaceuticals to make greater use of air lift. Airlines are adding dedicated freighters and refining cold-chain services to match rising demand from healthcare shippers, while competitive fare cuts triggered by new entrants underscore how pricing pressure can swiftly reshape capacity decisions. Persistent jet-fuel price swings and currency volatility remain real headwinds, but operators are adapting through fleet upgrades and closer supplier partnerships, keeping overall growth on track.
Key Report Takeaways
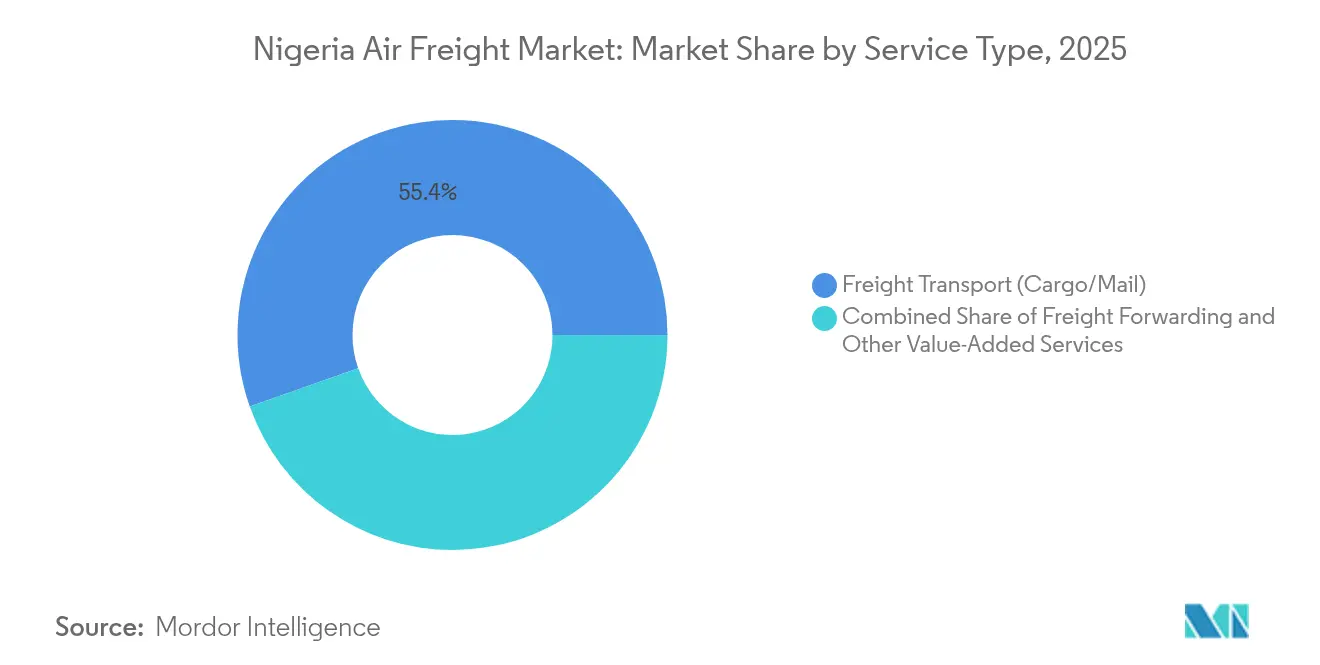
- By service type, freight transport commanded 55.40 % market share in 2025, while value-added services are set to grow the fastest at a 10.92 % CAGR through 2031.
- By destination, international routes held 80.20 % of market size in 2025; domestic air freight is forecast to expand at a 9.35 % CAGR to 2031.
- By carrier type, belly cargo accounted for 53.60 % of traffic in 2025, whereas dedicated freighters are expected to post the highest CAGR of 9.85 % during the forecast period.
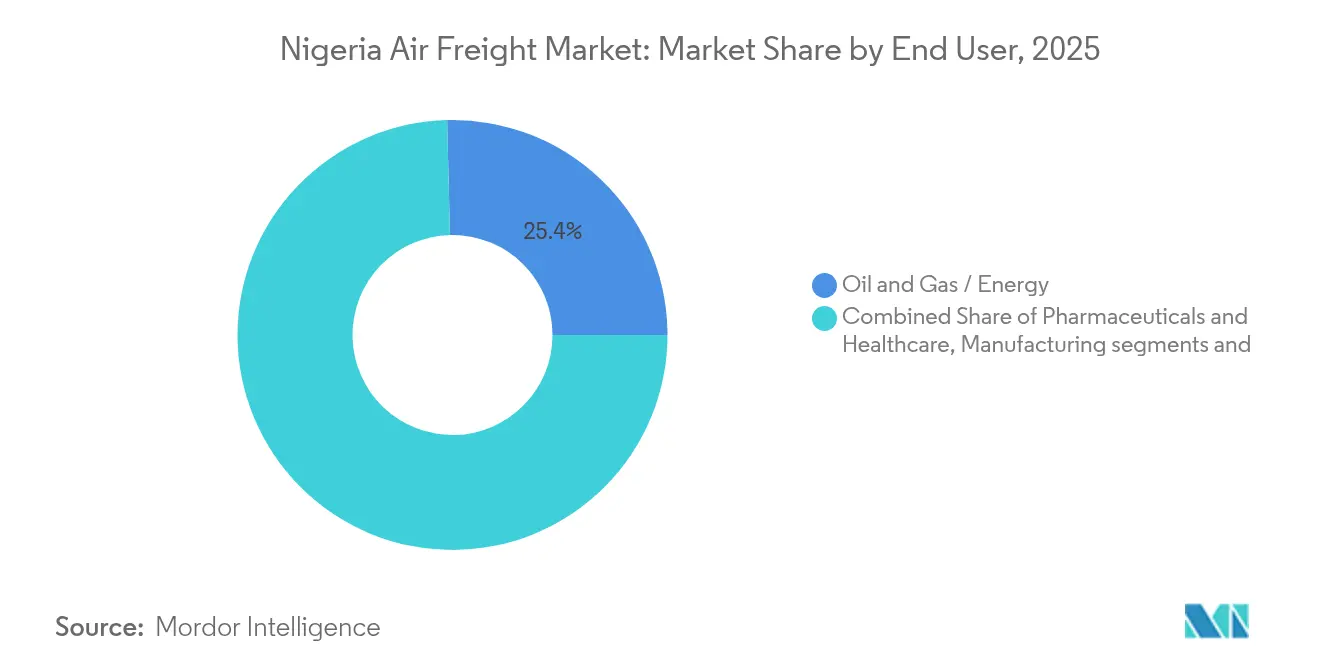
- By end-user industry, oil & gas dominated with a 25.40 % share in 2025, while pharmaceuticals and healthcare lead growth prospects at an 10.83 % CAGR to 2031.
- By cargo type, general cargo represented 72.20 % of the market size in 2025; special cargo is projected to rise fastest with a 10.42 % CAGR through 2031.
- By geography, the South West region captured 46.80 % of market share in 2025, and North Central is positioned for the strongest regional growth at a 11.40 % CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Nigeria Air Freight Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing E-commerce Penetration Boosting B2C Air Cargo Volumes | +1.8% | National (Lagos-Abuja axis) | Medium term |
| Oil and Gas Project Time-Critical Logistics Demand | +1.5% | Delta region, Lagos | Short term |
| Pharma Cold-Chain Expansion Around Lagos-Abuja Corridor | +1.2% | Lagos-Abuja corridor | Medium term |
| Perishable Agri-Export Programs (Shea Butter, Flowers, Sea-Food) | +0.90% | Agricultural belts to Lagos | Medium term |
| Nigeria Customs Process Digitization (Trade Single Window) | +1.40% | National | Short term |
| Regional Hub-Spoke Connectivity via Ethiopian & Emirates Interline Agreements | +1.00% | Lagos outward | Medium term |
| Source: Mordor Intelligence | |||
Growing E-commerce Penetration Boosting B2C Air Cargo Volumes
Rapid adoption of online retail is driving a noticeable uptick in smaller, higher-frequency consignments that move best by air. Express operators say daily tonnage has begun to outstrip pre-pandemic highs, even though overall capacity additions remain modest. Because shoppers expect two-day delivery nationwide, merchants now embed air freight costs into product pricing as a standard rather than a premium service. This behavioural change is reshaping airline belly-hold planning, with carriers allocating more square metres to loose parcels instead of palletised freight.
Oil and Gas Project Time-Critical Logistics Demand
Large energy investments such as the multi-billion-dollar Ogidigben Gas Revolution Industrial Park and the recently commissioned Dangote refinery require precision equipment that cannot risk maritime delays. Charter brokers consequently report higher utilisation of nose-loader freighters capable of lifting out-of-gauge pieces into Niger Delta airstrips. By fulfilling maintenance-critical deliveries within hours, air freight is directly supporting project timelines, and in turn, the sector’s capital inflow reinforces Nigeria Air Freight industry revenue. The pattern underlines how a single mega-project can ripple across forwarding, ground handling, and regional airport development.
Pharma Cold-Chain Expansion Around the Lagos-Abuja Corridor
Investments in temperature-controlled warehouses at Lagos and Abuja airports have expanded available cold storage by thousands of pallet positions. Airlines are responding with dedicated cool-dolly fleets and real-time monitoring to meet stringent pharmaceutical handling protocols. As vaccines and biotechnological products move through these corridors, failure-rate data show a steady decline, encouraging even conservative shippers to choose air instead of costly refrigerated trucking. This virtuous cycle is positioning Nigeria as an emerging West-African distribution hub for temperature-sensitive medicine.
Perishable Agri-Export Programs (Shea Butter, Flowers, Sea Food)
Government-backed export corridors now link northern crop clusters directly with Lagos cargo terminals, reducing dwell times for produce such as shea butter and cut flowers. Exporters have started negotiating seasonal block-space agreements with carriers, a practice that was rare five years ago. Indications are that air-lifted perishables are achieving higher price realisations abroad than equivalent sea shipments, encouraging farmers to plant varieties suited for the air channel. This development also diversifies the Nigeria Air Freight market away from its historic dependence on inbound consumer goods.
Restraints Impact Analysis*
| Restraint | (~)% Impact on Market CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic Jet-A1 Supply Disruptions Driving Cost Volatility | –1.2 % | National | Short term |
| Airport Cargo Infrastructure Congestion (Lagos MMIA) | –1.1 % | Lagos MMIA | Medium term |
| High Security Surcharges Due to Cargo Pilferage Risk | –0.8 % | National | Short term |
| Naira FX Liquidity Constraints Impacting Freight Payments | –1.3 % | National | Short term |
| Source: Mordor Intelligence | |||
Chronic Jet-A1 Supply Disruptions Driving Cost Volatility
Frequent spikes in aviation fuel prices force carriers to adopt dynamic surcharges that complicate budgeting for shippers. Although some airlines hedge, most Nigerian operators rely on spot purchases, making them vulnerable to exchange-rate swings. These pressures accelerate the search for fuel-efficient aircraft such as B737-800BCF conversions, which promise lower burn per tonne-kilometre. A trend toward strategically staging uplift in neighbouring states with steadier supply is also emerging, indirectly stimulating regional cooperation.
Airport Cargo Infrastructure Congestion (Lagos MMIA)
Lagos Murtala Muhammed International Airport is nearing its physical limits, with ramp congestion at peak hours causing delays and additional ground handling fees. Cargo handlers have begun implementing appointment-based truck docks to smooth gate arrivals, mimicking best practices at larger global hubs. As a result, airlines capable of operating off-peak schedules gain a competitive edge because they avoid ground queues. The congestion challenge is prompting renewed calls for a dedicated cargo airport or at least significant apron expansion to safeguard future Nigeria Air Freight market growth.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
Service Type: Value-Added Services Outpace Core Transport
Value-Added Services are forecast to expand their Nigeria Air Freight market share rapidly, with the segment’s market size expected to post a 10.92 % CAGR between 2026 and 2031. Customs brokerage, insurance, and specialised packaging now often bundle with transport in one invoice, and shippers increasingly regard these extras as indispensable rather than optional. Digital customer portals introduced by forwarders allow real-time milestone visibility, which strengthens loyalty and drives repeat business. A visible outcome is that freight operators now recruit compliance specialists almost as aggressively as they hire load-planners.
Freight Transport (Cargo and Mail), which holds 55.40 % of current revenue, remains indispensable because it underpins all other offerings. Yet its relative share is slowly eroding as logistics providers monetise ancillary activities with higher margins. Carriers that once sold only space are pivoting toward door-to-door solutions, capturing greater wallet share per shipment. This transition illustrates how the Nigeria Air Freight industry is moving up the value chain in response to client expectations.


Destination: Domestic Routes Gain Momentum
International services currently represent 80.20 % of Nigeria Air Freight market size, sustained by outbound crude-oil-linked spare parts and inbound consumer electronics. The segment benefits from extensive intercontinental belly capacity on routes to Europe and the Middle East, keeping unit rates comparatively competitive. Nevertheless, its CAGR is projected below the domestic segment because lanes are close to maturity on frequency and gauge. Continuous diversification into non-oil exports is expected to prevent stagnation, but growth will likely track global GDP more than local structural shifts.
Domestic air freight is forecast to grow at a 9.35 % CAGR through 2031, outpacing all other destination categories. E-commerce fulfilment and pharmaceutical resupply along the Lagos-Abuja spine are prime contributors. New cargo-friendly terminals in Maiduguri and Kano shorten distances to underserved northern markets, making next-day delivery economically viable. As shippers gain confidence in schedule reliability, modal substitution from road to air should continue, particularly during the rainy season.
Carrier Type: Freighters Gaining Market Share
Dedicated freighters are projected to lift their Nigeria Air Freight market share to parity with belly cargo by the end of the decade, supported by an 9.85 % CAGR. Growth is propelled by specialised needs such as temperature-controlled pharmaceuticals and outsized industrial parts that cannot fit in passenger holds. Nigerian operators adding converted narrow-body freighters gain flexibility to serve secondary airports with limited ground equipment. This fleet evolution also opens overnight express opportunities that belly-hold schedules cannot match.
Belly cargo retains advantages on high-density intercontinental routes, currently commanding a 53.60 % share of tonnage. Its competitiveness stems from marginal cost economics, where freight rates chiefly cover handling rather than airframe operation. The main risk is that any unforeseen passenger demand slump could remove lift, pushing shippers toward dedicated freighter contracts. Consequently, belly-heavy airlines are incentivised to maintain balanced passenger strategy to secure freight loyalty.
End-User Industry: Pharmaceuticals Lead Growth Trajectory
Oil and gas maintains the largest single Nigeria Air Freight market share at 25.40 %, yet its growth trajectory is modest compared with emerging verticals. The sector’s heavy-lift and urgent-part requirements generate consistent charter work, and value-added forwarders now deliver cradle-to-site solutions within the Niger Delta. Still, gradual energy transition policies worldwide signal that diversification will be prudent for carriers. As local refineries reach steady state, maintenance rather than construction will dominate future movements, slightly dampening volume escalation.
Pharmaceuticals and healthcare are forecast to register a 10.83 % CAGR between 2026 and 2031, the fastest in the market. Expansion of accredited cold rooms and real-time temperature mapping has reassured global manufacturers that Nigeria can meet Good Distribution Practice standards. As a result, vaccine distributors increasingly position regional stock in Lagos for re-export to neighbouring countries, amplifying throughput. This phenomenon showcases how infrastructure maturity can unlock entirely new revenue streams.
Cargo Type: Special Cargo Driving Innovation
General Cargo dominates the Nigeria Air Freight Market with a 72.20% share in 2025, encompassing the broad range of standardized shipments that form the backbone of air freight operations. This predominance reflects the versatility and cost-efficiency of general cargo handling for many commodity types. However, the market is witnessing a significant shift toward Special Cargo, which is projected to grow at a CAGR of 10.42% (2026-2031), nearly double the overall market growth rate of 6.32%.
This accelerated growth in Special Cargo is being driven by increasing demand for specialized handling of temperature-sensitive pharmaceuticals, perishable agricultural exports, and high-value oil and gas equipment. The trend is prompting investments in specialized facilities and equipment, with airlines enhancing their operations to include temperature-controlled environments for pharmaceuticals and other sensitive goods. The air cargo industry's adaptation to post-COVID requirements has further accelerated innovations in special cargo handling, particularly for cold chain logistics. This evolution is creating new competitive dynamics as carriers and handling agents differentiate through specialized capabilities, with collaborative approaches emerging to enhance cold chain infrastructure and improve the efficiency of special cargo operations.
Geography Analysis
The South West region commands 46.80 % market share of the Nigeria Air Freight market in 2025, giving it the largest regional market size and consolidating its long-standing status as the nation’s primary logistics gateway. Lagos’s Murtala Muhammed International Airport (MMIA) alone processes roughly 47,000 metric tons of freight each year, anchoring a dense network of ground handlers and express integrators that few other Nigerian airports can currently match . The presence of large-scale manufacturing zones, Nigeria’s biggest consumer base, and the USD 21 billion Dangote refinery complex keeps south-west outbound lifts steady throughout the year. These structural advantages allow airlines to schedule multiple daily wide-body rotations, which in turn creates attractive frequency for small-parcel e-commerce shipments. An important knock-on effect is that the region’s abundant belly capacity holds line-haul rates in check, indirectly lowering logistics costs for shippers elsewhere in the country who trans-ship through Lagos. Even so, rising congestion at MMIA is prompting some forwarders to pre-book off-peak slots, an operational workaround that underlines the value of dependable time windows for temperature-sensitive cargo.
North Central is forecast to post a 11.40 % CAGR between 2026 and 2031, meaning its market size is expanding almost twice as fast as the national average. Abuja’s steadily growing role as a consolidation hub for domestic distribution explains much of this momentum; the city’s more temperate climate supports cold-chain reliability, making it the logical midpoint on the Lagos–Abuja pharmaceutical corridor. Recent investments in GDP-compliant storage have reduced temperature excursions on biologics shipments, encouraging healthcare producers to base regional inventory in the capital. As volumes rise, forwarders are moving to daily narrow-body freighter services rather than ad-hoc road transfers, a shift that frees capacity at Lagos while improving product shelf life. The region’s growth also benefits from improved road and rail links that shorten trucking legs into the Middle Belt, where agricultural producers can now reach urban markets faster. The inference emerging from these developments is that Abuja’s hub function is transforming from political epicentre to indispensable logistics pivot for time-critical consignments nationwide.
Although North West and North East currently account for modest slices of Nigeria Air Freight market share, infrastructure upgrades point to accelerating expansion. The completion of the Maiduguri runway extension allows international wide-body operations from January 2025, positioning the city as a new entry point for humanitarian aid and seasonal crop exports . In parallel, the reopened Nigeria–Niger border at Jibiya-Maradi has revived land trade worth hundreds of millions of dollars annually, giving air-to-road routings fresh relevance for high-value goods moving into the Sahel . The planned Chinese-funded railway from Kano to Maradi will further stitch together air, rail and road legs, potentially lowering last-mile costs for exporters that fly produce out of Kano’s Mallam Aminu Kano International Airport. As dedicated freighters obtain traffic rights to these revamped gateways, local farmers and spare-parts suppliers gain access to time-definite services once obtainable only through Lagos. The likely outcome is a gradual narrowing of the regional share gap as northern airports capture niche, high-yield cargo streams that thrive on reduced ground transit times.
Regulatory Landscape
Nigeria air freight operates under the Nigeria Civil Aviation Regulations (Nig. CARs 2023), administered by the Nigeria Civil Aviation Authority (NCAA). The rules include provisions covering areas such as dangerous goods handling and air transport economic oversight. For market entry and compliance in forwarding, the NCAA guidelines for registration of air freight forwarders require a minimum authorized share capital of NGN 2,000,000, which shapes participation and formalization across the forwarding ecosystem.
On trade facilitation and operational control, agencies are tightening data visibility and moving airport cargo community processes toward digitization. The Federal Airports Authority of Nigeria (FAAN) has been progressing a centralized cargo-operator data approach through an Integrated Cargo Stakeholders Registry (ICSR), while the Council for the Regulation of Freight Forwarding in Nigeria (CRFFN) has mandated stakeholder registration on a national air cargo registry framework, improving traceability across shippers, forwarders, and handling entities.
Value Chain Analysis
Nigeria's air freight value chain runs from shippers (including oil and gas, pharmaceuticals, perishables, and retail parcels) to freight forwarders and consolidators, and then to airlines (belly cargo and dedicated freighters). Ground handlers at key gateways, notably Lagos MMIA and Abuja, connect air movements to onward domestic line-haul via trucking into distribution nodes along the Lagos-Abuja axis and toward northern markets. International flows generally route through hubbed networks of large foreign carriers, such as Ethiopian Airlines Cargo and Emirates SkyCargo, while domestic and regional distribution depends more on local operators and charter activity for time-critical and outsize movements.
Value capture concentrates in regulated and capacity-constrained nodes, including airport cargo terminals, screening and inspection, cold-chain storage, and ground handling. Congestion and compliance requirements add cost, but they also create differentiation for operators that can meet service standards consistently. Dedicated-freighter operators such as Allied Air, operating Boeing 737-400F aircraft (around 20,000 kg payload class) from a Lagos-led network, show how narrow-body freighters feed secondary airports and support express-like schedules. As digitization of manifests and stakeholder registries progresses, handoffs between forwarders, handlers, and border agencies increasingly hinge on data completeness and process adherence, not only on uplift availability.
Competitive Landscape
International mega-carriers continue to dominate headline capacity, but local airlines are reshaping competition through nimble route choices and pricing. Ethiopian Airlines Cargo leverages Addis Ababa’s integrated hub to feed Nigerian traffic into intercontinental freighters, offering shippers reliable transit times that match European benchmarks. Emirates SkyCargo’s commitment to double overall capacity this decade, including new freighters earmarked for African lanes, signals long-run intent to defend share. These moves compel Nigerian operators to specialise in segments where local knowledge adds tangible value, such as inland trucking integration and regulatory navigation.
Domestic challenger Air Peace has proven that aggressive fare strategies on passenger services can shift cargo dynamics by injecting fresh belly capacity and stimulating rate competition. Its London launch quickly led to fare reductions by foreign rivals, demonstrating price elasticity in both passenger and freight markets. Although such tactics squeeze margins, they also raise utilisation, which can offset lower yields if managed carefully. The episode illustrates how a single local entrant can reprice entire corridors, forcing incumbents to reassess allocation of wide-body assets.
Specialisation is the new battleground. Handling agents at Lagos are pursuing Good Distribution Practice certification to court pharmaceutical traffic, while forwarders are investing in online booking portals that quote door-to-door rates in real time. Security accreditation has become another differentiator, with technology such as tamper-evident seals and GPS-tracked trucks extending protection beyond the airport perimeter. As shippers grow more discerning, carriers lacking either niche capability or credible alliances risk relegation to rate-taker status, underscoring the importance of continuous service innovation.
Nigeria Air Freight Industry Leaders
Ethiopian Airlines Cargo
Emirates SkyCargo
Turkish Cargo
DHL Aviation
Allied Air
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Airport and border process modernization is creating room for time-definite services and higher-yield special cargo handling. In July 2026, the Nigeria Customs Service moved to deploy non-intrusive inspection capability (cargo scanners) at Nnamdi Azikiwe International Airport, Abuja, targeting faster cargo inspections and improved controls. This supports forwarders, handlers, and integrators building premium offerings around shorter dwell times and more predictable release windows. NCAA-led discussions around a Pre-Loading Advance Cargo Information (PLACI) approach also point toward earlier data submission and risk-based screening, which can improve planning for airlines and handlers and reduce exceptions and rework for compliant shippers.
Capacity and network opportunities are also taking shape as cargo gateway diversification efforts move beyond Lagos MMIA. Cargo-operations plans tied to Gateway International Airport, Iperu (Ogun State), including initiatives involving Allied Air and airport service partners, aim to decongest Lagos while building new feeder patterns for e-commerce parcels, perishables, and light manufacturing exports. With international routes still dominating total volume, Nigeria-focused players that pair airport-side compliance and cold-chain readiness with domestic trucking integration have clearer pathways to expand door-to-door offerings, especially along the Lagos-Abuja corridor and on northbound lanes supported by upgraded regional airports.
Recent Industry Developments
- July 2026: Commissioned a new cargo facility at the General Aviation Terminal in Lagos as part of the Cargo Village project and mandated use of National Single Window for cargo manifests. The facility expands Lagos cargo throughput by integrating digital clearance workflows, enhancing end-to-end efficiency. Decongests Lagos hub and accelerates digitized cargo clearance.
- July 2026: Begin readiness assessments for deployment of CX180 180DH pallet cargo scanners at Nnamdi Azikiwe International Airport, Abuja awaiting regulatory approval. The move strengthens security protocols while improving throughput efficiency at a strategic Nigerian gateway. Improves inspection efficiency and revenue assurance at a key Nigerian gateway.
- June 2026: NAHCO (Nigerian Aviation Handling Company) secured a three-year cargo handling contract with FlyGabon and renewed contracts with Qatar Airways, Saudia Airlines, and ASKY Airlines. The expansion deepens cargo handling capacity and strengthens carrier partnerships across the region. Expands high-value export and inbound traffic throughput via Nigeria gateways.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Nigeria air freight market is sized as the gross revenue earned from moving cargo and mail by air within Nigeria and on international routes connected to Nigeria, including the main service and handling charges typically billed in the shipment flow.
Scope exclusions: Military airlift and purely private, non-commercial carriage are excluded from the market value.
Segmentation Overview
- By Service Type
- Freight Transport (Cargo/Mail)
- Freight Forwarding
- Other Value-Added Services (Customs brokerage, insurance, etc.)
- By Destination
- Domestic
- International
- By Carrier Type
- Belly Cargo
- Freighter
- By End-User Industry
- Manufacturing
- Oil & Gas / Energy
- Pharmaceuticals & Healthcare
- Perishables & Food
- Retail & Consumer Goods
- Others
- By Cargo Type
- General Cargo
- Special Cargo
- By Region (Nigeria)
- South West
- South South
- South East
- North Central
- North West
- North East
Data Sources, Market Sizing, and Validation
Desk Research
Desk work begins with building a simple fact base around Nigeria air cargo activity and trade context, then translating that activity into value using observable pricing and operational markers. Public sources help anchor the demand pool, especially when volumes shift around major holidays, FX pressure, or airport capacity constraints.
We typically refer to non-paywalled sources such as National Bureau of Statistics air transport reports, Federal Airports Authority of Nigeria cargo throughput disclosures, Nigeria Customs Service trade releases, World Bank macro indicators, and ICAO datasets where available for cross-checking. We also review airline and logistics company filings and presentations, reputable press coverage, and airport operator updates for route additions and capacity changes. For fill-in checks, selective paid subscriptions are used for company financials and intelligence, news and financials, and shipment-level import and export patterns. These desk sources are illustrative, and many other public and proprietary references are also used to collect, validate, and clarify data points.
Primary Interviews and Surveys
We use interviews and surveys with airline, airport-handling, freight-forwarding, customs, and shipper professionals working in Nigeria. Their input helps clarify cargo tonnage, freight yields, route mix, and value-added fees, while also filling gaps in airport and carrier records. These discussions provide a check on the assumptions used before final review.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 18% |
| Mid tier: 48% | Functional/Unit leaders: 30% |
| Smaller Players: 25% | Managers: 52% |
Market-Sizing & Forecasting
Sizing starts from a top-down build where airport cargo throughput and trade-linked demand signals are used to reconstruct the payable air freight activity tied to Nigeria, then the value is derived using validated yield and service-charge assumptions. Once that first total is formed, it is corroborated with selective bottom-up approximations, such as sampled rate-per-kg by corridor multiplied by estimated tonnage splits, plus channel checks with forwarders to make sure the totals behave like the real market.
Key inputs we track include airport cargo tonnage by major gateways, import versus export mix, domestic versus international share, freighter versus belly capacity availability, and average yield movements in USD (with currency timing kept consistent for the base year). Where direct pricing is patchy, gaps are handled through corridor-based ranges and conservative midpoint selection, which is then stress-tested with primary feedback. For forecasting, we mainly use scenario analysis supported by a short multivariate regression check, where variables like GDP and trade direction, capacity additions, and fuel-driven pricing pressure are used to shape the outlook and then reviewed with expert consensus before finalizing the curve.
Data Validation & Update Cycle
Validation is done through repeated cross-checks so the value estimate stays tied to observable cargo activity and realistic pricing. Model outputs are compared against independent signals such as throughput trends at key airports, trade direction patterns, and known capacity shifts, and then unusual jumps are investigated before sign-off.
A second analyst review is completed to confirm math integrity, assumptions, and year alignment, and follow-up calls are triggered when a large variance appears by corridor or service line. The report is refreshed annually, with interim updates when material events occur, and a final pre-delivery pass is completed so clients receive the latest updated view.
Mordor Intelligence's Nigeria Air Freight Market Size Compared Against Other Published Estimates
Different published market sizes can look far apart because the underlying revenue pool is not always defined in the same way, and because some authors lean more on volume proxies without fully matching them to billable charges. In air freight, even small differences in what gets counted as chargeable activity can shift the final value meaningfully.
Forwarding and ground handling revenues are outside Mordor Intelligence's scope, so estimates that add these adjacent logistics services into the same total will naturally show a larger number even if the tonnage view is similar.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 8.18 B (2025) | |
| Global Consultancy A | USD 3.08 B (2024) | Uses a narrower value pool closer to airline line-haul only, and does not fully price in domestic legs and common accessorial charges that are typically billed in Nigeria-linked air cargo moves. |
| Regional Consultancy B | USD 3.01 B (2025) | Builds from a limited airport set and applies a near-constant yield assumption across corridors, which can understate value when international mix and premium cargo shares rise. |
Taken together, the spread mostly comes from what revenue lines are included and how yields are translated from tonnage into USD value. Our estimate is designed to be repeatable because it ties activity to clear throughput signals, applies corridor-sensitive pricing checks, and then re-tests the totals with practitioner feedback before final numbers are locked.


Key Questions Answered in the Report
What is the current Nigeria Air Freight market size?
The market is valued at roughly USD 8.7 billion in 2026, with steady growth anticipated through 2031.
Which segment is growing fastest in the Nigeria Air Freight industry?
Pharmaceuticals and healthcare show the highest projected CAGR because of expanding cold-chain infrastructure and rising healthcare demand.
Why is domestic air cargo growing faster than international cargo?
E-commerce expansion, improved regional airports, and dedicated corridors for perishables are accelerating internal flows, boosting domestic CAGR above international lanes.
How are fuel price fluctuations affecting air-freight operators in Nigeria?
Jet-A1 volatility raises operating costs and drives frequent surcharge adjustments, pushing airlines to seek more fuel-efficient fleets and alternate refuelling points.
Which airports are emerging as alternatives to Lagos for cargo traffic?
Upgraded facilities in Abuja, Maiduguri, and Kano are attracting pharmaceuticals, humanitarian aid, and regional trade consignments, gradually easing pressure on Lagos.
How is digital customs reform influencing the market?
The National Single Window system reduces paperwork and clearance lead times, making air freight more attractive for importers and exporters who value speed.
Page last updated on:





