
India Road Freight Transport Market Analysis by Mordor Intelligence
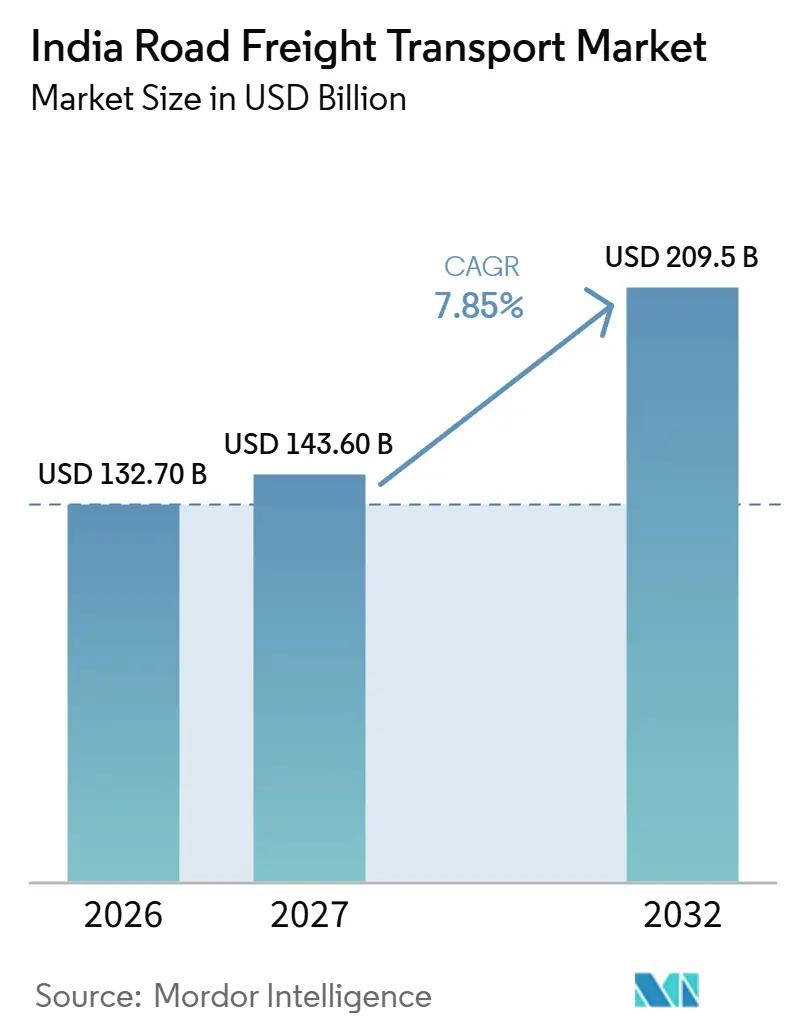
The India road freight transport market size is expected to increase from USD 132.7 billion in 2026 to USD 143.6 billion in 2027 and reach USD 209.5 billion by 2032, growing at a CAGR of 7.85% over 2027-2032.
India's manufacturing expansion and widening fast-moving consumer goods (FMCG) distribution strengthen demand for coordinated road movements between production centers and dispersed customers. Providers can respond through network visibility and access to partner vehicles, bringing shipment requirements and available transport capacity into a connected service. The West Asia conflict drove a crude-price spike beginning on February 28, 2026, adding fuel-cost pressure to this expansion. Stronger demand can translate into carrier revenue only when staffed capacity supports dependable dispatch and freight charges recover operating costs.
Key Report Takeaways
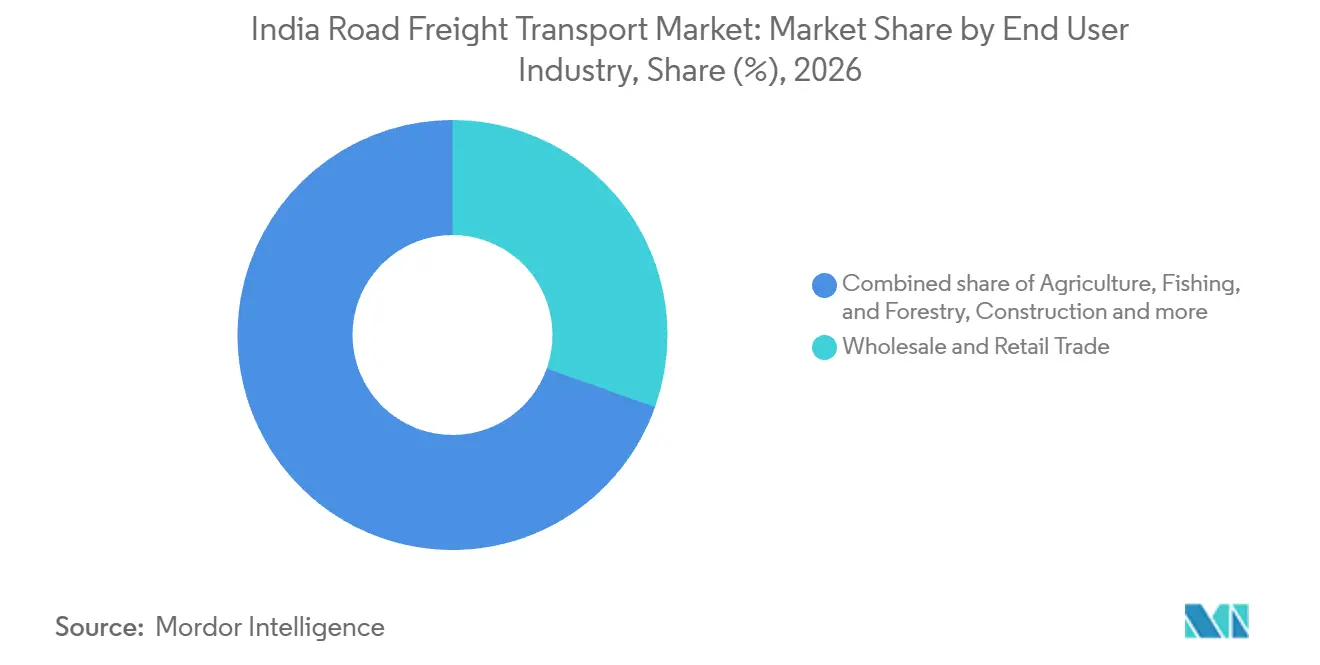
- By end user industry, wholesale and retail trade held a 30.44% India road freight transport market share in 2026, and manufacturing is forecast to be the fastest-growing segment with a 9.95% CAGR over 2027-2032.
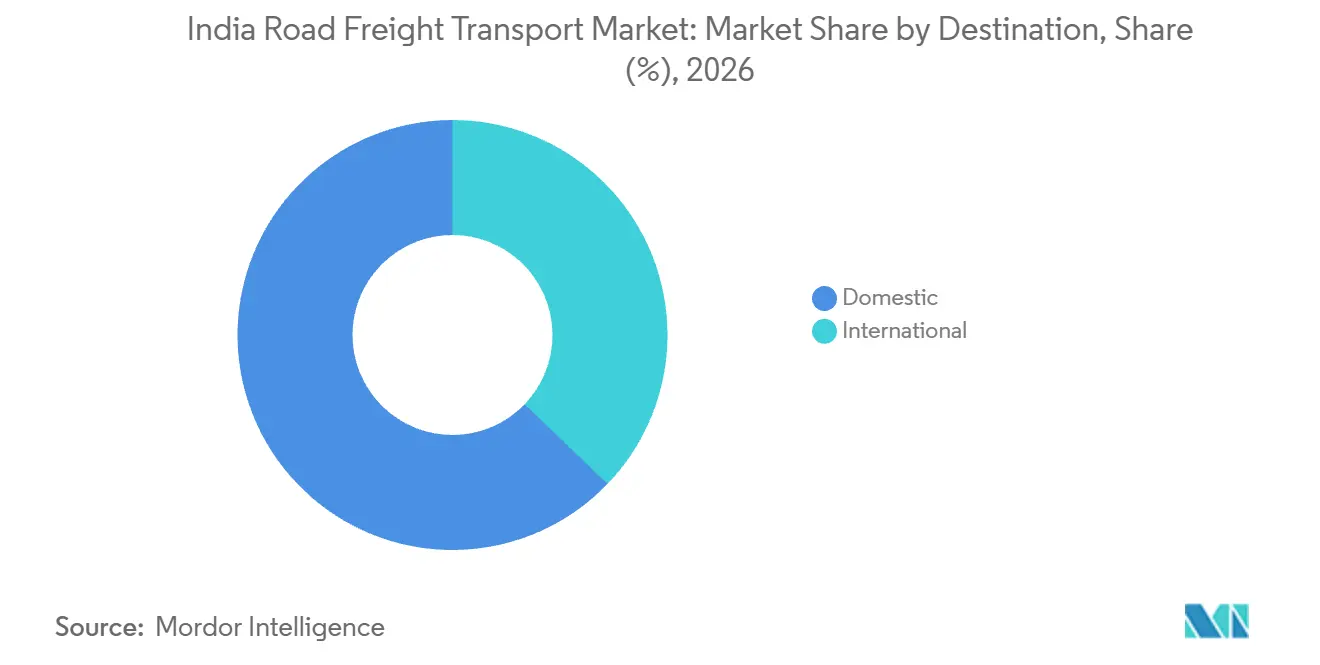
- The destination mix was led by domestic transport, with a 62.82% share of the India road freight transport market size in 2026, while international transport is forecast to grow fastest at an 8.85% CAGR over 2027-2032.
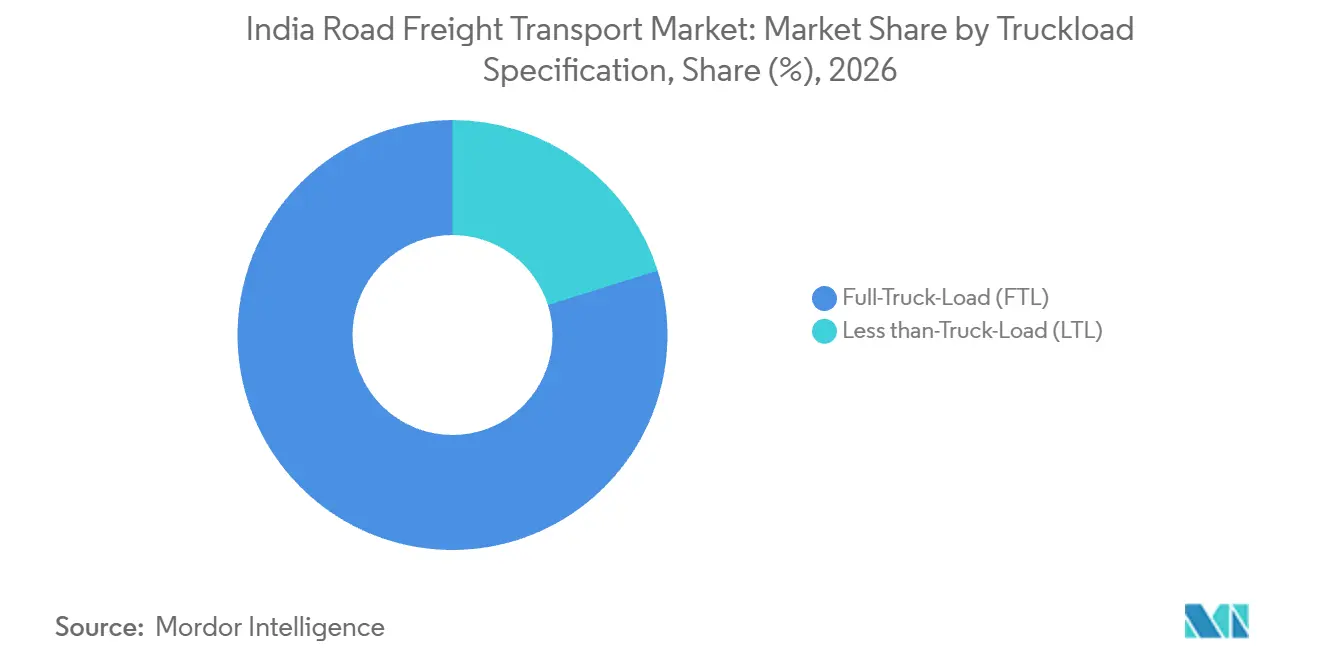
- Full-truck-load (FTL) services led the truckload specification mix with a 79.84% share in 2026, while less than-truck-load (LTL) services are forecast to grow fastest at a 9.85% CAGR over 2027-2032.
- By containerization, non-containerized freight accounted for 86.31% of road freight service value in 2026, and containerized freight is the fastest-growing segment with an 8.78% CAGR forecast over 2027-2032.
- The distance mix favored long-haul transport, which held a 75.42% share in 2026, whereas short-haul transport is forecast to grow fastest at an 8.85% CAGR over 2027-2032.
- Goods configuration was led by solid goods, with 72.88% of road freight service value in 2026, while fluid goods are forecast to grow fastest at a 9.17% CAGR over 2027-2032.
- Non-temperature-controlled services led the temperature-control mix with a 94% share in 2026, while temperature-controlled services are forecast to grow fastest at a 9.4% CAGR over 2027-2032.
- Geographically, western and southern corridors led overall freight volumes in 2025, while Southern India's fast-growth trajectory extends through 2031.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Road Freight Transport Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Manufacturing Push Under Make in India Initiative | +3% | Nationwide | Long term (≥ 4 years) |
| Rising FMCG Distribution into Rural & Semi-Urban Markets | +2.2% | Nationwide | Medium term (2-4 years) |
| Growth in Construction & Infrastructure Material Movement | +2.4% | Nationwide | Medium term (2-4 years) |
| Warehousing Expansion Across Tier-2 and Tier-3 Cities | +1.8% | Indore, Madhya Pradesh | Medium term (2-4 years) |
| Dedicated Freight Corridors Supporting Multimodal Integration | +0.9% | New Rewari to New Palanpur | Long term (≥ 4 years) |
| Growth of Quick Commerce & Hyperlocal Delivery Models | +1.2% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Manufacturing Push Under Make in India Initiative
India's manufacturing gross value added at constant prices grew 10.7% in 2025-26, a provisional estimate under the revised series with a 2022-23 base.[1] Expanding real manufacturing activity strengthens the demand case for carriers serving the movement of production inputs and finished goods. A plant raising physical output needs inbound materials and outbound finished-goods movements, creating potential loaded trips on both sides of production. Coordinating those movements where routes align gives a carrier a way to reduce empty repositioning between factory assignments. Additional production can then raise demand for vehicle capacity on established factory lanes, even before manufacturers add new destinations.
Rising FMCG Distribution into Rural & Semi-Urban Markets
Reaching additional consumer outlets creates a freight opportunity whose value depends on distribution coverage as well as shipment size. Hindustan Unilever added approximately 200,000 stores to its total reach during FY 2025-26 while expanding coverage into rural hinterlands. For carriers serving this expansion, the freight requirement extends across a wider delivery footprint as brands reach additional retail outlets. Combining compatible deliveries can make dispersed outlets commercially serviceable without requiring each destination to generate a full truckload. Each added store is a separate delivery point, so the expansion increases the drops to schedule and makes the number combined within a circuit commercially consequential.
Growth in Construction & Infrastructure Material Movement
Construction creates transport demand during project execution, giving material haulers a commercial role before completed infrastructure carries ordinary traffic. The National Highways Authority of India constructed 5,313 kilometers of national highways in FY 2025-26, about 15% above its 4,640-kilometer target.[2] For carriers serving highway works, the location and sequence of construction activity determine where additional material-haulage capacity can earn revenue. Such work can support concentrated demand during execution, but a completed stretch changes the requirement for the vehicles assigned to it. A hauler's utilization then depends on how quickly its trucks can be reassigned to the next construction site, since a completed stretch ends the work it was serving.
Warehousing Expansion Across Tier-2 and Tier-3 Cities
Regional fulfillment capacity creates a destination for replenishment freight as well as a starting point for customer distribution. In June 2025, Amazon India launched its first fulfillment center in Indore as part of 5 new centers operational ahead of Prime Day 2025. Strategic partners operated and managed the centers, whose combined storage capacity exceeded 1.8 million cubic feet. For carriers serving such nodes, the commercial opening lies in connecting regional storage with replenishment and outbound distribution. Because strategic partners operated these centers, the replenishment and outbound haulage associated with the Indore opening may be contracted through those partner operators.
Restraints Impact Analysis of India Road Freight Transport Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic Driver Shortage Across Long-Haul Routes | -1.4% | Jawaharlal Nehru Port | Long term (≥ 4 years) |
| Highly Fragmented Small Fleet Operator Base | -1.1% | Nationwide | Long term (≥ 4 years) |
| Diesel Price Volatility Impacting Margins | -0.8% | Nationwide | Short term (≤ 2 years) |
| Urban Congestion & First/Last-Mile Inefficiencies | -0.5% | Mumbai and Delhi | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Chronic Driver Shortage Across Long-Haul Routes
Driver availability can constrain a freight operation even when cargo and vehicles are ready for dispatch. A 2025 International Transport Workers' Federation study, including April 2024 interviews, reported that unattractive working conditions in India's trucking industry were resulting in driver shortages. In May 2026, a container freight station trailer-driver shortage delayed evacuation of 25,000 import containers at Jawaharlal Nehru Port, India's Ministry of Ports, Shipping and Waterways reported. The commercial consequence is a mismatch between cargo-handling capacity and the workforce needed to release freight into the road network. In February 2026, Allcargo Group launched heavy motor vehicle driver training for women holding light motor vehicle licenses in India's port logistics corridor. Where drivers cannot be assigned to required movements, additional vehicle capacity alone cannot remove the dispatch bottleneck or its associated cargo delay.
Highly Fragmented Small Fleet Operator Base
Fragmented spot contracting can weaken a small carrier's control over the rate needed to recover its operating costs. ICRA reported in June 2026 that small fleet operators dominated India's road-logistics industry, where spot contracting was prevalent. Fuel-cost pass-through could be relatively prompt but incomplete, depending on supply and demand for trucks in the local market. A quick price adjustment therefore need not preserve the earnings available to sustain repeat service. For shippers seeking dependable capacity, the commercial constraint is continuity at viable rates because a crowded spot market can leave individual operators exposed to unrecovered costs.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Road Freight Transport Market Segment Analysis
By End User Industry:
Retail Scale Meets New Manufacturing CapacityWholesale and retail trade accounted for a 30.44% share of the India road freight transport market size in 2026. Delhivery's Express Parcel business delivered 1 billion e-commerce parcels in FY 2025-26. That retail-related operating scale provides a substantial stream of individual consignments for transport networks to aggregate into road movements. For the largest segment, the commercial task is to convert numerous separate orders into coordinated capacity without treating every destination as a dedicated truck assignment. A large parcel base supports shared road departures, but committing more trucks becomes worthwhile only when orders combine into viable loads on particular lanes.
Manufacturing is the fastest-growing segment, with a forecast CAGR of 9.95% over 2027-2032. CG Semi began commercial production at its G1 semiconductor assembly, packaging and test facility in Sanand in July 2026. The facility has peak capacity of 300 million units per year, and CG Power and Industrial Solutions is the venture's majority partner. India's manufacturing industrial production grew 9% year over year in August 2026, according to the Ministry of Statistics and Programme Implementation's quick estimate. Output growth increases the inputs and finished goods requiring transport, creating a larger potential haulage task for carriers serving factory dispatches.

By Destination:
Domestic Reach and Cross-Border ServiceDomestic transport represented a 62.82% India road freight transport market share in 2026. VRL Logistics reported more than 1 million customers across India in FY 2025-26, based on GST identification numbers in its system, and stated that all its business operations were in India. Its customers included corporate businesses, clearing and forwarding agents, wholesalers and retailers. With customers ranging from corporate businesses to wholesalers and retailers, a domestic carrier's volume can depend on serving many shippers on shared lanes rather than on any single account.
International transport is the fastest-growing segment, with a forecast CAGR of 8.85% over 2027-2032. Petrapole Land Port recorded 111,210 cargo movements in FY 2025-26 at the India-Bangladesh border. That operating base places part of the international freight opportunity at land crossings, where the road movement and its border interface form a connected service. Carriers can organize capacity around these established cross-border flows, with commercial performance depending on the continuity of cargo handoffs across the journey. If a border handoff stalls, the assigned truck remains committed beyond the domestic leg, increasing the capacity tied up in each international delivery.
By Truckload Specification:
Full Loads Anchor Value as Consolidation ExpandsFull-truck-load (FTL) was the largest segment, accounting for 79.84% of road freight service value in 2026. In Safe & Secure Logistics' Indian booking register, FTL represented 24% of consignments but 85.3% of charged tonnage from August 2025 to March 2026. The format can therefore carry substantial freight weight without accounting for the same number of individual orders. For shippers with enough cargo to use a complete vehicle, the service packages capacity around a consignment rather than a shared departure. The buyer commits to a vehicle movement for its load, so the operator earns from deploying truck capacity to that consignment.
Less than-truck-load (LTL) is the fastest-growing segment, with a forecast CAGR of 9.85% over 2027-2032. Delhivery's part-truck-load (PTL) freight tonnage reached 542,000 metric tons in the first quarter of FY 2026-27, up 18.4% from the first quarter of FY 2025-26. Shared capacity gives smaller consignments access to line-haul transport without a shipper needing to fill an entire truck. That model makes aggregation at departure points central to the business because individual orders have to form a viable combined movement. As PTL tonnage increases, fuller departures spread movement costs across more freight, while additional departures create a different requirement for vehicles and terminal capacity.
By Containerization:
Bulk Freight and New Load ConfigurationsNon-containerized freight was the largest segment, with 86.31% of road freight service value in 2026. The Ministry of Coal recorded 298.5 million metric tons of external raw-coal dispatch by road in FY 2024-25. Adani Ports and Special Economic Zone Ltd. (APSEZ) reported more than 25,000 owned and managed trucks across its containerized and bulk-cargo trucking business in its 2025-26 report. Bulk transport can therefore be offered within a broader freight network, with operators combining this business with other cargo movements. The reported truck total spans containerized and bulk work, so allocation between the 2 determines the capacity available for non-containerized freight.
Containerized freight is the fastest-growing segment, with a forecast CAGR of 8.78% over 2027-2032. On May 7, 2026, Jawaharlal Nehru Port Authority reported average daily gate movement of around 20,000 TEUs of containerized cargo by road. Volvo Trucks launched a road train operated by Delhivery in Nagpur on February 15, 2025, including a 24-foot containerized intermediate trailer. Regular terminal movements make departure planning commercially important because operators must match truck availability with the cargo to be moved. The road-train configuration expands the load carried in a combined vehicle movement, shifting the operating decision toward assembling sufficient cargo for that larger departure.
By Distance:
Long-Haul Scale and Repeat Urban ConnectionsLong-haul transport was the largest segment, accounting for 75.42% of road freight service value in 2026. Safe & Secure Logistics recorded 134,506 consignments on lanes of 1,500 to 1,999 kilometers from August 2025 to March 2026. Its network was weighted toward west-to-east parcel lanes. For carriers operating over those distances, vehicle positioning after delivery can shape the next revenue-earning movement as much as the initial dispatch. In this west-to-east network, securing the next load determines how much empty repositioning must be recovered through the revenue from loaded movements.
Short-haul transport is the fastest-growing segment, with a forecast CAGR of 8.85% over 2027-2032. By May 2026, Amazon India had deployed around 50 Eicher Pro-X electric trucks for intra-city freight. They moved goods between fulfillment hubs on city outskirts and micro-fulfillment centers closer to customers. That model can support repeated facility-to-facility replenishment, with useful vehicle capacity determined by the flow between nearby nodes. City-scale links reward short turnaround, since a truck that loads and releases quickly can add departures without lengthening its route.
By Goods Configuration:
Industrial Solids and Specialized Fluid TransportSolid goods formed the largest segment, accounting for 72.88% of road freight service value in 2026. ACC reported cement sales volume of 43.9 million metric tons in FY 2025-26, up 12% year over year. An expanding physical sales base creates a potential distribution task for carriers, whose commercial requirement is to arrange productive loaded movements around the producer's dispatch needs. If a carrier's cement contract fixes its dispatch allocation, access to additional loads determines whether higher producer sales can increase haulage revenue.
Fluid goods are the fastest-growing segment, with a forecast CAGR of 9.17% over 2027-2032. TCI Chemlog, a TCI Group subsidiary, provides chemical-logistics services for solid, liquid and gaseous products across road, rail and coastal routes. It uses ISO tank containers, gas tankers and flexi tanks for multimodal chemical movements. For fluid-goods buyers, commercial value depends on the connection between containment, road collection and the other transport legs used for a particular shipment. A specialist can differentiate its freight service through coordinated equipment and handling at those interfaces, connecting specialized cargo requirements with the road movement.
By Temperature Control:
Ambient Reach and Refrigerated Service ExpansionNon-temperature-controlled transport was the largest segment, with 94% of road freight service value in 2026. As reported in August 2026, dairy producer Milky Mist Dairy Food Limited operated 34 ambient trucks within its own logistics fleet, supplying 57 clearing and forwarding agent warehouse depots in India. Ambient vehicles can form a dedicated part of a producer's broader distribution network, with transport requirements organized around the goods assigned to that service. For buyers whose goods do not need active temperature control, the movement can be organized around capacity, timing and depot coverage. An outside carrier's case for depot contracts therefore rests on service or utilization gains relative to a producer's own ambient fleet.
Temperature-controlled transport is the fastest-growing segment, with a forecast CAGR of 9.4% over 2027-2032. By April 2025, Deepika Frozen Food Carrier had added 10 MXL refrigerated trucks, bringing its fleet to 40 vehicles. Each new truck had a payload capacity of 21 metric tons. Capacity committed to a refrigerated movement is also a commitment to preserve the conditions specified for that load throughout the road leg. Payload and temperature control consequently form one service commitment, giving specialized operators a defined role for customers needing both capabilities delivered together.
Geography Analysis
Western and southern corridors Road Freight Transport Market
Western and southern corridors led overall freight volumes in 2025. From FY 2020-21 through March 17, 2026, NHAI constructed 2,457 kilometers of national highways in Maharashtra and 1,235 kilometers in Tamil Nadu under Bharatmala. These cumulative road works provide infrastructure relevant to repeated freight movements in both parts of the country. For corridor-focused carriers, the commercial value of that road base depends on linking successive loads across the locations their customers serve. Maharashtra's Bharatmala construction was roughly twice Tamil Nadu's over this period, placing more of this paired highway expansion in the western corridor.
Southern India Road Freight Transport Market
Southern India's fast-growth trajectory through 2031 creates opportunities around industrial logistics capacity. In September 2025, Allcargo Supply Chain, part of Allcargo Logistics, announced the launch of its Panapakkam logistics park near Chennai as a ready-to-go-live facility. Its announced design included 30 truck bays capable of handling more than 300 vehicles per day and approximately 60,000 metric tons of monthly facility throughput capacity. For the park's announced truck-handling capacity to generate haulage work, bay access and vehicle arrivals have to be scheduled together.
Regional differences also shape the access leg of a freight service, with Lucknow illustrating an urban delivery constraint in Northern India. The Department for Promotion of Industry and Internal Trade's Logistics Ease Across Different States (LEADS) 2025 found chronic congestion and poor non-expressway traffic flow affecting last-mile delivery in Lucknow and other major Uttar Pradesh cities. The North-eastern states showed a different pattern of logistics ecosystem performance, with Mizoram classified as an Exemplar and Tripura and Meghalaya as High Performers. Among the North-eastern states, Arunachal Pradesh, Nagaland, Manipur and Assam were classified as Accelerators in the same assessment. Urban access conditions and state logistics capabilities can therefore create different execution costs within one national freight contract.
Regulatory Framework and Outlook
This comparison covers selected jurisdictions from the perspective of road-freight operators planning new electric-truck purchases. National policy sets future truck safety requirements, while Maharashtra combines goods-vehicle taxation with an EV policy exemption. For a fleet buyer, the commercial effect comes from how vehicle equipment and registration choices interact with the date of purchase.
Regulatory Table of India Road Freight Transport Market
| Decision factor | India | Maharashtra |
|---|---|---|
| Primary authority | Ministry of Road Transport and Highways | Motor Vehicle Department; Transport Department as EV-policy nodal body |
| Key instruments or direction | Adopted truck safety requirements from October 2027 and January 2028 | Laden-weight goods-vehicle tax; EV Policy 2025 exemption for qualifying registrations through March 2030 |
| Commercial effect | Future braking, stability, emergency-braking and driver-assistance equipment requirements | Goods-vehicle tax depends on laden weight; qualifying EVs receive complete motor vehicle tax relief |
| Current policy attractiveness | Medium | High |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
The adopted national timetable adds revised braking, stability and emergency-braking requirements from October 1, 2027, and listed driver-assistance systems from January 1, 2028. Maharashtra's tax exemption applies to EVs sold and registered in the state from April 1, 2025, through March 31, 2030.[3] Complete state motor vehicle tax relief supports Maharashtra's high current rating, while the national timetable's adopted equipment obligations support a medium rating for prospective fleet purchases. The exemption window through March 31, 2030 supports state-policy continuity for qualifying purchases, with laden-weight taxation determining exposure outside the exemption.
Value Chain Stages
The value chain compares shipment consolidation, line-haul transport and final distribution as distinct sources of carrier earnings. In FY 2025-26, TCI Freight, a division of Transport Corporation of India (TCI), reported hub-and-spoke surface transport across more than 19,000 pin codes. Its services covered FTL, LTL, over-dimensional and cross-border cargo. Across these services, carrier earnings depend on connecting collection and final distribution with the intervening surface movement.
Value Chain Analysis Table of India Road Freight Transport Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Shipment collection and consolidation | LTL carriers such as VRL Logistics Ltd. and TCI Freight | Collection and consolidated-freight charges | Insufficient origin volume to fill shared departures | Combine compatible consignments around coordinated departure times |
| Line-haul transportation | FTL operators such as Mahindra Logistics and Delhivery Ltd. | Line-haul freight charges | Mismatch between load locations and available vehicles | Link successive loaded movements across the transport network |
| Final distribution | Parcel carriers such as VRL Logistics Ltd. and Delhivery Ltd. | Delivery freight charges | Misaligned terminal release and delivery schedules | Coordinate terminal dispatch with destination delivery rounds |
| Source: Mordor Intelligence | ||||
VRL reported competitive pricing and localized volume moderation in FY 2025-26, along with exits from selected low-margin businesses over the prior 2 years. Its experience points to a limit on expanding consignments when their charges cannot sustain the associated network work. Rejecting unremunerative traffic is part of how such a network manages its capacity.
Competitive Landscape
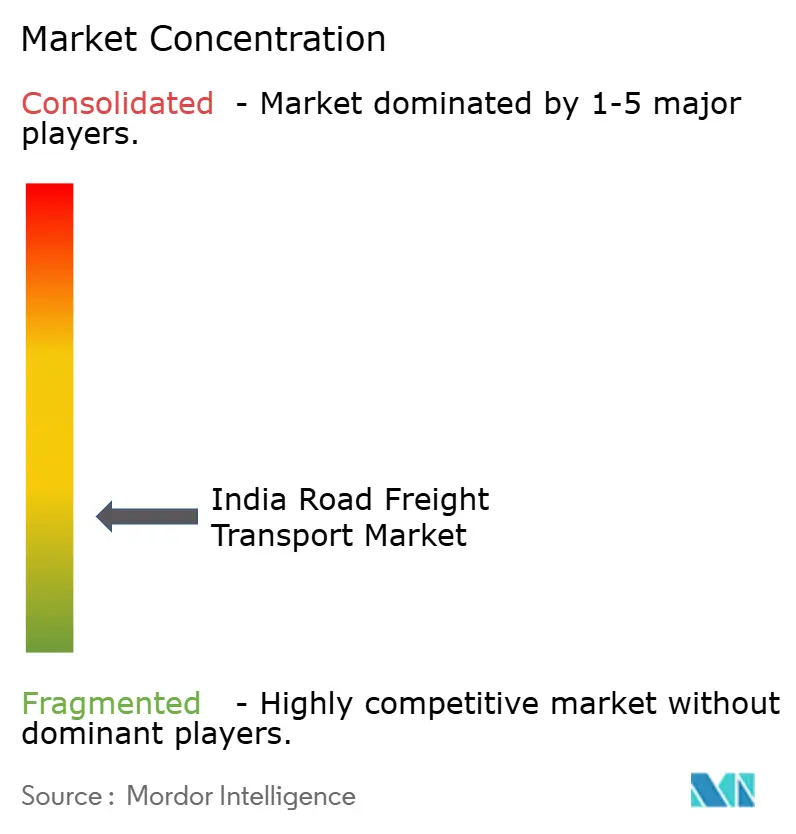
The fragmented competitive field includes A.P. Moller-Maersk, Allcargo Logistics (including AllcargoGATI), CJ Darcl Logistics Limited, Delhivery Ltd. and DHL Group. In FY 2024-25, AllcargoGATI's network included 18 express distribution centers, 22 logistics parks and 84 distribution hubs, supported by more than 4,300 vendor trucks. CJ Darcl, whose business includes road transport and multimodal logistics, reported access to more than 1.12 million vehicles in its market network as of March 31, 2026. Both networks draw on external vehicle capacity, so vendor relationships and network coverage support scale beyond the vehicles they own.
In FY 2024-25, AllcargoGATI launched HubEye, a proprietary digital platform that provided real-time visibility into its line-haul network. Connecting that visibility to terminal and truck movements across a vendor-supplied network can support closer control of dispatch, making digital coordination commercially relevant alongside physical reach. CJ Darcl's pan-India B2B road transport model combines vendor-sourced vehicles with selectively owned commercial vehicles, including container trucks and tractor trailers, giving it 2 ways to arrange capacity. For business shippers, these approaches can concentrate responsibility for capacity access, movement visibility and dispatch coordination within a contracted network spanning multiple origins and destinations.
Delhivery Ltd. completed its acquisition of Ecom Express in July 2025, making Ecom Express a subsidiary. DHL Group's DHL Supply Chain business operates a healthcare-only multi-client logistics center in Bhiwandi with temperature-controlled storage from −190°C to 45°C. The Bhiwandi facility serves pharmaceuticals and medical devices. For parcel rivals, the completed acquisition means competing against a Delhivery group with a larger combined network. Fleet additions also bring regulatory positioning into competition, since operators must align new truck specifications with MoRTH's adopted safety-equipment timetable.
India Road Freight Transport Industry Leaders
-
A.P. Moller-Maersk
-
Allcargo Logistics (including AllcargoGATI)
-
CJ Darcl Logistics Limited
-
Delhivery Ltd.
-
DHL Group
- *Disclaimer: Major Players sorted in no particular order
India Road Freight Transport Market Companies Covered in this Report
- A.P. Moller-Maersk
- Allcargo Logistics (including AllcargoGATI)
- CJ Darcl Logistics Limited
- Delhivery Ltd.
- DHL Group
- Expeditors International of Washington, Inc.
- GEODIS
- Mahindra Logistics
- Nippon Express Holdings
- Transport Corporation of India (TCI)
- V-Trans
- Varuna Group
- VRL Logistics Ltd.
- Safexpress
- Shree Tirupati Logistics
- Xpressbees
- Om Logistics Supply Chain
- CKB Group
- Glottis
- SAR Logistics
Recent Industry Developments in India Road Freight Transport Market
- May 2026: Ashok Leyland announced a 715-vehicle order from VRL Logistics, including freight trucks and staff buses. At the announcement, 300 trucks had been delivered and 415 vehicles were scheduled for delivery during 2026.
- Apr 2026: Tata Motors began delivering electric prime movers to BillionE Mobility and announced an additional 250-unit order for phased delivery, with deployment planned for long-haul steel, cement and other industrial freight in India.
- Apr 2026: GreenLine Mobility Solutions announced a USD 275 million equity investment, including a USD 20 million commitment from Nikhil Kamath, to support planned deployment of more than 10,000 LNG and electric trucks in India.
Scope and Methodology
By End User Industry
| Agriculture, Fishing, and Forestry |
| Construction |
| Manufacturing |
| Oil and Gas, Mining and Quarrying |
| Wholesale and Retail Trade |
| Others |
By Destination
| Domestic |
| International |
By Truckload Specification
| Full-Truck-Load (FTL) |
| Less than-Truck-Load (LTL) |
By Containerization
| Containerized |
| Non-Containerized |
By Distance
| Long Haul |
| Short Haul |
By Goods Configuration
| Fluid Goods |
| Solid Goods |
By Temperature Control
| Non-Temperature Controlled |
| Temperature Controlled |
| By End User Industry | Agriculture, Fishing, and Forestry |
| Construction | |
| Manufacturing | |
| Oil and Gas, Mining and Quarrying | |
| Wholesale and Retail Trade | |
| Others | |
| By Destination | Domestic |
| International | |
| By Truckload Specification | Full-Truck-Load (FTL) |
| Less than-Truck-Load (LTL) | |
| By Containerization | Containerized |
| Non-Containerized | |
| By Distance | Long Haul |
| Short Haul | |
| By Goods Configuration | Fluid Goods |
| Solid Goods | |
| By Temperature Control | Non-Temperature Controlled |
| Temperature Controlled |
Market Definition
- Agriculture, Fishing, and Forestry (AFF) - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the AFF industry players on road freight transport service. The end user players considered are the establishments primarily engaged in growing crops, raising animals, harvesting timber, harvesting fish & other animals from their natural habitats and providing related support activities. Herein, across the value chain, Logistics Service Providers (LSPs) play a crucial role in acquisition, storage, handling, transportation, and distribution activities for the optimal & continuous flow of inputs (seeds, pesticides, fertilizers, equipment, and water) from manufacturers or suppliers to the producers and smooth flow of output (produce, agro-goods) to distributors/ consumers. This includes both termperature controlled and non-temperature controlled logistics, as and when required according to the shelf life of goods being transported or stored.
- Construction - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the construction industry players, on road freight transport service. The end user players considered are the establishments primarily engaged in constructing, repairing and renovating residential & commercial buildings, infrastructure, engineering works, subdividing and developing land. Logistics Service Providers (LSPs) play a crucial role in increasing profitability of construction projects by maintaing the inventory of raw materials & equipment, time-critical supplies and by providing other value added services for effective project management.
- Containerized Road Freight Transport - The segment captures the external (outsourced) logistics expenditure incurred by the road freight transport service end users on Full-Truck-Load (FTL) services. FTL road freight transport is characterized as a full single load not combined with other shipments. It comprises of shipments (i) devoted to the goods of a single shipper (ii) taken directly from a point of origin to one or more destination points (iii) comprising of bulk mail truck transportation (iv) comprising of both Container (Full Container Load, FCL)/Non-Container trucking services (v)comprsing of goods requiring temperature controlled or non-temperature controlled transportation services (vi) comprising of bulk liquid tankering (vii) invoving trucking of waste (viii) hazardous material trucking. Related value added services (VAS) of sorting, consolidation, deconslidation are included in the other services segment of freight and logistics market.
- Export Trends and Import Trends - Overall logistics performance of an economy is positively and significantly (statistically) correlated to its trade performance (exports and imports). Hence, in this industry trend, total value of trade, major commodities/ commodity groups and the major trade partners, for the studied geography (country or region as per the scope of report) have been analysed alongside the impact of major trade/logistics infrastructure investments & regulatory environment.
- Fluid Goods - The segment captures the external (outsourced) logistics expenditure incurred by the road freight transport service end users for the transport of bulk liquids, that are often used in extraction, manufacturing, food processing, agriculture industries among others. It includes transportation of liquids like (i) Chemicals/ hazardous goods (for instance acids) (ii) Water (potable as well as waste) (iii) Oil and gas (upstream as well as downstream like gasoline, fuel, crude oil, or propane), (iv) Food grade bulk liquids (like milk, or juice), (v) Rubber, (vi) Agrichemical products, among others. These goods are generally transported through tanker trucking.
- Fuel Price - Fuel price spikes can cause delays and diruption for logistics service providers (LSPs), while drops in the same can result in higher short-term profitability and increased market rivalry to offer consumers with the best deals. Hence, the fuel price variations have been studied over the review period and presented along with the causes as well as market impacts.
- Full-Truck-Load (FTL) Road Freight Transport - The segment captures the external (outsourced) logistics expenditure incurred by the road freight transport service end users on Full-Truck-Load (FTL) services. FTL road freight transport is characterized as a full single load not combined with other shipments. It comprises of shipments (i) devoted to the goods of a single shipper (ii) taken directly from a point of origin to one or more destination points (iii) comprising of bulk mail truck transportation (iv) comprising of both Container (Full Container Load, FCL)/Non-Container trucking services (v)comprsing of goods requiring temperature controlled or non-temperature controlled transportation services (vi) comprising of bulk liquid tankering (vii) invoving trucking of waste (viii) hazardous material trucking. Related value added services (VAS) of sorting, consolidation, deconslidation are included in the other services segment of freight and logistics market.
- GDP Distribution by Economic Activity - Nominal Gross Domestic Product and distribution of the same, across major economic sectors in the geography studied (country or region as per scope of the report) have been studied and presented in this industry trend. As GDP is positively related to the profitability and growth of logistics industry, this data has been used in adjunction to the input-output tables/ supply-use tables for analyzing the potential major contributing sectors towards the logistics demand.
- GDP Growth by Economic Activity - Growth of Nominal Gross Domestic Product across major economic sectors, for the geography studied (country or region as per scope of the report) have been presented in this industry trend. This data has been utilized for assessing the growth of logistics demand from all the market end users (economic sectors considered here).
- Inflation - Variations in both Wholesale Price Inflation (YoY change in producer price index) and Consumer Price Inflation have been presented in this industry trend. This data has been used to assess the inflationary environment as it plays a vital role in smooth functioning of the supply chain, directly impacting the logistics operational cost components e.g., pricing of tyres, driver wages & benefits, energy/fuel prices, maintenace costs, toll charges, warehousing rents, custom brokerage, forwarding rates, courier rates etc. hence impacting the overall freight and logistics market.
- Key Industry Trends - The report section named "Key Industry Trends" include all the key variables/parameters studied to better analyze the market size estimates and forecasts. All the trends have been presented in the form of data points (time series or latest available data points) along with analysis of the paramter in the form of concise market relevant commentary, for the geography studied (country or region as per the scope of report).
- Key Strategic Moves - The action taken by a company to differentiate from its competitor or used as a general strategy is referred to as a key strategic move (KSM). This includes (1) Agreements (2) Expansions (3) Financial Restructuring (4) Mergers and Acquisitions (5) Partnerships, and (6) Product Innovations. Key players (Logistics Service Providers, LSPs) in the market have been shortlisted, their KSM have been studied and presented in this section.
- Less than-Truck-Load (LTL) Road Freight Transport - The segment captures the external (outsourced) logistics expenditure incurred by the road freight transport service end users on Less than-Truck-Load (LTL) services. LTL road freight transport is characterized as multiple shipments combined onto a single truck for multiple deliveries within a network. It comprises of establishments (i) primarily engaged in general and specialized freight trucking of less than complete truck-loads, (ii) characterized by the use of terminals to consolidate shipments, generally from several shippers, into a single truck for haulage between a load assembly terminal and a disassembly terminal, where the load is sorted and shipments are re-routed for delivery (iv) Less than-Container-Load (LCL) shipping/ Groupage Shipping in case of trucking services. The activities in scope include (i) local pick-up, (ii) line-haul, and (iii) local delivery. Related value added services (VAS) of sorting, consolidation, deconslidation are included in the other services segment of freight and logistics market.
- Logistics Performance - Logistics Performance and Logistics Costs are the backbone of trade, and influences trade costs, making countries compete globally. Logistics performance is influenced by market wide adopted supply chain management strategies, government services, investments & policies, fuel/ energy costs, inflationary environment etc. Hence, in this industry trend, the logistics performance of the geography studied (country/ region as per the scope of report) has been analysed and presented over the review period.
- Major Truck Suppliers - Market share of truck brands is influenced by factors like geographical preferences, portfolio of truck types, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological innovations (like electric vehicles, digitalization, autonomous trucks), fuel efficiency, financing options, annual maintenance costs, availability of substitutes, marketing startegies etc. Hence, the distribution (share % for base year of the study) of truck sales volume for leading truck brands and commentary on current market scenario & market anticipation over the forecast period have been presented in this industry trend.
- Manufacturing - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the Manufacturing industry players, on road freight transport service. The end user players considered are the establishments primarily engaged in the chemical, mechanical or physical transformation of materials or substances into new products. Logistics Service Providers (LSPs) play a crucial role in maintaining a smooth flow of raw materials across the supply chain, enabling timely delivery of finished goods to distributors or end customers and storing & supplying the raw materials to clients for just-in-time manufacturing.
- Modal Share - Freight Modal Share is influenced by factors like modal productivity, government regulations, containerization, distance of shipment, temperature control requirements, type of goods, international trade, terrain, speed of delivery, shipment weight, bulk shipments, etc. Also, modal share by tonnage (tons) and modal share by freight turnover (ton-km) differ as per average distance of shipments, weight of major commodity groups transported in the economy and number of trips. This industry trend represents the distribution of freight transported by mode of transport (tons as well as ton-km), for the study base year.
- Oil and Gas, Mining and Quarrying - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the extraction industry players, on road freight transport service. The end user players considered are the establishments that extract naturally occurring mineral solids, such as coal and ores; liquid minerals, such as crude petroleum; and gases, such as natural gas. Logistics Service Providers (LSPs) covers entire phases from upstream to downstream and plays a crucial role in the transportation of machinery, drilling equipments, extracted minerals, crude oil & natural gas and refined/ processed products from one place to another.
- Other End Users - Other end user segment captures the external (outsourced) logistics expenditure incurred by the financial services (BFSI), real estate, educational services, healthcare, and professional services (administrative, waste management, legal, architectural, engineering, design, consulting, scientific R&D), on road freight transport service. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies and documents to/from these industries such as transporting any equipment or resources required, shipping confidential documents and files, movement of medical goods & supplies (surgical supplies and instruments, including gloves, masks, syringes, equipment) to name a few.
- Producer Price Inflation - It indicates inflation from viewpoint of the producers viz. the average selling price received for their output over a period of time. Annual change (YoY) of producer price index is reported as wholesale price inflation in the "Inflation" industry trend. As WPI captures dynamic price movements in most comprehensive way, it is widely used by governments, banks, industry, business circles and is deemed important in formulation of trade, fiscal and other economic policies. The data has been used in adjunction to consumer price inflation for better understanding the inflationary environment.
- Road Freight Pricing Trends - Freight pricing by mode of transport (USD/tonkm), over the review period, has been presented in this industry trend. The data has been used in assessing the inflationary environment, impact on trade, freight turnover (tonkm), road freight transport market demand and hence the road freight transport market size.
- Road Freight Tonnage Trends - Freight tonnage (weight of goods in tons) handled by mode of transport, over the review period, has been presented in this industry trend. The data has been used as one of the parameters apart from average distance per shipment (km), freight volume (tonkm), and freight pricing (USD/tonkm) to assess the freight transport market size.
- Road Freight Transport - Hiring a road freight transport logistics service provider (LSP) or haulier (outsourced logistics), for the transport of commodities constitutes road freight transport market. The scope of study includes (i) road transport of goods reported by hauliers registered in the reporting countries (ii) transport of raw materials or manufactured goods (solids as well as fluids) (iii) transport using commerical motor vehicles (rigid trucks or tractor-trailers, (iv) Full-Truck-Load (FTL) or Less than-Truck-Load (LTL) transport (v) containerized or non-containerized transport (vi) temperature controlled or non-temperature controlled trasnport, (vii) short haul or long haul (Over-the-road, OTR) transport, (viii) used office or household goods transport (movers and packers), (ix) other specialized cargo transport (dangerous goods, oversized cargo) and (x) outsourced first mile/ middle mile/last mile delivery shipments undertaken by road freight transport players. The scope does not include (i) transport undertaken by hauliers registered in other countries (ii) last mile meal delivery market (iii) grocery delivery market (iv) transportation via road network undertaken/ reported by Courier, Express, and Parcel (CEP) players.
- Road Length - As infrastructure plays a vital role in an economy's logistics performance, variables like length of roads, distribution of road length by surface category (paved v/s unpaved), distribution of road length by road classification (expressways v/s highways v/s other roads), have been analysed and presented in this industry trend.
- Segmental Revenue - Segmental Revenue has been triangulated or computed and presented for all the major players in the market. It refers to the road freight transport market specific revenue earned by the company, over the base year of study, in the geography studied (country or region as per the scope of report). It is computed through the study and analysis of major parameters like financials, service portfolio, employee strength, fleet size, investments, number of countries present in, major economies of concern, etc. that have been reported by the company in its annual reports, webpage. For companies having scarce financial disclosures, paid databases like D&B Hoovers, Dow Jones Factiva have been resorted to and verified through industry/expert interactions.
- Short Haul Road Freight Transport - The segment captures the external (outsourced) logistics expenditure incurred by the road freight transport service end users on local trucking (less than 100 miles). It includes the road transport of goods (i) within a single administrative area and its hinterland, (ii) by smaller trucks and pickup trucks (iii) via containerized as well as dry bulk services (iv) intermodal from ports, container terminals or airports, and (v) outsourced first mile/ last mile delivery shipments undertaken by road freight transport players.
- Transport and Storage Sector GDP - Value and growth of Transport and Storage Sector GDP has a direct relation to the freight and logistics market size, and hence road freight transport market size. Therefore, this variable has been studied and presented over the review period, in value terms (USD) and as share % of total GDP, in this industry trend. The data has been supported by concise and relevant commentary around the investments, developments, and current market scenario.
- Trends in E-Commerce Industry - Enhanced internet connectivity and boom in smartphone penetration, coupled with increasing disposable incomes, has led to a phenomenal growth in the e-commerce market globally. Online shoppers require fast and efficient delivery of their orders leading to an increase in the demand for logistics services especially e-commerce fulfilment services. Hence, the Gross Merchandise Value (GMV), historial and projected growth, breakup of major commodity groups in e-commerce industry for the studied geography (country or region as per scope of the report) have been analysed and presented in this industry trend.
- Trends in Manufacturing Industry - Manufacturing industry involves the transformation of raw materials into finished products, while logistics industry ensures the efficient flow of raw materials to the factory, and the transport of manufactured products to the distributors & consumers. Demand-Supply of both industries are highly cross-linked and critical for a seamless supply chain. Hence, the Gross Value Added (GVA), breakup of GVA into major manufacturing sectors, and growth of manufacturing industry over the review period have been analysed and presented, in this industry trend.
- Trucking Fleet Size By Type - Market share of truck types is influenced by factors like geographical preferences, major end user industries, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological disruptions (like electric vehicles, digitalization, autonomous trucks) etc. Hence, the distribution (share % for base year of study) of truck parc volume by type of truck, market disruptors, truck manufacturing investments, truck specifications, truck use & import regulations, and market anticipation over the forecast period have been presented in this industry trend.
- Trucking Operational Costs - The prime reasons for measuring/ benchmarking logistics performance of any trucking company are to reduce operational costs and increase profitability. On the other hand, measuring operational costs helps to identify whether and where to make operational changes to control expenses and identify areas for improved performance. Hence, in this industry trend, trucking operational costs and the variables involved viz. driver wages & benefits, fuel prices, repairs & maintenance costs, tyre costs etc. have been studied over the base year of study, and presented for the geography studied (country or region as per the scope of report).
- Wholesale and Retail Trade - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the wholesalers and retailers, on road freight transport service. The end user players considered are the establishments primarily engaged in wholesaling or retailing merchandise, generally without transformation, and rendering services incidental to the sale of merchandise. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies to and finished products from production houses to the distributors and finally to the end customer covering activites like material sourcing, transportation, order fulfillment, warehousing & storage, demand forecasting, inventory management etc.
| Keyword | Definition |
|---|---|
| Cabotage | Road transport by a motor vehicle registered in a country performed on the national territory of another country. |
| Cross Docking | Cross docking is a logistics procedure where products from a supplier or manufacturing plant are distributed directly to a customer or retail chain with marginal to no handling or storage time. Cross docking takes place in a distribution docking terminal; usually consisting of trucks and dock doors on two (inbound and outbound) sides with minimal storage space. The name ‘cross docking’ explains the process of receiving products through an inbound dock and then transferring them across the dock to the outbound transportation dock. |
| Cross Trade | International road transport between two different countries performed by a road motor vehicle registered in a third country. A third country is a country other than the country of loading/embarkation and than the country of unloading/disembarkation. |
| Dangerous Goods | The classes of dangerous goods carried by Road are those defined by the fifteenth revised edition of the UN Recommendations on the Transport of Dangerous Goods, United Nations, Geneva 2007. They include Class 1: Explosives; Class 2: Gases; Class 3: Flammable Liquids; Class 4: Flammable solids- substances liable to spontaneous combustion; substances which, on contact with water, emit flammable gases; Class 5: Oxidizing substances and organic peroxides; Class 6: Toxic and infectious substances; Class 7: Radioactive material and Class 8: Corrosive substances, Class 9: Miscellaneous dangerous substances and articles. |
| Direct Shipment | Direct shipment is a method of delivering goods from the supplier or the product owner to the customer directly. In most cases, the customer orders the goods from the product owner. This delivery scheme reduces transportation and storage costs, but requires additional planning and administration. |
| Drayage | A drayage is a form of trucking service that connects the different modes of shipping (intermodal), such as ocean freight or air freight. It’s a short-haul trip that transports goods from one place to another, usually before or after its long-haul shipping process. Drayage trucks move cargo to and from various destinations, such as container ships, storage lots, order fulfillment warehouses, and rail yards. Typically, drayage only transports goods in short distances and operates only in one metropolitan area. It also requires only one trucker in a single shift. But despite this, but it plays an important role in long-haul shipping because it gets the goods to the cargo and vice versa. It makes intermodal transport much more efficient and enables the seamless transfer of goods to the end customer. |
| Dry van | A dry van is a type of semi-trailer that's fully enclosed to protect shipments from outside elements. Designed to carry palletized, boxed or loose freight, dry vans aren't temperature-controlled (unlike refrigerated “reefer” units) and can't carry oversized shipments (unlike flatbed trailers). |
| Final Demand | Final demand includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. |
| Flatbed Truck | A flatbed truck is a type of truck with rigid design. It has a back body that is flatly shaped for easy loading and unloading of goods. The flatbed truck is mostly used to transport heavy, oversized, wide and indelicate goods such as machinery, building supplies or equipment. Due to the truck open body, the goods transported with it must not be vulnerable to rain. By functionality, the flatbed truck is comparable to a flatbed trailer. |
| Inbound Logistics | Inbound logistics is the way materials and other goods are brought into a company. This process includes the steps to order, receive, store, transport and manage incoming supplies. Inbound logistics focuses on the supply part of the supply-demand equation. |
| Intermediate Demand | Intermediate demand includes goods, services, and maintenance and repair construction sold to businesses, excluding capital investment. |
| International Loaded | Place of loading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of unloading in a different country. |
| International Unloaded | Place of unloading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of loading in a different country. |
| OOG cargo | Out of Gauge (OOG) cargo is any cargo that can not be loaded into six-sided shipping containers simply because it is too large. The term is a very loose classification of all cargo with dimensions beyond the maximum 40HC container dimensions. That is a length beyond 12.05 meters – a width beyond 2.33 meters – or a height beyond 2.59 meters. |
| Pallets | Raised platform, intended to facilitate the lifting and stacking of goods. |
| Part load | A part load describes goods which only fills a truck partially. In essence, the quantity of the shipment is bigger than the Less Than Truckload (LTL) shipment. Also, the shipment cannot fully occupy a truck i.e. its capacity is much lower than a Full Truckload (FTL) shipment. |
| Paved Road | Road surfaced with crushed stone (macadam) with hydrocarbon binder or bituminized agents, with concrete or with cobblestone. |
| Reverse Logistics | Reverse logistics comprises of the sector of supply chains that process anything returning inwards through the supply chain or traveling ‘backward’ through the supply chain. |
| Road Freight Transport Service | Hiring a trucking agency for transport of commodities (raw materials or manufactured goods including both solids and liquids) form the origin to a destination within the country (domestic) or cross-border (international) constitutes road freight transport market. The service might be Full-Truck-Load or Less than-Truck-Load, containerized or non-containerized, temperature controlled or non temperature controlled, short haul or long haul. |
| Tautliner vehicle | Tautliner and curtainsider are used as generic names for curtain sided trucks/trailers. The curtains are permanently fixed to a runner at the top and detachable rails/poles at front and rear, allowing the curtains to be drawn open and forklifts used all along the sides for easy and efficient loading and unloading. When closed for travel, vertical load restraint straps are attached to a rope rail beneath the truck bed, connecting the truck bed and curtain along both sides. Winches at either end of the curtain tension it, hence the 'Tautliner' name. This stops the curtain from flapping or drumming in the wind and can also help retain light loads from slipping sideways. |
| Transport for hire or reward | The carriage for remuneration of goods. |
| Unpaved Road | Road with a stabilized base not surfaced with crushed stone, hydrocarbon binder or bituminized agents, concrete or cobblestone. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is considered to be a part of the pricing, and the average selling price (ASP) is varying throughout the forecast period for each country
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


