
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 3.59 Billion |
| Market Size (2027) | USD 3.75 Billion |
| Market Size (2032) | USD 4.67 Billion |
| Growth Rate (2027 - 2032) | 4.49 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Germany Crop Protection Chemicals Market Analysis by Mordor Intelligence
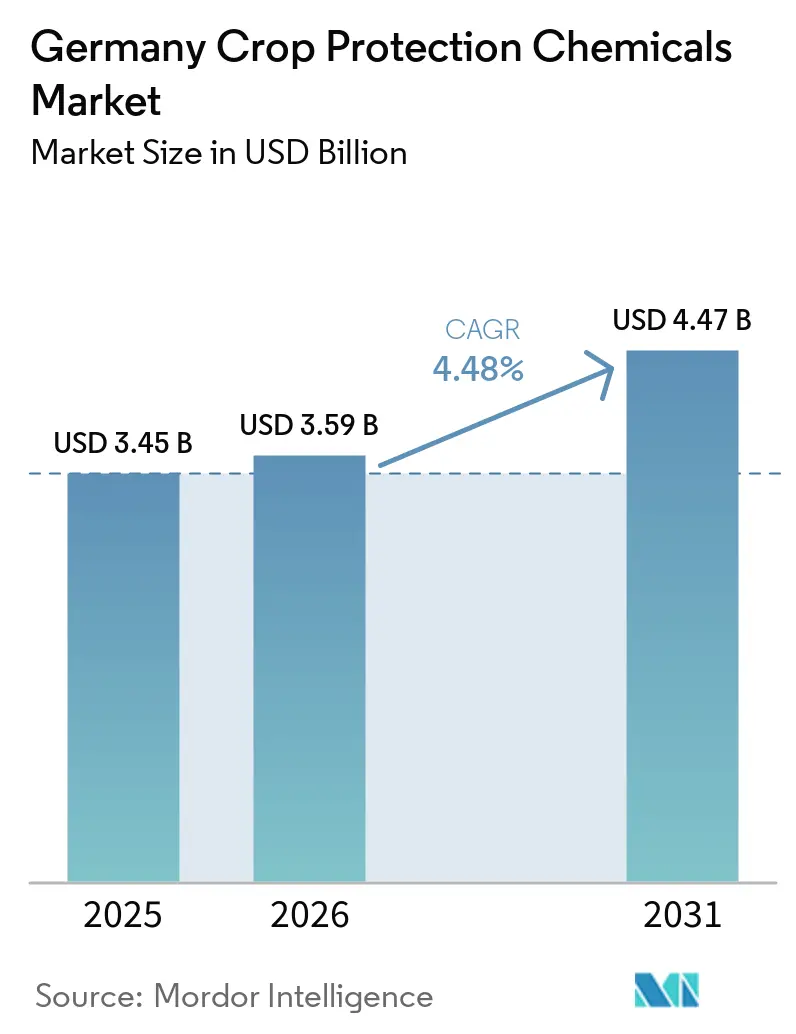
The Germany crop protection chemicals market size was valued at USD 3.59 billion in 2026 and is forecast to grow from USD 3.75 billion in 2027 to reach USD 4.67 billion by 2032, at a CAGR of 4.49% during the forecast period from 2027 to 2032. The market benefits from intensive cereal, oilseed rape, and sugar beet rotations that require recurring protection programs. Tighter EU approvals are reducing the range of available active substances and increasing demand for replacement products and co-formulations. Precision tools are shifting purchases away from high product volumes toward products that demonstrate reliable results on each treated hectare. Suppliers are responding with regulatory pipelines, diverse crop protection portfolios, and digital support that helps growers manage records and application decisions. Germany's large arable base and advanced commercial farms support demand even as sustainability regulations limit some conventional uses.
Key Report Takeaways
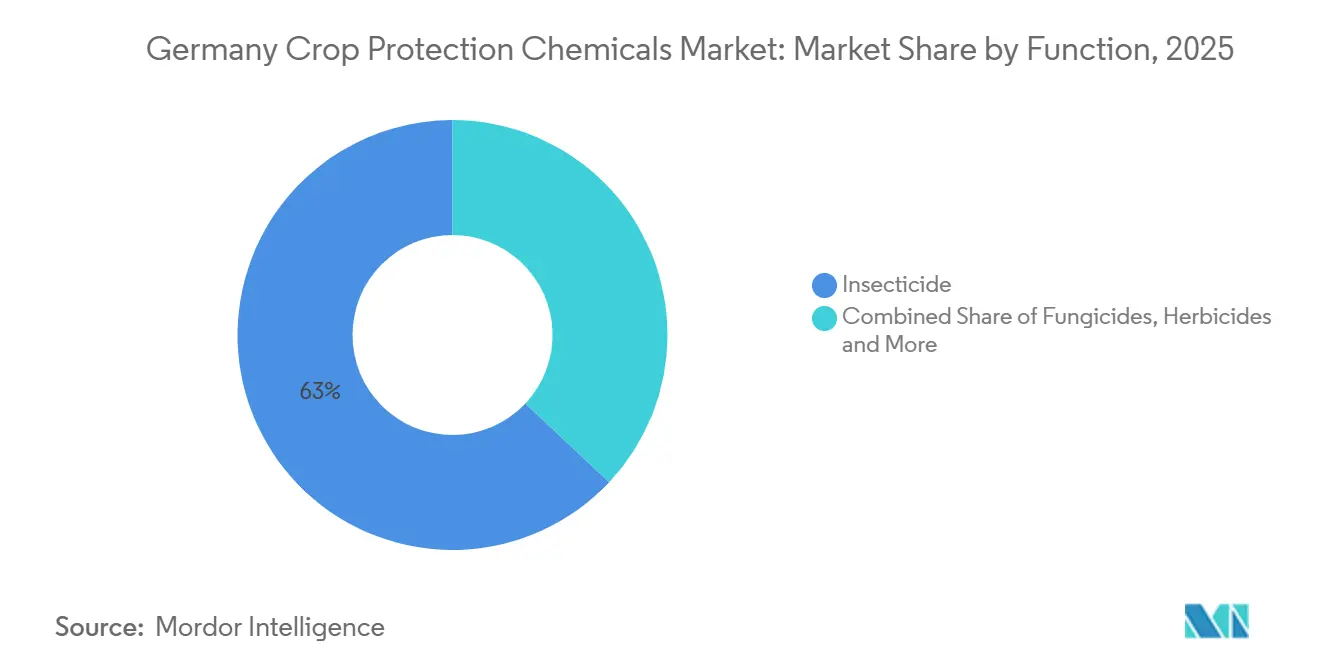
- By function, insecticides accounted for 63% of the Germany crop protection chemicals market share in 2026, while molluscicides are forecast to grow at a CAGR of 5.1% from 2027 to 2032.
- By application mode, foliar application accounted for 53% of the Germany crop protection chemicals market size in 2026, while seed treatment is forecast to grow at a CAGR of 5.5% from 2027 to 2032.
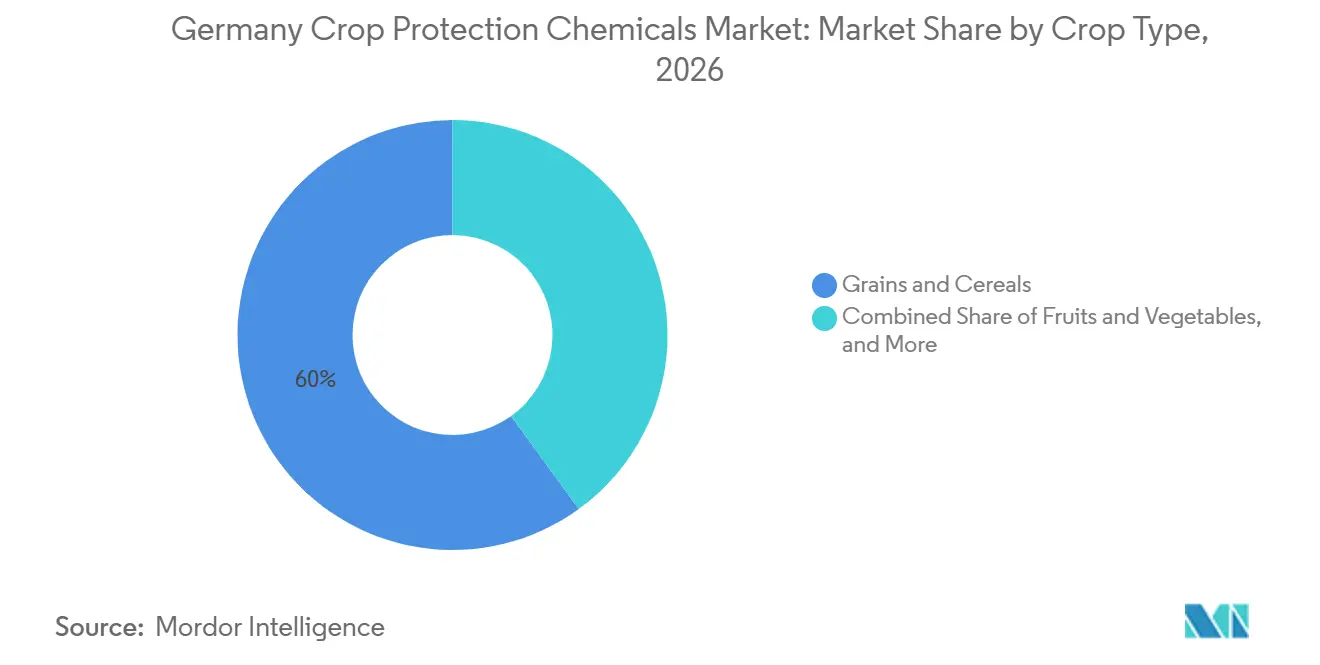
- By crop type, grains and cereals accounted for 60% of the market share in 2026, while fruits and vegetables are forecast to grow at a CAGR of 5.3% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Germany Crop Protection Chemicals Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Sustainable Agriculture and Integrated Pest Management Demand | +0.8% | Germany, Central EU | Long term (≥ 4 years) |
| Precision Agriculture and Variable-Rate Application | +0.7% | Germany, Netherlands, Western EU | Medium term (2-4 years) |
| Climate-Driven Pest Pressure in Temperate Crops | +0.7% | Germany, Northern and Central Europe | Short term (≤ 2 years) |
| Yield Protection in Cereals, Oilseeds, and Sugar Beets | +0.6% | Germany | Medium term (2-4 years) |
| AI-Guided Spray Timing Increasing Premium Formulation Mix | +0.5% | Germany, Netherlands, France | Medium term (2-4 years) |
| Local Product Availability Through Parallel-Trade Normalization | +0.3% | Germany, Central EU | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Sustainable Agriculture and Integrated Pest Management Demand
Germany’s 2024 Zukunftsprogramm Pflanzenschutz aligned national pesticide-reduction efforts with the EU goal of reducing chemical pesticide use and risk by 2030[1]. This policy supports the Germany crop protection chemicals market, as growers require selective crop protection products when broad-spectrum uses are restricted. These products can command greater value when they offer targeted control and fit documented integrated pest management programs. Bavaria's target to reduce the use of synthetic chemical plant protection products by 50% by 2028 is supporting a greater emphasis on integrated pest management, precision application, and alternative crop protection approaches[2]. Scouting records, treatment thresholds, and spray diaries also increase the value of advisory services attached to product sales. Suppliers that combine crop advice, digital records, and crop protection products can build stronger relationships with German growers. This supports continued demand for targeted crop protection products and integrated pest management solutions. As growers adjust to pesticide-reduction targets, suppliers offering solutions that balance crop-protection efficacy and sustainability are likely to remain relevant in the market.
Precision Agriculture and Variable-Rate Application
The increasing adoption of precision agriculture is supporting more targeted and efficient application of crop protection products in Germany. A 2026 study published in the journal Precision Agriculture found that real-time herbicide spot spraying was economically viable for sugar beet farms above 60 to 172 hectares and cereal farms above 300 to 400 hectares in northwestern Germany[3]. This creates an adoption base among commercial farms that can support the Germany crop protection chemicals market. Camera-based systems can target individual areas without requiring growers to replace the whole sprayer. Growers using these systems favor selective products with measurable performance over calendar-based product purchases. Treated volumes may stabilize as fewer unnecessary passes are made under sustainability rules, while value per treatment can still rise as the product mix shifts toward more specialized formulations. This shift can support demand for crop protection products that are compatible with targeted application systems and enable more precise use of active ingredients.
Climate-Driven Pest Pressure in Temperate Crops
Changing weather patterns are increasing the risk of pest and disease pressure in Germany’s temperate crops, supporting recurring demand for crop protection products. Warmer conditions and irregular rainfall are extending pest and disease pressure in German temperate crops. Wetter autumns following dry summers can favor slug emergence during oilseed rape establishment, supporting demand for molluscicides alongside fungicide and insecticide use. This pattern also encourages growers to diversify product programs beyond historical treatment schedules, supporting demand for crop protection products across multiple application periods.
Yield Protection in Cereals, Oilseeds, and Sugar Beets
Germany’s winter wheat, oilseed rape, sugar beet, and barley rotations create recurring demand for fungicides, herbicides, and seed treatments. The BVL registered Bayer AG’s Buteo Start for sugar beet in 2025, demonstrating that new product registrations continue in high-value crop programs. Repeated rotations expose pathogens to similar modes of action across seasons, which can accelerate resistance pressure and support the use of tank mixes and co-formulated products. The Germany crop protection chemicals market therefore benefits from higher technical requirements in cereal and oilseed programs. Products that combine effective control with resistance management can retain value even where grower use is closely regulated. Continued focus on yield protection supports demand for effective and increasingly specialized crop protection solutions.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EU Active-Substance Non-Renewal and Maximum-Residue-Level Tightening | -0.6% | Germany, EU-27 | Short term (≤ 2 years) |
| Herbicide Resistance and Fewer Effective Modes of Action | -0.4% | Germany, Northern Europe | Medium term (2-4 years) |
| Water-Protection Zones and State-Level Application Constraints | -0.3% | Germany | Medium term (2-4 years) |
| Product Stewardship, Reporting, and Liability Burden | -0.2% | Germany, Central EU | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
EU Active-Substance Non-Renewal and Maximum-Residue-Level Tightening
The European Commission did not renew the approval of flufenacet in May 2025, requiring Member States to withdraw authorizations by December 10, 2025, with any applicable grace periods expiring by December 10, 2026. BVL subsequently revoked German product authorizations containing flufenacet, with product-specific use-up periods extending into December 2026. A separate change to the acetamiprid residue limits led to partial revocations for specific German crop uses from August 2025. These actions restrict the choices available to growers and require companies to revise product plans quickly. Large suppliers with established regulatory pipelines have an advantage, as they can fund new dossiers and replacements. The ongoing review of active substances can also increase manufacturers' development and registration costs. As fewer products remain approved for specific uses, companies may face longer timelines and higher costs to maintain their product portfolios in Germany.
Herbicide Resistance and Fewer Effective Modes of Action
Resistance in ryegrass and blackgrass is reducing the practical effectiveness of herbicide programs in German winter cereals. Growers may require several partial-efficacy treatments, whereas a single treatment once provides adequate control. Flufenacet had been an important soil-active tool in resistance management, and its withdrawal narrowed the available pre-emergence options. FMC Corporation received a 120-day emergency authorization for Fundatis, powered by Isoflex Active, for winter barley and winter wheat, effective September 28, 2026. This authorization reflects the urgency of finding new modes of action. Resistance increases per-hectare costs and reduces farmers' flexibility during the transition to replacement products. These constraints can limit the effectiveness of existing herbicide portfolios and increase the need for alternative solutions with different modes of action.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Function: Insecticides Lead, While Molluscicides Grow Faster
Insecticides accounted for 63% of Germany crop protection chemicals market size by function in 2026, supported by recurring aphid, flea beetle, and Colorado potato beetle pressure across cereal, oilseed, and root-crop rotations. Herbicides formed the next major category, although the flufenacet withdrawal has altered competition between pre-emergence and post-emergence products, with different roles in resistance management. Fungicides remained central to winter wheat Septoria programs and to oilseed rape programs for sclerotinia and light leaf spot. Molluscicides are forecast to grow at a CAGR of 5.1% from 2027 to 2032 as wetter autumn conditions increase slug pressure during oilseed rape and winter cereal establishment. Nematicides remain a minor function, serving potato and sugar beet production areas in northern and eastern Germany.
BASF SE invested EUR 919 million (USD 994 million) in research and development in its Agricultural Solutions division in 2024, supporting the development of crop protection products, seeds and traits, digital tools, and sustainability solutions for different crop systems. The Germany crop protection chemicals industry favors suppliers with broad product portfolios and registrations across major functional categories. Maintaining a diverse range of registered active ingredients and effective formulations requires substantial investment in research, development, and regulatory compliance, creating challenges for smaller portfolio holders.

By Application Mode: Foliar Application Leads, While Seed Treatment Grows Faster
Foliar application accounted for 53% of the Germany crop protection chemicals market size by application mode in 2026, as large cereal and oilseed areas required several fungicide, herbicide, and insecticide passes during the growing season. Soil treatment remained important in potato, sugar beet, and vegetable rotations where pre-planting control is integral to pest management. Fumigation was concentrated in high-value greenhouse and specialty horticulture operations. Chemigation was used mainly in irrigated sugar beet and vegetable areas in eastern Germany, where precision platforms can combine protection and crop-management decisions. Seed treatment is forecast to grow at a CAGR of 5.5% from 2027 to 2032 as growers seek systemic early-season disease and pest protection.
BVL authorized Buteo Start for flupyradifurone use in German sugar beet during 2025, confirming ongoing registration activity in the seed treatment category. Seed treatments can establish control before pathogen and pest populations necessitate later corrective foliar applications. The Germany crop protection chemicals industry is placing greater value on application modes that manage pressure before it becomes harder to control.
By Crop Type: Grains and Cereals Lead, While Fruits and Vegetables Grow Faster
Grains and cereals accounted for 60% of Germany crop protection chemicals market value by crop type in 2026, supported by extensive winter wheat, winter barley, and rye rotations on the northern plains. Pulses and oilseeds, especially oilseed rape, require intensive herbicide and fungicide programs while also supporting rising molluscicide use during autumn emergence. Commercial crops such as sugar beet create concentrated demand for insecticides and fungicides in northern and eastern beet-growing zones. Turf and ornamental crops remain a smaller premium category where residue standards are important. Fruits and vegetables are forecast to grow at a CAGR of 5.3% from 2027 to 2032 as specialty growers adopt premium products and reduced-risk chemistry.
Specialty growers use low-residue formulations to meet fresh-produce retail specifications and export-channel residue requirements. This creates a difference between volume concentration in cereals and value concentration in some specialty applications within the Germany crop protection chemicals market. The use of selective, low-residue crop protection products can expand the options available for applications subject to residue and resistance constraints. The Germany crop protection chemicals industry can serve this need while maintaining broad product coverage for the higher-volume cereal base.
Geography Analysis
Northern Germany provides the volume base through cereal and oilseed plains in Schleswig-Holstein, Lower Saxony, Saxony-Anhalt, and Brandenburg. Winter wheat and oilseed rape programs in these areas often require several fungicide and herbicide applications in a season. Eastern German farms have large field blocks that are suitable for precision systems, and the 300 to 400 hectare economic threshold for cereal spot spraying supports early adoption in these regions.
Southern Germany contributes a different product mix through hops, vineyards, fruit, and vegetable production. Bavaria, Baden-Württemberg, and Rhineland-Palatinate require intensive fungicide and insecticide programs for high-value specialty crops. Bavaria's target to reduce pesticide use by 50% by 2028 is increasing the focus on integrated pest management, precision application, and low-residue crop protection products, supporting earlier uptake of premium products compared to the northern cereal belt. Market size in southern states is supported by specialized crop requirements and strict retail and export residue standards.
Western Germany serves as a distribution node for parallel-trade products and cooperative supply networks. North Rhine-Westphalia and Rhineland-Palatinate connect growers to authorized products sourced from other European Union markets under parallel-import rules. This infrastructure supports availability and price competition as the number of approved active substances declines.
Competitive Landscape
The Germany crop protection chemicals market is moderately concentrated in 2026, led by Bayer AG, BASF SE, and Syngenta Group, which hold broad registrations and established distribution relationships across major crop programs. Their portfolios include crop protection products and digital agronomic services, while regulatory pipelines remain important as active substances are withdrawn. BASF SE and ADAMA Ltd. signed a co-development and commercialization agreement for Gilboa-based fungicide formulations in December 2025. Each company will independently develop and commercialize its own cereal formulations based on the active ingredient. The agreement shares development work for a new European fungicide option while allowing independent commercialization.
The Germany crop protection chemicals market also includes FMC Corporation, UPL Limited, Nufarm Limited, HELM AG, Certis Belchim B.V., Kwizda Agro GmbH, Life Scientific Ltd., Sharda Cropchem Limited, and Sipcam Oxon S.p.A. Mid-tier suppliers use patent-expiry opportunities and parallel trade to provide more affordable options through cooperative and wholesale distribution channels. According to FMC Corporation, Isoflex active has potential applications across more than 55 million planted hectares in the EU, subject to national product authorizations.
Digital tools that combine spray records, crop guidance, and application timing can improve customer retention in a compliance-focused market. The Germany crop protection chemicals market remains difficult for smaller companies due to substantial registration and stewardship costs. Suppliers must also maintain product efficacy, meet evolving regulatory requirements, and provide technical support to sustain their market positions. These factors favor companies with established product portfolios, regulatory expertise, and distribution networks, while limiting the ability of smaller suppliers to compete across multiple crop protection categories.
Germany Crop Protection Chemicals Industry Leaders
-
BASF SE
-
Bayer AG
-
Syngenta Group
-
FMC Corporation
-
Corteva, Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- October 2026: FMC Corporation’s Fundatis herbicide received a 120-day emergency authorization under Article 53 for use against blackgrass and ryegrass in winter barley and winter soft wheat in Germany. The authorization is valid from September 28, 2026, to January 25, 2027, with 60,000 liters approved for each crop. Fundatis combines Isoflex active with a second active ingredient, providing a new HRAC Group 13 mode of action for winter cereals.
- April 2026: FMC Corporation announced EU regulatory approval for Isoflex active (bixlozone), a herbicide active substance. FMC had submitted product dossiers for cereals, corn, oilseed rape, and potatoes and anticipated launching products containing the active substance from 2027, subject to further regulatory decisions.
- June 2025: Germany’s Federal Office of Consumer Protection and Food Safety (BVL) revoked the authorizations of additional plant protection products containing flufenacet following the European Commission’s non-renewal of the active substance in May 2025 under Implementing Regulation (EU) 2025/910.
Germany Crop Protection Chemicals Market Report Scope
Crop protection chemicals are substances used in agriculture to control pests, diseases, weeds, and other harmful organisms that affect crop yield and quality. They include herbicides, insecticides, fungicides, nematicides, and molluscicides applied to crops, seeds, and soil. The scope excludes biological crop protection products, fertilizers, plant growth regulators, and other agricultural inputs that do not primarily function as pesticides.
The Germany crop protection chemicals market is segmented by function (Fungicide, Herbicide, Insecticide, Molluscicide, and Nematicide), by application mode (Chemigation, Foliar, Fumigation, Seed Treatment, and Soil Treatment), and by crop type (Commercial Crops, Fruits and Vegetables, Grains and Cereals, Pulses and Oilseeds, and Turf and Ornamental). Market forecasts are provided in terms of value (USD) and volume (metric tons) for all segments.
By Function
| Fungicide |
| Herbicide |
| Insecticide |
| Molluscicide |
| Nematicide |
By Application Mode
| Chemigation |
| Foliar |
| Fumigation |
| Seed Treatment |
| Soil Treatment |
By Crop Type
| Commercial Crops |
| Fruits and Vegetables |
| Grains and Cereals |
| Pulses and Oilseeds |
| Turf and Ornamental |
| By Function | Fungicide |
| Herbicide | |
| Insecticide | |
| Molluscicide | |
| Nematicide | |
| By Application Mode | Chemigation |
| Foliar | |
| Fumigation | |
| Seed Treatment | |
| Soil Treatment | |
| By Crop Type | Commercial Crops |
| Fruits and Vegetables | |
| Grains and Cereals | |
| Pulses and Oilseeds | |
| Turf and Ornamental |
Market Definition
- Function - Crop Protection Chemicals are apllied to control or prevent pests, including insects, fungi, weeds, nematodes, and mollusks, from damaging the crop and to protect the crop yield.
- Application Mode - Foliar, Seed Treatment, Soil Treatment, Chemigation, and Fumigation are the different type of application modes through which crop protection chemicals are applied to the crops.
- Crop Type - This represents the consumption of crop protection chemicals by Cereals, Pulses, Oilseeds, Fruits, Vegetables, Turf, and Ornamental crops.
| Keyword | Definition |
|---|---|
| IWM | Integrated weed management (IWM) is an approach to incorporate multiple weed control techniques throughout the growing season to give producers the best opportunity to control problematic weeds. |
| Host | Hosts are the plants that form relationships with beneficial microorganisms and help them colonize. |
| Pathogen | A disease-causing organism. |
| Herbigation | Herbigation is an effective method of applying herbicides through irrigation systems. |
| Maximum residue levels (MRL) | Maximum Residue Limit (MRL) is the maximum allowed limit of pesticide residue in food or feed obtained from plants and animals. |
| IoT | The Internet of Things (IoT) is a network of interconnected devices that connect and exchange data with other IoT devices and the cloud. |
| Herbicide-tolerant varieties (HTVs) | Herbicide-tolerant varieties are plant species that have been genetically engineered to be resistant to herbicides used on crops. |
| Chemigation | Chemigation is a method of applying pesticides to crops through an irrigation system. |
| Crop Protection | Crop protection is a method of protecting crop yields from different pests, including insects, weeds, plant diseases, and others that cause damage to agricultural crops. |
| Seed Treatment | Seed treatment helps to disinfect seeds or seedlings from seed-borne or soil-borne pests. Crop protection chemicals, such as fungicides, insecticides, or nematicides, are commonly used for seed treatment. |
| Fumigation | Fumigation is the application of crop protection chemicals in gaseous form to control pests. |
| Bait | A bait is a food or other material used to lure a pest and kill it through various methods, including poisoning. |
| Contact Fungicide | Contact pesticides prevent crop contamination and combat fungal pathogens. They act on pests (fungi) only when they come in contact with the pests. |
| Systemic Fungicide | A systemic fungicide is a compound taken up by a plant and then translocated within the plant, thus protecting the plant from attack by pathogens. |
| Mass Drug Administration (MDA) | Mass drug administration is the strategy to control or eliminate many neglected tropical diseases. |
| Mollusks | Mollusks are pests that feed on crops, causing crop damage and yield loss. Mollusks include octopi, squid, snails, and slugs. |
| Pre-emergence Herbicide | Preemergence herbicides are a form of chemical weed control that prevents germinated weed seedlings from becoming established. |
| Post-emergence Herbicide | Postemergence herbicides are applied to the agricultural field to control weeds after emergence (germination) of seeds or seedlings. |
| Active Ingredients | Active ingredients are the chemicals in pesticide products that kill, control, or repel pests. |
| United States Department of Agriculture (USDA) | The Department of Agriculture provides leadership on food, agriculture, natural resources, and related issues. |
| Weed Science Society of America (WSSA) | The WSSA, a non-profit professional society, promotes research, education, and extension outreach activities related to weeds. |
| Suspension concentrate | Suspension concentrate (SC) is one of the formulations of crop protection chemicals with solid active ingredients dispersed in water. |
| Wettable powder | A wettable powder (WP) is a powder formulation that forms a suspension when mixed with water prior to spraying. |
| Emulsifiable concentrate | Emulsifiable concentrate (EC) is a concentrated liquid formulation of pesticide that needs to be diluted with water to create a spray solution. |
| Plant-parasitic nematodes | Parasitic Nematodes feed on the roots of crops, causing damage to the roots. These damages allow for easy plant infestation by soil-borne pathogens, which results in crop or yield loss. |
| Australian Weeds Strategy (AWS) | The Australian Weeds Strategy, owned by the Environment and Invasives Committee, provides national guidance on weed management. |
| Weed Science Society of Japan (WSSJ) | WSSJ aims to contribute to the prevention of weed damage and the utilization of weed value by providing the chance for research presentation and information exchange. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


