
GCC International Express Service Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 0.72 Billion |
| Market Size (2027) | USD 0.78 Billion |
| Market Size (2032) | USD 1.13 Billion |
| Growth Rate (2027 - 2032) | 7.57 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
GCC International Express Service Market Analysis by Mordor Intelligence
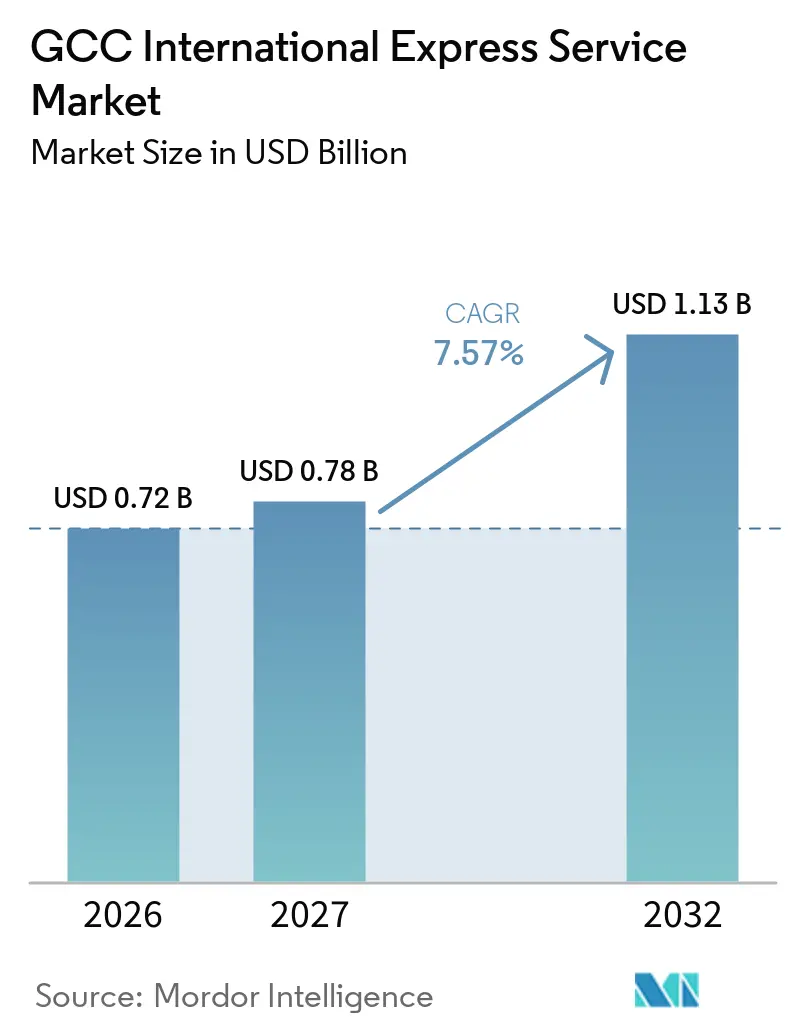
The GCC international express service market size is valued at USD 0.72 billion in 2026 and is estimated to grow from USD 0.78 billion in 2027 to reach USD 1.13 billion by 2032, at a CAGR of 7.57% during the forecast period (2027-2032).
The GCC international express service market is shaped by cross-border online purchases, customs modernization, and the Gulf’s role between Asian exporters and consumers in Africa and Europe. A uniform 12-digit Harmonized System tariff supports machine-readable classification and more consistent clearance procedures across the six member states. National logistics programs are adding air cargo capacity, bonded storage, and local delivery coverage, which increases the volume that carriers can serve. The GCC international express service market also faces exposure to airspace disruptions, maritime bottlenecks, and higher labor costs related to workforce localization. Operators are responding by separating premium services for time-sensitive shipments from value services for price-sensitive parcels and cash-on-delivery orders.
Key Report Takeaways
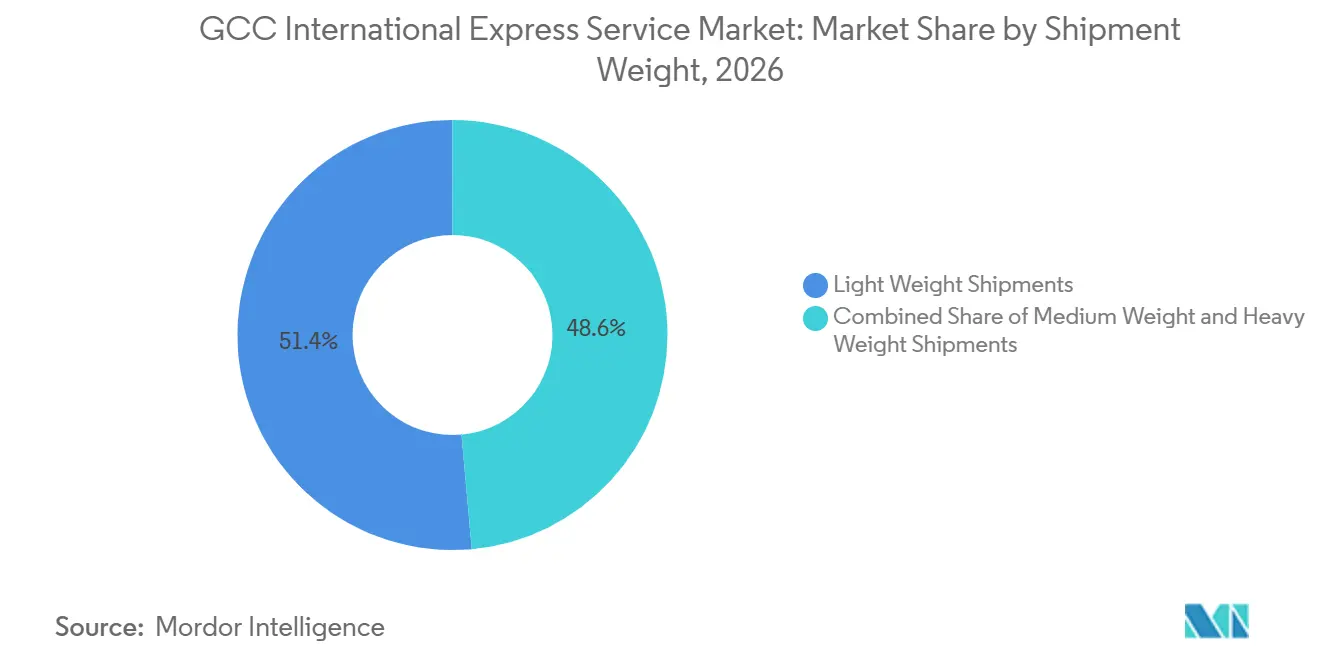
- By shipment weight, light weight shipments held 51.43% of the GCC international express service market share in 2026, and are forecast to expand at a 7.76% CAGR through 2032.
- By route, intra-regional GCC shipments held 74.13% of the GCC international express service market size in 2026, while inter-regional shipments are forecast to expand at a 7.80% CAGR through 2032.
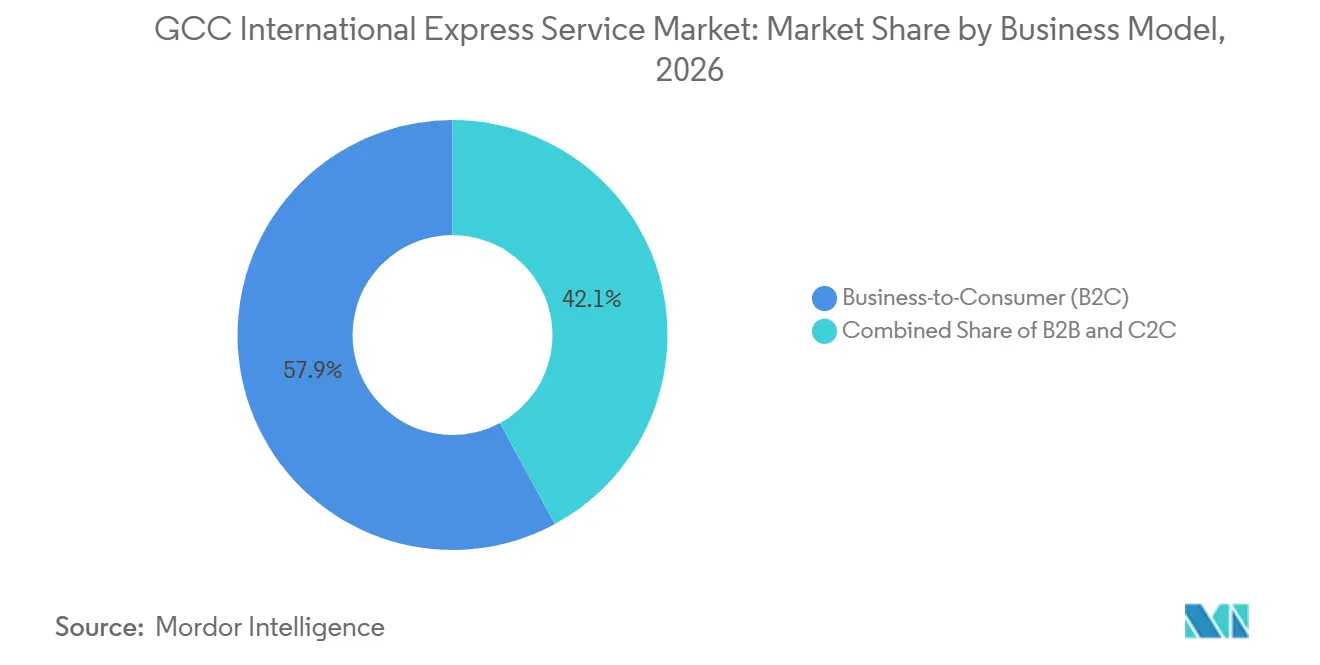
- By business model, B2C held 57.89% of the GCC international express service market share in 2026, and is forecast to expand at an 8.42% CAGR through 2032.
- By mode of transport, road held 50.34% of the GCC international express service market size in 2026, while air is forecast to expand at an 8.10% CAGR through 2032.
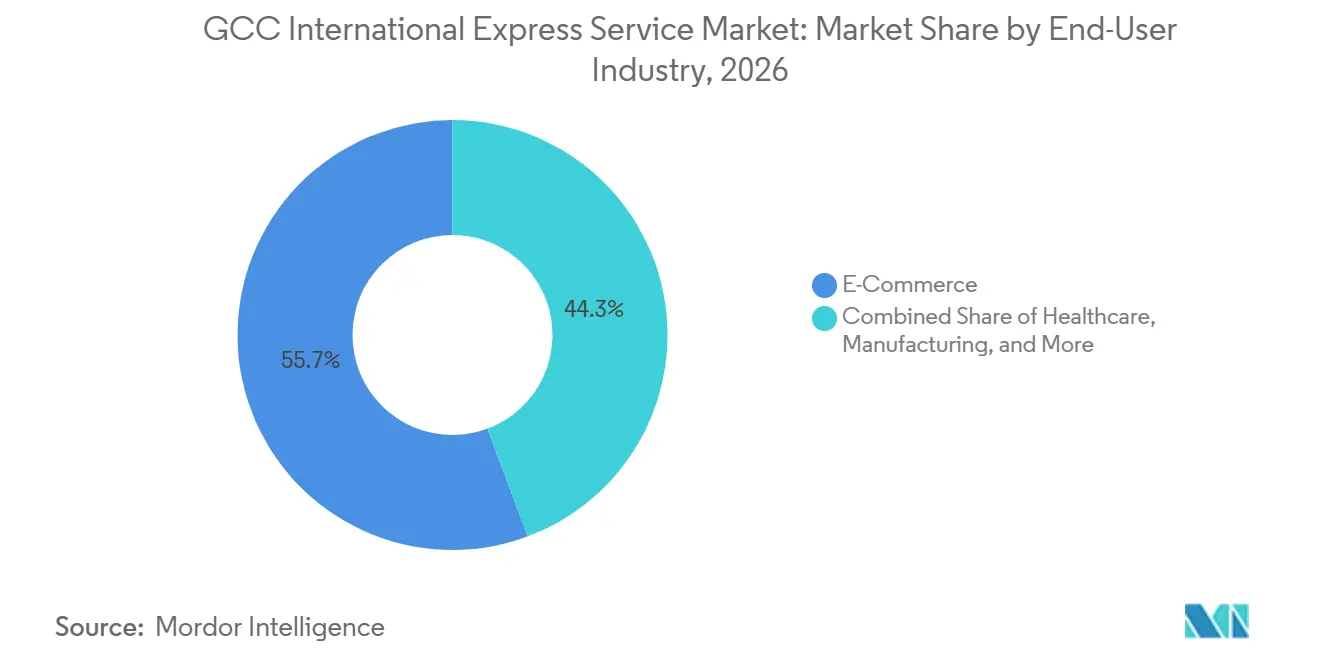
- By end user industry, e-commerce held 55.70% share in 2026 and is forecast to expand at an 8.28% CAGR through 2032.
- By country, Saudi Arabia held 53.85% share in 2026, while the United Arab Emirates is forecast to expand at an 8.07% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of GCC International Express Service Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cross-Border E-Commerce Growth | +2.1% | Global, led by United Arab Emirates and Saudi Arabia | Medium term (2-4 years) |
| GCC Customs-Duty Harmonization | +1.3% | All six GCC member states | Short term (≤ 2 years) |
| 24-Hour Clearance at Major Air Cargo Hubs | +0.9% | United Arab Emirates and Saudi Arabia | Short term (≤ 2 years) |
| Expansion of Bonded Logistics Zones | +0.8% | United Arab Emirates, Oman, Saudi Arabia, Bahrain | Medium term (2-4 years) |
| Pharmaceutical Cold-Chain-as-a-Service | +0.7% | United Arab Emirates and Saudi Arabia, with effects in Qatar and Oman | Long term (≥ 4 years) |
| Cross-Border Returns Consolidation and Duty Recovery | +0.5% | GCC-wide, led by United Arab Emirates and Saudi Arabia | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Cross-Border E-Commerce Growth
Cross-border e-commerce remains an important source of parcel demand for the GCC international express service market because consumers increasingly order products not held in domestic inventories. DHL expects GCC e-commerce to grow at nearly 11% annually through 2027 and identifies cross-border logistics as a notable area of activity within the region[1]. Delivery speed can affect a buyer’s willingness to complete an order, especially for products with limited local availability or a short purchase cycle. This makes predictable delivery windows important to platforms, sellers, and consumers, rather than simply an added shipping feature. Express providers that can link shipment data, customs processing, and last-mile updates are better placed to support this demand. The GCC international express service market, therefore, depends on service consistency as well as parcel volume, since recurring online demand can move quickly toward providers with better delivery reliability.
GCC Customs-Duty Harmonization
The GCC Integrated Customs Tariff moved to a 12-digit classification structure across member states from January 2025, creating a common basis for product classification[2]. A common structure gives operators a clearer foundation for preparing declarations across multiple GCC destinations. It also makes accurate product data more valuable, because the quality of submitted information affects whether a shipment can move through automated clearance. The GCC international express service market benefits when classification and declaration processes are less dependent on manual correction. Operators with integrated customs systems can use the change to reduce avoidable data errors and handoffs. The remaining advantage will depend on how consistently importers, marketplaces, and carriers apply the classification requirements in daily operations.
24-Hour Clearance at Major Air Cargo Hubs
Air cargo hubs in the United Arab Emirates and Saudi Arabia remain central to time-sensitive express movements because they connect international flights with regional delivery networks. The GCC international express service market gains from facilities that can handle high-value, temperature-sensitive, and urgent shipments without creating unnecessary transfer delays. GSK’s regional vaccine distribution hub in Abu Dhabi received its first shipments in 2025, showing the importance of a coordinated cargo and health logistics environment. Such operations require clear customs processes, dedicated handling, and reliable transfers to local distribution networks. Hub performance can influence where manufacturers place regional inventory, particularly when a delayed shipment can affect product quality or availability. Investment in Saudi airport and logistics capacity could also increase competitive pressure on established United Arab Emirates gateways over time.
Expansion of Bonded Logistics Zones
Bonded zones allow goods to be stored, processed, and re-exported before duties or value-added tax are triggered at domestic market entry. This structure can improve inventory placement for businesses serving several GCC markets from a single location. DP World and Oman’s Public Authority for Special Economic Zones and Free Zones agreed to develop Al Rawdah Special Economic Zone near the Oman-United Arab Emirates border in 2025[3]. The GCC international express service market can benefit when bonded storage, customs brokerage, and dispatch operations operate in the same logistics environment. This reduces the number of transfers needed before parcels enter an express network. The approach is particularly relevant for re-export activity, regional inventory consolidation, and shipments that may be redirected to another GCC destination.
Restraints Impact Analysis of GCC International Express Service Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Limited Last-Mile Infrastructure Outside Tier-1 Cities | -1.8% | Saudi Arabia, Oman, Kuwait, Qatar | Long term (≥ 4 years) |
| Workforce Nationalization and Skilled-Labor Constraints | -1.1% | Saudi Arabia and the United Arab Emirates | Medium term (2-4 years) |
| Geopolitical Choke Points and Airspace Disruption | -1.4% | Global, concentrated in GCC air and maritime corridors | Short term (≤ 2 years) |
| Cargo Security Rules for Lithium-Battery Shipments | -0.6% | Global, applicable at all GCC air gateways | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Limited Last-Mile Infrastructure Outside Tier-1 Cities
The GCC international express service market faces higher delivery costs when networks extend beyond the largest cities into lower-density areas. Routes outside major urban centers may involve fewer parcels per stop, longer travel distances, and greater uncertainty in final delivery locations. This makes it difficult to keep the cost per delivery aligned with customer expectations for express services. Cash-on-delivery orders can add further work because collections, failed deliveries, and return movements require extra handling. Address quality also remains important, since unclear locations can require drivers to call customers or carry out manual searches. National address initiatives can improve this over time, but providers still need enough route density to make expanded coverage financially sustainable.
Workforce Nationalization and Skilled-Labor Constraints
Nationalization policies can increase staffing pressure for logistics companies that depend on specialized operational roles. Saudi Arabia’s Ministry of Human Resources and Social Development reported progress in labor-market programs and continued enforcement activity during 2025[4]. The GCC international express service market needs to balance local hiring goals with the need for experienced customs, dangerous-goods, cold-chain, and operations personnel. Training programs can help companies create local capability, but the process takes time and may increase near-term labor costs. Larger carriers may be better positioned to build formal development tracks and retain specialist expertise during the transition. Smaller providers may find compliance more difficult when operational requirements rise at the same time as wage and training costs.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
GCC International Express Service Market Segment Analysis
By Shipment Weight:
Light Weight Shipments Lead E-Commerce Parcel FlowsLight weight shipments held 51.43% of the GCC international express service market share in 2026 and are forecast to expand at a 7.76% CAGR through 2032. This category fits the operating model of online retail parcels, documents, samples, small consumer electronics, and many healthcare consignments. Automated sortation systems are usually designed to process large volumes of parcels within a limited size and weight range. The GCC international express service market size for light shipments is supported by frequent orders rather than high revenue from individual consignments. Direct-to-consumer sellers also tend to ship beauty products, personal care items, accessories, and electronics in smaller parcels. These shipment profiles reward operators who can process high volumes with frequent scans and predictable routing.
Medium weight shipments serve customers who need faster delivery than economy freight but do not require the premium handling used for the smallest urgent parcels. Industrial components, medical devices, fashion goods, and business supplies can fall into this range. Heavy shipments represent a smaller share of parcel movements, but their value per shipment can be higher when they support production-critical activity. A delayed spare part can have consequences that outweigh the additional cost of express transport. Providers, therefore, need weight-based pricing and network design that recognize different service needs rather than applying a single delivery model.

By Route:
Intra-Regional GCC Shipments Anchor Revenue While Inter-Regional Gains PaceIntra-regional GCC shipments held 74.13% of the GCC international express service market size in 2026. These flows benefit from shorter distances, strong trade links, and the movement of regional inventory between Gulf markets. The market share held by intra-regional routes reflects the importance of replenishment shipments between free zones, warehouses, retailers, and business customers. United Arab Emirates logistics facilities remain important starting points for regional movements because many firms stage goods there before distributing them across the Gulf. Predictable customs treatment and established road corridors can support next-business-day services on major routes. This makes regional flows important for carriers that need stable network utilization and recurring commercial demand.
Inter-regional shipments are forecast to expand at a 7.80% CAGR from 2027 to 2032. These flows connect GCC buyers and sellers with production centers and consumer markets outside the region. Goods entering free zones can be processed, consolidated, or redirected before being sent to Africa, South Asia, Europe, or East Asia. FedEx expanded its direct presence in Saudi Arabia in September 2025 and introduced a dedicated nonstop service connecting the Kingdom with the United States and Europe. Direct lanes can reduce the need for intermediate transfers and strengthen service choices for companies with international customers. The GCC international express service market may need these international connections as exporters and online sellers seek more dependable access to customers outside the Gulf.
By Business Model:
B2C Volumes Set the Competitive TempoB2C held 57.89% of the GCC international express service market share in 2026 and is forecast to expand at an 8.42% CAGR through 2032. This growth is tied to marketplace activity, social commerce, and consumer demand for international products with short delivery windows. The GCC international express service market gains B2C volume when retailers make faster shipping visible at the point of purchase. However, B2C orders can create additional complexity because delivery addresses, consumer availability, payment methods, and return requests vary more than in contract-based business shipments. Providers need mobile delivery tools that show clear status updates and allow drivers to manage delivery exceptions quickly. The resulting service quality can influence whether a consumer returns to the same seller or platform for a future purchase.
B2B shipments remain important because they can generate more revenue per consignment and often operate under formal service-level agreements. Financial services, healthcare buyers, manufacturers, and wholesalers need reliable handling of documents, consumables, cards, parts, and inventory replenishment. These customers often value shipment visibility and exception alerts as much as the stated transit time. C2C activity is smaller but can grow as resale platforms expand for used electronics, luxury goods, and personal items. Insurance, proof of delivery, and traceability can matter more for these transactions because individual senders and recipients may have limited experience with shipping procedures.
By Mode of Transport:
Road Dominates Intra-GCC Flows, Air Accelerates on Premium CorridorsRoad transport held 50.34% of the GCC international express service market size in 2026. It remains a practical option for intra-GCC shipments that can accept transit times of 1 to 3 days. Road networks are especially relevant for medium-weight consignments where air transport can be costly relative to shipment value. Bonded truck corridors also support movements from United Arab Emirates free zones to neighboring markets while goods remain under customs control. The GCC international express service market size tied to road services depends on route reliability, border processing, and the availability of regional trucking capacity. Road operations provide a base volume that helps carriers balance more expensive air services and maintain coverage across major trade corridors.
Air transport is forecast to expand at an 8.10% CAGR from 2027 to 2032. It is well-suited to pharmaceuticals, high-value electronics, documents, and inter-regional shipments that require a short delivery window. Emirates SkyCargo reported that it had moved more than 1 million pharmaceutical shipments through Dubai during the previous decade, illustrating the scale of controlled healthcare cargo handled through the hub. Air services require stronger controls for regulated cargo, but they can create higher-value opportunities for carriers with reliable airport, customs, and last-mile links. Rail and short-sea routes may eventually complement road networks, although their role in express services remains limited while projects are developed.
By End User Industry:
E-Commerce Anchors Demand as Healthcare Verticals AccelerateE-commerce accounted for 55.70% of the GCC international express service market share in 2026 and is forecast to expand at an 8.28% CAGR through 2032. The category is large because marketplaces create frequent parcel movements across national borders and within regional distribution networks. Seller rankings, fulfillment promises, and visible delivery options can encourage merchants to use express services even where margins are limited. Customs brokerage is also valuable for sellers who need to meet product registration and conformity requirements before delivery. The GCC international express service market, therefore, benefits when platforms, merchants, and carriers share accurate item-level shipment data. These connections reduce the chance that a parcel reaches a border without the information needed for clearance.
Healthcare is the fastest-growing non-e-commerce vertical because biologics, vaccines, and specialized treatments often require controlled transport and complete handling records. Manufacturing also creates an important express demand for spare parts, electronic components, and equipment needed to prevent production delays. Financial services and offline retail create recurring demand for documents, card stock, replenishment goods, and other scheduled deliveries. These segments may move fewer parcels than e-commerce, but their service expectations can be more demanding. Carriers can strengthen their position by designing specialist processes rather than treating every shipment as a standard consumer parcel.
Geography Analysis
Saudi Arabia held 53.85% of the market share in 2026. The country’s large consumer base and position as a destination for regional replenishment and imported online orders support this scale. FedEx completed a transition to direct-serve operations in Saudi Arabia during 2025 and announced a regional Riyadh hub connecting Bahrain, Kuwait, and Qatar. Saudi logistics development can improve the country’s access to premium international corridors and create stronger domestic distribution links. However, delivery costs outside Riyadh, Jeddah, and Dammam remain a challenge when parcel density is lower. The GCC international express service market needs to solve this last-mile issue if carriers are to turn broad geographic demand into profitable coverage.
The United Arab Emirates is forecast to expand at an 8.07% CAGR from 2027 to 2032. Its free zones, air hubs, and re-export activity allow companies to stage inventory for nearby Gulf markets as well as Africa and South Asia. The GCC international express service market benefits from this concentration because international and regional flows can use the same logistics infrastructure. Moreover, the Sharjah-Oman logistics corridor recorded 66.26% growth in cargo value during its first 3 months after its May 2026 launch. This result shows that formal cross-border links can make previously dispersed demand more visible and easier to serve. United Arab Emirates providers can use this network position to combine domestic delivery, regional distribution, and international forwarding in one operating model.
Qatar, Bahrain, Kuwait, and Oman account for the remaining share of the GCC international express service market. Qatar supports demand for premium goods, financial documents, healthcare supplies, and air cargo movements through Hamad International Airport. Bahrain’s logistics zone offers potential for bonded storage and re-export activity linked to Saudi Arabia and Qatar. Kuwait’s consumer demand can support cross-border B2C delivery, although last-mile networks remain concentrated around Kuwait City. Oman can become a more important consolidation location because its border infrastructure and port access can support regional returns and re-export flows. DP World’s Al Rawdah agreement also supports the longer-term case for Oman as a cross-border logistics location.
Competitive Landscape
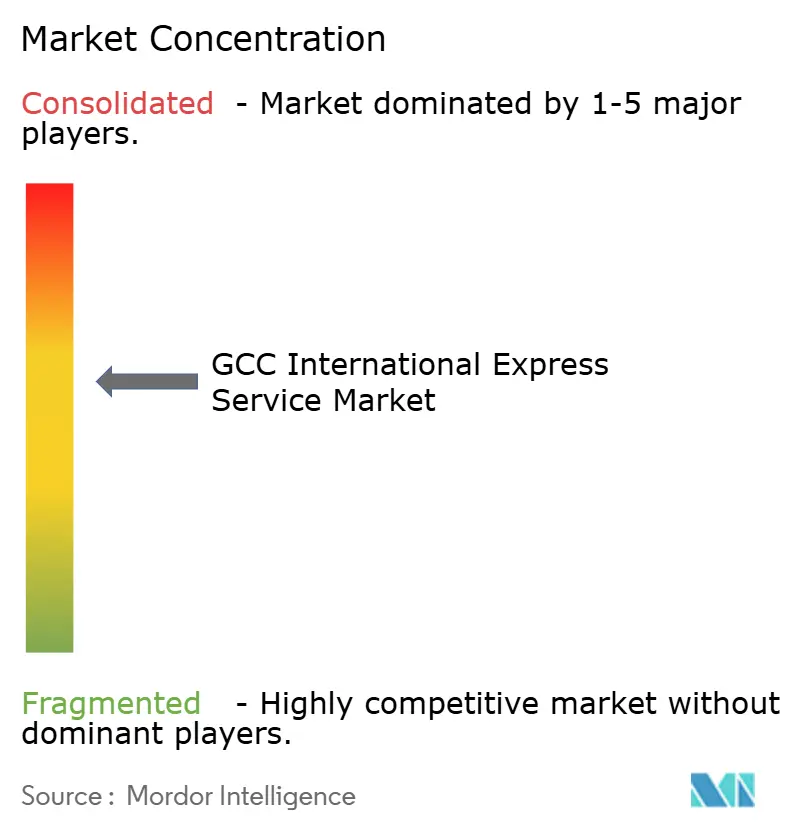
The GCC international express service market is moderately consolidated among global integrators, which use air networks, customs systems, and international delivery coverage to serve multinational customers. At the same time, regional carriers, postal operators, and local last-mile providers compete for business based on local coverage, payment flexibility, and delivery execution. This creates a divided competitive environment rather than one controlled by a single business model. Global operators tend to be stronger in international lanes and complex commercial shipments. Regional providers can be more flexible in cash collection, local language support, address resolution, and consumer delivery preferences. The GCC international express service market rewards companies that can combine international reliability with local operating knowledge.
FedEx strengthened its Saudi Arabia presence in September 2025 through direct-serve operations, a dedicated nonstop service to the United States and Europe, and a regional Riyadh hub. This move adds direct international capacity while also improving the company’s regional network position. DP World and Oman’s Public Authority for Special Economic Zones and Free Zones agreed to develop Al Rawdah Special Economic Zone, creating a second example of investment focused on cross-border logistics infrastructure. DHL’s GCC e-commerce material also indicates that cross-border online activity remains a key logistics consideration for businesses serving the region. These actions show that network capacity, customs capability, and regional inventory placement remain practical areas of competition.
Pharmaceutical handling, returns consolidation, customs data integration, and secondary-city delivery are areas where providers can differentiate themselves. Healthcare services require robust handling controls and recorded shipment conditions, which can favor carriers with specialized facilities and trained teams. Returns services are important because online sellers need a way to collect, inspect, restock, or redirect goods after a cross-border customer return. Customs data systems can reduce delays, but they require clean product information from sellers and strong integration with clearance processes. Competition will remain active because providers face pressure from international integrators above them and locally focused delivery platforms below them.
GCC International Express Service Industry Leaders
-
Aramex PJSC
-
DHL Group
-
FedEx Corporation
-
United Parcel Service, Inc.
-
Saudi Post- SPL (including Naqel Express)
- *Disclaimer: Major Players sorted in no particular order
GCC International Express Service Market Companies Covered in this Report
- Aramex PJSC
- DHL Group
- FedEx Corporation
- United Parcel Service, Inc.
- Saudi Post- SPL (including Naqel Express)
- Emirates Post Group
- SMSA Express Transportation Company Ltd.
- Qatar Post
- Postaplus
- Agility Global PLC (Shipa)
- iMile Delivery Services LLC
- AJEX Logistics Services
- J&T Global Express Limited
- S.F. Holding Co., Ltd.
- Asyad Express
- Zajil Express Trading Company L.L.C.
- SkyNet Worldwide Express LLC
- First Flight Couriers (Middle East) L.L.C.
- Century Express Courier Services LLC
- Bahrain Post
- Sa'ee Logistic Services
Recent Industry Developments in GCC International Express Service Market
- July 2026: FedEx signed a Memorandum of Understanding with Dubai Chambers to support the international expansion of Dubai-based businesses, combining FedEx's global logistics network with preferential shipping programs and customs advisory support for Dubai Chambers member companies. The MoU reinforces Dubai's positioning as a global trade hub by integrating express logistics into institutional business development programs.
- July 2025: Emirates Post (under parent company 7X) signed a new agreement with DHL Express to roll out DHL Express Easy at select Emirates Post branches, while 7X simultaneously partnered with Amazon to accelerate urban last-mile delivery across the United Arab Emirates. The dual partnership transforms Emirates Post's nationwide branch network into a multi-carrier access point for both international express and domestic e-commerce fulfillment.
- July 2025: Asyad Express launched a technology-driven Reverse Logistics Platform providing GCC-wide coverage for e-commerce parcel returns, integrating doorstep pickup, quality inspection, and inventory reintegration with full shipment visibility. The platform is designed to help GCC retailers convert returns management from a cost center into a customer retention and duty-recovery mechanism.
- June 2025: DHL Group announced a EUR 500 million (USD 588.2 million) investment plan targeting Saudi Arabia and the United Arab Emirates across all four divisions. The investment is aligned with DHL's Strategy 2030 "Accelerate Sustainable Growth" program.
GCC International Express Service Market Report Scope
Segmentation Overview
| Light Weight Shipments |
| Medium Weight Shipments |
| Heavy Weight Shipments |
| Inter-Regional Shipments |
| Intra-Regional GCC Shipments |
| Business-to-Business (B2B) |
| Business-to-Consumer (B2C) |
| Consumer-to-Consumer (C2C) |
| Air |
| Road |
| Others |
| E-Commerce |
| Financial Services (BFSI) |
| Healthcare |
| Manufacturing |
| Primary Industry |
| Wholesale and Retail Trade (Offline) |
| Others |
| Saudi Arabia |
| United Arab Emirates |
| Qatar |
| Bahrain |
| Kuwait |
| Oman |
| By Shipment Weight | Light Weight Shipments |
| Medium Weight Shipments | |
| Heavy Weight Shipments | |
| By Route | Inter-Regional Shipments |
| Intra-Regional GCC Shipments | |
| By Business Model | Business-to-Business (B2B) |
| Business-to-Consumer (B2C) | |
| Consumer-to-Consumer (C2C) | |
| By Mode of Transport | Air |
| Road | |
| Others | |
| By End User Industry | E-Commerce |
| Financial Services (BFSI) | |
| Healthcare | |
| Manufacturing | |
| Primary Industry | |
| Wholesale and Retail Trade (Offline) | |
| Others | |
| By Country | Saudi Arabia |
| United Arab Emirates | |
| Qatar | |
| Bahrain | |
| Kuwait | |
| Oman |
Market Definition
- Courier, Express, and Parcel - The Courier, Express, and Parcel services, often called as CEP Market, refers to the logistics and postal service providers which specialize in moving small goods (parcels/packages). It captures the overall market size (USD) and market volume (number of parcels) of (1) the shipments/parcels/packages which are under 70kgs/ 154lbs weight, (2) Business Customer packages viz. Business-to-Business (B2B) & Business-to-Consumer (B2C) as well as private customer packages (C2C), (3) non-express parcel delivery services (Standard and Deferred) as well as express parcel delivery services (Day-Definite-Express and Time-Definite-Express), (4) domestic as well as international shipments.
- Demographics - To analyse total addressable market demand, population growth & forecasts have been studied and presented in this industry trend. It represents population distribution across categories like gender (male/female), development area (urban/rural), major cities among other key parameters like population density and final consumption expenditure (growth and share % of GDP). This data has been used for assessing the fluctations in demand & consumption expenditure, and the major hotspots (cities) of potential demand.
- Domestic Courier Market - Domestic Courier Market refers to the CEP shipments wherein the origin and destination is within the boundary of the geography studied (country or region as per the scope of report). It captures the market size (USD) and market volume (number of parcels) of (1) the shipments/parcels/packages which are under 70kgs/ 154lbs weight, including light weight shipments, medium weight shipments and heavy weight shipments (2) Business Customer packages viz. Business-to-Business (B2B) & Business-to-Consumer (B2C) as well as private customer packages (C2C), (3) non-express parcel delivery services (Standard and Deferred) as well as express parcel delivery services (Day-Definite-Express and Time-Definite-Express).
- E-Commerce - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the e-tailers, through online sales channel, on Courier, Express, and Parcel (CEP) services. The scope includes (i) the supply chain of a company's online customer orders being fulfilled, (ii) the process of getting a product from the point of manufacturing to the point at which it is delivered to consumers. It involves managing inventory (deferred as well as time critical), shipping, and distribution.
- Export Trends and Import Trends - Overall logistics performance of an economy is positively and significantly (statistically) correlated to its trade performance (exports and imports). Hence, in this industry trend, total value of trade, major commodities/ commodity groups and the major trade partners, for the studied geography (country or region as per the scope of report) have been analysed alongside the impact of major trade/logistics infrastructure investments & regulatory environment.
- Financial Services (BFSI) - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the BFSI players, on Courier, Express, and Parcel (CEP) services. CEP is important to the financial services industry in shipping of confidential documents and files. The establishments in this sector are engaged in (i) financial transactions (that is, transactions involving the creation, liquidation, or change in ownership of financial assets) or in facilitating financial transactions, (ii) financial intermediation, (iii) the pooling of risk by underwriting annuities and insurance, (iv) providing specialized services that facilitate or support financial intermediation, insurance and employee benefit programs, and (v) monetary control - the monetary authorities.
- Fuel Price - Fuel price spikes can cause delays and diruption for logistics service providers (LSPs), while drops in the same can result in higher short-term profitability and increased market rivalry to offer consumers with the best deals. Hence, the fuel price variations have been studied over the review period and presented along with the causes as well as market impacts.
- GDP Distribution by Economic Activity - Nominal Gross Domestic Product and distribution of the same, across major economic sectors in the geography studied (country or region as per scope of the report) have been studied and presented in this industry trend. As GDP is positively related to the profitability and growth of logistics industry, this data has been used in adjunction to the input-output tables/ supply-use tables for analyzing the potential major contributing sectors towards the logistics demand.
- GDP Growth by Economic Activity - Growth of Nominal Gross Domestic Product across major economic sectors, for the geography studied (country or region as per scope of the report) have been presented in this industry trend. This data has been utilized for assessing the growth of logistics demand from all the market end users (economic sectors considered here).
- Healthcare - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the Healthcare players (Hospitals, clinics, mrdical centres) , on Courier, Express, and Parcel (CEP) services. The scope includes CEP services involved in the defrerred as well time critical movement of medical goods & supplies (surgical supplies and instruments, including gloves, masks, syringes, equipment). The establishments in this sector (i) include the ones providing medical care exclusively (ii) deliver services by trained professionals (iii) involve processes, including labor inputs of health practitioners with the requisite expertise (iv) are defined based on the educational degree held by the practitioners included in the industry.
- Inflation - Variations in both Wholesale Price Inflation (YoY change in producer price index) and Consumer Price Inflation have been presented in this industry trend. This data has been used to assess the inflationary environment as it plays a vital role in smooth functioning of the supply chain, directly impacting the logistics operational cost components e.g., pricing of tyres, driver wages & benefits, energy/fuel prices, maintenace costs, toll charges, warehousing rents, custom brokerage, forwarding rates, courier rates etc. hence impacting the overall freight and logistics market.
- Infrastructure - As infrastructure plays a vital role in an economy's logistics performance, variables like length of roads, distribution of road length by surface category (paved v/s unpaved), distribution of road length by road classification (expressways v/s highways v/s other roads), rail length, volume of containers handled by major ports and tonnage handled by major airports have been analysed and presented in this industry trend.
- International Express Service Market - International Express Service Market refers to the CEP shipments wherein the origin or destination is not within the boundary of the geography studied (country or region as per the scope of report). It captures the market size (USD) and market volume (number of parcels) of (1) the shipments/parcels/packages which are under 70kgs/ 154lbs weight, including light weight shipments, medium weight shipments and heavy weight shipments (ii) Inter-Region as well as Intra-Region Shipments
- Key Industry Trends - The report section named "Key Industry Trends" include all the key variables/parameters studied to better analyze the market size estimates and forecasts. All the trends have been presented in the form of data points (time series or latest available data points) along with analysis of the paramter in the form of concise market relevant commentary, for the geography studied (country or region as per the scope of report).
- Key Strategic Moves - The action taken by a company to differentiate from its competitor or used as a general strategy is referred to as a key strategic move (KSM). This includes (1) Agreements (2) Expansions (3) Financial Restructuring (4) Mergers and Acquisitions (5) Partnerships, and (6) Product Innovations. Key players (Logistics Service Providers, LSPs) in the market have been shortlisted, their KSM have been studied and presented in this section.
- Logistics Performance - Logistics Performance and Logistics Costs are the backbone of trade, and influences trade costs, making countries compete globally. Logistics performance is influenced by market wide adopted supply chain management strategies, government services, investments & policies, fuel/ energy costs, inflationary environment etc. Hence, in this industry trend, the logistics performance of the geography studied (country/ region as per the scope of report) has been analysed and presented over the review period.
- Manufacturing - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the Manufacturing industry (including Hi-Tech/Technology) players, on Courier, Express, and Parcel (CEP) services. The end user players considered are the establishments primarily engaged in the chemical, mechanical or physical transformation of materials or substances into new products. Logistics Service Providers (LSPs) play a crucial role in maintaining a smooth flow of raw materials across the supply chain, enabling timely delivery of finished goods to distributors or end customers and storing & supplying the raw materials to clients for just-in-time manufacturing.
- Other End Users - Other end user segment captures the external (outsourced) logistics expenditure incurred by the construction, real estate, educational services, and professional services (administrative, waste management, legal, architectural, engineering, design, consulting, scientific R&D), on Courier, Express, and Parcel (CEP) services. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of time critical supplies and documents to/from these industries such as transporting any equipment or resources required, shipping confidential documents and files.
- Primary Industry - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the AFF (Agriculture, Fishing, and Forestry) and Extraction indsutry (Oil &Gas, Quarrying and Mining) players, on Courier, Express, and Parcel (CEP) services. The end user players considered are the establishments (i) primarily engaged in growing crops, raising animals, harvesting timber, harvesting fish & other animals from their natural habitats and providing related support activities; (ii) that extract naturally occurring mineral solids, such as coal and ores; liquid minerals, such as crude petroleum; and gases, such as natural gas. Herein, Logistics Service Providers (LSPs) (i) play a crucial role in acquisition, storage, handling, transportation, and distribution activities for the optimal & continuous flow of inputs (seeds, pesticides, fertilizers, equipment, and water) from manufacturers or suppliers to the producers and smooth flow of output (produce, agro-goods) to distributors/ consumers; (ii) cover entire phases from upstream to downstream and play a crucial role in the transportation of machinery, drilling equipments, extracted minerals, crude oil & natural gas and refined/ processed products from one place to another. This includes both termperature controlled and non-temperature controlled logistics, as and when required according to the shelf life of goods being transported or stored.
- Producer Price Inflation - It indicates inflation from viewpoint of the producers viz. the average selling price received for their output over a period of time. Annual change (YoY) of producer price index is reported as wholesale price inflation in the "Inflation" industry trend. As WPI captures dynamic price movements in most comprehensive way, it is widely used by governments, banks, industry, business circles and is deemed important in formulation of trade, fiscal and other economic policies. The data has been used in adjunction to consumer price inflation for better understanding the inflationary environment.
- Segmental Revenue - Segmental Revenue has been triangulated or computed and presented for all the major players in the market. It refers to the courier, express, and parcel (CEP) market specific revenue earned by the company, over the base year of study, in the geography studied (country or region as per the scope of report). It is computed through the study and analysis of major parameters like financials, service portfolio, employee strength, fleet size, investments, number of countries present in, major economies of concern, etc. that have been reported by the company in its annual reports, webpage. For companies having scarce financial disclosures, paid databases like D&B Hoovers, Dow Jones Factiva have been resorted to and verified through industry/expert interactions.
- Transport and Storage Sector GDP - Value and growth of Transport and Storage Sector GDP has a direct relation to the freight and logistics market size. Hence, this variable has been studied and presented over the review period, in value terms (USD) and as share % of total GDP, in this industry trend. The data has been supported by concise and relevant commentary around the investments, developments, and current market scenario.
- Trends in E-Commerce Industry - Enhanced internet connectivity and boom in smartphone penetration, coupled with increasing disposable incomes, has led to a phenomenal growth in the e-commerce market globally. Online shoppers require fast and efficient delivery of their orders leading to an increase in the demand for logistics services especially e-commerce fulfilment services. Hence, the Gross Merchandise Value (GMV), historial and projected growth, breakup of major commodity groups in e-commerce industry for the studied geography (country or region as per scope of the report) have been analysed and presented in this industry trend.
- Trends in Manufacturing Industry - Manufacturing industry involves the transformation of raw materials into finished products, while logistics industry ensures the efficient flow of raw materials to the factory, and the transport of manufactured products to the distributors & consumers. Demand-Supply of both industries are highly cross-linked and critical for a seamless supply chain. Hence, the Gross Value Added (GVA), breakup of GVA into major manufacturing sectors, and growth of manufacturing industry over the review period have been analysed and presented, in this industry trend.
- Wholesale and Retail Trade (Offline) - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the wholesalers and retailers, through offline sales channel, on Courier, Express, and Parcel (CEP) services. The end user players considered are the establishments primarily engaged in wholesaling or retailing merchandise, generally without transformation, and rendering services incidental to the sale of merchandise. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies to and finished products from production houses to the distributors and finally to the end customer covering activites like material sourcing, transportation, order fulfillment, warehousing & storage, demand forecasting, inventory management etc.
| Keyword | Definition |
|---|---|
| Axle Load | The axle load refers to the total load (weight) bearing on the roadway through wheels connected to a given axle. Across the globe, there are systems in place to ensure axle load monitoring, wherein surpassing the defined limits set by the concerned regulatory authority can lead to penalty/fine. For transportation of goods via road this can be an important determinant of costs as knowledge about the axle load limits can be used to (i) load the vehicle optimally for maximizing profits (ii) avoid exceeding the same and hence the probable fines associated (iii) avoid wear and tear of the vehicle (iv) avoid damage to pavement resulting in noticeable public maintenance and repair costs (v) achieve better turnaround time. |
| Back Haul | Backhaul is the return movement of a transport vehicle from its original destination to its original point of departure, and can include full, partial, or empty truck loads (all or part of the way) depending on the visibility of the local freight ecosystem. In this regard, transportation of empty containers to the point of origin, known as deadheading is also a significant factor, considering the supply/container shortages across the geographies, resulting in cost escalation and under optimized profit potential attainment. Generally, the carriers offer discounts on the backhaul, to secure freight for the trip. |
| Bill of Lading (BOL) | A bill of lading is a legal contract document issued by a carrier to a shipper to acknowledge reception of their cargo, and is evidence for the contract of carriage between the two parties. Broadly it details the (i) type, quantity, and other specifications of the goods being carried (ii) destination, and terms & conditions of the shipment (iii) carrier and drivers with all the necessary information to process the shipment, which can be used for insurance and customs clearance purposes (iv) assurance that the consignment is damage-free and ready to be shipped to the consignee. In this regard, a house bill of lading (HBL) is a document issued by a freight forwarder or a non-vessel operating common carrier (NVOCC) to acknowledge receipt of items for shipment (to a shipper). If shipments from several shippers are involved a master bill of lading (MBL) might be involved which is a consolidated version of the same for all the shipments being taken care of by the carrier (to a common destination) and might be issued by the carrier to the freight forwarder or the shipper (depending on who books the transport). |
| Bunkering | Bunkering is the process of supplying fuel to power the propulsion system of a ship. It includes the logistics of loading and distributing the fuel among available shipboard tanks. In this regard, (i) Bunker fuel is technically any type of fuel oil used aboard ships. It gets its name from the containers on ships and in ports that it is stored in; in the days of steam they were coal bunkers but now they are bunker-fuel tanks, (ii) Bunker refers to the spaces (Tank) on board a vessel to store fuel, (iii) Bunker trader refers to a person dealing in trade of bunker (fuel), (iv) Bunker call is made when a cargo ship anchors or berths in a port to take on bunker oil or supplies, (v) Bunkering service is the supply of a requested quality and quantity of bunkers to a ship. Bunkering is signficant from point of view of freight rates applicable to the shipper as Bunker Contribution (BUC)/ Fuel Adjustment Factor (FAF)/ Bunker Adjustment Factor (BAF) are applied by shipping lines to offset the effect of fluctuations in the cost of bunkers. |
| Cabotage | Transport by a vehicle registered in a country, performed on the national territory of another country. Cabotage law may restrict domestic cargo traffic to be carried in its own nationally registered, and sometimes built and crewed vehicles, though regulations vary across industries/commodity groups/countries and sometimes specify maximum allowable percentage of cabotage that can be serviced by foreign registered fleet. |
| C-commerce | Collaborative commerce (also known as C-commerce), (i) describes electronically enabled business interactions among an enterprise’s internal personnel, business partners and customers throughout a trading community (industry, industry segment, supply chain or supply chain segment); (ii) is the optimization of supply and distribution channels to capitalize on the global economy by using new technology efficiently. Advantages of C-commerce, to detail few include (i) maximization of organization's efficiency and profitability (ii) technology integration with physical channels to allow companies to work together (iii) increased information exchange such as inventory and product specifications, using the web as an intermediary (iv) increased competitiveness by reaching a broader audience. Examples of C-commerce, also known as peer-to-peer commerce, include (i) companies that allow consumers to rent things from each other, or marketplaces, such as Meta (formerly Facebook) Marketplace, that allow the sale of used goods; (ii) DoorDash teamed up with many national brands, such as McDonald’s and Chipotle, to offer fast food delivery, building their business model on c-commerce. They have since expanded their delivery service from restaurants to retailers and even offer 'fleets' of drivers to businesses. |
| Courier | A business/company that delivers packages/parcels/shipments (upto 70 kgs) including quick door to door pickup and delivery service for goods or documents, domestically or internationally, on a commercial contract basis. Example, DHL Group, FedEx, United Parcel Service of America, Inc., USPS, International Distributions Services, J&T Express, SF Express among several others |
| Cross docking | Cross docking is a practice in logistics management that includes unloading incoming delivery vehicles and loading the materials directly into outbound delivery vehicles, omitting traditional warehouse logistical practices and saving time and money. It requires close synchronization of both inbound and outbound movements. It is highly significant in reduction of costs pertaining to warehousing & storage (and the associated Value Added Services). |
| Cross Trade | International transport between two different countries performed by a vehicle registered in a third country. A third country is a country other than the country of loading/embarkation and the country of unloading/disembarkation. Cross Trade law may restrict international cargo traffic to be carried by respective country's registered vehicles, and sometimes built and crewed vehicles, though regulations vary across industries/commodity groups/countries and sometimes specify maximum allowable percentage of cross trade that can be serviced by foreign registered fleet. |
| Customs Clearance | The process of declaring and clearing cargoes through customs. It includes the procedures involved in getting cargo released by Customs through designated formalities such as presenting import license/permit, payment of import duties and other required documentations by the nature of the cargo. In this regard, a customs broker is a person or company licensed by the respective department of the country to act on behalf of freight importers and exporters. |
| Dangerous Goods | Dangerous goods (or hazardous materials or HAZMAT) include flammable liquids/solids, gases (compressed, liquified, dissolved under pressure), corrosives, oxidising substances, explosive substances and articles, substances which on contact with water emit flammable gasses, organic peroxides, toxic substances, infectious substances, radioactive materials, miscellaneous dangerous goods and articles. |
| First mile Delivery | First mile delivery refers to the (i) first stage of the freight/shipment/cargo/courier transportation (ii) the transportation of goods from a merchant’s premises or warehouse to the next fulfillment centre/warehouse/hub from where the goods are forwarded (iii) shipping goods from local distribution centers to stores (For retailers) (iv) transportation of finished goods from a plant or a factory to a distribution center (For manufacturers), (v) pick up of goods from the end-customer’s home or store followed by movement to a warehouse or storage location (movers and packers), (vi) process where goods are picked up from a retailer and then transferred to third-party logistics providers or courier service providers to be delivered to the end-consumer (e-commerce). Once the package reaches the next warehouse or the courier’s hub, it is then sorted and transported further until it reaches the customer’s doorstep. Example, if one chooses UPS as a courier, first-mile delivery will be the product being delivered from manufacturer's/retailer's warehouse to the UPS’s warehouse/ fulfilment centre. |
| Last Mile Delivery | Last mile delivery refers to the very last step of the delivery process when a parcel is moved from a transportation hub (warehouse or a distribution center or fulfillment centre) to its final destination, which usually is a personal residence/retail store/ business, or parcel locker. It accounts for around half of the total cost involved in entire process of first mile, middle mile, and last mile delivery, though it can vary shipment to shipment, based on commodity, business model and similar factors. |
| Milkrun | A Milk Run is a delivery method used to transport mixed loads from various suppliers to one customer, using lean management principles applied to logistics. Instead of each supplier sending a truck every week to meet the needs of one customer, one truck (or vehicle) visits the suppliers to pick up the loads for that customer. This method of transport got its name from the dairy industry practice, where one tanker used to collect milk from several dairy farms for delivery to a milk processing company. A milk run can be a more efficient way to handle logistics but require proper planning. If the route involves products from different companies, there is need for an agreement about cost-sharing and other aspects of the cooperative delivery arrangement. Once the group settles these issues, this delivery method can save time and money for everyone by pooling operation costs and resources. |
| Multi country consolidation | Multi-Country Consolidation (MCC) is a cost-effective solution that consolidates one's cargo from different countries of origin to build Full Container Loads (FCL). MCC is most suitable for companies that import light volumes of goods from multiple countries but want to take advantage of the more economic FCL freight rates. Apart from costing some of the other advantages include (i) flexibility to choose suppliers from a wider range of origin countries without worrying about the logistics to final destination from each origin, (ii) ability to pick the most suitable suppliers from many different countries for one's business operations. The increase in one's sourcing options by MCC provides the kind of flexibility needed in competitive global markets. |
| Q-commerce | Q-commerce, also referred to as quick commerce, is a type of e-commerce where emphasis is on quick deliveries, typically in less than an hour. The companies providing Q-Commerce services might have vertically intergrated model or might be using third party delivery platforms (outsourced logistics). It has advantages like (i) competitve USP, (ii) potential to earn greater profit margins, (iii) better customer experience, (iv) guaranteed availability of products, (v) traceability, and (vi) scaleability. |
| ReverseLogistics | Reverse logistics is a type of supply chain management that moves goods from customers back to the sellers or manufacturers and may involve ciruclar economy principles (3Rs) viz. recycling, reuse (repurposing, reselling), reducing or repairing. In this regard, reverse commerce (or Recommerce) is the selling of previously owned items through physical or online marketplaces/distribution channels to buyers who reuse, recycle or resell them. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is considered to be a part of the pricing, and the average selling price (ASP) is varying throughout the forecast period for each country
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


