
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.23 Billion |
| Market Size (2026) | USD 1.31 Billion |
| Market Size (2031) | USD 1.76 Billion |
| Growth Rate (2026 - 2031) | 6.10 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Food Colorants Market Analysis by Mordor Intelligence
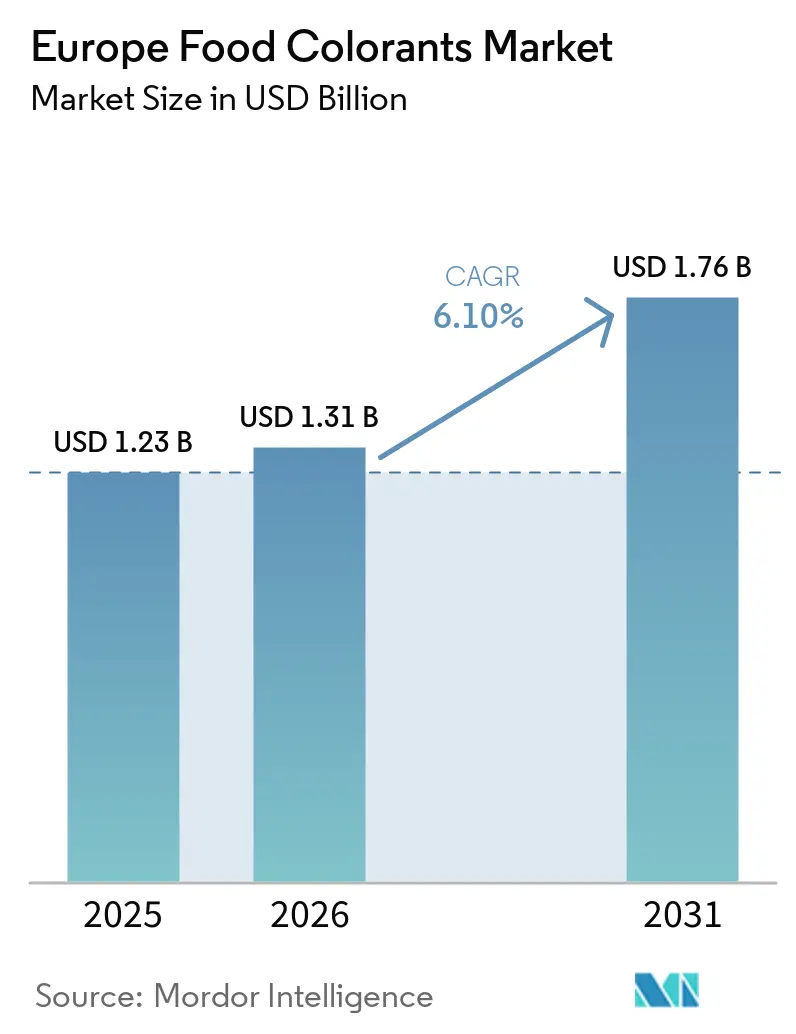
The Europe food colorants market size was valued at USD 1.23 billion in 2025 and estimated to grow from USD 1.31 billion in 2026 to reach USD 1.76 billion by 2031, at a CAGR of 6.10% during the forecast period (2026-2031). The European food colorants market is shifting toward plant-derived and fermentation-derived pigments as food companies respond to ingredient transparency and regulatory scrutiny. Regulation (EC) No 1333/2008 requires authorized color additives to remain subject to safety review, which keeps reformulation on the agenda for manufacturers across the region. The removal of titanium dioxide (E171) from use in EU food has made white color replacement a direct formulation need, while warning requirements for certain synthetic colors continue to support the use of natural alternatives. Suppliers are responding with more application support, stable blue pigments, and systems that work in beverages, dairy products, and confectionery. The European food colorants market, therefore, has opportunities in clean-label reformulation, but cost, stability, and raw material availability remain material constraints on adoption.
Key Report Takeaways
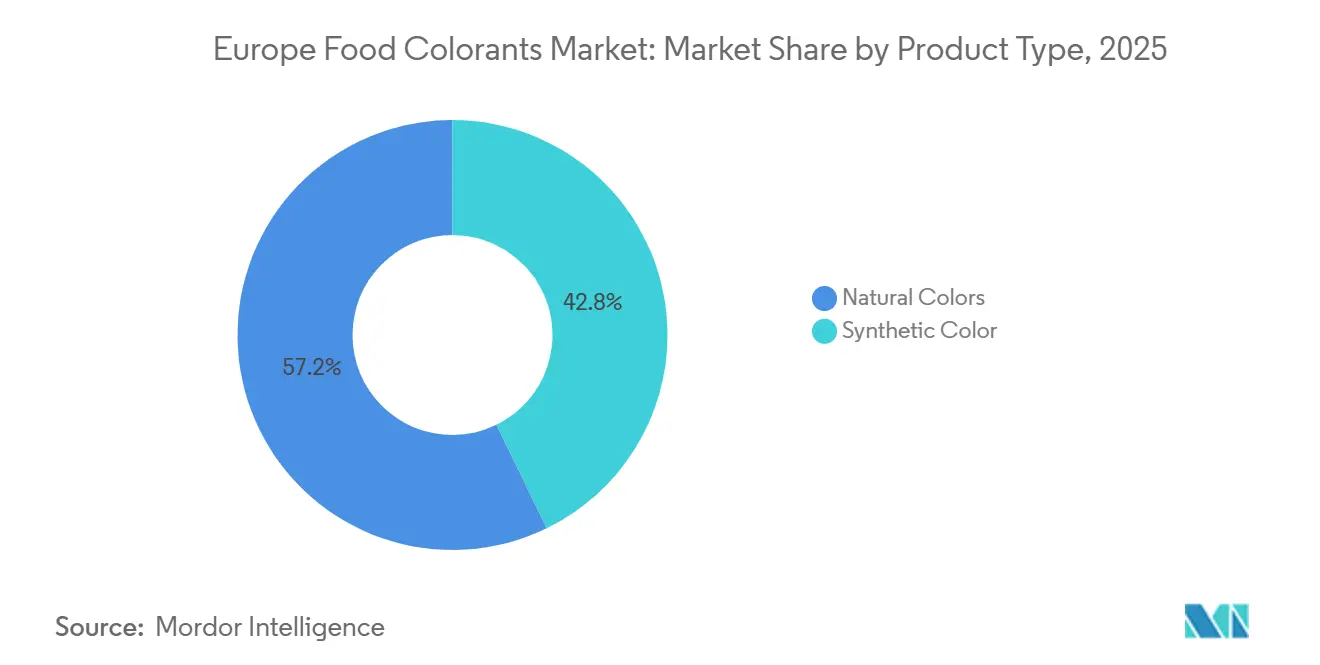
- By product type, natural colors led the Europe food colorants market with a 57.23% share in 2025, while natural colors are anticipated to register the fastest CAGR of 6.67% during 2026-2031.
- By color, red shades accounted for the largest share of the Europe food colorants market, at 28.64% in 2025, while blue shades are projected to grow at the fastest CAGR of 7.27% during 2026-2031.
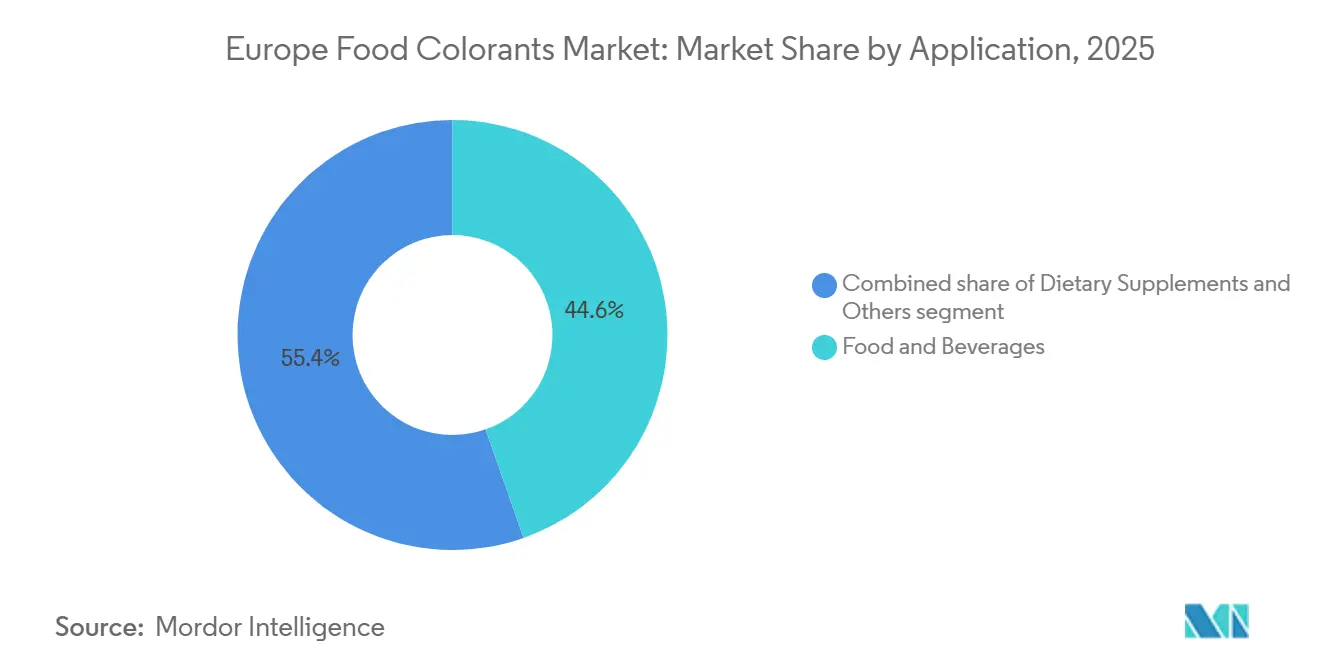
- By application, food and beverages led the Europe food colorants market with a share of 44.63% in 2025, while dietary supplements are anticipated to register the fastest CAGR of 7.49% during 2026-2031.
- By geography, Germany accounted for the largest share of the Europe food colorants market, at 21.75% in 2025, while Poland is projected to grow at the fastest CAGR of 6.95% during 2026-2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Food Colorants Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Clean-Label Reformulation and Consumer Rejection of Artificial Colors | +1.8% | Global, with strongest early adoption in the United Kingdom, Germany, France, and the Netherlands | Short term (≤ 2 years) |
| EU Restrictions, Warning Labels, and Synthetic Color Reassessment | +1.4% | EU-wide, with spillover to the United Kingdom through retained warning-label legislation | Short term (≤ 2 years) |
| Growth of Functional, Organic, and Plant-Based Beverages | +0.9% | Core demand in Germany, Sweden, and the Netherlands, with spillover to Poland | Medium term (2-4 years) |
| Expansion of Plant-Based Meat and Dairy Alternatives | +0.7% | Germany, the United Kingdom, and the Netherlands, with a secondary wave in Poland and Belgium | Medium term (2-4 years) |
| Upcycling of Fruit and Vegetable Processing By-products into Pigments | +0.4% | Spain, Italy, and the Netherlands, with broader EU application | Long term (≥ 4 years) |
| Fermentation-Derived and Biotechnology-Enabled Color Production | +0.5% | Denmark, Germany, and France, with expansion across the EU | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Clean-Label Reformulation and Consumer Rejection of Artificial Colors
Clean-label reformulation has become an operating requirement for many European food manufacturers rather than a limited brand exercise. Retailers, including Tesco and Carrefour, have reduced the use of artificial colors in private-label products, narrowing the addressable space for synthetic alternatives. Regulation (EC) No 1333/2008 sets the legal structure for authorized food additives, and the EU framework retains a warning requirement for the colors commonly associated with the Southampton study[1]. This environment places a greater burden on food producers to select colors that meet label expectations without compromising the product's recognizable appearance. The European food colorants market benefits because natural-color suppliers can support reformulation, stability testing, and color matching rather than only sell a raw ingredient. The U.S. Food and Drug Administration revoked authorization for FD&C Red No. 3 in January 2025, adding another reason for multinational brand owners to review color strategies across regions.
EU Restrictions, Warning Labels, and Synthetic Color Reassessment
The EU's food color regulatory framework is structurally biased toward progressive restriction of synthetic options, and this bias is now generating commercially significant reformulation cycles. EFSA's January 2025 approval of Galdieria sulphuraria-derived phycocyanin, a fermented, stable natural blue, triggered reformulation activity across 22 European dairy brands within six months of authorization, as manufacturers replaced spirulina formulations carrying seaweed off-notes in yogurt and ice cream. The December 2025 EFSA positive opinion on Jagua blue marks the first viable primary natural blue for high-temperature and low-pH applications across Codex-recognized food categories, with EU market authorization expected between June and August 2026. A regulatory blind spot worth noting is the pace of the Commission's follow-through on positive EFSA opinions: delays between scientific opinions and formal authorization can run six to twelve months, leaving natural color suppliers unable to commercialize approved innovations and constraining cash-flow visibility for capital-intensive biotech entrants. Compliance factors, including the EU Novel Food Regulation and the Organic Regulation (RCE 889/2008), further shape which fermentation-derived and algae-based colors scale commercially first in the European market.
Growth of Functional, Organic, and Plant-Based Beverages
Functional, organic, and plant-based beverages need colors that remain stable through production and deliver a clear appearance on the shelf. Germany has a large demand base for plant-based drinks, where private-label products account for a significant share of sales and receive close attention to ingredient declarations, according to the Good Food Institute Europe. Such products often require carotenoid-, curcumin-, or spirulina-based systems that can withstand processing conditions without producing undesirable flavors. GNT Group states that its Blue for Beverages technology uses spirulina to offer blue shades for sports drinks and carbonated beverages while supporting clean-label positioning. Suppliers that combine pigment supply with application support can become more embedded in customer formulations, as beverage trials are difficult to replicate across multiple production settings. The European food colorants market gains from this pattern as more beverages require color systems designed for heat, acidity, and light exposure. The additional work required to stabilize a pigment can increase formulation cost, but it can also make established supplier relationships more durable.
Expansion of Plant-Based Meat and Dairy Alternatives
Plant-based meat and dairy alternatives depend on visual cues because consumers judge resemblance to familiar food products before tasting them. A 2025 Frontiers in Nutrition comparative study confirmed that all plant-based meat products analyzed contained natural color additives, compared to only 12.5% of conventional burger-type products, positioning color engineering as a core competency in plant-based formulation[2]. This makes color selection part of product development, particularly where a manufacturer needs a meat-like red or brown appearance after cooking. Carotenoid systems can be used in many heat-treated products, while anthocyanins and other natural colors may require careful control of pH and processing conditions. Once a color system has been validated for a specific matrix, changing suppliers or ingredients may require additional trials and a label review. The European food colorants market is supported by this technical dependency, even when plant-based brands face price pressure in retail. Suppliers that can help food companies meet both color and label requirements are more likely to retain business than suppliers offering a standard pigment without formulation support.
Restraints Impact Analysis of Europe Food Colorants Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Higher Cost-in-Use of Natural Pigments | -1.2% | Global, with the strongest effect in Central and Eastern Europe where synthetic prices set cost benchmarks | Short term (≤ 2 years) |
| Heat, Light, pH, and Matrix Stability Constraints | -0.8% | EU-wide, with the greatest effect in beverage and dairy products with intensive thermal processing | Medium term (2-4 years) |
| Raw-Material Supply Volatility and Import Dependence | -0.7% | Countries with high extra-EU import reliance, including Germany, France, and the Netherlands | Medium term (2-4 years) |
| Limited Availability of Stable Natural Blue and White Alternatives | -0.5% | EU-wide, with the blue gap most acute in Northern and Western Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Higher Cost-in-Use of Natural Pigments
Natural pigments can cost two to five times more than synthetic alternatives when measured on a cost-per-unit-color-strength basis. Many plant-source pigments occur at very low concentrations in biomass, so suppliers need more raw material and carefully controlled extraction to reach EU specifications. Regulation (EU) No 231/2012 sets purity specifications for food additives, adding quality-control needs for producers and users. These cost pressures are more difficult for small and midsized food companies, especially where retailers are highly sensitive to final product prices. Fermentation may lower the cost burden over time by reducing reliance on agricultural extraction and improving production consistency. The European Research Council has described work at the Technical University of Denmark showing that yeast-fermentation production of betalain-type colors could reduce land use and carbon dioxide impact by 90% compared with extraction from red beets. Until such approaches reach a broad commercial scale, the higher cost of natural ingredients remains a restraint on the European food colorants market.
Heat, Light, pH, and Matrix Stability Constraints
Natural pigments can lose strength or change shade during processing, which limits their use in acidic drinks, fruit preparations, and UHT dairy products. Anthocyanins used for red and purple shades are sensitive to pH, heat, and light, so a formulation may look different after storage or thermal treatment. Spirulina-derived blue has historically had difficulty in products with low pH, including some energy drinks and sports beverages. Givaudan reported that Everzure Galdieria, made with Galdieria sulphuraria microalgae, received FDA approval in May 2025 and is intended to provide a natural blue option for acidic foods and beverages. Encapsulation and microemulsion approaches can protect sensitive pigments, but they increase formulation complexity and cost. This technical barrier favors suppliers with application laboratories and can slow the substitution of synthetic colors in the European food colorants market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Food Colorants Market Segment Analysis
By Product Type:
Natural Colors Define the Conversion DecadeNatural colors held 57.23% of European food-colorant sales in 2025, making them the leading product type. Their position reflects long-running reformulation by food companies that need to respond to consumer scrutiny, retailer policies, and EU labeling requirements. The category includes anthocyanins, carotenoids, curcumin, carmine, spirulina, and a developing range of fermentation-derived pigments. Carotenoids, such as beta-carotene, annatto, and paprika extract, are important in baked products, processed cheese, and heat-treated drinks because of their useful thermal performance. Carmine remains a strong natural red choice, although vegan and halal requirements have increased interest in anthocyanin and fermentation-based alternatives. Natural colors also allow producers to meet demand for ingredients perceived as more recognizable, though the final choice still depends on application conditions and cost. EFSA’s food-color work remains central to this transition because safety assessment and authorization determine which new pigments can be used by food manufacturers.
Natural colors are also the fastest-growing product type, with the European food colorants market size for the segment projected to grow at a 6.67% CAGR during 2026-2031. Growth is expected as product developers in Germany, the United Kingdom, and France continue to replace synthetic colors in branded grocery products. Synthetic colors still serve applications where natural alternatives cannot yet deliver the required hue, intensity, stability, or cost position. Azo dyes, including Tartrazine, continue to appear in some foodservice and export-oriented production, even as many branded food companies reduce their use. Blue remains a significant conversion area because Brilliant Blue FCF can be difficult to replace in acidic and carbonated products. GNT Group states that its Blue for Beverages technology uses spirulina to create clean-label blue shades for sports drinks and carbonated beverages. The pace of conversion will depend on whether newer natural pigments can meet technical needs without making the finished product materially more expensive.
By Color:
Blue Gains Ground as the Supply Gap NarrowsRed shades accounted for 28.64% of the European food colorants market share in 2025, the highest proportion among color categories. Their demand is driven by confectionery, bakery decoration, beverages, and meat alternatives, in which red is often central to the expected product appearance. The red category offers formulators several natural options, including black carrot and elderberry anthocyanins, red beet betanins, and carmine. Those alternatives differ in stability, label position, source, and suitability for vegan or halal products. Green, yellow, and orange shades maintain demand in dairy products, snacks, and cereals. Curcumin-based yellow can also benefit from its association with familiar plant ingredients, although its use still depends on the processing environment. A broad range of red sources supports customer choice, but it also requires suppliers to guide manufacturers toward the right system for the intended product.
Blue shades are forecast to be the fastest-growing color category, at a 7.27% CAGR between 2026 and 2031. The category is gaining attention because blue has fewer natural alternatives that remain stable during heat treatment or in acidic beverages. Oterra reported a positive EFSA opinion for Jagua blue in December 2025, a development that could expand natural-blue use after the authorization process is completed. Purple and pink also represent growth areas in confectionery and functional beverages, where product appearance is part of differentiation. Oterra introduced FruitMax Purple 105 in 2025, combining black-carrot concentrate and hibiscus extract for beverage and confectionery use in EU and Codex markets. Brown shades are another area of development for premium beverages that need a clean-label alternative to caramel colors. The Europe food colorants market will continue to depend on technical improvements in blues and other difficult shades because these gaps determine where synthetic colors remain hard to replace.
By Application:
Dietary Supplements Drive PremiumizationFood and beverages represented 44.63% of the Europe food colorants market size in 2025, making this the largest application segment. The segment includes bakery and confectionery, dairy, snacks and cereals, and nonalcoholic beverages. Bakery and confectionery use colors for frosting, gummies, coatings, and decorations that need consistent strength from batch to batch. Beverage labels are highly visible to consumers, so the warning statement associated with certain synthetic colors can directly influence reformulation decisions. Dairy is also an important area because food manufacturers need alternatives to titanium dioxide for white and opaque products. Oterra and Seprify announced a 2025 commercial partnership to bring a cellulose-based white colorant to food and beverage applications as a replacement for titanium dioxide. These applications give the European food colorants market a broad base of demand, but each food matrix requires separate stability and sensory evaluations.
Dietary supplements are projected to be the fastest-growing application, at a 7.49% CAGR during 2026-2031. Gummies, softgels, effervescent powders, and tablets use color to distinguish formats, flavors, and nutrient positioning. These products may place greater value on visual differentiation than many mainstream food categories, reducing sensitivity to ingredient costs. Natural colors are useful where a supplement brand wants to align a plant-based or wellness-oriented message with its visual design. Product developers still need to validate performance because a pigment can behave differently in a dry tablet, a gummy, or a liquid supplement. Other applications, including pet food and cosmetic-adjacent products, provide an additional path for suppliers with color portfolios that extend beyond food and beverages. The Europe food colorants market can benefit from this wider use, provided suppliers maintain the technical and regulatory support needed for each application.

Geography Analysis
Western Europe Food Colorants Market
Germany held 21.75% of the European food colorants market share in 2025, making it the region’s largest market. Its position is linked to a large food and beverage manufacturing base and early adoption of natural-color systems by domestic producers. Health-focused consumer demand and attention to ingredient transparency have supported this adoption across packaged food, beverages, dairy products, and confectionery. German suppliers such as Symrise and Döhler combine natural pigments with flavor and nutrition capabilities, which can make their offerings more difficult for customers to replace. This integrated approach matters when a food producer needs to adjust taste, appearance, and label declarations simultaneously. Germany’s role also reflects the weight of its food manufacturing sector in European procurement and product-development decisions. The United Kingdom remains relevant because its warning-label rules continue to mirror the EU approach for the Southampton Six colors, despite its departure from the EU single market. Major retailers in the United Kingdom have also maintained private-label requirements that favor natural colors without E-number declarations. France adds demand through premium food and confectionery, where origin and natural positioning can support higher-value color formulations. Givaudan’s work with Fermentalg on Everzure Galdieria illustrates France’s role as both a consumer market and a location for natural-color technology development.
Northern and Central Europe Food Colorants Market
Poland is projected to be the fastest-growing geography, with a 6.95% CAGR during 2026-2031. Its food processing sector is moving from synthetic formulations toward natural colors as exporters serve Western European retailers with more stringent clean-label requirements. This change gives Polish manufacturers a reason to align ingredients and labeling with the standards used in German and United Kingdom grocery channels. The country’s growth is therefore tied to export demand as well as changes in domestic food production. Poland also has room for natural-color adoption in applications where cost has previously favored synthetic dyes. Belgium contributes demand through its confectionery manufacturing base, particularly for stable red and brown shades. Sweden’s organic-food culture supports the use of organic-certified natural-color formulations. Scotland-based ScotBio produces spirulina-based blue colorants, while Copenhagen-based Chromologics is developing a fermentation platform for red pigments, adding technical activity across Northern Europe. These developments show that the fastest-growing country market is part of a wider regional transition, rather than an isolated change in one national market.
Broader European Markets
Italy and Spain occupy important positions in the Europe food colorants market because of their food-processing strengths and their demand for category-specific formulations. Italian use centers on confectionery, pasta, and cheese, where carotenoid and annatto systems are commonly relevant. Sensient has production facilities in Italy within its international natural-color network, giving customers regional access to supply and application capabilities. Spain and the Netherlands also support the regional supply base through food processing, agricultural inputs, and access to beverage and bakery customers. GNT Group’s EXBERRY facility in Mierlo, the Netherlands, serves the plant-based color category, while the country’s role in agricultural processing creates demand for ingredients used in processed-food exports. The Netherlands also has a distribution role that can connect ingredient suppliers with European food manufacturers. Spain’s agricultural and food-processing base gives it relevance for fruit and vegetable-derived pigments. Across the rest of Europe, demand will vary with local food categories, retailer standards, and the ability of producers to absorb higher natural-color costs. This geographic mix helps explain why the Europe food colorants market includes both mature Western markets and faster-developing Central and Eastern European markets.
Competitive Landscape
The European food colorants market is moderately concentrated, with Oterra, Givaudan, Sensient Technologies, Döhler, GNT Group, and other established specialists competing in natural-color supply. These companies benefit from botanical sourcing, regulatory experience, application laboratories, and the ability to offer multiple color solutions across food categories. Oterra has a strong position in botanical colors and has continued to develop the natural-blue pipeline. The report of a positive EFSA opinion for Jagua blue is important because stable natural blue remains a limiting area for many food applications. Givaudan Sense Colour combines formulation capability with fermentation partnerships to build its natural-blue offering. In May 2025, Givaudan announced FDA approval of Everzure Galdieria, a phycocyanin-rich blue made from Galdieria sulphuraria microalgae. Döhler competes through blends that can be combined with flavor systems, while GNT has positioned EXBERRY plant-based colors around solvent-free processing and retailer clean-label needs. The market structure rewards suppliers that can solve a product-development problem rather than simply provide a pigment.
Competitive attention is concentrated on stable blue, titanium dioxide replacements, and pigments made from food-processing by-products. Natural blue below pH 3 remains an open technical area because many beverage and confectionery products are acidic. White replacement is another gap because no option has reached broad price parity with titanium dioxide. Oterra’s 2025 partnership with Seprify targeted this need through a cellulose-based white colorant intended for food and beverage products. Upcycled colors are also gaining attention because they use fruit, vegetable, algae, and spice by-products that might otherwise have lower-value uses. The U.S. Department of Agriculture’s National Agricultural Library identifies research into agro-industrial by-products for next-generation natural food colorants, including approaches to extract usable pigments from waste streams. These areas may attract newer suppliers because they address supply resilience, cost, and label preferences at the same time. However, success still depends on regulatory approval, consistent quality, and the ability to scale production.
Chromologics represents a biotechnology-focused entrant in the Europe food colorants market. The company is developing red pigments through precision fermentation using Talaromyces atroroseus fungus, with the aim of reducing dependence on agricultural feedstocks. In November 2025, Chromologics raised EUR 7 million from Novo Holdings, EIFO, Döhler Ventures, Collateral Good Ventures, and Synergetic to support regulatory work and production scale-up for Natu.Red. Established companies retain advantages in customer qualification, supply continuity, and established application support[3]. New entrants can still gain relevance where they offer a color that is more stable, more acceptable on label, or less exposed to crop-related supply disruptions. Intellectual property is becoming more important as suppliers seek protection for formulations and production systems. The European Patent Office published a beetroot-composition patent grant in May 2025, reflecting continuing activity around differentiated natural-color technologies.
Europe Food Colorants Industry Leaders
-
Oterra A/S
-
Givaudan SA
-
Sensient Technologies Corporation
-
Döhler GmbH
-
Koninklijke DSM N.V.
- *Disclaimer: Major Players sorted in no particular order
Europe Food Colorants Market Companies Covered in this Report
- Oterra A/S
- Givaudan SA
- Sensient Technologies Corporation
- Döhler GmbH
- Koninklijke DSM N.V.
- BASF SE
- Symrise AG
- Archer Daniels Midland Company
- Kerry Group plc
- Kalsec Inc.
- DDW The Color House
- Riken Vitamin Co., Ltd.
- GNT Group B.V.
- Chromologics A/S
- ScotBio
- PROCONA, SEIMEX Group
- Plant-Ex Ingredients Ltd.
- Sancan
- Coralim
- Brenntag SE
Recent Industry Developments in Europe Food Colorants Market
- November 2025: Oterra A/S and Swiss innovator Seprify announced a strategic commercial partnership to market a plant-based white colorant as a replacement for titanium dioxide (TiO₂) in food and beverage applications. Seprify's patented cellulose-based technology delivers opacity and whitening effects that match TiO₂, while offering a clean-label and renewable profile. Customer trials were active at launch across Europe and globally.
- November 2025: Chromologics A/S raised EUR 7 million from Novo Holdings, EIFO, Döhler Ventures, Collateral Good Ventures, and Synergetic, taking total funding to approximately EUR 20 million. The round funds EFSA and FDA regulatory submissions for Natu.Red®, a red colorant produced by precision fermentation of Talaromyces atroroseus fungus, and production scale-up through a large-scale CMO partner.
- October 2025: Oterra launched FruitMax® Purple 105, a clean-label purple colorant for beverage and confectionery applications, approved for EU and Codex countries. The product is derived from black carrot concentrate and hibiscus extract, delivering superior stability over single-source anthocyanin solutions in low-pH applications, including carbonated beverages and gummies.
Europe Food Colorants Market Report Scope
Food colorants refer to natural or synthetic substances added to food, beverages, dietary supplements, and related products to impart, enhance, or restore color. The European Food Colorants Market is segmented by product type, color, application, and country. By product type, the market is divided into Natural Color and Synthetic Color. Natural Color is further segmented into Anthocyanins, Carotenoids, Curcumin, Carmine, Spirulina, and Other Types. Synthetic Color is further segmented into Azo Dyes (Tartrazine, Sunset Yellow, etc.), Brilliant Blue FCF, and Others. By color, the market includes Blue, Green, Red, Yellow, Purple, Orange, Pink, and Others. By application, the market is segmented into Food and Beverages, Dietary Supplements, and Other Applications. Food and Beverages is further segmented into Bakery and Confectionery, Dairy Products, Snacks and Cereals, Beverages, and Others. By country, the report covers Germany, the United Kingdom, Italy, France, Spain, the Netherlands, Poland, Belgium, Sweden, and the rest of Europe, with market size and forecasts provided for each country. The market sizing has been done in value terms in USD and volume in metric tons for all the abovementioned segments.
Segmentation Overview
By Product Type
| Natural Color | Anthocyanins |
| Carotenoids | |
| Curcumin | |
| Carmine | |
| Spirulina | |
| Other Types | |
| Synthetic Color | Azo Dyes (Tartrazine, Sunset Yellow, etc.) |
| Brilliant Blue FCF | |
| Others |
By Color
| Blue |
| Green |
| Red |
| Yellow |
| Purple |
| Orange |
| Pink |
| Others |
By Application
| Food and Beverages | Bakery and Confectionery |
| Dairy Products | |
| Snacks and Cereals | |
| Beverages | |
| Others | |
| Dietary Supplements | |
| Other Applications |
By Country
| Germany |
| United Kingdom |
| Italy |
| France |
| Spain |
| Netherlands |
| Poland |
| Belgium |
| Sweden |
| Rest of Europe |
| By Product Type | Natural Color | Anthocyanins |
| Carotenoids | ||
| Curcumin | ||
| Carmine | ||
| Spirulina | ||
| Other Types | ||
| Synthetic Color | Azo Dyes (Tartrazine, Sunset Yellow, etc.) | |
| Brilliant Blue FCF | ||
| Others | ||
| By Color | Blue | |
| Green | ||
| Red | ||
| Yellow | ||
| Purple | ||
| Orange | ||
| Pink | ||
| Others | ||
| By Application | Food and Beverages | Bakery and Confectionery |
| Dairy Products | ||
| Snacks and Cereals | ||
| Beverages | ||
| Others | ||
| Dietary Supplements | ||
| Other Applications | ||
| By Country | Germany | |
| United Kingdom | ||
| Italy | ||
| France | ||
| Spain | ||
| Netherlands | ||
| Poland | ||
| Belgium | ||
| Sweden | ||
| Rest of Europe | ||
Key Questions Answered in the Report
What is the size of the Europe food colorants market?
The Europe food colorants market is valued at USD 1.31 billion in 2026 and is projected to reach USD 1.76 billion by 2031, at a 6.1% CAGR.
Which product type leads food colorants in Europe?
Natural colors lead, with 57.23% share in 2025, and they are also forecast to grow at a 6.67% CAGR through 2031.
Which color category is growing fastest in Europe?
Blue shades are projected to record the fastest growth, with a 7.27% CAGR during 2026-2031.
Which country has the largest share of food colorant demand in Europe?
Germany leads the regional market with 21.75% share in 2025, supported by its food and beverage manufacturing base.