
Assistive Robotics Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 12.65 Billion |
| Market Size (2031) | USD 31.29 Billion |
| Growth Rate (2026 - 2031) | 19.86 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Assistive Robotics Market Analysis by Mordor Intelligence
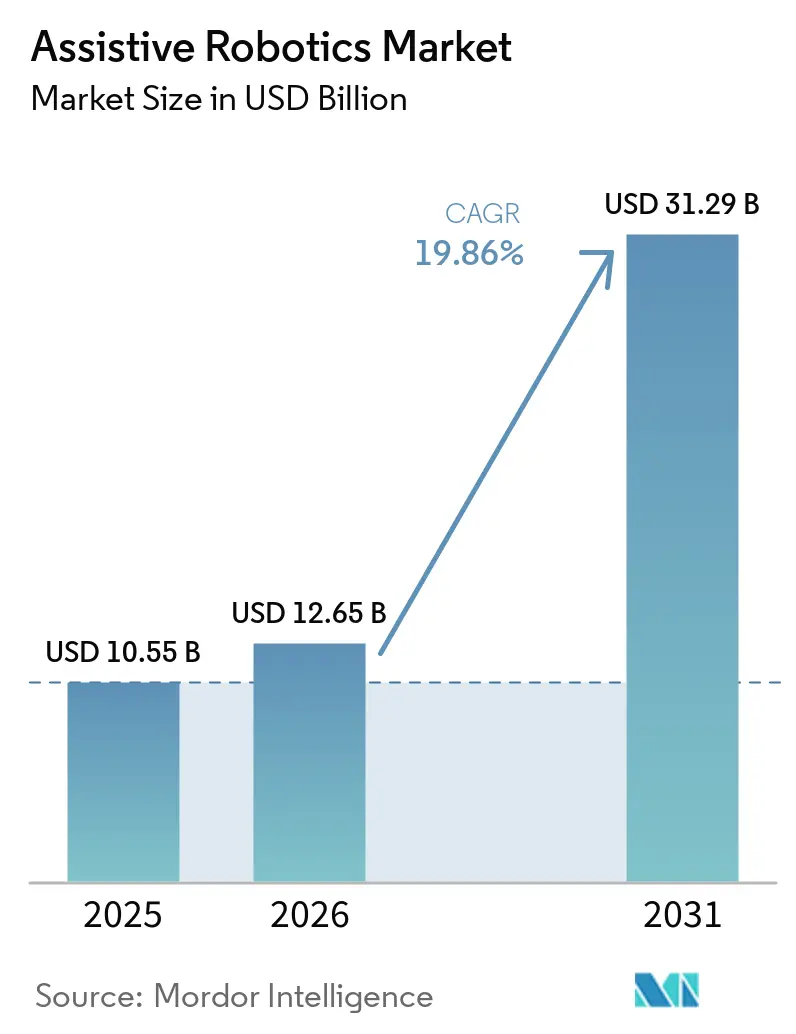
The assistive robotics market size is expected to grow from USD 10.55 billion in 2025 to USD 12.65 billion in 2026 and is forecast to reach USD 31.29 billion by 2031 at 19.86% CAGR over 2026-2031. This rapid expansion coincides with labor shortages in eldercare, growing surgical volumes, and regulators' increasing acceptance of autonomous medical devices, all of which are transforming robots from experimental curiosities into operational necessities. Hospitals are prioritizing multi-modal platforms that combine physical support with cognitive engagement, while home-based rehabilitation is emerging as a mainstream care model. Governments in Japan, South Korea, and China are subsidizing healthcare robots to address demographic pressures, while payers in the United States and Germany are adding reimbursement codes that facilitate capital purchases. Competitive dynamics are driving a shift toward open, AI-enabled systems, and supply-chain volatility in precision sensors is prompting manufacturers to adopt dual-sourcing strategies.
Key Report Takeaways
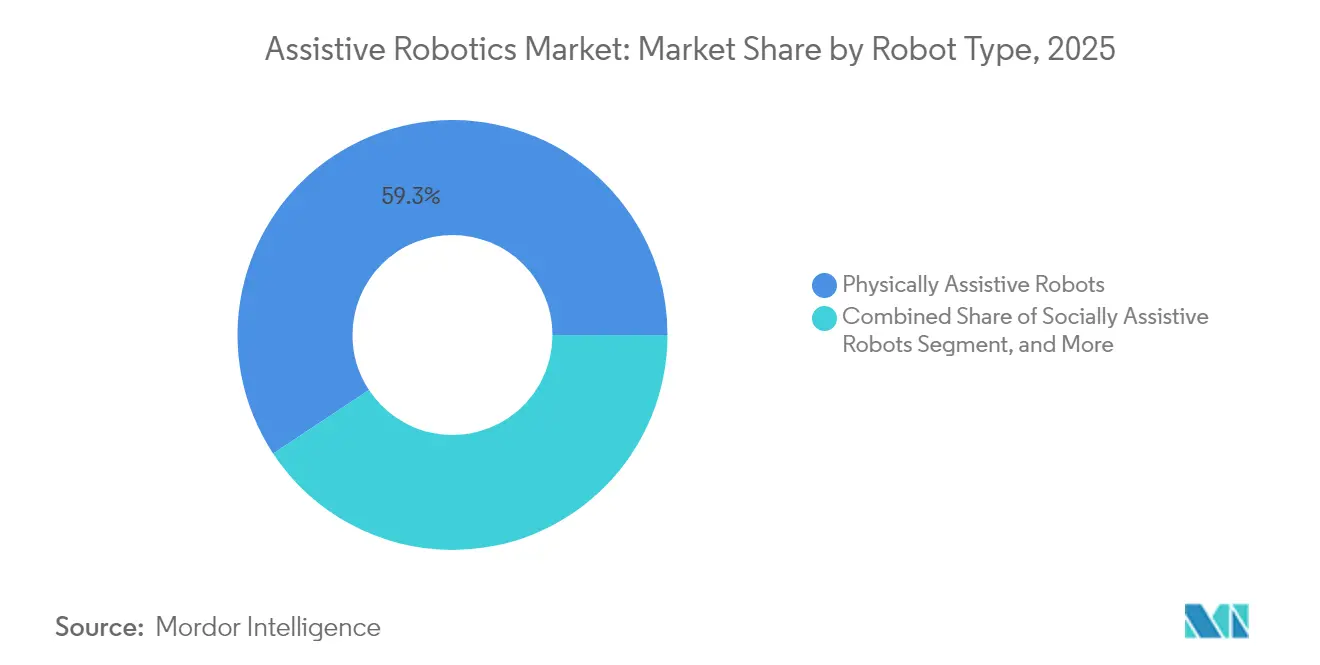
- By robot type, physically assistive platforms led with 59.28% revenue share in 2025; mixed assistive robots are forecast to expand at a 21.65% CAGR through 2031.
- By mobility, mobile systems captured 57.05% of the assistive robotics market share in 2025, while the segment is projected to grow at a 21.05% CAGR through 2031.
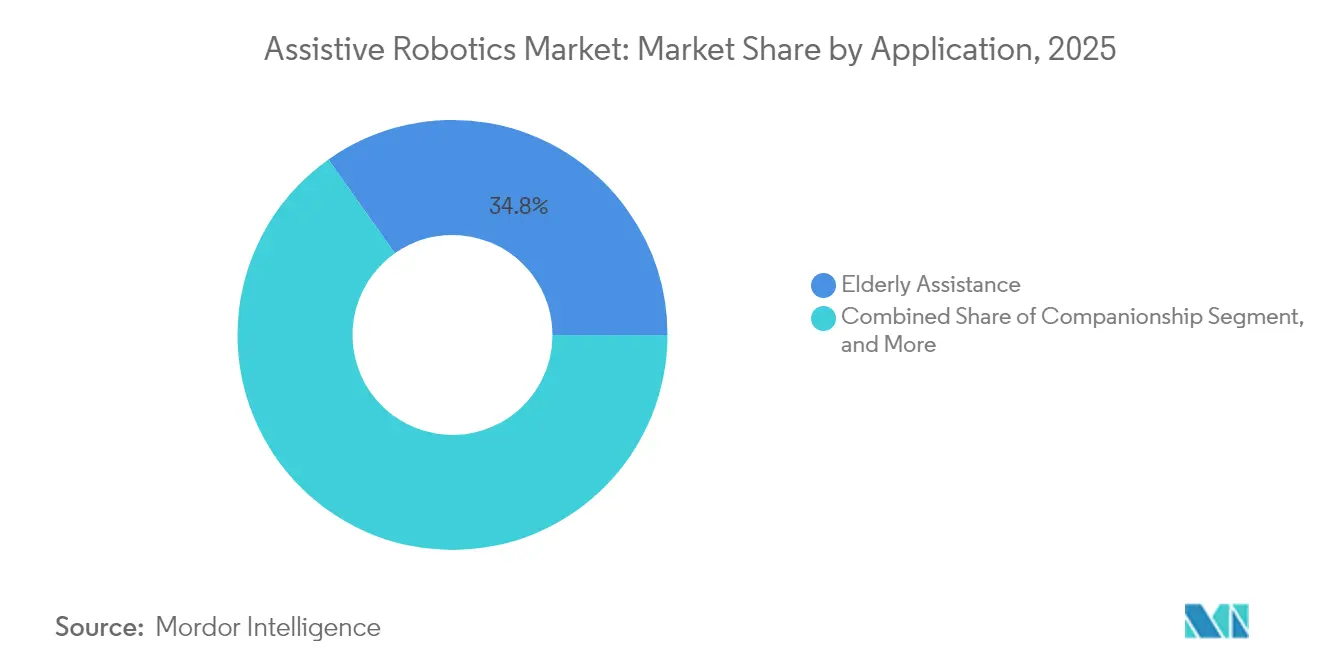
- By application, elderly assistance led with 34.79% revenue share in 2025; surgery assistance accounted for a 21.32% CAGR forecast between 2026 and 2031, outpacing all other use cases.
- By end user, hospitals led with 54.43% revenue share in 2025; homecare settings are projected to advance at a 21.95% CAGR through 2031.
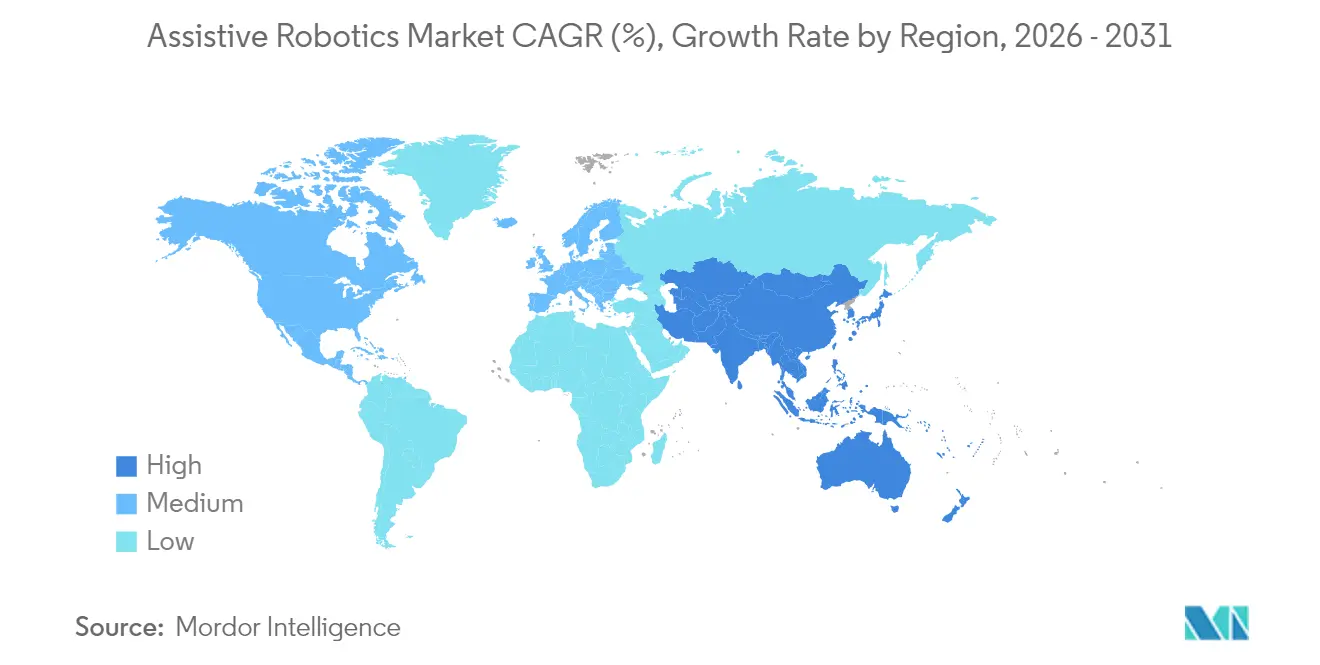
- By geography, North America led with a 39.62% revenue share in 2025; the Asia Pacific is projected to expand at a 22.35% CAGR from 2026 to 2031, surpassing North America’s growth pace.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Assistive Robotics Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising geriatric population accelerating care demand | +5.2% | Global, most acute in Japan, South Korea, Italy, Germany | Long term (≥ 4 years) |
| Growing adoption of robot-assisted surgery procedures | +4.8% | North America and Europe, expanding into APAC urban centers | Medium term (2-4 years) |
| Integration of AI with assistive robots enhancing autonomy | +3.9% | Global, led by United States, China, Israel | Medium term (2-4 years) |
| Surge in home-based rehabilitation and tele-rehabilitation models | +3.1% | North America, Western Europe, Australia | Short term (≤ 2 years) |
| Emergence of soft robotics improving safety and wearability | +2.4% | Global, with early traction in Japan and United States | Long term (≥ 4 years) |
| Government reimbursement for exoskeletons in select markets | +1.8% | Japan, Germany, United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Geriatric Population Accelerating Care Demand
Global aging is widening the caregiver gap, prompting providers to turn to robotic solutions that help alleviate workforce shortages.[1]United Nations, “World Population Ageing Report 2024,” UN.ORG Japan mandated the installation of robotic lifts in all new nursing facilities starting in 2025, triggering significant orders for transfer-assist platforms. South Korea has allocated USD 120 million to deploy companion robots in 5,000 senior centers by 2027, framing robots as a solution to social isolation. Italy reported that 23% of citizens over 65 live alone, which is accelerating the adoption of social-cognitive robots for medication reminders and emergency alerts. Robots costing USD 30,000 can offset the cost of 0.5 full-time caregivers over five years in high-wage countries, resulting in a sub-three-year payback and validating their economic viability.
Growing Adoption of Robot-Assisted Surgery Procedures
Hospitals in the United States performed more than 1.5 million robotic surgeries in 2024, a 22% increase year-over-year, driven by new reimbursement codes that now cover partial nephrectomy and lobectomy procedures.[2]American College of Surgeons, “Robotic Surgery Statistics 2024,” FACS.ORG Stryker’s Mako orthopedic platform reached 1,500 installed units by late 2024, with revision surgeries decreasing by 30% compared to manual techniques. Europe’s Medical Device Regulation streamlined software update approvals, enabling AI planning tools that reduce operative time by 18 minutes per procedure. The resulting productivity boosts support hospital capital budgets and encourage community facilities to join the adoption curve.
Integration of AI with Assistive Robots Enhancing Autonomy
Kinova’s Gen3 arm utilizes vision and reinforcement learning to adjust grasping according to object weight and shape, eliminating the need for manual reprogramming. The United States Food and Drug Administration cleared three AI-enabled rehabilitation robots in 2024, reflecting regulatory comfort with autonomy in patient-facing systems.[3]U.S. Food and Drug Administration, “510(k) Clearances - Rehabilitation Robotics 2024,” FDA.GOV China published AI safety standards for service robots that require fail-safe protocols, signaling seriousness about export-ready compliance. Large language models integrated into social robots now support 15-minute cognitive assessments, enriching clinical decision-making.
Surge in Home-Based Rehabilitation and Tele-Rehabilitation Models
Hocoma’s Armeo Power gained FDA clearance for home use in 2024, letting stroke survivors complete therapy under remote supervision. Medicare began reimbursing clinicians for up to 40 minutes of remote therapeutic monitoring per month, catalyzing device orders among home-health agencies. ReWalk Robotics shifted 35% of exoskeleton sales to households as coverage expanded and a lighter battery module improved residential usability. Tele-rehabilitation platforms integrating robotics generated USD 1.2 billion in revenue in 2024, with rural regions capturing the most upside.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capital and maintenance costs for healthcare providers | -3.6% | Global, most acute in emerging markets and rural systems | Short term (≤ 2 years) |
| Limited clinical evidence for long-term outcomes | -2.1% | Global, particularly Europe and North America | Medium term (2-4 years) |
| Fragmented regulatory frameworks slowing approvals | -1.8% | Europe, Latin America, Southeast Asia | Medium term (2-4 years) |
| Supply chain volatility in critical sensors and actuators | -1.4% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High Capital and Maintenance Costs for Healthcare Providers
Robotic surgery systems cost USD 1.5-3.0 million upfront and require annual service contracts averaging USD 150,000, which restricts their adoption among community hospitals with low case volumes. Exoskeletons priced at USD 80,000-120,000 face similar hurdles outside large academic centers. Exclusive maintenance agreements exacerbate the total cost of ownership, and pay-per-procedure leases often shift risk back onto providers. These financial barriers remain acute in emerging markets where capital budgets are limited.
Limited Clinical Evidence for Long-Term Outcomes
A 2024 systematic review found only 12% of exoskeleton studies extended beyond six months, leaving payers hesitant to fund multi-year deployments. Companion robots face an even thinner evidence base, leading NICE to withhold routine coverage in 2024 due to insufficient data on cost-effectiveness. Manufacturers are launching real-world registries, but actionable results are not expected to arrive before 2027, creating a near-term drag on market acceleration.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Robot Type: Multifunctional Platforms Win Budget Approval
Mixed platforms are projected to expand at a 21.65% CAGR, outpacing physically assistive incumbents as healthcare systems seek single investments that tackle mobility and social-cognitive needs. Physically assistive solutions held 59.28% of 2025 revenue, but growth is moderating as saturation builds in core lifting and transfer applications. Socially assistive robots remain the smallest slice, yet increased demand for cognitive engagement in memory care is driving orders for conversational units. Panasonic’s Hospi now bundles a greeting interface that reduced nurse call-button use by 18% in trials.
Providers appreciate the modularity of mixed robots, which can add or remove arms, screens, or conversational software to fit patient requirements, extending lifecycles and smoothing return on investment. Regulators are clarifying the paths for combination devices, simplifying approvals that previously required dual submissions. This framework is expected to shorten commercialization cycles and fuel broader adoption of hybrid designs.


By Mobility: Untethered Designs Capture Homecare Momentum
Mobile robots commanded 57.05% of the revenue in 2025 and are projected to track a 21.05% CAGR, as simultaneous localization and mapping algorithms enable autonomous navigation in cluttered homes. Stationary robots remain critical in operating rooms that need sub-millimeter accuracy, yet their fixed nature limits cross-departmental utility. Hospitals deploy mobile units for logistics, with autonomous carts now handling 30% of internal deliveries at many U.S. medical centers.
The Asia Pacific leads the mobile shift, where urban homes’ tight footprints demand adaptable systems, whereas North America retains a larger stationary base, thanks to spacious residences that can accommodate fixed rehabilitation setups. Supply constraints in precision sensors could hinder mobile deployments, but manufacturers are redesigning boards to accommodate multiple sensor brands, thereby protecting shipment schedules.
By Application: Surgical Robotics Drives the Fastest Revenue Uptick
Elderly assistance accounted for 34.79% of 2025 revenue, while surgery assistance is the fastest-growing application, with a 21.32% CAGR through 2031. The widening reimbursement landscape for orthopedic and minimally invasive procedures is a prime catalyst. Robotic systems reduce the need for open surgery by 40% in complex cases, a metric that CFOs directly translate into shorter lengths of stay and fewer readmissions.
Handicap assistance follows in growth as private insurers broaden coverage beyond workplace accidents, increasing demand for healthcare assistive robotics that support mobility and rehabilitation. Companion robots are becoming increasingly common in memory-care wings, where they deliver medication reminders and engage residents in cognitive games. Defense customers are adopting medical-grade robots for search and rescue, validating cross-domain use cases that could upscale production volumes and reduce per-unit costs in healthcare.
By End User: Homecare Surges Under Readmission Penalties
Hospitals accounted for 54.43% of revenue in 2025, yet homecare is growing at the fastest rate, with a 21.95% CAGR, as payers penalize avoidable readmissions under programs such as the United States Hospital Readmissions Reduction initiative.
ReWalk’s lighter exoskeletons and Barrett Technology’s WAM arm both recorded double-digit sales to individual consumers, illustrating the direct-to-patient pivot. Rehabilitation centers are differentiating themselves through the use of advanced robotics to justify premium rates, while nursing homes are increasingly leasing exoskeletons to manage staffing gaps.
Geography Analysis
North America remains the largest regional buyer, accounting for USD 4.18 billion of the assistive robotics market size in 2025, and benefiting from cohesive reimbursement frameworks, robust venture funding, and a dense cluster of surgical robot manufacturers. The United States anchors demand as Medicare opens coverage to new orthopedic indications, and the Veterans Health Administration deploys exoskeletons for mobility-impaired veterans. Canada’s provincial pilots signal early momentum, though broad coverage decisions remain pending.
Europe contributed approximately USD 2.16 billion in 2025 sales, led by installations in Germany and the United Kingdom. Germany’s statutory insurance coverage for robotic gait therapy spurred a 35% spike in Lokomat orders, while French caps on annual reimbursement restrain device classes eligible for coverage. Southern and Eastern European markets are price-sensitive, with Italy and Spain emphasizing lower-cost manual therapy despite favorable clinical data.
The Asia Pacific region booked USD 3.58 billion in 2025 revenue and is projected to surpass North America by 2028. Japan’s Ministry of Health, Labour and Welfare is funding offsets for upfront costs of nursing-home robots, and South Korea’s robotics innovation fund is investing USD 200 million in early-stage firms. China’s policy push for one million service robots by 2027 has driven a 48% rise in healthcare installations, with domestic brands capturing a significant share of the hospital market through aggressive pricing. Australia and New Zealand continue to adopt homecare robots under disability and accident schemes.
The Middle East and Africa generated USD 0.27 billion in 2025, with the United Arab Emirates leveraging partnerships to establish itself as a regional hub for robotic rehabilitation.
South America posted USD 0.36 billion, underpinned by Brazil’s private health insurance segment investing in surgical robotics to attract medical tourists. Despite smaller baselines, both regions could accelerate as telemedicine infrastructure reduces barriers to support services.

Regulatory Landscape
Assistive robotics regulation is tightening around safety, cybersecurity, and AI risk governance, with a growing reliance on formal standards and medical-device pathways for patient-facing systems. In medical rehabilitation robots, IEC 80601-2-78:2019+AMD1:2024 (published March 2024) updates particular requirements for basic safety and essential performance, while ANSI/CAN/UL 3300 (first edition issued May 2024) anchors safety expectations for service and companion-type robots used in public and home environments. In parallel, the US FDA continues to use the 510(k) pathway for rehabilitation robotics, and multiple AI-enabled rehabilitation robot clearances in 2024 point to higher acceptance of autonomy when controls, verification, and post-market expectations are addressed.
In the EU, manufacturers must manage dual compliance across product safety and AI governance, especially as the EU AI Act (Regulation (EU) 2024/1689) intersects with machinery and medical-device obligations for assistive platforms that include AI decision support. The policy timetable also adds concrete milestones: the EU Cyber Resilience Act (Regulation (EU) 2024/2847) begins cybersecurity reporting obligations for manufacturers on September 11, 2026, and the EU Product Liability Directive (Directive (EU) 2024/2853) must be transposed by December 9, 2026. That shift increases the need for traceability, incident readiness, and lifecycle software management across connected assistive robots.
Value Chain Analysis
The assistive robotics value chain starts with core components (precision sensors, actuators, batteries, embedded compute, and connectivity modules), moves into OEM design and assembly, and then extends into software development (navigation, perception, AI planning, teleoperation, and clinical workflow tools), clinical validation, and regulatory submission. Downstream, distribution often combines direct sales into hospitals and rehabilitation centers with channel partners for homecare, plus recurring service contracts for preventive maintenance, calibration, and software updates. System integration and commissioning are pivotal for clinical adoption, covering EHR/IT integration, training, and safety validation within care environments.
Bottlenecks concentrate upstream in critical sensors and actuators, and the report context links this to sensor supply volatility and extended lead times. That dynamic pushes OEMs toward dual-sourcing, board redesigns, and strategic inventory. Regulatory classification also shapes the chain: medical-grade devices require clinical evidence generation and post-market surveillance capabilities, while socially assistive systems rely more heavily on cybersecurity, functional safety, and human-robot interaction testing aligned to standards such as UL 3300. As platforms shift toward open architectures, public APIs from players such as Kinova increase the influence of third-party accessories and software partners in differentiation, while logistics and field-service networks drive total cost of ownership and uptime for hospitals and homecare providers.
Competitive Landscape
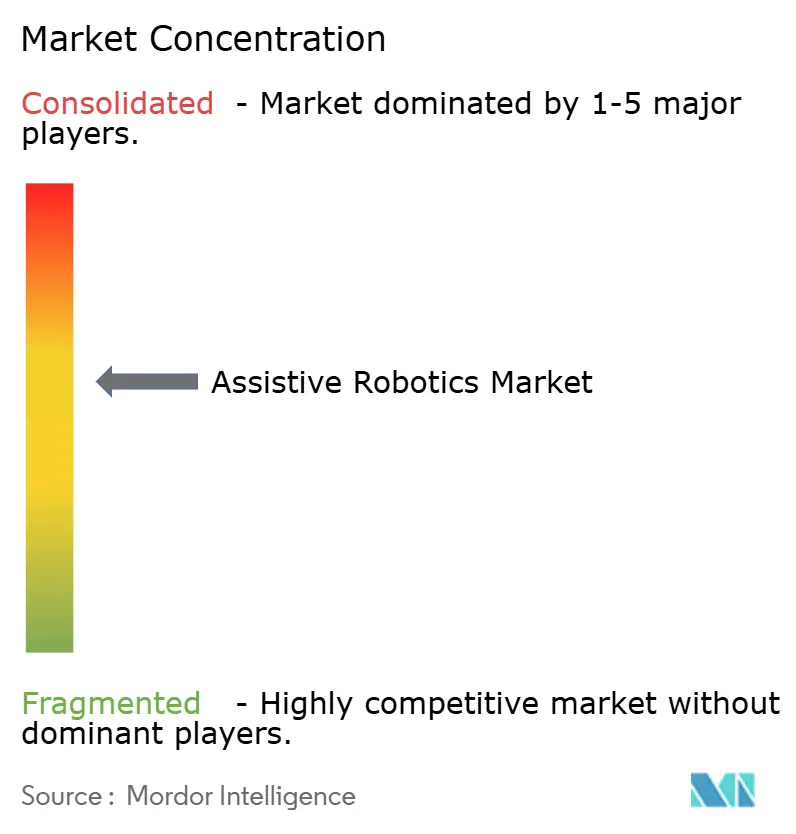
Assistive robotics presents a moderately fragmented structure. Intuitive Surgical controls 70% of surgical-robot revenue, backed by 8,500 installed da Vinci units and a thriving consumables pipeline that produced USD 6.2 billion in 2024 service and instrument sales. Medtronic’s Hugo obtained FDA clearance for urology in 2024, and Johnson and Johnson’s Ottava platform is slated for 2026, introducing price-competitive pressure. Rehabilitation and mobility assistance remain dispersed, with no firm exceeding a 15% share, leaving room for differentiated user interfaces or EHR integrations.
Strategic movement favors open architectures. Kinova released public APIs in 2024, sparking the development of third-party accessories and deepening customer lock-in through ecosystem effects. Stryker’s USD 240 million acquisition of Serf SAS integrates AI surgical planning onto its Mako platform, reinforcing a data-driven moat. Hyundai Motor Company launched the USD 35,000 H-MEX exoskeleton, leveraging automotive supply chains to undercut medical-device pricing. Patent activity in soft robotics rose 62% year-over-year, with 340 compliant-actuator grants in 2024 alone.
Supply-chain volatility in sensors has doubled lead times, increasing from six months in 2023 to 12 months in 2025, prompting dual sourcing, design revisions, and strategic stockpiling across manufacturers. Evidence gaps remain a headline risk; long-term outcome studies, especially for socially assistive systems, trail commercialization timelines and could temper payer adoption.
Assistive Robotics Industry Leaders
Kinova Inc.
Ekso Bionics Holdings Inc.
Cyberdyne Inc.
Focal Meditech BV
ReWalk Robotics Ltd.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Opportunities are widening where policy programs and reimbursement pathways reduce upfront barriers and make deployments more repeatable across eldercare, rehabilitation, and home-based therapy. Government-backed funding and industrial programs provide concrete routes to scale: Catalonia published Order EMT/45/2025 under its Smart Digital Health program (within the RETECH initiative) to fund assistive robotics and sensorization projects, and China announced a Three-Year Action Plan (2026-2028) involving 14 agencies to upgrade the rehabilitation assistive device industry, targeting 50 core technologies and 80 flagship products. These programs increase procurement visibility for OEMs and integrators and accelerate pilots that can convert into framework purchasing by regional health systems.
White space is concentrated in multi-modal, home-deployable platforms that combine physical assistance with remote monitoring and adaptive autonomy, aligning with the market shift toward home rehabilitation and tele-rehabilitation models already supported by new reimbursement mechanisms. Product strategies that lower total cost of ownership and reduce dependency on constrained components, notably precision sensors, also create near-term competitive openings via redesign, alternate sourcing, and modular upgrades. Partnerships that bring industrial manufacturing disciplines into service and assistive robots are emerging as well, including Mitsubishi Motors and Highlanders, Inc. signing an MOU (July 2026) to collaborate on mass-production of humanoid robots at the Kyoto Plant, which indicates a pathway to higher-volume production methods that can translate into more accessible assistive form factors when validated for care settings.
Recent Industry Developments
- June 2026: Kinova launched KIMA, a next-generation medical robotic arm aimed at assistive and clinical workflows that demand high precision and safe human interaction. The release strengthens Kinova's portfolio beyond research and industrial-adjacent deployments, supporting broader integration into rehabilitation and hospital environments where validated medical-grade performance and serviceability are decisive.
- December 2025: Ekso Bionics entered an exclusive US distribution agreement to become the distributor of MediTouch's BalanceTutor rehabilitation system. Expanding its rehabilitation portfolio through distribution improves Ekso's access to clinic budgets and supports bundled pathway selling alongside exoskeleton-based gait and mobility programs.
- June 2024: Ekso Bionics announced a research partnership with Shepherd Center focused on robotic rehabilitation, supporting evidence generation in neurological recovery settings. The collaboration aligns with payer and provider demands for stronger clinical outcomes data, which influences procurement decisions and coverage discussions for assistive robotics.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the assistive robotics market covers robots and robot-like systems that help people with daily activities, mobility, rehabilitation, caregiving, companionship, or task support across healthcare and home settings. The market is measured as revenue generated from sales and related solution delivery in USD.
Scope exclusions: We exclude basic non-robot assistive devices and general-purpose industrial robots that are not designed for direct human assistance.
Segmentation Overview
- By Robot Type
- Physically Assistive Robots
- Socially Assistive Robots
- Mixed Assistive Robots
- By Mobility
- Mobile Robots
- Stationary Robots
- By Application
- Elderly Assistance
- Handicap Assistance
- Surgery Assistance
- Companionship
- Public Relation
- Industrial Tasks
- Defense and Search and Rescue
- By End User
- Hospitals
- Rehabilitation Centers
- Homecare Settings
- Other End User
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure of the market and to ground the demand drivers behind adoption. We referenced public sources such as World Health Organization aging and disability datasets, World Bank population and health spending indicators, OECD health statistics, and national health agency publications on long-term care and rehabilitation capacity.
To translate activity signals into a market view, we also reviewed sources such as US FDA medical device databases, public procurement notices and tenders, peer-reviewed journals on rehabilitation and care robotics outcomes, and trade association releases tied to robotics and assistive technology. Company annual reports, investor presentations, and reputable press were used to cross-check product positioning and geographic exposure, supported by paid subscriptions focused on company financials and patent databases when needed. These examples are not exhaustive, and other public sources were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating what is truly purchased and deployed, and how pricing changes across robot types, care settings, and geographies. We spoke with a balanced mix of manufacturers, component and software providers, distributors and integrators, and hospital, rehabilitation, and homecare stakeholders across major regions to confirm adoption pacing and realistic buying cycles for the forecast period.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 31% | CXOs: 12% | APAC: 45% |
| Mid tier: 55% | Functional/Unit leaders: 39% | EMEA: 34% |
| Smaller Players: 14% | Managers: 49% | Americas: 21% |
Market-Sizing & Forecasting
Sizing starts with a top-down demand pool build using healthcare delivery and population signals, and then it is translated into revenue using adoption and pricing logic that fits assistive robots. Indicators used as model inputs included elderly population growth, rehabilitation and long-term care capacity, surgical and therapy procedure volumes where relevant, reimbursement and subsidy direction, and the installed base progression of assistive robot deployments (where traceable through public signals).
Results were then corroborated with selective bottom-up approximations, such as sampled average selling price (ASP) ranges by robot type and mobility category, channel checks on typical order sizes, and a supplier and integrator roll-up where coverage was adequate. When bottom-up visibility was thin in certain countries, assumptions were bridged using comparable market analogs and then re-validated through interviews.
For forecasting, scenario analysis was used to reflect how quickly adoption can move with policy support, hospital staffing pressure, and product readiness, and then the scenarios were anchored to the consensus trajectory shared by primary respondents. ASP changes were modeled with a practical split between mix shift (more complex systems gaining share) and pricing pressure (scaling and competition), before final totals were locked.
Data Validation & Update Cycle
We check model outputs against independent signals like healthcare capital spending direction, robotics shipment and installation disclosures where available, and the timing of major reimbursement or safety policy changes. Outliers are reviewed at the country and application level, and the assumptions are re-tested when a region shows growth that does not match underlying demand drivers.
Each report goes through multiple analyst review steps before sign-off, and follow-up calls are triggered when new product approvals, funding programs, or large-scale deployments could change near-term adoption. The study is refreshed annually, and interim updates are made for material events. Before delivery, a fresh data pass is completed so clients receive the most current view.
Mordor Intelligence's Assistive Robotics Market Estimate Compared With Other Published Estimates
Published market sizes for assistive robotics can vary, even when they appear to cover the same scope. The differences usually come from what counts as an assistive robot, how pricing is treated, which years are used as the base, and whether assumptions are rechecked with people close to purchasing and deployment.
In practice, the biggest gap drivers are refresh cadence and currency timing (which matters when growth is fast), plus whether ASP is modeled as a flat average or adjusted for mix shifts between physically assistive, socially assistive, and mixed systems. The model is also sensitive to whether clinical and homecare deployments are separated cleanly, and whether adoption curves are validated with recent procurement and rollout signals, which is where Mordor Intelligence keeps the sizing tied to what is actually being bought in the market.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 12.65 B (2026) | |
| Global Consultancy A | USD 15.10 B (2025) | Uses a different base year and may apply a broader pricing mix early in the forecast, which can lift the starting value when ASP and currency conversion timing are not normalized to a consistent year. |
| Industry Publisher B | USD 4.83 B (2025) | Appears to apply a narrower monetized scope and more conservative adoption and ASP progression, which can reduce the counted revenue when certain end uses or higher-value systems are not fully captured. |
The table indicates that the spread is mainly driven by base-year selection and how ASP and scope are handled, not just forecast optimism. By keeping the steps traceable to demand signals, adoption checks, and practical pricing assumptions, the final number stays easier to reproduce and defend when clients pressure-test it.


Key Questions Answered in the Report
What is the projected value of assistive robotics by 2031?
The assistive robotics market is expected to reach USD 31.29 billion by 2031 based on a 19.86% CAGR between 2026 and 2031.
Which application is growing fastest?
Surgery assistance is expanding at a 21.32% CAGR through 2031, driven by widening reimbursement and proven clinical benefits.
Why are mobile assistive robots attracting investment?
Mobile platforms capture 57.05% of 2025 revenue and support home-care growth because untethered navigation enables use in varied residential layouts.
How are governments influencing adoption?
Subsidies in Japan and South Korea and China’s strategic policy support are cutting upfront costs and accelerating hospital deployments.
What challenges slow adoption among smaller hospitals?
Upfront costs of USD 1.5-3.0 million per surgical system and annual maintenance of about USD 150,000 inhibit purchases by community facilities.
Which region will grow the fastest through 2031?
Asia Pacific is expected to post a 22.35% CAGR through 2031 as demographic urgency and policy incentives converge to support large-scale rollouts.
Page last updated on:





