
Asia-Pacific Manufacturing Inspection Equipment Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
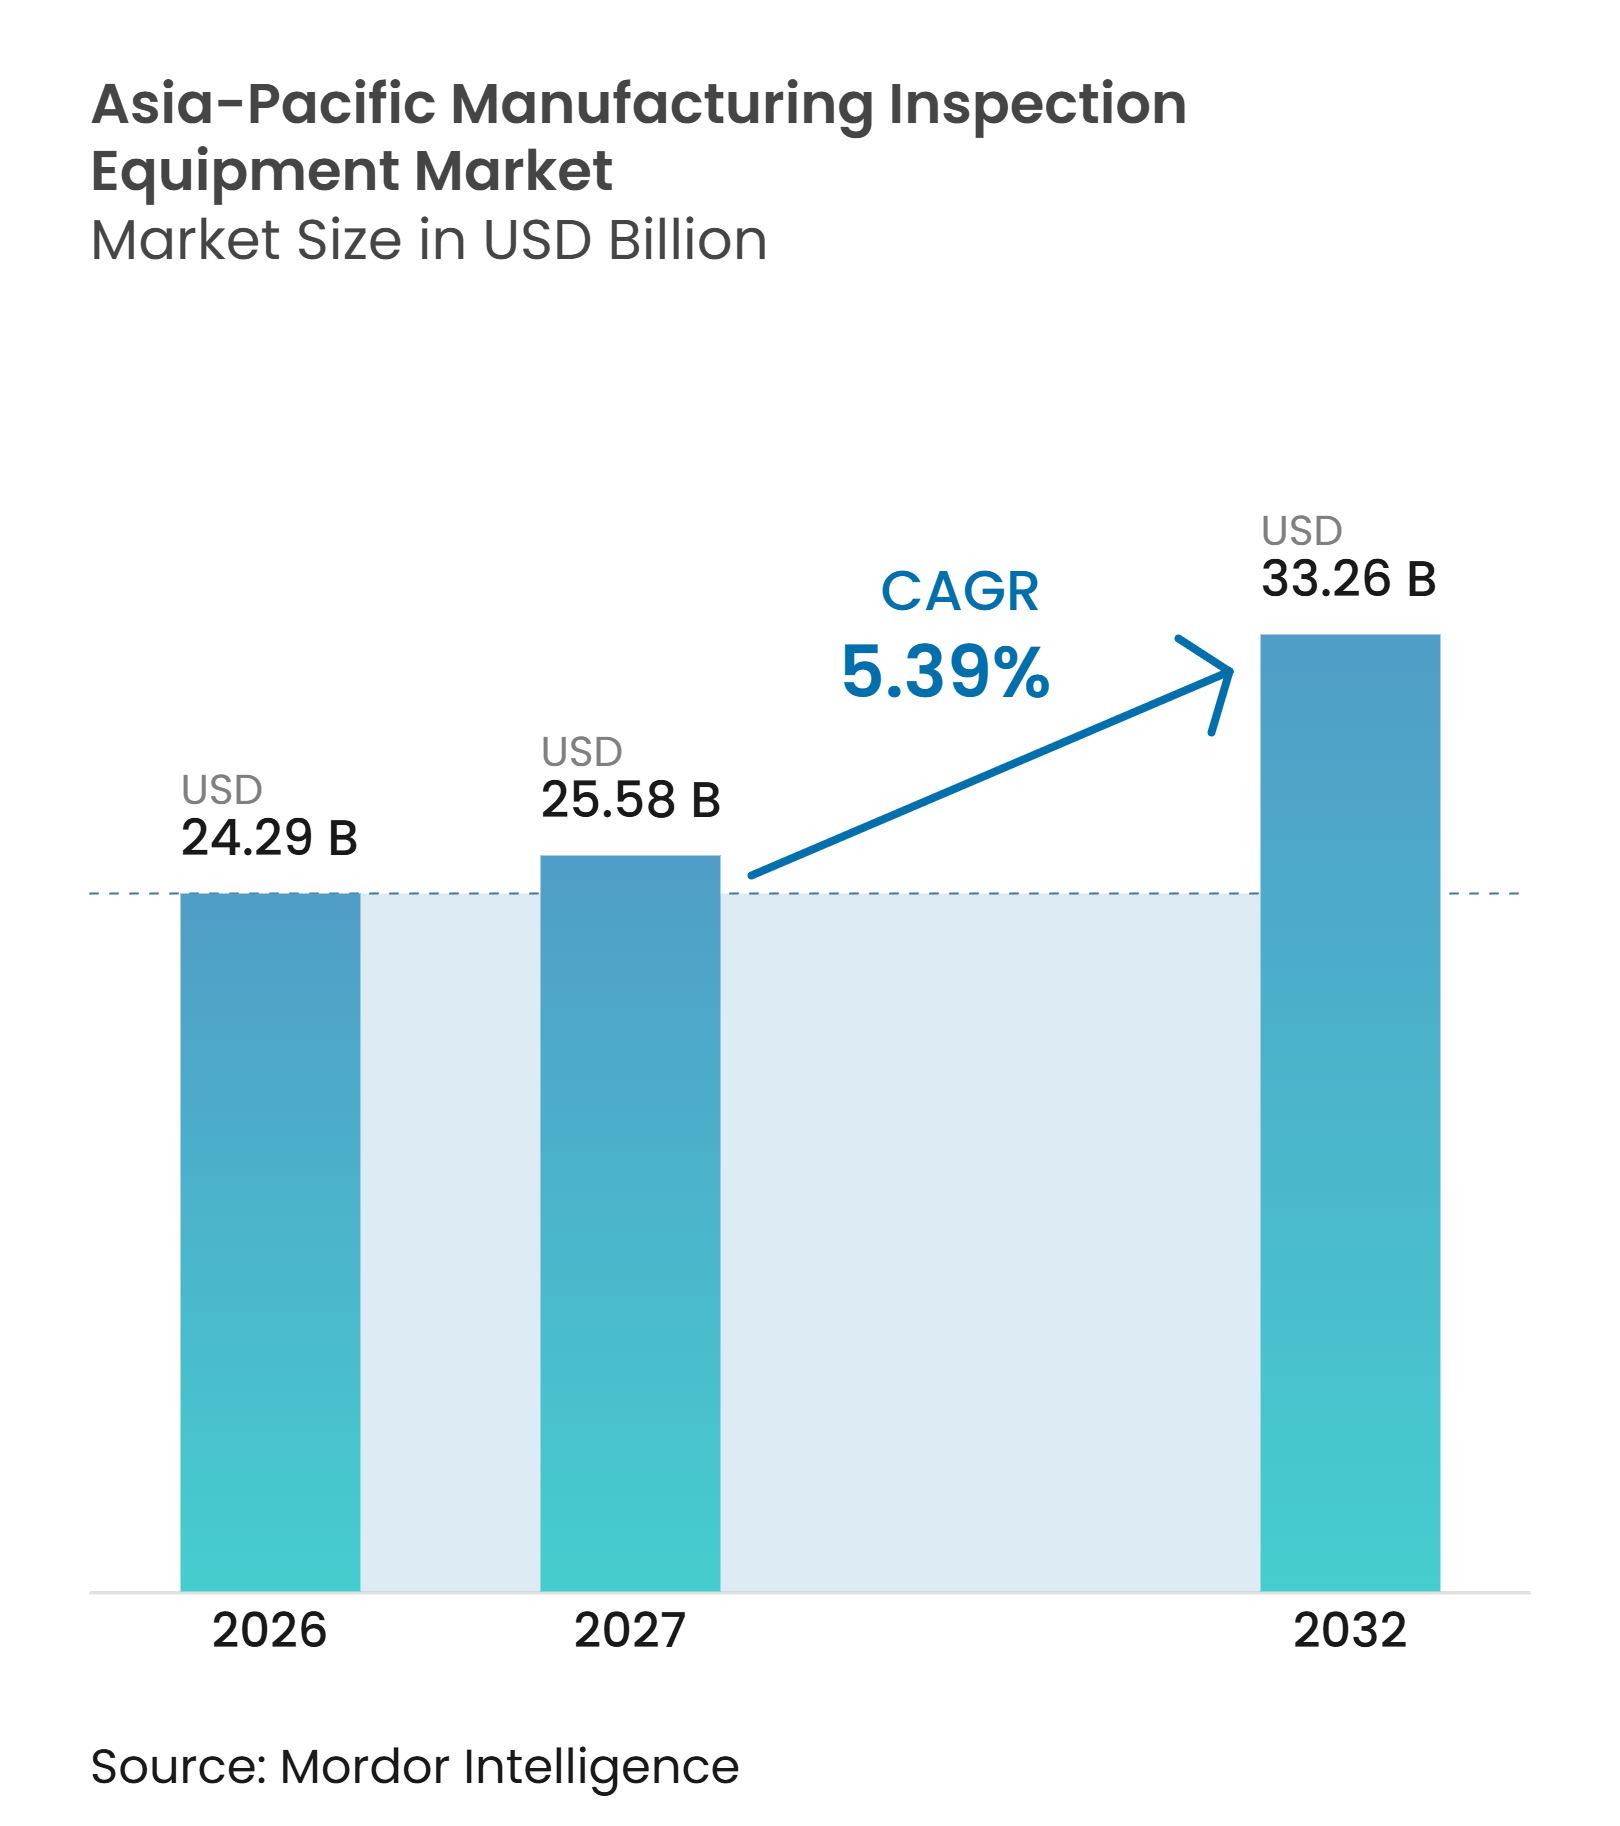
| Base Year Market Size (2026) | USD 24.29 Billion |
| Market Size (2027) | USD 25.58 Billion |
| Market Size (2032) | USD 33.26 Billion |
| Growth Rate (2027 - 2032) | 5.39 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Manufacturing Inspection Equipment Market Analysis by Mordor Intelligence
The Asia-Pacific Manufacturing Inspection Equipment Market size is projected to be USD 24.29 billion in 2026, USD 25.58 billion in 2027, and reach USD 33.26 billion by 2032, growing at a CAGR of 5.39% from 2027 to 2032.
Semiconductor fabrication spending is the central demand variable, as planned capacity additions require inspection at wafer, mask, packaging, and final production stages. Smart manufacturing programs also support equipment demand because factories need automated quality control as production lines become more connected. Battery plants and power-electronics facilities are adding demand for cell integrity testing, coating inspection, and dimensional verification. Export controls, electronics demand cycles, currency movement, and uneven adoption among smaller manufacturers may affect purchase timing, but they do not remove the underlying need for higher production quality. The Asia-Pacific manufacturing inspection equipment market is also changing as suppliers offer AI-supported software and managed inspection services alongside capital equipment.
Key Report Takeaways
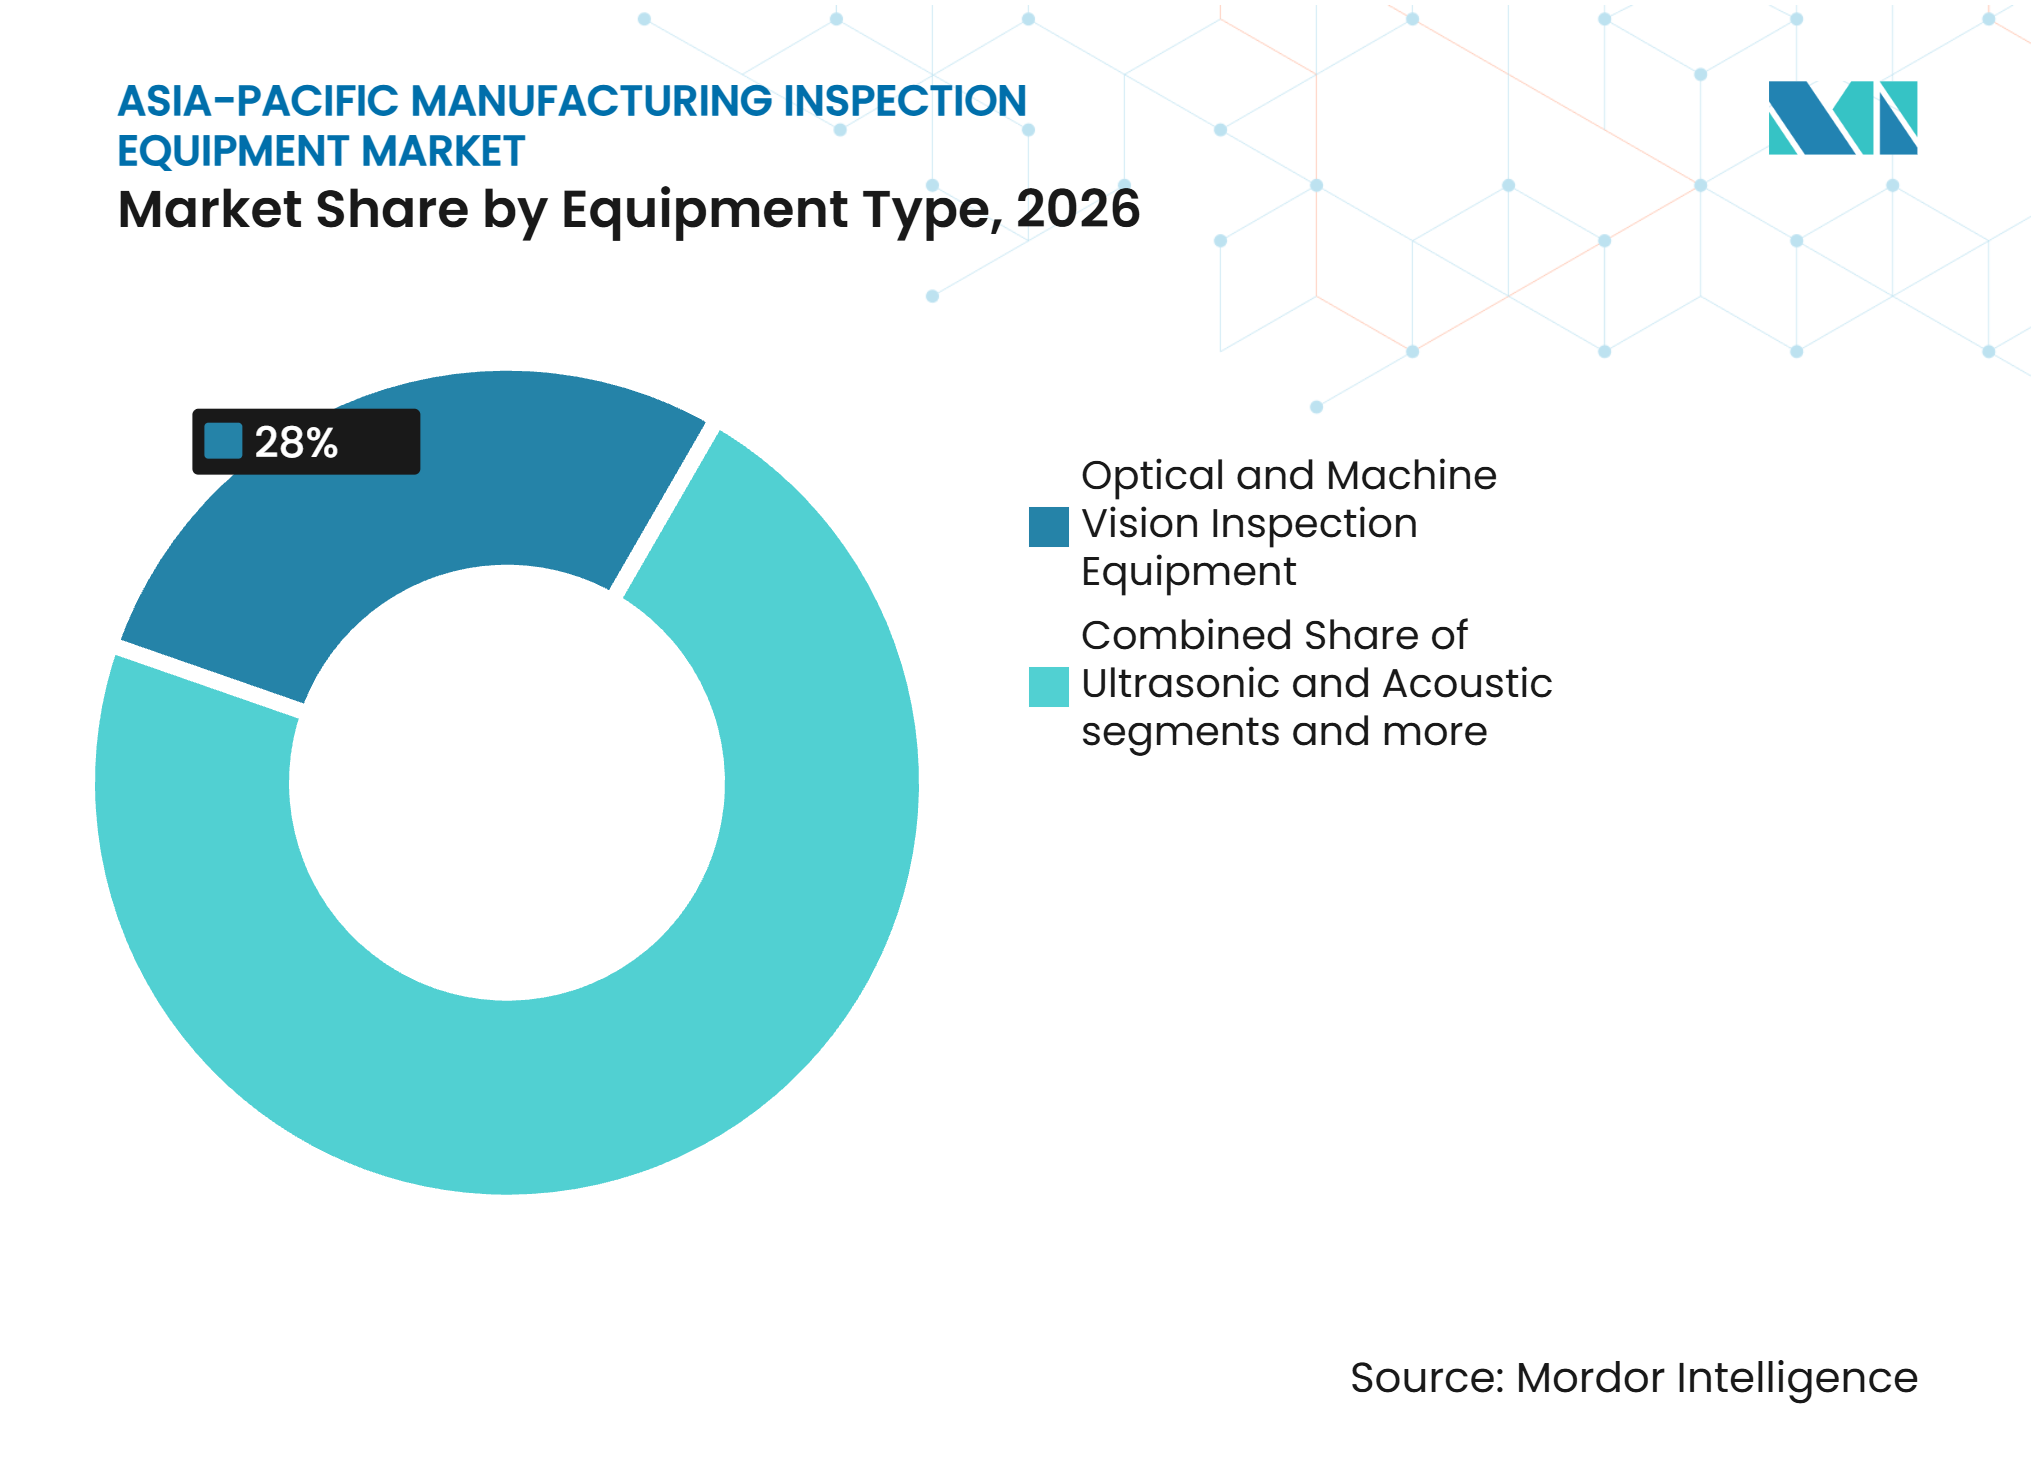
- By equipment type, optical and machine vision inspection equipment held 28% of Asia-Pacific manufacturing inspection equipment market share in 2026, while specialized semiconductor inspection equipment is forecast to grow at an 8.8% CAGR through 2032.
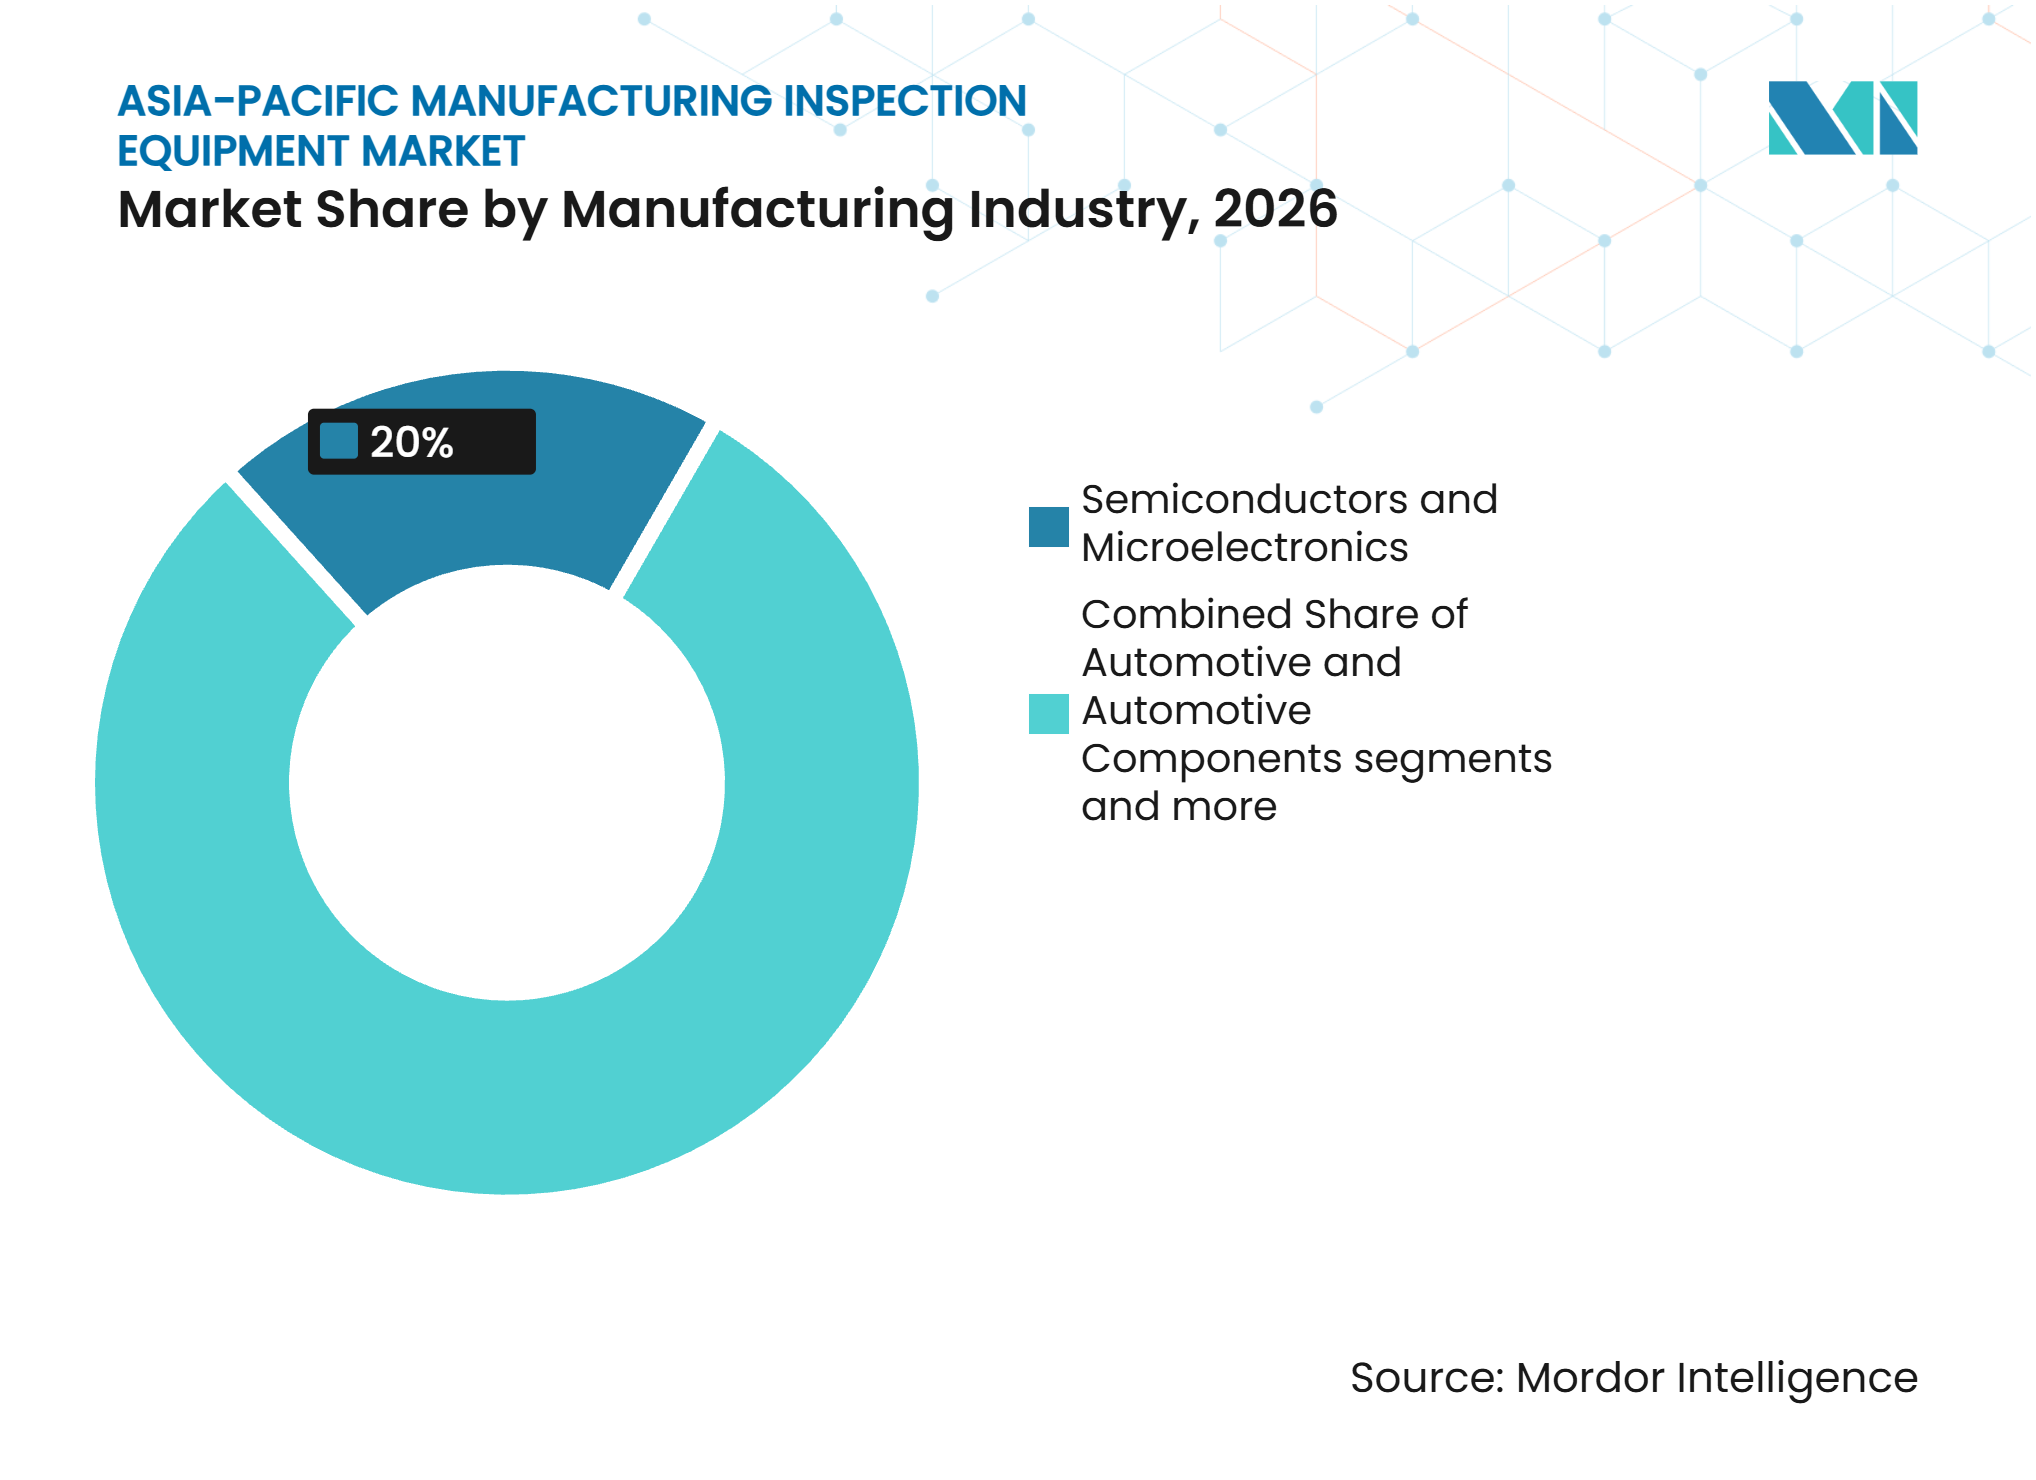
- By manufacturing industry, semiconductors and microelectronics held 20% of Asia-Pacific manufacturing inspection equipment market size in 2026 and are forecast to expand at a 9% CAGR through 2032.
- By geography, China accounted for 40% of regional revenue in 2026, while India is forecast to grow at an 8% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Asia-Pacific Manufacturing Inspection Equipment Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Semiconductor, Electronics, and Advanced Packaging Capacity | +1.5% | China, Taiwan, South Korea, Japan, with gains in Malaysia and Singapore | Short term (≤ 2 years) |
| Smart Factory and Industrial Automation Investment | +1.2% | Asia-Pacific, led by China, India, Malaysia, Singapore, and Vietnam | Medium term (2-4 years) |
| Stricter Export Quality, Product Safety, and Traceability Requirements | +0.9% | Asia-Pacific, with early gains in India and ASEAN manufacturing clusters | Medium term (2-4 years) |
| EV Battery, Renewable Energy, and Power Electronics Manufacturing Scale-Up | +0.7% | China, Indonesia, India, Thailand, and Malaysia | Medium term (2-4 years) |
| AI-Enabled Edge Inspection for Zero-Defect Production | +0.6% | Asia-Pacific, led by Taiwan, South Korea, and Japan, with ASEAN adoption | Long term (≥ 4 years) |
| Localization of Inspection Supply Chains in China, India, and Southeast Asia | +0.4% | China, India, Vietnam, Malaysia, and Thailand | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of Semiconductor, Electronics, and Advanced Packaging Capacity
Semiconductor capital spending is raising demand for wafer, mask, and advanced packaging inspection systems across the Asia-Pacific manufacturing inspection equipment market. Global front-end fab equipment investment is expected to reach USD 110 billion in 2025, including USD 38 billion in China, USD 21 billion in Taiwan, USD 21.5 billion in South Korea, and USD 14 billion in Japan.[1] Global semiconductor capacity is expected to reach 33.6 million wafers per month in 2025, with sub-7nm capacity increasing 16%. SEMI identified 18 fab construction projects planned to begin in 2025, including 4 in Japan, 3 in China, 2 in Taiwan, 1 in South Korea, and 1 in Southeast Asia. More advanced process nodes need more inspection steps at each lithography level so that unit demand can rise faster than fab counts. Export controls are also encouraging domestic inspection equipment development in China, creating separate supply tiers for advanced and mid-range systems.
Smart Factory and Industrial Automation Investment
Smart manufacturing programs create a more stable order base for the Asia-Pacific manufacturing inspection equipment market because inspection is part of quality automation. Malaysia aims to establish at least 3,000 smart factories by 2030 under the New Industrial Master Plan 2030.[2] India’s National Mission on Manufacturing targets manufacturing’s contribution to GDP at 25% by 2035 through priority industrial clusters and capital-goods development.[3] Rockwell Automation reported that 94% of surveyed Asia-Pacific manufacturers had invested or planned to invest in AI and machine learning over the next 5 years. The same study found that 47% named quality control as their primary AI use case. Public financing and manufacturing plans can reduce the purchase volatility that would result from private capital expenditure cycles alone.
Stricter Export Quality, Product Safety, and Traceability Requirements
Quality and conformity rules are increasing the need for reliable testing and inspection equipment across the Asia-Pacific manufacturing inspection equipment market. APEC issued guidance in January 2025 on standardization and conformity assessment governance for member economies. The guidance reinforces ISO/IEC 17025 and ISO/IEC 17020 as baseline frameworks for export certification. The APEC Electrical and Electronic Equipment Mutual Recognition Arrangement requires accredited testing and periodic factory surveillance under ISO/IEC 17067. These requirements extend quality procedures to suppliers that have not used automated inspection before. ISO 9001 certification and ISO/IEC 17025 accreditation also support recurring demand for instrument replacement and recalibration during supplier qualification and export licensing work.
EV Battery, Renewable Energy, and Power Electronics Manufacturing Scale-Up
EV battery investment is creating specialized demand in the Asia-Pacific manufacturing inspection equipment market. CATL and its partners began a USD 6 billion integrated battery project in Indonesia in 2025, with first-phase annual capacity of 6.9 GWh. The project covers nickel processing, battery cell production, and recycling, which gives inspection suppliers several production points to address. Battery facilities require electrode uniformity imaging, cell integrity testing, and dimensional verification that conventional electronics AOI platforms were not designed to provide. The growth of cylindrical, prismatic, and pouch cell formats also requires different inspection configurations. These requirements are shifting equipment development toward battery-specific systems and creating a new customer base beyond legacy electronics production lines.
Restraints Impact Analysis of Asia-Pacific Manufacturing Inspection Equipment Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Capital Cost and Total Cost of Ownership | -0.8% | Asia-Pacific, especially smaller manufacturers in India, Vietnam, Indonesia, and Thailand | Short term (≤ 2 years) |
| Shortage of Certified Inspection and Automation Specialists | -0.5% | Asia-Pacific, especially Vietnam, Thailand, and India’s electronics base | Medium term (2-4 years) |
| Integration Friction with Legacy Production Lines | -0.4% | Brownfield factories in China and ASEAN industrial estates | Medium term (2-4 years) |
| Data Residency, Cybersecurity, and Cross-Border Connectivity Constraints | -0.3% | China, India, Vietnam, Indonesia, and ASEAN | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Capital Cost and Total Cost of Ownership
Advanced inspection systems remain difficult to purchase for smaller manufacturers in ASEAN and India. The purchase price is only part of the cost because software licenses, recalibration, consumables, and downtime add to the life-cycle commitment. These costs can delay management approval when a facility has limited working capital or limited access to financing. The constraint is most visible among manufacturers that are moving from manual quality checks to their first automated platform. Integration needs can further increase the initial budget when a system must connect with older production lines. The Asia-Pacific manufacturing inspection equipment market therefore has room for modular systems and financing models that reduce the initial payment burden.
Shortage of Certified Inspection and Automation Specialists
A shortage of qualified workers can slow equipment installation and limit use after deployment. The International Labour Organization reported that 68% of employers in Thailand’s automotive sector cited a shortage of qualified applicants as a major recruitment obstacle in 2025. The EV transition is expected to require more than 53,000 specialist positions in Thailand. An ILO and VCCI survey found that close to 60% of respondents in Vietnam saw skilled-worker shortages as a moderate or severe challenge. Rockwell Automation found that 41% of Asia-Pacific manufacturers were using AI and automation to address skills gaps. Suppliers that offer no-code recipe generation and autonomous defect review can make systems easier to use in talent-constrained facilities.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia-Pacific Manufacturing Inspection Equipment Market Segment Analysis
By Equipment Type:
Optical Vision Holds the Largest Share While Semiconductor Platforms Grow FasterOptical and machine vision inspection equipment held 28% of regional revenue in 2026. The equipment serves electronics PCB assembly, automotive body production, food and beverage labeling, and pharmaceutical blister packaging. Its lower unit cost and broad applicability support its position as a common first automated inspection purchase for mid-sized manufacturers. KEYENCE reported 13.5% year-over-year sales growth in Asia during FY2025 Q2. Cognex added 9,000 customer accounts in 2025, 3 times its 2024 rate.
Specialized semiconductor inspection equipment has the fastest forecast growth at 8.8% CAGR through 2032, making its Asia-Pacific manufacturing inspection equipment market size the most rapidly expanding equipment category. Below-2nm logic, high-bandwidth memory stacking, chiplets, and hybrid bonding all increase the need for process control. Process-control hardware generally represents 10% to 15% of fab equipment budgets, and its importance rises as defect limits tighten. Onto Innovation launched its Atlas G6 OCD metrology platform for gate-all-around logic and high-bandwidth memory control in September 2025. Lasertec released the ACTIS A200HiT system in October 2025 for actinic EUV patterned-mask inspection with carbon nanotube pellicle support.



By Manufacturing Industry:
Semiconductors Combine the Largest Share with The Fastest GrowthSemiconductors and microelectronics accounted for 20% of the Asia-Pacific manufacturing inspection equipment market share in 2026. The vertical also has the highest forecast CAGR at 9% through 2032 because advanced chip production needs inspection at many stages. KLA reported USD 12.16 billion in revenue for the fiscal year ended June 2025. China, Taiwan, Korea, and Japan represented 81% of the company’s sales during that year. Applied Materials reported fiscal 2025 revenue of USD 20.8 billion in semiconductor systems, with Taiwan, China, and South Korea contributing 74% of total revenue.
Automotive and automotive components are the second-largest consuming vertical in the Asia-Pacific manufacturing inspection equipment industry. Japan’s precision-production requirements, South Korea’s EV transition, and China’s domestic supply chains support demand for coordinate measurement, dimensional gauging, and nondestructive testing. Batteries and Energy Storage is the fastest-emerging non-semiconductor vertical because cell formats and chemistries require distinct inspection configurations. Food and Beverage Products and Pharmaceuticals support machine vision and contamination detection in Japan, Australia, and ASEAN. Aerospace, Defense, and Other Transportation Equipment support premium CT and ultrasonic testing in Japan, South Korea, and Australia. Medical Devices and Healthcare Products add demand in India and ASEAN, where verification is aligned with ISO 13485 requirements.

Geography Analysis
China accounted for 40% of the Asia-Pacific manufacturing inspection equipment market share in 2026. Its position reflects dense electronics, automotive, industrial machinery, and consumer-goods production. China’s fab equipment investment is expected to reach USD 38 billion in 2025. Export restrictions are reshaping supplier access, while domestic vendors are expanding in mid-range inspection platforms. Japan remains a major demand center through automotive quality standards, advanced semiconductor packaging, and defense manufacturing. SEMI counted 4 new fab construction starts in Japan during 2025.
South Korea invested USD 21.5 billion in semiconductor equipment during 2025, driven by AI-server memory demand. Taiwan directed USD 21 billion toward semiconductor equipment, supporting advanced logic, EUV mask qualification, and packaging metrology. India has the highest geographic growth rate at 8% CAGR through 2032. Electronics incentives, semiconductor OSAT projects, and pharmaceutical export capacity support its Asia-Pacific manufacturing inspection equipment market size. The Government of India targets manufacturing’s share of GVA to rise from 14% in 2025 to 21% by 2032. India recorded USD 165.1 billion in manufacturing investment commitments in 2024, but this figure is not used as a current-year demand measure.
ASEAN is gaining demand as manufacturers diversify production locations. The ASEAN Investment Report recorded USD 20 billion in digital-economy manufacturing greenfield FDI and USD 13 billion in special-economic-zone investment during 2025. Malaysia is important because it hosts semiconductor back-end operations and supports smart-factory financing. Vietnam is adding SMT and electronics assembly capacity, creating initial AOI and SPI installation opportunities. Australia and the Rest of Asia-Pacific represent a smaller, stable share supported by food quality control, mining-equipment inspection, and pharmaceutical production. Across these geographies, the Asia-Pacific manufacturing inspection equipment market benefits from new lines that need quality systems from the beginning.
Competitive Landscape
Market Concentration
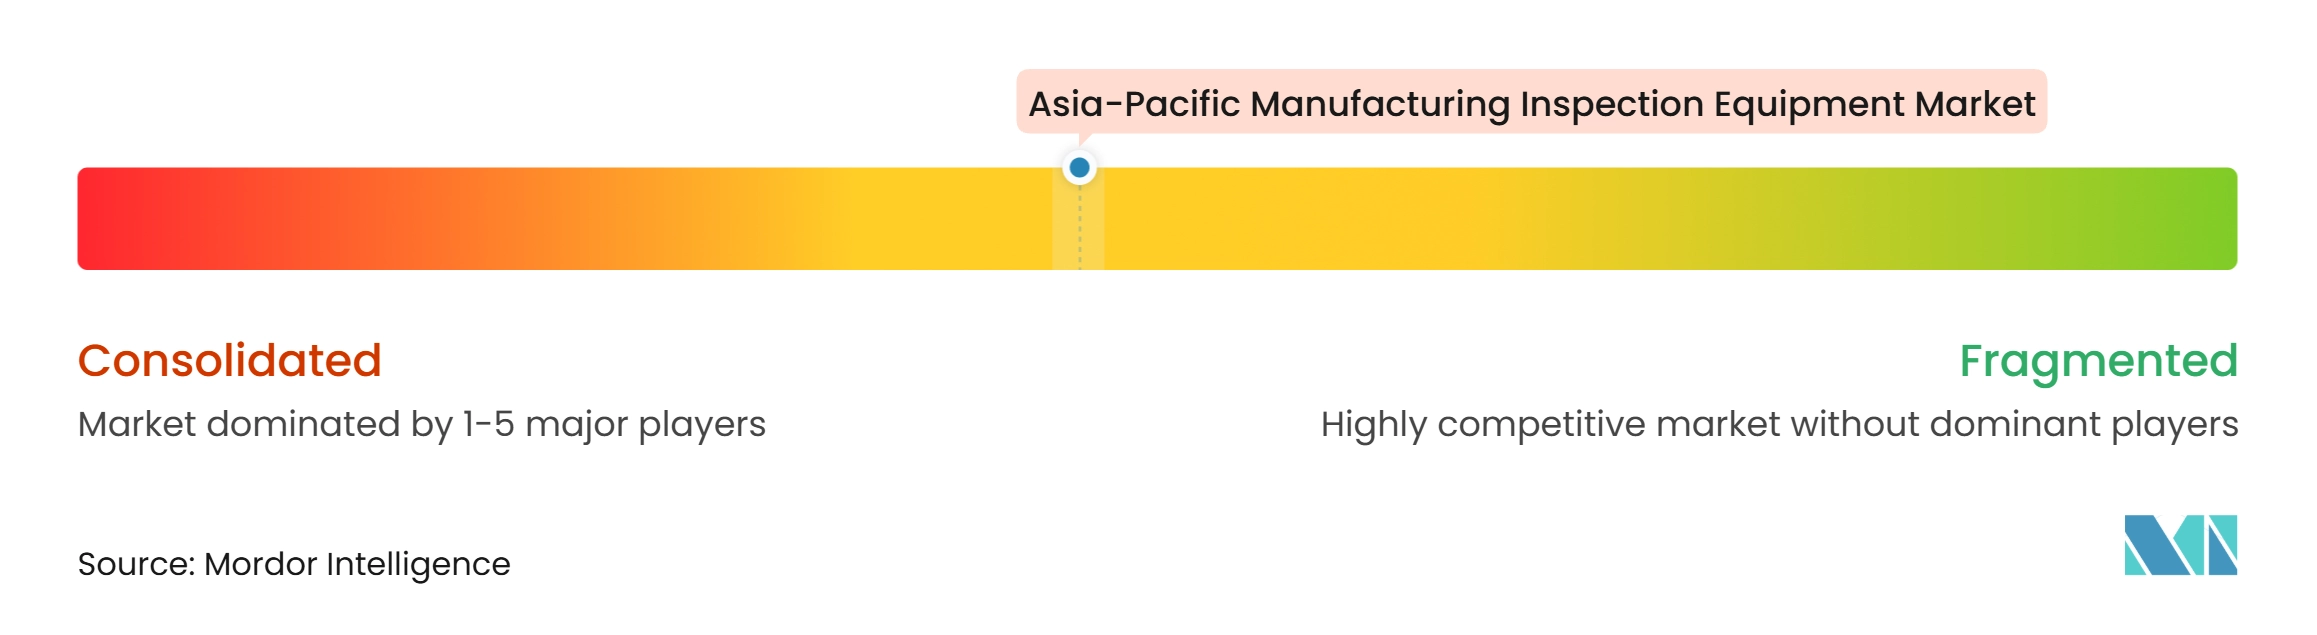
The Asia-Pacific manufacturing inspection equipment market exhibits a medium level of market concentration. KLA Corporation and Applied Materials lead in wafer and advanced-packaging inspection for leading nodes. Lasertec, Onto Innovation, and Camtek have positions in mask inspection, optical critical-dimension metrology, and heterogeneous-integration verification. KLA reported that international revenue represented 89% of total sales in fiscal 2025. Hexagon and Carl Zeiss compete in premium dimensional metrology, while Mitutoyo and Renishaw operate across standard and high-precision tiers.
Hexagon launched the MAESTRO coordinate measuring machine in May 2025 with a digital-first architecture, single-cable sensor system, cloud-native Nexus connectivity, and no-code programming. The product addresses the shortage of trained measurement specialists. ViTrox and Koh Young are strengthening their AOI, SPI, and AXI offerings with no-code AI recipe generation and autonomous defect review. OMRON, SAKI, and Test Research compete through equipment connectivity and smart-factory integration as well as hardware capability. These strategies matter because buyers want systems that can operate with fewer specialized staff. The Asia-Pacific manufacturing inspection equipment market is therefore moving toward equipment plus software, service, and line-integration offerings.
AI-native vendors are also offering managed inspection and outcome-based arrangements that lower the initial adoption barrier for smaller manufacturers. This approach can change the revenue model for conventional OEMs that depend mainly on equipment sales. Areas with remaining opportunity include affordable modular platforms, localized AI models for low-data defect classes, battery-recycling inspection, and cross-factory quality-data interoperability. These opportunities coexist with high supplier intensity rather than a single dominant vendor base. The Asia-Pacific manufacturing inspection equipment market has a competitive structure where leadership varies by technology and factory requirement. This structure supports regional challengers in standardized AOI applications while leaving advanced semiconductor tiers concentrated.
Asia-Pacific Manufacturing Inspection Equipment Industry Leaders
-
Hexagon AB
-
Carl Zeiss AG
-
KEYENCE CORPORATION
-
Cognex Corporation
-
Mitutoyo Corporation
- *Disclaimer: Major Players sorted in no particular order
Asia-Pacific Manufacturing Inspection Equipment Market Companies Covered in this Report
- Hexagon AB
- Carl Zeiss AG
- KEYENCE CORPORATION
- Cognex Corporation
- Mitutoyo Corporation
- Nikon Corporation
- AMETEK, Inc.
- Renishaw plc
- Evident Corporation
- Baker Hughes Company, Waygate Technologies
- KLA Corporation
- Applied Materials, Inc.
- Lasertec Corporation
- Onto Innovation Inc.
- Camtek Ltd.
- OMRON Corporation
- Koh Young Technology, Inc.
- SAKI CORPORATION
- Test Research, Inc.
- Viscom SE
- ViTrox Corporation Berhad
Recent Industry Developments in Asia-Pacific Manufacturing Inspection Equipment Market
- August 2026: ViTrox announced AI-powered inspection technologies for Productronica India 2026, including its QX1 HR & HS 3D automated X-ray inspection system for advanced semiconductor applications. The development addresses inspection requirements for high-density packaging, C4 bumps, and other complex components.
- May 2026: Nidec Advance Technology launched its AURCA series, an AI-based inspection and measurement solution for semiconductors and printed substrates. The system combines AI-based defect detection, full-color optical inspection, and analytical feedback to support yield improvement and earlier identification of production defects.
- December 2025: Lasertec Corporation released the MAGICS Series M9750 and M9751 mask blank inspection and review systems, expanding its actinic inspection portfolio to address EUV mask qualification at sub-2nm nodes and strengthening its position in actinic mask inspection for leading Asia-Pacific foundries.
Asia-Pacific Manufacturing Inspection Equipment Market Report Scope
The Asia-Pacific Manufacturing Inspection Equipment Market Report is Segmented by Equipment Type (Optical and Machine Vision Inspection Equipment, Dimensional and Geometric Inspection Equipment, and More), by Manufacturing Industry (Semiconductors and Microelectronics, Food and Beverage Products, and More), and by Geography (China, Japan, India, South Korea, and More). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Optical and Machine Vision Inspection Equipment |
| Dimensional and Geometric Inspection Equipment |
| Radiographic and Computed Tomography Inspection Equipment |
| Ultrasonic and Acoustic Inspection Equipment |
| Electromagnetic and Magnetic Inspection Equipment |
| Thermal and Infrared Inspection Equipment |
| Specialized Semiconductor Inspection Equipment |
| Material Identification and Composition Inspection Equipment |
| Leak and Seal Integrity Inspection Equipment |
| Product Contamination and Physical Conformity Inspection Equipment |
| Other Specialized Manufacturing Inspection Equipment |
| Automotive and Automotive Components |
| Aerospace, Defense and Other Transportation Equipment |
| Semiconductors and Microelectronics |
| Other Electronics and Electrical Equipment |
| Batteries and Energy Storage Products |
| Industrial Machinery, Metal Products and Fabrication |
| Chemicals, Plastics and Industrial Materials |
| Food and Beverage Products |
| Pharmaceuticals and Biopharmaceuticals |
| Medical Devices and Healthcare Products |
| Textiles, Apparel, Footwear and Accessories |
| Furniture, Homeware, Toys and Other Consumer Products |
| Building Materials and Construction Products |
| Packaging, Paper and Printed Products |
| Other Manufactured Products |
| China |
| Japan |
| India |
| South Korea |
| Taiwan |
| Australia |
| ASEAN(Indonesia, Vietnam, Thailand, Singapore, Malaysia, Philippines, etc.) |
| Rest of Asia-Pacific |
| By Equipment Type | Optical and Machine Vision Inspection Equipment |
| Dimensional and Geometric Inspection Equipment | |
| Radiographic and Computed Tomography Inspection Equipment | |
| Ultrasonic and Acoustic Inspection Equipment | |
| Electromagnetic and Magnetic Inspection Equipment | |
| Thermal and Infrared Inspection Equipment | |
| Specialized Semiconductor Inspection Equipment | |
| Material Identification and Composition Inspection Equipment | |
| Leak and Seal Integrity Inspection Equipment | |
| Product Contamination and Physical Conformity Inspection Equipment | |
| Other Specialized Manufacturing Inspection Equipment | |
| By Manufacturing Industry | Automotive and Automotive Components |
| Aerospace, Defense and Other Transportation Equipment | |
| Semiconductors and Microelectronics | |
| Other Electronics and Electrical Equipment | |
| Batteries and Energy Storage Products | |
| Industrial Machinery, Metal Products and Fabrication | |
| Chemicals, Plastics and Industrial Materials | |
| Food and Beverage Products | |
| Pharmaceuticals and Biopharmaceuticals | |
| Medical Devices and Healthcare Products | |
| Textiles, Apparel, Footwear and Accessories | |
| Furniture, Homeware, Toys and Other Consumer Products | |
| Building Materials and Construction Products | |
| Packaging, Paper and Printed Products | |
| Other Manufactured Products | |
| By Geography | China |
| Japan | |
| India | |
| South Korea | |
| Taiwan | |
| Australia | |
| ASEAN(Indonesia, Vietnam, Thailand, Singapore, Malaysia, Philippines, etc.) | |
| Rest of Asia-Pacific |
Key Questions Answered in the Report
What is the forecast growth rate for manufacturing inspection equipment in Asia-Pacific?
The sector is forecast to grow at 5.39% CAGR from 2027 to 2032, reaching USD 33.26 billion by 2032.
Which equipment category leads revenue in Asia-Pacific?
Optical and machine vision inspection equipment leads with a 28% share in 2026 because it serves many factory applications.
Which equipment category is growing fastest?
Specialized semiconductor inspection equipment is forecast to expand at 8.8% CAGR through 2032 as chip designs require tighter process control.
Which manufacturing vertical has the highest growth rate?
Semiconductors and microelectronics are forecast to grow at 9% CAGR through 2032 and held a 20% share in 2026.
Which Asia-Pacific country has the largest share of demand?
China accounts for a 40% share in 2026, supported by its large electronics, semiconductor, automotive, and machinery base.
Why is India becoming an important destination for inspection equipment suppliers?
India is forecast to grow at 8% CAGR through 2032, supported by electronics incentives, semiconductor projects, and pharmaceutical production.