
Thailand Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
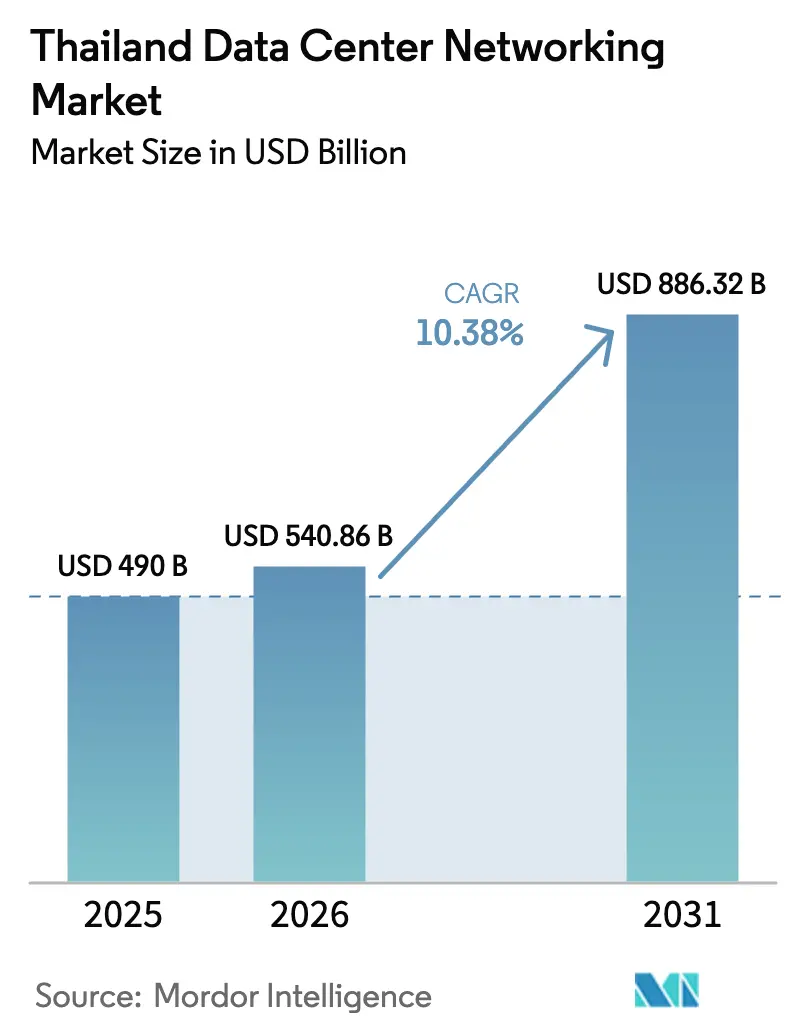
| Base Year Market Size (2025) | USD 490 Billion |
| Market Size (2026) | USD 540.86 Billion |
| Market Size (2031) | USD 886.32 Billion |
| Growth Rate (2026 - 2031) | 10.38 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Thailand Data Center Networking Market Analysis by Mordor Intelligence
Thailand data center networking market size in 2026 is estimated at USD 540.86 million, growing from 2025 value of USD 490 million with 2031 projections showing USD 886.32 million, growing at 10.38% CAGR over 2026-2031. Growth is fueled by the government-backed Thailand 4.0 program, hyperscale capital inflows, and accelerating cloud adoption. Deepening fiber backbones, falling latency targets for AI workloads, and a widening edge footprint in provincial cities are also shaping the Thailand data center networking market. Foreign investors continue to be attracted by tax holidays, green-energy credits, and proximity to subsea cable landing stations, while domestic enterprises ramp up network automation to offset labor shortages. Rising electricity tariffs, however, intensify the focus on power-efficient routing and switching platforms.
Key Report Takeaways
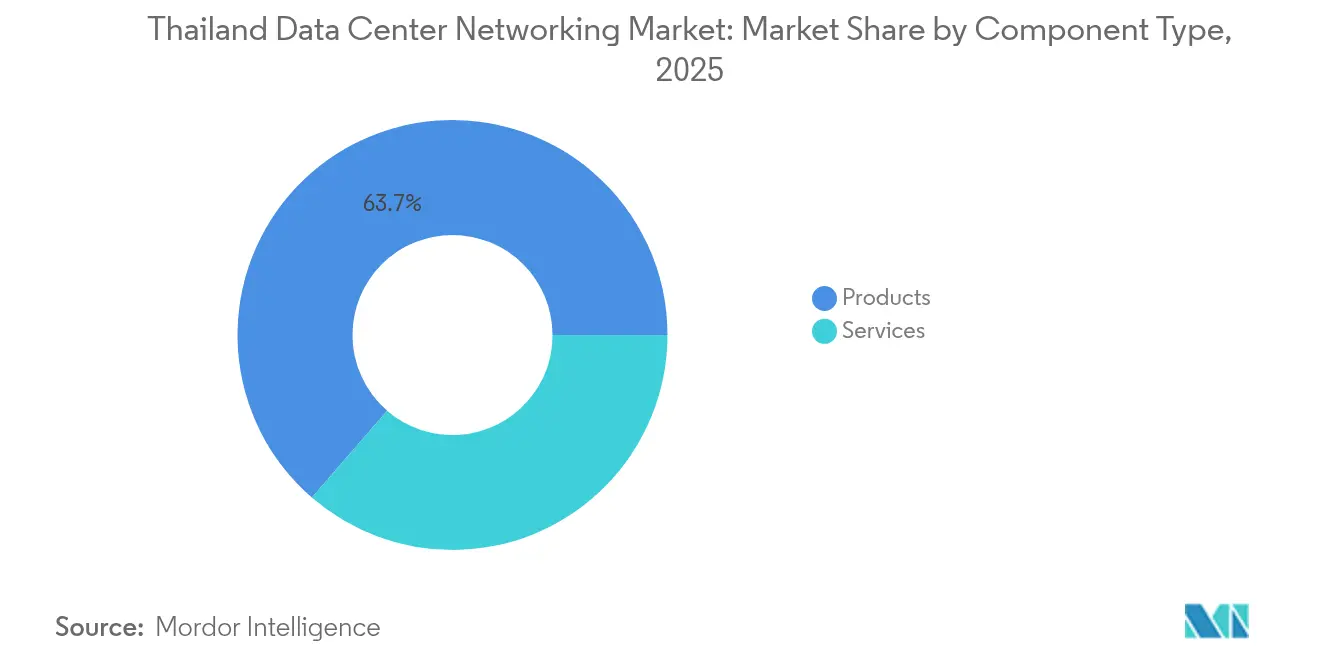
- By component, products led with 63.65% revenue share in 2025, while services are forecast to post the fastest 11.78% CAGR through 2031.
- By end-user, IT & telecommunications held 34.74% of Thailand data center networking market share in 2025; healthcare & life sciences is set to grow at 12.96% CAGR through 2031.
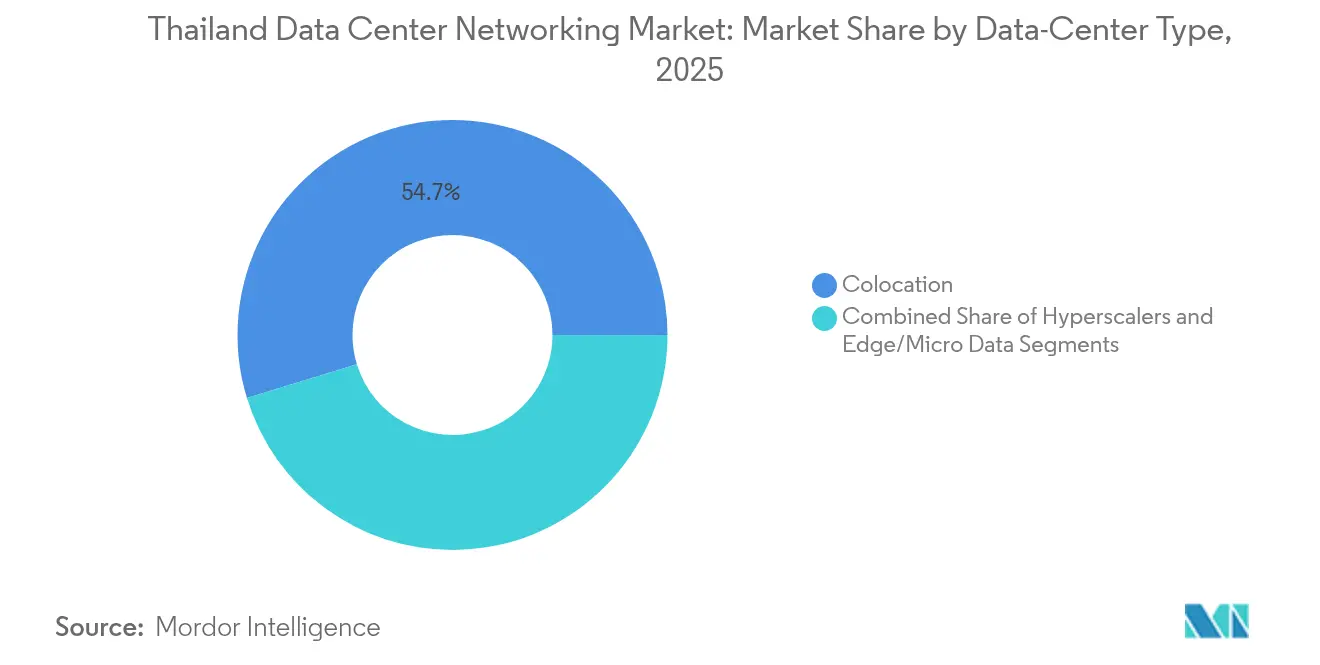
- By data-center type, colocation captured 54.73% of the Thailand data center networking market size in 2025, yet hyperscalers and cloud service providers are advancing at a 13.92% CAGR to 2031.
- By bandwidth, 50-100 GbE commanded 35.88% revenue share in 2025, whereas >100 GbE will expand at 14.12% CAGR by 2031.
- Cisco, Huawei, and Juniper together supplied just under 40% of switching and routing ports shipped in 2024, indicating a moderately concentrated vendor environment.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Thailand Data Center Networking Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cloud-first and hyperscale build-outs | +2.8% | National (Bangkok, EEC) | Medium term (2-4 years) |
| Thailand 4.0 digital-economy initiatives | +2.1% | National | Long term (≥ 4 years) |
| OPEX-reduction pressure spurring network automation | +1.7% | National, enterprise | Short term (≤ 2 years) |
| ASEAN Digital Gateway and cross-border traffic corridors | +1.4% | Regional | Medium term (2-4 years) |
| OTT video / e-sports edge traffic | +0.9% | Provincial cities | Short term (≤ 2 years) |
| ERC green-energy credit incentives | +0.6% | National | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Cloud-first and hyperscale build-outs
Hyperscale cloud providers are scaling 400 GbE and 800 GbE fabrics to support AI and real-time analytics requirements concentrated in the Eastern Economic Corridor. Microsoft, AWS, and Google collectively announced more than USD 6 billion of incremental capacity in 2025 alone, triggering a steady upgrade cycle among regional carriers that peer with these facilities.[1]Government Public Relations Department, “BOI Approves THB 241 Billion Data Center Investments,” thailand.go.th The resulting demand for high-port-density spine switches and coherent optics is cascading into enterprise roadmaps. Vendors such as Ciena introduced 8192-slot coherent routers that deliver 800 Gbit/s per channel while consuming 30% less power.[2]François Locoh-Donou, “Introducing the 8192 Coherent Router,” Ciena Insights Blog, ciena.com Large local banks are mirroring these architectures inside private cloud zones to keep latency below 1 ms for real-time payment rails.
Thailand 4.0 digital-economy initiatives
Public-sector digitalization mandates stable, low-latency networking from provincial hospitals to revenue-collection offices. Universal broadband targets by 2027 require hundreds of micro data centers at the sub-district level, each linked by software-defined WAN overlays. The Personal Data Protection Act is accelerating demand for encrypted east-west traffic visibility and zero-trust segmentation, pushing firewall throughput requirements above 1 Tb/s.
OPEX-reduction pressure spurring network automation
Electricity costs climbed to USD 0.11/kWh in 2025, and utilities signaled an additional 4% hike tied to upcoming carbon levies. Operators are turning to intent-based networking and closed-loop automation to trim 20-30% of routine configuration hours. Cisco’s Network Services Orchestrator and Red Hat Ansible are now bundled with pre-built playbooks for optical wavelength provisioning.
ASEAN Digital Gateway and cross-border traffic corridors
Thailand’s role in regional data corridors is being strengthened by new submarine cable landings that cut round-trip latency to Singapore below 25 ms. The government signed memoranda with Laos and Cambodia to harmonize IX taxation, spurring demand for terabit-scale border routers with deep packet inspection. Export-oriented manufacturers are adopting on-premises encryption appliances capable of handling 400 GbE links to meet data-residency requirements of clients anchored in Vietnam and Indonesia.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capex for advanced networking gear | -1.9% | National, mid-market | Short term (≤ 2 years) |
| Shortage of SDN / DevNet skill sets | -1.2% | National | Medium term (2-4 years) |
| Delays in subsea-cable landing permits | -0.8% | Coastal regions | Medium term (2-4 years) |
| Rising electricity tariffs and looming carbon tax | -0.7% | National | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High capex for advanced networking gear
A typical 800 GbE leaf-spine deployment for a 5 MW facility can exceed USD 4 million in capital outlay, placing it beyond the reach of Thailand’s mid-sized service providers. Leasing options are limited because local banks remain cautious about residual-value risk on rapidly obsoleting optical modules.
Shortage of SDN / DevNet skill sets
Industry surveys indicate that certified DevNet professionals number fewer than 2,000 nationwide, leading to salary premiums upward of 70% over traditional CCNP roles. The talent bottleneck delays migration projects and forces operators to rely on vendor professional services.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Services Accelerate Despite Products Dominance
Products dominated 63.65% of 2025 revenue thanks to brisk orders for fixed-configuration spine switches and coherent optics. The Thailand data center networking market size for products is projected to reach USD 514.27 million by 2031 at an 8.12% CAGR, sustained by switch-to-server refresh cycles. In parallel, professional services, managed network operations, and training recorded a 11.78% CAGR, benefiting from scarce in-house DevSecOps talent. Enterprises choose managed services to obtain 24/7 monitoring and intent-based change control, cutting mean-time-to-repair below 30 minutes. Vendors bundle lifecycle support to guarantee firmware compliance under the Personal Data Protection Act. Demand for SLA-bound services stems from regulatory penalties that can exceed 3% of annual revenue for downtime-induced data breaches.
The Thailand data center networking market is also witnessing expanded consumption of proactive maintenance services that harness AI-driven telemetry. Operators ingest streaming sensor data into predictive models that pre-empt line-card failures up to 20 days in advance. Consulting and design services are in demand during edge-site build-outs, where space and cooling constraints call for custom topologies. Remote hands services gain traction among overseas cloud providers co-locating hardware in Bangkok but lacking resident engineers.


By End-User: Healthcare Emerges as Growth Leader
IT & telecommunications held 34.74% of Thailand data center networking market share in 2025, driven by 5G backhaul densification and OTT content caching nodes. Yet healthcare & life sciences will post a 12.96% CAGR through 2031 as hospitals digitalize imaging archives and deploy tele-ICU platforms. The Thailand data center networking market size for healthcare could top USD 112.34 million by 2031, assuming continued e-health reimbursement incentives. High-resolution CT scans generate 1–2 TB per session, pushing edge storage and 100 GbE interconnect mandates inside hospital campuses.
Pharmaceutical labs in Rayong are building air-gapped data centers for genome analytics using 400 GbE clusters. BFSI remains a high-value vertical with sustained appetite for deterministic low-latency networks supporting real-time settlement and fraud analytics. Government agencies expand secure WAN overlays that meet Cyber Security Act stipulations. Media & entertainment companies leverage adaptive bitrate encoding nodes placed in tourist hotspots, while manufacturing outfits operate private 5G MEC hubs enabling digital twins.
By Data-Center Type: Hyperscalers Drive Transformation
Colocation operators commanded 54.73% of revenue in 2025, but hyperscalers are adding capacity at twice the pace of carrier-neutral builds. The Thailand data center networking market is seeing hyperscalers deploy larger 18-50 MW campuses needing 1024-port spine meshes. Saturation of Bangkok’s power grid pushes new builds toward the EEC, where tax holidays and LNG terminal access lower PUE. Colocation players respond by integrating software-defined interconnection fabrics, allowing enterprises to spin up 10 GbE cross-connects within minutes.
Edge and micro data centers register an 11.46% CAGR through 2031, reflecting IoT and smart-city rollouts. Low-height racks and outside-plant enclosures dominate these sites, often powered via rooftop solar. Operators adopt open-compute switches flashed with SONiC to meet budget constraints. Workload orchestration platforms facilitate live VM migrations between edge clusters and core regions, ensuring compliance with data-sovereignty rules.
By Bandwidth: Ultra-High-Speed Migration Accelerates
The 50-100 GbE tier retained 35.88% market share in 2025, offering an optimal balance of cost and throughput for most enterprises. Thailand data center networking market size for this tier will still climb because enterprises stagger upgrades, but its share will slip as AI training and inference require 400 GbE fabrics. Deployments above 100 GbE rise at 14.12% CAGR, propelled by hyperscale AI clusters using NVLink and RoCE.
Less than or equals to 10 GbE ports persist in out-of-band networks and KVM management links. Meanwhile, 25-40 GbE acts as a stepping-stone for SMEs migrating from 1 GbE. Vendors now ship optics supporting both PAM4 and coherent modulation, simplifying field upgrades. Dynamic bandwidth licensing enables pay-as-you-grow, curbing initial capex anxieties.
Geography Analysis
Bangkok concentrates nearly 70% of installed rack capacity and remains the primary junction for subsea cables linking India and Singapore. The capital’s dense fiber rings and proximity to IXs lower transit costs, making it the preferred landing zone for multicloud edge nodes. The Thailand data center networking market benefits from municipal incentives that discount grid power by 3% for data centers achieving PUE below 1.3.
The Eastern Economic Corridor—covering Chonburi, Rayong, and Chachoengsao—anchors the second-largest cluster of hyperscale campuses. Land grants, LNG import terminals, and high-voltage substations accelerate approvals. The Thailand data center networking market share of the EEC will approach 27.62% by 2031 as AWS, Google, and local conglomerates commission multi-availability-zone regions.
Provincial cities such as Chiang Mai and Phuket experience double-digit growth in micro-edge nodes. Smart-tourism projects stream 8K VR content that demands under-10 ms latency, prompting deployment of MEC cabinets beside 5G base stations. National broadband projects extend fiber backhaul to 40,000 villages, enabling edge-aggregation routers that hand off traffic to regional IXs. The trend diversifies capacity away from the Bangkok metro and underpins a resilient, distributed topology.
Regulatory Landscape
Thailand’s data center networking ecosystem is increasingly shaped by investment and operating conditions linked to Board of Investment (BOI) promotions and sector-specific oversight. BOI Notification Sor. 9/2568, effective November 2025, restructured incentives for data center projects and introduced tighter operational requirements referenced by market participants, including PUE thresholds (such as 1.3) and security certification expectations (for example, ISO/IEC 27001) as part of enhanced benefit plans. In 2026, BOI-related screening tightened further through requirements that new applications include a power supply confirmation letter from the Energy Regulatory Commission (ERC), linking project approvals more directly to grid readiness and energy planning.
Alongside investment promotion, Thailand’s regulatory perimeter for data centers has broadened. In 2026, a Subcommittee on Energy Management for Data Center Investment and Project Screening chaired by the Minister of Energy was established to function as a one-stop filter for resource and clean-energy assessment, affecting how and when large campuses secure power and proceed to deployment. Separately, the National Broadcasting and Telecommunications Commission (NBTC) has been reported as considering changes that elevate licensing oversight (including a potential move toward a Type 3 framework), and the Industry Ministry has been drafting legislation to regulate data centers as distinct entities, with coverage spanning environmental, energy consumption, and zoning standards. These updates influence site selection and network rollout timing.
Value Chain Analysis
The Thailand data center networking value chain starts with upstream silicon, optics, and network OS and software inputs, then moves into OEM networking platforms (switching, routing, security, and optical interconnects) supplied by global vendors such as Cisco Systems, Huawei Technologies, Juniper Networks, Dell Technologies, and Hewlett Packard Enterprise (HPE). Products then pass through local distributors and system integrators that handle design, integration, and operations, while services such as managed network services, maintenance, and training expand to offset the shortage of SDN/DevNet skill sets referenced by industry participants.
Downstream demand is anchored by colocation operators, hyperscalers, and large enterprises building private cloud zones, with large-scale capacity programs increasingly concentrated in Bangkok and the Eastern Economic Corridor (EEC). Industrial estates in Chonburi and Rayong are prominent development nodes for new campuses, and connectivity requirements tie the chain to carriers and internet exchange ecosystems. Power readiness has become a gating input to the value chain, with coordination among the BOI, the Ministry of Energy, and the ERC shaping project sequencing and, in turn, procurement cadence for high-speed fabrics and optical interconnects.
Competitive Landscape
Global incumbents—Cisco, Huawei, and Juniper—supplied just under 40% of switch and router ports in 2024, signaling moderate concentration. Each vendor now bundles AI-driven assurance engines, seeking stickier software annuities. Cisco promotes Routed Optical Networking that collapses IP and optical layers, lowering total cost by up to 45%.[3]Kip Compton, “Routed Optical Networking Explained,” Cisco Blogs, cisco.com Huawei offers CloudFabric 3.0 with lossless Ethernet for AI clusters, while Juniper’s Apstra automates multi-vendor fabrics through intent-based design.
Local system integrators—G-Able, MFEC, and Jasmine—address customization gaps by offering site preparation, power-train integration, and bilingual NOC services. Hyperscalers fast-track campus builds via joint ventures with property developers that provide land, power, and renewable PPAs. Partnerships between CP Group and BlackRock aim to erect a 200-MW “Giga Data Hub” near Rayong, pressuring incumbents to pre-position inventory and swap lines to meet condensed procurement windows.
Optical component vendors—Ciena and Lumentum—push coherent pluggables that fit QSFP-DD form factors, enabling easy upgrades from 100 GbE to 400 GbE without chassis replacement. The open-optics trend erodes traditional vendor lock-ins and intensifies price competition. Meanwhile, security appliance specialists such as Palo Alto Networks collaborate with NTT DATA to bake 5G-aware firewalls into edge data centers. The evolving mix of traditional hardware, disaggregated white-box platforms, and managed services keeps bargaining power distributed among buyers.
Thailand Data Center Networking Industry Leaders
Cisco Systems Inc.
Huawei Technologies Co. Ltd.
Juniper Networks Inc.
Dell Technologies Inc.
Hewlett Packard Enterprise (HPE)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A key whitespace in Thailand data center networking is the scale-up of high-speed switching, routing, and optical interconnect capacity required by the large build pipeline and AI-oriented deployments. As of Q2 2026, Thailand’s capacity pipeline under construction or planned was cited at 944 MW versus 216 MW of live capacity, a gap that translates into demand for spine-leaf fabrics, coherent optics, and higher-bandwidth east-west security inspection in new and expanding facilities. The pipeline is also being enabled through formal investment facilitation: the BOI approved over 223 billion baht (USD 6.8 billion) across 25 projects under the Thailand FastPass mechanism, reinforcing near-term procurement visibility for in-country network build-outs.
Energy procurement and compliance-linked design requirements are creating more specific opportunities in power-efficient architectures and automation tooling. The Direct Power Purchase Agreement (DPPA) pilot launched in January 2026 provides a mechanism for qualifying data centers (minimum 50 MW IT load) to procure renewable electricity, which can improve project bankability and support networking rollouts for hyperscale campuses that rely on high port-density designs. On the workload side, AI hosting and multi-AZ cloud infrastructure add incremental requirements for low-latency fabrics and resilient interconnects, illustrated by Datasection (Thailand) Co. Ltd. investing USD 235.2 million in high-performance GPU server infrastructure for AI hosting in Bangkok and Pathum Thani. This supports adjacent demand for high-throughput networking, lossless Ethernet configurations, and operational services able to sustain rapid change cycles.
Recent Industry Developments
- July 2026: Broke ground on Bangkok 4 data center campus in Chonburi. The launch expands Thai hyperscale capacity in Chonburi and strengthens regional data center interconnection for Thai enterprises. It signals accelerated capacity buildup in the Eastern Economic Corridor corridors, enhancing connectivity and supply security for cloud and AI workloads.
- July 2026: Ground-breaking for a 6 billion baht hyperscale data center in Muangthong Thani (Bangkok area) with 21MW IT capacity. The project creates a new hyperscale campus in the northern Bangkok region and expands high-capacity IT load to meet AI and cloud demand. It tightens competition for Tier-1 data-center space in Greater Bangkok by increasing available scale and access to premium sites.
- May 2026: Signed an US$880 million green loan for the 100MW BKK Campus data center in Chonburi. This financing underscores a major Thai data-center campus development and reinforces funding for large scale capacity expansions. It demonstrates green financing to enable hyperscale rollout and underpins regional connectivity build-out in the Eastern Economic Corridor.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Thailand data center networking market is defined as the revenue generated from networking products and related services used inside data centers in Thailand to connect servers, storage, and external networks, across enterprise, colocation, and cloud facilities.
Scope exclusions: The sizing excludes general telecom access networks outside data center sites (such as last mile mobile and fixed broadband) and consumer Wi-Fi equipment.
Segmentation Overview
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less Than equals to 10 GbE
- 25–40 GbE
- 50–100 GbE
- Greater Than 100 GbE
Data Sources, Market Sizing, and Validation
Desk Research
We start by building a fact base on Thailand data center buildout and connectivity conditions, and then we map where networking spend typically sits within that infrastructure stack. Public and official sources help anchor the assumptions, such as Thailand's Board of Investment announcements and incentive programs, National Statistical Office indicators for ICT usage, regulator publications from the NBTC on connectivity, and energy and power system context from EPPO and EGAT.
To keep the model realistic, we also review operator and supplier filings, investor presentations, and credible press coverage for reported expansions, capacity additions, and technology shifts inside facilities. A few paid subscriptions are used only in approved ways, mainly for company financials and intelligence, patent databases, and shipment level import and export checks that help validate Thailand specific supply flows. The desk sources listed above are illustrative, and many other references are used to collect data, clarify definitions, and cross-check assumptions.
Primary Interviews and Surveys
Primary work is used to confirm what is actually being purchased and deployed in Thailand facilities, and then to correct desk assumptions that are too broad for this country. We speak with a mix of data center operators, cloud and colocation users, channel partners, and technical specialists who can validate typical port speeds, refresh cycles, and service attachment rates, which are then used to triangulate the final model outputs.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 37% | CXOs: 18% |
| Mid tier: 45% | Functional/Unit leaders: 35% |
| Smaller Players: 18% | Managers: 47% |
Market-Sizing & Forecasting
Sizing is built using a top-down approach where Thailand's data center demand pool is reconstructed from capacity additions and utilization signals, and then translated into networking spend based on architecture and refresh behavior. The model is subsequently checked with selective bottom-up approximations, such as sample bill-of-material style roll ups for common network layers and channel checks on typical pricing bands, before totals are adjusted.
A few inputs matter most in this market, including the pace of new data center capacity and expansions, the mix of hyperscale and colocation builds versus enterprise rooms, adoption of higher bandwidth interconnects, average switch and router pricing progression by port speed, and service attach rates for installation, maintenance, and managed support. Where direct observations are thin, gaps are handled by using ranges agreed in interviews and then stress-tested against import and shipment signals.
For forecasting, scenario analysis is used because expansion timing can move based on power availability, permitting, and major tenant decisions. The short-term path is tied to announced capacity and expected commissioning windows, while the medium-term outlook follows normalized refresh cycles and traffic growth expectations shared by industry respondents.
Data Validation & Update Cycle
Each major input is cross-checked against at least one independent signal, and then the full model is reviewed for outliers, step changes, and unrealistic price or volume jumps. When variances look too large, the assumptions are revisited and, if needed, respondents are re-contacted to confirm what changed and why.
Before sign-off, another analyst reviews the calculation chain so arithmetic and logic are consistent across years, with special attention to currency conversion timing and scope alignment. The report is refreshed annually, and interim updates are made when material events occur, such as large capacity announcements, policy shifts, or significant changes in equipment pricing. Right before delivery, a final check is performed so clients receive the latest view.
Mordor Intelligence's Thailand Data Center Networking Market Size Versus Other Published Estimates
Published market sizes for Thailand data center networking can look far apart because different studies count different equipment layers and they also do not always treat services and upgrades in the same way. Timing also matters because some estimates use announcement-led build plans, while others rely on installed capacity signals that lag.
The main gap comes from whether general enterprise campus networking and telecom edge connectivity are included, where Mordor Intelligence counts only networking sold for in-facility data center use and then applies Thailand-specific refresh cycles and port-speed mix rather than broad regional averages.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 490.00 M (2025) | |
| Regional Consultancy A | USD 610.00 M (2025) | Often broadens scope to include campus switching and WAN edge upgrades tied to digital transformation programs, which inflates networking value beyond data center walls. |
| Industry Association B | USD 430.00 M (2025) | Tends to undercount by focusing on hyperscale projects and a narrower set of high-speed ports, which misses spend from enterprise rooms and service revenue attached to deployments. |
The spread in the table is mostly explained by scope choices and how price and mix are carried through the forecast years. By keeping the demand pool tied to Thailand facility activity and validating key levers like bandwidth mix and refresh timing with primary checks, the final number stays traceable to repeatable steps and clear inputs.


Key Questions Answered in the Report
What is the current size of the Thailand data center networking market?
The market stands at USD 540.86 million in 2026 and is forecast to reach USD 886.32 million by 2031, implying a 10.38% CAGR.
Which segment is growing fastest?
Services, particularly managed operations and integration, are expanding at 11.78% CAGR due to talent shortages and rising network complexity.
Why are hyperscalers investing heavily in Thailand?
Factors include tax incentives in the Eastern Economic Corridor, strategic proximity to ASEAN traffic corridors, and government support under Thailand 4.0.
What bandwidth tier is advancing most quickly?
Links above 100 GbE, including 400 GbE and 800 GbE, are growing at 14.12% CAGR as AI and real-time analytics workloads surge.
How are rising power costs influencing network design?
Operators adopt power-efficient silicon, routed optical architectures, and AI-driven automation to curb OPEX as electricity tariffs climb.
What are the major restraints facing the market?
High upfront cost for cutting-edge gear and a shortage of SDN/DevNet talent can delay deployments and limit broader technology uptake.
Page last updated on:
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Thailand Data Center Rack Market Racks demand across Thailand, covering rack size, rack height and rack type.
- China Data Center Water Consumption Market Water use demand across China, covering source of water procurement, data-center type and data-center size.
- Sweden Data Center Construction Market Construction in Sweden, split by infrastructure, tier and end user.
- Sweden Data Center Storage Market Storage in Sweden, split by facility size and tier.
- Switzerland Data Center Storage Market Switzerland storage, split by storage technology, storage type and facility type.
- Thailand Data Center Storage Market Storage in Thailand, split by storage technology, storage type and facility type.
- Africa Data Center Storage Market Storage demand across Africa, covering storage technology, storage type and facility type.
- Sweden Data Center Physical Security Market Sweden physical security, split by solution type and service type.
- Thailand Data Center Physical Security Market Physical security demand across Thailand, covering solution type, service type and end user.





