
South America Data Center Optical Connectivity Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
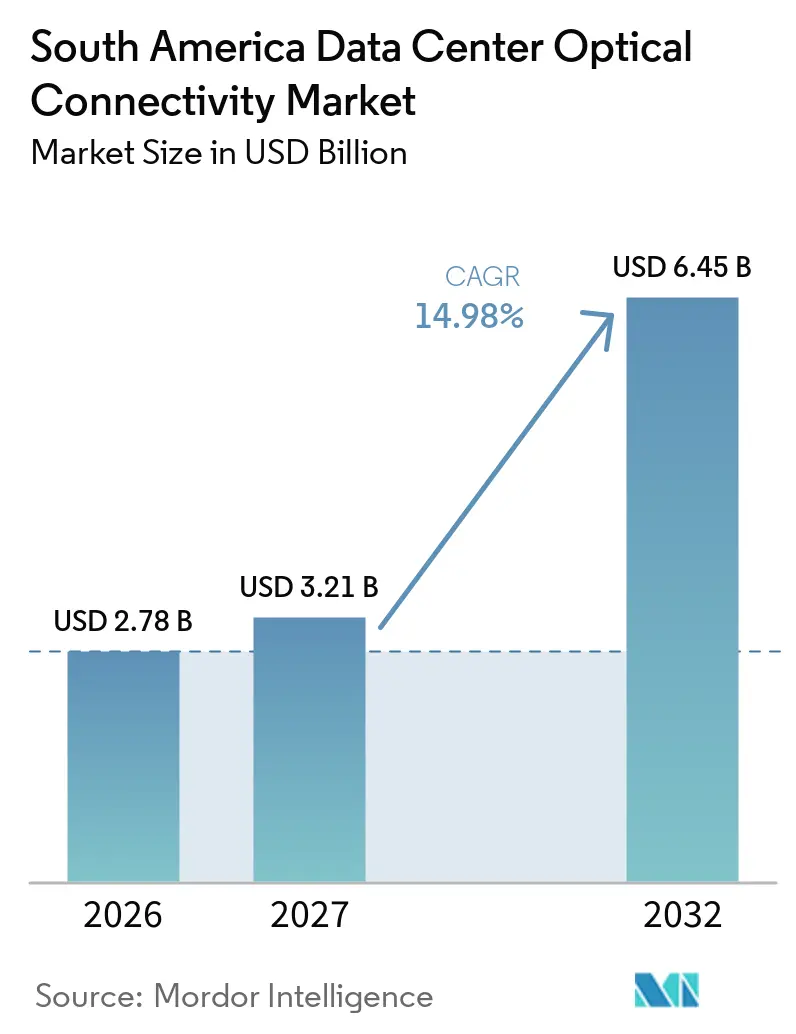
| Base Year Market Size (2026) | USD 2.78 Billion |
| Market Size (2027) | USD 3.21 Billion |
| Market Size (2032) | USD 6.45 Billion |
| Growth Rate (2027 - 2032) | 14.98 % |
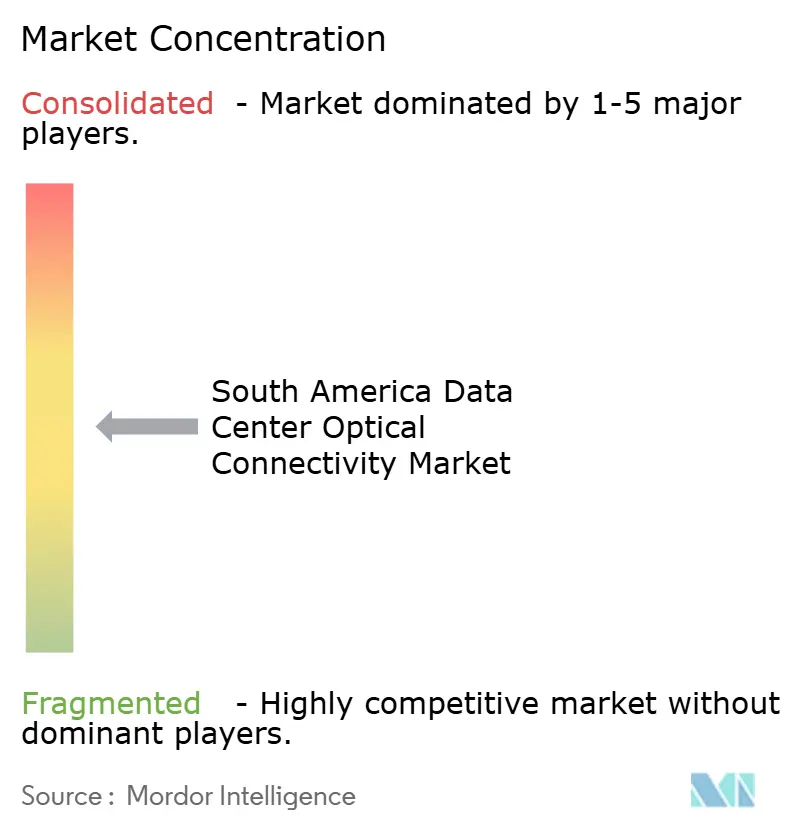
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South America Data Center Optical Connectivity Market Analysis by Mordor Intelligence
The South America Data Center Optical Connectivity Market size is expected to increase from USD 2.78 billion in 2026 to USD 3.21 billion in 2027 and reach USD 6.45 billion by 2032, growing at a CAGR of 14.98% over 2027-2032.
Demand is increasingly tied to AI-ready campuses, where dense compute clusters require more high-speed links than conventional cloud deployments. New hyperscale and colocation construction in Brazil is expected to support purchases of transceivers, fiber assemblies, connectors, and optical switching systems. Subsea cable projects are also increasing the need for coherent optical equipment at landing stations and on links to major data center hubs. Supply limitations for advanced modules, local import costs, and power availability will shape deployment schedules and vendor choices. The South America data center optical connectivity market therefore combines a large established base of pluggable optics with a gradual move toward higher-density photonic architectures.
Key Report Takeaways
- By product type, Optical Transceivers held 43.17% of the South America data center optical connectivity market share in 2026, while Optical Circuit Switches are projected to expand at a 28.94% CAGR through 2032.
- By connectivity architecture, Conventional Pluggable Optics held 74.31% of revenue in 2026, while Co-Packaged Optics are projected to expand at a 32.46% CAGR through 2032.
- By data rate, up to 400 Gbps held 39.61% of revenue in 2026, while above 1.6 Tbps is projected to expand at a 30.71% CAGR through 2032.
- By reach, 7-100 Meters held 33.79% of revenue in 2026, while 100-500 Meters is projected to expand at a 28.13% CAGR through 2032.
- By application, Switch-to-Switch connections held 26.97% of revenue in 2026, while GPU-to-GPU interconnects are projected to expand at a 31.37% CAGR through 2032.
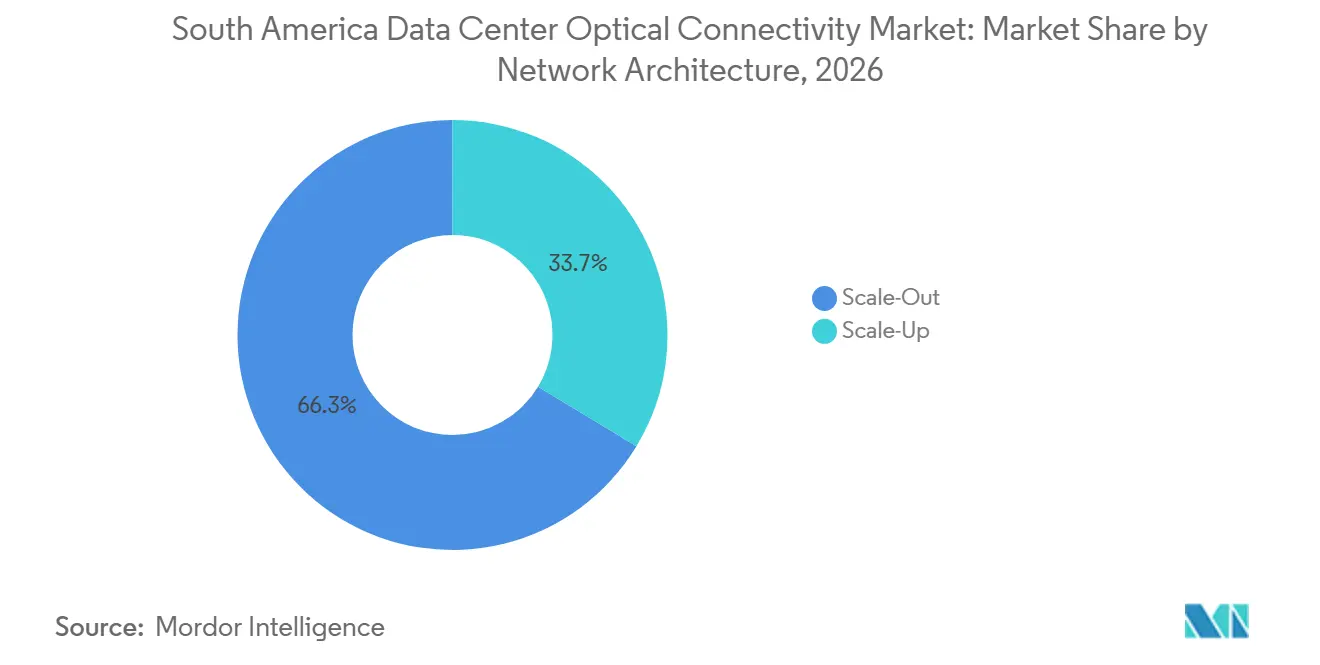
- By network architecture, Scale-Out held 66.34% of revenue in 2026, while Scale-Up is projected to expand at a 29.64% CAGR through 2032.
- By data center type, Hyperscale facilities held 46.23% of revenue in 2026 and are projected to expand at a 30.15% CAGR through 2032.
- By country, Brazil held 73.57% of revenue in 2026 and is projected to expand at a 31.28% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of South America Data Center Optical Connectivity Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI Cluster and Generative AI Infrastructure Expansion | +4.2% | Brazil-centric, with early spillover to Argentina | Medium term (2-4 years) |
| Hyperscale and Colocation Data Center Investment | +3.5% | Brazil, with extension to Rest of South America | Long term (≥ 4 years) |
| Subsea Cable Landing and Regional Interconnection Expansion | +2.4% | Brazil coastal corridors and Argentina | Medium term (2-4 years) |
| 800G Migration Across High-Density Data Center Fabrics | +1.9% | Global supply chain, concentrated demand in Brazil | Short term (≤ 2 years) |
| Carrier-Neutral Data Center Interconnection Growth | +1.4% | São Paulo, Rio de Janeiro, Fortaleza, Buenos Aires, and Santiago | Short term (≤ 2 years) |
| Brazil-Centered AI and Cloud Infrastructure Corridors | +1.1% | Brazil, with connections to Argentina and Chile | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
AI Cluster and Generative AI Infrastructure Expansion
AI workloads are increasing the number of high-speed optical links needed inside each data center rack and across campus networks. Ascenty announced USD 1.2 billion for 4 AI-focused hyperscale facilities in São Paulo state, including a facility at Sumaré designed for large-scale AI workloads. These designs require substantial GPU-to-switch and GPU-to-GPU connectivity, which raises optical module intensity per megawatt of installed IT capacity. The South America data center optical connectivity market is consequently becoming more exposed to the technical choices made in AI cluster designs. Higher bandwidth and lower latency requirements favor advanced optical links over copper connections at the most demanding layers. The effect is concentrated in Brazil first, then may extend to other regional hubs as AI capacity is commissioned.
Hyperscale and Colocation Data Center Investment
Large campus investments create procurement cycles that extend from construction through commissioning and later capacity additions. Ada Infrastructure began work on its GRU10 campus in Franco da Rocha with a planned BRL 2.7 billion (USD 500 million) investment through 2030.[1] Equinix opened the SP6 facility in Santana de Parnaíba after a USD 114 million investment, adding carrier-neutral capacity to the São Paulo network core. Such facilities require active optics and passive fiber infrastructure as new halls and interconnection rooms are fitted out. Shared colocation sites also need dense cross-connects among tenants, carriers, and cloud providers. This investment pattern supports a broader supplier base for the South America data center optical connectivity market.
Subsea Cable Landing and Regional Interconnection Expansion
Subsea cable landings create demand for optical termination, coherent transmission, and terrestrial links between coastal sites and data center clusters. Firmina entered service in 2026 and connects the United States with Brazil, Argentina, and Uruguay across a 14,517 km route. The system adds strategic importance to landing points such as Praia Grande, Las Toninas, and Punta del Este. V.tal has also outlined the Synapse project, a 9,700 km system between São Paulo and Tuckerton, New Jersey, with a branch to Fortaleza and a construction schedule beginning in the second half of 2026. These routes require links from landing infrastructure to metro and regional data center networks. This strengthens the role of coherent optics in the South America data center optical connectivity market.
800G Migration Across High-Density Data Center Fabrics
The transition from 400G to 800G is being driven by traffic patterns in AI training and large cloud fabrics. Nokia states that 800G ZR and ZR+ optics can increase fiber capacity where AI-related traffic outpaces 400G capability. New 800G deployments need compatible switches, transceivers, cabling, and thermal management. This change places greater attention on qualification, interoperability, and delivery timing for optical vendors. The South America data center optical connectivity market is likely to adopt 800G after global reference deployments and local validation cycles are completed. Import procedures and sequential facility commissioning can delay the regional rollout relative to larger mature markets.
Restraints Impact Analysis of South America Data Center Optical Connectivity Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Import Duties, Customs Delays, and Long Qualification Cycles | -1.8% | Brazil primary, Argentina secondary | Short term (≤ 2 years) |
| Limited Regional Availability of Advanced Photonic Engineering Skills | -1.2% | South America-wide | Long term (≥ 4 years) |
| Grid Reliability and High Electricity Costs in Major Data Center Hubs | -0.8% | São Paulo, Rio de Janeiro, and Fortaleza | Medium term (2-4 years) |
| Regional Fragmentation of Procurement, Standards, and Service Support | -0.5% | South America-wide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Import Duties, Customs Delays, and Long Qualification Cycles
Import duties and administrative procedures can increase the delivered cost and lead time for high-speed optical equipment. The input draft identifies Brazil as the most exposed market because advanced semiconductors, server components, and optical hardware rely on imports. Vendor qualification adds another layer of time, especially for 800G and 1.6 Tbps families that require field testing, firmware validation, and environmental checks. These processes may restrict the ability of operators to shift quickly to alternative suppliers. The South America data center optical connectivity market therefore benefits when vendors can provide local engineering and support. The challenge is most immediate in large Brazilian procurement programs and can also affect Argentina.
Limited Regional Availability of Advanced Photonic Engineering Skills
Advanced optical systems need engineers with experience in high-speed integration, photonics packaging, and system validation. The European Photonics Industry Consortium describes persistent demand for specialist optical engineering roles and related production expertise.[2] South America does not yet have a deep regional manufacturing cluster for the newest photonic components. Deployment teams often depend on vendor programs or specialists trained abroad. That reliance can lengthen qualification for new products and favor established vendor relationships. It may also limit the pace at which operators qualify a wider supplier list for the South America data center optical connectivity market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South America Data Center Optical Connectivity Market Segment Analysis
By Product Type:
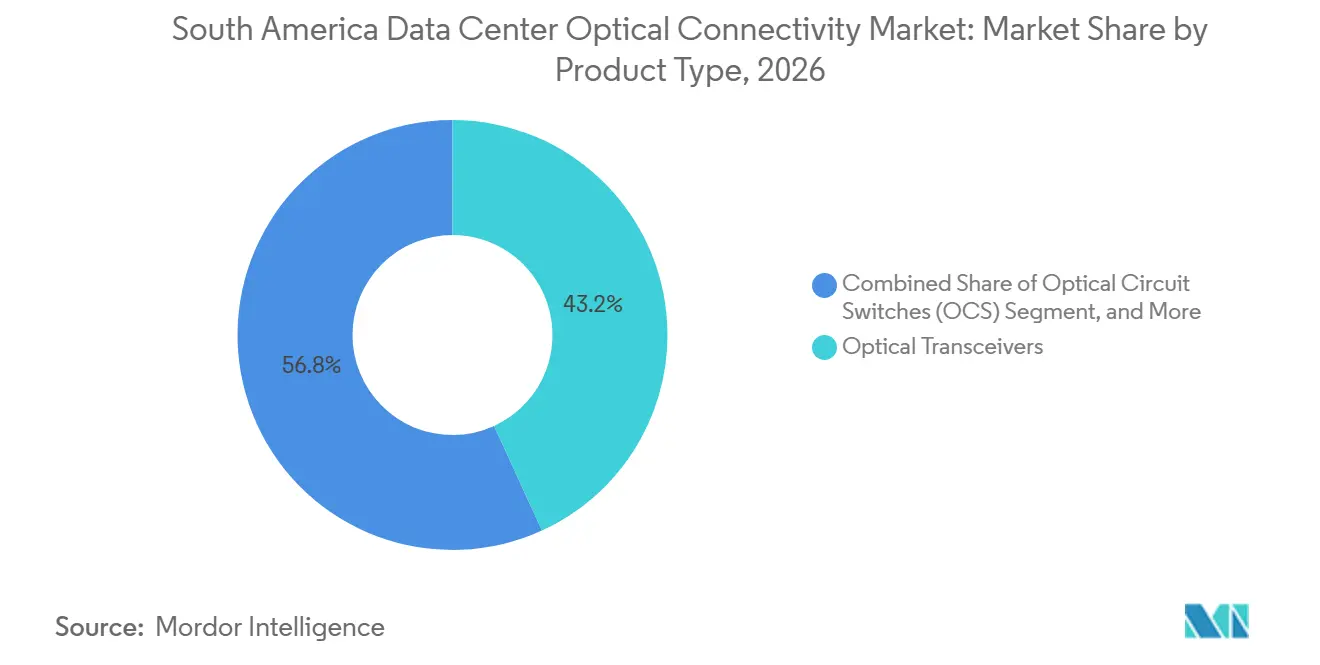
Transceivers Lead Today and Optical Circuit Switches Define the Next PhaseOptical Transceivers held 43.17% of the South America data center optical connectivity market share in 2026. They remain the standard pluggable interface for new switches and for upgrades to installed equipment. Their position reflects continuing deployment of 400G and 800G modules at hyperscale, colocation, and enterprise sites. Active Optical Cables are the second-largest product group and serve shorter links where compact routing and thermal performance matter. Fiber-optic cable assemblies, connectors, and optical interconnect assemblies form the passive layer required for each new data hall. These products are purchased alongside active modules as facilities expand or refresh network capacity.
Optical Circuit Switches are projected to expand at a 28.94% CAGR through 2032. They use a photonic path to reduce repeated optical-electrical-optical conversions in dense AI fabrics. The Open Compute Project identifies MEMS, liquid-crystal, piezoelectric, and silicon photonics approaches as relevant optical circuit switching technologies for AI infrastructure. The technology has the clearest fit in large AI campuses where power use and rack density are major design factors. Early adoption in South America should center on the largest Brazilian sites rather than broadly across all facilities. Suppliers will need to show dependable operation and integration support before optical circuit switches move beyond a limited number of high-capacity deployments.

By Connectivity Architecture:
Pluggable Optics Prevail and Co-Packaged Optics Approaches an Inflection PointConventional Pluggable Optics held 74.31% of connectivity architecture revenue in 2026. Their installed base is supported by established interfaces, module replacement practices, and supply chains. Operators can replace or upgrade pluggable modules without redesigning the switching platform. Linear Pluggable Optics and Linear Receive Optics are gaining relevance for short-reach AI links where some digital signal processing functions are unnecessary. Near-Packaged Optics offer a middle path by increasing density while retaining more modularity than fully integrated systems. This balance can appeal to operators who want greater efficiency but remain cautious about a complete architecture change.
Co-Packaged Optics are projected to expand at a 32.46% CAGR through 2032. The Optical Compute Interconnect consortium was formed by AMD, Broadcom, Meta, Microsoft, NVIDIA, and OpenAI to develop an open specification for scale-up optical interconnects. A common interface can reduce the risk of relying on one proprietary supply chain. Lumentum demonstrated a DWDM ELSFP laser module for Optical Compute Interconnect applications and targeted initial availability in the first half of 2027. Co-Packaged Optics initially fit the most advanced AI campuses, where bandwidth density outweighs the benefit of front-panel module replacement. The South America data center optical connectivity market will likely adopt it after operators establish engineering, maintenance, and procurement processes for the new architecture.
By Data Rate:
The 400 Gbps Installed Base Dominates and Above 1.6 Tbps Sets the CeilingUp to 400 Gbps held 39.61% of the data-rate segment in 2026. This range includes a large installed base across colocation, enterprise, and earlier hyperscale networks. New 400G ports still serve edge sites and smaller deployments that do not need 800G capacity. The 800 Gbps tier is receiving more attention for new AI clusters and high-density cloud fabrics. This shift allows operators to add capacity on existing fiber pairs while planning for increased thermal and power requirements. The speed mix will consequently remain varied across South American facilities through the forecast period.
Above 1.6 Tbps is projected to expand at a 30.71% CAGR through 2032. Cisco and NVIDIA introduced the Ultra-Dense Small Form Factor Pluggable at OCP Summit in October 2026, with 400 Gbps per lane in a 16-lane form factor.[3] The announcement indicates continued work on connectivity beyond the current 1.6 Tbps generation. Operators will need denser connectors, improved cable routing, and stronger thermal planning to accommodate these interfaces. South American users are expected to encounter the technology first in new facilities designed for demanding AI workloads. Availability and qualification will determine how quickly these speeds move into regional production networks.
By Reach:
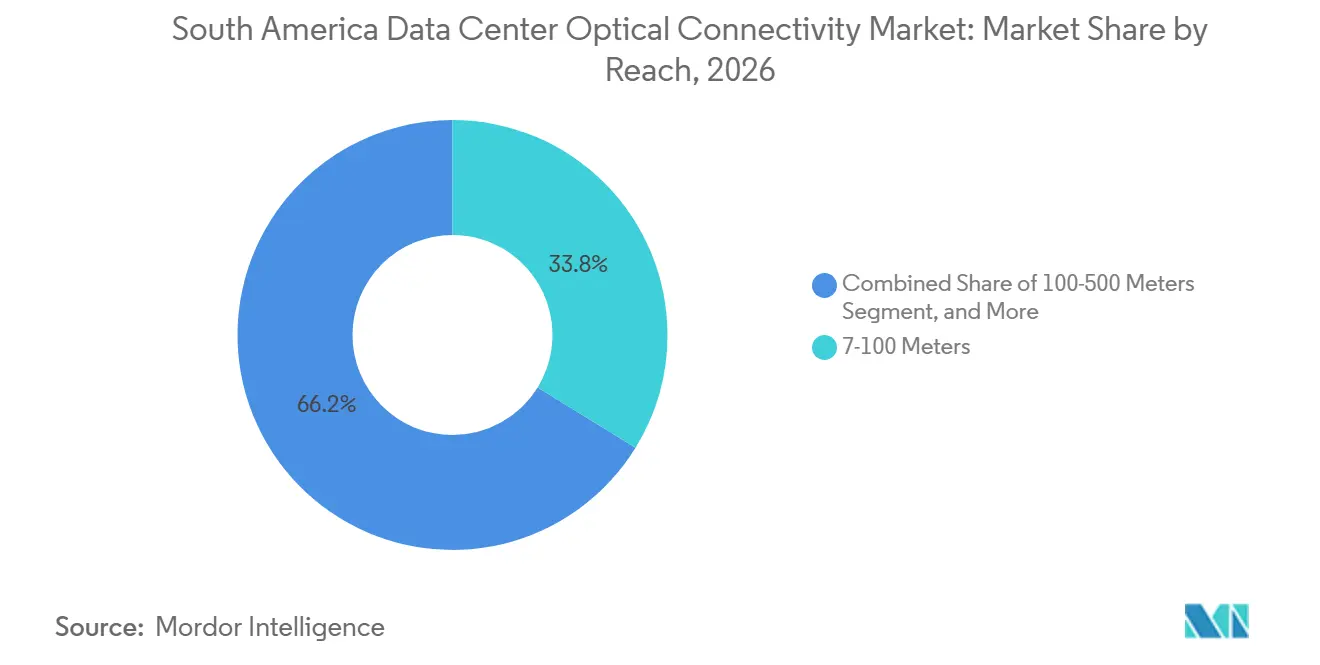
Intra-Row Links Dominate and Campus-Scale Reach Emerges with AI ArchitectureThe 7-100 Meters tier held 33.79% of revenue in 2026. It covers standard inter-row, inter-rack, and server-to-top-of-rack links used in conventional data center fabrics. Active optical cables and multimode transceivers commonly serve this distance range. Shorter categories up to 3 Meters, 3-5 Meters, and 5-7 Meters support direct-attach and board-level links inside dense racks. GPU systems increase the amount of short-distance cabling needed in a limited floor area. This makes short-reach design and cable management important to the South America data center optical connectivity market.
The 100-500 Meters tier is projected to expand at a 28.13% CAGR through 2032. It supports connections among data halls, buildings, and parts of a multi-building campus. Coherent optical products can support longer campus and metro links where additional fiber is difficult to deploy. This type of technology can be useful where additional fiber is difficult to deploy. Above 500 Meters links also matter for metro data center interconnection and connections from cable landings. The reach mix will expand as campuses and cross-border terrestrial routes become more important to regional network design.
By Application:
Switch-to-Switch Anchors the Installed Base and GPU-to-GPU Defines the Growth EdgeSwitch-to-Switch connections held 26.97% of application revenue in 2026. These links form the spine-leaf fabric that moves traffic among compute nodes in cloud and scale-out environments. Server-to-switch links and storage connectivity account for a further substantial share of intra-data center demand. Data center interconnection serves the longer links between facilities in a metropolitan area or across regions. High-capacity coherent systems support longer regional data center interconnection routes. The diversity of applications requires suppliers to support both short pluggable links and coherent transport platforms.
GPU-to-GPU interconnects are projected to expand at a 31.37% CAGR through 2032. These links are central to scale-up AI systems in which large accelerator groups exchange data at very low latency. The Optical Compute Interconnect specification is intended to support open optical scale-up connectivity for this use case. Adoption will track the rollout of AI clusters, particularly in São Paulo campuses designed around GPU workloads. These networks need higher bandwidth density than broad cloud fabrics and can require different packaging choices. The South America data center optical connectivity market can, therefore, expect application demand to shift toward a more AI-specific mix.
By Network Architecture:
Scale-Out Commands Today's Market and Scale-Up Signals the Next Infrastructure WaveScale-Out held 66.34% of network architecture revenue in 2026. It remains the prevailing model for cloud computing, content delivery, distributed applications, and AI inference. Large numbers of nodes communicate through spine-leaf fabrics, creating a substantial need for pluggable transceivers at each switch port. The architecture's position is consistent with the strong share held by Conventional Pluggable Optics. Expansion of enterprise cloud workloads and existing colocation capacity supports continued demand for this model. Its growth profile is more measured because it is already widely deployed across the regional installed base.
Scale-Up is projected to expand at a 29.64% CAGR through 2032. This architecture connects a more tightly coupled set of accelerators for AI training workloads. Its design places greater pressure on latency, bandwidth density, and power consumption than scale-out systems. Co-Packaged Optics and Optical Circuit Switches have a stronger rationale where electrical interconnect overhead constrains performance. The South America data center optical connectivity market will see scale-up adoption first at large hyperscale campuses that can invest in specialized infrastructure. Operators will balance performance benefits against the need for new operational skills and a maturing supplier ecosystem.
By Data Center Type:
Hyperscale Leads Across Both Share and Growth and Edge Expands at the PeripheryHyperscale facilities held 46.23% of the market in 2026 and are projected to expand at a 30.15% CAGR through 2032. Major investment announcements have focused on high-capacity campuses that support cloud, AI, and GPU workloads. These facilities use more optical links per megawatt than many earlier data center designs. Each AI rack can require many high-speed modules for switching and accelerator communications. This makes hyperscale projects the principal source of demand for the South America data center optical connectivity market size over the forecast period. Colocation remains important because it brings carriers, cloud providers, and enterprise customers into the same interconnection environment.
Carrier-neutral sites need high-density optical cross-connects between cages, suites, and network platforms. DE-CIX launched neutral internet exchanges in São Paulo and Rio de Janeiro in 2025 to support high-capacity traffic interconnection. Enterprise facilities are declining as workloads move toward cloud and colocation, though installed networks still need maintenance and periodic upgrades. Edge and micro data centers are an emerging source of distributed short-reach demand across Brazil. This broadens the geographic spread of optical demand even while hyperscale campuses retain the greatest share. Suppliers that address both concentrated campuses and distributed edge locations can participate across the full facility mix.
Geography Analysis
São Paulo and Fortaleza Data Center Optical Connectivity Market
Brazil held 73.57% of the South America data center optical connectivity market share in 2026 and is projected to expand at a 31.28% CAGR through 2032. São Paulo is the regional center for large campuses, with activity across Santana de Parnaíba, Osasco, Barueri, Sumaré, Vinhedo, and Franco da Rocha. Ascenty's USD 1.2 billion AI investment and Ada Infrastructure's planned BRL 2.7 billion campus investment demonstrate the concentration of high-capacity projects in this corridor. Equinix's SP6 opening further adds carrier-neutral capacity in the area. Fortaleza is also a significant cable landing location and supports demand for coherent termination and data center interconnection equipment.
Brazil and Argentina Data Center Optical Connectivity Market
Brazil's importance rests on the combined presence of hyperscale campuses, submarine cable infrastructure, and increasing AI workload deployment. Further technical infrastructure expansion by global cloud providers strengthens the case for sustained optical demand in Brazil. International vendors must also navigate local procurement, support, and compliance needs as they pursue these opportunities. Argentina holds the second-largest regional position due to cable landing infrastructure and demand around Buenos Aires. Firmina connects at Las Toninas, which sustains the relevance of optical termination and amplification systems. Macroeconomic and currency instability can make long-term equipment procurement more difficult in Argentina.
South America Data Center Optical Connectivity Market
Chile, Colombia, Peru, Uruguay, and smaller markets form a developing extension of the regional opportunity. Conecta Infra launched with a USD 350 million plan for more than 6,000 km of neutral fiber infrastructure that will connect Argentina and Chile to Brazilian data center hubs through 2028.[4] The rollout can create demand for terrestrial optical links along corridors that have received less investment. Punta del Este and Lima also gain relevance through their roles in regional cable systems and planned connectivity corridors. Santiago and Bogotá can benefit as cloud and colocation capacity extends beyond Brazil. These markets remain smaller than Brazil but add diversification to the South America data center optical connectivity market.
Competitive Landscape
The South America data center optical connectivity market is moderately fragmented in components and moderately concentrated in advanced platform technologies. Coherent, Lumentum, Ciena, Cisco, and Nokia are active in high-speed coherent optics, data center interconnection systems, and emerging photonic platforms. InnoLight and Hisense Broadband participate in non-coherent pluggable segments where price and module availability are important. Competition is strongest in the move from 800G toward 1.6 Tbps, where technical qualification and supply access carry significant weight. Vendors must demonstrate stable performance, interoperability, and support for a variety of switching environments. Regional providers Padtec and Furukawa Electric LatAm offer local manufacturing or service capabilities in passive fiber and optical networking equipment.
Platform suppliers are expanding their positions through product development and ecosystem participation. Cisco and NVIDIA announced the Ultra-Dense Small Form Factor Pluggable in October 2026 with TE Connectivity and Amphenol, extending work on high-density AI optical connections. Lumentum demonstrated a DWDM ELSFP laser module for Optical Compute Interconnect applications and expects initial availability in the first half of 2027. Broadcom and the other Optical Compute Interconnect participants are developing an open specification that can encourage multivendor supply. These actions position suppliers for scale-up AI networks as well as established pluggable deployments.
Local integration represents an important competitive capability because it can reduce deployment friction for Brazilian customers. Vendors that provide qualification, configuration, testing, and field support can help operators manage import timing and product validation. The market concentration score is 5 out of 10 because several global suppliers lead distinct high-speed technology layers, while component choices remain distributed among a wider range of vendors. The availability of open specifications may reduce dependence on a single supplier for next-generation laser and interconnect components. This creates room for specialized companies that can meet performance and manufacturing requirements. Competitive outcomes will depend on supply reliability, regional service coverage, and the ability to support the shift from conventional modules to new photonic architectures.
South America Data Center Optical Connectivity Industry Leaders
-
Cisco Systems, Inc.
-
Huawei Technologies Co., Ltd.
-
Lumentum Holdings Inc.
-
Ciena Corporation
-
Arista Networks, Inc.
- *Disclaimer: Major Players sorted in no particular order
South America Data Center Optical Connectivity Market Companies Covered in this Report
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Coherent Corp.
- Lumentum Holdings Inc.
- Broadcom Inc.
- Arista Networks, Inc.
- Ciena Corporation
- Nokia Corporation
- Telefonaktiebolaget LM Ericsson
- Intel Corporation
- Marvell Technology, Inc.
- Sumitomo Electric Industries, Ltd.
- Accelink Technologies Co., Ltd.
- InnoLight Technology (Suzhou) Ltd.
- Hisense Broadband Multimedia Technologies Co., Ltd.
- Fujitsu Optical Components Limited
- Source Photonics, Inc.
- Padtec S.A.
- Furukawa Electric LatAm S.A.
- Amphenol Corporation
- TE Connectivity Ltd.
Recent Industry Developments in South America Data Center Optical Connectivity Market
- June 2026: Ada Infrastructure broke ground on its GRU10 data center campus in Franco da Rocha, São Paulo, with a planned BRL 2.7 billion (USD 500 million) investment through 2030. The campus is designed for cloud, AI, and GPU workloads and will be served by 2 on-site substations totaling 300 MW of capacity, generating multiyear optical connectivity procurement programs.
- May 2026: Ascenty announced a USD 1.2 billion investment in 4 AI-focused hyperscale data centers across the state of São Paulo, including South America's first facility purpose-designed from the ground up for large-scale AI workloads at its Sumaré campus. Construction of certain facilities is expected to begin in Q3 2026, with first operations from Q4 2027.
- August 2025: Ciena announced that BR.Digital deployed WaveLogic 6 Extreme technology in Brazil, achieving 1.1 Tbps single-wavelength transmission over links exceeding 800 km and extending the serviceable life of existing fiber assets across BR.Digital's wholesale network.
South America Data Center Optical Connectivity Market Report Scope
The South America data center optical connectivity refers to high-speed fiber-optic components, cables, and transceivers engineered to facilitate high-bandwidth, low-latency data transmission within and between data centers across the region.
The South America Data Center Optical Connectivity Market Report is Segmented by Product Type (Optical Transceivers, Active Optical Cables, Fiber-Optic Cable Assemblies, Optical Connectors, Optical Interconnect Assemblies, and Optical Circuit Switches), Connectivity Architecture (Conventional Pluggable Optics, Linear Pluggable Optics (LPO/LRO), Near-Packaged Optics (NPO), and Co-Packaged Optics (CPO)), Data Rate (Up to 400 Gbps, 800 Gbps, 1.6 Tbps, and Above 1.6 Tbps), Reach (Up to 3 Meters, 3-5 Meters, 5-7 Meters, 7-100 Meters, 100-500 Meters, and Above 500 Meters), Application (GPU-to-Switch, GPU-to-GPU, Switch-to-Switch, Server-to-Switch, Storage Connectivity, and Data Center Interconnect), Network Architecture (Scale-Up and Scale-Out), Data Center Type (Hyperscale, Colocation, Enterprise, and Edge and Micro Data Centers), and Country (Brazil, Chile, Argentina, and Rest of South America). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Optical Transceivers |
| Active Optical Cables |
| Fiber-Optic Cable Assemblies |
| Optical Connectors |
| Optical Interconnect Assemblies |
| Optical Circuit Switches |
| Conventional Pluggable Optics |
| Linear Pluggable Optics (LPO/LRO) |
| Near-Packaged Optics (NPO) |
| Co-Packaged Optics (CPO) |
| Up to 400 Gbps |
| 800 Gbps |
| 1.6 Tbps |
| Above 1.6 Tbps |
| Up to 3 Meters |
| 3-5 Meters |
| 5-7 Meters |
| 7-100 Meters |
| 100-500 Meters |
| Above 500 Meters |
| GPU-to-Switch |
| GPU-to-GPU |
| Switch-to-Switch |
| Server-to-Switch |
| Storage Connectivity |
| Data Center Interconnect |
| Scale-Up |
| Scale-Out |
| Hyperscale |
| Colocation |
| Enterprise |
| Edge and Micro Data Centers |
| Brazil |
| Chile |
| Argentina |
| Rest of South America |
| By Product Type | Optical Transceivers |
| Active Optical Cables | |
| Fiber-Optic Cable Assemblies | |
| Optical Connectors | |
| Optical Interconnect Assemblies | |
| Optical Circuit Switches | |
| By Connectivity Architecture | Conventional Pluggable Optics |
| Linear Pluggable Optics (LPO/LRO) | |
| Near-Packaged Optics (NPO) | |
| Co-Packaged Optics (CPO) | |
| By Data Rate | Up to 400 Gbps |
| 800 Gbps | |
| 1.6 Tbps | |
| Above 1.6 Tbps | |
| By Reach | Up to 3 Meters |
| 3-5 Meters | |
| 5-7 Meters | |
| 7-100 Meters | |
| 100-500 Meters | |
| Above 500 Meters | |
| By Application | GPU-to-Switch |
| GPU-to-GPU | |
| Switch-to-Switch | |
| Server-to-Switch | |
| Storage Connectivity | |
| Data Center Interconnect | |
| By Network Architecture | Scale-Up |
| Scale-Out | |
| By Data Center Type | Hyperscale |
| Colocation | |
| Enterprise | |
| Edge and Micro Data Centers | |
| By Country | Brazil |
| Chile | |
| Argentina | |
| Rest of South America |
Key Questions Answered in the Report
What is the South America data center optical connectivity market size?
The market is projected at USD 2.78 billion in 2026, USD 3.21 billion in 2027, and USD 6.45 billion by 2032.
What CAGR is forecast for South American data center optical connectivity through 2032?
The market is projected to expand at a 14.98% CAGR from 2027 to 2032.
Which connectivity architecture is expanding fastest in the region?
Co-Packaged Optics is projected to expand at a 32.46% CAGR through 2032.
Why are AI data centers increasing demand for optical links?
AI clusters require dense GPU-to-GPU and GPU-to-switch connections with high bandwidth and low latency.
Which country is the leading destination for data center optical connectivity investment in South America?
Brazil leads with a 73.57% revenue share in 2026 and is projected to expand at a 31.28% CAGR through 2032.
Which product category leads optical connectivity demand in South American data centers?
Optical Transceivers lead with a 43.17% revenue share in 2026.