
South America Commercial Roofing Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 3.10 Billion |
| Market Size (2027) | USD 3.30 Billion |
| Market Size (2032) | USD 4.52 Billion |
| Growth Rate (2027 - 2033) | 6.50 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South America Commercial Roofing Market Analysis by Mordor Intelligence
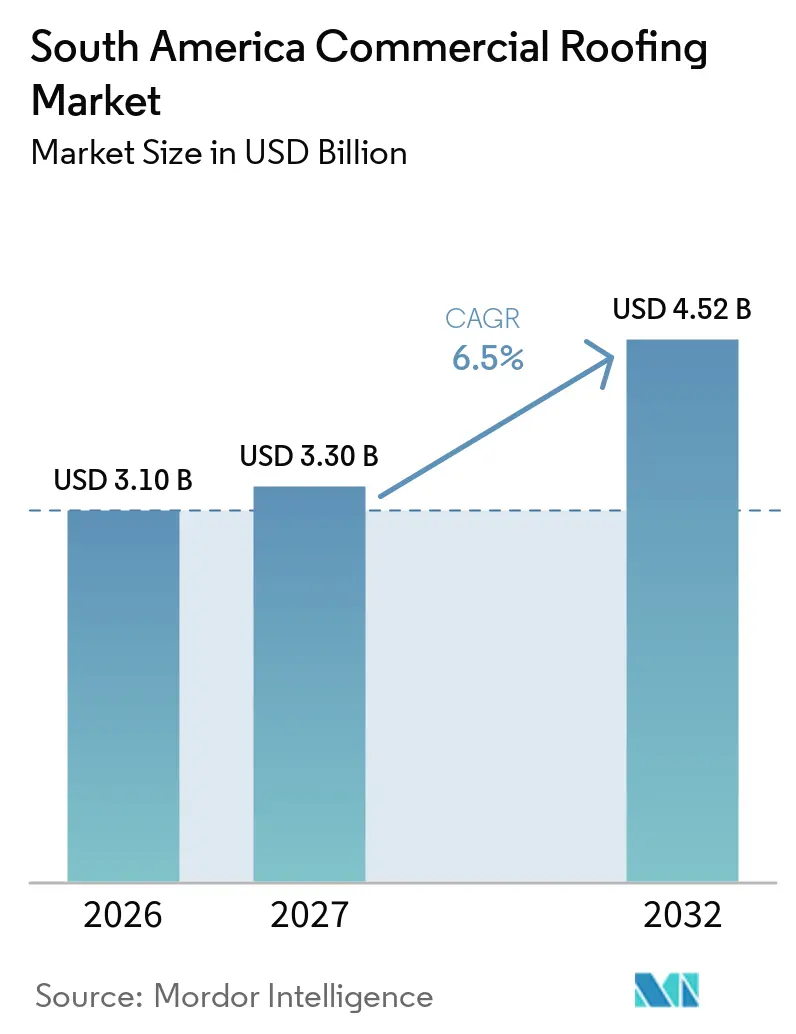
The South America Commercial Roofing Market size is expected to grow from USD 3.10 billion in 2026 to USD 3.30 billion in 2027 and is forecast to reach USD 4.52 billion by 2032 at 6.5% CAGR over 2027-2032.
The South America commercial roofing market is moving toward systems that can serve large commercial buildings, support solar equipment, and meet formal performance requirements. New logistics sites, cold-chain facilities, agribusiness processing plants, hospitals, and retail projects are widening demand for engineered roof systems. International tenants also influence material choices when their building standards call for cool roofs or solar-ready designs. Suppliers can benefit when they combine local supply, documented warranties, and trained installers. Currency pressure and costly project finance may delay some projects, but they are more likely to shift activity toward established urban markets than eliminate demand.
Key Report Takeaways
- By material type, metal roofing held 35.00% of the South America commercial roofing market share in 2026, while single-ply membranes are forecast to grow at a 7.00% CAGR through 2032.
- By construction type, new construction accounted for 55.00% of the South America commercial roofing market size in 2026 and is projected to expand at a 7.10% CAGR through 2032.
- By application, retail captured 38.00% of the South America commercial roofing market share in 2026, while industrial and logistics facilities are forecast to grow at a 7.00% CAGR through 2032.
- By geography, Brazil held 45.00% of revenue in 2026, while Colombia is forecast to grow at a 7.00% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of South America Commercial Roofing Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Nearshoring and Agribusiness Logistics Facilities | +1.8% | Brazil, Argentina, Colombia, Peru | Short term (≤ 2 years) |
| Urban Retail and Healthcare Refurbishment | +1.2% | Brazil, Colombia, Chile, Peru | Medium term (2-4 years) |
| Solar Adoption on Low-Slope Commercial Roofs | +0.9% | Chile, Brazil, Colombia, Peru | Medium term (2-4 years) |
| Domestic Steel Supply and Metal Roofing Availability | +0.8% | Brazil, Argentina | Short term (≤ 2 years) |
| Institutional Infrastructure Modernization | +0.7% | Colombia, Peru, Brazil | Medium term (2-4 years) |
| Port, Airport, and Industrial-Corridor Investment | +0.6% | Brazil, Peru, Argentina | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Nearshoring and Agribusiness Logistics Facilities
The South America commercial roofing market gains demand from logistics warehouses and food processing facilities that need broad, durable roof spans. ADN Parque Logístico opened in Ventanilla, Peru, in September 2025, with more than 280,000 square meters of modular warehouses pursuing Building Research Establishment Environmental Assessment Method certification. The project received USD 53 million in financing from IDB Invest, which described it as Peru’s first sustainable logistics complex[1]. DP World opened a multi-customer warehouse in Cajamar, Brazil, in August 2025 and expanded its contract logistics footprint to 100,000 square meters[2]. Lamb Weston also opened a USD 300 million processing facility in Mar del Plata, Argentina, in October 2025, adding a large food-sector site that requires durable building systems[3]. These projects favor suppliers that can meet the loading, hygiene, temperature-control, and installation needs of industrial facilities.
Urban Retail and Healthcare Refurbishment
Retail development and healthcare refurbishment create a separate stream of demand for the South America commercial roofing market. Colombia’s Ministry of Health confirmed USD 384 million for recovery work at Hospital San Juan de Dios in Bogotá, including 3 new hospital blocks. Hospitals need sound moisture control, ventilation coordination, and roof capacity for service equipment, which raises the importance of system quality. Retail projects also require large covered areas and predictable construction schedules. This supports materials that can be installed efficiently while giving owners a clear basis for maintenance planning.
Solar Adoption on Low-Slope Commercial Roofs
Solar deployment on low-slope roofs is changing roof selection in the South America commercial roofing market. A roof selected for solar equipment must manage heat, water, structural loads, and the interface between the membrane and mounting system. In Peru, BSF Almacenes del Perú and Kondu commissioned a 1.5 megawatt-peak photovoltaic installation with more than 2,400 panels at a logistics condominium in Lurín during December 2025. In Chile, Mallplaza Vespucio inaugurated a 1.234 megawatt-peak commercial rooftop system in May 2025 across 13,300 square meters. These projects make reflective membranes and engineered metal systems more relevant because the roof becomes part of the building’s energy plan.
Domestic Steel Supply and Metal Roofing Availability
Domestic steel availability strengthens the position of metal roofing in the South America commercial roofing market. Locally supplied metal sheets can help contractors align material procurement with demanding construction schedules. Coated steel panels are particularly suitable for large logistics, agricultural, and industrial structures because they offer wide spans and efficient installation. This availability can reduce reliance on imported polymer inputs and help suppliers compete on delivery reliability as well as material cost. The advantage is most relevant where construction schedules require timely delivery across long inland transport routes.
Restraints Impact Analysis of South America Commercial Roofing Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Currency Volatility in Imported Polymers and Equipment | -0.9% | Argentina, Brazil, Peru | Short term (≤ 2 years) |
| Limited Long-Term Project Finance | -0.7.0% | Argentina, Rest of South America | Medium term (2-4 years) |
| Uneven Enforcement of Wind and Fire Standards | -0.4% | Brazil, Colombia, Rest of South America | Medium term (2-4 years) |
| Weak Formal Roofing-Recycling Channels | -0.3% | Brazil, Argentina, Chile | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Currency Volatility in Imported Polymers and Equipment
Currency changes can make imported membrane systems more difficult to price in the South America commercial roofing market. Thermoplastic polyolefin, ethylene propylene diene monomer, and polyvinyl chloride systems depend on petrochemical inputs that are often priced in USD. A sudden local currency decline can raise delivered costs after a project budget has been approved. Contractors may then favor products with shorter supply chains or delay a final system choice. Suppliers can reduce the risk through local inventory, transparent price terms, and materials that are available within the country.
Limited Long-Term Project Finance
High borrowing costs can slow commercial construction activity and limit the specifications chosen for a project. Projects with long development periods require financing that remains viable beyond the first construction phase. Peru had USD 3.46 billion in port terminal investment commitments under public-private partnership concessions as of April 2025. Where capital markets are less developed, developers may select lower-cost roof systems even when premium systems offer a longer service life. This makes project timing and financing conditions important to the pace of the South America commercial roofing market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South America Commercial Roofing Market Segment Analysis
By Material Type:
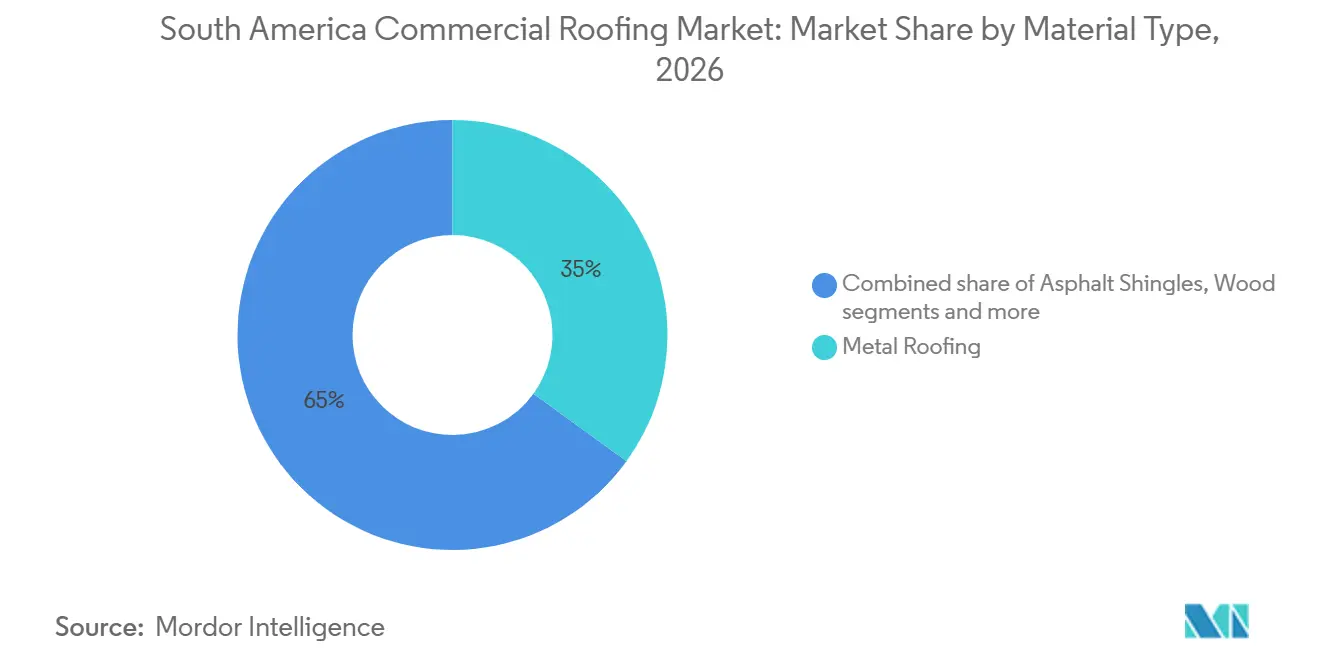
Metal Roofing Provides the Largest Base While Single-Ply Membranes Grow FasterMetal roofing held 35.00% of revenue in 2026, making it the largest material group in the South America commercial roofing market. Its position reflects cost efficiency across industrial, logistics, and agro-processing buildings that need large roof spans. Galvanized, aluminum-zinc coated, and pre-painted steel sheets are commonly selected for installation speed and structural flexibility. Brazil’s ABNT NBR 14513 and ABNT NBR 14514 standards guide the performance of profiled steel roofing sheets in commercial construction. The commercial roofing industry uses metal roofing where project schedules require practical material availability and predictable installation.
Single-ply membranes, including thermoplastic polyolefin, ethylene propylene diene monomer, and polyvinyl chloride, are forecast to grow at a 7.00% CAGR through 2032. Thermoplastic polyolefin has a reflective surface and heat-welded seams that support its use on flat commercial roofs. It can suit facilities that plan rooftop photovoltaic installations because roof and mounting compatibility can be addressed at the design stage. Ethylene propylene diene monomer remains relevant for buildings with high ultraviolet exposure and a need for long service life. Polyvinyl chloride is used where chemical resistance is important, including food processing and pharmaceutical facilities.

By Construction Type:
New Construction Leads Current Demand and GrowthNew construction represented 55.00% of revenue in 2026 and is projected to record a 7.10% CAGR through 2032. This shows that the South America commercial roofing market is supported by an expanding commercial building base rather than only replacement demand. New logistics parks, hospitals, retail complexes, and food-processing sites allow owners to select materials before occupancy. New projects also give suppliers an opportunity to secure warranties and installer relationships early in a building’s life.
Reroofing and replacement accounted for the remaining 45.00% of construction-type demand in 2026. This part of the South America commercial roofing market remains important because roof failures, weather exposure, and changing building requirements can shorten a replacement cycle. Carlisle Companies stated in its fiscal 2025 annual filing that reroofing represented 70% of its global commercial roofing business. This global measure does not define the regional mix, but it shows why replacement business can become valuable as commercial assets mature. Suppliers that install systems during the current new-build cycle can later benefit from warranty renewals, inspections, and replacement work. The developing building stock creates a long-term service opportunity alongside current construction sales.
By Application:
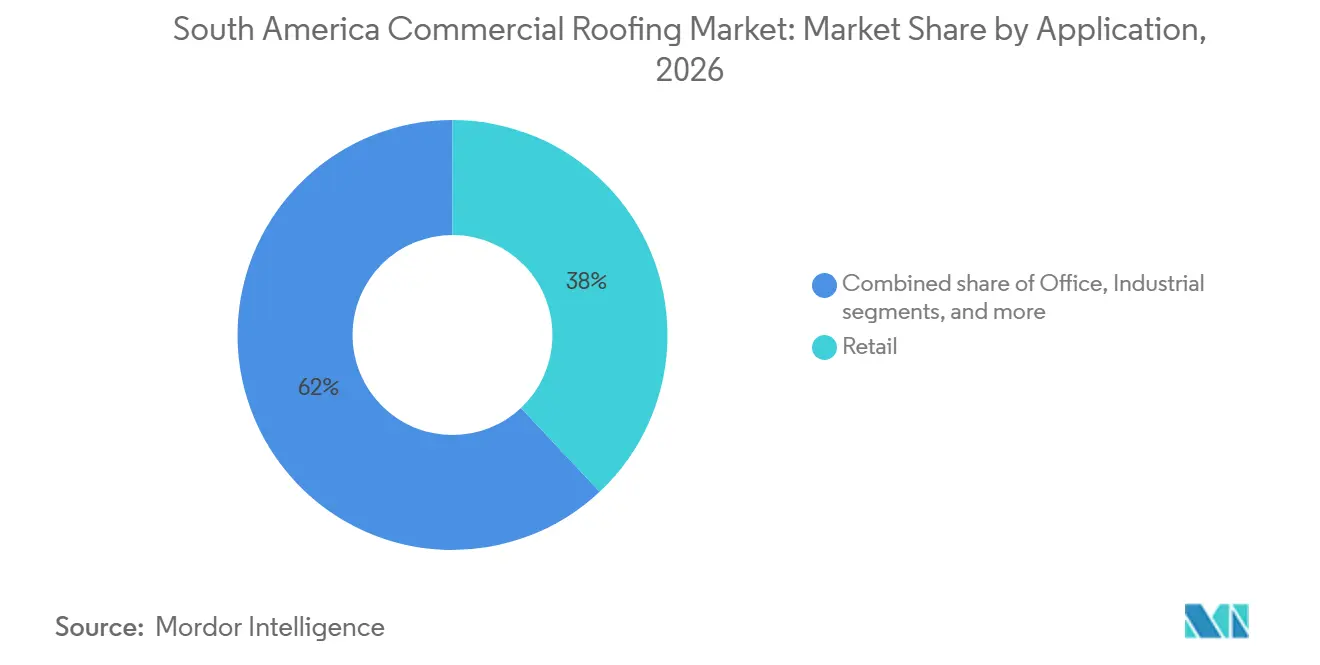
Retail Has the Largest Share While Industrial Logistics Expands FasterRetail held 38.00% of revenue in 2026, the largest application share in the South America commercial roofing market. Large-format retail buildings and mixed-use projects need broad roof coverage and often include energy efficiency requirements. Colombia, Chile, and Brazil provide demand for modern retail space and related commercial development. Office buildings form a secondary source of demand in major metropolitan areas. Hotels, education facilities, and other institutional buildings add further volume where durability can be more important than the lowest initial cost.
Industrial and logistics facilities are projected to grow at a 7.00% CAGR through 2032, the highest rate among the application groups. These buildings require roofs that can span wide bays, support thermal management, and in some cases carry solar equipment. The supplied research draft noted clear spans of 30 to 50 meters for industrial logistics structures. Colombia’s industrial gross leasable area vacancy declined 65% between 2020 and 2024, while rents increased 55.00%, according to the supplied research draft. Agribusiness logistics in Brazil and Argentina further expands the addressable base for high-performance commercial systems.
Geography Analysis
Brazil accounted for 45.00% of revenue in 2026, making it the largest country in the South America commercial roofing market. Its demand base includes port infrastructure, logistics warehouses, agro-industrial processing, retail construction, and healthcare facilities. Brazil’s Ministry of Ports and Airports reported USD 3.4 billion in port-sector investment during 2025. Port expansion creates requirements for storage sheds, distribution centers, and related industrial buildings.
Colombia is projected to record the fastest country growth at a 7.00% CAGR through 2032. Healthcare modernization, logistics expansion, and retail projects support demand across more than 1 roofing category. Peru is also becoming a material logistics and infrastructure location. Fraport’s subsidiary Lima Airport Partners opened the new Jorge Chávez International Airport terminal in May 2025 after a USD 2 billion expansion program. The terminal covers 270,000 square meters and has capacity for 40 million passengers each year.
Argentina contributes demand through agribusiness investment despite currency and financing constraints. Louis Dreyfus Company inaugurated a grain storage and port terminal in Santa Elena, Entre Ríos, in August 2025. Bolivia, Ecuador, Paraguay, and Uruguay offer smaller opportunities connected to agribusiness and cross-border logistics. Inland distribution distances and limited long-term financing constrain project conversion in these countries.
Competitive Landscape
The South America commercial roofing market is moderately consolidated at the manufacturing and system supply level. Sika, Saint-Gobain, Holcim, Kingspan, Soprema, and Carlisle compete through product breadth, factory locations, warranty programs, and approved installer networks. Local suppliers compete where they provide steel sheets, panels, or materials that meet country-specific requirements. Competition is strongest where owners require a complete system rather than a single roofing product. The South America commercial roofing market rewards suppliers that provide technical support from design through commissioning.
Manufacturing investment is one way leading suppliers reduce delivery times and build regional relevance. Sika reported the opening of a new Colombia facility in the first quarter of 2026 and referenced its new Ecuador facility that began operations in the first quarter of 2025. The facilities produce construction-related materials and expand Sika’s local supply network. Holcim completed the acquisition of a majority stake in Cementos Pacasmayo in March 2026. Holcim valued the transaction at USD 1.5 billion on a 100% basis and described it as its largest Latin American acquisition.
Portfolio depth matters as customers seek compatible waterproofing, insulation, roof, and adhesive systems. Etex announced USD 70 million in investments across Peru, Chile, and Argentina during July 2025 to expand plasterboard capacity and improve operational sustainability. These moves can make it harder for single-product suppliers to match a full building-system offer. Regional installers and local manufacturers remain important where price, immediate availability, and practical installation skills guide purchasing decisions.
South America Commercial Roofing Industry Leaders
-
Saint-Gobain
-
Sika AG
-
Holcim
-
Kingspan Group plc
-
Etex Group
- *Disclaimer: Major Players sorted in no particular order
South America Commercial Roofing Market Companies Covered in this Report
- Saint-Gobain
- Sika AG
- Holcim
- Kingspan Group plc
- Etex Group
- Soprema Group
- BlueScope Steel
- Carlisle Companies Incorporated
- GAF Materials Corporation
- Owens Corning
- Johns Manville
- IKO Industries Ltd.
- TechnoNICOL Corporation
- BMI Group
- RENOLIT SE
- Atlas Roofing Corporation
- Duro-Last Inc.
- Versico Roofing Systems
- Tremco Construction Products Group
- Firestone Building Products (Elevate)
Recent Industry Developments in South America Commercial Roofing Market
- June 2026: Geoquest signed an agreement to acquire Grupo TDM's geosynthetics division. The division produces waterproofing geomembranes and geocells at plants in Peru and Brazil. Geoquest stated that the acquired business employed 220 people and generated USD 80 million in 2025 revenue. The transaction expands Geoquest’s South American waterproofing portfolio across 6 countries.
- March 2026: Holcim completed the acquisition of a majority stake in Cementos Pacasmayo, Peru's leading building materials producer with USD 630 million in 2025 net sales. The transaction was valued at USD 1.5 billion on a 100% basis. Holcim described it as its largest Latin American acquisition to date and expected it to be earnings per share accretive from year 1. The acquisition gives the company a stronger position in Peru’s broader construction-materials supply chain.
- February 2026: Sika AG opened a production facility in Puerto Tirol, Chaco, Argentina, and a new site in Cali, Colombia. Sika stated that the sites manufacture mortars, tile adhesives, acrylic coatings, and construction admixtures. The Argentina facility is the group’s 8th plant in the country. The investments expand Sika’s ability to serve construction demand across the Andean and Southern Cone markets.
South America Commercial Roofing Market Report Scope
Segmentation Overview
| Asphalt Shingles |
| Clay & Concrete Tiles |
| Metal Roofing |
| Bituminous / Modified Bitumen Membranes |
| Single-Ply Membranes (TPO, EPDM, and PVC) |
| Wood |
| Others |
| New Construction |
| Reroofing and Replacement |
| Retail |
| Office |
| Industrial |
| Others |
| Brazil |
| Argentina |
| Chile |
| Peru |
| Colombia |
| Rest of South America |
| By Material Type | Asphalt Shingles |
| Clay & Concrete Tiles | |
| Metal Roofing | |
| Bituminous / Modified Bitumen Membranes | |
| Single-Ply Membranes (TPO, EPDM, and PVC) | |
| Wood | |
| Others | |
| By Construction Type | New Construction |
| Reroofing and Replacement | |
| By Application | Retail |
| Office | |
| Industrial | |
| Others | |
| By Countries | Brazil |
| Argentina | |
| Chile | |
| Peru | |
| Colombia | |
| Rest of South America |
Key Questions Answered in the Report
What is the projected value of South America commercial roofing by 2032?
The South America commercial roofing market is forecast to reach USD 4.52 billion by 2032, rising from USD 3.30 billion in 2027 at a 6.50% CAGR, driven by demand from logistics, retail, industrial, and institutional construction. Supplier investment in local capacity and installer support can also improve availability for complex commercial projects across the region, particularly in major logistics and urban construction corridors.
Which roofing material holds the largest share in South America?
In the South America commercial roofing market, metal roofing leads with 35.00% of revenue in 2026, supported by industrial, logistics, and agro-processing construction. Its wide-span suitability supports use in large facilities, while local material availability can help contractors manage demanding project schedules and transport needs.
Which material category is growing fastest through 2032?
Single-ply membranes are forecast to grow at a 7.00% CAGR through 2032 as solar-ready and reflective roof designs become more relevant for flat commercial buildings.
What is the largest construction type for commercial roofs?
In the South America commercial roofing market, new construction holds 55.00% of 2026 revenue and also has the highest forecast growth rate at 7.10% through 2032. New logistics and institutional projects support this position.
Which application is expected to grow fastest?
In the South America commercial roofing market, industrial and logistics facilities are forecast to expand at a 7.00% CAGR through 2032 because warehouses and temperature-controlled facilities need durable systems with broad roof spans.
Which country is growing fastest in the region?
Within the South America commercial roofing market, Colombia is forecast to record a 7.00% CAGR through 2032, supported by healthcare, logistics, and retail investment across new and refurbished facilities.