
Singapore E-commerce Market Analysis by Mordor Intelligence
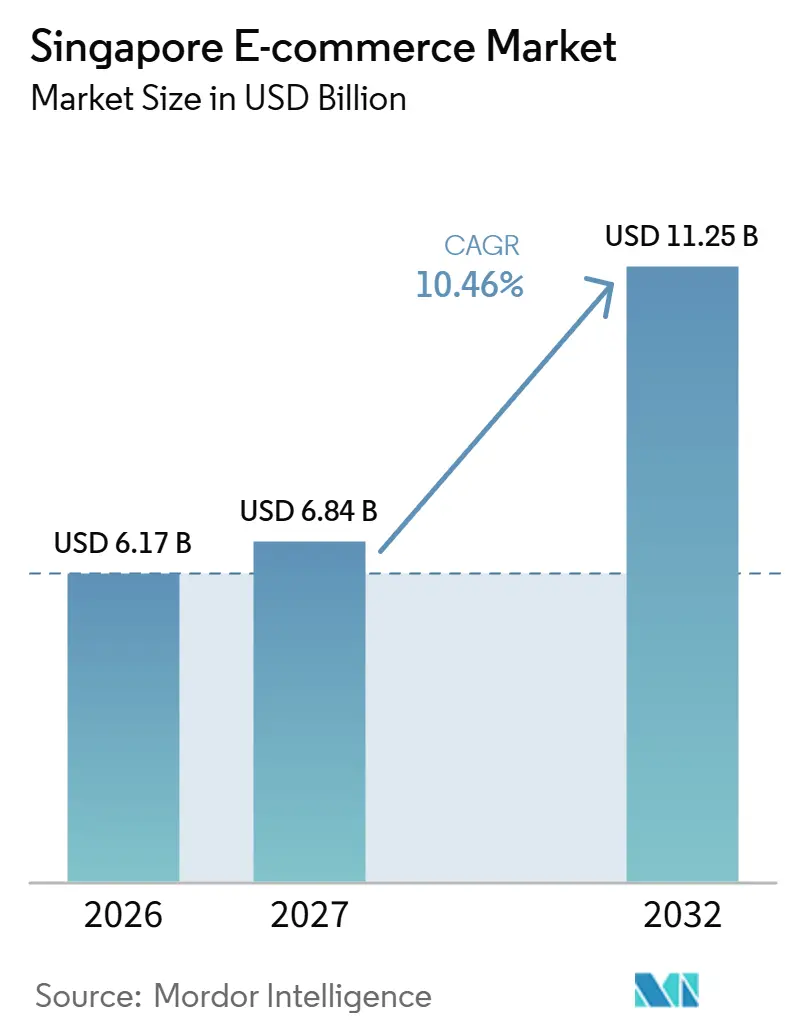
The Singapore e-commerce market size was valued at USD 6.17 billion in 2026 and estimated to grow from USD 6.84 billion in 2027 to reach USD 11.25 billion by 2032, at a CAGR of 10.46% during the forecast period (2027-2032).
In Singapore, established wallet use and repeat grocery ordering give retailers a base for developing recurring online customer relationships. Same-day fulfillment and AI-assisted livestream selling can expand the purchase occasions and presentation formats that retailers can address. Business sellers can build on electronic agreements and phased invoice connectivity to connect online orders with the wider commercial transaction. Scam risk and delivery-handoff constraints add operating friction, making reliability a commercial requirement. For grocery retailers, wallet-enabled checkout and dependable handoffs must work together if additional ordering occasions are to become repeat business.
Key Report Takeaways
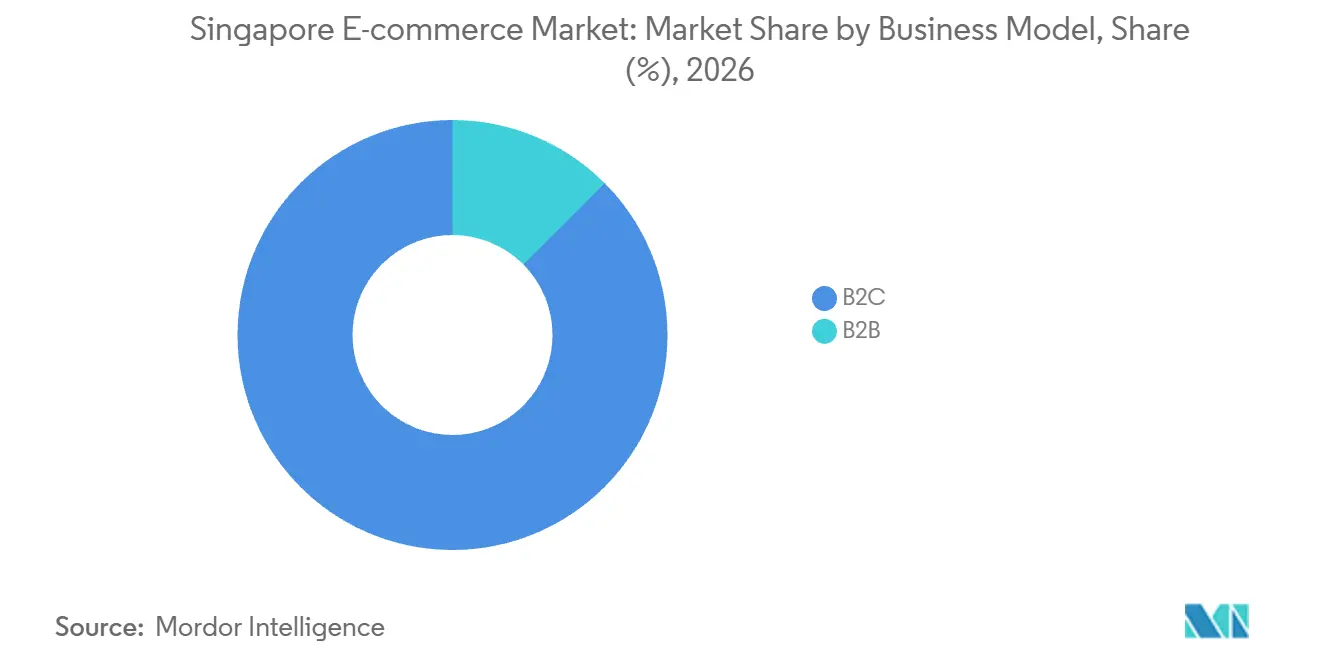
- By business model, B2C held an 87.48% Singapore e-commerce market share in 2026, while B2B is forecast to be the fastest-growing segment at a CAGR of 11.95% during 2027-2032.
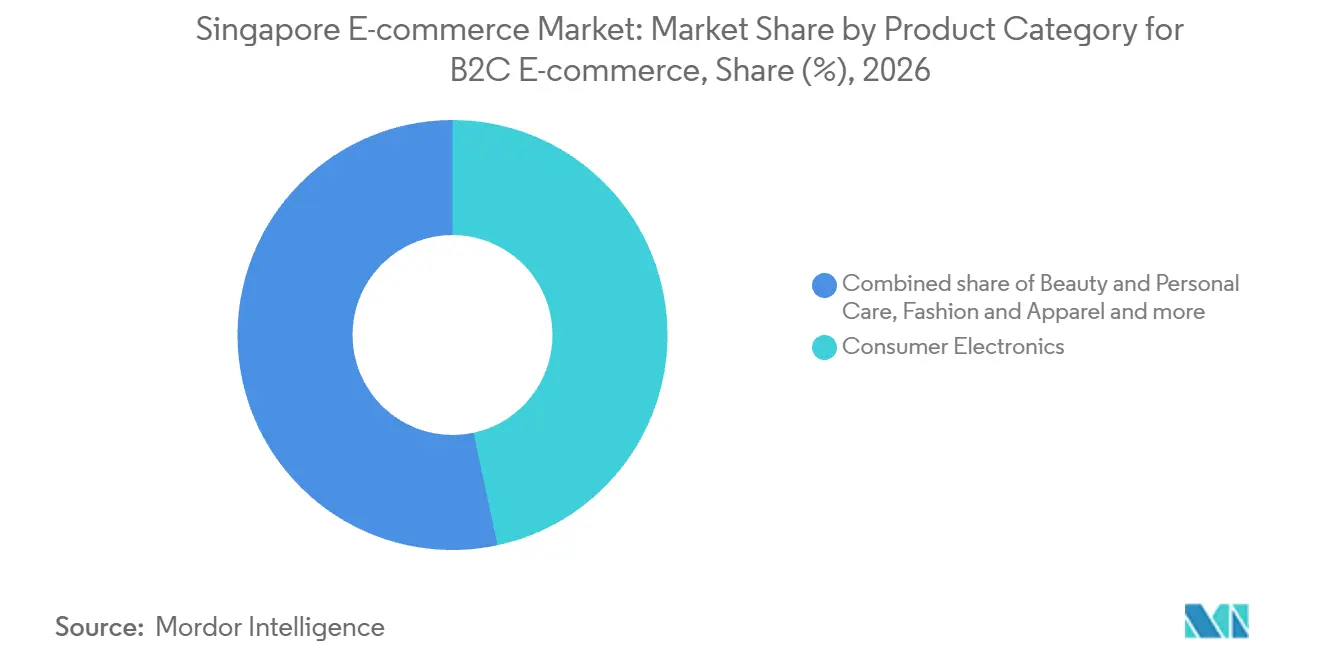
- Among B2C product categories, consumer electronics led with a 46.63% share of B2C e-commerce sales in 2026, and food and beverages are forecast to grow fastest at a CAGR of 12% during 2027-2032.
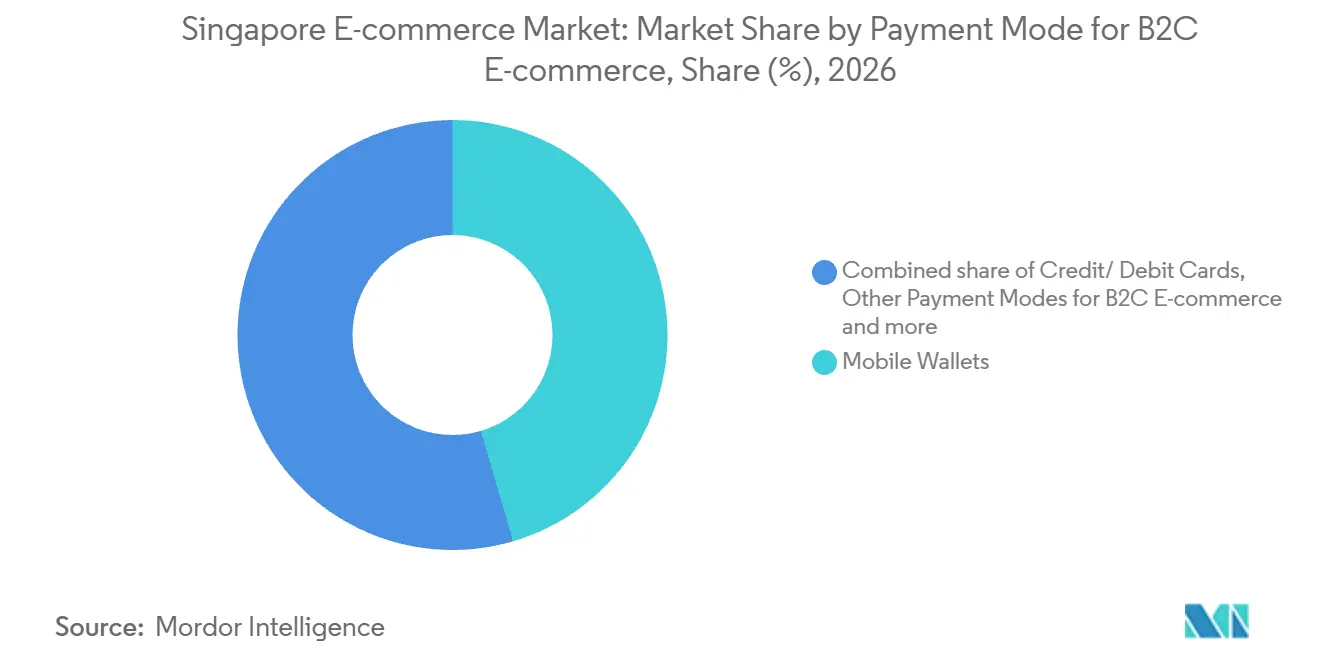
- Across B2C payment modes, mobile wallets led with 45.45% of B2C e-commerce payment value in 2026, and other payment modes are forecast to be the fastest-growing segment at a CAGR of 12% during 2027-2032.
- In the device mix, smartphones held a 78.3% share of B2C e-commerce purchase value in 2026 and are forecast to be the fastest-growing segment at a CAGR of 11.45% during 2027-2032.
- Geographically, Central Region generated the largest portion of e-commerce gross merchandise value in 2024.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Singapore E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising digital-wallet penetration | +4.4% | Nationwide | Short term (≤ 2 years) |
| Phased mandatory nationwide e-invoice adoption for GST-registered B2B firms | +1.5% | Nationwide | Long term (≥ 4 years) |
| Same-day island-wide fulfillment race | +3.4% | Central Region, North, North-East and East | Short term (≤ 2 years) |
| AI-powered live-stream commerce boom | +2.1% | Nationwide | Medium term (2-4 years) |
| Government carbon-reduction logistics grants | +0.6% | Nationwide | Medium term (2-4 years) |
| Cross-border China-Singapore free-trade corridors | +0.9% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising digital-wallet penetration
Wallet acceptance is a distribution choice as well as a checkout feature because it determines which existing payment flows a merchant can serve. Global Payments data put digital wallets at 40% of Singapore e-commerce spend in 2025. For a buyer intending to pay through a wallet, an unsupported checkout can create a choice between changing payment methods and abandoning that order. Adding wallet acceptance can therefore widen usable demand at the point of payment without relying on a separate increase in shopping interest. The near-term commercial opening is access to wallet-funded purchases already occurring online, making checkout coverage relevant before further customer recruitment.
Phased mandatory nationwide e-invoice adoption for GST-registered B2B firms
The phased e-invoicing requirement gives business sellers a defined timetable for connecting transaction records with tax reporting. Since April 1, 2026, businesses applying for voluntary GST registration have been required to submit invoice data directly to IRAS through InvoiceNow, regardless of incorporation date or business structure. Overseas entities and businesses liable to register wholly under the Reverse Charge regime are exempt. Singapore also announced that remaining GST-registered businesses would be required to submit invoice data directly to IRAS through InvoiceNow in phases from April 2028 through April 2031.[1] From April 2028, new compulsory registrants join the requirement, while existing businesses enter from lower to higher annual-supplies bands based on accounting periods ending in 2025. The scheduled widening can support B2B online sales workflows by adding counterparties able to exchange invoices digitally, with the highest band entering in April 2031.
Same-day island-wide fulfillment race
Rapid grocery fulfillment broadens the purchases that can be served online when buyers need goods within the same day. RedMart by Lazada said RedMart Now grocery-delivery orders grew by a factor of 6 from its February 2026 launch through October 2026.[2] The company also reported increasing the service’s same-day grocery-delivery capacity by 200% in 2026. These developments pair greater service use with a larger operational commitment, making fulfillment a substantive competitive investment. For grocery operators, additional capacity can accommodate time-sensitive orders that a slower delivery offer would struggle to serve.
AI-powered live-stream commerce boom
AI avatars offer an additional presentation format for brands seeking to sustain a recurring livestream selling channel. By August 2026, Singapore snack brand Irvins used AI avatars for livestream selling at least weekly. Irvins had sold through livestreams for about 2 years before starting AI experimentation, giving the activity a foundation in an established selling channel. For similar sellers, the opportunity is to extend how products are presented across recurring sessions while keeping product information and purchase steps coherent. Repeatable AI-assisted sessions can increase selling availability, with commercial value depending on whether viewers can translate the presentation into an executable online order.
Restraints Impact Analysis of Singapore E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating parcel-locker congestion | -0.6% | Nationwide | Short term (≤ 2 years) |
| Surge in e-commerce scams and compliance costs | -1.1% | Nationwide | Short term (≤ 2 years) |
| Manpower shortages in last-mile delivery | -0.5% | Nationwide | Medium term (2-4 years) |
| Data-sovereignty rules limiting cloud scaling | -0.2% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating parcel-locker congestion
Parcel-locker capacity constrains the delivery format an operator can promise to condominium residents. Shopee’s Parcel Santa guidance says SingPost first attempts delivery to the condominium locker. When that locker is full, the guidance sends parcels that fit to the letterbox and larger parcels to the doorstep instead. For that parcel, the fallback removes the locker handoff from the delivery offer.
Surge in e-commerce scams and compliance costs
Failed online purchases expose buyers to losing payment while leaving legitimate sellers with a harder trust problem. Singapore recorded 3,865 reported e-commerce scam cases in the first half of 2026, up 19.3% from the same period in 2025.[3] Victims paid for goods or services they did not receive, making delivery assurance commercially significant before payment. For marketplaces, the risk creates a need to distinguish accountable sellers without treating every completed login as proof of a safe transaction. By February 2026, Carousell had implemented stronger authentication, account suspensions and restrictions on reusing implicated Singpass credentials. Unfulfilled paid orders make payment protection an operating burden even when login controls are strengthened.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Singapore E-commerce Market Segment Analysis
By Business Model:
Consumer Scale and Electronic Business AgreementsB2C accounted for an 87.48% share of the Singapore e-commerce market size in 2026, making it the largest segment. Within retail trade, online retail sales represented an estimated 15.7% of Singapore retail trade sales in August 2026. The August estimate exceeded the 15.2% recorded in July 2026. With most retail trade sales that month made through other channels, online ordering works as an extension of existing retail businesses.
B2B is forecast to be the fastest-growing segment, at a CAGR of 11.95% during 2027-2032. Singapore’s Electronic Transactions Act supports electronic signatures for business sales and procurement agreements, subject to party choice and statutory exclusions. For buyers and suppliers choosing an eligible electronic agreement, the framework can connect online order formation with contract execution through an electronic process. For a B2B seller designing an online order flow, the practical first step is to identify which agreement types qualify for electronic signing.

By Product Category for B2C E-commerce:
Electronics Buyers and Grocery FrequencyConsumer electronics was the largest segment, accounting for 46.63% of B2C e-commerce sales in 2026. Airwallex and Statista’s January 2025 survey covered 1,000 Singapore-based shoppers who had bought internationally online in the previous 12 months. Of these respondents, 56% said they bought electronics from international sellers. For online sellers, the result identifies an electronics buyer group whose purchases connect Singapore demand with foreign supply. A Singapore electronics retailer targeting these shoppers needs a proposition that can compete with the international sellers they already use.
The food and beverages segment is forecast to be the fastest-growing segment, at a CAGR of 12% during 2027-2032. In February 2026, foodpanda reported that monthly grocery order frequency among its Singapore shoppers had increased by 7% since 2023. It also reported 8% more products in each Singapore grocery order in 2025 than in 2024. These measures point to different operating demands, as repeat ordering makes service availability relevant while larger item counts change the work attached to each basket. For a grocery operator facing both patterns, faster delivery alone would leave the additional picking and packing required by larger baskets unaddressed.
By Payment Mode for B2C E-commerce:
Wallet Reach and Alternative Payment UseMobile wallets were the largest segment, accounting for 45.45% of B2C e-commerce payment value in 2026. DBS reported more than 3 million PayLah! users in Singapore in FY2025. The wallet also powered over 60% of QR transactions in Singapore hawker centers during FY2025. The hawker-center result demonstrates wallet use in an everyday payment setting, giving online wallet checkout a familiar payment format to draw on. For an online merchant, the potential benefit is access to an established wallet audience when its checkout supports that payment method.
Other payment modes for B2C e-commerce are forecast to be the fastest-growing segment, at a CAGR of 12% during 2027-2032. Worldpay reported buy now, pay later (BNPL) payments at 3% of Singapore e-commerce transaction value in 2025. That use gives deferred payment a commercial role in online buying, creating an option for sellers whose offer can be served through payment at a later point. Credit cards were the top choice in Airwallex and Statista’s January 2025 survey of 1,000 Singapore-based shoppers who had bought internationally online in the prior 12 months. Card acceptance addresses the surveyed cross-border shoppers’ leading preference, while BNPL serves a separate payment-timing choice.
By Device:
Mobile Intent and Retailer App ChannelsThe smartphone segment accounted for 78.3% of B2C e-commerce purchase value in 2026, making it the largest segment, and is forecast to be the fastest-growing segment, at a CAGR of 11.45% during 2027-2032. Integral Ad Science’s September 2026 survey of 509 Singapore consumers found that 71.1% planned to use a mobile device most for online shopping during the 2026 holiday season. A holiday offer that cannot be completed on a mobile device would leave the preferred shopping route unavailable to that 71.1% of surveyed consumers.
By October 2025, DFI Retail Group reported more than 80,000 downloads of Guardian Singapore’s shopping app since its July 2025 launch. This gives a health and beauty retailer a dedicated mobile entry point that can be developed separately from a marketplace storefront. An owned shopping app can organize a specialist’s range within a dedicated retail journey. The commercial return from that channel depends on progressing from download acquisition to completed orders.
Geography Analysis
Central Region E-commerce Market
Central Region generated the largest portion of the Singapore e-commerce market’s gross merchandise value in 2024. RedMart Now’s February 2026 launch included selected Central Region areas among its initial grocery-delivery coverage. The grocery service offers delivery in as fast as 30 minutes. Address-level coverage, rather than a region-wide presence, sets which Central Region households a grocery service can reach.
North and North-East districts became additional grocery-delivery areas for RedMart by Lazada’s RedMart Now service when it expanded coverage there in August 2026. RedMart opened a fulfillment center on October 1, 2026, to support RedMart Now’s expansion into the East. RedMart also opened a fulfillment center in August 2026 to support the North and North-East expansion. Both regional expansions paired new delivery destinations with fulfillment infrastructure, making capacity provision part of the wider grocery offer.
West Region’s commercial context combines major economic nodes, including Jurong Lake District, Jurong Innovation District and Tuas Port. Within Jurong East, Jurong Gateway serves as Jurong Lake District’s commercial core, with office and retail uses. In the North-East, Punggol Digital District integrates business, education and community functions with retail and dining at Punggol Coast Mall and The Market Village. Lazada unit RedMart launched RedMart Now in Clementi on February 6, 2026, offering residents grocery delivery in as little as 30 minutes. Grocery sellers competing for Clementi’s urgent purchases therefore face a locally launched online delivery alternative.
Regulatory Framework and Outlook
The comparison covers the E-Commerce Code issued under the Online Criminal Harms Act and its application to the designated services Carousell, Facebook Marketplace and Facebook Business Pages. The Singapore Police Force administers the Code through its Online Criminal Harms Act (OCHA) Office. From a designated platform operator’s perspective, policy attractiveness depends on balancing transaction protection with the work required to implement account and advertising controls.
Regulatory Table of Singapore E-commerce Market
| Decision factor | Singapore national framework | Designated e-commerce services in Singapore |
|---|---|---|
| Primary authority | Singapore Police Force’s OCHA Office | Singapore Police Force’s OCHA Office |
| Key instruments or direction | E-Commerce Code under the Online Criminal Harms Act | Enhanced account-login and anti-scam advertising measures due January 31, 2027 |
| Commercial effect | Risk-calibrated seller verification and payment protection, with certain waivers possible | Implementation work for account-consent and advertising controls |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
Defined platform-protection duties support a Medium attractiveness rating for an operator able to implement the controls. The Hardening direction follows the enhanced measures issued in August 2026 and scheduled for implementation by January 31, 2027. Calibrated full or partial waivers from certain requirements can alter an operator’s obligations, but the announced transition makes account and advertising controls an implementation priority.
Value Chain Stages
The value chain compares how merchants, transaction intermediaries and logistics providers capture revenue as an online order moves toward delivery. Shopee provides a marketplace while the sales contract remains directly between buyer and seller. That separation leaves the merchant responsible for the product sale while creating distinct service-earning opportunities around payment, order preparation and distribution.
Value Chain Analysis Table of Singapore E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Merchandising and online offer creation | Direct online retailers such as Ikano Pte Ltd (IKEA Singapore) | Revenue from direct online product sales | Some IKEA products may be unavailable or store-only | Show channel availability before checkout |
| Marketplace order matching | Marketplace operators such as Shopee Singapore Private Limited and Lazada Group SA | Shopee commissions and transaction fees on successful sales, with seller-borne GST | Coordination between seller obligations and platform services | Make responsibility for each order step explicit |
| Payment acceptance | Payment processors such as Stripe | Per-transaction fees that vary by payment method | Managing method-dependent acceptance costs | Align the payment mix with transaction economics |
| Warehousing and order preparation | Warehousing and fulfillment providers such as Ninja Van and Singapore Post Limited | Fulfillment service revenue, with Ninja Van billing under agreed contracts | Risk of inconsistent marketplace-to-warehouse order records | Reconcile order records before picking |
| Distribution and delivery | Enterprise delivery providers such as Singapore Post Limited | Service revenue from enterprise distribution and delivery | Complexity of consolidating multiple warehouse flows | Choose dedicated pickup or consolidated distribution to fit the shipment flow |
| Source: Mordor Intelligence | ||||
Ninja Van’s use of partner warehouses and Singapore marketplace integrations shows why coordination can be supplied separately from warehouse ownership. For merchants using several service providers, a consistent order handoff can protect continuity between sale, preparation and delivery. Ninja Van bills for fulfillment under agreed onboarding contracts, tying its service earnings to order preparation and handling.
Competitive Landscape
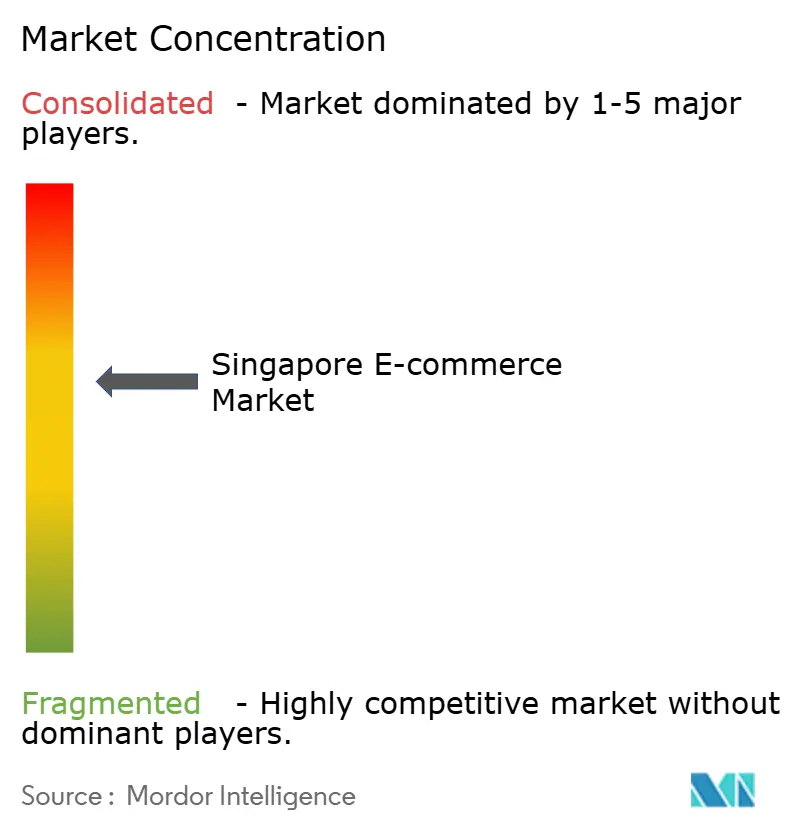
Singapore’s High Court ordered Qoo10 Pte Ltd wound up on November 11, 2024, appointing liquidators to manage the insolvent company. The exit leaves four of the five leading platform operators active. Sea Ltd (Shopee), Lazada Group SA, ByteDance Ltd (TikTok Shop) and Amazon Asia-Pacific Holdings Pte Ltd offer competing routes to online buyers. Lazada’s September 2025 Gmarket partnership made South Korean sellers’ products available to Singapore shoppers as part of a 5-country regional offer. This partnership makes access to overseas assortment a competitive asset for the platform and gives merchants a route into a local shopping relationship through an established intermediary.
In May 2026, Amazon Singapore announced an expansion of international-store selection and a decision to phase out local fulfillment, including Amazon Fresh and grocery partners. The announcement set July 6, 2026, as the start of Amazon.sg’s focus on selection from its stores in the United States, Japan and Germany. Amazon also said eligible international-store orders would offer delivery in as little as 2 days. The announced shift makes cross-border assortment and eligible delivery speed the basis for comparison with locally fulfilled grocery offers.
TikTok Shop said its active local sellers in Singapore grew 1.3 times between June 2025 and June 2026. That expansion gives seller participation a central role in competitive direction because a platform’s buyer offer depends on the merchants willing to transact through it. In the Ministry of Home Affairs’ March 2026 transaction-safety ratings, TikTok Shop, Amazon, Lazada and Shopee shared the top tier for platforms that had implemented all listed anti-scam safety features. The shared rating makes those safeguards a competitive baseline, while TikTok Shop’s seller growth signals an expansion in its merchant supply. Because the four leading platforms share the top safety tier, matching safeguards alone leaves challengers competing on merchant supply against TikTok Shop’s expanding seller base.
Singapore E-commerce Industry Leaders
-
Sea Ltd (Shopee)
-
Lazada Group SA
-
Qoo10 Pte Ltd
-
ByteDance Ltd (TikTok Shop)
-
Amazon Asia-Pacific Holdings Pte Ltd
- *Disclaimer: Major Players sorted in no particular order
Singapore E-commerce Market Companies Covered in this Report
- Sea Ltd (Shopee)
- Lazada Group SA
- Amazon Asia-Pacific Holdings Pte Ltd
- Qoo10 Pte Ltd
- ByteDance Ltd (TikTok Shop)
- Adevinta ASA (Gumtree SG)
- Carousell Pte Ltd
- FairPrice Online Pte Ltd
- RedMart Pte Ltd
- Zalora South East Asia Pte Ltd
- Shein Singapore Pte Ltd
- Elementary Innovation Pte Ltd (Temu)
- Sephora Digital SEA Pte Ltd
- iHerb LLC
- Courts Asia Ltd
- Ikano Pte Ltd (IKEA Singapore)
- Decathlon Singapore Pte Ltd
- Love, Bonito Pte Ltd
- Charles & Keith
- Apple South Asia Pte Ltd
Key Opportunities for Market Participants
These opportunities compare ways that e-marketplaces and e-retailers can improve merchant access and the conditions of online buying. Singapore’s September 2025 TR 76 guidance addresses merchant terms, listing transparency, merchant recourse and automated tools. The recommendations are voluntary guidance for these operators, with social commerce and food e-commerce supply-chain guidance outside their scope.
Market Opportunities Table of Singapore E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Merchant channel diversification | 2025 guidance recommends generally allowing cross-platform sales and avoiding unjustified service tying | Merchants seeking more than one online sales channel | Offer clear, separable listing and service terms | Coordinating product listings across channels | Merchant sellers; Shopee and Lazada |
| Transparent price and return offers | 2025 guidance recommends accurate listing prices, return policies and disclosure of additional mandatory fees | B2C online buyers comparing goods | Display item prices, additional fees and return terms before payment | Keeping seller-supplied prices and policies consistent | Buyers; marketplaces such as FairPrice |
| Merchant complaints and appeals service | 2025 guidance recommends mechanisms for merchant complaints and appeals | Sellers contesting listing or account decisions | Provide documented appeal routes and reasoned case responses | Operational effort required for individual case review | Merchant sellers; Shopee and Lazada |
| Explainable automated shopping tools | 2025 guidance recommends explainable, transparent and fair tools with legal-risk management | E-marketplaces considering automated shopping tools | Make tool-driven shopping outputs explainable and review related legal risks | Keeping explanations consistent with actual tool behavior | Platform merchants and buyers; Shopee and Lazada |
| Source: Mordor Intelligence | |||||
The central opening is a marketplace offer that combines merchant choice with clear buyer-facing terms. Cross-platform access has limited commercial value if listings or appeals become harder to manage, so the proposed plays pair access with accountable transaction practices. Automation fits this opening when its shopping outputs remain understandable to merchants and buyers.
Recent Industry Developments in Singapore E-commerce Market
- Oct 2026: RedMart by Lazada opened a fulfillment center to support RedMart Now’s grocery-delivery expansion into Singapore’s East.
- Aug 2026: The Singapore Police Force issued an enhanced E-Commerce Code for Carousell, Facebook Marketplace and Facebook Business Pages, requiring stronger consent for new or unrecognized device logins and scam-advertising safeguards by January 31, 2027. Certain requirements permit calibrated full or partial waivers.
- May 2026: Amazon Singapore announced the phase-out of local fulfillment, including Amazon Fresh and grocery partners, and set July 6, 2026, for a focus on selection from its United States, Japan and Germany stores.
Singapore E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The Singapore e-commerce market measures annual spending on goods and services bought online by businesses and consumers in Singapore. It includes business-to-business and business-to-consumer purchases. Business-to-consumer purchases are classified by product category, payment mode and device used.
Scope exclusions: Offline sales of goods and services, e-commerce platform and marketplace revenue, and payment processing revenue are excluded.
Segments Covered in This Report
- By Business Model
- B2B
- B2C
- By Product Category for B2C E-commerce
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories for B2C E-commerce
- By Payment Mode for B2C E-commerce
- Credit/ Debit Cards
- Mobile Wallets
- Other Payment Modes for B2C E-commerce
- By Device
- Smartphone
- Desktop / Laptop
- Other Device Types for B2C E-commerce
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Singapore Department of Statistics online retail series, the Inland Revenue Authority of Singapore's InvoiceNow timetable, the U.S. International Trade Administration's Singapore e-commerce guide, and IMDA digital economy material can inform online-sales trends, business digitization, market context and consumer commerce. These public sources help distinguish online retail activity from broader services revenue and provide dated indicators for Singapore-specific assumptions.
Company filings, annual reports, investor materials and reputable Singapore business press can provide company-level channel, fulfillment and transaction context for cross-checks. The named sources are not exhaustive and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
A structured interview and survey program would include Singapore online retailers, marketplace and payment providers, logistics firms, and business procurement users, with executives and functional leads able to explain transaction boundaries and operating trends. Respondents would test secondary-source assumptions and identify missing or double-counted sales. Estimates would be triangulated against public indicators and company disclosures, with unresolved gaps treated through bounded assumptions and documented analyst judgment.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 42% | Functional/Unit leaders: 35% | |
| Smaller Players: 24% | Managers: 45% |
Market-Sizing & Forecasting
A top-down model would estimate Singapore's annual online purchase spending across B2B and B2C, then use seller disclosures and sampled average order value times order volume as selective bottom-up checks. Key indicators would include online retail's share of retail sales, e-commerce revenue reported by services firms, household online spending, business digitization milestones such as InvoiceNow adoption, and platform or retailer disclosures. Each helps test a distinct demand or transaction channel. Segment shares would be built from reported category, payment and device splits, supplemented by surveys and retailer evidence, then reconciled to the relevant B2C total. Historical series and the annual forecast horizon could be modeled with regression where indicators move together, with scenario analysis for structural changes. Expert interviews would test whether chosen drivers and resulting segment paths are plausible. Missing indicators would be handled with bounded assumptions and cross-checks against observed totals. Selective supplier and channel estimates would be reconciled to avoid counting platform or payment fees as sales.
Data Validation & Update Cycle
Analysts would triangulate official statistics, company disclosures, survey evidence and independent market signals, then investigate outliers, year-to-year breaks and material variances against the prior estimate. A second review would check the transaction boundary, units, currency, segment sums and forecast assumptions before sign-off. Analysts would re-contact relevant respondents when a definition is unclear or a material contradiction remains. The model would be refreshed annually, updated between cycles after material regulatory or market events, and given a fresh pre-delivery review.
Mordor Intelligence's Singapore Ecommerce Market Size Compared With Other Published Estimates
The Singapore e-commerce market measures annual spending on goods and services bought online by businesses and consumers in Singapore. Key indicators would include online retail's share of retail sales, e-commerce revenue reported by services firms, household online spending, business digitization milestones such as InvoiceNow adoption, and platform or retailer disclosures.
Key Gap Drivers are addressed through a consistent transaction boundary, market-specific demand inputs and cross-checks across the study. Analysts would triangulate official statistics, company disclosures, survey evidence and independent market signals, then investigate outliers, year-to-year breaks and material variances against the prior estimate.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 6.84 B (2027) | |
| Commerce Analytics Firm A | USD 7.7 B (2025) | Physical-goods GMV across three named marketplaces, rather than the full online-retail universe measured by this study. |
| Commerce Data Provider B | USD 9.704 B (2025) | At its 2025 base, this estimate is 41.9% above this report's 2027 value of USD 6.8 B, 2 years later. |
Mordor Intelligence ties the estimate to the study’s defined coverage and demand model. Analysts would triangulate official statistics, company disclosures, survey evidence and independent market signals, then investigate outliers, year-to-year breaks and material variances against the prior estimate.
Key Questions Answered in the Report
What is the Singapore e-commerce market size and growth outlook?
Size was USD 6.17 billion in 2026 and is estimated at USD 6.84 billion in 2027, with USD 11.25 billion forecast for 2032 at a 10.46% CAGR during 2027-2032.
What factors support demand for online goods in Singapore?
Wallet acceptance, same-day fulfillment and AI-assisted livestreams expand the ways online goods can be bought and sold. In 2026, RedMart reported increasing RedMart Now’s same-day grocery-delivery capacity by 200%.
Which business model and B2C product category lead online commerce in Singapore?
B2C accounted for 87.48% of the industry’s value in 2026. Consumer electronics led B2C online sales with a 46.63% share in 2026.
Which companies compete for Singapore’s online shoppers?
Major competitors include Sea Ltd (Shopee), Lazada Group SA, ByteDance Ltd (TikTok Shop) and Amazon Asia-Pacific Holdings Pte Ltd.
What challenge could shape the outlook for online commerce in Singapore?
Singapore recorded 3,865 reported e-commerce scam cases in the first half of 2026, up 19.3% from the first half of 2025. Transaction protection therefore has a direct role in the sector’s commercial outlook.
Which region led e-commerce gross merchandise value in Singapore?
Central Region generated the largest portion of gross merchandise value in 2024. RedMart Now expanded into the North and North-East in August 2026.