
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 46.21 Billion |
| Market Size (2026) | USD 49.12 Billion |
| Market Size (2031) | USD 64.77 Billion |
| Growth Rate (2026 - 2031) | 5.69 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Saudi Arabia Freight and Logistics Market Analysis by Mordor Intelligence
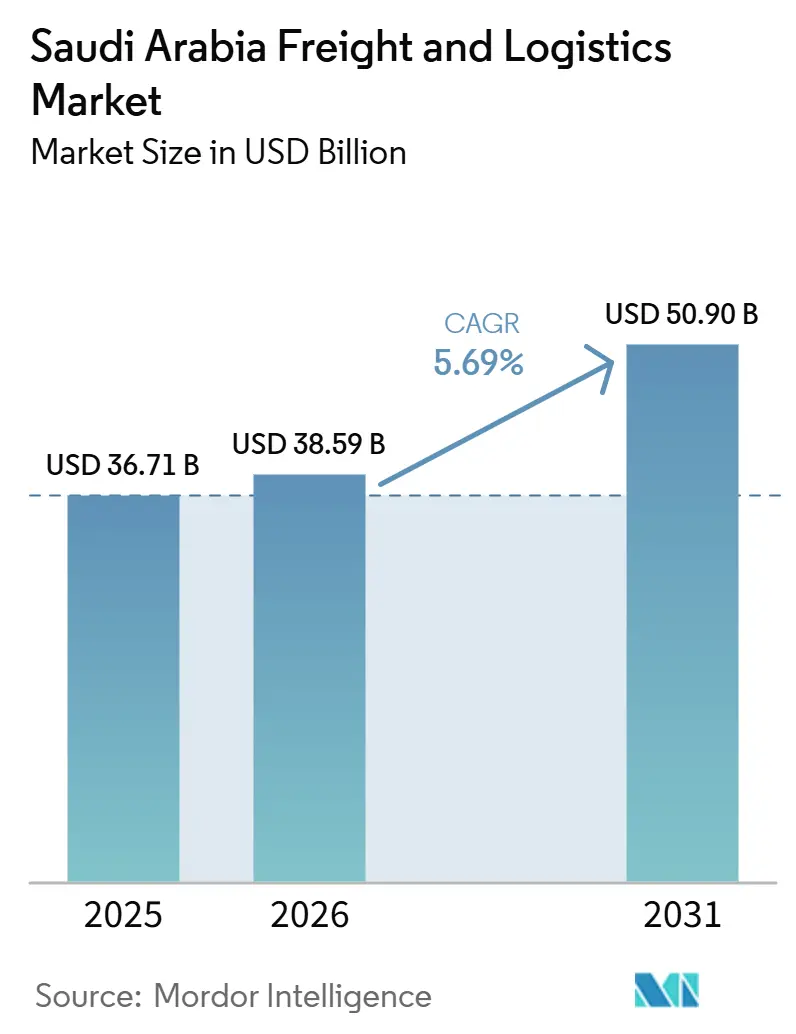
The Saudi Arabia freight and logistics market size was valued at USD 46.21 billion in 2025 and estimated to grow from USD 49.12 billion in 2026 to reach USD 64.77 billion by 2031, at a CAGR of 5.69% during the forecast period 2026-2031.
The Saudi Arabia freight and logistics market is being supported by port upgrades, logistics zone development, privatization, and investment linked to Vision 2030. Growth is increasingly tied to non-oil activity, manufacturing, e-commerce, and re-export services rather than commodity-linked volumes alone. Global logistics providers are investing alongside established domestic operators, which is raising the importance of network coverage, customs capability, and service reliability. New links between Red Sea and Gulf gateways could improve Saudi Arabia’s role in regional transit flows, while labor availability, uneven route density, and clearance processes remain operational constraints. The Saudi Arabia freight and logistics market also has opportunities in cold-chain capacity, integrated multimodal services, and technology-enabled fulfillment.
Key Report Takeaways
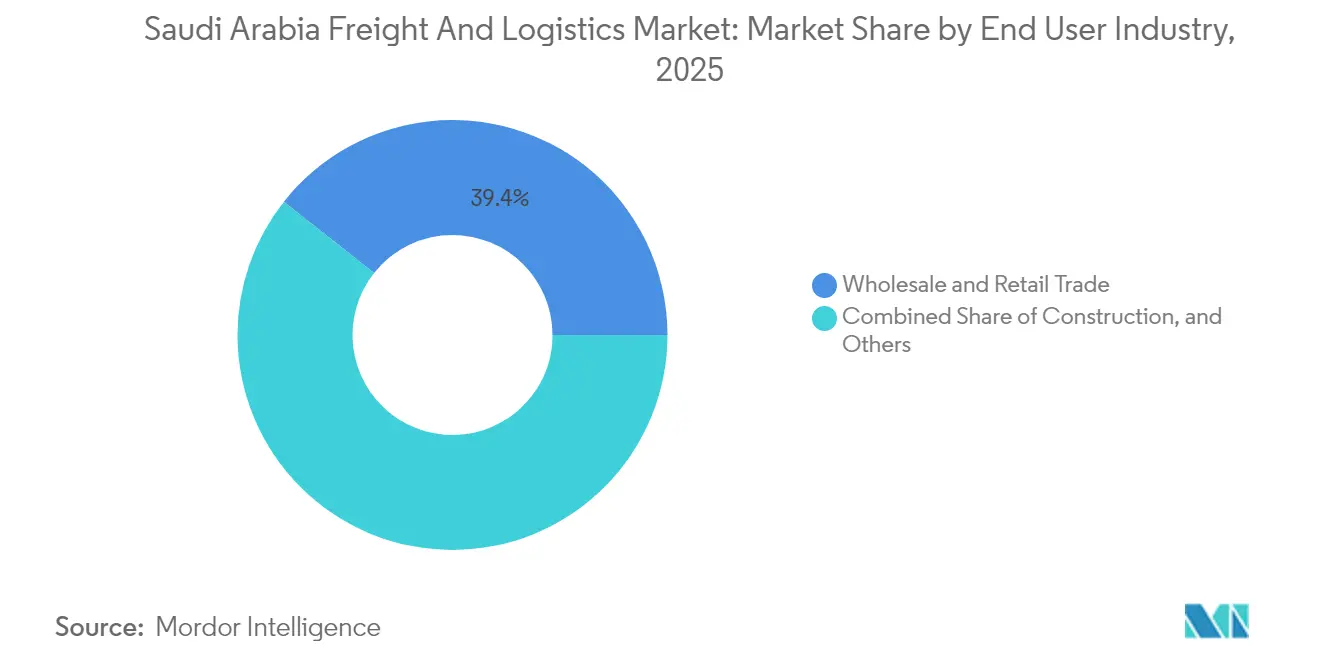
- By end-user industry, wholesale and retail trade excluding e-commerce held 35.52% of the Saudi Arabia freight and logistics market share in 2025, while e-commerce/e-retail is forecast to grow at an 8.96% CAGR through 2031.
- By logistics function, freight transport accounted for 60.19% of the Saudi Arabia freight and logistics market size in 2025, while courier, express, and parcel is forecast to expand at a 6.36% CAGR through 2031.
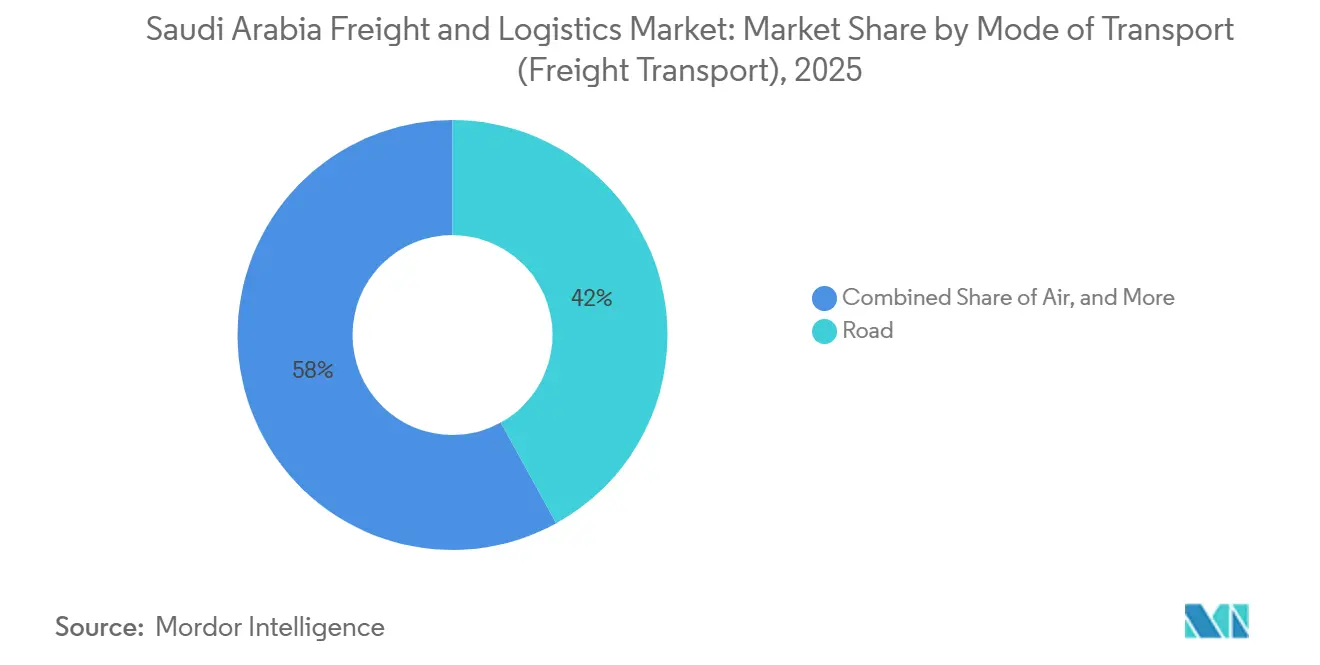
- By freight transport mode, road held 41.99% of freight transport value in 2025, while air freight is projected to grow at a 6.76% CAGR through 2031.
- By CEP destination, domestic CEP held 65.29% of CEP value in 2025, while international CEP is forecast to grow at a 6.62% CAGR through 2031.
- By warehousing temperature control, non-temperature-controlled warehousing held 77.87% of warehousing and storage value in 2025, while temperature-controlled warehousing is projected to grow at a 6.63% CAGR through 2031.
- By freight forwarding mode, sea and inland waterways held 65.12% of freight forwarding value in 2025, while air forwarding is forecast to grow at a 6.21% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Saudi Arabia Freight and Logistics Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vision 2030 Logistics Infrastructure Investment and Privatization | +1.3% | National, with concentration in Riyadh, Jeddah, and the Eastern Province | Long term (≥ 4 years) |
| Expansion of Ports, Special Economic Zones, and Logistics Parks | +0.9% | Western coast and Eastern Province, with links to the NEOM Red Sea corridor | Medium term (2-4 years) |
| E-commerce, Omnichannel Retail, and Parcel Network Expansion | +1.2% | Riyadh, Jeddah, Dammam, Makkah, and Madinah | Short term (≤ 2 years) |
| Industrial Localization, Manufacturing Growth, and Mining Development | +0.7% | Northern mineral belt, Eastern Province, and Yanbu | Long term (≥ 4 years) |
| Saudi Arabia’s Emergence as an Asia-Europe-Africa Multimodal Gateway | +0.6% | Red Sea ports, Arabian Gulf ports, and national transit routes | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Vision 2030 Logistics Infrastructure Investment and Privatization
Vision 2030 is changing how logistics infrastructure is financed and operated in Saudi Arabia. The National Transport and Logistics Strategy seeks to raise the logistics sector’s contribution to gross domestic product from 6% in 2021 to 10% by 2030.[1] This direction requires stronger service quality, wider digital adoption, and more reliable capacity, not simply new facilities. Private operators with concession commitments are likely to face clearer performance requirements than operators working mainly through public procurement. That environment may favor companies with established capital resources, compliance systems, and large customer contracts. The Saudi Arabia freight and logistics market, therefore, faces more competition for major contracts, while smaller providers may need partnerships or specialist positions to remain relevant.
Expansion of Ports, Special Economic Zones, and Logistics Parks
Port-linked logistics zones are becoming an important part of Saudi Arabia’s logistics network.[2] Their value comes from the ability to place storage, forwarding, customs activity, and cargo handling close to the port. This setup can reduce handoffs and help operators serve import, export, and re-export customers with more predictable lead times. Facilities in bonded areas may also offer a practical advantage for companies handling cross-border e-commerce and consolidation activity. The Saudi Arabia freight and logistics market is consequently placing greater value on logistics assets with customs access and direct freight connections. The need for regulated storage is also increasing, where food, pharmaceuticals, and other controlled products require documented handling conditions.[3]
E-commerce, Omnichannel Retail, and Parcel Network Expansion
E-commerce is changing delivery networks faster than most other demand sources in the Saudi Arabia freight and logistics market. Riyadh accounts for a large share of order density, which supports faster delivery economics in the capital but makes lower-density routes harder to serve profitably. Saudi e-commerce gross merchandise value exceeded USD 15 billion in 2025. Retailers and delivery firms are responding by adding dark stores, neighborhood fulfillment points, and tracking tools. These investments can improve convenience, but they also increase the fixed costs that operators need to cover through route density and repeat order volumes.
Saudi Arabia’s Emergence as an Asia-Europe-Africa Multimodal Gateway
Saudi Arabia’s location between Asia, Europe, and Africa supports its ambition to carry a larger share of regional cargo movements. The practical value of that position depends on reliable connections between Red Sea ports, Gulf ports, rail facilities, roads, and inland distribution sites. Multimodal routes can offer an alternative for cargo owners when maritime capacity or security conditions disrupt a single route. The Saudi Arabia freight and logistics market can benefit when transit flows also create demand for bonded storage, cargo consolidation, customs work, and local value-added services. These services may produce more local economic value than simple vessel calls or road transit. The opportunity may depend on consistent execution across ports, rail, border processes, and commercial agreements.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Saudization, Driver Availability, and Skilled Logistics Labor Constraints | -0.6% | National, with the greatest pressure in road freight, last-mile delivery, and warehouses | Short term (≤ 2 years) |
| High First- and Last-Mile Costs Across Low-Density and Remote Areas | -0.5% | Northern and southern provinces, rural areas, and secondary cities | Medium term (2-4 years) |
| Port Dwell-Time Variability and Cross-Agency Clearance Complexity | -0.4% | Jeddah Islamic Port, King Abdulaziz Port, and smaller regional ports | Short term (≤ 2 years) |
| Limited Rail Freight Capacity and Intermodal Equipment Availability | -0.3% | National, especially the North-South Railway and East-West corridor | Long term (≥ 4 years) |
| Geopolitical, Maritime Security, and Insurance Cost Exposure | -0.5% | Red Sea lanes, Arabian Gulf corridors, and import-dependent supply chains | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Saudization, Driver Availability, and Skilled Logistics Labor Constraints
Labor availability remains a constraint for road freight, delivery operations, customs work, and warehouse management. The issue extends beyond headcount because providers need drivers, digital operations staff, and trained personnel for regulated supply chains. Compliance obligations may protect licensed operators from informal competition, but they can also raise recruitment and training needs. The Saudi Arabia freight and logistics market is particularly exposed, where automation cannot quickly replace a driver or a trained warehouse worker. Companies with formal training programs and higher-quality operating systems may be better placed to meet these requirements. Smaller operators may face more pressure if they cannot sustain workforce development and retain skilled staff.
High First- and Last-Mile Costs Across Low-Density and Remote Areas
Saudi Arabia’s land area and uneven population distribution create a basic cost challenge for national logistics networks. Riyadh, Jeddah, and Dammam generate density, while northern, southern, and rural routes can have lower utilization and empty return trips. These conditions affect both business-to-business freight and household parcel delivery. The Saudi Arabia freight and logistics market needs broader delivery coverage, but coverage alone does not guarantee viable unit economics. Parcel lockers, pickup points, better addressing, and route optimization can reduce delivery costs, although their deployment takes time and capital. Autonomous trucking could eventually help on long intercity routes, but it is not an immediate solution for present operating constraints.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Freight Rate Intelligence
Air Freight Rate Trends
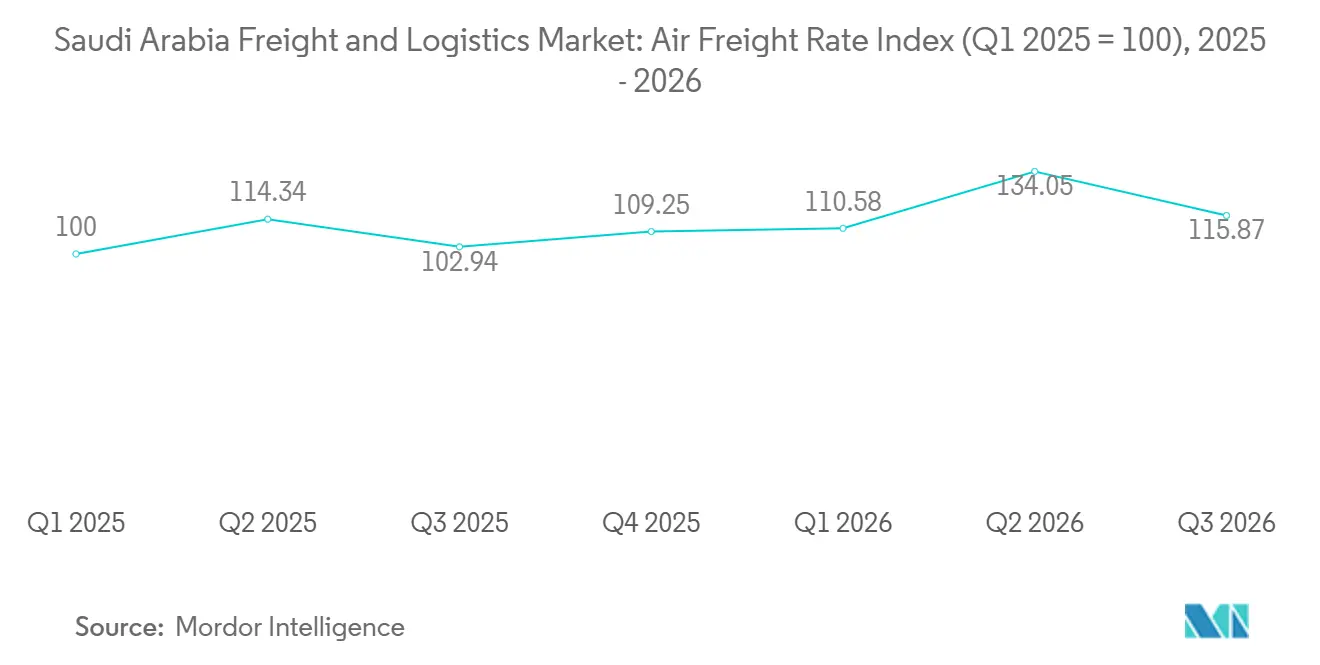
Air freight rates from King Khalid International Airport in Riyadh changed sharply between January 2025 and September 2026. European lanes reached their highest levels in March and April 2026, with Riyadh to Frankfurt reaching USD 8.3 per kg, Riyadh to London reaching USD 9.6 per kg, and Riyadh to Amsterdam reaching USD 10.8 per kg. By September 2026, the respective rates had fallen to USD 5.7, USD 6.6, and USD 6.1 per kg. The earlier peak reflected capacity constraints on Europe-bound routes, cargo repositioning, and shipments brought forward ahead of expected regulatory changes. Riyadh to New York followed a different pattern, rising to USD 17.0 per kg in June 2026 before falling to USD 11.1 per kg in September 2026. The June increase aligned with higher transatlantic demand and pressure on available belly capacity.
Regional routes also showed different pricing pressures. Riyadh to Dubai reached USD 6.5 per kg in March 2026 and declined to USD 4.2 per kg in September 2026. Riyadh to Mumbai rose to USD 8.4 per kg in June 2026 and remained at USD 7.7 per kg through July and August. Riyadh to Shanghai reached USD 7.6 per kg in June 2026 and settled at USD 5.5 per kg in September. The Saudi Arabia freight and logistics market needs flexible air capacity because short-term rate changes can affect the economics of time-sensitive shipments. Saudia Cargo’s use of demand forecasting and capacity management tools is intended to improve load planning, although the effect on contract rates may depend on wider market conditions.

Sea Freight Rate Trends
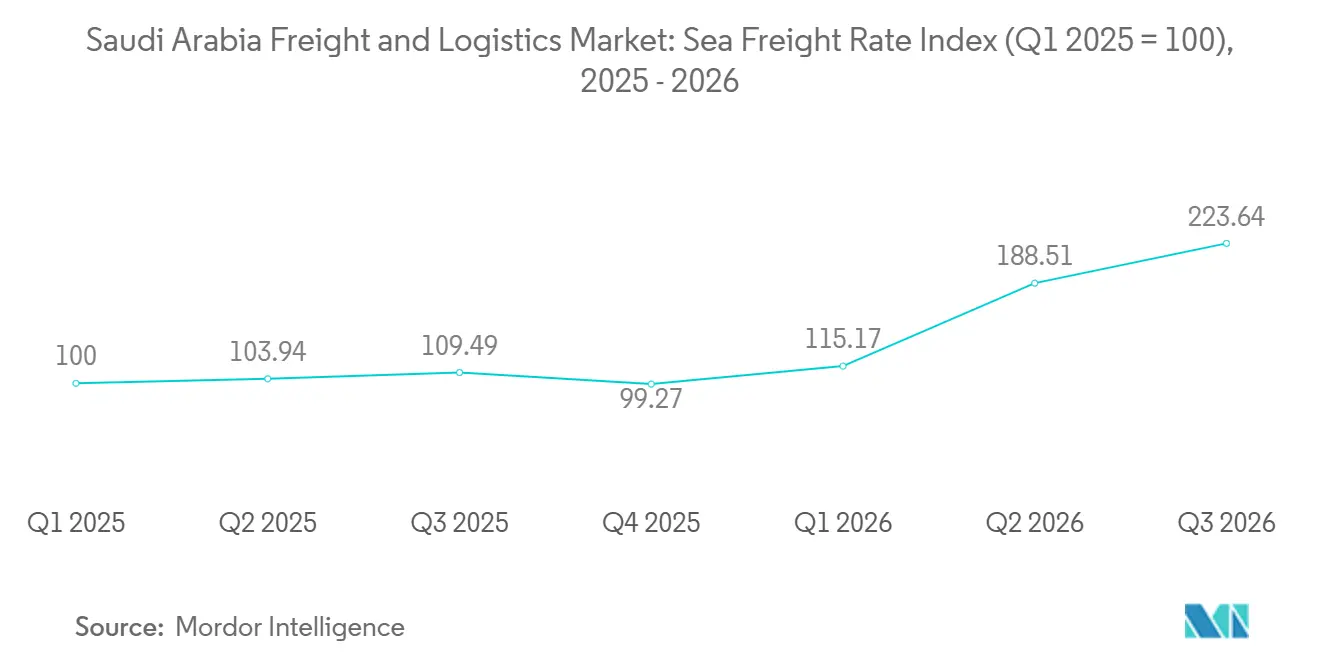
Sea freight rates on Saudi Arabia’s major trade lanes were particularly volatile between January 2025 and September 2026. The Jeddah to Jebel Ali route rose from USD 2,066 per 40-ft GP container in January 2025 to USD 20,818 in July 2026, before declining to USD 12,848 in September 2026. The Jeddah to Nhava Sheva lane rose from USD 1,504 to USD 5,015 over the same period before settling at USD 3,200 in September 2026. Security concerns and cargo rerouting affected vessel availability and pricing on these regional corridors. The Saudi Arabia freight and logistics market is exposed when short-haul lanes become more expensive than longer routes to Asia. Shippers with time-critical cargo may shift freight between sea and air when these changes persist.
Jeddah to Alexandria rates remained elevated because some vessels had to divert around the Cape of Good Hope rather than use the usual Red Sea and Suez route. The longer routing adds 10 to 14 sailing days and raises fuel costs by 25% to 35%. Jeddah to Los Angeles reached USD 9,582 per 40-ft GP container in September 2026, while Jeddah to Shanghai peaked at USD 2,385 in June 2026 before declining. Export routes from Yanbu to Tokyo and Busan were comparatively stable because mineral and petrochemical cargo flows were more predictable. These conditions make long-term capacity agreements more important for companies with regular volumes on affected routes. They also strengthen the case for forwarders that can offer alternative modes and reliable status information.
Supply Chain Risk and Resilience
Where Logistics Costs Are Rising
Logistics costs are rising due to overlapping pressure from fuel, labor, security, insurance, and compliance requirements. Road freight operators face exposure to fuel-price changes and longer routes between Riyadh, Jeddah, and the Eastern Province. Marine cargo insurance also rose on affected Gulf routes, which added pressure to the cost of container shipments. Port and terminal handling costs can further compress forwarding margins when surcharges rise faster than customer contract rates. The Saudi Arabia freight and logistics market requires operators to manage these costs without weakening service commitments. Providers with access to more than one transport mode can respond more effectively when a specific lane experiences an abrupt rate increase.
The Productivity Challenge
Automation is a practical response to simultaneous labor constraints and rising shipment volumes. Automated storage, retrieval, picking, and material-handling systems can raise throughput where customer volumes justify the investment. Port dwell-time variability can create wider supply-chain losses because delayed containers disrupt delivery schedules and inventory planning. Digital customs systems can reduce manual steps, but smaller forwarders may still face difficulty managing cross-agency requirements without specialist staff. Warehouse productivity is also affected by the mix of cargo, because pharmaceutical, cold-chain, and bonded e-commerce inventory require more documented handling than ambient goods. The Saudi Arabia freight and logistics market can improve productivity when operators combine technology with trained staff, standardized processes, and faster exception management.
The Forces Rewriting Global Supply Chains
Saudi Arabia’s logistics system is being influenced by trade-route diversification and industrial localization. Maritime disruption has increased the importance of Red Sea facilities, Gulf gateways, inland dry ports, rail links, and connecting road corridors. Industrial sites need reliable flows of raw materials, components, packaging, project equipment, and finished goods. Mining and energy projects also require specialized handling and heavy freight capacity. These requirements support specialist operators with the right fleet, storage, compliance, and customs capabilities. The Saudi Arabia freight and logistics market can capture more value when transit cargo is combined with bonded storage, consolidation, light processing, and dependable multimodal connections.
Changing Logistics Landscape
How Consumer Expectations Are Changing Logistics
Consumer delivery expectations are influencing warehouse and transport design across Saudi Arabia. Online shoppers increasingly expect clear delivery windows, order tracking, and practical options when the first delivery attempt fails. These expectations push retailers and logistics providers to position inventory closer to urban demand. Large distribution centers remain useful for national stockholding, but they cannot always meet same-day or next-day delivery needs on their own. Dark stores and local fulfillment nodes can shorten delivery distances in major cities. They also add fixed costs and need sufficient order density to operate efficiently. The Saudi Arabia freight and logistics market is, therefore, balancing centralized inventory economies with more localized customer service needs.
Winning the Last Mile
Last-mile delivery economics depend on route density, delivery success, and the handling of returns. Dense urban routes allow drivers to make multiple deliveries within a compact area. Secondary cities and rural areas are more difficult because travel distance rises while the number of stops may remain low. Pickup locations and parcel lockers can reduce the need for repeated door-to-door visits. Address quality and real-time customer communication can also improve delivery completion rates. Reverse logistics is becoming more important as online retail requires reliable returns, exchanges, inspection, and reintegration of goods. Providers that manage these activities efficiently can support merchant relationships and reduce the cost of failed deliveries.
Building the Next Generation Supply Chain
The next generation of supply-chain capability combines physical transport with timely and usable information. The Saudi Arabia freight and logistics market needs consistent data exchange across ports, carriers, warehouses, customs functions, and customers. Warehouse management systems, transport management systems, and order platforms can improve the consistency of inventory and shipment data. These tools are most effective when customers, carriers, warehouses, and customs processes can exchange information without repeated re-entry. Automation can improve throughput in high-volume facilities and can support load matching, route planning, and risk assessment in transport and customs operations. Digital maturity varies widely across the Saudi Arabia freight and logistics market, which may make it harder for smaller providers to serve higher-value contracts. Companies that link technology investment to clear operating needs can improve capacity planning, inventory control, and exception management.
Segment Analysis
By End-User Industry: E-Commerce Gains Ground on Retail Incumbency
Wholesale and retail trade excluding e-commerce held 35.52% of the Saudi Arabia freight and logistics market share in 2025. The position reflected the scale of established consumer goods distribution and traditional retail supply chains. These flows remain important to Jeddah and Dammam port activity and to domestic warehouse networks. The segment’s established scale continues to support regular replenishment, palletized distribution, and port-linked inventory management.
E-commerce/e-retail is the fastest-growing end-user segment, with an 8.96% CAGR through 2031. This difference in growth rates points to a shift toward smaller, more frequent, and more time-sensitive shipments. The Saudi Arabia freight and logistics market is, therefore, seeing more demand for inventory visibility, delivery scheduling, and returns management. Oil and gas, mining, and quarrying continue to support project cargo and heavy freight needs. Manufacturing, agriculture, fishing, and forestry add demand for industrial distribution and controlled-temperature handling. Construction, healthcare, education, and public-sector supply chains require flexible logistics support, while retail operators increasingly need omnichannel capabilities.
By Logistics Function: Freight Transport Dominates, but CEP Expands
Freight transport accounted for 60.19% of the Saudi Arabia freight and logistics market size in 2025. Its scale reflects domestic distribution requirements and the movement of imports, minerals, petrochemicals, and industrial cargo. Road transport held 41.99% of freight transport value, underlining the continuing role of trucks in national distribution. Sea and inland waterways remain central to international trade volumes. Freight transport also depends on warehousing and forwarding services to coordinate cargo across the network.
Courier, express, and parcel is projected to grow at a 6.36% CAGR through 2031. The function is being shaped by online retail, cross-border orders, and faster delivery expectations. International CEP is forecast to grow faster than domestic CEP, although domestic CEP retained 65.29% of the CEP value in 2025. The segment’s revenue growth may not always match parcel volume growth because price competition can reduce revenue per shipment. Providers must balance delivery speed with network density, automation, and disciplined pricing. Freight forwarding and warehousing continue to complement transport by coordinating shipments and holding inventory closer to demand centers.
By Freight Transport Mode: Road Anchors Volume, Air Unlocks Value
Road freight held 41.99% of freight transport value in 2025 and remains the most widely accessible mode across Saudi Arabia’s administrative regions. It links ports, industrial cities, warehouses, retailers, and remote communities. Road operators also face the greatest exposure to driver availability, fuel costs, and empty return trips. It remains essential for domestic distribution because other modes do not reach every customer location.
Air freight is projected to grow at a 6.76% CAGR through 2031. Its use is strongest where delivery speed, product integrity, or cargo value offsets higher transport costs. Pharmaceutical products, electronics, and urgent industrial shipments are important use cases. Rail can support broader intermodal use when equipment and service reliability improve, while pipelines remain important to the energy system. Sea freight provides the main connection for imported consumer goods and many export movements. Better transfers between ports, rail, roads, and inland terminals can improve customer choice during capacity shortages.
By CEP Destination: Domestic Scale, International Velocity
Domestic CEP held 65.29% of the CEP value in 2025. The segment is supported by local retail parcels, food delivery, and the established reach of Saudi Post-SPL and other national networks. Domestic volumes are concentrated in major cities, where repeated stops make delivery networks more efficient. Local coverage and existing customer relationships remain important advantages for established providers.
International CEP is forecast to grow at a 6.62% CAGR through 2031. The growth reflects cross-border e-commerce and a larger role for Saudi Arabia in re-export logistics. International parcels require stronger customs documentation, labeling controls, and handoffs between carriers.[4] Global companies can use partnerships or equity investments to access domestic delivery networks without duplicating every local asset. Domestic firms retain advantages in local coverage, address knowledge, and relationships with public-sector entities. The Saudi Arabia freight and logistics market is likely to reward CEP providers that combine local density with dependable cross-border processing.
By Warehousing Temperature Control: Cold Chain Moves to the Center
Non-temperature-controlled warehousing held 77.87% of warehousing and storage value in 2025. Ambient facilities still serve the broadest set of consumers, construction, and industrial goods. This type of storage remains essential for high-volume products that do not require controlled conditions. Its broad customer base keeps it central to the warehouse network.
Temperature-controlled warehousing is projected to grow at a 6.63% CAGR through 2031. Its growth is tied to food security, pharmaceutical distribution, dairy, poultry, online grocery, and quick-commerce operations. This segment requires documented temperature integrity and trained handling procedures, creating higher entry barriers than standard storage. LogiPoint began construction of a 12,000 m² Grade A temperature-controlled facility in Jeddah in June 2026. ASMO also began work on a 1.4 million m² logistics site in the Eastern Province in May 2026 to serve energy and manufacturing-related needs. The Saudi Arabia freight and logistics market has an opportunity to develop more specialized storage where certified capacity remains limited.
By Freight Forwarding Mode: Sea Dominates, Air Accelerates
Sea and inland waterways held 65.12% of the freight forwarding value in 2025. This position reflects the importance of maritime imports for food, consumer goods, and industrial inputs. Forwarders use sea-based networks to coordinate large container volumes and related port services. Land-border forwarding also remains relevant for trade with nearby GCC countries and Jordan.
Air forwarding is projected to grow at a 6.21% CAGR through 2031. It supports shipments where speed and handling quality have greater value than the cost of transport. Pharmaceuticals, electronics, and cross-border e-commerce returns are among the relevant cargo types. A.P. Moller-Maersk opened a 225,000 m² logistics park at Jeddah Islamic Port, supported by a USD 250 million investment. The facility combines port-side warehousing, distribution, and container-yard functions. Forwarders increasingly need customs capability and transparent status information across multimodal handoffs.
Geography Analysis
The Western Region is a major logistics area because Jeddah Islamic Port handles a significant share of Saudi Arabia’s seaborne imports. The region connects import cargo to the country’s largest consumption centers and to Red Sea trade routes. Jeddah’s logistics assets are also relevant for warehousing, re-export services, and controlled-temperature distribution. The Saudi Arabia freight and logistics market share associated with western gateways is reinforced by established port-side infrastructure. Yanbu serves specialized petrochemical and energy logistics needs. Port of NEOM is developing as an additional Red Sea node for container, manufacturing, and multimodal activity.
The Central Region is led by Riyadh, which combines national consumption demand with a growing role in logistics operations. Riyadh generates a large share of online order volumes and needs dense fulfillment and delivery networks. The Special Integrated Logistics Zone near King Khalid International Airport supports bonded logistics and air cargo connections. DHL Supply Chain committed EUR 130 million (USD 152.92 million) to develop a regional logistics and distribution hub within SILZ, with construction scheduled to begin in 2026. Riyadh Dry Port also has a role in connecting inland distribution to rail and port corridors. Its central location can support delivery to the wider Najd area and northern regions.
The Eastern Province is a key freight base for energy, petrochemicals, manufacturing, and Arabian Gulf trade. Dammam, Jubail, and Ras Al Khair connect industrial customers to ports, rail links, and specialized logistics sites. The Dammam Integrated Logistics Zone and the ASMO development at King Salman Energy Park show continued investment in industrial logistics capacity. The Northern Region has strategic importance for mineral freight, including traffic linked to the North-South Railway. The Southern Region has lower freight density but is gaining relevance through Jizan port and industrial activity. The Saudi Arabia freight and logistics market may need stronger links between these regional nodes if it is to provide dependable national coverage.
Competitive Landscape
Market Structure and Competitive Positioning
The Saudi Arabia freight and logistics market contains large global integrators, domestic conglomerates, regional providers, and many smaller operators. The largest companies have an advantage where they control port-side sites, bonded capacity, broad transport networks, or major customer contracts. DHL Group, A.P. Moller-Maersk, CMA CGM, and DSV have expanded their strategic positioning through investments and network development. Domestic groups, including Almajdouie, Bahri, Saudi Post-SPL, and Zahid Group, have established local operating experience and access to national customer relationships. Competition remains fragmented in road freight, domestic CEP, and standard warehousing. Price competition is particularly strong where services are easy for customers to compare.
Specialized Capabilities and Technology-Led Competition
Large providers are using infrastructure-led strategies to secure longer-term customer relationships. Maersk’s Jeddah logistics park brought port-side warehousing, distribution, and container handling into 1 operation. DHL eCommerce completed a minority investment in Saudi-based AJEX Logistics Services to strengthen its access to local parcel delivery capacity. JINGDONG Property announced a warehousing partnership with the Saudi Ports Authority in December 2025. These moves show that providers are seeking assets and partnerships that strengthen customs access, network density, and control over cargo flows.
Fulfillment Evolution and Strategic Differentiation
Digital tools are also becoming more important in last-mile delivery, freight matching, warehouse management, and shipment visibility. iMile Delivery Services, TruKKer, and AJEX compete through technology platforms and flexible network models, while larger providers are also investing in digital systems. Cold-chain logistics is a potential area of differentiation because certified facilities require specialized assets and operating discipline. Companies serving pharmaceuticals, food, and high-value goods can earn stronger positions when they meet the relevant handling requirements. Consolidation may increase in CEP and specialized warehousing, while local road freight is likely to remain more fragmented.
Saudi Arabia Freight and Logistics Industry Leaders
-
Almajdouie Group
-
Bahri
-
A.P. Moller-Maersk
-
Aramex
-
DHL Group
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: Saudi Ports Authority (Mawani) signed a partnership agreement with Dubai-based DP World and Red Sea Gateway Terminal for a SAR 641 million (USD 170 million) investment to expand cargo handling capacity at Jeddah Islamic Port.
- April 2026: Saudi Arabia Railways (SAR), Saudi Ports Authority (Mawani), and Bahri (National Shipping Company) launched an integrated multimodal logistics service that combines rail freight, port handling, and national shipping into a seamless cargo-movement solution. The first phase involves transporting over 45,000 tons of DAP (diammonium phosphate fertilizer inputs) via specialized containers from Ras Al-Khair to the Hail cargo yard.
- February 2026: ASMO (a joint venture between Saudi Aramco and DHL Supply Chain) signed a forward-funded development agreement with Bahrain-based Arcapita for a purpose-built 1.4 million m² logistics hub at King Salman Energy Park (SPARK) in the Eastern Province.
- February 2026: MEDLOG (MSC) officially inaugurated MEDLOG 1, a state-of-the-art integrated logistics park at King Abdulaziz Port in Dammam. The facility spans more than 100,000 m² and provides an annual handling capacity exceeding 300,000 TEUs, significantly strengthening MEDLOG's integrated logistics capability in the Kingdom.
Saudi Arabia Freight and Logistics Market Report Scope
By End-User Industry
| Agriculture, Fishing, and Forestry |
| Construction |
| Manufacturing |
| Oil and Gas, Mining, and Quarrying |
| Wholesale and Retail Trade |
| Others |
By Logistics Function
| Courier, Express, and Parcel (CEP) | Domestic CEP |
| International CEP | |
| Freight Forwarding | Air Freight Forwarding |
| Sea and Inland Waterways Freight Forwarding | |
| Other Modes of Freight Forwarding | |
| Freight Transport | Air Freight Transport |
| Pipeline Transport | |
| Rail Freight Transport | |
| Road Freight Transport | |
| Sea and Inland Waterways Freight Transport | |
| Warehousing and Storage | Non-Temperature-Controlled Warehousing |
| Temperature-Controlled Warehousing | |
| Other Logistics Services |
| By End-User Industry | Agriculture, Fishing, and Forestry | |
| Construction | ||
| Manufacturing | ||
| Oil and Gas, Mining, and Quarrying | ||
| Wholesale and Retail Trade | ||
| Others | ||
| By Logistics Function | Courier, Express, and Parcel (CEP) | Domestic CEP |
| International CEP | ||
| Freight Forwarding | Air Freight Forwarding | |
| Sea and Inland Waterways Freight Forwarding | ||
| Other Modes of Freight Forwarding | ||
| Freight Transport | Air Freight Transport | |
| Pipeline Transport | ||
| Rail Freight Transport | ||
| Road Freight Transport | ||
| Sea and Inland Waterways Freight Transport | ||
| Warehousing and Storage | Non-Temperature-Controlled Warehousing | |
| Temperature-Controlled Warehousing | ||
| Other Logistics Services | ||
Market Definition
- Agriculture, Fishing, and Forestry (AFF) - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the AFF industry players. The end user players considered are the establishments primarily engaged in growing crops, raising animals, harvesting timber, harvesting fish & other animals from their natural habitats and providing related support activities. Herein, Logistics Service Providers (LSPs) play a crucial role in acquisition, storage, handling, transportation, and distribution activities for the optimal & continuous flow of inputs (seeds, pesticides, fertilizers, equipment, and water) from manufacturers or suppliers to the producers and smooth flow of output (produce, agro-goods) to distributors/ consumers. This includes both termperature controlled and non-temperature controlled logistics, as and when required according to the shelf life of goods being transported or stored.
- Construction - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the construction industry players. The end user players considered are the establishments primarily engaged in constructing, repairing and renovating residential & commercial buildings, infrastructure, engineering works, subdividing and developing land. Logistics Service Providers (LSPs) play a crucial role in increasing profitability of construction projects by maintaing the inventory of raw materials & equipment, time-critical supplies and by providing other value added services for effective project management.
- Courier, Express, and Parcel - The Courier, Express, and Parcel services, often called as CEP Market, refers to the logistics and postal service providers which specialize in moving small goods (parcels/packages). It captures the overall market size (USD) and market volume (number of parcels) of (1) the shipments/parcels/packages which are under 70kgs/ 154lbs weight, (2) Business Customer packages viz. Business-to-Business (B2B) & Business-to-Consumer (B2C) as well as private customer packages (C2C), (3) non-express parcel delivery services (Standard and Deferred) as well as express parcel delivery services (Day-Definite-Express and Time-Definite-Express), (4) domestic as well as international parcels.
- Demographics - To analyse total addressable market demand, population growth & forecasts have been studied and presented in this industry trend. It represents population distribution across categories like gender (male/female), development area (urban/rural), major cities among other key parameters like population density and final consumption expenditure (growth and share % of GDP). This data has been used for assessing the fluctations in demand & consumption expenditure, and the major hotspots (cities) of potential demand.
- Export Trends and Import Trends - Overall logistics performance of an economy is positively and significantly (statistically) correlated to its trade performance (exports and imports). Hence, in this industry trend, total value of trade, major commodities/ commodity groups and the major trade partners, for the studied geography (country or region as per the scope of report) have been analysed alongside the impact of major trade/logistics infrastructure investments & regulatory environment.
- Freight Forwarding - Freight forwarding which herein refers to the freight transportation arrangement (FTA) industry includes establishments primarily engaged in arranging & tracking transportation of freight between shippers and carriers. Logistics Service Providers (LSPs) considered are freight forwarders, NVOCCs, custom brokers and marine shipping agents. Others segment under Freight Forwarding captures the revenue earned through value added services of FTA like custom brokerage/clearance activities, preparation of freight related documentation, consolidation-deconsolidation of goods, cargo insurance & compliance, arrangement of warehousing & storage, liasing with shippers, and freight forwarding through other modes of transport viz. road and rail.
- Freight Pricing Trends - Freight pricing by mode of transport (USD/tonkm), over the review period, has been presented in this industry trend. The data has been used in assessing the inflationary environment, impact on trade, freight turnover (tonkm), freight and logistics market demand by mode of transport segments and hence the overall freight and logistics market size.
- Freight Tonnage Trends - Freight tonnage (weight of goods in tons) handled by mode of transport, over the review period, has been presented in this industry trend. The data has been used as one of the parameters apart from average distance per shipment (km), freight volume (tonkm), and freight pricing (USD/tonkm) to assess the freight transport market size.
- Freight Transport - Freight Transport refers to the hiring of a logistics service provider (outsourced logistics) for the transport of commodities (raw materials/final/intermediate/finished goods including both solids and fluids) from the origin to a destination within the country (domestic) or cross-border (international).
- Freight and Logistics - External expenditure on (or outsourced) facilitation of freight transport (freight transportation), arrangement of freight transport through an agent (freight forwarding), warehousing and storage (temperature controlled or non-temperature controlled), CEP (domestic or international courier, express and parcel) and other value-added logistics services involved in the transportation of commodities (raw materials or finished goods including both solids and fluids) from the origin to a destination within the country (domestic) or cross-border (international), through one or more modes of transportation viz. road, rail, sea, air and pipelines constitute freight and logistics market.
- Fuel Price - Fuel price spikes can cause delays and diruption for logistics service providers (LSPs), while drops in the same can result in higher short-term profitability and increased market rivalry to offer consumers with the best deals. Hence, the fuel price variations have been studied over the review period and presented along with the causes as well as market impacts.
- GDP Distribution by Economic Activity - Nominal Gross Domestic Product and distribution of the same, across major economic sectors in the geography studied (country or region as per scope of the report) have been studied and presented in this industry trend. As GDP is positively related to the profitability and growth of logistics industry, this data has been used in adjunction to the input-output tables/ supply-use tables for analyzing the potential major contributing sectors towards the logistics demand.
- GDP Growth by Economic Activity - Growth of Nominal Gross Domestic Product across major economic sectors, for the geography studied (country or region as per scope of the report) have been presented in this industry trend. This data has been utilized for assessing the growth of logistics demand from all the market end users (economic sectors considered here).
- Inflation - Variations in both Wholesale Price Inflation (YoY change in producer price index) and Consumer Price Inflation have been presented in this industry trend. This data has been used to assess the inflationary environment as it plays a vital role in smooth functioning of the supply chain, directly impacting the logistics operational cost components e.g., pricing of tyres, driver wages & benefits, energy/fuel prices, maintenace costs, toll charges, warehousing rents, custom brokerage, forwarding rates, courier rates etc. hence impacting the overall freight and logistics market.
- Infrastructure - As infrastructure plays a vital role in an economy's logistics performance, variables like length of roads, distribution of road length by surface category (paved v/s unpaved), distribution of road length by road classification (expressways v/s highways v/s other roads), rail length, volume of containers handled by major ports and tonnage handled by major airports have been analysed and presented in this industry trend.
- Key Industry Trends - The report section named "Key Industry Trends" include all the key variables/parameters studied to better analyze the market size estimates and forecasts. All the trends have been presented in the form of data points (time series or latest available data points) along with analysis of the paramter in the form of concise market relevant commentary, for the geography studied (country or region as per the scope of report).
- Key Strategic Moves - The action taken by a company to differentiate from its competitor or used as a general strategy is referred to as a key strategic move (KSM). This includes (1) Agreements (2) Expansions (3) Financial Restructuring (4) Mergers and Acquisitions (5) Partnerships, and (6) Product Innovations. Key players (Logistics Service Providers, LSPs) in the market have been shortlisted, their KSM have been studied and presented in this section.
- Liner Shipping Bilateral Connectivity Index - It indicates a country pair's integration level into global liner shipping networks and plays a crucial role in determining bilateral trade, which in turn potentially contributes toward the prosperity of a country and its surrounding region. Hence the major economies connected to the country/ region as per scope of the report, have been analyzed and presented in "Liner Shipping Connectivity" industry trend.
- Liner Shipping Connectivity - This industry trend analyses the state of connectivity to the global shipping networks based on the status of maritime transport sector. It includes the analysis of liner shipping connectivity, bilateral shipping connectivity, and port liner shipping connectivity indices for the geography (country/ region as per scope of the report) over the review period.
- Liner Shipping Connectivity Index - It indicates how well countries are connected to global shipping networks based on the status of their maritime transport sector. It is based on five components of the maritime transport sector: (1) The number of shipping lines servicing a country, (2) The size of the largest vessel used on these services (in TEUs), (3) The number of services connecting a country to the other countries, (4) The total number of vessels deployed in a country, (5) The total capacity of those vessels (in TEUs).
- Logistics Performance - Logistics Performance and Logistics Costs are the backbone of trade, and influences trade costs, making countries compete globally. Logistics performance is influenced by market wide adopted supply chain management strategies, government services, investments & policies, fuel/ energy costs, inflationary environment etc. Hence, in this industry trend, the logistics performance of the geography studied (country/ region as per the scope of report) has been analysed and presented over the review period.
- Major Truck Suppliers - Market share of truck brands is influenced by factors like geographical preferences, portfolio of truck types, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological innovations (like electric vehicles, digitalization, autonomous trucks), fuel efficiency, financing options, annual maintenance costs, availability of substitutes, marketing startegies etc. Hence, the distribution (share % for base year of the study) of truck sales volume for leading truck brands and commentary on current market scenario & market anticipation over the forecast period have been presented in this industry trend.
- Manufacturing - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the Manufacturing industry players. The end user players considered are the establishments primarily engaged in the chemical, mechanical or physical transformation of materials or substances into new products. Logistics Service Providers (LSPs) play a crucial role in maintaining a smooth flow of raw materials across the supply chain, enabling timely delivery of finished goods to distributors or end customers and storing & supplying the raw materials to clients for just-in-time manufacturing.
- Maritime Fleet Load Carrying Capacity - Maritime fleet load carrying capacity depicts the development state of an economy's maritime infrastructure & trade. It is influenced by factors like volume of production, international trade, major end user industries, maritime connectivity, environmental regulations, investments in port infrastructure development, port container cargo handling capacity etc. This industry trend represents the maritime fleet load carrying capacity by type of ship viz. container ships, oil tankers, bulk carriers, general cargo, among other types alongwith the influencing factors for the geography studied (country/ region as per scope of the report), over the review period.
- Modal Share - Freight Modal Share is influenced by factors like modal productivity, government regulations, containerization, distance of shipment, temperature control requirements, type of goods, international trade, terrain, speed of delivery, shipment weight, bulk shipments, etc. Also, modal share by tonnage (tons) and modal share by freight turnover (ton-km) differ as per average distance of shipments, weight of major commodity groups transported in the economy and number of trips. This industry trend represents the distribution of freight transported by mode of transport (tons as well as ton-km), for the study base year.
- Oil and Gas, Mining and Quarrying - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the extraction industry players. The end user players considered are the establishments that extract naturally occurring mineral solids, such as coal and ores; liquid minerals, such as crude petroleum; and gases, such as natural gas. Logistics Service Providers (LSPs) covers entire phases from upstream to downstream and plays a crucial role in the transportation of machinery, drilling equipments, extracted minerals, crude oil & natural gas and refined/ processed products from one place to another.
- Other End Users - Other end user segment captures the external (outsourced) logistics expenditure incurred by the financial services (BFSI), real estate, educational services, healthcare, and professional services (administrative, waste management, legal, architectural, engineering, design, consulting, scientific R&D). Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies and documents to/from these industries such as transporting any equipment or resources required, shipping confidential documents and files, movement of medical goods & supplies (surgical supplies and instruments, including gloves, masks, syringes, equipment) to name a few.
- Other Services - Other Services segment captures revenue earned through (1) Value added services (VAS) for freight transportation by road, rail, air and sea & inland waterways, (2) VAS for marine cargo transportation (operation of terminal facilities such as harbours and piers, operation of waterway locks, navigation, pilotage and berthing activities, lighterage, salvage activities, lighthouse activities, among other miscellaneous support activities), (3) VAS for land freight transportation (operation of terminal facilities such as railway stations, stations for the handling of goods, operation of railroad infrastructure, switching and shunting, towing and road side assistance, liquefaction of gas for transportation purposes, among other miscellaneous support activities), (4) VAS for air cargo transportation (operation of terminal facilities such as airway terminals, airport and air-traffic-control activities, ground service activities on airfields, runway maintenance, inspection/ ferrying/ maintenance/ testing of aircrafts, aircraft fuelling services, among other miscellaneous support activities), (5) VAS for warehousing and storage service (operation of grain silos, general merchandise warehouses, refrigerated warehouses, storage tanks etc., storage of goods in foreign trade zones, blast freezing, crating goods for shipping, packing and preparing goods for shipping, labelling and/or imprinting the package, kit assembling and packaging services, among other miscellaneous support activities), and (6) VAS for courier, express and parcel service (pickup, sorting).
- Port Calls and Performance - The performance of ports is key to an economy's freight movement, trade, global connectivity, successful growth strategies, investment attractiveness for production & distribution systems, and thus affects GDP, employment, per capita income and industrial growth. Hence, the port perfomance parameters like median time spent by vessels in the ports; average age, size, cargo carrying capacity, container carrying capacity, of vessels entering the ports, port calls, and container port throughput have been analysed and presented in this industry trend.
- Port Liner Shipping Connectivity Index - It reflects a port's position in the global liner shipping network, wherein a higher value of index is associated with better connectivity. Efficient and well-connected ports (1) contribute towards minimizing transport costs, linking supply chains and supporting international trade, (2) pave the way for economies of scale and development of expertise by permitting producers to better exploit possibilities in domestic as well as foreign markets. Hence the major ports of strategic importance, in the country/ region as per scope of the report, have been analyzed and presented in "Liner Shipping Connectivity" industry trend.
- Port Throughput - It reflects the amount of cargo or number of vessels a port handles annually. It can be related to (1) cargo tonnage, (2) container TEU, and (3) vessel calls. Port throughput in terms of total containers handled (TEU's), has been presented in the "Port Calls and Performance" industry trend.
- Producer Price Inflation - It indicates inflation from viewpoint of the producers viz. the average selling price received for their output over a period of time. Annual change (YoY) of producer price index is reported as wholesale price inflation in the "Inflation" industry trend. As WPI captures dynamic price movements in most comprehensive way, it is widely used by governments, banks, industry, business circles and is deemed important in formulation of trade, fiscal and other economic policies. The data has been used in adjunction to consumer price inflation for better understanding the inflationary environment.
- Segmental Revenue - Segmental Revenue has been triangulated or computed and presented for all the major players in the market. It refers to the freight and logistics market specific revenue earned by the company, over the base year of study, in the geography studied (country or region as per the scope of report). It is computed through the study and analysis of major parameters like financials, service portfolio, employee strength, fleet size, investments, number of countries present in, major economies of concern, etc. that have been reported by the company in its annual reports, webpage. For companies having scarce financial disclosures, paid databases like D&B Hoovers, Dow Jones Factiva have been resorted to and verified through industry/expert interactions.
- Transport and Storage Sector GDP - Value and growth of Transport and Storage Sector GDP has a direct relation to the freight and logistics market size. Hence, this variable has been studied and presented over the review period, in value terms (USD) and as share % of total GDP, in this industry trend. The data has been supported by concise and relevant commentary around the investments, developments, and current market scenario.
- Trends in E-Commerce Industry - Enhanced internet connectivity and boom in smartphone penetration, coupled with increasing disposable incomes, has led to a phenomenal growth in the e-commerce market globally. Online shoppers require fast and efficient delivery of their orders leading to an increase in the demand for logistics services especially e-commerce fulfilment services. Hence, the Gross Merchandise Value (GMV), historial and projected growth, breakup of major commodity groups in e-commerce industry for the studied geography (country or region as per scope of the report) have been analysed and presented in this industry trend.
- Trends in Manufacturing Industry - Manufacturing industry involves the transformation of raw materials into finished products, while logistics industry ensures the efficient flow of raw materials to the factory, and the transport of manufactured products to the distributors & consumers. Demand-Supply of both industries are highly cross-linked and critical for a seamless supply chain. Hence, the Gross Value Added (GVA), breakup of GVA into major manufacturing sectors, and growth of manufacturing industry over the review period have been analysed and presented, in this industry trend.
- Trucking Fleet Size By Type - Market share of truck types is influenced by factors like geographical preferences, major end user industries, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological disruptions (like electric vehicles, digitalization, autonomous trucks) etc. Hence, the distribution (share % for base year of study) of truck parc volume by type of truck, market disruptors, truck manufacturing investments, truck specifications, truck use & import regulations, and market anticipation over the forecast period have been presented in this industry trend.
- Trucking Operational Costs - The prime reasons for measuring/ benchmarking logistics performance of any trucking company are to reduce operational costs and increase profitability. On the other hand, measuring operational costs helps to identify whether and where to make operational changes to control expenses and identify areas for improved performance. Hence, in this industry trend, trucking operational costs and the variables involved viz. driver wages & benefits, fuel prices, repairs & maintenance costs, tyre costs etc. have been studied over the base year of study, and presented for the geography studied (country or region as per the scope of report).
- Warehousing and Storage - Warehousing and storage segment captures revenue earned through the operation of general merchandise, refrigerated and other types of warehousing & storage facilities. These establishments take responsibility for storing the goods and keeping them secure in lieu of charges. Value added services (VAS) they may provide are considered to be a part of the "other services" segment. Here VAS refer to a range of services, related to the distribution of a customer's goods and can include labelling, breaking bulk, inventory control & management, light assembly, order entry & fulfillment, packaging, pick & pack, price marking & ticketing and transportation arrangement.
- Wholesale and Retail Trade - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the wholesalers and retailers. The end user players considered are the establishments primarily engaged in wholesaling or retailing merchandise, generally without transformation, and rendering services incidental to the sale of merchandise. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies to and finished products from production houses to the distributors and finally to the end customer covering activites like material sourcing, transportation, order fulfillment, warehousing & storage, demand forecasting, inventory management etc.
| Keyword | Definition |
|---|---|
| Axle Load | The axle load of a wheeled vehicle is the total weight bearing on the roadway for all wheels connected to a given axle. |
| Back Haul | Backhaul is the return movement of a transport vehicle from its original destination to its original point of departure. |
| Bill of Lading | A bill of lading is a legal document issued by a carrier to a shipper that details the type, quantity, and destination of the goods being carried. |
| Bunkering | Bunkering is the process of supplying fuel and/or gasoil to be used to power the propulsion system of a ship (such fuel is referred to as bunker). It includes the logistics of loading and distributing the fuel among available shipboard tanks. A person dealing in trade of bunker (fuel) is called a bunker trader. |
| Bunkering Service | Bunkering service is the supply of a requested quality and quantity of bunkers to a ship. |
| C-commerce | C-commerce (Collaborative commerce) describes electronically enabled business interactions among an enterprise’s internal personnel, business partners and customers throughout a trading community. The trading community could be an industry, industry segment, supply chain or supply chain segment. |
| Cabotage | Transport by a vehicle registered in a country performed on the national territory of another country. |
| Cartage Agent | A ground transportation service that provides pickup and delivery of freight in locations not served directly by an air or ocean carrier. |
| Contract logistics | Contract logistics refers to the outsourcing of resource management tasks by one company to a third-party company specializing in logistical matters, such as transportation, warehousing, and order fulfillment. |
| Courier | A business that is used to send messages, packages, etc. Courier service refers to the fast or quick, door to door pickup and delivery service for goods or documents. It can be local or international. A company that provides such delivery services is called a courier company. A courier company hires people to provide their services. Such a person hired by the courier service company is called a courier. |
| Cross docking | Cross docking is a practice in logistics management that includes unloading incoming delivery vehicles and loading the materials directly into outbound delivery vehicles, omitting traditional warehouse logistical practices and saving time and money. |
| Cross Trade | International transport between two different countries performed by a vehicle registered in a third country. A third country is a country other than the country of loading/embarkation and than the country of unloading/disembarkation. |
| Customs Clearance | The procedures involved in getting cargo released by Customs through designated formalities such as presenting import license/permit, payment of import duties and other required documentations by the nature of the cargo such as FCC or FDA approval. |
| Customs seal | Customs seal means a seal, stamp or any other preventive means affixed by customs officials to ensure the inviolability of goods, commercial means of transport or warehouses. |
| Dangerous Goods | Dangerous goods (or hazardous materials or HAZMAT) include flammable liquids/solids, gases, compressed, liquified, dissolved under pressure, corrosives, oxidising substances, explosive substances and articles, substances, which on contact with water, emit flammable gasses, organic peroxides, toxic substances, infectious substances, radioactive materials, miscellaneous dangerous goods and articles. |
| Direct Shipment | Direct shipment is a method of delivering goods from the supplier or the product owner to the customer directly. In most cases, the customer orders the goods from the product owner. This delivery scheme reduces transportation and storage costs, but requires additional planning and administration. |
| Drayage | A drayage is a form of trucking service that connects the different modes of shipping (intermodal), such as ocean freight or air freight. It’s a short-haul trip that transports goods from one place to another, usually before or after its long-haul shipping process. Drayage trucks move cargo to and from various destinations, such as container ships, storage lots, order fulfillment warehouses, and rail yards. Typically, drayage only transports goods in short distances and operates only in one metropolitan area. It also requires only one trucker in a single shift. |
| Dry Docking | Dry docking is a term used for repairs or when a ship is taken to the service yard. During dry docking, the whole ship is brought to a dry land so that the submerged portions of the hull can be cleaned or inspected. |
| Dry van | A dry van is a type of semi-trailer that's fully enclosed to protect shipments from outside elements. Designed to carry palletized, boxed or loose freight, dry vans aren't temperature-controlled (unlike refrigerated “reefer” units) and can't carry oversized shipments (unlike flatbed trailers). |
| Feedering | Transport service whereby loaded or empty containers in a regional are transferred to a “mother ship” for a long-haul ocean voyage. |
| Final Demand | Final demand includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. |
| First mile Delivery | First mile delivery refers to the first stage of the transportation. This is when the parcel leaves the seller’s warehouse and is taken by the courier pick up agent to process it or take it to the warehouse. Once the package reaches the post office or the courier’s hub, it is then sorted and transported further until it reaches the customer’s doorstep. |
| Fiscal storage services | It means a facility, clearly separated from other premises, where the excise goods are produced, processed, held, received or dispatched under a duty suspension arrangement by an authorized depositor, in the course of his business, under conditions laid down by the customs authorities. |
| Flat Bed | It has a back body that is flatly shaped for easy loading and unloading of goods. The flatbed truck is mostly used to transport heavy, oversized, wide and indelicate goods. |
| Flatbed Truck | A flatbed truck is a type of truck with rigid design. It has a back body that is flatly shaped for easy loading and unloading of goods. The flatbed truck is mostly used to transport heavy, oversized, wide and indelicate goods such as machinery, building supplies or equipment. Due to the truck open body, the goods transported with it must not be vulnerable to rain. By functionality, the flatbed truck is comparable to a flatbed trailer. |
| Freight Transit Time | Transit time is how long it takes for a shipment to be delivered to its final destination after being picked up from a designated pick up point. |
| Halal Logistics | It refers to the process of managing the logistics operations such as fleet management, storage/warehousing, and materials handling according to the principles of Shariah law in ensuring the integrity of the halal products at the point of consumption. |
| Haulage | The commercial transport of goods. |
| Inbound Logistics | Inbound logistics is the way materials and other goods are brought into a company. This process includes the steps to order, receive, store, transport and manage incoming supplies. Inbound logistics focuses on the supply part of the supply-demand equation. |
| Intermediate Demand | Intermediate demand includes goods, services, and maintenance and repair construction sold to businesses, excluding capital investment. |
| International Loaded | Place of loading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of unloading in a different country. |
| International Unloaded | Place of unloading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of loading in a different country. |
| Last Mile Delivery | Last mile delivery refers to the very last step of the delivery process when a parcel is moved from a transportation hub to its final destination—which, usually, is a personal residence or retail store. |
| Less than-Truck-Load (LTL) | Less-than-truckload, also known as less-than-load (LTL), is a shipping service for relatively small loads or quantities of freight. An LTL provider combines the loads and shipping requirements of several different companies on their trucks, using a hub-and-spoke system to get goods to their destinations. |
| Locomotives Haluage | The transport of coal, ore, workers, and materials underground by means of locomotive-hauled mine cars. The locomotive may be powered by battery, diesel, compressed air, trolley, or some combination such as battery-trolley or trolley-cable reel. |
| Milkrun | A Milk Run is a delivery method used to transport mixed loads from various suppliers to one customer. Instead of each supplier sending a truck every week to meet the needs of one customer, one truck (or vehicle) visits the suppliers to pick up the loads for that customer. This method of transport got its name from the dairy industry practice, where one tanker used to collect milk from several dairy farms for delivery to a milk processing company. |
| Multi country consolidation | Multi-Country Consolidation (MCC) is a cost-effective solution that consolidates ones cargo from different countries of origin to build Full Container Loads (FCL). MCC is most suitable for companies that import light volumes of goods from multiple countries but want to take advantage of the more economic FCL freight rates. |
| Multi-Modal Logistics | Multimodal transportation or multimodal shipping refers to logistics and freight processes that require multiple modes of transportation. |
| Omni Channel Logistics | Omnichannel distribution is a multichannel approach taken by companies to give customers a way to purchase and receive orders from several sales channels with one-touch seamless integration. Some of the ways include- 1. Buy online, then pick-up at the brick and mortar store; 2. Buy online, then have it delivered to the home or another location; 3.In store purchase, with the delivery either to the home or another location; 4. Drop ship from a warehouse or manufacturing center to store, home or other location; 5.Buy online, then return at store or online; 6. Buy online, then return online. |
| OOG cargo | Out of Gauge (OOG) cargo is any cargo that can not be loaded into six-sided shipping containers simply because it is too large. The term is a very loose classification of all cargo with dimensions beyond the maximum 40HC container dimensions. That is a length beyond 12.05 meters – a width beyond 2.33 meters – or a height beyond 2.59 meters. |
| Other ships | Other ships include: Liquefied petroleum gas carriers, liquefied natural gas carriers, parcel (chemical) tankers, specialized tankers, reefers, offshore supply vessels, tugboats, dredgers, cruise, ferries, other non-cargo ships |
| Other Specialised Cargo | Other specialised goods include pre-slung goods (Goods, one or more items, supplied with a sling or slings), mobile units (Mobile Self Propelled Units, Non Self Propelled Units, unrolled vehicles), oversized equipment load (light and heavy machinery that is often too big or too heavy), high value freight that needs extra protection like electronics, financial services road freight. |
| Outsourced Freight Transport | Transport for hire or reward; The carriage for remuneration of goods. |
| Pallets | Raised platform, intended to facilitate the lifting and stacking of goods. |
| Part load | A part load describes goods which only fills a truck partially. In essence, the quantity of the shipment is bigger than the Less Than Truckload (LTL) shipment. Also, the shipment cannot fully occupy a truck i.e. its capacity is much lower than a Full Truckload (FTL) shipment. |
| Paved Road | Road surfaced with crushed stone (macadam) with hydrocarbon binder or bituminized agents, with concrete or with cobblestone. |
| Q-commerce | Q-commerce, also referred to as quick commerce, is a type of e-commerce where emphasis is on quick deliveries, typically in less than an hour. |
| Quay | A stone or metal platform lying alongside or projecting into water for loading and unloading ships. |
| Recommerce | Recommerce is the selling of previously owned items through online marketplaces to buyers who reuse, recycle or resell them. |
| ReverseLogistics | Reverse logistics is a type of supply chain management that moves goods from customers back to the sellers or manufacturers. |
| Road Freight Transport Service | Hiring a trucking agency for transport of commodities (raw materials or manufactured goods including both solids and liquids) form the origin to a destination within the country (domestic) or cross-border (international) constitutes road freight transport market. The service might be Full-Truck-Load or Less than-Truck-Load, containerized or non-containerized, temperature controlled or non temperature controlled, short haul or long haul. |
| Roll-on/roll-off cargo | Roll-on/roll-off (RORO or ro-ro) ships are cargo ships designed to carry wheeled cargo, such as cars, motorcycles, trucks, semi-trailer trucks, buses, trailers, and railroad cars, that are driven on and off the ship on their own wheels or using a platform vehicle, such as a self-propelled modular transporter. |
| Swap bodies | A swap body, swop body, exchangeable container or interchangeable unit, is one of the types of standard freight containers for road and rail transport. |
| Tank Barge | A non-self-propelled vessel constructed or adapted primarily to carry liquid, solid or gaseous commodities or cargos in bulk in cargo spaces (or tanks) through rivers and inland waterways, and may occasionally carry commodities or cargos through oceans and seas when in transit from one inland waterway to another. The commodities or cargos transported are in direct contact with the tank interior. |
| Tautliner vehicle | Tautliner and curtainsider are used as generic names for curtain sided trucks/trailers. The curtains are permanently fixed to a runner at the top and detachable rails/poles at front and rear, allowing the curtains to be drawn open and forklifts used all along the sides for easy and efficient loading and unloading. When closed for travel, vertical load restraint straps are attached to a rope rail beneath the truck bed, connecting the truck bed and curtain along both sides. Winches at either end of the curtain tension it, hence the 'Tautliner' name. This stops the curtain from flapping or drumming in the wind and can also help retain light loads from slipping sideways. |
| Transloading | Transloading is a shipping term that refers to the transfer of goods from one mode of transportation to another en route to their ultimate destination. |
| Tsubo | A Japanese unit of area equal to 35.58 square feet. |
| Unpaved Road | Road with a stabilized base not surfaced with crushed stone, hydrocarbon binder or bituminized agents, concrete or cobblestone. |
| Vessel Husbandry Services | It includes ship maintenance, repairs, cleaning, upkeep of the hull and rigging and equipment. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period for each country.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


