
North America Manufacturing Inspection Equipment Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 6.92 Billion |
| Market Size (2027) | USD 7.45 Billion |
| Market Size (2032) | USD 9.61 Billion |
| Growth Rate (2027 - 2032) | 5.22 % |
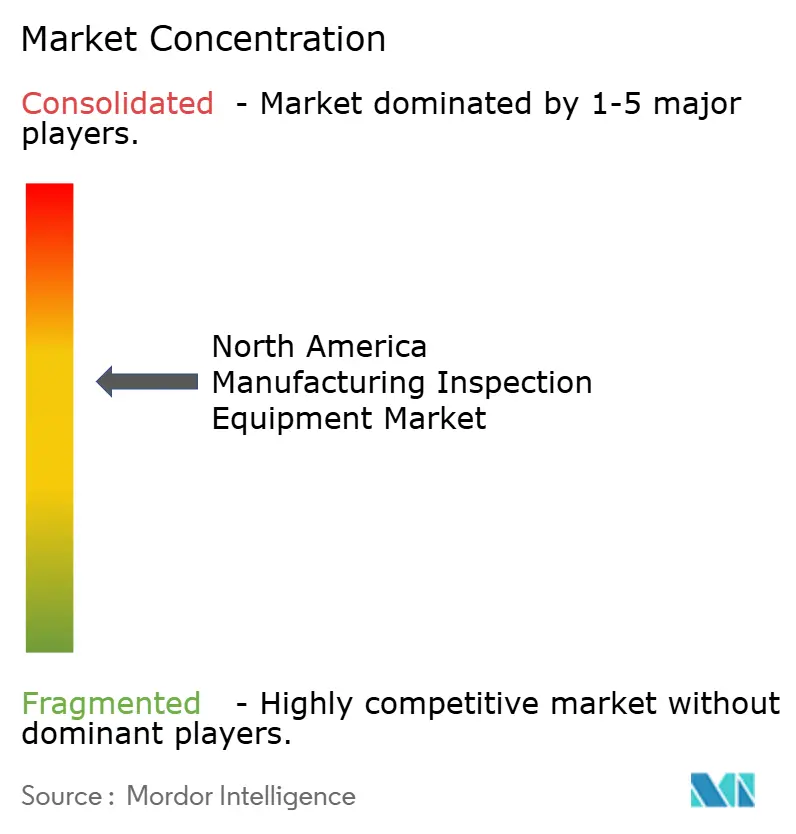
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Manufacturing Inspection Equipment Market Analysis by Mordor Intelligence
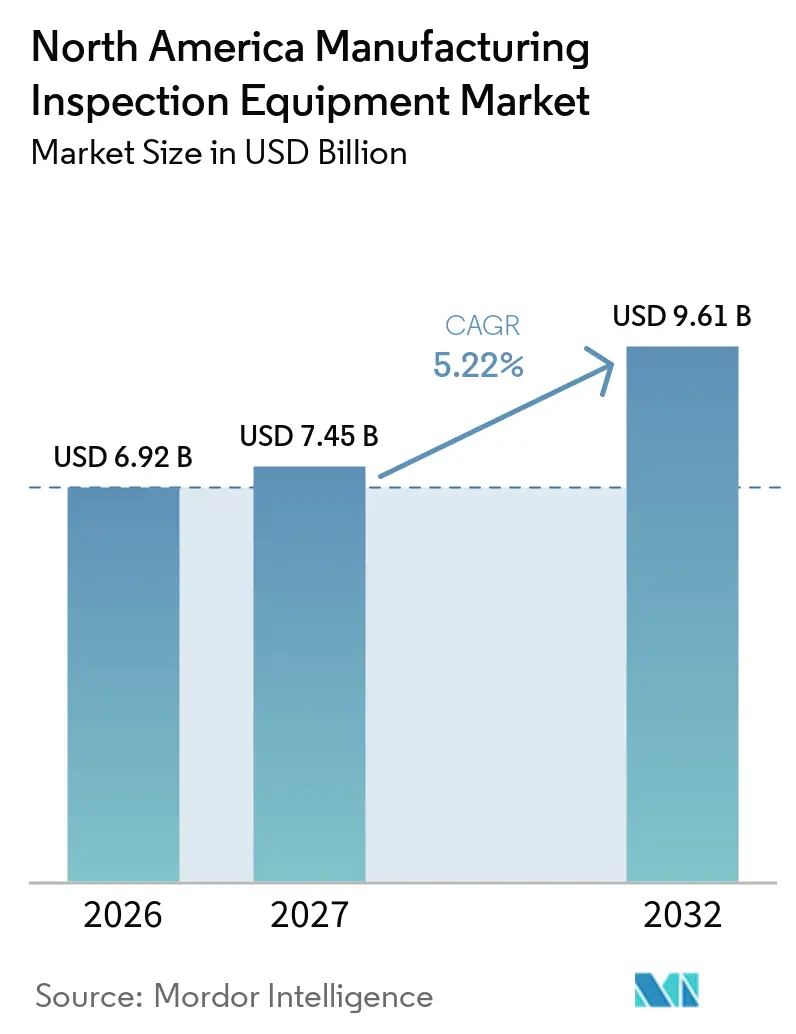
The North America Manufacturing Inspection Equipment Market size is expected to increase from USD 6.92 billion in 2026 to USD 7.45 billion in 2027 and reach USD 9.61 billion by 2032, growing at a CAGR of 5.22% over 2027-2032.
The North America manufacturing inspection equipment market is supported by new semiconductor fabs, battery plants, and regional supplier facilities that require inspection during production rather than only at the final quality check. Federal semiconductor incentives and private investment are moving advanced production capacity into the region, which raises demand for specialized process-control tools. Manufacturers are also placing inspection systems directly in production lines, where vision data can help detect defects before they move to the next stage. The opportunity is strongest where production tolerances, traceability rules, and safety requirements make manual checks insufficient, although cost, system integration, and qualified staffing remain constraints.
Key Report Takeaways
- By equipment type, optical and machine vision inspection equipment held 28% of the North America manufacturing inspection equipment market share in 2026, while specialized semiconductor inspection equipment is forecast to expand at an 8.2% CAGR through 2032.
- By manufacturing industry, automotive and automotive components held 19% of the North America manufacturing inspection equipment market size in 2026, while semiconductors and microelectronics recorded the highest projected CAGR at 8.5% through 2032.
- By geography, the United States held 78% in 2026, while Mexico recorded the highest projected CAGR at 6.8% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Manufacturing Inspection Equipment Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Reshoring of Semiconductor and Electronics Manufacturing | +1.2% | United States, Mexico | Medium term (2-4 years) |
| Expansion of Electric Vehicle and Battery Manufacturing | +1.0% | United States, Canada, Mexico | Short term (≤ 2 years) |
| Tighter Quality, Traceability, and Product-Safety Requirements | +0.8% | United States, Canada, Mexico | Medium term (2-4 years) |
| Adoption of Smart Factories and Inline Process Control | +0.6% | United States, Mexico | Medium term (2-4 years) |
| Sub-10-Micrometer Inspection for Advanced Packaging and Miniaturized Electronics | +0.4% | United States | Long term (≥ 4 years) |
| Inspection Data as a Production-Rate Constraint in Skilled-Labor-Short Manufacturing Plants | +0.3% | United States, Canada | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Reshoring of Semiconductor and Electronics Manufacturing
The North America manufacturing inspection equipment market benefits from semiconductor construction that creates multi-year procurement cycles for process-control equipment. By July 2025, the United States Department of Commerce had awarded USD 30.9 billion in direct funding and USD 5.5 billion in loans to 19 companies across 40 semiconductor projects.[1] One CHIPS-funded leading-edge logic fab in Arizona was certified complete in June 2025. The Semiconductor Industry Association reported more than USD 540 billion in announced United States semiconductor manufacturing investments since the CHIPS Act was enacted.[2] It also cited a Commerce projection that the United States share of global leading-edge logic manufacturing will rise to 20% by 2030. New cleanrooms require wafer, reticle, and packaging inspection that can work with increasingly small features, while USMCA supply chains extend demand into Mexican electronics facilities.
Expansion of Electric Vehicle and Battery Manufacturing
Battery factories increase the need for checks at coating, calendering, cell assembly, and formation stages, where makers use optical, X-ray, CT, and seal-integrity systems. Toyota began production at its USD 13.9 billion battery plant in North Carolina in November 2025, with 30 GWh of annual capacity across 14 production lines. Toyota also confirmed up to USD 10 billion in additional United States investment over five years. Panasonic Energy began mass production at its 4.7 million-square-foot Kansas facility in July 2025 and targets 32 GWh of annual capacity. The company expects its Kansas and Nevada sites to reach 73 GWh of combined United States output. These investments make inspection a recurring production requirement rather than a periodic metrology purchase.
Tighter Quality, Traceability, and Product-Safety Requirements
The North America manufacturing inspection equipment market is also supported by requirements that make traceable production records more important. The FDA Quality Management System Regulation became effective in February 2026 and aligns medical-device quality requirements with ISO 13485.[3] This change increases the value of automated inspection reports and lot-level records for regulated producers. Aerospace manufacturers also need dimensional and nondestructive inspection that supports production approvals and accredited processes. These conditions move inspection closer to a production-gating role and encourage investment earlier in the supplier chain.
Adoption of Smart Factories and Inline Process Control
The move from downstream quality checks to inline process control expands the use of inspection across the production floor. Rockwell Automation reported that 50% of manufacturers plan to use artificial intelligence or machine learning for quality control. Cognex reported USD 249 million in second-quarter 2025 revenue, 4% higher than the prior year, with demand from electronics and packaging production lines contributing to growth. Its One Vision platform enables cloud-based model training and edge deployment for machine-vision applications. Advanced packaging and miniaturized electronics further increase the need for high-resolution inspection as traditional systems reach resolution limits. Plants with skilled-labor gaps also have a stronger reason to use inspection data to protect production rates.
Restraints Impact Analysis of North America Manufacturing Inspection Equipment Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Capital Cost and Integration Complexity of Advanced Inspection Cells | -0.8% | North America | Short term (≤ 2 years) |
| Shortage of Qualified Metrology and NDT Personnel | -0.5% | United States, Canada | Medium term (2-4 years) |
| Limited Interoperability of Inspection Data Across Legacy Manufacturing Systems | -0.3% | United States, Canada | Medium term (2-4 years) |
| Qualification Delays for AI-Based Defect Decisions in Safety-Critical Production | -0.2% | United States | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Capital Cost and Integration Complexity of Advanced Inspection Cells
Industrial CT platforms, multisensor CMMs, and specialized semiconductor tools cost from USD 500,000 to several million dollars per installation before commissioning and calibration needs are included. This spending is difficult for smaller manufacturers that may not have dedicated automation budgets. A new inspection cell must also connect with existing MES, ERP, and SCADA systems, often through custom integration work. This can extend deployment schedules by six to eighteen months, especially in older facilities with limited mechanical or software flexibility. The same legacy-system issue limits the interoperability of inspection data across equipment brands and plant systems. High initial cost and longer implementation periods can delay the shift from manual checks to automated inspection even where the productivity case is clear.
Shortage of Qualified Metrology and NDT Personnel
A limited supply of qualified metrology and nondestructive testing staff can restrict utilization of advanced systems after installation. In May 2025, ASNT urged federal departments to include nondestructive testing in the national workforce development strategy. The United States Department of Labor approved ASNT National Guidelines for Apprenticeship Standards, which support the longer-term training pipeline. ASNT identified workforce development as a primary priority while demand rises for phased-array ultrasonic testing, full-matrix capture, and industrial CT. Level II and Level III certification still takes years, which slows the availability of experienced staff. Safety-critical facilities can also take time to qualify AI-based defect decisions, limiting use even when software is technically available.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Manufacturing Inspection Equipment Market Segment Analysis
By Equipment Type:
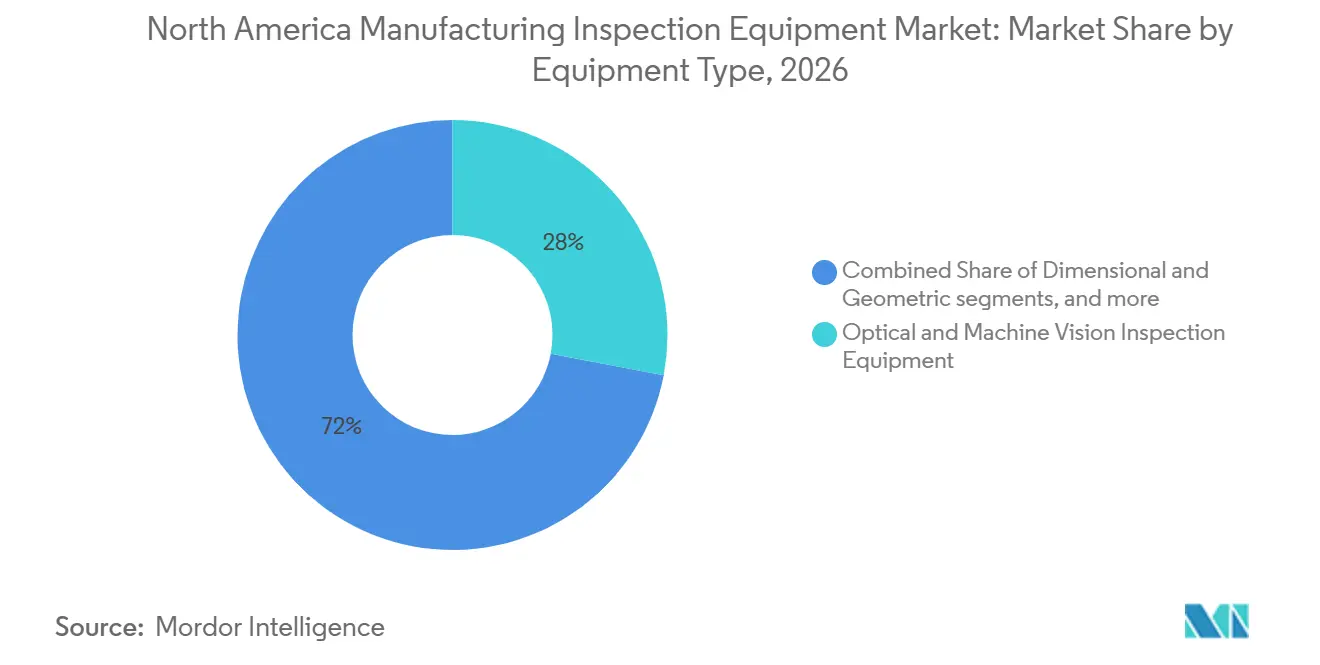
Optical Platforms Lead While Semiconductor Tools AccelerateOptical and machine vision inspection equipment held 28% of the regional total in 2026 because it can support many production settings. These systems inspect surface defects on automotive panels, confirm component placement in electronics assembly, review packaging labels, and check dimensions in precision machining. Cognex states that its In-Sight 3800 combines higher processing speed with Edge Learning tools that work from a small image sample. This can reduce configuration work for smaller plants that lack large engineering teams. Optical tools also fit production lines where manufacturers need a repeatable check without moving parts to a separate laboratory. Their value increases when defects must be identified early enough to avoid rework in later steps. Dimensional and geometric tools, including CMMs, laser trackers, 3D scanners, and surface profilometers, are used where battery housing, aerospace structures, and advanced packages require tighter tolerances.
Specialized semiconductor inspection equipment is expected to grow at an 8.2% CAGR from 2027 to 2032, the highest rate among equipment types; fab construction and the greater inspection intensity of advanced nodes and packaging support this expansion. A November 2025 ASME review identified through-silicon via inspection and hybrid-bonding metrology as demanding quality challenges in advanced packaging. Defectivity is moving into the submicron range, which increases pressure on legacy tools and supports replacement demand for new X-ray CT and nano-imaging platforms. KLA reported that advanced packaging process control was a primary research and development focus in fiscal 2025. These systems are selected for the specific process layer and defect type that a fab must control. That makes technical qualification, service capability, and measurement performance important factors in supplier selection. Leak and seal-integrity equipment serves pharmaceutical, food, beverage, and chemical applications where product safety controls remain essential.

By Manufacturing Industry:
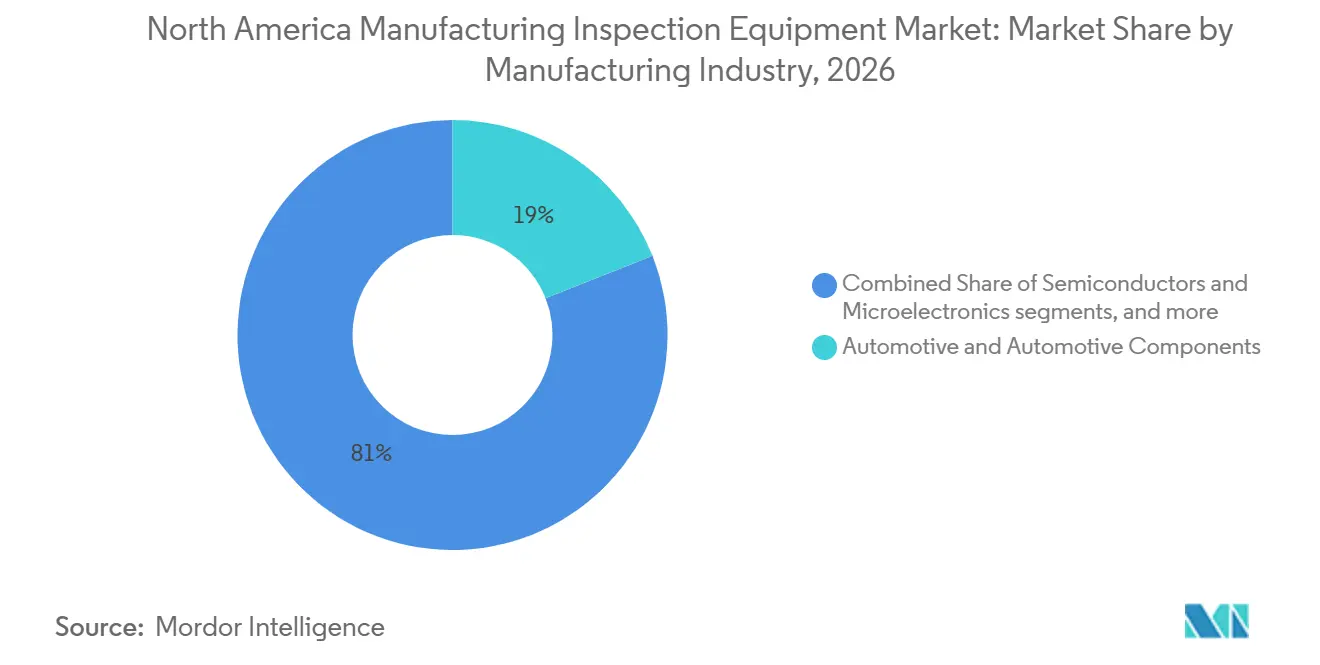
Automotive Anchors Demand as Semiconductor Verticals SurgeAutomotive and automotive components held 19% of the North America manufacturing inspection equipment market size in 2026. The segment uses machine vision, CMMs, and laser scanners across body, powertrain, and battery-module assembly. Electric-vehicle platforms require additional checks for battery-pack sealing, weld quality, and cell-level defects, which go beyond the inspection needs of established internal-combustion vehicle lines. Each added inspection point helps manufacturers identify a process deviation before the vehicle or battery proceeds to a later assembly stage. Aerospace, defense, and other transportation equipment also use traceable dimensional and nondestructive inspection because structural parts must meet strict production standards. Medical devices and healthcare products have high inspection intensity per unit of output, as the FDA QMSR strengthens quality-system alignment and traceability expectations. Industrial machinery, chemicals, food, and beverage producers maintain demand through supplier audits and lean production practices. These applications give the North America manufacturing inspection equipment market a broad base beyond large automotive plants. They also balance project-based demand in newer sectors with recurring inspection needs in established production lines. The mix reduces dependence on the investment cycle of any single manufacturing vertical.
Semiconductors and microelectronics are forecast to expand at an 8.5% CAGR from 2027 to 2032, the highest rate among manufacturing industries. The segment requires process-control investment that is more intensive than comparable conventional manufacturing projects. Semiconductor investment announcements and government support have expanded the addressable base for wafer, reticle, and packaging inspection. Batteries and Energy Storage Products are another developing vertical because each additional production line requires several inspection systems. Toyota and Panasonic battery projects show the scale of new cell-production capacity that is being added in the United States. Battery producers also need inspection systems that can operate at the speed of continuous cell manufacturing. The North America manufacturing inspection equipment industry has room to serve both cleanroom-focused requirements and broader factory automation needs. This mix helps suppliers that can connect measurement hardware with production data and plant workflows. It also creates different purchasing patterns, from large fab projects to repeat orders from automotive and battery suppliers. This demand profile favors suppliers that can support installation, calibration, and ongoing software updates.
Geography Analysis
United States Manufacturing Inspection Equipment Market
The United States held 78% of the regional total in 2026. Its position reflects a concentration of aerospace, semiconductor, pharmaceutical, and automotive production, all of which require more inspection than many general manufacturing activities. CHIPS-supported logic fabs in Arizona, Ohio, and Oregon are being developed alongside battery plants in North Carolina, Kansas, and Tennessee. These projects require measurement and defect-control tools at multiple production stages. The United States is expected to retain its leading position as fabs move from construction to volume production and increase spending on process control.
Mexico Manufacturing Inspection Equipment Market
Mexico is forecast to grow at a 6.8% CAGR from 2027 to 2032, the highest rate in the North America manufacturing inspection equipment market. Automotive, electronics, and aerospace producers are adding supplier capacity in the Monterrey, Guadalajara, and Tijuana corridors. USMCA regional-content requirements and efforts to reduce exposure to distant sourcing have supported these location decisions. Export-focused facilities must meet OEM audit standards and traceability obligations. These requirements favor machine vision, CMM, and nondestructive testing systems over manual processes.
Canada Manufacturing Inspection Equipment Market
Canada contributes a stable share through aerospace production in the Montreal-Quebec corridor, automotive assembly in Ontario, and battery-materials processing. Its aerospace and industrial producers use nondestructive testing and dimensional inspection to support transport and certification requirements. Battery-mineral processing increases the need for compositional analysis and material-identification tools, including X-ray fluorescence systems. Canada has a smaller absolute base than the United States, which limits its headline growth rate. The North America manufacturing inspection equipment market has different country roles, with United States scale, Mexican growth, and Canadian precision applications.
Competitive Landscape
The North America manufacturing inspection equipment market exhibits a medium level of market concentration. KLA has a dominant position in DUV reticle mask inspection and reported a more than 90% share in that niche. Semiconductor process control also includes Applied Materials, while Cognex and KEYENCE lead machine vision. Cognex uses its One Vision platform to reduce the setup burden for vision applications. Asian machine-vision and sensor suppliers add price pressure in optical equipment, which can challenge incumbents with higher cost structures.
Dimensional metrology competition strengthened when AMETEK completed its acquisition of FARO Technologies for USD 920 million in July 2025. The transaction added FARO 3D measurement, laser projection, and imaging capabilities to AMETEK Ultra Precision Technologies alongside Creaform and Virtek. This expands AMETEK’s ability to compete with Hexagon across 3D scanning, laser tracking, and structured-light measurement. Hexagon launched MAESTRO in May 2025 as a CMM designed for digital manufacturing workflows and AI-driven quality analytics. It also introduced PRESTO Quality Station configurations for automated large-component inspection.
The North America manufacturing inspection equipment market still has openings in inspection-as-a-service for smaller manufacturers that cannot fund major capital purchases. Interoperable data platforms that connect multiple equipment brands with MES environments are another area without a dominant provider. Patent activity in AI-based defect classification spans established suppliers and startups, increasing the importance of software differentiation. This could shift some competitive value toward platforms that simplify model setup and data exchange.
North America Manufacturing Inspection Equipment Industry Leaders
-
ZEISS
-
Hexagon AB
-
Cognex Corporation
-
KLA Corporation
-
KEYENCE CORPORATION
- *Disclaimer: Major Players sorted in no particular order
North America Manufacturing Inspection Equipment Market Companies Covered in this Report
- ZEISS
- Hexagon AB
- Cognex Corporation
- KLA Corporation
- KEYENCE CORPORATION
- Applied Materials, Inc.
- Baker Hughes Company
- Evident Corporation
- Eddyfi Technologies Inc.
- MISTRAS Group, Inc.
- Nikon Corporation
- Mitutoyo Corporation
- Renishaw plc
- OMRON Corporation
- SICK, Inc.
- Basler AG
- Thermo Fisher Scientific Inc.
- Mettler-Toledo International Inc.
- Ametek, Inc.
- Intertek Group plc
- Nordson Corporation
- Bureau Veritas SA
- Applus Services, S.A.
- Sonatest Ltd.
- Magnaflux
Recent Industry Developments in North America Manufacturing Inspection Equipment Market
- June 2026: UnitX launched the DeteX AI smart camera, designed for rapid deployment of automated visual inspection on production lines.
- May 2026: Cognex Corporation launched the In-Sight 3900 embedded AI vision system, powered by Qualcomm Dragonwing platforms. It offers up to 4× faster processing than previous-generation Cognex vision systems and resolution up to 25 megapixels.
- November 2025: Toyota commenced production at its USD 13.9 billion battery plant in Liberty, North Carolina, its first battery facility outside Japan, targeting 30 GWh of annual capacity across 14 production lines for HEV, PHEV, and BEV formats. Toyota confirmed an additional United States investment commitment of up to USD 10 billion over five years.
- July 2025: AMETEK, Inc. completed the acquisition of FARO Technologies for USD 920 million, integrating FARO 3D measurement, laser projection, and imaging solutions into its ultra-precision technologies division alongside Creaform and Virtek.
North America Manufacturing Inspection Equipment Market Report Scope
The North America Manufacturing Inspection Equipment Market Report is Segmented by Equipment Type (Optical and Machine Vision Inspection Equipment, Dimensional and Geometric Inspection Equipment, and More), by Manufacturing Industry (Semiconductors and Microelectronics, Food and Beverage Products, and More), and by Geography (United States, Canada, Mexico). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Optical and Machine Vision Inspection Equipment |
| Dimensional and Geometric Inspection Equipment |
| Radiographic and Computed Tomography Inspection Equipment |
| Ultrasonic and Acoustic Inspection Equipment |
| Electromagnetic and Magnetic Inspection Equipment |
| Thermal and Infrared Inspection Equipment |
| Specialized Semiconductor Inspection Equipment |
| Material Identification and Composition Inspection Equipment |
| Leak and Seal Integrity Inspection Equipment |
| Product Contamination and Physical Conformity Inspection Equipment |
| Other Specialized Manufacturing Inspection Equipment |
| Automotive and Automotive Components |
| Aerospace, Defense and Other Transportation Equipment |
| Semiconductors and Microelectronics |
| Other Electronics and Electrical Equipment |
| Batteries and Energy Storage Products |
| Industrial Machinery, Metal Products and Fabrication |
| Chemicals, Plastics and Industrial Materials |
| Food and Beverage Products |
| Pharmaceuticals and Biopharmaceuticals |
| Medical Devices and Healthcare Products |
| Textiles, Apparel, Footwear and Accessories |
| Furniture, Homeware, Toys and Other Consumer Products |
| Building Materials and Construction Products |
| Packaging, Paper and Printed Products |
| Other Manufactured Products |
| United States |
| Canada |
| Mexico |
| By Equipment Type | Optical and Machine Vision Inspection Equipment |
| Dimensional and Geometric Inspection Equipment | |
| Radiographic and Computed Tomography Inspection Equipment | |
| Ultrasonic and Acoustic Inspection Equipment | |
| Electromagnetic and Magnetic Inspection Equipment | |
| Thermal and Infrared Inspection Equipment | |
| Specialized Semiconductor Inspection Equipment | |
| Material Identification and Composition Inspection Equipment | |
| Leak and Seal Integrity Inspection Equipment | |
| Product Contamination and Physical Conformity Inspection Equipment | |
| Other Specialized Manufacturing Inspection Equipment | |
| By Manufacturing Industry | Automotive and Automotive Components |
| Aerospace, Defense and Other Transportation Equipment | |
| Semiconductors and Microelectronics | |
| Other Electronics and Electrical Equipment | |
| Batteries and Energy Storage Products | |
| Industrial Machinery, Metal Products and Fabrication | |
| Chemicals, Plastics and Industrial Materials | |
| Food and Beverage Products | |
| Pharmaceuticals and Biopharmaceuticals | |
| Medical Devices and Healthcare Products | |
| Textiles, Apparel, Footwear and Accessories | |
| Furniture, Homeware, Toys and Other Consumer Products | |
| Building Materials and Construction Products | |
| Packaging, Paper and Printed Products | |
| Other Manufactured Products | |
| By Geography | United States |
| Canada | |
| Mexico |
Key Questions Answered in the Report
What is the forecast value of the North America manufacturing inspection equipment market by 2032?
The forecast value is USD 9.61 billion by 2032, up from USD 7.45 billion in 2027, with a 5.22% CAGR over 2027-2032.
Which equipment category leads demand in North America?
Optical and machine vision inspection equipment leads with a 28% share in 2026 because it serves automotive, electronics, packaging, and precision-machining applications.
Which manufacturing sector is growing fastest for inspection systems?
Semiconductors and microelectronics are projected to grow at an 8.5% CAGR through 2032, supported by fab construction and advanced packaging requirements.
Why is battery manufacturing important for inspection equipment demand?
Battery lines need checks at coating, calendering, assembly, and formation stages, and major 2025 capacity additions by Toyota and Panasonic add demand for these systems.
Which country is growing fastest in North America?
Mexico is projected to grow at a 6.8% CAGR through 2032 as automotive, electronics, and aerospace suppliers add export-oriented production capacity.
What limits adoption of advanced inspection cells?
High capital cost, integration work in older facilities, limited availability of qualified staff, and longer AI qualification processes can delay deployment.