
Managed Wi-Fi Assurance and Analytics Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 4.38 Billion |
| Market Size (2032) | USD 8.79 Billion |
| Growth Rate (2027 - 2032) | 14.95 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Wi-Fi Assurance and Analytics Services Market Analysis by Mordor Intelligence
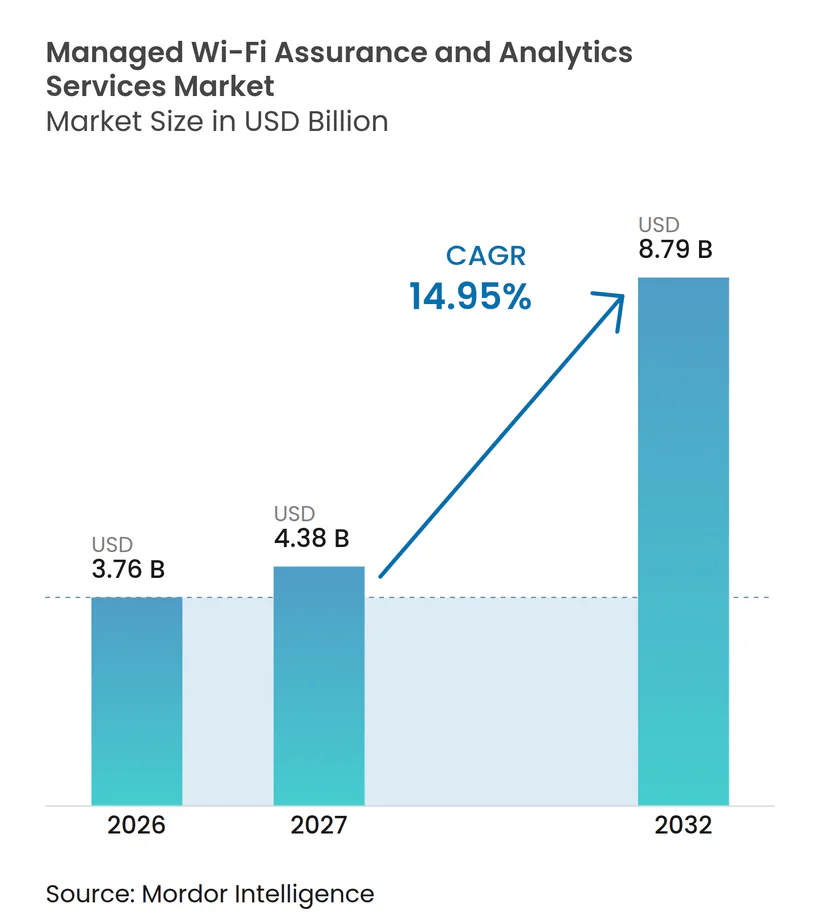
The managed Wi-Fi assurance and analytics services market size is projected to expand from USD 3.76 billion in 2026 and USD 4.38 billion in 2027 to USD 8.79 billion by 2032, registering a CAGR of 14.95% between 2027 and 2032. The market is moving from reactive maintenance contracts toward assurance models that use real-time telemetry, cloud management, and automated network operations. Enterprises need more consistent wireless performance as collaboration tools, video analytics, connected equipment, and distributed work sites place greater pressure on local networks. Wi-Fi 7 upgrades also prompt buyers to reassess the management and analytics tools attached to their access point estates. Providers with integrated assurance platforms, multi-site controls, and practical automation are better placed to win recurring contracts. Privacy obligations, data-location rules, and shortages of advanced wireless engineers could slow implementation and increase delivery costs for the Managed Wi-Fi assurance and analytics services market.
Key Report Takeaways
- By service model, fully managed services held 39.53% of revenue in 2026, while co-managed and partially managed services are projected to expand at a 15.93% CAGR through 2032.
- By deployment mode, cloud-based platforms accounted for 62.13% of revenue in 2026 and are projected to expand at a 16.24% CAGR through 2032.
- By application, network health, performance assurance, and auto-remediation held 32.63% of managed Wi-Fi assurance and analytics services market revenue in 2026, while predictive maintenance and automated remediation are projected to expand at a 17.46% CAGR through 2032.
- By end user, corporate offices and financial services accounted for 27.31% of revenue in 2026, while manufacturing, warehousing, and logistics are projected to expand at an 18.47% CAGR through 2032.
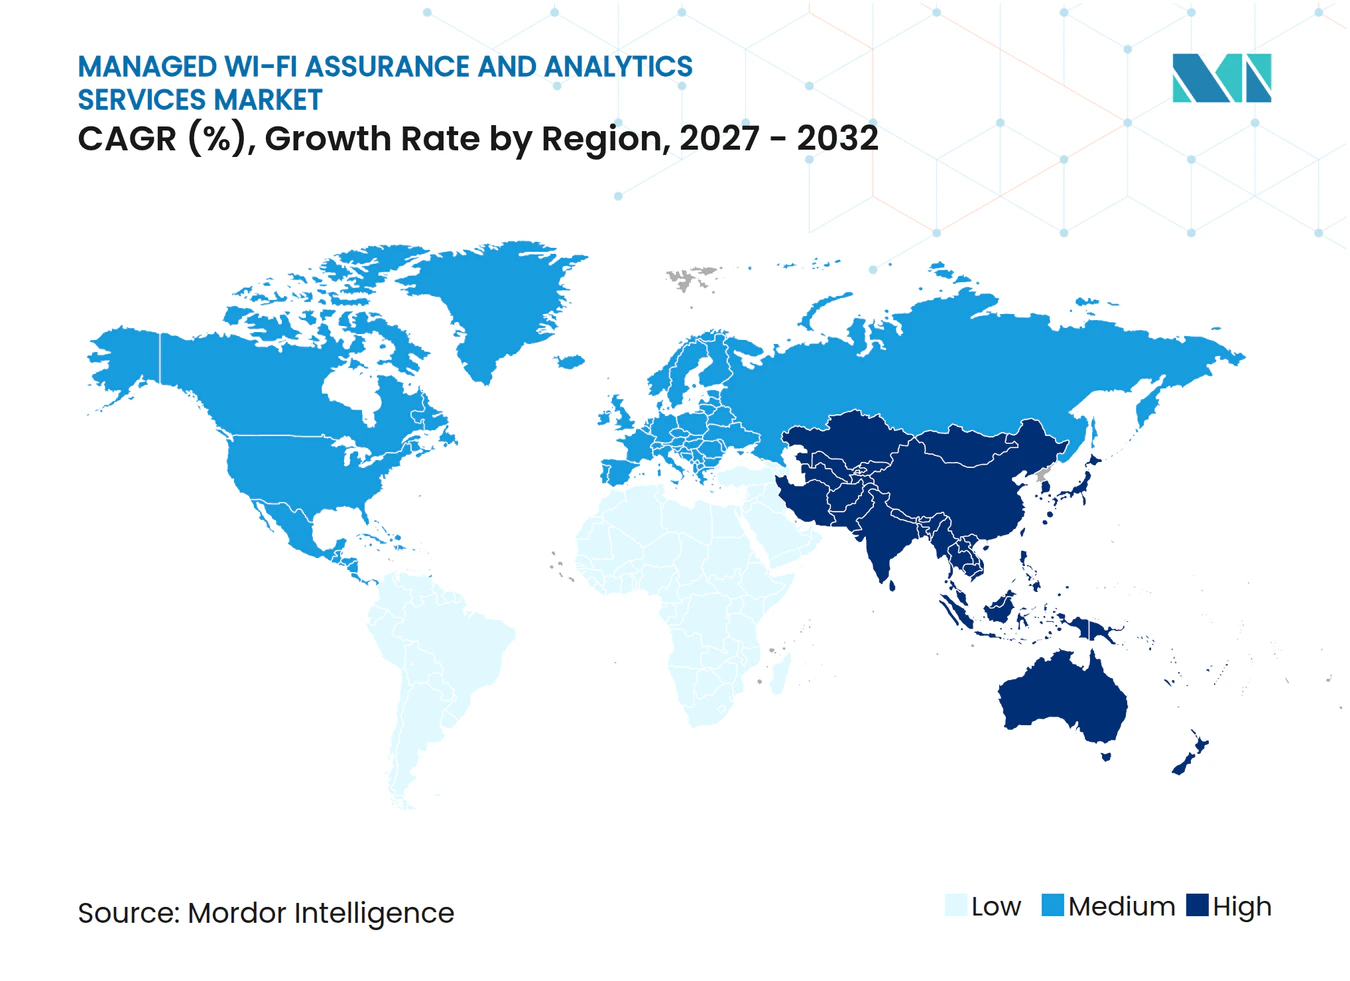
- By geography, North America held 36.27% of managed Wi-Fi assurance and analytics services market revenue in 2026, while Asia-Pacific is projected to expand at a 16.53% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Wi-Fi Assurance and Analytics Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Enterprise and Service Provider Demand for Predictable Wi-Fi Experience | +3.8% | Global, with highest intensity in North America and Western Europe | Short term (≤ 2 years) |
| Cloud-Managed Network Operations and AIOps Adoption | +3.2% | Global, with Asia-Pacific scaling rapidly alongside North America | Short term (≤ 2 years) |
| Wi-Fi 6E and Wi-Fi 7 Upgrade Cycles | +2.5% | North America, Europe, Asia-Pacific core, with spillover to the Middle East and Africa | Medium term (2-4 years) |
| Distributed Sites, IoT, and High-Density Connectivity Requirements | +2.0% | Global, with early gains in North America, Germany, China, and Japan | Medium term (2-4 years) |
| Edge Processing for Faster, Lower-Cost Assurance Decisions | +1.3% | North America and Asia-Pacific core, with early adoption in European Union smart-factory corridors | Long term (≥ 4 years) |
| Multi-Tenant Broadband and Managed In-Home Wi-Fi Expansion | +1.0% | Asia-Pacific, Europe, and South America, supported by national broadband programs | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Enterprise and Service Provider Demand for Predictable Wi-Fi Experience
The Managed Wi-Fi assurance and analytics services market is benefiting from contracts that measure user experience rather than simple network availability. Enterprises running AI collaboration, video analytics, and digital twin applications cannot accept recurring latency or connection failures. A Wireless Broadband Alliance survey found that 76% of respondents identified security and privacy as enterprise Wi-Fi priorities, while 70% highlighted quality-of-experience and quality-of-service measures. These priorities make service-level commitments more important in managed wireless agreements. As edge inference becomes more common, providers can extend assurance services toward monitoring how applications perform over the network. This broadens the role of the Managed Wi-Fi assurance and analytics services market beyond basic connectivity support.
Cloud-Managed Network Operations and AIOps Adoption
Cloud-managed operations are changing how providers deliver wireless support across many customer sites. Automation can reduce repetitive work and allow service teams to focus on complex outages and customer-specific requirements. This makes recurring service plans more attractive when buyers need support without expanding internal network operations teams. The commercial value also rises when a provider has collected enough site history to establish a reliable performance baseline. Moving to another platform may then require rebuilding that baseline and retraining operational processes. The Managed Wi-Fi assurance and analytics services market, therefore, favors vendors that combine practical automation with clear customer visibility and control.
Wi-Fi 6E and Wi-Fi 7 Upgrade Cycles
Wi-Fi 6E and Wi-Fi 7 refresh programs create a natural point for enterprises to review their assurance contracts. The Federal Communications Commission expanded very-low-power device operation across the 6 GHz band in March 2025, and the rule took effect on May 5, 2025.[1] Wi-Fi 7 can use multiple bands for simultaneous traffic flows, which creates richer and more complex telemetry. That complexity increases the value of tools that identify performance problems before they affect users. Access point upgrades can also bring new device types, applications, and security requirements into one management environment. The Managed Wi-Fi assurance and analytics services market gains when hardware modernization is linked to a broader review of operational support.
Distributed Sites, IoT, and High-Density Connectivity Requirements
Wireless estates now cover branches, stores, hospitals, warehouses, venues, and other dispersed locations rather than one campus. These sites often support large numbers of connected devices with varying traffic patterns and reliability requirements. The Wireless Broadband Alliance reported that 41% of survey respondents expected strong traffic growth at stadiums and event venues, while 24% identified industrial and manufacturing IoT applications. Such environments create demand for device classification, behavioral monitoring, and anomaly detection. Cisco reported that its BottleRock 2026 deployment used 475 access points for 58,380 unique Wi-Fi clients, and 48.3% of clients connected through the 6 GHz band. The Managed Wi-Fi assurance and analytics services market can serve these settings with analytics that go beyond radio frequency optimization.
Restraints Impact Analysis of Managed Wi-Fi Assurance and Analytics Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Protection, Consent, and Data Residency Requirements | -1.5% | European Union, India, Gulf Cooperation Council, with spillover to Asia-Pacific | Short term (≤ 2 years) |
| Shortage of Advanced Wireless Operations Skills | -1.2% | Global, most acute in North America, the United Kingdom, and Asia-Pacific emerging markets | Medium term (2-4 years) |
| MAC Address Randomization Reducing Repeat-Device Accuracy | -0.9% | Global, particularly relevant to retail and venue analytics deployments | Medium term (2-4 years) |
| Fragmented Telemetry and Non-Standardized Multi-Vendor Correlation | -0.8% | Global, with highest complexity in large enterprise and carrier environments | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Protection, Consent, and Data Residency Requirements
Privacy rules define what Wi-Fi analytics providers may collect, store, and transfer between locations. The Spanish Data Protection Authority stated in its 2025 guidance that Wi-Fi tracking data can be personal data and that a lawful basis is needed for location and presence analytics.[2] The guidance also stresses data minimization when providers use aggregated insights. Data-residency requirements in the European Union, India, and Gulf Cooperation Council countries can require geographically distributed processing. This increases infrastructure needs and makes cross-border service delivery more difficult. The Managed Wi-Fi assurance and analytics services market will reward providers that embed consent controls and localized processing options into their platforms.
Shortage of Advanced Wireless Operations Skills
The shortage of engineers who can operate AI-supported wireless environments can limit how quickly providers can onboard new customers. Traditional wireless specialists may have deep protocol and radio frequency expertise, but limited experience with automated operations. Newer AI-focused talent may understand automation but lack practical knowledge of complex multi-vendor radio environments. The U.S. Department of Labor reported that the telecommunications apprenticeship pipeline served 11,734 apprentices in fiscal 2024. This pipeline supports workforce development, but it does not remove the immediate need for experienced delivery teams. The Managed Wi-Fi assurance and analytics services market may face slower expansion in regions where advanced wireless skills are scarce.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Wi-Fi Assurance and Analytics Services Market Segment Analysis
By Service Model:
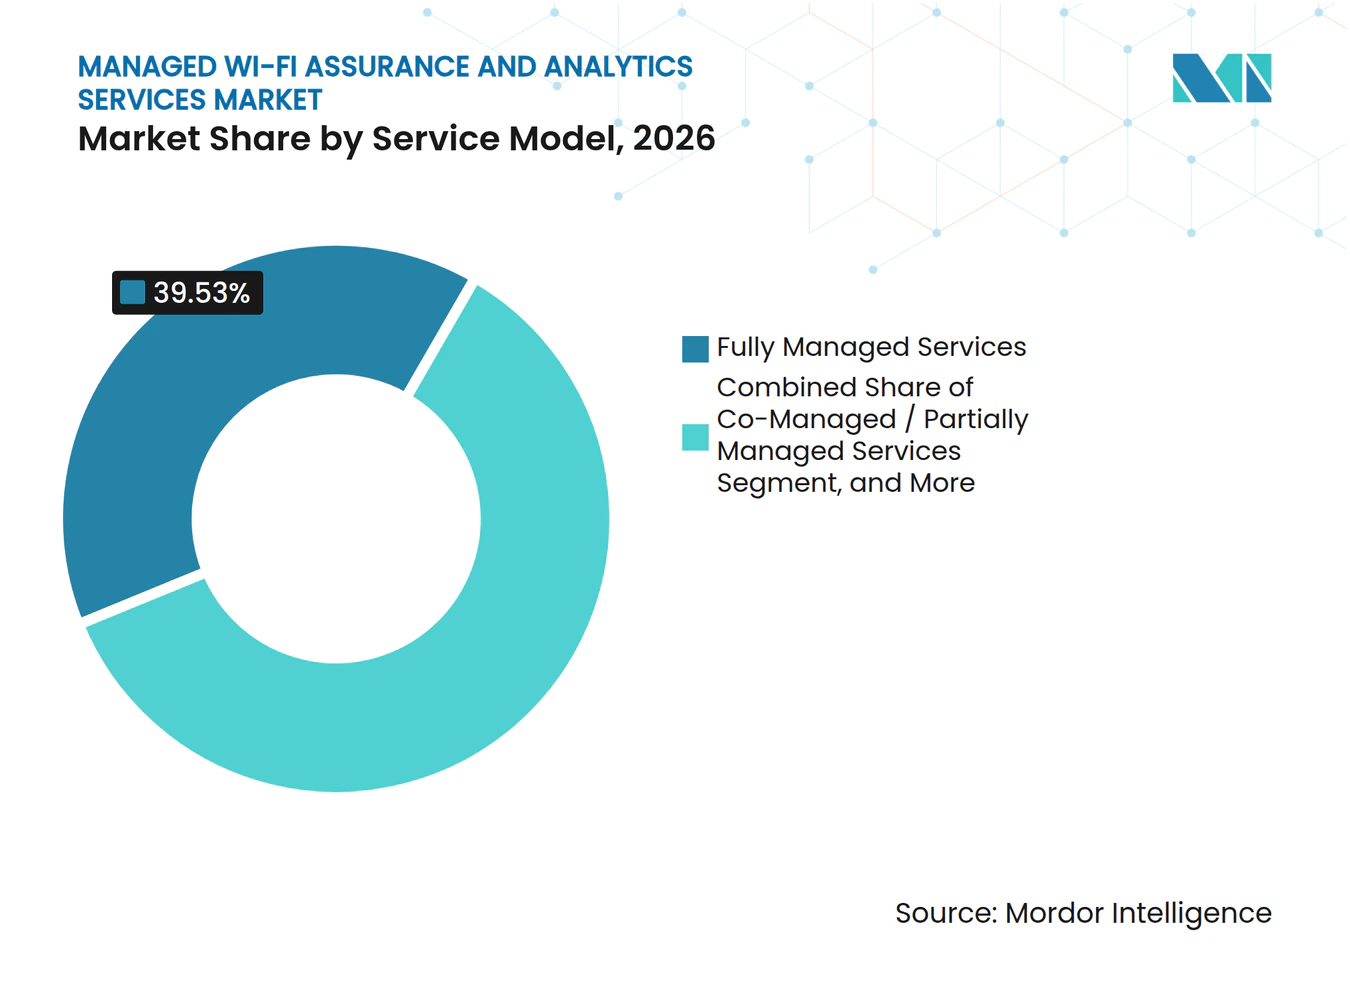
Co-Managed Services Increase Buyer ControlFully managed services held 39.53% of the Managed Wi-Fi assurance and analytics services market share in 2026, reflecting demand from organizations with many sites and limited internal wireless expertise. Retail chains, logistics operators, and hospitality groups use these contracts to obtain one operating model across dispersed locations where consistent support, incident handling, policy maintenance, and performance reporting would be difficult to staff locally. The model gives buyers defined responsibilities and predictable access to specialists as estates expand, access points are replaced, and new connected devices enter service. It also lets providers combine analytics, operational support, and service reporting in a recurring agreement rather than treating each network fault as a separate project. This established base gives the Managed Wi-Fi assurance and analytics services market a dependable source of demand among enterprises that prioritize continuity over direct operational control.
Co-managed and partially managed services are projected to expand at a 15.93% CAGR through 2032, led by mid-sized companies and regulated users that need external skills while retaining access to live network information and key operating decisions. Financial services and health care organizations can favor shared-control structures when policy, audit, security, or risk teams require direct oversight of assurance actions and the ability to override automation. The model provides a path from internal management toward wider service support without requiring the buyer to build a complete network operations center at once. Self-managed and SaaS-enabled tools also remain relevant to cloud-native organizations that want to keep assurance knowledge in house while using vendor analytics and automation engines. Open application programming interfaces and standards-based integration matter to these customers because they reduce dependence on one operating approach and widen the available choices within the Managed Wi-Fi assurance and analytics services industry.



By Deployment Mode:
Cloud Platforms Set the Operating ModelCloud-based deployment accounted for 62.13% of the Managed Wi-Fi assurance and analytics services market size in 2026, supported by enterprises that need a common operational view across branches, campuses, remote sites, and growing access point estates. Centralized platforms can distribute policy updates, analytics, and support processes without requiring specialists to visit every location, which improves the practical reach of a managed service provider. Subscription pricing can align operating spending with changing device counts, site openings, and service requirements, rather than tying buyers to a fixed capital cycle. These features allow smaller locations to use automated assurance capabilities that would be difficult to operate with local tools and limited staff. The result is an operating model that supports both large enterprise estates and smaller distributed deployments within the Managed Wi-Fi assurance and analytics services market.
Cloud-based platforms are projected to expand at a 16.24% CAGR through 2032, showing that centralized orchestration is relevant both to current deployments and future spending. Hybrid configurations remain important for banks, health systems, government bodies, and other organizations that need local processing, lower latency, or tighter data controls while still using central tools for policy and management. On-premises systems also retain a role in defense facilities and critical infrastructure sites where links to external clouds are restricted by security requirements. Providers therefore need flexible architectures that support different operating and compliance needs without forcing every customer into the same deployment approach. This deployment mix helps the Managed Wi-Fi assurance and analytics services market address customers that cannot adopt a fully cloud-based architecture but still require consistent assurance methods.
By Application:
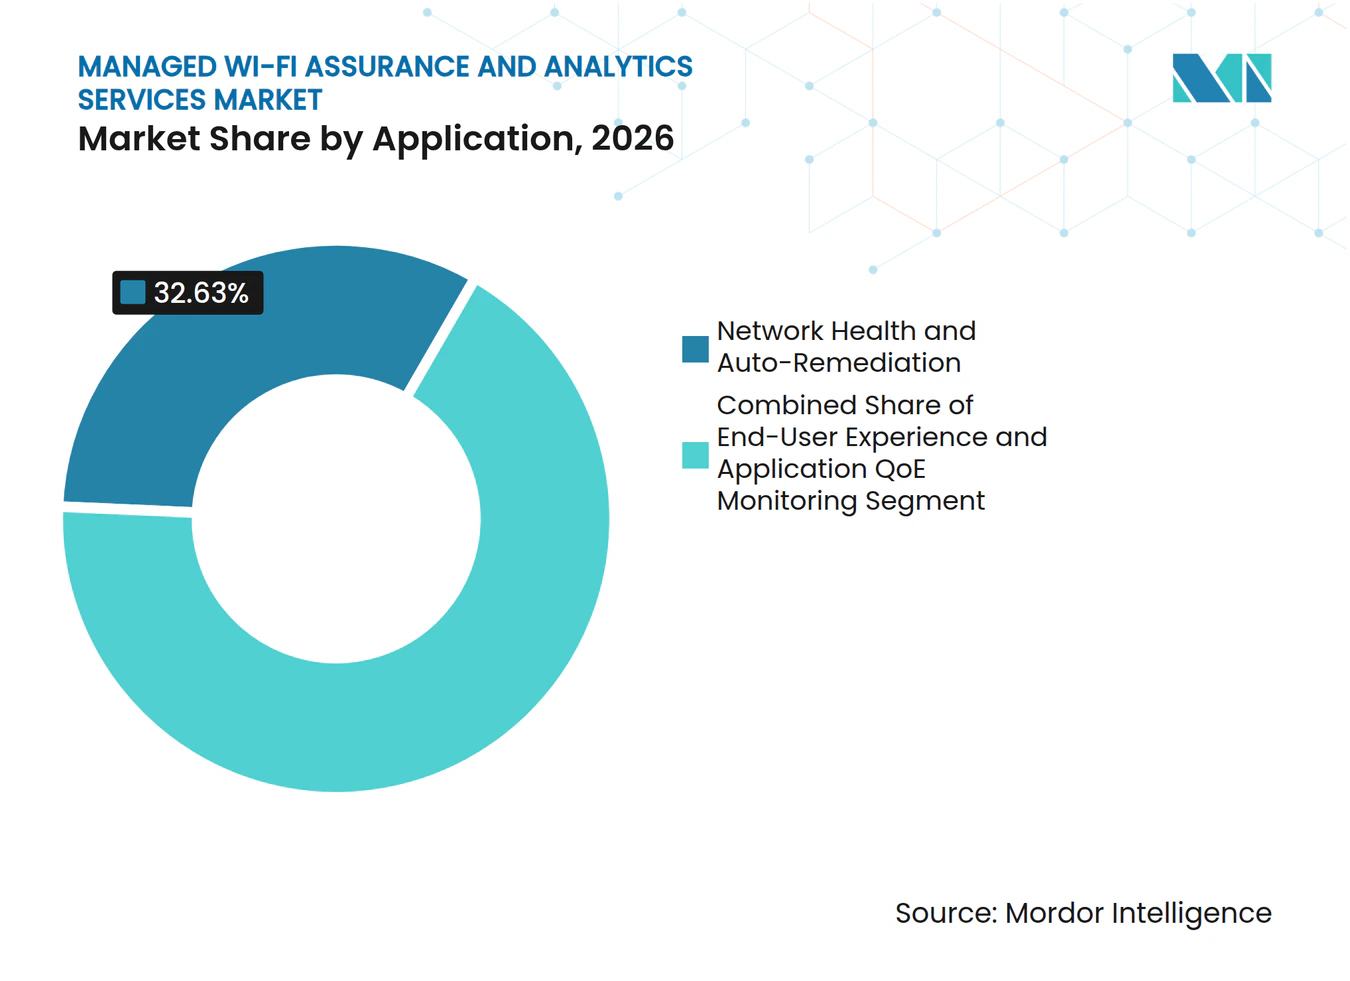
Predictive Operations Move Beyond Basic MonitoringNetwork health, performance assurance, and auto-remediation held 32.63% of revenue in 2026, making these functions the operational base of many managed service contracts. They address radio conditions, service commitments, root-cause analysis, and corrective actions, which helps enterprises maintain reliable connections for staff, guests, connected devices, and operational applications. The scope extends beyond checking whether an access point is online because it considers how devices join the network, how traffic performs, and whether recurring faults can be isolated before they become wider disruptions. Providers can use this data to show whether agreed service conditions are being met across locations that face different usage patterns. This foundation is central to the Managed Wi-Fi assurance and analytics services market because more specialized analytics functions depend on sustained operational visibility.
Predictive maintenance and automated remediation are projected to expand at a 17.46% CAGR through 2032 as buyers shift assurance spending toward avoiding outages instead of responding after users are affected. Automated tools can identify recurring patterns and prepare service teams to resolve likely faults earlier, particularly where video calls, enterprise software, and collaboration platforms depend on stable wireless conditions. Location intelligence and venue analytics also support retail, hospitality, and smart-building sites that monitor presence, visitor activity, and the operational use of space. Security analytics, wireless intrusion prevention, and device compliance remain important in regulated deployments, where assurance and security responsibilities are increasingly assessed together. The Wi-Fi Alliance identifies WPA3 and related enterprise security capabilities as part of the current enterprise wireless environment[3], extending the Managed Wi-Fi assurance and analytics services market from network observation into security-aligned support.

By End User:
Industrial Sites Create Specialized DemandCorporate offices and financial services accounted for 27.31% of the Managed Wi-Fi assurance and analytics services market size in 2026, supported by high-density office networks and strict expectations for reliability at headquarters, trading environments, and branch locations. Existing contracts can expand as more applications, employee devices, and collaboration tools depend on wireless access throughout the working day. Financial services buyers also value formal operating controls, clear performance reporting, and the ability to review service outcomes across multiple sites. Corporate users need dependable connectivity for hybrid work, employee mobility, and applications that cannot tolerate repeated interruptions. These requirements create a durable demand base for the Managed Wi-Fi assurance and analytics services market across established enterprise estates.
Manufacturing, warehousing, and logistics are projected to expand at an 18.47% CAGR through 2032 as Industry 4.0 deployments add autonomous guided vehicles, connected workers, and real-time quality control sensors to industrial networks. These applications need dependable handoffs and active monitoring for moving assets, which creates requirements that traditional office-focused service designs may not fully address. Retail, hospitality, sports, and entertainment venues also use assurance and location analytics to improve guest experience and support site operations. Broadband and telecommunications providers are extending managed in-home Wi-Fi services as subscriber experience becomes a useful way to reduce churn. Plume stated that its platform draws insights from more than 50 million homes and 600 million connected devices across 450 internet service providers in 60 countries, while health care, life sciences, education, and academic institutions are adopting cloud-managed assurance to reduce reliance on on-site wireless staff.
Geography Analysis
North America Managed Wi-Fi Assurance and Analytics Services Market
North America held 36.27% of the Managed Wi-Fi assurance and analytics services market share in 2026, supported by significant enterprise managed-service spending, mature cloud infrastructure, and early Wi-Fi 7 adoption. Cisco reported a 23% increase in Wi-Fi 6E and Wi-Fi 7 access point deployments across its 5 million managed networks during the second half of 2025.[4] This refresh activity can increase the scope of related assurance contracts as enterprises reconsider the management and analytics layers around new hardware. Canada and Mexico add demand through carrier-managed Wi-Fi models and broadband investment programs. The high number of vendors in North America can pressure margins while favoring providers that can show clear operational savings and reliable service outcomes.
APAC Managed Wi-Fi Assurance and Analytics Services Market
Asia-Pacific is projected to expand at a 16.53% CAGR through 2032, as enterprise digitalization in China, India, South Korea, and Japan increases the number of sites and devices requiring centralized wireless support. Spectrum policy influences the opportunity because access to the 6 GHz band supports Wi-Fi 6E and Wi-Fi 7 deployments, and Vietnam and Indonesia adopted frameworks permitting these technologies in 2025. Manufacturing deployments in Japan and South Korea add dense IoT telemetry that requires active monitoring and analytics. China is a major campus-network opportunity, while India combines business digitization with an evolving wireless policy environment. The Managed Wi-Fi assurance and analytics services market can gain in Asia-Pacific where providers adapt their platforms to varied regulatory and operating conditions.
EMEA and South America Managed Wi-Fi Assurance and Analytics Services Market
Europe maintains enterprise demand led by Germany, the United Kingdom, and France across financial services, manufacturing, and public-sector uses, with Wi-Fi 7 refresh activity, smart buildings, and hospitality networks supporting managed services. South America, the Middle East, and Africa are less mature but offer room for outsourced assurance where internal engineering capacity is limited, especially in smart-city, hospitality, and broadband settings. The Wireless Broadband Alliance found that 33% of respondents had deployed city-wide public Wi-Fi and 39% planned deployments for 2026 or 2027. The United Arab Emirates, Saudi Arabia, South Africa, and Nigeria provide an early base for managed public or in-home Wi-Fi services.
Competitive Landscape
Market Concentration
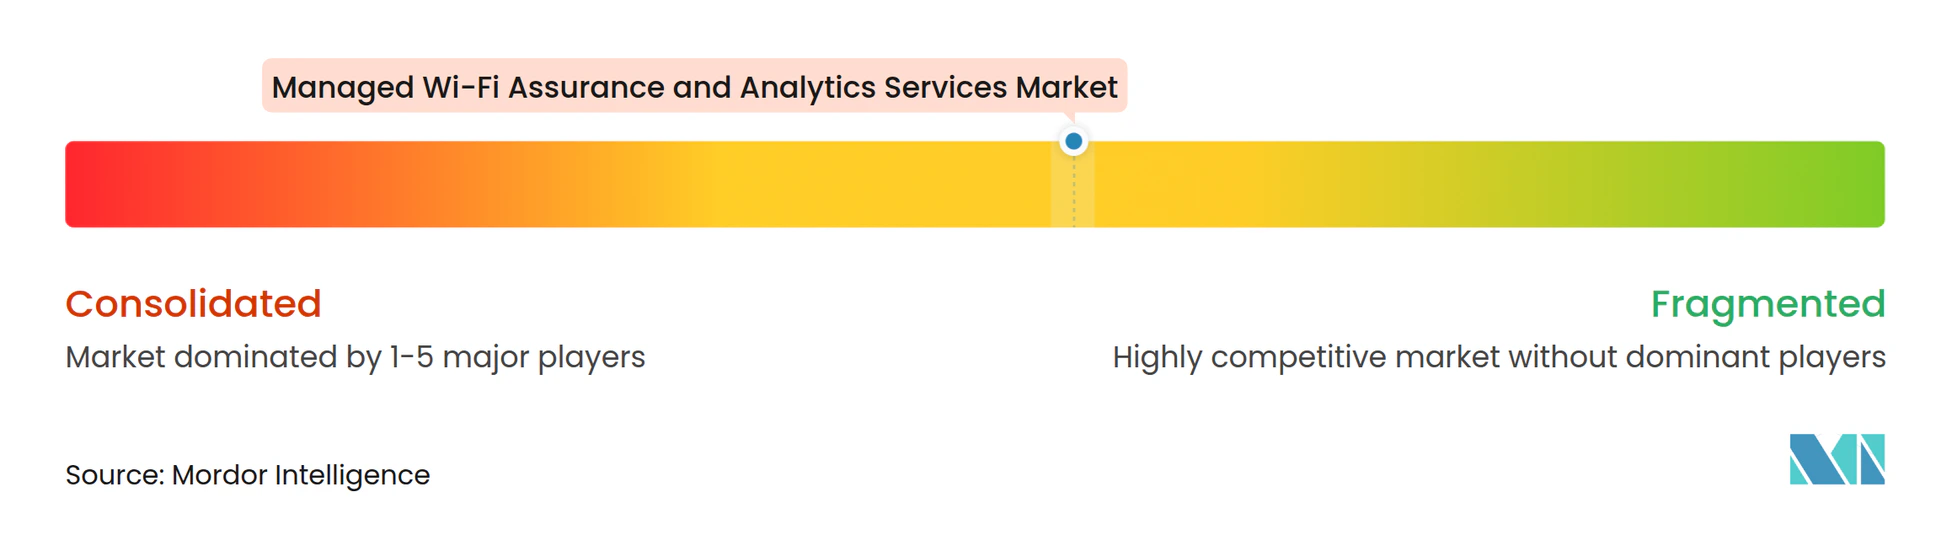
The Managed Wi-Fi assurance and analytics services market includes established platform vendors and a broad set of specialized analytics providers, creating a moderately fragmented full-stack layer and a more fragmented specialist field. Full-stack vendors connect access point hardware, cloud management, assurance software, and radio resource controls, which can raise switching costs because customer operating processes and performance history become tied to one platform. Specialized firms compete where they have deep knowledge of a user base or service environment, and Plume serves internet service providers with subscriber-level network intelligence drawn from a large installed base of connected homes and devices. Vendors also participate in standards work because future service requirements can influence product design, qualification, and buyer expectations. This combination of platform depth and specialized data gives the Managed Wi-Fi assurance and analytics services market different competitive paths rather than a single vendor model.
Multi-vendor assurance remains an open area because many organizations operate access points and related equipment from more than one supplier, making a unified management view dependent on telemetry normalization and correlation across separate systems. Providers that support heterogeneous wireless estates without requiring a full hardware replacement can address this customer need, especially where existing investment makes single-vendor replacement costly. Broadband Forum TR-369 and Wireless Broadband Alliance operator-managed Wi-Fi frameworks support more open service models for providers with varied residential gateway fleets. Buyers compare providers on measurable operational outcomes, integration depth, privacy controls, and their ability to serve widely distributed sites with different service needs. The Managed Wi-Fi assurance and analytics services industry can therefore support integrated platforms as well as hardware-neutral analytics overlays.
Strategic product releases show how leading companies are responding. In May 2026, Extreme Networks updated Extreme Platform ONE and introduced the AP5060, AP3020, and AP3060 Wi-Fi 7 series for industrial, education, health care, and retail uses, while Plume described an open, carrier-grade agentic AI platform in February 2026 to monitor, diagnose, and resolve subscriber connectivity issues across network infrastructure and customer premises equipment. In October 2025, Airties introduced Nova, a software-as-a-service testing platform for broadband providers managing device lifecycle and Wi-Fi 6E and Wi-Fi 7 updates. These moves show that the Managed Wi-Fi assurance and analytics services market is addressing automation, device diversity, and service quality together.
Managed Wi-Fi Assurance and Analytics Services Industry Leaders
-
Cisco Systems, Inc.
-
Hewlett Packard Enterprise
-
CommScope, Inc.
-
Extreme Networks, Inc.
-
Fortinet, Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Wi-Fi Assurance and Analytics Services Market Companies Covered in this Report
- Cisco Systems, Inc.
- Hewlett Packard Enterprise
- CommScope, Inc.
- Extreme Networks, Inc.
- Ubiquiti Inc.
- Huawei Technologies Co., Ltd.
- Fortinet, Inc.
- Arista Networks, Inc.
- Cambium Networks Corporation
- TP-Link Corporation Limited
- D-Link Corporation
- NETGEAR, Inc.
- Plume Design, Inc.
- ASSIA, Inc.
- ADTRAN Holdings, Inc.
- Airties S.A.S.
- Cloud4Wi S.r.l.
- Purple WiFi Limited
- Skyfii Limited
- RetailNext, Inc.
- Cloud5 Communications, LLC
- Open Networking Foundation
Recent Industry Developments in Managed Wi-Fi Assurance and Analytics Services Market
- September 2026: Plume Design announced a commercial deployment with Mobinet, Mongolia's broadband provider, to power the mobihome service with AI-optimized Wi-Fi, advanced cybersecurity protection, parental controls, and real-time home network management. The deployment extended Plume's internet service provider footprint to its 60th country.
- October 2025: Airties unveiled the Nova connectivity experience testing platform at Network X Paris. The software-as-a-service testing solution is designed to help broadband service providers accelerate time to market, reduce testing costs, and maintain performance across device lifecycles, including Wi-Fi 6E and Wi-Fi 7 firmware updates.
- August 2025: Plume Design and Advanced Media Technologies launched the SuperPod Wi-Fi 7 mesh access point exclusively for National Cable Television Cooperative members. The launch supported Plume's hardware-agnostic strategy by combining its software-as-a-service platform with third-party certified access points.
- July 2025: Extreme Networks launched Extreme Platform ONE as an all-in-one AI-powered networking platform. The platform integrated Wi-Fi, switching, security, and analytics through one management interface and included third-party device management.
Global Managed Wi-Fi Assurance and Analytics Services Market Report Scope
Managed Wi-Fi assurance and analytics services are comprehensive, outsourced enterprise IT solutions where a third-party service provider leverages AI, ML, and cloud-managed telemetry to proactively optimize, troubleshoot, and secure a company's wireless network infrastructure. Moving beyond basic connectivity monitoring, these services continuously track real-time end-user experiences and extract actionable business intelligence from network traffic patterns under strict Service Level Agreements (SLAs).
The Managed Wi-Fi Assurance and Analytics Services Market Report is Segmented by Service Model (Fully Managed Services, Co-Managed / Partially Managed Services, and Self-Managed / SaaS-Enabled Analytics and Assurance Platforms), Deployment Mode (Cloud-Based, On-Premises, and Hybrid), Application (Network Health, Performance Assurance, and Auto-Remediation, End-User Experience and Application QoE Monitoring, Location Intelligence, Presence and Venue Analytics, Wireless Security, WIPS, and Device Compliance Analytics, and Predictive Maintenance and Automated Remediation), End User (Corporate Offices and Financial Services, Retail, Hospitality, Sports, and Entertainment Venues, Broadband, Carrier, and Telecommunications Service Providers, Healthcare and Life Sciences, Education and Academic Institutions, Manufacturing, Warehousing and Logistics, and Other End Users), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Fully Managed Services |
| Co-Managed / Partially Managed Services |
| Self-Managed / SaaS-Enabled Analytics & Assurance Platforms |
| Cloud-Based |
| On-Premises |
| Hybrid |
| Network Health, Performance Assurance & Auto-Remediation |
| End-User Experience & Application QoE Monitoring |
| Location Intelligence, Presence & Venue Analytics |
| Wireless Security, WIPS & Device Compliance Analytics |
| Predictive Maintenance and Automated Remediation |
| Corporate Offices and Financial Services |
| Retail, Hospitality, Sports, and Entertainment Venues |
| Broadband, Carrier, and Telecommunications Service Providers |
| Healthcare and Life Sciences |
| Education and Academic Institutions |
| Manufacturing, Warehousing and Logistics |
| Other End Users |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Service Model | Fully Managed Services | |
| Co-Managed / Partially Managed Services | ||
| Self-Managed / SaaS-Enabled Analytics & Assurance Platforms | ||
| By Deployment | Cloud-Based | |
| On-Premises | ||
| Hybrid | ||
| By Application | Network Health, Performance Assurance & Auto-Remediation | |
| End-User Experience & Application QoE Monitoring | ||
| Location Intelligence, Presence & Venue Analytics | ||
| Wireless Security, WIPS & Device Compliance Analytics | ||
| Predictive Maintenance and Automated Remediation | ||
| By End User | Corporate Offices and Financial Services | |
| Retail, Hospitality, Sports, and Entertainment Venues | ||
| Broadband, Carrier, and Telecommunications Service Providers | ||
| Healthcare and Life Sciences | ||
| Education and Academic Institutions | ||
| Manufacturing, Warehousing and Logistics | ||
| Other End Users | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed Wi-Fi assurance and analytics services market?
The sector is projected to expand from USD 3.76 billion in 2026 and USD 4.38 billion in 2027 to USD 8.79 billion by 2032, at a 14.95% CAGR.
What is driving demand for managed Wi-Fi assurance services?
Demand is supported by distributed sites, connected devices, Wi-Fi 7 upgrades, and the need to monitor user experience rather than network uptime alone.
Which service model leads managed Wi-Fi assurance adoption?
Fully managed services held 39.53% of revenue in 2026, while co-managed and partially managed services are projected to expand at a 15.93% CAGR through 2032.
Why are cloud-based Wi-Fi assurance platforms important?
Cloud-based platforms held 62.13% of revenue in 2026 and are projected to expand at a 16.24% CAGR through 2032 because they centralize management across sites.
Which end users are expanding their Wi-Fi assurance spending most quickly?
Manufacturing, warehousing, and logistics are projected to expand at an 18.47% CAGR through 2032 as connected industrial operations require dependable wireless coverage.
Which region is expected to expand fastest through 2032?
Asia-Pacific is projected to expand at a 16.53% CAGR through 2032, supported by enterprise digitalization and expanded support for newer Wi-Fi standards.