
Managed Sustainable IT Compliance Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 14.75 Billion |
| Market Size (2032) | USD 28.14 Billion |
| Growth Rate (2027 - 2032) | 13.79 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Europe |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Sustainable IT Compliance Services Market Analysis by Mordor Intelligence
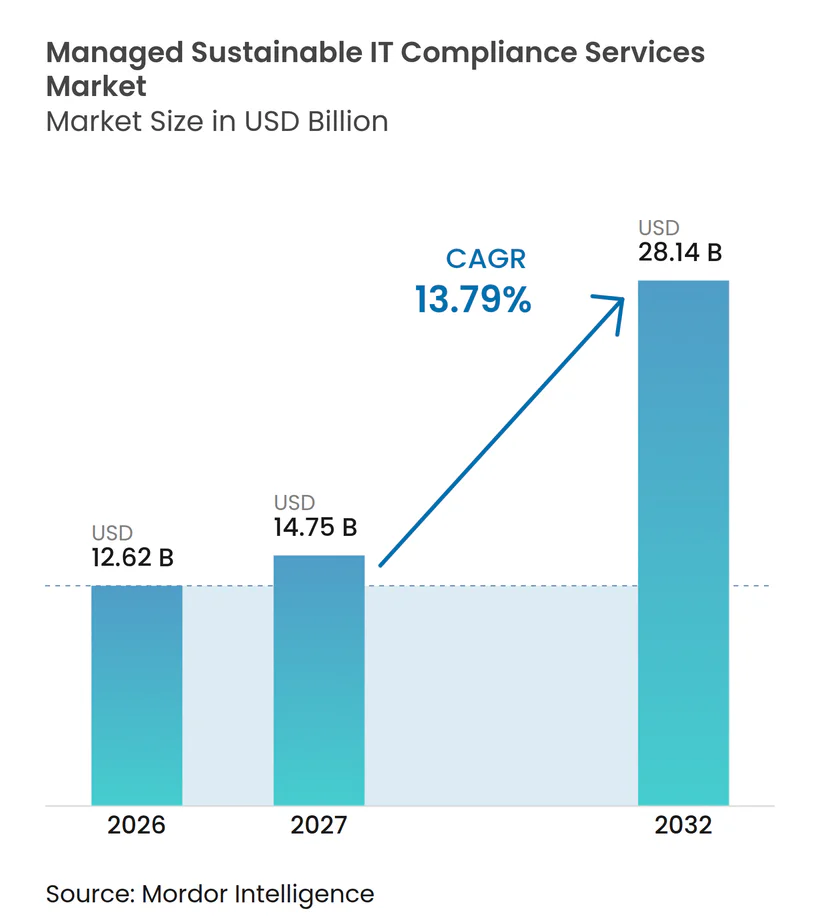
The Managed sustainable IT compliance services market size is projected to expand from USD 12.62 billion in 2026 and USD 14.75 billion in 2027 to USD 28.14 billion by 2032, registering a CAGR of 13.79% between 2027 to 2032. Regulation is moving sustainable IT work from periodic reporting into operating processes that can be reviewed by an external assurance provider. The Managed sustainable IT compliance services market benefits when reporting obligations require clear data trails from IT assets, energy use, procurement records, and supplier emissions. Data center expansion also creates a direct link between compliance spending and the practical management of power, cooling, renewable electricity, and carbon data. Providers are responding by combining reporting workflows with cloud operations, asset management, and supplier engagement services. This favors firms that can integrate data across existing enterprise systems while maintaining evidence that can withstand assurance reviews.
Key Report Takeaways
- By service type, Sustainability Reporting and Compliance Management held 34.10% revenue share in 2026, while Energy Management and IT Decarbonization are projected to expand at a 15.52% CAGR through 2032.
- By delivery model, cloud-based services held 57.91% revenue share of the managed sustainable IT compliance services market in 2026 and are projected to expand at a 15.24% CAGR through 2032.
- By enterprise size, large enterprises held 75.42% revenue share in 2026, while SMEs are projected to expand at a 16.10% CAGR through 2032.
- By end-user industry, IT and telecommunications held 25.59% revenue share of the managed sustainable IT compliance services market in 2026, while healthcare and life sciences are projected to expand at a 15.79% CAGR through 2032.
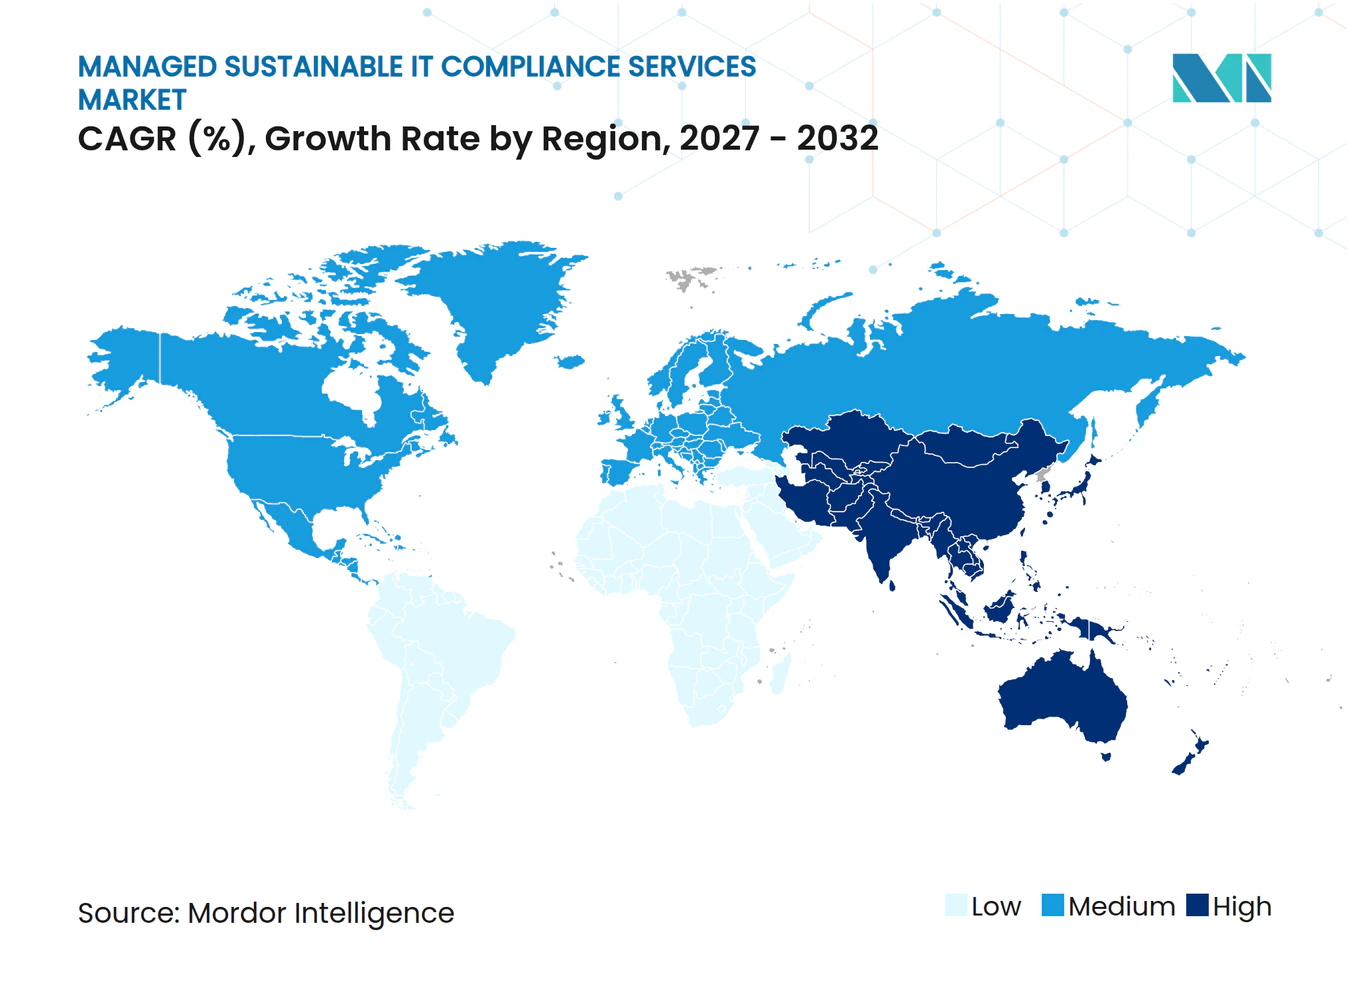
- By geography, Europe held 36.22% revenue share in 2026, while Asia-Pacific is projected to expand at a 17.10% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Sustainable IT Compliance Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Mandatory Sustainability Disclosure and Assurance Requirements | +2.8% | Global, concentrated in EU and UK | Short term (≤ 2 years) |
| Enterprise Net-Zero Commitments and Supplier Screening | +1.9% | Global, early leadership in Europe and North America | Medium term (2-4 years) |
| Hyperscale Data Center and AI Workload Expansion | +2.5% | North America, Asia-Pacific core, spill-over to Europe | Short term (≤ 2 years) |
| Rising Energy Costs and Measurable IT Efficiency Savings | +1.6% | Global, particularly intense in Europe and Japan | Medium term (2-4 years) |
| Cross-Framework Control Reuse and Continuous Compliance Automation | +1.4% | Global, leadership in EU and North America | Medium term (2-4 years) |
| Procurement-Embedded Carbon and Compliance Evidence Requirements | +1.2% | UK, EU, Australia, growing Asia-Pacific influence | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Mandatory Sustainability Disclosure and Assurance Requirements
Regulatory deadlines are changing enterprise IT purchases more directly than discretionary technology cycles. CSRD disclosures require companies in scope to address energy consumption across endpoints, servers, and networks, hardware end-of-life handling, and Scope 3 Category 1 emissions from hardware procurement. ESRS 2 applies to all in-scope entities and calls for a traceable path from source records and emission factors to the reported result. The Managed sustainable IT compliance services market therefore places greater value on managed data collection than on isolated reporting advice. The Omnibus I changes and voluntary SME standard apply from FY2027, giving providers a defined approach for smaller organizations while preserving core requirements for in-scope companies. Providers that cannot preserve data lineage face a weaker position as assurance cycles become more demanding.
Enterprise Net-Zero Commitments and Supplier Screening
Supplier carbon screening is becoming a contractual requirement rather than a voluntary practice. The UK Procurement Policy Note 016, effective February 2025, sets standard contractual terms for carbon reduction schedules and contract-specific greenhouse gas targets.[1] The Joint Alliance for CSR assessed 734 companies through its 2025 Supplier Engagement Program, using a 5-level sustainability maturity model. TeamViewer found that generic spend-based factors had overstated supplier-linked Scope 3 emissions by a median 75% when it used supplier-specific emission intensities verified against ISO 14064. The managed sustainable IT compliance services market can address this gap with recurring supplier data collection and verification work. These requirements also extend compliance demand beyond the entity subject to a reporting rule and into its Tier 1 supplier base.
Hyperscale Data Center and AI Workload Expansion
AI infrastructure and energy regulation are creating a sustained need for services that connect data center operations to compliance evidence. Data center electricity use surged 17% in 2026, while investment by 5 large technology companies exceeded USD 400 billion in 2025 and is set to increase 75% in 2026. The IEA expects energy demand from AI-optimized data centers to triple by 2030. A peer-reviewed estimate places AI data center electricity demand at 239-295 TWh in 2030. Germany requires a PUE of 1.2 or lower for new data centers from July 2026 and 100% renewable electricity from January 2027. The managed sustainable IT compliance services market benefits when providers combine PUE improvement, renewable procurement evidence, and carbon attribution in a single managed service.
Rising Energy Costs and Measurable IT Efficiency Savings
The Managed sustainable IT compliance services market gains relevance when efficiency gains can be measured and verified. A Dell-sponsored assessment found that moving from 16th to 17th generation PowerEdge servers could reduce power draw by up to 33% for CPU-based AI inference workloads. The assessment estimated annual savings above USD 170,000 for a one-third refresh of a 5,000-server estate. A peer-reviewed network switch refresh analysis reported 58.53% energy efficiency improvement, USD 440,000 in operating savings, and a 30.5% carbon footprint reduction from a USD 220,000 investment. Schneider Electric reported that its internal EcoStruxure IT program reduced energy consumption and emissions by 30%. These results support service offerings that monitor efficiency gains and convert them into auditable reporting data.
Restraints Impact Analysis of Managed Sustainable IT Compliance Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Cost of Sustainable IT Transformation | -2.2% | Global, especially acute for SMEs and emerging markets | Short term (≤ 2 years) |
| Shortage of Sustainable IT and Compliance Specialists | -1.9% | Global, acute in North America and Europe | Medium term (2-4 years) |
| Fragmented Multi-Cloud and Scope 3 Data Lineage | -1.5% | Global, concentrated in multi-cloud enterprises | Medium term (2-4 years) |
| Uncertain Renewable Availability and Workload Variability | -1.1% | Asia-Pacific core, parts of Europe and South America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Upfront Cost of Sustainable IT Transformation
Upfront costs remain a material barrier, especially for organizations outside the largest enterprise tier. Continuous, auditable data collection often requires integration with ERP systems, HR platforms, procurement portals, and cloud billing APIs. This is an operating model change rather than a small software purchase. Mid-market companies can face customer pressure to provide Scope 3 data without the budget for a full managed service stack. ISO 14001 certification can provide a lower-cost entry point where supplier qualification programs use it as a data-readiness indicator.[2] The Managed sustainable IT compliance services market needs service packages that can lower initial adoption costs without losing the controls required for reliable reporting.
Shortage of Sustainable IT and Compliance Specialists
Sustainable IT compliance requires a combination of environmental accounting knowledge, infrastructure operations experience, and regulatory understanding. These skills are difficult to source because they are rarely developed together within one role. The shortage affects both prospective clients and managed service providers. Automation can reduce manual work in data collection and framework mapping. However, assurance preparation and advisory decisions still require people with specialized qualifications. The managed sustainable IT compliance services market is, therefore, constrained by skills even as it creates demand for automation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Sustainable IT Compliance Services Market Segment Analysis
By Service Type:
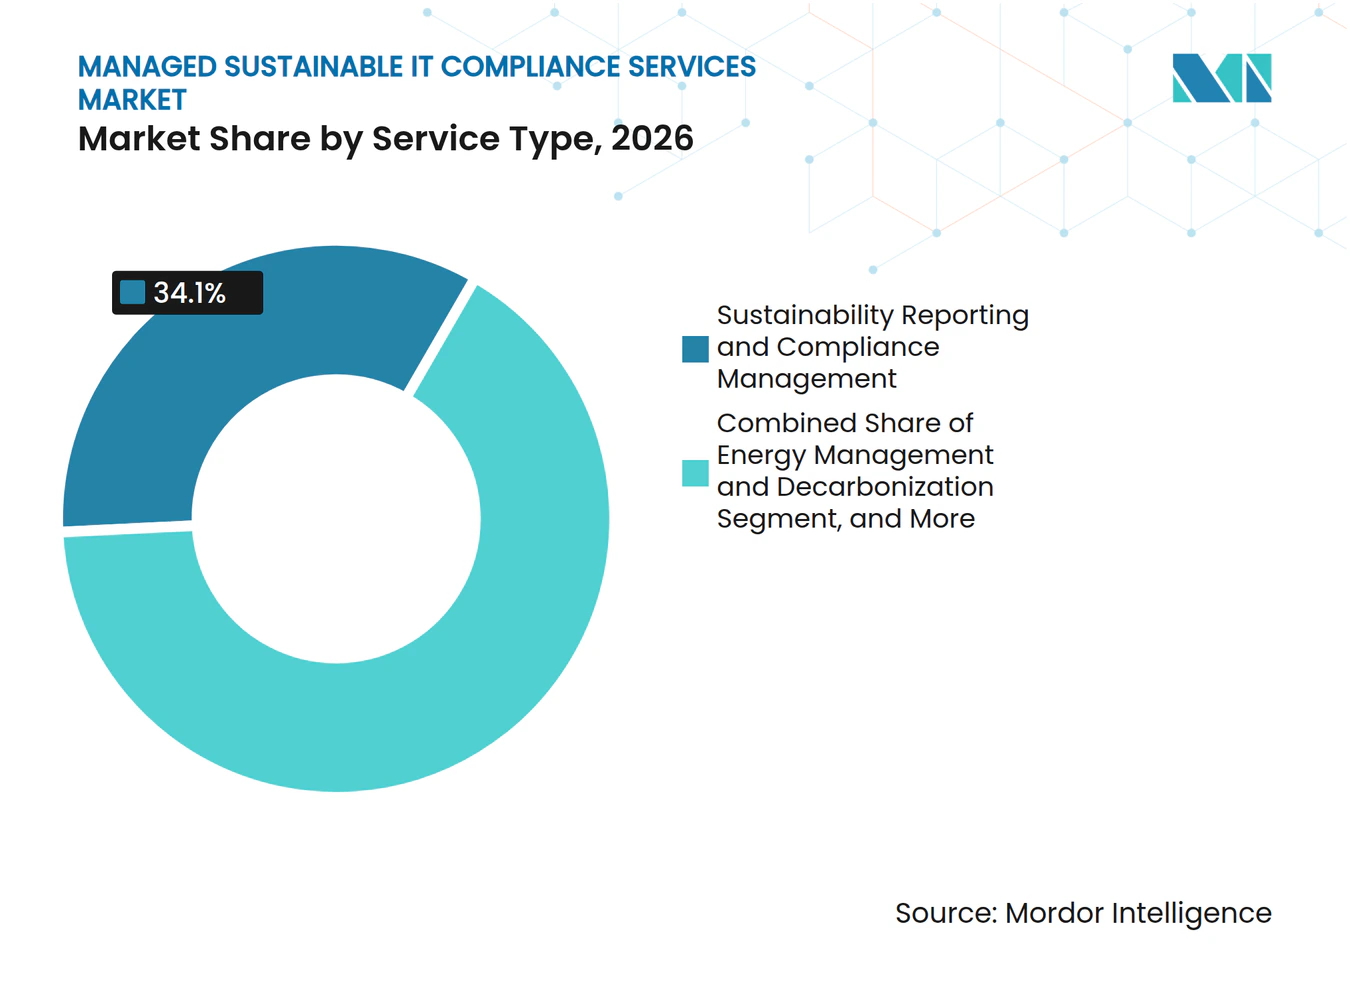
Reporting Infrastructure Leads While Decarbonization Services AccelerateSustainability Reporting and Compliance Management held 34.10% of market revenue in 2026. The Managed sustainable IT compliance services market gives this service type a leading role because regulatory deadlines require data collection infrastructure that supports third-party assurance. Energy Management and IT Decarbonization is projected to expand at a 15.52% CAGR through 2032. The segment benefits from binding data center efficiency and renewable electricity requirements in Germany, Singapore, and Japan.
Reporting and energy work reinforce one another because meter-level operating data supports climate disclosures. Sustainable IT Asset Lifecycle Management gains relevance as equipment refresh decisions expose embedded procurement emissions and end-of-life reporting needs. Supply Chain Sustainability and Supplier Compliance also gains demand as enterprises collect more structured supplier data. The Joint Alliance for CSR program shows how annual assessments can create a recurring supplier engagement process. The Managed sustainable IT compliance services industry is moving toward connected services rather than stand-alone reporting products. The Managed sustainable IT compliance services market can capture this demand when reporting and operating data use common controls.



By Delivery Model:
Cloud-Based Services Extend Their LeadCloud-based services held 57.91% of market revenue in 2026 and are projected to expand at a 15.24% CAGR through 2032. The managed sustainable IT compliance services market favors these platforms because they can collect data once and map it across several disclosure frameworks.[3] CDP and GRI released a mapping tool in October 2025 to connect climate and energy disclosures across their frameworks. SAP added IFRS S1 and S2 capabilities across Sustainability Footprint Management and Sustainability Control Tower in September 2026.
On-premises services remain relevant for regulated clients with material data-residency requirements. Financial services and government-related organizations often need local data processing under privacy and sovereignty rules. Hybrid delivery can maintain continuity for clients with legacy systems while adding cloud-based reporting workflows. Germany's renewable electricity mandate and Japan's PUE benchmarks favor providers that can place verified energy data within operational systems. The managed sustainable IT compliance services market consequently rewards delivery models that make evidence available without disrupting established infrastructure. This position strengthens when clients need both local processing and common reporting workflows.
By Enterprise Size:
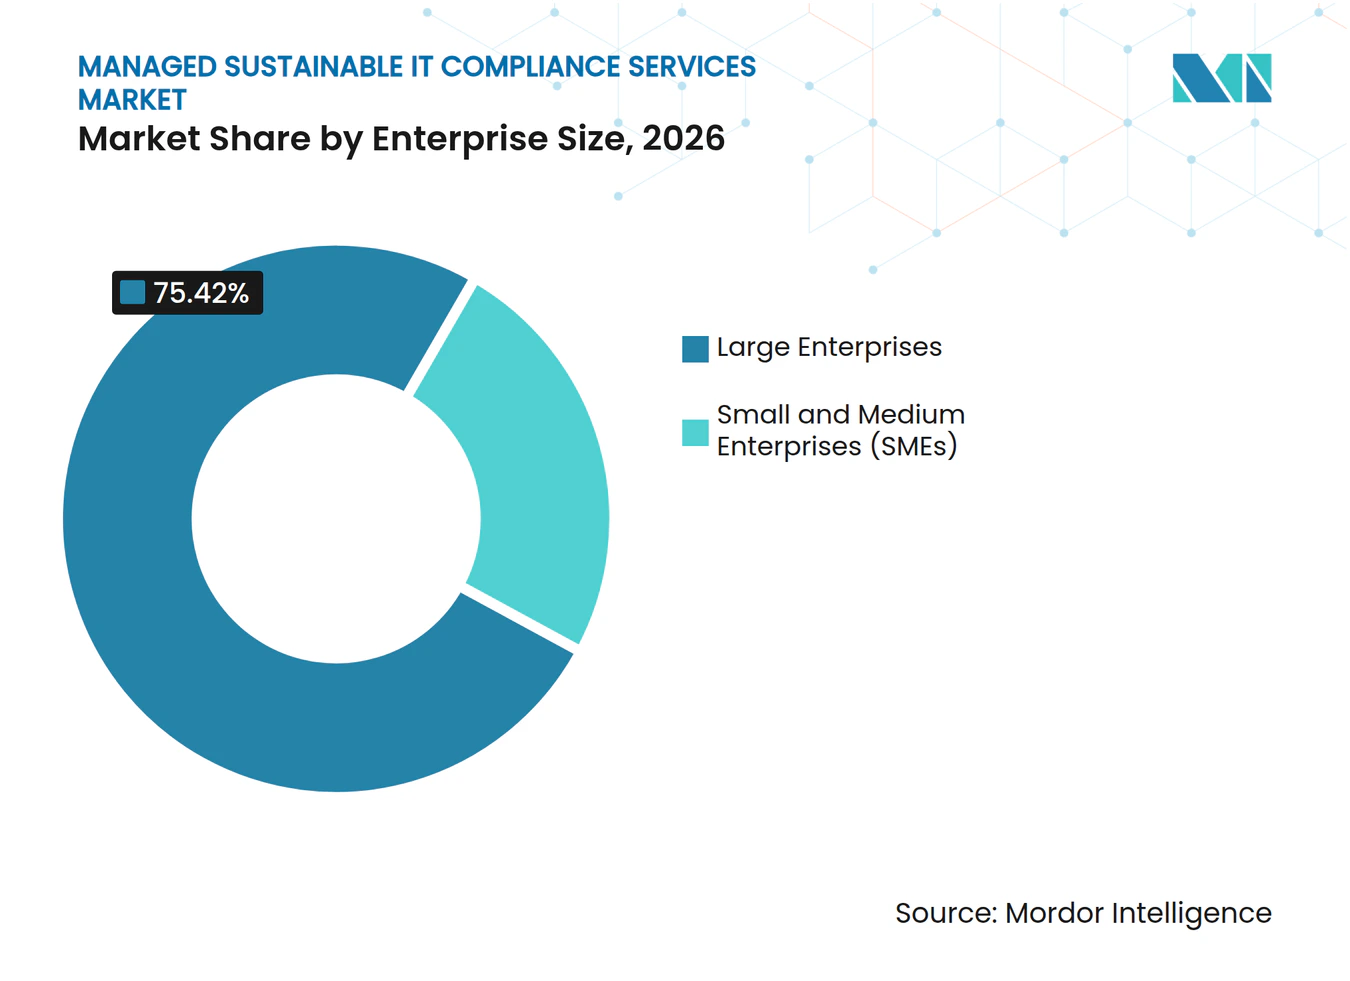
Large Enterprises Lead While SMEs AccelerateLarge enterprises held 75.42% revenue share in 2026 because they face direct regulatory exposure and can fund broad managed services programs. They commonly need reporting, energy optimization, asset lifecycle management, and supplier compliance controls at the same time. SMEs are projected to expand at a 16.10% CAGR through 2032. The Managed sustainable IT compliance services market size for SMEs is supported by requests from large customers for structured supplier emissions information.
The Omnibus I value-chain cap from January 2027 moderates requests to suppliers with fewer than 1,000 employees. It does not remove the need to provide material information to major customers. The voluntary VSME standard gives providers a basis for more standardized SME offerings. ISO 14001 can also act as an entry point when procurement teams use environmental management certification as a qualification signal. Providers that simplify deployment and price services for smaller suppliers can address a clear adoption gap. The managed sustainable IT compliance services market can become more accessible when providers package essential controls for smaller companies.

By End-User Industry:
IT and Telecommunications Lead While Healthcare Advances FastestIT and telecommunications held 25.59% revenue share in 2026 because companies in this sector face both infrastructure and corporate reporting exposure. They operate systems that consume energy while supplying technology to clients that need associated emissions data. Healthcare and life sciences is projected to expand at a 15.79% CAGR through 2032. Its requirements span CSRD, environmental classification rules, and technology architecture obligations for medical device manufacturers.
Life sciences organizations need stronger supply chain data collection as they improve Scope 3 disclosure coverage. IT and telecommunications providers also need to document their own Scope 1, 2, and 3 impacts. BFSI has a meaningful need for data controls because sustainability assessment can extend to financing and investment activity. Manufacturing, energy and utilities, retail and e-commerce, and other end users participate at different spending levels. The Managed sustainable IT compliance services market requires control designs suited to each sector's operating systems, suppliers, and reporting responsibilities. The Managed sustainable IT compliance services market must therefore support different evidence needs without fragmenting underlying data controls.
Geography Analysis
Europe Managed Sustainable IT Compliance Services Market
Europe held 36.22% of market revenue in 2026. CSRD requires in-scope large companies to address energy use, hardware disposal, and hardware procurement emissions. Germany requires qualifying data centers to register and requires a PUE of 1.2 or lower for new facilities from July 2026.
United Kingdom and France Managed Sustainable IT Compliance Services Market
European data center PUE values ranged from 1.15 to 1.66, with an EU average of 1.36, in a 2025 assessment prepared for the European Commission.[4] The UK adds public procurement demand through PPN 006 and PPN 016, including carbon reduction plans and contract-level monitoring. France's AMF asked listed companies to provide measurable and time-bound greenhouse gas reduction targets in line with ESMA recommendations. The managed sustainable IT compliance services market is the largest in Europe because the region has dense reporting and operating requirements.
APAC, the Americas and MEA Managed Sustainable IT Compliance Services Market
Asia-Pacific is projected to expand at a 17.10% CAGR through 2032. Singapore passed its Digital Infrastructure Bill in October 2026, requiring licensing and adjustable PUE and clean-energy standards for data centers above 3 MW critical IT load. Japan targets a PUE of 1.4 for large data center operators by FY2030 with annual reporting obligations. NTT DATA converted 13 Japanese data centers to 100% renewable electricity in FY2025. North America remains relevant to providers serving large data center operators. The Managed sustainable IT compliance services market also has earlier-stage opportunities in South America, the Middle East, and Africa, where multinational reporting programs and digital infrastructure investment are expanding the addressable base.
Competitive Landscape
Market Concentration
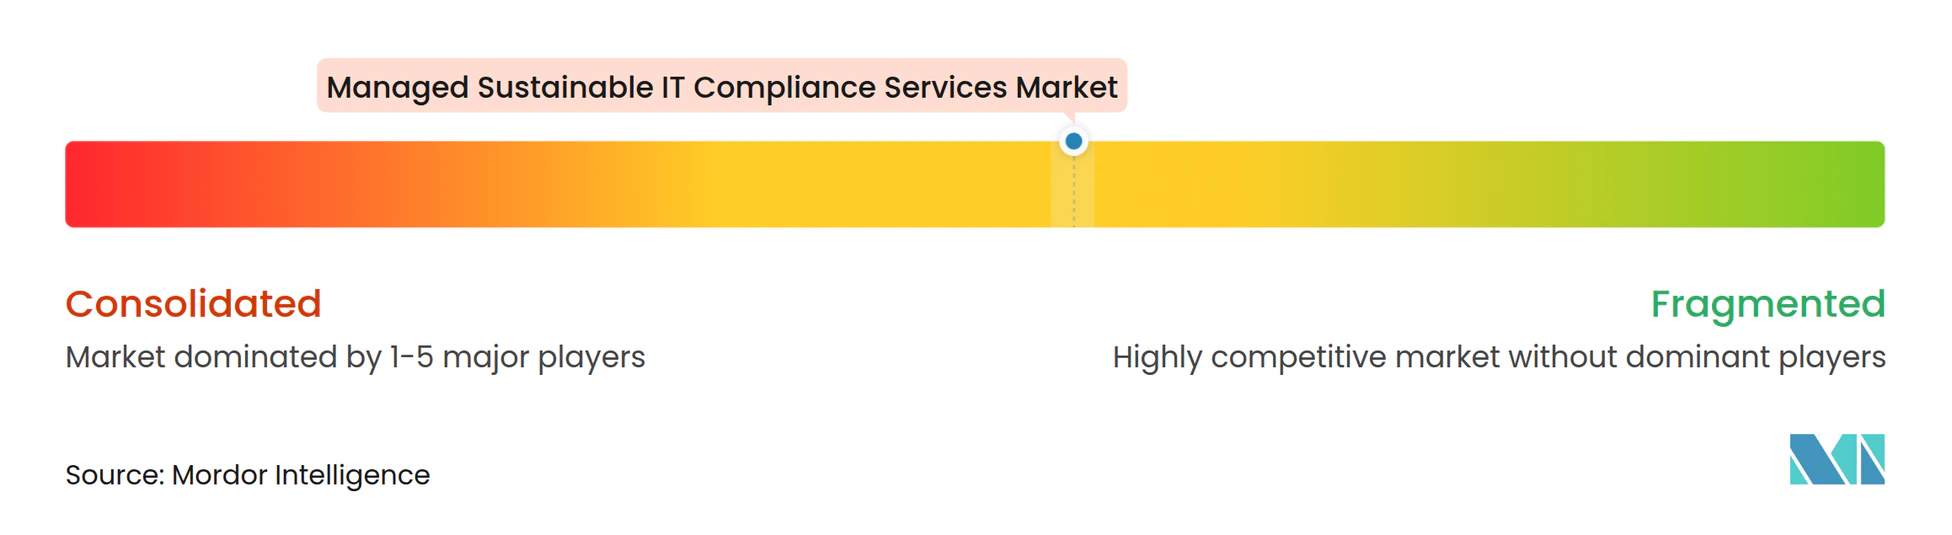
The managed sustainable IT compliance services market is moderately fragmented in the premium enterprise tier. Accenture, Capgemini, IBM, Infosys, TCS, and Wipro have a practical advantage through established managed services relationships and access to enterprise technology, procurement, and sustainability teams. Their service models increasingly join compliance automation with ERP, cloud billing, and infrastructure operations. Providers can use shared data controls across several reporting frameworks.
Kyndryl's Sustainability Advisor on Kyndryl Bridge maps energy, emissions, water, and e-waste at the server and virtual machine level. Capgemini's ESG Lens provides pre-built connectors for SASB, GRI, and TCFD reporting, showing how service providers tailor platforms for sector needs. SAP introduced an approach in September 2026 that supports configuration across IFRS S1, IFRS S2, and ESRS E1 reporting. These examples show how the Managed sustainable IT compliance services market is shifting toward platforms that preserve a common data scope while producing several reporting outputs. The Managed sustainable IT compliance services market is also shaped by automation that allocates Scope 3 emissions across cloud and supplier environments.
Opportunity remains in the SME tier because the VSME standard provides a template for standardized packages. Supplier-specific Scope 3 records verified to ISO 14064 are another opening where a single provider has not established clear infrastructure leadership. New platform-led providers may compete on automation depth rather than on advisory headcount. Providers without assurance-ready controls face greater risk as limited assurance requirements mature.
Managed Sustainable IT Compliance Services Industry Leaders
-
Accenture PLC
-
Atos SE
-
Capgemini SE
-
Cisco Systems, Inc.
-
Dell Technologies Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Sustainable IT Compliance Services Market Companies Covered in this Report
- Accenture PLC
- Amazon Web Services, Inc.
- Atos SE
- Capgemini SE
- Cisco Systems, Inc.
- Cognizant Technology Solutions Corporation
- Dell Technologies Inc.
- Genpact Limited
- HCL Technologies Limited
- Hewlett Packard Enterprise Company
- IBM Corporation
- Infosys Limited
- Kyndryl Holdings, Inc.
- LTIMindtree Limited
- NTT DATA Group Corporation
- SAP SE
- Schneider Electric SE
- Tata Consultancy Services Limited
- Tech Mahindra Limited
- Wipro Limited
- Workiva
Recent Industry Developments in Managed Sustainable IT Compliance Services Market
- October 2026: Tata Consultancy Services partnered with ManageEngine, Zoho Corporation, to deploy enterprise IT management solutions on TCS SovereignSecure Cloud, enabling government and enterprise clients in India to manage AI and cloud workloads while meeting India's data sovereignty and regulatory compliance requirements.
- October 2026: The European Commission formally adopted the revised ESRS and the VSME voluntary standard under Omnibus I, applying from FY2027, giving managed service providers a standardized compliance framework for the SME market and a transition window for in-scope FY2026 companies.
- September 2026: SAP announced integration across SAP Sustainability Footprint Management and SAP Sustainability Control Tower, enabling ESRS E1, IFRS S2, and CDP reporting from a single data collection scope, operationalizing the "configure once, report many" compliance architecture.
- February 2026: Schneider Electric announced the addition of Carbon Usage Effectiveness, CUE, to EcoStruxure IT reporting for 2026, expanding sustainability tooling from energy consumption tracking to direct carbon intensity measurement, alongside UPS replacement forecasting in asset lifecycle management.
Global Managed Sustainable IT Compliance Services Market Report Scope
Managed sustainable IT compliance services are outsourced IT governance and operational solutions where a specialized third-party provider monitors, audits, and aligns an organization's information technology infrastructure with environmental, social, and regulatory sustainability frameworks.
The Managed Sustainable IT Compliance Services Market Report is Segmented by Service Type (Sustainability Reporting and Compliance Management, Energy Management and IT Decarbonization, Sustainable IT Asset Lifecycle Management, Supply Chain Sustainability and Supplier Compliance, and Other Service Types), Delivery Model (Cloud-Based, On-Premises, and Hybrid), Enterprise Size (Large Enterprises and Small and Medium-Sized Enterprises), End-User Industry (IT and Telecommunications, Banking, Financial Services, and Insurance [BFSI], Manufacturing, Energy and Utilities, Retail and E-Commerce, Healthcare and Life Sciences, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Sustainability Reporting and Compliance Management |
| Energy Management and IT Decarbonization |
| Sustainable IT Asset Lifecycle Management |
| Supply Chain Sustainability and Supplier Compliance |
| Other Service Types |
| On-premises |
| Cloud-Based |
| Hybrid |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| IT and Telecommunications |
| Banking, Financial Services, and Insurance (BFSI) |
| Manufacturing |
| Energy and Utilities |
| Retail and E-Commerce |
| Healthcare and Life Sciences |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Service Type | Sustainability Reporting and Compliance Management | |
| Energy Management and IT Decarbonization | ||
| Sustainable IT Asset Lifecycle Management | ||
| Supply Chain Sustainability and Supplier Compliance | ||
| Other Service Types | ||
| By Delivery Model | On-premises | |
| Cloud-Based | ||
| Hybrid | ||
| By Enterprise Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By End-User Industry | IT and Telecommunications | |
| Banking, Financial Services, and Insurance (BFSI) | ||
| Manufacturing | ||
| Energy and Utilities | ||
| Retail and E-Commerce | ||
| Healthcare and Life Sciences | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the Managed sustainable IT compliance services market size?
The Managed sustainable IT compliance services market is projected to expand from USD 12.62 billion in 2026 and USD 14.75 billion in 2027 to USD 28.14 billion by 2032, at a 13.79% CAGR.
Which service type leads managed sustainable IT compliance services?
In the Managed sustainable IT compliance services market, Sustainability Reporting and Compliance Management leads with 34.10% revenue share in 2026, reflecting the need for auditable disclosure data.
Why are cloud-based services important for sustainable IT compliance?
Cloud-based services held 57.91% revenue share in 2026 and can consolidate data collection across several reporting frameworks.
Which organizations are adopting these services fastest?
SMEs are projected to expand at a 16.10% CAGR through 2032 as customer supply chain requests bring compliance needs to smaller suppliers.
Which end-user sector is expanding fastest?
Healthcare and life sciences is projected to expand at a 15.79% CAGR through 2032 due to overlapping reporting, supply chain, and technology requirements.
Which region is projected to expand fastest?
Asia-Pacific is projected to expand at a 17.10% CAGR through 2032, supported by new data center efficiency and clean-energy rules.