
Managed Storage Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 19.25 Billion |
| Market Size (2032) | USD 28.53 Billion |
| Growth Rate (2027 - 2032) | 8.18 % |
| Fastest Growing Market | Middle East |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Storage Services Market Analysis by Mordor Intelligence
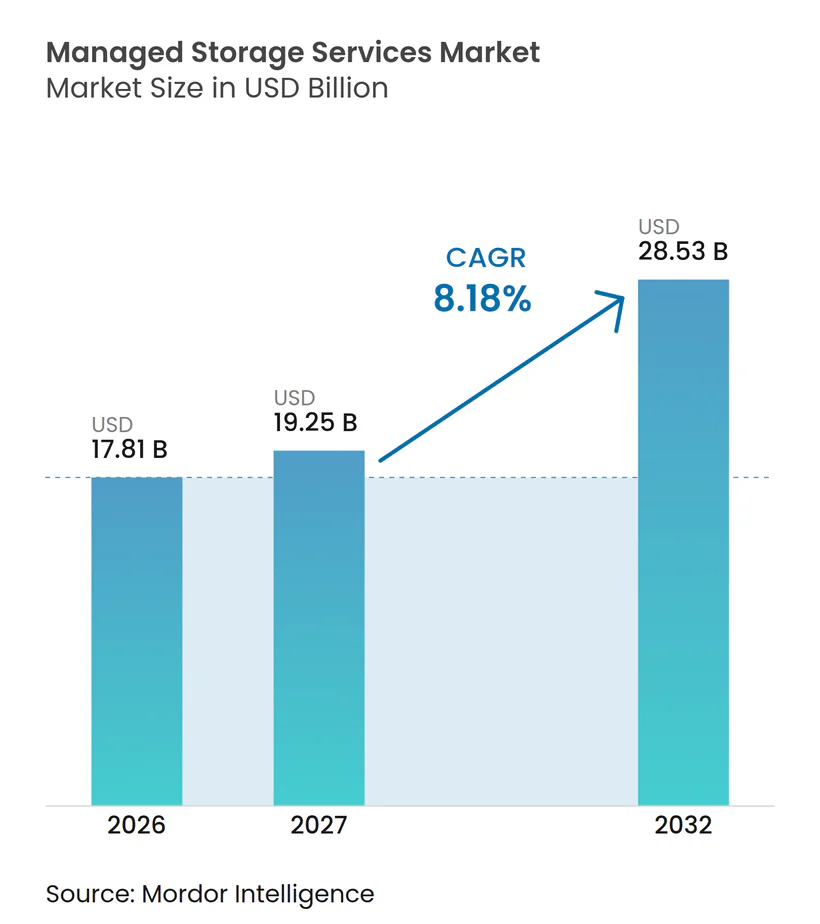
The managed storage services market size is projected to expand from USD 17.81 billion in 2026 and USD 19.25 billion in 2027 to USD 28.53 billion by 2032, registering a CAGR of 8.18% between 2027 to 2032. The managed storage services market is being shaped by persistent AI data, stricter requirements for recovery, and laws that link data storage to location and retention periods. Organizations are looking for providers that can manage capacity, security, and compliance through a single operating model. This favors managed service providers that can coordinate data across on-premises systems and cloud environments. Competitive strategies are shifting from basic capacity management toward resilience, policy enforcement, and lifecycle automation. The opportunity in the managed storage services market is strongest where organizations need predictable costs without giving up recovery performance or control of regulated data.
Key Report Takeaways
- By solution type, Storage Provisioning and Operations held 34.54% of the managed storage services market share in 2026, while Compliance and Security Management is projected to expand at a 9.67% CAGR through 2032.
- By deployment type, Hybrid held 45.76% of the managed storage services market share in 2026, while Cloud-Native is projected to expand at a 9.76% CAGR through 2032.
- By industry sector, Banking, Financial Services, and Insurance accounted for 24.42% of revenue in 2026, while Healthcare and Life Sciences is projected to expand at a 9.69% CAGR through 2032.
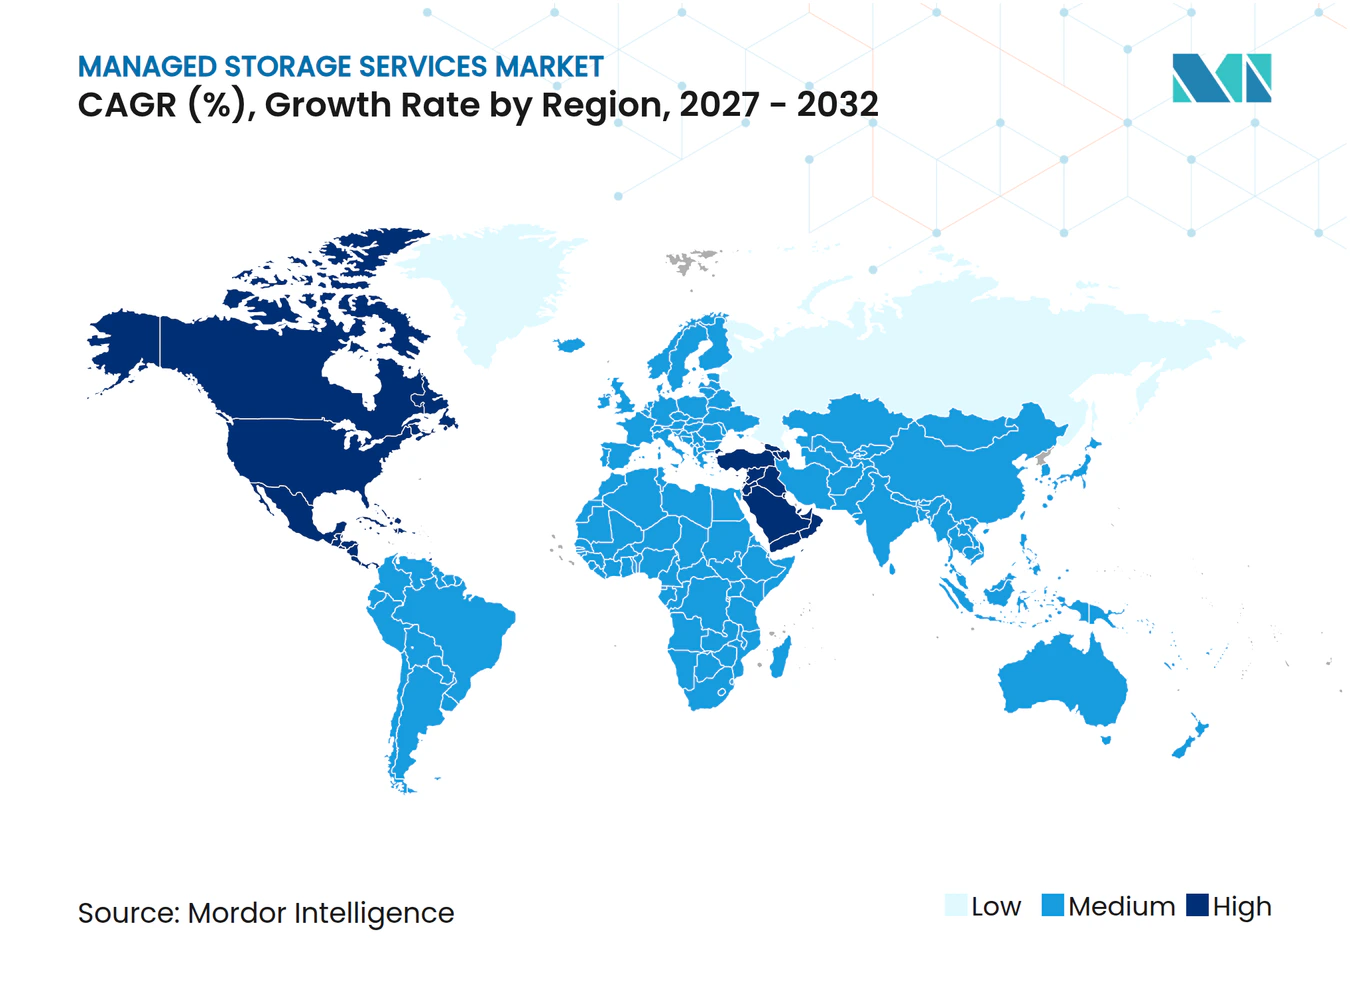
- By geography, North America held 38.42% of revenue in 2026, while the Middle East is projected to expand at a 9.78% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Storage Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI Workloads Increase Demand for High-Performance Managed Storage | +2.3% | Global, concentrated in North America and Asia-Pacific | Short term (≤ 2 years) |
| Enterprise Data Growth | +1.8% | Global | Medium term (2–4 years) |
| Hybrid and Multicloud Complexity | +1.4% | North America and Europe, with spillover to Asia-Pacific | Medium term (2–4 years) |
| Ransomware and Cyber-Resilience Requirements | +1.2% | Global | Short term (≤ 2 years) |
| Data Residency and Retention Regulations | +0.7% | Europe, Asia-Pacific, and Middle East | Medium term (2–4 years) |
| Consumption-Based Storage Models Expand Small and Medium-Sized Enterprise Access | +0.5% | Global, with the highest impact in Asia-Pacific and South America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
AI Workloads Increase Demand for High-Performance Managed Storage
Enterprise AI deployments are changing the performance and persistence requirements placed on storage systems. Seagate found that 99% of 2,712 enterprise IT decision-makers expect AI to increase storage needs during the next 3 years, while 38% said they were fully prepared for that demand.[1] Inference generates logs, retrieval context, and model checkpoints that must remain available for later runs. This increases the managed storage services market opportunity beyond visible user output. Providers can respond through automated tiering, GPU-attached flash caches, and elastic capacity contracts. These capabilities help customers avoid building specialist teams and purchasing capacity before they need it.
Enterprise Data Growth
Data creation and replication are expanding the volume that enterprises need to retain, classify, and recover. Western Digital reported that nearly 95% of 763 IT and business decision-makers saw generative AI-related data volume increase during the prior 12 months, and 61% reported an increase of 25% or more.[2] The same research found that 96% expected to need faster archive retrieval for inference and retrieval-augmented generation applications. Archive tiers are therefore becoming more active parts of the data estate. Komprise identified AI data classification and lifecycle tiering as leading unstructured-data management challenges. The managed storage services market can benefit where providers combine classification, retention enforcement, and cost control in one service.
Hybrid and Multicloud Complexity
Organizations with on-premises systems and multiple cloud platforms must manage placement, protection, and access across different environments. IBM Research demonstrated that dynamic, time-to-live-based placement policies across cloud regions can cut storage costs by up to 6 times compared with static placement.[3] Applying those policies requires technical skills and continuous operational attention. The managed storage services market therefore favors providers that can present a single control plane across infrastructure locations. Commvault expanded its Flex ecosystem to Hitachi Vantara and NetApp in April 2026 to support resilient protection for external flash storage pools. This approach supports organizations that need to retain existing hardware investments while improving recovery and governance.
Ransomware and Cyber-Resilience Requirements
Ransomware attacks increasingly target storage and backup environments rather than only endpoint systems. Sophos reported that 97% of organizations with encrypted data recovered it, but recovery through backups reached its lowest rate in 6 years. This weakens the assumption that a backup alone assures a clean recovery. The managed storage services market is responding with immutable storage, isolated recovery environments, and anomaly detection. These services also support boards and insurers that expect documented recovery controls. NetApp and Commvault formed a strategic alliance in March 2026 that combined AI-powered ransomware protection on primary storage with threat-aware backup.
Restraints Impact Analysis of Managed Storage Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Egress and Recovery Charges Increase Total Cost of Ownership | -1.3% | Global, concentrated in North America and Europe | Short term (≤ 2 years) |
| Shortage of Specialized Storage and Cyber-Recovery Skills | -0.9% | Global | Medium term (2–4 years) |
| Sovereign Infrastructure Duplication Increases Operating Complexity | -0.7% | Europe, Middle East, and Asia-Pacific | Medium term (2–4 years) |
| Customer Resistance to Outsourcing Storage Operations | -0.5% | Europe and Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Egress and Recovery Charges Increase Total Cost of Ownership
Cloud egress fees can change the economics of managed storage when an organization needs to restore or move a large data set. Backblaze and Dimensional Research found that 95% of 403 leaders managing more than 250 TB in the cloud had experienced unexpected cloud storage charges. The study also found that 58% viewed egress and data movement costs as the main barrier to multicloud strategies. These charges are particularly difficult during ransomware recovery, when data access is urgent. Providers with fee-neutral egress models can make total costs easier to assess. The managed storage services market may face slower switching from hyperscaler-anchored contracts where recovery costs remain uncertain.
Shortage of Specialized Storage and Cyber-Recovery Skills
The skills gap can delay adoption in the managed storage services market because customers need enough internal expertise to assess a provider and manage service obligations. ISC2 found that 59% of cybersecurity teams reported critical or significant skills needs in 2025, up from 44% in 2024. Only 5% of respondents reported no current skills gaps. Storage engineering, cyber recovery, and hybrid operating skills are often held by separate teams. This creates difficulties in setting recovery point objectives, validating immutable tiers, and testing clean recovery environments. Some organizations may postpone outsourcing when they cannot judge performance terms or negotiate them with confidence.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Storage Services Market Segment Analysis
By Solution Type:
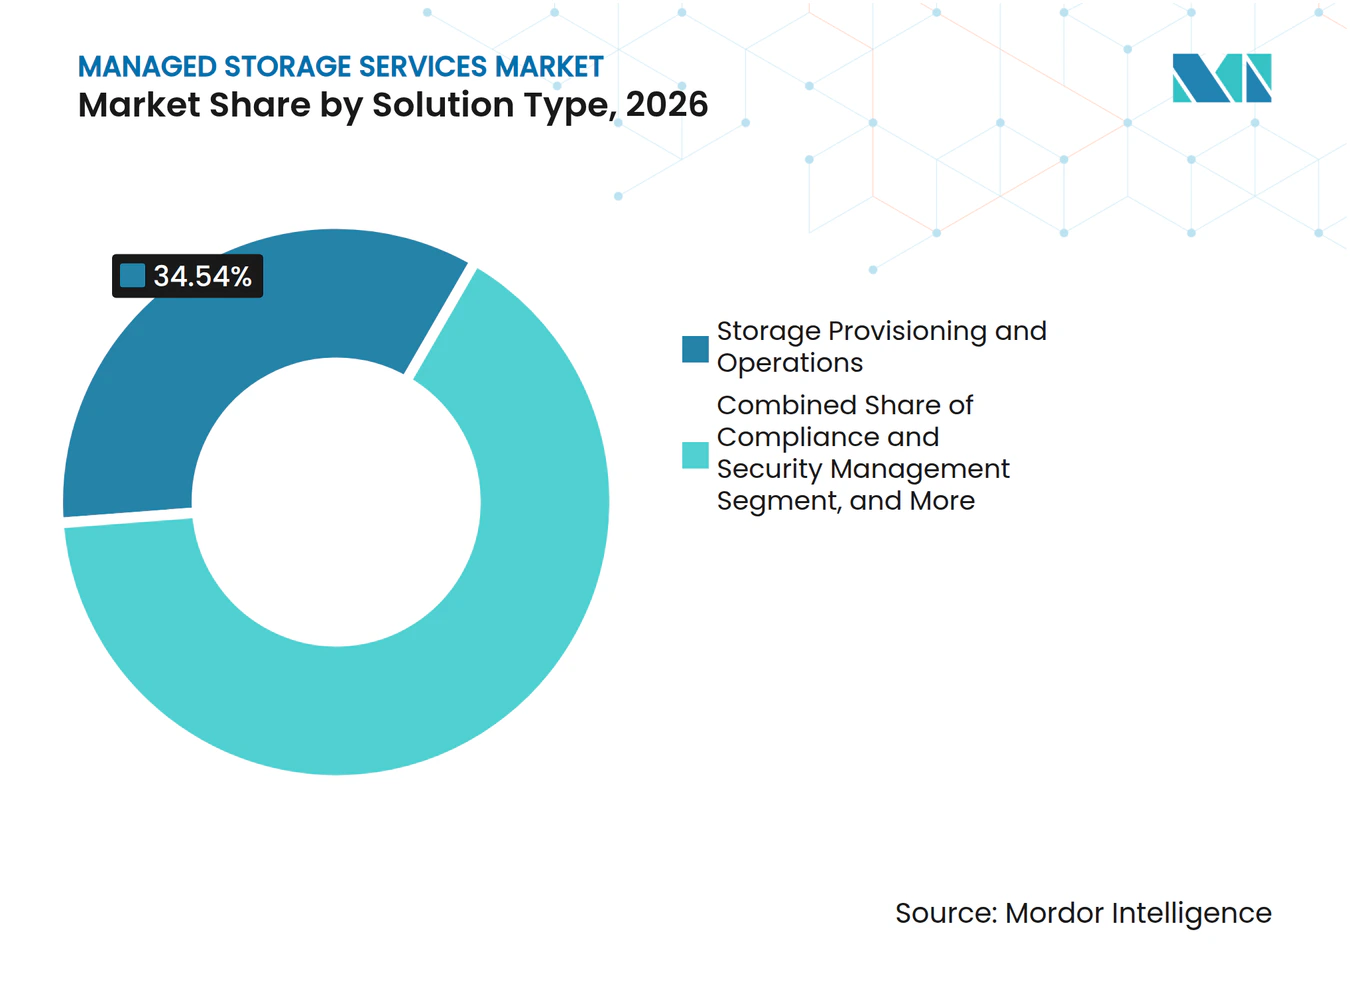
Compliance and Security Redefine Storage ValueStorage Provisioning and Operations held 34.54% of the managed storage services market size in 2026. It remains the operational base that organizations need before they can add security, backup, reporting, or retention services. Compliance and Security Management is projected to expand at a 9.67% CAGR through 2032 as recovery mandates, residency obligations, and cyber insurance requirements increase. Within the managed storage services market, this part of the managed storage services industry aligns policy controls and audit documentation with ISO/IEC 27040, HIPAA, and the General Data Protection Regulation.
Backup and Restore Management and Archiving and Retention Management support providers that want broader enterprise relationships, especially as retained AI data must be retrieved faster for inference use cases. Backup offerings now include immutability, isolated recovery environments, and anomaly detection. Capacity Planning and Reporting helps buyers identify overprovisioning as data volumes rise. The managed storage services market is also seeing provisioning platforms absorb security functions, as shown by NetApp's October 2025 addition of AI-driven data breach detection and isolated recovery capabilities.



By Deployment Type:
Hybrid Dominance Anchors a Cloud-Native InflectionHybrid deployment accounted for 45.76% of the managed storage services market size in 2026. Large enterprises continue to operate legacy on-premises infrastructure alongside cloud workloads, and a managed service layer can coordinate protection and governance across those locations. Hybrid arrangements create long customer relationships because replacing a control plane often requires extensive data migration. In the managed storage services market, Cloud-Native deployment is projected to expand at a 9.76% CAGR through 2032 as AI, software as a service, and real-time analytics workloads require elastic storage without long provisioning lead times.
On-premises managed storage remains relevant in financial services, healthcare, and the public sector where sensitive data must stay under direct organizational control or in a sovereign-compliant environment. NetApp announced Keystone Sovereign in October 2026 for qualified European customers, with initial pilots in Germany and France and controls for data residency, logs, backups, telemetry, support escalation, and operational access. Commvault Flex connects software-defined storage pools with external flash arrays from Hitachi Vantara, HPE, VAST Data, and NetApp. The managed storage services market continues to favor models that preserve existing hardware investments and allow flexibility across vendors.
By Industry Sector:
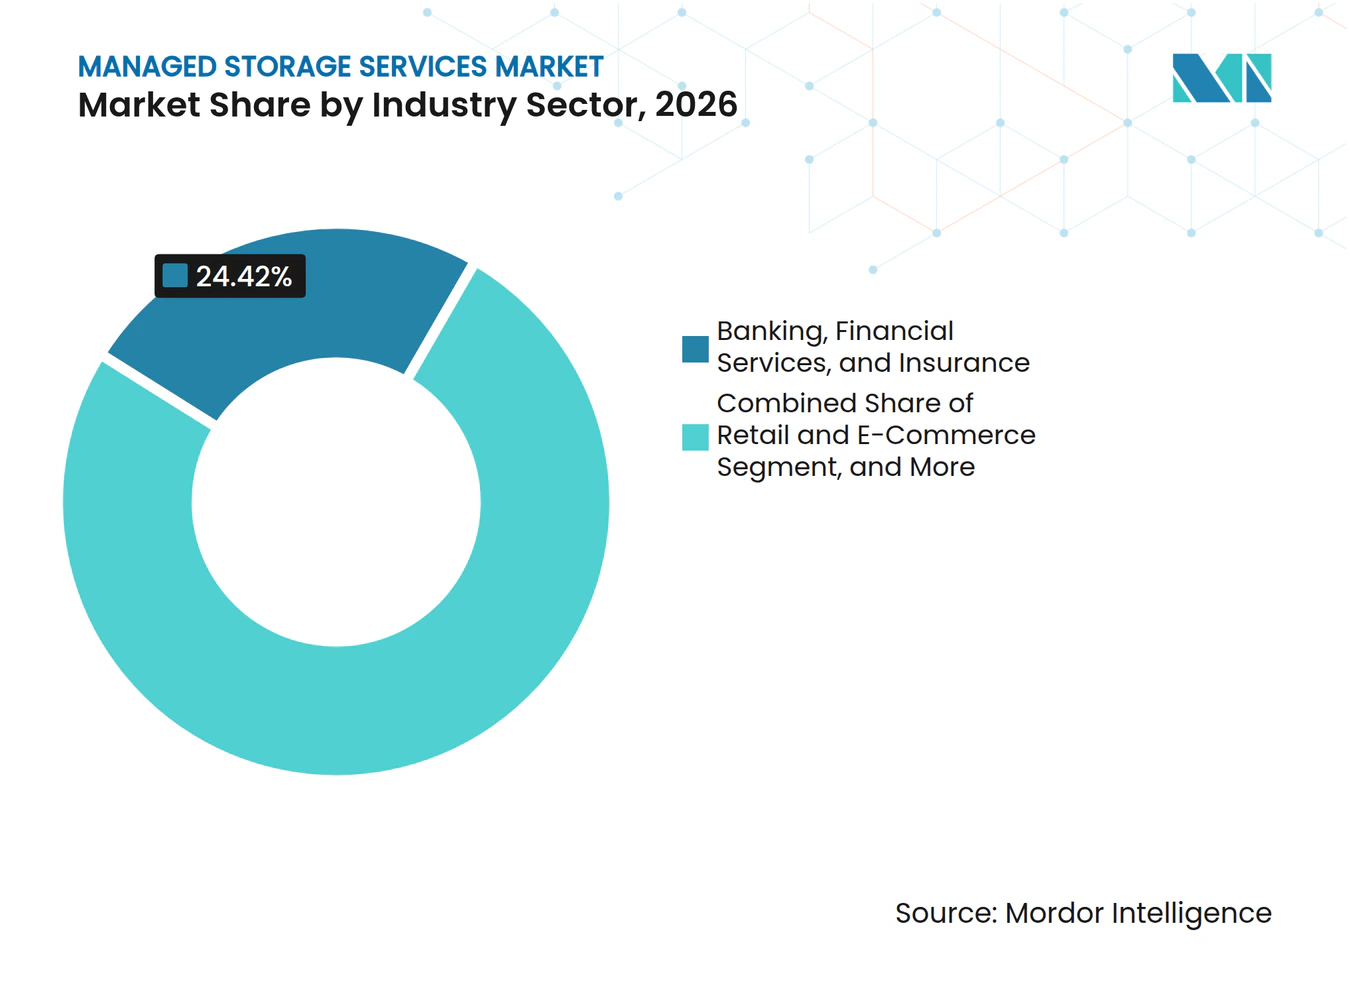
Healthcare Accelerates as BFSI Remains the AnchorBanking, Financial Services, and Insurance accounted for 24.42% of the managed storage services market in 2026. The sector needs reliable storage because transaction intensity, regulatory reviews, payment uptime, anti-money-laundering retention duties, and cyber insurance criteria make recovery a senior management concern. Information Technology and Telecommunications, Government and Public Sector, Manufacturing, Retail and E-Commerce, and Energy and Utilities each create distinct needs, including 5G session storage, sovereign infrastructure, and capacity for operational technology and Internet of Things data. These requirements support differentiated service designs rather than a common storage package.
Healthcare and Life Sciences is projected to expand at a 9.69% CAGR through 2032. The European Health Data Space Regulation entered into force on March 26, 2025, and created a framework for health-data sharing across the European Union. Texas Senate Bill 1188 took effect on January 1, 2026, and requires electronic health records of Texas residents to be physically maintained in the United States. Precision medicine, genomics, and multi-omics workflows create large files that favor high-throughput object storage and hybrid cloud designs, supporting compliant archiving and residency-ready services.

Geography Analysis
North America held 38.42% of revenue in 2026. The region combines high enterprise cloud adoption with a mature hyperscaler ecosystem and strong cyber-resilience requirements. HIPAA, state-level electronic health record requirements, and cyber insurance standards influence storage procurement. Iron Mountain reported USD 1.9 billion in first-quarter 2026 revenue, up 21.6% year over year, while its data center and digital growth businesses expanded by more than 50%.
Europe is the second-largest region by revenue in the managed storage services market. The EU Data Act became fully applicable on September 12, 2025, requiring cloud providers to remove switching obstacles and limiting switching charges. The NIS2 Directive requires backup, disaster recovery, and crisis management plans with management-level accountability. Germany, the United Kingdom, and France have mature demand from financial services, manufacturing, and public sector users. India has a distinctive requirement profile because its information technology services sector is expanding while the Digital Personal Data Protection Act strengthens localization expectations.
The Middle East is projected to expand at a 9.78% CAGR through 2032. Sovereign digital programs, new cloud regions, and localization requirements are turning demand into formal procurement processes. Saudi Arabia's Public Investment Fund committed USD 6 billion in 2025 to a sovereign data center ecosystem under Vision 2030, and Amazon Web Services announced a USD 5.3 billion Saudi cloud region at LEAP 2025, scheduled to become operational in 2026. Microsoft committed more than USD 15 billion across Gulf infrastructure, including a 200 MW Abu Dhabi expansion with G42. South America is led by Brazil's financial services digitalization, while Africa is building demand through financial inclusion, mobile-first enterprise designs, and data center investment in South Africa, Nigeria, and Egypt.
Competitive Landscape
Market Concentration
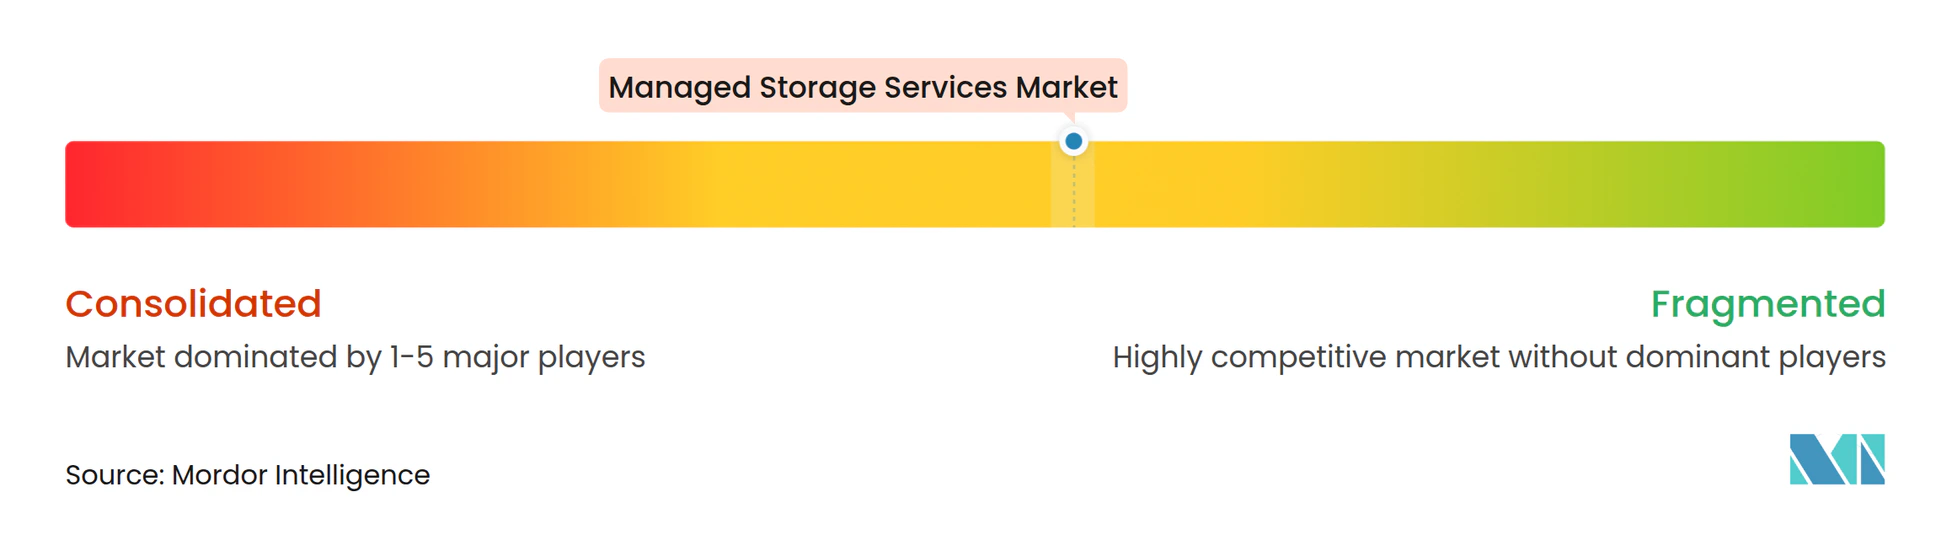
The managed storage services market is moderately concentrated among major platform providers and fragmented across specialists. Cohesity completed its combination with Veritas's enterprise data protection business in December 2024. The combined business became the largest standalone data protection vendor with a reported 19% share. Providers including NetApp, Rubrik, and Commvault compete through integrated resilience platforms that combine primary storage, backup, recovery, and compliance controls. The managed storage services market also includes specialists in cloud object storage, software-defined infrastructure, and immutable backup.
Rubrik reported strong enterprise adoption of cyber vaulting and immutable recovery infrastructure in its first quarter of 2026. In July 2026, the company committed more than USD 500 million to United Kingdom operations over 5 years and made Rubrik Security Cloud available on AWS European Sovereign Cloud. Commvault and NetApp announced their closed-loop cyber-resilience alliance in March 2026, combining NetApp Autonomous Ransomware Protection with Commvault threat-aware backup and Synthetic Recovery. NetApp also introduced planned Keystone Sovereign pilots in Germany and France in October 2026. ISO/IEC 27040 documentation and Zero Trust controls are becoming meaningful differentiators because buyers need evidence that can be reviewed by auditors and insurers.
White-space demand remains in sovereign and edge-compliant services for regulated users in the Middle East and Asia-Pacific. VAST Data, WEKAIO, and DDN Storage address AI workloads through high-throughput architectures designed for GPU-intensive processing. Wasabi Technologies raised USD 70 million in January 2026 at a USD 1.8 billion valuation, with Pure Storage participating as a strategic investor. The investment supports a commercial relationship between cloud object storage and enterprise flash infrastructure, with fee-neutral egress positioned as a response to cost concerns.
Managed Storage Services Industry Leaders
-
Dell Technologies Inc.
-
Huawei Technologies Co., Ltd.
-
NetApp, Inc.
-
Pure Storage, Inc.
-
Hewlett Packard Enterprise Company
- *Disclaimer: Major Players sorted in no particular order
Managed Storage Services Market Companies Covered in this Report
- NetApp, Inc.
- Pure Storage, Inc.
- Hitachi Vantara LLC
- Qumulo, Inc.
- VAST Data, Inc.
- Wasabi Technologies LLC
- Backblaze, Inc.
- Cloudian, Inc.
- Scality, Inc.
- Zadara Storage, Inc.
- StorPool Storage AD
- MinIO, Inc.
- WEKAIO, Inc.
- DataCore Software Corporation
- DDN Storage
- ExaGrid Systems, Inc.
- Cohesity, Inc.
- Rubrik, Inc.
- Acronis International GmbH
- Veeam Software Group GmbH
- Commvault Systems, Inc.
- Druva Inc.
- Veritas Technologies LLC
- Arcserve, LLC
- Iron Mountain Incorporated
Recent Industry Developments in Managed Storage Services Market
- October 2026: NetApp and Oracle Plan Fully Managed OCI NetApp Storage Service. NetApp and Oracle announced plans to launch a fully managed OCI-native service delivering ONTAP data-management capabilities, covering databases, enterprise applications, EDA, HPC, and AI data pipelines, on Oracle Cloud Infrastructure, targeting general availability within 12 months. The partnership extends NetApp's managed storage ecosystem to Oracle Cloud customers requiring familiar ONTAP APIs and governance within a hyperscaler-managed delivery model.
- October 2026: NetApp Introduces Keystone Sovereign for European Data Residency Compliance. NetApp introduced Keystone Sovereign, a planned storage-as-a-service offering for qualified European customers with regional controls covering data residency, logs, backups, telemetry, support escalation, and operational access, with initial pilots in Germany and France. The offering extends cloud-like consumption economics to sovereign-compliant on-premises deployments for regulated organizations operating under EU Data Act and NIS2 compliance obligations.
- September 2026: CrowdStrike Integrates with Commvault, Rubrik, and VAST Data for Security-Triggered Cyber Recovery. CrowdStrike's security agents gained the capability to trigger automated cyber recovery workflows in Commvault, Rubrik, and VAST Data platforms, enabling security-event-driven storage recovery without manual IT intervention. This integration shortens mean time to clean recovery and reduces dependence on specialized storage personnel during ransomware incidents, an operationally significant development for enterprises that cannot staff dedicated storage-security operations teams.
- July 2026: Rubrik Commits More Than USD 500 Million to UK Investment and Establishes EMEA Headquarters in London. Rubrik announced a more than USD 500 million 5-year investment in the United Kingdom and established a London office as its EMEA headquarters. Rubrik Security Cloud became available on the AWS European Sovereign Cloud, and the company added enterprise and public-sector customers including Harbour Energy, Manchester City Council, and the Scottish Government.
Global Managed Storage Services Market Report Scope
The Managed Storage Services Market refers to the industry comprising outsourced services that enable organizations to plan, provision, operate, monitor, secure, optimize, and maintain data storage infrastructure across on-premises, cloud, hybrid, and multi-cloud environments.
The Managed Storage Services Market Report is Segmented by Solution Type (Storage Provisioning and Operations, Backup and Restore Management, Archiving and Retention Management, Capacity Planning and Reporting, and Compliance and Security Management), Deployment Type (On-Premises, Hybrid, and Cloud-Native), Industry Sector (Banking, Financial Services, and Insurance, Healthcare and Life Sciences, Government and Public Sector, Information Technology and Telecommunications, Retail and E-Commerce, Manufacturing, Energy and Utilities, and Other Industry Sectors), and Geography (North America [United States, Canada, and Mexico], South America [Brazil, Argentina, Colombia, and Rest of South America], Europe [Germany, United Kingdom, France, Italy, Spain, and Rest of Europe], Asia-Pacific [China, Japan, India, South Korea, Australia, Singapore, Indonesia, and Rest of Asia-Pacific], Middle East [Saudi Arabia, United Arab Emirates, Turkey, Israel, Qatar, Kuwait, and Rest of Middle East], and Africa [South Africa, Nigeria, Egypt, and Rest of Africa]). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Storage Provisioning and Operations |
| Backup and Restore Management |
| Archiving and Retention Management |
| Capacity Planning and Reporting |
| Compliance and Security Management |
| On-Premises |
| Hybrid |
| Cloud-Native |
| Banking, Financial Services, and Insurance |
| Healthcare and Life Sciences |
| Government and Public Sector |
| Information Technology and Telecommunications |
| Retail and E-Commerce |
| Manufacturing |
| Energy and Utilities |
| Other Industry Sectors |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Colombia | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Singapore | |
| Indonesia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Israel | |
| Qatar | |
| Kuwait | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Egypt | |
| Rest of Africa |
| By Solution Type | Storage Provisioning and Operations | |
| Backup and Restore Management | ||
| Archiving and Retention Management | ||
| Capacity Planning and Reporting | ||
| Compliance and Security Management | ||
| By Deployment Type | On-Premises | |
| Hybrid | ||
| Cloud-Native | ||
| By Industry Sector | Banking, Financial Services, and Insurance | |
| Healthcare and Life Sciences | ||
| Government and Public Sector | ||
| Information Technology and Telecommunications | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Energy and Utilities | ||
| Other Industry Sectors | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Colombia | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Singapore | ||
| Indonesia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Israel | ||
| Qatar | ||
| Kuwait | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the 2026 value and 2032 outlook for managed storage services?
It is USD 17.81 billion in 2026 and is projected to reach USD 28.53 billion by 2032 at an 8.18% CAGR.
Which managed storage services deployment model has the largest share?
Hybrid deployment led with 45.76% of revenue in 2026 because enterprises continue to run both on-premises and cloud workloads.
Which solution type is expanding fastest in managed storage services?
Compliance and Security Management is projected to expand at a 9.67% CAGR through 2032 as buyers prioritize policy enforcement and recovery assurance.
Why are AI workloads changing storage requirements?
AI programs produce persistent logs, retrieval context, and checkpoints, which increases retention, retrieval, and lifecycle-management needs.
Which sector is expected to expand fastest for managed storage services?
Healthcare and Life Sciences is projected to expand at a 9.69% CAGR through 2032, supported by interoperability requirements, precision medicine data, and residency rules.
Which region is expected to expand fastest?
The Middle East is projected to expand at a 9.78% CAGR through 2032 because sovereign digital programs and cloud infrastructure investments are increasing procurement activity.