
Managed SaaS Application Operations Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 20.93 Billion |
| Market Size (2032) | USD 40.96 Billion |
| Growth Rate (2027 - 2032) | 14.37 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed SaaS Application Operations Services Market Analysis by Mordor Intelligence
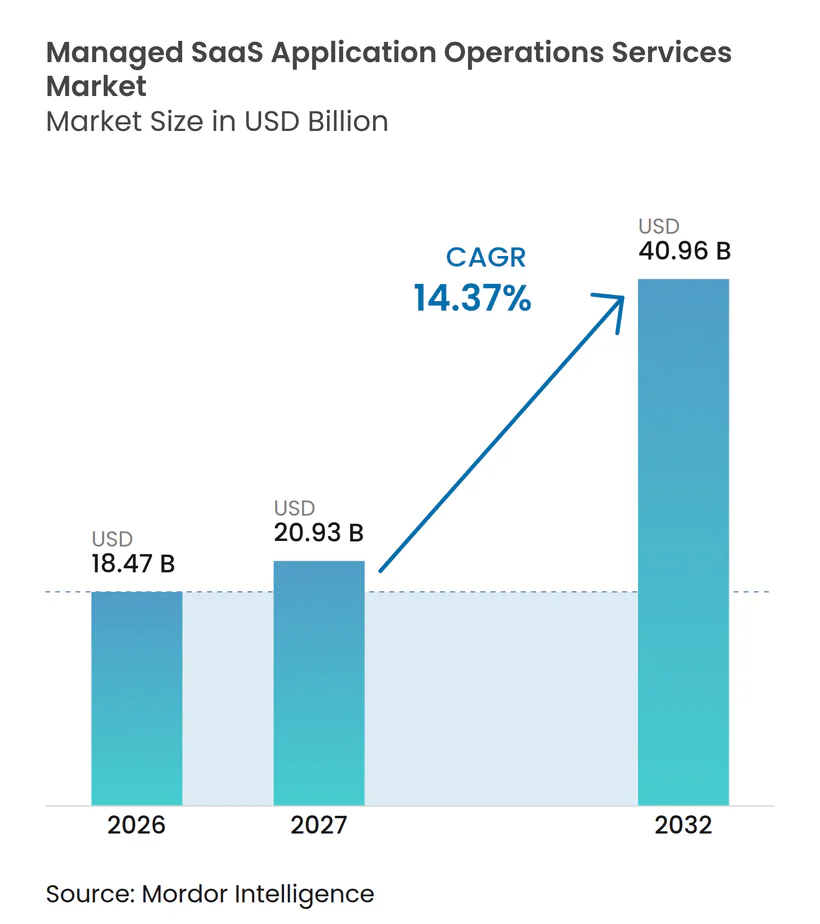
The Managed SaaS application operations services market size is projected to expand from USD 18.47 billion in 2026 and USD 21.13 billion in 2027 to USD 40.96 billion by 2032, registering a CAGR of 14.37% between 2027 to 2032. The Managed SaaS application operations services market is supported by enterprises moving responsibility for complex, multi-vendor application estates to specialist providers. Service continuity, access control, release coordination, and integration management are becoming connected operational requirements rather than separate support activities. Buyers increasingly evaluate providers on their ability to maintain reliable business applications while making platform changes visible and accountable. Security requirements, data handling expectations, and a shortage of experienced cloud operations staff strengthen demand for managed delivery models. The Managed SaaS application operations services market also benefits when providers can combine application expertise with clear governance, measurable service levels, and practical support for AI-enabled workflows, because this approach lets customers separate routine operational delivery from internal decisions on application priorities, business process design, investment timing, and the acceptable balance between standardization and local flexibility.
Key Report Takeaways
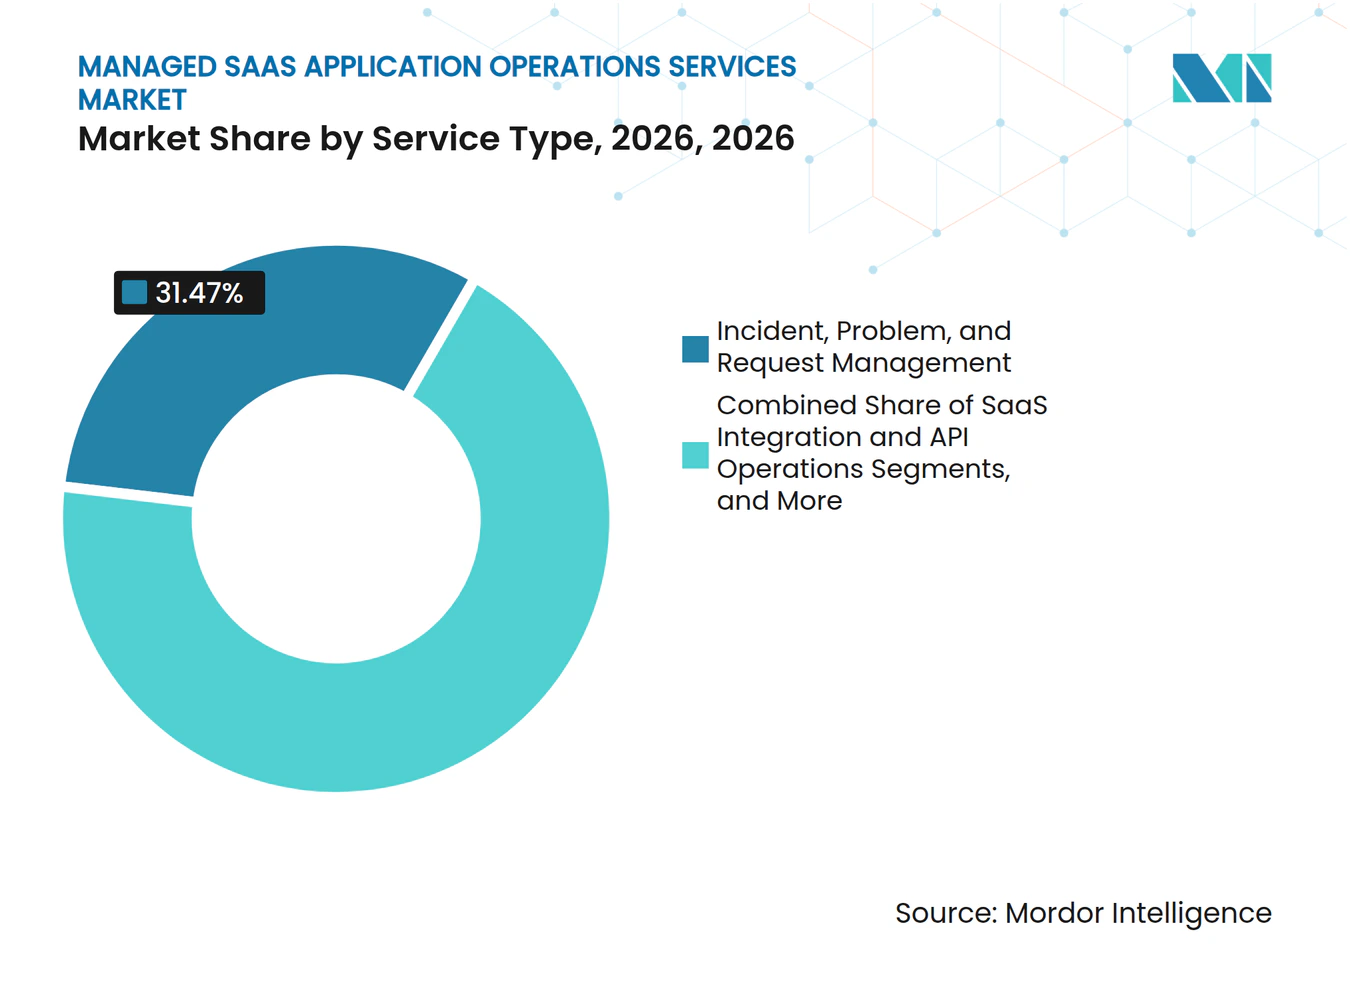
- By service type, Incident, Problem, and Request Management led with 31.47% of the Managed SaaS application operations services market share in 2026, while Security, Compliance, and Identity Operations is projected to expand at a 15.83% CAGR through 2032.
- By deployment model, Cloud-Based delivery held 61.73% share in 2026, while Hybrid delivery is projected to expand at a 15.41% CAGR through 2032.
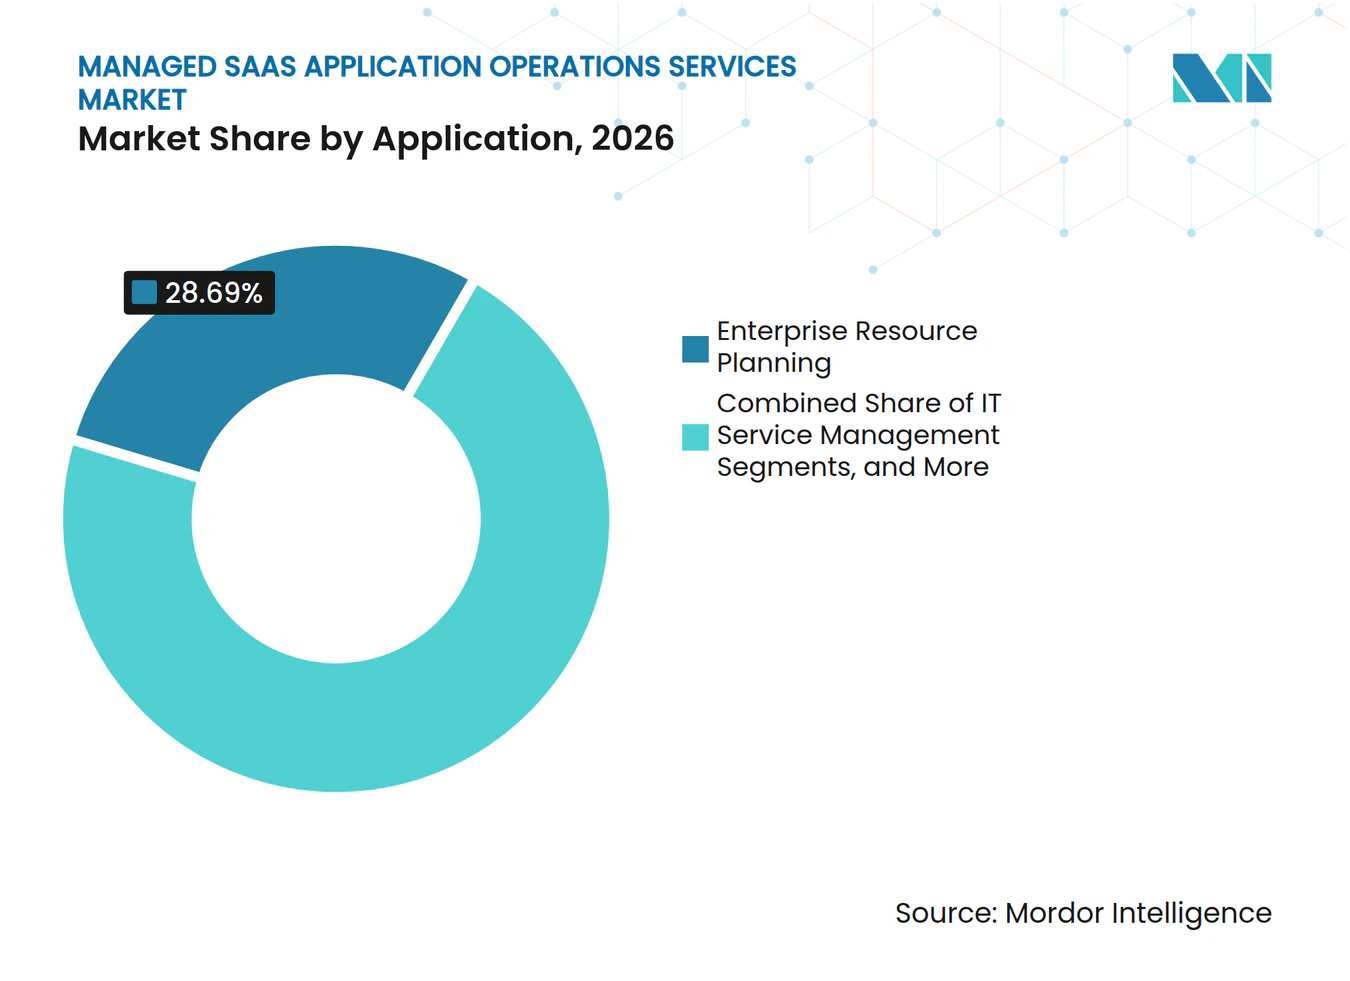
- By application, Enterprise Resource Planning accounted for 28.69% share in 2026, while Marketing, Commerce, and Customer Experience is projected to expand at a 15.47% CAGR through 2032.
- By organization size, Large Enterprises held 68.42% share in 2026, while Small and Medium Enterprises are projected to expand at a 15.54% CAGR through 2032.
- By end-user industry, BFSI accounted for 23.78% share in 2026, while Healthcare is projected to expand at a 15.21% CAGR through 2032.
- By geography, North America held 38.62% share in 2026, while Asia-Pacific is projected to expand at a 15.36% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed SaaS Application Operations Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Enterprise SaaS Estate Complexity | +3.0% | Global, strongest in North America and Europe where multi-vendor SaaS footprints are deepest | Medium term (2-4 years) |
| Demand for Continuous Application Reliability | +2.8% | Global, most acute in BFSI and healthcare across North America and Europe | Short term (≤ 2 years) |
| Cloud Talent Shortages and Outsourcing Demand | +2.5% | Global, intensified in North America, Western Europe, and Southeast Asia | Short term (≤ 2 years) |
| Security, Compliance, and Resilience Requirements | +2.2% | North America and the EU core, with spillover to Asia-Pacific and the Middle East and Africa | Medium term (2-4 years) |
| SaaS Integration Debt and API Dependency Growth | +1.6% | Global, concentrated in mid-size and large enterprises across major regions | Medium term (2-4 years) |
| AI-Assisted Remediation and Autonomous Operations | +1.4% | North America leads adoption, followed by Asia-Pacific and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Enterprise SaaS Estate Complexity
The Managed SaaS application operations services market responds to an operating problem created by years of decentralized software purchasing, acquisitions, and platform customization. IBM identifies recurring cost growth from underused licenses, duplicate applications, customization lock-in, and poorly governed operational and security risks in multi-vendor portfolios.[1] These issues make renewal decisions harder because application owners often lack a shared view of dependencies, usage, and accountability. They also make it difficult to connect data and workflows across systems when organizations introduce AI tools into business processes. Managed providers can address this burden by documenting platforms, standardizing operating procedures, and coordinating support across vendors. The resulting service need extends beyond routine administration because the customer must make the estate more manageable without interrupting essential work.
Demand for Continuous Application Reliability
The Managed SaaS application operations services market is also shaped by the expectation that business applications remain responsive throughout daily operations. Enterprises increasingly judge support quality through incident detection, change coordination, recovery time, and the experience of people using the application. The supplied production case study reported that agentic AIOps reduced median incident detection time from 18.0 minutes to 6.1 minutes and mean time to resolution from 42.0 minutes to 11.1 minutes. These results illustrate why monitoring is moving from passive dashboard review toward active detection and controlled remediation. In BFSI and healthcare, a brief degradation during high-volume periods can affect regulated processes, customer service, and internal productivity. Providers that maintain clear escalation paths and structured change controls can therefore become part of the customer’s day-to-day service model.
Cloud Talent Shortages and Outsourcing Demand
The Managed SaaS application operations services market gains support when organizations cannot retain specialists across every platform in a growing application portfolio. Internal teams must understand cloud configuration, access governance, vendor release schedules, integration dependencies, and the needs of individual business functions. That combination is difficult to sustain when critical knowledge sits with a small group of employees. Outsourcing standard platform operations allows customers to retain control of business priorities while accessing a wider delivery pool for repeatable work. It also reduces disruption when a skilled employee leaves or when new applications are added quickly. The commercial value lies in bringing predictable coverage, documented expertise, and repeatable service routines to work that is necessary but does not always require an internal team to perform every task.
Security, Compliance, and Resilience Requirements
The Managed SaaS application operations services market is supported by organizations that need stronger controls over access, identities, APIs, and configuration changes. The Cloud Security Alliance reported that 86% of surveyed organizations viewed SaaS security as a high priority, while 58% struggled to enforce user privileges across applications.[2] The same report found that 54% lacked automation for identity lifecycle management, 55% reported employee adoption of SaaS tools without security-team involvement, and 56% raised concerns about overprivileged API access. These gaps create demand for ongoing access reviews, policy enforcement, identity lifecycle work, and continuous posture monitoring. Providers can make those controls easier to operate by integrating them with incident response, audit evidence, and documented ownership. Security, Compliance, and Identity Operations is consequently projected to expand at a 15.83% CAGR through 2032.
Restraints Impact Analysis of Managed SaaS Application Operations Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Privacy and Cross-Border Processing Concerns | -1.8% | The EU and jurisdictions with data-residency mandates, with spillover to global multinationals serving European operations | Medium term (2-4 years) |
| Customer Reluctance to Outsource Business-Critical SaaS Control | -1.5% | Global, most pronounced in BFSI, healthcare, and government | Medium term (2-4 years) |
| Integration Complexity Across Proprietary SaaS APIs | -1.2% | Global, intensified in enterprises with large heterogeneous portfolios and Asia-Pacific mid-market deployments | Long term (≥ 4 years) |
| Underdeveloped Runbook and Telemetry Standards Across SaaS Vendors | -0.9% | Global, most acute where SaaS adoption is newer and vendor standardization is less mature | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Privacy and Cross-Border Processing Concerns
Data processing rules can limit how managed service providers design support models for customers operating across several jurisdictions. The Managed SaaS application operations services market must therefore accommodate service designs that identify where data is accessed, where diagnostic information is stored, and which team has authority to act during an incident. Customers may require data to remain in a designated location, which affects remote access, backup arrangements, diagnostic work, and subcontractor oversight. European customers also expect providers to support portability and switching rights established under the EU Data Act. These obligations increase the importance of documenting processing roles, access boundaries, and incident responsibilities before work begins. They can slow decisions when the service model relies on delivery centers outside the customer’s preferred jurisdiction. Providers with clear data-residency options, auditable processes, and transparent subcontracting arrangements are better placed to reduce this concern.
Customer Reluctance to Outsource Business-Critical SaaS Control
Customers can hesitate to transfer responsibility for applications that affect revenue, patient care, or regulated transactions. The concern is not limited to cost because business leaders want clear visibility into decisions, ownership, and escalation when an important application fails. A managed engagement may take longer to approve when customers believe a provider will operate as a black box. This is particularly relevant for BFSI, healthcare, and government organizations with formal accountability requirements. Transparent dashboards, detailed escalation matrices, and shared service reviews can reduce uncertainty without removing the customer’s authority over business outcomes. The restraint remains meaningful because providers must demonstrate trust and operational discipline before they are granted responsibility for critical applications.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed SaaS Application Operations Services Market Segment Analysis
By Service Type:
Incident and Security Services Anchor Both Ends of the Maturity CurveIncident, Problem, and Request Management held 31.47% of the Managed SaaS application operations services market share in 2026, making it the largest service type. It is often the starting point because customers first seek dependable handling of user issues, recurring problems, service requests, and disruption across core platforms. The service can establish operating routines that later support wider work on releases, access governance, integrations, and platform optimization. Enterprises value a provider that can receive, classify, resolve, and document incidents without losing the business context that determines their priority. A consistent incident process also creates evidence on recurring failures and service bottlenecks. This can help customers identify where deliberate changes to configuration, process ownership, vendor coordination, or internal training are needed. Incident management therefore serves both as a direct operational service and as a foundation for a broader account relationship. It remains important across organizations that are standardizing support after rapid SaaS adoption.
Security, Compliance, and Identity Operations is projected to expand at a 15.83% CAGR through 2032, the highest rate among service types. The segment is supported by the difficulty of maintaining access controls across applications that are owned by different business functions and vendors. The Cloud Security Alliance found that many organizations still struggle with privilege enforcement and identity lifecycle automation. Managed providers can combine access certification, account review, policy monitoring, and response procedures within a regular operating schedule. This model helps customers move away from manual checks that occur only before an audit or after an incident. Managed Application Monitoring and Observability is also changing as AIOps supports faster detection and more structured response. Release, Patch, and Upgrade Management remains necessary because missed vendor releases can leave useful capabilities unavailable. SaaS Integration and API Operations addresses connection maintenance and dependency management, while integrated service portfolios can carry stronger value than a single service line.



By Deployment Model:
Hybrid Delivery Reflects Incomplete Cloud JourneysCloud-Based delivery held 61.73% of the Managed SaaS application operations services market share in 2026. The Managed SaaS application operations services market uses this model because standardized delivery can bring consistent support to customers whose applications are distributed across locations and business units. It reflects the use of scalable delivery environments and the preference for operating standardized services across multiple customers. Cloud-based models can support centralized monitoring, repeatable runbooks, remote coordination, and automation for common tasks. They are particularly practical when applications are already delivered as software as a service and can be managed through vendor controls and secure access. Customers still require accountability for data access and service outcomes even when the delivery model is centralized. Providers must therefore maintain strong identity controls, clear operational records, and reliable handoffs between teams. The large share of cloud-based delivery shows that most customers accept remote operational support when governance is visible. It also sets a baseline for providers that want to serve large multi-country accounts.
Hybrid delivery is projected to expand at a 15.41% CAGR through 2032, reflecting the fact that many enterprise estates still include on-premises systems. These systems may remain in place because of data-residency requirements, latency needs, contractual commitments, or deep connections with older business processes. A hybrid estate requires providers to coordinate changes and monitoring across environments that have different tools, controls, and operating practices. This creates a larger service requirement than a fully standardized cloud environment because the provider must manage the points where systems connect. On-premises managed services remain relevant for regulated customers, particularly in BFSI and government. TCS partnered with ManageEngine in October 2026 to bring IT service management capabilities to the TCS SovereignSecure Cloud for government institutions and regulated industries.[3] Such offerings show how data-residency expectations can sustain demand for delivery models that bridge cloud and local environments. Providers with unified observability and coordinated governance are positioned to meet this need.
By Application:
ERP Leads Spend While Marketing and Customer Experience Applications Drive New GrowthEnterprise Resource Planning accounted for 28.69% of the Managed SaaS application operations services market share in 2026. Within the Managed SaaS application operations services market, ERP work demands a detailed understanding of process dependencies because finance, procurement, and supply chain users often rely on the same connected environment. ERP platforms are central to financial, procurement, supply chain, and operational workflows, which makes disruption costly and makes change control essential. Systems such as SAP S/4HANA and Oracle Fusion Cloud can be deeply customized, creating a continuing need for knowledgeable support after implementation. Regular vendor updates also require teams to assess effects on integrations, user roles, process configurations, and embedded capabilities. This work is difficult to treat as occasional support because each change can affect several business functions. Customers often require providers to maintain documentation, coordinate testing, and manage the transition from planned release to stable production use. The large ERP share reflects the operational importance of applications that connect core enterprise processes. It also reflects the practical challenge of retaining sufficient internal expertise for every part of a complex platform.
Marketing, Commerce, and Customer Experience is projected to expand at a 15.47% CAGR through 2032. The category includes connected customer engagement tools, commerce applications, customer data platforms, and CRM components that must work together across sales and service teams. The segment benefits from a growing need to manage releases and integrations across fragmented customer-facing stacks. Providers must coordinate vendor changes while ensuring that data movement, workflow logic, and access controls remain aligned with business operations. Salesforce introduced Agentforce IT Service in 2026, which shows that platform vendors are also extending support for AI-enabled IT operations. Customer Relationship Management and IT Service Management continue to require dependable operational support as digital programs extend over multiple years. Human Capital Management and collaboration platforms also need identity governance and optimization as hybrid work remains established. Across applications, customers are placing more weight on utilization, AI feature adoption, and multi-year cost control than on implementation speed alone.

By Organization Size:
Large Enterprises Lead, SMEs Are Fastest-GrowingLarge Enterprises held 68.42% of the Managed SaaS application operations services market share in 2026. Their scale creates demand because global deployments often involve numerous platforms, business units, external vendors, and regulatory requirements. Large organizations also tend to have greater absolute SaaS spending and more complex governance needs than smaller customers. A managed provider can supply around-the-clock coverage, platform specialists, and standardized processes that are difficult for one internal team to maintain across every application. These customers typically seek a structured relationship that defines service levels, accountability, reporting, and escalation. They may also use providers to coordinate operations across several application ecosystems rather than relying on a different supplier for each platform. The large-enterprise segment therefore remains the main source of current spending for broad managed application operations engagements. Its requirements favor providers with deep delivery capacity and established governance practices.
Small and Medium Enterprises are projected to expand at a 15.54% CAGR through 2032. Their demand is supported by the same need for dependable operations, but their procurement budgets and internal staffing models differ from those of large enterprises. Productized offerings can combine remote monitoring, automation, preconfigured runbooks, and defined service packages at a cost that smaller organizations can evaluate more easily. The talent gap can be particularly difficult for smaller companies because they may not be able to offer the retention packages needed for several specialists. This creates an opportunity for providers that can make a focused service accessible without imposing a large-enterprise delivery structure. Cloud adoption across Asia-Pacific and South America broadens the potential customer base for these models. Mid-market providers and SaaS-focused specialists may be well placed to serve this group, while large IT services firms often prioritize higher-value enterprise accounts. The segment’s expected expansion reflects a gradual widening of the managed service customer base.
By End-User Industry:
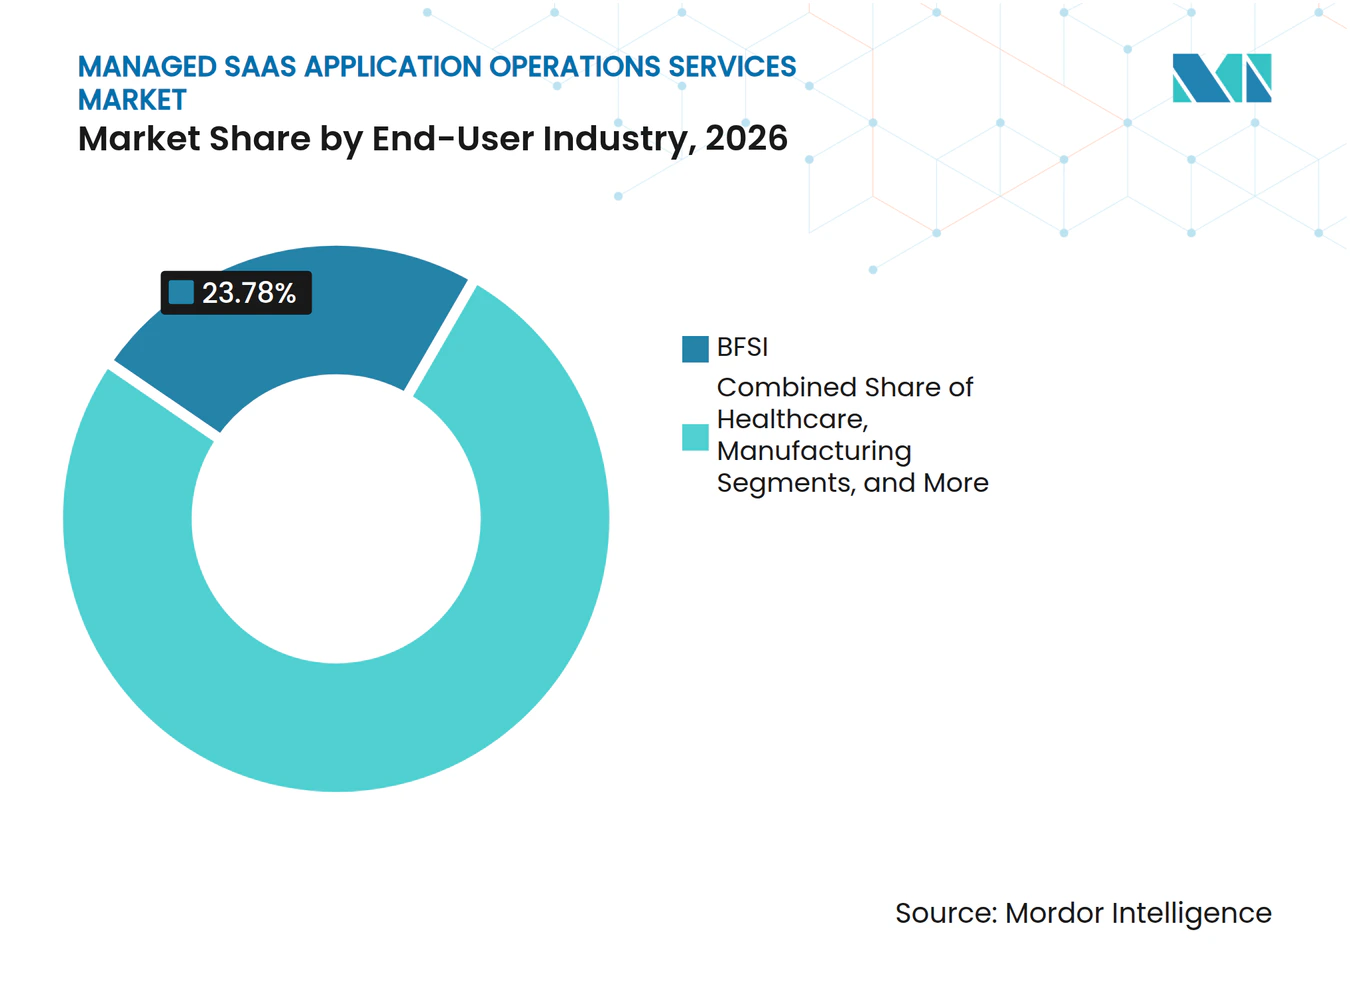
BFSI Anchors Revenue, Healthcare Grows FastestBFSI accounted for 23.78% of the Managed SaaS application operations services market share in 2026. Banks and insurers manage applications across core banking, risk, compliance, customer engagement, and internal operations, often under strict third-party oversight. This environment requires providers to demonstrate strong service continuity, access controls, audit evidence, and defined incident procedures. The European Union’s Digital Operational Resilience Act places greater focus on third-party risk management for information and communication technology services. That emphasis reinforces the value of clear accountability and documented operating practices in managed engagements. CGI reported that 2-thirds of banks were willing to rely on managed services for trade finance operations, while nearly 60% were willing to do so for payments. These applications show that providers can gain responsibility for important functions when they demonstrate dependable service. BFSI remains a major source of demand because operational failure can have direct regulatory and customer consequences.
Healthcare is projected to expand at a 15.21% CAGR through 2032, the fastest rate among end-user industries. Healthcare organizations need application support that protects sensitive information and maintains availability for clinical, administrative, and billing workflows. Complex environments can also limit the time available for internal teams to work on AI, analytics, and data modernization priorities. Managed services can help by taking responsibility for standardized operational tasks while the organization retains control over clinical and business decisions. The service model must remain transparent because providers handle applications connected to patient outcomes and regulatory responsibilities. IT and Telecommunications, Retail and E-Commerce, and Manufacturing also maintain spending as their SaaS portfolios mature. Government and Defense require compliance-focused delivery designs, including sovereign cloud models in some cases. Energy and Utilities, Transportation and Logistics, Hospitality and Travel, and Education represent smaller but developing customer groups with similar needs for continuity, identity governance, and platform coordination. The Managed SaaS application operations services market therefore serves both heavily regulated and operationally distributed sectors.
Geography Analysis
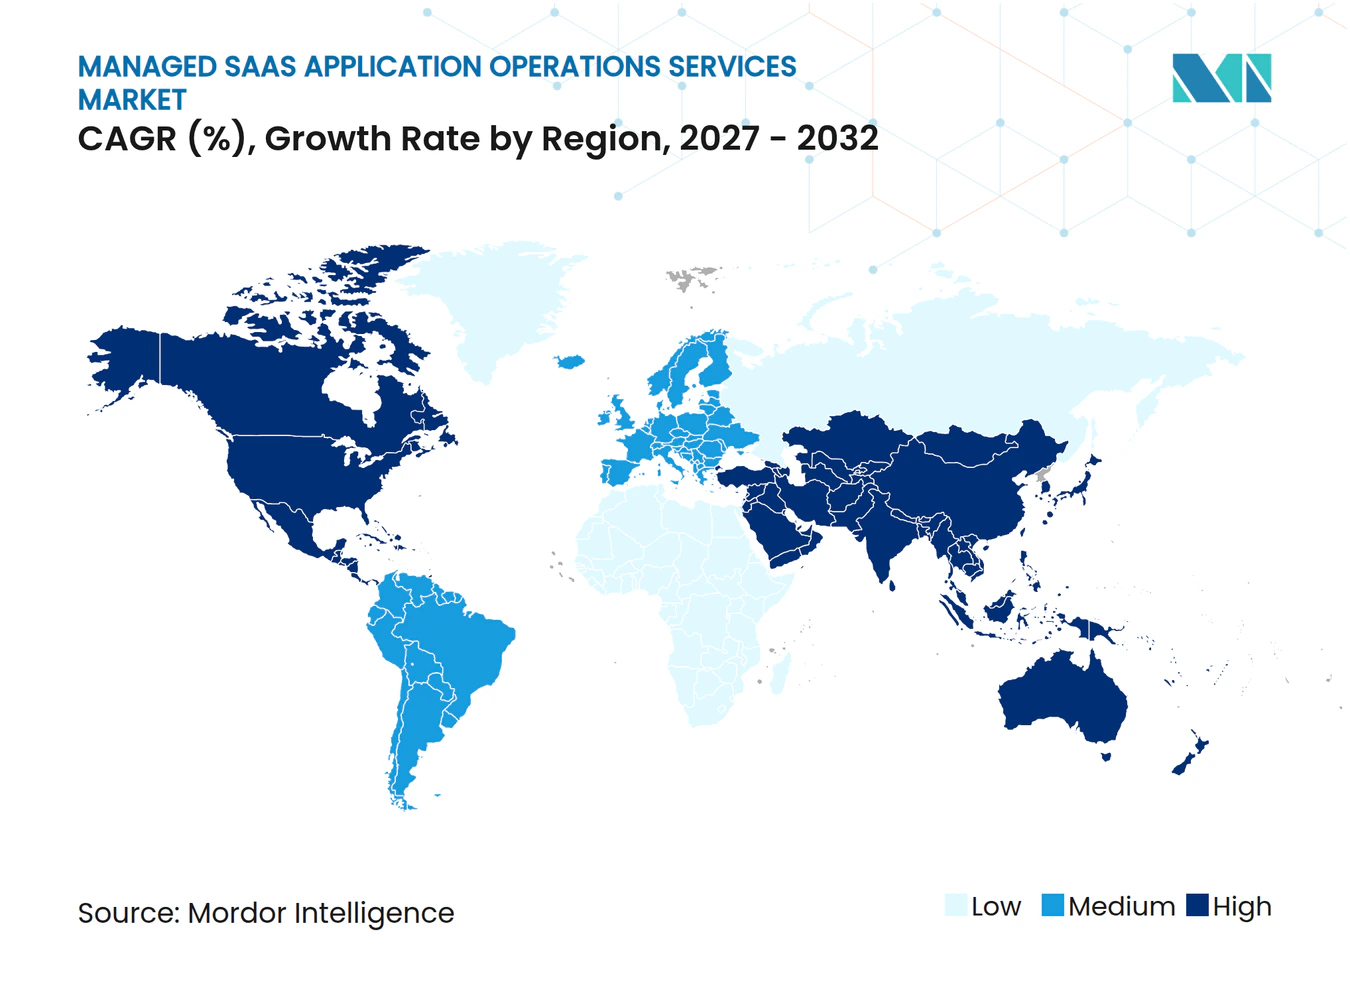
North America held 38.62% of the Managed SaaS application operations services market share in 2026. The Managed SaaS application operations services market has a substantial installed base in the region because complex application estates have been in use for years, span business units and vendors, and require continuing operational attention after implementation. Mature procurement practices and a persistent need for cloud and application operations specialists support demand for formal governance, reliable service coverage, and providers that can extend work from incident handling into security, releases, and integration coordination. Canada and Mexico add demand as regional supply chains and BFSI networks extend SaaS use across the continent. North America remains the largest regional opportunity because customers are familiar with managed delivery models and expect measurable operating discipline, documented accountability, and dependable support for regulated as well as general business applications.
Asia-Pacific is projected to expand at a 15.36% CAGR through 2032, making it the fastest-growing regional segment. China, India, Japan, and Southeast Asia are important sources of demand as enterprises increase cloud adoption, modernize application environments, and look for support that fits both mature operating models and newer SaaS deployments. India is important on the provider side because TCS, Infosys, HCLTech, Wipro, and Tech Mahindra operate global delivery centers that support enterprise clients across the region. Japan and Australia-New Zealand remain more mature demand markets, while government digitalization and evolving data-protection rules across Southeast Asia and India add compliance considerations to operational support. The Managed SaaS application operations services market can benefit when providers combine regional delivery capacity with local knowledge of data handling requirements, customer expectations, and the governance practices required for application estates with differing levels of maturity.
Europe remains significant because regulatory requirements increase the operational burden associated with enterprise SaaS estates, with Germany, the United Kingdom, France, and the Nordic countries representing important sources of application operations spending. South America, led by Brazil and Argentina, is developing demand as retail, BFSI, and e-commerce organizations increase SaaS adoption, although infrastructure limitations can affect delivery costs. The Middle East, led by Saudi Arabia and the United Arab Emirates, is seeing digital transformation investment connected with national Vision programs, which creates demand from government and energy organizations for managed operations with clear control frameworks. Africa, including South Africa, Egypt, and Nigeria, remains an earlier-stage opportunity but follows a consistent adoption path, requiring providers to align service design with local infrastructure conditions and delivery capacity.
Competitive Landscape
Market Concentration
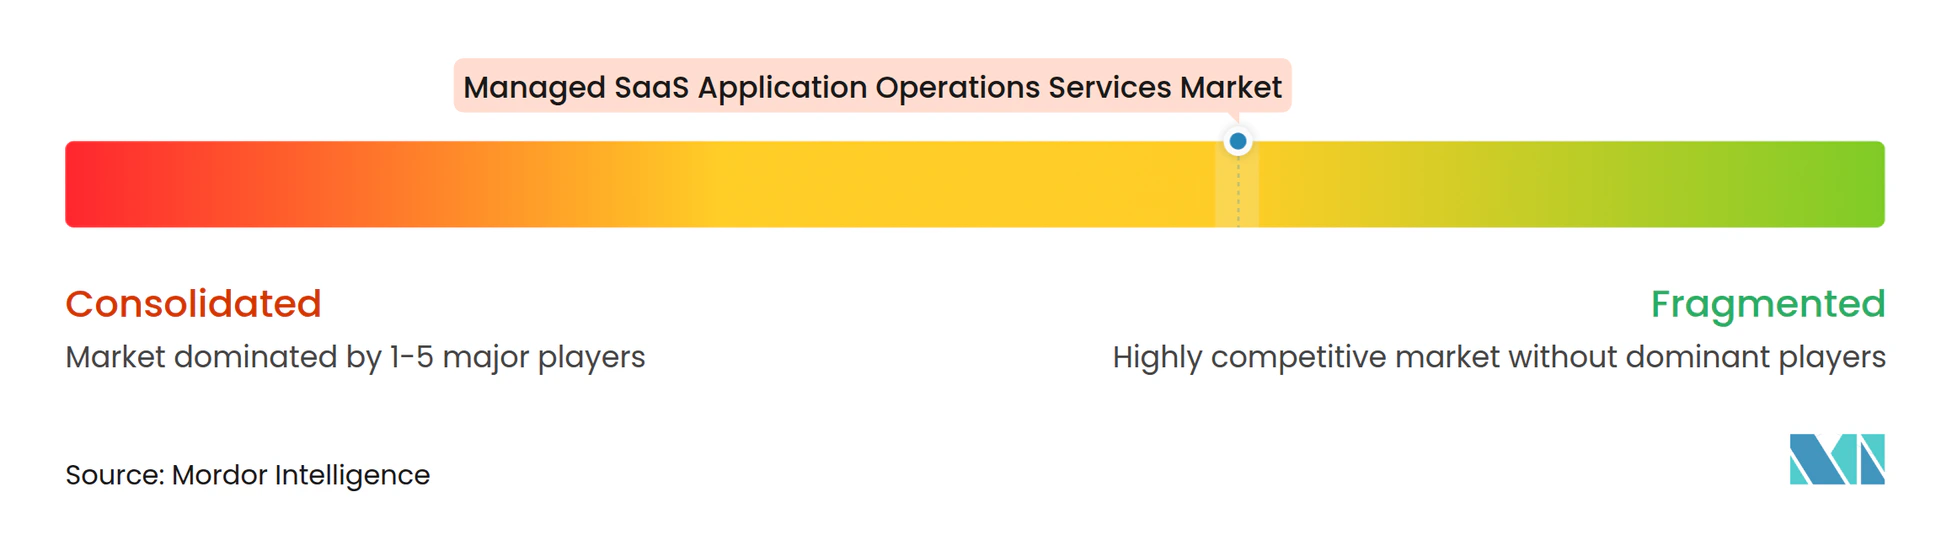
The Managed SaaS application operations services market is moderately concentrated among major providers, while the mid-market and specialist tier remains fragmented. In the Managed SaaS application operations services market, this structure gives buyers a choice between broad multi-platform coverage from global firms and focused support for a defined application, control area, or industry workflow. Accenture, Capgemini, HCLTech, IBM, Infosys, TCS, and Wipro are prominent providers with the scale to support broad enterprise application portfolios and platform-specific expertise across SAP, Salesforce, Oracle, ServiceNow, and Workday. Large customers often prefer providers that coordinate several ecosystems while retaining the detailed knowledge needed for each application, which favors firms with dedicated delivery teams, reusable processes, and structured governance. Specialist providers remain relevant where customers need deep expertise in a specific platform, identity domain, or industry workflow, so the competitive structure combines large integrators with focused firms that deliver narrower but high-value services.
Competition increasingly depends on whether a provider can connect operational coverage with security, compliance, transparent accountability, and clear control over hybrid environments. Customers are less likely to accept a general support model when an application affects regulated activity or a critical customer process, so providers differentiate through real-time reporting, defined ownership boundaries, controlled automation, and access to experienced platform specialists. Identity and security services are important because customers need continuing control over accounts, permissions, APIs, and configuration changes across applications operated by several business functions. TCS partnered with ManageEngine to add IT service management capabilities to its SovereignSecure Cloud for regulated use cases, showing how providers can pair delivery infrastructure with platform capabilities when data residency and governance requirements limit standard delivery choices. The Managed SaaS application operations services market rewards providers that can make this governance visible to buyers without forcing them to abandon residual on-premises systems or reduce oversight of business-critical application decisions.
AI-supported operations are becoming a practical differentiator when they improve detection, diagnosis, and controlled remediation within a governed service model. A 2026 production study showed that AIOps can reduce detection and resolution times in an enterprise environment, while Splunk extended AI SRE in Splunk Observability Cloud to support code-level remediation proposals and engineer review in September 2026. Providers can use similar capabilities to offer an outcome-focused proposition, but security certifications, documented controls, and demonstrated performance remain necessary to show that automation is accountable. Buyers retain bargaining power because they can select specialists for individual applications or service domains, and the available material does not establish a top-5 combined share despite the prominence of major global providers.
Managed SaaS Application Operations Services Industry Leaders
-
Accenture plc
-
International Business Machines Corporation
-
Tata Consultancy Services Limited
-
Capgemini SE
-
HCL Technologies Limited
- *Disclaimer: Major Players sorted in no particular order
Managed SaaS Application Operations Services Market Companies Covered in this Report
- Accenture plc
- International Business Machines Corporation
- Tata Consultancy Services Limited
- Capgemini SE
- HCL Technologies Limited
- Cognizant Technology Solutions Corporation
- Infosys Limited
- Dell Technologies Inc.
- Microsoft Corporation
- Amazon Web Services, Inc.
- Google LLC
- Oracle Corporation
- SAP SE
- Salesforce, Inc.
- ServiceNow, Inc.
- Wipro Limited
- Tech Mahindra Limited
- NTT DATA Corporation
- Fujitsu Limited
- DXC Technology Company
- Deloitte Touche Tohmatsu Limited
Recent Industry Developments in Managed SaaS Application Operations Services Market
- October 2026: TCS partnered with ManageEngine, the enterprise IT management division of Zoho Corporation, to integrate IT service management capabilities into TCS SovereignSecure Cloud, enabling government institutions and regulated industries to manage cloud and AI workloads with national data-residency guarantees.
- October 2026: Adesso expanded its partnership with ServiceNow to bring the ServiceNow AI Control Tower to market as a managed service across EMEA, delivering consulting, implementation, and AI governance operations, including AI discovery, security, and observability, from a single integrated service engagement.
- September 2026: Splunk extended its AI SRE capability in Splunk Observability Cloud to code-level remediation using Claude Managed Agents, and the system takes incident root cause and diagnostic context from observability telemetry, proposes targeted code fixes, and opens a pull request for engineer review, advancing managed incident response from detection to governed autonomous remediation.
- May 2026: ServiceNow and Lenovo announced a multi-year strategic agreement to reduce enterprise IT support costs and improve operational governance through AI-native operations, combining Lenovo's device ecosystem with ServiceNow's workflow automation platform.
Global Managed SaaS Application Operations Services Market Report Scope
The Managed SaaS Application Operations Services Market encompasses outsourced monitoring, maintenance, integration, security, compliance, incident management, and optimization of enterprise SaaS applications across diverse industries and deployment environments globally. The market is Segmented by Service Type (Managed Application Monitoring and Observability, Incident, Problem, and Request Management, Release, Patch, and Upgrade Management, SaaS Integration and API Operations, Security, Compliance, and Identity Operations, and Other Service Types), Deployment Model (On-Premises, Cloud-Based, and Hybrid), Application (Enterprise Resource Planning, Customer Relationship Management, Human Capital Management, Enterprise Collaboration and Productivity, IT Service Management, Marketing, Commerce, and Customer Experience, and Other Application Types), Organization Size (Small and Medium Enterprises and Large Enterprises), Organization Size (Small and Medium Enterprises, and Large Enterprises), End-User Industry (IT and Telecommunications, BFSI, Healthcare, Retail and E-Commerce, Manufacturing, Government and Defense, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed Application Monitoring and Observability |
| Incident, Problem, and Request Management |
| Release, Patch, and Upgrade Management |
| SaaS Integration and API Operations |
| Security, Compliance, and Identity Operations |
| Other Service Types |
| On-Premises |
| Cloud-Based |
| Hybrid |
| Enterprise Resource Planning |
| Customer Relationship Management |
| Human Capital Management |
| Enterprise Collaboration and Productivity |
| IT Service Management |
| Marketing, Commerce, and Customer Experience |
| Other Application Types |
| Small and Medium Enterprises |
| Large Enterprises |
| Information Technology and Telecommunications |
| BFSI |
| Healthcare |
| Retail and E-Commerce |
| Manufacturing |
| Government and Defense |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Rest of Africa |
| By Service Type | Managed Application Monitoring and Observability | |
| Incident, Problem, and Request Management | ||
| Release, Patch, and Upgrade Management | ||
| SaaS Integration and API Operations | ||
| Security, Compliance, and Identity Operations | ||
| Other Service Types | ||
| By Deployment Model | On-Premises | |
| Cloud-Based | ||
| Hybrid | ||
| By Application | Enterprise Resource Planning | |
| Customer Relationship Management | ||
| Human Capital Management | ||
| Enterprise Collaboration and Productivity | ||
| IT Service Management | ||
| Marketing, Commerce, and Customer Experience | ||
| Other Application Types | ||
| By Organization Size | Small and Medium Enterprises | |
| Large Enterprises | ||
| By End-User Industry | Information Technology and Telecommunications | |
| BFSI | ||
| Healthcare | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Government and Defense | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the Managed SaaS application operations services market?
The market is projected to expand from USD 18.47 billion in 2026 and USD 21.13 billion in 2027 to USD 40.96 billion by 2032, at a 14.37% CAGR.
Which service type leads managed SaaS application operations services?
Incident, Problem, and Request Management leads with a 31.47% share in 2026.
Which deployment model is expanding fastest?
Hybrid delivery is projected to expand at a 15.41% CAGR through 2032, as enterprises continue to operate cloud and on-premises systems together.
Why do enterprises use managed SaaS application operations services?
Enterprises use these services to improve application reliability, coordinate releases and integrations, and strengthen identity and security controls.
Which end-user industry has the highest projected expansion?
Healthcare is projected to expand at a 15.21% CAGR through 2032 because it requires dependable support for complex and sensitive application environments.
Which region is projected to expand fastest?
Asia-Pacific is projected to expand at a 15.36% CAGR through 2032, supported by cloud adoption across China, India, Japan, and Southeast Asia.