
Managed Mobile Security Management Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
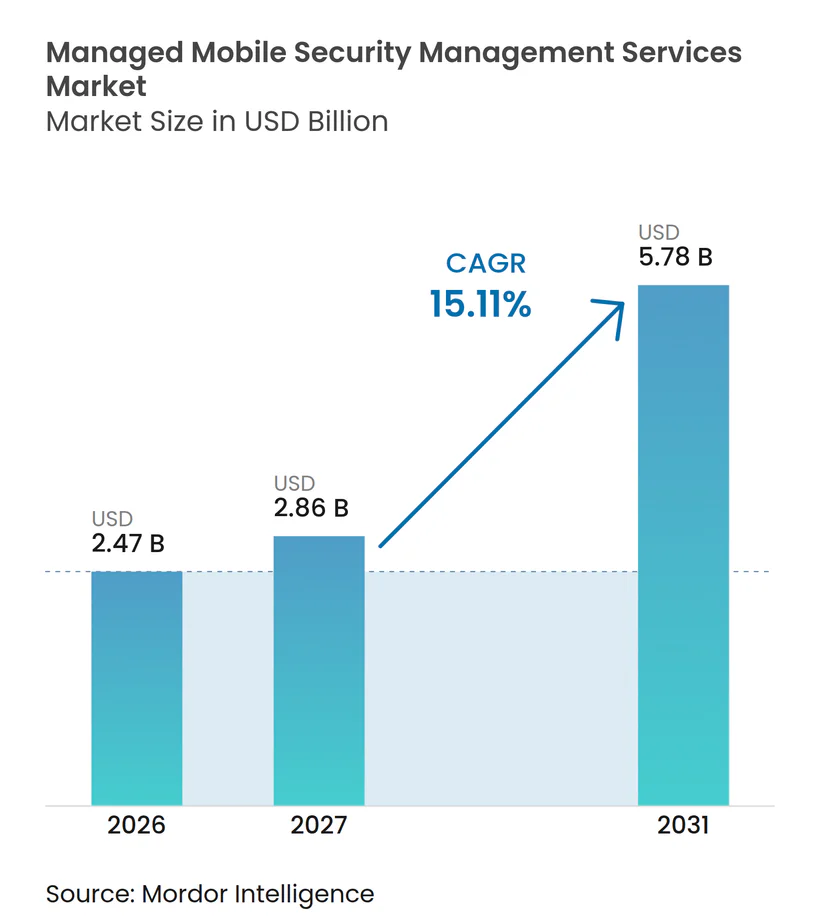
| Market Size (2027) | USD 2.86 Billion |
| Market Size (2031) | USD 5.78 Billion |
| Growth Rate (2027 - 2032) | 15.11 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Mobile Security Management Services Market Analysis by Mordor Intelligence
The managed mobile security management services market size is expected to increase from USD 2.47 billion in 2026 to USD 5.78 billion by 2032, growing at a CAGR of 15.11% over 2027-2032. Mobile phones, tablets, and connected endpoints increasingly provide access to identity systems, cloud applications, and core business workflows, which raises the impact of compromised devices. The managed mobile security services market is gaining traction as enterprises need continuous monitoring across personal, corporate-owned, and shared devices that run different operating systems and applications. AI-generated phishing, smishing, QR-phishing, and mobile malware are creating threats that basic mobile device management tools cannot always detect or investigate. Demand is also supported by privacy requirements, sector compliance obligations, and zero-trust programs that require organizations to record mobile risks and control access to sensitive applications. Providers are competing through fully managed offerings, analyst-assisted platforms, and carrier-integrated services, while integration with legacy identity, device management, and service desk systems can delay deployment and limit adoption among budget-constrained organizations.
Key Report Takeaways
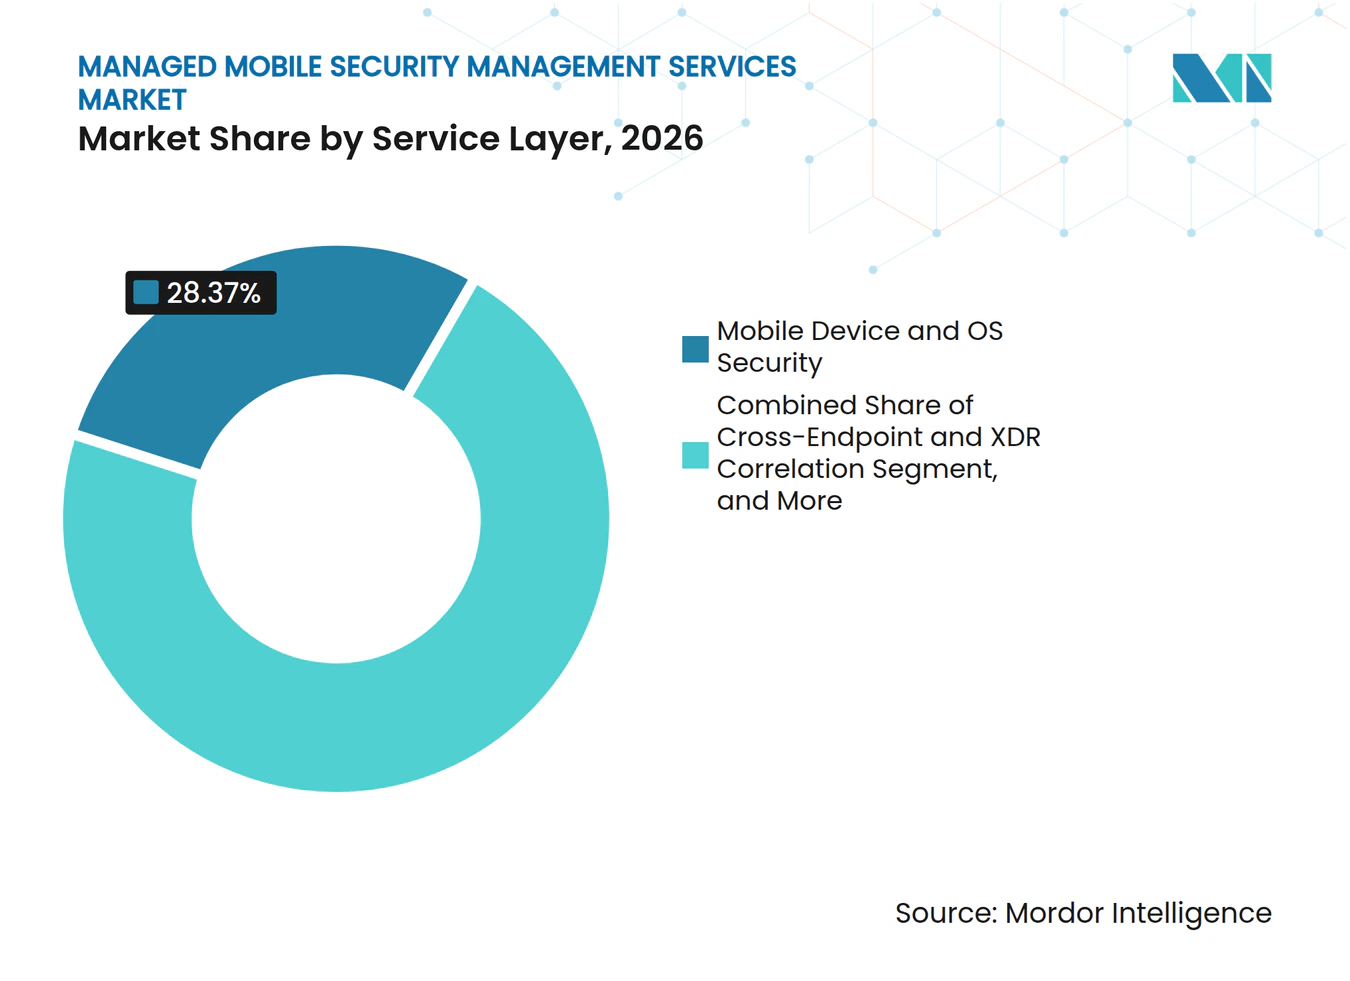
- By service layer, mobile device and OS security held 28.37% of managed mobile security management services market share in 2026, while cross-endpoint and XDR correlation is projected to expand at a 15.83% CAGR through 2032.
- By enterprise size, large enterprises held 66.83% share in 2026, while small and medium enterprises are projected to expand at a 16.27% CAGR through 2032.
- By service delivery model, fully managed services held 44.27% share in 2026, while Managed Platform with Analyst Add-On is projected to expand at a 15.91% CAGR through 2032.
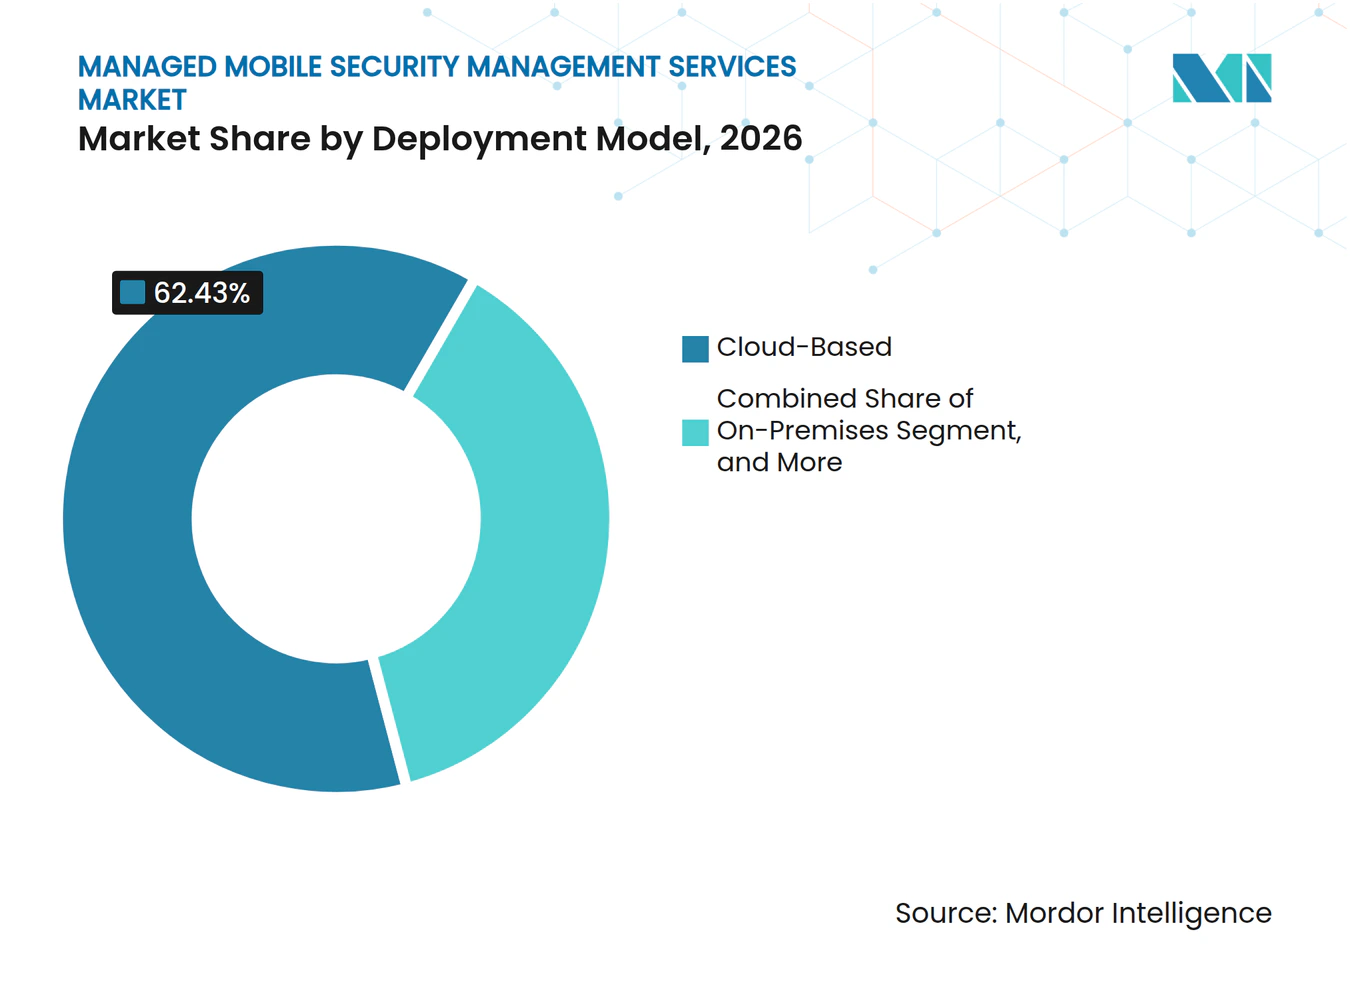
- By deployment model, cloud-based services held 62.43% share in 2026, while hybrid deployment is projected to expand at a 15.63% CAGR through 2032.
- By end-user industry, BFSI held 26.87% share in 2026, while healthcare is projected to expand at a 15.47% CAGR through 2032.
- By geography, North America held 39.17% share in 2026, while Asia-Pacific is projected to expand at a 16.07% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Mobile Security Management Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Mobile Phishing, Smishing, and QR-Phishing Attacks | +4.1% | Global | Short term (≤ 2 years) |
| BYOD and Remote-Work Proliferation | +3.4% | Global, concentrated in North America and Asia-Pacific | Medium term (2-4 years) |
| Tightening Privacy and Sector Compliance Mandates | +2.8% | Europe and North America, with Asia-Pacific spillover | Medium term (2-4 years) |
| Zero-Trust Integration for Mobile Endpoints | +2.4% | North America and Europe | Medium term (2-4 years) |
| Mobile Risk Telemetry Blind Spots in Existing Security Operations Centers | +1.7% | Global | Long term (≥ 4 years) |
| Privacy-Preserving On-Device Analytics for BYOD Environments | +1.3% | Asia-Pacific and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating Mobile Phishing, Smishing, and QR-Phishing Attacks
Phishing campaigns targeting mobile users have become more targeted and harder to detect with basic device controls. Zimperium reported that phishing events detected on employees' mobile devices increased by 380% since January 2025, while the number of devices on which employees clicked malicious links increased by 110%. QR-phishing increased 146% quarter over quarter in Q1 2026, and the Anti-Phishing Working Group recorded a further 40% increase in smishing from Q1 to Q2 2026. Zimperium also found that 86% of phishing campaigns carried AI-generated content, increasing the need for continuously refreshed threat intelligence and managed investigation.
BYOD and Remote-Work Proliferation
Zimperium reported that the average employee device had 80 applications, only 9 of which were work-related, and that more than 22% of Android devices had sideloaded applications. The managed mobile security management services market can address this fragmented environment through behavioral monitoring and response that extends beyond policy-based mobile device management. This need is especially relevant across the managed mobile security management services market for smaller organizations that lack dedicated mobile security staff.
Tightening Privacy and Sector Compliance Mandates
Mobile security governance is becoming more formal as privacy rules and sector requirements place greater attention on device data and application behavior. France's CNIL published Deliberation No. 2025-024 in April 2025, clarifying GDPR obligations for mobile application publishers, SDK providers, and operating system providers. The guidance requires proportionality assessments when mobile device attestation processes personal data. NIS2 enforcement across European Union member states in 2025 also increased expectations for incident reporting and risk management for essential service operators.
Zero-Trust Integration for Mobile Endpoints
Mobile endpoints are increasingly included in zero-trust security programs because they access sensitive applications and identity services. Verizon reported that 43% of organizations had adopted zero trust, including 47% of enterprises and 38% of small and medium businesses. CrowdStrike launched Falcon Zero Trust Assessment for iOS and Android in May 2025, linking real-time device trust scoring with Android Enterprise Device Trust signals.[1] Verizon Business introduced Trusted Connection in March 2025 for midsize businesses that need secure access across connected devices, web, cloud, SaaS, and private applications.
Restraints Impact Analysis of Managed Mobile Security Management Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Integration Complexity With Legacy Identity and IT Stacks | -2.1% | Global | Short term (≤ 2 years) |
| Budget Constraints Among Mid-Sized Enterprises | -1.6% | Global | Medium term (2-4 years) |
| Cross-Tenant Data Isolation and Data-Sovereignty Requirements | -1.1% | Europe and Asia-Pacific | Medium term (2-4 years) |
| Mobile Risk-Scoring Explainability and Employee-Trust Friction | -0.8% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Integration Complexity With Legacy Identity and IT Stacks
Managed mobile security deployments often require connections to identity providers, unified endpoint management platforms, and service management tools. These systems may use different data models, APIs, and configuration methods, which can extend onboarding and create professional services costs. NIST has documented the importance of integrating BYOD security controls across enterprise systems, including identity, device, application, and data protection. Providers may need custom connectors for each identity provider-device management combination, which complicates sales and delivery. The issue is particularly relevant when real-time client telemetry is required for analyst-backed services. Integration gaps can create visibility limitations that reduce the value of a managed mobile security management services market offering.
Budget Constraints Among Mid-Sized Enterprises
Mid-sized organizations need stronger mobile protection but often face limits on security spending and internal expertise. Verizon found that 57% of small and medium businesses acknowledged a resource disadvantage in responding to cybersecurity incidents. Adoption of advanced multifactor authentication was also lower among small and medium businesses, at 45% compared with 57% for enterprises. Providers in the managed mobile security management services market must balance the cost of analyst-supported operations with smaller device fleets and lower per-seat budgets. Modular offerings in the managed mobile security services market enable clients to start with core managed services and add higher-touch support as risk and compliance requirements rise.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Mobile Security Management Services Market Segment Analysis
By Service Layer:
Foundational Device Security Supports Demand While XDR Integration Changes DeliveryMobile device and OS security accounted for 28.37% share in 2026. The category addresses device hardening, operating system patch monitoring, and mobile malware detection. Mobile application and runtime security address application behavior, while network and web security focus on unsafe connections and web-based threats. Identity and user behavior analytics add monitoring for unusual user activity. Mobile transaction and account-takeover risk analytics remain important for financial institutions because a compromised banking session can create direct loss exposure.
Cross-endpoint and XDR correlation is projected to expand at a 15.83% CAGR from 2027 to 2032. Security teams increasingly need a single view of mobile, endpoint, cloud, and network telemetry rather than separate mobile dashboards. Zimperium identified 34 active mobile malware families targeting more than 1,200 financial brands across 90 countries in 2025, underscoring the scope of the risk that specialized mobile telemetry can detect.[2] Zimperium and CrowdStrike integrated mobile threat intelligence with Falcon Next-Gen SIEM in March 2025. Providers in the managed mobile security management services market that fit within broader security operations environments may be better positioned to serve buyers seeking fewer separate tools.



By Enterprise Size:
Large Enterprises Lead Spending While Smaller Organizations Increase AdoptionLarge enterprises accounted for 66.83% share in 2026. Their larger device fleets, broader compliance responsibilities, and ability to manage long-term service contracts support this position. Many large organizations use co-managed arrangements or analyst add-on models. These models allow internal teams to retain policy oversight and first-level triage. The external provider can then supply advanced analytics, specialist threat intelligence, and response support.
Small and medium enterprises are projected to expand at a 16.27% CAGR from 2027 to 2032. Fully managed services can be more practical for these organizations than hiring and retaining dedicated mobile security specialists. CrowdStrike included Falcon for Mobile in its Falcon Go SMB endpoint protection bundle, illustrating the use of lower-entry offerings for smaller buyers. These customers may still reassess subscriptions when the service does not show clear quarterly prevention or response outcomes. Clear reporting, modular pricing, and visible security outcomes are important for maintaining relationships in the managed mobile security management services market.
By Service Delivery Model:
Fully Managed Services Lead While Analyst-Assisted Platforms Gain GroundFully managed services accounted for 44.27% of the managed mobile security services market in 2026. This model appeals to enterprises that want a third party to operate mobile security tools and manage day-to-day response. Mid-sized organizations and public-sector users can benefit even when they do not have dedicated mobile security analysts. The model also supports documented security controls and recurring reporting. This can help clients with audits and internal governance requirements.
Managed Platform With Analyst Add-On is projected to expand at a 15.91% CAGR from 2027 to 2032. This format combines automated monitoring with human review for investigations, policy exceptions, and escalations. Lookout launched AI Visibility and Governance in April 2026 to identify AI-enabled applications on mobile devices and flag Shadow AI activity for analyst review. The approach reflects demand for automation at scale without removing contextual judgment from complex cases. The mobile security management services industry, therefore, supports several operating models rather than a single service design.
By Deployment Model:
Cloud-Based Services Lead While Hybrid Models Address Data Control NeedsCloud-based services held 62.43% share of the managed mobile security management services market in 2026. Cloud delivery allows providers to update threat intelligence, distribute policy changes, and add analytics capacity without client-side infrastructure investment. This approach can reduce deployment time for users with cloud-connected applications and identity systems. Cloud delivery helps reduce delays that can occur when security traffic must pass through on-premises inspection systems. These operational factors explain the strong use of cloud-based services in the managed mobile security management services market.
Hybrid deployment is projected to expand at a 15.63% CAGR from 2027 to 2032. Regulated organizations may need localized processing for certain mobile telemetry while still relying on global threat intelligence. Financial institutions are a clear example, as data residency requirements can coexist with the need for broad threat coverage. Providers must maintain consistent performance between local and cloud components. On-premises deployment remains relevant for government and defense users with network isolation requirements, although sovereign cloud delivery offers an alternative.

By End-User Industry:
BFSI Maintains the Largest Position While Healthcare Expands FastestBFSI held 26.87% share in 2026. The sector faces mobile transaction fraud, account-takeover attempts, and extensive compliance requirements. PCI DSS and the SWIFT Customer Security Program create additional pressure for documented controls. Zimperium tracked 34 mobile malware families targeting more than 1,200 financial brands across 90 countries in 2025. Leagsoft reported coverage across 6 major Chinese state-owned banks after winning a mobile security project with China Construction Bank in 2026.
Healthcare is projected to expand at a 15.47% CAGR from 2027 to 2032. Hospitals, telemedicine providers, and medical device manufacturers are extending clinical workflows to mobile devices. Shared devices between shifts create specific enrollment, access, and data separation requirements. HIPAA requires documented safeguards for electronic protected health information, making audit-ready management valuable. Government and defense require strong controls, while manufacturing is increasing its use of mobile devices in managed mobile security services.
Geography Analysis
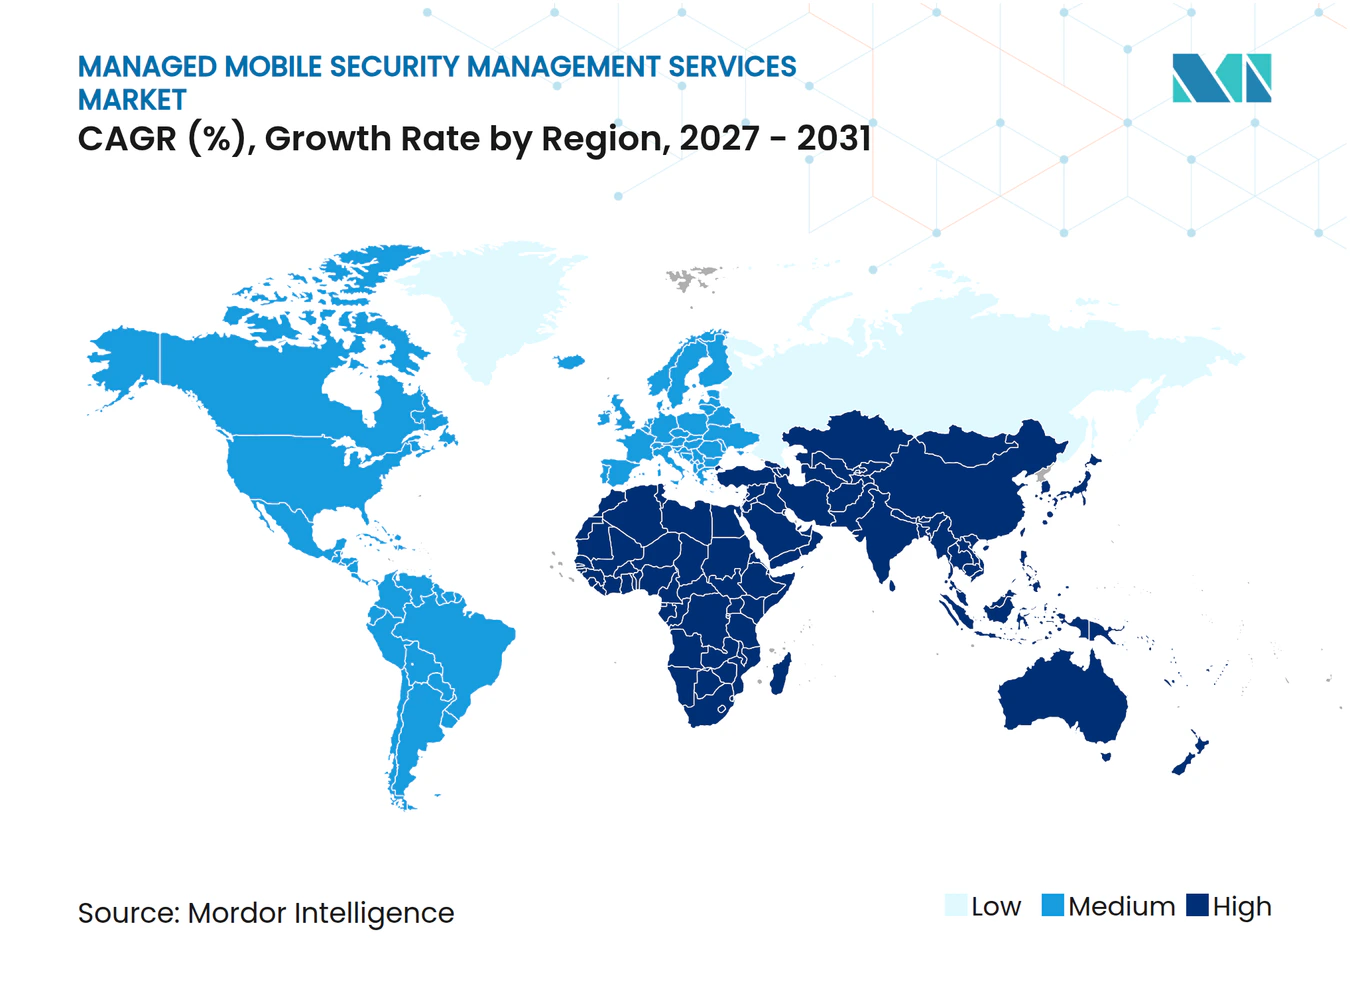
North America held 39.17% of the managed mobile security management services market share in 2026. AT&T Business and Palo Alto Networks made AT&T Dynamic Defense and AT&T SASE available in July 2026. Verizon Business launched Trusted Connection in March 2025 for midsize enterprises. United States demand is supported by CISA requirements and the Department of Defense Cybersecurity Maturity Model Certification framework. Canada is increasing its endpoint security activity in financial services and government, while Mexico is supported by mobile use in manufacturing and stronger corporate governance practices.
Europe has a material position in the managed mobile security management services market because GDPR and NIS2 require stronger risk management and incident reporting. The United Kingdom, Germany, and France lead adoption through their respective mobile security and data protection frameworks. France's CNIL guidance for mobile applications provides a clear example of the region's close attention to data processing and mobile device attestation. South America is developing in the managed mobile security management services market through Brazil's LGPD-driven mobile data governance activity, particularly in financial services.
Asia-Pacific is projected to expand at a 16.07% CAGR from 2027 to 2032. GSMA reported that Asia-Pacific cybersecurity spending is forecast to reach USD 60.6 billion by 2028, with a 10.6% CAGR from 2025. iCubed Systems launched Trend Vision One Mobile Security in December 2025 through its CLOMO MDM platform in Japan.[3] GSMA Intelligence also indicated that nearly two-thirds of mobile operators in Asia-Pacific had adopted proactive security approaches, compared with 53% globally.
Competitive Landscape
Market Concentration
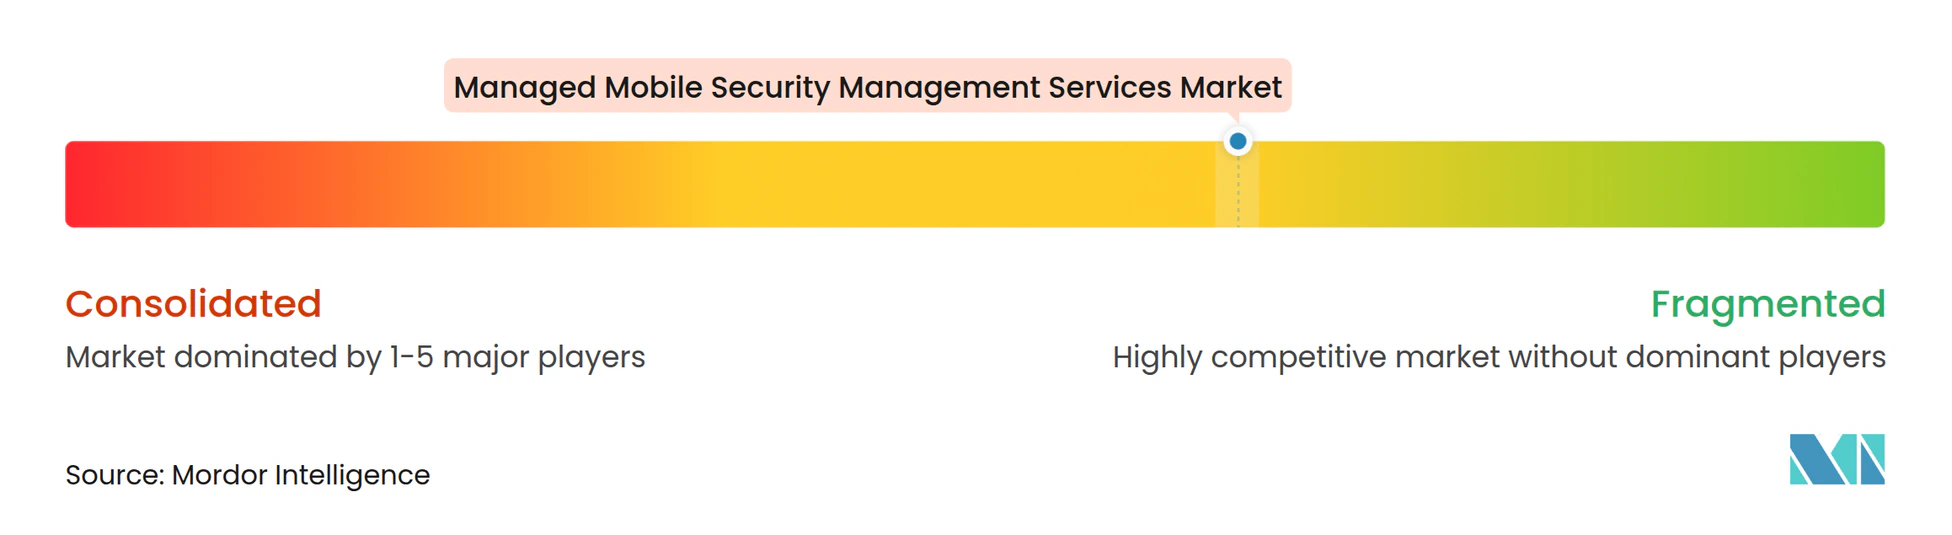
The managed mobile security management services market is moderately fragmented. Large IT services providers, telecom operators, endpoint security vendors, unified endpoint management specialists, and pure-play mobile security firms all compete for enterprise contracts. Accenture, IBM, NTT DATA, and Kyndryl provide mobile protection as part of broader managed security portfolios. AT&T and Verizon combine security services with network operations. Ivanti, Jamf, and Omnissa focus on device management, while Zimperium, Lookout, and Pradeo contribute specialized mobile threat intelligence.
Competition increasingly centers on integrating mobile signals into broader security operations. CrowdStrike released Falcon Zero Trust Assessment for iOS and Android in May 2025, combining mobile posture scoring with Android Enterprise Device Trust signals. Zimperium and Sekoia announced an October 2026 integration to bring mobile threat telemetry into an autonomous security operations platform. These examples address a recurring issue where mobile threats are examined separately from cloud and endpoint incidents. Providers in the managed mobile security management services market that make mobile alerts usable within one investigation process can offer a clearer operating case to enterprise buyers.
Carrier and technology partnerships are another important competitive approach in the managed mobile security management services market. AT&T and Cisco launched a secure access service edge offering in August 2025 for distributed enterprises. T-Mobile and Palo Alto Networks announced their managed SASE offering in May 2025, bringing SIM-based authentication and 5G security capabilities to wireless endpoints. Pradeo expanded through partner integrations with Samsung SDS, Techstep, and Fence, showing how specialists can use channels rather than relying only on direct enterprise sales.
Managed Mobile Security Management Services Industry Leaders
-
Accenture plc
-
AT&T Inc.
-
Broadcom Inc.
-
Cisco Systems, Inc.
-
CrowdStrike Holdings, Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Mobile Security Management Services Market Companies Covered in this Report
- Accenture plc
- AT&T Inc.
- Broadcom Inc.
- Cisco Systems, Inc.
- CrowdStrike Holdings, Inc.
- International Business Machines Corporation
- Ivanti, Inc.
- JAMF Software, LLC
- Kyndryl Holdings, Inc.
- Lookout, Inc.
- Microsoft Corporation
- NTT DATA Corporation
- Omnissa, LLC
- Palo Alto Networks, Inc.
- Verizon Communications Inc.
- Zimperium, Inc.
- Pradeo Security Systems SAS
Recent Industry Developments in Managed Mobile Security Management Services Market
- October 2026: Zimperium and Sekoia announced an integration bringing Zimperium Mobile Threat Defense telemetry into Sekoia's autonomous SOC platform, enabling security teams to correlate mobile threat signals with broader enterprise security events and conduct AI-assisted investigations. This directly addresses the persistent blind spot of mobile threats being investigated in isolation from endpoint and cloud incidents.
- July 2026: AT&T Business and Palo Alto Networks announced the general availability of AT&T Dynamic Defense with Palo Alto Networks and AT&T SASE with Palo Alto Networks, delivering AI-driven, fully managed threat prevention and unified SASE integrated into AT&T's enterprise network. Both offerings include a practical path to quantum resilience, targeting the complexity of securing multi-cloud environments and mobile and remote workforces.
- April 2026: Lookout launched AI Visibility and Governance, a mobile-first capability that discovers sanctioned and unsanctioned AI-enabled applications on corporate-owned and BYOD devices, monitors AI agent behavior, and enforces data guardrails to prevent sensitive information from reaching unapproved AI services.
- February 2026: AT&T upgraded ActiveArmor Advanced Mobile Security to include identity fraud reimbursement up to USD 1 million per subscriber and real-time alerts for financial and credit activity, adjusting the monthly per-line price from USD 3.99 to USD 7.
Global Managed Mobile Security Management Services Market Report Scope
The Managed Mobile Security Management Services Market encompasses outsourced services that help organizations secure, monitor, manage, and protect mobile devices, applications, data, and networks from cyber threats. The report analyzes market trends, demand drivers, challenges, competitive dynamics, and growth opportunities across service types, deployment models, organization sizes, end-user industries, and geographic regions.
The Managed Mobile Security Management Services Market Report is Segmented by Service Layer (Mobile Device and OS Security, Mobile Application and Runtime Security, Mobile Network and Web Security, Mobile Identity and User Behavior Analytics, Mobile Transaction and Account-Takeover Risk Analytics, and Cross-Endpoint and XDR Correlation), Enterprise Size (Large Enterprises, and Small and Medium Enterprises), Service Delivery Model (Fully Managed Services, Co-Managed Services, and Managed Platform With Analyst Add-On), Deployment Model (On-Premises, Cloud-Based, and Hybrid), End-User Industry (Information Technology and Telecommunications, BFSI, Healthcare, Retail and E-Commerce, Manufacturing, Government and Defense, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Mobile Device and OS Security |
| Mobile Application and Runtime Security |
| Mobile Network and Web Security |
| Mobile Identity and User Behavior Analytics |
| Mobile Transaction and Account-Takeover Risk Analytics |
| Cross-Endpoint and XDR Correlation |
| Large Enterprises |
| Small and Medium Enterprises |
| Fully Managed Services |
| Co-Managed Services |
| Managed Platform With Analyst Add-On |
| On-Premises |
| Cloud-Based |
| Hybrid |
| Information Technology and Telecommunications |
| BFSI |
| Healthcare |
| Retail and E-Commerce |
| Manufacturing |
| Government and Defense |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Rest of Africa |
| By Service Layer | Mobile Device and OS Security | |
| Mobile Application and Runtime Security | ||
| Mobile Network and Web Security | ||
| Mobile Identity and User Behavior Analytics | ||
| Mobile Transaction and Account-Takeover Risk Analytics | ||
| Cross-Endpoint and XDR Correlation | ||
| By Enterprise Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By Service Delivery Model | Fully Managed Services | |
| Co-Managed Services | ||
| Managed Platform With Analyst Add-On | ||
| By Deployment Model | On-Premises | |
| Cloud-Based | ||
| Hybrid | ||
| By End-User Industry | Information Technology and Telecommunications | |
| BFSI | ||
| Healthcare | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Government and Defense | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed mobile security management services market?
The managed mobile security management services market size is USD 2.47 billion in 2026 and is projected to reach USD 5.78 billion by 2032, at a 15.11% CAGR from 2027 to 2032.
What is driving demand for managed mobile security services?
Growing mobile phishing, personal device use, privacy requirements, and zero-trust adoption are increasing the need for continuous mobile monitoring and response.
Which service category has the largest share?
Mobile device and OS security leads the service layer with a 28.37% share in 2026, supported by demand for device hardening, patch monitoring, and malware detection.
Which enterprise group is growing fastest?
Small and medium enterprises are projected to grow at a 16.27% CAGR through 2032 as fully managed services offer an alternative to building in-house capabilities.
Which deployment approach is expanding fastest?
Hybrid deployment is projected to expand at a 15.63% CAGR through 2032 because regulated organizations need localized data handling and cloud-scale threat intelligence.
Which region is expanding fastest?
Asia-Pacific is projected to expand at a 16.07% CAGR through 2032, supported by enterprise digitization, 5G availability, and cybersecurity investment.