
Managed Field Support Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 15.87 Billion |
| Market Size (2032) | USD 24.37 Billion |
| Growth Rate (2027 - 2032) | 8.96 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Field Support Services Market Analysis by Mordor Intelligence
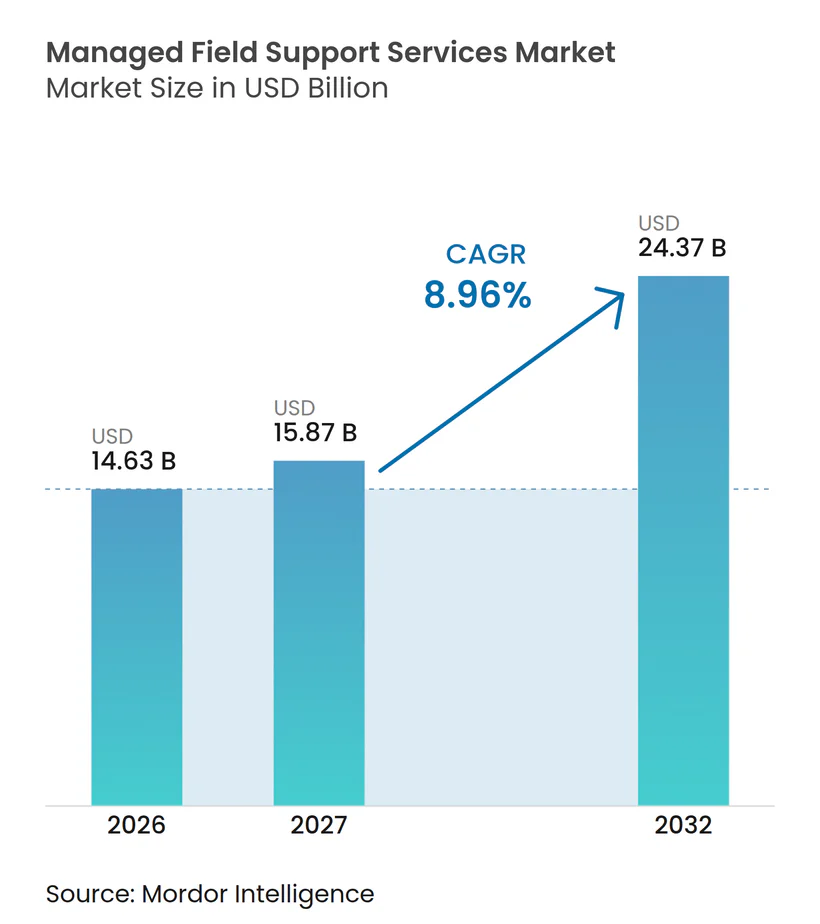
The managed field support services market size is projected to expand from USD 14.63 billion in 2026 and USD 15.87 billion in 2027 to USD 24.37 billion by 2032, registering a CAGR of 8.96% between 2027 to 2032. The managed field support services market is supported by AI infrastructure deployment, larger multi-vendor technology estates, and limited availability of certified field technicians. These conditions are moving work that enterprises once handled internally into longer-term outsourced service contracts. Providers are responding with remote diagnostics, predictive maintenance, and service models that link payment to asset availability or service outcomes. Data sovereignty, third-party access controls, and difficult links between operational technology and information technology can slow adoption. The strongest opportunities favor providers that can deliver local coverage, specialized technical skills, and consistent support across mixed hardware and software environments.
Key Report Takeaways
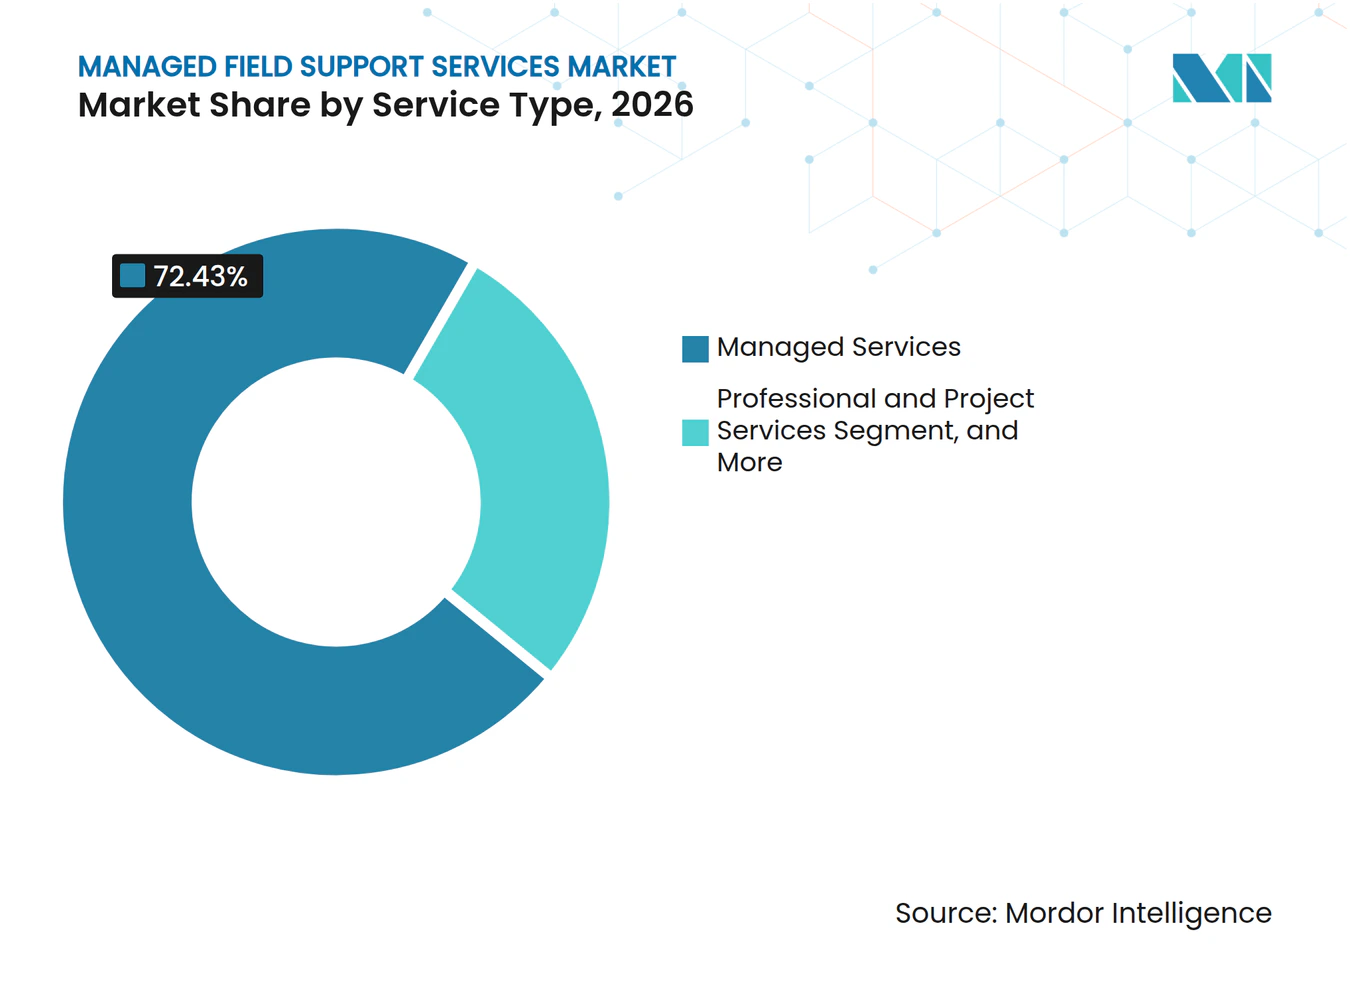
- By service type, managed services held 72.43% of the managed field support services market share in 2026, while professional and project services are projected to expand at a 9.27% CAGR through 2032.
- By deployment model, hybrid configurations held 46.37% share in 2026, while cloud-based delivery is projected to expand at a 9.63% CAGR through 2032.
- By technology model, OEM-authorized support held 33.27% share in 2026, while AI-enabled and predictive support is projected to expand at a 9.43% CAGR through 2032.
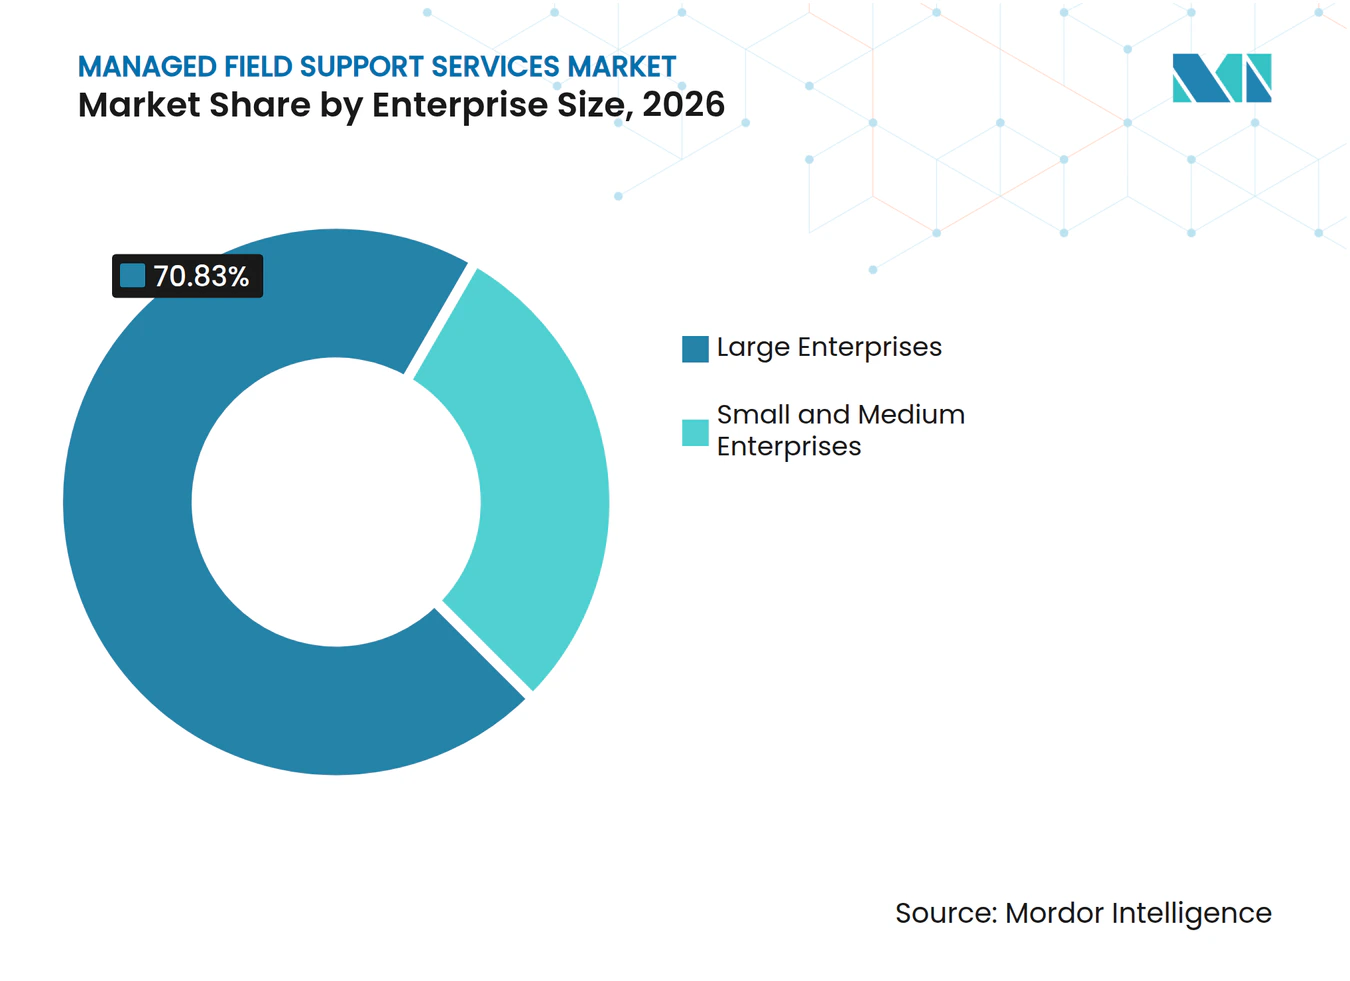
- By enterprise size, large enterprises held 70.83% share in 2026, while SMEs are projected to expand at a 9.17% CAGR through 2032.
- By industry vertical, information technology and telecommunications held 26.43% share in 2026, while data centers and cloud infrastructure are projected to expand at a 9.87% CAGR through 2032.
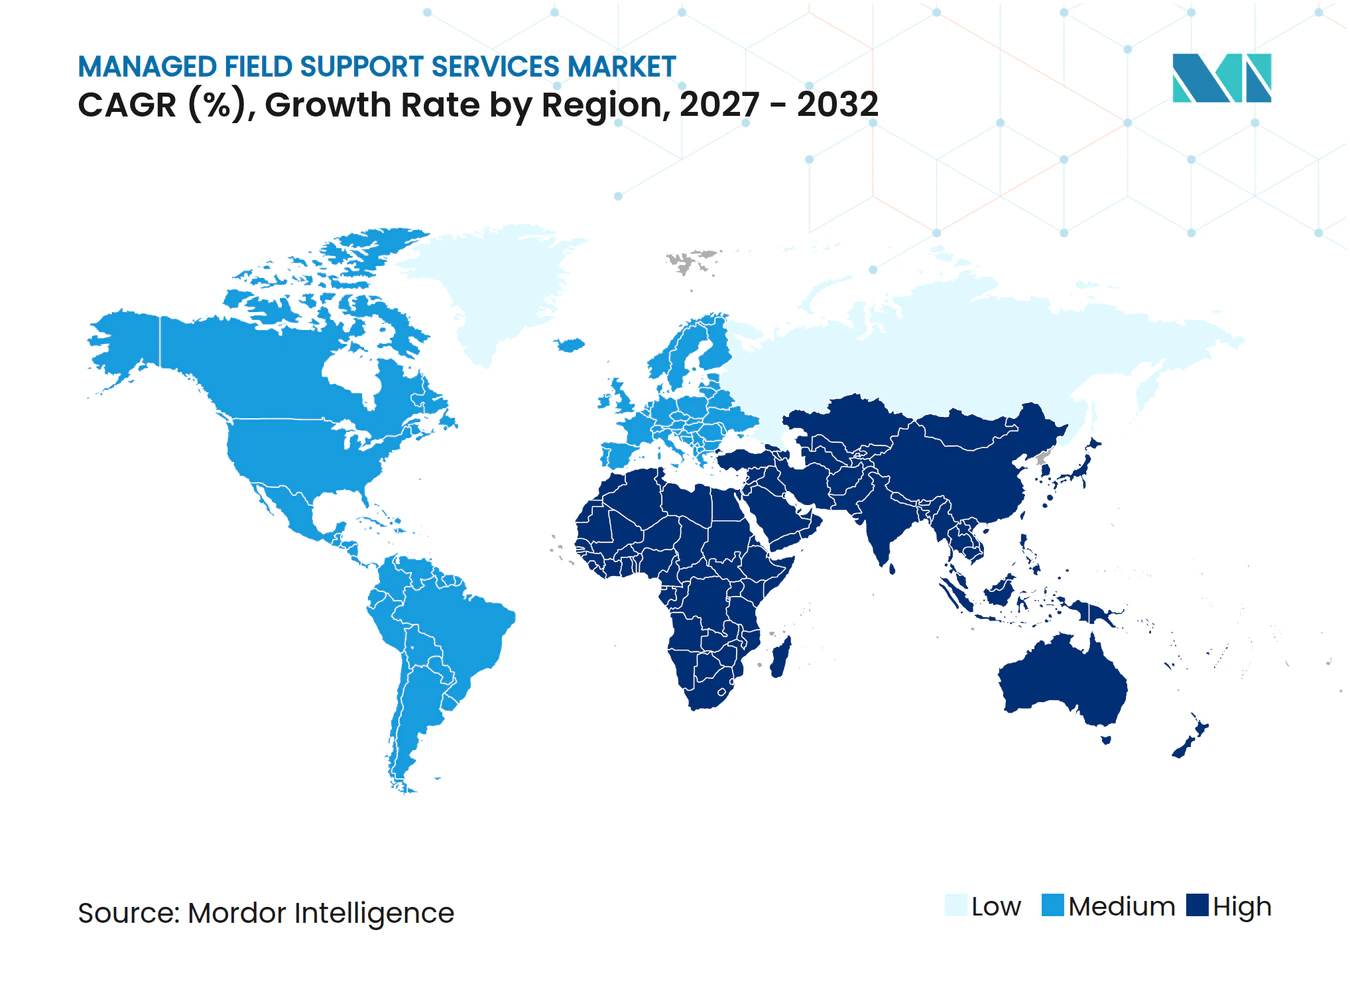
- By geography, North America held 36.17% share in 2026, while Asia-Pacific is projected to expand at a 9.93% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Field Support Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI Infrastructure and Connected-Asset Expansion | +2.2% | Global, concentrated in North America and Asia-Pacific | Short term (≤ 2 years) |
| Enterprise Shift Toward Outcome-Based Support Contracts | +1.8% | North America and Europe, early adoption in Asia-Pacific | Medium term (2-4 years) |
| Multi-Vendor Technology Estate Complexity | +1.5% | Global | Short term (≤ 2 years) |
| Data Center and Network Footprint Expansion | +1.3% | North America, Asia-Pacific core, spill-over to Middle East | Short term (≤ 2 years) |
| Remote Diagnostics and Predictive Maintenance Adoption | +0.9% | Global | Medium term (2-4 years) |
| Remote-Site Coverage Gaps Driving Specialized Fulfillment | +0.7% | Africa, South America, Rest of Asia-Pacific, rural North America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
AI Infrastructure and Connected-Asset Expansion
AI infrastructure is increasing the need for specialized on-site support in the managed field support services market. GPU clusters, liquid-cooling equipment, and high-density racks require technicians with skills that routine hardware support teams may lack. Field Nation reported that Amazon, Alphabet, Microsoft, and Meta committed USD 650 billion to AI infrastructure in 2026, 67% more than their 2025 outlay.[1] This spending supports more complex environments where providers must maintain specialized equipment and respond quickly to failures. Providers that train technicians in GPU maintenance and liquid-cooling protocols can compete for higher-value assignments. Providers that do not update their technical capabilities may lose access to new infrastructure contracts.
Enterprise Shift Toward Outcome-Based Support Contracts
The managed field support services market is moving toward contracts that measure performance through uptime, first-time fix rates, and service continuity. This approach places greater emphasis on reliable data, clear baselines, and agreed service governance. ServiceNow and Accenture introduced AI-powered managed security services in June 2026 that combine IT and OT risk management on the ServiceNow AI Platform. The launch shows how providers are combining platforms and services to support measurable operational results. Outcome-based contracts can improve alignment between buyers and providers when both parties use the same performance definitions. They can also create disputes when service data, responsibility boundaries, or reporting rules are unclear.
Multi-Vendor Technology Estate Complexity
Mixed technology estates make a single point of accountability more valuable to enterprise buyers. Each supplier can introduce separate monitoring tools, escalation processes, service terms, and diagnostic requirements. HPE refocused its Complete Care Service in March 2026 around a unified AI-powered support experience with dedicated Service Experience Managers and Technical Advisors. The service is designed to coordinate support across hybrid and multi-vendor environments. Providers that connect configuration records, dispatch processes, and service history can reduce the administrative load for customers. This capability can support stronger pricing when the customer operates a large and varied technology estate.
Data Center and Network Footprint Expansion
Data center construction is widening the physical coverage requirements of the managed field support services market. Field Nation reported that data center construction grew 35% in 2025, data center field work on managed services platforms grew 18.3% year over year, and work order volume increased 216% over 5 years. New capacity is extending into locations where technician networks and spare parts inventories are less mature. That expansion increases the value of providers that can position qualified engineers and components near emerging centers of demand. Network infrastructure near data centers also needs on-site support that remote monitoring cannot fully replace. Providers with local coverage can therefore be better placed to win contracts that require short response times.
Restraints Impact Analysis of Managed Field Support Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Third-Party Privileged-Access and Data-Sovereignty Risk | -1.4% | Global, heightened in Europe and government sectors | Short term (≤ 2 years) |
| Legacy OT and Proprietary-Interface Integration Complexity | -1.1% | Global, concentrated in manufacturing, utilities, and government | Medium term (2-4 years) |
| OEM Warranty and Parts-Access Restrictions | -0.7% | Global | Medium term (2-4 years) |
| Shortage of Certified Legacy-Hardware and Edge Technicians | -0.6% | Remote and frontier markets globally, North America rural corridor | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Third-Party Privileged-Access and Data-Sovereignty Risk
Third-party technicians often need elevated access to production systems, creating a material concern for buyers in the managed field support services market. Data location, session recordings, diagnostic logs, and subcontractor access can each affect supplier selection. These issues are especially important in Europe and public-sector environments where data residency and security requirements are strict. Buyers increasingly require time-limited access, approved storage locations, session records, and clear visibility into subcontractors. Service providers must show that their operating model can protect systems while enabling timely diagnostics and repair. Strong access controls can therefore become a competitive requirement rather than only a compliance measure.
Legacy OT and Proprietary-Interface Integration Complexity
Manufacturers, utilities, and government organizations may operate equipment that does not work with standard remote support tools. PLC and SCADA environments can require specialized knowledge, controlled access, and a site visit when remote resolution is not possible. The resulting dispatch can raise delivery costs and make service-level commitments harder to meet. The managed field support services market needs engineers who understand both operational technology and information technology in these settings. ServiceNow and Accenture's June 2026 collaboration addressed this convergence through combined IT and OT risk management services. Smaller providers may find it difficult to fund the required training, process controls, and specialized staffing.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Field Support Services Market Segment Analysis
By Service Type:
Managed Contracts Support Recurring RevenueManaged services held 72.43% of the managed field support services market share in 2026. The segment benefits from recurring agreements that shift operational risk and staffing pressures to specialist providers. These contracts commonly cover break-fix work, monitoring, and lifecycle management. Their scope can also include AI readiness reviews, vendor coordination, and lifecycle advice. Customers use them to create more predictable support budgets and to reduce the burden on internal information technology teams. Providers benefit from multi-year revenue visibility and closer customer relationships. The managed field support services market size tied to managed contracts reflects the importance of dependable, ongoing support across multi-site estates.
Professional and project services are projected to expand at a 9.27% CAGR through 2032. This segment serves work that needs expert-led execution outside the normal scope of recurring support agreements. AI infrastructure deployments, cloud migrations, technology refreshes, staff augmentation, and equipment commissioning support demand. GPU-dense data center pods may require planning and installation skills that differ from those for standard maintenance tasks. Buyers often use the same provider for ongoing support and discrete transformation projects.


By Deployment Model:
Hybrid Operations Remain the Practical ChoiceHybrid configurations held 46.37% of the managed field support services market share in 2026. Large organizations often cannot migrate every workload or service process to cloud-based support simultaneously. Sensitive workloads, legacy applications, and regulatory obligations can require local processing or direct on-site control. Hybrid delivery lets buyers combine remote management with on-premises intervention where it is needed. It also gives providers a way to support gradual modernization rather than a single large transition. HPE's Complete Care Service combines hybrid-environment monitoring with operational support tools. This model fits organizations managing mixed infrastructure across multiple sites.
Cloud-based delivery is projected to grow at a 9.63% CAGR through 2032. Remote diagnostics, subscription pricing, and simpler access to specialist expertise support adoption among SMEs. Cloud delivery can reduce upfront spending while allowing support teams to monitor a broader asset base. It can also give providers more standardized processes for dispatch, reporting, and service management. On-premises support still has an important role in financial services, defense, and healthcare. These sectors may limit cloud handoffs because of security, network isolation, or data residency requirements. The managed field support services market will therefore continue to depend on flexible delivery models rather than a complete shift to cloud-only support.
By Technology Model:
AI-Enabled Support Gains GroundOEM-authorized support held 33.27% of the managed field support services market share in 2026. Warranty obligations and access to proprietary diagnostic tools help sustain this position. Buyers may also retain OEM relationships to support hardware life-cycle planning and replacement decisions. Dell was recognized as a Leader in the IDC MarketScape Worldwide Hardware Support Services assessment, citing AI-driven observability and predictive monitoring in its ProSupport portfolio. Vendor-agnostic support remains relevant for organizations with mixed infrastructure from several suppliers. ITSM and CMDB integration can also connect service dispatch to change controls and asset records.
AI-enabled and predictive support is projected to advance at a 9.43% CAGR through 2032. These models seek to identify problems earlier and to organize diagnostics, parts checks, and technician schedules before a failure becomes more serious. PTC launched ServiceMax AI in September 2025 with multi-agent work order execution and a Knowledge API that connects documents across enterprise systems.[2] The release reflects a shift toward automated coordination of field work and service information. Predictive models can reduce avoidable dispatches when the underlying asset and service data are reliable. Outcome-based and SLA-linked support can package these capabilities into commercial terms that reward better service performance.
By Enterprise Size:
Large Enterprises Lead While SMEs Grow FasterLarge enterprises held 70.83% of the managed field support services market share in 2026. Their multi-site technology estates, demanding service levels, and ability to fund long-term contracts support this position. Global organizations need consistent maintenance and repair practices across many jurisdictions. They also need a unified view of assets, incidents, vendors, and service performance. HPE's March 2026 service update assigns dedicated advisors and managers to help customers manage complex hybrid environments. This approach is well-suited to large customers that want one accountable partner across a broad technology footprint.
SMEs are projected to grow at a 9.17% CAGR through 2032. Cloud-delivered support reduces the need for large upfront technology and staffing investments. It can give smaller firms access to remote monitoring, ticket management, and specialist technical support. Fixed-fee packages can also make support costs easier to plan. Sharp Business Systems Deutschland launched a nationwide managed services program in March 2026, offering cloud, endpoint management, and helpdesk services for businesses lacking in-house information technology capabilities. These offerings can help SMEs use more formal support models as their technology needs increase.

By Industry Vertical:
IT and Telecom Retain the Largest ShareInformation technology and telecommunications held 26.43% of the managed field support services market share in 2026. The vertical depends on continuous availability across a distributed network and hardware environments. Telecom operators need rapid dispatch across many sites, which internal teams can find costly to scale. BFSI is the second-largest vertical because core banking services require high levels of uptime. Healthcare needs support for connected medical-device networks. Retail and e-commerce demand is concentrated around point-of-sale systems. Government and defense contracts can be long-term and may require personnel with specific clearances.
Data centers and cloud infrastructure are projected to expand at a 9.87% CAGR through 2032. Hyperscale construction and larger cloud estates are increasing the need for installation, maintenance, monitoring, and parts coordination. Field Nation reported that data center work order volume grew 216% over 5 years. The service requirements in this vertical are more specialized because of high-density equipment and strict uptime expectations. Providers need credible coverage for data center locations, certified technical staff, and readily available components. The managed field support services market has room for suppliers that can provide lifecycle support for both established and new data center sites.
Geography Analysis
North America held 36.17% of the managed field support services market share in 2026. The region has major hyperscale data center clusters, large enterprise technology estates, and established outsourcing practices. New capacity is also extending beyond traditional hubs into locations that need more local field coverage and spare parts availability. This expansion increases demand for technicians in secondary markets. United States enterprises are also using service models that focus on reliability and repair outcomes, while Canada adds data-residency considerations, and Mexico's nearshore services ecosystem gives buyers another delivery option.
Asia-Pacific is projected to expand at a 9.93% CAGR through 2032. China, India, Japan, and Southeast Asia are modernizing information technology environments while adding data center capacity. In Japan, enterprise environments increasingly combine equipment from multiple suppliers, thereby supporting multi-vendor coverage. In October 2026, Lotte Innovate signed a memorandum of understanding with ITCEN CTS for specialized staffing and infrastructure support at the Ansan Global Cloud Center under a 5-year outsourced operations contract. The managed field support services market in the region, therefore, depends on both modernization demand and providers' ability to manage local operating requirements.
Europe has substantial demand in Germany, the United Kingdom, and France. GDPR and the EU NIS2 Directive make data residency and incident-response documentation important supplier selection factors. Germany is seeing fixed-fee managed services aimed at SMEs that need cloud, endpoint management, and helpdesk support. The Middle East is emerging through Saudi Arabia's Vision 2030 program and UAE investment in AI infrastructure, while South America has demand in Brazil and Argentina, especially in BFSI and government settings, and Africa has developing opportunities in South Africa, Egypt, and Nigeria as technology estates expand.
Competitive Landscape
Market Concentration
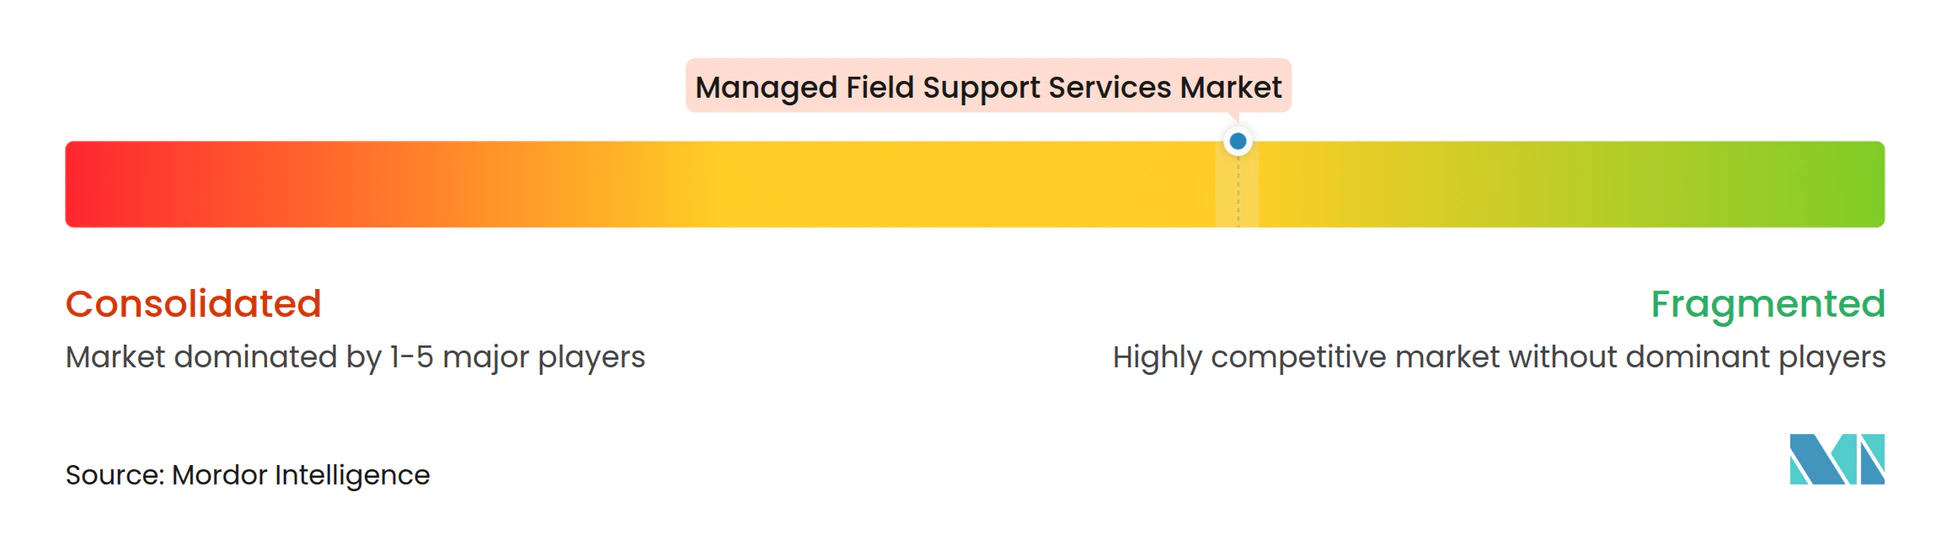
The managed field support services market is moderately fragmented. Global information technology service groups, OEM service arms, third-party maintenance specialists, field service management platform vendors, and regional managed service providers serve different customer needs. Larger providers benefit from broad technician networks, geographic coverage, and spare-parts inventories. Third-party maintenance specialists compete through vendor-agnostic coverage, flexible service levels, and price options. Park Place Technologies completed its merger with Service Express in January 2026, creating a combined business with more than 3,000 employees, more than 20,000 customers across 4 continents, and stated annual revenue of USD 1.2 billion, showing how coverage scale can influence contract competitiveness.
Technology is becoming a more important source of differentiation in the managed field support services market. Providers are using automation to improve dispatch decisions, remote diagnostics, parts handling, and service reporting. ServiceNow introduced a Parts Management AI Agent in April 2026 to reconcile parts usage with work orders at job closure, helping reduce billing errors and revenue leakage. PTC's September 2025 ServiceMax AI release added multi-agent work order execution and tools for service parts planning. Suppliers that connect these tools to field operations can improve responsiveness and support outcome-oriented contracts.
Partnerships are also helping providers build capabilities faster than internal development alone would allow. ServiceNow and Accenture launched joint AI-powered managed security services in June 2026 that combine IT and OT risk management.[3] HPE refocused Complete Care Service in March 2026 around unified support for AI-powered hybrid environments. Opportunities remain in OT-aware support for manufacturers, data center lifecycle services in newer locations, and cloud-delivered packages for SMEs, although the available information does not provide combined share data for the leading companies.
Managed Field Support Services Industry Leaders
-
IBM Corporation
-
Microsoft Corporation
-
Hewlett Packard Enterprise Co
-
Dell Technologies Inc
-
Oracle Corporation
- *Disclaimer: Major Players sorted in no particular order
Managed Field Support Services Market Companies Covered in this Report
- IBM Corporation
- Microsoft Corporation
- Hewlett Packard Enterprise Co
- Dell Technologies Inc
- Oracle Corporation
- Salesforce, Inc.
- IFS AB
- ServiceNow, Inc.
- SAP SE
- PTC Inc.
- Fujitsu Limited
- Atos SE
- Accenture plc
- Cisco Systems, Inc.
- NetApp, Inc.
- Park Place Technologies, LLC
- Service Express, LLC
- Rimini Street, Inc.
- ServicePower, Inc.
- Zinier, Inc.
- Evernex Group SAS
Recent Industry Developments in Managed Field Support Services Market
- October 2026: Lotte Innovate signed a memorandum of understanding with ITCEN CTS for specialized staffing and infrastructure support at South Korea's Ansan Global Cloud Center, 40 MW, completion 2027, under a 5-year outsourced operations contract.
- June 2026: ServiceNow and Accenture launched joint AI-powered managed security services combining IT-OT risk management on the ServiceNow AI Platform, paired with an AI-powered migration solution to automate transitions from legacy cybersecurity systems.
- June 2026: ePlus expanded its managed services portfolio with Enhanced Maintenance Support for HPE ProLiant servers, combining 24x7 HPE-certified engineer coverage and single-call multi-vendor support through a secure multi-tenant monitoring platform.
- March 2026: HPE refocused Complete Care Service as a unified AI-powered support experience, assigning each client a dedicated Service Experience Manager and Technical Advisor backed by HPE OpsRamp for hybrid multi-vendor observability and Compute Ops Management for automated server lifecycle management.
Global Managed Field Support Services Market Report Scope
The managed field support services market covers outsourced on-site technical support, installation, maintenance, repair, and troubleshooting services for hardware, software, and network infrastructure. These services enable organizations to deploy, manage, and maintain IT assets across geographically distributed locations through third-party service providers.
The Managed Field Support Services Market Report is Segmented by Service Type (Managed Services and Professional and Project Services), Deployment Model (On-Premises, Cloud-Based, and Hybrid), Technology Model (Vendor-Agnostic Multi-Vendor Support, OEM-Authorized Support, AI-Enabled and Predictive Support, ITSM- and CMDB-Integrated Support, and Outcome-Based and SLA-Linked Support), Enterprise Size (Large Enterprises and Small and Medium Enterprises), Industry Vertical (Information Technology and Telecommunications, BFSI, Healthcare, Retail and E-Commerce, Data Centers and Cloud Infrastructure, Government and Defense, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed Services |
| Professional and Project Services |
| On-Premises |
| Cloud-Based |
| Hybrid |
| Vendor-Agnostic Multi-Vendor Support |
| OEM-Authorized Support |
| AI-Enabled and Predictive Support |
| ITSM- and CMDB-Integrated Support |
| Outcome-Based and SLA-Linked Support |
| Large Enterprises |
| Small and Medium Enterprises |
| Information Technology and Telecommunications |
| BFSI |
| Healthcare |
| Retail and E-Commerce |
| Data Centers and Cloud Infrastructure |
| Government and Defense |
| Other Industry Verticles |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Rest of Africa |
| By Service Type | Managed Services | |
| Professional and Project Services | ||
| By Deployment Model | On-Premises | |
| Cloud-Based | ||
| Hybrid | ||
| By Technology Model | Vendor-Agnostic Multi-Vendor Support | |
| OEM-Authorized Support | ||
| AI-Enabled and Predictive Support | ||
| ITSM- and CMDB-Integrated Support | ||
| Outcome-Based and SLA-Linked Support | ||
| By Enterprise Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By Industry Verticle | Information Technology and Telecommunications | |
| BFSI | ||
| Healthcare | ||
| Retail and E-Commerce | ||
| Data Centers and Cloud Infrastructure | ||
| Government and Defense | ||
| Other Industry Verticles | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed field support services market?
The managed field support services market size is USD 14.63 billion in 2026 and is projected to reach USD 24.37 billion by 2032 at an 8.96% CAGR.
What is driving demand for managed field support services?
AI infrastructure, larger multi-vendor technology estates, data center expansion, and the need for specialized technical coverage are supporting demand.
Which service type leads managed field support services?
Managed services lead with 72.43% share in 2026, supported by recurring agreements for monitoring, repair, and lifecycle management.
Which deployment model is expanding fastest?
Cloud-based delivery is projected to expand at a 9.63% CAGR through 2032 because it supports remote diagnostics and subscription-based support.
Which end-use vertical is growing fastest?
Data centers and cloud infrastructure is projected to expand at a 9.87% CAGR through 2032 as hyperscale and cloud capacity grows.
Which region is growing fastest for managed field support services?
Asia-Pacific is projected to expand at a 9.93% CAGR through 2032, supported by technology modernization and data center development.