
Managed Digital Risk and Brand Protection Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
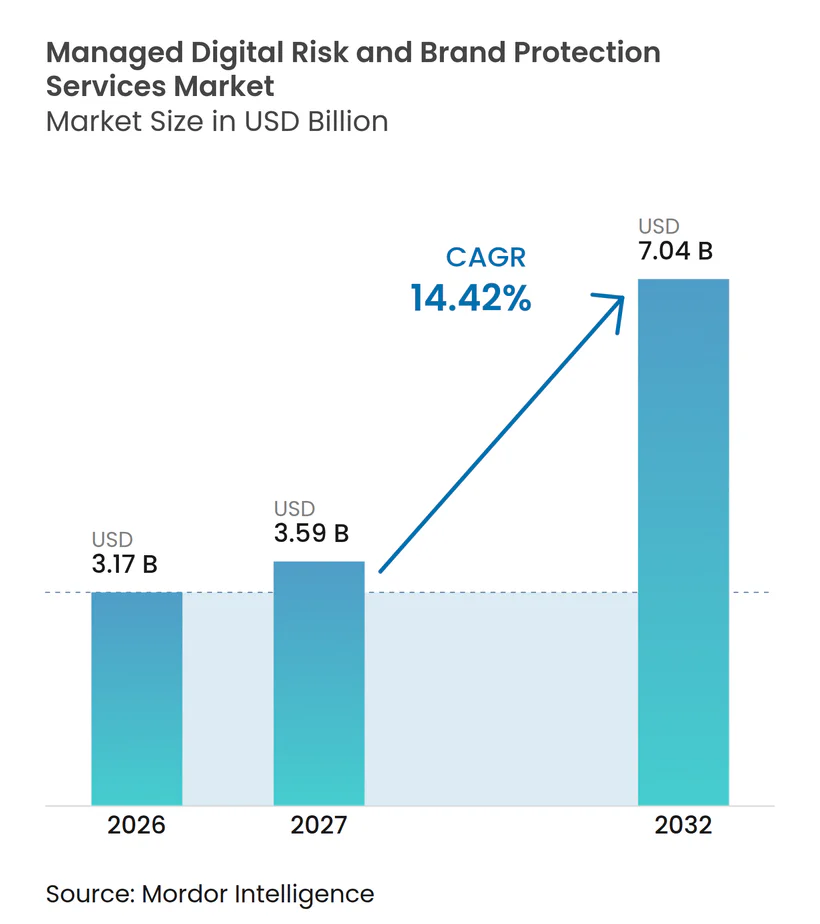
| Market Size (2027) | USD 3.59 Billion |
| Market Size (2032) | USD 7.04 Billion |
| Growth Rate (2027 - 2032) | 14.42 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Digital Risk and Brand Protection Services Market Analysis by Mordor Intelligence
The managed digital risk and brand protection services market size is valued at USD 3.17 billion in 2026 and is forecast to reach USD 7.04 billion by 2032, growing at a CAGR of 14.42% from 2027 to 2032. Escalating impersonation, phishing, counterfeit listings, and fraudulent storefronts are moving brand protection closer to core revenue and fraud-prevention priorities. The managed digital risk and brand protection services market is also expanding because cross-border e-commerce and social commerce create more places where misuse can spread across platforms and jurisdictions. AI-enabled detection and automated takedowns are changing how providers compete, with speed, coverage, and the ability to connect related sellers becoming more important. Regulatory accountability for platforms strengthens the need for documented monitoring and enforcement processes in Europe and increasingly across Asia-Pacific.
Key Report Takeaways
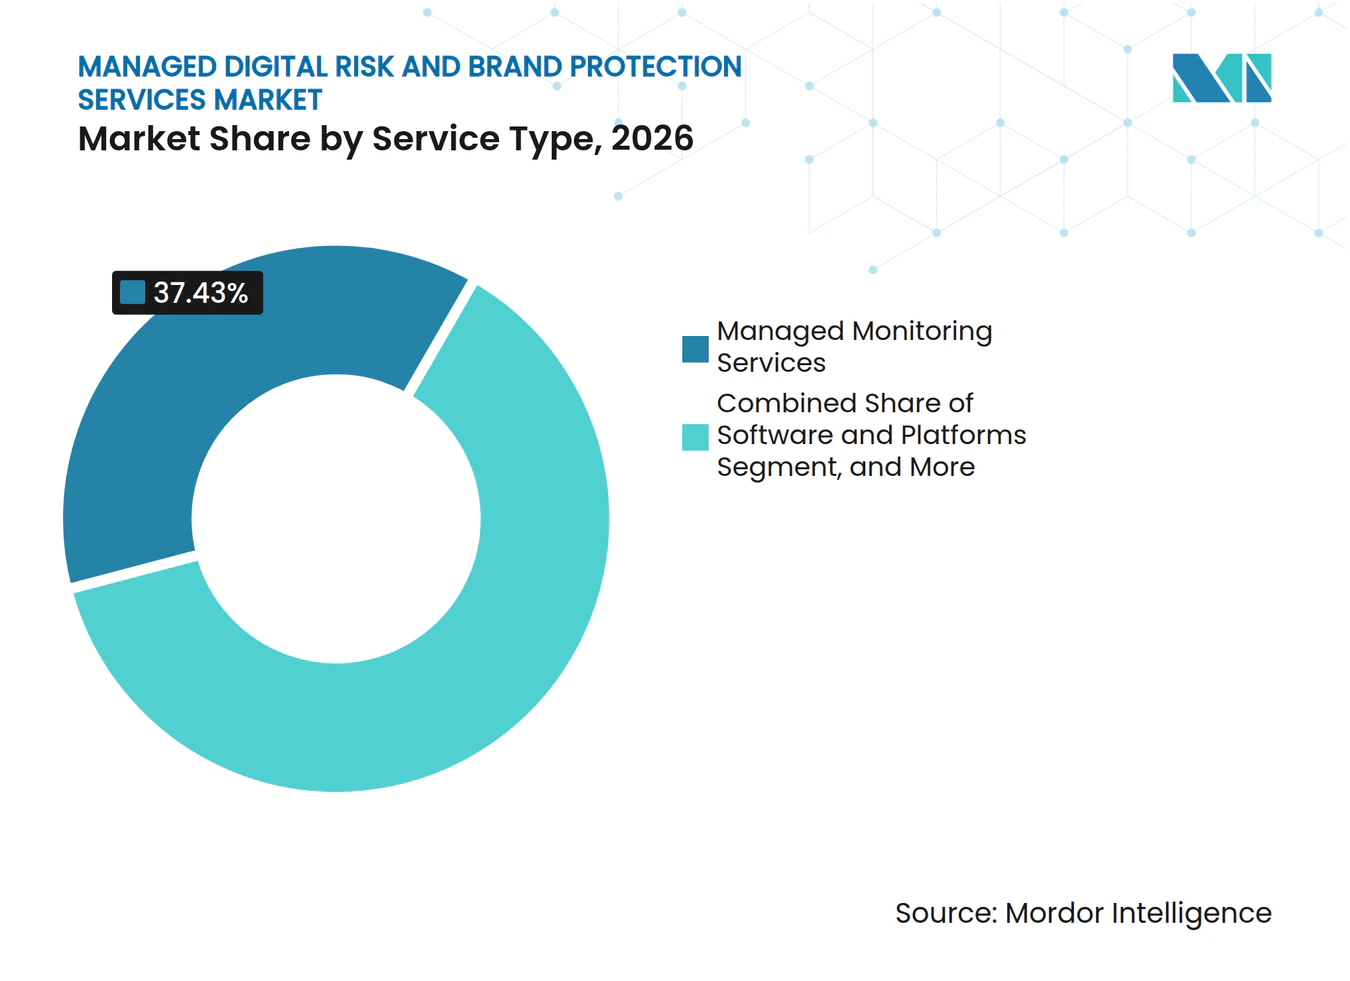
- By service type, managed monitoring services held 37.43% of the managed digital risk and brand protection services market share in 2026, while managed enforcement and takedown services are projected to grow at a CAGR of 15.67% through 2032.
- By delivery model, fully managed services held 34.87% of the market in 2026, while co-managed services are expected to expand at a CAGR of 15.11% through 2032.
- By organization size, large enterprises held 63.27% of the market in 2026, while small and medium enterprises are projected to grow at a CAGR of 15.34% through 2032.
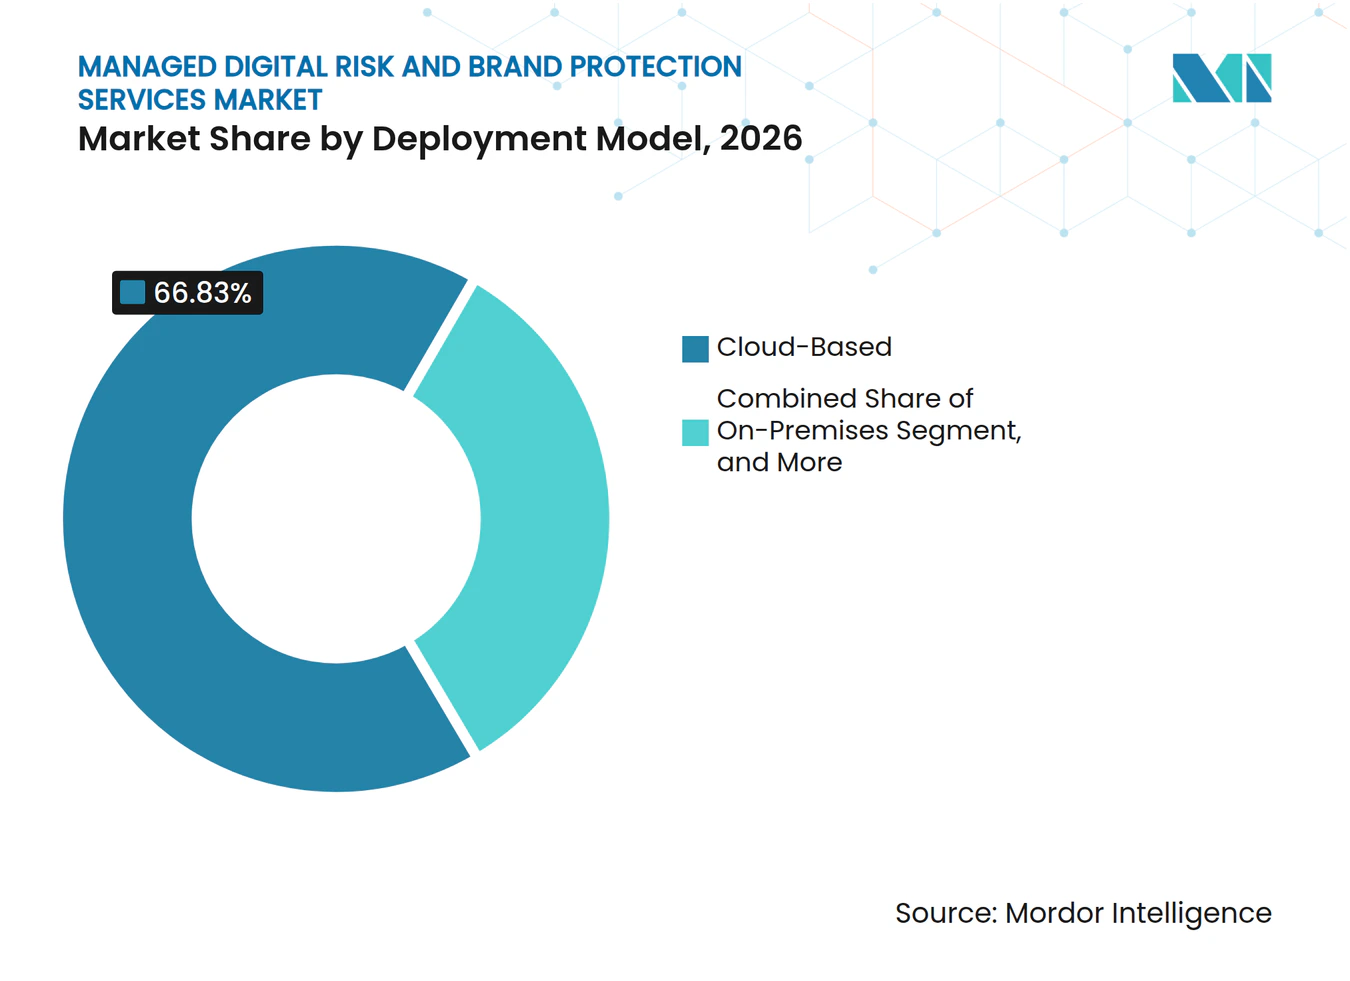
- By deployment model, cloud-based deployment accounted for 66.83% of the market in 2026, while hybrid deployment is projected to expand at a CAGR of 15.23% through 2032.
- By end-user industry, retail and e-commerce held 26.47% of the managed digital risk and brand protection services market in 2026, while BFSI is expected to grow at a CAGR of 15.93% through 2032.
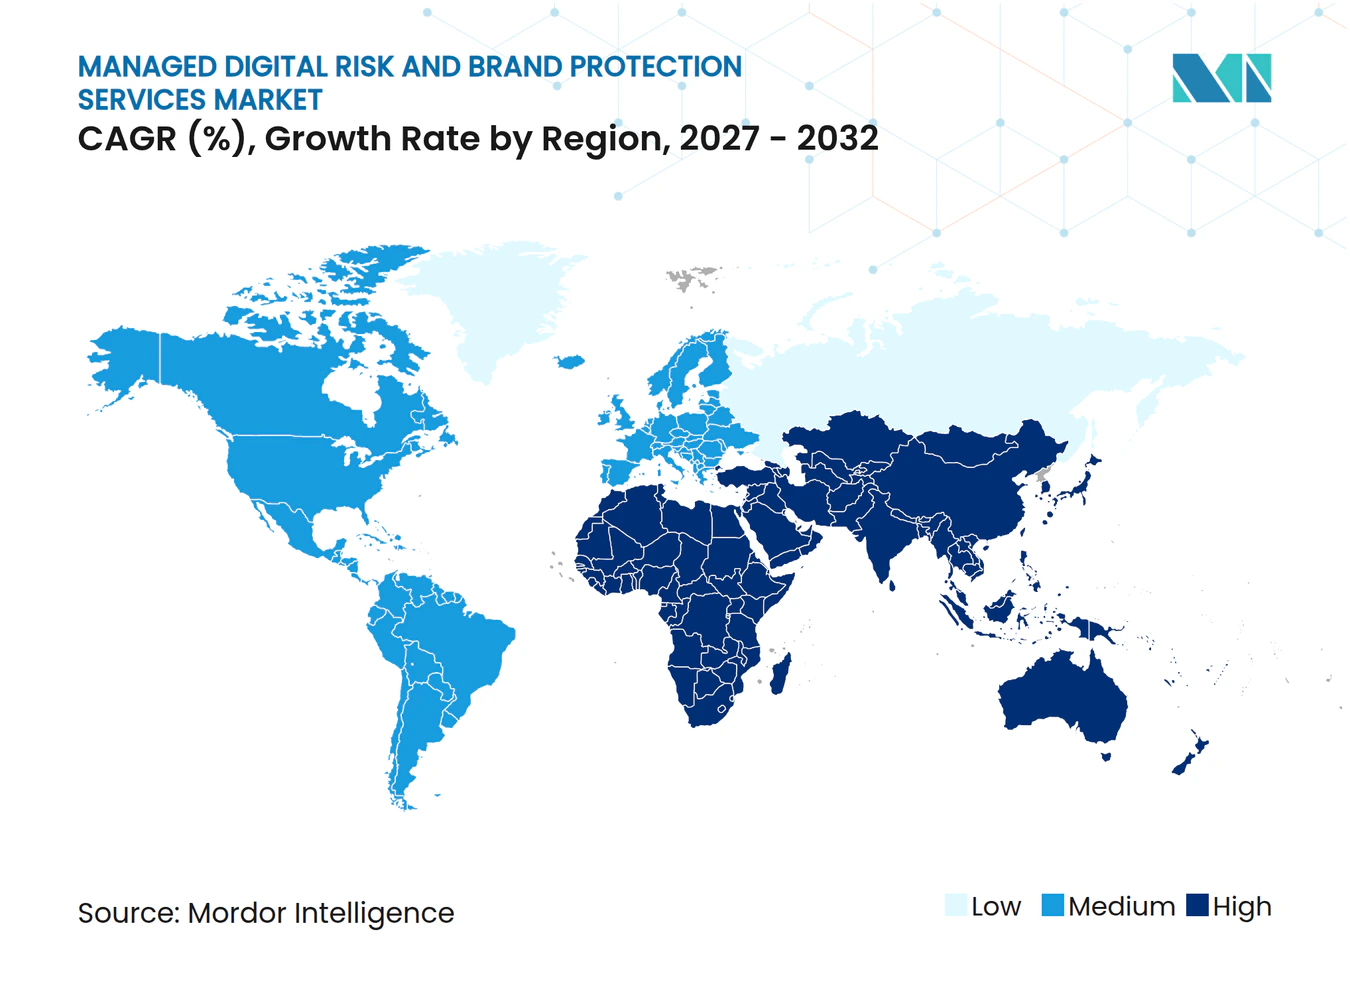
- By geography, North America held 42.37% of the market in 2026, while Asia-Pacific is projected to grow at a CAGR of 15.29% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Digital Risk and Brand Protection Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Brand Impersonation and Phishing Losses | +3.2% | Global, peak concentration in North America and Western Europe | Short term (≤ 2 years) |
| Expansion of Cross-Border E-Commerce and Social Commerce | +2.8% | Asia-Pacific core, spillover to Europe and North America | Short term (≤ 2 years) |
| AI-Enabled Detection and Automated Takedowns | +2.3% | Global | Medium term (2-4 years) |
| Regulatory and Platform Accountability Requirements | +1.9% | Europe, North America, growing reach in Asia-Pacific | Medium term (2-4 years) |
| Generative AI Search and Shopping Abuse | +1.7% | Global, concentrated in North America and Western Europe | Short term (≤ 2 years) |
| Identity Graphs for Seller Network Disruption | +1.2% | Global, early adoption in North America and Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Brand Impersonation and Phishing Losses Drive Enterprise Procurement
Brand impersonation has become a material revenue and consumer-harm issue that enterprises cannot treat as a routine operating cost because it can redirect customers before they reach an authentic site, weaken brand confidence, and create recurring work for security, fraud, legal, and customer service teams. The Federal Trade Commission recorded USD 3.5 billion in reported imposter-scam losses in 2025, with business impersonation accounting for nearly USD 1 billion. The FBI recorded USD 20.9 billion in cybercrime losses in its 2025 Internet Crime Report, while phishing and spoofing generated 191,561 complaints.[1] Community banks and smaller credit unions faced a sharper increase in targeting during 2025, widening demand beyond the traditional enterprise customer base. This pressure supports the managed digital risk and brand protection services market because buyers need faster monitoring, clear escalation paths, and enforcement across websites, domains, social channels, advertisements, and marketplaces, with a managed partner able to keep the work organized when a case affects several customer-facing channels at once.
Expansion of Cross-Border E-Commerce and Social Commerce Widens Enforcement Surface
Social commerce has shifted counterfeit distribution from isolated marketplace listings to coordinated operations that use several platforms and jurisdictions, with the same campaign using a social post to attract attention, a marketplace listing to process a sale, and an overseas fulfillment route to distance the seller from the customer. MarqVision described routes where an illicit operator promotes products on TikTok, transacts through a Southeast Asian marketplace, and fulfills orders from a Chinese warehouse. In October 2025, OLAF and the EUIPO brought together more than 100 participants from over 50 customs authorities and major online platforms to address e-commerce counterfeiting. Markenverband estimated that 6% of branded products imported into Europe are counterfeit, with cosmetics, toys, electronics, and apparel among the affected categories. Tighter enforcement in China is shifting some activity to Indonesia, Thailand, and the Philippines, increasing the need for regional monitoring. The managed digital risk and brand protection services market benefits when brand owners need one provider to coordinate evidence, detection, and action across channels rather than manage separate marketplace responses, particularly where the same seller or campaign moves quickly between social, retail, payment, and fulfillment environments.
AI-Enabled Detection and Automated Takedowns Redefine Operational Economics
AI-based monitoring is reducing the time needed to identify and act on brand threats, which strengthens the case for managed enforcement spending and can surface disguised listings and recurring patterns that keyword searches or manual image reviews may not consistently identify. Corsearch stated that its Zeal 2.0 platform processes an average of 150,000 listings per client each day and uses semantic detection to identify disguised infringements. Netcraft reported a 99.8% takedown success rate across more than 50,000 phone-scam takedowns and a 21-hour median resolution time for its Phone Scam Disruption service. Microsoft documented that AI tools can create fraudulent e-commerce storefronts in minutes rather than days. MarqVision reported continuing high-volume action against counterfeits and illegal content in February 2025. The managed digital risk and brand protection services market, therefore, favors providers that close the gap between detection, evidence collection, case prioritization, and takedown action, because a rapid response is more useful to a client when the supporting evidence and reporting record are available in the same workflow.
Regulatory and Platform Accountability Requirements Create Durable Compliance Demand
The Digital Services Act requires EU intermediaries to operate notice-and-action processes and verify relevant trader information, making disciplined recordkeeping and responsive workflows more important for platforms and brand owners reporting harmful activity. The European Commission can impose fines of up to 6% of worldwide annual turnover for breaches of the Digital Services Act. Germany’s Digital Services Act established the Bundesnetzagentur as the national Digital Services Coordinator and assigned it enforcement responsibilities. These requirements encourage brand owners to maintain evidence, escalation records, and coordinated reporting procedures. Compliance measures in Vietnam, India, and Singapore extend similar demand into the Asia-Pacific. The managed digital risk and brand protection services market gains traction where organizations must demonstrate reliable monitoring and manage enforcement across multiple legal systems, since a service provider can help align evidence, reporting, case ownership, and platform follow-up with the client’s internal compliance process.
Restraints Impact Analysis of Managed Digital Risk and Brand Protection Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented Enforcement and Jurisdictional Friction | -2.1% | Global, most acute in Southeast Asia, Middle East, and Africa | Medium term (2-4 years) |
| Integration and Skilled Analyst Constraints | -1.6% | Global | Medium term (2-4 years) |
| Free Platform-Native Enforcement Reducing Third-Party Spend | -1.3% | Global, concentrated in North America and Western Europe | Short term (≤ 2 years) |
| Adversarial Evasion and Reappearance Costs | -0.9% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Fragmented Enforcement and Jurisdictional Friction Elevate Per-Takedown Costs
Counterfeit operators exploit differences in trademark rights, platform standards, and enforcement agreements to sustain cross-border activity. A seller can promote through a United States social platform, transact on a Southeast Asian marketplace, and fulfill from a Chinese warehouse, creating different response times, local filing requirements, and evidence standards for what is effectively one case. The 2025 APEC Digital Enforcement Guidebook identified jurisdictional fragmentation as a central challenge for cross-border trademark enforcement. The problem is more severe in parts of Africa and the Middle East, where coordination of customs and local expertise in domain disputes can be limited. It can also make results less predictable for clients who need timely removal across several channels. Providers with multilingual networks and trusted-flagger status are better placed to absorb this complexity, while smaller specialists may face higher operating costs and may need to rely on more limited platform relationships or local support arrangements for individual countries.
Integration and Skilled Analyst Constraints Limit Deployment Velocity
Integrating brand protection data with security, fraud, and legal systems can delay deployment, especially for mid-market organizations. Platforms often need to exchange data with security information and event management systems, fraud engines, and legal case-management tools, while clients also need clear ownership of review and escalation decisions. ISC2 estimated a global cybersecurity workforce gap of more than 4 million professionals in 2025. The co-managed model gives clients strategic control while providers handle high-volume monitoring and enforcement work. This arrangement supports the projected 15.11% CAGR for co-managed services, but it does not remove the work needed to integrate systems and define responsibilities. First-time buyers in Asia-Pacific and South America may experience slower adoption due to limited specialist skills and integration resources.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Digital Risk and Brand Protection Services Market Segment Analysis
By Service Type:
Monitoring Anchors Revenue While Enforcement Scales FastestManaged monitoring services held 37.43% of the managed digital risk and brand protection services market share in 2026 because monitoring is the starting point for enforcement across domains, social platforms, marketplaces, and app stores. It gives clients the visibility needed to identify misuse before it can be escalated or removed. Investigation and intelligence services are gaining relevance in BFSI and government accounts that need attribution and evidence for legal action. Consulting and support services also provide revenue through onboarding and program design. These services remain important when a client is building internal processes or entering a new online channel, and they give the managed digital risk and brand protection services market a recurring base of work that can support longer-term enforcement programs.
Managed enforcement and takedown services are projected to grow at a 15.67% CAGR through 2032, as buyers seek clear, measurable action rather than threat alerts alone. Akamai launched Brand Guardian in March 2026 to combine impersonation detection, internet visibility, and automated takedowns.[2] Red Points launched AI Commerce Protection in October 2025 to detect and remove counterfeit listings in AI-powered shopping experiences. The managed digital risk and brand protection services market is moving toward integrated workflows that connect monitoring directly to action.



By Delivery Model:
Fully Managed Leads While Co-Managed Services AccelerateFully managed services held 34.87% of the market in 2026 because many enterprises want continuity in a field where enforcement speed can reduce financial loss and consumer harm. The model is useful for clients that do not have specialist teams for marketplace monitoring, domain abuse, or cross-border escalation. Self-managed software remains relevant for organizations with mature security operations centers and internal investigators. Project-based services remain suited to product launches, market-entry scans, and rapid-response work. The managed digital risk and brand protection services industry continues to support several delivery approaches because client resources vary widely, and the market must serve organizations with very different internal skills, budgets, and escalation processes.
Co-managed services are projected to grow at a CAGR of 15.11% through 2032 as organizations retain strategic oversight and use provider analysts and automation for high-volume enforcement. Bolster AI launched its Signals platform in October 2025 to bring external fraud telemetry and cyber-risk data together for senior security teams. This approach supports teams that need brand intelligence as part of broader fraud and threat-management programs. It also lets clients define priorities while the provider handles repeatable activity. Providers will need orchestration tools that connect their enforcement engines with existing client security systems, since integration requirements remain a barrier to adoption and clients need a practical way to review cases without creating duplicate work across teams.
By Organization Size:
Large Enterprises Lead While Small and Medium Enterprises ExpandLarge enterprises held 63.27% of the market in 2026 because they manage multi-brand intellectual property portfolios across many platforms and jurisdictions. Their procurement processes and security resources also support comprehensive monitoring programs. Large global brands may face misuse across retail channels, social networks, domains, and mobile applications simultaneously. This breadth makes managed services valuable even when internal legal or security teams are well developed. The managed digital risk and brand protection services market share of large enterprises reflects the scale and continuity of their enforcement needs, including the need to set global policy while managing local reporting, review, and legal requirements.
Small and medium enterprises are projected to grow at a CAGR of 15.34% through 2032 as automation reduces the cost of individual enforcement actions. MarqVision stated that brands typically see 5% to 10% top-line gains from addressing counterfeit and unauthorized seller interference. Fashion, consumer goods, and specialty brands increasingly face impersonation on TikTok Shop and Shopee, even when they lack the scale of globally recognized brands. This shift expands demand for analyst support without requiring a fully outsourced program.
By Deployment Model:
Cloud Leads While Hybrid Addresses Data ResidencyCloud-based deployment accounted for 66.83% of the market in 2026 because continuous, multi-platform scanning requires flexible computing capacity. It supports real-time monitoring across a broad set of online channels. MarqVision stated that its platform spans more than 1,500 platforms in more than 118 countries via shared infrastructure. Aggregated signals can help improve AI detection performance by enabling providers to identify repeated abuse patterns. On-premises deployment remains relevant for organizations in government, defense, and financial services that have strict requirements for sensitive data, particularly where internal controls limit the movement of telemetry or evidence outside the organization.
Hybrid deployment is projected to grow at a 15.23% CAGR through 2032 as enterprises combine cloud-based detection with local data processing. This model addresses data-residency requirements in Germany, India, China, and Saudi Arabia. It lets an organization use scalable detection while retaining selected information inside its own environment. The managed digital risk and brand protection services market size for hybrid deployment is supported by buyers who need both broad visibility and stronger controls over data handling. Providers need flexible application programming interfaces and deployment options that link cloud enforcement orchestration with locally hosted data stores, so client teams can use shared detection capabilities without giving up control over selected information.

By End-User Industry:
Retail Leads While BFSI Gains From Fraud ConvergenceRetail and e-commerce held 26.47% of the market in 2026 because branded consumer goods create a strong incentive for counterfeiters and unauthorized sellers. Social commerce adds new locations for product misuse and customer deception. Retailers also need to protect product listings, domains, advertisements, social accounts, and customer communications. These needs make continuous monitoring more important than occasional investigations. The managed digital risk and brand protection services market serves this sector by enabling providers to combine product, brand, and fraud-related evidence into a single program, allowing clients to see related activity and act before a misleading listing or message reaches more consumers.
BFSI is projected to grow at a CAGR of 15.93% through 2032 as brand impersonation increasingly overlaps with account takeover and financial fraud. Allure Security reported that account takeover linked to impersonation can affect a credit union's annual revenue by 2.7% to 11%. Healthcare, manufacturing, government, and defense are also expanding steadily as AI-generated impersonation of providers, certifications, and services becomes more consequential. Information technology and telecommunications firms face exposure both as targets and as infrastructure providers used by attackers. Vendors that support security, fraud, marketing, and legal teams can make a stronger case for shared budgets within these organizations, which gives the managed digital risk and brand protection services market a role in both loss prevention and brand-integrity work.
Geography Analysis
North America held 42.37% of the managed digital risk and brand protection services market share in 2026 because it has many globally recognized brands, mature security procurement, and established enforcement tools. The Federal Trade Commission reported more than USD 70 million in consumer redress and more than a dozen actions under its Impersonation Rule by April 2026. The United States accounts for most regional revenue, while Canada and Mexico are expanding as brands face cross-border exposure from infringement networks in South America and Asia-Pacific. Co-managed services are becoming increasingly relevant as security operations centers incorporate external brand information into broader threat management.
Europe is the second-largest region, with Germany, the United Kingdom, and France providing the main revenue base, while Germany’s Bundesnetzagentur is responsible for national coordination and enforcement under the German Digital Services Act framework. Markenverband reported that 6% of branded products imported into Europe are counterfeit, providing a clear reason for investment in enforcement.[3] South America is a developing opportunity, with phishing campaigns targeting retail brands across Mexico, Chile, and Brazil. Kaspersky identified more than 1,000 malicious phishing domains targeting online retail brands in these countries during 2025. Axur’s local language capability and platform relationships give it a meaningful regional position, while Mercado Libre’s brand protection programs support use of managed enforcement services.
Asia-Pacific is projected to expand at a CAGR of 15.29% through 2032, the highest regional growth rate in the managed digital risk and brand protection services market. The region combines counterfeit manufacturing networks with fast-growing social commerce, which creates a large and changing enforcement surface. Japan and South Korea are growing enterprise demand centers, and MarqVision’s September 2025 funding included support for Japan expansion and a Tokyo office. Platform liability rules in China, counterfeit reporting in Vietnam, and tighter data protection requirements in India strengthen compliance-related demand. The Middle East and Africa hold a smaller share, with Saudi Arabia, the United Arab Emirates, and South Africa acting as the more advanced submarkets as international brands expand monitoring requirements.
Competitive Landscape
Market Concentration
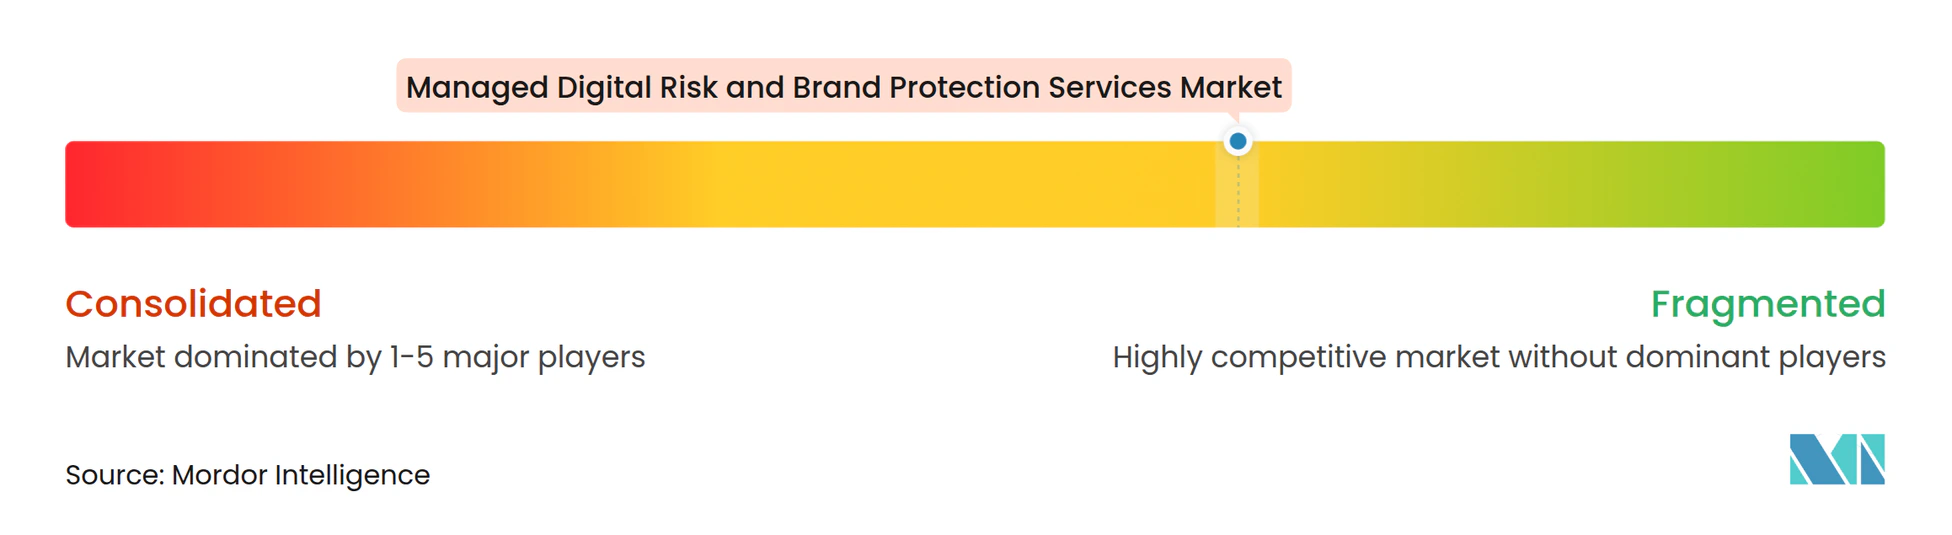
The managed digital risk and brand protection services market remains fragmented, with specialist platforms, cybersecurity vendors, and AI-focused companies competing across related service categories. MarkMonitor and Corporation Service Company rely on established domain management and legal enforcement relationships to retain large enterprise clients, while Red Points, Bolster AI, and MarqVision compete by offering automation, broad coverage, and enforcement speed.
Group-IB and CybelAngel combine intelligence and brand protection capabilities, which gives them relevance in BFSI accounts, while Axur has a regional advantage in South America through language capabilities and local platform relationships. This mix of competitors means clients can choose providers based on industry needs, geography, operational model, and integration requirements. Competitive activity focuses on protection for AI chatbots and agentic commerce, stronger identity graphs, seller-network analysis, and closer links between brand telemetry and external attack surface management.
Akamai launched Brand Guardian in March 2026, adding automated fraud detection and takedown capabilities to its broader internet platform. Red Points launched Actor Networks in October 2025 to connect infringing actors using shared identifiers such as email addresses, phone numbers, payment accounts, and warehouse addresses. Tracer AI launched a dedicated ChatGPT protection solution in June 2025, reflecting the move toward monitoring AI-driven shopping and information channels.
Managed Digital Risk and Brand Protection Services Industry Leaders
-
ZeroFox, Inc.
-
BrandShield Ltd.
-
Netcraft Ltd
-
MarkMonitor Inc.
-
Corporation Service Company
- *Disclaimer: Major Players sorted in no particular order
Managed Digital Risk and Brand Protection Services Market Companies Covered in this Report
- ZeroFox, Inc.
- BrandShield Ltd.
- Netcraft Ltd
- MarkMonitor Inc.
- Corporation Service Company
- OpSec Security
- Bolster AI, Inc.
- MarqVision, Inc.
- Fortra, LLC
- Group-IB Global Private Limited
- CybelAngel SAS
- Axur Segurança e Defesa Cibernética S.A.
- BrandVerity, Inc.
- Tracer, Inc.
- Allure Security Technology, Inc.
- Recorded Future, Inc.
Recent Industry Developments in Managed Digital Risk and Brand Protection Services Market
- September 2026: Netcraft added 5 more of the top 12 US financial institutions as customers in 2026 with accelerating takedown volume, demonstrating growing large-bank adoption of AI-powered brand threat disruption as a mainstream managed security capability.
- June 2026: ZeroFox's Signals Research Program uncovered a sustained domain impersonation operation identifying 73 correlated domains registered between July 2025 and June 2026 that impersonated ZeroFox, Red Points, Corsearch, and Group-IB, revealing that threat actors systematically target the trust infrastructure on which managed enforcement networks depend.
- May 2026: Bolster AI launched Fraudulent Ads Monitoring, expanding external threat protection to paid advertising channels where AI-generated brand impersonation campaigns increasingly exploit search and social advertising before authentic brand communications reach consumers.
- March 2026: Akamai launched Brand Guardian on March 25, 2026, an AI-powered evolution of its Brand Protector product integrating impersonation detection, global internet traffic monitoring, and automated takedowns at 99.99% accuracy targeting financial services, retail, and healthcare enterprises.
Global Managed Digital Risk and Brand Protection Services Market Report Scope
The Managed Digital Risk and Brand Protection Services Market encompasses third-party services that help organizations identify, monitor, assess, and mitigate digital threats affecting their brands, assets, customers, and employees. These services include digital risk monitoring, brand impersonation detection, phishing and fraud monitoring, social media monitoring, domain monitoring, dark web surveillance, threat intelligence, and takedown services.
The Managed Digital Risk and Brand Protection Services Market Report is Segmented by Service Type (Managed Monitoring Services, Managed Enforcement and Takedown Services, Investigation and Intelligence Services, and Consulting, Implementation, Training, and Support Services), Delivery Model (Fully Managed Services, Co-Managed Services, Self-Managed Software, and Project-Based Services), Organization Size (Large Enterprises and Small and Medium Enterprises), Deployment Model (On-Premises, Cloud-Based, and Hybrid), End-User Industry (Information Technology and Telecommunications, BFSI, Healthcare, Retail and E-Commerce, Manufacturing, Government and Defense, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed Monitoring Services |
| Managed Enforcement and Takedown Services |
| Investigation and Intelligence Services |
| Consulting, Implementation, Training, and Support Services |
| Fully Managed Services |
| Co-Managed Services |
| Self-Managed Software |
| Project-Based Services |
| Large Enterprises |
| Small and Medium Enterprises |
| On-Premises |
| Cloud-Based |
| Hybrid |
| Information Technology and Telecommunications |
| BFSI |
| Healthcare |
| Retail and E-Commerce |
| Manufacturing |
| Government and Defense |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Rest of Africa |
| By Service Type | Managed Monitoring Services | |
| Managed Enforcement and Takedown Services | ||
| Investigation and Intelligence Services | ||
| Consulting, Implementation, Training, and Support Services | ||
| By Delivery Model | Fully Managed Services | |
| Co-Managed Services | ||
| Self-Managed Software | ||
| Project-Based Services | ||
| By Organization Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By Deployment Model | On-Premises | |
| Cloud-Based | ||
| Hybrid | ||
| By End-User Industry | Information Technology and Telecommunications | |
| BFSI | ||
| Healthcare | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Government and Defense | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed digital risk and brand protection services market?
The market is valued at USD 3.17 billion in 2026 and is forecast to reach USD 7.04 billion by 2032, growing at a CAGR of 14.42% from 2027 to 2032.
What is driving demand for managed digital risk and brand protection services?
Brand impersonation, phishing losses, cross-border social commerce, AI-enabled fraud, and platform accountability requirements are increasing demand.
Which service type is growing fastest in managed digital risk and brand protection?
Managed enforcement and takedown services are projected to grow at a CAGR of 15.67% through 2032.
Which customer group is expected to expand fastest?
Small and medium enterprises are projected to grow at a CAGR of 15.34% through 2032 as automation lowers enforcement costs.
Which region has the fastest projected growth?
Asia-Pacific is projected to grow at a CAGR of 15.29% through 2032, supported by social commerce growth and counterfeit manufacturing networks.