
Managed CNAPP Operations Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 3.69 Billion |
| Market Size (2032) | USD 7.28 Billion |
| Growth Rate (2027 - 2032) | 14.56 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed CNAPP Operations Services Market Analysis by Mordor Intelligence
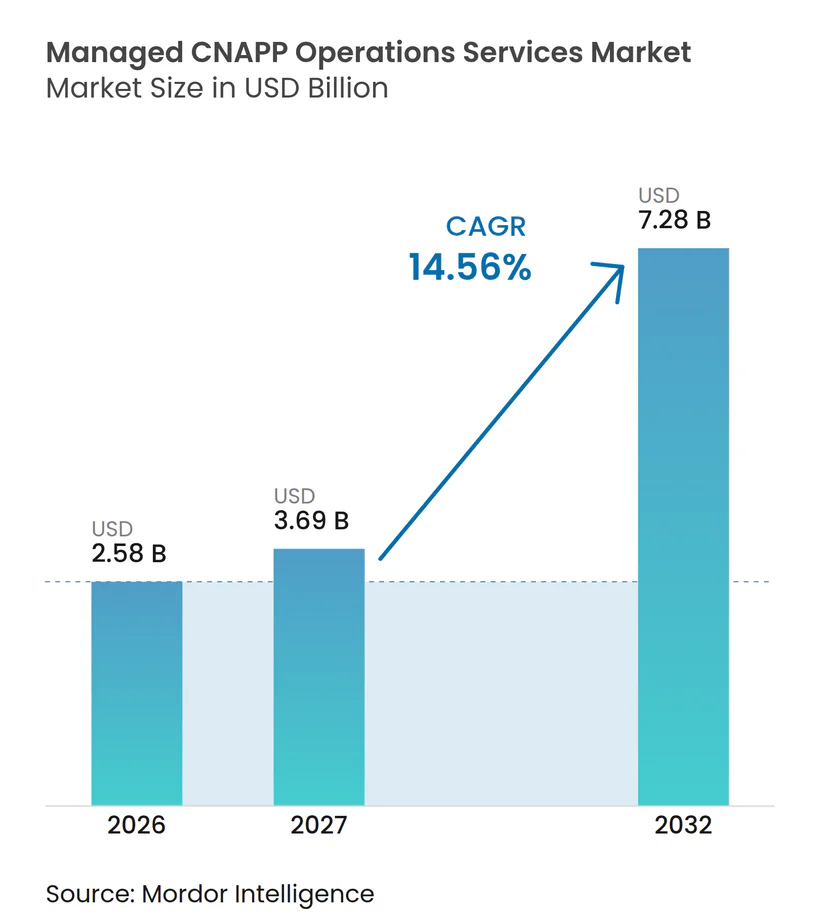
The Managed CNAPP Operations Services Market size is projected to be USD 2.58 billion in 2026, USD 3.69 billion in 2027, and reach USD 7.28 billion by 2032, growing at a CAGR of 14.56% from 2027 to 2032.
The managed CNAPP operations services market is supported by a gap between the rapid deployment of cloud security platforms and the staff required to operate them consistently. Enterprises can install platforms quickly, but investigation, connector oversight, and audit reporting require ongoing analyst time. Multi-cloud use and cloud-native application delivery add to the volume of findings that internal teams must assess and resolve. Providers that combine operating services with detection, compliance, and remediation capabilities can expand the scope of client engagements as security requirements become more demanding. Competition is shaped by large technology service firms with broad delivery capacity and specialists with deep knowledge of individual platforms.
Key Report Takeaways
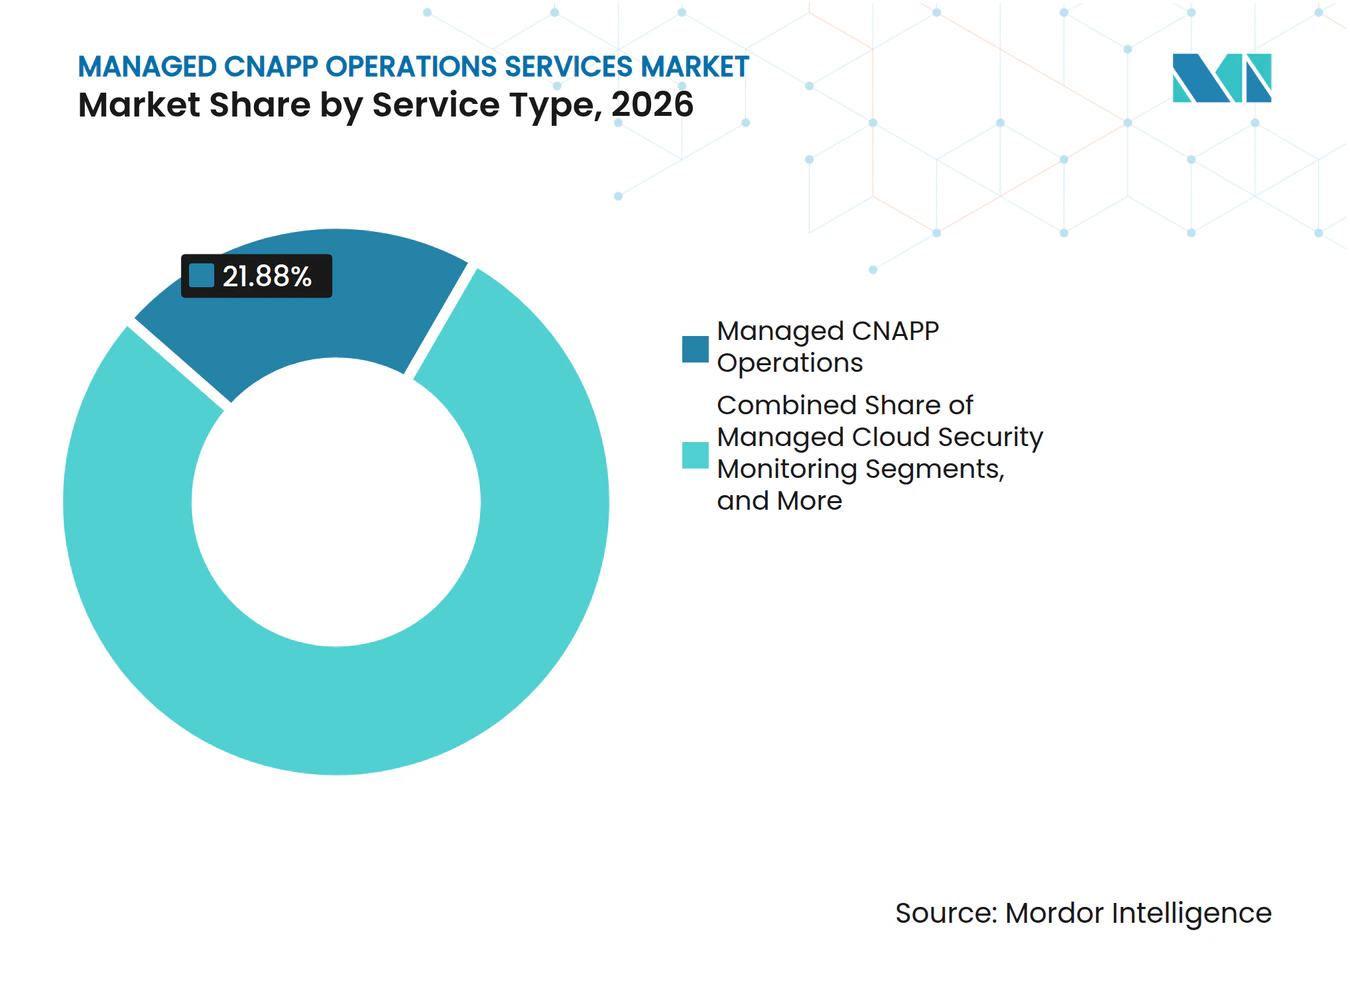
- By service type, Managed CNAPP Operations held 21.88% of the managed CNAPP operations services market share in 2026, while Managed Cloud Detection and Response is projected to expand at a 14.82% CAGR through 2032.
- By CNAPP platform supported, Wiz held 15.24% of the managed CNAPP operations services market share in 2026, while Microsoft Defender for Cloud is projected to expand at a 14.86% CAGR through 2032.
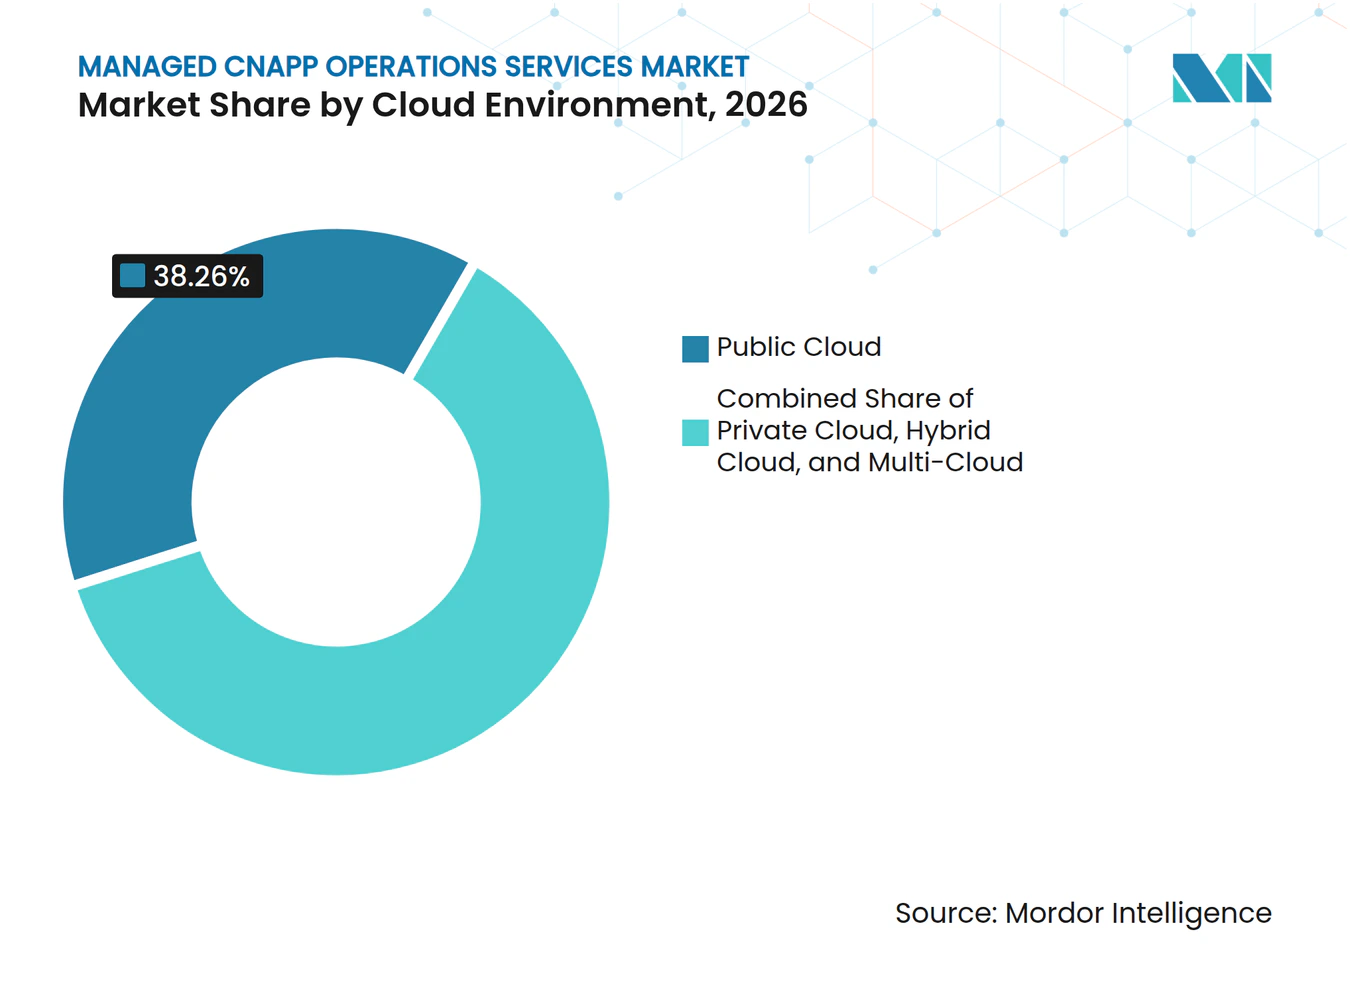
- By cloud environment, public cloud held 38.26% revenue share in 2026, while multi-cloud is projected to expand at a 14.93% CAGR through 2032.
- By organization size, large enterprises held 79.22% revenue share in 2026, while small and medium-sized enterprises are projected to expand at a 15.14% CAGR through 2032.
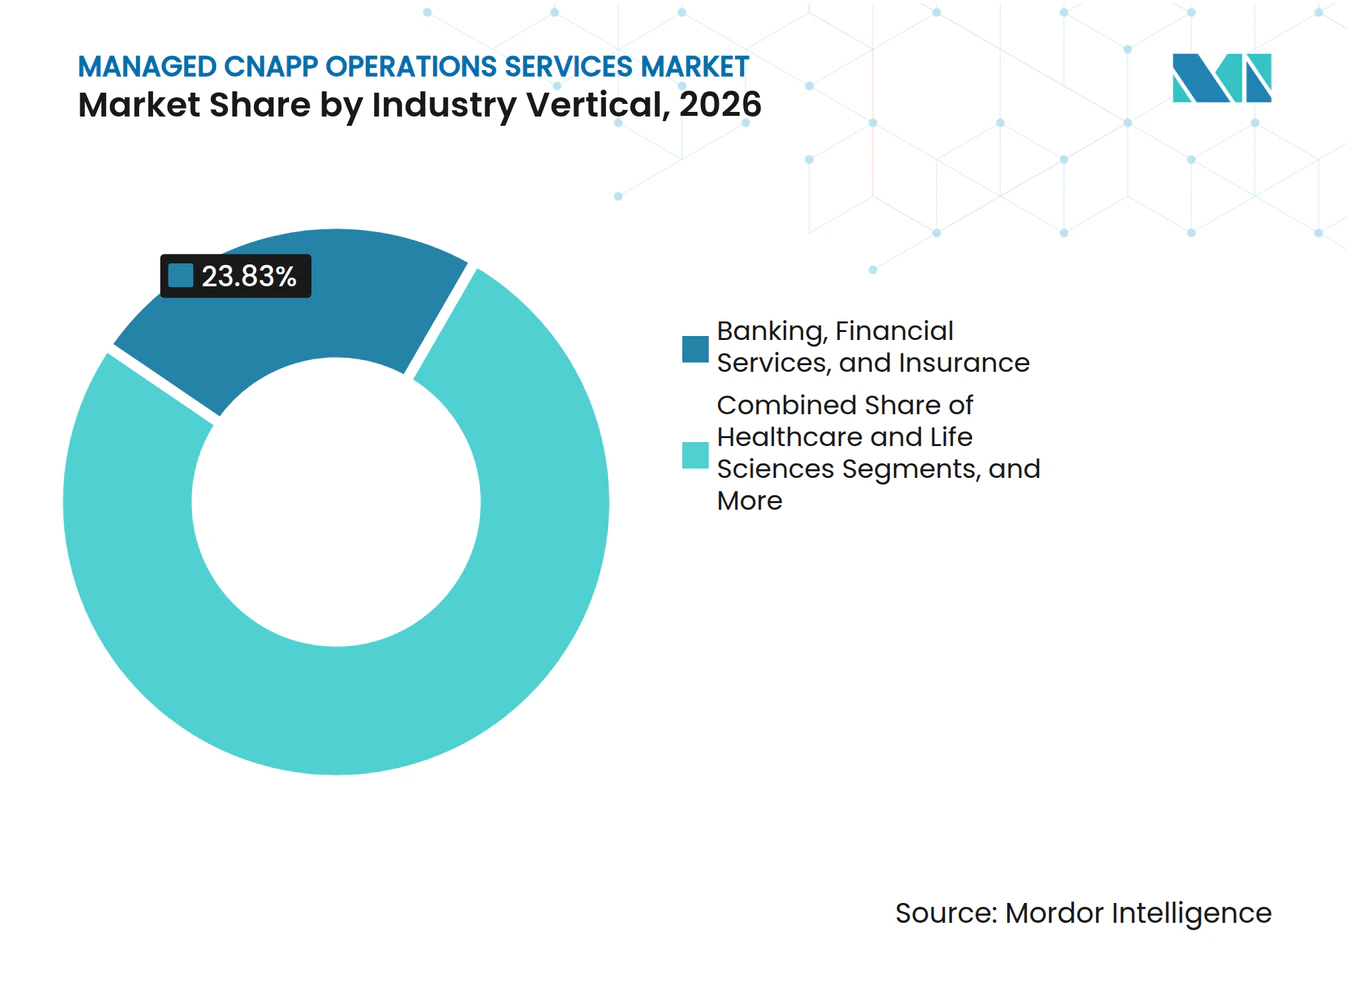
- By industry vertical, Banking, Financial Services, and Insurance held 23.83% revenue share in 2026, while Information Technology and Telecommunications is projected to expand at a 15.16% CAGR through 2032.
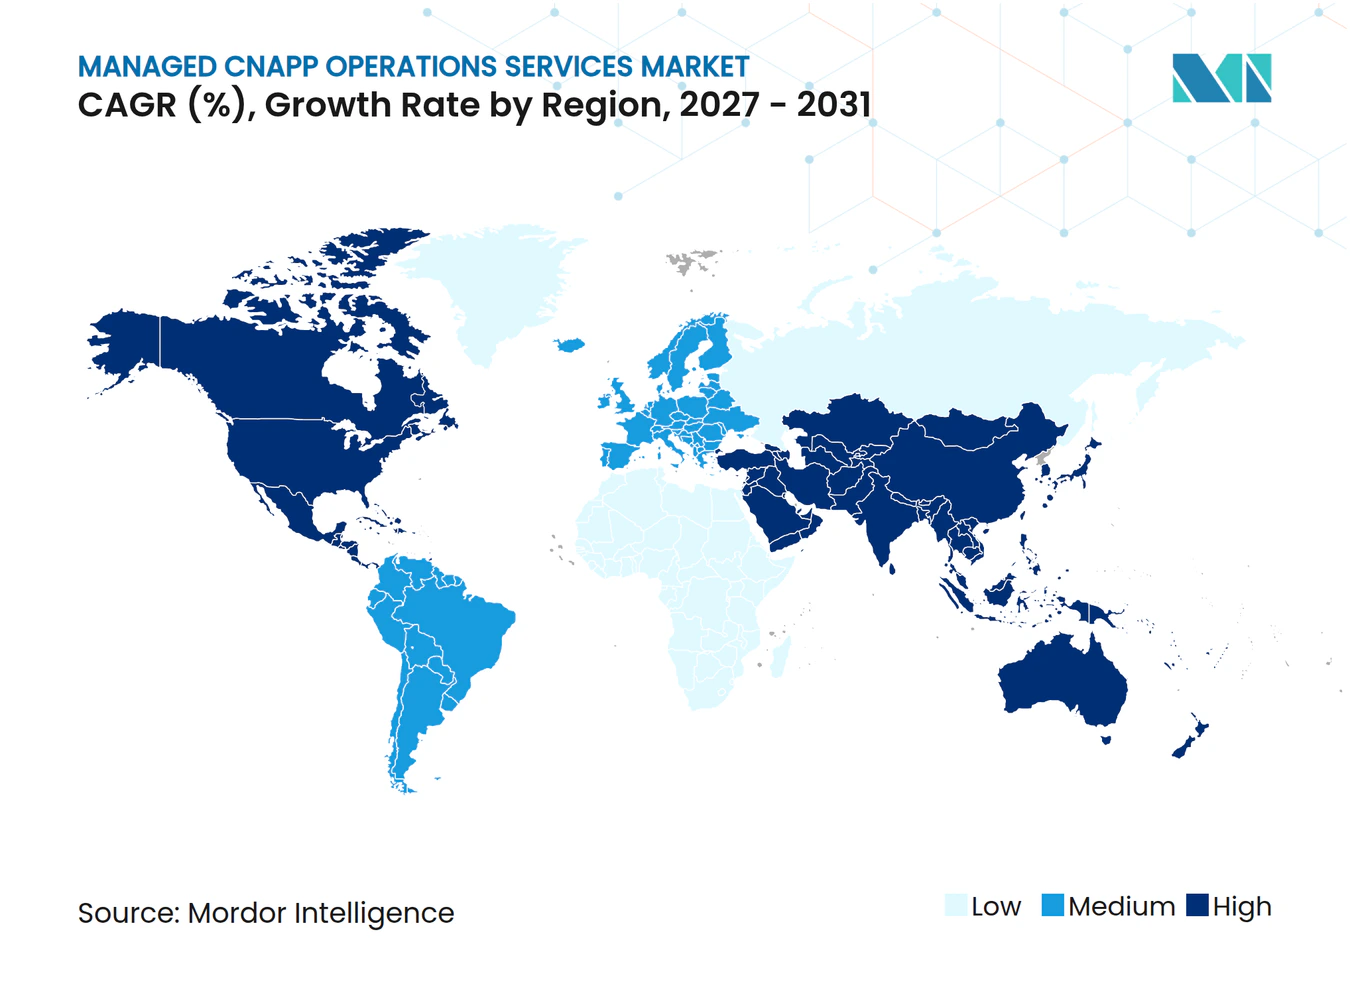
- By geography, North America held 52.38% revenue share in 2026, while Asia-Pacific is projected to expand at a 15.23% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed CNAPP Operations Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Accelerating Multi-Cloud and Hybrid-Cloud Complexity | +3.5% | Global | Medium term (2-4 years) |
| Shortage of Skilled Cloud-Security Professionals | +2.8% | Global | Short term (≤ 2 years) |
| Stricter Cloud Compliance and Continuous-Evidence Requirements | +2.4% | North America and EU | Medium term (2-4 years) |
| Expansion of Cloud-Native Workloads, Containers, and Serverless Applications | +1.9% | Asia-Pacific core, spillover to North America and EU | Long term (≥ 4 years) |
| Persistent Alerts From Deprovisioned Resources | +1.2% | Global | Short term (≤ 2 years) |
| Demand for Human-Validated AI Remediation | +0.8% | North America and EU | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Accelerating Multi-Cloud and Hybrid-Cloud Complexity
The managed CNAPP operations services market benefits as multi-cloud use becomes an operating reality rather than a design objective. A SANS survey found that 63% of respondents identified complexity as the main challenge when securing multiple clouds.[1] Thales reported that enterprises use an average of 2.1 public cloud providers, while 54% also use hybrid cloud models.[2] Each account, Kubernetes cluster, and serverless environment needs authorized connections, mapped policies, and recurring reauthorization. This creates a maintenance burden that rises with the cloud estate. Providers that take responsibility for connector governance can differentiate their managed CNAPP operations services through fuller operational coverage.
Shortage of Skilled Cloud-Security Professionals
The shortage of skilled cloud-security professionals makes external delivery more important for the managed CNAPP operations services market. ISC2 reported that 59% of security teams faced critical or significant skills shortages in 2025, compared with 44% in 2024. Cloud security was the second most pressing skills need and was cited by 36% of respondents. Organizations may have approved roles but still struggle to recruit practitioners with the required platform and cloud knowledge. Once a provider understands a client’s tuning rules, suppression logic, and remediation workflows, replacing that operating knowledge internally becomes difficult. This supports strong retention where managed teams become embedded in daily cloud security processes.
Stricter Cloud Compliance and Continuous-Evidence Requirements
Stricter cloud compliance requirements are changing the work required from security teams. The European Commission states that NIS2 strengthens cybersecurity obligations for essential and important entities across the European Union. These obligations increase the value of continuous control evidence, incident reporting, and third-party risk records. The managed CNAPP operations services market can support buyers that need policy checks and audit-ready reporting on an ongoing basis. Continuous monitoring is more difficult to manage through occasional manual reviews. In Germany, cloud service procurement also places value on BSI C5:2020 attestation, which affects how providers select supporting platforms for regulated customers.
Expansion of Cloud-Native Workloads, Containers, and Serverless Applications
Cloud-native workloads are expanding the security surface addressed by the managed CNAPP operations services market. Snyk reported that 78% of production workloads were deployed as containers or serverless applications. Datadog found that serverless container adoption reached 46% among organizations running containers, compared with 31% 2 years earlier. Short-lived workloads create vulnerability windows that can close before scheduled scans identify them. This makes continuous runtime monitoring more relevant than periodic posture snapshots. Service providers need to identify findings before workloads are decommissioned and translate those findings into practical action. This requirement extends managed delivery beyond configuration monitoring alone.
Restraints Impact Analysis of Managed CNAPP Operations Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| CNAPP Integration and Connector-Mapping Complexity | -1.4% | Global | Medium term (2-4 years) |
| High Implementation and Ongoing Operating Costs | -1.1% | Asia-Pacific and South America | Short term (≤ 2 years) |
| Vendor Lock-In and Proprietary Agent Concerns | -0.7% | North America and EU | Medium term (2-4 years) |
| Production-Change Risk and Human-in-the-Loop Dependencies | -0.5% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
CNAPP Integration and Connector-Mapping Complexity
CNAPP integration and connector mapping can slow adoption in the managed CNAPP operations services market. Large cloud estates require configuration, API authorization, and policy normalization across AWS, Azure, Google Cloud, and private environments. ARMO found that 97% of organizations use 3 to 8 security tools to detect and respond to cloud attacks.[3] The same study found that 30% missed active attacks because alerts were not correlated across those tools. A unified console does not remove fragmentation immediately because connection migrations and policy consolidation take time. Larger integrators can use automation frameworks and reusable connector libraries, while specialists may need to price for higher client-specific labor.
High Implementation and Ongoing Operating Costs
High implementation and operating costs can delay managed CNAPP operations services decisions. Engagements require platform licensing, connector development, agent or sensor deployment, and experienced analyst capacity. ARMO reported an average of 4,080 security alerts each month in managed CNAPP environments and 6,994 alerts for each verified incident. This alert volume can raise the labor required for each confirmed action if tuning and suppression are not maintained. Budget sensitivity is more pronounced in Asia-Pacific and South America, where the visible monthly cost can be harder to justify. Providers that improve alert scoring before human review can protect service economics without reducing detection coverage.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed CNAPP Operations Services Market Segment Analysis
By Service Type:
Detection and Response Gains Ground on Core OperationsManaged CNAPP Operations held 21.88% of the managed CNAPP operations services market size in 2026. It is the base service structure from which providers introduce additional capabilities as a client’s security program matures. The service includes posture management, misconfiguration triage, connector governance, and recurring reporting. These activities are foundational, but organizations often underestimate the sustained labor they require. The service provides a stable entry point for the managed CNAPP operations services market because it addresses routine operating tasks that cannot be left unattended.
Managed Cloud Detection and Response is projected to expand at a 14.82% CAGR from 2027 to 2032. Demand reflects the need for real-time investigation and containment beyond configuration-focused posture management. Tamnoon launched a dedicated Managed CDR service in June 2025 that combines Wiz Defend, Amazon GuardDuty, and CrowdStrike Falcon in a unified triage workflow. Compliance and evidence generation is also relevant in BFSI and government settings where audit artifacts must be maintained regularly. Monitoring, remediation and optimization, and incident response and threat hunting are modular additions that support outcome-based contracts.



By CNAPP Platform Supported:
Wiz Leads While Microsoft Defender AcceleratesWiz accounted for a 15.24% revenue share in 2026. Its agentless architecture can reduce onboarding work because providers do not need to install an agent on every workload. This helps where clients place a high value on time to value. Platform-aligned providers can use this architecture to bring client cloud environments into managed coverage more quickly. The managed CNAPP operations services market therefore includes a substantial ecosystem built around platforms that simplify initial visibility.
Microsoft Defender for Cloud is projected to expand at a 14.86% CAGR from 2027 to 2032. This pattern reflects additive adoption by organizations that already use Azure and Microsoft 365 infrastructure. Google completed its USD 32 billion acquisition of Wiz in March 2026, which raised neutrality questions for some AWS- and Azure-focused buyers. Palo Alto Networks introduced Cortex Cloud in February 2025 as the next generation of Prisma Cloud, with cloud detection and response capabilities. Check Point also completed a global rollout with Wiz in September 2025 that combined cloud network security with CNAPP visibility.
By Cloud Environment:
Public Cloud Leads as Multi-Cloud Adoption SurgesPublic cloud held 38.26% of the managed CNAPP operations services market size in 2026. The share reflects the concentration of enterprise workloads on AWS, Azure, and Google Cloud. Connector libraries for hyperscaler APIs are also more mature than those for many other environments. This supports broad managed coverage across public cloud accounts. The managed CNAPP operations services market remains tied to the scale and operational complexity of these large cloud estates.
Multi-cloud is projected to expand at a 14.93% CAGR from 2027 to 2032. Organizations use 2 or more hyperscalers to improve resilience, manage cost, and access provider-specific AI and analytics services. Thales identified an average of 2.1 public cloud providers per enterprise, creating a need for consistent policies across different APIs, identity structures, and logging formats. Private and hybrid environments remain important for regulated industries and government entities with data residency requirements. Platform-neutral providers compete with specialists whose deeper expertise can command higher margins on complex Kubernetes and serverless deployments.

By Organization Size:
Large Enterprises Dominate as SMEs Scale UpLarge enterprises held 79.22% of revenue in 2026. Their cloud estates can span hundreds of accounts across several providers and business units. These environments create alert and remediation workloads that can exceed in-house capacity even when budgets are available. Acquired businesses and multi-geography cloud operations add further connector and policy complexity. This makes specialist delivery an efficient operating option for many large buyers in the managed CNAPP operations services market.
Small and medium-sized enterprises are projected to expand at a 15.14% CAGR from 2027 to 2032. Standardized, SaaS-style service models make managed operations more accessible to organizations without dedicated security operations centers. CTC launched a Managed CNAPP service in Japan in 2025 for Wiz implementation, alert detection, and operating reporting across multi-cloud environments. The company set a 3-year combined sales target of JPY 2 billion (USD 13.25 million) for its Wiz-related delivery. Buyers can begin with posture management and add detection, response, or compliance modules as their needs become more developed.
By Industry Vertical:
BFSI Leads While IT and Telecommunications Expands FastestBanking, Financial Services, and Insurance held 23.83% of revenue in 2026. The vertical manages high-value data, faces sophisticated threats, and works under detailed regulatory expectations. These conditions make continuous cloud security operations more important than periodic security reviews. Managed delivery can provide the recurring records and monitoring needed by financial institutions. This supports the role of the managed CNAPP operations services market in regulated cloud environments.
Information Technology and Telecommunications is projected to expand at a 15.16% CAGR from 2027 to 2032. These organizations use containerized applications, multi-cloud tools, and developer-operated infrastructure extensively. Their cloud estate can develop faster than security staffing levels. Healthcare and life sciences also use continuous posture monitoring to protect cloud-hosted patient information. Government and defense demand is shaped by FedRAMP High and CMMC requirements in the United States. Retail, e-commerce, and manufacturing are expanding from compliance-based assessments toward continuous monitoring as containerized development becomes more common.
Geography Analysis
North America Managed CNAPP Operations Services Market
North America held 52.38% revenue share in 2026. The region combines high hyperscaler spending, early CNAPP adoption, and established managed security procurement. United States demand is influenced by cybersecurity disclosure rules, NIST CSF 2.0 use, and FedRAMP High requirements for government-adjacent workloads. Canada is supported by financial services and federal government digitization, while Mexico is supported by manufacturing and retail cloud programs. Many multinational contracts are invoiced from United States headquarters, which can increase North America’s recorded share relative to the location of active delivery.
South America Managed CNAPP Operations Services Market
South America remains at an earlier stage of adoption. Brazil leads regional activity as LGPD-related compliance needs encourage managed security use in financial services and healthcare. Argentina and Chile are developing as cloud migration maturity and awareness of managed CNAPP services progress together. The managed CNAPP operations services market faces a more price-sensitive buying environment in this region. Providers need operating models that show value against the direct monthly cost.
APAC and EMEA Managed CNAPP Operations Services Market
Asia-Pacific is projected to expand at a 15.23% CAGR from 2027 to 2032. Japan is developing as a managed CNAPP services center, and NTT DoCoMo Business launched an AI Security Posture Management solution based on Wiz in November 2025. China is organized around domestic hyperscalers and national cybersecurity requirements, which favor domestic managed delivery. India and South Korea are increasing cloud security demand through financial services and IT services adoption. Europe is supported by DORA, NIS2, GDPR, and German BSI C5:2020 procurement expectations. The Middle East and Africa is led by Saudi Arabia and the United Arab Emirates, while South Africa and Egypt remain important financial services centers.
Competitive Landscape
Market Concentration
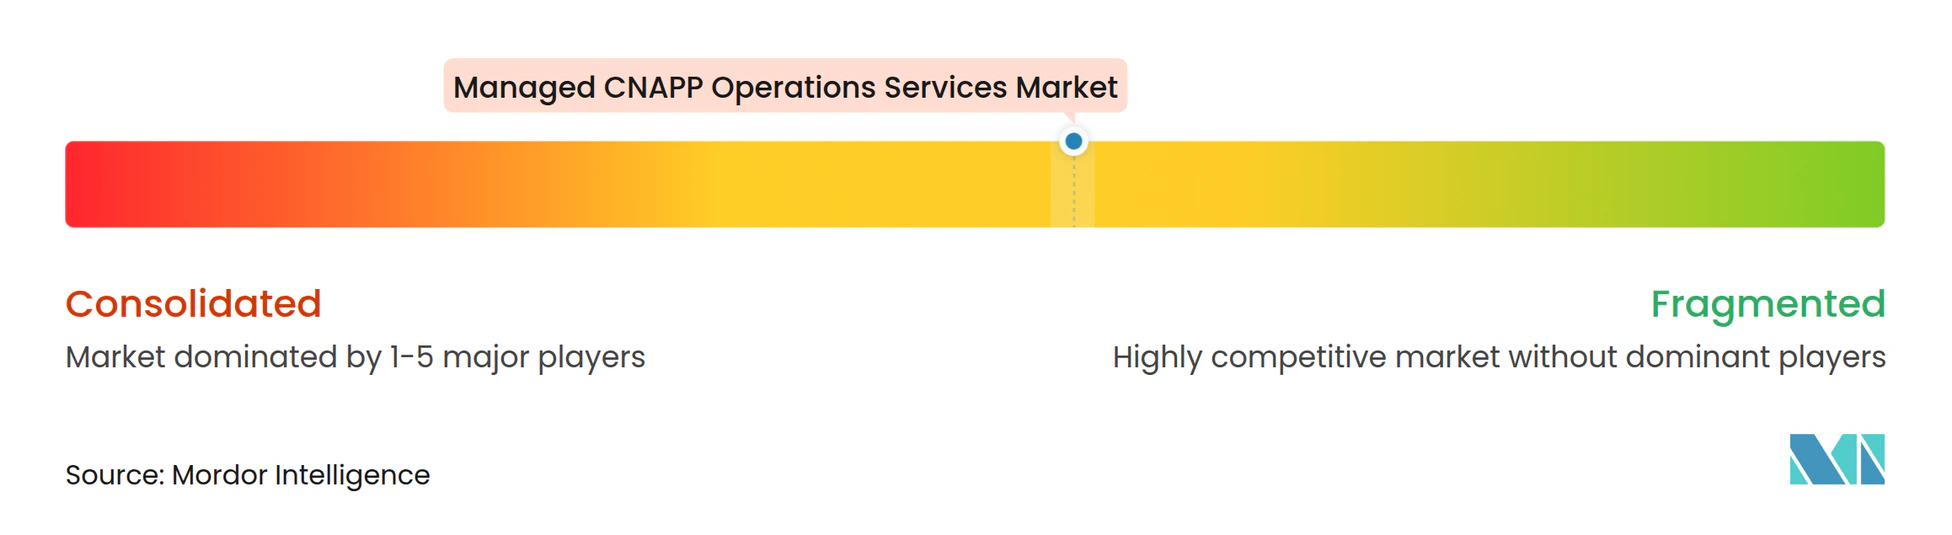
The managed CNAPP operations services market is moderately fragmented. Global IT service providers compete through delivery scale, broad platform coverage, and relationships with hyperscalers. Specialist providers compete through alert tuning, cloud-specific remediation guidance, and faster onboarding on selected platforms. This structure gives buyers a choice between broad integration capability and focused technical depth. A market concentration score of 6 out of 10 reflects the presence of large global providers alongside a meaningful specialist tier, with no combined top-player share stated in the available evidence.
Providers are increasingly using AI-assisted triage to improve delivery economics. Alert scoring and suppression can reduce the analyst effort required before a human validates a finding. Wipro and CrowdStrike launched the CISO Command Center in September 2026, combining consulting-led risk strategy with AI-native managed detection and response. Tamnoon uses its Tami AI agent to consolidate and prioritize alerts before human CloudPros review recommendations. The managed CNAPP operations services market can benefit when automation improves response consistency without removing human review from production changes.
Trust and compliance credentials also affect provider selection. SOC 2 Type II attestation and ISO 27001 certification are important for providers serving regulated customers. CMMC Level 3 accreditation can differentiate providers serving United States government-adjacent cloud environments. Accenture expanded its Google Cloud partnership in March 2026 and integrated Google Security Operations with its Cybersecurity AI Migration Factory. Google’s Unified Security Recommended program expanded in December 2025 to include Palo Alto Networks alongside CrowdStrike, Fortinet, and Wiz. Providers that can normalize findings across more than 1 CNAPP platform can address buyers that use several platforms at the same time.
Managed CNAPP Operations Services Industry Leaders
-
Accenture plc
-
Deloitte Touche Tohmatsu Limited
-
Tata Consultancy Services Limited
-
International Business Machines Corporation
-
Wipro Limited
- *Disclaimer: Major Players sorted in no particular order
Managed CNAPP Operations Services Market Companies Covered in this Report
- Accenture plc
- Deloitte Touche Tohmatsu Limited
- Tata Consultancy Services Limited
- International Business Machines Corporation
- Wipro Limited
- Capgemini SE
- HCL Technologies Limited
- Kyndryl Holdings, Inc.
- Cognizant Technology Solutions Corporation
- NTT DATA Corporation
- DXC Technology Company
- Persistent Systems Limited
- Mphasis Limited
- LTIMindtree Limited
- GuidePoint Security LLC
- Check Point Software Technologies Ltd.
- Novacoast, Inc.
- Integrity360 Group Limited
- Tamnoon, Inc.
- Lightstream Technical Services, LLC
- Palo Alto Networks, Inc.
- CrowdStrike Holdings, Inc.
- Orca Security Ltd.
- Wiz, Inc.
- Microsoft Corporation
Recent Industry Developments in Managed CNAPP Operations Services Market
- September 2026: Wipro and CrowdStrike launched the CISO Command Center, a consulting-led cybersecurity practice combining Wipro Intelligence solutions, CyberTransform and CyberShield, with the CrowdStrike Falcon platform. The Center delivers integrated protection across endpoint security, cloud security, exposure management, and AI security through a unified security operations center, operationalizing an enterprise risk-led model that extends beyond tool-driven managed detection and response.
- May 2026: eSentire launched MDR for Wiz, extending its managed detection and response portfolio to the Wiz platform. The service covers both Wiz Cloud, agentless CSPM and CIEM monitoring, and Wiz Defend, runtime monitoring, providing 24/7 SOC investigation across AWS, Azure, and Google Cloud through eSentire's Atlas correlation engine, with streamlined onboarding enabling Wiz connection within minutes.
- March 2026: Accenture expanded its strategic partnership with Google Cloud, integrating the Google Security Operations platform with Accenture's Cybersecurity AI Migration Factory for accelerated SIEM transitions and unified cloud security delivery. Accenture simultaneously deployed Wiz across its own global cloud footprint, reinforcing its position as a key managed delivery partner for the combined Google Cloud and Wiz stack following Google's acquisition.
- March 2026: Google completed its USD 32 billion acquisition of Wiz, the largest acquisition in Google's history and among the largest in cybersecurity, placing the leading CNAPP platform under hyperscaler ownership. The transaction cleared the United States Department of Justice and European Commission without formal behavioral conditions, though the Cloud Security Alliance identified it as a material vendor-risk event requiring enterprise CNAPP dependency reviews.
Global Managed CNAPP Operations Services Market Report Scope
The Managed CNAPP Operations Services Market comprises outsourced, 24/7 security services in which a third-party provider operates and manages a Cloud-Native Application Protection Platform (CNAPP) on behalf of an organization, covering continuous cloud security posture management, misconfiguration remediation, vulnerability and entitlement management, runtime threat detection and response, and alert triage across cloud-native environments (containers, Kubernetes, serverless, microservices, and multi-cloud).
The Managed CNAPP Operations Services Market Report is Segmented by Service Type (Managed CNAPP Operations, Managed Cloud Security Monitoring, Managed Cloud Detection and Response, Managed Compliance and Evidence Generation, Managed Remediation and Optimization, Managed Incident Response and Threat Hunting), CNAPP Platform Supported (Wiz, Prisma Cloud, Orca Security, Microsoft Defender for Cloud, CrowdStrike Falcon Cloud Security, Check Point CloudGuard, Other CNAPP Platforms), Cloud Environment (Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), Industry Vertical (Banking, Financial Services, and Insurance, Healthcare and Life Sciences, Government and Defense, Information Technology and Telecommunications, Retail and E-Commerce, Manufacturing, Other Industry Vertical), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed CNAPP Operations |
| Managed Cloud Security Monitoring |
| Managed Cloud Detection and Response |
| Managed Compliance and Evidence Generation |
| Managed Remediation and Optimization |
| Managed Incident Response and Threat Hunting |
| Wiz |
| Prisma Cloud |
| Orca Security |
| Microsoft Defender for Cloud |
| CrowdStrike Falcon Cloud Security |
| Check Point CloudGuard |
| Other CNAPP Platforms |
| Public Cloud |
| Private Cloud |
| Hybrid Cloud |
| Multi-Cloud |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| Banking, Financial Services, and Insurance |
| Healthcare and Life Sciences |
| Government and Defense |
| Information Technology and Telecommunications |
| Retail and E-Commerce |
| Manufacturing |
| Other Industry Vertical |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| South Africa | |
| Egypt | |
| Rest of Middle East and Africa |
| By Service Type | Managed CNAPP Operations | |
| Managed Cloud Security Monitoring | ||
| Managed Cloud Detection and Response | ||
| Managed Compliance and Evidence Generation | ||
| Managed Remediation and Optimization | ||
| Managed Incident Response and Threat Hunting | ||
| By CNAPP Platform Supported | Wiz | |
| Prisma Cloud | ||
| Orca Security | ||
| Microsoft Defender for Cloud | ||
| CrowdStrike Falcon Cloud Security | ||
| Check Point CloudGuard | ||
| Other CNAPP Platforms | ||
| By Cloud Environment | Public Cloud | |
| Private Cloud | ||
| Hybrid Cloud | ||
| Multi-Cloud | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By Industry Vertical | Banking, Financial Services, and Insurance | |
| Healthcare and Life Sciences | ||
| Government and Defense | ||
| Information Technology and Telecommunications | ||
| Retail and E-Commerce | ||
| Manufacturing | ||
| Other Industry Vertical | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| South Africa | ||
| Egypt | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the managed CNAPP operations services market size?
The managed CNAPP operations services market is USD 2.58 billion in 2026 and is projected to reach USD 7.28 billion by 2032 at a 14.56% CAGR.
Which managed CNAPP service is expanding fastest?
Managed Cloud Detection and Response is projected to expand at a 14.82% CAGR from 2027 to 2032.
Which cloud environment has the largest share of managed CNAPP services?
Public cloud held 38.26% revenue share in 2026, supported by enterprise workloads on AWS, Azure, and Google Cloud.
Why are organizations using managed CNAPP operations services?
Multi-cloud complexity, shortages of cloud-security skills, continuous compliance needs, and more cloud-native workloads are increasing the need for external operating support.
Which organizations account for the largest demand for managed CNAPP services?
Large enterprises held 79.22% of revenue in 2026 because their cloud estates create substantial alert, connector, and remediation workloads.
Which region is expected to expand fastest for managed CNAPP services?
Asia-Pacific is projected to expand at a 15.23% CAGR from 2027 to 2032, supported by cloud adoption and demand for cloud-native security capabilities.