
LPG Vaporizer Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 1.52 Billion |
| Market Size (2032) | USD 1.75 Billion |
| Growth Rate (2027 - 2032) | 2.83 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
LPG Vaporizer Market Analysis by Mordor Intelligence
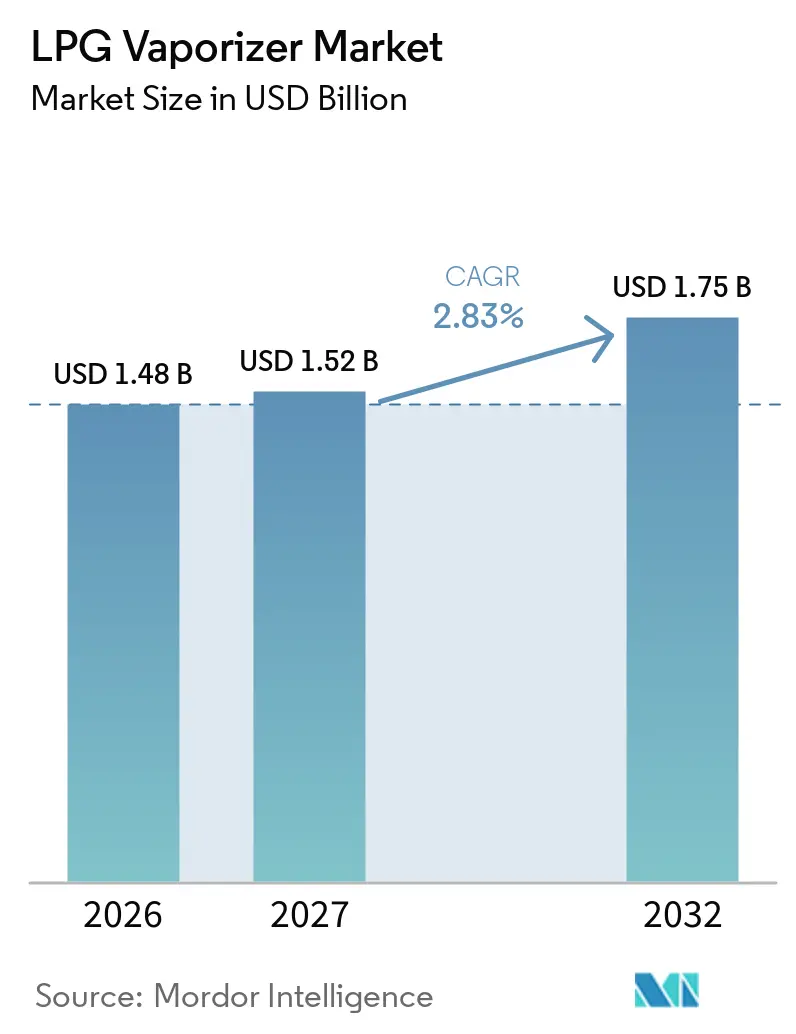
The LPG Vaporizer Market size is expected to increase from USD 1.48 billion in 2026 to USD 1.52 billion in 2027 and reach USD 1.75 billion by 2032, at a CAGR of 2.83% over 2027-2032. Demand is supported by industrial fuel conversion, off-grid energy systems, and projects that need reliable LPG delivery at a defined pressure and flow rate for normal operations. Electric equipment had already become the leading technology, and its faster growth points to replacement demand moving toward a smaller set of digitally capable products that can meet operating, maintenance, and compliance requirements. New terminal and storage projects can create equipment orders when they require pipeline injection, truck loading, or continuous supply to downstream users, rather than simply adding storage capacity without downstream fuel-handling capability. Suppliers are responding through product upgrades, local distribution relationships, and service capabilities that address compliance, commissioning, maintenance, documentation, and uptime requirements over long equipment lives. High installation costs, long replacement cycles, and site-specific heat-source requirements continue to limit wider standardization, keep many purchasing decisions tied to individual project conditions, and preserve the importance of experienced suppliers in the LPG vaporizer market.
Key Report Takeaways
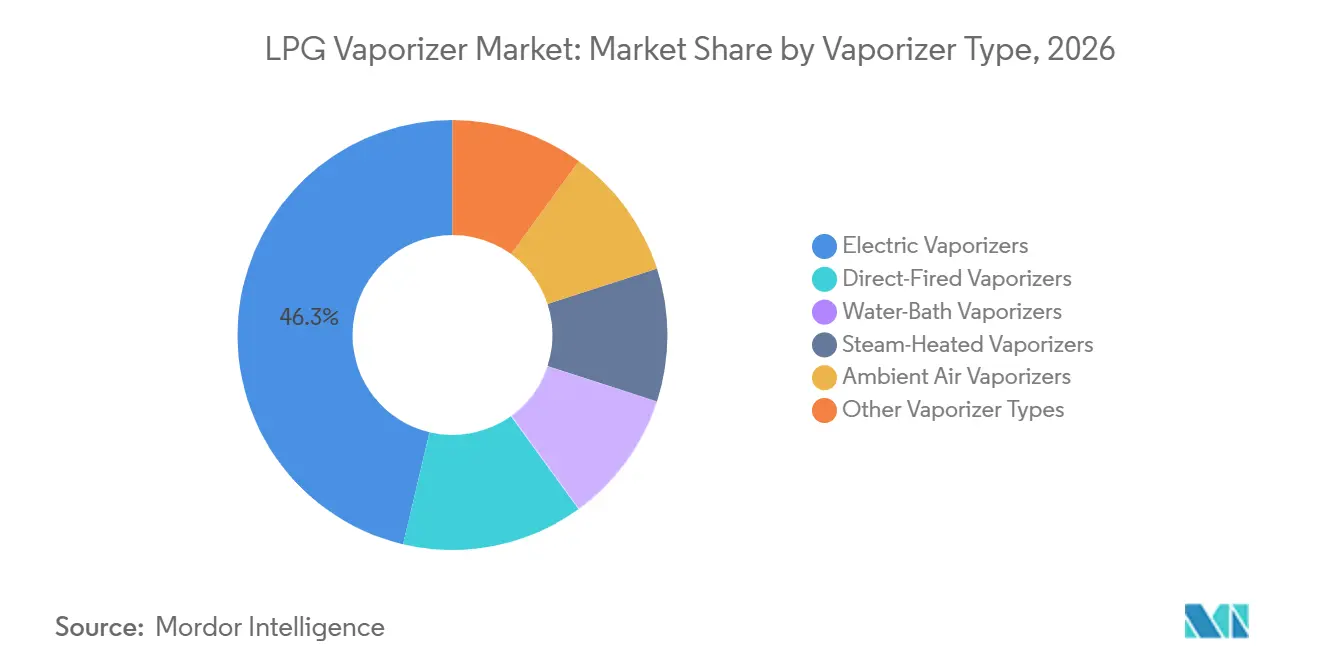
- By vaporizer type, electric vaporizers held 46.3% of the LPG vaporizer market share in 2026 and recorded the highest projected CAGR at 3.8% through 2032.
- By capacity, medium-capacity vaporizers held 35.2% of the LPG vaporizer market share in 2026, while high-capacity systems recorded the highest projected CAGR at 3.4% through 2032.
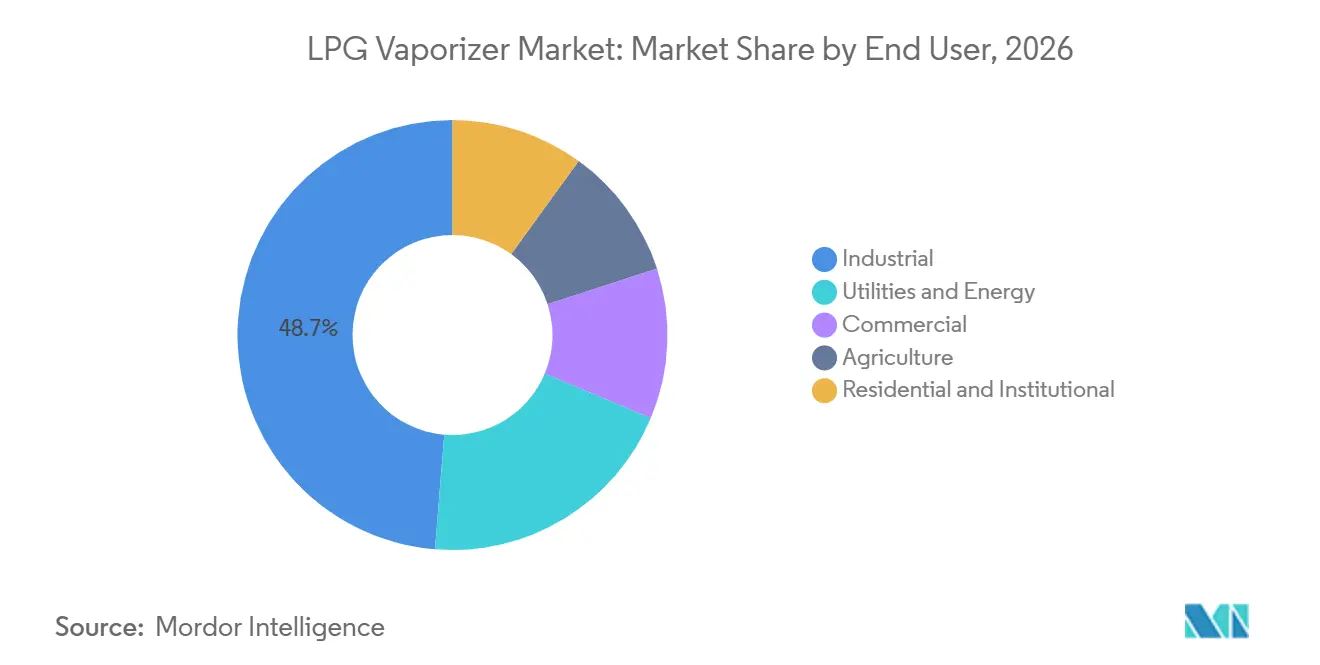
- By end user, industrial users held 48.7% share in 2026, while commercial applications recorded the highest projected CAGR at 3.7% through 2032.
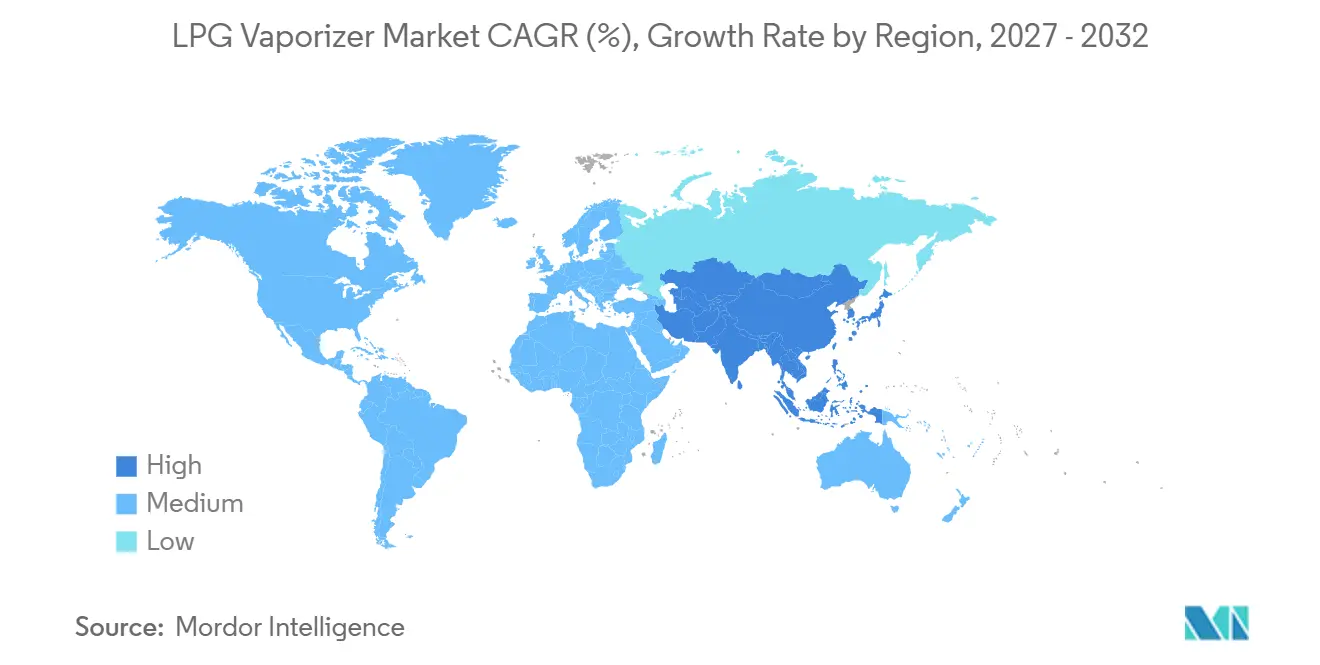
- By geography, North America held 32.1% share in 2026, while Asia-Pacific recorded the highest projected CAGR at 4.2% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of LPG Vaporizer Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Industrial and Commercial LPG Consumption | +0.70% | Global, concentrated in North America, Europe, and East Asia | Medium term (2-4 years) |
| LPG Infrastructure Expansion in Off-Grid and Emerging Markets | +0.50% | Sub-Saharan Africa, South and Southeast Asia, South America | Long term (≥ 4 years) |
| Demand for High-Capacity Vaporization in Petrochemical and Process Industries | +0.40% | Middle East, China, India, Southeast Asia | Medium term (2-4 years) |
| Shift Toward Electric and Digitally Controlled Vaporization | +0.50% | Global, strongest in North America, Japan, and Europe | Short term (≤ 2 years) |
| Vaporizer Demand from Propane-Air Standby and Peak-Shaving Systems | +0.30% | North America and Europe utility markets | Medium term (2-4 years) |
| Growing Adoption of LPG for Distributed and Backup Energy Applications | +0.30% | Global, accelerating in data-center-dense regions in North America and APAC | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Expansion of Industrial and Commercial LPG Consumption
Industrial process heating continues to move away from solid fuels and heavier hydrocarbons toward gaseous alternatives where operating needs and local supply conditions permit. LPG requires vaporization equipment before it can be used in many industrial systems, which keeps equipment demand tied to changes in consumption rather than to fuel storage alone and makes equipment selection part of a site’s wider fuel-delivery planning. EU imports of liquefied gas, including LPG, rose 12.1% year over year in Q1 2025, showing continued demand across European industrial and commercial users.[1] India’s LPG consumption rose 4% to 29.65 million metric tonnes in FY 2023-24, supported by wider access to subsidized supply and a broader distribution network.[2] Residential distribution growth can increase pressure at terminals and encourage industrial buyers to secure dedicated on-site capacity instead of relying only on shared local supply arrangements. These buyers often require redundant configurations because a supply interruption can affect production, creating more specific procurement needs in the LPG vaporizer market.
LPG Infrastructure Expansion in Off-Grid and Emerging Markets
Storage and import facilities in off-grid and emerging markets create demand for downstream vaporization equipment because stored liquid LPG must be converted for loading, distribution, and end use. The IFC Board approved a USD 250 million financing package in June 2026 for Sahara Group’s LPG terminal program in Ghana, Nigeria, Kenya, and Tanzania. The planned site capacities range from 6,000 MT to 30,000 MT, showing that the program addresses supply infrastructure rather than a small local storage need. Petredec and ASAS Group awarded engineering, procurement, and construction contracts in June 2025 for the Tanga LPG Terminal in Tanzania, with 40,000 m³ of Phase 1 storage and a late-2027 completion target. Such facilities need controlled conversion of stored LPG for pipeline injection and truck-loading operations, which ties terminal development to vaporizer specification work, installation design, and later maintenance planning in the LPG vaporizer market. They can also create service and replacement opportunities for suppliers that qualify for long-cycle terminal work in the LPG vaporizer market.
Shift Toward Electric and Digitally Controlled Vaporization
Electric vaporizers are becoming more important in industrial and commercial installations because they remove on-site combustion from the equipment design and give users another way to meet operating constraints. This can reduce the need for ventilation structures, flue-gas compliance, and some separation requirements that apply to direct-fired units, although site conditions still determine the final choice. Algas-SDI positioned its COMPEXX Cryogenics Electric Vaporizer in 2026 for customers operating both LPG and LNG systems. The product example reflects demand for equipment that can serve more than 1 fuel-handling environment where operators want consistent operating practices. KAGLA VAPORTECH describes remote-monitoring panels, self-diagnosis functions, and hazardous-area certifications for its electric water-bath vaporizer range. Digital controls support condition-based maintenance and can reduce unplanned downtime, strengthening the position of capable vendors in the LPG vaporizer market, where service responsiveness and plant availability affect purchasing decisions.
Vaporizer Demand from Propane-Air Standby and Peak-Shaving Systems
Propane-air systems use vaporized propane mixed with air to support gas supply during peak demand or supply disruptions, giving vaporizer equipment a role beyond routine industrial use. This use case is less dependent on ordinary production cycles because utilities and large facilities need standby capacity when demand exceeds available gas supply. The National Propane Gas Association reported in 2025 that data-center construction connected to natural-gas networks had renewed interest in propane-air standby systems. TransTech Energy supplies propane-air peak-shaving systems for this application, while Standby Systems supplies LPG and propane systems that include vaporizers and peak-shaving plants. The vaporizer remains the conversion component that enables these systems to deliver a usable fuel blend when supply conditions tighten, so reliability and compliance requirements remain central to project design and supplier selection. Installation requirements under the 2024 edition of NFPA 58 make established compliance experience important for suppliers serving this part of the LPG vaporizer market.
Restraints Impact Analysis of LPG Vaporizer Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timelin |
|---|---|---|---|
| High Installation, Certification, and Integration Costs | -0.40% | Global, most pronounced in emerging markets | Medium term (2-4 years) |
| Stringent Separation, Ventilation, and Interlock Requirements | -0.20% | North America and Europe code-driven markets | Short term (≤ 2 years) |
| Site-Specific Utility and Heat-Transfer-Medium Constraints | -0.20% | Global, strongest impact in off-grid and emerging markets | Long term (≥ 4 years) |
| Long Replacement Cycles and Limited Standardization of Custom Systems | -0.20% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Installation, Certification, and Integration Costs
The cost of an LPG vaporizer system extends beyond the equipment purchase price and includes the work required to make the installation ready for safe operation. Site preparation, civil works, pressure-rated piping, safety interlocks, engineering documents, and certification can raise the full project cost for the buyer. These requirements can delay purchases by hotels, restaurants, and institutional kitchens in developing markets even when LPG would otherwise meet their operating needs. Kenya’s 2025 guidelines for LPG reticulation require parallel vaporizer installation for maintenance redundancy, P&ID documentation, and professional engineering certification. The compliance steps add time and cost, while they also create a higher threshold for suppliers that lack experience with formal project documentation, engineering review, safety controls, and installation coordination. Modular, pre-engineered products can reduce part of the burden, but they do not address all large customized installations in the LPG vaporizer market.
Long Replacement Cycles and Limited Standardization of Custom Systems
Custom systems for industrial and petrochemical sites can operate for 15-25 years before replacement, which makes each major purchasing decision relatively infrequent. Operating life limits annual equipment demand even when LPG consumption grows, and more users depend on vaporization equipment in their normal operations. Replacement projects also depend on heat-source availability, pressure ratings, utility specifications, local safety requirements, and site geometry, so a product cannot always be substituted directly. These conditions reduce equipment interchangeability across manufacturers and make supplier changes more costly for end users who already understand their existing equipment. Established suppliers can benefit when they hold detailed knowledge of the installation and can support the customer through maintenance, spare parts, and compliance work. Digital upgrades that add monitoring without full replacement may create service activity between major capital purchases in the LPG vaporizer market and give end users a way to improve oversight of aging equipment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
LPG Vaporizer Market Segment Analysis
By Vaporizer Type:
Electric Systems Lead Replacement DemandElectric vaporizers held 46.3% of the LPG vaporizer market in 2026 and are forecast to grow at a 3.8% CAGR through 2032. Their scale and growth rate show that many replacement orders are moving toward electric solutions instead of maintaining older combustion-based configurations. Older direct-fired and water-bath equipment can be replaced with electric units where a suitable power supply, site layout, and operating profile are available. Electric systems remove combustion from the vaporizer and can simplify some installation and compliance requirements for users managing space, ventilation, and emission considerations. They also support operating models that use sensors, control electronics, and remote diagnostics to make maintenance planning more systematic.
Direct-fired vaporizers remain useful at large off-grid industrial facilities where electricity is unreliable or expensive, and a different heat source is more practical. Steam-heated and water-bath systems still serve petrochemical sites that need stable temperatures and high volumes under specific process conditions. Ambient-air products remain suitable for lower-demand uses in temperate climates where minimal infrastructure investment is the priority. KAGLA VAPORTECH’s water-bath electric series includes remote monitoring, self-diagnosis, and hazardous-area certifications. These features favor suppliers with pre-certified lines, maintenance knowledge, and reliable service support in the LPG vaporizer market.

By Capacity:
Medium Systems Form the Core Installed BaseMedium-capacity units accounted for 35.2% of the global LPG vaporizer market in 2026. Their scale reflects use across manufacturing sites, commercial distribution networks, and light industrial heating locations with recurring but not terminal-scale fuel needs. These installations create replacement and aftermarket work for suppliers that maintain commercial and light-industrial channels close to local customers. Medium-capacity systems provide more flow than small equipment without requiring the engineering scope, footprint, and procurement process associated with terminal-scale capacity. Their broad role maintains a stable installed base across many locations, even as capital investment becomes more visible at the high-capacity end of the LPG vaporizer market.
High-capacity vaporizers are forecast to grow at a 3.4% CAGR through 2032. Petrochemical clusters, industrial parks, and bulk import terminals in the Middle East, South Asia, and Southeast Asia support this growth because these sites need continuous high-volume conversion. The IFC approval for Sahara Group’s four-terminal program illustrates the structured financing that can support high-capacity demand. Buyers at this scale commonly need ASME-certified pressure vessels, local engineering-code compliance, and suppliers capable of supporting longer project schedules. Low-capacity units continue to support distributed and standby uses, although gas networks can reduce some small on-site applications in the LPG vaporizer market.
By End User:
Industrial Users Retain the Largest Installed BaseIndustrial users held 48.7% of the LPG vaporizer market in 2026. Manufacturing, chemical processing, food and beverage production, and pharmaceutical heating need reliable process fuel that can be delivered without interruption to normal production routines. Industrial customers often use redundant parallel vaporizer banks to protect operations from downtime, particularly where an interruption could disrupt process heating or material handling. This preference can increase equipment demand relative to LPG volumes alone because reliability requirements can lead to additional installed capacity, parallel equipment, and more detailed service arrangements. The segment also values technical support, compliance knowledge, spare parts access, and long operating life when selecting a supplier.
Commercial users are forecast to expand at a 3.7% CAGR through 2032. Hotels, restaurants, bakeries, health-care facilities, and laundries use LPG where piped natural gas is unavailable or insufficient for their operating needs. Growth is associated with urbanizing areas in Southeast Asia, India, and Latin America, where commercial facilities are expanding along with local distribution access. Utilities and energy users add demand through propane-air plants during peak consumption, while agriculture uses low- and medium-capacity units for heating and drying. India’s Pradhan Mantri Ujjwala Yojana targeted 103.5 million LPG connections by 2025-26, supporting broader distribution networks and community infrastructure needs.
Geography Analysis
North America held 32.1% of the LPG vaporizer market in 2026. Mature propane distribution infrastructure, industrial process-fuel use, and utility peak-shaving systems support demand across both established industrial customers and facilities that need emergency supply capability. The United States and Canada use propane-air equipment at utility facilities and industrial heating sites, while commercial users rely on LPG in areas without natural-gas service. The National Propane Gas Association reported in 2025 that hyperscale data-center construction was renewing interest in propane-air standby plants. Mexico contributes additional demand as commercial and light-industrial distribution networks extend into more urban and industrial locations that need dependable fuel access beyond established natural-gas coverage, adding to the regional role of the LPG vaporizer market.
Europe has a demanding compliance environment and a steady replacement cycle for installed systems. Germany, France, Italy, the United Kingdom, and Poland remain major consumption centers with different local codes and established channels for LPG equipment and related services. The EU Fit for 55 framework targets a 55% net reduction in greenhouse gas emissions by 2030. LPG continues to serve facilities beyond the natural-gas grid, which supports equipment demand where alternative fuel connections are not readily available. EU imports of liquefied gas rose 12.1% year over year in Q1 2025.
Asia-Pacific is forecast to grow at a 4.2% CAGR through 2032, the fastest rate among the regional markets. China’s industrial clusters and petrochemical hubs support large installations, while India’s infrastructure development and subsidized LPG distribution program support community-level vaporization needs. Indian LPG consumption reached 29.65 million metric tonnes in FY 2023-24. Indonesia, Vietnam, and Thailand add demand through off-grid programs and industrial expansion that rely on LPG where networked gas is not available. South America and the Middle East and Africa represent a smaller but growing part of the LPG vaporizer market. Brazil and Argentina support commercial and agricultural use, while the Middle East requires heavy-duty equipment for petrochemicals and export terminals. Petredec’s Tanga project and the IFC-backed Sahara program show the infrastructure activity developing across Africa.
Competitive Landscape
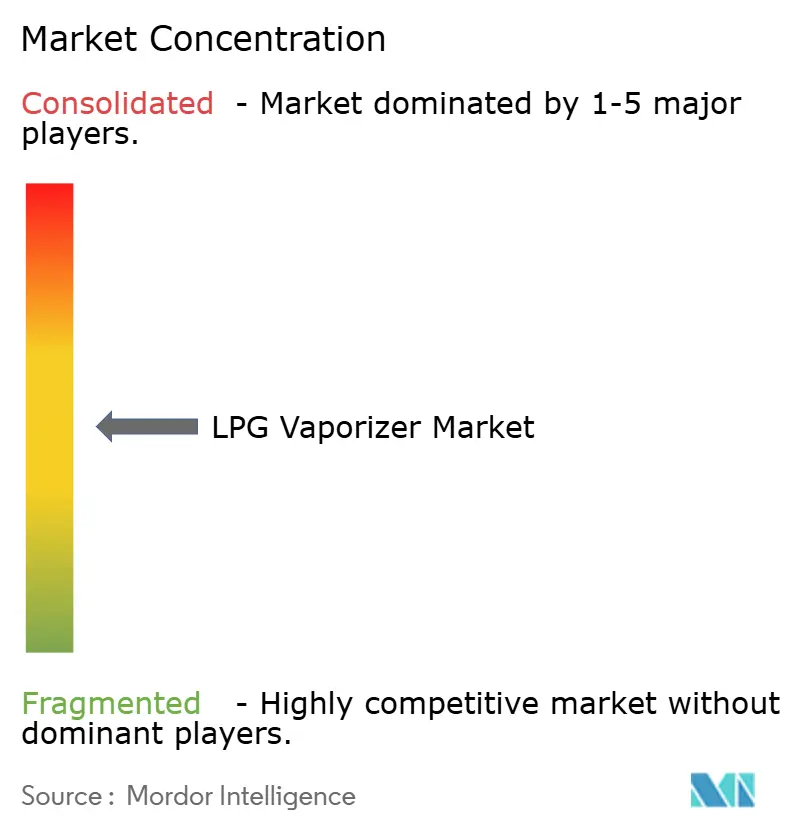
The LPG vaporizer market is moderately fragmented because no supplier holds a dominant position across every region and application. Algas-SDI, KAGLA VAPORTECH, Meeder Equipment, and PEGORARO GAS TECHNOLOGIES have positions in specific vaporizer types and regional markets, rather than a single common product position. SHV Energy, TransTech Energy, and Standby Systems combine equipment with storage, controls, and engineering services when buyers need an integrated project package. This mix gives buyers a choice between specialist products and integrated systems, depending on local installation conditions and procurement practices. Technical performance, local service coverage, and compliance experience shape bidding outcomes as strongly as product availability, especially when buyers are comparing different equipment designs for site-specific operating conditions.
Regional specialization limits direct competition in many local markets. Nihon Genma Mfg. has relationships with Japanese industrial users, while Anil Engineering and SEPL serve South Asia and its growing LPG equipment requirements. ADCENG Gas Equipment operates in Sub-Saharan Africa, and FAS Flüssiggas-Anlagen GmbH serves German-speaking Europe, where local practice and technical support can influence selection. Algas-SDI acquired the Dragon Shield product line in July 2024, expanding its gas-safety portfolio. In 2025, Algas-SDI appointed Gas Chile SpA as its authorized distributor in Chile.
Technology and certification remain central to competitive positioning. Algas-SDI shipped its first SH200-Ultra Low NOx burners in May 2026 and positioned its COMPEXX Electric Vaporizer for LPG and LNG customers in February 2026. In September 2026, it announced an exclusive partnership with Steam Generation Africa that added local equipment stocking and field support for PHOENIX burners. Vendors with ASME or CE Mark credentials can be better positioned for tenders where buyers require documented compliance with recognized standards. Smart monitoring and predictive-maintenance functions can deepen service relationships with industrial and utility customers across the LPG vaporizer market, particularly where equipment availability and planned maintenance are procurement priorities.
LPG Vaporizer Industry Leaders
-
TransTech Energy, LLC
-
SHV Energy
-
Algas-SDI
-
Cavagna Group
-
Standby Systems, Inc.
- *Disclaimer: Major Players sorted in no particular order
LPG Vaporizer Market Companies Covered in this Report
- ADCENG Gas Equipment (Pty) Ltd.
- Aether DBS LLC
- Algas-SDI
- Alternate Energy Systems, Inc.
- Anil Engineering Pvt Ltd
- FAS Flussiggas-Anlagen GmbH
- KAGLA VAPORTECH CORPORATION
- Kosan Crisplant a/s
- Maxquip Inc.
- Meeder Equipment Company
- Nihon Genma Mfg. Co., Ltd.
- PEGORARO GAS TECHNOLOGIES Srl
- PSG, a Dover Company
- Ransome Manufacturing Co.
- RegO Products
- SEPL, Saraswat Engineers Pvt. Ltd.
- SHV Energy
- Standby Systems, Inc.
- Tamura Corporation
- TransTech Energy, LLC
- Vapor Power International, LLC
- Zeeco, Inc.
Recent Industry Developments in LPG Vaporizer Market
- September 2026: Algas-SDI announced an exclusive partnership with Steam Generation Africa (Pty) Ltd as its sole PHOENIX burner partner across the African continent, incorporating locally stocked equipment and field-support expertise to capture the surge in LPG-fired industrial activity linked to Africa's terminal infrastructure build-out.
- June 2026: The IFC Board approved a USD 250 million financing package for Sahara Group's multi-country LPG storage terminal program, covering greenfield sites in Tema, Ghana (6,000 MT), Apapa, Nigeria (15,000 MT), Mombasa, Kenya (30,000 MT), and Dar es Salaam, Tanzania (6,000 MT), creating direct upstream demand for large-capacity vaporizer systems at each new terminal.
- May 2026: Algas-SDI shipped its first SH200-Ultra Low NOx burners to an OEM partner, commercializing a combustion product engineered to meet stringent emissions standards for LPG process-heating applications and expanding the company's clean-combustion product range.
Global LPG Vaporizer Market Report Scope
An LPG vaporizer is an industrial device that converts liquefied petroleum gas from a liquid to a gaseous state through controlled heating, ensuring a stable and continuous gas supply.
The global LPG vaporizer market is segmented by vaporizer type, capacity, end user, and geography. By Vaporizer type, the market is segmented into direct-fired vaporizers, electric vaporizers, water-bath vaporizers, steam-heated vaporizers, ambient air vaporizers, and other vaporizer types. By capacity, the market is segmented into low-capacity vaporizers, medium-capacity vaporizers, and high-capacity vaporizers. By end user, the market is segmented into industrial, commercial, utilities and energy, agriculture, and residential and institutional. The report also covers the market size and forecasts for the global LPG vaporizer market across 26 countries in the key regions. For each segment, market sizing and forecasts are provided in terms of value (USD).
Segmentation Overview
| Direct-Fired Vaporizers |
| Electric Vaporizers |
| Water-Bath Vaporizers |
| Steam-Heated Vaporizers |
| Ambient Air Vaporizers |
| Other Vaporizer Types |
| Low-Capacity Vaporizers |
| Medium-Capacity Vaporizers |
| High-Capacity Vaporizers |
| Industrial |
| Commercial |
| Utilities and Energy |
| Agriculture |
| Residential and Institutional |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| France | |
| Italy | |
| Spain | |
| United Kingdom | |
| Poland | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Indonesia | |
| Vietnam | |
| Thailand | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| Egypt | |
| South Africa | |
| Morocco | |
| Rest of Middle East and Africa |
| By Vaporizer Type | Direct-Fired Vaporizers | |
| Electric Vaporizers | ||
| Water-Bath Vaporizers | ||
| Steam-Heated Vaporizers | ||
| Ambient Air Vaporizers | ||
| Other Vaporizer Types | ||
| By Capacity | Low-Capacity Vaporizers | |
| Medium-Capacity Vaporizers | ||
| High-Capacity Vaporizers | ||
| By End User | Industrial | |
| Commercial | ||
| Utilities and Energy | ||
| Agriculture | ||
| Residential and Institutional | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| France | ||
| Italy | ||
| Spain | ||
| United Kingdom | ||
| Poland | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Indonesia | ||
| Vietnam | ||
| Thailand | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| Egypt | ||
| South Africa | ||
| Morocco | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the forecast growth rate for the global LPG vaporizer market?
The LPG Vaporizer Market size is expected to increase from USD 1.48 billion in 2026 to USD 1.52 billion in 2027 and reach USD 1.75 billion by 2032, growing at a CAGR of 2.83% over 2027-2032.
Which vaporizer technology is growing fastest?
Electric vaporizers are the fastest-growing type, with a projected 3.8% CAGR through 2032, and they held 46.3% share in 2026, making them the leading technology in the supplied assessment.
Which capacity range has the strongest growth outlook?
High-capacity systems have the highest projected capacity-segment CAGR at 3.4% through 2032, supported by terminal, petrochemical, and industrial projects requiring continuous high-volume fuel delivery.
Which end-user group leads demand for LPG vaporizers?
Industrial users led demand with 48.7% share in 2026 because process operations need reliable and continuous fuel supply for heating, processing, and production activities.
Which region is growing fastest for LPG vaporizer equipment?
Asia-Pacific is forecast to grow at 4.2% CAGR through 2032, supported by industrial expansion and off-grid LPG programs across major and emerging economies.