
Guidance and Steering System For Precision Agriculture Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 3.9 Billion |
| Market Size (2031) | USD 5.40 Billion |
| Growth Rate (2026 - 2031) | 6.72 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Guidance and Steering System For Precision Agriculture Market Analysis by Mordor Intelligence
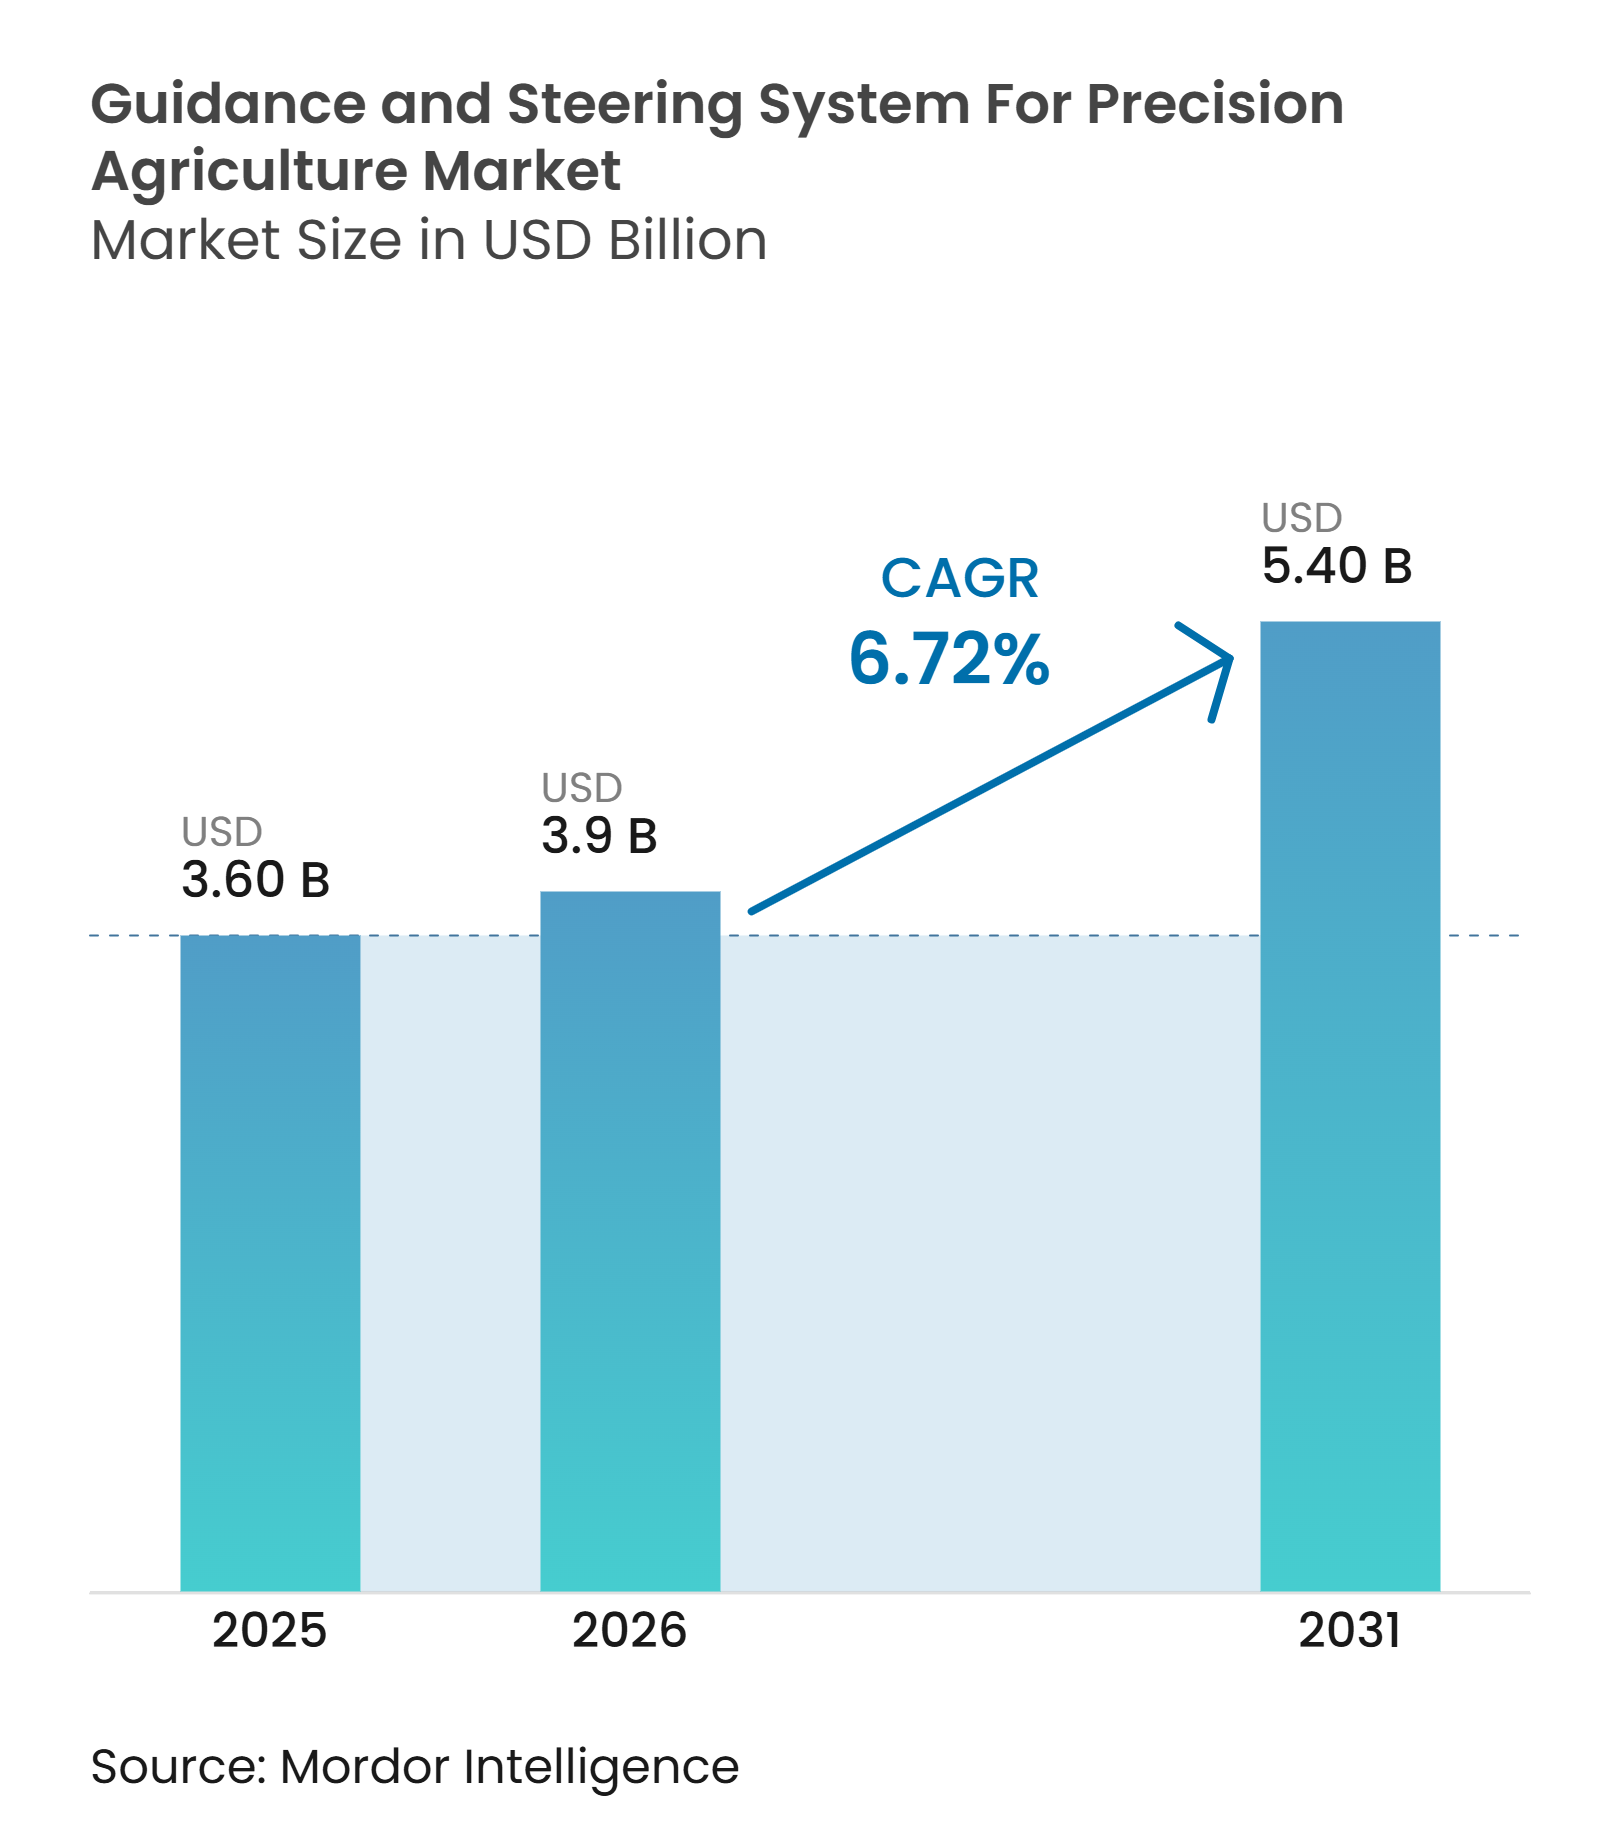
The guidance and steering system for the precision agriculture market size was valued at USD 3.60 billion in 2025, projected to increase to USD 3.9 billion in 2026, and reach USD 5.40 billion by 2031, growing at a CAGR of 7.10% over 2026-2031. Growth is supported by persistent farm labor shortages, higher fuel and input costs, and a broader base of operators seeking equipment upgrades rather than full replacements. Demand is centered on GNSS positioning and automated steering, while farms that already use autosteer are adding tools to optimize seed, fertilizer, and crop protection use. This progression gives suppliers opportunities to build recurring revenue through correction services, field planning software, and over-the-air updates. North America remains the largest regional revenue base due to the availability of precision-ready equipment, correction networks, and established dealer infrastructure. However, the guidance and steering systems market for precision agriculture faces adoption constraints from equipment costs, installation requirements, uneven connectivity, and limited interoperability across mixed-brand fleets.
Key Report Takeaways
- By component, hardware accounted for 51.2% of the guidance and steering system for precision agriculture market share in 2025, while software is forecast to expand fastest at a 13.4% CAGR through 2031.
- By farm size, large farms (greater than 1,000 hectares) represented 54.3% of revenue in 2025, while small farms (less than 100 hectares) are projected to grow at a 13% CAGR through 2031.
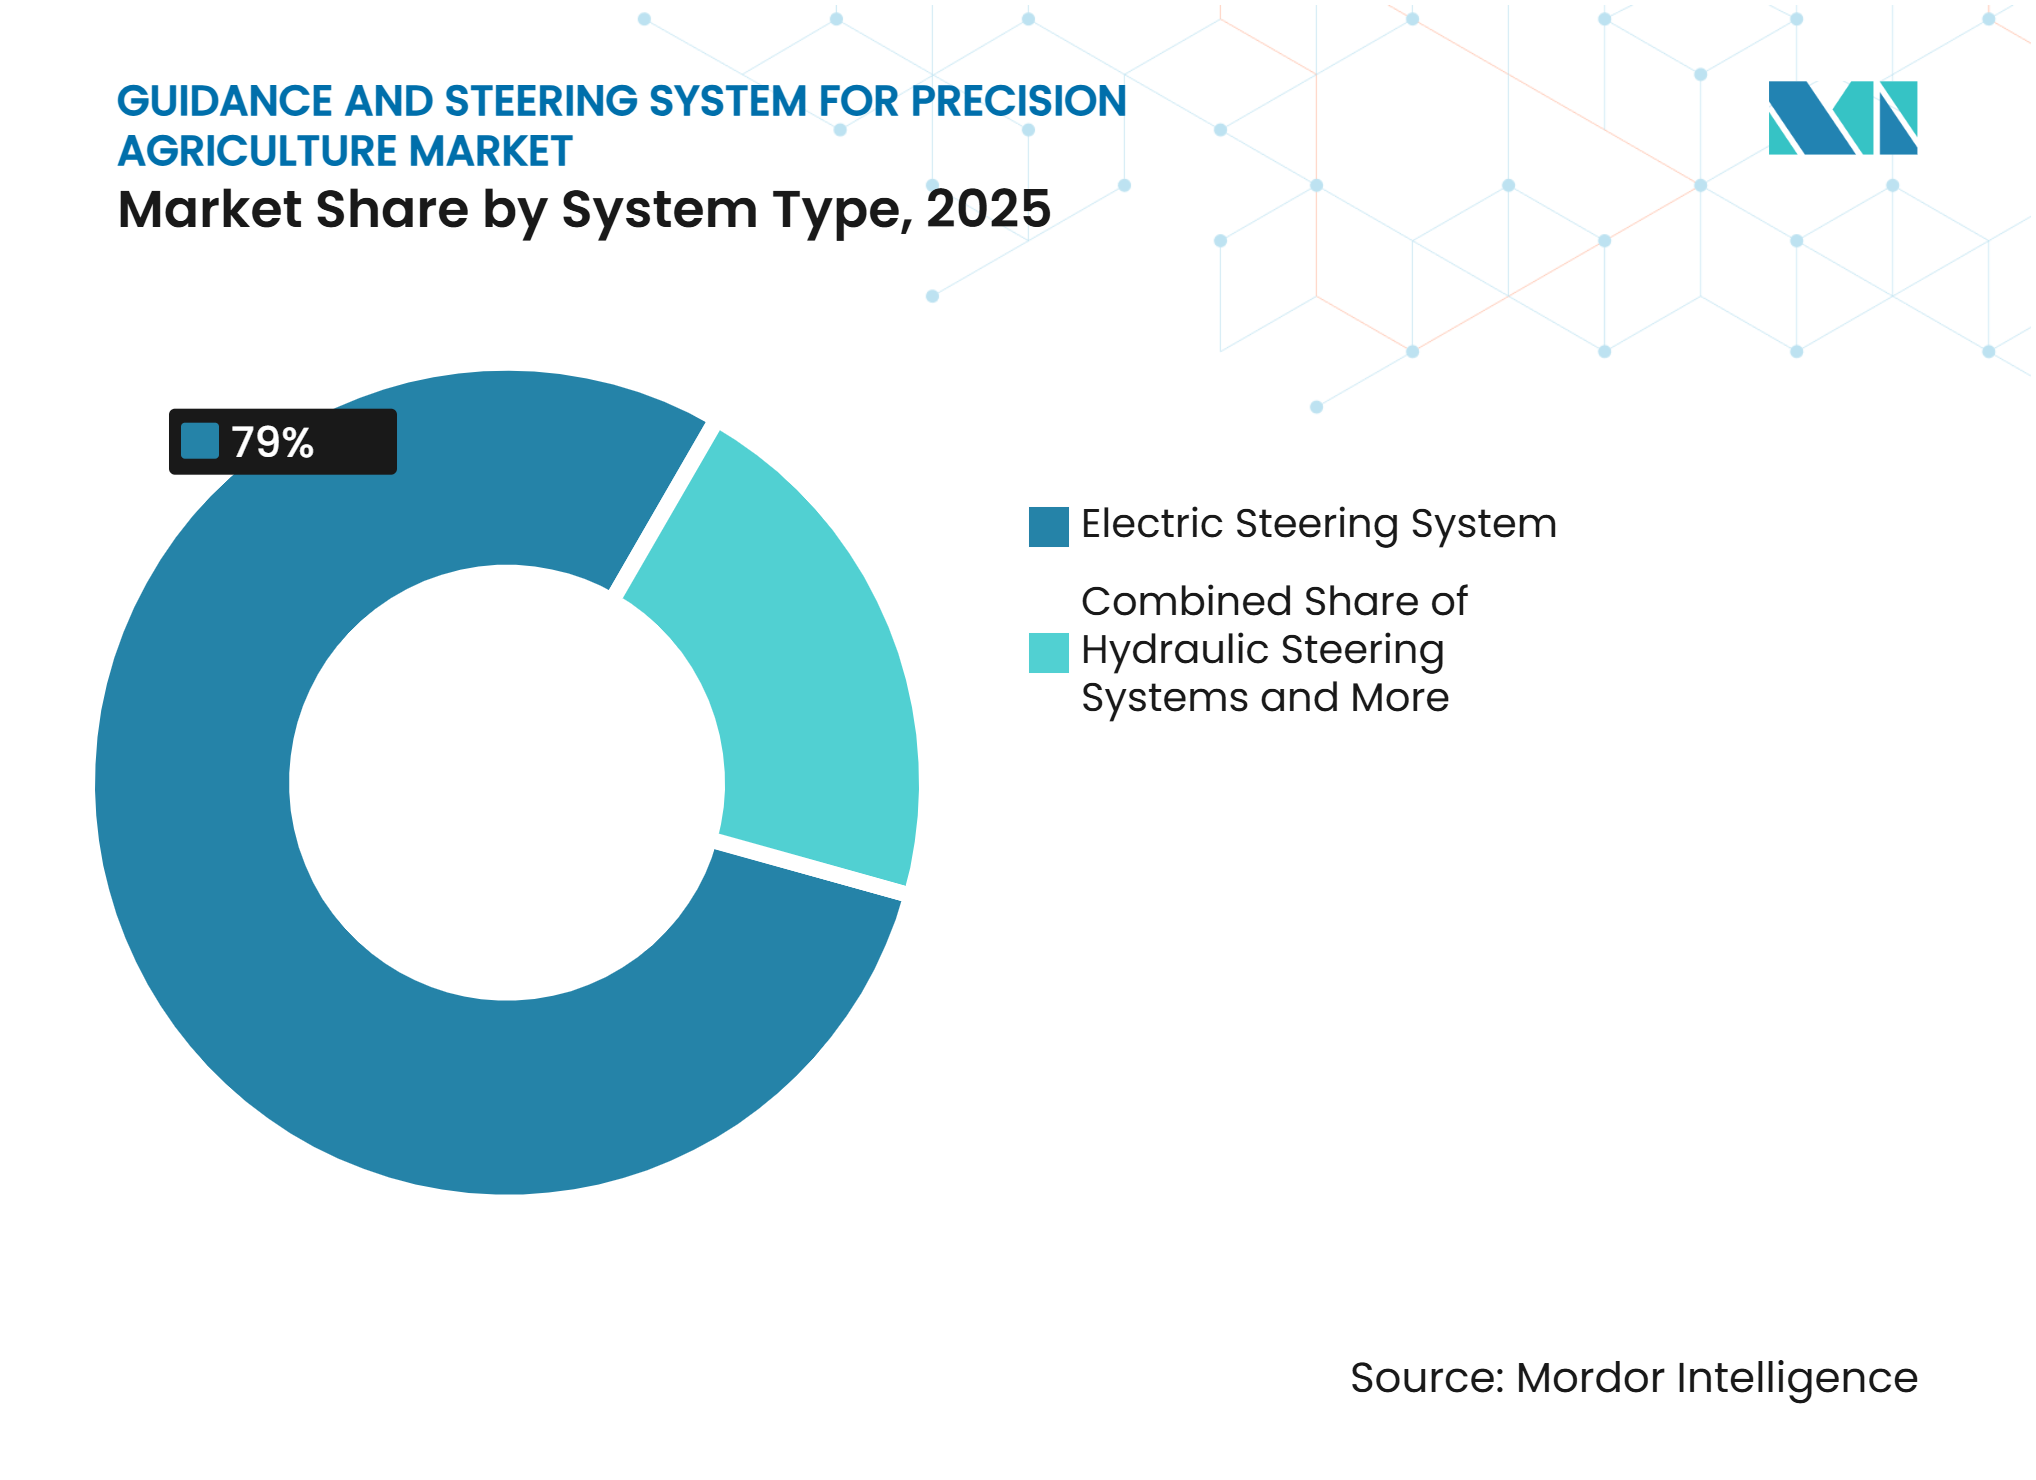
- By system type, electric steering systems accounted for 79% of revenue in 2025 and are forecast to be the fastest-growing, with a 10.1% CAGR during 2026-2031.
- By geography, North America held 44% of the guidance and steering system for precision agriculture market size in 2025, while Asia-Pacific is projected to grow fastest at a 14% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Guidance and Steering System For Precision Agriculture Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| GNSS and RTK Accuracy Improving Field Economics | 1.80% | Global, with strongest relevance in North America and Europe | Long term (≥ 4 years) |
| Labor Ahortages Accelerating Assisted and Automated Steering | 1.50% | North America, Europe, Australia, and East Asia | Medium term (2-4 years) |
| Rising Input Costs Increasing Demand for Pass-to-Pass Accuracy | 1.30% | Global, especially South America, North America, and Europe | Short term (≤ 2 years) |
| Mixed-Fleet Retrofit Demand Expanding the Addressable Base | 1.00% | South America, Asia-Pacific, and the Middle East and Africa | Medium term (2-4 years) |
| Satellite IoT and Edge-AI Enabling More Reliable Guidance | 0.80% | Asia-Pacific and North America, with early adoption in the Middle East and European innovation centers | Long term (≥ 4 years) |
| Sustainability Incentives Rewarding Reduced Overlap and Input Waste | 0.70% | Europe and North America, with growing relevance in Australia and South America | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
GNSS and RTK Accuracy Improving Field Economics
RTK guidance reduces pass-to-pass error to 2.5 cm, compared with the 20 cm to 30 cm accuracy associated with wide-area differential GPS. This precision helps operators avoid overlapping seed and fertilizer bands during planting and application. Avoiding overlap can reduce input waste by 5% to 8% per acre on farms where inputs are applied repeatedly. The guidance and steering system for the precision agriculture market benefits where savings can be spread across large commodity-grain acreage. Deere and Company's AutoPath Boundaries, introduced in 2024 and standard on Model Year 2027 8 Series tractors, generate paths from field boundaries through the G5 display and remove the need for manual line setting. Receivers that work across GPS, GLONASS, Galileo, BeiDou, and QZSS improve satellite coverage and reduce signal interruptions. Higher availability matters because a system that remains usable for more hours can protect planting and spraying schedules. China's network of more than 5,000 BeiDou correction reference stations reduces the need for costly farm-owned base stations and can lower the entry cost for smaller farms.
Labor Shortages Accelerating Assisted and Automated Steering
Labor shortages are increasing the value of assisted and automated steering across North America, Europe, and coastal East Asia. The USDA's 2025 Farm Labor Survey found that 62% of surveyed grain and oilseed operations had difficulty filling seasonal equipment-operator roles[1]. Automated steering allows experienced workers to focus on route planning, maintenance, and data management rather than on continuous steering. In assisted configurations, one operator can oversee two to three machines. This approach can help farms maintain field activity when skilled operators are unavailable, and the guidance and steering system for the precision agriculture market benefits when labor capacity is extended across more equipment. AGCO's PTx OutRun retrofit platform supports driverless grain-cart and tillage work on John Deere 8R and Fendt 900-series tractors, and OutRun Tillage received the 2026 Davidson Prize. Automated steering also supports more consistent work during night and twilight planting periods. Fatigue-related line deviations can exceed 15 cm during these hours, and that loss of accuracy can later appear in remote-sensing yield data.
Rising Input Costs Increasing Demand for Pass-to-Pass Accuracy
Higher fertilizer, crop protection chemical, and diesel costs continue to pressure farm margins. In this context, avoidable overlap becomes a direct operating cost rather than a minor field-management issue. A 3% reduction in fertilizer overlap on a 2,000-hectare canola farm at 2025 Brazilian nitrogen prices can offset the annualized cost of a mid-tier RTK system within one growing season. The guidance and steering system for the precision agriculture market benefits when farmers view accuracy as a means of managing operating costs. PTx Trimble introduced the NAV-960 guidance controller in April 2025, offering up to 50% better availability than the NAV-900 and up to 16 times greater processing power[2]. The product targets row-crop operators who require dependable centimeter-level positioning. Input cost volatility is also encouraging farmers with older guidance units to upgrade before replacing their tractors. In high-input-cost regions, this trend can reduce the historic 7-year to 10-year replacement cycle to 4 years to 6 years.
Mixed-Fleet Retrofit Demand Expanding the Addressable Base
Many tractors in use worldwide were not sold with factory-installed guidance capability. Electric retrofit kits allow farmers to add RTK-capable steering without purchasing a new tractor. Suppliers such as FJ Dynamics, CHC Navigation, AllyNav, and ComNav Technology serve this segment of the precision agriculture guidance and steering system market. These systems can be used on tractors up to 30 years old when the hydraulic system supports a CAN-Bus steering valve interface. CNH introduced FleetPro F10.6 and F12.6 guidance kits in November 2025 through its aftermarket line. The 10-inch configuration was priced at EUR 4,449 (USD 4,870) and used CHC Navigation technology to address mixed-fleet operators. Retrofit availability also broadens distribution beyond traditional farm machinery dealers. Agricultural cooperatives and independent retailers can stock steering kits alongside seed and crop inputs, thereby expanding access to these products.
Restraints Impact Analysis of Guidance and Steering System For Precision Agriculture Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Cost and Retrofit Complexity | -1.80% | Global, with the greatest effect in the Middle East and Africa, South Asia, and smallholder settings | Long term (≥ 4 years) |
| Interoperability Gaps Across OEM and Implement Ecosystems | -1.20% | Global, with greater relevance for mixed-brand fleets in North America and Europe | Medium term (2-4 years) |
| Rural Connectivity and Correction-Service Coverage Gaps | -0.80% | Interior Asia-Pacific, remote South American areas, and the Middle East and Africa | Medium term (2-4 years) |
| Cybersecurity, Data Governance, and Operational Liability Risk | -1% | North America and Europe, with increasing relevance in Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Upfront Cost and Retrofit Complexity
The total cost of RTK guidance remains a challenge for farms with limited capital. This cost includes hardware, installation, dealer calibration, and recurring correction-service subscriptions. For farms below 100 hectares with limited profitability per hectare, these expenses can be substantial. In Sub-Saharan Africa and South Asia, target farms may earn less than USD 2,000 per year, making a USD 2,500 steering kit a multi-year investment. Where financing and public support are unavailable, this limits participation in the guidance and steering system for precision agriculture market. Older tractors may also require steering valves, angle sensors, and CAN-Bus gateway adapters. Dealer installation on these platforms can take 4 to 8 hours and add 30% to 50% to the hardware cost. Larger farms face a different situation; according to the ABARES 2026/27 Farm Capital Expenditure Outlook, GPS guidance budgets for Australian broadacre farms increased 41% in 2026.
Interoperability Gaps Across OEM and Implement Ecosystems
Proprietary equipment protocols make it difficult to use a single guidance system across multiple tractor and implement brands. A farm operating Deere & Company and CNH tractors with third-party implements may require different guidance computers, correction subscriptions, and data formats. This increases costs and operational complexity in managing a mixed fleet, and limits the broader efficiency that guidance and steering systems for precision agriculture are intended to deliver. Reichhardt GmbH Steuerungstechnik's GREEN FIT platform is formally authorized by Deere & Company to provide full AutoTrac functionality on non-Deere & Company vehicles. The platform addresses part of this challenge, but each cross-brand integration still requires engineering work and certification. ISOBUS has improved implement communication, and Danfoss received ISOBUS certification for its XL104 controller in September 2025. Data ownership and cloud platform lock-in remain unresolved for farms seeking to consolidate records across multiple vendors.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Guidance and Steering System For Precision Agriculture Market Segment Analysis
By Component:
Hardware Retains the Largest Base While Software Expands QuicklyHardware accounted for 51.2% of component revenue in 2025. GNSS receivers, steering motors, and cab displays are the primary pieces of equipment farmers purchase when adding guidance capability. The dominance of hardware reflects the capital-equipment nature of the guidance and steering systems in the precision agriculture market. These components provide the positioning and actuation required for automated field passes. Hardware is also necessary for both factory-installed systems and many retrofit packages, with its revenue base supported by ongoing equipment replacement and upgrades. Displays and receivers remain key points of contact between the operator and the broader precision system. Hardware suppliers must maintain compatibility with the expanding range of software features.
Software is forecast to grow at a 13.4% CAGR through 2031, the highest rate among all components. Software enables a tractor equipped with a GNSS receiver and display to add features through firmware and subscription tools, increasing the usefulness of existing equipment without requiring a full hardware replacement. Ag Leader Technology, Inc. launched RightPath in November 2025 as a passive implement steering software unlock for the GPS 7500 receiver, illustrating how suppliers can expand functionality on an existing hardware base. Services also contribute recurring revenue through correction-data subscriptions, dealer installation, and over-the-air updates. Trimble Inc.'s Trimble TerraStar and Shanghai Huace Navigation Technology Ltd.'s CHC Navigation PointSky are examples of proprietary correction networks that generate revenue per machine annually. Together, software and services are shifting more value toward subscriptions and data-enabled functions.
By Farm Size:
Large Farms Supply Revenue While Small Farms Record the Fastest GrowthLarge farms above 1,000 hectares accounted for 54.3% of revenue in 2025. This segment's share of the guidance and steering system market for precision agriculture is supported by the short payback period resulting from applying precision technology across extensive acreage. Large farms in North America's grain belt, Brazil's Cerrado, and Australia's wheat belt led earlier adoption cycles. On farms above 500 hectares, savings in seed, fertilizer, and fuel can recover system costs within one to two growing seasons. These operators also have the capital and dealer access needed for advanced systems. Their existing equipment base supports replacement and feature upgrades. Many now seek headland-turn automation, implement steering, and remote diagnostics. Large-farm demand remains an important source of revenue for manufacturers.
Small farms below 100 hectares are projected to grow at a 13% CAGR through 2031. Lower prices for electric steering kits, the availability of microfinance, and public subsidies are supporting this expansion in South and Southeast Asia, Sub-Saharan Africa, and parts of Latin America. Smaller operators can add steering systems without replacing tractors, which reduces the initial investment. Medium farms between 100 hectares and 1,000 hectares sit between the early and later stages of adoption. Many of these farms are purchasing a second or third generation of guidance systems. PTx Trimble's Precision Core Bundle combines a NAV-860 controller, GFX-1060 display, Autopilot steering, and RTK correction in a retail-ready package for medium farms. Bundled systems can simplify procurement and reduce dealer installation time. As price barriers fall, smaller farms are expected to contribute more unit volume to the guidance and steering system for precision agriculture market.
By System Type:
Electric Steering Systems Lead Revenue and GrowthElectric steering systems accounted for 79% of system-type revenue in 2025 and are estimated to grow at a 10.1% CAGR during 2026-2031. Their dominant position stems from simpler installation, lower system cost compared to hydraulic alternatives, and compatibility with compact utility tractors. Electric systems can connect with CAN-Bus vehicle networks and exchange data with tractor management systems, supporting features such as headland-turn automation and autonomous speed control. These systems are particularly relevant in Asian markets, where electric-only compact tractors are becoming more common. Their retrofit potential also makes them accessible for older machinery. These practical installation and compatibility advantages make electric steering the primary choice for many operators, adding automation to existing fleets.
Hydraulic steering remains relevant for high-horsepower articulated and four-wheel-drive tractors operating in demanding soil conditions, where the required steering force exceeds what current electric motors can reliably provide. Danfoss A/S previewed its EHi electrohydraulic steering system at iVT Expo Cologne 2026, combining electronic control with hydraulic force. OEM guidance systems offer dealer support and warranty coverage, while aftermarket systems provide flexibility for farms operating multiple equipment brands. Trimble, Inc., FJ DYNAMICS INTERNATIONAL LIMITED, Shanghai Huace Navigation Technology Ltd. (CHC Navigation), and Shanghai AllyNav Technology Co., Ltd. are examples of manufacturers serving the retrofit category. The key distinction between OEM and aftermarket systems lies in integrated support versus equipment-brand flexibility.



Geography Analysis
North America held the largest regional share of the guidance and steering system for precision agriculture market, accounted for 44% of global revenue in 2025. The region has a dense base of precision-ready tractors, established RTK correction networks, and dealers capable of installing complex systems. Large grain and oilseed farms in the United States and Canada have used guidance systems for more than a decade, and many are transitioning from early RTK hardware to semi-autonomous and fully autonomous platforms. Brazil's large soybean and corn operations in the Cerrado and the MATOPIBA frontier, which adopt both OEM-installed and retrofit steering systems, have helped the South America region to grow from 2022 to 2026. Brazil's Moderagro credit line and ABC+ Plan recognize precision agriculture hardware as an eligible expenditure[3].
Europe's growth is driven by CAP eco-schemes and the Green Deal's Farm to Fork strategy, which provide incentives for the documented application of precision inputs. Germany and France account for substantial OEM-grade precision farming spending, while Poland, the United Kingdom, and the Netherlands are important retrofit markets for mid-sized arable farms. Asia-Pacific is forecast to expand at a 14% CAGR from 2026 to 2031, the fastest among the regions discussed. China had issued more than 2.7 million BeiDou-enabled agricultural terminals nationally by 2026, while India's smart agriculture programs and Japan's farm labor shortage contribute to demand. China's BeiDou civil-signal compliance requirements also raise technical standards for domestic suppliers. This regional growth broadens the customer base beyond the established markets in North America and Europe.
Commercial farms in South Africa, Kenya, Nigeria, and Egypt are expanding mechanization and adopting productivity tools. The Middle East is projected to grow during the forecast period, supported by Saudi Arabia's Vision 2030 self-sufficiency programs and the United Arab Emirates' precision irrigation initiatives. North America leads the market, while Asia-Pacific is expected to grow fastest, driven by precision farming adoption, government initiatives, agricultural modernization, and increasing demand for satellite-based PPP and L-Band correction services in regions with limited RTK infrastructure.
Competitive Landscape
Market Concentration
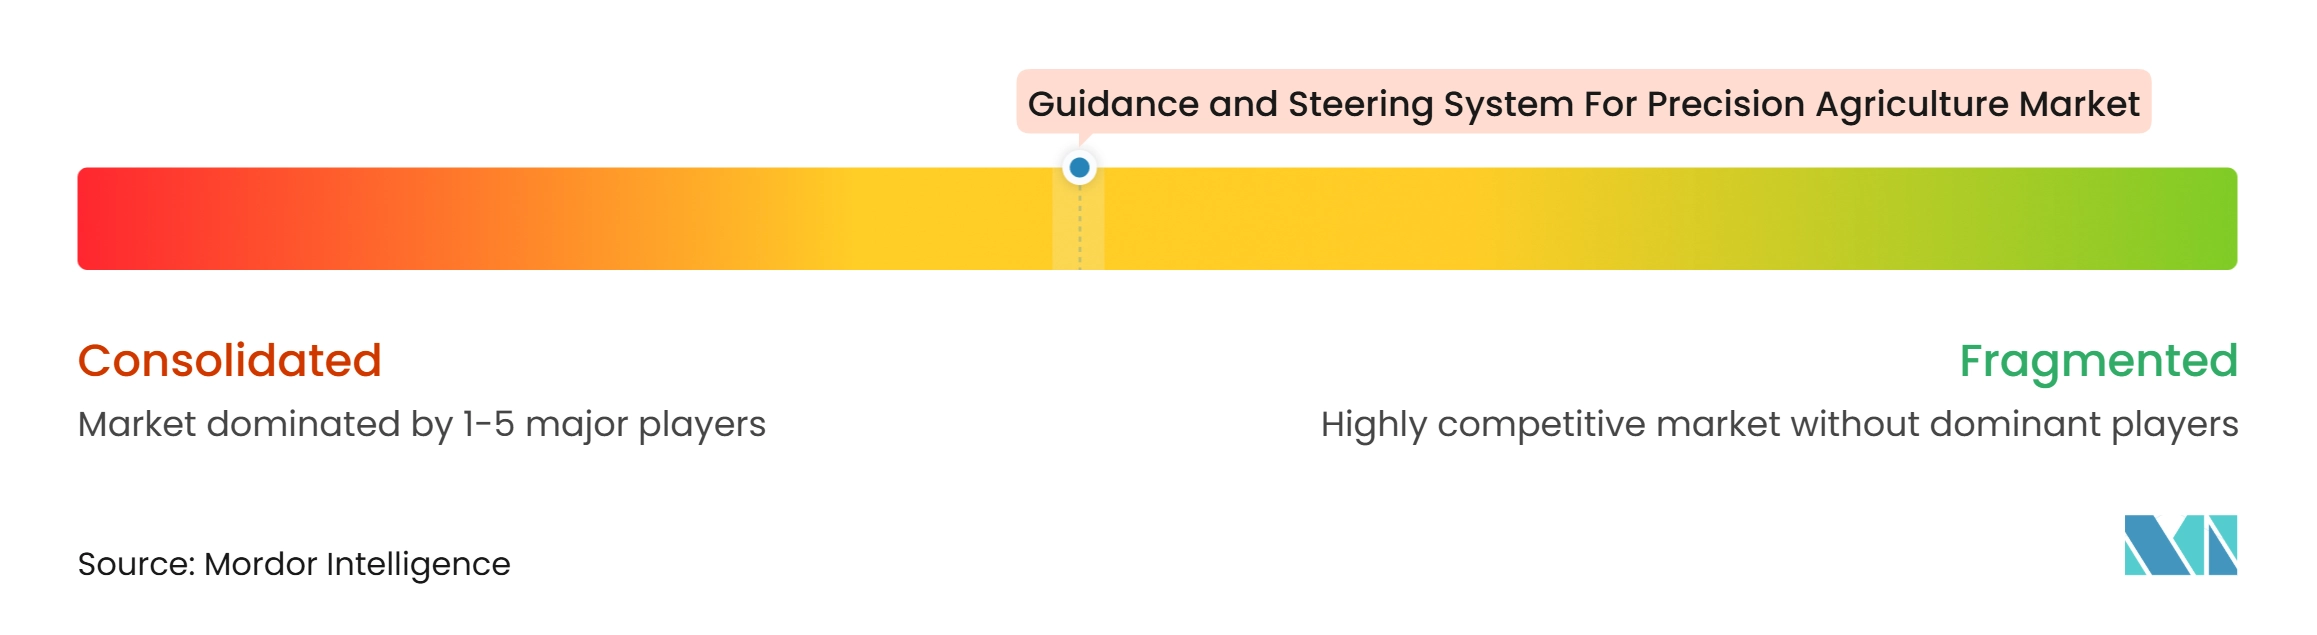
The guidance and steering system for the precision agriculture market is moderately concentrated in 2025. The five leading companies are Deere & Company, AGCO Corporation, CNH Industrial N.V., Topcon Corporation, and Hexagon AB. Deere & Company combines StarFire receivers, AutoTrac software, and the G5 CommandCenter display in a connected product ecosystem, supporting customer retention and premium pricing. Trimble Inc. and AGCO Corporation formed the PTx Trimble joint venture in 2024 to combine positioning and correction capabilities with agricultural distribution. By May 2025, the venture had added more than 50 North American Fendt and Massey Ferguson dealers for brand-neutral retrofit sales. The expansion strengthens aftermarket access for the combined business.
CNH Industrial N.V. uses the Raven precision portfolio for premium aftermarket customers and FleetPro for cost-sensitive retrofit buyers. This two-tier approach allows CNH Industrial N.V. to serve both full-featured row-crop operators and mixed-fleet farms with tighter budgets. Hexagon AB acquired Septentrio in March 2025, strengthening its positioning technology for autonomous farming systems. Its NovAtel SMART7 receiver serves as the GNSS platform for Fendt precision farming machinery, demonstrating how component suppliers can build demand through OEM equipment relationships. Topcon signed an agreement with Xona Space Systems in February 2026 for early access to Pulsar low Earth orbit navigation services. This targets more reliable guidance in areas with limited connectivity and sparse ground correction infrastructure.
FJ DYNAMICS INTERNATIONAL LIMITED, Shanghai Huace Navigation Technology Ltd., Shanghai ComNav Navigation Technology Co., Ltd, and Beijing UniStrong Science & Technology Co., Ltd. compete in price-sensitive emerging markets. Their full-constellation GNSS systems with ISOBUS compatibility are priced 30% to 50% below Western OEM equivalents, encouraging established suppliers to differentiate through software, service, and distribution. Ag Leader's RightPath and CHC Navigation's IS100 reflect growing interest in semi-autonomous implement guidance for trailed equipment. Reichhardt's GREEN FIT platform holds a specialized position as it is formally licensed to integrate Deere AutoTrac with non-Deere vehicles, combining aftermarket flexibility with OEM standards compliance.
Guidance and Steering System For Precision Agriculture Industry Leaders
-
Deere & Company
-
AGCO Corporation
-
CNH Industrial N.V.
-
Topcon Corporation
-
Hexagon AB
- *Disclaimer: Major Players sorted in no particular order
Guidance and Steering System For Precision Agriculture Market Companies Covered in this Report
- Deere & Company
- Trimble Inc.
- CNH Industrial N.V.
- AGCO Corporation
- Topcon Corporation
- Hexagon AB
- Ag Leader Technology
- TeeJet Technologies
- FJ Dynamics International Limited
- SDF S.p.A.
- Danfoss A/S
- Farmscan Pty Ltd
- Beijing UniStrong Science & Technology Co., Ltd.
- CHC Navigation
- AllyNav Technology Co., Ltd.
- ComNav Technology Ltd.
Recent Industry Developments in Guidance and Steering System For Precision Agriculture Market
- May 2026: FJ DYNAMICS INTERNATIONAL LIMITED unveiled the FJD AT2 Ultra Auto Steer System with a 16-inch HD display and AI Voice Control, integrating FieldFusion cloud farm management and support for hydraulic and CAN-Bus steering architectures
- April 2026: Kubota Corporation made a strategic investment in Agtonomy and announced commercial deployment of the autonomous M5 Narrow tractor for specialty crops across the western United States
- February 2026: TOPCON Corporation signed an agreement with Xona Space Systems, Inc. for early access to the Pulsar low Earth orbit satellite navigation constellation
- November 2025: SDF S.p.A. introduced the DEUTZ-FAHR 8 Series TTV at Agritechnica 2025, held in Hanover, Germany, in November 2025. One of the key innovations in the new tractor range is the integration of DEUTZ-FAHR TAGS (Tractor Assisted Guidance System) into its electronic architecture.
Global Guidance and Steering System For Precision Agriculture Market Report Scope
A guidance and steering system for precision agriculture is an advanced system that uses satellite navigation and sensors to automatically or semi-automatically steer farm vehicles like tractors, sprayers, and harvesters.
The gguidance and steering system for precision agriculture report is segmented by technology (guidance systems, variable-rate technology, remote sensing, unmanned aerial vehicles, robotics and autonomous equipment, and others), by component (hardware, software and services), by farm size( small farms, medium farms, and large farms), by system type( robotics and autonomous equipment hydraulic steering systems, integrated oem guidance systems, and aftermarket retrofit guidance systems), and by geography(North America, Europe, Asia-Pacific, South America, Middle East and Africa). The market forecasts in terms of value are provided in USD.
Segmentation Overview
| Hardware |
| Software |
| Services |
| Small Farms (Less than 100 Hectares) |
| Medium Farms (100 - 1,000 Hectares) |
| Large Farms (Greater than 1,000 Hectares) |
| Electric Steering Systems |
| Hydraulic Steering Systems |
| Integrated OEM Guidance Systems |
| Aftermarket Retrofit Guidance Systems |
| North America | United States |
| Canada | |
| Mexico | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| France | |
| United Kingdom | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Israel | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Kenya | |
| Nigeria | |
| Rest of Africa |
| By Component | Hardware | |
| Software | ||
| Services | ||
| By Farm Size | Small Farms (Less than 100 Hectares) | |
| Medium Farms (100 - 1,000 Hectares) | ||
| Large Farms (Greater than 1,000 Hectares) | ||
| By System Type | Electric Steering Systems | |
| Hydraulic Steering Systems | ||
| Integrated OEM Guidance Systems | ||
| Aftermarket Retrofit Guidance Systems | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| France | ||
| United Kingdom | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Israel | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Kenya | ||
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the forecast for guidance and steering systems in precision agriculture?
The market is projected to grow from USD 3.9 billion in 2026 to USD 5.4 billion by 2031 at a 7.1% CAGR.
Which technology holds the largest revenue share?
Guidance systems led technology revenue with a 37.5% share in 2025.
Which component is growing fastest?
Software is projected to expand at a 13.4% CAGR through 2031 as suppliers add subscription-based functions.
Why are smaller farms adopting automated steering?
Lower-priced electric retrofit kits, financing, and subsidy programs are reducing the initial cost of adoption.
Which region is growing fastest?
Asia-Pacific is projected to grow at a 14% CAGR through 2031, supported by China's BeiDou programs, India's smart agriculture initiatives, and labor constraints in Japan.