
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 220.71 Billion |
| Market Size (2026) | USD 247.9 Billion |
| Market Size (2031) | USD 443.14 Billion |
| Growth Rate (2026 - 2031) | 12.32 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Germany Payments Market Analysis by Mordor Intelligence
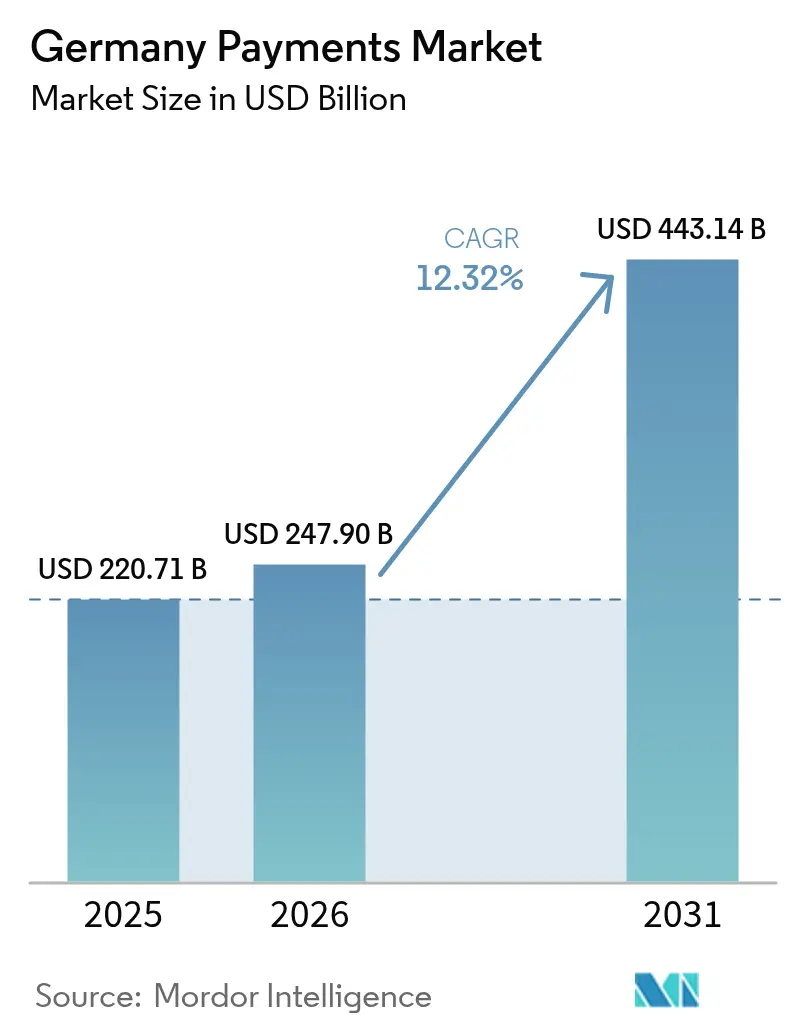
Germany payments market size in 2026 is estimated at USD 247.9 billion, growing from 2025 value of USD 220.71 billion with 2031 projections showing USD 443.14 billion, growing at 12.32% CAGR over 2026-2031. The up-swing signals a decisive transition from cash to digital instruments, propelled by the Instant Payments Regulation, mobile-wallet penetration, and the European Central Bank’s preparations for a digital euro. Point-of-sale (POS) transactions still anchor day-to-day commerce, but e-commerce, buy-now-pay-later (BNPL) plans, and real-time transfers are accelerating adoption curves as merchants seek faster settlement and richer data.[1]European Central Bank, “Digital Euro – Preparation Phase Report,” ecb.europa.eu Card schemes protect incumbent volumes through tokenization and strong-customer-authentication, while domestic banks leverage SEPA Instant rails to build account-to-account propositions. Competitive pressure intensifies as Wero, PayPal, and Klarna scale embedded solutions that bypass legacy card interchange economics. Headline risks include fee caps, core-banking obsolescence, and inflation-linked cost pressure on processors, yet each headwind also nudges providers toward higher-margin advisory and data services within the Germany payments market.
Key Report Takeaways
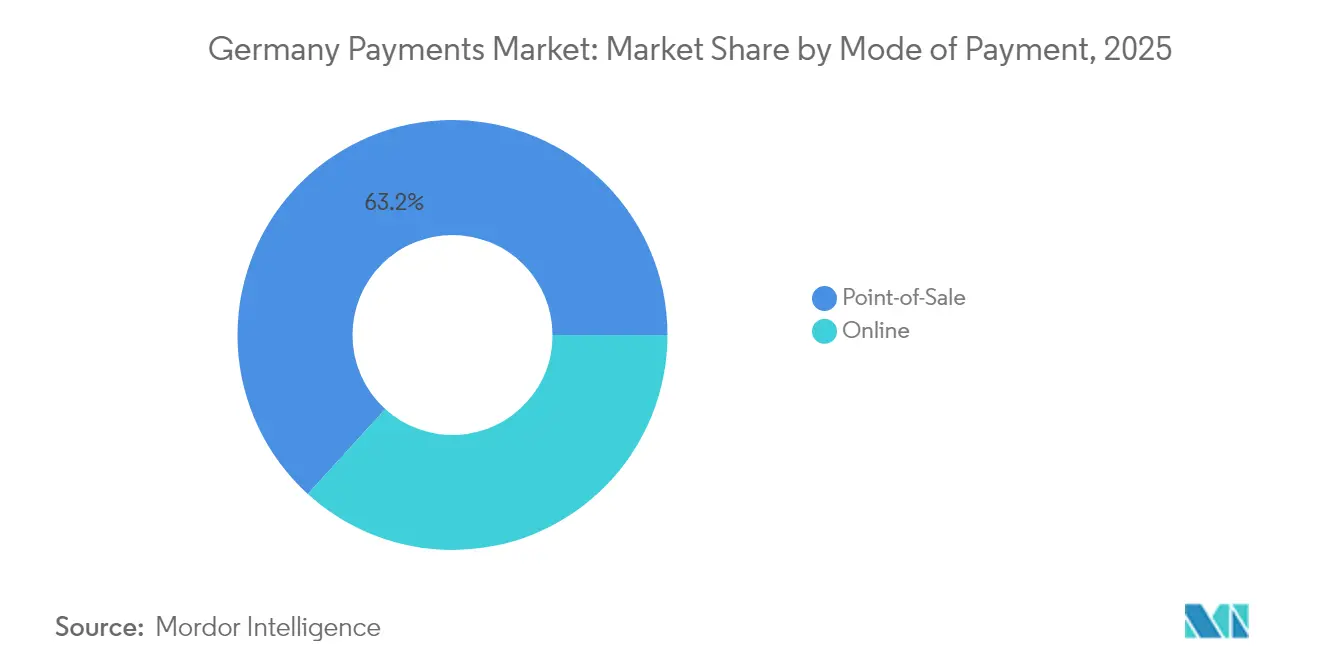
- By mode of payment, POS card payments led with 37.62% of Germany payments market share in 2025; overall Point-Of-Sale Payment held at around 63.25% share; digital wallets are forecast to grow at 15.74% CAGR to 2031.
- By interaction channel, point-of-sale retained 69.85% revenue share in 2025, while e-commerce is projected to expand at 14.25% CAGR through 2031.
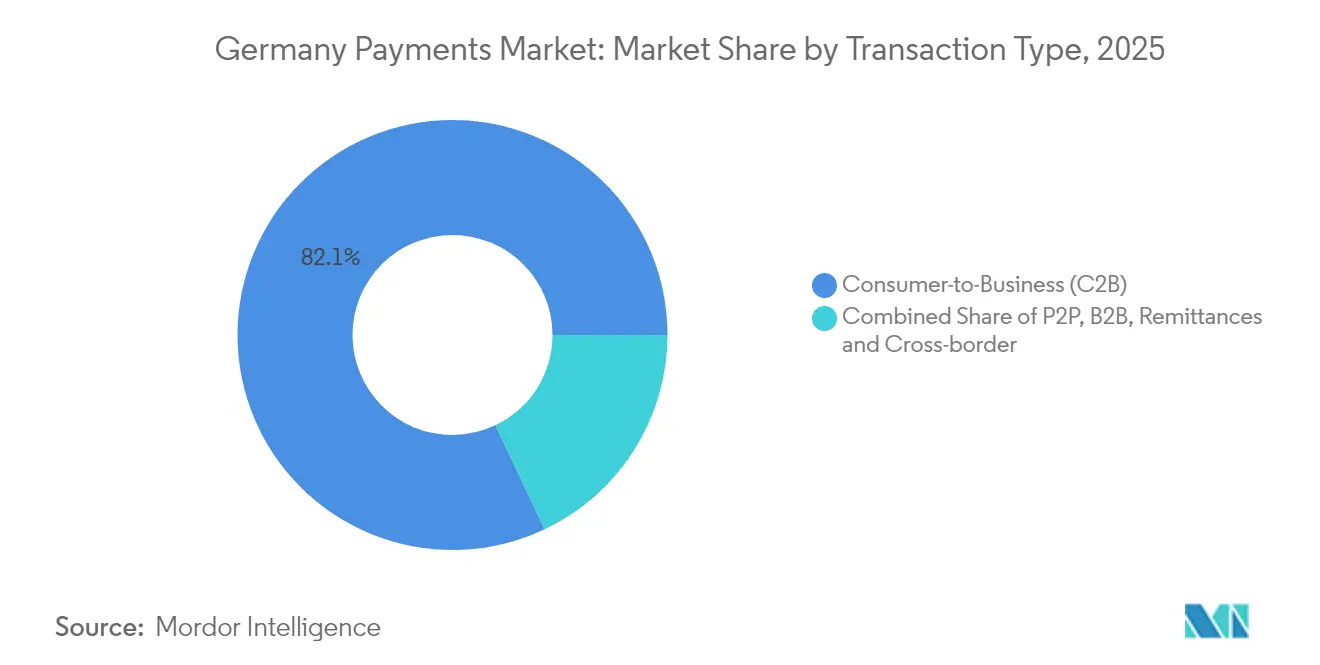
- By transaction type, consumer-to-business flows captured 82.05% of 2025 volumes; person-to-person payments should accelerate at 17.2% CAGR to 2031.
- By end-user industry, retail held 29.25% share of the Germany payments market size in 2025, whereas hospitality and travel is advancing at 14.65% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Germany Payments Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Explosion of Mobile-Wallet Acceptance at German POS Terminals | +2.8% | National, with early gains in Berlin, Munich, Hamburg | Medium term (2-4 years) |
| E-commerce Boom Fueling Card-Not-Present Volumes | +3.2% | National, stronger in urban centers | Short term (≤ 2 years) |
| Government-backed Instant-Payment Infrastructure Drives the Market | +2.1% | EU-wide, concentrated in Germany | Short term (≤ 2 years) |
| Surging Buy-Now-Pay-Later (BNPL) Adoption Among Millennials | +1.9% | National, with spillover to Austria, Switzerland | Medium term (2-4 years) |
| Merchant Demand for Omnichannel Checkout Experiences | +1.7% | National, retail-focused regions | Medium term (2-4 years) |
| Fin-Tech Partnerships Enabling Embedded-Payment Use-Cases | +1.4% | National, B2B concentrated in Frankfurt, Stuttgart | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Explosion of Mobile-Wallet Acceptance at German POS Terminals
PayPal’s contactless debut in 2025—enabled by Digital Markets Act access to Apple’s NFC chipset—removed a long-standing technical barrier and let non-bank wallets compete directly with Apple Pay and Google Pay at 286,000 VR Payment terminals.[2]VR Payment, “Terminal Network Statistics 2025,” vr-payment.de Merchant queues shortened, checkout data improved, and mobile usage jumped as cash lost relevance. Banks responded by integrating girocard tokens into Android and iOS wallets to retain top-of-mind status at the point of tap. The network effect is self-reinforcing: each accepting merchant encourages more consumers, who in turn press other merchants to upgrade. Over the medium term the uplift adds 2.8 percentage points to the Germany payments market CAGR, particularly in high-traffic urban micro-segments.
E-commerce Boom Fueling Card-Not-Present Volumes
Online shopping reached 82% household penetration by 2023 and remains on a steep trajectory. Lidl and Kaufland’s Click to Pay roll-out trimmed authentication friction, lifting conversion while allowing Mastercard to march toward its 100% tokenization target. Higher basket values and purchase frequency in digital channels give payment providers revenue leverage even when physical retail stabilizes. Digital identity projects and one-click checkout standards converge to suppress fraud rates, further nudging late adopters into the channel. The result is a 3.2 percentage-point boost to overall growth in the Germany payments market, with CNP volumes eclipsing face-to-face growth by more than 2:1.
Government-Backed Instant-Payment Infrastructure Drives the Market
Mandatory acceptance of real-time transfers from January 2025 forced every bank to modernize clearing pipes. Deutsche Bank processed 27% more instant transfers in the first month, and corporates began shifting supplier payouts to 24/7 rails to improve working-capital rotation. Fintechs exploit these rails through API overlays, offering cash-flow dashboards and variable-recurring-payment links for subscription merchants. The rails also underpin Wero’s pan-European wallet, creating a competitive alternative to card networks. Because instant settlement removes chargeback exposure and cuts scheme fees, merchants steer customers toward it with small discounts, broadening adoption. The structural benefit adds 2.1 percentage points to the Germany payments market CAGR during 2025-2030.
Surging Buy-Now-Pay-Later Adoption Among Millennials
Klarna’s 30% revenue leap in 2024 confirmed BNPL’s journey into the mainstream. German millennials entering higher disposable-income brackets prefer flexible installment plans over revolving credit. PayPal’s in-app BNPL for in-store purchases extends the model beyond online carts. Merchants appreciate average-order-value lifts and lower checkout abandonment, while consumers enjoy cost transparency. As regulators tighten credit-worthiness rules, leading providers differentiate through open-banking data analytics to keep default rates contained. The mechanism contributes 1.9 percentage points to the compound expansion of the Germany payments market and re-shapes merchant subsidy economics.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Interchange-Fee Caps Compressing Issuer Economics | -1.8% | EU-wide, concentrated in Germany | Medium term (2-4 years) |
| Legacy Core-Banking Systems Slowing API Roll-outs | -1.2% | National, affecting traditional banks | Long term (≥ 4 years) |
| Consumer Privacy Concerns over PSD2 Data-Sharing | -0.9% | EU-wide, particularly Germany | Short term (≤ 2 years) |
| Fragmented KYC/AML Requirements for Cross-border Payments | -0.7% | EU cross-border, affecting German banks | Medium term |
| Source: Mordor Intelligence | |||
Interchange-Fee Caps Compressing Issuer Economics
Proposed fee ceilings could shift USD 502 million of annual economics from issuers to merchants. German banks therefore accelerate account-to-account propositions and seek subscription-style revenues from digital identity or loyalty add-ons. Card schemes respond by unbundling value-added services—fraud scoring, token vaults, instalment APIs—to preserve relevance. Smaller issuers, lacking scale, may retreat from consumer cards altogether, trimming innovation budgets and shaving 1.8 percentage points off the otherwise robust CAGR in the Germany payments market.[3]Payment Systems Regulator, “Card Scheme Fee Changes 2019-2024,” psr.org.uk
Legacy Core-Banking Systems Slowing API Roll-outs
Many German banks still run on 1980s mainframes that complicate real-time data exposure. Middleware layers add latency, raise project costs, and create brittle integration points for fintech partners. As PSD2 successor rules mandate premium APIs, the technology debt becomes a strategic liability. Processor Worldline has already reported merchant-relationship terminations triggered by compliance delays rather than price factors. Over the long term, delayed product introductions and duplication of effort dilute growth, subtracting 1.2 percentage points from the Germany payments market trajectory.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mode of Payment: Cards Continue to Anchor but Wallets Scale Faster
POS card payments held 37.62% Germany payments market share in 2025, underscoring consumers’ familiarity with girocard and dual-network debit credentials. Overall, Point-of-Sale Payment is largest share with 63.25%. Credit and prepaid cards together stayed below 15% because many Germans prefer immediate settlement over revolving credit. Yet digital wallets, helped by open-NFC policy and SEPA Instant reach, are expanding at 15.74% CAGR. Their share of Germany payments market size for online checkouts is forecast to eclipse cards by 2028. Unlike cards, wallets can weave loyalty, buy-now-pay-later, and identity verification into one interface, making them magnets for merchant upselling. Cash use is slipping into single-digit range for transactions above EUR 50 (USD 54) as public transport and event venues pivot to tap-only acceptance. Meanwhile, QR code and wearable payments ride contactless rails but remain niche, capturing less than 2% of 2025 volume. Over the forecast period, regulators will watch wallet concentration to ensure competitive balance, yet the consumer tide is clearly in favor of tap-to-phone and in-app credentials.


By Interaction Channel: Physical POS Dominates but Digital Commerce Lifts Overall Growth
The brick-and-mortar environment delivered 69.85% of 2025 transaction value, reflecting Germany’s dense grocery and discount-retail footprint. Yet e-commerce posted a 14.25% CAGR, adding incremental spend faster than physical outlets. Mobile commerce—fueled by same-day delivery and 5G coverage—accounts for more than half of online checkouts in urban corridors. PayPal’s contactless launch blurs channel boundaries by letting shoppers re-use the same credential online and in stores. That convergence encourages merchants to invest in unified token vaults and customer-data platforms. Within the Germany payments market, omnichannel experiences will reduce stand-alone online fraud rates and harmonize loyalty programs, supporting profitable growth across both channels.
By Transaction Type: Consumer Purchases Prevail while Peer Transfers Accelerate
Consumer-to-business flows represented 82.05% of 2025 volumes and keep rising with retail turnover growth. Business-to-business payments are slower to digitize due to batch invoicing habits and enterprise resource planning (ERP) dependencies, yet API-based request-to-pay pilots hint at future change. Person-to-person transfers, growing at 17.2% CAGR, are the bright spot. Wero’s phone-number rails and Deutsche Bank’s One-Pay FX corridor ease friction and start to cannibalize cash gifting and paper giro transfers. Remittance corridors remain modest in value but gain from application programming interfaces (APIs) that drop fees below 1% and deliver funds in seconds. The embedded finance movement also opens new transaction types—gig-worker payouts, insurance claim disbursements, marketplace seller settlements—broadening the Germany payments market size without cannibalizing headline categories.
By End-user Industry: Retail is the Base, Travel Leads the Upswing
Retail owned 29.25% of 2025 value, with supermarkets, DIY stores, and discount chains keeping debit volumes high. Hospitality and travel rebound sharply, advancing at 14.65% CAGR as global tourism normalizes and events like UEFA Euro 2024 trigger surge capacity. Hotels add self-service kiosks linked to instant payment options, trimming check-in times and staffing overhead. Airlines introduce in-app wallet boarding passes with integrated duty-free ordering, monetizing ancillary services. Healthcare digitizes slower but benefits from mandatory e-prescription flows that link pharmacy payments to insured reimbursement. Utility bill payments migrate to e-invoices tied to real-time direct debits, improving collection rates and data granularity. Collectively these vertical trends expand the Germany payments market while de-risking reliance on any single sector.
Geography Analysis
Germany payments market growth is uneven across the federal landscape. Metropolitan areas—Berlin, Munich, Hamburg, and Frankfurt—show mobile-payment penetration above 60% among residents aged 18-35, while rural districts still favor cash for small-value purchases. ATM consolidations reduce cash availability, nudging older demographics toward contactless girocard and wallet options. Northern states—Schleswig-Holstein and Hamburg—exhibit the highest card penetration, mirroring Scandinavian influence, whereas Bavaria preserves stronger cash usage, citing tradition and privacy. Real-time rails reduce cross-state payment delays, enabling SMEs in Saxony and Thuringia to settle invoices 24/7.
Cross-border commerce thrives on EU harmonization. Wero’s reach into France and Belgium creates a regional network effect, and merchants in Cologne and Aachen already offer wallet acceptance to serve Belgian day-trippers. The forthcoming digital euro pilot, coordinated by the Bundesbank, could test retail scenarios in Frankfurt’s fintech cluster, where 59% of surveyed consumers express willingness to adopt a central-bank-issued instrument. Overall, geographic disparities will narrow over time as infrastructure gaps close, yet localized marketing remains vital to capture regional attitudes inside the Germany payments market.
Regulatory Landscape
Germany payments are primarily governed under the Payment Services Supervision Act (ZAG), which implements PSD2 and sets BaFin authorization and ongoing supervision requirements for payment institutions and e-money institutions, while certain providers (such as account information services) follow registration pathways. Alongside BaFin licensing, the Deutsche Bundesbank oversees payment systems under the Eurosystem framework, including oversight of card payment schemes and arrangements used in Germany.
The EU Instant Payments Regulation (EU) 2024/886 is a key compliance driver for banks and payment service providers, adding operational and reporting requirements for SCT Inst participation and performance. BaFin highlighted the Instant Payments Regulation reporting obligations, with an initial reporting deadline in April 2026, and the Bundesbank continues to apply Eurosystem oversight to major electronic payment instruments and schemes in Germany, keeping supervisory focus on resilience, security, and scheme governance.
Value Chain Analysis
The Germany payments value chain starts with end users (consumers and businesses) and merchants, then moves through front-end acceptance (POS terminals, e-commerce checkouts, and wallet integrations) and merchant service providers (PSPs/acquirers) that route transactions into card and account-to-account rails. Card payments run through schemes (including girocard and international networks), issuers, acquirers, processors, and tokenization and authentication services, then settle through banking infrastructure. Account-to-account flows use SEPA Credit Transfer and SEPA Instant rails, with interbank clearing and settlement supported by Bundesbank infrastructure such as the RPS SEPA-Clearer and SEPA Card Clearing (SCC) collections.
Regulated entities (banks, payment institutions, and e-money institutions) sit at the core of execution and safeguarding. BaFin supervision under the ZAG shapes onboarding, KYC/AML, and operational controls, while EBA guidelines for authorization and registration provide cross-EU supervisory consistency. On the demand side, the consumer shift toward cashless is visible in 2025, when cashless payment methods accounted for 55% of recorded purchases, raising throughput requirements for acquirers and processors and increasing the importance of fraud management, strong customer authentication, and data-driven orchestration across omnichannel payments.
Competitive Landscape
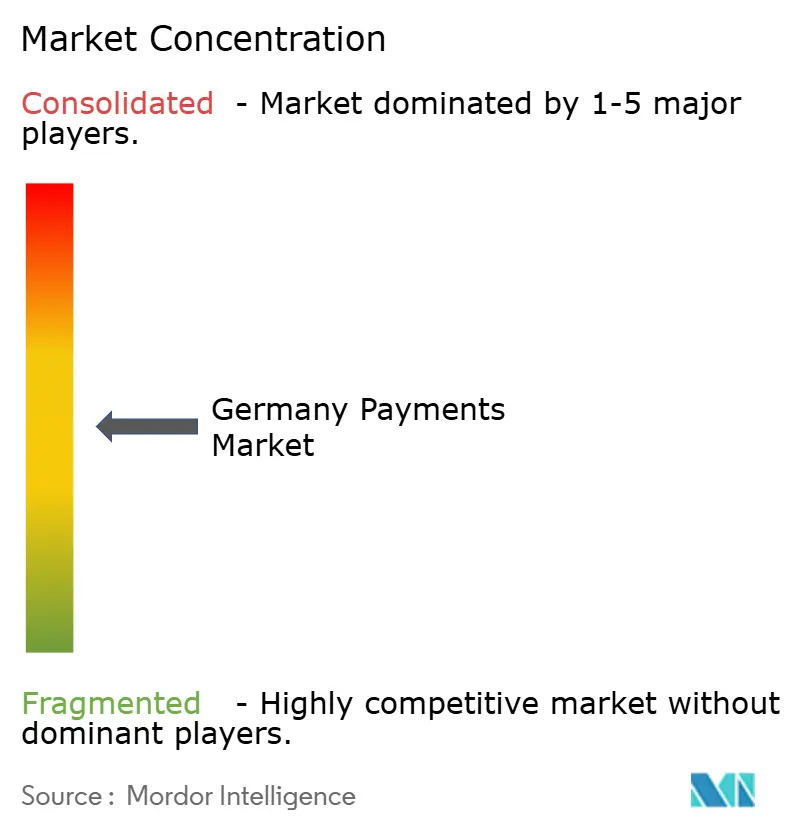
The Germany payments market exhibits moderate fragmentation and intensifying consolidation. International schemes (Visa, Mastercard), domestic girocard, global wallets (PayPal, Apple Pay, Google Pay), and European challengers (Wero) form overlapping layers of acceptance. Market leaders invest in tokenization, risk engines, and value-added APIs to protect interchange revenue as regulators impose caps. Banks pursue joint ventures—such as Commerz Globalpay—to modernize acquiring and keep merchant relationships.
Worldline, Nexi, and Stripe compete for enterprise omnichannel mandates, differentiating via uptime, developer tooling, and data analytics. Fintech disrupters like Ivy target B2B pay-ins and pay-outs with cloud-native stack, under-cutting legacy processor pricing. Acquirers look downstream, acquiring ISV platforms to embed payments into vertical SaaS, while processors move upstream into treasury services to offset margin squeeze. Patent filings at the European Patent Office show heightened activity around secure NFC and biometric authentication, evidencing ongoing innovation that could reshape share positions. Overall competitive tension fosters rapid product iteration, benefiting merchants and end users within the Germany payments market.
Germany Payments Industry Leaders
Mastercard Inc.
Visa Inc.
Girocard (Deutsche Kreditwirtschaft)
PayPal Holdings Inc.
Google Pay (Alphabet Inc.)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Instant payments and account-to-account checkout create a clear whitespace for merchants looking for lower-cost acceptance and faster settlement, reinforced by EU Instant Payments Regulation implementation milestones for receiving and sending SCT Inst. With cashless payments reaching 55% of recorded purchases in 2025, providers have a practical basis for migrating repeat-pay use cases, including subscription collections, supplier payouts, and marketplace settlements, from batch processes and cards to real-time rails, especially where merchants prioritize cash-flow visibility and reduced scheme fees.
European-sovereign wallet and acceptance options are also expanding merchant choice in Germany as Wero is incorporated into e-commerce acquiring stacks. For example, Nexi announced in April 2026 that it is implementing Wero for eCommerce in Germany, with merchants including BAUR, Quelle, and Buenting Group preparing for implementation. Public-sector digitization adds further acceptance opportunities, with a binding agreement reached in June 2026 between the federal government and the 16 states on the Deutschland-Stack, including development of ePayBL for public sector payments, creating room for PSPs and integrators to connect compliant payment flows to government service journeys while meeting German and EU oversight expectations.
Recent Industry Developments
- May 2026: Visa announced a EUR 500 million investment in European payment infrastructure, including a new Eurozone data center to process transactions regionally. The move supports data sovereignty and resilience priorities for German merchants, issuers, and regulators as volumes shift further toward digital channels.
- April 2026: Mastercard-backed initiative Deutschland zahlt digital transitioned into a registered association to formalize governance and sustain long-term efforts to expand digital acceptance. A more structured vehicle strengthens coordination across stakeholders that promote POS digitization among smaller merchants.
- June 2025: Worldline launched Wero for German e-commerce as part of the European Payments Initiative, bringing a European wallet option into merchant checkout flows. This broadened alternatives to cards and global wallets for online acceptance and supports account-to-account style propositions aligned with SEPA Instant rails.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Germany payments market is defined as the gross transaction value processed through card payments, digital wallets, account-to-account transfers, and cash-at-checkout across in-store and online purchases for consumers and businesses.
Scope exclusions: We exclude payments tied to motor-vehicle and real-estate purchases, utility bill settlement, mortgage or loan servicing, and securities trading.
Segmentation Overview
- By Mode of Payment
- Point-of-Sale
- Card (Debit, Credit, Pre-paid)
- Digital Wallets (Apple Pay, Google Pay, Interac Flash)
- Cash
- Other POS (Gift-cards, QR, Wearables)
- Online
- Card (Card-Not-Present)
- Digital Wallet and Account-to-Account (Interac e-Transfer, PayPal)
- Other Online (COD, BNPL, Bank Transfer)
- Point-of-Sale
- By Interaction Channel
- Point-of-Sale
- E-commerce/M-commerce
- By Transaction Type
- Person-to-Person (P2P)
- Consumer-to-Business (C2B)
- Business-to-Business (B2B)
- Remittances and Cross-border
- By End-user Industry
- Retail
- Entertainment and Digital Content
- Healthcare
- Hospitality and Travel
- Government and Utilities
- Other End-user Industries
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts with building a clean fact base on payment activity, channel shift, and regulatory direction in Germany. We typically use public sources such as Deutsche Bundesbank statistics, ECB payments data, Eurostat digital economy indicators, BIS payment and settlement publications, and OECD macro series to align definitions and time series.
To translate these signals into a practical sizing model, we also review bank and payment network disclosures, annual reports, investor presentations, and reputable financial press coverage for adoption cues and product mix changes. Where needed, we cross-check company financials using paid company intelligence and news databases, and we also use a paid patent database to spot areas where investment is moving (for example, real-time rails and authentication). This list is illustrative only, and we referenced additional sources for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary work is used to pressure-test the desk assumptions with the people closest to payment issuance, acceptance, processing, and risk controls. We speak with a mix of banks, payment service providers, merchants, and supporting ecosystem participants across Germany, so we can close gaps in pricing, channel mix, and usage behavior before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 18% |
| Mid tier: 47% | Functional/Unit leaders: 39% |
| Smaller Players: 22% | Managers: 43% |
Market-Sizing & Forecasting
Sizing is built with a top-down and bottom-up blend, where national payment activity and channel indicators are reconstructed first, and then checked using selective supplier and merchant-level sanity tests. The top-down spine leans on payment mix shares, online versus in-store splits, and reported transaction value series, which are then adjusted to match the market definition used in this report.
To keep the model grounded, we feed in a small set of practical variables that move transaction value in Germany, such as private consumption and retail sales direction, e-commerce share changes, card and wallet adoption patterns, account-to-account usage momentum, and the pace of contactless and mobile checkout. When certain parts of the value chain do not disclose enough, we handle the gap through bounded assumptions that are anchored to interview ranges and cross-checked against independent signals like bank commentary and publicly reported acceptance trends.
For forecasting, scenario analysis is used so the outlook can flex when adoption speed, pricing, or regulation shifts faster than expected. A base case is constructed first, and then the downside and upside cases are used to verify that the final forecast stays realistic against the demand drivers we track and the constraints stakeholders highlighted.
Data Validation & Update Cycle
Validation is done in layers so the final totals do not rely on one data line. We compare outputs against independent indicators like payment instrument shares and macro-consumption direction, and then we review any sharp jumps that do not match what interviewees describe in day-to-day payment flows.
Before sign-off, the model is reviewed by another analyst to check formulas, unit consistency, and currency timing, followed by a final variance pass on key assumptions. Reports are refreshed annually, and interim updates are triggered when material events occur, such as rule changes, major platform moves, or abrupt shifts in consumer payment behavior. Right before delivery, we complete a fresh review pass so clients receive the most current view we can support.
Mordor Intelligence's Germany Payments Market Estimate Compared With Other Published Estimates
Published estimates for Germany payments can look far apart, even when they all sound like they measure the same thing. In most cases, the differences come from what is counted as a payment transaction, which spending buckets get included, and whether values are reported as transaction value or as provider revenue.
By tracking scope exclusions and refresh timing, Mordor Intelligence ties the 2025 total to card, wallet, account-to-account, and cash-at-checkout purchase flows, and it keeps out categories like utilities, loan servicing, securities, and large-ticket vehicle or real-estate payments that can inflate totals. Some estimates also apply a more aggressive growth path by assuming faster e-commerce shift or quicker wallet substitution, while others compress the number by focusing only on digital instruments or by using a different currency conversion point.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 220.71 B (2025) | |
| Industry Association A | USD 315.00 B (2025) | Uses a broader transaction basket that can include recurring bill payments and other large-ticket categories, and it may report gross flows without separating out excluded use cases. |
| Global Consultancy B | USD 180.00 B (2025) | Narrows the scope to mainly electronic instruments and card-led spend, which can undercount cash-at-checkout and some account-to-account purchase flows in mixed payment journeys. |
The spread in the table is mainly explained by scope boundaries and what each publisher treats as a purchase payment versus a broader money movement. Our approach stays repeatable because each adjustment is linked back to observable payment mix signals and interview-validated assumptions, which makes the final value easier to reconcile year to year.


Key Questions Answered in the Report
What is the projected value of the Germany payments market in 2031?
It is projected to reach USD 443.14 billion, reflecting a 12.32% CAGR during 2026-2031.
Which payment mode is growing fastest in Germany?
Digital wallets are expanding at 15.74% CAGR, driven by NFC access and instant-payment rails that reduce checkout friction.
How will interchange-fee caps affect German issuers?
Fee ceilings could strip as much as 1.8 percentage points from market CAGR by compressing card-issuer margins and shifting focus to value-added services.
Why are instant payments important for merchants?
Regulated real-time transfers lower settlement risk, improve cash-flow timing, and cut scheme fees, encouraging merchants to promote account-to-account options.
Which end-user industry shows the fastest growth?
Hospitality and travel lead with a 14.65% CAGR as tourism normalizes and contactless solutions gain popularity during large events such as UEFA Euro 2024.
Are peer-to-peer transfers significant in Germany?
Yes, person-to-person payments are growing at 17.2% CAGR, propelled by Wero’s phone-number rails and broader instant-payment infrastructure.
Page last updated on:





