
Size and Share of Europe Solder Materials Market In Semiconductor Industry
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 0.62 Billion |
| Market Size (2027) | USD 0.68 Billion |
| Market Size (2032) | USD 1.03 Billion |
| Growth Rate (2027 - 2032) | 10.74 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Analysis of Europe Solder Materials Market In Semiconductor Industry by Mordor Intelligence
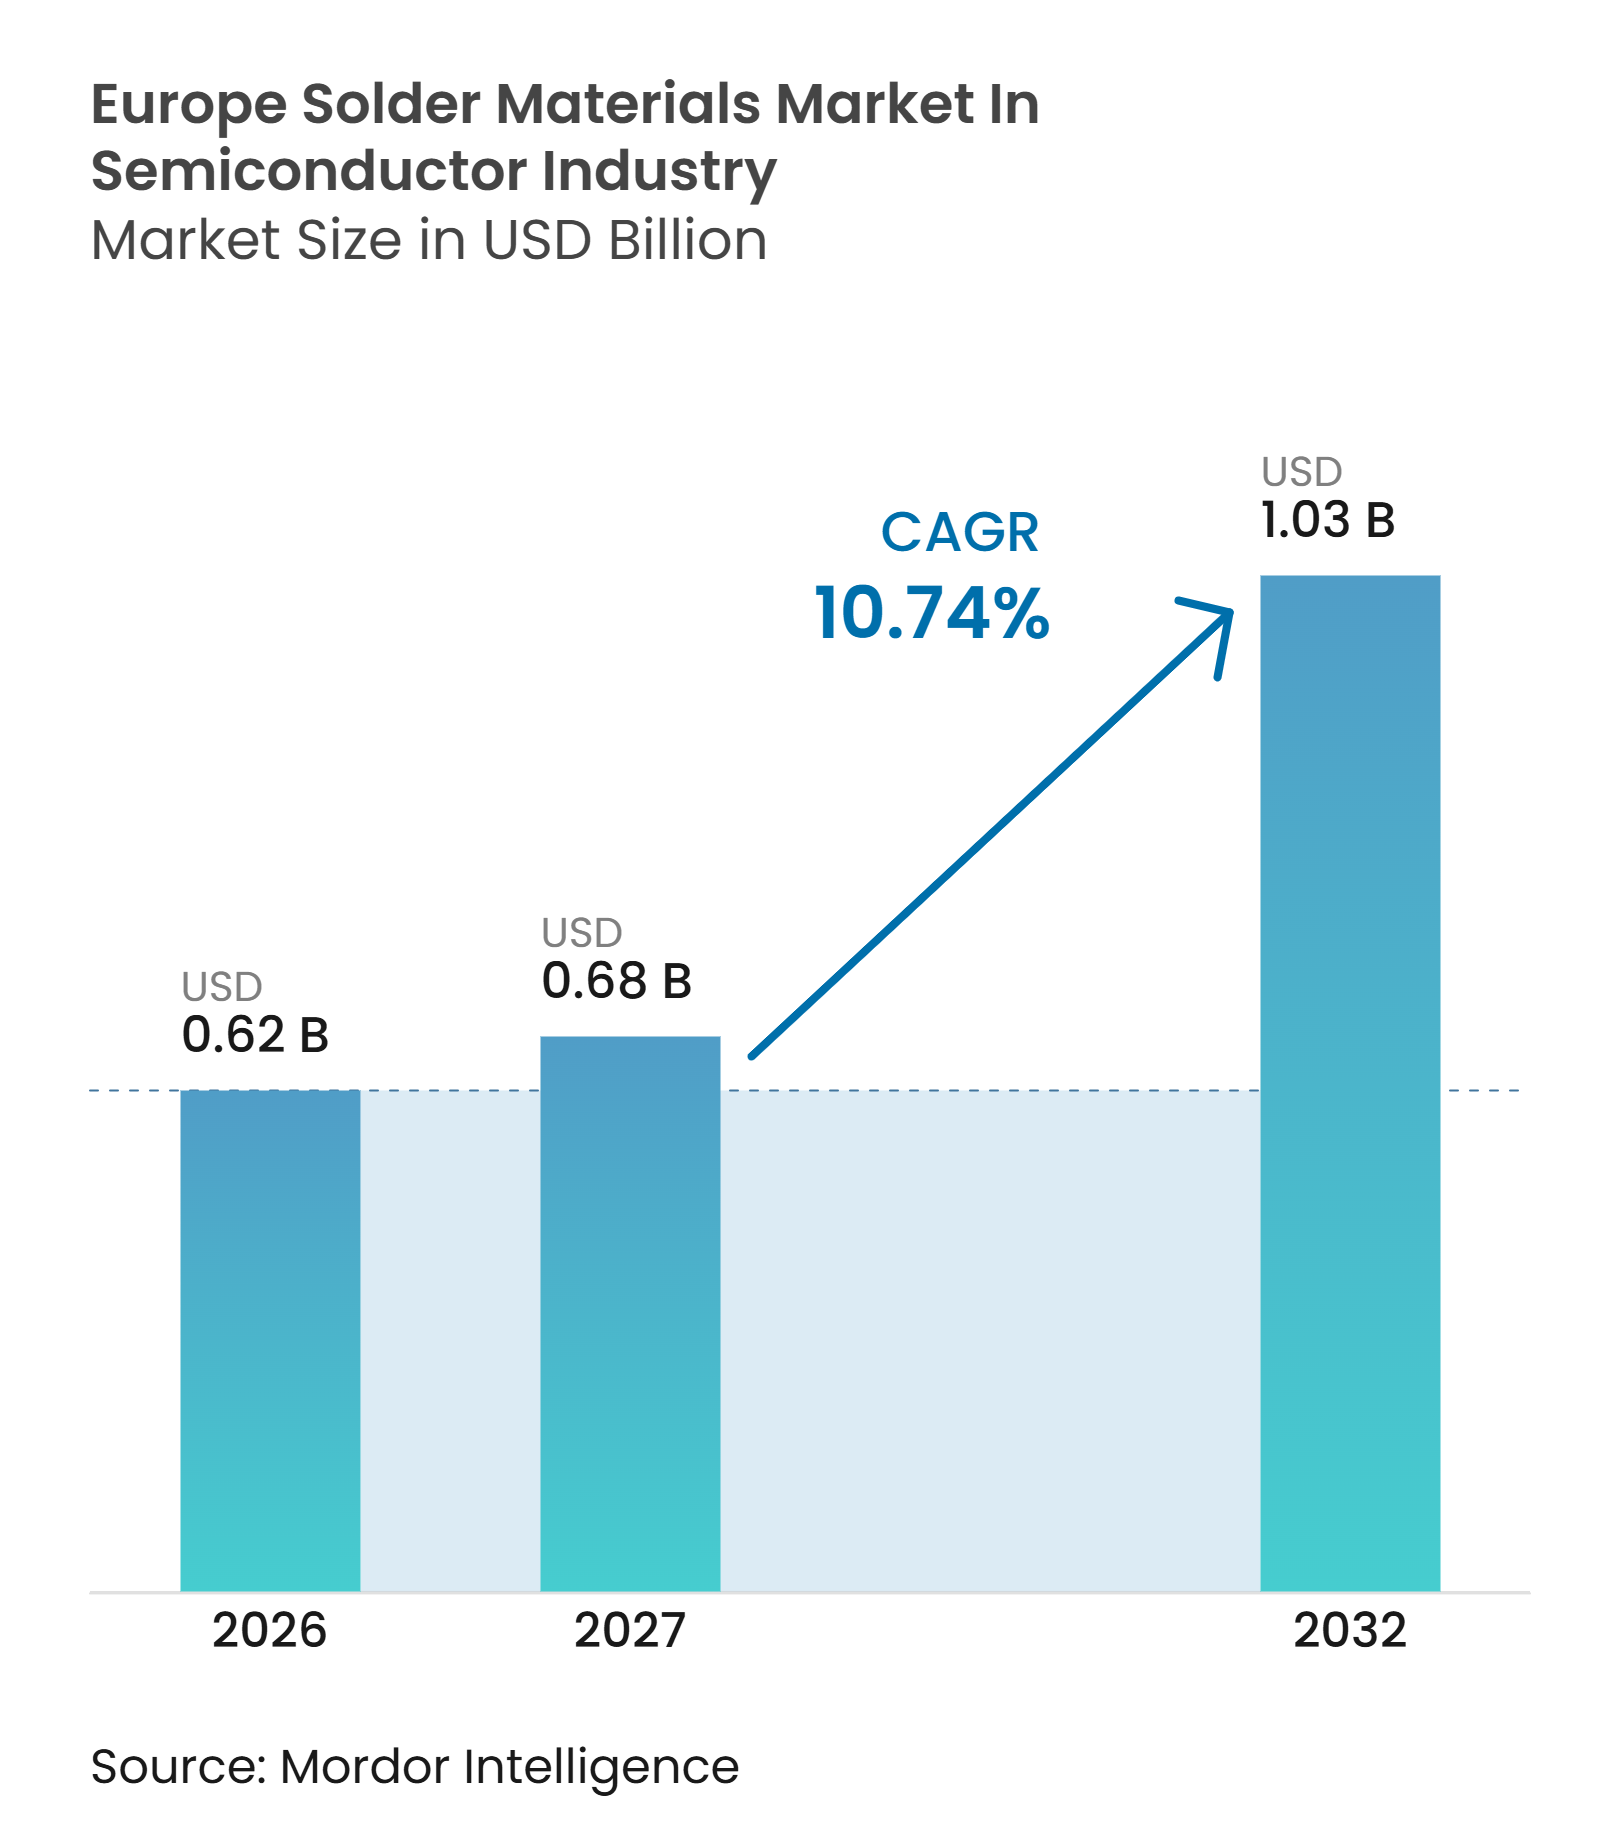
The Europe solder materials market in semiconductor industry size was valued at USD 0.62 billion in 2026 and estimated to expand from USD 0.69 billion in 2027 to reach USD 1.03 billion by 2032, at a CAGR of 10.74% during the forecast period (2027-2032). The Europe solder materials market in the semiconductor industry is shifting toward semiconductor packaging uses that require tighter process control and specialized materials, especially where automotive and industrial reliability requirements are central. Electric vehicle power systems, industrial power devices, and advanced packages are increasing demand for materials that can manage heat, current density, and repeated thermal cycling throughout the device operating life. The commercial position of suppliers depends less on standard alloy volumes and more on their ability to complete long qualification programs with automotive and industrial customers. The planned expansion of European semiconductor manufacturing also creates demand for solder paste, balls, preforms, wire, fluxes, and powder across wafer bumping, device packaging, and package assembly. Regulatory deadlines for lead-containing high-temperature solders are accelerating work on qualified lead-free alternatives, while sintering technologies remain a selective substitute in die attach applications.
Key Report Takeaways
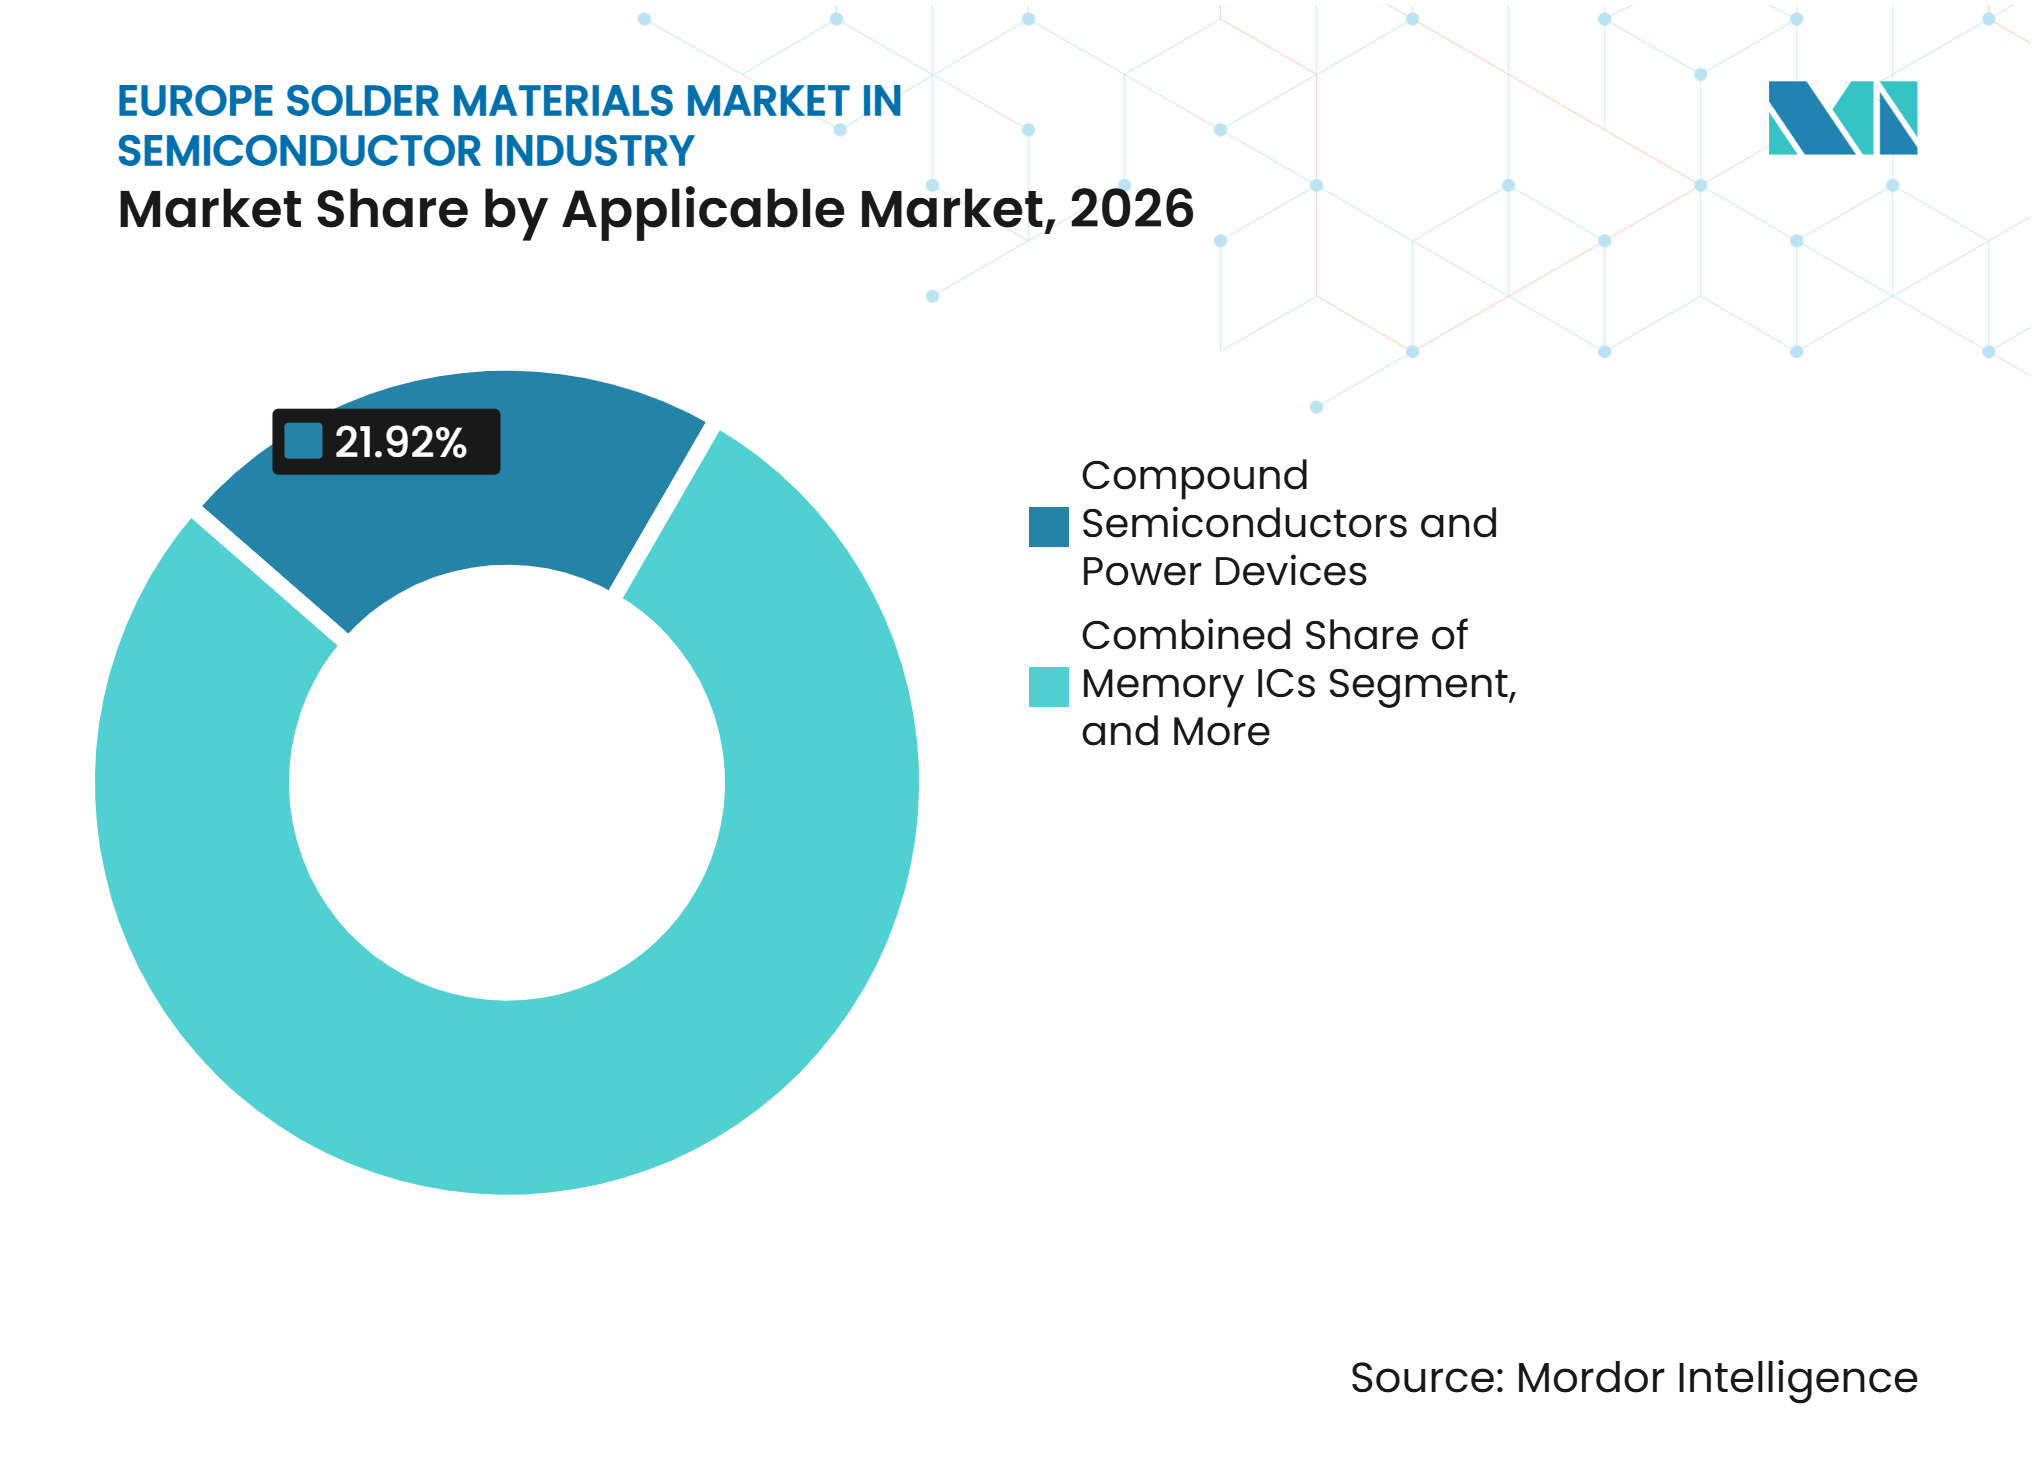
- By applicable market, compound semiconductors and power devices held 21.92% of the Europe solder materials market in semiconductor industry share in 2026 and are projected to expand at an 11.16% CAGR through 2032.
- By product form, solder paste held 37.71% of the Europe solder materials market in semiconductor industry size in 2026, while solder balls and spheres are expected to expand at an 11.23% CAGR through 2032.
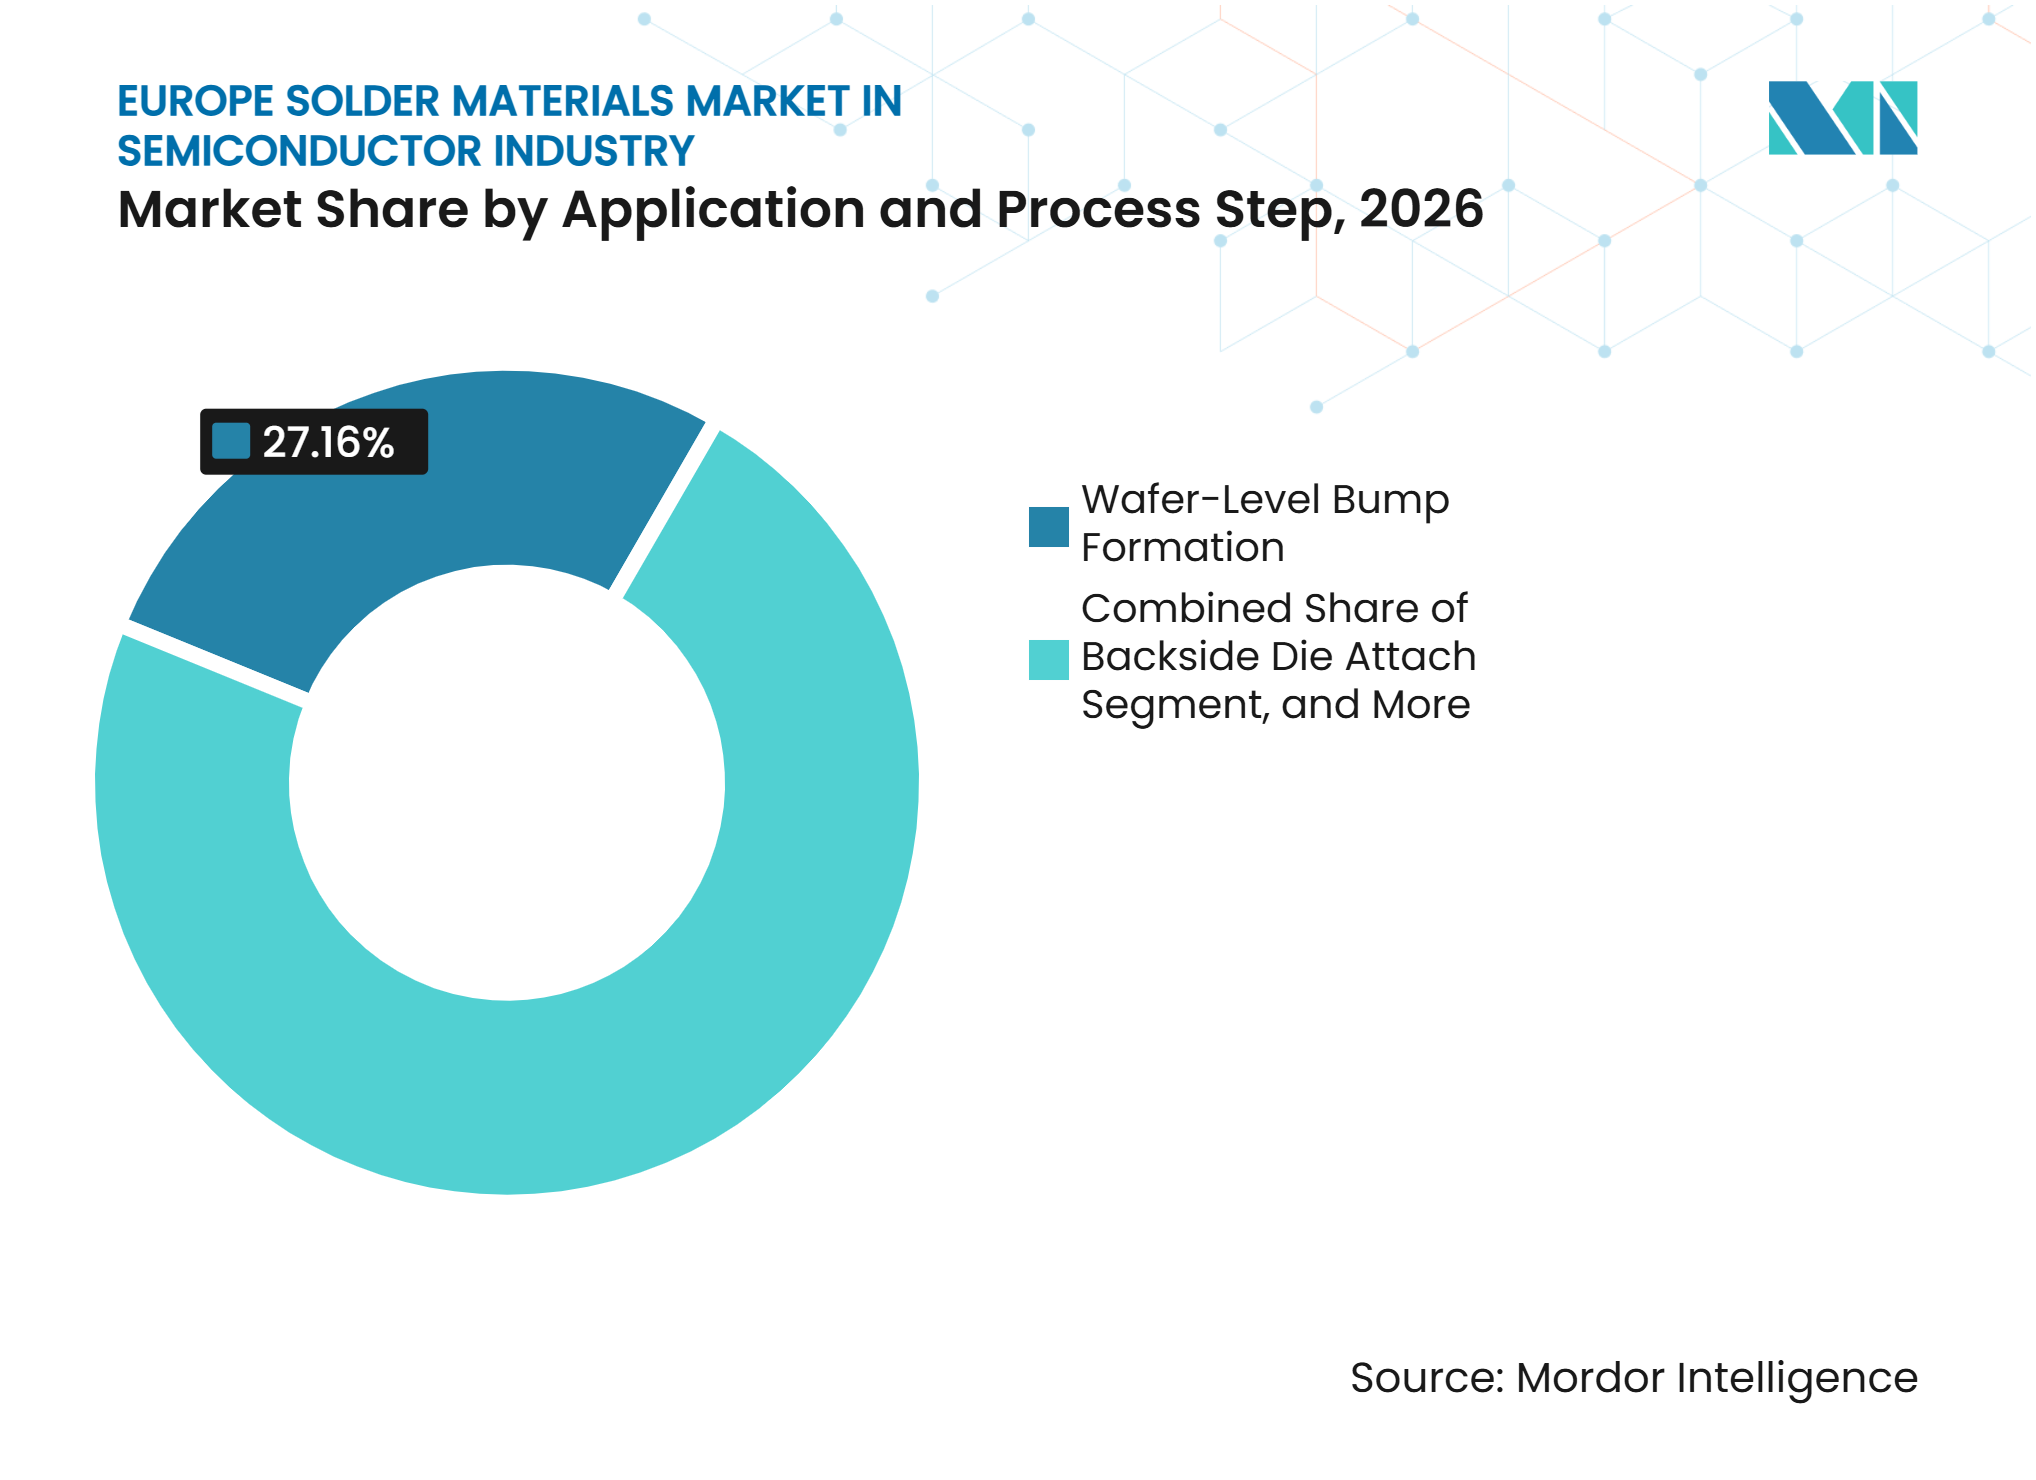
- By application and process step, wafer-level bump formation accounted for 27.16% of the Europe solder materials market in semiconductor industry size in 2026 and is projected to expand at an 11.47% CAGR through 2032.
- By geography, Germany held 30.74% of the Europe solder materials market in semiconductor industry share in 2026, while Italy is expected to expand at an 11.38% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Solder Materials Market in the Semiconductor Industry of Europe Solder Materials Market In Semiconductor Industry*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Automotive Electrification and Semiconductor Content Growth | +3.6% | Germany, France, Italy, Rest of Europe | Long term (≥ 4 years) |
| Lead-Free Material Adoption Under EU RoHS Requirements | +2.5% | Global, with regulatory mandate centered in EU | Short term (≤ 2 years) |
| Growth of Advanced Semiconductor Packaging and Fine-Pitch Interconnects | +1.9% | Germany, United Kingdom, Rest of Europe | Medium term (2-4 years) |
| Expansion of European Power Electronics and Compound Semiconductor Manufacturing | +1.6% | Italy, Germany, France | Long term (≥ 4 years) |
| Semiconductor Supply-Chain Localization and European Capacity Investment | +1.3% | Germany, France, Italy, Rest of Europe | Medium term (2-4 years) |
| Qualification Demand for High-Reliability Automotive and Industrial Devices | +0.8% | Germany, France, United Kingdom | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Automotive Electrification and Semiconductor Content Growth
Electric vehicle programs are increasing the importance of power modules, onboard chargers, DC-DC converters, and control systems in the Europe solder materials market for the semiconductor industry. These applications require interconnect materials that can withstand vibration and repeated temperature fluctuations over extended operating lifetimes, often within compact assemblies that place different materials under continuous mechanical stress. Automotive power packaging also requires higher-value material specifications than conventional consumer electronics assembly because process failures can compromise the reliability of the complete powertrain system. The resulting demand supports solder paste, preforms, and spheres qualified for low voiding and thermal fatigue performance. European automotive semiconductor activity is expected to expand significantly during the forecast period, with power electronics anticipated to demonstrate strong growth. This shift increases revenue intensity per packaged device, even when unit volumes do not grow at the same pace, and reinforces the importance of material suppliers that can support joint design and validation.
Lead-Free Material Adoption Under EU RoHS Requirements
The EU RoHS timetable is setting a clear development window for high-temperature solder formulations in the Europe solder materials market in the semiconductor industry. The European Commission adopted Delegated Directive (EU) 2025/1802 in September 2025 and replaced the earlier high-melting-temperature solder exemption with seven sub-entries that expire on December 31, 2027.[1] The change places lead-free qualification work at the center of supplier product plans for automotive and industrial semiconductor assembly, where established processes cannot be changed without detailed reliability evidence. Bosch Semiconductors reported that the DA5 Consortium assessed more than 210 candidate materials from 18 suppliers and selected more than 50 materials for further testing.[2] Its findings showed that a single lead-free material had not yet demonstrated general suitability across all power semiconductor die attach uses as of 2025. Suppliers that complete customer qualification before the exemption deadline can establish a durable position in applications where approved materials are difficult to replace and where a new approval can require both material and process testing.
Growth of Advanced Semiconductor Packaging and Fine-Pitch Interconnects
Fine-pitch assembly is raising the technical threshold for suppliers serving the Europe solder materials market in the semiconductor industry. Packaging roadmaps are moving toward much denser interconnect layouts, which require controlled particle size, stable printing behavior, suitable low-alpha performance, and careful control of paste transfer in small apertures. SEMI reports that advanced packaging is enabling new system capabilities through heterogeneous integration and higher interconnect density. This direction increases the use of specialized solder balls and pastes in wafer-level and flip-chip processes, where materials need to perform consistently at high placement density. MacDermid Alpha introduced ALPHA OM-377 in June 2026 for ultra-fine feature printing down to 008004 component sizes.[3] The need to meet these process requirements narrows the capable supplier base and supports application-engineering services alongside material sales, particularly when assemblers move to newer package architectures.
Expansion of European Power Electronics and Compound Semiconductor Manufacturing
Power electronics capacity is creating targeted demand for high-temperature interconnection materials across the Europe solder materials market in the semiconductor industry. STMicroelectronics is developing a fully integrated silicon carbide facility in Catania, Italy, supported by an Italian state aid measure approved by the European Commission. The company plans significant investment in the facility, which is expected to achieve substantial wafer production capacity at full scale. Silicon carbide devices require die attach and package materials that can manage higher operating temperatures and thermal conductivity requirements over extended operating cycles. The manufacturing buildout therefore favors qualified preforms, paste, and spheres over undifferentiated solder products, particularly in device and module applications with stringent reliability specifications. It also creates opportunities for suppliers that can support process development near new production sites and provide material samples during production ramp-up.
Restraints Impact Analysis of Europe Solder Materials Market in the Semiconductor Industry of Europe Solder Materials Market In Semiconductor Industry*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatility in Tin, Silver, Indium, and Other Alloying-Metal Prices | -1.6% | Global, with direct cost pass-through across all European countries | Short term (≤ 2 years) |
| Qualification Complexity for Lead-Free Solder in High-Reliability Applications | -1.1% | Germany, France, United Kingdom, Italy | Long term (≥ 4 years) |
| Substitution by Silver Sintering, Copper Sintering, and Adhesive Bonding | -0.7% | Germany, Italy, silicon carbide and gallium nitride power electronics hubs | Medium term (2-4 years) |
| Limited European Availability of Advanced Packaging Substrates and Bumping Capacity | -0.4% | United Kingdom, Rest of Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Volatility in Tin, Silver, Indium, and Other Alloying-Metal Prices
Alloy input costs remain an immediate restraint on margins in the Europe solder materials market in the semiconductor industry. Tin, silver, and indium are important inputs for several solder formulations, and their price movements affect production costs, contract pricing, inventory planning, and supplier sourcing decisions. The effect is especially material for SAC alloys because both tin and silver can alter the cost of the same formulation, limiting the natural protection that a single-metal exposure can provide. Suppliers cannot always pass through these costs immediately when customers have long qualification cycles and fixed supply agreements. This encourages procurement teams to seek longer supply contracts and encourages formulators to develop low-silver or silver-free alternatives that can satisfy customer reliability requirements. MacDermid Alpha presented ALPHA OM-100 SnCX 07 as a silver-free solder paste for high-reliability electronics assembly in 2026
Qualification Complexity for Lead-Free Solder in High-Reliability Applications
Material qualification can delay adoption of new products in the Europe solder materials market in the semiconductor industry. Automotive and industrial devices require evidence that solder joints can perform under high temperature, current, and mechanical stress through the expected operating life of the component. A 2025 study from the Institution of Engineering and Technology noted that high-temperature power module packaging requires carefully selected die attachment materials because reliability conditions are demanding. The DA5 Consortium did not identify a universal lead-free replacement for all power semiconductor die attach applications in its 2025 assessment. This creates an entry barrier because suppliers need strong application engineering resources, access to customer validation programs, and the ability to support testing at the assembly line. It can also limit supply flexibility when regulatory requirements require a rapid alloy reformulation, even when a technically promising material is available.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Solder Materials Market In Semiconductor Industry Segment Analysis
By Applicable Market:
Compound Semiconductors Lead Demand and ExpansionCompound semiconductors and power devices held 21.92% of the Europe solder materials market in semiconductor industry in 2026 and are projected to expand at an 11.16% CAGR through 2032. This segment combines the largest reported share with the fastest reported expansion among applicable markets. Silicon carbide traction inverters and gallium nitride charging systems require packaging materials that can tolerate demanding thermal and electrical conditions. Their assembly can require low-voiding solder, high-temperature preforms, and materials compatible with copper or direct-bonded-copper substrates. The Europe solder materials market in semiconductor industry benefits from the increasing use of these devices in electric vehicles and industrial power equipment.
Memory integrated circuits remain an important demand source because automotive electronics and data-intensive systems require reliable packaged memory. Logic and analog integrated circuits provide steady demand for paste and preforms, while sensors, MEMS, and RF devices add specialized demand where small packages and wafer-level assembly are important. Optical and photonic packages remain smaller in the current mix, but their use in data interconnects and lidar supports demand for preforms and low-alpha solder balls. IEC/EN 61249-2-21 continues to guide halogen-free and lead-free material requirements in electronic assemblies. These requirements make validated materials and process expertise central to the segment rather than simply alloy availability.



By Product Form:
Solder Paste Holds the Broadest Position While Solder Balls Gain SpeedSolder paste accounted for 37.71% of the Europe solder materials market size in 2026 because it is used across a broad range of assembly processes. It supports surface-mount reflow on power substrates, package assembly, and selected wafer bumping applications. Direct copper bonding and silver sintering can substitute for solder in specific die attach uses, but they do not replace paste in many package-level interconnect processes. Low-silver and silver-free SAC formulations are receiving attention because they can reduce exposure to alloy input costs. MacDermid Alpha stated that its ALPHA OM-100 SnCX 07 paste delivers reliability comparable with SAC formulations and up to 50% greater mechanical strain resistance.
Solder balls and spheres are expected to record an 11.23% CAGR through 2032, supported by WLCSP, fan-out wafer-level packaging, and BGA packages. Advanced computing and automotive electronics are increasing the need for dependable ball attachment across these package types. Low-alpha performance is increasingly relevant as memory and logic features become more sensitive to alpha-induced soft errors. MacDermid Alpha launched low-alpha tin plating solutions in 2025 for semiconductor packaging applications that require controlled alpha emissions. Solder preforms retain an important role in power electronics, while wire, standalone fluxes, and externally sold powder support wider use of paste, balls, and preforms.
By Application and Process Step:
Wafer-Level Bump Formation Sets the Technology PaceWafer-level bump formation held 27.16% of the Europe solder materials market size in 2026 and is expected to expand at an 11.47% CAGR through 2032. Its position reflects the role of bumping in flip-chip, WLCSP, interposer, and 2.5D or 3D integration designs. Smaller pitch requirements raise the need for consistent solder ball geometry and alloy performance. This process step also requires materials that maintain standoff height and resist electromigration at higher current densities. The Europe solder materials industry therefore places high value on process support for wafer-level bumping rather than on material supply alone.
Die-to-substrate interconnection through flip-chip uses solder balls and fluxes in C4 bumping for automotive, industrial, and RF packages. Package-to-board interconnection through BGA and CSP remains a high-volume, mature process, although larger copper-core ball designs create specialty demand where thermal management is required. Backside die attach faces substitution from silver and copper sintering, especially for silicon carbide and gallium nitride power devices. An IET study reported that copper-sintered die attachment provided substantially lower thermal resistance than transient liquid-phase sintering for comparable die sizes. Package sealing and component attachment use preforms and wire in hermetic, optical, and sensor packaging, subject to quality rules such as IATF 16949 and IPC J-STD-005.

Geography Analysis
Germany
Germany held 30.74% of regional demand in 2026, supported by automotive semiconductor assembly, power electronics, and fabrication investment. GlobalFoundries announced a EUR 1.1 billion (USD 1.21 billion), investment in October 2025 to expand Dresden beyond 1 million wafers per year by the end of 2028 for automotive, Internet of Things, and defense applications at 28/22 nm and 16/12 nm nodes. This capacity supports bumping materials and preforms at the fabrication and packaging stages. Heraeus Electronics and STANNOL strengthen the country's materials base, while IATF 16949 requirements reinforce the value of local application support.
Italy
Italy is projected to expand at an 11.38% CAGR through 2032, the fastest reported geographic rate in the Europe solder materials market in the semiconductor industry. The European Commission approved EUR 2 billion (USD 2.2 billion), in Italian aid for STMicroelectronics' planned 200 mm silicon carbide facility, which supports demand for high-temperature die attach, package sealing, and module interconnection materials. STMicroelectronics also stated that its Agrate Brianza 300 mm facility targets 4,000 wafers per week by 2027 for smart power and mixed-signal technologies. The parallel expansion of silicon carbide and silicon capacity diversifies local demand across several solder formats, while EU Chips Act support and RoHS requirements shape the materials qualification path.
Western Markets and Emerging Hubs
The United Kingdom is expanding its advanced packaging infrastructure through the National Advanced Semiconductor Packaging and Integration Centre near Glasgow, which provides wafer preparation, die attach, interconnect, encapsulation, assembly, and testing capabilities. Custom Interconnect Limited commissioned a PacTech solder ball laser reflow system to support wafer, interposer, flip-chip, wafer-level chip-scale package, and ball grid array applications. France supports packaging demand through STMicroelectronics’ Crolles fabrication facility and its co-investment program with GlobalFoundries. The Netherlands, Belgium, and Austria contribute specialized clusters through ASML, ams OSRAM, and NXP, with demand driven by photonics packaging and automotive integrated circuits. Russia remains constrained by export controls and limited access to advanced packaging technologies, reducing its contribution to future European demand.
Competitive Landscape
Market Concentration
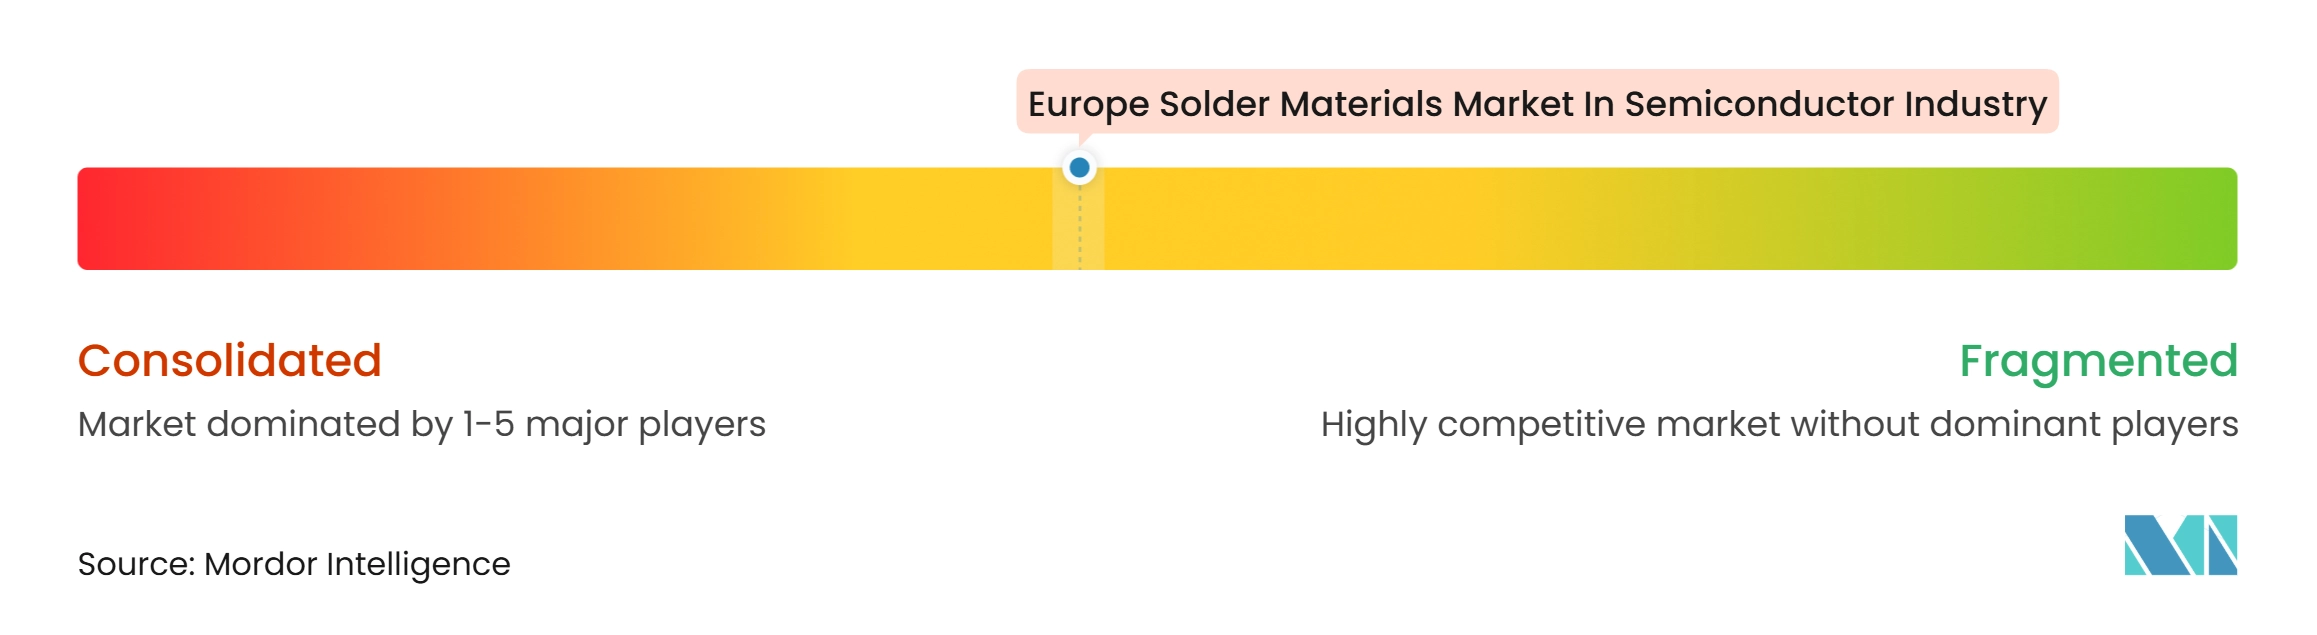
The Europe solder materials market in semiconductor industry shows moderate concentration among tier-1 formulators. Henkel AG and Co. KGaA, MacDermid Alpha Electronics Solutions, Heraeus Electronics, Indium Corporation, and Senju Metal Industry compete through alloy intellectual property, flux chemistry, and application engineering. Customer qualification requirements can protect an approved material for several years because replacement involves extensive testing and production validation. Heraeus Electronics, MacDermid Alpha Electronics Solutions, and Henkel concluded patent infringement and nullity proceedings against Senju Group in Germany in February 2025. The case concerned Senju's M794 alloy and patent EP 1 617 968 B1 covering the Innolot lead-free alloy system.
Balver Zinn Josef Jost GmbH and STANNOL GmbH and Co. KG serve niche positions in wire, flux, and standard alloy products for industrial and power electronics customers. Their proximity to European customers can support responsive technical service and regional supply. The Europe solder materials market in semiconductor industry has open opportunities in lead-free high-temperature die attach, ultra-fine-pitch solder balls, and hybrid assembly flows that combine sintering and solder materials. Henkel has developed copper sintering material with thermal conductivity above 300 W/(m·K) for copper lead frames and silicon carbide power modules. This move shows that suppliers are addressing the boundary between sintering and solder-based interconnect approaches rather than treating them as entirely separate markets.
MacDermid Alpha launched ALPHA OM-377 in June 2026 to address ultra-fine feature printing in dense electronic assemblies. It also launched ATROX CD 560-1 in June 2026 as a zero-PFAS alternate silver filler die attach paste for metal leadframe packages. These launches reflect a focus on process performance, raw-material exposure, and evolving environmental requirements. Larger firms can also use data-led formulation tools to shorten development cycles, while smaller formulators may have fewer resources for comparable research programs.
Leaders of Europe Solder Materials Market In Semiconductor Industry
-
Henkel AG & Co. KGaA
-
Indium Corporation
-
Illinois Tool Works Inc.
-
Senju Metal Industry Co., Ltd.
-
MacDermid Alpha Electronics Solutions
- *Disclaimer: Major Players sorted in no particular order
Europe Solder Materials Market In Semiconductor Industry Companies Covered in this Report
- Henkel AG & Co. KGaA
- Indium Corporation
- Illinois Tool Works Inc.
- Senju Metal Industry Co., Ltd.
- KOKI Company Ltd.
- MacDermid Alpha Electronics Solutions
- AIM Solder
- Heraeus Electronics
- Balver Zinn Josef Jost GmbH
- Nihon Superior Co., Ltd.
- Tamura Corporation
- Qualitek International Inc.
- STANNOL GmbH & Co. KG
- ZESTRON
- Interflux Electronics N.V.
- Fusion Inc.
- SHENMAO Technology Inc.
- Nihon Almit Co., Ltd.
- Inventec Performance Chemicals
- DKL Metals Ltd.
Recent Industry Developments in Europe Solder Materials Market In Semiconductor Industry
- November 2026: Henkel Adhesive Technologies commercialized Loctite Bergquist TGR 5000SF, a high-performance thermal grease engineered for high-power components in critical semiconductor applications, extending Henkel's portfolio of thin bond-line, low-thermal-impedance thermal interface materials targeting AI hardware, power electronics, and EV powertrain modules.
- October 2026: Henkel launched the Loctite ABLESTIK CDF 900 series, a next-generation conductive die attach film with thermal conductivity exceeding 8 W/(m·K), specifically designed to address thermal and stress challenges in AI, 5G, and high-performance computing semiconductor packages.
- June 2026: MacDermid Alpha Electronics Solutions launched ATROX CD 560-1, a zero-PFAS alternate silver filler die attach paste designed for metal leadframe packages and high-speed automated dispensing, addressing silver price volatility and PFAS elimination requirements in European electronics manufacturing.
- June 2026: MacDermid Alpha Electronics Solutions introduced ALPHA OM-377, a no-clean solder paste engineered for ultra-fine feature printing down to 008004 component sizes, delivering consistent paste transfer efficiency across fine-pitch designs and improved first-pass yield through reduced Head-in-Pillow and Non-Wet Open defects.
Scope of Report on Europe Solder Materials Market In Semiconductor Industry
The Europe Solder Materials Market in Semiconductor Industry refers to the regional market for solder-based interconnect materials used in semiconductor packaging, wafer-level assembly, flip-chip bonding, and advanced IC packaging, including solder balls, solder paste, solder wire, solder preforms, fluxes, and specialized alloys serving Europe’s semiconductor packaging, automotive electronics, aerospace/defense, industrial automation, and high-reliability electronics sectors.
The Europe Solder Materials Market in Semiconductor Industry Report is Segmented by Applicable Market (Logic ICs, Memory ICs, Compound Semiconductors and Power Devices, Analog ICs, Sensors, MEMS and RF Devices, and Optical and Photonic Devices), Product Form (Solder Paste, Solder Balls and Spheres, Solder Preforms, Solder Wire, Solder Fluxes, Standalone, and Solder Powder, Externally Sold), Application and Process Step (Wafer-Level Bump Formation, Die-to-Substrate Interconnection, Conventional Flip-Chip, Package-to-Board Interconnection, BGA and CSP Ball Attach, Backside Die Attach, and Package Sealing and Component Attachment), and Geography (Germany, United Kingdom, France, Italy, Russia, and Rest of Europe). The Market Forecasts Are Provided in Terms of Value (USD).
Segmentation Overview
| Logic ICs |
| Memory ICs |
| Compound Semiconductors and Power Devices |
| Analog ICs |
| Sensors, MEMS and RF Devices |
| Optical and Photonic Devices |
| Solder Paste |
| Solder Balls and Spheres |
| Solder Preforms |
| Solder Wire |
| Solder Fluxes, Standalone |
| Solder Powder, Externally Sold |
| Wafer-Level Bump Formation |
| Die-to-Substrate Interconnection, Conventional Flip-Chip |
| Package-to-Board Interconnection, BGA and CSP Ball Attach |
| Backside Die Attach |
| Package Sealing and Component Attachment |
| Germany |
| United Kingdom |
| France |
| Italy |
| Russia |
| Rest of Europe |
| By Applicable Market | Logic ICs |
| Memory ICs | |
| Compound Semiconductors and Power Devices | |
| Analog ICs | |
| Sensors, MEMS and RF Devices | |
| Optical and Photonic Devices | |
| By Product Form | Solder Paste |
| Solder Balls and Spheres | |
| Solder Preforms | |
| Solder Wire | |
| Solder Fluxes, Standalone | |
| Solder Powder, Externally Sold | |
| By Application and Process Step | Wafer-Level Bump Formation |
| Die-to-Substrate Interconnection, Conventional Flip-Chip | |
| Package-to-Board Interconnection, BGA and CSP Ball Attach | |
| Backside Die Attach | |
| Package Sealing and Component Attachment | |
| By Geography | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe |
Key Questions Answered in the Report
What is the Europe solder materials market in semiconductor industry size?
The market was valued at USD 0.62 billion in 2026 and is estimated to reach USD 1.03 billion by 2032 at a 10.74% CAGR.
Which applicable market leads demand for semiconductor solder materials in Europe?
Compound semiconductors and power devices held 21.92% of demand in 2026 and are projected to expand at an 11.16% CAGR through 2032.
Which solder product form has the largest position in Europe?
Solder paste held 37.71% of demand in 2026 because it supports several assembly and packaging processes.
What is driving demand for solder balls and spheres?
WLCSP, fan-out wafer-level packaging, and BGA applications are expected to support an 11.23% CAGR for solder balls and spheres through 2032.
Why do EU RoHS rules matter for semiconductor solder suppliers?
The revised high-temperature solder exemption entries expire on December 31, 2027, making qualified lead-free alternatives important for high-reliability applications.
Which country has the strongest position in Europe?
Germany held 30.74% of demand in 2026, while Italy is projected to record the fastest geographic expansion at an 11.38% CAGR through 2032.