
Europe Inspection Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 33.84 Billion |
| Market Size (2027) | USD 35.76 Billion |
| Market Size (2032) | USD 46.71 Billion |
| Growth Rate (2027 - 2032) | 5.49 % |
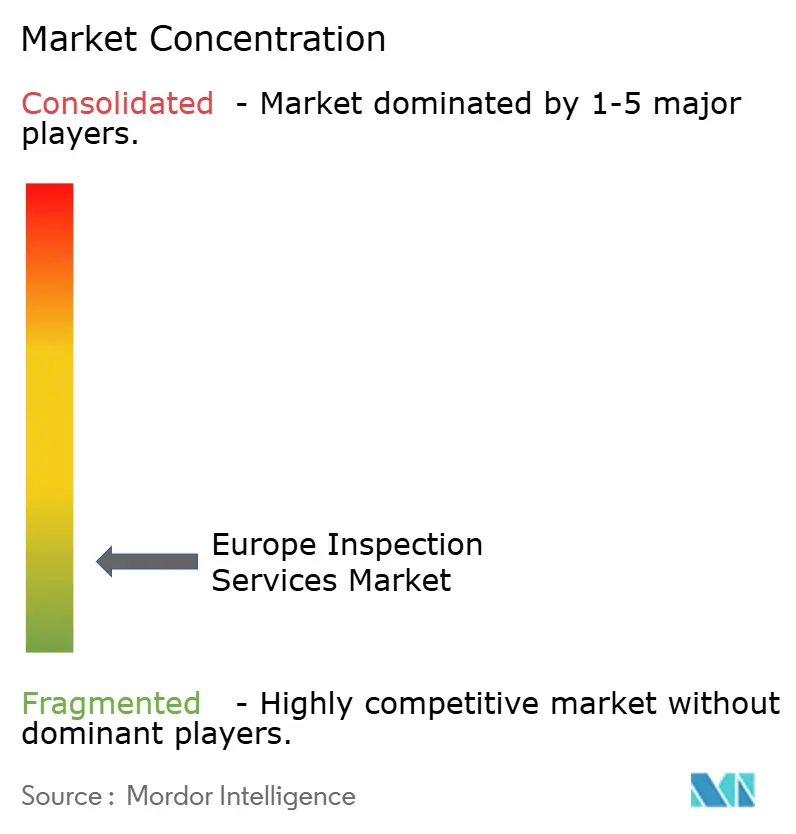
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Inspection Services Market Analysis by Mordor Intelligence
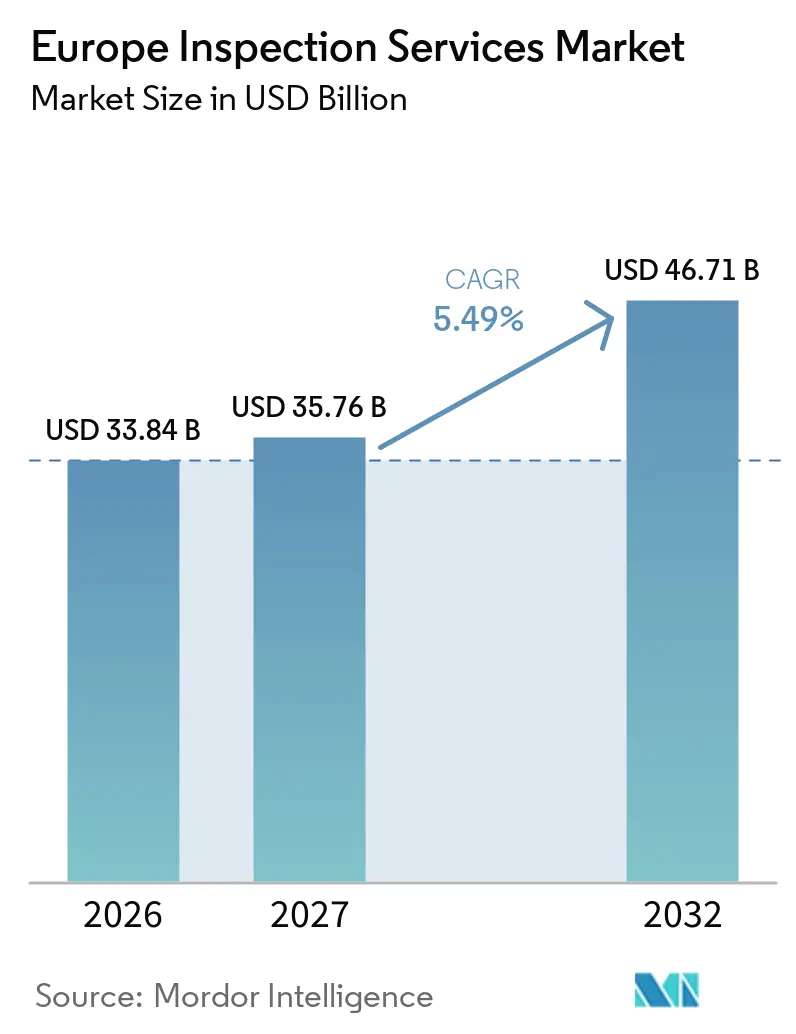
The Europe Inspection Services Market size is expected to increase from USD 33.84 billion in 2026 to USD 35.76 billion in 2027 and reach USD 46.71 billion by 2032, growing at a CAGR of 5.49% over 2027-2032.
The Europe inspection services market is supported by tighter product compliance requirements, investment in energy and transport assets, and wider use of accredited external providers. Digital Product Passport requirements can create recurring verification work because manufacturers need reliable records across product supply chains. Asset owners are also extending the life of infrastructure and industrial equipment, which increases the need for condition assessments and periodic integrity checks. In addition, the expansion of renewable energy installations, electricity transmission networks, rail infrastructure, and industrial modernization projects is creating demand for specialized inspections throughout asset construction, commissioning, and operation. Inspection providers are increasingly expected to verify equipment performance, identify defects, assess material quality, and document compliance with applicable technical and safety standards. These requirements are particularly relevant for complex assets that operate under demanding environmental conditions or require regular maintenance to minimize unplanned downtime. The growing emphasis on traceability and supplier accountability is also encouraging manufacturers to use independent inspection services at multiple stages of production and distribution.
Key Report Takeaways
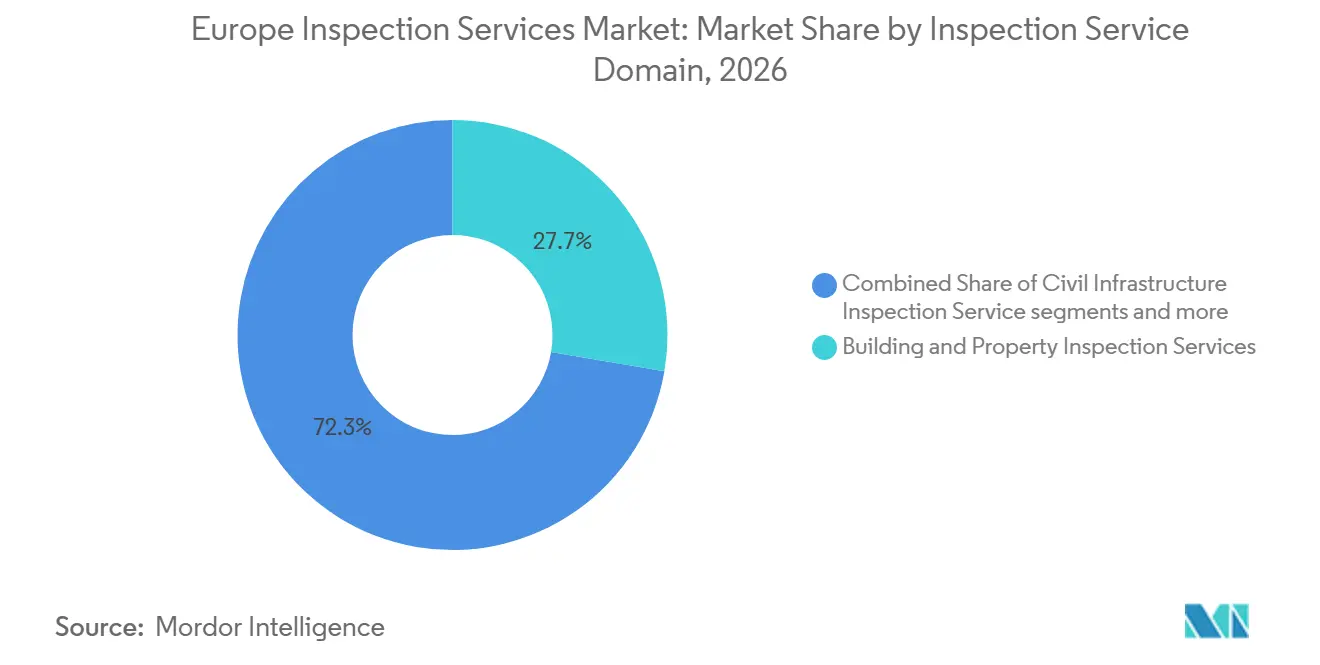
- By inspection service domain, building and property inspection services held 27.7% of the Europe inspection services market share in 2026, while civil infrastructure inspection services are forecast to grow at a 6.6% CAGR through 2032.
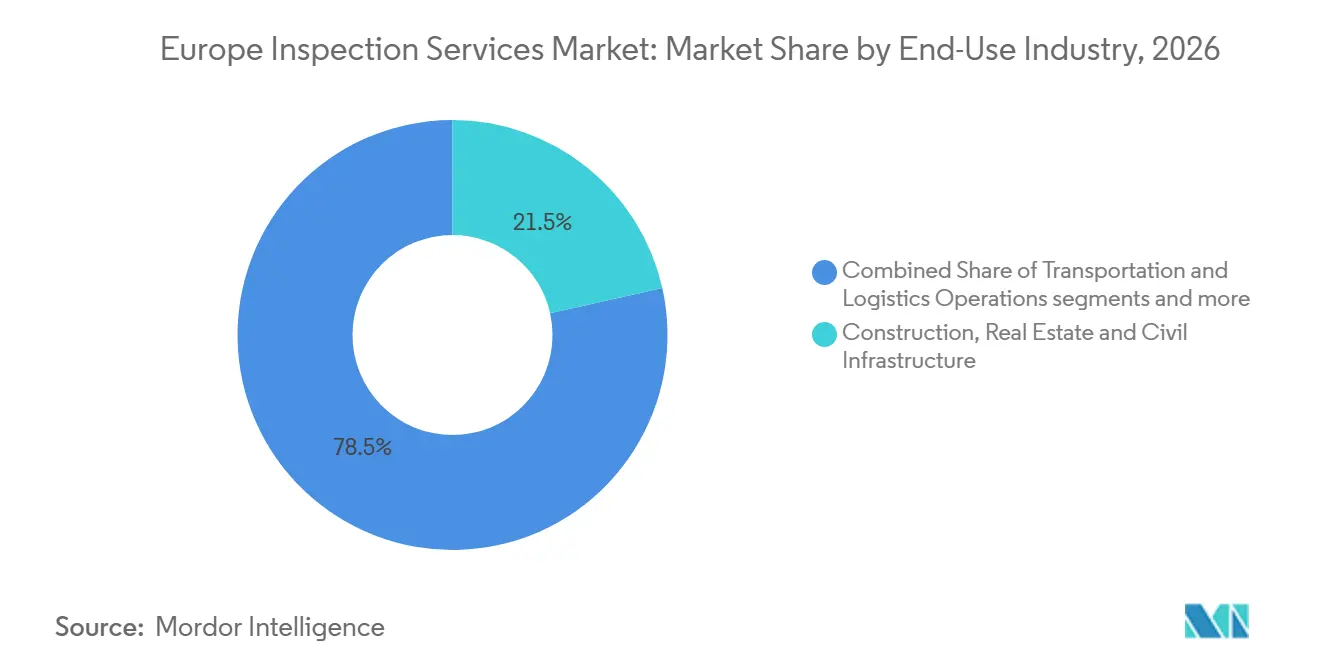
- By end-use industry, construction, real estate, and civil infrastructure accounted for 21.5% of the Europe inspection services market size in 2026 and are projected to grow at a 6.1% CAGR through 2032.
- By geography, Germany held 19.5% of the Europe inspection services market share in 2026, while the United Kingdom is forecast to expand at an 8.7% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Inspection Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EU Product Compliance and Market-Surveillance Intensification | +1.1% | EU-wide, with enforcement intensity concentrated in Germany, France, and the Netherlands | Short term (≤ 2 years) |
| Aging Industrial, Energy, and Transport Assets | +0.9% | United Kingdom North Sea, Germany's chemical-industrial belt, Eastern European industrial hubs, and Benelux petrochemical clusters | Medium term (2-4 years) |
| Renewable-Energy and Grid-Modernization Build-Out | +0.7% | Northern and Western Europe, including Germany, the Netherlands, the United Kingdom, Ireland, and Denmark | Medium term (2-4 years) |
| Outsourcing of Liability-Critical Inspection Work | +0.5% | Western European manufacturing and energy corridors, with broader global relevance | Long term (≥ 4 years) |
| Aerospace, Rail, and Defense MRO Intensity | +0.4% | Germany, United Kingdom, France, Italy, Spain, Poland, and the Netherlands | Medium term (2-4 years) |
| Digital Product Passports and Traceable Inspection Data | +0.3% | EU-wide, with future coverage across batteries, textiles, electronics, tires, and furniture | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
EU Product Compliance and Market-Surveillance Intensification
The Europe inspection services market benefits when product compliance rules require manufacturers and importers to document and verify conformity. Regulation (EU) 2019/1020 establishes the EU framework for market surveillance and product compliance, which creates a continuing need for inspection bodies that can support regulated economic operators.[1] The General Product Safety Regulation requires economic operators to maintain product and traceability information, which extends the recordkeeping burden across product supply chains.[2] These obligations make inspection demands less discretionary because companies cannot postpone legally required conformity work when trading conditions weaken. The planned consolidation of CE-marking and conformity processes could further increase the value of providers that work across several product categories. The Europe inspection services market also gains from more consistent enforcement because customers need inspection partners that can apply requirements across several EU jurisdictions.
Aging Industrial, Energy, and Transport Assets
Aging industrial, energy, and transport assets are expanding the inspection workload for owners who need to manage safety, reliability, and service life. The EU-funded H2PipelineInspect project is developing ultrasonic guided-wave techniques for identifying hydrogen-induced cracks in pipelines, supporting inspection needs as parts of the gas network are adapted for hydrogen use.[3] The EU-funded TUBERS project also addresses robotic inspection and repair for water pipelines, reflecting the operational importance of assessing buried and difficult-to-access utility assets. These programs point to demand for risk-based inspections, fitness-for-service assessments, and ongoing structural health monitoring rather than only fixed-interval checks. The Europe inspection services market can therefore capture work throughout an asset’s operating life, including work that supports life extension and renewal decisions. This pattern is especially relevant in process industries, utilities, and transport networks, where failure can result in high safety and service costs.
Renewable-Energy and Grid-Modernization Build-Out
Renewable-energy projects and power-grid upgrades create inspection work from commissioning through long-term operation. EirGrid announced a procurement program exceeding EUR 1 billion (USD 1.2 billion) for offshore-grid operation and maintenance activities, subsea inspection and repair, and asset health monitoring. The program indicates the scale of specialist work associated with offshore transmission infrastructure in the Europe inspection services market. New offshore connections require structural, electrical, cable, and subsea expertise that differs from conventional building inspections. The European Commission’s cable-security action has also increased attention on the physical integrity and resilience of submarine infrastructure. Providers with renewable-energy and marine capabilities can compete for recurring inspection contracts as these assets move from construction into operation. Northern and Western European markets are particularly relevant because they combine offshore energy development with established grid networks.
Outsourcing of Liability-Critical Inspection Work
The Europe inspection services market is also shaped by the movement from in-house verification to accredited external providers. External specialists give smaller manufacturers access to techniques such as CT scanning, phased-array ultrasonics, and creep testing without the cost of owning those capabilities. The EU-supported ZDZW project examined smart inspection services for manufacturing, including service approaches that lower adoption barriers for smaller businesses. Outsourcing can also help customers manage compliance responsibility because an accredited provider can document the inspection process and conformity outcome. Providers are increasingly pairing site inspections with digital compliance records and customer dashboards, which makes their services more continuous. This creates an opportunity in the Europe inspection services market for firms that can deliver technical work, evidence management, and reliable customer support through one contract.
Restraints Impact Analysis of Europe Inspection Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Certified NDT and Specialist Inspectors | -0.8% | Pan-European, most acute in aerospace NDT hubs and offshore energy inspection clusters | Short term (≤ 2 years) |
| High Cost of Advanced Inspection Technology for SMEs | -0.6% | EU-wide, with a greater effect on Eastern European industrial SMEs and lower-capital markets | Medium term (2-4 years) |
| Cross-Border Standards and Accreditation Friction | -0.4% | Intra-EU markets, including Benelux, the Nordic-Baltic corridor, and Central European manufacturing zones | Medium term (2-4 years) |
| Cybersecurity and Evidentiary Risk in Remote Inspection | -0.3% | Digital-inspection intensive markets, including Germany, the Netherlands, the United Kingdom, and Scandinavian countries | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Shortage of Certified NDT and Specialist Inspectors
The supply of qualified nondestructive testing personnel remains a constraint for the Europe inspection services market. EN ISO 9712 sets requirements for qualification and certification of personnel who perform nondestructive testing, and senior qualifications require practical experience that cannot be created quickly. The American Society for Nondestructive Testing has highlighted the need to build skills, trust, and technology capacity across the digital NDE ecosystem. A limited supply of experienced inspectors can lengthen project schedules and increase the cost of complex work in aerospace, energy, and offshore sectors. Automation can support routine tasks, but human professionals remain responsible for judgments and sign-off in many regulated applications. Inspection firms are therefore likely to place greater weight on training, retention, and internal technical academies.
High Cost of Advanced Inspection Technology for SMEs
High equipment costs can prevent small and medium-sized enterprises from using advanced inspection tools. The ZDZW project identifies smart inspection services as a way to make advanced manufacturing inspection more accessible to smaller firms. EFFRA has identified financial constraints and limited digital infrastructure as barriers to the deployment of zero-defect approaches in European manufacturing. The Machinery Regulation adds requirements related to protecting software and data that are relevant to machinery conformity, increasing compliance needs for connected systems. Smaller companies can be exposed to the same future compliance expectations as larger firms while having less capital to invest in equipment and secure digital infrastructure. Service-based inspection models can reduce this barrier, but providers still need to make the technical and cybersecurity investments that underpin the service.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Inspection Services Market Segment Analysis
By Inspection Service Domain:
Building Services Lead, While Civil Infrastructure ExpandsBuilding and property inspection services held 27.7% of the Europe inspection services market share in 2026. Recurring structural assessments, energy-performance certificates, mechanical, electrical, and plumbing checks, and handover inspections support this leading position. These requirements cannot usually be postponed by property owners or construction firms, which makes revenue more stable than activity tied only to new projects. Property transactions also require technical due diligence and condition information, adding to the Europe inspection services market size associated with buildings. The Construction Products Regulation provides a harmonized framework for marketing construction products and supports the wider conformity environment surrounding construction activity.
Civil infrastructure inspection services are forecast to expand at a 6.6% CAGR through 2032, the highest rate among service domains. Aging roads, bridges, tunnels, water networks, and new renewable-energy assets create work in design, commissioning, operation, rehabilitation, and life-extension programs. Industrial facilities and fixed asset inspection services also remain important for pressure vessels, pipelines, storage tanks, and installed process equipment in energy and chemical settings. Manufactured products, transport assets, commodities, and site-process services add demand through conformity checks, periodic vehicle testing, cargo verification, food hygiene audits, and environmental compliance work. The European Accreditation multilateral agreement supports the mutual recognition of accredited results and helps providers serve cross-border projects across the Europe inspection services market.

By End-Use Industry:
Construction Holds the Largest Position and the Highest Growth RateConstruction, real estate, and civil infrastructure accounted for 21.5% of the Europe inspection services market share in 2026 and are forecast to grow at a 6.1% CAGR through 2032. New-build certification, transaction due diligence, and structural safety reviews provide a stable source of work for this end-use category. Offshore wind, solar facilities, and hydrogen networks also require commissioning and integrity work beyond conventional construction inspections. These projects can expand the Europe inspection services market size for providers that combine building knowledge with energy and infrastructure capabilities. The revised Construction Products Regulation reinforces the conformity framework affecting products and projects in this end-use area.
Power generation, renewable energy, and utilities require specialized checks for offshore systems, grids, battery storage, and hydrogen infrastructure. Oil and gas, refining, manufacturing, healthcare, pharmaceuticals, transport, food, retail, mining, and household services provide additional demand across the Europe inspection services market. Asset life-extension programs support work in process industries, while supplier audits, product conformity, and in-process quality inspections support manufacturing. Medical-device conformity and quality requirements create recurring work for notified bodies, including under Commission Implementing Regulation (EU) 2026/977. Alstom’s planned Rybnik locomotive maintenance center also reflects rail maintenance and inspection demand in Poland.
Geography Analysis
Germany, France and Italy Inspection Services Market
Germany held 19.5% of the Europe inspection services market share in 2026. Its engineering, industrial, and automotive base supports product safety, roadworthiness, energy systems, and chemical plant integrity work. DEKRA reported EUR 4.4 billion (USD 5.2 billion) in group revenue in 2025, and its Germany, Switzerland, and Austria region generated EUR 2.7 billion (USD 3.2 billion). The country’s established technical bodies and dense industrial base support a broad inspection ecosystem. France combines manufacturing compliance, infrastructure certification, and service providers with European networks. SOCOTEC United Kingdom & Ireland acquired LSTC Group in October 2025, adding electrical transmission and distribution inspection capability for grid-safety work. Italy, Spain, and the Netherlands have distinct demand pools in construction, wind energy, North Sea infrastructure, and petrochemicals. Bureau Veritas completed the acquisition of Contec AQS and related businesses in Italy in January 2025 to strengthen its building and infrastructure position. Poland is developing through infrastructure investment and rail maintenance demand, including Alstom’s Rybnik project.
United Kingdom and Russia Inspection Services Market
The United Kingdom is forecast to grow at an 8.7% CAGR through 2032, the fastest national rate in the Europe inspection services market. The United Kingdom retains major inspection activity through pressure-system and lifting-equipment requirements, while energy-transition assets add grid and infrastructure needs. Its development plan and 2025 investment program support transportation, energy, mining, healthcare, and urban projects. Russia is more self-contained because of geopolitical conditions, while the Rest of Europe includes Nordic offshore-energy work, Central and Eastern European infrastructure activity, and smaller Western European markets. EirGrid’s offshore-grid procurement program illustrates the potential scale of specialist work in peripheral European markets.
Competitive Landscape
The Europe inspection services market exhibits a low level of market concentration. SGS, Bureau Veritas, Intertek, TÜV SÜD, DEKRA, TÜV Rheinland, DNV, and Applus+ form the leading competitive tier. Accreditation is fundamental because regulated customers need providers that can demonstrate independence, competence, and consistent methods. The European Accreditation Multilateral Agreement supports recognition of accredited conformity assessments across national systems. Larger businesses benefit from broad accreditation networks, while focused specialists can still compete where they have deeper technical expertise.
Digital services are becoming more important after a provider meets core accreditation requirements. TÜV Rheinland has developed battery-passport work using QR-coded lifecycle data for automotive customers, and TÜV SÜD acquired SustainCERT in July 2026 for digital carbon-verification capabilities. These moves seek recurring data and verification revenue in addition to one-time field assignments. Bureau Veritas agreed to acquire Lotusworks in April 2026, adding commissioning and quality assurance capabilities for data centers and semiconductor facilities. Lotusworks had EUR 131 million (USD 154.1 million) in 2025 revenue and 750 employees, which increases Bureau Veritas’s exposure to complex assets with specialized inspection needs.
RINA, Element Materials Technology, Testia, and TWI compete in marine inspection, materials testing, aerospace NDT, and research-backed welding work. They differentiate through technical knowledge, speed, and tailored service design. The Europe inspection services market has room for accessible digital inspection services for smaller customers and independent verification of Digital Product Passport data. Secure record management, qualified people, accredited scope, and customer trust will remain central competitive requirements.
Europe Inspection Services Industry Leaders
-
SGS SA
-
Bureau Veritas SA
-
Intertek Group plc
-
TÜV SÜD AG
-
DEKRA SE
- *Disclaimer: Major Players sorted in no particular order
Europe Inspection Services Market Companies Covered in this Report
- SGS SA
- Bureau Veritas SA
- Intertek Group plc
- TÜV SÜD AG
- DEKRA SE
- TÜV Rheinland AG
- DNV AS
- Eurofins Scientific SE
- Applus+ Servicios Tecnológicos S.L.U.
- TÜV NORD GROUP
- Kiwa N.V.
- Lloyd's Register Group Limited
- RINA S.p.A.
- UL Solutions Inc.
- Element Materials Technology Group Ltd.
- MISTRAS Group, Inc.
- SOCOTEC Group SA
- VDE Testing and Certification Institute
- Institut de Soudure Groupe
- Testia
- TWI Ltd
Recent Industry Developments in Europe Inspection Services Market
- July 2026: TÜV SÜD acquired SustainCERT, a Luxembourg-based digital monitoring, reporting, and verification platform serving regulated and voluntary carbon markets. The acquisition positions TÜV SÜD to compete in digital environmental assurance and extends its verification portfolio into software-enabled recurring-revenue services.
- April 2026: Bureau Veritas signed an agreement to acquire Lotusworks, a global specialist in mission-critical assets commissioning and quality assurance operating in the United States and Europe, with 750 employees and EUR 131 million (USD 154.1 million) in 2025 revenues. The deal creates a EUR 300 million (USD 352.9 million) inspection platform in data centers and semiconductor manufacturing, equal to 15% of Bureau Veritas’s Buildings and Infrastructure division.
- March 2025: SPIE signed an agreement to acquire SGS Industrial Services Group, which employs 800 specialists primarily in Germany and Austria. The acquisition positions SPIE around Germany’s energy transition and infrastructure investment pipeline and deepens its industrial inspection value chain.
Europe Inspection Services Market Report Scope
The Europe Inspection Services Market Report is Segmented by Inspection Service Domain (Building and Property Inspection Services, Civil Infrastructure Inspection Services, and More), by End-Use Industry (Construction, Real Estate and Civil Infrastructure, Households and Individual Consumers, and More), and by Geography (Germany, France, United Kingdom, Italy, and more). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Building and Property Inspection Services | Residential, Commercial and Institutional Building Inspections |
| Structural, Building Envelope, MEP and Fire-Safety Inspections | |
| Property Condition, Construction and Handover Inspections | |
| Civil Infrastructure Inspection Services | Roads, Bridges, Tunnels and Rail Track Infrastructure |
| Dams, Civil Water Infrastructure and Other Civil Engineering Structures | |
| Industrial Facilities and Fixed Asset Inspection Services | Industrial Plants and Installed Process Equipment |
| Pressure Vessels, Pipelines and Storage Tanks | |
| Energy Generation and Utility Systems | |
| Other Stationary Industrial Equipment | |
| Manufactured Product and Production-Process Inspection Services | Raw Material and Component Inspection |
| In-Process Manufacturing Inspection | |
| Finished-Product and Production-Process Conformity Inspection | |
| Transportation Vehicle and Mobile Asset Inspection Services | Road Vehicles and Commercial Fleets |
| Rail Rolling Stock | |
| Aircraft and Aviation Assets | |
| Ships and Other Marine Vessels | |
| Other Mobile Transportation Assets | |
| Commodity, Cargo and Trade Inspection Services | Bulk and Containerized Cargo Inspection |
| Traded Commodity Inspection | |
| Consignment Condition, Quantity and Quality Verification | |
| Loading, Unloading and Custody-Transfer Inspection | |
| Other Operational Site and Process Inspection Services | Physical Hygiene and Workplace Safety Inspection |
| Agricultural Site Inspection | |
| Other Operational Compliance Inspection |
| Oil and Gas, Including Petroleum Refining and Petrochemicals |
| Power Generation, Renewable Energy and Utilities |
| Manufacturing and Industrial Processing (Excluding Industries Separately Classified) |
| Construction, Real Estate and Civil Infrastructure |
| Transportation and Logistics Operations |
| Mining and Quarrying |
| Agriculture, Food and Beverage |
| Wholesale, Retail and Commodity Trading |
| Healthcare, Pharmaceuticals and Life Sciences |
| Households and Individual Consumers |
| Other Commercial Services and Public Institutions |
| Germany |
| United Kingdom |
| France |
| Italy |
| Spain |
| Netherlands |
| Poland |
| Russia |
| Rest of Europe |
| By Inspection Service Domain | Building and Property Inspection Services | Residential, Commercial and Institutional Building Inspections |
| Structural, Building Envelope, MEP and Fire-Safety Inspections | ||
| Property Condition, Construction and Handover Inspections | ||
| Civil Infrastructure Inspection Services | Roads, Bridges, Tunnels and Rail Track Infrastructure | |
| Dams, Civil Water Infrastructure and Other Civil Engineering Structures | ||
| Industrial Facilities and Fixed Asset Inspection Services | Industrial Plants and Installed Process Equipment | |
| Pressure Vessels, Pipelines and Storage Tanks | ||
| Energy Generation and Utility Systems | ||
| Other Stationary Industrial Equipment | ||
| Manufactured Product and Production-Process Inspection Services | Raw Material and Component Inspection | |
| In-Process Manufacturing Inspection | ||
| Finished-Product and Production-Process Conformity Inspection | ||
| Transportation Vehicle and Mobile Asset Inspection Services | Road Vehicles and Commercial Fleets | |
| Rail Rolling Stock | ||
| Aircraft and Aviation Assets | ||
| Ships and Other Marine Vessels | ||
| Other Mobile Transportation Assets | ||
| Commodity, Cargo and Trade Inspection Services | Bulk and Containerized Cargo Inspection | |
| Traded Commodity Inspection | ||
| Consignment Condition, Quantity and Quality Verification | ||
| Loading, Unloading and Custody-Transfer Inspection | ||
| Other Operational Site and Process Inspection Services | Physical Hygiene and Workplace Safety Inspection | |
| Agricultural Site Inspection | ||
| Other Operational Compliance Inspection | ||
| By End-Use Industry | Oil and Gas, Including Petroleum Refining and Petrochemicals | |
| Power Generation, Renewable Energy and Utilities | ||
| Manufacturing and Industrial Processing (Excluding Industries Separately Classified) | ||
| Construction, Real Estate and Civil Infrastructure | ||
| Transportation and Logistics Operations | ||
| Mining and Quarrying | ||
| Agriculture, Food and Beverage | ||
| Wholesale, Retail and Commodity Trading | ||
| Healthcare, Pharmaceuticals and Life Sciences | ||
| Households and Individual Consumers | ||
| Other Commercial Services and Public Institutions | ||
| By Geography | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Netherlands | ||
| Poland | ||
| Russia | ||
| Rest of Europe | ||
Key Questions Answered in the Report
What is the forecast growth rate for Europe's inspection services?
The Europe inspection services market is forecast to expand at a 5.49% CAGR from 2027 to 2032, reaching USD 46.7 billion in 2032.
Which inspection service has the largest revenue share in Europe?
Building and property inspection services held the largest share at 27.7% in 2026.
Which service area is growing fastest in Europe?
Civil infrastructure inspection services is forecast to grow at a 6.6% CAGR through 2032, supported by aging assets and new energy infrastructure.
Which end-use sector leads inspection demand in Europe?
Construction, real estate, and civil infrastructure led with 21.5% share in 2026 and is forecast to grow at a 6.1% CAGR through 2032.
Which country is expected to grow fastest for inspection services?
The United Kingdom is forecast to grow at an 8.7% CAGR through 2032, supported by infrastructure and public-investment programs.
What factors constrain the adoption of advanced inspection services?
A shortage of certified specialists and the cost of advanced inspection technology for smaller firms are the main constraints.