
Data Center Insurance Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 8.97 Billion |
| Market Size (2032) | USD 17.62 Billion |
| Growth Rate (2027 - 2032) | 14.46 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Data Center Insurance Market Analysis by Mordor Intelligence
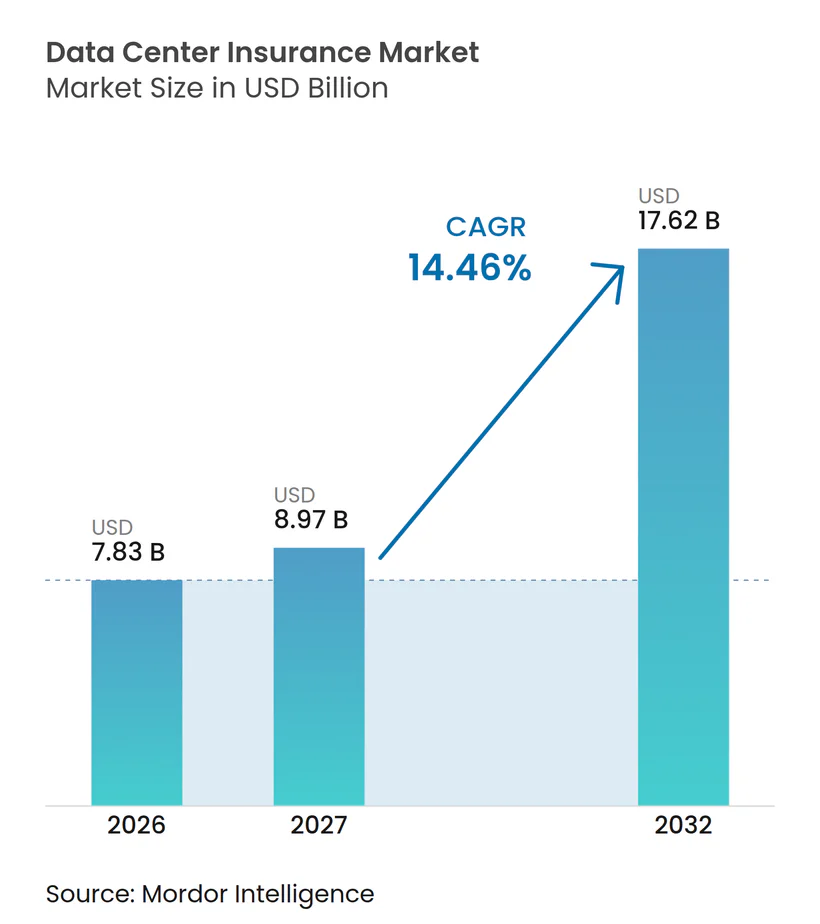
The Data Center Insurance Market size is projected to be USD 7.83 billion in 2026, USD 8.97 billion in 2027, and reach USD 17.62 billion by 2032, growing at a CAGR of 14.46% from 2027 to 2032. The Data Center Insurance Market is expanding as AI infrastructure raises the value and technical complexity of facilities under construction and in operation. Large campuses increasingly need cover that follows assets from construction through commissioning and live operations. Lenders are also placing greater weight on insurance terms because service interruptions can weaken contracted cash flow. Insurers are responding with coordinated property, business interruption, cyber, liability, and parametric products. Capacity limits and higher retentions may leave an opening for captives, insurance-linked securities, and specialized underwriting facilities.
Key Report Takeaways
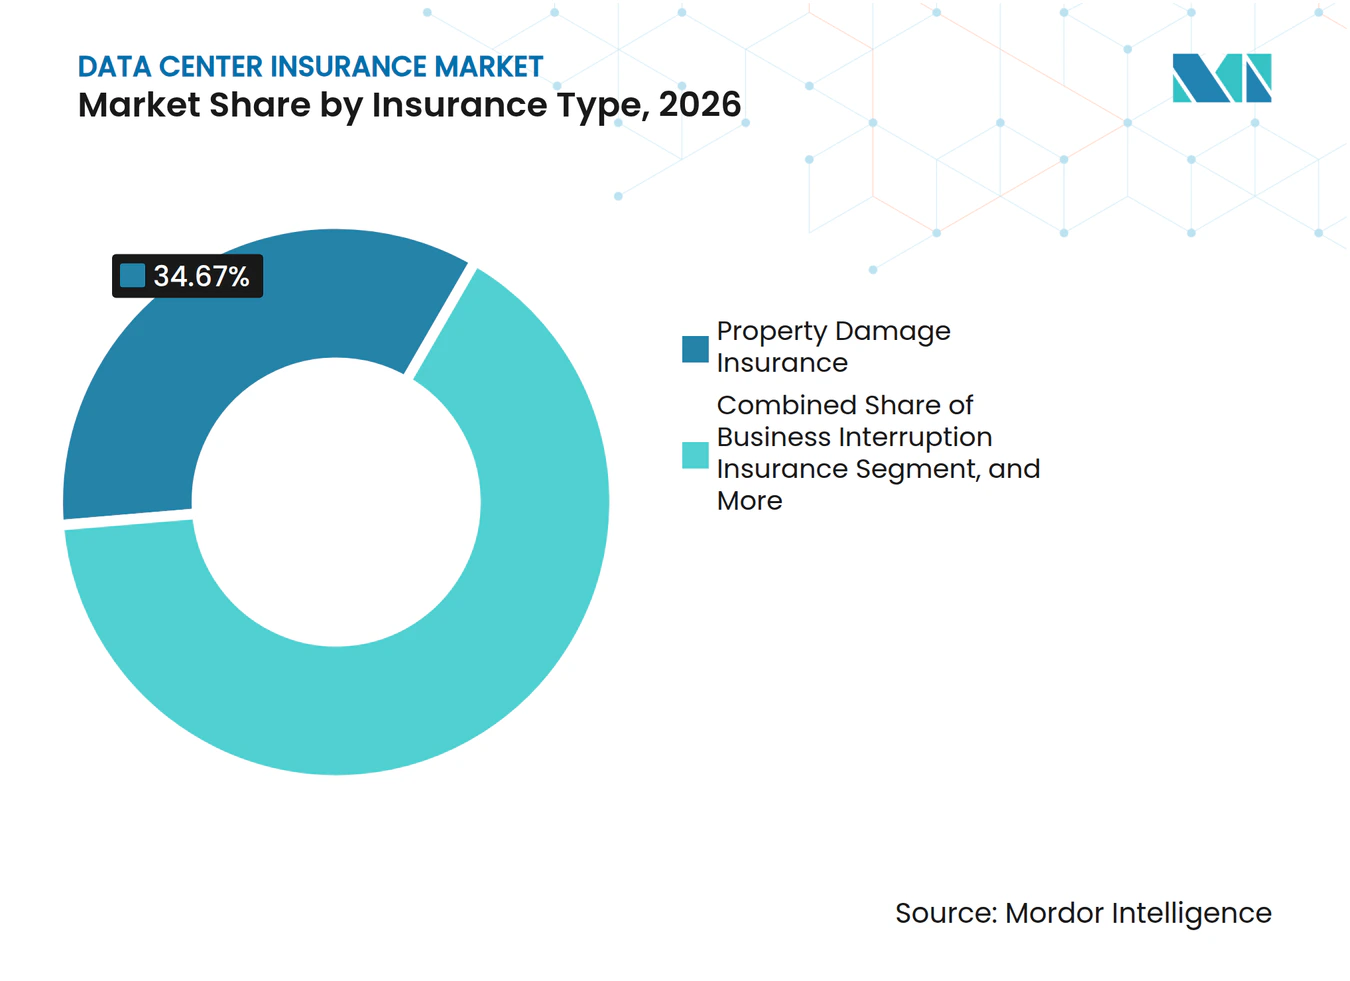
- By insurance type, property damage insurance held 34.67% of the Data Center Insurance Market share in 2026, while cyber insurance is projected to expand at a 15.83% CAGR through 2032.
- By coverage structure, combined property and business interruption policies accounted for 38.43% of the Data Center Insurance Market size in 2026, while parametric insurance is expected to grow at a 15.17% CAGR through 2032.
- By risk exposure, electrical and mechanical equipment failure accounted for 23.87% of the share in 2026, while cyber-related operational disruption is projected to grow at a 15.63% CAGR through 2032.
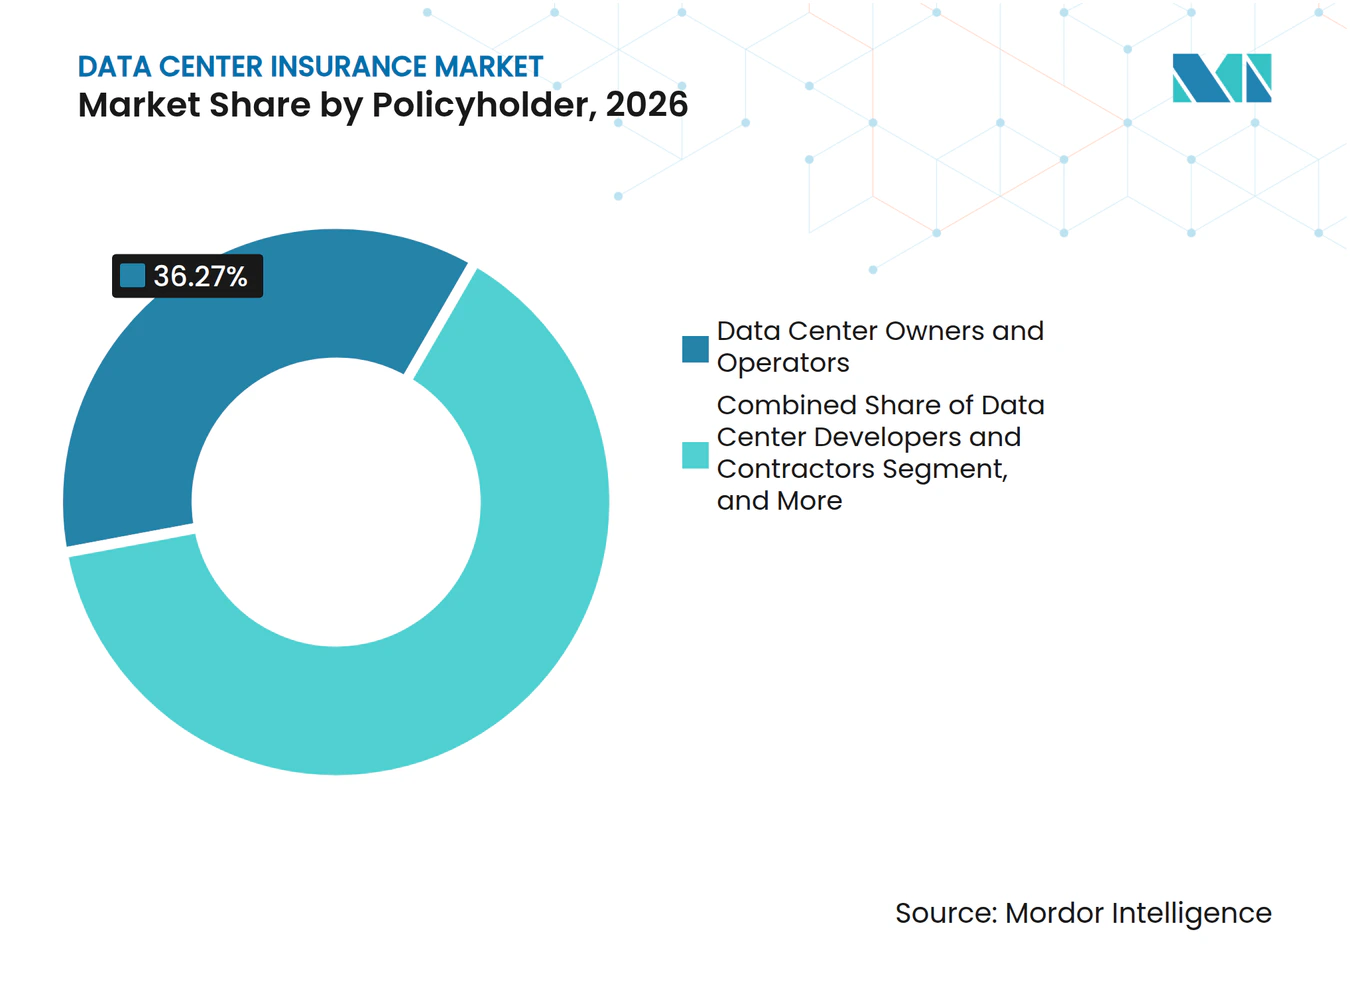
- By policyholder, data center owners and operators accounted for 36.27% of premium in 2026, while cloud service providers are expected to expand at a 15.43% CAGR through 2032.
- By insurance distribution channel, insurance brokers and consultants held 52.63% share in 2026, while MGAs and specialist underwriting agencies are projected to grow at a 15.79% CAGR through 2032.
- By data center size, large data centers accounted for 41.37% of premium in 2026, while hyperscale data centers are expected to grow at a 15.24% CAGR through 2032.
- By data center type, colocation data centers held 43.83% of premium in 2026, while cloud service providers are projected to expand at a 15.41% CAGR through 2032.
- By geography, North America held 44.67% of premium in 2026, while Asia-Pacific is projected to grow at a 15.86% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Data Center Insurance Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising AI and Cloud Compute Demand | +3.2% | Global, led by North America and Asia-Pacific | Long term (≥ 4 years) |
| Expansion of High-Value Data Center Construction Pipelines | +2.7% | North America and Europe, spill-over to Asia-Pacific and Middle East | Medium term (2-4 years) |
| Growing Financial Cost of Downtime and SLA Breaches | +2.1% | Global, concentrated in North America and Asia-Pacific | Short term (≤ 2 years) |
| Rising Demand for Integrated Property, Business Interruption, Cyber, and Liability Cover | +1.8% | Global, particularly North America and Western Europe | Medium term (2-4 years) |
| Greater Lender and Investor Scrutiny of Data Center Resilience | +1.4% | North America, Europe, Asia-Pacific core | Medium term (2-4 years) |
| Adoption of Parametric Downtime and Cloud Outage Insurance | +1.2% | Global, concentrated in North America and Western Europe | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising AI and Cloud Compute Demand
The Data Center Insurance Market is supported by rapid investment in AI infrastructure, which increases both asset values and operational dependencies. AI servers require more than 100 kilowatts per rack, compared with the conventional 5-15 kilowatt range. This density increases the consequences of cooling failures, fires, and equipment failures. Inference workloads are expected to become the dominant AI compute need by 2027, which extends exposure across continuous operating periods. These changes favor insurance programs that assess physical and digital risks together.
Expansion of High-Value Data Center Construction Pipelines
The Data Center Insurance Market benefits when construction values rise because builder risk, delay in start-up, cargo, and liability requirements increase. Average project cost reached USD 633 million in 2025, while per-square-foot cost reached USD 1,033. Concurrent construction and commissioning can create uncertainty over the point at which each policy attaches. Large projects, therefore, need clearer handover terms between construction and operational coverage. Lender requirements also make insurance a central part of financing from ground-breaking through stabilization.
Growing Financial Cost of Downtime and SLA Breaches
A 45-minute outage at a 100 MW facility generating USD 144 million in annual rent can produce USD 24 million in service-credit losses. The loss can reduce annual cash flow by 42%, even where no physical damage has occurred. Standard property coverage often does not respond to this type of contractual loss. Power supply failures account for 45% of outages, which places UPS reliability at the center of resilience discussions. The October 2025 AWS us-east-1 outage generated estimated losses of USD 500 million to USD 650 million for US companies. This exposure supports demand for SLA and digital business interruption protection.
Rising Demand for Integrated Property, Business Interruption, Cyber, and Liability Cover
A single event can generate property, business interruption, cyber, and liability claims simultaneously. The Data Center Insurance Market is moving toward coordinated coverage because separate policies can produce gaps and disputes at the time of a claim. Large campuses may require USD 10 billion or more in program limits. No single carrier can provide sufficient capacity for many of these placements. Updated risk engineering requirements are also shaping policy terms and construction specifications. FM Global's 2026 guidance raised the recommended wall fire-resistance rating from 1 hour to 2 hours. Integrated programs can align coverage with those common technical requirements.
Restraints Impact Analysis of Data Center Insurance Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Premiums, Deductibles, and Coverage Retentions | -1.2% | Global, most acute in North America and Asia-Pacific | Short term (≤ 2 years) |
| Limited Capacity for Concentrated, Multibillion-Dollar Risks | -0.9% | Global, particularly for hyperscale projects in North America and Europe | Medium term (2-4 years) |
| Exclusions and Sublimits for Catastrophe, Cyber, and Emerging Technologies | -0.7% | Global, spill-over to emerging markets | Medium term (2-4 years) |
| Limited Loss History and Nonstandardized Risk Data for AI-Ready Facilities | -0.6% | Global, most acute in South Korea, India, and Southeast Asia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Premiums, Deductibles, and Coverage Retentions
Premium pressure can make the coverage lenders require difficult for smaller operators to afford. Construction costs in Asia-Pacific rose 10% year-over-year in 2025, which makes replacement values harder to maintain at renewal.[1] Facilities that once required USD 2 billion in limits can require USD 20 billion for infrastructure alone. Computing hardware can further increase total exposure. A South Korean operator reportedly deemed a proposed 2026 premium rate for an AI data center too expensive. Higher costs may lead some buyers to retain more risk or accept partial cover.
Limited Capacity for Concentrated, Multibillion-Dollar Risks
Business interruption exposure is difficult to model because it depends on computing capacity and interconnected locations. Geographic concentration compounds this issue when natural events affect multiple campuses in a single region. More of the US capacity is in high-hail-frequency areas, and nearly 40% is in significant-to-very-high tornado-day areas. Captives and insurance-linked securities can supplement conventional reinsurance when carrier limits are constrained.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Data Center Insurance Market Segment Analysis
By Insurance Type:
Cyber Coverage Expands Within a Broad Protection MixProperty damage insurance held 34.67% of the data center insurance market in 2026 because physical asset values remain the core basis for program design. Data Center Insurance Market size for property-related programs is supported by AI campuses that can exceed USD 20 billion in construction cost before hardware is installed. Cyber insurance is projected to grow at a 15.83% CAGR through 2032 as connected controls expand the operational attack surface. Cooling, power, and monitoring systems can create loss pathways even where access to hardware is tightly controlled. Business interruption coverage remains a major severity concern because revenue can exceed a building's replacement value. Natural catastrophe coverage is also becoming more important as facility locations face hail, tornado, flood, and other severe weather exposures.
Construction and erection all-risk, general liability, and equipment breakdown policies continue to serve distinct risk requirements. The Data Center Insurance Market must also address litigation connected with zoning, environmental concerns, and noise from new projects. Data center lawsuits and arbitrations have more than tripled since 2021, which broadens liability needs beyond conventional operational claims. AIG introduced a parametric cloud outage product in August 2026 with a 2-hour waiting period. This compares with a 30-day threshold often associated with conventional business interruption policies. Faster triggers can make cover more relevant for short service interruptions. The result is a wider product mix that assigns different tools to physical damage, downtime, and digital events.



By Coverage Structure:
Parametric Triggers Address Short-Duration EventsCombined property and business interruption policies held 38.43% of the coverage structure premium in 2026. This share reflects the close connection between physical loss and revenue disruption at facilities that must operate continuously. The Data Center Insurance Market share held by these combined programs demonstrates why customers value aligned limits and claims processes. Parametric insurance is expected to grow at a 15.17% CAGR through 2032. It addresses short, non-damage outages that may be financially significant but are difficult to recover under indemnity policies. Pre-agreed triggers may refer to uptime, power voltage, or cooling performance. Payment can occur after an agreed event without a traditional proof-of-loss process.
Standalone policies remain relevant for smaller operators that have more standardized exposures. Package policies are gaining interest among enterprise customers who want fewer gaps across related risks. Captive and self-insurance structures are also growing among hyperscale operators because commercial capacity may not fully cover a single campus. Hybrid structures can combine parametric protection for short events with indemnity cover for larger losses. This design separates fast, measurable disruptions from complex physical claims. It can also make the allocation of risk more transparent for investors and lenders. The Data Center Insurance Market is therefore developing policy structures around the different financial effects of outage types.
By Risk Exposure:
Equipment Failure Remains the Largest ExposureElectrical and mechanical equipment failure accounted for 23.87% of the risk exposure segment in 2026. Electrical and mechanical equipment failures led to the Data Center Insurance Market share, as power and cooling systems are essential to continuous operations. Power failures, mainly related to UPS faults, account for 45% of data center outages. Cooling failures account for another 14% of outages. Cyber-related operational disruption is projected to grow at a 15.63% CAGR through 2032 as connected technology expands.
Water damage and flooding accounted for nearly 24% of total loss costs in the same analysis. Direct-to-chip liquid cooling can introduce more complex water pathways in GPU-dense environments. Rapid construction can also bring less experienced contractors into specialized cooling work. Severe convective storms caused USD 51 billion in global losses during 2025. A battery explosion at South Korea's National Information Resources Service in September 2025 disabled 647 government services. These events show why equipment, weather, fire, and supply disruptions need an integrated risk review.
By Policyholder:
Owners Lead Current Premium DemandData center owners and operators represented 36.27% of the premium in 2026. Their direct ownership of high-value assets and SLA obligations creates demand for property, liability, and business interruption coverage. The Data Center Insurance Market size associated with owner-and-operator programs reflects these broad contractual and asset exposures. Cloud service providers are projected to grow at a 15.43% CAGR through 2032. Colocation providers remain significant buyers because multiple tenants share the same physical environment.
Developers and contractors have different needs during construction, including all-risk construction, start-up delays, and contractor liability cover. Equipment and service providers also face large replacement values for dense GPU installations. These buyer groups require policy language that addresses their specific role in the facility lifecycle. Their different needs sustain demand for specialized underwriting rather than a single standard policy.

By Insurance Distribution Channel:
Brokers Lead Complex PlacementsInsurance brokers and consultants held 52.63% of the distribution channel premium in 2026. Their position reflects the need to organize capacity from many insurers within layered and syndicated placements. The Data Center Insurance Market share held by intermediaries is reinforced by their role in negotiating wording, limits, and lender conditions. MGAs and specialist underwriting agencies are expected to grow at a 15.79% CAGR through 2032. They can apply concentrated technical knowledge to projects that do not fit generic commercial terms. Direct insurance still has a role for smaller facilities with standardized risks. Reinsurance-supported programs are gaining relevance for hyperscale projects that require additional capital sources.
The broker channel has become an important competitive gateway for insurers seeking large mandates. Aon, Marsh McLennan, and Howden have built dedicated practices and underwriting facilities for data center risks. Aon's Data Center Lifecycle Insurance Program reached USD 2.5 billion in capacity during January 2026. Marsh expanded its Nimbus facility to USD 2.7 billion in July 2026. These facilities give buyers structured access to capacity and technical support. Lenders may also view broker-designed minimum coverage standards as relevant to financing decisions. This makes intermediary expertise important throughout the placement process.
By Data Center Size:
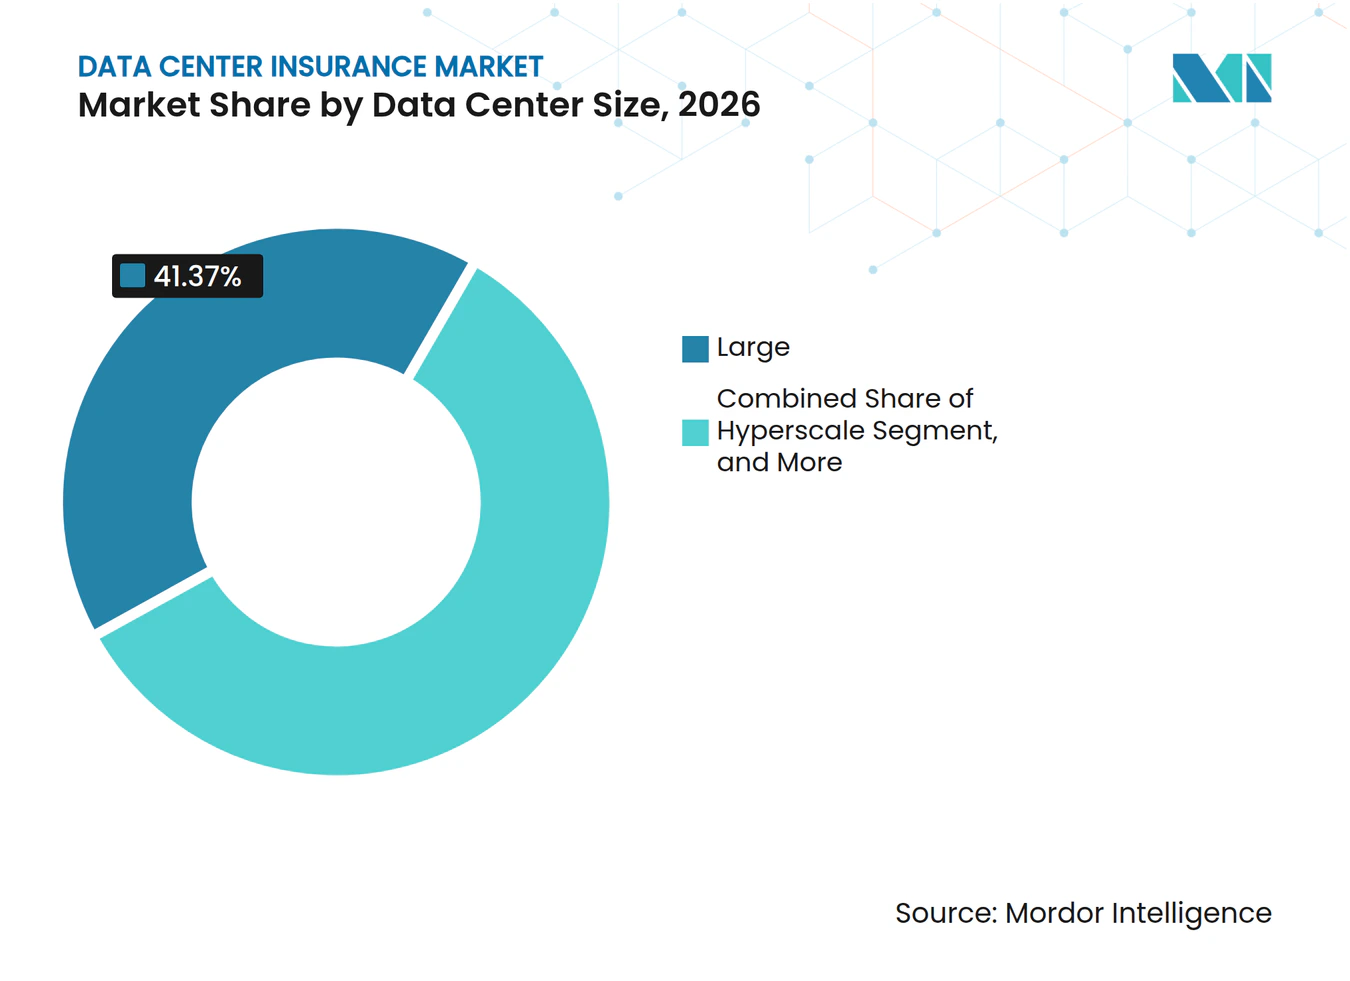
Hyperscale Facilities Set the Capacity ChallengeLarge data centers accounted for 41.37% of premiums in 2026 due to their combination of high insured values, multiple tenants, and contractual service obligations. Hyperscale data centers are expected to grow at a 15.24% CAGR through 2032. These values require several insurers to participate in the same placement. Small data centers often use standard commercial property forms. Medium facilities are increasingly seeking broader lifecycle cover as operations become more complex.
Hyperscale exposure involves more than the size of a building or server hall. A campus can involve technology companies, specialist developers, utilities, equity sponsors, and public or private lenders. Each party may have different expectations for construction, property, cyber, and liability coverage. ATA launched its Global Data Center and AI Infrastructure Insurance facility in January 2026 with up to USD 750 million in capacity.[2] The facility combined property, computer hardware, cyber, cargo, environmental liability, and terrorism coverages.
By Data Center Type:
Colocation Supports Current Premium VolumeColocation data centers accounted for 43.83% of premium by data center type in 2026. Their multi-tenant structure places several revenue streams and SLA obligations on a single physical asset. Cloud service providers are projected to expand at a 15.41% CAGR through 2032. The Data Center Insurance Market share represented by colocation reflects the need to consider each tenant's contractual exposure. Cloud service providers are supported by demand for cloud-hosted AI inference services and continuing hyperscale construction. Enterprise and edge data centers are also adding premium volume. Edge sites place critical workloads closer to industrial, financial, and emergency-response users.
CSP-operated facilities typically have greater rack density and more complex interconnection than many colocation sites. Their operators may also invest more heavily in risk engineering and operational resilience. Business interruption at these sites remains difficult to structure because it depends on computing capacity, energy use, and linked campus operations. This complexity supports the use of parametric and captive arrangements. Distributed edge deployments create a different challenge because risk is spread across many smaller locations. Insurers need to assess how local failures could affect services that depend on a wider network. The Data Center Insurance Market is adapting coverage structures to both centralized hyperscale risk and distributed edge exposure.
Geography Analysis
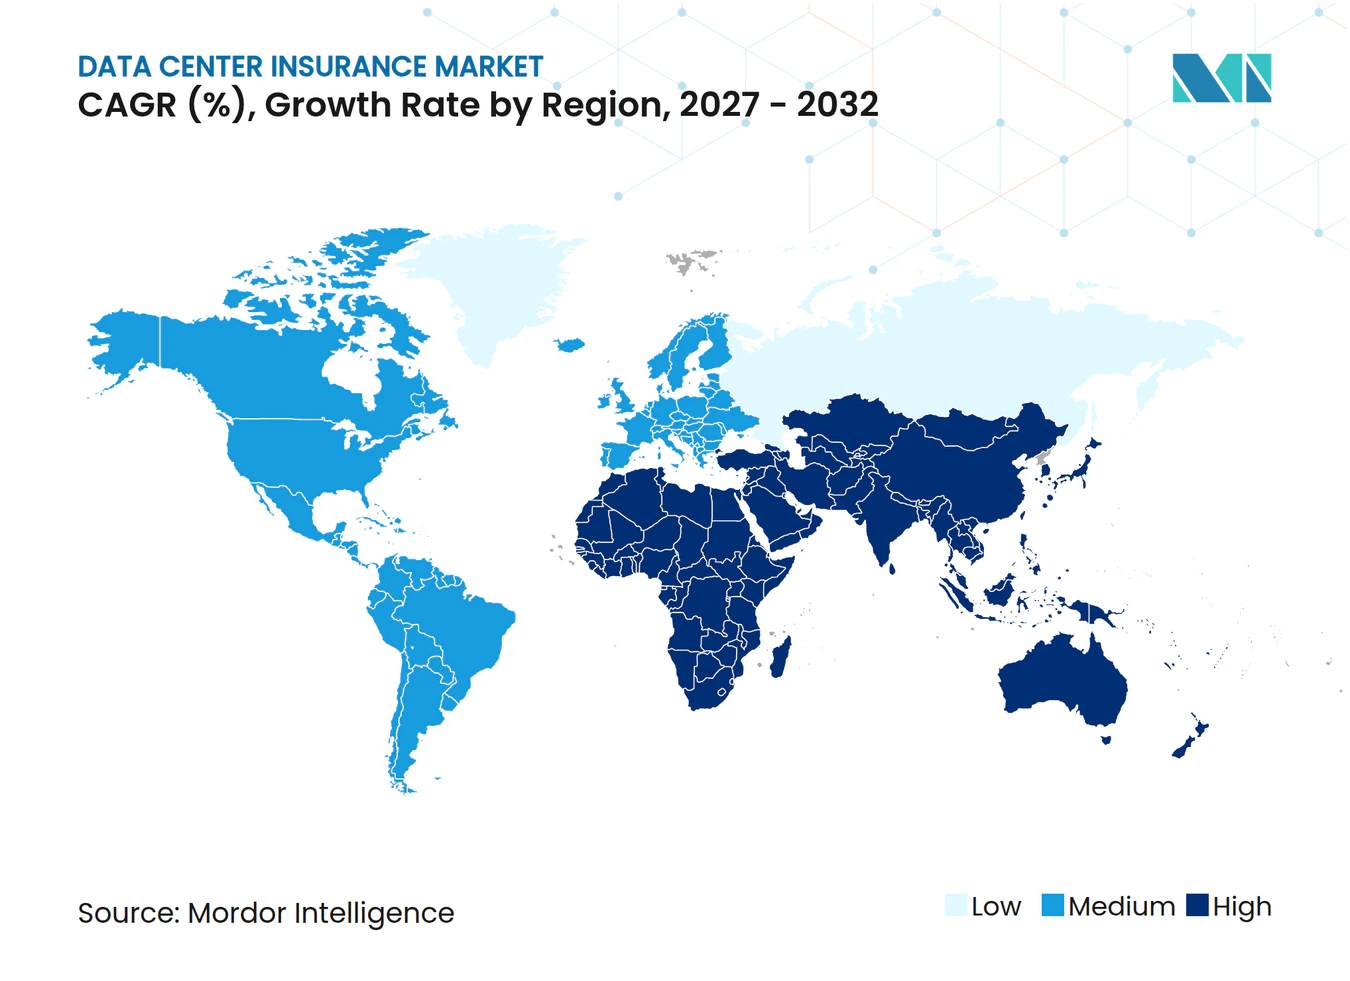
North America held 44.67% of the Data Center Insurance Market share in 2026. The US pipeline exceeded 430 GW of disclosed capacity, with 59% under active development and nearly 80 GW under construction by mid-2026. The Federal Reserve estimated that annualized US data center investment would reach USD 370 billion by mid-2026. This pace increases demand for both construction and operational insurance. More than 400 data center moratoriums have affected 18% of tracked US sites since January 2026.
Asia-Pacific is projected to grow at a 15.86% CAGR through 2032. Regional capacity is expected to rise from 9 GW to more than 28 GW by 2030, excluding China. Southeast Asia accounted for half of the capacity under construction in the first half of 2026. Construction costs rose 10% year-over-year in 2025, and 89% of existing regional capacity faced chronic heat and drought stress. South Korea planned 18.4 GW of AI data center capacity by 2035. Samsung Fire and Marine Insurance was developing AI data center risk-assessment guidelines in 2026.
Western Europe's project pipeline was valued at USD 695 billion in the third quarter of 2026. GDPR and the EU AI Act are important compliance considerations for policy terms related to data sovereignty and localization. Zurich expanded Data Center Project Guard to Brazil, Germany, Italy, the Nordics, and Spain during June 2026.[3] Brazil is South America's main hub and AXA introduced a dedicated data center solution there during September 2026. UAE and Saudi Arabian facilities face a different underwriting concern following drone strikes on facilities in the UAE and Bahrain. Africa remains at an earlier stage, although project finance standards are creating baseline insurance expectations.
Competitive Landscape
Market Concentration
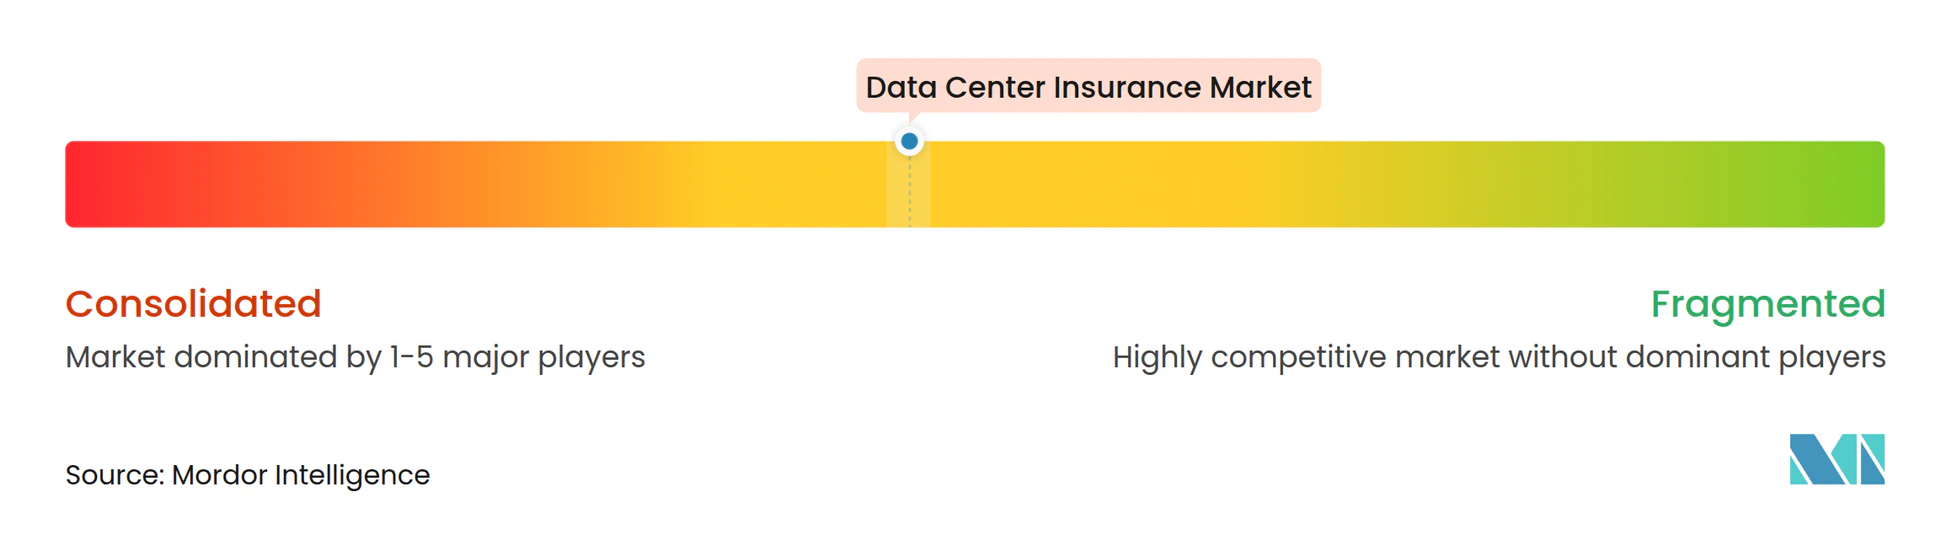
The Data Center Insurance Market has moderate-to-high concentration at the reinsurance tier, while primary insurance remains more fragmented. Munich Re and Swiss Re have technical and capacity positions in complex global programs. Primary insurers, Lloyd's syndicates, and regional carriers compete across specific policy lines and geographies. Product breadth and risk engineering increasingly matter more than price for large placements. AIG, Chubb, Zurich, and AXA XL have been building coordinated products across construction, property, cyber, and liability. The commercial opening remains strongest in SLA-linked parametric protection, edge-computing liability, and environmental risk. These areas have fewer established underwriting frameworks.
AIG expanded its cloud outage offering in August 2026 through a partnership with Parametrix. The product uses parametric digital business interruption protection within a cyber policy. Zurich expanded its Data Center Project Guard offering beyond the US during June 2026. The offering combines builders risk, parametric weather protection, and post-construction operational property coverage. Aon expanded its lifecycle program to USD 2.5 billion in January 2026. These actions indicate that participants are seeking longer-term relationships throughout the project lifecycle.
Parametrix has developed monitoring for more than 750 data centers and 7,000 cloud services.[4] Its model supports real-time trigger determination and rapid claims settlement. This capability creates pressure on conventional indemnity products to respond faster to measurable outages. Howden also partnered with Foresight to analyze Primavera P6 construction schedules for hidden delay risks in hyperscale projects. Broker platforms can influence carrier selection because they organize structured capacity for major projects. Competition is therefore taking place through capacity, product design, engineering capability, and access to specialist data.
Data Center Insurance Industry Leaders
-
Munich Reinsurance Company
-
Swiss Reinsurance Company Ltd.
-
Allianz SE
-
AXA XL Insurance Company
-
Zurich Insurance Group Ltd.
- *Disclaimer: Major Players sorted in no particular order
Data Center Insurance Market Companies Covered in this Report
- Munich Reinsurance Company
- Swiss Reinsurance Company Ltd.
- Allianz SE
- AXA XL Insurance Company
- Zurich Insurance Group Ltd.
- Chubb Limited
- American International Group, Inc.
- The Society of Lloyd’s
- Beazley plc
- Berkshire Hathaway Specialty Insurance Company
- Factory Mutual Insurance Company
- HDI Global SE
- QBE Insurance Group Limited
- Tokio Marine HCC
- Sompo International Holdings Ltd.
- CNA Financial Corporation
- The Travelers Companies, Inc.
- Howden Broking Group Limited
- Marsh & McLennan Companies, Inc.
- Aon plc
Recent Industry Developments in Data Center Insurance Market
- September 2026: AXA launched a comprehensive data center insurance solution in Brazil, offering property, cyber, cargo, engineering, and performance bond coverages under a one-stop-shop structure. The launch positions AXA as the first major European insurer with a dedicated data center product in Brazil, which ranks fifth globally by number of data centers, signaling broader South American market ambitions.
- August 2026: AIG launched a parametric cloud outage solution developed in partnership with Parametrix, offering a 2-hour waiting period trigger and integrating parametric digital business interruption protection within a single cyber policy. The solution is backed by Parametrix's monitoring of over 750 data centers and 9,000+ technology service providers globally.
- July 2026: Marsh expanded its Nimbus data center construction insurance facility to USD 2.7 billion in capacity and extended the program's reach to Asia, responding to accelerating investment across Southeast Asia. The expansion makes Nimbus one of the largest dedicated data center construction facilities available to the global market.
- June 2026: Zurich Insurance expanded its Data Center Project Guard offering beyond the US to Brazil, Germany, Italy, the Nordics, and Spain, broadening international access to its integrated builders risk, parametric weather coverage, and post-construction operational property solution. The company indicated plans to add further countries in subsequent phases.
Global Data Center Insurance Market Report Scope
The Data Center Insurance Market represents the annual revenue generated from specialized commercial insurance premiums designed to protect data center infrastructure across its entire lifecycle, from construction to full operations. This market encompasses specialized policies and tailored coverage types that address the unique risks associated with mission-critical digital infrastructure, including property damage, cyber liability, business interruption, equipment breakdown, professional liability, and general liability.
The Data Center Insurance Market Report is Segmented by Insurance Types (Property Damage Insurance, Business Interruption Insurance, Equipment Breakdown Insurance, Cyber Insurance, Natural Catastrophe Insurance, General and Third-Party Liability Insurance, Construction and Erection All-Risk Insurance, and Other Insurance Types), Coverage Structure (Standalone Policies, Combined Property and Business Interruption Policies, Package Policies, Parametric Insurance, and Captive and Self-Insurance Arrangements), Risk Exposure (Fire and Explosion, Electrical and Mechanical Equipment Failure, Power Supply Disruption, Flooding and Water Damage, Windstorms and Severe Weather, Earthquakes and Other Geophysical Hazards, Cyber-Related Operational Disruption, and Third-Party and Supply Chain Disruption), Policyholder (Data Center Owners and Operators, Colocation Providers, Cloud Service Providers, Data Center Developers and Contractors, and Data Center Equipment and Service Providers), Insurance Distribution Channel (Direct Insurance, Insurance Brokers and Consultants, Managing General Agents and Specialist Underwriting Agencies, and Reinsurance-Supported Insurance Programs), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation, Cloud Service Providers (CSPs), and Enterprise and Edge), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Property Damage Insurance |
| Business Interruption Insurance |
| Equipment Breakdown Insurance |
| Cyber Insurance |
| Natural Catastrophe Insurance |
| General and Third-Party Liability Insurance |
| Construction and Erection All-Risk Insurance |
| Other Insurance Types |
| Standalone Policies |
| Combined Property and Business Interruption Policies |
| Package Policies |
| Parametric Insurance |
| Captive and Self-Insurance Arrangements |
| Fire and Explosion |
| Electrical and Mechanical Equipment Failure |
| Power Supply Disruption |
| Flooding and Water Damage |
| Windstorms and Severe Weather |
| Earthquakes and Other Geophysical Hazards |
| Cyber-Related Operational Disruption |
| Third-Party and Supply Chain Disruption |
| Data Center Owners and Operators |
| Colocation Providers |
| Cloud Service Providers |
| Data Center Developers and Contractors |
| Data Center Equipment and Service Providers |
| Direct Insurance |
| Insurance Brokers and Consultants |
| Managing General Agents and Specialist Underwriting Agencies |
| Reinsurance-Supported Insurance Programs |
| Small |
| Medium |
| Large |
| Hyperscale |
| Colocation |
| Cloud Service Providers (CSPs) |
| Enterprise and Edge |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Rest of Africa |
| By Insurance Type | Property Damage Insurance | |
| Business Interruption Insurance | ||
| Equipment Breakdown Insurance | ||
| Cyber Insurance | ||
| Natural Catastrophe Insurance | ||
| General and Third-Party Liability Insurance | ||
| Construction and Erection All-Risk Insurance | ||
| Other Insurance Types | ||
| By Coverage Structure | Standalone Policies | |
| Combined Property and Business Interruption Policies | ||
| Package Policies | ||
| Parametric Insurance | ||
| Captive and Self-Insurance Arrangements | ||
| By Risk Exposure | Fire and Explosion | |
| Electrical and Mechanical Equipment Failure | ||
| Power Supply Disruption | ||
| Flooding and Water Damage | ||
| Windstorms and Severe Weather | ||
| Earthquakes and Other Geophysical Hazards | ||
| Cyber-Related Operational Disruption | ||
| Third-Party and Supply Chain Disruption | ||
| By Policyholder | Data Center Owners and Operators | |
| Colocation Providers | ||
| Cloud Service Providers | ||
| Data Center Developers and Contractors | ||
| Data Center Equipment and Service Providers | ||
| By Insurance Distribution Channel | Direct Insurance | |
| Insurance Brokers and Consultants | ||
| Managing General Agents and Specialist Underwriting Agencies | ||
| Reinsurance-Supported Insurance Programs | ||
| By Data Center Size | Small | |
| Medium | ||
| Large | ||
| Hyperscale | ||
| By Data Center Type | Colocation | |
| Cloud Service Providers (CSPs) | ||
| Enterprise and Edge | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the Data Center Insurance Market?
The Data Center Insurance Market is projected to reach USD 8.97 billion in 2027 and USD 17.62 billion by 2032, with a 14.46% CAGR.
What is driving demand for data center insurance?
AI infrastructure spending, higher construction values, tighter lender requirements, and increasing downtime exposure are expanding insurance needs.
Which insurance type is growing fastest for data centers?
Cyber insurance is projected to grow at a 15.83% CAGR through 2032 as operational technology and cloud dependencies increase.
Why are parametric policies relevant for data centers?
They can pay after a predefined uptime, voltage, or cooling trigger, which can address short non-damage service interruptions.
Which region leads data center insurance demand?
North America held 44.67% of premium in 2026, supported by a large US development pipeline and high levels of investment.
What limits insurance capacity for hyperscale campuses?
Individual campuses can require USD 10 billion to USD 30 billion in limits, while global capacity for a large placement is estimated at USD 15 billion to USD 20 billion.