
Construction Project Management Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 12.13 Billion |
| Market Size (2032) | USD 18.12 Billion |
| Growth Rate (2027 - 2032) | 8.35 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Construction Project Management Services Market Analysis by Mordor Intelligence
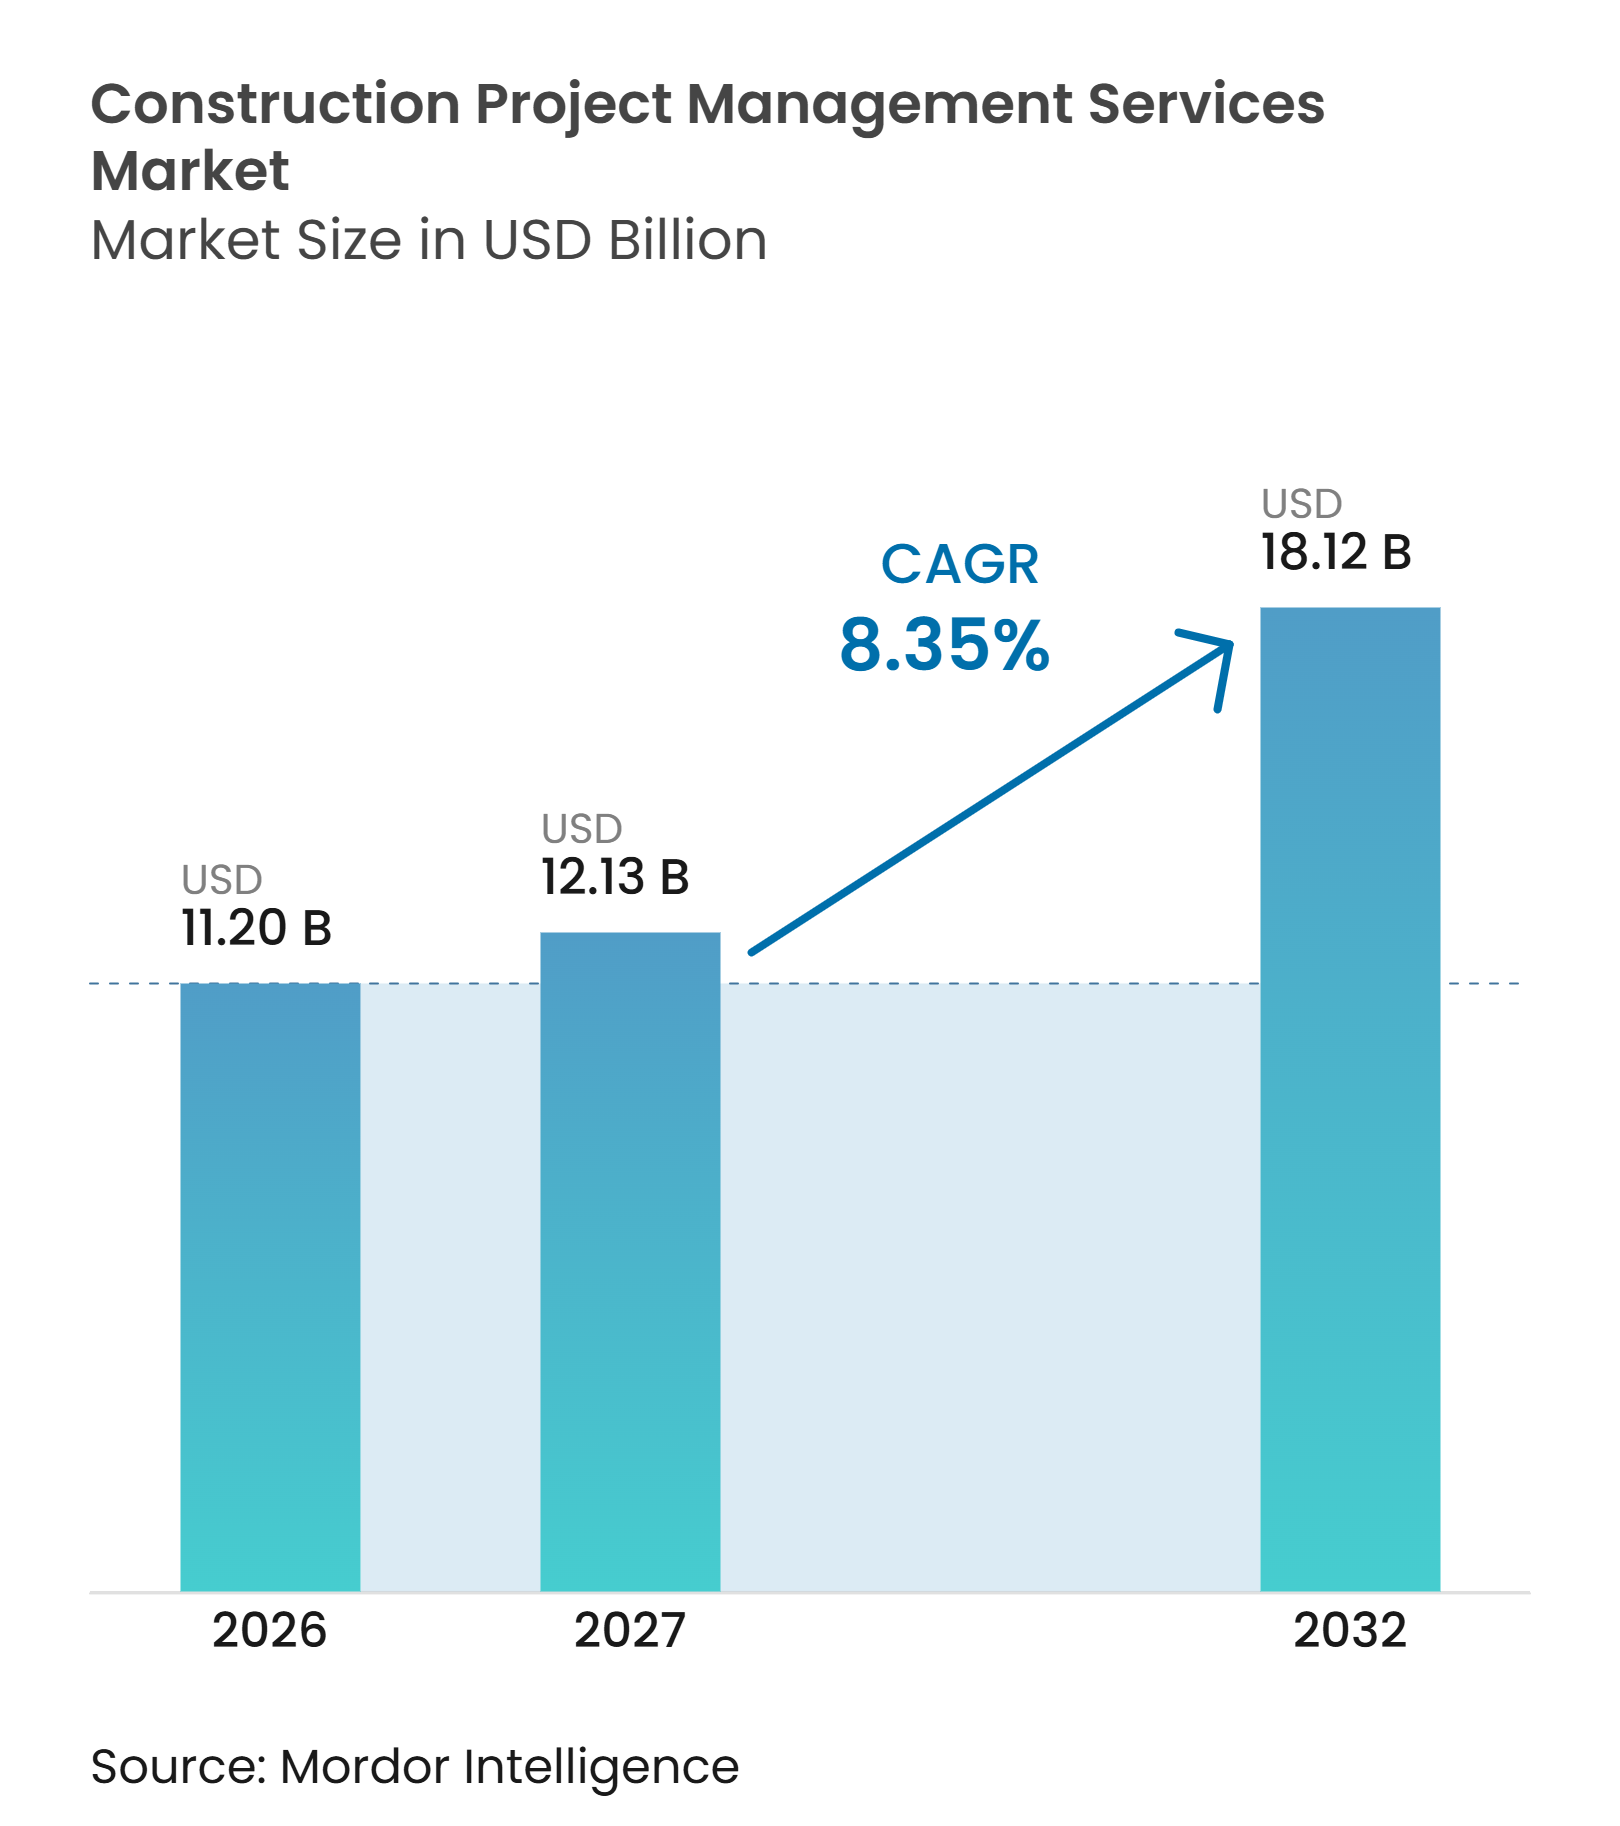
The Construction Project Management Services Market size is projected to be USD 11.20 billion in 2026, USD 12.13 billion in 2027, and reach USD 18.12 billion by 2032, growing at a CAGR of 8.35% from 2027 to 2032.
Demand is rising as public agencies and private owners use specialist teams to plan, govern, and control large capital programs. Owners are also shifting more work toward early-stage capital planning, commercial controls, and program governance. Data center, life sciences, transport, water, and energy projects require stronger coordination across contractors and regulators. Digital project controls create opportunities for providers that combine experienced managers with reliable, shared project data. Price pressure remains strongest in routine construction management assignments, while complex mandates support longer contracts and higher-value advisory work.
Key Report Takeaways
- By service type, Project and Program Management held 41.0% of the Construction project management services market in 2026, while the input does not identify a forecast CAGR for the fastest-growing service type.
- By project type, Infrastructure Construction held 38.0% of the Construction project management services market in 2026, while Industrial Construction is forecast to grow at a 9.30% CAGR through 2032.
- By service delivery mode, On-Site Project Management held 61.0% of the Construction project management services market in 2026, while Remote Project Management is forecast to grow at an 11.61% CAGR through 2032.
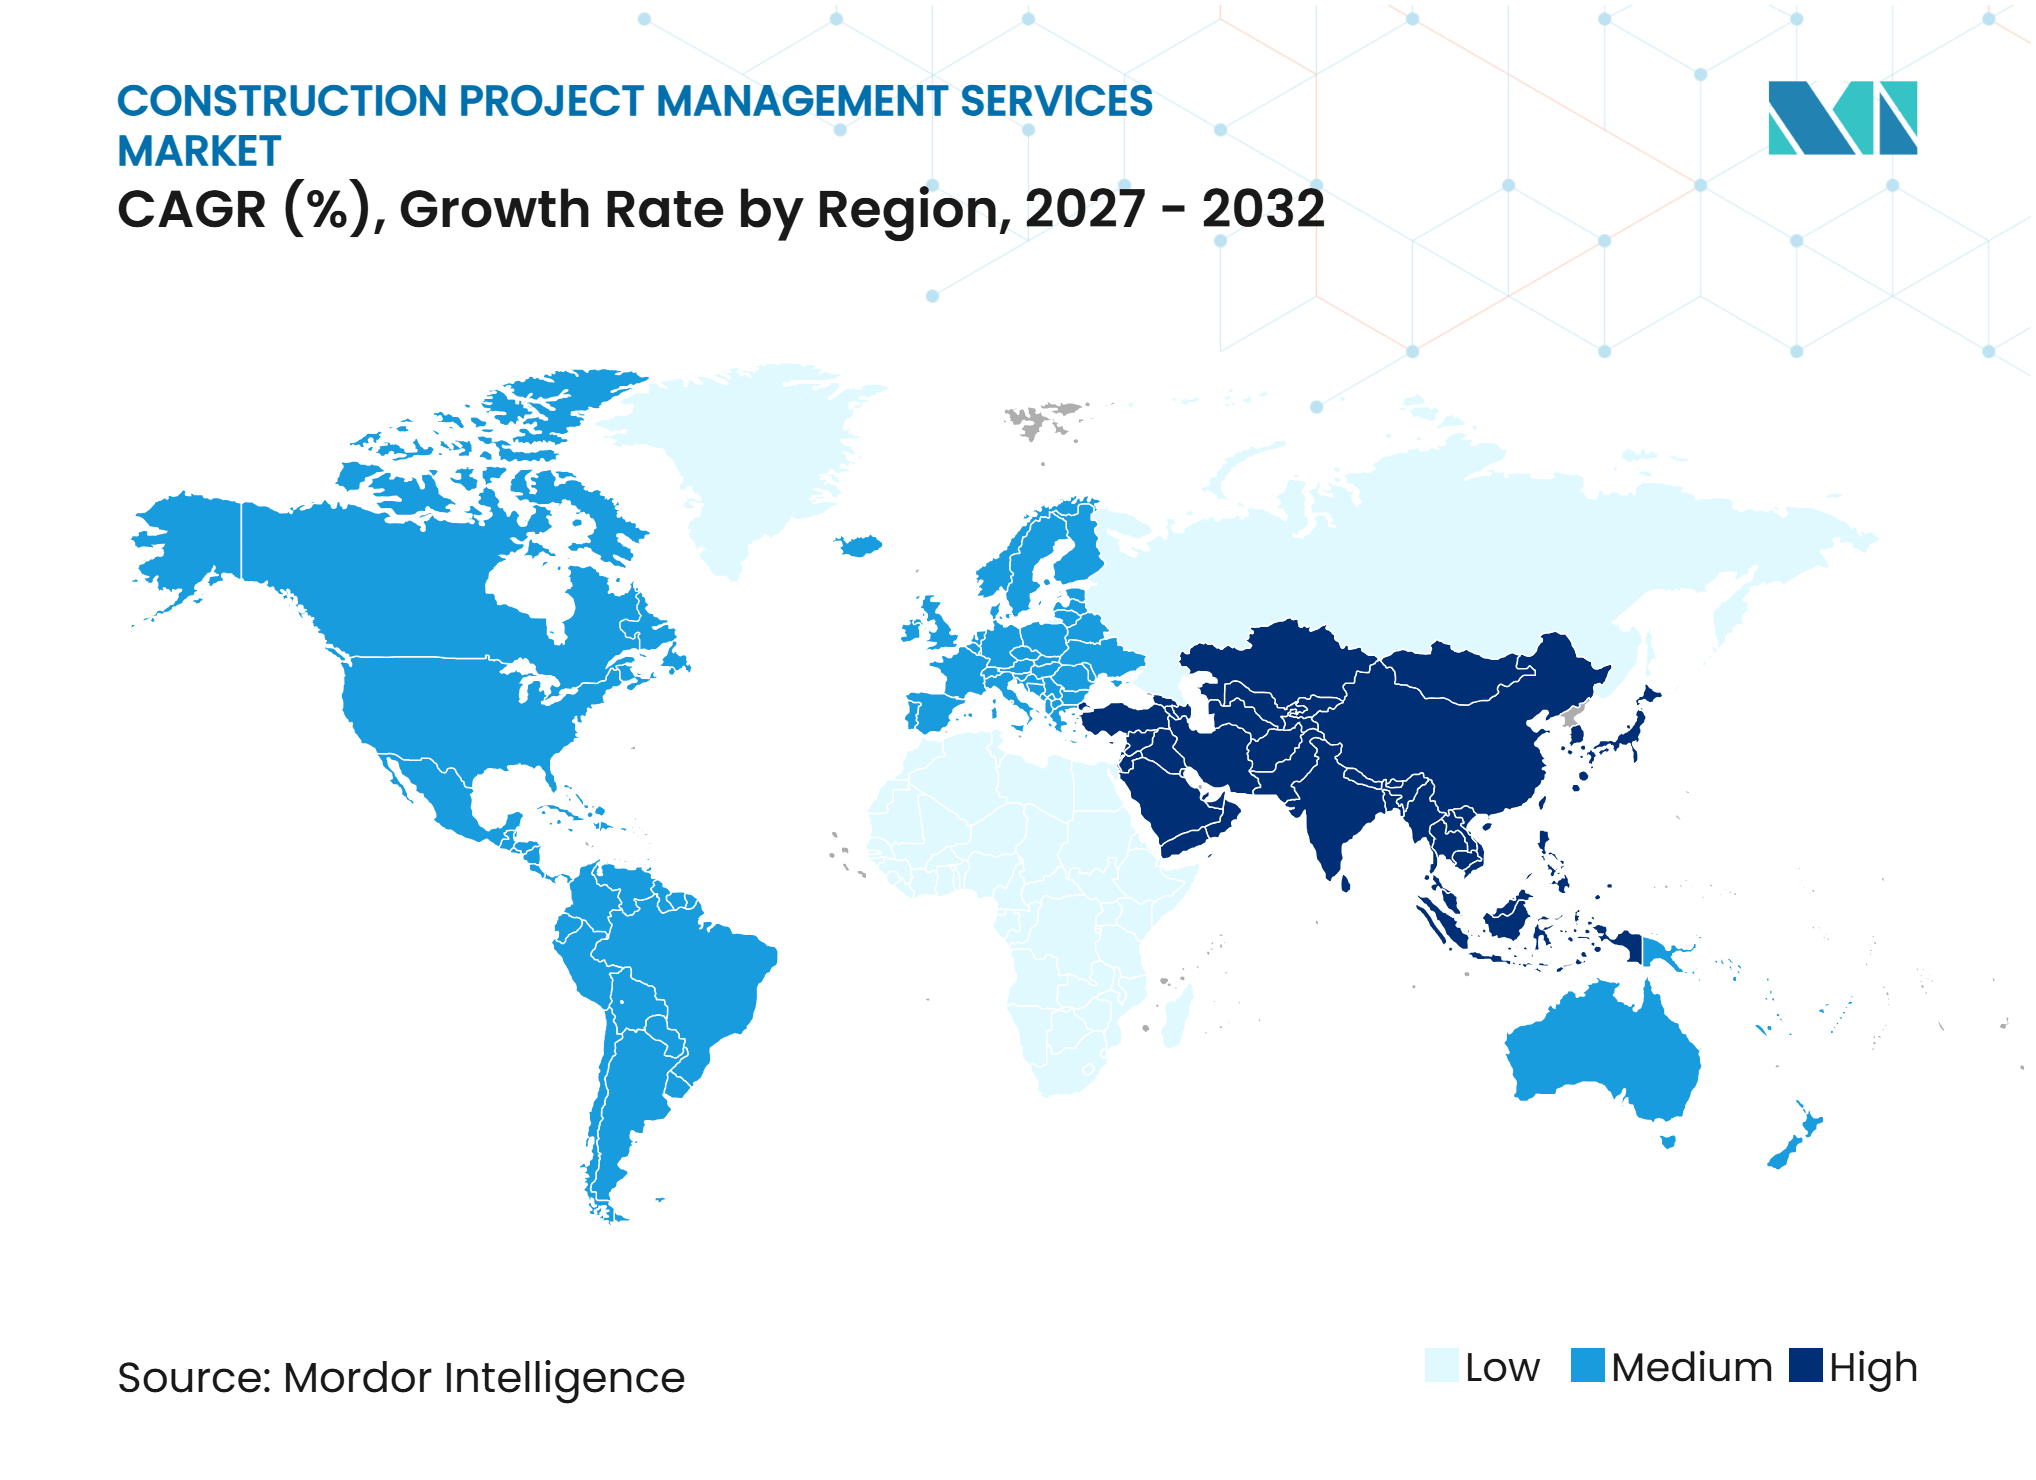
- By geography, North America held 33.0% of the Construction project management services market in 2026, while Asia-Pacific is forecast to grow at a 10.50% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Construction Project Management Services Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Public Infrastructure and Energy Investment | +2.5% | Global, concentrated in North America, the Gulf Cooperation Council, and South Asia | Long term (≥ 4 years) |
| Complexity of Mega-Project Delivery | +1.9% | Global, strongest in the Gulf Cooperation Council, Asia-Pacific, and North America | Long term (≥ 4 years) |
| Outsourcing by Asset Owners | +1.6% | Global, most advanced in North America and Western Europe | Medium term (2-4 years) |
| Programmatic Capital Spending by Data Centers and Life Sciences | +1.4% | North America, Western Europe, and Asia-Pacific core markets | Medium term (2-4 years) |
| Shortage of Owner-Side Delivery Talent | +0.8% | North America, Western Europe, and Australia | Short term (≤ 2 years) |
| Claims Avoidance Through Early-Warning Controls | +0.5% | Global, with early adoption in the Gulf Cooperation Council and North America | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Public Infrastructure and Energy Investment
Public infrastructure and energy investment gives the Construction project management services market a steadier project pipeline than private construction cycles. Large programs require coordinated delivery across transport, water, power, and public facilities. Public owners also face documentation duties that increase the value of specialist project controls. The Federal Emergency Management Agency Buy America Preference requirements add compliance work for eligible U.S. projects. Gulf Cooperation Council programs linked to Expo 2030 Riyadh and FIFA 2034 continue to support selective project management opportunities. These programs favor providers that can manage procurement, reporting, and delivery governance over several years.
Complexity of Mega-Project Delivery
Complex projects increase demand for providers that can coordinate many contracts, interfaces, and approval routes. Mace reports that more than 11,000 megaprojects and 250 giga-projects are active worldwide. Such work needs consistent risk registers, decision processes, and schedule controls across many teams. Collaborative delivery models also require managers who can build alignment among owners, designers, contractors, and regulators. Digital coordination can improve visibility, but it does not replace experienced program leadership. The Construction project management services market therefore benefits where owners have high delivery risk and limited internal oversight capacity.
Outsourcing by Asset Owners
Asset owners outsource delivery work when they need specialist systems, wider talent access, or flexible capacity. The choice is most valuable when a program needs early capital planning and commercial controls. Outsourced teams can bring established reporting practices to complex portfolios. Some public agencies are rebuilding internal project controls capability, which limits outsourcing for routine work. Providers therefore need to show measurable outcomes rather than simply supply staff. The Construction project management services market gains most where specialists complement internal teams on demanding assignments.
Programmatic Capital Spending by Data Centers and Life Sciences
Data center and life sciences programs are creating focused demand for disciplined project delivery. These assets need close coordination of power, cooling, commissioning, quality systems, and complex suppliers. Jacobs was appointed engineering, procurement, and construction management lead for Hut 8's River Bend data center in Louisiana. Life sciences facilities also require program teams that understand regulated manufacturing environments. The Construction project management services market benefits as owners seek predictable schedules for assets with high operating and capital stakes. Providers with mission-critical experience can compete for scopes that are harder to standardize.
Restraints Impact Analysis of Construction Project Management Services Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Construction-Cycle Volatility and Project Delays | -1.9% | Global, acute in North America and Western Europe | Short term (≤ 2 years) |
| Fee Pressure in Commoditized Assignments | -1.3% | Southeast Asia, South America, with spillover to North America and Europe | Medium term (2-4 years) |
| Fragmented Liability and Professional Risk | -1% | Global, most pronounced in multi-jurisdictional programs | Long term (≥ 4 years) |
| Procurement Fragmentation Across Jurisdictions | -0.7% | Southeast Asia, Europe, and South America | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Construction-Cycle Volatility and Project Delays
Construction-cycle volatility can delay project starts and weaken fee visibility for service providers. Higher materials costs, financing costs, and labor constraints can lead owners to phase or rescope work. Fixed-fee assignments are exposed when consultants must remain ready during uncertain mobilization periods. Project delays can also increase the cost of retaining specialist teams. Multi-year public frameworks offer some protection because they provide a broader volume of work. The Construction project management services market remains exposed where private investment decisions change quickly.
Fee Pressure in Commoditized Assignments
Fee pressure is highest when clients buy routine supervision work primarily on price. In those assignments, providers have less room to invest in people, data systems, and specialist capability. Mid-sized firms face particular pressure between lower-cost suppliers and established premium providers. Differentiated commercial controls, sector specialization, and public framework positions can improve resilience. The Construction project management services market has stronger pricing where teams share responsibility for delivery outcomes. Firms that rely only on broad, standard scopes face the clearest margin risk.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Construction Project Management Services Market Segment Analysis
By Service Type:
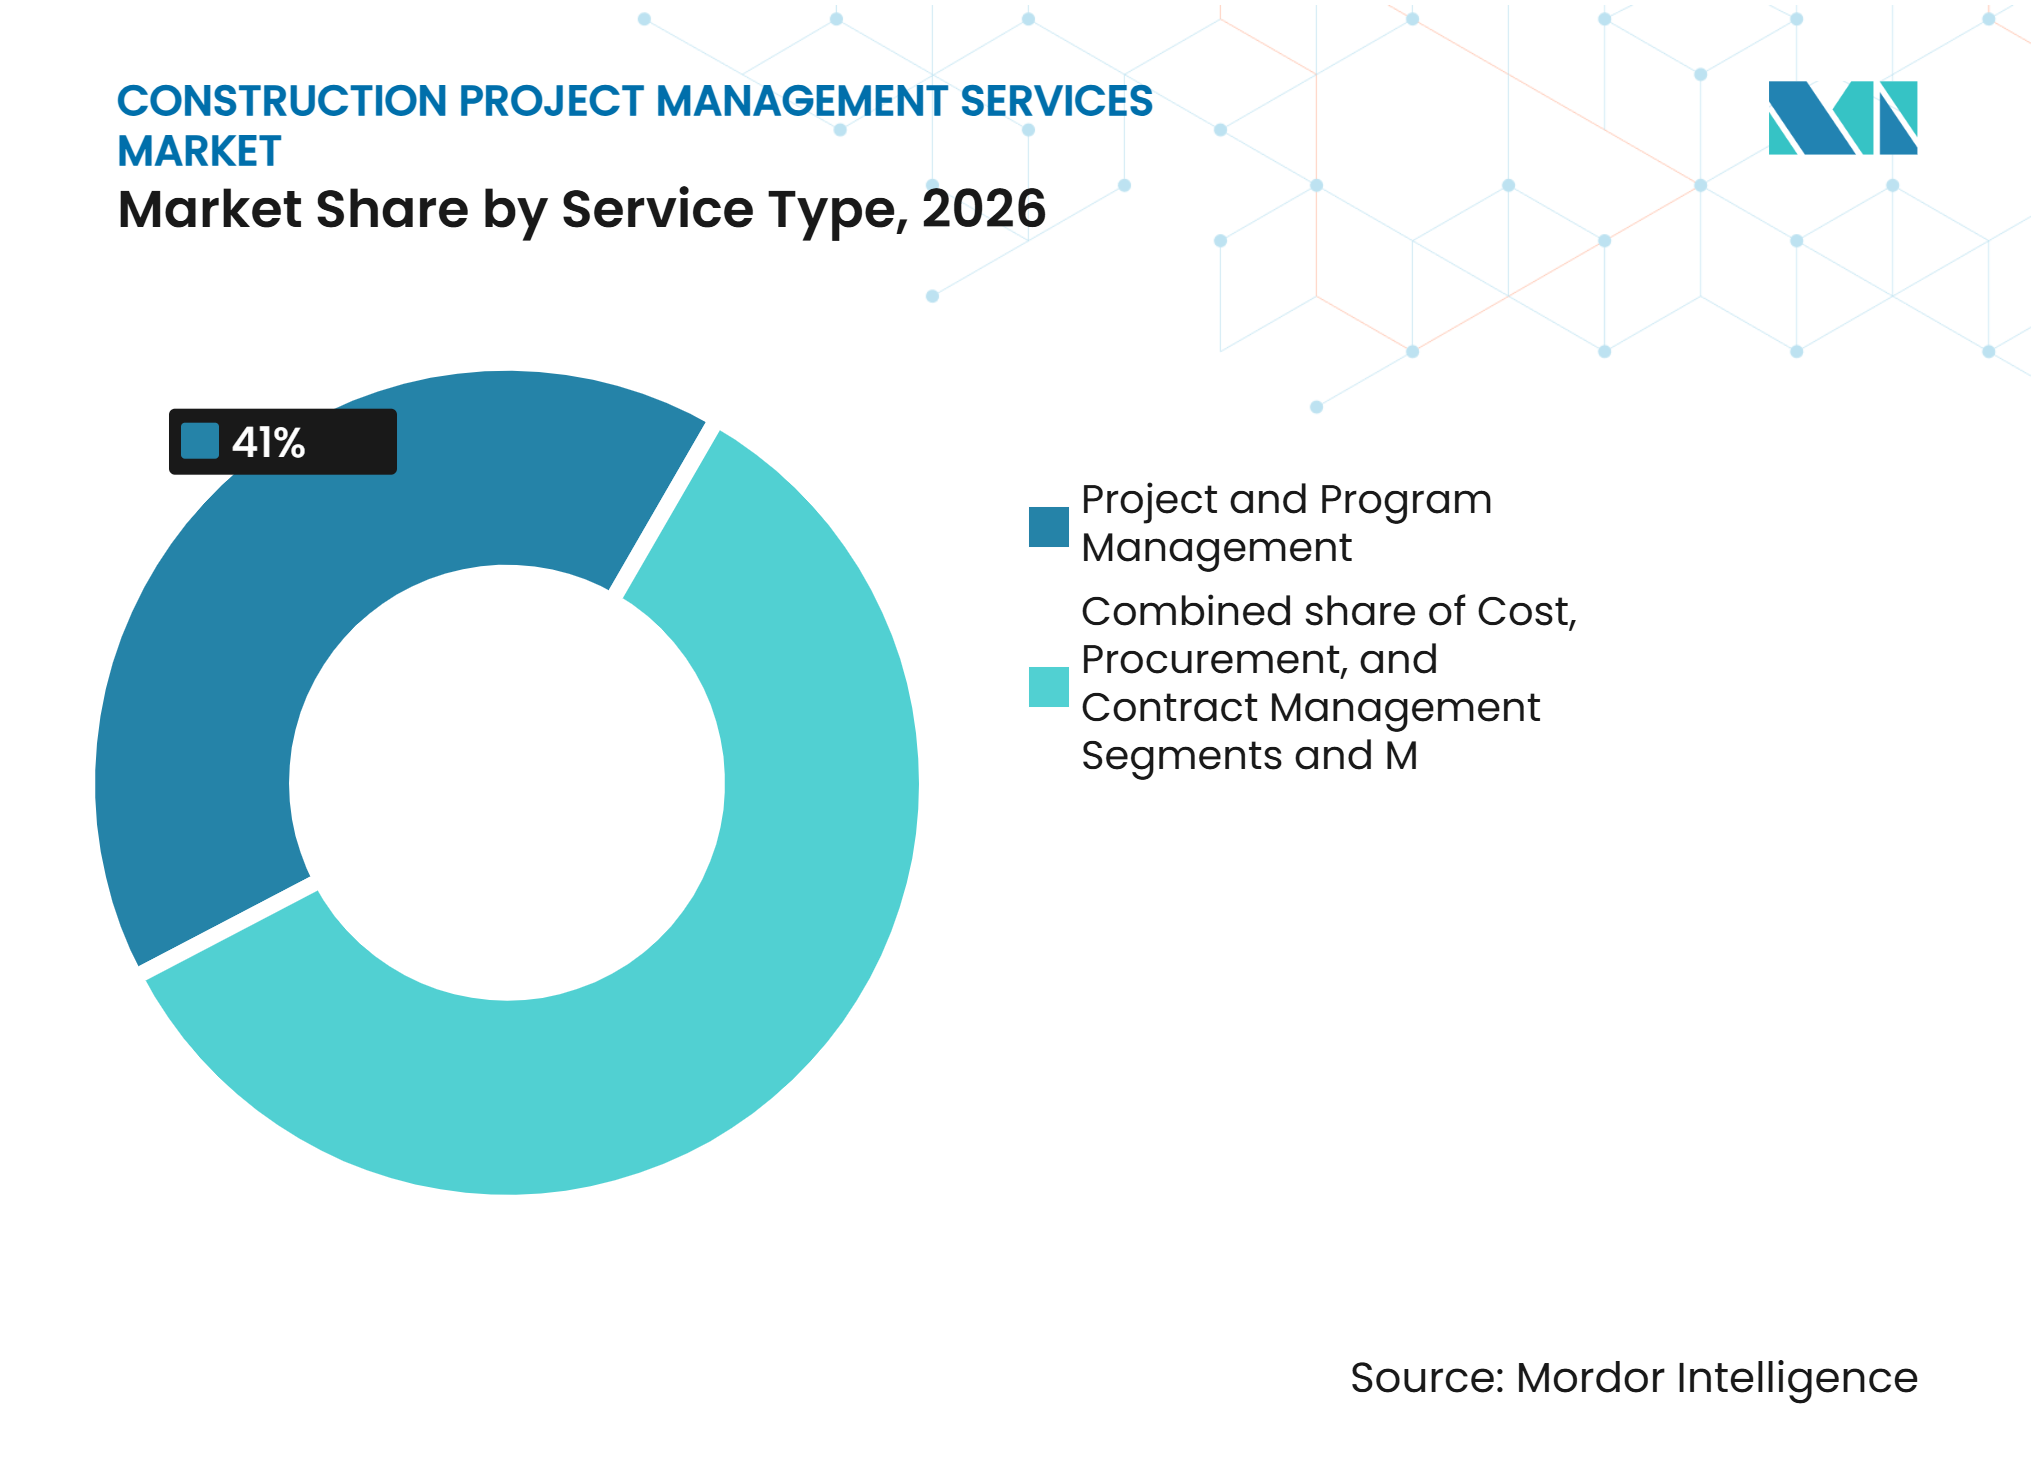
Project and Program Management Leads the Service MixProject and Program Management held a 41.0% Construction project management services market share in 2026, making it the largest service category. The segment covers capital planning, program governance, project management offices, and senior reporting. Its scale reflects owner demand for support before construction work begins. Large owners use these teams to connect budget decisions with schedule, procurement, and risk controls. This work becomes more valuable when a program includes many projects and delivery partners. The Royal Institution of Chartered Surveyors supports professional standards that help clients assess capability in complex built-environment work. These requirements can create an advantage for providers with established governance practices. Project and Program Management is also forecast to grow at a 9.00% CAGR through 2032, reinforcing its role as the leading service type.
Cost, Procurement and Contract Management remains important because cost inflation and long-lead equipment can affect delivery decisions early. Owners increasingly need commercial controls from the start rather than after a contract is awarded. Construction Supervision and Quality Management continues to serve regulated work in water, nuclear, and life sciences facilities. The other services category includes risk advisory, claims management, and digital program controls. These services can expand as clients look for earlier warnings of commercial problems. The input does not provide a forecast growth rate for a fastest-growing service type. The Construction project management services industry therefore depends on service providers that can combine senior governance with practical commercial discipline. Firms that only offer basic supervision face greater competition from lower-cost providers.



By Project Type:
Infrastructure Construction Anchors DemandInfrastructure Construction held 38.0% of the Construction project management services market in 2026, supported by long-term transport, water, and energy programs. Public programs can provide a more stable base because they are less dependent on short-term private investment. The American Road and Transportation Builders Association states that U.S. states committed USD 300.5 billion in highway and bridge formula funds across 129,600 projects. This pipeline needs planning, procurement, schedule oversight, and reporting through several delivery stages. Water and energy projects also require teams that can manage environmental and utility approvals. The segment favors providers that understand public procurement and stakeholder engagement. Infrastructure work often runs for years, which can strengthen client relationships and improve visibility. It remains the largest project type within the Construction project management services market.
Industrial Construction is forecast to expand at a 9.30% CAGR through 2032, the fastest rate among project types. Data centers, semiconductor facilities, and reshoring-related factories are increasing the need for specialist program teams. These projects require controlled power, utilities, equipment installation, and commissioning processes. Jacobs' River Bend appointment shows how owners use engineering, procurement, and construction management for major data center programs. Life sciences projects add documented quality and compliance requirements. Commercial Construction continues to benefit from data center shell-and-core work and urban conversion activity. Residential Construction remains the smallest category and faces pressure from affordability conditions. Providers with experience across infrastructure and industrial work can reduce their reliance on one investment cycle.
By Service Delivery Mode:
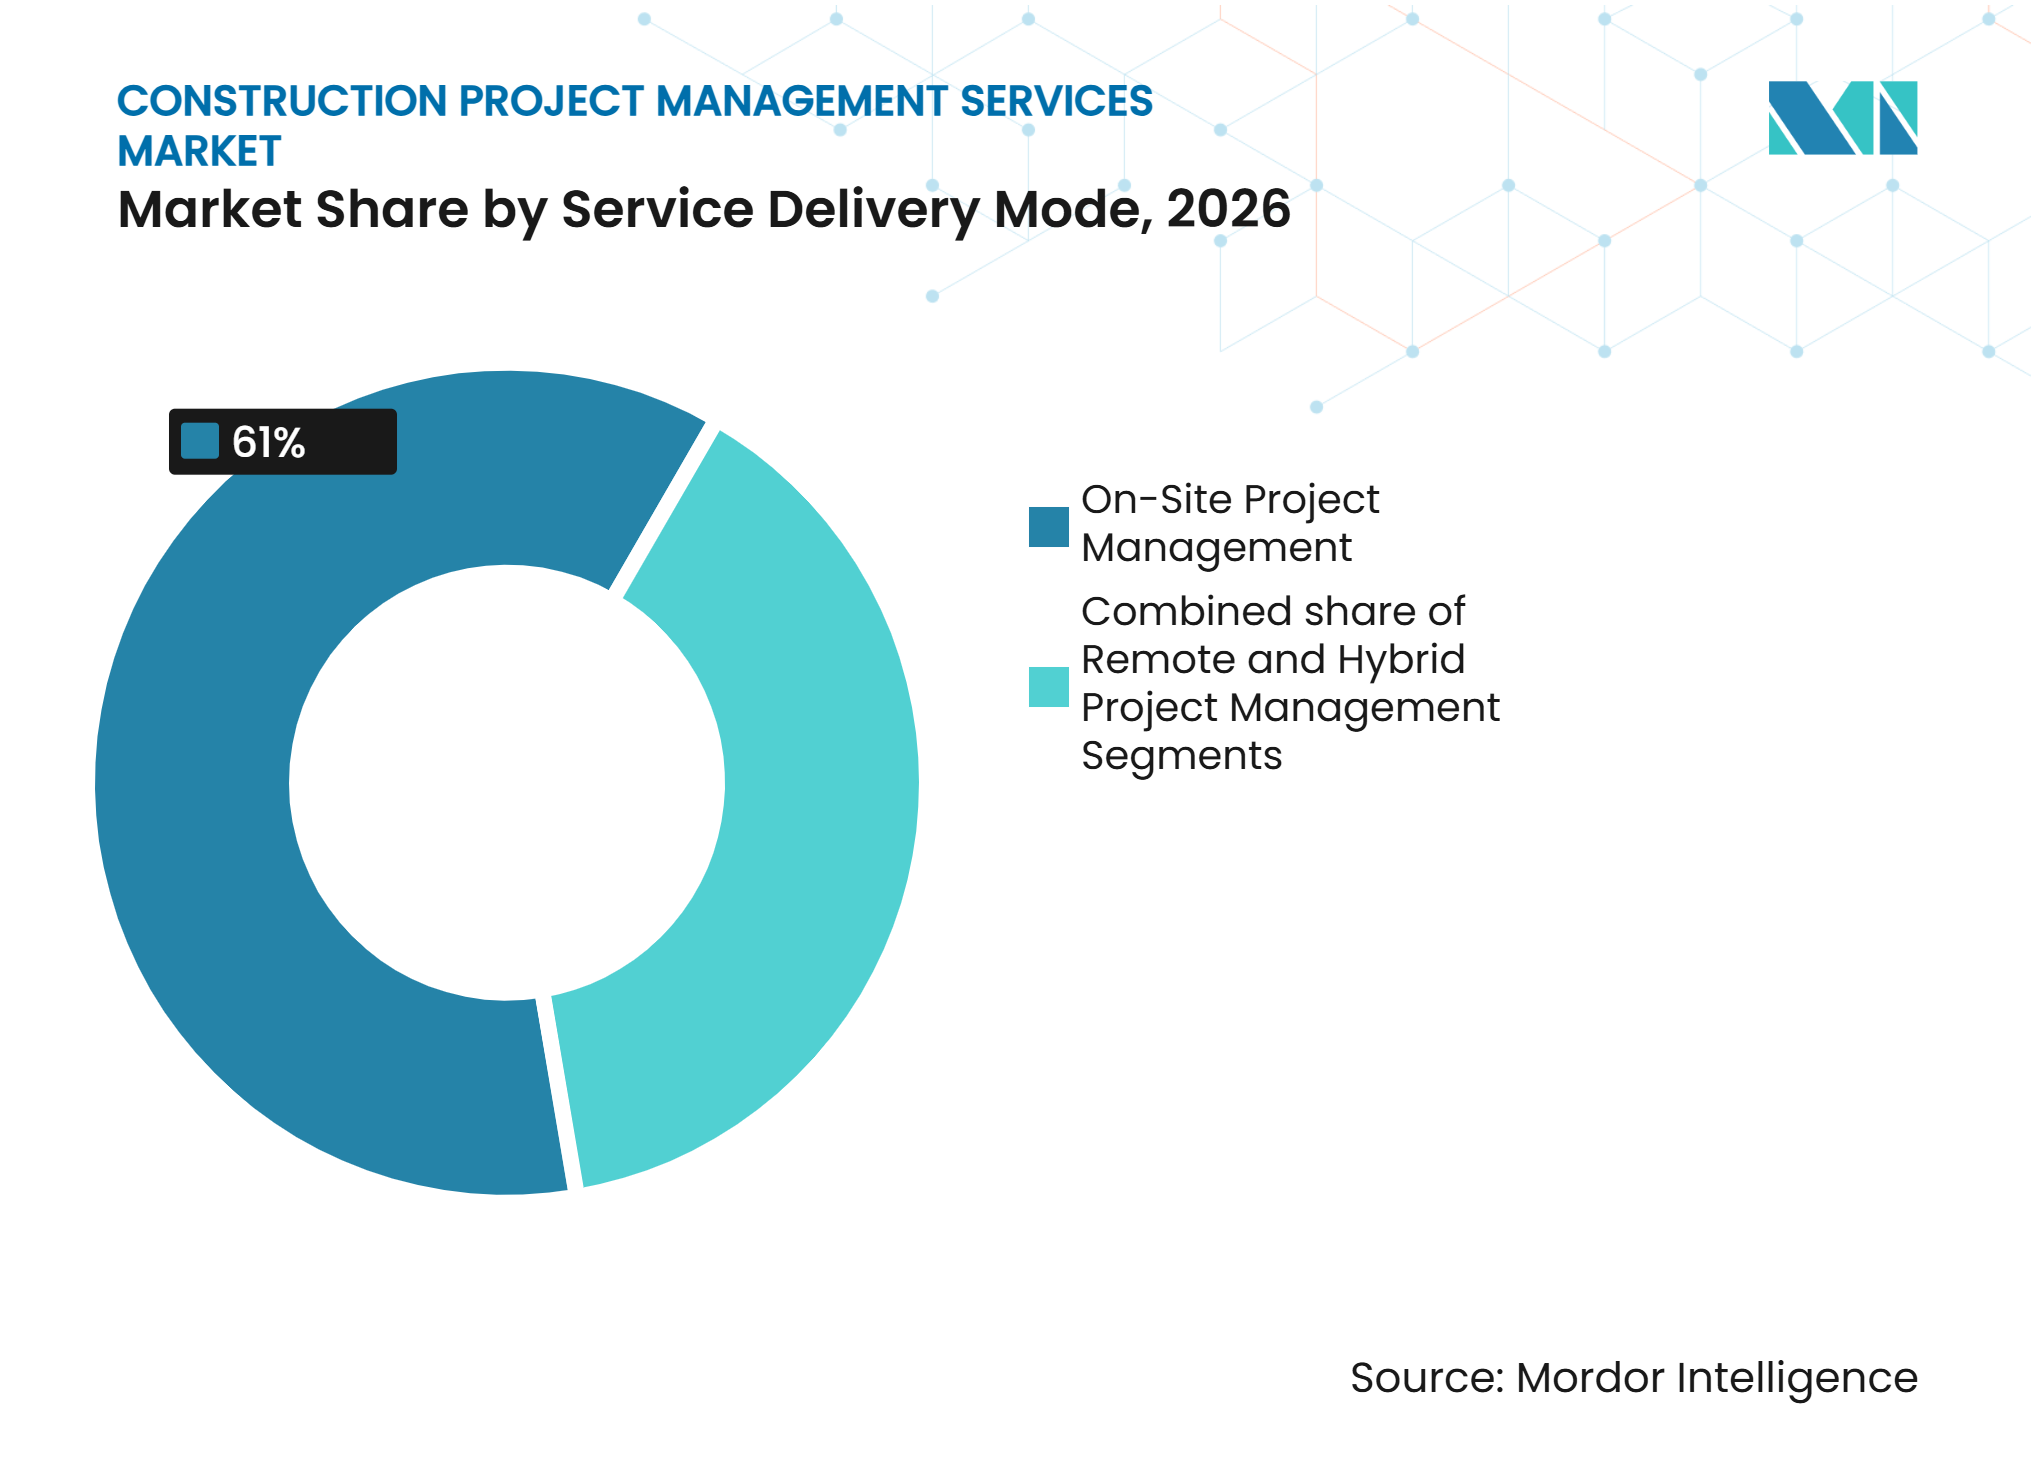
On-Site Management Remains CentralOn-Site Project Management held 61.0% of the Construction project management services market in 2026. It remains necessary where physical coordination, site quality reviews, and contractor interfaces require daily attention. Large, multi-contractor projects still need managers who can address issues as they occur. Owners also rely on site teams to maintain safety, quality, and stakeholder coordination. Digital tools can improve access to information, but they cannot fully replace physical oversight. On-site work is especially important in regulated manufacturing, complex transport, and infrastructure projects. The segment's position shows that technology is changing work allocation rather than eliminating field roles. It remains the largest delivery mode in the Construction project management services market.
Remote Project Management is projected to grow at an 11.61% CAGR through 2032, the highest rate among delivery modes. Cloud systems, drone-based progress monitoring, connected sensors, and shared data platforms make distributed oversight more practical. The Royal Institution of Chartered Surveyors identifies artificial intelligence investment as a current consideration for construction investors. Remote approaches can help experienced staff support more than one site without constant travel. Hybrid delivery combines senior remote leadership with on-site teams responsible for quality and local engagement. Adoption will be strongest where owners have reliable project data and clear processes for decisions. Providers that invest in data quality can make remote work more credible for clients. The Construction project management services industry will continue to use site-based teams for tasks that demand direct presence.

Geography Analysis
North America
North America held 33.0% of the Construction project management services market in 2026. Transport, water, energy, and data center capital programs support demand for program controls across the region. The United States provides the largest national contribution because its public infrastructure pipeline includes many separate projects. The American Road and Transportation Builders Association reports USD 300.5 billion in state commitments for highway and bridge formula funds across 129,600 projects. Such projects require reporting, procurement coordination, and careful control of contractor interfaces. Water programs also create work where Environmental Protection Agency requirements and per- and polyfluoroalkyl substances compliance duties affect planning. The Water Infrastructure Finance and Innovation Act supports eligible water infrastructure financing. Data center investment is shifting talent needs toward mechanical, electrical, and plumbing coordination, power systems, and commissioning. AECOM's Highway 413 assignment demonstrates the role of long-term program management contracts in Canada. Firms with public-sector experience and established technical teams have a strong position in the region.
Asia-Pacific
Asia-Pacific is forecast to grow at a 10.50% CAGR through 2032. Government infrastructure and private manufacturing investment are expanding at the same time across several countries. India needs delivery capacity for roads, metro systems, urban development, and industrial corridors. Southeast Asia is also attracting semiconductor and electric vehicle investment that needs specialized utilities and environmental controls. Hong Kong's Northern Metropolis is a 30,000-hectare program connecting northern Hong Kong with Shenzhen. Mace Consult's appointment introduced a program management office model and digital reporting platform for the development. This model can help agencies collect information and make decisions across a large portfolio. Providers need local teams that understand procurement, permitting, and stakeholder requirements. Strong digital controls can be a differentiator where programs are spread across many sites. Asia-Pacific offers the fastest growth outlook for the Construction project management services market.
Europe, Middle East and Africa, and South America
Europe combines steady demand from long-term transport, energy, and nuclear work with growing grid and hydrogen programs. The United Kingdom needs specialist delivery teams for nuclear decommissioning, new nuclear capacity, offshore energy, and major transport programs. In the Middle East, Expo 2030 Riyadh and FIFA 2034 infrastructure continue to support large delivery opportunities. Bechtel was selected in 2025 as project management consultant for the 2030 World Expo in Riyadh. The mandate covers infrastructure program management across a 6-square-kilometer site. Digital auditability and Environmental, Social, and Governance requirements are becoming more important in the United Arab Emirates. South America is gaining work from public-private partnership transport programs and mining investment. However, procurement timing and political cycles can delay awards. Providers with local partners and resilient risk processes are better placed across these mixed geographies.
Competitive Landscape
Market Concentration
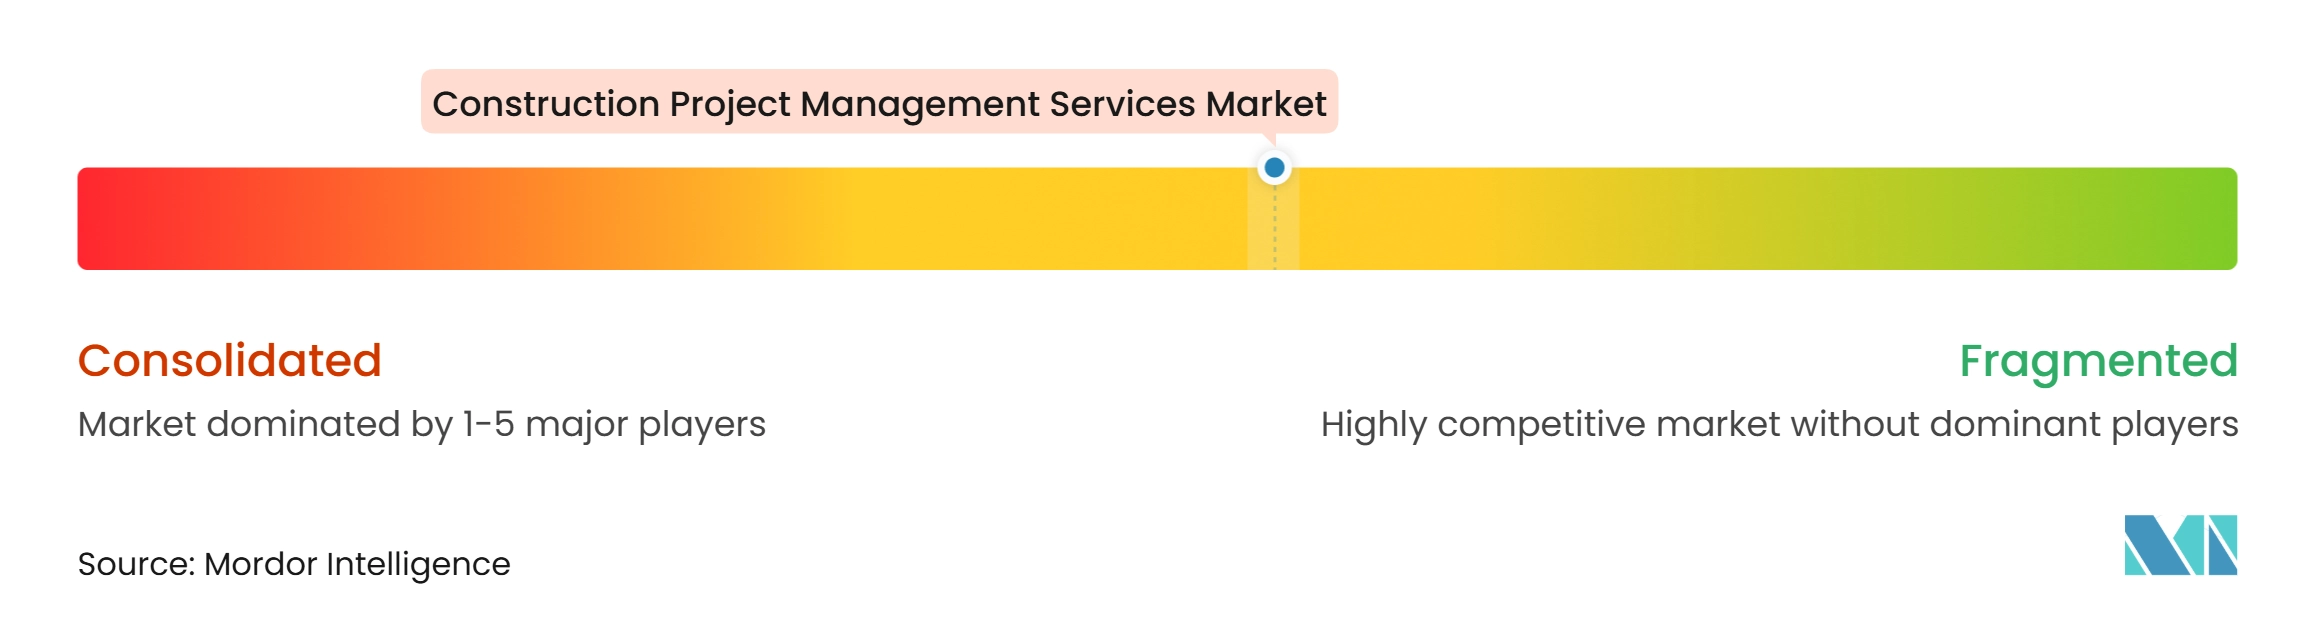
The Construction project management services market is moderately consolidated among large providers with long client relationships and public framework positions. AECOM, Jacobs Solutions, WSP Global, Parsons Corporation, and AtkinsRéalis Group compete through geographic reach, technical depth, and program delivery credentials. Procore's 2026 common data environment announcement shows that software providers are also competing for control of connected project information. This puts pressure on professional services firms to pair digital tools with experienced judgment and credible governance.
Strategic moves increasingly focus on capability depth rather than simple geographic expansion. Jacobs completed its acquisition of the remaining 35% stake in PA Consulting in January 2026 for USD 1.6 billion, adding advisory capabilities across digital transformation, health, energy, defense, and complex program delivery. Jacobs also became engineering, procurement, and construction management lead for Hut 8's River Bend data center. AECOM's October 2026 Highway 413 appointment strengthened its position in long-duration Canadian transport delivery.
Regional and mid-sized firms compete through local regulatory knowledge, sector expertise, and faster mobilization. Professional standards from the Royal Institution of Chartered Surveyors and information management practices aligned with International Organization for Standardization 19650 can influence public and institutional procurement. Parsons' work on the Dubai Metro Blue Line shows the value of established transit expertise, while Arcadis expanded its German rail position through its 2025 acquisition. Competition will remain active as clients seek providers that can manage cost, schedule, digital information, and compliance together.
Construction Project Management Services Industry Leaders
-
AECOM
-
Jacobs Solutions Inc.
-
WSP Global Inc.
-
Arcadis NV
-
Tetra Tech, Inc.
- *Disclaimer: Major Players sorted in no particular order
Construction Project Management Services Market Companies Covered in this Report
- AECOM
- Jacobs Solutions Inc.
- WSP Global Inc.
- Arcadis NV
- Tetra Tech, Inc.
- Fluor Corporation
- Bechtel Corporation
- Turner Construction Company
- KBR, Inc.
- AtkinsRealis Group Inc.
- Mott MacDonald Group Limited
- HDR, Inc.
- Ramboll Group A/S
- Black & Veatch Holding Company
- Stantec Inc.
- Hill International, Inc.
- Parsons Corporation
- GHD Group Pty Ltd.
- Sweco AB
- SNC-Lavalin Constructors Inc.
Recent Industry Developments in Construction Project Management Services Market
- November 2026: Jacobs was selected by ACCIONA to provide multidisciplinary design and project delivery services for the Warkworth to Te Hana Ara Tūhono section of New Zealand's Northland Corridor highway program. The work covers design management, utility relocations, digital engineering, and geotechnical engineering services.
- October 2026: An AECOM-led joint venture, 413 Continuity Partners, was awarded Ontario's Highway 413 Program Management Consultant contract by the Ministry of Transportation. The 10-year assignment covers program management, technical leadership, environmental coordination, and construction oversight.
- September 2026: Parsons Corporation was awarded a USD 85 million agreement as owner's advisor for the progressive design-build development of U.S. Space Command's new 950,000-square-foot headquarters at Redstone Arsenal, Alabama. The agreement has a 75-month performance period.
Global Construction Project Management Services Market Report Scope
Segmentation Overview
| Project and Program Management |
| Cost, Procurement and Contract Management |
| Construction Supervision and Quality Management |
| Other Project Management Service |
| Residential Construction |
| Commercial Construction |
| Industrial Construction |
| Infrastructure Construction |
| On-Site Project Management |
| Remote Project Management |
| Hybrid Project Management |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia - Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia - Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| South Africa | |
| Nigeria | |
| Rest of Middle East & Africa |
| By Service Type | Project and Program Management | |
| Cost, Procurement and Contract Management | ||
| Construction Supervision and Quality Management | ||
| Other Project Management Service | ||
| By Project Type | Residential Construction | |
| Commercial Construction | ||
| Industrial Construction | ||
| Infrastructure Construction | ||
| By Service Delivery Mode | On-Site Project Management | |
| Remote Project Management | ||
| Hybrid Project Management | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia - Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia - Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| South Africa | ||
| Nigeria | ||
| Rest of Middle East & Africa | ||
Key Questions Answered in the Report
What is the projected value of construction project management services by 2032?
The sector is projected to reach USD 18.12 billion by 2032, from USD 12.13 billion in 2027, at an 8.35% CAGR.
Which service type has the largest share in construction project management services?
Project and Program Management is the largest service type, with 41% of revenue in 2026.
Which project type is growing fastest through 2032?
Industrial Construction is forecast to grow at a 9.30% CAGR, supported by data centers, semiconductor facilities, and manufacturing projects.
Why are data centers important to project management providers?
Data centers require complex power, cooling, utility, equipment, and commissioning coordination, which increases demand for specialist delivery teams.
Which delivery mode is growing fastest?
Remote Project Management is projected to expand at an 11.61% CAGR through 2032 as connected data and digital monitoring broaden its use.
Which region has the fastest growth outlook?
Asia-Pacific is forecast to grow at a 10.50% CAGR through 2032, supported by infrastructure and manufacturing investment.